Small Cap Value Report - Tue 22 May 2018 - PIL, BMY, TPT, R4E

Good morning, it's Paul here.
CVA newsflash
There was an interesting twist in the topical theme of retailer/hospitality companies seeking to restructure their property portfolios using CVAs.
CityAM reported via the Sunday Times, that Next (in which I have a long position) is asking for a "CVA clause" in new leases. This would trigger a rent cut for Next, if any of its neighbours gain a rent reduction through a CVA.
If a landlord is desperate to attract or retain Next as an anchor tenant in a struggling shopping centre, then they might agree to this.
Therefore, if Next is successful in gaining favourable CVA clauses in new leases, then that could result in landlords voting against some future CVAs. My feeling is that landlords may start to dig their heels in, and refuse some future CVA proposals. Otherwise, the flood gates would open, as numerous struggling retailers chanced their luck with a CVA proposal.
Landlords might start refusing CVA proposals, as a deterrent & warning to retailers seeking to exploit the process unreasonably. Perhaps landlords should demand equity (through options or warrants) as part of agreeing CVAs? After all, why should landlords take all the pain, only to see restructured retailers emerge as highly profitable, and shareholders receiving all the benefits from the CVA process?
Let's start with a profit warning:
Produce Investments (LON:PIL)
Share price: 149.5p (down 8.8% today, at 08:49)
No. shares: 27.3m
Market cap: £40.8m
Trading update (profit warning)
Produce Investments plc, (AIM:PIL) ("Produce," "Company" or the "Group"), a leading operator in the fresh potato and daffodil sectors, is today providing an update on current trading...
It's quite a nasty profit warning today;
... the Board now expect the Group's profit for the year ending 30th June 2018 to be substantially below current market expectations.
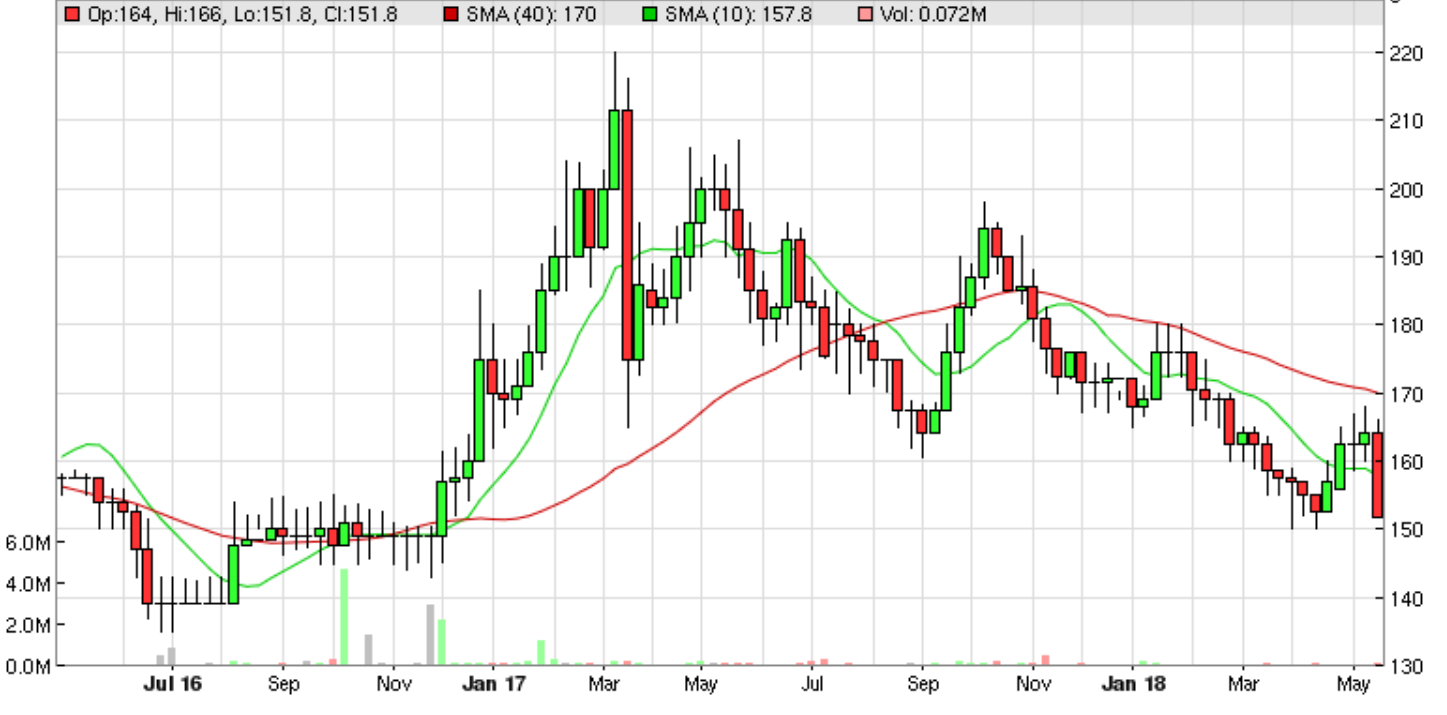
The reason that the share price is only down about 9% today, seems to be because the weather issue was pretty obvious, and was mentioned in detail with the interim results commentary on 22 Mar 2018, here. Although management seems to have been too optimistic about the full year outcome back in March.
Other points mentioned today;
- Impairment of intangibles will be incurred this year.
- lower margins on UK potato crop, in an "oversupplied market"
- Moving year end to August (from June) in future.
My opinion - why on earth would I want to own shares in a potato grower? the only reason would be if the dividend income was very good. Stockopedia shows the forecast yield at 4.87%, which is pretty good actually. Although with profits now much lower than forecast, there is a risk that divis might be cut.
The PER looks very low, but of course that is likely to rise now that the company has said that it will miss forecasts by a substantial amount.
I've had a quick look at the most recent balance sheet, and there's rather too much debt for my liking, and a pension deficit.
It seems strange that broker forecasts were not reduced, given that the weather problems should have been foreseen. Existing forecast is for 26p EPS. Substantially below that could be anything below say 20p, at a guess. Since the company hasn't given proper guidance, then the share is impossible to value.
It doesn't interest me at all. Although I can see an argument for buying a weather-dependent share like this when the weather has been adverse, as the share could then be attractively cheap, and subsequently recover in a good weather year.
As you can see below, the share price is back to where it was 2 years ago. Although investors have received a decent flow of divis over that time.
Bloomsbury Publishing (LON:BMY)
Share price: 222p (up 7.3% today, at 09:42)
No. shares: 75.33m
Market cap: £167.2m
Preliminary results - for the year ended 28 Feb 2018, from this book publisher (including Harry Potter).
I'm impressed, these are good figures (and outlook).
Key points;
- Revenue up 13% to £161.5m, which is slightly above the consensus forecast of £161.2m shown on the StockReport
- Adjusted diluted EPS up 10% to 13.92p (PER of 15.9) - ahead of the 13.5p consensus forecast
- Total dividends up 12% to 7.51p (also ahead of 7.0p forecast) - well covered by both earnings and cashflow. This gives a yield of 3.4%
- Excellent balance sheet, includes net cash of £25.4m - which is material to the valuation of the company
- Strong cashflows this year & last year, although note that increased trade creditors boosted cashflow in both years
That all looks impressive.
Adjustments - I always like to double-check that the adjustments being made to accounts, to arrive at the headline EPS figure, are reasonable.
Here is note 3 from today's accounts;
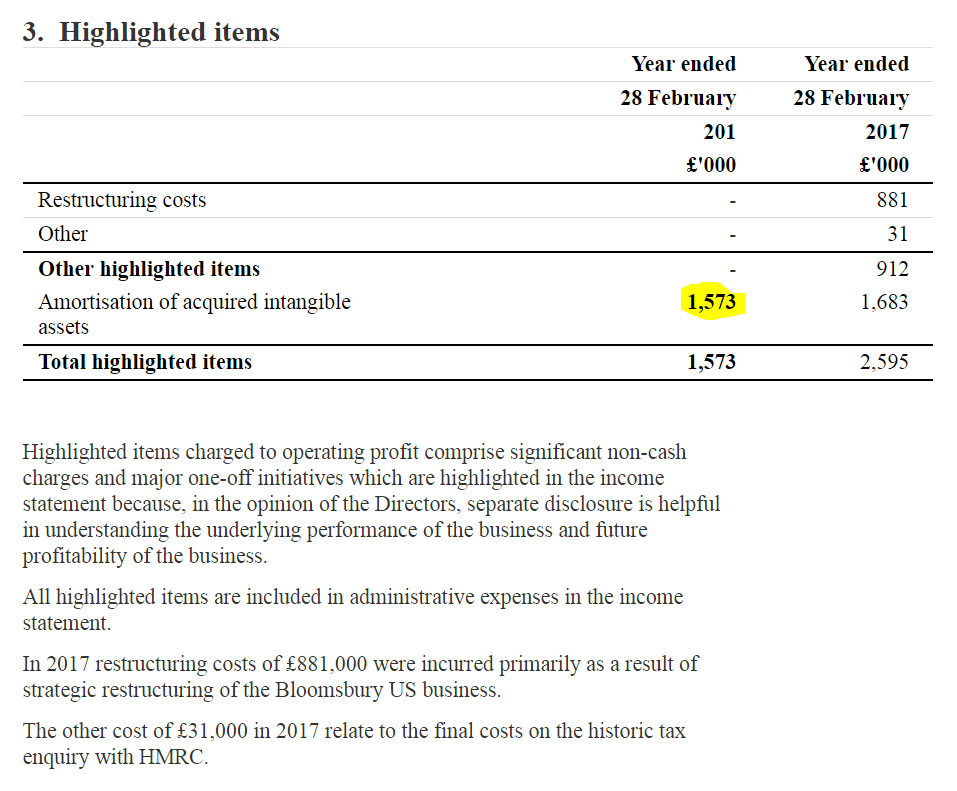
That looks absolutely fine to me. The only item this year is stripping out amortisation of acquired intangibles (i.e. goodwill), which is perfectly sensible & reasonable, in my view.
Outlook - is also impressive. I won't cover all the detail, but the conclusion is good;
... the Board believes the Group's performance will be well ahead of our previous expectations for the forthcoming 2018/19 year.
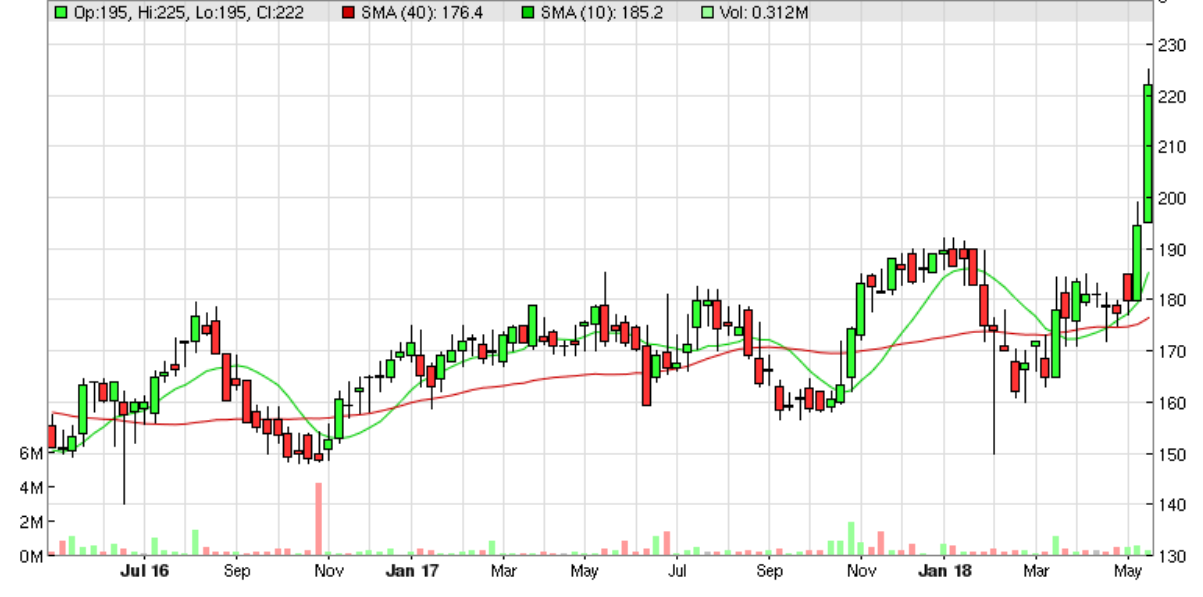
Shareholders must be delighted with that, although it looks like the good news might have leaked out yesterday;
Valuation - unfortunately, I can't find any broker updates today, there's nothing on Research Tree as yet. That's a pity, as to value the company now, I'm having to use a degree of guesswork.
The existing forecast for the current year seems to be only 13.3p EPS (down 4.5% on 02/2018 actual result). What does "well ahead" mean? At a guess, maybe 5-15%? That implies EPS of somewhere between 14.0p and 15.3p - so at 222p per share, the PER would be between 14.5 and 15.9.
Given that the net cash pile is about 15% of the market cap, I would be inclined to adjust down that forecast PER range, by 15%, which gives a PER of 12.3 to 13.5 - that's on an adjusted basis resetting the balance sheet to a nil cash or debt basis.
My opinion - the valuation looks fairly attractive for a company that seems to be firing on all cylinders. It has a very attractive balance sheet, and a reasonable yield too.
Overall then, this gets a thumbs up from me. I'm impressed with the figures and the outlook, and the valuation looks attractive, even after recent gains. The question is how high can the valuation of a book publisher go? It's likely to face a permanent headwind of investor scepticism in the long-term prospects for the sector.
EDIT: There are some excellent reader comments below on these results from Bloomsbury Publishing (LON:BMY) - especially comment numbers 12,13, and 14, so please do scroll down to have a look at those.
Topps Tiles (LON:TPT)
Share price: 72.25p (up 4.7% today, at 11:01)
No. shares: 193.5m
Market cap: £139.8m
(at the time of writing, I hold a long position in this share)
Topps Tiles Plc, the UK's largest tile specialist, announces its interim results for the 26 weeks ended 31 March 2018.
This share cropped up in my talk at the Mello Derby investor conference a few weeks ago. I noted how the valuation looked reasonable, and the share could have growth upside from it entering a new market - commercial tiling (Parkside) - thus potentially (long-term) doubling the size of its addressable market.
Therefore, after the conference I decided to dip my toe in with a smallish initial purchase.
For the half year;
- Revenues (adjusted to exclude Parkside) up 2.8% to £109.6m (of which LFL growth was +0.6% - NB they define LFL as including online, as well as stores, which is a bit cheeky)
- Adjusted profit before tax down 28.7% to £7.2m
- Adjusted EPS down 26.8% to 3.01p (4.11p H1 LY)
Adjustments - I think the company is pushing the envelope here, with some of these adjustments (see table below). However, they're relatively modest in size, so I can live with this;
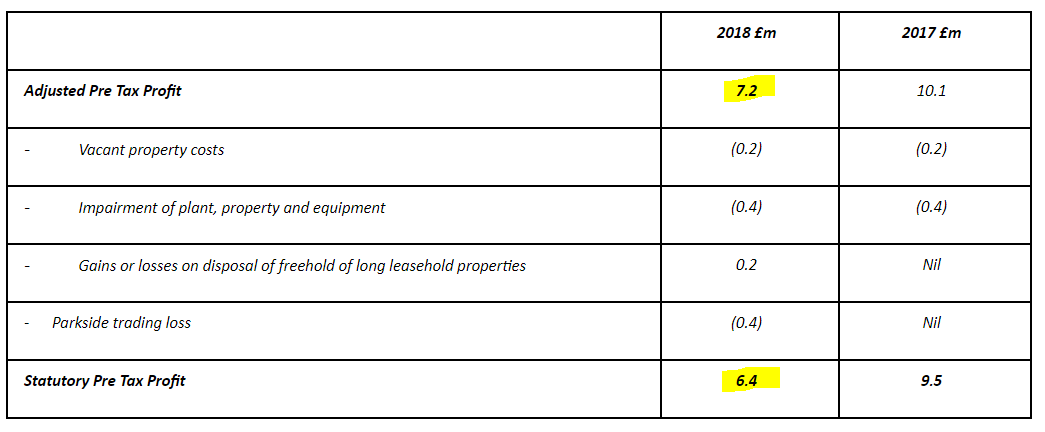
I think it's always worth scrutinising adjustments, as creative accounting often rears its ugly head! However, in general I think most companies are simply trying to show the underlying trading performance of a business. We're free to adjust the figures manually ourselves anyway, if we don't agree with any adjustments.
Balance sheet - I'm not madly keen on this, as it has a bit more debt than I would like. Net debt is £25.1m. However, the cash generative nature of the business is such that this is not a concern.
However, if trading were to seriously fall off a cliff, then I would be out of here like a shot.
Interim dividend - held at 1.1p. The full year divis will be 2x covered, so that implies a small cut in the final divi is probably on the cards.
Current trading - is down 0.2% LFL for the 7 weeks to 19 May 2018. Since this includes online sales, which are likely to be strongly up, then the performance of the stores is likely to be worse than this headline number.
Outlook - this sounds similar to the wording last time, from memory;
We continue to take a prudent view of the second half outlook and expect that pre-tax profits for the full year will be within the current range of market expectations....
... The current range of analyst expectations is £15.5 million to £16.5 million, with consensus at £15.9 million
It fills me with joy when I see a company clearly stating what market expectations are! This is very private-investor-friendly, so well done to Topps and its advisers - excellent stuff. Everyone should do this please.
Broker commentary - there's a very useful update from Liberum, published today, and available to subscribers of Research Tree. They've prepared a useful chart showing LFL sales by quarter, for the last 2 years.
Forecasts are unchanged, with 6.3p adj. EPS expected for this year, which looks do-able, and results in current year forecast PER of 11.5.
My opinion - I'd say this is a satisfactory set of results, in terms of being what was expected. I have a few reservations though: balance sheet not as strong as I would like, and the reporting of LFL including online sales is probably masking a bigger deterioration in store sales - which would explain why profit has fallen a fair amount.
On the plus side, the valuation looks reasonable, and this has always struck me as a well managed business, with a strong market niche. I like the expansion into commercial tiling, and that's the main reason I decided to buy some shares in this company. The new growth potential from that could, at some point, possibly trigger a re-rating of this share.
A risk to consider is that competitors doing CVAs (e.g. Carpetright) are gaining an unfair competitive advantage by lowering their rents drastically, and exiting all their problem stores in one fell swoop. This is both a threat and an opportunity to Topps - because it should gain market share in the areas where Carpetright is closing stores.
I'll see how things progress over the next year or so. If progress is made, then I'll buy more. If profits continue to deteriorate, then I'll ditch them. Hence why it's only a small opening position for me, at the moment. I usually like to scale into positions over time, depending on the progress the company is making, starting off small.
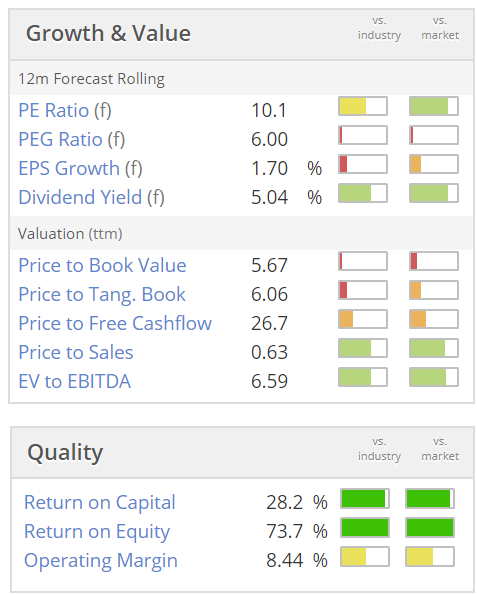
Value and quality look quite good, but the missing link is earnings growth;
Reach4Entertainment Enterprises (LON:R4E) - just a quick comment here, as the company doesn't interest me at all really. This is a supposed turnaround situation, under new management, of a group of marketing companies focused on theatre.
There are far too many adjustments to the accounts, which massages a £2.4m operating loss into a £976k positive adjusted EBITDA.
2018 is expected to be a "year of transition", which is code for profit not rising any time soon.
Despite having raised £5.5m in fresh equity, in Dec 2017, the balance sheet still looks weak - NTAV is only £590k. The current ratio isn't great either, at 1.01 (well below my usual cut-off, of 1.3)
I can't see any attractions to this share, and why it's valued at £16.3m, when it doesn't make any real profit, is beyond me. Investors here must have faith in the new management, and their ability to improve performance. That's not something I'm inclined to punt on.
Unless I have a second wind later, that's probably it for today.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Someone Aberforth Partners LLP/Nortrust Nominees Ltd is showing some interest in Topps Tiles (LON:TPT) (from 5 to 10%) :
Announcement: Wed 23rd May, 2018 3:46pm
https://www.stockopedia.com/share-prices/topps-tiles-LON:TPT/news/topps-tiles-holdings-in-company-urn:newsml:reuters.com:20180523:nRSW0793Pa/
... or maybe it is just an annual thing ...
Announcement: Fri 26th May, 2017 4:02pm
https://www.stockopedia.com/share-prices/topps-tiles-LON:TPT/news/topps-tiles-tr-1-notifications-of-major-interests-in-shares-urn:newsml:reuters.com:20170526:nRSZ4282Ga/
In 18 years they might get to 100%.
Hopefully its ok to post the link here, but there's a nice video interview with Bloomsbury Publishing (LON:BMY) CEO Nigel Newton talking to Proactive Investors earlier today: https://youtu.be/8Q37eJYNBR4
Many thanks for the excellent reader comments today on Bloomsbury Publishing (LON:BMY) picking up on a few things that I didn't cover in the main report. I don't usually have time to read all the narrative that goes with figures, so I particularly like it when readers pick up on stuff that I've missed, and add comments here, it really adds value, so thank you!
I've added a note in the main report, flagging up the excellent reader comments, so hopefully other readers will see them.
Investing is a team sport, so thanks for your input everyone!
Best wishes, Paul.
Hi Paul, I always particularly enjoy your analysis around NXT, and wondered if you might make a comment about MKS their 'competitor' and rapidly emerging small cap considering they have basically halved in the last couple of years, wihen they report this week, I have never read any opinion from you on these so would appreciate even a one liner.
Paul,
On Bloomsbury Publishing (LON:BMY) you ask "The question is how high can the valuation of a book publisher go? It's likely to face a permanent headwind of investor scepticism in the long-term prospects for the sector."
I think you may wish to consider the growth in digital with regard in particular to the academia market-
"The Bloomsbury 2020 strategy to leverage our academic and professional assets into the academic library market, is delivering well with digital resource revenues up 20% to £4.7 million. Five major new digital resources were launched in the year, ahead of plan. On track to deliver targeted £5 million of profit and £15 million revenue in 2021/22"
If this was a retailer moving from bricks and mortar to online sales I believe you may have a different view of the growth prospects? This and not Harry Potter is the main reason behind my long term conviction in the company. I am particularly interested in the development of the Chinese literary collection to be translated into English.
Dave
In full agreement Dave, although I think that Harry Potter and the various spin offs will contribute for several years to come. As mentioned earlier, the non-consumer side of Bloomsbury Publishing (LON:BMY) appears to have some striking similarities with Relx (LON:REL).
In fairness to Paul his review of the company is much more positive than previous, although I think that the longer term prospects for Bloomsbury Publishing (LON:BMY) are under appreciated.
All the best
Jonno
I agree Jonno that HP will continue to contribute to Bloomsbury Publishing (LON:BMY) for many years to come. The high gross profit and recurring revenues (schools and uni's) from digital is very appealing. Their stable of other top authors is also excellent but both writers changing publishers and the public's taste can be fickle.
Impossible to put a figure on it but if they become the leading platform for english language translations of chinese literature there could be huge upside.
Paul's report was excellent and very positive. I just don't think the market fully appreciates the potential for digital publishing.
Dave
The risk is always that Harry Potter sales will tail off quickly in the next few years.
Over the past few years it has been supported by movies, theme park openings, and new musicals. All these have driven interest in the books.
But where is new interest /demand going to come from in the next few years for HP?
But where is new interest /demand going to come from in the next few years for HP?
There's one born every minute... new customers that is! :-)
All the best, Si
Exactly - Like with Peppa Pig for example - Watched the original Wizard of Oz with the little one (almost 6) last night - She loved it - Classics - Just saying.
I was just about to reply then noted Si and Matylda's responses and could not have put it better. Perhaps the best example is a little company called Disney, Mickey and pals have been making money for over half a century.
However it may be that HP has peaked, all I want is for it to produce reasonable sales whilst the digital growth comes into play. I maintain the market doesn't fully realise the potential for digital. Bloomsbury Publishing (LON:BMY) are conservative by nature but they expect annual digital profits of £5M within three years.
However it may be that HP has peaked, all I want is for it to produce reasonable sales whilst the digital growth comes into play. I maintain the market doesn't fully realise the potential for digital. Bloomsbury Publishing (LON:BMY) are conservative by nature but they expect annual digital profits of £5M within three years.
Dave,
Yes, I increased my holding following this weeks excellent FY results. I can't remember such bullish outlook statements either from a usually understated and conservative management. It's easy to miss the ongoing value of Intellectual Property such as the Harry Potter franchise and its endowment like quality, which I'm sure will generate earnings for many years to come.
All the best, Si
Produce Investments (LON:PIL) seems to be on a hiding to nothing, no matter how good the metrics seem at any one time. A good crop means oversupply and lower prices. A poor crop means fewer sales and lower profits. The company has niche products, but even these are subject to the vagaries of our perfidious weather.
Bloomsbury Publishing (LON:BMY) taking on IBT Taurus is a new venture for them, as they are shifting into academic publishing. This is a good move. Universities subsidise publications by their staff, generally to a level that covers production costs. The results is the publisher gets a cart load of free books, which are then sold at HORRENDOUS prices to academic libraries. Print runs are small, but profits potentially very high. What a contrast!
Just a mention that Bloomsbury Publishing (LON:BMY) spent some of its £25m a few weeks ago when acquiring academic publisher IBT Tauris for £5.8m, of which £4.8m was satisfied in cash. IBT is expected to contribute £3.5m revenue in the current year to end of Feb 2019.
Also, in case anyone missed it, £13.2 m profit before adjustments and 'Due to the strong trading in the year, the Group was able to make a management bonus provision of £2.3 million'.
GAN mentioned in yesterdays report is moving up strongly. A long way to go to catch up to micro stock Web. The entire sector is on fire after the USA ruling.
Gan, the gaming software company headed by Dermot Smurfit Jr, has said that its medium-term strategy is to seek a listing on New York's Nasdaq Exchange.
Speaking to the Irish Independent, Mr Smurfit said that investors in the US represent "a natural audience" for the company, where it is easier to explain Gan's equity story than in the UK.
Gan yesterday announced that it had raised £7.5m (€8.6m) as it continues its expansion in the US.
The funds have been raised on the back of a US Supreme Court ruling that last week struck down a federal law severely restricting sports betting.
The ruling is expected to lead to a liberalisation of US betting laws.
Gan said that it would use the funds - which were raised through a share issue - to "substantially" increase its engineering resources to better serve US clients' services, seek new US clients and launch new services there in anticipation of the more widespread internet sports betting.
Proceeds will also be used to repay in full a £2m loan note issued in April 2017 "in order to strengthen the company's balance sheet".
The company is now debt-free and capitalised to levels the directors of Gan believe "are reasonably required to serve major multi-property and multi-state casino groups in the US".
"This strategic capital-raising exercise positions Gan to consolidate its US market position and capture substantial incremental revenue opportunities available resulting from both internet gaming and sports-betting regulation in New Jersey, Pennsylvania and other US states expected to regulate internet gambling in the near future," said Mr Smurfit.
Apologies Paul
With reference to my earlier post got the ticker wrong, it should be Relx (LON:REL).
Jonno
Good morning Paul
Excellent results from Bloomsbury Publishing (LON:BMY) this morning and confident outlook statement in which it says the performance for 2018/19 will be well ahead of previous expectations, The company is generating a significant amount of cash, £25m on the balance sheet, that it is reinvesting in developing its non consumer division (academic publishing and related digitisation) that has higher margins and more predictable earnings that the consumer division (publishing Harry Potter etc.). The former in my view has similarities to £RELX that at some point might be a potential suitor for Bloomsbury Publishing (LON:BMY). Wishful thinking perhaps but stranger things have happened.
I am aware that you have been somewhat 'lukewarm' on publishing companies in the past and am conscious that books are subject to the fickle of the consumer, but nonetheless would appreciate your views time permitting.
All the best
Jonno
Uninspiring interims from Renew Holdings (LON:RNWH) (Renew if the £ thingy doesn't work). Steady as she goes with the dividend up 10% and the all important margin still edging upwards to 4.9%. Main hope is that the new QTS acquisition boosts performance in the railway engineering field. I know you have criticised the balance sheet in the past but would value your update. I'm long.
Yes please to Bloomsbury Publishing (LON:BMY) . Good set of results (flagged by a 7% increase in share price yesterday!) and very upbeat “well ahead of expectations” outlook. Harry Potter franchise still strong but other strings to the bow as well.
https://www.investegate.co.uk/bloomsburypublishing--bmy-/rns/final-results/201805220700057924O/
Shares are well up (about 20-25%) since the interims in October, albeit quite volatile, but still a decent “V” score of 80 suggests more to come.
Gus.
Bloomsbury Publishing (LON:BMY) please, results and outlook look great
Morning! Versarien (LON:VRS) (makers of actually decent graphene and graphene inks and other industrial businesses, CEO tweets too much, makes money but not profit yet and conventionally overvalued) have had Matt Walker https://www.linkedin.com/in/matt-walker-5bb13330 Head of Outward Direct Investment (DIT) seconded to them for a year. Unprecedented support by government (?) though to my mind confirms my suspicions that they did need some help bringing international deals, like a big China one they're working on, in. Anyone else got any thoughts on this development? (I'm overweight).
If Versarien (LON:VRS) have taken on the DIT head of outward direct investment that makes me think they must be looking at building a facility in China to secure the deal there?
And I imagine that gives rise to the usual concerns about intellectual property rights and requirements for technical transfers in China that are a bit more under the spotlight these days thanks to Mr. Trump.
Yes John, I believe Jinan already have a factory, and Versarien (LON:VRS) machines, picked out. PWC are working on the China contract with them so I think if anyone can protect the IP it would be them. Other leverage they have with Jinan is access to future 2d material developments from manchester & Cambridge, which will not be forthcoming if ip is infringed. Worth googling molybdenum sulphide & boron nitride to see what they can do. As ever, however, there is a risk a university or ici or the like might invent a better mousetrap for producing even thinnergraphene nanoplatelets, or cvd sheets (the actual one-late stuff produced by chemical vapour deposition). As ever, dyor. Even if you don't buy vrs the potential in graphene / 2d materials is mind bogglingly interesting.
My morning smallcap tweet: Marvel at the Potter Universe.
Accrol Group (LON:ACRL), Produce Investments (LON:PIL), Bloomsbury Publishing (LON:BMY), Mountfield (LON:MOGP), Epwin (LON:EPWN), Joules (LON:JOUL)
Accrol (ACRL) Open offer: 1 for 10 at 15p (same as placing price). 38% discount.
Produce Investments (PIL) warns again. As warned, weather did hit crops badly. Add in a margin squeeze and the FY profit will be substantially below mkt expectations. Moving 2019 FY end to August so that Jersey potato crop always falls within YE. What a terrible business agriculture is but is it a buying opp?
Bloomsbury (BMY) FY adj pretax up 10% to £13.2m, above market expectations. Rev up 13%. Harry Potter sales up 31%. I'm amazed at the stamina of the Potter Universe. Guides FY19 well ahead of board's previous expectations.
Mountfield Group (MOGP) orders of £2.4m, expected to be completed in this current financial year. Expect more orders from the same client this FY.
Epwin Group (EPWN) AGM stmt. Expects to meet market expectations for 2018, despite adverse weather and some continuing materials cost inflation. H2 weighting.
Joules Group (JOUL) Chmn to leave end July. Appoints CEO of DFS. "Joules is a premium lifestyle brand with an authentic heritage." A collector of zeitgeist cliches too.
Mountfield (LON:MOGP) - a tiddler but seems to be on a roll with new contract wins so must be doing something right. Needs to turn these wins into decent Net Profit to re-rate the share price imho.
Edit - I believe results are out soon so will keep an eye on its progress!
Entertainment One (ETO) full year results to 31st March 2018..
Here, CEO Darren Throop talks through highlights:
http://www.piworld.co.uk/2018/05/22/entertainment-one-eto-results-interview-may-2018/
Worth a watch