Small Cap Value Report (Tue 22 Oct 2024) - HFD, HTG, EMR

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
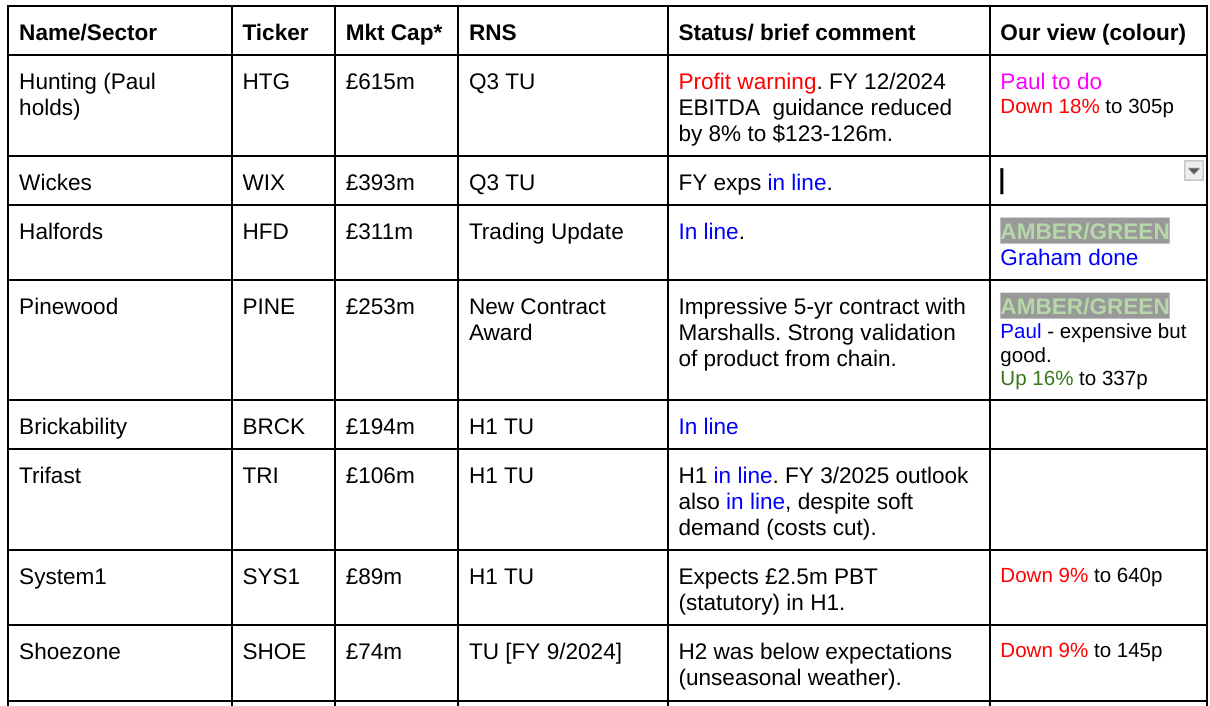
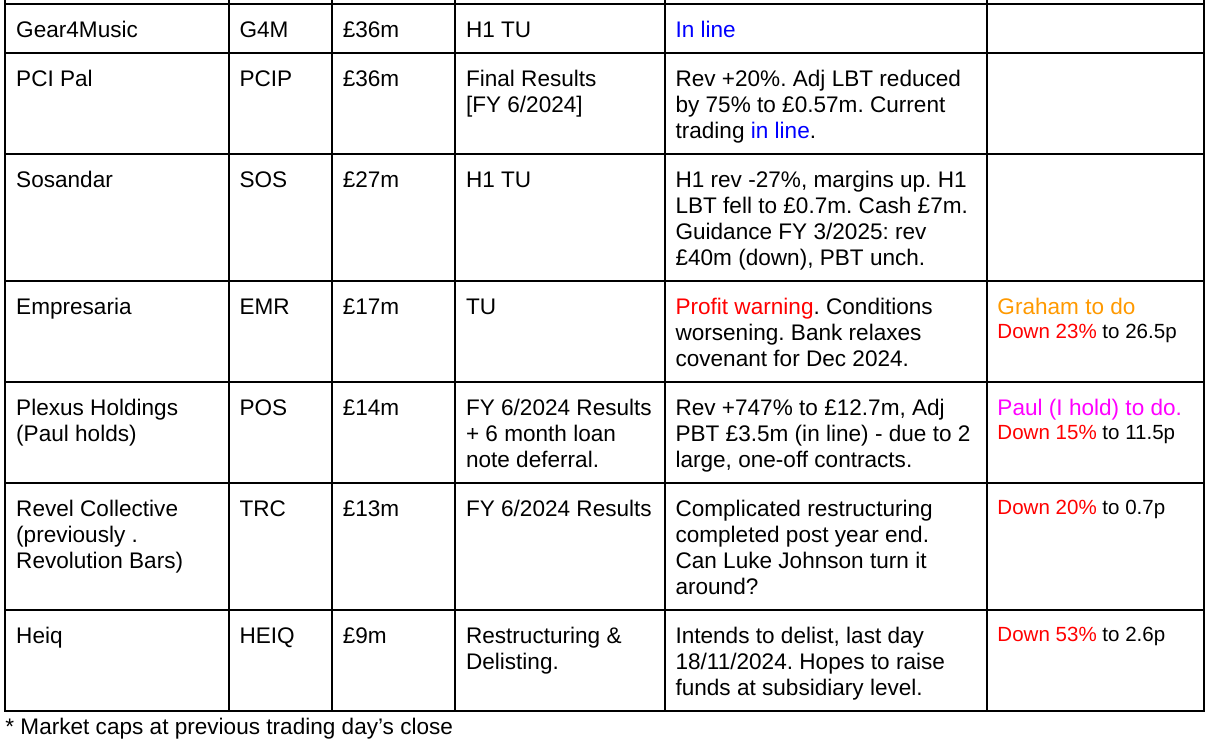
Summaries
Halfords (LON:HFD) - up 2% to 145p (£317m) - Trading Update - Graham - AMBER/GREEN
It’s an in-line update from the UK’s leading provider of motoring and cycling services and products. LfL sales are approximately flat which is reasonable considering the strong growth seen in H1 last year. At a modest earnings multiple and with the potential for margins to expand, this could be interesting.
Hunting (LON:HTG) (Paul holds) - down 18% to 305p (£504m) - Trading Update [profit warning] & Bank Facilities - Paul (I hold) - BLACK / GREEN
Slower demand in Q4 means this oil/gas engineering group lops -12% off EPS for 2024, and -15% from 2025. The earnings trend is still strongly upwards though, so it's a pity they over-egged the previously raised forecasts. Balance sheet is particularly good, with net cash now forecast for end 2024. A large new bank facility seems earmarked for acquisitions. For me, the improved value outweighs the disappointment on earnings forecasts.
Paul's Section:
Hunting (LON:HTG) (Paul holds)
Down 18% to 305p (£504m) - Trading Update [profit warning] & Bank Facilities - Paul (I hold) - BLACK / GREEN
Oh dear, this one isn’t panning out as hoped. Hunting is a specialist engineering group, mainly focused on the oil & gas industry.
Checking my previous notes, I was GREEN on 29/8/2024 on publication of in line H1 results, and re-confirmed guidance for FY 12/2024 which had been slightly raised in July. Prior to that, all seemed to be going so well at HTG with a series of large orders, record order books, strong balance sheet, negligible net debt. Management seemed ebullient in a recent webinar.
The tone has changed today, with an 8% drop in EBITDA guidance for FY 12/2024.
What’s gone wrong? The Q3 performance bullet points look OK apart from the last one -
“Ongoing subdued US onshore market and low natural gas pricing have led to trading within the Hunting Titan operating segment (Perforating Systems product group) being at break-even during the quarter. Cost cutting initiatives are being planned to further right-size the Titan business to prevailing market conditions.”...
“With the recent decline in the oil price and renewed falls in US natural gas pricing, sentiment has reduced in recent weeks in areas of the sector, which will likely lead to lower client activity within certain product groups throughout the remainder of the year, most notably within the short-cycle Perforating Systems product group, as highlighted above.”
Everything else seems to be going OK, and we’re given very precise guidance for the financial damage -
“While Hunting's other product groups continue to perform well, based on this short-term market outlook, 2024 full-year Group-level EBITDA guidance is being prudently reduced to between c.$123-$126 million, a reduction of c.8% on previous guidance issued in July 2024.”
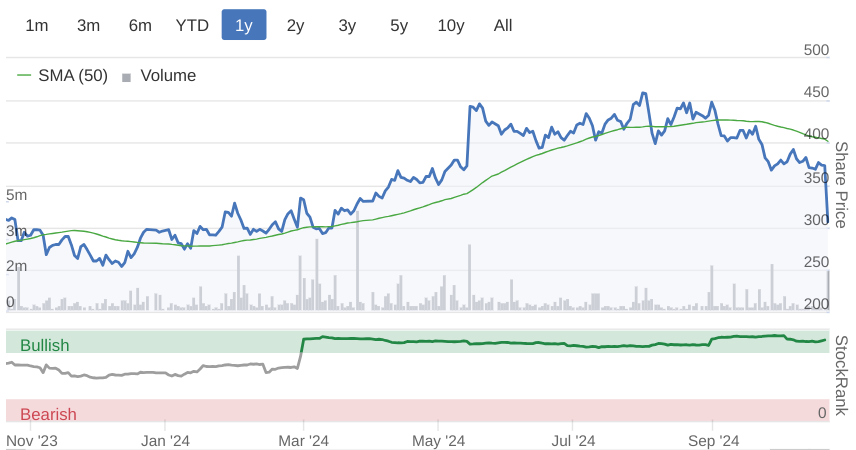
That’s hardly a disaster, yet the share price has cumulatively lost about a third from its highs earlier this year. This seems a rather excessive reaction to me.
Broker updates - 3 brokers provide updates today, many thanks. ED doesn’t provide the customary New vs Old table, unless I missed it. We need this information to assess the scale of the downgrades. Zeus does provide this table, and for FY 12/2024 it lowers adj EPS from 39.6 US cents, to 35.0 cents, a 12% drop. That’s a fair bit, considering the shortfall is all from just Q4.
Zeus also lowers FY 12/2025 forecast EPS by 15% to 46.9 cents.
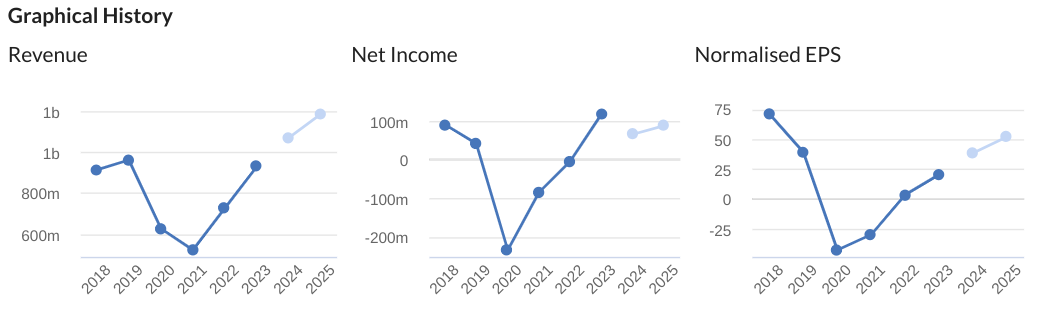
The context of these forecast drops is that HTG will still be showing a very impressive growth trend in both revenues and profit over the five calendar years from 2021 to 2025. What a pity they overcooked the previous forecasts, it’s a pity management didn’t under-promise and over-deliver, so the way I see this situation, HTG is performing very well, but there’s been a failure of its forecasting, with over-optimism. I can forgive that, assuming nothing else is likely to go wrong. The downside risk is that its large contract wins are one-offs, and we’re seeing an unsustainable burst of higher profits now. I don’t know the sector at all well, so can’t give a view on that.
Valuation - today’s hefty 18% share price fall to 305p, coming on top of a previous drift down from the 450p peak in Aug 2024, means this share could be a bargain providing nothing else goes wrong, perhaps?
FY 12/2024, 35 cents new forecast converts into sterling of 27.0 pence = PER 11.3x
FY 12/2025, 46.9 cents new forecast converts into sterling of 36.1 pence = PER 8.4x
Clearly then, if it avoids another profit warning, we might have a bargain on our hands. Especially considering HTG is also so well financed, with a remarkably strong balance sheet. After today’s fall, Price to Tangible Book Value is now under 1x.
Paul’s opinion - we all hate profit warnings, but they’re unavoidable sometimes.
In this case I find a very well-financed business, that’s in an excellent up-trend for growth in both revenues and profits, backed by a large order book.
What a pity then that a slowdown in one division has pulled the group forecasts down below guidance. That strikes me as a failure to budget prudently.
Even though the forecast blobs below will come down a bit, there’s still a lovely positive trend -
Valuation seems reasonable.
Year end net cash is now forecast to be $63m (previous forecast $32m) due to receivables being collected.
I have to flag it as BLACK due to this being a profit warning. However, that’s just a flag, it’s not an opinion.
As regards my opinion on fundamentals, I see this as a relatively minor disappointment, which has more than overshot on the downside in coming from 450p in August, to 305p now. That strikes me as an overreaction, hence why I’m sticking with GREEN. The profit warning isn’t due to performance collapsing, it’s just due to aggressive forecasting. The profit trend is still strongly upwards, but the PER is now into single digits for 2025, with complete NTAV backing too.
A more cautious view would be that the concerns noted about demand from the oil & gas sector could be a warning that further demand reductions may be in the pipeline. You can make your own mind up about that, I don’t know what the future holds.
Given the fundamentals looking attractive, I’m more inclined to add to my position by averaging down, than selling it despondently. Obviously at this stage nobody knows what the right decision is, it’s nothing more than educated guesswork - unless you’re a time traveller from the future.
Graham’s Section:
Halfords (LON:HFD)
Up 2% to 145p (£317m) - Trading Update - Graham - AMBER/GREEN
Let’s cover the key points in today’s H1 trading update:
Like-for-like sales "broadly flat” (-0.1%).
£30m of savings to mitigate £35m of inflation.
Expansion in gross margin.
Autocentres - LfL sales +0.8% vs. exceptionally strong period last year. Price-conscious customers trading down into budget tyres. Technician wage inflation.
Retail - wettest spring since 1986. LfL sales down 0.7%. Motoring products more resilient than expected, but Leisure cycling was challenging.
Outlook - unchanged.
Despite pockets of improving consumer sentiment, the short-term outlook remains uncertain, particularly for big ticket, discretionary purchases
CEO comment excerpt:
“While consumers remain cautious in their discretionary spending compounded by uncertainty around the contents of the upcoming Autumn Budget, we have continued to focus on controlling the controllables and I am pleased with our performance in the first half of FY25. Our services and B2B-led strategy has supported Halfords’ growth despite two of our core markets remaining significantly below pre-Covid levels, enabling us to absorb more than £130m of inflation since FY20 while maintaining a strong balance sheet…
Graham’s view
Paul and I had a funny interaction recently where we noticed that most, but not all, companies seemed unhappy with the weather in 2024. The weather often seems to be the scapegoat when companies do poorly.
As we are now in October, we have objective facts for Spring and Summer 2024.
Summer 2024: there was average rainfall in the UK. Scotland was particularly wet (18% more than average) but England was particularly dry (23% less than average). Temperatures were cooler than average, but in England they were very close to average.
(Recently Rank (LON:RNK) said that fewer visits to its bingo halls was in part caused by “sunny weather” - the weather was dry perhaps, but not particularly sunny!).
Spring 2024: was exceptionally hot and wet, especially in the south.
Overall, I think it’s reasonable to accept that the rain could have kept customers away from HFD’s retail stores in H1 (April - September), but that momentum should have improved as the period progressed and as we move into H2 (October - March).
I’m inclined to leave Paul’s AMBER/GREEN stance (as of June) unchanged. The balance sheet is probably fine - there isn’t any net debt worth talking about. The valuation multiple is modest, and the company remains profitable and dividend-paying:
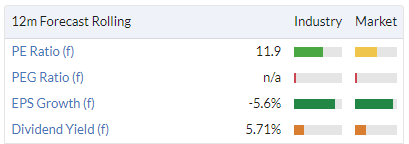
It operates on razor-thin net profit margins, which is both a risk and an opportunity.
Anecdotally, I have started using Halford’s local car bulb fitting service and I regret that I wasn’t using it years ago. So they can count on me as a happy customer!
Empresaria (LON:EMR)
Down 22% to 27p (£13m) - Trading Update - Graham - AMBER/RED
We haven’t been following this one in 2024 as the market cap has been rather small. But it pops up on the radar this morning with a profit warning.
We last looked at it in November 2023, with Paul taking a neutral position.
Share price momentum hasn’t turned around since then:
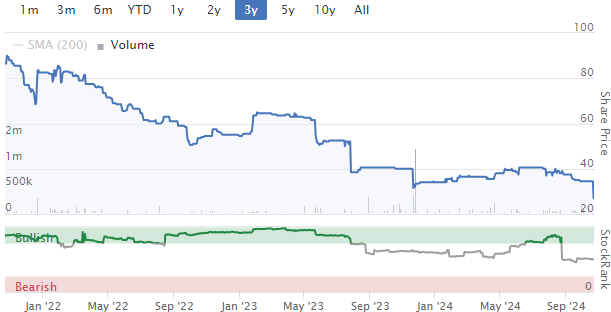
Today’s news: the challenges in recruitment/staffing persist, as we have seen with other recruiters such as SThree (LON:STEM) . Empresaria’s sectors are defined as Professional, IT, Healthcare, "Property, Construction & Engineering” and Commercial, and it operates in 16 countries.
Empresaria has seen “conditions worsening in a number of markets and permanent recruitment demand generally remaining extremely subdued”.
Q3 net fee income is down 4% year-on-year (it was down 9% in H1).
Q4 is now expected to be “worse than previously forecast with market conditions in Germany particularly challenging”, and the adverse conditions are expected to continue into H1 2025.
Full-year adj. PBT is now expected to be “no less than £2.0m”.
At the interim results this year, the company said it was “broadly in line” with the consensus forecast at the time, which was for £4.3m of full-year adj. PBT.
Bank loans have run into covenant issues, which is always something I take very seriously as it is the first sign of financial distress developing. The interest cover covenant is being relaxed to 4x (from 3x) for the December 2024 test.
As of 30th September, net debt is £13.6m with available headroom of £6.5m (excludes invoice financing).
Graham’s view
The September level of net debt is the same as the interims (June 2024). Checking the interims for more detail, I find the following breakdown of gross borrowings:
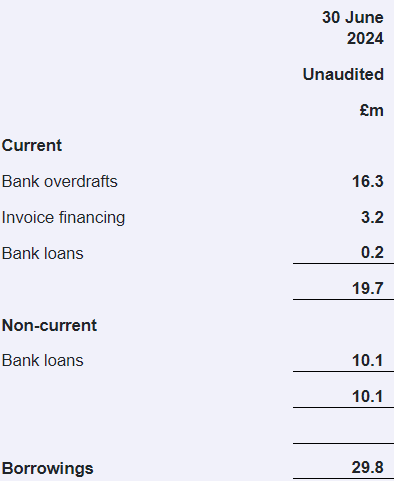
I was hoping to find a greater emphasis on invoice financing, as that has a clear and specific purpose, but the borrowings are mostly in the form of overdrafts and a revolving credit facility.
The interims did show a surplus of current assets over current liabilities (£58m vs £53m), with over £40m of current assets sitting in receivables (amounts owed by customers). So Paul’s interpretation last year that the bank loans were funding receivables might still apply.
That said, it is possible for recruiters to fund their receivables without relying so heavily on external funds and it might be overly cautious but I do appreciate that when I see it.
For context, EMR’s net fee income was £25m in H1, so their gross borrowings (nearly £30m) exceeded what they earned from customers over six months.
The risk that interest cover is at risk of falling below 4x is a point of concern not just for the bank but also for shareholders.
Perhaps this is the low, and trading is about to turn around next year, but I am inclined to give this an AMBER/RED today on the basis that the company is struggling to make real profits (it made an operating loss in H1 2024 and made a loss in 2023) and now has a covenant issue. There is every chance that conditions could improve in 2025 and that these shares could take off once again, but the facts as they stand suggest to me that EMR should be treated with considerable caution.
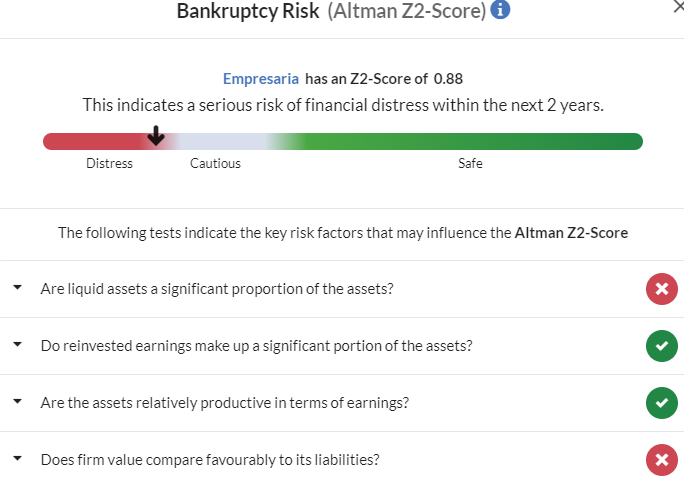
The Altman Z-Score for bankruptcy risk has also noticed something:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

96 comments
Inheritance tax rise in budget? New Treasury figures illustrate it's already rising by stealth
Inheritance tax receipts shot up by £400m between April and September compared with the same period last year, new government figures show.
This meant a record haul for the Treasury of £4.3bn. Sky Money.
Other tax receipts in link above as well.
Can't see the "stealth" in there!
Paul, any thoughts on TRC Revel Collective / Revolution Bars?
Paul
I cannot find your comments on the trading update from Alphawave (LON:AWE).
superficually, the update looks positive. But it is all about bookings.
you have written extensively about AWE in the past. Always very negative
I think you should comment
Steve (from the Edinburgh mafia)
The International Monetary Fund (IMF) has upgraded its projection for UK growth this year by 0.4% to 1.1% - the largest upward revision for any advanced economy.
https://news.sky.com/story/imf...
I am struggling to see where that comes from. In my industry (automotive/Motorsports), the bottom has fallen out since the budget was announced. Everywhere on my industrial estate, companies in different industries are on short time or reduced hours due to a lack of work. I cannot see how we going to see such growth unless they assume it is coming from a bounce once the budget has been announced?
You can add discretionary/luxury retail to that list too - worst I've known in over 30 years, excluding COVID lockdowns
I read today that these upgrades were based on data from pre-july, and a continuation of the fiscal policies of that govt
Sosandar (LON:SOS) hosted a webinar for their trading update today. Revenue down but margins up, as strategy, so profit in line. The store rollout is going to plan. Lots of questions video & podcast.
Is Craneware (LON:CRW) back at entry level, or is it time to walk away?
This stock has round tripped up to £24 only to return to the start of year price of around £18.
It seems to be still struggling to show much progress from the 2021 purchase of Sentry, although revenues have grown, profits are still below where they were, and only forecast to make significant progress this year.
Margins of 10% are well below previous levels of over 25% and NTAV is negative.
Any thoughts appreciated.
Craneware (LON:CRW) is a large holding in AIM IHT portfolios so pre-Budget selling may be a factor.
Craneware (LON:CRW) is a large holding in AIM IHT portfolios so pre-Budget selling may be a factor
Yep, either CGT or IHT selling, for sure. Chart looks like all the others I listed here, with a good earnings report only briefly interrupting the fall. Indeed, perhaps encouraging it!
Operating numbers are only so-so for software. Very much not best of breed. But deeply entrenched in a very conservative ecosystem with strong secular drivers. Would be an excellent tuck-in acquisition for Cerner/Oracle. Looks like a buying opportunity to me.
Thanks BnB
Really useful walkthrough of your portfolio last week.
Anyone applying for the Applied Nutrition IPO?
Offer of up to 137,408,477 Shares at an Offer Price expected to be between 136 and 160
pence per Share. So MKt Cap at the top end of £219.8m
Revenue growth of 42% from 2023 to 2024, GP £41m (2024). PAT has grown from £8.2m(2022) to £18.6m(2024)
You've mis calculated the market cap there, that's the number of shares they are offering, not the total share capital. The total share capital is 250m, so the market cap will be between £340-400m depending on the offer price.
The £18.6m figure for last year would have resulted in EPS of 7.5p, so at 136p it would trade on a LTM multiple of 18x and top of the range 160p would be just over 21x
When you factor in listing costs vs 15% growth forecast for 2024, I'm not convinced EPS will grow much beyond 8.5p (£21m), so I don't think it looks great value.
Interesting to see how much liquidity there is post IPO and how it trades, Anything below the 136p price would be more interesting, but I don't think it's worth applying for shares before it lists.
Thanks for the clarification re. share count. Rating looks racy based on that. #Applied Nutrition
Plexus Holdings (LON:POS) - results were below consensus on revenue and more so on profit. Was this due to the fact that the retiring exceutives took £693k compensation for loss of office? Odd that they received compensation for retiring, but nice gig for them!
Plexus has always been a capital intensive business and will always be reliant on lumpy contracts or selling businesses/technology to survive in my view. The continued material uncertainty audit opinion implied by the warning in the preliminary announcement is surely a red flag, as is the rolling over the loan. It should have been paid with the compensation for loss of office monies in my view. The fact that this happened possibly suggests that the ex-CEO might not be totally aligned with the success of the business.
Anyway, the pressure is on. They either announce some contract wins within 6 months otherwise funding will be an issue and no positive news will mean dilution. Quite speculative I would say. Not for me, as I think there is now slightly more downside risk than upside risk in 2025. Good luck to holders. Still could come good.
Hi topvest,
The adj PBT figure for Plexus Holdings (LON:POS) [I hold] was exactly in line with the last broker forecast from Mar 2024. However, as you point out, the main adjustment between £3.5m adj PBT and £2.8m statutory PBT was £0.7m for Directors compensation for loss of office.
It refers to the Remuneration Committee Report, but that is not included in today's RNS, but will presumably be within the Annual Report when that is subsequently published (it's not yet on Plexus's website).
I probably shouldn't comment without knowing the details, but given the old Directors (who controlled c.60% of the equity) chose to retire, I find it perplexing that they get paid for loss of office. Did they sack themselves?!
The Founder/CEO Ben van Bilderbeek stepped down from CEO to Non-Exec Chairman.
The old Chairman Jeff Thrall stepped down from Chairman to a Non-Exec.
The old CFO retired from the Board.
So the question needs to be asked, why did two Directors accrue compensation for loss of office? Looks like it's been booked as a cost, but not actually paid - with payment presumably coming out of what seems to be an imminent fundraise.
When I speak to new management I'll ask about this, as it seems inappropriate for the controlling shareholders and long-standing Directors to retire (well past normal retirement age too) and be given a walloping lump of (deferred) cash.
That said, BvB did save the company using his own money in 2023, with loans & asset purchases, which prevented what could have been at the time ruinous dilution, when the share price was in low single digits. But even so...
Regards, Paul.
Just taking a look at Manolete Partners (LON:MANO) as the numbers looked interesting on the stock report page, especially with nett cash at £16.6m wow, ah but then I look at the results rns Sep 24 for the y/e Mar 24 and it clearly says "As at 31 March 2024, the Company had cash balances of £1.4m and borrowings of £13.7m resulting in a net debt of £12.3m"
So why the discrepancy Stocko ? I was hoping we could trust these numbers, or am I missing something ?
Threeputt you have read it right Manolete Partners have invested heavily in new cases, with most of their cases taking about a year, the expectation is their next results should start to show payback. They account for a set of cartel cases going back to 2011 against price fixing, 15.1m is the accounted for value. The problem is their margins have been lower than historic and Covid is still being blamed for delays. If the Cartel win comes to a conclusion and they start to clear the cases then cash should start to flow back in. Many have lost faith that they will do this hence the SP action.
Manolete Partners (LON:MANO) . Wins average a year after the case starts. Cash takes another year to come in.
This is because the stock report shows "Cash etc", which is not the same as "Cash & Equivalents".
If you look at the definition, or indeed at the b/s in Stocko, you will observe Stocko aggregates "Cash & Equivalents" with "Short Term Investments" to come up with the "Cash etc" number.
So it very much depends on what a company can get past its auditor within "Short term investments".
Look at Note 13 of the Manolete accounts for the detail - in effect they divide the legal costs of getting cases to their current stage between current and non-current investments, with the current proportion making it through to short term investments and therefore Stocko's "Cash etc" category.
It is not possible to represent everything accurately in the Stocko report page - they don't have space and have to aggregate (although the Stocko b/s did provide a big clue as to what was happening).
With industrial companies it generally gives the right impression, but Stocko isn't really configured to get under the hood of some financials.
Halfords (LON:HFD) Anecdotally, I have been getting the impression that the in-store product range has been thinned out considerably over the past two years or so which will account for some of the considerable cost savings, with a pivot to streamlining service offerings, eg online booking of bicycle servicing slots. Not sure this bodes well for how the shopfloor-extensive bricks and mortar business will develop.
Halfords (LON:HFD) Anecdotally, I have been getting the impression that the in-store product range has been thinned out considerably over the past two years or so which will account for some of the considerable cost savings, with a pivot to streamlining service offerings, eg online booking of bicycle servicing slots. Not sure this bodes well for how the shopfloor-extensive bricks and mortar business will develop.
If the whole company is run like the Cambridge store I visited last Friday, then god help anyone investing in the shares. What a miserable retail experience it is. Simply dreadful. Massive cold barn of a shop, with half empty shelves and no staff anywhere to be found. Click and collect is meant to be a quick process but I could have spent the whole afternoon stood at the collection point had I not kicked off. It would be quicker to just pick your chosen items off the shelves yourself and going to the lone checkout operator.
Sadly I have to agree regarding the stores and availability of staff.
Chippenham' store is better than this with 2 staff on tills and often queuing. It uses my email to deliver my receipt.
Just cant get that excited about UK retail. I feel the so called upitty-up of the UKs prospects is a red herring and things are going to get worse before they get better.
Yesterday there was some debate on the merits of investing in the mining sector with one view being that because of the potential of foreign governments moving the goalposts it was akin to a spin of the roulette wheel. I would argue that the retail sector has far more headwinds from UK government intervention and ever changing costs whether that be minimum wage, NIC, business rates, corporation tax, health & safety requirements etc etc. The list seems to get longer and the margins slimmer. IMO investing in retail is the real gamble.
I had a similar experience at a London branch of Halfords. Miserable staff unfortunately seem to be becoming the norm in retail but what really struck me was the empty shelves resulting in a lack of product choice.
MGNS is one I bought in July 2017. I think I bought it because it had a high stock-rank, and one that I thought I'd only hold for a year. Boy am I glad I held on though. (Up 17.5% today. Crikey)
It has a high Quality score (99), a ROE of around 17%. It has net cash. Nice! One thing I look for is revenues per share growing by at least 5% pa over a decade (you can work this out from Stocko's Accounts dropdown). MGNS has managed about 6%. It trades on a PE of 13 with a P/FCF of 9.3.
Find a few of those types of companies and the odds are heavily stacked in your favour that you will beat the market over time.
Agreed. Have held for several years but couldn’t resist taking the profit today on the massive uplift.
Guess I should count myself lucky - big shot in the arm with MGNS more than makes up for crazy drops on Vistry last week and Hunting today. The Market is just so unforgiving - I won't be averaging down as Paul suggests - which most likely means I'll be missing out, but relieved when HTG is back on track
There are just four WEEKS until Mello's 10 Year Anniversary Show on Tuesday 19th & Wednesday 20th November 2024! Come and join us at The Derby Conference Centre, 9am-7pm.
This unique venue, with it’s unique sunken exhibition space, has been voted the investor favourite venue so we listened and here it is..
.
We have created a two day investor conference that will include 12 top quality keynote speakers, 8 educational workshops and panel sessions, 40 exhibiting companies plus over 60 company presentations for investors to evaluate and understand their current or potential investments. Paul, Ed and the Stockopedia team should be there to meet and chat in a wonderful, friendly networking environment
A selection of attending companies includes Warpaint, Time Finance, The Property Franchise Group, Polar capital, Smiths News, Rockwood Strategic, Transense Technology, Filtronic, Manx Financial, Lightscience Technology, Image Scan, RTC Group and many more!
The featured keynote speakers include leading Technology fund manager Ben Rogoff and Peter Pereira Gray the ex head of Investments at the £30billion Wellcome Trust, and many more.
For more information, click here: https://melloevents.com/mello10tickets/
For HALF PRICE tickets use code 50OFFSTOCKO https://www.tickettailor.com/events/melloeventslimited/1376680
Weird things happening with the Momentum scores this morning, I have reported via the green button. This is System1 (LON:SYS1) for example - it looks as though red and green may have reversed?
It turns out some changes were made to the software - they have been rolled back so it's working as intended again... impressively speedy response!
The AI summary of Plexus results is deeply impressive in the speed and detail of its production. The conversational style is still a little contrived. But it’s certainly more convincing that Bullhead and Alphaflight’s pretend conversations.
Hi BnB, where can I find it the AI summary ?
Hi BnB, where can I find it the AI summary ?
See Paul Hill’s post early in the thread
Pinewood gets it first external contract and shares up 16%. There should be more to come
I think the AI bot would benefit from a training course.
Mr Contrarian on top form - Shoe Zone (LON:SHOE) "flip-flopping"!
His one-liners are inspired and hit their target every time
My favourite was about Nike's new range of brightly coloured premium running shoes retailing for nearly US$300 . . . . . . "they'll certainly see you coming"
What a market! Can I say its a croc?
Hi SontleyM - Just to be clear, do you mean a croc of gold ora croc of s**t?
Buy gold sell Crocs
Croc shoes?
My investment in Shoe Zone (LON:SHOE) is now well below the plimsoll line.
Brilliant Roger :-)
I used to be well heeled after investing in this; now I am down on my uppers
I hope they kick on from here, but you might need to tread carefully
Meaning it is eating your money? Alternatively is it a crock, like an old banger?
The FD is appropriately named Terry Boot
Morgan Sindall (LON:MGNS)
Share price up today from this quality business. I hold.
Wrt Plexus Holdings (LON:POS) , it appears house broker Cavendish "have taken a very prudent view with their forecasts".
Cutting FY25 and FY26 sales estimates to £4.7m (Adj PBT -£3.3m vs +£3.4m LY ) and £7.6m respectively vs £12.7m LY. Albeit equally retaining their 40p/share target price
RE Plexus Holdings (LON:POS) - Cavendish actually hasn't cut its FY6/25 or FY 6/26 estimates, since they are freshly introduced today - there weren't any forecasts previously for these years.
But I take your point that, as expected, revs & profit will go backwards from the exceptionally good FY 6/24 numbers, which as we knew all along would be majorly boosted by the company's largest ever rental contract (now largely completed, and has risen again from £8m to £9m as disclosed today). I'm not seeing this £9m contract as a one-off any more, because the commentary today makes it clear that more similar work could follow on, and the equipment will be released for redeployment quite soon. They intend publicising this deal in the industry. There's also news that 4 new sets of equipment are being deployed to meet strong demand.
Lots of two-way business in the shares today, with high volume of buys and sells, much higher than usual.
It's a classic case of glass half full or half empty. I like the figures, and the commentary very much. However, I dislike the cash running low again, and the reiteration that another fundraise of some kind will be necessary. That's obviously going to put off risk averse investors, I'm personally more relaxed because mgt own 60%, and have been highly effective in avoiding dilution before, despite a multi-year fallow patch.
Definitely not for widows & orphans! Given the material uncertainty going concern statement, I'm afraid it has to be an automatic AMBER/RED for our colour-coding system here. Although personally I'm relaxed about the dilution risk, as it talks about pre-emption rights in the commentary.
More later, but I didn't want today's SCVR to be dominated by an obscure micro cap, just because I happen to hold some personally.
Regards, Paul.
Re O&G sector in general and Plexus Holdings (LON:POS) - I am mindful that many avoid natural resources, but a useful read for anyone heavily invested https://www2.deloitte.com/us/e...
It is certainly a competitive market where all work is subject to a tender process, however successful deployment is key and by all accounts they are having repeat business and in niche areas, drillers are very conservative and performance driven people ,this bodes well for the future. We need to hear more about their Methane well capabilities and deployment. I am a holder and optimistic about the future.
As we have Hunting (LON:HTG) and Plexus Holdings (LON:POS) I thought I would post the above which shows the price of Oil convertible into Gold. It's an old fashioned way to think about things dating back to the Gold Standard. Some macro gurus still talk about this... and it's at an interesting level.... since everyone is a gold bull.... Oil should be on the radar. The reasons why it is not are rather obvious. Holders of the above stocks may find it reassuring that Oil could regain strength soon.
Shoe Zone (LON:SHOE) the last bits have gone this morning. What a turn of fortunes and so quickly. There's an opportunity here for sure, but not until I hear the finals in January. Held in my lads ISA, he's keen on Amazon.com (NSQ:AMZN) now so no worries as to where to redeploy the cash.
Hunting PLC (LON:HTG) Today's Q3 update has many positives but trading at Titan has not yet improved in H2. ED lowers EBITDA estimates by 7% for FY24, but raise y/e net cash outcome. OurFair Value now seen at 397p/share, as per new research note available here:
https://www.equitydevelopment....
Oct 22 (Reuters) - British energy services firm Hunting (LON:HTG) lowered its annual profit outlook on Tuesday, partly hurt by prospective lower client activity for the rest of the year due to a decline in oil prices and renewed falls in U.S. natural gas pricing.
The company now expects its 2024 group core profit between $123 million and $126 million, compared with its previous forecast range of $134 million to $138 million.
Plexus Holdings (LON:POS) I wonder about the risk of delisting given this:
“Plexus' smaller market cap can be a negative factor if consideration is given to raising additional funds in the public markets….. the Group is reliant on raising additional funding, ….. there can be no certainty regarding the timing and quantum of future funding and therefore this indicates a material uncertainty which may cast significant doubt regarding the Group's ability to continue as a going concern.”
Id say the risk is the other way round but what do I know. ie an equity raise at some point... hopefully with some new business in the book.
Re :Plexus
One line in the statement caught my eye
"The Group operates in highly competitive markets and often competes directly with large multi-national corporations who have greater resources and are more established."
Plexus then go on to say
"To mitigate this risk, Plexus has an active R&D programme"
Off course the large multi national competitors also have R&D programmes. Very difficult to see what Plexus can offer shareholders.
At a market cap of 14million, these larger companies could probably aquire Plexus if it has anything of interest. More likely in my view that shareholders will have to cough up.
I suspect there's almost zero chance of Plexus Holdings (LON:POS) delisting. I discussed this with management previously, and wouldn't have taken a big stake if I thought this was a risk. They told me the advantages of being UK listed are worth every penny - that they're seen as a serious, significant player in the industry, and it opens doors wide open at the oil majors. Whereas private companies struggle to be heard, and are often asked for personal guarantees from Directors, which doesn't happen at Plexus since they listed. So the listing is seen as a major asset by the company.
Clearly it needs a top-up fundraise, but my view is that this should be doable at a sensible price, since they've just published superb results. That's a totally different ballgame from the usual AIM situation of negligible progress, zero revenues, and continuing cash burn. Also a new (experienced) management team to present the investment case freshly could be a good thing.
I'd like to see the uncertainty over cash resolved asap, so that attention turns to all the positive points. Old management has a track record of jealously guarding against dilution, since they own c.60% of the company. Look at all the hoops it jumped through in the last 2 years. With any luck they can find an industry strategic investor (Schlumberger again?) to fund a small placing, rather than going cap in hand to a depressed AIM market.
It is a risk factor for sure though.
Regards, Paul.
Spoilt for choice today with Brickability (LON:BRCK) inline , Morgan Sindall (LON:MGNS) significantly ahead, and Plexus Holdings (LON:POS) all reporting.
If I read the second Plexus Holdings (LON:POS) rns correctly are they really paying 20% on the loan, seems a tad expensive.
My morning smallcap tweet: A second lease of death
Heiq (LON:HEIQ) Shoe Zone (LON:SHOE) Sosandar (LON:SOS) Mulberry (LON:MUL) Colefax (LON:CFX) Halfords (LON:HFD) System1 (LON:SYS1) Empresaria (LON:EMR) Pinewood Technologies (LON:PINE) Sabre Insurance (LON:SBRE), Wickes (LON:WIX), Mind Gym (LON:MIND), Trifast (LON:TRI), Newmark Security (LON:NWT), Gear4music (HOLDINGS) (LON:G4M), Brickability (LON:BRCK), PCI- PAL (LON:PCIP)
◄HeiQ (HEIQ)► this spinner of yarns has initiated a second restructuring plan aimed at reducing costs by up to an additional 20%. Considering disposals. Announces delisting on 19 Nov. No vote needed since it's on the equity shares (transition) category of the LSE. [SP=5.5 Cap=9m]
◄Shoe Zone (SHOE)► a real flip-flop outfit this one. Warns FY-Sep rev down 2.7% ansd adj pretax £9.5m+ (£16.5m). Blames weather in H2. [SP=160 Cap=74m]
◄Sosandar (SOS)► cuts FY-Mar rev guidance to £40m from £45.6m but pretax in line with f/c of £1m.. H1-Sept rev £16.2m down 27% "reflecting margin enhancement prioritisation". [SP=10.5 Cap=26m]
◄Mulberry (MUL)► rejects hiked 150p offer from Frasers, [SP=129.6 Cap=91m]
◄Colefax (CFX)► £4.8m max buyback at 780 via reverse bookbuild. [SP=763.6 Cap=49m]
◄Halfords (HFD)► guides H1-Sep rev flat and increase in gross margin - no fig given. Outlook unchanged. [SP=142 Cap=311m]
◄System1 (SYS1)► guides H1-Sept platform rev up 53%. Q2 was actually down on the exceptionally strong Q1. No new FY guidance. [SP=692 Cap=88m]
◄Empresaria (EMR)► warns FY24 £2m+ as it expects Q4 worse than forecast with Germany particularly challenging. Bank relaxes interest cover covenant to 3x (from 4x) for December testing, "ensuring that we expect to remain compliant". [SP=33.27 Cap=17m]
◄Pinewood Technologies (PINE)► wins 5 year contract from Marshall Motors to implement Pinewood systems into their stores. No £££. [SP=290 Cap=253m]
◄Sabre Insurance (SBRE)► guides FY-Dec profit in line despite premium growth moderated slightly. [SP=137.4 Cap=343m]
In line: WIX, MIND, TRI, NWT, G4M, BRCK, PCIP
Looks like things are still going well for System1 (LON:SYS1) . Revenue growing 50%+ each quarter (yoy). Have moved focus to the US and unlike lots of businesses it seems to be paying off. Sounds like they are going to ramp up to take advantage of the situation - which is probably the right thing to do. It would be interesting to get others opinion.
Revenue declined across all lines in Q2 vs Q1, given the share price move comparing to last year is fairly pointless...
The lack of growth between Q2 and Q1 is worrying - and management haven't given enough commentary to explain why Q1 was "exceptionally strong", and why growth will continue in Q3 onwards.
However, even if you take the worse case scenario of say no further growth at ALL....
PBT for H1 was £2.5m.
However, this is depressed, as they ramped up opex for growth/expansion. Opex went up +£2.6m in H1. Some of this extra is "capex-like" - headcount, event marketing, business dev - for the USA expansion. You have to spend now, and the benefits accrue later. However, unlike capex, it is expensed to the P&L immediately.
If you conservatively say £1m of the +£2.6m increase is this type of cost, then the "true" run-rate of PBT in H1 is £3.5m.
Annualised, and then converted it is about 40.7p EPS yearly run-rate.
I see the SP is now down this morning to c600p, which gives a 15x PE. Which is a bit of a bargain, for a company that almost likely will continue strong growth in the next few years, as well as huge operational gearing and super high margins (PBT margin of 28% in H1!).
I am mulling topping up, waiting to see more of the tree shake of "casual" investors who jumped in looking for a quick buck on TU day...
(I hold in the Boon Fund)
Hi Boon,
What are your thoughts re the CEO comment this morning;
"and will be accelerating and significantly increasing investment in the coming months to build our position in America and revitalise System1's Innovation proposition."
Sounds to me that Opex will go up even further in Q2
I think James (CEO) at System1 (LON:SYS1) will want to avoid the debacle of his predecessor, and only increase costs while still meeting the broker forecast. James was brought in because he is a good operator, not a visionary; so he's unlikely to be highly risk taking and doing a big gamble splurge on USA investment and draw heat from investors with poor short term financial results. (Disclosure - I worked with James in the past, but many years ago).
Maybe that's why the broker has still kept the profit forecast for the year, despite already achieving 54% of it in H1.
IMO I am fully supportive of investment for the USA region. The market is huge. The platform is proven.
Profits will be depressed in this ramp-up phase because all the costs (sales people, business dev, sales commissions on new clients, event marketing, etc) are all opex in nature, cannot be capitalised. When they logically should be treated as such.
The compelling story here is the super high gross margin, and even with the depressed PBT in H1 the PBT margin is still nearly 30%. Nuts.
The key risk here is whether there is a big market in the USA for them, and whether competitors can catch up. The AGM presentation has a good Q&A at the end where management address questions on this; its still a leap of faith. But for me, working in the marketing industry, I haven't seen any competitive platform in the USA that is as good as System1.
The other big risk is of course an economic downturn and therefore marketers scaling back budgets.
(I hold in the Boon Fund)
I must admit, the update wasn't what I had been hoping for. I didn't like the Q on Q drop in revenue, nor the failure to be concrete on profit expectations (v the very confident Q1 update). I am thinking there may well be opportunities to buy in cheaper at a later date. (I no longer hold)
LONDON, Oct 22 (Reuters) - British luxury brand Mulberry MUL.L on Tuesday rejected a second takeover proposal from Mike Ashley's Frasers Group FRAS.L, saying the possible offer is "untenable".
Frasers had on Oct. 11 raised its proposal to 150 pence per Mulberry share, valuing the brand, best known for its handbags, at 111 million pounds ($144 million).
Plexus Holdings (LON:POS) we are very optimistic about the growth of the
business and the opportunities which are suited to our unique mix of
proprietary products and engineering capability.
Plexus Holdings (LON:POS)
Going Concern, liquidity, and finance requirements
As a relatively small business with adequate, but not excess cash resources, and following a number of loss-making years, Plexus has to closely monitor and manage cash flow. Additionally, Plexus' smaller market cap can be a negative factor if consideration is given to raising additional funds in the public markets.
The Group undertakes cashflow forecasting throughout the year to ensure the going-concern assumption is still appropriate. As disclosed, the Group is reliant on raising additional funding, an event that was indicated at the time the convertible loan arrangements were entered into in October 2022, and there can be no certainty regarding the timing and quantum of future funding and therefore this indicates a material uncertainty which may cast significant doubt regarding the Group's ability to continue as a going concern.
Plexus Holdings (LON:POS)
Quick take on Plexus' FY24 results and extended loan agreement from Google's NotebookLM podcast
https://drive.google.com/file/...
A great analysis of the current state affairs. Thanks for posting Paul.
Fascinating Paul, is this all AI generated? I take it it’s not you and your wife in the study channeling your best CNBC accents over the tea and toast??? But thanks very much!
Thanks Chumba & Ox2906.
Yes its all AI generated - simply from today's 2 announcements.
That's scary what AI can do now
!
Not over keen on today's announcement personally, the growing concern statement has put me right off Plexus Holdings (LON:POS) I just sold out anyway, just a small holding.. now what to buy before it burns a hole in my pocket
Thanks for sharing, Paul - how was this done?
NotebookLM. It's free. Use "Deep dive conversation Two hosts (English only)". Frankly I think you are better off using one of the AIs to summarise it and then you can specify what you are looking for. It's much quicker to read than it is to listen.
Impressive.I read that NVIDIA (NSQ:NVDA) are focussing on producing ai chips for physical robots too now... with the software/operating system on a recurring revenue model.Fits in with Musk's Tesla (NSQ:TSLA) and his robots idea, if he has any time when not giving away money to people to sign petitions lately, and lobbying for laxer regulation in his sectors.They haven't even got their self-driving robotaxis working well enough yet.
This is interesting Paul, who actually produced this? Is it Company sponsored?
Hi Paul,
thanks for the latest Vox interview which was an excellent listen.
By contrast this link seems to be an AI generated ‘discussion’. From the tone I think the prompt be along the lines of ‘write me a 20 minute interview that appears balanced but whose purpose is to generally extoll the virtues of Plexus’.
It’s an interesting use of the available AI tools (which I’m just starting to use regularly myself) but I must admit I have very mixed feelings about its use here where we have so much quality (real) analysis and actual opinions.
Cheers
Jonny
I think this is a very good point. Understanding the prompt / instruction for AI analysis is absolutely key. I imagine it's possible to exaggerate / emphasise positive points even in most updates (e.g. in Plexus Holdings (LON:POS) case you could ignore the going concern statement and/or have no awareness of broker forecasts, which are material to an an investment decision - FYI haven't listened to the podcast above so not sure if they do.) With human market commentators you can often judge reliability in a common sense way (do they hold a position in the company, are they being paid for their comments, do they have a strong track record etc.) - maybe not so easy for AI.
Hence my question, this would appear to be a piece of marketing masquerading as analysis...
It's just an AI. I'm assuming Paul did it himself. Unless he is using deliberately biased prompts eg give me the positives from these company statements etc then I doubt that very much. The obvious thing to do is copy and paste the same thing into another AI and see what answer you get. It takes less than 20 seconds.
For avoidance of doubt I wasn’t remotely meaning to suggest that Paul fed a biased prompt, I was simply raising the point, exactly as you say, that the results are aligned with the prompt and therefore need to be viewed together. Apologies if it came across otherwise. Personally I thought the commentary was mostly factual but the inanely chirpy tone, aside from being highly nauseating (‘won’t you bring that down for me’…), is likely to lead listeners to a more positive view of the business than a rational analyst (such as either of the Paul’s!) would convey.
I can see the value of generative AI like this in quickly getting unfamiliar listeners up to speed on key facts and themes, but these should be presented with a clear health warning and not as anything like a podcast, which it isn’t.
Don't worry I didn't read it that way. I think you made a good observation re: the potential issue(s) with generative AI creating convincing, conversational, human-like analysis. I listened to the first few minutes and it's astounding how it knows to play with the pitch/pace/intonation to convey a feeling/thought. Crazy times.
Plexus Holdings PLC Final Results Summary (Year Ending June 30, 2024):
Interested in Paul’s analysis of Plexus Holdings (LON:POS) results. But wondered should some of the news not have been RNSed such as this: “Signed a new Master Services Agreement with a well management company - anticipated to generate a variety of work in the P&A sector as well as in Jack-up exploration and appraisal drilling worldwide.”
Plexus Holdings (LON:POS) TU reads like a blue sky medical innovation that lurches from treating one condition to another with occasional revenues. No substantive progress since Feb of this year. I know I’m being a bit harsh with this comparison. The revenues are real. But they are non-recurring. If the best they can offer is a MSA giving them the right to tender for projects then this update is as convincing as the rise in bookings over at Alphawave IP (LON:AWE) that never turn into profits.
I hope I’m wrong on both. And to clarify, I like Plexus and its product. I just find it impossible to value on anything but the story. And I learned that approach doesn’t offer a sensible risk/reward years ago. Good luck to holders though, especially Paul. The product clearly meets an important climate goal.
Outlook statemnt not that comforting - Aiming to 'maintain profitability' and 'completion of the big 8m rental contract allows resources to pursue other similar work'. Sounds like they haven't got anything to replace it yet...
The higher the MOVE index, the bigger the magnitude of expected movements in Treasury yields, and therefore the greater the uncertainty among investors. The index was at 50 in June 2021 but sits at 130 today, indicating there’s much more uncertainty about the extent of movements in bond yields.
The MOVE index can be used to infer investors’ expectations about how much bond yields will fluctuate. An index value of 130 corresponds to daily fluctuations of +/–8 bp, barring extreme events. But over the past 20 years, the daily fluctuation has been an average of +/–3 bp. A good illustration of just how much uncertainty there is in today’s fixed income markets!
taken from Camignac after a simple google search on MOVE.
Conclusion : the adverse "surprise" increase in bond yields yesterday should not be much of a surprise. The difference between Tips and Treas remain anchored at 2.33% ... expected inflation. Which is around the magic 0.2% MoM CPI. MOVE rose slightly. No need for alarm.