Small Cap Value Report (Tue 22 Sept 2020) - SDRY, AUG, JDG, TRI, PRV, IDEA

Good morning, it's Paul here with the SCVR for Tuesday. I'm up early today, to catch up with a couple of stragglers from yesterday.
Timings - looking to finish about 4pm today, but there's plenty up already.
Agenda - as usual, I've selected the results/trading updates which fit my criteria for small caps, and where I know something about the companies. Plus I've included a couple of reader requests. But please bear in mind that I can't cover everything, and getting a deluge of requests every day tends to overwhelm me.
Judges Scientific (LON:JDG) - interim results
Trifast (LON:TRI) - AGM statement (trading update)
Porvair (LON:PRV) - trading update (9 months)
Ideagen (LON:IDEA) - final results
Ergomed (LON:ERGO) - interim results
Tandem (LON:TND) - half year report
If there's time, I might also briefly mention a couple of micro caps
.
Superdry (LON:SDRY)
133p (down 12% yesterday) - mkt cap £109m
Many thanks to a reader who emailed me an up-to-date broker note on SDRY, that was very helpful. I know we're not mean to pass around broker notes, but how on earth can I write these reports, if I can't get access to research forecasts? Actually, I'm probably better off making my own estimates, as the latest broker note doesn't make any sense at all to me.
It forecasts current year FY 04/2021 revenues of £690m, down only 2% on FY 04/2020 actual, reported yesterday. This doesn't make sense, because we were also told yesterday that revenues in the first 20 weeks of FY 04/2021 across all channels, are down 27%. The trend has worsened within that, in that the latest 7 weeks saw a deterioration to -30.3% revenue shortfall against last year.
H1 revenues were £369.1m last year, so if the company ends the half year down 27%, this year we would see an £85m drop in sales to £284m (for H1). That would result in a heavy loss, because last year H1 was only breakeven.
Since the broker is only forecasting a full year drop of £14.4m revenues for FY 04/2021, this implies recouping about £70m of additional revenues above last year's in H2. How likely is that? Last year H2 FY 04/2020 was £335.3m revenues (hit in Q4 by covid, for the last month or so). I make that an assumption that H2 FY 04/2021 would need a +21% growth in revenues, in order to hit forecast. That seems a herioc assumption, even allowing for some catch up in March & April 2021 against comparatives when the stores were mostly shut in 2020.
All of this assumes that there won't be any further lockdowns, forcing more shop closures, something that is looking more of a possibility with each passing day, as covid cases keep rising.
For the above reasons, I reckon my gloomier estimate (where I see a loss of c.£100m being likely for FY 04/2021) look much more prudent than the unrealistically optimistic broker forecast. I'm happy to change my view, if the numbers show that I'm being overly cautious. The interim results should be interesting. All the while, the balance sheet is being eroded. Creditors can only be stretched so far, and I remain of the view that SDRY is likely to need refinancing at some stage.
.
Augean (LON:AUG)
Share price: 165p (down 13% yesterday)
No. shares: 104.5m
Market cap: £172.4m
All I can remember about Augean, is that it's some sort of recycling company, had a very large dispute over landfill tax, and reported stunningly good results while back, and I couldn't work out how it made so much profit. That's why I've always shied away from buying any shares in it.
Augean, one of the UK's leading specialist waste management businesses, announces its unaudited interim results for the six months ended 30 June 2020.
Landfill Tax Dispute - this is still a live issue, and looks material to the market cap. I've no idea what the second bullet point means, but the first one is fairly clear;
.

.
H1 results highlights look pretty decent, considering Jan-Jun 2020 was impacted by covid & lockdown. The business has remained very profitable, albeit down a bit on last year H1;
.

.
Outlook - the most important bit says;
Full year profit expected to be second half weighted with reducing impact of Covid-19 and lower oil price
The Board expects to broadly meet market expectations for the full year maintaining our growth profile assuming no further Covid-19 lockdowns in the second half
That sounds fine to me. Stockopedia shows a consensus of 16.8p EPS for FY 12/2020, which is a PER of 9.8 - seems cheap.
Dividends - Augean doesn't seem to pay there, I'd want to look into why that is, before buying any shares in it.
Balance sheet - looks reasonable. As you would expect, it has quite high fixed assets, and some debt - which is mostly offset by a cash pile. So no problems I can see.
My opinion - I don't understand this sector, and hence it's not of interest to me. I have to understand where profits come from, and this business seems to make far higher profit margins than I would have imagined. Landfill is obviously a regulated sector, and if it's become too profitable, then I suppose the Government might decide to plunder it for more tax revenues? Talking of which, I wouldn't want to buy before the HMRC issue is resolved, over landfill tax.
A PER of just below 10, for an apparently highly profitable business, is a pretty good starting point for further research, if readers want to take it further.
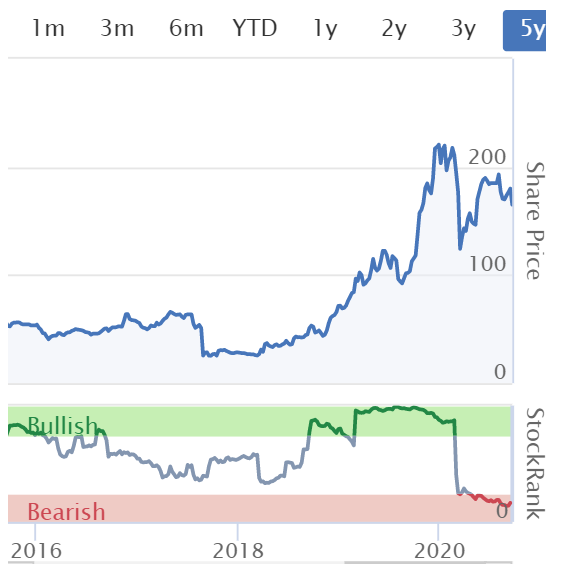
The StockRank turned from very positive to very negative, see below, which seems an unusual move.
EDIT: Thanks to subscribers davidjhill and Berksbee, who have both added interesting points about Augean in the comments section below. That helps to fill in some of the gaps in my knowledge, so much appreciated! We like it when readers share your knowledge of companies here, to add to the group's understanding of things. End of edit.
.
.
Judges Scientific (LON:JDG)
Share price: 5220p (up 2.4%)
No. shares: 6.28m
Market cap: £327.8m
Judges Scientific, the group focused on acquiring and developing companies in the scientific instrument sector, announces its Interim Results for the six months ended 30 June 2020.
It's important to remember that we're looking at accounts which have inevitably been impacted by covid. Taking that into account, the numbers from JDG look reasonable;
Revenues down 6.8% to £37.4m in H1 - but this is helped by acquisition(s), organic revenues were down 12%
Earnings also took a hit from covid, with adj EPS down 22.5% to 84.2p
Interim divi is up 10% to 16.5p, but that's only 20% of earnings, and very small in yield terms, so I can't get excited about it being raised by 10%
Adjusted net debt is modest, at £3.9m
Balance sheet - adequate, but NTAV is small, at £5.7m (NAV: £31.0m, less £25.3m intangibles)
Order book - this is a concern. The commentary says that management believes orders have been deferred rather than cancelled, which I'm sure is true, because I trust management at Judges, based on their excellent track record. But the organic order book was down a lot, 17%, in H1, and has shortened to 10.8 weeks. Order intake in H2 is also down. So there must be a risk that the company might not be able to fully rebuild the order book, hence we could be seeing some profit impact of covid being deferred, possibly?
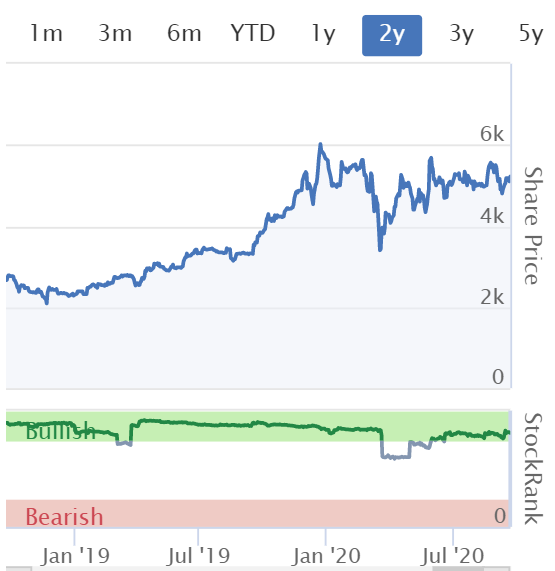
Outlook - cautious confidence in meeting full year expectations. Note below how expectations have been lowered, and we're now looking at about 150p for FY 12/2020, giving a PER of 34.8 - that's too expensive for me. We're being asked to pay up-front for a substantial recovery in future earnings, above the c.150p likely for this year. I don't find that an attractive proposition. I'd rather pay maybe 20 times for this year's earnings (c. £30 per share), then make a profit on the company recovering to higher earnings in future. How does it make sense to pay a £22 premium on top of that, in the hope of future earnings recovering?
My opinion - a nice, well run group of companies, but the current valuation looks too high for me. Particularly, as we could see ongoing impacts from covid - the budgets of universities are mentioned in the narrative as being under pressure, which could perhaps make it difficult to rebuild the order book? Given all the uncertainty out there, I cannot see why we should be paying top whack for anything right now.
.
.
Boris Johnson speech re tighter restrictions
I've just watched the Prime Minister's statement to the House of Commons, re the introduction of tighter restrictions to stem the spread of covid. It's pretty much as trailed by the media, with no shock or unexpected measures. Therefore I couldn't think of any particular repercussions for shares. The sectors under pressure (bars, restaurants, travel, live events, etc) are likely to remain under pressure, so the stock market has probably already priced-in slightly tighter restrictions.
The main thing from our point of view, as investors, is that I didn't see anything in today's announcements which would do fresh harm to the economy. Hopefully it might go some way to reducing the spread of this disease, whilst still allowing life to carry on for the vast majority who are not under any serious threat from it.
They probably got the balance about right, I'd say. So nothing for me to rant about. Back to results statements then.
.
Trifast (LON:TRI)
98.5p (up 1.6% today) - mkt cap £121m
Leading international specialists in the design, engineering, manufacture and distribution of high quality industrial and Category 'C' components principally to major global assembly industries
FY 03/2020 was challenging, but maintained revenues > £200m, and a 9% operating margin.
Fundraising done in June 2020.
Q1 (April, May & June) saw a "meaningful reduction in revenues", with an improving trend moving into Q2.
H1 revenues "slightly ahead of base case". Base case is full year revenues 16% below last year - so this is far from good.
Activity & pipeline encouraging.
My opinion - I'd like to see the numbers before forming a view on this, because revenues don't give us the full picture. Operational gearing can mean that profits fall a lot greater percentage than revenues. Interim results come out on 24 Nov 2020, so I'll review those at the time.
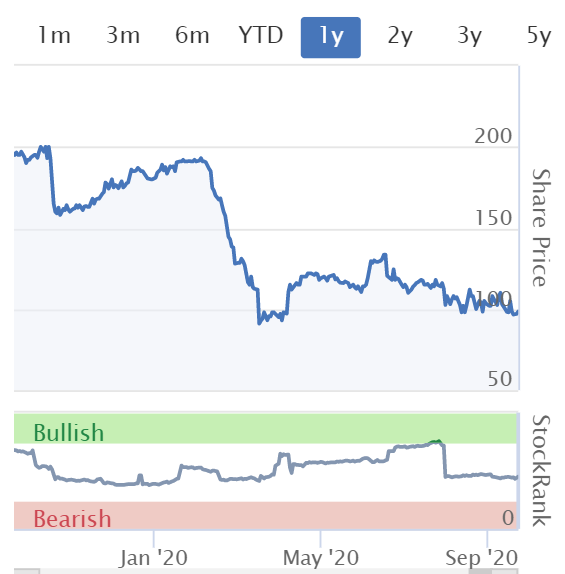
Note that the share price here has remained depressed. I suspect that the forthcoming interim results could look very weak, because a 16% full year drop in revenues, suggests that H1 could be a good bit worse than that, and I note that the company is coy about giving us detailed figures today.
On the upside, this has seemed a well-run group i the past, so I have no reason to believe it won't recover fully in due course.
.
.
Porvair (LON:PRV)
500p (up 1.8%) - mkt cap £230m
Porvair, the specialist filtration and environmental technologies group, today issues a trading update for the nine months ended 31 August 2020.
This update stands out for a lack of information. Consider this;
Revenue for the nine-month period was 2.5% lower than the same period in 2019 (2.2% at constant currency1) despite the Covid-19 landscape.
The Group remains profitable and cash generative.
The first sentence above is fine - the covid/lockdown period seems to have only had a modest impact, with just a 2.5% drop in revenues vs last year.
The second sentence strikes me as rather ridiculous. In H1 Porvair made £8.8m profit on £73.2m revenues. So to say that it "remains profit & cash generative" tells us nothing! Of course it will still be profitable/cash generative, but how much? That's what we need to know. Is it trading in line with market expectations? Nothing is said about that.
Revenues - note £73.2m in H1 was up 2% on LY.
H1 + Q3 is now down 2.5% on LY.
I've crunched the numbers, and assuming an even seasonal pattern of revenues, I reckon this means Q3 was down c.12% on Q3 last year - that's quite a big miss on revenues. It's obscured by quoting the year to date figures.
Net cash of £0.4m looks fine
My opinion - I would have liked to see more open disclosure of the poor Q3 performance, rather than burying the bad news in YTD figures.
The broker consensus revenue forecast shown on Stockopedia is for a near 8% fall in FY 11/2020 revenues, so it looks as if a soft Q3 and Q4 was already baked into the pie. In which case, why didn't the company comment on performance vs market expectations?
If companies are going to issue trading updates, how about making them useful, and clear?
This is a decent, high quality business, but I'm not sure the premium rating is justified, because growth has gone off the boil, due to the macro picture & covid. Aviation must be a drag on Porvair' performance, as I seem to recall it makes special filters for aircraft.
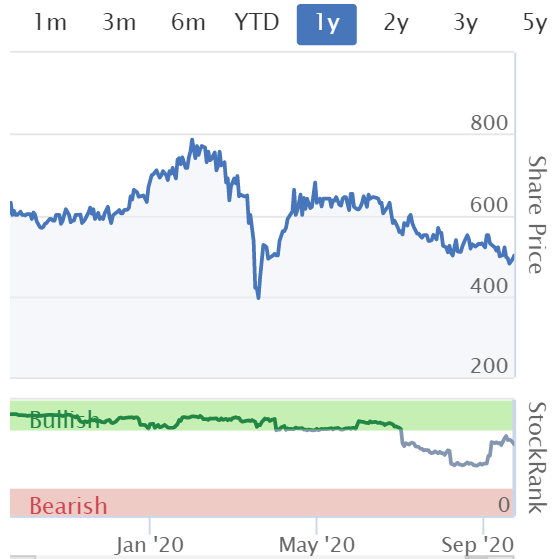
The forward PER is over 20, for a business that might take a while to recover to previous peak earnings. That doesn't seem particularly attractive to me. At best, it's probably priced about right, or maybe a bit too high still?
.
.
Ideagen (LON:IDEA)
197p (flat today) - mkt cap £444m
Ideagen PLC (AIM: IDEA), a leading supplier of Integrated Risk Management software to highly regulated industries, announces its audited final results for the year ended 30 April 2020.
These accounts are not the simplest to go through, as Ideagen has been highly acquisitive in recent years.
Revenue is up 21% to £56.6m, some organic, and some acquisitions.
Adj EPS is up 12% to 5.36p - giving a very aggressive valuation of 36.8 times PER. I can't get anywhere close to that valuation to make me want to buy this share, but that's what the market values it at.
Net bank debt is £16.8m, which doesn't look excessive, given the reliable recurring revenues, and low customer churn. It's a resilient business, with covid apparently not having much impact.
EBITDA & cashflow - there are so many adjustments to these figures. See note 4. The way I look at things, it is genuinely cash generative, because the £11.3m amortisation charge relating to acquisitions, is, in my opinion, a valid adjustment.
Capitalised R&D was £3.9m, so that's about a quarter of the cash generation. Hence we can disregard EBITDA.
Balance sheet - as mentioned before, I appreciate that software groups with reliable cashflows paid up-front by customers, can stretch their balance sheets without necessarily causing problems. In this case, NAV is £76.9m, but being acquisitive, the balance sheet is top-heavy with £113.8m intangibles. I would write off all of that, to arrive at NTAV negative at £(36.9)m. Because it keeps making more acquisitions, then I can't see this changing any time soon. There was an equity raise to help pay for some acquisitions a year earlier.
Working capital looks weak, but that's because a £25m bank loan is shown in current liabilities. That doesn't seem to tie in with a 2023 expiry date of bank facility, so I'm not sure what it's doing in current liabilities?
It looks as if the bank facility has been doubled in size since year end, which I think is starting to look too much debt, and a placing would now make sense to moderate the bank debt, and strengthen the balance sheet.
The Group has sufficient liquidity and funding facilities. As at 30 April 2020 the Group was £25 million drawn down against its total Revolving Credit Facility ("RCF") of £40 million (which is in place until March 2023) and had cash on hand of £8.2million.
Since the year-end, the Group acquired Qualsys Limited. The initial £14million consideration paid at completion was funded via a further drawdown of the RCF.
In September 2020 the RCF facility was extended by £10million to provide additional headroom. This Group's facilities are subject to certain financial covenants.
On the upside, there is now no further deferred consideration to be paid - something important to check at acquisitive groups.
My opinion - in a covid world, this type of recurring revenue business deserves a premium price, because it's resilient whatever happens to the economy.
What I don't like is the balance sheet, with negative NTAV and (in my view) debt which has gone too high since the year end. I just like more conservatively financed balance sheets, a purely personal preference.
Personally I wouldn't be interested in buying this share unless it was under a quid, and the balance sheet was more robust. I don't suppose David Hornsby will want to talk to me again.
.
.
work-in-progress
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
Thank you Paul, your opinions are very much valued, and you’re generous with your time. I have a feeling you haven’t been feeling the love recently so I thought I’d let you know it’s there
Thanks TS :-)
Hi Paul, are you still going to have a look at Ergomed
thanks
I know that SCVR is not interested in Natural Resources stocks, but in case anyone else is, I have done a Note called Horses for courses in Natural Resources - Power Metal Resources plc (POW), just published on the Discuss page. I hope you enjoy it, and would welcome comments/feedback/views.
Re Boohoo (LON:BOO)
The instis will have got themselves into a tiz about the supply chain. They hate the idea of looking bad. I'm sure this is all about patting them on the head, looking concerned and respectable and saying everything is OK.
Sensible thing to do. Last thing holders want is instis panic selling.
PIs are less likely to worry about how holding them looks, only about the facts. And they're less likely to move the market if they sell.
Paul today 'Given all the uncertainty out there, I cannot see why we should be paying top whack for anything right now.' Sound advice for sure!
It's an opinion, not advice!
Ooops Sorry to have used the A word Paul - but its still an excellent opinion!
You're forgiven, Chris! :-)
Following on from my earlier comment about company events I received this from Robert Munday at Research Tree:
“Yes I completely share your view and we hope our soon-to-be-launched enhancement to our Events Hub will allow companies to easily add a slot in their roadshow diary for “everyone else”.
There are some companies that are already doing this via the likes of Yellowstone, Sharesoc, piworld, mello, and more recently InvestorMeetCompany. We already aggregate all but one of those providers on our Events Hub and we’re hoping our own offering can build on that too.
Regarding Boohoo, the Zeus team have come back this morning and said they were speaking to the PR about it. We have a good relationship with the IR so I will try that route as well.
Thank you Michael, efforts in chasing are appreciated. Cheers Tommy
Thx Tommy.
I will be honest and say I am not sure how important it is to have this access but it ticks me off that small PI's are ignored or looked down upon. I wonder back in 2015 when Boohoo (LON:BOO) was trading at 22p and the price had just collapsed from 70p how many instis were even in the stock.
If I had to allocate my time to these or say PIWorlds weekly webinars the latter would win but I normally run a reasonably concentrated portfolio (if you exclude my covid punts just 13 stocks) and therefore I like to absorb any information I can on my holdings and of course as and when they come along potential new holdings.
Michael
These services are mushrooming but does anyone know how they make money?
paul - pls review Judges Scientific (LON:JDG) - I expected a drop - it's up!
Re down time and the access issues at AJ Bell mentioned yesterday, the company is now advising on its web site that they are ‘experiencing difficulties paying cash withdrawals’ Doesn’t sound good.
They are a right shower , a few weeks ago I had to phone in a trade (which has higher charges) the price I was quoted was 25p (10%) higher than the actual market price (I was slightly above NMS) If i was a cynic I would say they were skimming a margin to mug punters .I made a formal complaint and just got an apology .Beware.
Re A J Bell. I have had uniformly good experience with them to date, apart from yesterday's website slowdown. When there isn't an online trade available at the size I want, I have often give them limit orders that are significantly above the offer price and had it filled quickly inside the spread. On the basis of this experience, I don't believe they are taking a dishonest margin.
Agree with your experience. I moved to them last year from a full broker service and to be honest got a bit frustrated with the online trade sizes and lack of ability to get what I wanted. But, after a couple of phone calls I have become proficient in the limit order system, and with careful monitoring of spot prices (via IG) I find it pretty easy to pick a price that gets filled quickly. Great service for £9.95 a trade.
Tremor International (LON:TRMR)
really surprised this isn't flying today. The Q3 trading update is enormous and vastly under the radar in my opinion. $90-95m of revenue and growth of 40% in video. The self serve business has rocketed from $2m to $9m revenue too so that strategy is clearly starting to contribute meaningfully. $78m of cash which is 1/3rd of its market cap despite buy backs.
The market just hates £TRMR. I used hold quite a large position and just gave up on it. And sold out for a loss.
IMO the company should do two things:
- change it’s head office to somewhere in the US
- Change its listing to the NASDAQ where I think it would rated more highly. Perhaps not as highly as £TTD (I hold) but at a more sensibly valuation.
Regards
Michael
I agree. I thought it already changed its head office to US a few months back but maybe I got that wrong. Agree a US listing would be a much more preferable route. Given the CEO is US based that may be more likely in time Hopefully.
re Tremor International (LON:TRMR)
a bit puzzled why you think this should fly. The year on year comparisons show gross profit down, ebitda down, reported loss increased. These are not the figures that will make the dealers mark it up 30% immediately.
I agree that it is a very positive update - but this is a company which is in transition, and I don't think I am clever enough to be able to translate the growth in the new lines of business into a valuation. I continue to hold because I think the management are at least heading the right way.
Because $90-95m of quarterly revenues for Q3 is huge. And it means the anticipated $400m+ revenue expectations for 2021 are much more likely to be met.
Listed peers trade at EV/EBITDA of 15-17
Tremor International (LON:TRMR) currently trades on 4*
looks way undervalued to me
This is a prime example of a company that the market just doesn't trust. After Telit and the problems with the CEO of Taptica (which became Tremor) the market just doesn't like companies with a big Israeli link. The same applies to £KAPE. It is hard to discuss valuations when a substantial body of investors, for whatever reason, regard the company as uninvestable. I'm surprised that the arrival of Rebekah Brooks to the board didn't change this perception btw.
Given RB's proximity to phone hacking, I'm not sure she's likely to improve the perception of trustworthiness of any body she's associated with.
Absolutely. Clear the market is full of mistrust. However, I take comfort from the fact that the current CEO is US based, has built up and sold this type of business before creating lots of shareholder value along the way. Clearly knows what he is doing, where the market is heading and has a trustworthy track record from what I can glean. The company is a merger of Taptica and RythmOne so plenty of DD was done on both companies so seems inordinately harsh to value it almost at a suspicion of fraud level.
Value will out though so having seen todays results I am more than happy to wait for it to arrive now.
Hi Paul, any thoughts on Sigma Capital (LON:SGM)? It seems it hasn't been covered here since 2017, but there has been a lot of recent positive news on the company. Director's dealings, new Chairman, roll out of the PRS REIT and today's JV announcement for £1bn investment in rental homes all seem very positive.
I’m fascinated by the lack of interest in Sigma.
It has significant tail winds with the increase in the PRS sector, government backing (both financial via Homes England and non-financial), a proven business model and operational experience and effectiveness. Overlay significant director buying and an increasing dividend and to me it represents superb upside with very limited downside.
It has become something of a “farm bet” in my portfolio.
Cambridge Cognition:
Interims show substantial progress
Rev up 39%, Order book strong 57% of 2021 revs booked
Costs cut, breakeven in Q4 anticipated
Strong progress
Been enjoying the ride as bought after the change in management, placing and turnround started showing improvement.
Interested to hear your thoughts Paul
Hi Michael,
I hold a few Cambridge Cognition Holdings (LON:COG) and think it seems to be (finally!) turning a corner.
The problem is lack of liquidity in its shares, hence hardly worth me mentioning it here, because people won't be able to buy shares in it. I only managed to get 5,000 shares a little while ago, and more recently had to resort to repeat buys of 2,000 shares equivalent on IG's platform (which is quite good actually, as they often add liquidity to the market). But that seemed to push the price up against me, so I stopped buying.
Regards, Paul.
Thanks Paul
Agree with you.
Looks like it's doing very well
Following in the footsteps of IXI
£LIT. Here's the interview overview of FY20 results, we did with Patrick Maloney, CEO, video & podcast. One of the things LIT are most excited about is their newly launched asset management division, following a close of the US$150m Global Alternative Returns Fund, which is already 61% committed. Beyond this, all case resolutions are progressing as they'd hope. The PBT A$9.2m is lower because three investments have slipped into FY21, but they get paid more due to the delay, when they do get paid. In total, they now have total assets under management of $304m as at September 20. The CV19 environment is positive for litigation funding. So, with the additional funds under management, they feel their growth opportunity has been further accelerated. There is a management presentation to investors with Q&A tomorrow at 9.30am. Register here. If you can't make it, there will be a recording of a presentation in due course.
Judges Scientific (LON:JDG) analysts webinar from this morning will be published over the next few days. David Cicurel, CEO, as reassuring as ever. Mark Lavelle, COO, a great addition to this quality team. Undoubtedly CV19 has impacted order flow, but they've still increased the dividend, have reinstated targets, and hope the environment will bring up acquisition opportunities, as it did with Heath Scientific earlier this year.
Finally, do join us for the piworld interview/live webinar with Richard Crow, AKA Cockney Rebel, this Thursday 24th September, at 1pm. Richard targets 30% return pa. We will hear more of how he screens for stocks and what he's looking for, with examples. As always, there will be the opportunity to ask your questions. Register here.
hi Paul
Augean (LON:AUG) a few points to note
I see Augean (LON:AUG) as a long term play on waste disposal trends that should continue to grow and generate mountains of cash. Thus I consider it way too cheap at existing prices but then I'm happy to hold for 5 years as I think it can generate me 20%+ p/a compounding.
Hi David,
I agree with all you comments. Somewhere in the back of my mind I seem to remember that other waste disposal companies have successfully won their cases against HMRC for tax refunds. I believe it is just a waiting game with £AUG.
Augean’s profit: Presumably there is extraction of soil gravel etc. which can be sold. Someone will pay Augean to fill the hole with Landfill and maybe Augean can cream of the energy that comes from the gases etc. At least three ways of making a profit.
Hi Paul, a little more to add on £:AUG. If I remember rightly, AUG owns one of the very few hazardous waste certified sites in the UK. Also they used to pay dividends but stopped when the tax dispute started.
I'm going to the Manolete Partners (LON:MANO) AGM this morning at 10.30 am. Any questions?
Why does the litigation finance industry report considerable accounting profits and yet consistently negative cashflow (operating cashflow and free cashflow)? Does this not tell us that the accounting profits being reported are highly questionable?
In order to position myself for the coming recession, I looked at Monolete and Begbies Traynor. I came to the decision not to invest in the Manolete due to the negative cashflow.
Has anyone got views on Litigation Capital Management?
Total error!
Hinap,
I hold Litigation Capital Management (LON:LIT) both personally and in a Grand children's trust.
It listed at a bad time for litigation funders as the Burford bear raid was about to break. I'm sure that LIT has been tarred with the same brush , that of booking profits well in advance of realisation and questionable interior accounting, etc. LIT swears it is not sinning in any way, and as a holder, I tend to believe it. Certainly, post Burford, I'm sure it took on board the accusations, tidied up it's act and now runs 'clean'. Litigation finance is, clearly, a long term process, sometimes taking years to go through the courts and this will result in lumpy profits as 'win-some-lose-some' results are inevitable. It seems to me that LIT is well capitalised, well (cautiously) run and I'm in it for the long run Or, at least , my Grand children are.
I have also been tempted in a small way by Nicola Fulston's Rbg Holdings (LON:RBGP), which is in similar territory, but more because I like her style that any hope of massive growth!
Thanks Jasper,
I like the fact that they have a section on their website about the accounting policy...shows an element of transparency.
Their pairing up with funds appears to be. Good long term move.
I am keeping hold my small position but would add on an uptick in momentum in the share price.
Hi Jasper
I don't know much about Litigation Capital Management (LON:LIT), but agree with you on £RBGP. the latter has a number of potentially diverse revenue streams, although in fairness it is the original RBG legal practice that is currently taking the strain.
It is still early days for the litigation finance division, recently branded 'Lionfish' it currently has 9 cases in the pipeline, 3 executed and 6 approved for funding. The company states that litigation investments are held at fair value which is cost or thereabouts and that it does not account for unrealised gains.
Convex Capital constitutes the third potential revenue stream. It was purchased in September 2019 and has been heavily impacted by the pandemic . It focuses on facilitating the sale of owner managed businesses, where the founder/entrepreneur wishes to exit.
Neither Lionfish or Convex Capital contributed to profit for the 6 months to 30 June. As you say litigation finance takes time to come to fruition and is likely to result in profits being somewhat' lumpy' and erratic. I suspect the same is true of corporate finance transactions.
In my view it looks to be very good value when compared to its peer group. I hold, but as always the usual caveat of DYOR applies.
All the best
I hold Litigation Capital Management (LON:LIT) .
H1 2019 was a stonker. H2 would have been good had it not been C19 headwinds.
However, As Tamzin pointed out above, given delay due to C19, Litigation Capital Management (LON:LIT) now are entitled for more fees. So if you look with short term lenses, C19 prevented them from gaining rev that they may have got in FY 20. However, if you look with LT perspective, Litigation Capital Management (LON:LIT) gained by getting more rev ultimately from these 3 deferred cases. Hence the smaller profit compared to FY19, which prima facie looks a bad performance. However, if you look underneath the bonnet:
- they spent A500k more circa on litigation expenses (presumably because they have more deals)
- they are financially armed to do more litigation financing deals globally with the AUM (incidentally, they have the 1st litigation management company to engage in this at least in the northern hemisphere). They have used a large portion of their first fund. They have two more $150mn funds potentially lined up according to the CEO.
- they've spent this year to set up offices in Singapore, London (maybe more - not sure) and relocationing staff (I suspect this contributed to increase in staff expenses of A$1mn
- they have got super sticky with two eminent global law firms for deal origination.
IMHO, I think their first mover advantage in 1. AUM and 2. deal origination from partnerships with global law firms provides them with an excellent moat. With firepower + sniffing out deals, provided they have the ability to turn the deals into realized financial outcomes, Litigation Capital Management (LON:LIT) will grow. The question is do they have the ability? Given their past track record, I think it's fair to say yes.
In addition, as I understand from Patrick, the CEO, courts are gradually going online now. Don't know whether this has already been implemented. So C19 may have limited delay impact in future.
Regarding their accounting, each case is held in their books at COST and not at fair value until a settlement / verdict is given. So no issues regarding short seller accusations here.
Probably best to go thru Tamzin's videos to get a feel. From what I can gather, this co. is about go places.
BTW Simon Thompson just recommended 1.5 hours ago.
DYOR
BTW for the 3 cases which were deferred - they get more fees presumably because the arrangement with the client is the longer the time associated with the case, the higher the contingency fees.
Hi Paul, would you look at Tanden today Tandem (LON:TND) please?
It looks like a decent set of interim results in an area which appears to offer growth for shareholders. Interim dividend doubled to 3pps.
Covered by Castleford Tiger in Tamzin's interview last week, focussed on re-engagement with shareholders.
Hi OldSchool,
We've covered Tandem (LON:TND) here loads of times before, so it's a well-known story. Very illiquid share though. But yes, I'll do a brief section on its interim results today.
Regards, Paul.
Hello Paul. Decent Final Results from K3 Capital (LON:K3C) this morning. Your comments would be appreciated. You're continually doing an excellent job with your daily SCVRs. Thank you.
Positive prelims from K3 Capital (LON:K3C), acquisitions appear to be bedding in well creating more diversified and resilient revenue streams. Outlook is generally confident. I hold
Constructive views, positive and negative welcome.
If K3C are sticking with the existing broker forecast, then revenue and PBT are both forecast to rise but EPS is forecast to drop. Given the acquisitions were stated as earnings enhancing, an explanation should have been forthcoming.
I recall a reader here once said (or it could have been Graham), investing K3C is equivalent to taking a punt on the UK economy. So if you fancy the economy's chances, then thumbs up for K3C
Hi Abtan
I put a reply on your article on Augean (LON:AUG) yesterday, just wanted to flag as not sure if you will go back into it and check.
Have you written directly to the company and asked them why they are not updating as a PI, and stating companies which are good as an example, even if a basic quarterly update to the market?
If not, it is an easy start to send an email off to the CEO. Then see if there are other frustrated holders here and get them to do the same. Same subject but slightly different language is always good rather than exactly the same text ten times.
Just thinking that in my old job when I got one letter sent "to the CEO" it was a quick reply and issued out, but when he got 10 or 20 letters on the same issue "to the CEO", I was called into his office "to explain WTF was going on" and all the responses went out with my personal email and mobile number on saying contact me in the first instance...e.g. do not let this happen again.
Just a thought
Tommy (I do not hold)
Strong H1 results and outlook from SaaS provider Ergomed (LON:ERGO) this morning. Maybe benefiting from COVID research spending? Would be great if you could take a look Paul?
My morning smallcap tweet: Tandem in high gear
Open Orphan (LON:ORPH) Trifast (LON:TRI) OptiBiotix Health (LON:OPTI) Iofina (LON:IOF) Porvair (LON:PRV) Grafenia (LON:GRA) Bion (LON:BION) Ethernity Networks (LON:ENET) Litigation Capital Management (LON:LIT) 1pm (LON:OPM) £June Tandem (LON:TND) Judges Scientific (LON:JDG), Learning Technologies (LON:LTG), Alliance Pharma (LON:APH)
Open Orphan (ORPH) wins contract to support a study involving 750 people. No £££. [SP=14.81 Cap=99m]
Trifast (TRI) guides H1 rev slightly ahead of base case assumptions. Pipeline and activity levels remain encouraging. [SP=97 Cap=132m]
OptiBiotix Health (OPTI) non exclusive license agreement for SlimBiome Medical with HiLife Vitamins & Herbs to commercialise it in USA. Will discuss exclusive deal after 6 month trial. No £££. [SP=51.5 Cap=45m]
Iofina (IOF) refinance debt at 2.5% plus LIBOR. [SP=13.04 Cap=25m]
Porvair (PRV) guides rev for Q1-3 down 2.5%. Co remains profitable and cash generative. [SP=491 Cap=226m]
Grafenia (GRA) Aug rev down c. 30%, similar to July, expect Sept 25-30% down. Layoffs to save £0.9m PA. [SP=6.2 Cap=7m]
Bion (BION) buys two biogas power plants for MYR45.99m (£8.7m). Gets new loan. [SP=1.5 Cap=9m]
Ethernity Networks (ENET) wins order from Indian telecom OEM. $1.5m stage payments in 2020 and 2021. "This deal represents a landmark achievement for Ethernity. It initiates a strategic partnership and opens a new channel in India." [SP=15.2 Cap=6m]
Litigation Capital Management (LIT) FY(June) gross profit up 7% to A$21.7m, pretax A$9.2m, down due to three investments shifting into FY21. Outlook: expects the resolution of seven investments this FY, generating gross profit A$30-A$47m. [SP=67.4 Cap=78m]
1pm (OPM) FY(May) pretax £2m (£7.9m). Trading: remains profitable, trading "steadily increasing with financial results for the first quarter ahead of the Group's internal operating budget." [SP=16.26 Cap=15m]
NAHL H1(June) rev down 22%, pretax £1.8m (£4.6m). Outlook: Aug personal injury enquiry volumes recovered to c. 70% of prior year. UK residential property market looks set to be buoyant for the rest of the year. [SP=NA Cap=NA]. I hold.
Tandem (TND) H1(June) rev up 6%, U/L pretax £1.4m (£0.37m). Div 3.12p. Outlook continues to be broadly positive, domestic demand remains encouraging. [SP=370 Cap=19m]
Judges Scientific (JDG) H1(June) rev down 7%, adj pretax down 22%. Outlook: organic orders in H2 down 13.8%, YTD down 16.2%. Research funding and university financing may take time to recover. Believes that many of the orders not obtained have been deferred rather than cancelled. [SP=4900 Cap=308m]
In line: Learning Technologies (LON:LTG) Alliance Pharma (LON:APH)
Morning Paul, IDEA look like they've posted another decent set of numbers. Would be interested in your thoughts on this this onw. thxs, Alex
I understand Ideagen (LON:IDEA) is very popular but I struggle to see the merits here.
37x for mid single digit organic revenue growth. Heavily adjusted results - almost as if they don't realise acquisitions are part of their strategy!
Development costs > amortisation. Over the last 10 years, Op Cash < Acquisitions + development costs.
Last 3 years, Total assets & total assets - Goodwill up by more than a third, FCF/share is up 10% (and this excludes acquisitions)! Paying increasing dividends but keep issuing new shares.
Then again, while shareholders are willing to keep funding acquisitions for ever higher adjusted EPS, who am I to argue.
I don't hold!
Morning, I didnt plan on posting today, but yesterday i made some changes so the link now points to lse.co.uk instead of investegate.co.uk, and as i made the output thought why not upload it here. Have a good day! :)
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
E-commerce sales* up 164%; now 19% of total Group sales (H1 19/20: 7%).7% in constant currency, largely driven by lower overall costs and B&Q performance.6% (to 19 September 2020) and growth across all banners and categories.3% decline of the market over the same period, representing a continued narrowing of the gap between our sales performance and the market.
It is helpful to read your posts as they save some time.
As a holder of #COG I was pleased to read 93million of contract wins however this is unfortunately an error, the correct figure is more like 9.3million which is a great improvement LFL.
Hi Paul
I think your comment on broker notes is connected to my comment yesterday (which received 39 thumbs so seems to chime with others) about information dissemeination. I wrote:
"Hi
Boohoo (LON:BOO)
Hope somebody can enlighten me. I received an invite from Research Tree:
"Zeus Capital is organising the following Roadshow Meeting for the following company(s): boohoo group Plc"
I cannot attend because it is only for institutional investors. (though I only discover that once I have clicked through!)
I am a shareholder in Boohoo (LON:BOO) and while only a minute portion of the company it is a 10% holding for me.
How can some information be available to certain shareholders and not to others. Surely the information should be either insider information and not for release or not and available to all.
Otherwise it means that certain individuals are trading at an advantage to others and I cannot see how that can be right.
I know it is legal but I do not understand why.
Searching for enlightenment!"
If you have a moment could you explain what the logic is on people who can see certain information being restricted.
If in the Zeus presentation the Booho management "let slip" that Q# is going to be a stonker then certain investors are going to be able to trade on information available to the market as a whole.
Thank you.
Regards
Michael.
Hi Michael FBS,
I cant seem to find Pauls comments on Broker notes, or anything on your question,
'How can some information be available to certain shareholders and not to others. Surely the information should be either insider information and not for release or not and available to all.
Did Paul, or anyone else answer, its such a fundamental question?
thankyou (apologies if I've missed this)
Hi John
Paul’s intro above:
“Many thanks to a reader who emailed me an up-to-date broker note on SDRY, that was very helpful. I know we're not mean to pass around broker notes, but how on earth can I write these reports, if I can't get access to research forecasts? ”
Prompted me to re-post my question from yesterday. It appears that Paul is not able to get his hands on broker notes and I assume attend such things as Zeus Capital’s Boohoo (LON:BOO) road show even though I suspect he has a significant portion of his net wealth tied up in the stock and probably understands the company better than most of the “analysts” who will attend the roadshow, most(all?) of whom will have never run (or any) fashion business in there lives.
I hoping Paul will answer but I know how time crunched he is.
I understand that companies focus on disseminating information to large investors for supposed cost reasons but what I don’t understand is why under the rules that is allowed or at least why they are not obliged to put out a recording and or transcript shortly after the event. And frankly the cost argument doesn’t wash; if Tamzin at PIWorld can do it for free and with no adverts then it is not beyond the wit or wallet of public companies to do the same.
Regards
Michael Broom Smith
I've been complaining about lack of access to broker research, and sometimes company management, for years. It's a structural problem in the UK market. Things are improving a lot of late though - an unintended benefit of covid, is that many more companies are now doing results presentations online.
Some old school brokers, like Numis, Shore Capital, etc, are incredibly arrogant and seem to think it's their job to protect management from pesky private investors, and to ensure that only their clients receive privileged information (e.g. broker research) despite the fact that the client company is actually paying for it!
Yet when you listen to the Q&A on online webinars set up for the benefit of PIs by IMC, PIWorld, and others, the quality of the questions from PIs is superb, with many just as smart & insightful as city analysts.
I get the impression that companies which are engaging with their PI shareholders through webinars are both enjoying it, and finding it useful in helping to stimulate interest in, and liquidity of their shares.
It's also an important legal principle, that companies should be treating all shareholders equally. Giving privileged access to larger investors & analysts is arguably breaking company law. It certainly wouldn't do any harm to remind companies and brokers about that. Companies have a legal duty to communicate equally with all investors, so they should feel obliged to run a PI webinar with results statements every 6 months.
Thanks Paul
When Michael posed the question about shareholders yesterday a google led me to an article about fiduciary duties of directors that included "The need to act fairly between members, for example, treating those with few shares in the same manner as institutions with a large shareholding".
https://www.begbies-traynorgro...
Thank you for the link. I have written to Zeus asking for an explanation.
Hi Paul & MichealFBS
Thankyou for your replies broker access. I too think the webinars now available from Tamzin etc are one of the biggest steps forward of recent times. When actually getting access to a update with city analysts i am often surprised at the poor questions and almost apologetic phrasing used. For instance when a company drops its previously championed KPI, i mean come on the the obvious question, but they often dont or give a leading question to soften it. Rubbish!!
I think though that you have to question the quality if analysts of small caps, its not the pinnacle of the analyst job ladder so what is the quality likely to be, junior analysts or journey men who are not very good. As such i have little time for broker research as so much conflict of interest and why the access to management is so important.
I have no idea how to research the ‘quality’ analysts, i assume there are some?
As for IR i find some good, some completely hopeless, Zues just rude. In general its not a good sign for me if there is no direct company contact numbers for IR - a personal hate is the IR contact being the general info@ - says a lot.
When I did Investor Relations, we used to hold analyst meetings and media meetings separately because the two camps had different interests in the company (analysts being more technical; the media more wide-ranging - get them together and they'd bore each other). We also had one-one meetings with institutional investors, and occasional special days with them focussing on a particular aspect of the business.
Part of the role of investor relations is to ensure no price sensitive information is divulged - worst case is that it is - in which case a stock exchange announcement has to be rushed out to inform all investors of what's been said. Institutional investors and analysts themselves don't want to be recipients of inside information because it compromises them - if they act on it, they risk prosecution and so it inhibits them from taking actions that otherwise they might have made.
This was for a large FTSE100 company - boohoo is on AIM where the rules are less stringent than the main market, but the same principles should apply. I suspect that the point of the meeting you have highlighted is to let institutional investors see for themselves how the company operates, to look management in the eye, and probably to address the issues relating to their supply lines and reservations about their corporate governance.
Thank you for your insights pj8.
Taking your second para:
“Part of the role of investor relations is to ensure no price sensitive information is divulged.....”
That from a layman’s point of view begs the question - if none of the information is price sensitive, in that It aids the analyst in his/her price discovery what is the point? All information divulged by management will in some way have a bearing on the price, won’t it? For example in the case of Boohoo (LON:BOO) if asked about the supply chain issues if they reply no comment that implies any comment would be price sensitive one way or the other or they answer in some fashion that has got to be price sensitive in some way.
Anyway I think it is wrong and FCA or ANOTHER should be doing something about it.
Regards
Michael.
The point is to aid understanding of the businesses - take SCVR. Paul will often confess to gaps in his knowledge about companies - sometimes he meets management alone to explore these and to learn more from them what makes them tick. He reports back in this column - but what he says is never inside information, but more his improved perception, which might have allayed some of his reservations, or explained apparent anomalies. The purpose of investor relations is to provide those in the market with sufficient information to allow them to form a realistic opinion of what the company is worth.
Thank you for your insights pj8.
Taking your second para:
“Part of the role of investor relations is to ensure no price sensitive information is divulged.....”
That from a layman’s point of view begs the question - if none of the information is price sensitive, in that It aids the analyst in his/her price discovery what is the point? All information divulged by management will in some way have a bearing on the price, won’t it? For example in the case of Boohoo (LON:BOO) if asked about the supply chain issues if they reply no comment that implies any comment would be price sensitive one way or the other or they answer in some fashion that has got to be price sensitive in some way.
Anyway I think it is wrong and FCA or ANOTHER should be doing something about it.
Regards
Michael.