Small Cap Value Report (Tue 23 April 2024) - MCG, JUP

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
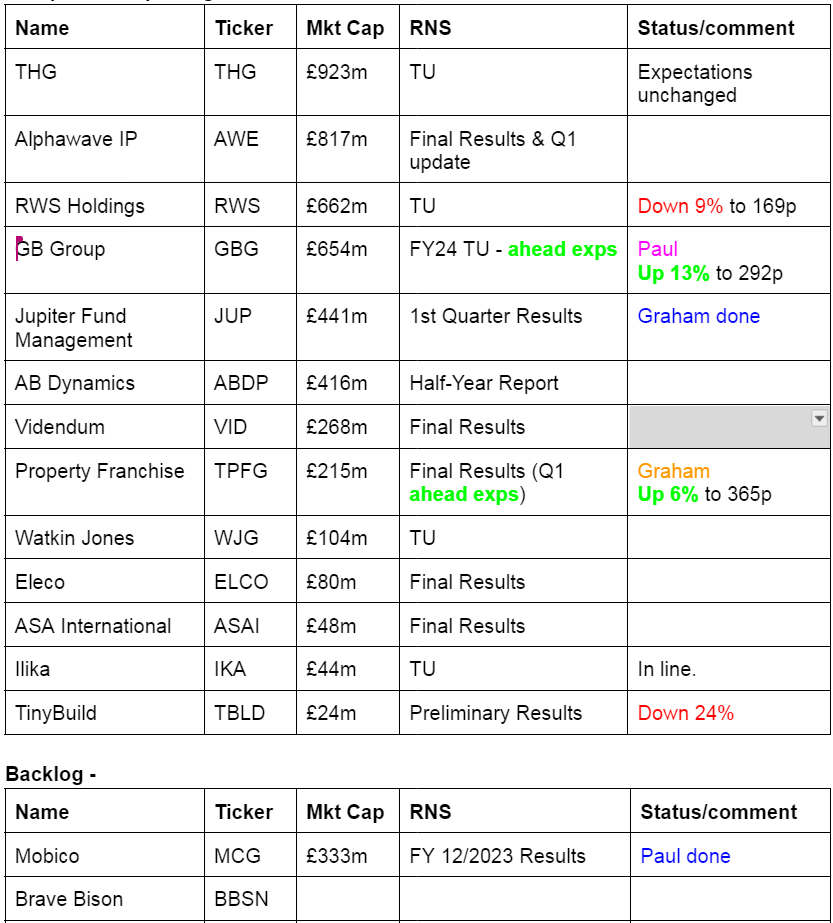
Companies Reporting Today
Mid Morning Movers (with news) -
ABF
.
JD.
.
ITIM
Summaries of main sections -
Mobico (LON:MCG) - down 10% y’day to 54.2p (£333m) - (Delayed) FY 12/2023 Results - Paul - AMBER/GREEN
Delayed 2023 results came out yesterday. Weak balance sheet and too much debt, but debt maturities and cost look reasonable. So providing trading doesn't deteriorate further, then the 3.0x covenant gearing (limit 3.5x) could be OK, but it's getting tight. Guidance is for a slight improvement in 2024 trading. Equity looks very cheap, but above average risk I'd say. It looks tempting for a recovery punt in my view.
Jupiter Fund Management (LON:JUP) - down 0.6% to 80.5p (£439m) - 1st Quarter Results - Graham - GREEN
This Q1 update is consistent with our previous reporting on many fund managers, including Jupiter: large outflows but AuM refuses to shrink, buoyed by market movements. Jupiter suggest they had “underlying” inflows (if you exclude the largest outflows) - but let’s see if they can produce real inflows in Q2!
Paul’s Section:
Mobico (LON:MCG)
Down 10% y’day to 54.2p (£333m) -(Delayed) FY 12/2023 Results - Paul - AMBER/GREEN
Issued yesterday. This is a large, international public transport group. It’s having a difficult time, with 2 months ago the first warning that accounts would be delayed by complicated onerous contracts in Germany. Then a mild profit warning followed on 25/3/2024, although it confirmed significant covenant headroom on borrowings, and £175-185m guidance for adj operating profit.
The highlights table below shows how, after big depreciation and finance charges, there’s hardly any PBT, and these are the adjusted numbers! Statutory numbers show losses before tax in 2022 and 2023. Also note the heavy debt burden, and big falls in EPS & divis, so not a happy picture -
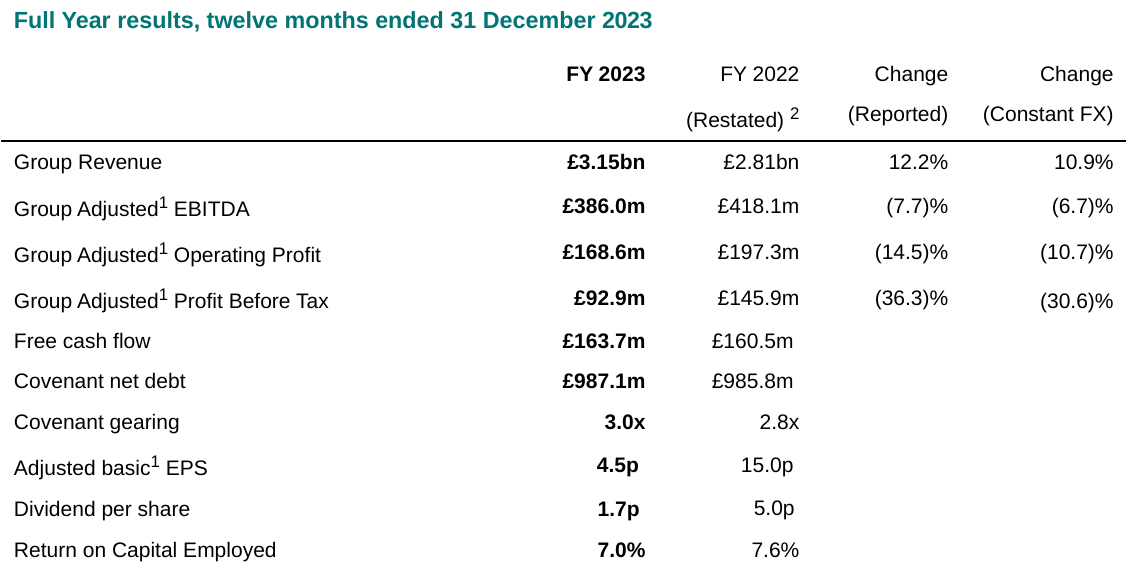
It says the covenant limit for gearing is 3.5x, so that’s not a huge amount of headroom, vs 3.0x above. Although debt maturities look fine, providing it can stay within the covenants -
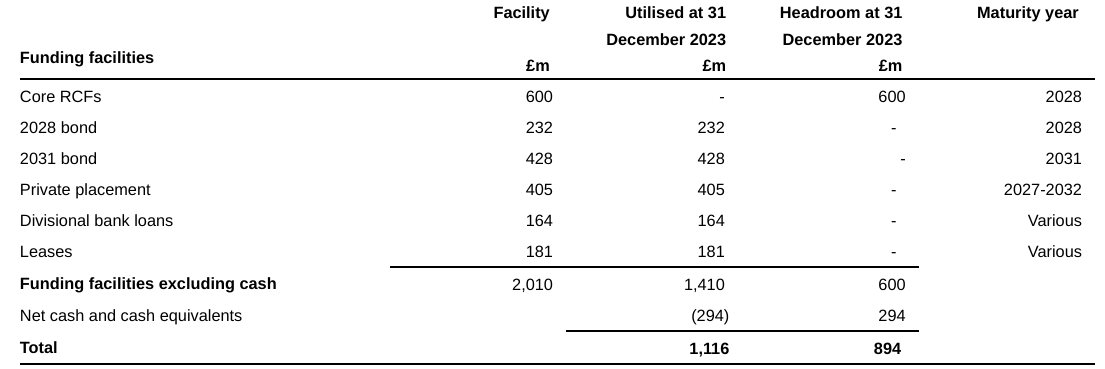
Improved debt maturity and liquidity with £600m RCF refinanced to 2028, and €500m bond refinanced to 2031.
The table below on debt headroom & maturities doesn’t strike me as a company in financial distress (although it might become distressed if profits fall again in 2024 and the leverage covenant becomes threatened by falling EBITDA - that’s the main downside risk here) -
Dividends - the 1.7p in the table above is the interim divi only. There is no final divi, and it does’t expect to pay divis in FY 12/2024, to focus on de-gearing. So for now the yield is zero. It says today that divis may be reintroduced when gearing has come down.
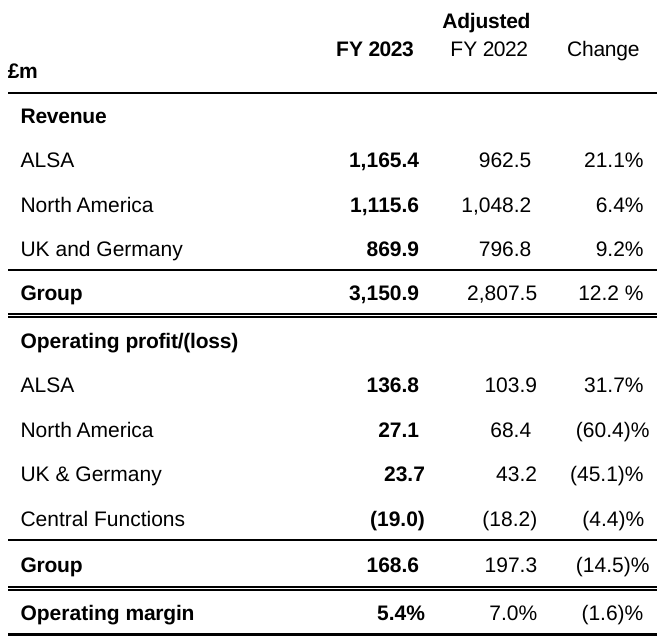
Divisional performance - as you can see from the operating profit section below, ALSA is currently the only part of the business performing well, with the other divisions being poor (and deteriorating). So it clearly needs a turnaround, and has some restructuring activity already underway -
Pension deficit recovery payments are not large relative to the size of the group -
The agreed deficit repayments on the West Midlands Bus plan are £7.5m, £7.7m and £7.8m per annum for the three years from 1 April 2023.
Balance sheet - is very weak, and MCG is dependent on borrowings. NAV was £1,066m at 31/12/2023, but that includes £1,552m of intangible assets. Write those off, and NTAV is horrible, at negative £(486)m. So there’s a hole in the balance sheet that needs to be gradually repaired, the way I look at it. Hopefully that can be achieved from retaining profits for a few years?
If trading deteriorates in future years, then the downside risk is that it breaches borrowing covenants, and has to do an emergency equity raise (maybe at a discount). That doesn’t look an imminent risk though.
Outlook - the latest guidance says -
Based on current market conditions Adjusted Operating Profit for FY 24 is expected to be within the range of £185m to £205m. Similarly to FY 23, we expect a greater bias to the second half of the year, given the phasing of cost reduction programmes and the timing of price increases.
This compares with comparable adj op pr of £169m in FY 12/2023.
On c.£3bn revenues, it wouldn’t take much of a change in variables to see guidance go either up or down.
Paul’s opinion - that’s probably as far as I can take this, in a quick review. It’s a large, complex business, with a market cap of a very low £333m. Debt is large, but seems to have long maturities, and a fair bit of it was recently refinanced on quite decent terms.
I could be wrong, but I’m quite drawn to this share as a speculative recovery idea. The danger is that I don’t know the business well enough to make that call really.
I’ll take a risk, and up my view from amber to AMBER/GREEN, with the proviso that this is more thinking in terms of a speculative rebound trade, or even possible bid interest from overseas, rather than particular enthusiasm for rather weak fundamentals.
EDIT: I've just noticed that the largest shareholder at 19% in MCG is Jorge Cosmen, who also sits on the board as a non-independent NED. It looks as if he may have got his shares through MCG acquiring ALSA, with which he seems to have previous connections. If any readers have more colour on this, please do leave a comment.
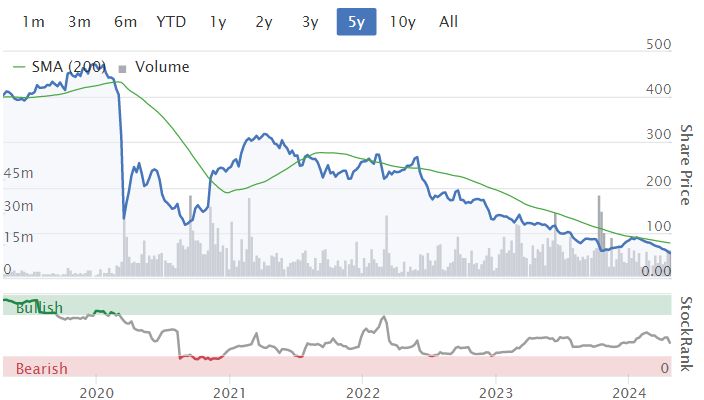
At 5-year lows -
Graham's Section
Jupiter Fund Management (LON:JUP)
Down 0.6% to 80.5p (£439m) - 1st Quarter Results - Graham - GREEN
Outflows continue at Jupiter: another £1.6 billion in Q1 (to March).
They are at least offset by positive market movements (£2.0 billion), so that AuM climbs to £52.6 billion.
The relevant table:
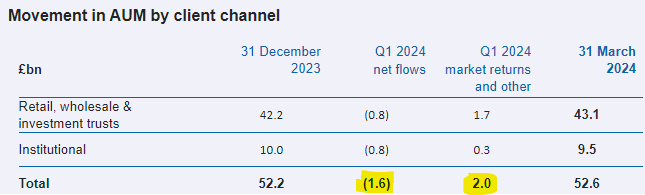
Jupiter suggest that there were “underlying net inflows of £0.3bn”, rather than net outflows of £1.6 billion, if you exclude “outflows related to strategies managed by the Value team and to the Chrysalis Investment Trust”.
The Value team has been hit by fund manager departures, while Jupiter has given up its control of the Chrysalis Investment Trust.
Graham’s view
I wouldn’t exclude the outflows from the Value team, because I think these outflows are a symptom of Jupiter’s overall predicament (persistent outflows, combined with vulnerability to fund managers leaving and setting up elsewhere).
£1.1 billion was pulled from the Value team in Q1, leaving £7.5 billion in AuM. It would be brave to bet on the outflows ending there.
Similarly, the loss of control of Chrysalis could be viewed as a one-off event. If everything else at Jupiter was going swimmingly, then it would be easier to make this argument. But in the current circumstances, I would again view the loss of control of Chrysalis as being part of the overall picture of outflows.
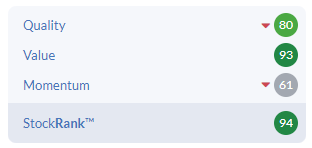
So where do we go from here? I’ve been positive on this share due to the extraordinary cheapness, not just in terms of earnings multiples but also versus AuM.
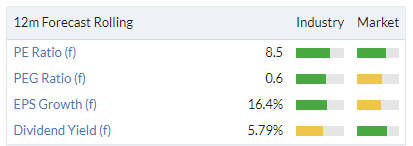
Based on today’s figures, I think that investors are getting nearly £120 of AuM for every £1 invested in Jupiter stock. This is an extraordinarily depressed valuation, not just against Jupiter’s history but even against the rest of the fund management sector today.
I am therefore going to have to view this one positively, even given the continued outflows.
Note that AuM did rise, despite investors pulling their money out. The fund management sector is unusual that way - they can keep growing even as they lose customers!
I think I first turned positive on this share in the second half of 2022. The share price hasn’t agreed with me yet:
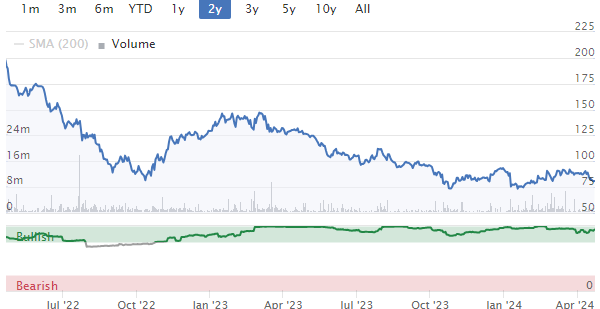
But the StockRanks certainly do agree with me:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Georgia Capital (LON:CGEO) Bank of Georgia (LON:BGEO)
Interesting day. Bank of Georgia (LON:BGEO) broke out of its malaise following its full year accounts and rose over 5% whereas Georgia Capital (LON:CGEO) hardly moved.
The increase was worth @£25m to Georgia Capital (LON:CGEO) . MV of the shares it holds is £480m compared to its own market value of £556m. Current discount to NTBV is over 50% allowing for the rise in Bank of Georgia (LON:BGEO) since the year end which is more relevant to private equity companies holding all unquoted investments.
Both (and I hold both) produce their Q1 figures in mid-May which should be interesting given the current growth in the Georgian economy.
Not for widows and orphans, given its location, but both seem to be very good value at the moment.
A.
The Chart looks like something out of the US Tech madness, GCEO that is. But clicked on the Martin Zweig Growth Screen and picks out some leads. Have US sector so more leads than I can deal with in a lifetime. UK's Journeo (LON:JNEO) in the list and seems to have some "right stuff".
VP (LON:VP.)
Not sure what if anything is happening, probably very little! Up 8.5% on increased volume. Jeremy Pilkington, the founder and 50% equity holder put the business up for sale some years ago, but failed to receive an acceptable offer.
Hi Paul
Re MCG
You don't mention the forthcoming disposal of their NA school bus division which will commence q3 after the bids are finalised for 24/25 schools contracts, and aim to complete by year end.
That would put a huge dent in the debt.
They also have 294 million cash and 600 undrawn rcf, are generating plenty of fcf, not exactly living off debt.
Lastly Cosmens have been adding under 2 funds ( Northern express and European express) since Dec, along with another Spanish fund Azvalor, so assuming they possibly in concert, not far off the magical 30%
I think he desperately wants Alsa back
@MCG
"I think he desperately wants Alsa back"
A quick google brought up this article, from 2023, celebrating ALSA's centenary
Quién está detrás de Alsa, la mayor flota española de autobuses | El Periódico de España (epe.es)
gives a flavour of the Cosmens.
As to Azvalor, see Our Assets — Azvalor, they appear to back family-owned/founder-managed businesses (incl. J D Wetherspoon (LON:JDW) which also supports your thesis.
Interesting!
ATB
Thanks for the link.
Probably more hopeful at this stage!!
I think one problem here is that the disposal of the school bus operation was supposed to happen in quarter 1 but they didn't get an acceptable price, so now they are giving themselves more time.
It makes sense to delay until the school bids are confirmed q3 with improved inflation linked margins, giving suitors clearer visibility on 25 earnings. Besides given their cashflow generation, they don't need a fire sale, they can meet their interest payments until a successful sale or rates are cut.
Jupiter Fund Management (LON:JUP) Thanks for opinion Graham. I bought Jupiter Fund Management (LON:JUP) based on view that it’s oversold. However it’s taking a while for any turnaround to materialise. Still waiting for larger fish to get interested at this price.
My stop loss will be if the SP closes below 71p.
Jupiter Fund Management (LON:JUP) bobbling along on the bottom still. At this value though it must be a reasonable recovery play. Similar over at Liontrust Asset Management (LON:LIO). It still seems to me that most people in the UK are not very motivated by investment, so I do see brand-recognition being enough to pull money back in if we see a decent FTSE rally. I hold.
On Jupiter Fund Management (LON:JUP) and others.
Really don't understand why one of them don't adopt a factor based approach combined with a qualitative approach (*) and publicise/sell it as that. A rules / team based method stops stars emerging and that is OK, for every buffet there are many woodfords.
People like computers ... up to a point then they like having a human make the final decision.
(*) yes this is what happens here. There are not many new ideas.
It strikes me that Jupiter have lost most of their star managers (which retail buy), and have hemorrhaged assets, making it unlikely that DFM starts buying them, unless they are offering something really differentiated, which they don't seem to be. Until one or both of those start to turn, and they have adjusted costs necessarily, they are unlikely to go anywhere.
Their two flagship bond funds have lost circa £5bn AUM since the end of 2020, despite fixed income now being infinitely more attractive.
Little to nothing in the way of performance fees coming in, and relentless consumer duty pressure on management fees, but very well paid teams... don't see how this turns around easily.
These shows should be of interest…
We have two FREE events this week with something for everyone!
Starting off with Mello Investment Trusts and Funds today, Tuesday 23rd April, at 1pm.
1:00pm Emma Bird, Head of Investment Trust Research, Winterflood Securities presents “Discounts: Risk or Opportunity?”
1:30pm Company presentation by JPMorgan Asia Growth & Income plc
2:00pm Company presentation by Literacy Capital
2:30pm Company presentation by International Biotechnology Trust
3:00pm Andrew Latto presents Global Investment Returns 1900-2023
For more information, click here: https://melloevents.com/mitf-2...
Register for FREE here: https://us06web.zoom.us/webina...
Mello Results Special on Thursday 25th April at 1pm.
Programme:
1.00pm Company Presentation by Gelion plc
1:40pm Update from SIGnet
1:50pm Company Presentation by Team Internet
2:30pm Results Round Up
2:50pm Company Presentation by Journeo
3:30pm Results Round Up
3:50pm Company presentation Aeorema Communications
4:20pm Company Presentation by Zinc Media
4:50pm Update from ShareSoc
5.00pm Company Presentation by accesso
5:40pm Results Round Up with Paul Scott
6,00pm Company presentation by The Property Franchise Group
For more information, click here: https://melloevents.com/mrs-25...
Register for FREE here: https://www.tickettailor.com/e...
RWS Holdings (LON:RWS) half year trading statement wasn't very well received by the market with a 13% drop in the SP last I looked. The dreaded second half weighting was in there along with not less than 21 mentions of the magic "AI". The update wasn't great but I'm wondering if perhaps this might be oversold now with the SP having done a complete round trip back to 2015 numbers (albeit not accounting for the increased share count due to COVID, since declining again with buybacks), a forward p/e of around 7 and a dividend yield about the same.
The founder still holds a sizeable percentage although he is getting on in years now so perhaps that's weighing somewhat but there were some fairly sizeable director buys throughout 2023.
The CEO statement wouldn't have anyone rushing to top up here "...full year expectations remains dependent on continuing to successfully leverage our growth initiatives and AI offerings to compensate for ongoing headwinds in some areas." but I do wonder if longer term this may represent decent value with annual revenues exceeding the market cap. I don't hold anymore but I'm watching from the sidelines and could be tempted back in at some point.
I'm a holder and I'm underwhelmed - it feels like the same tape is played at each update, Andrew Bode's stake was previously a source of comfort to me as you indicate however he has now taken a step back from the management and that can be seen/felt in company updates IMO, if you look at the core returns of the business too, while cash generation is still good, returns on invested capital have been falling, I can't help but feel that Alphabet et al are going to eat their lunch, managements' response has been that their data is held confidentially and clients are data sensitive (i.e. companies don't want detailed patent info shared with ChatGPT etc) however I'm growing increasingly cynical about this... I've a vested interest to believe in the bull case if someone can make it!
Pinewood Technologies (LON:PINE)
Do we really have to scroll through 5 comments discussing when the special div. goes xd when we have already paid Stocko to provide the answer?
Full year results snapshot for tinyBuild (LON:TBLD) . These are worse than I was expecting & I wasn't expecting much. They need to get costs back under control quickly! They've almost run out of cash again after a recent fundraise. Currently a heavily loss making company that is trying to right the ship after a series of poor acquisitions have almost sunk them.
They are re-focussing on live service games now and do have several promising looking titles in the pipeline. Watch the trailer for Kingmakers if you're interested, it looks hilarious & has received a huge amount of attention. If they can deliver on the quality they probably have a hit, but that's a big if.
I hold. A mistake along my investing journey.
Re Property Franchise (LON:TPFG) and Belvoir.
I see the FY results out this morning - all good. Having said that I only skimmed the RNS
Question
Where are the results for Dec 31 year for Belvoir? And their dividend?
Given the merger was done in February I had thought that there would have been some kind of proforma balance sheet and P&L of the combined entities as at December 31st in the RNS
Perhaps I'm being thick, or am I missing something -- If I am can someone explain or give me a good kick up the...
I am replying to my own query re Property Franchise (LON:TPFG) here so my apologies to subscribers regarding my earlier post.
The original RNS of January 10th contains a summary of the merger which amongst other guff explains the terms of the merger. What I DID NOT READ at the time and which I have now done was the full notice which followed several pages later.
This stated - para7 Dividends sub para Final Dividends -- that there would be a final divi of 7.4p (as in today's RNS). Merger RNS goes on to say this been calculated so as to meet the dividend expectations of each set of shareholders, both BLV and TPFG.
So I've just given myself a good telling for not reading the umpteen page document in the first place
Mobico (LON:MCG) FWIW I go to heathrow a lot on National Express. The fare is up about 40% compared to last year the coach was full and it is still a lot cheaper than the train. This increase almost entirely goes down to the bottom line.
If they can do this across the group, profits will rise enormously.
Are you checking train ticket prices about 5 weeks before? I go up to London, over 2 hours by train for under £10. Looked at National Express and it costs far more and would cost me almost £10 to even get to the pickup point.
I live in Cornwall, the train to Paddington is more than double the price, then i have to pay for the train from Paddington to LHR. £10 is dream!
National Express from my nearest pickup point, in 5 weeks time to LHR, is over £40 and that is the cheapest fare on the day. There were 3 hour gaps between buses, train is every hour. Do they have Wifi that works?
It also takes 6 hours, by train it takes about 3.5 hours.
So depends where you live.
A bit of perspective. Cost of just the electricity (using average home charge) for and ev car would be c. £20 from Cornwall to London. Factor in staff costs, running costs, depreciation etc etc and expecting to get to London from Cornwall for anything less than £50 is surely unrealistic.
I'm not coming from Cornwall, I'm on the Norfolk/Suffolk border. My prices were based from there. Sorry for any confusion. Don't know why it takes it so long by bus.
Penzance to LHR is about £45, takes 9 hours by NEX. By train to Paddington is about £65, with a railcard about £43. Train takes about 5 hours. Yes you will have take the tube to LHR, cost about £3?
I think you'll find that the increase, instead of going to the bottom line, is probably going to increased wages, increased fuel costs, increased interest expense, increased auto servicing costs....
The key problem for Mobico (LON:MCG) National Express services in the UK is the stiff and aggressive competition from Flixbus. They have been throwing lots of money in expanding new routes and stealing volume.
What a remarkable company Alpha International (LON:ALPH. Announcement this morning that they earned £20m profit in Q1 24 on interest income alone. Throw in the core business and FY 24 profit will be c£115m. Excluding their cash pile of £180m, gives a PE of less than 6!
Yes, interest rates are likely to fall but even at 3% (currently 4% in Q1), profit would be c£100m.
They are joining the main market on the 2nd May
ALPHA
Im not sure all these companies that earning interest income on clients deposits qualifies as remarkable.
In fact quite the opposite feels a bit morally bankrupt.
Not beyond the realms of reality that there may well be some regulatory pushback in the future as companies filling their coffers with interest earned on clients money is pretty bad form.
Notwithstanding this daylight robbery Alpha as you point out is a good company but bumper profits on the back of interest earned on clients deposits is as we say in the fat cat "a bit of a piss take"
But that is what banks do all the time. Why leave money in accounts that don't earn interest?
If l transfer money it is only in the account, for a short time, they will only have it for 1 day max. But then my current accounts pays nothing or only 1%
Hi Planetx,
in their current annual report Alpha International (LON:ALPH) explain it like this:
"The Group is only able to obtain attractive interest rates on these overnight client cash balances because of our ability to aggregate numerous individual client balances,
many of which are transitory in nature and typically only held for a short amount of time.
Whilst the increased interest income stream is a positive boost for the Group and a natural by-product of our increasingly diversified product offering, we are mindful that aspects of its dynamics are driven by macroeconomics beyond our control. As previously outlined, we have therefore chosen to recognise this income on client balances as ‘net treasury income – client balances’ and exclude it from our underlying results."
To be honest, I am struggling a bit to go from this to "morally bankrupt" and "daylight robbery" ... would you be able to expand a bit on your perspective? (I do accept that there may be some regulatory questions at some point)
thanks!
They hit the nail on the head
It’s “interest on clients balances”
Should be paid to the client not used as a profit centre
Way of the world no doubt but it’s a back pocket tactic used to boost profits at the expense of clients
I’m not outraged but it does need calling out .
Nothing wrong with a bit of theft when you can get away with it in broad daylight and even get congratulated by your shareholders .
I’ll get my coat.
They’re not allowed to pay interest to the client apparently because they don’t have a banking licence. So the client is fully aware of this and chooses to do business with Alpha. So no daylight robbery involved just good business sense/opportunities for Alpha.
I'm really not sure what you are "calling out" here. The business model of Alpha International (LON:ALPH) involves moving money around for businesses and so those clients have to send that money to Alpha. Since they have a lot of clients Alpha are able to aggregate these "in transit" funds and have arranged to be paid interest. Sounds like a sensible business decision.
You might as well argue that if a business has clients who make prepayments to them in order to be delivered a service at a later date then that business should pay interest to those clients? Since the clients haven't received the service and arguably they could have earned interest on that money.
From that perspective British Gas should be paying me interest on all of the money that they've taken up front to cover theoretical future bills. Since I can change supplier that money is mine and can be returned. So why aren't they paying me interest? If you want to "call" anything out then that's a good place to start.
Add British Gas to the list of thieves if that’s the case
Though not sure why you would want to pay British Gas in advance of receiving gas .
Just because it goes on doesn’t mean it’s right .
And of course if your supplier is other gas companies they do actually pay interest which is quite nice of them ..
Ovo used to be good, I used some years ago but have you seen their recent reviews?
With DD payments, often build up credit in the summer. I had over £300 last autumn, now down to about £100. They have reduced my DD by about 30%.
You can add airlines, retailers that take deposits or full payment for future deliveries, agents that take payments for Hotels and flights, stockbbrokers who make money on clients cash. Train companies.
Airlines probably the worst, as they have the money for a longer period and if they cancel it can take years to get your back.
Add British Gas to the list of thieves if that’s the case
To claim Alpha are thieves is a bit strong imo. They offer a financial service to clients by moving money around, they are not an investment service. The customers do not expect interest on monies held for one day - they expect a fast and secure service with a trusted operator who gives them the flexibility of moving money around at the speeds necessary and covering the currencies required - the service they offer they deliver very well!
As for the interest, I can't improve on Damian's assessment - why wouldn't they - it is just prudent management. This is a competitive industry and they are actually imo a very transparent and well run operation. I respect most of your opinions - but I do feel that your moral high ground is becoming somewhat tiresome. You have probably posted about 20 times about your opinions on Supreme for example. As I say I do respect your opinions but these constant attacks are becoming a bit of a bore imo - unless they are adequately backed up with facts. I think that there have been many responses today to show that Alpha are definitely not thieves! But yet you still maintain a very judgmental opinion regardless of the many people taking the time to explain why your thinking might be wrong - you do not address these responses but yet maintain this very extreme view.
FWIW (nowt): I was in agreement to the point of BG. I'm not sure if I have special privileges, but I pay for the gas I use. Therefore, my payment is in arrears with a promise to pay via DD.
Just to qualify my previous description of Alpha International (LON:ALPH); what a "remarkable" opportunity that you can buy a quality fintech on a pe of 6. If the sp doubled it wouldn't be expensive imo.
I'll leave the moral outrage over whether a bank should pay interest on my current account to others...
All well and good wanting interest on your transitory balance.
The key thing their customers are using them for is to avoid the outrageous spreads and arbitrary fees those with banking licences continue to levy.
The likes of Alpha International (LON:ALPH) and Wise (LON:WISE) give you market rate with a minimal charge, while the (no longer on the) high street lot will stick you for a spread + fee, then take their own sweet time to complete the transfer.
I hold Wise (LON:WISE)
This is a very good point. The savings being made and the service being offered is what matters. Why would a customer even care about the interest. If they paid 3% (annualised) interest on one day it equates to less than 83 pence on £10,000! Maybe this shows some perspective on its level of importance to customers.
Property Franchise (LON:TPFG)
As a previous holder of Belvoir, I was disappointed to see that Dorian and Louise were not joining the management team of the newly merged business. However they continue to be engaged in advising in the background and this mornings pre-merger results from Property Franchise (LON:TPFG) read well with a positive outlook statement.
With the anticipated reduction in interest rates, settling perhaps at around 3.5% the enlarged business certainly has opportunities for growth and what appears to be an exciting future.
Happy to be invested.
Hi Jonno
Any comment on my post re Property Franchise (LON:TPFG) about 15 mins ago. I should have appended to yours but i didnt see it.
Agree re Dorian and Louise.
Any comments on the disappearing Belvoir accounts
Re Mobico (LON:MCG) probably worth bearing in mind that the CFO departure might result in some reappraisal of stuff in due course….personally I think the risk here is huge…not least because they have significant exposure to political interventions…& as we know they’re often irrational in nature
Property Franchise (LON:TPFG) Full Year 2023. Revenue and PTP a little ahead yoy; EPS flat year on year. All a smidge above forecasts. They've done very well considering the UK residential sales market was -19%.
Q124 is ahead of expectations with revenue and profit. Lettings continue strong and there's a growth in sales. Obviously the Belvoir acquisition is to bed in this year, with BLV management staying on for the year. Canaccord do not raise forecasts this morning but I suspect an upgrade could come if interest rates go down and resi market continues strong. (As of March24 forecasts for FY24 EPS +1%; FY25 EPS +17%).
Here's a FY23 overview video or podcast by management.
It has to also be remembered that rents have risen very sharply and this will also drive top line, I suspect rents have sort of hit a ceiling providing what ever Gov is in place acts sensibly. Osbournes changes to taxation, renters reform bill and higher interest rates have simply cut the supply of property rents available. Its staggering how few new properties are coming onto the mkt, I'm a BTL landlord. Simple supply and demand rents have risen sharply but I'm not winning and neither are tenants.
Pinewood Technologies (LON:PINE) shares consolidate this am 1-20. The close yesterday was roughly 39p which equates to 786p this morning. I’m surprised they didn’t combine the consolidation with the ex special div date to ease our mathematical woes!
they did didnt they? Return of £358m to Shareholders | Company Announcement | Investegate
Actually they might be ex special div today too…DYOR :) in which case the share price should be around 300p…
Wasn't today the record date for the special dividend to be paid on 7 May?
22, yesterday I believe.
Private Investor Webinar with Currys (LON:CURY) today at 12.30pm.
Dan Homan, Director of Investor Relations, Carla Fabiano, Head of Investor Relations, and Joe Saunders, Investor Relations Manager, will provide an introduction to Currys Plc, update on current trading and discuss future prospects. There will be time for Q&A at the end.
Register here
Does it really need 3 people in investor relations (full stop) to explain the business?!
Good morning Paul - whatever time did you get up this morning?
Haha very early! Flight back to UK, just landed, will be at my PC by 9am!
Now that is what I call dedication! I'm nominating you for a pay rise!