Small Cap Value Report (Tue 24 Aug 2021) - IGR, ESYS, BVC

Good morning, it's Paul & Jack here today, with the SCVR for Tuesday.
Agenda -
Paul's Section:
Ig Design (LON:IGR) - trading update today flags cost of sea freight, and supply chain disruption - no surprise there, everyone is experiencing problems in that area. Strong demand & cost mitigation have kept things on track to meet market expectations. So a reassuring update today I think.
Batm Advanced Communications (LON:BVC) - outstanding interim results caught my eye yesterday, but two thirds of the profit is from a one-off disposal. Also there seem some one-off contracts from covid - ventilators and testing kits. Looks an innovative group, but I've no idea how to value it, given the difficulty in ascertaining future profit levels.
Jack's Section:
Essensys (LON:ESYS) - fairly robust results over a disrupted year. The group's SaaS products are well-positioned for the growing flexible work market and the US sounds like a big opportunity. The recent fundraise gives the group c£37m of net cash to accelerate growth plans, but for now this appears to be reflected in the valuation given revenue of £22m and a market cap of more than £200m.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Ig Design (LON:IGR)
522p (pre market open) - mkt cap £506m
IG Design Group plc, one of the world's leading designers, innovators and manufacturers of celebrations, craft, gifting, stationery and creative play products, today issues a trading update for the four months ended 31 July 2021.
Strong revenue growth but challenging cost headwinds
IGR has a 31 March year end.
Good start to the financial year
Comparable revenues up 25% on 2020, and up 10% on 2019 (the more meaningful comparison)
“Challenging cost headwinds” - especially in sea freight, as is being reported by many companies at the moment
“Operational disruption” from continuing impact of covid
Strong demand & cost mitigation measures have kept trading in line with expectations (that’s how it reads to me, but wording is a little ambiguous)
Full year FY 03/2022 outlook sounds OK
Looking forward the Group's orderbook for the year continues to be ahead of prior year, underpinning a full year sales outlook ahead of expectations, and as a result the full year forecast earnings remain in line with current market expectations, albeit with the ongoing issues associated with the current supply chain and Covid-19 related challenges.
Net debt - reduced, and now insignificant. Although note that this group does have large seasonal swings in working capital, so a snapshot in time may not tell the full picture -
At 31 July 2021 the Group had net debt of $5 million (31(st) July 2020: net debt $29 million) reflecting the strong cash generation in the prior year and ongoing robust cash management in the current year.
My opinion - we’re all aware of current supply chain problems, which raises the risk of profit warnings, if things get worse.
IGR seems to have a buffer from higher demand, and today’s update strikes me as reassuring.
Although it does call into question the wisdom of so many UK companies having supply chains that seem so dependent on China, an increasingly externally hostile one-party dictatorship.
That raises a major risk, if or when tensions flare up seriously over Taiwan, South China Sea, etc. Investors do need to bear this in mind, as it could lead to a complete shutdown in trade at some point in the future. How do we avoid that risk though, when China is now the workshop of the world?
It would be good to see companies diversifying their supply chains, and onshoring production closer to home, but even then the raw materials would probably come from China! Personally I’d like to see fewer companies in my portfolio so dependent on Far Eastern supply chains. Maybe that means looking more at services companies, rather than companies which shift physical goods from the Far East?
In terms of valuation - IGR looks priced about right to me.
.

.
Batm Advanced Communications (LON:BVC)
88.6p (unchanged at 13:41) - mkt cap £387m
This is an Israel-based company with telecoms and medical divisions, which has been listed on the main UK market for about 25 years - impressive staying power. Apart from a brief flurry between 2009-2011, there have not been any divis.
I wouldn’t normally take things any further, as experience has taught me that it’s generally best to avoid overseas small caps that list in the UK. However, the 25 year history of its London listing, and really impressive headline results numbers yesterday have caught my eye.
Revenue of $71.4m in H1 - a meaningful amount, but down 7.7% on H1 LY
Gross margin notably higher, at 36.0% vs 29.7% H1 LY - although still quite low in absolute terms
Humongous increase in adj operating profit from $2.8m to $20.5m - there are clearly some one-offs in that.
Bio-medical division is the main part of the business, with H1 revenues of $55.1m, and an adj operating profit of $9.4m - an exceptional contract for ventilators is mentioned, so I don’t know how sustainable the profits are?
Diagnostic test kits for covid-19 are also mentioned, so that could again be a variable factor.
Disposal of NGSoft (non-core business) generated a one-off profit of $13.0m, so that makes up about two thirds of the reported operating profit.
Outlook/Guidance - more detail is given, but this is the key bit -
As a result, the Group expects revenue for full year 2021 to be approximately 5% ahead of market expectations. With the greater than expected ongoing demand for the Group's COVID-19 diagnostic solutions, which are higher margin products, combined with the capital gain from the sale of NGSoft recognised during H1 2021, the Group anticipates full year EBITDA to be more than 20% ahead of market expectations, reflecting growth in EBITDA of over 40% year-on-year.
Balance sheet - looks very strong on paper, including $62.2m in cash. Receivables of $38.9m, and inventories of $33.8m both look rather high to me.
Dividends - given the strong balance sheet, and cash pile, why isn’t it paying divis? This cropped up in the webinar which I listened into yesterday. Previously the company had indicated its intention to distribute surplus cash to shareholders, which was reiterated in the webinar. When asked about timing, management replied that it needs to be approved at the AGM in Oct 2021, at which time they will also announce the amount of the dividend.
It will be interesting to see how much cash is paid out in due course.
My opinion - neutral. I don’t normally invest in overseas small caps that list in the UK. Too many of them have gone wrong in the past.
That said, Israeli companies listed in the UK have a mixed performance. I did well on a thing called Pilat Media a few years ago, which was taken over at about 3x the previous price. Then Plus500 (LON:PLUS) has been a rollercoaster, and ran into regulatory problems, but survived and prospered. Tremor International (LON:TRMR) has also had a very bumpy journey but seems to be thriving now. Xlmedia (LON:XLM) also went all over the place. So it’s a strange area. Israeli companies seem very good at tech, and innovation, but you don’t always necessarily get what you think you’re buying! Mind you, we can say that about lots of other companies from other countries too, including the UK!
Management did a good presentation on the webinar yesterday, and there certainly seem to be some interesting parts within BATM. It struck me as being mainly an innovation company, which seems to have done well with some covid-related products. Mgt also talked about a new lollipop they are developing which is lemon flavoured, and makes covid testing much more pleasant, e.g. for children, which sounds like a good idea.
Overall, it’s much too complicated, and difficult for me to analyse, so I’ll leave it there. I just review the numbers, and with one-off, exceptional contracts & profit on disposal, trying to work out future profits is too speculative for me to form any view on the shares. Good luck to holders!
.
.
Essensys (LON:ESYS)
Share price: 315p (+2.94%)
Shares in issue: 64,385,219
Market cap: £202.8m
Essensys provides software to the coworking industry. It’s got two platforms: Connect and Operate. Both aim to reduce the costs and operational challenges of day-to-day management of these flexible workspaces.
The business was actually founded back in 2006 at a time when the flexible workspace market was fairly mature in London. It took four years for the group to refine its product and customer adoption quickly followed. With a London base secured, the group has more recently set its sights on the US market, which has been a significant growth engine for the business.
Flexible workspace in the US is at 2% and is forecast to grow to 30%, so management is enthusiastic about the opportunity there, with brokers citing a £2.5bn addressable opportunity in total.
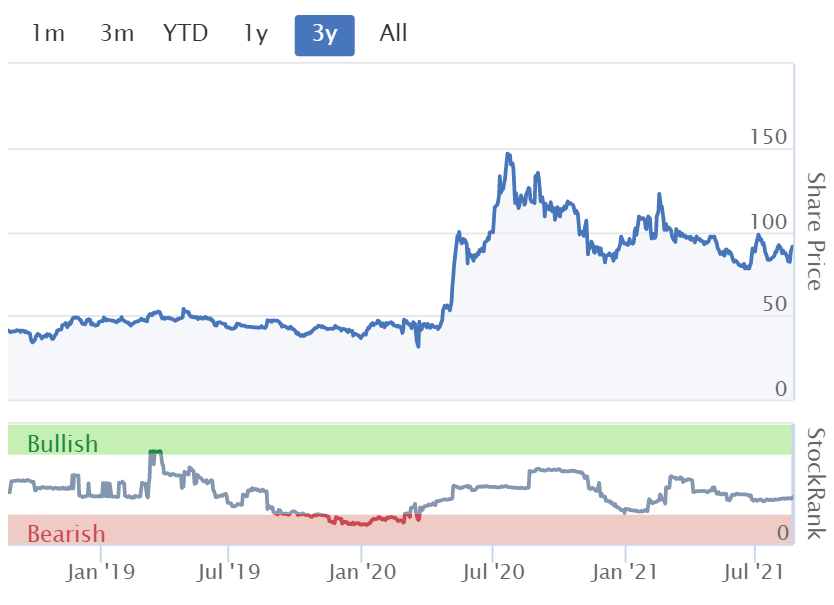
The share price chart looks as you might expect given all that’s happened, with a recent doubling to all-time highs as the market anticipates an accelerated structural shift towards new ways of working.

The market cap is now nearly £200m on forecast FY21 revenue of £22m. Revenue is growing but, at a CAGR of 16.7%, is it growing fast enough to justify that price to sales ratio?

The company is not yet earning reliable profits but cash generation per share looks to be more robust. Still a high multiple though, with price to trailing twelve month cash flow some 61x (and negative free cash flow after investment).
Trading update for the year to 31 July 2021
Highlights:
- Group revenue -2.22% to £22m, of which 87% was recurring (FY20: 86%),
- Adjusted EBITDA ‘in line with consensus market expectations’,
- US recurring revenue +20% to $12.15m,
- Constant currency annual recurring revenue run-rate in July +4% year-on-year to £20.5m,
- Net cash at year end of £36.9m (£5m pre-fundraise).
Essensys closed the financial year with 474 live Connect sites, up 13% year-on-year. The majority of the 28 new Connect sites are to be delivered in H1 FY21.
Around £32m of net proceeds were raised in July via an over-subscribed placing and open offer. This will be used to pursue the group's growth plan over the next three years, accelerating its global go-to-market activities and product development roadmap.
As part of this new plan, Eric Schaffer was appointed CEO of the newly established Asia Pacific business. This expanded capacity appears to be driving decent growth in the US.
Mark Furness, CEO commented:
essensys has made great progress this year, delivering results in line with expectations, continued growth in recurring revenues, and the addition of a number of new strategic customers. This reflects the long-term structural drivers for flexible real estate offerings, which have been accelerated by Covid-19. We have a clear plan to capture this market opportunity, reflected in our recent placing to raise £32m and early progress with our expansion in Asia Pacific.
Conclusion
Essensys is well-placed to trade into a potentially structural growth trend, there’s been some senior hires, a strategy revision, and a significant fundraise. The office real estate area is changing rapidly with a renewed desire for flexibility at the heart of that change. It’s still run by its founder-CEO Mark Furness, who is also the largest shareholder.
Essensys has been supporting a substantial shift in working habits for around 15 years and it seems as though its software-as-a-service solutions are widely used in this exciting space, allowing building owners and landlords to scale up their flexible working footprints.
But the valuation seems steep to me. It does look like the fundraise and linked growth plan are feeding into broker estimates, with FY22 revenue expected to jump from £22.4m to £28.3m. So it’s all about whether or not Essensys can capitalise on the pipeline opportunity in the medium term and justify a high growth rating.
There is a risk to the downside though if the group can’t match the anticipated growth rates. Some notable institutions increased their stakes in the recent fundraise: BlackRock, Amati, Canaccord. No doubt they see a significant opportunity, but I’d need to be much more confident of that opportunity myself before buying in at these levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Northern Bear (LON:NTBR) Northern Bear
Ok - bit of an oi oi update from the company today.
It appears there has been something akin to a bloodless coup today , this really has kind of come from out of nowhere as the old clasic song would say (sigh 80's is old skool now) .
What is interesting here is that the price has been drifting very much nowhere - currently just over 50p compared to its historical pre covid levels of 70p plus. As a holder i would say the business is in as rude health as it was before covid so i have zilch concerns trading wisea dn 50p does seem in the doldrums.
The old and preumably tired chair of the board has been replaced by the wrinkeless (is that photoshop at play?) Jeff Baryshnik - who has previously loaded up on shares at the 70p ish price back in 2019.
https://northernbearplc.com/ne...
His first comments on taking over as chairman of the board are as follows.
“As a major shareholder in Northern Bear plc I am delighted to be appointed Chairman of the Company and look forward to increased engagement with all of the Company’s stakeholders in due course.”
Many on bulletin boards have been crying out for increased shareholder agreement for some time now - it appears those voices have got their wishes answered.
Not sure what this means going forward - i am kind of guesing if this bod wanted to take the company private he could have already put a bid in - so we wil have to wait and see.
His interests as large shareholder certainly should be more aligned with shareholders than the previous board who were deemed to be a bit of an old boys club sucking out shedloads of directors salaries (personally i wouldnt necessarily agree with that sentiment)
It will be interesting to see what plans for shareholder value creation Jeff has - i could be tempted to add a few myself here if the price is close to the 50p level in the morning. Note this is the ultimate in illiquid small caps so you pay your money and take your chance - delisting has to be a possibility here.
Ref the agm that did take place today 2 of the proposed resolutions failed - the one relating to issuing boatload of new shares - i am not unhappy with that situation. Sahme i didn't hop on the metro to see what all the fun is about. Rumour is JB was heard singing along to a Michael Jackson song as he entered the building (that rumour is made up by mee)
all resolutions, other than Resolutions 7 and 8 in respect of share issuance authorities and pre-emption rights, were duly passed.
Resolutions 7 and 8: Authority to allot shares and dis-apply pre-emption rights
As part of its strategy, the Company continues to assess acquisition opportunities as they arise. The ability to issue shares for cash without the need for further shareholder approval will enable the Company to take advantage of such opportunities in a timely manner.Accordingly, Resolution 7, which will be proposed as an ordinary resolution, renews the Directors’ authority to allot up to 5,599,582 Ordinary Shares (representing 30 per cent. of the Issued Share Capital). Resolution 8, which will be proposed as a special resolution, renews the Directors’ power to allot up to 933,263 Ordinary Shares (representing 5 per cent of the Issued Share Capital), for cash, without first offering such shares toexisting Shareholders. This special resolution also enables the Company, in the event of a rights issue or openoffer, to overcome certain practical difficulties which may arise in connection with fractional entitlements.
The authorities conferred by Resolutions 7 and 8 shall expire at the earlier of the conclusion of the Company’s annual general meeting held in 2021 or (if earlier) 31st August 2021.
rmillaree - thanks for that re Northern Bear (LON:NTBR) , which I would not have otherwise spotted. I am one of those who accepted Jeff Baryshnik's 72p tender offer in 2019 giving me a marginal profit.
I was glad to get out because of so many instances of management failing to engage with PIs. This began for me in Jan. 18 when it took two weeks of badgering by PI's as the sp sank before they put out a statement saying no material consequences from Carillion liquidation.
A quick note to say that I also looked at the Q3 results today (required by bond holders) for Benchmark Holdings (LON:BMK) and rapidly came to the conclusion that I have no idea how to analyse or value the company. It's involved in biotechnology for fish. So had to abandon that one. We need to focus on fairly simple companies here, with numbers that are easy to interpret, otherwise there's no way we could cover so many companies.
Interesting share, but I agree... Benchmark Holdings (LON:BMK) is like the animal equivalent of a blue-sky pharma company.
I see that its trading at 4x revenues, with next year's revenue growth only less than 20%, according to brokers.
Eco Animal Health (LON:EAH) which has similar revenue (£100m-ish) also does animal healthcare products, is profitable, and only trading at 2x. Whereas BMK is still very loss-making, even when getting to 9-digit revenues... and 9-digits since 2016... if management can't turn a profit at that level of turnover once in the 5 years, what does that say?
Not a recommendation for Eco Animal Health, as it has its own major risks, but highlights some of the insane valuations.
Tp (LON:TPG) Looks like Science (LON:SAG) are going for 25% another 12m @6.5p
Good luck to everyone involved!
Tp (LON:TPG) Another 22m shares moving hands @6.5p
Hi Paul
The following update for Hotter Shoes appeared on the TRB today, though there is no announcement I can find on Investegate from Electra PE. There is no reference to performance v. expectations (management or market), however does appear on the face of it to be positive for Electra disposal later this year. Would appreciate your thoughts as always.
FASHION
Hotter Shoes posts strong sales growth
24 August, 2021 | by The Retail Bulletin
Hotter Shoes has posted a month-on-month sales increase of 24% for July.
Year-on-year, the retailer’s sales are now up 82% after online sales rose by 91%. Hotter has also experienced growth in its international markets with sales up 7% in the US.
Victoria Betts, chief commercial officer at Hotter Shoes, said: “As one of the largest shoe retailers in the UK, we have seen increased sales across both our online and physical stores in July, up 24% on June.
“We have seen significant changes in consumer shopping habits throughout the past year, and our ecommerce site continues to perform strongly with online sales unwavering, despite the reopening of physical stores.
“In addition, we have experienced strong activity surrounding our end of season sales, which we launched later than most competitors and as such, enabled us to compete not only on our superior quality, but price.”
The specialist footwear brand sells over 1.3 million pairs of shoes each year through its online site and bricks-and-mortar stores. In May, it announced that it would be floating on the London Stock Exchange’s junior AIM market in the fourth quarter of 2021.
cojo
Good find about Hotter Shoes - thanks for posting. Looks positive, I hold Electra Private Equity (LON:ELTA)
Hi cojode,
Indeed, I think Hotter Shoes looks a very good business. The listing for Electra Private Equity (LON:ELTA) (I hold) will become Hotter Shoes (to be called Unbound) once TGI has been spun out into a separate listing quite soon.
At the moment the valuation put on Hotter within ELTA looks ridiculously low, both in NAV, and also in the Edison research notes. With pro forma EBITDA possibly over £7m p.a., and high gross margins, and selling mostly online now most shops were closed in the pandemic restructuring, I think we could see a good long-term investment result from Unbound/Hotter.
It's also planning to branch out into other products for the over-55s, and is already a well-known & trusted brand for that lucrative demographic.
There's a Capital Markets Day (CMD) online on Sept 15, which I should be attending, so I'll report back.
Regards, Paul.
Essensys (LON:ESYS) (I hold)
Thanks for the write-up Jack.
Essensys (LON:ESYS) does indeed look expensive right now and I'm eager to see more granular growth metrics before deciding my next steps.
A few more thoughts, including some that drove my initial purchase:
*Given that these were covid/working-from-home years, I am cautiously hopeful that growth will be much higher in the coming years.
Alongside the high recurring revenue %, this seems like an excellent base from which operating leverage might be exploited in future years.
Pre-covid the UK grew revenues by +5% year-on-year and the US grew +45%.
There's also a green shoot of hope with a +3% YOY revenue growth in H2, which probably would have been higher at Constant Currency.
Things have of course slowed down a lot since 2019.
But if that US growth kicks in again then in a few years my hope is that the current share price will look cheap.
It will be interesting to see how the States is truly progressing when full year results are published.
Cheers
A
Thanks for the additional insights, Abtan. These recurring revenue software companies trade on such high multiples, but some of them really do deserve it and as you say, will end up looking cheap in hindsight. Essensys certainly looks to be in a good spot with years specialising in flexible working.
I wonder what the competition here might be like? Perhaps it will increase as the opportunity becomes more apparent - this fundraise and growth acceleration strategy could be important in terms of staying on the front foot.
Ig Design (LON:IGR) is a total bargepole job for me. I held it until a few years ago but sold when the management started to get greedy i.e. they started a Value Creation Scheme (VCS)... yes, one of those! When they refer to "Value" what that means is a scheme that is great value for the company management and terrible value for other shareholders, thus:
Under the VCS, the scheme awards will allow participants to share, in total, up to 12.5% of the value created ('VCS Pool') provided that the performance criteria are met. No individual award can be greater than £12.5 million. The maximum opportunity available under the VCS is up to 17.5% of the VCS Pool for the CEO and for the other Executive Directors up to 12.5% and 7.5%. Shares will be released to the participants either following the calculation of the VCS Pool or, in the case of the awards for the CEO, the other Executive Directors and three other senior executive, following the end of a further two year holding period. Awards may be structured as nil-cost options which can be exercised from release until the tenth anniversary of grant of the awards, or as conditional awards which deliver shares for nil-cost automatically at release.
For both plans together, the maximum dilution is 15% over a ten year period. For the VCS specifically, within the 15% limit, there is a dilution limit of 7.5%.
All the best, Si
Hi Simoan,
I share your revulsion for so-called value creation plans.
To my mind they're little more than legalised theft of part of the company from its rightful owners.
With so much more emphasis on ESG these days, I hope no more of those dreadful schemes will be approved by institutional shareholders for any management, in future.
Regards, Paul.
Absolutely agree Si.
I bought last year and remember this announcement when the SP was 400p ish after the CEO sold most of his holding. Was patient enough to wait for price recovery but trust in management was gone so lucky enough to get out at 550p. Still leaves a nasty taste though. Total disrespect for us small PIs
I have not been told why my previous post was moderated but perhaps Stocko didn't want everyone to know that there had been a serious data breach with IDs switching and other people's personal details visible. I reported this via the green button and have been told "We are logging everyone out. That should reset the proper details back."
Edit - now it appears to have been unmoderated!
I logged out as Maddog55 and now I have logged in again and it tells me I am Danbjay. There is some serious data breach going on here as I can see his personal details- real name and email etc
Now it has crashed me out again and I have logged in for the nth time. let's see if I can post this, then for the green button.
Anyone else having system issues today?
Yes, it looks as if 13/9 has come early - fails to load completely then crashes into the new site.
Even worse - that post was mine but it has switched my login to Maddog55
sharw
It's what we call you behind your back!
My profile name has changed also.
I've had a response from the Helpdesk "We performed a system upgrade late last night which caused a small number of users to see another user's account. As soon as we discovered this, we reversed the change and force logged everyone out of the site."
Paul, to be fair to Ig Design (LON:IGR) their gift wrapping paper production is in the local markets with modern highly automated machinery. I remember them saying their best performing paper mill is in Wales.
That's interesting, thanks John. I wonder if Ig Design (LON:IGR) disclose the % of production in each country or region? Companies often disclose sales by region, but it's often harder to find out where production happens. And even then, raw materials probably come from the Far East.
Clearly IGR has some issues with supply chains, because they just told us today they did!
In the main article I meandered more into my general worries about how reliant the West has become on China, so that bit wasn't specific to IGR only.
Regards, Paul.
I'm not an Ig Design (LON:IGR) holder currently so not necessarily up to date. The video here shows their South Wales manufacturing site making twist paper carrier bags for retail customers. They were able to adapt their gift wrapping paper line to make these bags very efficiently, smoothing out the seasonal demand. They do also say that they manufacture in China.
But basically everyone has international supply chains to some degree. I don't suppose the paper they use is from Welsh trees.
a good contract win for Open Orphan (LON:ORPH)
My morning smallcap tweet: News nuggets flicking the needle
TP (LON:TPG) Open Orphan (LON:ORPH) Spectris (LON:SXS) IG Design (LON:IGR) Tanfield (LON:TAN) Mediazest (LON:MDZ), Essensys (LON:ESYS)
TP Group (TPG) Science Group hike offer to 6.5p from 5.8p. [SP=6 Cap=47m]
Open Orphan (ORPH) £8.1m contract to test its inhaled human rhinovirus (hRV) antiviral product. [SP=20.92 Cap=140m]
Spectris (SXS) sells NDC Technologies for £130m. [SP=3861 Cap=4359m]
IG Design (IGR) guides FY earnings in line despite "ongoing issues associated with the current supply chain and Covid-19 related challenges." [SP=522 Cap=506m]
Tanfield (TAN) JV Snorkel Q2 rev up 140% and gross margin 8.9% (7.2%). "Board remain of the opinion that gross profit margins generally do not appear to have been in line with the industry averages. Accordingly, steps to investigate the historic margins, which includes ensuring all related party transactions have taken place at an arm's length basis, have commenced and are ongoing." [SP=2.26 Cap=4m]
MediaZest (MDZ) continues to win additional new project work with a strong uptake across the main vertical sectors in which it operates, with many delivered in H2. Recurring revenue contracts continue to be robust with several renewals and new contracts signed in the last 4 to 5 months. [SP=0.06 Cap=1m]
In line: Essensys (LON:ESYS)
Further statement from Science (LON:SAG) on TP Group.
https://www.investegate.co.uk/...
Essentially setting out their position on their indicative bid and conditions thereof as well as taking another swipe at the TP Board and the precarious financial position of the company. Interesting to note these conditions include an unconditional recommendation from the TP Board and access to full due diligence (i.e. appear to be saying they won’t go hostile). Also confirming their maximum bid level (subject to there being a competitor bid) is 6.5p.
Hardball being played by Science (LON:SAG), in effect appealing to shareholders of TP over the heads of the Board. To paraphrase, „Your company is s##t, finances are shot, we can take it off your hands but you have to force your Board to the negotiating table and if you don’t we‘ll walk away and leave you high and dry“ (albeit Science (LON:SAG) now hold 18% of the shares themselves).
Gus.
Can't think of many hostile bids for AIM companies that have succeeded, so it will be interesting to see how this plays out. Looks like institutional holders are the players in this game, and it is a little bit surprising if Science (LON:SAG) hadn't touched base with them.
Looks like institutional holders are the players in this game, and it is a little bit surprising if Science (LON:SAG) hadn't touched base with them.
SAG has already acquired significant stakes in Tp (LON:TPG) from Close Brothers and Ruffer so I think we can fairly sure they're in contact with the institutions. I'd guess today's announcement is to focus minds at the remaining holders - particularly M&G.
timarr
TPG has said that they will consider a properly funded offer at an appropriate price. We don't know what TPG thinks is an appropriate price. SAG have said they will walk away and hold onto a significant investment in what they have implied is a failing business if TPG don't accept 6.5p as their final offer. Judging by today's volume, few TPG holders are in a hurry to believe that SAG will walk away and sit on their trade investment for a year, subject to the impact of fluctuations in the TPG share price.
Let's hope that peace breaks out and that SAG come back with an offer that TPG considers appropriate. Otherwise, this could be bad for shareholders in both businesses.
I hold both SAG and TPG
If SAG do not improve their offer of 6.5p and “walk away”, why on earth would they want to retain an 18.5% stake in what they perceive as a failing business? I hold SAG.
Re. Science (LON:SAG) , if they don’t bid/buy the company, a meaningful shareholding (18% is good but probably 29% is better) would put them in a strong position to requisition an EGM and motion a vote of no confidence in the Board and a recommendation that they be replaced (probably by Science (LON:SAG) and other big shareholder nominees). This would be by a simple majority vote. Quite a commonly used tactic by Hedge Funds (recently done by Crystal Amber at Hurricane Energy (LON:HUR)) to dump incumbent execs that are seen as having an agenda other than that of the majority shareholders. More than one way to skin a cat.
Gus.
If Science (LON:SAG) do not improve their offer of 6.5p and “walk away”, why on earth would they want to retain an 18.5% stake in what they perceive as a failing business? I hold SAG.
They can't increased the bid, unless another bidder steps forward, because they stated that today's offer was final. They also stated that they'll retain their existing stake - probably with the aim of getting board representation.
Today's announcement isn't aimed at private investors or the Tp (LON:TPG) board but at other institutional holders of TPG who can now use this as evidence that this is the best deal they can get. It's probably aimed specifically at M&G who won't want to retain a tiny stake in proportion to the rest of their Recovery Fund.
timarr
Just because they say that they won't increase their bid doesn't mean that they can't. Or won't.
Just because they say that they won't increase their bid doesn't mean that they can't. Or won't.
Yes it does. The takeover code says:
where the statement concerned includes reference to the fact
that the terms of the possible offer “will not be increased” or are
“final” or uses a similar expression, the potential offeror will not be
allowed subsequently to make an offer on better terms.
Yes, you're right, thank you for pointing that out. On the basis of that, I have sold my holding in Tp (LON:TPG) as I don't think a competing offer is likely to appear.
I have also top-sliced some Science (LON:SAG) as I think that Tp (LON:TPG) may be a bigger can of worms than they expect plus I think that they will have to either take on more debt than would be comfortable for me or dilute shareholders or a combination of the two.
Acquiring Tp (LON:TPG) may or may not prove be a good move but I am, personally, not convinced by the arguments of synergies.
Yes, you're right, thank you for pointing that out. On the basis of that, I have sold my holding in Tp (LON:TPG) as I don't think a competing offer is likely to appear.
Probably correct. Science (LON:SAG) have now gone to 21%, getting close to the 25% threshold where they'll have a blocking stake for any competitor.
https://www.investegate.co.uk/...
timarr
Just because they say that they won't increase their bid doesn't mean that they can't. Or won't
AFAIK according to the Takeover Code they can't. 6.5p is where they stick unless there's a competing bid.
timarr
A good purchase if Science (LON:SAG) can get Tp (LON:TPG) for 6.5p. I've long thought Tp (LON:TPG) is a good company run purely for the Directors (I had quite a large holding in the past); would be good to see the back of them