Small Cap Value Report (Tue 24 Jan 2023) - EMAN, ITS, CFX, SAGA, WAND, SNR, ACRL, SNWS, CYAN, SAA, CPC

Good morning, it's Paul & Graham, here!
We've run out of time, managed to make a dent in today's huge list of news. Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda/Summaries
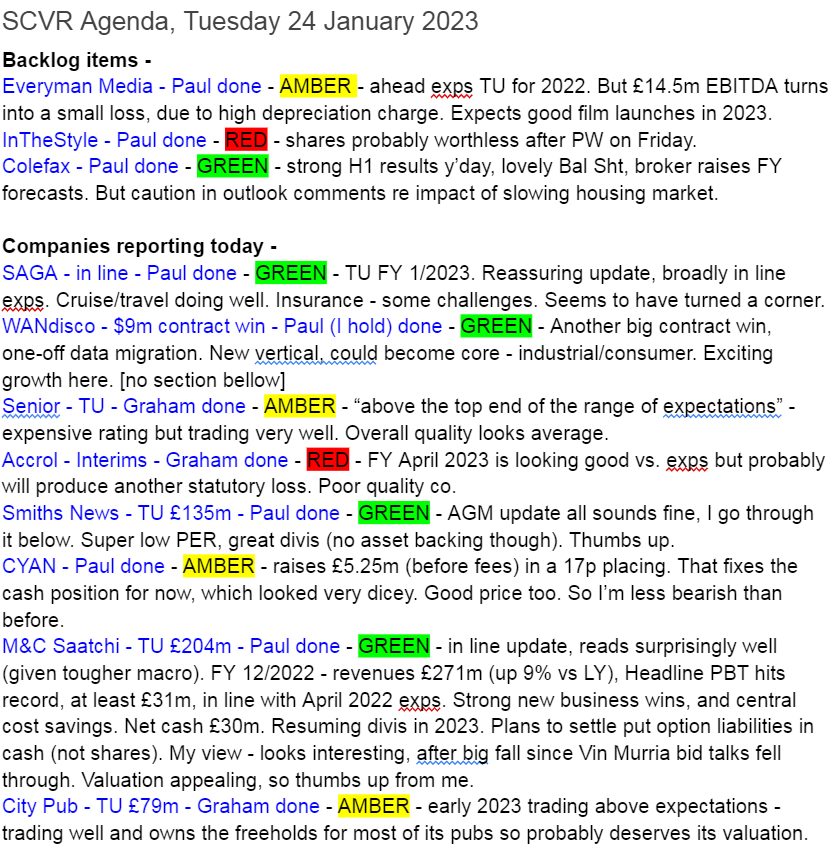
Finish time of 1pm, this is what we've managed to do -
.
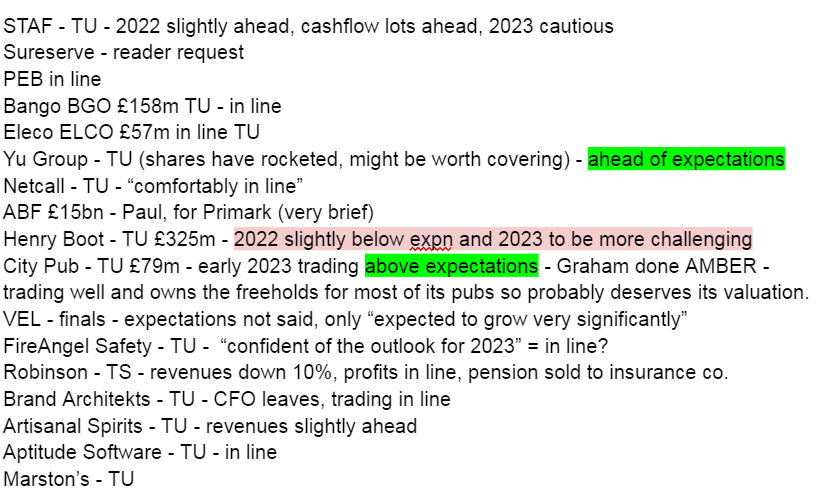
Lots left over though, here are the ones we didn't cover. I'll have a sift through these later today, and try to get some brief comments up tomorrow morning on the more interesting ones -
Paul's Section:
Everyman Media (LON:EMAN)
Up 9% yesterday, to 93.5p (mkt cap £85m) - TU for 52 wks to 29 Dec 2022. EBITDA “ahead of market expectations” at £14.5m. Operating 38 cinemas now (+2 in the last year). 5 new sites planned for 2023. Current trading “encouraging”. Expecting improved volume & quality of new film releases in 2023.
Note separate announcement - 2m “growth shares” in a subsidiary issued to CEO - needs a careful look.
My opinion - check out the broker research - £14.5m EBITDA for 2022 turns into a loss before tax of £(0.7)m. Continued small losses forecast for both 2023 and 2024. So I’m not sure what the point of this business is, if it’s not expected to generate any future profits? To borrow a phrase from Charlie Munger, re EBITDA -
“Does management think the tooth fairy pays for capital expenditures?”
In Style group (LON:ITS)
We already knew this me-too fast fashion business was in trouble, but a profit warning on Friday makes things worse still, with an increased loss for FY 12/2022. There’s still £3.2m in cash left, but I suspect ITS probably only has a few months left to survive. Equity probably worth little to nothing now. I can’t be certain, but it’s difficult to see why anyone would refinance the existing business, when it's trading so badly. Hence the most likely outcome I’d say is a delisting, or lurching into administration, and the business probably being bought out for tuppence halfpenny, minus all the liabilities, by management or a financial buyer.
Bottom line is, I think the existing equity is almost certainly ending up at zero, in the not-too-distant future. Hence it's a bargepole share, at any price.
Saga (LON:SAGA)
152p (pre market) - mkt cap £214m
Trading Update - for FY 1/2023.
This sounds OK. Although at the top it says -
We remain on track to report an Underlying Profit Before Tax of between £20m and £30m, in line with previous guidance.
Then at the bottom, it says this, which seems a little contradictory -
"Saga continued to demonstrate progress in the second half of the year, delivering a trading performance which is broadly in line with expectations.
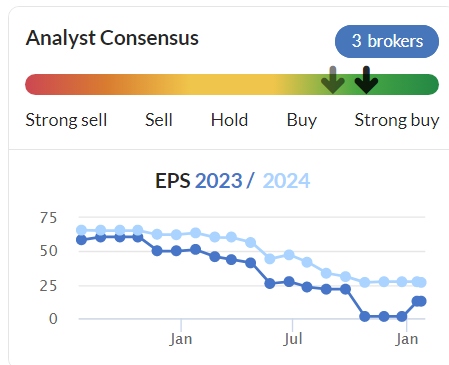
A reader here pointed out that recent broker consensus had edged up, from near breakeven 1.3p EPS, to 12.7p forecast EPS for FY 1/2023. So at least the trend of falling forecasts seems to have stopped -
There’s more detail in today’s update, but very quickly summarising the key points below, I don’t see anything of concern, it seems reassuring overall -
- Ocean cruise business doing well, with strong H2 bookings & increased prices.
- Cruise also well set up with bookings for the new financial year FY 1/2024.
- Travel business beginning to recover, at last, but small loss for FY 1/2023 (as expected , it says)
- Insurance broking “broadly in line with guidance”. Big increase in travel insurance.
- Underwriting business (that’s up for sale, we learned yesterday) experienced “some pressure”, motor insurance facing “challenging period”, with more expensive claims. Raising prices in response.
- Saga Money - growing, no detail provided.
- “Available cash” c.£140m at 31 Jan 2023 - ample liquidity.
- Net debt “slightly higher than at 31 July 2022” - no figure provided.
- Covenants on the (unused) bank facility (RCF of £50m, I think) have been favourably amended, to give more flexibility.
Capital Markets Day - strategy briefing - we can watch online at 3pm today, with recording & slides going up here later.
My opinion - this update seems reassuring, and has been anticipated by the market, with the share price already having doubled from the Oct 2022 low. I’m currently sitting on the sidelines, awaiting today’s news. The key thing for me is that performance had to stabilise, and not lurch further down towards losses, as that could trigger problems with the bonds (covenants linked to RCF covenants - so those being amended sounds good). It seems that performance has indeed stabilised, and with travel/cruise now recovering, the trajectory for profits should now be upwards.
All of this means it’s less risky today than it was yesterday, and that makes the risk of a dilutive equity raise look less likely. Also the risk from debt also seems to be receding somewhat, although that depends on your point of view.
Overall - it’s moving in the right direction now, I think. Let’s see what brokers do to their forecasts, as that should be key to whether there’s enough in the tank for another push upwards, or whether shares might need to consolidate after a strong recent run? Time will tell on that.
Colefax (LON:CFX)
Up 3% to 670p yesterday - mkt cap £48m
This is like a smaller version of Sanderson Design (LON:SDG) (one of my favourite value/GARP shares), making wallpaper and fabrics.
It had a one-off stellar year in FY 4/2022, and has since been guiding for a fall back in earnings this year.
Interim results out yesterday look really good, better than expected.
I’ve only got time for a very quick review, so here are some key points -
H1 revenue up 12% to £52m (growth mainly from forex, was 2.5% at constant currency)
Profit before tax (PBT) £5.2m (up 16% vs LY H1)
EPS up 30% to 51.3p in H1
No adjustments to the accounts, they’re squeaky clean!
Balance sheet is excellent with £32m NTAV. CFX seems particularly good at collecting in receivables, which are always low, this time only £8m. I think it must sell a fair bit on a pro forma basis (i.e. payment up-front before delivery), which is wonderful, because it removes risk of client going bust, and improves cashflow. Impressive £20m net cash pile.
Cashflow statement - there’s quite a lot of leased property, so note that the £2.9m payment of lease liabilities is near the bottom within financing, which means the numbers above that line are inflated - not the company’s fault, but the fault of IFRS 16 which has messed up the cashflow statement by putting some of rents (operating costs) within finance charges, which is total nonsense. Accounting standards really must repeal IFRS 16, but are probably too obstinate to do so. Meanwhile accounts users have to rejig accounts manually, to ensure they actually make sense.
Capex increased to £1.9m in H1 (H1 LY: £0.8m).
The stand-out item is £5.4m “purchase of own shares” in H1, and it was £6.8m last year. These are huge numbers for buybacks in a company with only £48m market cap. This is creating a very unusual situation where the share count is quite rapidly reducing by a lot - thus enhancing EPS, although liquidity deteriorates (see the crazily wide bid-offer spread).
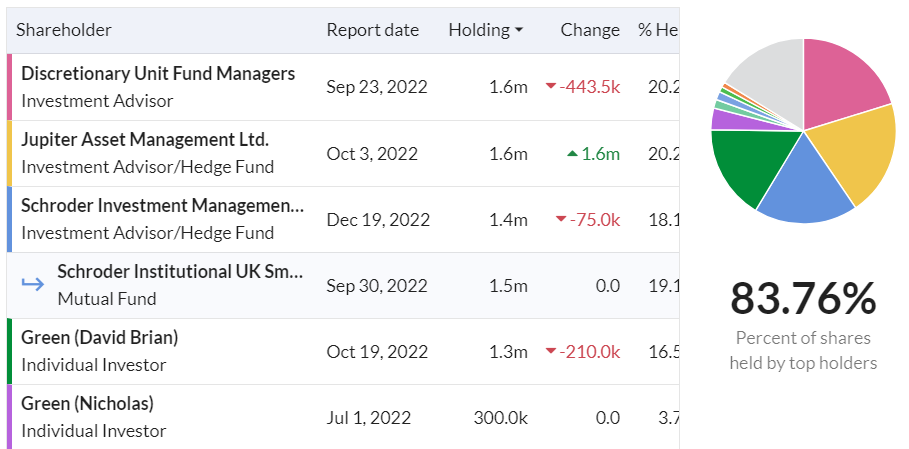
As you can see below the shares are very tightly held by 4 main holders - possible delisting risk? Although 3 fund managers hold enough to block any such move, so on reflection that risk looks small. It could mean an opportunistic bid for the company could be blocked, so I’m comfortable with this structure, on balance.
.
.
Outlook - good, but with some caution here - it’s nice to see mgt explain the dynamics of their sector openly like this, so investors don’t get carried away -
Our performance over the last six months reflects generally favourable trading conditions in all our major markets, in line with our expectations at the start of the year. In addition we benefitted from a very strong US Dollar exchange rate and as a result, we now expect our full year performance to 30 April 2023 to be ahead of previous expectations.
Our business is closely tied to high end housing market activity but with a time lag of six to twelve months. Over the last six months we are aware that housing transactions have slowed significantly in the US and the UK and we therefore expect trading in these markets to become progressively more challenging in the year ahead. We have experienced significant cost inflation over the last year, mainly driven by increased energy costs in our supply chain but there are tentative signs that the worst might be over.
Revised forecasts - note that a sizeable uplift in FY 4/2023 forecast has just come through overnight, and even this higher number of 76.2p EPS looks cautious, given that it’s already done 51.3p in H1 - this is what we want to see - forecasts that already factor in a softer macro position.
Forecast EPS for FY 4/2024 has been edged up a little, at 64.9p - note that this is below the current year, which again is what I want to see, given uncertain macro times. In a big recession of course, earnings would drop substantially, due to the operational gearing. So if you think that’s likely, then cyclical shares like this are probably best avoided altogether!
We can get some inkling of how companies perform in downturns from the pandemic experience (although massively distorted with Govt support measures), and even going back to 2008 (if a company is even vaguely similar to what it did back then, which CFX is).
CFX sailed through the pandemic with only a temporary dip in profitability.
It’s a similar picture in the 2008 recession - CFX remained profitable, on similar revenues to more recent years, with profits dropping by just over half in FY 4/2009, then recovering.
Hence CFX looks to me a resilient business that has a history of trading OK through recessions, which combined with a super-strong balance sheet, says to me that risk here looks negligible for long-term holders.
My opinion - this looks a good value share, thumbs up from me.
Although the lack of liquidity and wide spread could be an issue, so probably not something to attempt trading in & out of.
I see the positive update here also galvanised larger competitor Sanderson Design (LON:SDG) yesterday.
A very good long-term performer (depending on when you timed your purchase), and also note the high StockRank.
Looking for similar shares? Then have a look at the screens (I've put in clickable links below) that CFX passes (shown on every StockReport, just under the chart) -


Smiths News (LON:SNWS)
51.6p (down 7% at 11:34) - mkt cap £121m
Newspaper/magazines distributor. Holding its AGM today. Current year is FY 8/2023.
Everything sounds fine, key points -
Trading in line with market expectations (but no footnote)
Core revenues “ahead of historical trends”, due to cover price increases.
Inflation being managed in line with business plan.
Efficiency gains & cost controls on track.
Outlook - Board “remains confident in the Company’s profit and cash generation”.
“Significant progress” in contract renewals - 46% of revenues secured to 2029.
Strategy - enhance core operations, and develop “adjacent opportunities”, “moving up the value chain” - see 9 Nov 2022 results announcement for more details.
Final divi of 2.75p will be paid shortly (Feb 2023).
My opinion - this all sounds fine to me. We’ve been fans of this value share here since the turnaround first started, and it’s done well.
Still looks really good value, with a forward PER of 5.4 - but it won’t ever get a high rating, due to the structural decline of the core business. Fantastic divis now, yield of 7.5%. No balance sheet support though. It has to be a thumbs up again.
Graham’s Section:
Senior (LON:SNR)
Share price: 145.6p (+7%)
Market cap: £610m
This mid-sized engineering and defence group provides us with one of today’s “ahead of expectations” updates.
It has two major divisions: Aerospace and Flexonics. If you’re not sure what that second word means (neither am I!), here’s the description from Senior:
For a three-minute YouTube video showing what one of the companies in the Flexonics division does in its factories, see here.
Why does it matter? Well, the Flexonics division has outperformed at the end of FY 2022, while the Aerospace division is in line with expectations.
Therefore, group adjusted PBT for 2022 is now expected above the top end of the range of consensus expectations. This range of expectations is £16.2m - £18m, so adjusted PBT will be somewhere north of that.
Here’s the explanation of the outperformance:
Trading in the Flexonics Division has been ahead of previous expectations, driven by strong customer demand in the land vehicle and power & energy markets. In particular, demand for heavy duty truck and the levels of maintenance and overhaul in power & energy have improved since the last trading update.
My view
There’s very little else contained in this update, so it’s time to wrap this up.
Senior has been around for a long time - ninety years - and was first listed on the LSE in 1947. Can anyone confirm if it has been listed continuously since then, without interruption? That would surely make it one of the longest-listed companies!
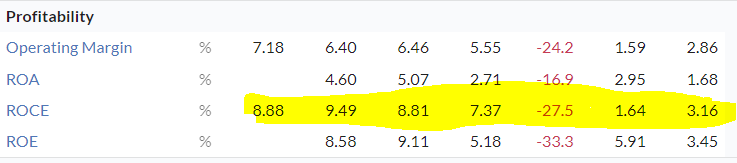
For as long as I’ve known of Senior, it has been considered a decent defence stock. I note that on their homepage, they are advertising a target ROCE of at least 13.5% over the medium-term.
However, their StockReport would suggest that this is not a target they’ve hit recently:
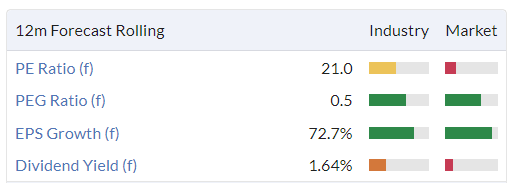
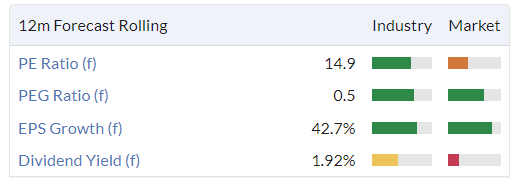
For me personally, aerospace and defence stocks tend not to have the quality characteristics that I’m looking for, and Senior is no exception to that. But for those who do invest in this sector, Senior is possibly one of the higher-quality companies, which is reflected in its premium rating:
There’s also the small matter of geopolitics and the tailwind that the current environment might produce for demand in this sector. It’s grim when you think about it, but maybe defence stocks are going to be a profitable bet for the next few years?
Accrol group (LON:ACRL)
Share price: 30.8p (+5%)
Market cap: £98m
This tissue paper company has a complicated past which was summarised extremely well by Paul in November.
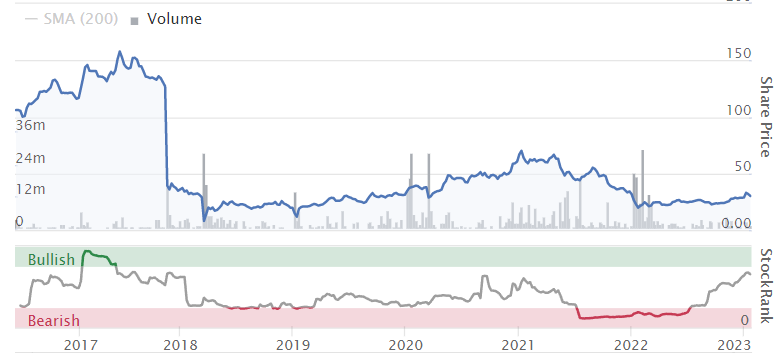
Since expectations were normalised in late 2017, the stock has traded within a range:
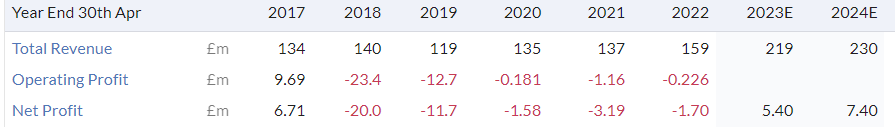
The reported numbers have not been very good but it is now expected to turn a profit again:
Let’s see the highlights from these interim results to October 2022:
Volumes up 14% vs. market up just 1%, i.e. market share growth (as noted by Paul, Accrol’s cheaper products do well in a consumer downturn).
Adjusted net debt £30.5m in October 2022, on track to reach a net debt/EBITDA multiple of <1.5x by the end of the financial year.
On track for revenue of £230m and adjusted EBITDA of £15.5m in this financial year, which are marginally ahead of expectations.
The prior expectations were revenues of £219m and adj. EBITDA of £15.0m.
I should note that despite Accrol reporting adj. EBITDA of £7.1m in H1, it actually made a statutory loss before tax of £0.9m.
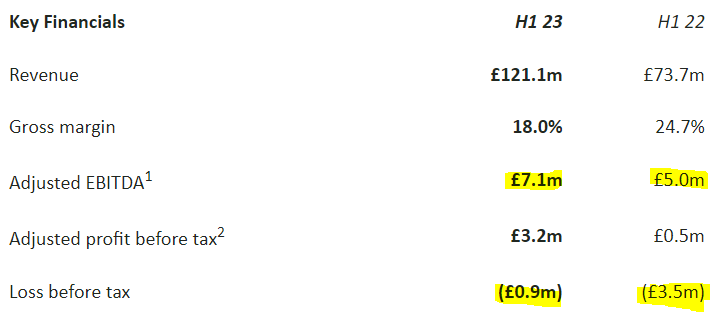
You can see that in H1 2022, the difference between adj. EBITDA (£5m) and the loss (£3.5m) was £8.5m.
In H1 2023, the difference is £8m.
These are big numbers between adjusted and statutory results for just a six-month period, for a company valued at less than £100m.
Therefore, if you are valuing this company on the basis of adj. EBITDA, then in my opinion you are at risk of wildly overvaluing it.
Included within the adjustments are share-based payments, worth £0.6m in H1 2023 and also £0.6m in H1 2022. It always strikes me as odd that management don’t consider these to be “real” or “underlying” costs, since they are simply a method of remunerating staff.
Outlook
The Group is well invested with adjusted net debt on track to be less than 1.5x EBITDA by the current year end (FY22: 3.0x). The Group's margins, which were impacted by the time-lag on price increases, are recovering in H2 FY23 and we are confident that this recovery to continue [sic] throughout FY24.
Strategic Review Outcome - Build a Mill
In a separate RNS, Accrol states its intention to build its own paper mill. This is not expected to cost more than £10m, will be operational by mid-2025, and will produce 40% of Accrol’s needed volumes.
Benefits of the mill will be 1) “reduced volatility in tissue input costs… providing greater customer pricing visibility and certainty”, and 2) “enhanced security and visibility of tissue supply, which will reduce working capital requirements in the UK tissue conversion business”.
My view
Let me compile a list of bull and bear points.
Bull points.
The company is in an economic sweet spot right now, as consumers trade down to discount brands to reduce their cost of living.
Has succeeded in passing on “significant price increases”. While there is a lag between input cost inflation and sale price increases, Accrol does appear to be very capable of passing on price increases.
If the plans to build a paper mill are realistic, the benefits should be significant and should reduce the risk of very sharp, unpredictable input cost increases for the tissue business (of course the paper mill will have its own raw material, energy and electricity costs, and these will need to be managed).
Bear points.
The company’s heavy focus on adjusted EBITDA leaves me feeling uneasy. As Buffett is supposed to have said: “Does management think the tooth fairy pays for capital expenditures?” Adjusted EBITDA hides depreciation, share-based payments, and even product development costs and software costs.
The company is still loss-making as of H1. According to a broker note I’ve found this morning from Liberum, the full-year result expected this year is for another reported loss.
The debt load is still a consideration, e.g. enterprise value is currently c. £130m. Another up to £10m will be needed to build the new paper mill.
In summary, I’m going to take a negative view on this stock because I can find little evidence of any quality in it, I don’t like the way it presents its figures, and its true rate of profitability seems poor.
City Pub (LON:CPC)
Share price: 73.63p (-1%)
Market cap: £76m
Let’s take a quick look at this trading update for Q4 and the full year ended 25th Dec 2022.
Trading in Q4 delivered accelerated LFL sales growth compared with 2019 of 7.8% as a result of improved planning to maximise revenues from events such as the World Cup and Christmas. The performance would have been even better, had it not been for the rail strikes, especially those towards the end of the year, where we estimate lost revenue to be in the region £0.75m (c. 3.5% of revenue for Q4).
Swings and roundabouts: the World Cup helped revenues, while rail strikes hindered it.
Performance of the “core estate” in 2022 was in line with expectations, with like-for-like sales 3% higher than 2019.
The first four weeks of 2023 are better: like-for-like sales are ahead of expectations and 25% higher than early 2022 (which was impacted to some extent by Covid).
Acquisitions - I find comfort in this statement:
…the Company has, particularly at this stage in the cycle, very strict criteria for acquiring pubs as we expect pub prices to continue to soften.
Nevertheless, two pubs have been added to the estate.
Net debt is low at £5m. The company has a “predominately freehold estate”, so rents shouldn’t be an issue.
My view
If I was investing in a pub group, I’d probably choose something with freehold properties, like this, since owning the freehold dramatically improves the worst-case outcome!
This share looks like it might be priced about right, given the low-risk nature of its property ownership and asset backing.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Smiths News (LON:SNWS) you could well be right donQ that too many traders could not resist selling. I still think this is a very sound share with a great Divi so I am going to hang on.
Smiths News Smiths News (LON:SNWS) fell over 8% today which I am struggling to get my head around. I hold. Could it be the lack of actual numbers in the Trading Update which caused some to sell?
Agreed re Smiths News (LON:SNWS) - I hold - what would have happened if it wasn’t in line with expectations? Still, a good little run, hopefully it rebuilds. Solid. Sound.
Don't forget the share price of Smiths News (LON:SNWS) changed from 27p to 59p (118%) in less than 4 months! Extreme move without any special news, I guess many PI thought that's a perfect time to take some profit.
Investegate |Carnival PLC Announcements | Carnival PLC: Cunard sees strongest start to Wave in the last decade
As Saga (LON:SAGA) is in the news today i thought this worth a read . From 3.00pm today .
Totally (LON:TLY) down c 10% - due to https://www.hsj.co.uk/quality-and-performance/ics-cancels-four-urgent-treatment-centre-contracts-after-performance-concerns/7034101.article
Coincidentally, yesterday - Employee Benefit Trust share sale - Further to the announcement made by the Company on 10 January 2023, Totally plc (AIM: TLY), a leading provider of frontline healthcare services, corporate fitness and wellbeing services across the UK and Ireland, announces that it has been notified by Apex Financial Services (Trust Company) Limited, the trustee of the Totally Employee Benefit Trust (the "EBT"), that the EBT has sold a total of 1,384,671 ordinary shares of 10 pence each in the capital of the Company ("Ordinary Shares") at an average price of 32.8 pence per Ordinary Share on behalf of Wendy Lawrence (Chief Executive Officer), Lisa Barter (Chief Financial Officer) and Gloria Cooke (former Clinical Quality Director) (the "Award Holders").
Absolute shambolic behaviour! Why is it that management can sell first before shareholders?
Totally (LON:TLY)
Why do you want to sell at all? As far as I can see all that is happening is that 4 contracts, that were previously extended, have simply come to their natural conclusion??
Graham, thanks for your Accrol group (LON:ACRL) comments.
Just to add the forecasts for FY 23 including aPTP & aEPS, which have been upgraded:
Revenue £230m.
Adj EBITDA £15.5m.
Adj PTP £7m
Adj EPS 1.8p
As you say, the outcome of the strategic review includes the plan to build its own paper mill, which will be funded through cash or debt.
We have a webinar with management this Friday 27 January, 12.30. With a Q&A which always tends to be fairly lively. Register: https://bit.ly/ACRL_H123_results_webinar
There will be a video recording afterwards which I'll post on Stocko.
Bango (LON:BGO).
FY REV $32.9m up 59% on 2021 and slightly ahead of expectations of $31.1m. H1 rev was only $10.8m so H2 $22.1m. This is also notable as BGO accounts in USD which has been quite a headwind. BOKU FY rev was up 1% so a significant difference.
ARR now $5m and 5x compared to Dec 2021.
EBITDA in line. Gross margin temporarily down to 80% due to increase in Audience revenue and also DOCOMO acquisition as clients transfer to BGO platform . GM to return to over 90% in 2024.
Transformational DOCOMO Acquisition 31st August progressing well. Almost doubles 2022 EUS and brings many new clients and routes producing a halo effect. DOCOMO acquisition of largest direct competitor in Japan (big market for DCB) makes Bango the only real option there. Many new and deeper conversations.
Bango generate their own cash which they are investing in their platform so it can cope with increasing growth and also people. They don't need to raise money.
I hold so biased.
WANdisco (LON:WAND)
Having worked in IT starting in 1970, I was curious and I did a lot of digging into WANdisco (LON:WAND) years ago. I decided all the good news was already baked in. The company name derives from Wide area network distributed computing and they have changed their target audience a couple of times but now concentrate on migrating customers to cloud computing. Not just storing data in the cloud but also using the compute power and communications. Web based data providers and users communicate directly to AWS et al and the on premise part shrinks to being the equivalent of a remote user once migration is complete. The intervening part is where Wand come in. There must be built into the software that runs on the cloud system and the on premise system some means of recording which data has been copied across to the cloud and whether it has changed since copying in the same way that Backup programs save time by not copying data that hasn't changed. Eventually (and depending on internet bandwith that could be some time) all the data is on the cloud server and all applications using that data are on the cloud server. Answer to how it's done is probably slowly, and probably frequently changing data done first (with a database I would guess there would be additions but not changes)
My question is are there presently enough big data customers to migrate to keep wand busy enough to repay an investment. Future big data imho will go straight to the cloud anyway, their ebullient CEO has sold about £5M worth as shown on Stocko so doesn't inspire me. I don't think in its present form it has a long future but it seems to be suggested, nudge nudge wink wink, that it could be the next Microsoft or Arm so get in early. Sit by the door ready for a sharp exit when the bubble pops imho.
Thanks for that info. on WANdisco (LON:WAND, I can't see the £10m director sale on Stocko, what date was that on?
There are plenty of share options, one was over £20m, seems excessive to me.
Sorry I remembered that wrong, it was the total of all his sales amounting almost £5M which as some would be to pay income tax on the options is perhaps not such a red flag. I've edited my original post.
WANdisco (LON:WAND) I traded them a bit a few years back and made some decent money but then realised that whilst the product is good it will take a long time for this to translate into significant revenues let alone profitability.
I am kicking myself as I thought they had good momentum at around the 360p level but didn't buy any so am a bit annoyed up at 1100p which has been more or less a straight line!
However, that said I think a $900m market cap is hefty. They have $24m of revenues and an order book of some $130m so thats 35* sales or 7* the order book value. Wow!
This one is indeed a difficult stock to comprehend but clearly there are guys out there who have decided it's worth paying mega money to use their 'cloud' services - or they would have gone elsewhere. If it is not a worthwhile service - then word would quickly have got out and their impressive list of partners (see their website) would have pulled out. The list of major shareholders is also intriguing - not the usual fund managers but names I have never come across - although I am aware that CRUX do hold in both their UK funds - but probably less than 1%
Any thoughts on the reason for jump in price of Accsys Technologies (LON:AXS) - up 15% today (I hold) or should by now be oblivious to such wild swings in price - esp for shares that have suffered
Whoops - its already come back to a mere 10% rise!
There was a heavy sell-off earlier on bad news - delays to completion of the new plant in Hull - it may just be response to the fact that no one is selling any more. Or possibly some ingenious individual has been counting lorries at the main plant in Belgium - who knows? I believe most of the stock here is in the hands of investors taking a long term view, so I see the volatility as normal. I hold.
Sureserve (Sure)
Good numbers again .
Good to see margin up from 5.7 to 6.1%, still low and they need to keep nudging this upwards.
23 million cash leaves them well placed for complimentary acquisitions, looks like their last acquisition is doing very well .
Great order book and great long term contracts .
Basically all very good .
It is on the cheap side for sure and I think will be a long term slow burn winner but cant see how it is going to rerate short term unless they sell off one if the 2 non core businesses that are up for sale.
Does anyone know what these 2 businesses are ? If they were sold for a chunk of cash then that would put a big wedge onto their cashpile ?
One of my major holdings but not exactly fireworks, though that is probably a good thing .
Note 6 of the financial statements confirm it's Sureserve Fire and Electrical Limited and Precision Lift Services Limited businesses, the rationale being they want to "drive growth from within their specialism of social housing energy services."
It looks like they generated revenue of £34m but LBT of (£1.6m), so presumably their sale would increase margins.
I've only started doing research here. Similar to a previous update from Graham, it does seem like a reasonably unremarkable business, albeit operating in a sector which should see growth over the next decade as the public sector lurches forward with their transition to cleaner energy, better energy solutions etc. As these results prove - it's a nicely resilient sector.
I watched an interview with Peter Smith (CEO) 6 months ago where he came across as down to earth, driven and refreshingly honest/transparent (it was a 60min career development interview internally where I work) which got me interested in the company.
As you say, they seem good value - and presumably is the sort of biz that, when they've sold their assets held for sale and acquired businesses which align with their strategy, they could/should start paying divis.
I've bought a small initial position today to help make sure I keep a closer eye on them!
A quick look at those companies at companies house last accounts I can see
Fire and Electrical - turnover 19 million , 2.5 million assets , 2m profit
probably 8-10 ,million ?
Lift Services - 8.5 million turnover , 1.3 assets , not a lot of profit
probably 2-3 million ?
Both pretty uninspiring fire and electrical looks ok for the right buyer, lift services looks a bit of a dog .
Yes, though I presume 2021 figures are on companies house. Note 6 suggests that - combined - they generated sales of £34m and LBT of (£1.6m) in 2022.
I agree with your points. Many competitors in both areas. Better to strategically focus where you can take market share.
Personally having to fight hard the urge to get a little bearish but this is mainly due to the US - UK market looks good - as does Sterling. V good piece today from J Authers re Leading Economic Indicators and difficulties in relying too heavily on this as a directional signal.
A word on discounts. Generally speaking we all love a discount - the idea of something for nothing. In investing they do tend to persist and so it is more useful to focus on the underlying. Never the less ... a large discount ... say 40% ... means you pay 60p in the £....which is great but the return on the way back up is 66%...and therefore leads to the question of what may drive this?
Two factors that could help would be a promise from the company to return the £.... and/or the £ rises...driving buying. Which leads me to Navient (NSQ:NAVI) which reports earnings tonight. E Bramson has a seat on the board and will be pushing them to improve prospects. Most likely reducing costs and returning excess capital. Shares in Navient have been steadily rising which I put down to increasing investor confidence in the interest rate cycle. The co has already been talking positively about costs. Further to previous posts I highlight Sherborne Investors (Guernsey) C (LON:SIGC) ... which is the Bramson activist vehicle. Its only investment is Navient (NSQ:NAVI) and current NAV is c80p... compared to the share price level of 50p.
I own Sherborne Investors (Guernsey) C (LON:SIGC) and am "hopeful" that Navient (NSQ:NAVI) have positive news tonight although I concede that "normally" reporting days have been pretty mixed. Turnaround isn't easy but success is more about execution than market backdrop which is why I lean towards it. Fingers crossed job.....
All the best during this positive first month of the year.
Sureserve (LON:SUR) Good results today. Seems to tick many boxes. Paul, could you review?
Didn't your mother teach you to say 'please'?
And thank you, along with a lot of other things like don't leave your football boots in the boot bag going moldy :)
...or teach you how to spell mouldy ;)
Microcap LON:VEL (£23m market cap) results for 31 October year end out today. (I hold)
Finally recovering from the pandemic as booming aerospace and defence sector OEM growth cascades down. I was impressed with how tightly this company's finances were managed during really tough times.
Today they issued a positive FY23 outlook "We have contracted UK and US business which, when in full production (at current OEM run rates), will significantly increase revenue, several times the FY22 level."
I think this is an exciting innovative UK engineering company with strong commercial prospects, underwritten by some long term contracts. They also provided links to Boeing and Airbus production forecasts:
www.boeing.com/commercial/market/commercial-market-outlook and www.airbus.com/en/products-services/commercial-aircraft/market/global-market-forecast
InvestorMeet Company presentation at 10am today.
https://www.investormeetcompan...
Thanks Cuddlesticks for bringing Velocity Composites (LON:VEL) to my/our attention. Not a company that I have come across before. The IMC presentation has encouraged me to do some research albeit the company is a bit smaller than my usual area of interest.
Cheers
Mark
Good morning all. Is anyone interested in Yu (LON:YU.) ( I hold ) it is specialist supplier of energy and utility solutions, similar to Telecom Plus, but for UK businesses. A good Q4 update this morning. Probably in a decent sweet spot at the moment.
Henry Boot (LON:BOOT)
An acceptable failure here ref miss in expectations - 1 profits are obly slightly below expectations and 2 its with regard to reduction in investment portfolio values - perhaps company could have predicted falls but no biggie.
Despite the slightly below expectations that a record year of underlying profits deliver - well done peeps as many other moan "we cant get labour for love nor money"
This company has an ultra conservative balance sheet and accounting methadology so is much better placed than most (imho) to tough it out in tough times. Having said that net debt is creeping up a bit- their balance sheet is awash with proper assets though and alot of their"profits" dont show up in the system till completion. Higher net debt should come with matching higher asset value - as an example tehir homebuilding side expects to go from 200 units per year to 600 the next few years , hard to do that without a bit more debt on the books.
I am happy to keep plodding along here picking up my divi and knowing that each year the "book value per share" is increasing nicely.
My morning smallcap tweet: Quantity Street
WANdisco (LON:WAND) Staffline (LON:STAF) NAHL (LON:NAH) Robinson (LON:RBN) Fireangel Safety Technology (LON:FA.) Artisanal Spirits (LON:ART) City Pub (LON:CPC) Deltex Medical (LON:DEMG) Henry Boot (LON:BOOT) Aptamer (LON:APTA) Norman Broadbent (LON:NBB) Accrol group (LON:ACRL), Pebble Beach Systems (LON:PEB), Saga (LON:SAGA), M&C Saatchi (LON:SAA), Bango (LON:BGO), Eleco (LON:ELCO), Brand Architekts (LON:BAR), Ceres Power Holdings (LON:CWR), Aptitude Software (LON:APTD), Smiths News (LON:SNWS), Netcall (LON:NET)
◄WANdisco (WAND)► $9m industrial and consumer goods contract win. [SP=1055 Cap=707m]
◄Staffline (STAF)► guides FY-Dec flat. U/L op profit marginally ahead, and cash flow substantially ahead of market expectations. [SP=33.05 Cap=55m]
◄NAHL (NAH)► guides FY-Dec rev up 7%, pretax £0.6m ahead of market expectations "due to lower than expected profit attributable to non-controlling interests in our LLPs, offset by an increase in borrowing costs due to higher UK interest rates". [SP=34.8 Cap=16m]. I hold.
◄Robinson (RBN)► guides FY-Dec rev up 10%, 1% organic but U/L volume down 10% due to "changes in consumer behaviour, delisting of certain products by our customers and overall reduced customer demand". Adj op profit in line. Expect further property sales in Chesterfield in 2023 and 2024. [SP=93.9 Cap=15m]
◄FireAngel Safety Technology (FA.)► guides FY-Dec rev up 32%, adj pretax -£2.1m (-£3m). Outlook confident. [SP=8 Cap=14m]
◄Artisanal Spirits (ART)► guides FY-Dec rev up 20%, slightly ahead of consensus of £21.6m. Profit? "Continued recovery in UK member venues and events: sales now seeing the benefits of more normalised trading conditions with a record December". Outlook in line. [SP=86.5 Cap=60m]
◄City Pub (CPC)► guides FY-Dec rev up 63%, in line. LFL up 3% on 2019. That's poor given 3 years' inflation. Outlook: Jan LFL up 25% and above expectations.. [SP=73 Cap=76m]
◄Deltex Medical (DEMG)► guides FY-Dec rev up 10%. Cash at hand £0.5m. "Continuing to work on securing a small number of substantial orders within its International division." [SP=1.34 Cap=9m]
◄Henry Boot (BOOT)► warns FY-Dec pretac slightly below market expectations due to year-end valuation movements in investment portfolio. Expects this FY to be more challenging. [SP=242.2 Cap=329m]
◄Aptamer (APTA)► wins two new fee-for-service contracts initially worth over £500k. [SP=39.9 Cap=28m]
◄Norman Broadbent (NBB)► guides FY-Dec Net Fee Income up 27% and EBITDA c.£100k (-£300k). In line? [SP=3.19 Cap=2m]
◄Accrol (ACRL)► Paper profits. H1. Guides FY-Mar rev and adj EBITDA marginally ahead of expectations at £230m and £15.5m respectively. Also outcome of strategic review. Will build a paper mill. Cash cost not above £10m funded out of free cash flow, existing banking facilities and or banking finance, whichever is most appropriate at the time. Will resume dividends as soon as is practicable. [SP=29.25 Cap=93m]. I hold.
In line: PEB, SAGA, SAA, BGO, ELCO, BAR, CWR, APTD, SNWS, NET
Morning All,
Sure Ventures (LON:SURE) excellent finals this morning, a beat on earnings and PBT. 15.6M PBT against a market cap of 140M looks cheap to me!
Sureserve, not sure ventures
Artisanal Spirits (LON:ART) - sales and membership growth drives momentum, new CEO.
Sustained growth in both sales revenue and membership numbers drove overall momentum for the Artisanal Spirits Company (ASC) in FY2022. The company is well placed to deliver results in line with expectations and achieve further growth in FY2023, under the new leadership of Andrew Dane as CEO, announced today. Sales revenue for the year ended 31st December 2022 increased by approximately 20% from £18.2m in FY2021 and is expected to be slightly ahead of our £21.6m forecast when the full audited numbers are announced in March 2023. A 12% increase in global membership numbers to around 37,000 drove the business forward. In our view, ASC’s valuation continues to look attractive, especially considering the amount of owned maturing whisky stock (i.e. £445m at nominal value). We reiterate our 150p Fair Value for the shares. Full details in our new note: https://www.equitydevelopment....
Sureserve (LON:SUR) Final results today Shore Capital say its a 16% beat PBT on their estimates.
Saga (LON:SAGA) says load factor for 23/24 cruise bookings currently 60% which they describe as 'strong'. But last year they said '86% for first half, 73% for full year' for 22/23 forward bookings.
Did people book early/carry over pandemic bookings last year (quite.possibly), is the cruise business suffering, or maybe a combination of the two? Or have I misread?
I looked back at 2019 & 2020 Jan uodates and they used a different metric then so I am not sure if it is comparable. E.g. in Jan 2020 they said 'We have [cruise] forward bookings for 2020/21 of 76% of full year target levels'.
I would certainly be interested in Pauls view on Saga (LON:SAGA) as like Patrick I am not sure what all the data is telling me. Words seem positive about travel returning, post COVID. I am also wary of the various debt covenants which seem to be varied with revisions to the Revolving credit facility. I will await the update from analyst presentation this afternoon before buying further or exiting.
Greyster
The covenants relate to the revolving credit facility. It is undrawn so zero surprise Saga (LON:SAGA) have wanted to amend terms.
Why? - because my guess is that the plan to sell the underwriting business is also linked to this. It appears to me that the financing strategy is to realise capital from that, combine it with the cash, generate £70m of operating cash inflows over next 2 years to broadly eliminate the risk around repayment or refinancing of the two sets of bonds. £150m is due in 2024 and the £250m is 2026. So cash+asset sale+free cashflow should equate to circa £300m meaning that just a £100m bond refinance in a couple of years would be needed and that shouldn't be difficult to achieve bar any big lurches down in business. That would then leave them with the cruise ship debt, which absent of any new covid type catastrophe, will then be paid down similar to a mortgage from cruise operating profits.
By removing any burdensome covenants on the RCF they can use all their cash for bond repayments and debt reduction and still leave themselves with headroom on working capital.
From the interims below........ see how that fits into the narrative I think is playing out. Remember what Saga (LON:SAGA) don't want to have to do is put a going concern note in the accounts if they haven't got fully financed plans to repay the £150m 2024 bond 12 months out. Looks like they've now achieved that.
The amendments to the RCF include:
-- removal of the condition that the facility is terminated on 1 March 2024, should the 2024 bond not be repaid by that date ; and
so they've swapped liquidity and bond linkage terms for a reduction in an undrawn facility.
Note : 2024 bonds are now trading at around 94 and 2026 are around 81, both up considerably over recent weeks with the latter yielding around 14% and neither no longer pricing in any real default risk.
That is excellent work DJ, thank you.
Btw I noticed the Civil Aviation Authority has published a consultation this morning on plans to move to separate customer monies from cash used to finance operations for holiday companies. I don't know if or how that affects Saga but probably another thing to look at. On Beach group (LON:OTB) already does this so is well placed.
Saga (LON:SAGA) already do it. they were one of the first I believe
Thanks!
I have just watched the capital markets presentation Saga (LON:SAGA) did today. Struck by the extent to which they aim to change the nature of business over the next 5-10 years, with huge plans for media (a destination website etc) with customer analytics etc. Clearly a very ambitious and enthusiastic team, but can they pull it off? No reason why the travel and cruise businesses can't take off again, after the exceptional circumstances of the last few years, but not sure about scale of the media business they say they are aiming for.
I contacted City of London Investment (LON:CLIG) to help me better understand the reasons for a reduction in EPS, and was delighted to receive a detailed response from this company, which always seems to be shareholder friendly.
In summary, FUM and therefore billings were down during the six months, but have now mostly recovered. A dollar sterling change helped compensate. I would guess that in the next six months the opposite will happen; FUM up but a reduction in dollar earnings.
Various expenses such as bonuses and post acquisition items were up. FX increased costs. This is a little disappointing. The merger/acquisition should add value and not lead to lots of transatlantic travel.
My view is unchanged, this is a high yield, negligible growth stock at this stage. The target EPS looks achievable. I hold.
Thanks for this update. Its bad that City of London Investment (LON:CLIG) did not include that information themselves yesterday rather than having to respond to a question.
I think that we should expect detailed results on February 22nd. Last week was a pre close statement, which is always quite brief.
I can't see any news yesterday from CLIG did I miss something?
It was Friday (20th)
thanks