Small Cap Value Report (Tue 24 Oct 2023) - SCS, RQIH, CABP, FDP

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
It's all kicking off today! 1 takeover, and 2 profit warnings here -
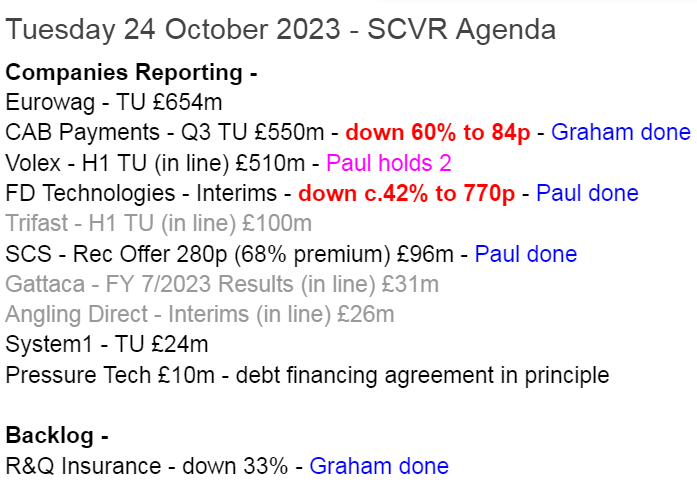
Summaries
SCS (LON:SCS) (Paul holds) - 169p (pre-market) £57m - Recommended cash bid 280p - Paul - GREEN
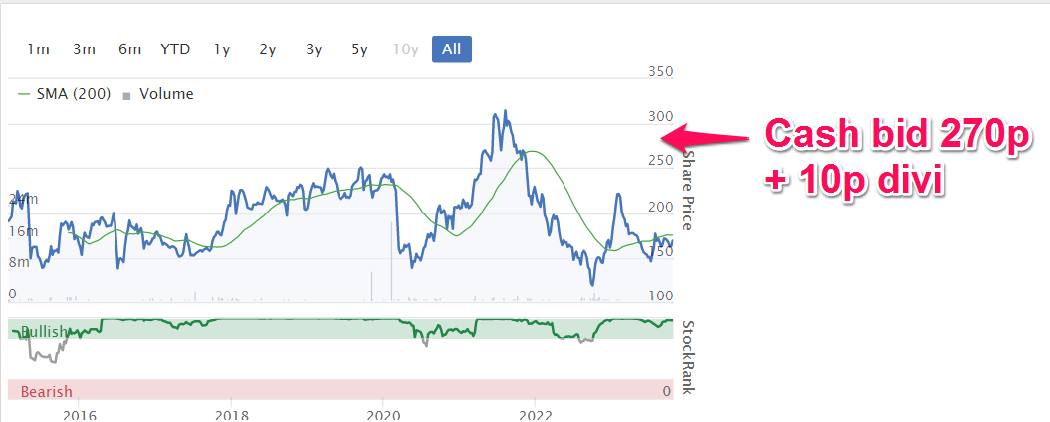
One of our favourite value shares here, with SCVR reports 5 times on it this year, always GREEN, and it was a mystery share in August. An Italian furniture retailer has offered a generous 66% premium, 270p bid + 10p divi. As we've mentioned here before, SCS has been a sitting duck for a takeover bid, due to its large cash pile, allowing a bidder to almost buy the business for free (using SCS's own cash pile). Not sure why it took so long for someone to act, but shareholders are rewarded nicely today.
R&Q Insurance Holdings (LON:RQIH) - down 52% yesterday to 24p (£90m) - Proposed Sale - Graham - AMBER/RED
I’m taking a neutral stance as the proposed sale of a subsidiary should take insolvency off the table. But shareholders will be left with a complex and in recent times highly unprofitable legacy insurance business. This one is difficult to analyse and perhaps best avoided.
Cab Payments Holdings (LON:CABP) - down 60% to 86.2p (£219m) - Q3 update (profit warning) - Graham - AMBER/RED
Having floated in July and posted a positive outlook in September, this FX company has materially downgraded revenue expectations and says the lost revenue will flow directly to the bottom line. IPO investors may feel hard done by but we’ve seen this many times before.
FD Technologies (LON:FDP) - Down 40% to 788p (£218m) - Interim Results (H1 to 8/2023) - Paul - AMBER/RED
I'm not familiar with this company, so it took me quite a while to realise that it's not my cup of tea at all. Looks like the fancy valuation might be down to excitement about AI, and it is generating very good ARR growth from the loss-making KX division. With a weak balance sheet, customer caution, and negative cashflow, I don't want to get involved in this.
Paul’s Section:
SCS (LON:SCS) (Paul holds)
169p (pre-market) £57m - Recommended cash bid 280p - Paul - GREEN
Marvellous news here for shareholders (I hold a small position).
Yet again we’re provided with more evidence that UK small/mid caps are too cheap, with another takeover bid. The bidder seems to be an Italian trade buyer, Poltronesofa, which retails Italian-made furniture from 300 stores, mainly in Italy and France.
Price is a healthy 66% premium to last night’s closing price, and is 270p + 10p divi, so 280p in total. That’s a fair price in my view, and a good premium, so I imagine shareholders are likely to gratefully accept this deal.
Results for FY 7/2023 are being published tomorrow, so we’ll be able to double-check these numbers against the takeover price.
Paul’s opinion - we’ve been saying here for as long as I can remember that ScS was an obvious sitting duck for a takeover bid, because a bidder could pay for the acquisition using ScS’s own cash pile, and a small amount of new debt. Today’s announcement mentions this point specifically -
… the failure of investors to properly value ScS's cash resources.
A complete no-brainer. So the only question is, why has it taken so long?!
Well done to subscribers here who either sold out at the top in 2021, or were patient, and rode out the last 2-years mispricing of this share by the stock market.
I see that current dividend yield (before factoring in the bid premium) was a remarkable 8.3%, so the only downside of this deal is losing a big dividend income. Still, at the takeover price, the dividend yield reduces to 4.9%, so you could easily reinvest your proceeds at a better yield without too much searching.
A much-needed morale boost, not just to ScS shareholders, but also to everyone holding small caps, as it’s mounting evidence that the UK market is mis-priced to the downside. That means a bull market is coming, timing uncertain, and lots of future profits to be had potentially, I reckon.
FD Technologies (LON:FDP)
Down 40% to 788p (£218m) - Interim Results (H1 to 8/2023) - Paul - AMBER/RED
Since it’s collapsing in price, I just assumed this must be a 2021 float. Actually not, it’s been listed for many years, and used to be called First Derivatives. We last looked at it here 5 years ago (Graham). I know literally nothing about it, so this is going to be a long haul to try to work out what’s going on.
Not helped by an opaque description of its activities, so I’ve bolded some key words, and reorganised the layout below -
About FD Technologies
FD Technologies is a group of data-driven businesses that unlock the value of insight, hindsight and foresight to drive organisations forward. The Group comprises -
KX, which provides software to accelerate AI-driven innovation;
First Derivative, providing consulting services which drive digital transformation in financial services and capital markets; and
MRP, which provides technology-enabled services for enterprise demand generation.
FD Technologies operates from 14 locations across Europe, North America and Asia Pacific, and employs 2,800 people worldwide.
Clear now? Not really, no.
Divisional commentary - summarised by me -
KX - performed in line with expectations in H1. Growing strongly, with “significant H2 pipeline providing confidence” of hitting +35% target growth in ARR - impressive, this part of the group sounds fine. Mentions AI a fair bit. KX is expanding quickly, but sounds like this is being driven by losses -
KX to achieve free-cash EBITDA breakeven by FY26 and margin of 20-25% by FY28
First Derivative - revenue down 1%, and similar result expected in H2. Customers being more cautious. Efficiency measures taken. “Evidence of improvement in pipeline” for next year (FY 2/2025).
MRP - sounds in line with expectations, but revenue down a lot, and it didn't even manage a positive adj EBITDA in H1, well down on last year. So this looks a problem division, but it's small.
Overall performance - it’s going to take me too long to analyse each of the 3 divisions, so let’s get to the H1 group results. Oh, it’s loss-making -
Revenue £142.5m (down 3%)
Loss before tax £(4.5)m (H1 LY: PBT of £1.1m), so a significant deterioration in performance this year.
Net bank debt flat at £7.2m
Outlook - here it is in full - I wouldn’t call H1 “resilient” personally, I think it’s weak, but anyway, here’s what the company says -
The Group delivered a resilient performance in H1, with good progress in KX and challenging market conditions in First Derivative and MRP. The growth in our KX pipeline, driven by our partnerships with CSPs and the recent launch of KDB.AI, provide confidence in achieving our target of at least 35% growth in ARR for the full year.
In First Derivative, we anticipate similar market conditions through H2 with the efficiency measures taken to date mitigating the impact on adjusted EBITDA, resulting in an H2 revenue and EBITDA performance similar to H1.
In MRP we continue to expect to deliver an adjusted EBITDA similar to last year.
At the Group level we expect FY24 revenue to be in the range of £285m to £295m. The additional investment in KX announced today is expected to result in a £9-10m impact to adjusted EBITDA in H2, resulting in FY24 adjusted EBITDA in the range of £24m to £26m.
Looking beyond the current year, we are pleased with the progress and momentum across the Group, particularly in KX where the partnerships with CSPs and launch of KDB.AI provide confidence in the medium-term outlook to accelerate our industry-leading growth rates.
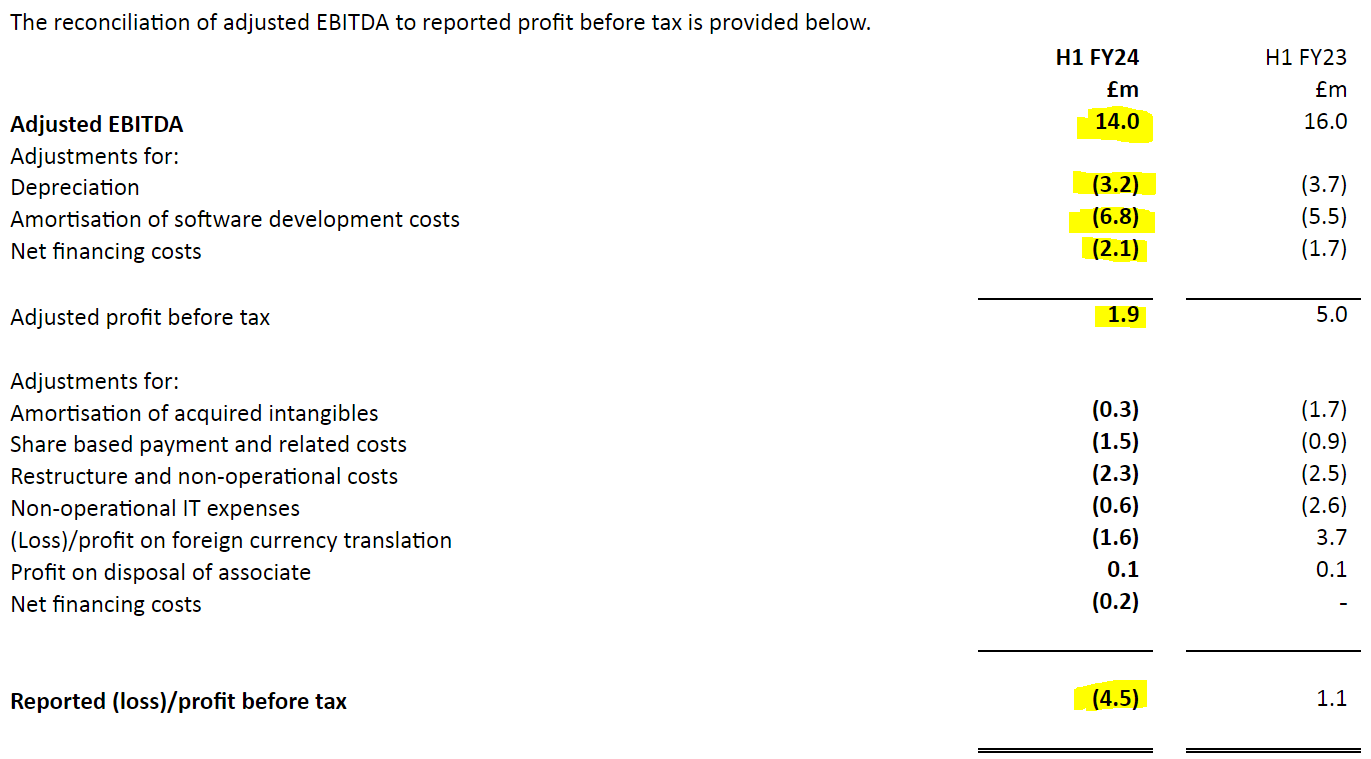
Adj EBITDA of £24-26m for FY 2/2024 might sound good, but it’s not real profit. Note how in H1 adj EBITDA of £14.0m turned into a PBT loss of £(4.5)m, a yawning gap of £18.5m, just in H1. Double that for the full year, and it suggests £24-26m adj EBITDA might result in a pre-tax loss of about £(12)m.
This reconciliation below shows that £14.0m H1 EBITDA is total fantasy, and can be ignored. Even the £1.9m adj PBT is stretching things, so in my view, the £(4.5)m loss before tax is the most realistic measure of performance.
Balance sheet - i.e. is it going to run out of cash?
This looks weak to me. NAV of £188m includes a huge £177m of intangible assets, so only £11m of NTAV - ie no asset backing to speak of.
Receivables looks high at £73m.
Lease liabilities are combined with bank debt, note 9 separates them. A fresh £30m bank loan was drawn down in the period, and partially offset by £23m of cash, hence the £7m net bank debt. I don’t like companies increasing borrowings, when their profit has gone into reverse.
It should have much more cash, given that customers have paid £36m up-front (deferred income creditor).
Cash generation - is negative, once the huge capitalised development spending (£13.7m in H1 alone) is taken into account. It sounds like they’re going to increase this “investment” further in H2.
My opinion - I don’t understand what the company does, but I very much understand that these are not good numbers.
This company is loss-making, and cash-burning. Therefore I cannot possibly value it on conventional metrics. EBITDA is total nonsense, due to the large amounts of payroll being capitalised onto the balance sheet, so that’s no good.
There’s not much asset-backing, and I don’t like the significant gross bank debt, considering it should be in a net cash position, due to clients paying a lot up-front.
So it’s a thumbs down from me.
It’s not a basket case though, so I’ll be kind, and go with AMBER/RED.
Shares like this often come with fancy valuations, due to optimism about the future. The danger with that, is that in economic downturns and bearish stock markets, the gloss can very easily vanish, and lead to a plunging share price.
The price has been gently recovering somewhat this morning, after the big initial 40% drop, now down about 31% (at 12:28).
It looks to me like an exciting, but loss-making growth company, KX, strapped to a mature business that does seem profitable, but is struggling to grow (First Derivative). So overall, this share doesn’t excite me at all. Although KX looks like the kind of thing the Americans might decide to buy at a wacky valuation.
These type of businesses look to be in the firing line for clients retrenching, so it’s a bad sector right now I think. More bad news to come, I wonder? Why get involved? If any readers are more positive, and have researched the company in more detail, then tell us what I'm missing!
Graham’s Section:
R&Q Insurance Holdings (LON:RQIH)
Share price: 24p (-52% yesterday)
Market cap: £90m
This stock saw a nasty fall yesterday in the aftermath of an announcement released on Friday evening (after the close).
This company has a complicated backstory: I discussed it here in August 2022. There was a bid for RQIH at 175p per share which fell through, and it emerged that the company needed additional funds. They ended up raising about £100m at a share price of 105p.
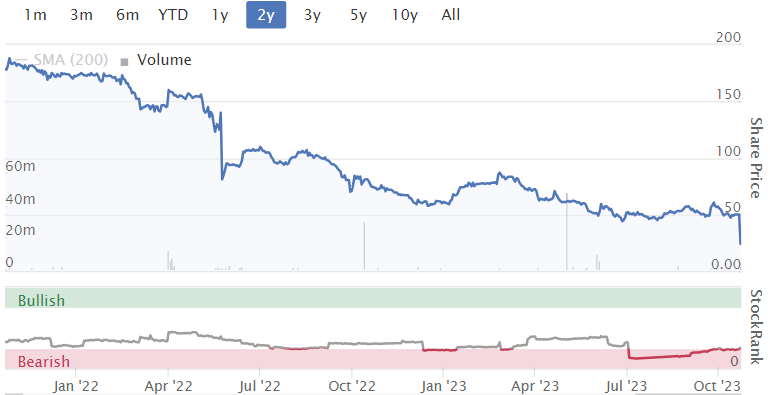
Well-known fund managers Slater and Phoenix have both had a rough ride with this one:
The latest news is that RQIH wants to sell one of its two businesses (“Accredited”) for $465 million. That headline sounds great, but it only gets worse from there:
The “expected net cash proceeds” from the sale are only $300m.
The “net cash proceeds available for utilisation immediately on closing” (explanation not given) are c. $170 - $210m.
This sum ($170 - $210m) will be “entirely used to facilitate a material de-leveraging of R&Q”.
So shareholders aren’t going to see a penny of this. Instead it looks like a bailout for a group in serious financial trouble.
RQIH says that if Accredited isn’t sold, it could be downgraded by the insurance industry’s credit rating agency, below the minimum rating required by its counterparties.
RQIH also says:
…the Board is of the view that the current financial leverage of R&Q is unsustainable and if the Sale were not to proceed and the Available Net Cash Proceeds were not available to facilitate a material de-leveraging of R&Q, R&Q may not be able to continue to satisfy or obtain waivers on the covenant requirements for its existing debt facilities or repay certain of its debt facilities as they become due.
Last year, certain major shareholders attempted to oust RQIH’s CEO. Under the proposed deal, he will leave RQIH and go to Accredited’s new owner.
RQIH will be left with a legacy insurance business. While having reserves under management of $1.1 billion, it sounds like they don’t want to take much underwriting risk in future and will instead focus on collecting fees for their work, sending the insurance risk off to those who are more capable of bearing it.
Graham’s view
The latest interim results disclosed that the “Legacy” business had an adjusted operating loss of $24m and an actual loss of $64m.
The previous full-year results said that Legacy had a pre-tax operating loss of $57m.
This is the business that RQIH shareholders will be left with.
Based on Friday’s RNS, there won’t be any special dividend or buyback to soften the blow. The proceeds from the proposed sale will need to be used entirely to deleverage.
Is it possible that the assets in the Legacy business might start to perform well over the next few years? Sure. But I imagine that very few people outside the business would be capable of predicting this.
I’m going to put a neutral view on this.
Positive points from the deal, assuming it goes ahead:
The controversial CEO leaves RQIH.
Insolvency should be off the table.
Simplification of the group: it becomes a pure insurance legacy business.
Negative points from the deal:
Shareholders lose their profitable subsidiary.
The subsidiary they are left with has been deeply unprofitable and its results are unpredictable (although RQIH wants to make its results more predictable in future by moving to a fee-based model).
No special dividend or share buyback reward for shareholders. Everything rests on the future performance of the Legacy business.
It might be tempting for shareholders to vote against the deal, but they’ve been told in as many words that they face the prospect of insolvency if they do.So it would be very brave if they attempted to hold out for something better.
For anyone who hasn’t yet got involved with this stock, I see little reason to want to get involved with it today. But I will maintain a neutral stance, as the bailout deal should at least take insolvency off the table.
Paul adds: Graham and I have had a negotiation over what colour code we should give RQIH, with me saying Graham's commentary sounded more negative than an AMBER view. So I challenged him on AMBER, with Graham replying with these useful additional points -
Graham adds: I don't mind AMBER/RED. The thing is I don't know if it's undervalued at this level. It's basically a black box. Its insurance assets could perform brilliantly next year! "Legacy business" is an insurance term, it's not that it's a redundant old fashioned, pointless business.
Overall then, we've compromised on AMBER/RED until more details become available for the remaining business.
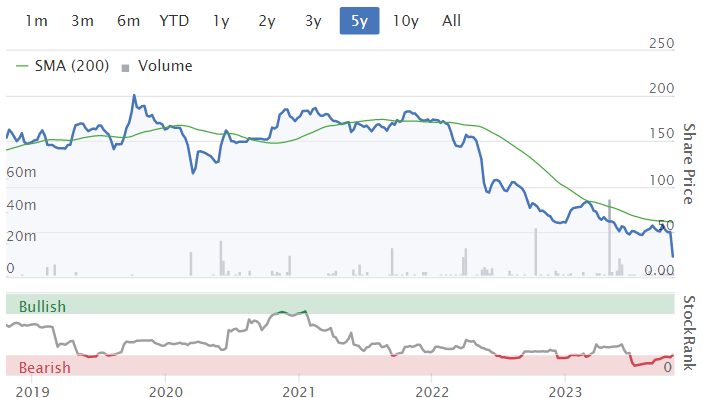
Cab Payments Holdings (LON:CABP)
Share price: 86.2p (-60%)
Market cap: £219m
This stock has been mentioned one time in the SCVR before today: on 2nd October, when I was discussing Peel Hunt (LON:PEEL) - joint bookrunners for the CAB Payments IPO. It is the largest IPO in the UK in 2023.
Let’s quickly review London’s IPO numbers:
2021: 119 IPOs, £16.3 billion raised.
2022: 45 IPOs, £1.6 billion raised.
2023 year to date: 23 IPOs, £950m raised (combined sources: A B).
As you can see, IPO activity has slowed to a crawl. Investor appetite simply isn’t there, as many of us are nursing losses from the poor performance of the last few years.
And so it must be particularly galling for those who did take part in the CABP IPO in July, to see what has happened to their investment so far.
The company came to the market offering shares at £3.35. It was “a secondary sell-down of existing ordinary shares” by shareholders, i.e. no money was raised for the company.
The market capitalisation implied by the offer price was an impressive £851 million.
The company describes itself as “a market leader in business-to-business cross-border payments and foreign exchange, specialising in hard-to-reach markets”. You can find their customer website here.
Interim results for H1 were published in September, showing adjusted EBITDA of £40m (£14m in H1 2022) and PBT of £24m (£11m in H1 2022).
Now let’s take a look at today’s trading update. Remember that the company already updated the market in mid-September:
In recent weeks, the Company has seen a number of changes to the market conditions in some of its key currency corridors, on top of the ongoing uncertainties surrounding the Naira, which are impacting both volumes and margins; most notably, the Central African franc (XAF) and West African franc (XOF). At the present time, these market conditions are compressing margins and reducing trading volume.
The result: revenue for 2023 is now expected to be 20% ahead of 2022. “This is around 17% below previously issued guidance.”
Furthermore, most of the lost revenue will flow through directly to lower profits, as the company is unwilling to cut costs due to “ongoing confidence in the medium-term potential of the business”.
They go on to say that if current market conditions persist, then “the soft exit rate from 2023 could result in 2024 revenue growth falling below the medium-term potential”. Hopefully the medium-term potential will appear again before 2025!
Graham’s view
I think that if investors believed the RNS - which states that the company is suffering a short-term blip on the path to medium-term success - there would be little reason for the shares to fall 60%.
Instead, I think we have the belief (perhaps the realisation) that the market has been sold a pup. People thought they were buying into an advanced fintech with a bright outlook. Now a few months later, they are being told that problems with African currency flows are going to devastate the profit result for the year.
I note that the Nigerian Naira was allowed to fall 23% in a single trading session in June, after a currency peg to the dollar was abandoned (the FT reports that the real, unofficial fall was more like 40%).
The two other currencies mentioned by CABP, the African francs, are pegged to the euro. I wonder what might happen if those pegs were also abandoned?
I have no idea what CABP shares are truly worth but I tend to avoid IPO shares for at least two years. This one has only been trading for a few months and based on today’s announcement, I don’t think investors can have any faith in the company. It might be a fun gamble for someone with money they don’t mind losing, but it doesn’t look like a serious investment to me. So this one is also going to be AMBER/RED.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

104 comments
JPMorgan involved in the IPO and shorting Cab Payments Holdings (LON:CABP)
"How does a world-class market like the London Stock Exchange intend to maintain a global reputation in the face of a disaster like CAB Payments Holdings PLC (LSE:CABP)?
To recap, foreign exchange provider CAB Payments came to market this July at an £851 million valuation, thus going right into the FTSE 250 and marking what was and will be the biggest London IPO of 2023.
In a few short months, CAB’s valuation has plummeted as much as 80% and is currently worth around £162 million.
This is great news for at least one major shareholder, that is JPMorgan Chase & Co (NYSE:JPM).
Fresh off from acting as sole sponsor and joint bookrunner in CAB’s IPO, JPMorgan’s British stockbroking subsidiary Cazenove took a short position on 0.5% worth of CAB’s outstanding shares, per the FCA’s short positions table.
With friends like that, who needs enemies?
In JPMorgan’s defence, its investment bank and asset-management wing are not bedfellows, or at least not meant to be, but it was hardly a vote of confidence for what was meant to be a lone bright spark in a torrid year for London’s capital markets.
Did JPMorgan see something the wider market was missing?
There may be potential criticisms of how CAB managed its risk disclosures in the lead-up to its flotation, specifically in relation to its dollar-naira forex corridor.
The value of the Nigerian naira has plunged over 90% since mid-June due to dollar shortages and a subsequent forex black market.
CAB conceded in a trading update today that “in recent weeks, the company has seen a number of changes to the market conditions in some of its key currency corridors, on top of the ongoing uncertainties surrounding the Naira, which are impacting both volumes and margins; most notably, the Central African franc (XAF) and West African franc (XOF)".
“At the present time, these market conditions are compressing margins and reducing trading volume,” the company said.
To that end, CAB issued a profit warning and now expects full-year revenues to be 17% below previously issued guidance.
This is a bit of a change of tone to CAB’s IPO prospectus, although CAB did indeed touch on the Nigerian policy changes currently proving troublesome.
It read: “While the FX market is still absorbing and adapting to the new policy guidance and it is thus difficult to know the impact it will have on the group's Naira take rates, if the Naira take rates were at post-mid-2021 levels into the second half of 2023, the directors expect the group could exceed the group's total income growth target for 2023.”
For the record, Naira trades constitute 23% of CAB’s revenues, according to the group’s prospectus, while XAF and XOF comprise 7% apiece.
Analysts raise eyebrows
CAB does not have a crystal ball, but were the current market uncertainties properly baked into the group’s initial IPO prospectus?
Some market commentators aren’t convinced.
Analyst Nick Anderson at Liberum had this to say: “In a nutshell, [management's] reputation is in tatters. While we think the underlying business has a strong proposition with a large market, management's inability to foresee events and guide is a major concern."
Another commentator, speaking on an anonymous basis with Proactive, said that the market is punishing CAB for a lack of transparency in market headwinds during the IPO, and while the nosedive in valuation is an “overreaction”, there is a “massive loss of trust” in CAB leadership.
Where does this leave CAB? Management will be hoping that this is indeed just an overreaction to headwinds caused by only one (albeit the largest) of CAB’s markets.
But, as one commentator said: “It’s disingenuous to blame a whole country and a currency for that level of decline”, rather than something more fundamental to the business.
Caz is just not the same since I was part of the audit team 40 years ago!
Thought I'd do a little commentary of Experian (LON:EXPN, which is a £24b cap company and caught my attention. It's down 9.3% today to 2437p. It's a CRA (Credit Reference Agency). It's a pretty weird fall, as there is no official news as to why. The only hint I could find was on ADVFN, saying it was related to US peer TRU (TransUnion) poor results today.
TRU has fallen 25% today. Blimey. It is a $9.4b company trading on a PE of 44 (everything is bigger in America, it seems). Although it reported an adjusted profit, its GAAP earnings was actually a loss. Weak lending and marketing activity in the UK was mentioned, which presumably spooked EXPN shares.
I still find it unlikely that EXPN's shares would fall to such an extent given that it has made no official announcement.
EXPN has a ROE of 28% over 5 years, which is obviously pretty good. The shares are highly rated, on a PE of 21. The shares reached a high of around 3548p in Dec 2021. Operating profits have only increased 4%pa over the last 5 years. It seems difficult to justify such a high PE on such mediocre results.
Legendary quality growth investor Nick Train has been a perennial bull on EXPN. I read that he topped up in April of this year. I don't know what price he paid, but it was almost certainly higher than now. There was a dip back in April, so presumably increasing his stake didn't hurt him too badly.
High valuations have a lot of danger. I have noticed that high valuations for quality shares has been increasingly tempered, although we possibly aren't there yet.
On company that I admire is RS (LON:RS1, although I don't hold any shares. It's a kind of "buy what you know" Peter Lynch type share for me, as I had used them when fiddling around with electronics, and much admired the company. It seemed to have traded at around 1250p in Nov 2021, but has since slipped back to 661p. It now trades on a pretty lowly rating of 11.5, and has ROE averaging 22%. Debt situation looks fine, and Stocko gives it a Q score of 92. So pretty good company, and one that I'm thinking of investing in come the new ISA season.
Maybe value investing will work out best over the next couple of years. I don't know. I think it's a reasonable enough strategy to hedge one's bests and invest in quality growth. A simple screen would be look for average ROE of at least 12.5%, minimal debt (say an interest cover of at least 5, or perhaps even 10) and a max PE of 18. PEs of quality companies do seem to be cooling off.
Thought I'd do a little commentary of Experian (LON:EXPN, which is a £24b cap company and caught my attention. It's down 9.3% today to 2437p. It's a CRA (Credit Reference Agency). It's a pretty weird fall, as there is no official news as to why. The only hint I could find was on ADVFN, saying it was related to US peer TRU (TransUnion) poor results today.
TRU has fallen 25% today. Blimey. It is a $9.4b company trading on a PE of 44.
Good to have your comment on this larger cap. Experian's fall is highly likely to be due to the poor outlook from Transunion today. Good analysis. But I have to pick you up on your description of TRU on a PE of 44x. Why look at last year's PE in November? It's on a FY23 PE of 19x BEFORE todays huge drop and will be on about 15x in the morning. TRU is a crap version of Experian or Equifax and both more volatile and less highly valued than its competitors. You've also been careful to pick a data point that suits your critique of Experian in focusing on operating profit rather than eps which has increased more steadily these last few years - but at a lower rate than would justify its valuation I'll grant. Having set that straight, I do think Experian has held up rather better than the market of late and was perhaps due a fall. The update from TRU has provided the nudge. Personally, I'm a fan of these data businesses and appreciate the stickiness of their products and services.
One company that I admire is RS (LON:RS1, although I don't hold any shares.
Me too. And I have been buying of late. I used to do a lot of business with them and was impressed with their operations. The same is true of Experian as it happens. I think things will worsen for RS before they improve but I do find the valuation compelling at these levels. They've invested very heavily in their systems this last decade and should do well in the medium term.
So, what else is on your list of companies you admire?
So, what else is on your list of companies you admire?
I have a very diversified portfolio, but they almost all have excellent operating numbers, returns, margins etc. That’s where my filter always starts and then I look for their products to be protected by IP or regulation and well integrated into their customer’s operations. So, life science tools mandated by the patent IP, sticky mission-critical software, niche high tech industrial products, proprietary data feeds. That sort of thing.
Just a little update on EXPN. The company gave a Q1 update on 13 Jul 2023. The shares reacted positively. "Organic revenue growth was 5%. Our growth expectations for the full year are unchanged" On the basis that the management are well-respected and not just a bunch of AIM spivs, it seems reasonable to conclude that the market overreacted to TRU's announcement today. Maybe a nice bounce tomorrow for EXPN? Let's see.
Good Energy (LON:GOOD) (I hold)
Looking for a possible explanation of the 57% price increase since the SCSW article was published two and a bit weeks ago, here is an extract of the article outlining the Investec forecasts for GOOD:
"...Investec forecasts pretax profit to virtually double every year from £2.3m this year to £4.2m, £7.4m and £15.2m in the following three..." It advises this corresponds to eps of 9.5p 18.3p 33.2p and 69.2p.
I haven't read the Investec research but assuming its forecasts are reasonable this has multi-bagger potential from a position entirely supported by cash at the time the article was published!!
It all depends on the price of gas as they do not hedge their supply to their customers. Good value (even if they do not achieve those estimates) but with risks if the price of natural gas keeps going up.
I too was alerted to £scs here. As much for the generous divis, receiving over £1k in three years. I almost bought more recently for the divis alone! Nice to have some good news in my portfolio. Thanks Paul for your commentary. It really did feel like when not if for a takeover.
I’ve also been an SCS customer, buying carpets that were twice the price (from memory) at John Lewis. Their service was great too, which made me a confident holder:
I used to be a substantial holder of RQIH but ending up deciding that they were continually taking revenue early. Maybe I was wrong, but I'm glad I got out.
Current holdings, all of which could be targets, but I rather hope that they aren't, I like the income:
Redde Northgate (LON:REDD)
TP Icap (LON:TCAP)
Wynnstay (LON:WYN)
Palace Capital (LON:PCA)
and a small recent holding in Jupiter Fund Management (LON:JUP)
CABP. What a disgrace. How can we expect to trust new issues when this kind of nonsense goes on continually? Oh well, I reiterate my rule:never buy a company unless it's been listed for at least 7 years. It gives us a chance for garbage to be flushed out. We really ought to be able to do better than this.
Many thanks Paul for flagging SCS - I bought in 2021 (near the high) and saw the share price fall last year and this but today's news was great. I'm Glad I resisted the urge to sell amongst this year's continued carnage.
FD Technologies (LON:FDP)
We had these as a decent-sized client at one of my businesses. Bloody awkward to deal with is all I remember. We were glad when the relationship broke down.
BnB - what, exactly, do FD Technologies (LON:FDP) do? I was hoping to find out from Paul but they have succeeded only in baffling him.
BnB - what, exactly, do FD Technologies (LON:FDP) do? I was hoping to find out from Paul but they have succeeded only in baffling him.
They do computer stuff. Things have moved on since my day but from their website:
KX - it's a suite of tools that accelerate data queries for rapid searching and improved analytics. The most technologically ambitious companies keep their data in unstructured form nowadays rather than in a traditional SQL-based database. Tools like Snowflake and MongoDB. KX claims to use AI to turbocharge access to these data lakes and other sources. It then accelerates and enhances the analysis and presentation of the selected data.
FD - Simples. A capital markets software consultancy
MRP - Lead generation and client engagement sales and marketing tools. Prospect profiling, direct mail, content generation, lead generation etc
Hiya Paul...held SCS (LON:SCS) for a while now...so surprised about the news but excited. However, with such a cash pile, is 280p enough??... I get this feeling that the shareholders/ institutions may reject this. What do ppl think?
Agree with those sentiments, 280p seems a bit of a low ball offer to me given the cash sitting on the balance sheet. Hopefully the major institutions will force a higher offer or maybe another interested party might enter the fray.
OMG - takeover fever. From the last 3 years, these are the ones I've been on the receiving end of :
AIR (Air Partner)
HSV (Homeserve - the annoying advertising junk mail ones)
CLG (Clipper Logistics - probably at the peak of interent retailing)
NUM ( Numis, financial broker)
BOTB
and now ... SCS !
All at various premiums - from next to nothing (BOTB) to today's 66% at SCS. Mind you, I can't think of one that beats the 100+ premium paid by the bidder for Avesco sometime in 2017.
Thanks and Thanks again to Paul and all the team for pointing out the attractions of many of these - balance sheets matter ! Unfortunately profit warnings - and how to respond to them also matter so much now [I've had two 40% drops in one day this year]- there is a Stocko article on this from 5 years or so ago - the gist was don't buy in shortly after the announcement.
As for current candidates, I can only think of Bloomsbury (BMY) for now.
All the best
Geoff
Well done Paul & all SCS (LON:SCS) holders.I'm feeling rather jealous with all these bids.I haven't had 1 at all yet this year!I was reading earlier, i think CityAm (THG (LON:THG) 's new purchase) that at least 1 company is being bought a week off the LSE on average.So perchance a suitable suitor will arrive soon.
IPO activity will have to start picking up again sooner rather than later or we'll be left with even less of a choice of businesses to invest in.And Paris, Frankfurt or some other European exchange will take over the LSE (in market capitalisation only hopefully!).P.p.s.Unfortunately i hold the competitor DFS Furniture (LON:DFS) too.
SCS (LON:SCS) Thank you Paul, that is the second super low risk / high upside situation you brought to my attention. The other was Begbies Traynor (LON:BEG) which I still hold on the basis that although the yield is now average they should pick up a lot of business following the rise in interest rates.
Congratulations to all SCS (LON:SCS) holders here, sadly I’m not one but the best thing I can derive from the bid is that 20/30/40% premiums aren’t good enough for a bombed out share in these lower markets, so 60/70/100% are setting the level shareholders should begin to expect and demand!! Paul you’re turning into our very own Betaville with all these bid tips ;))…well done all!
PF up 1% yesterday with the NTBR tender, up 1% today with the SCS bid. When will this bull market mania ever end? 8:)
Smiths News (LON:SNWS) which I hold seems on the move up 15% this month with Preliminary Results out on 8th November.
One number which will be of particular interest is Net Debt. It could be close to Zero which will give the Board more discretion over Dividends as I assume the Bank will no longer insist that Dividends are limited to £10m per annum. Stock Ranks still very good with Value 99 and Rank 98.
Smiths News (LON:SNWS) recent update showed surprising resilience and the core newspaper side has always been a well managed business. Very cheap on a PE of around 4. Some argue that this should be valued on a discounted cashflow basis as the business won't exist in 10 years, but not sure I agree with this - I suspect people will still be reading physical magazines and newspapers in 10 years, so while you're not going to see much growth I think this will still be churning out profits for many years.
Smiths News (LON:SNWS) also won some extra business to bolt onto its London operations recently I think. We didn't get round to covering it here, but looked a useful bit of extra business.
CAB payments Cab Payments Holdings (LON:CABP) wasn't even floated on AIM. Three joint brokers -Morgan Cazenove, Barclays and Cannacord.
Big pat on the back to PS and all SCS (LON:SCS) holders !! I never saw that coming !
R&Q Insurance Holdings (LON:RQIH) - what a disaster this business has been - and how did Slater and others get so caught up. Just look at the Director Deals over the past few years - and a gentle dig at Stocko - How can it be shown as 68 for Value and 23 for Momentum - as ever DYOR!
It was a Simon Thompson favourite
Would be useful to reference ST on it as I dont recall that in last 5+ years. Dave Thornton covered it in GCI when around 200p ish so maybe getting confused. I may be wrong but important not to pinpoint old views on the wrong tip sheet
ST has never covered or recommended it.
ST has never covered or recommended it.
Assuming we are talking about R&Q Insurance Holdings (LON:RQIH) then you are wrong. He did cover it in the IC and made a buy recommendation, but it was some time ago.
Link
Off topic today but I feel beholden to mention this, we have sold our top holding Vertu this morning after increasing warnings from knowledgeable friends on car sales across several large dealer groups. Margins are under severe pressure and sales falling quite badly, used car values are also being hit hard. We will happily buy back in if Vertu doesn't hit forecasts. I also assume any likely bidders for Vertu will also be aware of the trading environment and might wait. If they don't it will add to my collection of big mistakes. For what it's worth our top holding is now Ramsdens which we topped up on recently.
Vertu Motors (LON:VTU) I'm not an expert on the sector, but the outlook from just a couple of weeks ago was fairly positive and said trading had been strong in September. Unless things have suddenly deteriorated in last couple of weeks, I would be tempted to hold on as the chance of a bid coming through surely has to be high . Still very cheap and trading only just above net asset value. Also, remember that around half profits come from aftersales which shouldn't be affected by slowdown in vehicle sales
I am holding as well as the dividend , growth , cash generation and buybacks make this very cheap indeed.
Might be a grain of truth about used car value. Robert Forester said a couple of days ago, that they are shipping second hand diesels up north because of ULEZ. Values in the north are lower than London but I would assume they are paying less to acquire these vehicles given they will get less for them. Other than that, I reckon trading is holding up well in a tough market and the underlying value of VTU is a lot higher than the SP IMO. I hold and will continue to do so.
Who is "we" ?
Well done on SCS Paul, you called it early doors, great work!
Well done re SCS Paul and all who hold!!
Looking forward an exchange of views on FD Technologies (LON:FDP) today. Positive (albeit lower then PY) EBITDA but a pre-tax loss (after a tonne of adjustments, mainly depreciation).
Hot on the heels if an IC tip, whose view was that much of the investment case resided with it's KX division, which could be bought or spun out. Could be worth a deeper dive after a 40% drop this morning?
Morning Mark,
I'm looking at FD Technologies (LON:FDP) - what a nightmare, I know nothing about the business, and am having to research it from scratch. So heaven knows how long this is going to take me.
Luckily I have 2 glasses of white wine left over from last night, so I might have to deploy those after 1pm if it gets really bad!
Regards, Paul.
Paul, was one of Paul Hill's larger holdings, you may want to have a look at his discussions about it.
Oh dear, I might give the other Paul a wide berth then, to avoid rubbing salt into his wounds. It's very painful when a big position plunges. Still, he's a very good stock-picker overall, and some ideas work, others don't, for us all.
Thanks for your thoughts Paul on FD Technologies (LON:FDP). Popped it on the list after the IC tip but like you I struggled with it, and still do, even at 30% off.
Hi Rusty and Paul, I recall Paul Hill saying he'd sold this (or at least part of it) in one of the VOX recordings not too long ago. Hopefully that's correct. Thanks for all the work on the SCVR Paul.
Best, Michael
Where do I start? Bid candidates!
Not so sure about Equals, but agree Vertu Motors (LON:VTU), which I currently don't hold. I think Sanderson Design (LON:SDG) is a sitting duck
My top 10 plus 1, from my small cap portfolio, so I am talking my own book:
Bloomsbury Publishing (LON:BMY)
Centaur Media (LON:CAU)
Flowtech Fluidpower (LON:FLO)
Galliford Try Holdings (LON:GFRD)
Hargreaves Services (LON:HSP)
Jupiter Fund Management (LON:JUP)
M&C Saatchi (LON:SAA)
Palace Capital (LON:PCA)
Sanderson Design (LON:SDG)
Ten Entertainment (LON:TEG)
TT electronics (LON:TTG)
Still I know that I don't know and have no crystal ball. and takeover potential is a possible cherry on the cake.
I hold the above because I believe:
They are undervalued and underappreciated (Sanderson Design (LON:SDG) Hargreaves Services (LON:HSP) Palace Capital (LON:PCA)
Have good turnaround potential as and when the economic gloom lifts, that the market is not interested in Jupiter Fund Management (LON:JUP) M&C Saatchi (LON:SAA)
Are trading well in awful markets and generally remain unloved TT electronics (LON:TTG) Ten Entertainment (LON:TEG)
Jonno
Think we’re holding very similar
Bloomsbury / Hargreaves / Equals / Sanderson are 4 of my 10 core holdings .
I briefly held palace capital (and jet 2) last month but totally bottled it and jumped in and out, I went to fully invested but found I was really uncomfortable being stock rich cash poor .
So I bulleted 3 big positions (Titon ) .
Bizarrely the next day I blew the lot when the president of Indonesia decides to build a motorway across Java and my “tree hunters of Java “ project asked for it all .
I’d buy a lot more Sanderson but I have big chunk of Colefax too so I sort of treat them as a pair .
planetX
Nice to know that I am in good company.
I hold 27 stocks
My biggest positions are Volex (LON:VLX) Avingtrans (LON:AVG) IG group (LON:IGG) Jet2 (LON:JET2) Galliford Try Holdings (LON:GFRD) Bloomsbury Publishing (LON:BMY) . With the exception of Volex (LON:VLX) and Avingtrans (LON:AVG) which are the largest by some distance, these tend to move about a little.
My approach is to hold through the cycle unless the company fails to do so what it said it would, hence I continue to hold Jet2 (LON:JET2) and Palace Capital (LON:PCA) which I see trading at daft valuations, based on what is currently known.
I am building positions in Sanderson Design (LON:SDG) Porvair (LON:PRV) and Card Factory (LON:CARD) all of which are in my view undervalued for various reasons. I previously held Sanderson Design (LON:SDG) and was lucky enough to exit at around £2 having added significantly during the pandemic lows.
All the family portfolios operate within ISAs so I am adding to holdings by means of dividends. New money can't be added once the allowance is used. That imposes a discipline and avoids my bank account being seduced by market prices, which usually drift lower.
Good luck with the Java project, I shall stick with what I think I know, whether that turns out to be true time will tell.
Jonno
I hold Avingtrans as a top 3 position also
I had a big IHT exposure which is less severe now so previously I was limiting to Aim stocks . (Apart from Bloomsbury / Georgia capital / Bank of Georgia in pension )
I had Galliford but wasn’t Aim listed, I don’t think Pakace capital is IHT covered even though it Aim .
It is interesting how a persons personal circumstances can define investment strategy over and above pure company analysis .
SDG I keep adding to every tine it dips under a pound .
Think I will run a more concentrated portfolio in future .
My biggest mistakes have been in micro caps specifically Holders and Croma but I knew I was dancing on thin ice .
Croma is still interesting as it’s a good company but Holders worries me as the sector is under massive pressure and “the business case has changed” so that’s a run for the exit door job.
I was pretty lucky to have 20% weighting in Crestchic which was taken out but that cushion has been somewhat eroded.
Avingtans, Equals , Vertu by far the biggest holdings that’s around 45% those are the ones I am very comfortable with .
Having said that “the best investment you can make is yourself” so I’ve got 4 businesses I own / support financially and retirement which I tried just wasn’t for me .
I do think owning shares in other companies when you have owned your own business can be challenging especially when you the performance and rewards of sone AIM company directors / CEO”s who are quite obviously clueless .
Hence the excellent management at Avingtrans, Equals and Vertu is the biggest tick
I'd be very surprised if the top holders accept this low ball offer for SCS.
Im holding here and waiting for real value which I think will be on the table very soon.
Suprised Paul didn't mention that part.....
Hi Chri55,
Im holding here and waiting for real value which I think will be on the table very soon.
Suprised Paul didn't mention that part.....
Bit too cryptic for me, what are you getting at there please?
Paul.
The offer is clearly to cheap...
Maybe you didn't read it all properly, nothing cryptic.
No mention in the RNS of irrevocable acceptance from the major holders. Just the 0.8% by the directors. So the institutions haven't backed this take over at SCS (LON:SCS)
Exactly Pal, there's some big holders here that want to make money.
Hopefully some more bidders in the background...
Come on Paul it’s not good enough to keep pointing out to everyone that a share is cheap and it’s ripe for a takeover but you then have to make sure they don’t sell it too cheap once a 70% premium is offered!
SCS (LON:SCS) Thank you very much indeed Stocko! I walk away with a profit.
Top Takeover Bids challenge .
How about a top takeover bids competition ?
Everyone can claim to have highlighted takeover bids but I’m not sure what the % actually is ? Pretty low for sure
I said a few months ago takeover activity is the big chance in this market and looks to be coming true .
So how about a top 10 challenge ?
I had Sureserve, Crestchic and Gresham (very small holding )
My top 10, err , well I have 3 so far
Vertu
Equals
Sanderson
will add more as brain wakes up
AIR
WEN
SCS
RHIM (tender offer for 30%, if this count)
How about a top takeover bids competition ?
Fun idea. But I wish you’d suggested this a year ago as I’ve had a substantial number. I’m running short of decent prospects and don’t see the same potential in my portfolio today. Nevertheless 10 ideas (UK only) from my holdings:
Ashtead Technology Holdings
Beeks Financial Cloud
Diaceutics
Luceco
Somero
Treatt
UPGS
Volex
Wilmington
YouGov
Plus Equals which PlanetX already suggested
Good idea - although my last was WS Atkins so here is the list of 10 which WONT happen now!
Avation (LON:AVAP)
Card Factory (LON:CARD)
Equals (LON:EQLS)
Gaming Realms (LON:GMR)
Niox (LON:NIOX)
Renold (LON:RNO)
Sanderson Design (LON:SDG)
Volex (LON:VLX)
Vertu Motors (LON:VTU)
Alliance Pharma (LON:APH) - special situation by DBay
Angling Direct (LON:ANG) once cash stripped out also looks massively undervalued?
Cab Payments Holdings (LON:CABP) Another wonderful IPO collapses in record time.
I tried buying this as a trade before it entered the FTSE250 in August. All I can say is I love stop losses.
Morning Wolfie!
Good grief, thanks for flagging Cab Payments Holdings (LON:CABP) - it's down c.60% today! We'll have to look at that one next.
Regards, Paul.
EDIT: Graham's going to look at CABP, and I'll do FD Technologies (LON:FDP) next.
Cab Payments Holdings (LON:CABP) Down 73% now. Directors didnt even make it to the 6 month lock-in end date :)
No wonder so many IPOs come under immediate shorting pressure.
I am a bit surprised Cab Payments Holdings (LON:CABP) gets an AMBER/RED rather than a straight RED
Pressure Technologies (LON:PRES)
Positive news on refinancing by principle shareholders Rockwood Strategic (LON:RKW) and Peter Gyllenhammer. Mind you it comes at a price, 14% plus interest rates and warrants. Having said that the proposed sale of the PMC division, which is trading well has been initiated and looks promising.
if one can peer through the gloom the future for larger division Chesterfield Special Cylinders looks bright. Whatever one may think about Chris Mills and Peter Gyllenhammer's financial manoeuvrings at least they are putting their money where their mouth is. Given patience I expect this to be a good outcome for them and the company.
I hold
Pressure Tech
There is also a 3% arrangement fee.
I think the key is it means Lyoyds do not have a lean on the assets of the business as their funding was secured.
Smart move I think and hopefully they can now get on with business change without having to run everything by Lyoyds bankers .
Pressure Technologies (LON:PRES)
I agree with you Jonno, don't get me wrong the boys are taking the biscuit with these exorbitant interest rates BUT that will definitely force the Board into faster action with regard to the sale of PMC and with that sold then we have a very established, profitable, niche business with a clear runway to growth given the sectors it is in.
That is when I believe an industry player will step in and snap them up, after all the market cap is tiny, nice fit for Goodwin (LON:GDWN) and all their submarines perhaps?
Trifast
Quite a nice update .
They clearly have a plan and are on plan .
My FD used to say to me “I don’t want you to smash it out the park just deliver to budget”
Seems to be a simply strategy by rhat moms like good CEO
- reduce stock (better stock turn)
- increase margin (lift margin)
- maintain sales
- reduce overhead (consolidation of logistics )
Debt is down 10 million so presume that’s due to stock reduction, margin is up so that’s very good as the stock reduction has not been at the expense of margin, and they have reduced warehouse costs by consolidation .
Looks a really nice simple update to me .
Volex (LON:VLX) Trading in line with market expectations. Demand in medical and data centres offsets current softening in consumer electricals and EV, although destocking is slowing and order patterns normalising especially in EV, which is positive. Murat Ticaret integration proceeding with potential for cross selling opportunities.
"The easing of pressure in supply chains and higher interest rates have caused some Electric Vehicles and Consumer Electricals customers to closely manage inventory levels. This has been more than offset by strong demand in Medical and Complex Industrial Technology supported by better availability of key components. There is evidence of de-stocking slowing in some channels, as order patterns are starting to normalise, particularly in Electric Vehicles."
Result of cyber incident in line with original announcement, although $2m remediation costs anticipated.
"The Group confirms that all of its manufacturing sites are operational, and now delivering full production output. The effective deployment of the Group's business continuity strategy minimised customer disruption and there is not expected to be any material adverse impact to revenue or underlying operating profit as a result of the incident. Costs for the recovery and remediation of systems are anticipated to be approximately $2 million, which will be reported as an exceptional item in the second half of the year."
All in all good news I would suggest in challenging economic conditions and awful market for UK small cap shares, especially AIM listings.
I expect that Mr Market will be disinterested, but as a holder I remain sanguine.
Interesting to see value shares catching a bid now, and not just growth names.
SCS (LON:SCS) - Major holders have not committed, only the pitiful director holdings of 0.8%. Surely it's worth more than £100m?
An interesting point.... will the bid attract other potential bidders from Private Equity. I think Paul has mentioned in the past that SCS would be an ideal target for a PE buyer given the balance sheet strength.
Quite. I hold and am not remotely interested in selling at this price
Excellent result for SCS. I suppose that the value of any cash pile has increased in absolute terms. Not just in terms of operational utility for the business. Yielding nearly 5% and the opportunity to keep up with inflation instead of no return is a huge increase in the value of bare cash itself.
Paul is on the roll. Another take overbid as predicted. Expecting a lot of tooting his own horn this weekend podcast ;D :D ᕙ( •̀ ᗜ •́ )ᕗ
Oh yes, I'll be insufferable!!!! :-D
Congratulations to the holders of course! Quick disclosure -I dont hold unfortunately its been on my waiting list and the plan was to act after the TU (so slightly disgruntled:). I have a question regarding the disclosure rules on potential takeovers: two weeks ago the board said that there was a TU delay by two weeks. If they entered any kind of discussions/negotiations with the buyer - should not have they informed the market or is it possible that such an approach comes out completely out of the blue with the directors all fully aligned with the takeover? Thank you
Gattaca (LON:GATC) - "Robust foundations in place" - new note & audio summary here: https://www.equitydevelopment....
The implementation of the ‘four pillars’ of Gattaca’s new strategy resulted in adj. EBIT rising significantly, as did conversion rates too (up to 5.4% vs 0.2%). Impressively, this was achieved despite the Group’s markets turning more challenging during H2. NFI fell by 8.5% yoy, down by 1.8% in FY23, with a targeted exiting of lower margin contracts a factor.
Progress has been driven by self-help: on cost control, marketing, an improved culture, exiting low margin contracts and improved productivity levels. We think there is more to come as the new hires bear fruit and additional cost savings emerge (particularly in property).
Looking ahead there should be some recovery visible in recruitment markets over the next 12 months and at Gattaca we expect further improvement in the conversion rate. The £23.4m net cash at year-end also opens up many opportunities for the Group.
Based on a discounted cash flow model we raise our Fair Value to 175p per share.
My morning smallcap tweet: Furnishing a result for holders
SCS (LON:SCS) Cordel (LON:CRDL) Belluscura (LON:BELL) Volex (LON:VLX) LPA (LON:LPA) System1 (LON:SYS1) Cornerstone FS (LON:CSFS) Cambridge Cognition Holdings (LON:COG) Pressure Technologies (LON:PRES) ECO Animal Health (LON:EAH) Gore Street Energy Storage Fund (LON:GSF) Leeds (LON:LDSG), Trifast (LON:TRI), Angling Direct (LON:ANG), Gattaca (LON:GATC)
◄ScS (SCS)► 280p rec offer: 270p _ 10p div. 68% premium. [SP=165.52 Cap=56m]. I hold.
◄Cordel (CRDL)► contract for data capture and analysis with Network Rail. No £££. [SP=3.8 Cap=8m]
◄Belluscura (BELL)► direct to consumer program has exceeded co's initial expectations. [SP=27.5 Cap=38m]
◄Volex (VLX)► trading in line. Cyber incident: all manufacturing sites are operational, and delivering full production output. Estimates $2m of costs. [SP=281 Cap=509m]. I hold.
◄LPA Group (LPA)► guides FY-Sep rev up 11%. Orders up 30%. Co expected "an increase in H2 activity to offset the challenges faced in H1. We delivered strong trading in H2, leading to an underlying position of breakeven for the full year." In line then? Will pay divs again. [SP=75 Cap=10m]
◄System1 (SYS1)► guides H1-Sep rev up 27% and pretax just below £1m (zero). In line? "The sales momentum in the platform business continues, with platform revenue up 55% in Q2, 44% in H1 and all at an improved profit margin". [SP=181.2 Cap=23m]
◄Cornerstone FS (CSFS)► guides FY-Dec at least £8m up 66%, above mgmt exp. Adj EBITDA also above. [SP=13.82 Cap=8m]
◄Cambridge Cognition (COG)► launches AQUA, an automated quality assurance solution for central nervous system clinical trials. "AQUA is an entirely new solution for the clinical trials market providing a level of quality assurance that was not possible before, from a cost or time perspective, with traditional reviews by medical experts." [SP=70 Cap=24m]
◄Pressure Technologies (PRES)► agreement in principle with shareholders for £1.5m 5 yr loan facility. Will be used to refinance the existing debt and additional working capital. Fee 3% and interest 14.25% PA. Ow!. Also will sell Precision Machined Components division. [SP=25.75 Cap=10m]
◄Eco Animal Health (EAH)► FDA approves US and Canadian label claim indication for Aivlosin Water Soluble Granules in pigs. [SP=105.75 Cap=72m]
◄Gore Street Energy Storage Fund (GSF)► gets initial $60m loan financing for 200MW / 400MWh Big Rock project in California. [SP=67.8 Cap=326m]
◄Leeds (LDSG)► FY-May rev down 7%, pretax -£0.9m (-£3.2m). Material uncertainty going concern stmt. Also auditors "unable to obtain sufficient audit evidence in respect of the [discontinued] subsidiary KMR." [SP=14.55 Cap=4m]
In line: TRI, ANG, GATC
Bid news for SCS (LON:SCS) at 280p per share (I hold).
So this is the reason SCS (LON:SCS) delayed their results last week. I hold, I'm not too happy with the price but at least I will make a return which makes a nice change.
Morning Paul, looks like SCS (LON:SCS) finally got an offer which you've been saying for a while. 280 pence incl dividend 10p. Happy with that result (I hold)
i'm not exactly happy. It is a pitiful offer given the existing cash balance.
Yeah I see your point. But I don't see the share price getting there anytime soon. So I am happy to get the cash to redeploy elsewhere. (SCS (LON:SCS)
Not so happy about how SCS (LON:SCS) have added the dividend. If sold today i'm guessing i'll be offered about 255p. I could wait then for divi, but I'd guess everyone will be selling after the ex divi day on which the sp should in theory drop 10p for the divi, which could be worth then buying more. Too many decisions. Also, I've never reinvested divis automatically, how does that work in regards to the price your broker pays for them and how much do the brokers charge to reinvest dividends?
Actually surprised to be offered 271.4p to sell, so not a bad deal altogether.
Hi gmtrader, I haven't been a holder of too many companies that get taken over, but from memory I would tend to hold until the deal is completed.
Is there a reason why you would sell on the market before the deal completes? Is it just in case it falls through?
Selling early does mean you don't loose out if the deal falls through but I do not think that would be the case with SCS (LON:SCS) , there could even be a higher bid to come. For me selling at 271.4p, I don't loose too much (8.6p worth) and I don't have to wait until some time in 2024 to receive the funds. I can then put these funds else where. Where I haven't decided as there are so many under valued companies about and I still see the possibility of the markets dropping a bit more.
I am interested in the house builders but I'm not completely convinced they are cheap at the moment. PE for them are currently low, but if you compare the 12 month forecast PE to the 5 year average, they look expensive. (at least some of them do).
Makes sense, thanks for the explanation.
I agree about the markets, they're looking rough at the moment, I too think we have further to go.
Best of luck!
Would be an interesting discussion regarding where SCS holders will be reinvesting the proceeds. It was one of my largest holdings and now in the unexpected but not entirely pleasant situation of wondering where to put the proceeds. Likely adding to MBH and TW. although SONG looks an interesting and bombed out diversification from my usual but I just don't understand it enough.
I agree it would be interesting.
Michelmersh Brick Holdings (LON:MBH) I hold some. I may add more if it drops to new lows. I think I prefer Brickability (LON:BRCK) .
what makes you choose Taylor Wimpey (LON:TW.) compared to other builders? As I mentioned previously their 1 year PE forecast is actually higher than their 5 year average so maybe a bit expensive atm? Obviously they are very safe imo with plenty of cash and I’d say it’s just a case of when the sp turns around.