Small Cap Value Report (Tue 25 Jan 2022) - AMGO, WATR, SUP, SAAS, THG, ERGO, SPE, SUR, EKF

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
Agenda -
Paul's section:
Quick reviews of the largest fallers yesterday.
Sopheon (LON:SPE) - a positive update for FY 12/2021 - it's beaten the (low) expectations set in Dec 2021. I quite like the company, but it's difficult to justify the valuation on the poor performance over the last 4 years. It needs to step up a gear to maintain this valuation, in my opinion.
Sureserve (LON:SUR) - a reader request, and I form a positive view of the FY 9/2021 results. This looks a decent value/GARP company, performing well, and priced reasonably. The problems from its past (when it was called Lakehouse) look to have been fixed. It gets a thumbs up from me.
Jack's section
Ergomed (LON:ERGO) - adjusted EBITDA to be ahead of expectations, which appear to be for around £24m. The group has a very positive operational track record in recent times, including expansion overseas and notably in the US. Good organic growth continues, with firepower for acquisitions. The valuation remains ‘expensive’ and this is a risk depending on wider market sentiment, but the company's prospects are positive.
Ekf Diagnostics Holdings (LON:EKF) - continued strong trading and adjusted EBITDA will again be ahead of upgraded expectations. There’s a longer term growth strategy in place, which is positive as presently results are boosted by Covid testing. It’s an interesting company, but one I struggle to value.
Paul's market thoughts
We're seeing a remarkably rapid & steep decline in US markets, which very much sets the tone for sentiment in the UK. Take your pick from any of the reasons given (although most of these were already known, so don't strike me as particular catalysts for a big fall) -
- Higher inflation (due to supply chain problems and excess demand)
- Fed expected to raise interest rates 3-4 times in 2022 (but only by 0.25% each time, hardly a big deal)
- 10-year US Govt bond rate rising (but still insanely low, given where inflation is)
- Tapering of QE and the idea that the Fed might actually unwind some of the QE (which I don't think is ever likely to happen)
- Buying the dip stopped working
- Higher oil price & energy supply problems
- Risk of war in Ukraine
I think that's most of them. I'm not blase about these things, but the markets always have to "climb a wall of worry", and there are always macro economic and geopolitical worries.
I think it's more about a general unwinding of multiple speculative bubbles. We've been in pretty crazy market conditions for years now, in a long bull market. Valuations got very stretched by historic standards in growth companies, and there's no doubt that higher interest rates make future cashflows (long into the future) a lot less valuable now.
That said, to my mind, with inflation now eroding say 5-7% of our money each year, this makes sensibly priced equities a lot more attractive. Holding cash for a year or two seemed OK, when inflation was 0-2%, and remember for a long time people were worried about deflation. Now though, holding cash for any more than a few months, is seeing your assets decline in purchasing power. This bout of inflation is seriously bad news for the millions of pensioners out there, sitting on whacking great cash balances in their savings accounts, and earning negligible returns. If this current bout of inflation runs into 2023 (looking likely I'd say), then those pensioners could effectively see c.15% of their savings wiped out in purchasing power. Just like we saw in the 1970s and early/late 1980s. Holding cash for long periods in an inflationary environment is a terrible idea. That's why I think equities are becoming more attractive, not less. Divis of say 4-5% are not hard to find, and that reimburses us for nearly all the inflation impact on our money, with a chance of a capital gain on top too.
Equities are more attractive after recent steep falls too, due to BLASH (buy low and sell high). Over the years, I've trained my mind to think the opposite of the instinctive, negative emotional reaction to falling share prices. So instead of becoming despondent and panic-filled at my plummeting portfolio (my SIPP is down 13% year-to-date, just 24 days, with no gearing remember). My spread bet accounts are filed in the "Just don't ask" tray! It happens sometimes, I accept losses. This is the hangover after the party we all enjoyed from Oct 2020 to July 2021. I knew the party would end sometime, so adopted a hedging strategy, which would have worked if I'd run it for a few more months, but the losses in late 2021 meant I had to abandon it. Ho hum, there we go. Memo to self is obviously to just sell things next time, when all around me looks incredibly rosy, not try to dream up a fancy hedging strategy.
As regards yesterday's widespread panic selling, that looked to me very much like short term capitulation - a possible sign of a bottom, at least short term. Discussing this with friends last night, most disagreed, thinking it was just a typical powerful rally that you get in a bear market. Who knows? I can't predict market movements, nobody can with reliability (although plenty pretend they can!).
With about a third of the trades in the US being done by computers using a pre-programmed approach, often chasing direction (up or down), rather than valuation or logic, it's sometimes pointless trying to rationalise why share prices are doing what they do. It's often just the speculative flow of money.
The market is offering me unacceptably low prices for my shares, so I'm not selling. I think that's the key point to keep in mind. Or, if you think the outlook is awful, then the market might be offering a good price, in which case you would sell. Everyone just has to make up their own mind.
Are you investing long-term, and based on analysis of company fundamentals? That's what we focus on here, so this is not relevant to traders going in & out of shares. Lots of people think they're investors, but are actually trading, so it's important to know where you sit. For long-term investors, I think this is a time to check that your analysis is right, and if it is, then market gyrations are just background noise, to be ignored.
As we saw in early 2020, when the pandemic hit, markets roughly halved, it was total carnage, then they recovered. People who held their nerve recovered all their losses. What we're seeing at the moment is nowhere near as bad. I see it as healthy actually - speculative stuff in particular, on crazy valuations, has been slaughtered over the last year. As we saw in the March 2000 tech boom & bust, a lot of the new entrants, who created new paradigms and fancy ways to value shares on KPIs which we'd never heard of before, disappeared without trace. I think the same thing is happening now, as the Robinhood traders and Bitcoin crowd are gradually learning that fundamentals and valuation do actually matter, and their speculative gains melt away.
CNBC showed an interesting graphic last night, that Cathie Wood's boom & bust Ark fund, poster child for the latest tech boom, has now fallen so much that it's been overtaken by Uncle Warren & Charlie's slow but sure $BRK.A - very much tortoise & hare.
Anyway, my key message is that markets are inherently volatile, due to sentiment, and large elements of the market being used as a giant casino. That provides opportunities for longer term investors like most of us, to buy good assets cheaply from panic sellers, who are letting them go at an irrational price, due to fear of further price falls.
Once we've bought a share, then I think (providing the fundamentals remain positive), the day-to-day share price, and our running profit or loss, is just best ignored. Although an unusual fall in the share price, when the market is generally sound, is obviously a concern that means research needs to be revisited. But a general plunge in the market, which takes down good stocks and bad, is not a concern to me, and for long-term investors we can just ignore it.
Some individual shares will beat expectations, some will warn on profits. Hence why it's important to have a portfolio. You can't avoid profit warnings, so just accept the occasional one as an inherent risk in what we do.
As I remember saying when covid began in Feb 2020 - work out your strategy now. Either sell early (before markets plunge), or resolve to sit tight. The worst thing is to panic sell - because that's often at or near the bottom, when people capitulate. That remains relevant today. I don't know when the current sell-off ends, but with the pandemic apparently now drawing to a close, this strikes me as a funny time to be selling shares with good upside on fundamentals, like the re-opening trades that I'm mainly focused on.
If things really get too much for you, emotionally, then just turn off the computer! I sometimes do that, and have a nap, to de-stress. Going for a brisk walk, or cycle ride also helps, listening to music, gardening, whatever relaxes you. If you're not geared, then you can ride out any downturn, no matter how severe. As long as you're holding sensibly priced, decent quality companies, then everything should be fine in the long run. There's absolutely no point, and it's very emotionally destructive actually, to run "if only" scenarios through your mind. We can't change anything that has happened. So focus on now, and the future, as you can change that. Also, appreciate what you do have, even if it's less money than it was 6 months ago. This is how I handle horrible market conditions.
If you're holding speculative, over-priced stuff, then some tough decisions might still need to be made. That's up to each investor, we all have to work out our own strategy, learn from our mistakes, and hopefully do alright in the long run. Good luck, and don't panic! We're in this together, so if you're tearing your hair out with anxiety, post a comment below, and the community will I'm sure help you by discussing it - a problem shared, and all that.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Some large fallers from yesterday
Amigo Holdings (LON:AMGO)
3.5p (down 42% y’day) - mkt cap £17m
The market cap looks about £17m too high. An announcement yesterday made it clear that the company is teetering on the brink of insolvency. To avoid insolvency, it will have to do a Rights Issue that will involve issuing at least 19 new shares for every 1 existing share. If shareholders don’t approve this, then it will file for insolvency.
The announcement really couldn’t make it clearer that the equity is now worth nothing, or very little. The cause is that redress for customers is now taking priority, with negotiations underway. The court has made it clear that equity should be wiped out, if creditors are to take a haircut. That would leave the loan book going into run down, presumably managed by an Administrator?
Amazingly, there’s still time to sell, so I think the only logical course of action, is to sell for anything you can get, and donate the money to ZANE, instead of inactivity, and a probably 0p end result.
Water Intelligence (LON:WATR)
Down 18% yesterday to 815p on no news.
Unless I've missed something, this plunge in price seems down to panic selling meeting illiquidity.
WATR is on a high valuation rating, so I suppose it would only take a handful of people to panic sell, and the price tanks. We’re seeing a lot of that at the moment, so I don’t think it necessarily says anything bearish about the company itself.
WATR’s track record on growing EPS has been very good, but as I’ve been saying for some time, the valuation seemed to get well ahead of reality. It's obviously more attractive, now that the price has fallen a lot from the peak, but still doesn't strike me as a particular bargain.
Supreme (LON:SUP) (I hold)
Down 15% yesterday to 196p
This is another one that dropped really sharply, on the general market panic sell-off we say yesterday. Although looking at the chart, it’s only really scrubbed off a recent spike in price, which I seem to recall might have been due to year end tip sheet selections, or something similar?
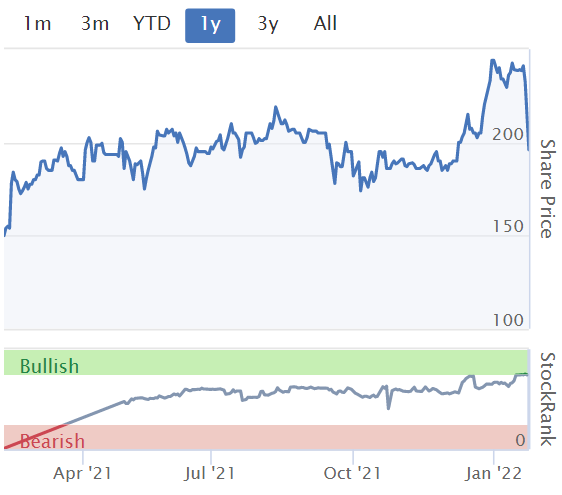
I reviewed its interim results in Dec 2021, which looked solid. Nice company, at a reasonable price, in my view. It’s only a tiny position in my portfolio currently, but I might top up when markets settle down a bit, if it drops a bit more.
Microlise (LON:SAAS)
167p (down 18% y’day) - mkt cap £195m
This company listed on AIM in July 2021. We’ve not covered it here before, so I’ll take a first look today.
There’s an investor presentation on IMC which I’m watching now, it’s a good introduction to the company. It claims dominant market share of transport management software in the UK - e.g. all 15 of largest retailers are Microlise clients. Product used internationally. Very low churn rate (under 1%). Great visibility as contracts are generally 5 year. Been around since 1982. 600 staff around the world. 400+ large (enterprise) customers, main part of the business. £18.6m raised in July 2021 to fund growth. (webinar overlooks that IPO also raised £42.6m for selling shareholders. Naughty!). Suite of 6 modules, not just telematics. IPO was 135p (now still above that, at 167p).
I’m rapidly losing interest, whilst looking through the AIM Admission Document, due to modest (and falling) levels of profitability for a company with almost £200m mkt cap -

.
Trading Update & Directorate Addition
The main financial highlight items look OK -
· Strong growth in Revenue and EBITDA, in line with market expectations
· Annual Recurring Revenue (ARR) run rate as at 31 December 2021 was £39.0m, an increase of 9% on December 2020 (£35.7m)
· Net cash at Period end of £13.4m
As we can see from the table above, that I copied from the AIM Admission Document, EBITDA looks meaningless (as it often is for software companies that capitalise large development spending).
Outlook - sounds a bit hesitant, and no specific guidance on profit is provided -
The Board remains confident in the Group's future growth which is underpinned by long-term structural drivers. The Group has a healthy pipeline of new opportunities, in the UK and internationally, and continues to invest in product development, notwithstanding the continued operating challenges caused by the pandemic and global microchip shortage. The Board expects these supply chain issues to last longer into 2022 than previous industry estimates, and the Group's management will continue to implement and execute its plans to mitigate the impact.
Valuation - with nothing said in today’s update in terms of profit guidance, and being a new listed company (hence no track record), this is tricky to value.
Many thanks to Singers for publishing an update note today, written by star tech analyst Kevin Ashton, no less!
He’s showing much higher historic adj profits than the numbers in the table above from the AIM Admission Document. So I’ll have to investigate what costs have been adjusted out?
Singers forecast 3.7p adj EPS for FY 12/2021 (which will be an 18 month period, but Kevin seems to have annualised the forecasts, to make sense)
Then 4.0p adj EPS in FY 12/2022
Then a drop to only 3.7p in FY 12/2023.
The reason for the earnings drop in 2023 seems to be that 2021 and 2022 have a zero tax charge, but kicks in again in 2023.
At 167p per share, the PER is 45 times 2023 forecasts. How on earth does that make sense?
My opinion - tech valuations seem to be coming down to earth, but Microlise still looks valued on a boom time rating from when it was floated.
It seems to me, on an initial look, that this company looks high quality (dependable, recurring SaaS revenues), and low churn, but the valuation is much too high to interest me.
There’s nothing magic about tech shares, and I think this share should probably be valued on a PER of maybe 20-25. That implies a share price of about 74-93p. It’s currently 167p, so looks significantly over-valued to me, in today’s much more sceptical markets, so I reckon this share is probably heading a good bit lower.
No wonder the owners were happy to trouser £42.6m in the IPO.
The pre-IPO balance sheet looks a bit strange, so I’ll be interested to view the next balance sheet.
.
Thg (LON:THG)
121p (down 19% yesterday) - mkt cap £1.24bn
This multi-£billion IPO (valuation peaked at an insane £8bn a year ago) looked seriously over-priced & over-hyped to me from day 1.
It’s now rapidly approaching small cap territory, with the market cap down to £1.24bn.
The trouble is, despite big, and rapidly rising revenues, it doesn’t seem to make a profit.
Also, the whole float was a story spun around supposedly ground-breaking software, and the latest buzzword of being a “platform” - hence no need to make any profits in a tech boom.
THG has since lost 85% of its peak valuation just one year ago, of about 800p. Reality is really biting with growth tech, and eCommerce businesses, as many valuations have crashed, but this one is particularly bad.
Looking at the last interims, it’s actually loss-making, because depreciation & amortisation (of development spend) together exceed EBITDA.
So I’m not tempted to bottom fish at this level. The balance sheet looks sound though, with plenty of cash, although note it also has £500m of debt.
I’ll wait to see where the dust settles. There’s talk of it spinning off its eCommerce beauty business into a separate listing, which sounds a bit desperate.
Moving on to today's updates:
Sopheon (LON:SPE)
885p (pre market open) - mkt cap £93m
Sopheon, the international provider of software and services for Enterprise Innovation Management solutions, is pleased to provide the following trading update for the year ended 31 December 2021.
I reviewed Sopheon’s positive-sounding update here on 20 Dec 2021, but came away unimpressed because “comfortable meet(ing) expectations” actually meant being only slightly over breakeven!
They must have clinched some contracts just before year end, or held a bit back for a rainy day, because today’s update now says revenues “will exceed $34m” - which is better than the previous estimate (from a Progressive research note) of $32.7m.
Annualised recurring revenue is >$20.5m - good, but that means about a third of revenue is still non-recurring, hence potentially lumpy licence wins could still make profits volatile.
Revenue visibility for 2022 is good, at $23.4m
EBITDA guidance -
Adjusted EBITDA is expected to exceed $6m (2020: $5.9m).
Net cash looks very healthy -
Net cash on 31 December 2021 was $24.1m (2020: $21.6m)
Deferred recruitment helped profitability. I’m impressed the company has been transparent about this, I think many companies would have kept this quiet -
In addition to the revenue out-performance, the profit result was assisted by the deferral of some of our anticipated investment plans, in particular in the staffing of product development. Like many other software businesses, we face ongoing challenges in recruiting technical staff…
Growth plans - good (faster growth?) or bad (higher costs)? It depends if the money is being spent wisely, and likely to generate a decent return on a timely basis -
Our growth initiatives will continue and accelerate in 2022.
SaaS - interesting commentary here - but it’s a really long haul for any software business to transition from one-off licences to SaaS - possibly beyond the investment horizons of many people? -
The improvement in ARR underlines continued traction in our migration to a Software as a Service ("SaaS") recurring revenue model, giving both enhanced revenue visibility to future periods and improved quality of earnings. Approximately 50% of more than 70 license transactions signed during 2021 were for SaaS contracts.
Moreover, the value of SaaS bookings was more than double that of perpetual contracts. This includes another six existing customers converting from the perpetual model to a SaaS model.
Gross retention of ARR returned to our normal strong levels, at 95% compared to 91.5% during the challenging conditions of 2020.
Diary date - 24 March 2022, for FY 12/2021 results.
Outlook - fairly general, but upbeat comments from the Chairman -
Sopheon's Chairman, Andy Michuda said: "As I noted in our December announcement, it was great to end the year with our first acquisition for some time, coupled with strong execution in the core business. We continue to explore and evaluate further M&A opportunities. In parallel, we are also advancing nicely on our stated transition towards a SaaS business, both operationally as well as financially, intended to enhance predictability, quality of earnings and overall shareholder return. I am encouraged with the foundational progress Greg and the team have made in 2021 and look forward to further positive developments as the new year progresses."
Broker update - Progressive has put out a note this morning, which doesn’t make any sense! They’ve noted the upward guidance on revenue & EBITDA, but then ignored it, by leaving adj EBITDA at $4.5m in their forecast, despite the company saying today it will be >$6.0m. That’s ridiculous! Progressive says it’s leaving estimates unchanged, to allow easy comparison with the trading update. Pull the other one! That’s the sort of excuse I make, when I don’t hear the alarm go off! Normally the analyst would revise up the forecasts when specific guidance is given, and provide an old & new table to show the comparison.
Finncap is more on the ball, with an updated note which does reflect the improved guidance given today by the company.
Note that $6.0m adj EBITDA only turns into $2.0m adj PBT, and 16.0p adj EPS - this is now the 3rd year when EPS has fallen. The trend looks awful :
2018: 61.2p
2019: 24.5p
2020: 17.2p
2021: 16.0p
[source: Finncap note today]
So despite all the upbeat commentary, the numbers that matter to a value/GARP investor are really not trending in a good way.
Finncap’s forecast for FY 12/2022 is even worse, with adj PBT of only £0.7m, and 3.4p EPS. That’s despite revenues forecast to rise 8.5%, and must be due to the increased costs alluded to in the commentary above. I imagine that's been set low, so the company can keep putting out ahead of expectations updates during 2022.
I understand that the company is not being run for short-term profits, it’s a growth company, supposedly. But revenue hasn’t gone anywhere for 4 years too! That’s meant to be because of the switch to SaaS. Fair enough, but flat revenues, and greatly declining profitability, doesn’t look any good to me. The valuation therefore hinges on expectations that the company can become a lot more profitable in future. This is not an ideal story to tell, in today’s much more sceptical market conditions.
My opinion - from reading things on the internet, I know many shareholders are very committed to Sopheon shares, so sorry if this article rattles your cage! But the fundamentals really don’t look much good here, at this moment in time. That makes the valuation questionable. It’s all based on hopes that the company can grow, and start to show an improving trend - which shouldn’t be too difficult, starting from what is now a low base in profitability.
I think it needs to show faster growth, to justify the valuation, but you may disagree.
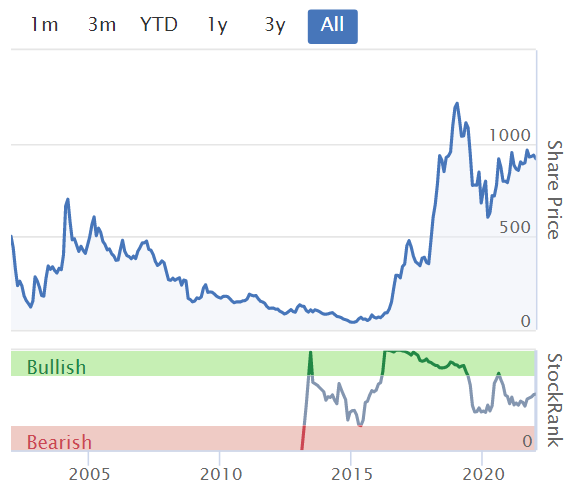
The trouble is, I don’t know whether the company will grow more strongly or not. I prefer shares where you can justify the valuation on the existing profits, then growth from that strong base provides your upside on the share price. Whereas Sopheon’s current profits probably only justify a share price of maybe 320p (20x 2021 EPS). The price is 885p, so that’s 565p extra valuation for hopes of future profit growth. It might achieve the growth, or it might not.
.
.
Sureserve (LON:SUR)
91.5p (up 6% at 10:24) - mkt cap £151m
Jack wrote an excellent review of this support services group here in Oct 2021 - well worth a read to get up to speed on the company, which is what I've just done.
Sureserve, the social housing energy services Group, is pleased to announce its audited preliminary results for the year ended 30 September 2021.
Financial highlights - this looks impressive -

Profit margins at contracting groups are usually low, but in this case PBT divided by revenues is 5.6% - not bad at all for the sector.
Adj EPS is 7.1p (diluted), barely different from statutory diluted EPS of 7.0p - pleasing to see very few adjustments, which tends to make me believe the numbers more.
The PER on FY 9/2021 earnings is therefore currently 12.9 - that looks about right to me, as this sector rarely attracts a high price.
Balance sheet - NAV of £60.3m, less £43.3m intangible assets (which I nearly always write off) arrives at NTAV of £17.0m - that looks fine to me.
The overall structure of the balance sheet looks fine, with £16.4m cash, and apparently no interest-bearing debt.
Note 22 says there are £20m in bank facilities available, recently renewed to Jan 2025, which should help with any unusual cashflow spikes. There’s possible scope for funding a modest acquisition from existing cash/debt I think.
Being a services business, it holds little inventories. Hence the balance sheet can run quite lean with no trouble at all. Fixed assets, and capex spending are also quite modest, which I like.
It gets clean bill of health for the balance sheet from me.
Cashflow statement - this also looks good - it’s a genuinely cash generative business.
I’m always ranting about IFRS 16 having messed up accounts, so have demonstrated in the picture below, how I manually adjust lease costs back up to the top (out of financing activities), for all companies. These are operating costs, so shouldn’t be in finance charges.
This adjustment reduces operating cashflow to £10,362k, which more closely reflects the real world than the distorted IFRS 16 figure of £14,170k. If you have to make manual adjustments to accounts because an accounting standard messes up the numbers, then that accounting standard needs to be scrapped (IFRS 16). Also maybe find some people with a bit of common sense & more real world experience, to set future accounting standards?
Overall, the cashflows look good, in both years. In FY 9/2021 only 20% was needed for capex. 15% was paid to shareholders in divis (so there’s clearly scope to raise divis if they wish) and the remaining cashflow resulted in a £6.77m increase in cash on the balance sheet.
That all looks really healthy to me.

.
Outlook - all good -

.
My opinion - I’ve not read all the narrative, I just wanted to interrogate the numbers, and see if I can find anything unpleasant, and assess the valuation.
SUR passes both tests with flying colours! This looks a decent business, at a reasonable valuation.
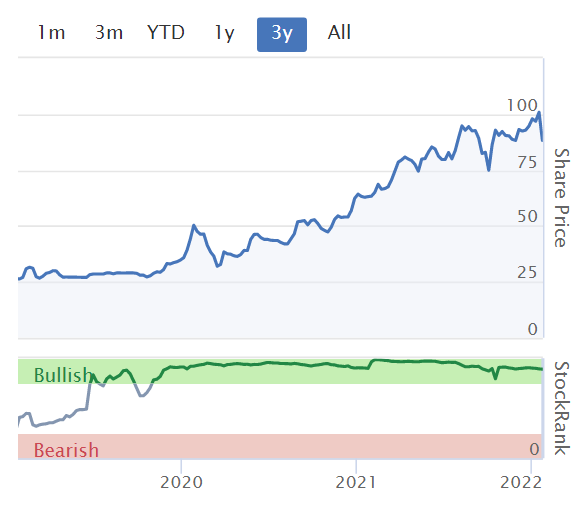
So a thumbs up from me. High StockRank too - useful because as speculative bubbles seem to be deflating now, I think that should set market conditions to favour high StockRank companies, ahead of more speculative story stocks which can do very well (for a limited time) in more frothy markets.
.
.
Jack’s section
Ergomed (LON:ERGO)
Share price: 1,115p (+5.19%)
Shares in issue: 49,138,071
Market cap: £547.9m
Founded in 1997, Ergomed is a full-service pharmaceutical services company.
Its two divisions are CRO, which provides Phase I to III clinical trial services, and PrimeVigilance, which provides postmarketing PV (Phase IV) services. The company has expertise across all common disease areas but is predominantly focused on oncology and rare diseases/orphan drugs.
Ergomed has performed very well in recent years, successfully tweaking its strategy and establishing bases in overseas markets (notably the US). The recent market sell off sees it back firmly in SCVR territory however, with a nearly a third wiped off the market cap since the start of the year.

- Adjusted EBITDA ahead of expectations,
- Revenue +37.3% (and +44.3% in constant currency) to £118.6m,
- Order book +24.2% to £240m,
- US growth of 59.5% (71% in constant currency),
- Cash up by £12.2m to £31.2, with no debt.
Unfortunately, the note detailing just what adjusted EBITDA expectations are has been left out of the update. The most recent Edison note has £24m penciled in, rising to £27.9m in FY22 and £34.9m in FY23. That’s about 21.5x EV/EBITDA for this year, likely less in the wake of today’s announcement.
Pharmacovigilance (PV) and the Ergomed’s Clinical Research Organisation (CRO) both continued to trade well in H2 and had strong order books heading into the new year.
CRO (including MedSource, acquired in December 2020) saw revenue increase by 85.6% to £58.1m and by 26.2% to £38.1m excluding the acquisition. PV revenue grew by 9.8% to £60.5m.
US performance has been driven by revenue growth, new key senior hires, ongoing investment in employment, and the integration of acquisitions. Further expansion is anticipated in the world’s largest pharmaceutical services market.
Dr Miroslav Reljanović, Executive Chairman of Ergomed, comments:
We start 2022 with an exceptionally strong platform - a robust order book, a track record of delivery and an offering that demonstrably meets the needs of a growing market. Ergomed is firmly positioned for further growth, both organically and through M&A, via geographic expansion and broadening of our service offering. We remain extremely confident in our future as a leading global provider of specialist pharmaceutical services.
Conclusion
There’s a lot to like about Ergomed, in my view.
Organic growth across both divisions, successful acquisitions, growing US sales, a robust order book, a growing cash balance with no debt, and positioned in the fast-growing rare disease, oncology, and pharmacovigilance sectors. Management has executed very well so far.
The questions remain the same: for how long can current growth rates be maintained, and are the shares too highly valued? The multiples here are roughly equivalent to that of MedPace over on the Nasdaq.
Ergomed is on the left below and MedPace on the right. Hopefully you can make out the figures.

I still grapple with the valuation. I think the group warrants a premium rating given the growth prospects and track record so far. That said, yesterday’s market fall shows that taking on companies at high valuations can invite a sharp correction. And the StockRanks are lukewarm, brought down by a Value Rank of just 18.
There is such a thing as recency bias. Just because yesterday was red for the market, it likely does not affect Ergomed’s medium-term prospects. It’s still the same company it was at 1,500p a few weeks ago. The group is growing and has been for some time. What’s more, today’s results are impacted by FX headwinds, so underlying progress is stronger.
The company is back on my radar at these levels, although I don’t tend to buy at such high multiples. I’m also instinctively wary of the phrase ‘adjusted EBITDA’... I’m curious to hear what others think of the company at 1,115p? I’m tempted to at least revisit the investment case.
Ekf Diagnostics Holdings (LON:EKF)
Share price: 66.3p (-1.04%)
Shares in issue: 463,930,564
Market cap: £307.6m
EKF is a listed point-of-care, central lab devices, and chemistry reagents business. It also has a partnership with Mt Sinai, which has led to a couple of recent stock market listings.
As a result of customer demand, EKF has invested significantly in increasing the company's fermentation capacity. Meanwhile the dramatic growth in its sample manufacture and collection business has been driven by Covid, but management is now working on diversifying income here into non-Covid diagnostic testing areas.
EKF Diagnostics Holdings… confirms that continued strong trading will result in its performance for the financial year ended 31 December 2021, including adjusted EBITDA, being ahead of already upgraded market expectations.
Trading in the core business in Q4 continued to be robust, with revenue up by more than 13% in the financial year. Ongoing demand for sample collection kits and testing remained strong.
Cash, net of borrowings, at 31 December 2021 was £19.6m (31 December 2020: £21.4m), reflecting further strong operational cash generation offset by ‘substantial investment’ in the business, as well as working capital expansion to support anticipated growth and the payment of a 1.1p per dividend in December 2021.
Significant investment was made to expand fermentation capabilities and contract manufacturing to drive further organic growth. Further investment in enzyme fermentation is scheduled for FY22. Growth and investment in the core business is complemented by a strategy to exploit expanded capabilities to meet the demand for contract manufacturing services.
Advanced Diagnostic Laboratory, the CLIA-certified lab testing business acquired in October 2021 is integrating well and has begun diversifying into non-COVID testing, ‘as evidenced by the recent partnership relating to the provision of a non-invasive prenatal testing service’.
Conclusion
What do I make of EKF? Frankly I’m still not sure. That’s not to dismiss the company, but I’m not appropriately familiar with its products, economics, end markets, and prospects. I wrote up some presentation notes in September (here) but have not looked further since then.
The Mt Sinai partnership has led to a couple of listings, and there could well be more coming. It’s hard to forecast, but it could potentially be a source of significant value.
Add to that another layer in that Covid testing is skewing results - the StockReport consensus figures suggest net profits are forecast to fall over FY21 and FY22. All in all, I think this is a hard company to value, and you don’t have to swing at every pitch.

That said, I have a positive overall impression of the management. What we do know is that this marks a strong end to the year with EKF again upgrading expectations. It comes across as a quality operator, a cut above other Covid-related stories.
The fact that the shares are down suggests the market can’t quite make up its mind right now either.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

130 comments
Re Ergomed (LON:ERGO)
Paul, you asked for comment on this company from holders or watchers of the name. I'm a fan of the CRO/CDMO "picks and shovels in Biotech" investment approach and I'm told by my bank's pharma analyst that we are still at the outset of a multi-year upcycle for such companies, bringing double digit revenue growth to all participants. Today's results for Catalent are a healthy read across and I was also encouraged by Lonza's results last week. I am a long term holder already but would be a buyer at today's levels.
”If things really get too much for you, emotionally, then just turn off the computer! I sometimes do that, and have a nap, to de-stress.”
Good advice. Basically what I’ve done since the end of October!!! So quite a long nap has been required.
Regards
Michael.
Hi Jack
Thanks for the write-up on Ergomed (LON:ERGO) . I don't hold this one, but I do hold Medpace , which I was fortunate to buy in early 2020.
I would ordinarily have sold Medpace by now given its rich rating, however, I have held due to the valuation implied by x2 CRO M&A's in 2021:
---
Medpace announced $220m Adj EBITDA for 2021 and is forecasting $270m for 2022. Taking the middle of these values and applying the same x25 multiple gives me a valuation of $6.25b.
Applying a x20 multiple for prudence implies a valuation of $5b.
The current EV is $5.8b so the downside at this moment looks limited, and should hopefully reduce over the next 12 months as the company continues to transform its large order book into revenue growth.
I'm also a fan of the rising Returns on Capital here, as well as the share buybacks.
---
Ergomed (LON:ERGO) I believe achieved £12m EBITDA in H1, so crudely I would expect them to achieve £25m for the full year.
x25 = a £625m valuation
Even applying a x20 multiple to account for the relatively small size of the organisation vs PR Health and PPD implies a valuation of £500m.
Today's EV is £535m.
So again the downside from here looks relatively limited, but I haven't really looked at Ergomed too much, or know what its order book looks like.
---
I would like to emphasise again that CRO's are not my area of expertise, but based on the numbers alone, there seems to be minimal downside for both Ergomed and Medpace at their current price levels, assuming of course that growth rates continue as they have done over the last couple of years. With Medpace thus far, there's little to imply that the growth won't continue for at least another year.
Cheers
A
Thank you Paul, that opening section really spoke to me as a new investor. This is my first time commenting, despite reading this report daily, along with the excellent comments others contribute. It's cheered me up to be honest, what a great community!
"..but Disney really is only Star Wars (Mandalorian and Bobba Fett) - the Marvell content is awful and I almost cancelled it because there was nothing else."
I think Walt Disney would be turning in his cryogenically frozen chamber if he was informed that "Disney really is only Star Wars".
Jesus wept.
Maybe you like to watch Frozen and Micky Mouse cartoons over and over again but I don't.
The rest of the content is poor.
"Eternals" was their latest big blockbuster movie and it was huge flop.
As was Wanda, Loki, Black Widow and all the other Marvel releases.
I've been cost averaging into ERGO for the past few years. I'll be holding onto this long term in my Investment ISA.
Paul, I think investing is always like being in thick woodland with a map, you can only have an approximate idea of where you are but you can look back later and work it out precisely with the map. I don't know if we are having a correction or something far worse at the moment.
However to re enforce your point about picking bargains in bad times, I've got a copy of George Blakey's 'History of the London Stock Market' in front of me and it shows that in the first week of 1975 in the depths of recession BP was available on a P/E of 2.6, with Lloyds at 2.1 and NatWest at 1.9. This week the figs would be 7.1 for BP and 8.1 and 9 for the banks, albeit neither is really the same institution that it was then, so it's not comparing eggs with eggs. As an aside inflation.eu shows CPI to have been above 19% at the time. Gulp!
Sureserve (LON:SUR) is another company where a jump in StockRank to >80 has preceded a steady icrease in share price. Is there a way to set a global alert for such SR increases, or to screen for them?
Sureserve (LON:SUR) has also spend many weeks in the Jim Slater Zulu Principle screen, which I have studiously observed, but then done nothing in response whilst the SP has appreciated!
Novacyt Sa (LON:NCYT) (I have no position) seems to have been punished for publishing an honest early strategy review and update from the new CEO.
basically trading at net cash for this year so market is saying Novacyt Sa (LON:NCYT) has no value going forward which seems a bit odd. The distribution capability alone is worth quite a bit. Bought at around 300p a while back so not one of my finest trades and should have sold when it spiked up on Omicron but no intention to sell here at net cash.
There’s a full page Private Eye Covid Investigation on Novacyt Sa (LON:NCYT) and their company Primerdesign in the current edition which holders may want to read.
Here is a link to the Private Eye article on Novacyt:
https://www.private-eye.co.uk/...
There is a worry, though, that inflation won't be "good" for the stock market. As we saw in the 70's, multiples declined towards very low values, paving the way for a stonking bull run in the 80's and 90's.
And, of course, what we care about is real returns, not absolute returns.
I seem to hold a contrarian view to most here, I haven't bought much in a while but I'm now selling some of my steady 'value' stocks - as people like to call them.
I also sold Taylor Wimpey and Rio Tinto which I was in the money on and I'm mostly looking for higher growth which has now been battered and bruised.
I know this is all about small caps but this market seems to be more about indexes falling and dragging down the large caps more.
I bought Netflix and Coinbase yesterday both at 10x EV/EBITDA after the deep ~50% sell-offs and they rallied in the second half of the day but I suspect there is more volatility to come.
Coinbase was down 14% yesterday morning when I bought and finished flat at EOD - crazy moves!
With Netflix, I don't buy the 'streaming is dead' nonsense we are hearing on CNBC and its fwd PE dropped from 47x to 25x fwd PE. Growth is still strong and I think gaming will be huge for them. APAC (India) and LATAM are huge growth areas. They are proving inflation resistant too as they increased UCAN prices 10% and still added 1.2m customers.
The one small cap I bought was THG which is just too cheap in my view but I already held some and doubled my position to average down the price as I really like the core business.
I tend to hold for the long run.
The problem with Netflix is they're now seeing intense competition from Disney and others. Reports of more subscribers signing up for a couple of months, watching the things they want to see, then switching to a different streamer. Surely this could kill the business model?
Yep that is a consideration but I would argue they are past the point of fickle content. They have a number of strong series IPs which have gone on to do 4 or more series and the content just keeps building, so new customers are getting a lot of value for the £14 pm compared to the likes of Disney.
I have both and like both but Disney really is only Star Wars (Mandalorian and Bobba Fett) - the Marvell content is awful and I almost cancelled it because there was nothing else.
My wife will only watch Netflix and I only really ever hear people say 'have you seen Squid Games' etc and content from Netflix, so I do think they have the best content in the world and certainly the best proprietary content.
Then add on gaming which they started on the app in Nov.
Disney also now producing some good 'serious' content - Dopesick and Get Back both excellent.
I seem to hold a contrarian view to most here, I haven't bought much in a while but I'm now selling some of my steady 'value' stocks - as people like to call them.
I also sold Taylor Wimpey and Rio Tinto which I was in the money on and I'm mostly looking for higher growth which has now been battered and bruised.
I know this is all about small caps but this market seems to be more about indexes falling and dragging down the large caps more.
I bought Netflix and Coinbase yesterday both at 10x EV/EBITDA after the deep ~50% sell-offs and they rallied in the second half of the day but I suspect there is more volatility to come.
Coinbase was down 14% yesterday morning when I bought and finished flat at EOD - crazy moves!
With Netflix, I don't buy the 'streaming is dead' nonsense we are hearing on CNBC and its fwd PE dropped from 47x to 25x fwd PE. Growth is still strong and I think gaming will be huge for them. APAC (India) and LATAM are huge growth areas. They are proving inflation resistant too as they increased UCAN prices 10% and still added 1.2m customers.
The one small cap I bought was THG which is just too cheap in my view but I already held some and doubled my position to average down the price as I really like the core business.
I tend to hold for the long run.
Not sure why my post duplicated, I got an error message when I clicked 'add comment' (don't blame me!)
I've found that when you get the error message occasionally, it has actually posted the comment. So you don't need to post it again, despite the error message.
Hi Paul ... thank you for all your level headed comments in far from a level headed market. Can I ask, are you or anyone else frustrated with Saga (LON:SAGA) marketing efforts? I'm a shareholder and marketing professional, so was keen to see their new strategy, tv ads and data marketing promises. So far I can't tell whether they've launched their new brand or not, I've seen their TV ad twice and think it's aimed at a niche market in the over 50's (not where the biggest opportunity lies) and they spend a fortune sending the previous owner of my house a heavy brochure every couple of weeks when they moved out almost six years ago. Also they don't appear to have a marketing director, just a very experienced (old) non exec with some marketing experience. Total incompetence ... any thoughts?
Sell your shares?
It's crossed my mind ...
Hi 55555
I couldn’t agree more re Saga (LON:SAGA) marketing. I get envelopes from them often twice a week and sometimes duplicated. I have a cruise booked with them but that doesn’t stop the paper glossies arriving on my doormat. As my headmaster’s report used to say “could do better”.
I've seen their TV ad twice and think it's aimed at a niche market in the over 50's (not where the biggest opportunity lies)
Isn't that what they do? Services for the over 50's?
I agree that postal marketing is a waste of time and resources. Do they monitor the response rate? Maybe it works for the over 50's? Im nearly 50 now but would be put off by a company sending me junk mail.
The trouble is their ads will put of those from their biggest prospect / age group ... in my view.
I just switched my car insurance to Saga - low price and very efficient quote system. I did have a look at the Saga financials as a result but they seem to have low return on capital. Cruise ships must be expensive and it's a very tough market at present. I won't be going cruising while the epidemic is still around.
Sorry been out all day so far. Would welcome your view Paul - or Jack - on the Staffline (LON:STAF) trading update today. Never a simple stock to evaluate.
Sorry been out all day so far. What is your view on £STAFF trading update please? Looks quite good but always like your comprehensive view on this stock, Paul - or Jack!
Hi ridavies,
Staffline (LON:STAF) is on my list of things to possibly look at tonight or early tomorrow, so leave it with me. We've reached capacity for today, in terms of what we have the mental capacity & time to write about!!
Best wishes, Paul.
Thanks for the market commentary today Paul, helping us to make sense of the crazy game!
I'm out mystery shopping Revolution Bars (LON:RBG) (I hold) - just to make sure my pleasant experience with food last weekend wasn't a one-off.
On the menu today, a delicious, freshly-made pepperoni pizza. Half price on mains for lunch deal, until 27 January so this pizza only cost me £4.75 - a bargain, as it was excellent quality.
The food really has drastically improved, it needed to!
it does look OK Paul, though if I had a FM Fulham Shore (LON:FUL) nearly then that would be my pref for a good pizza.
I agree - I would say the Fulham Shore (LON:FUL) pizzas are freshly made. I would be surprised if that Revolution Bars (LON:RBG) pizza dough was made on the premises.
I agree - I would say the Fulham Shore (LON:FUL) pizzas are freshly made. I would be surprised if that Revolution Bars (LON:RBG) pizza dough was made on the premises.
Well, I'm no expert but we make our own homemade pizza dough in batches, portion it out and freeze some for future use. I would defy anyone to tell the difference between fresh and frozen pizza dough when they are sober, let alone when it's smothered in tomato sauce, cheese and pepperoni and they've had a couple of drinks! And I'm very fussy about these kinds of things :-)
RBG (I hold) pizza offering was surprisingly good. Similar to, but not quite as good as FUL. In the past, RBG used horrible factory-made bases (you could see the dots on the back of it). Whereas now, it's freshly made. I queried this with the server, and she confirmed yes they're all made freshly.
I believe food is only about 20% of RBG's sales, so it's not going to shoot the lights out with better food, but I think it should definitely now be a plus, and then it gives them the opportunity to make money from people settling in for the afternoon & getting lathered on high margin drinks!
There are so many improvements, when I compare my latest visits to RBG, compared with say a couple of years ago - when you could see why profits were falling, just by visiting any site.
P.
Nice commentary on markets, Paul - there is no beating the benefits of experience !
Northcoders (LON:CODE)
Northcoders
This is my first posting after recently joining Stockopedia but I would appreciate any thoughts/ feedback on this. Thanks.
Market cap £18m with current share price of 280p (spread 3%).
This company was IPO’d back in July 2021. Issued a positive trading update today. I think it might be too small for SCVR to cover. Forecast EPS for 2021/2022/2023 is 2.5p/9.5p/36.9p respectively. Obviously, current year trading has been impacted by Covid as the training centres were shut. Shown below is today’s trading update. Feedback welcome (I am a holder).
Northcoders Group PLC is an independent provider of training programs for software coding. It offers a range of training and software development solutions to individual and corporate customers. Its offering includes bootcamp training courses, government-funded apprenticeships, and bespoke training courses, and software development solutions.
The Group has delivered a strong result. Underlying performance was in line with expectations and, as previously reported, cashflow benefitted from the additional course funding available from the Group's contract under the Department for Education's "Lifetime Skills Guarantees" and "Plan for Jobs" initiatives, secured in July 2021. Non-underlying costs are expected to be lower than expectations and therefore the reported result will be ahead of market expectations.
Revenue visibility for the new financial year to December 2022 stands at just over £3 million.
Consumer demand for the Group's core boot camp courses is growing strongly and we are pleased to report that the Group has now commenced its largest ever cohort with more than 100 students starting the course this month. With the benefit of increased marketing spend and geographic presence, the Board expects this growth in demand to continue as Northcoders significantly expands its list of hiring partners with large organisations such as AND Digital Limited, Wren Kitchens Limited and Sky Betting & Gaming.
A training hub in Newcastle has also been successfully opened to complement the Group's presence in Manchester and Leeds. Further hubs are planned to open in Birmingham and Liverpool over the next 12 months and we have received a special request from, Jason Stockwood, the Chairman of Grimsby Town Football Club to establish a facility at their stadium, which is indicative of the potential for further growth. Furthermore, the Group has also engaged with a new funding partner, Stepex Limited, allowing more students from a diverse range of backgrounds to benefit from the life-changing education that the Group provides.
As the national reach of Northcoders has expanded, the Group's Apprenticeship division also delivered contracts across the breadth of England. An increasing number of large employers, such as online fashion retailer, Pretty Little Thing, and logistics company, Hermes, are seeing the benefit of engaging with Northcoders to deliver apprenticeship courses on their behalf. The Group has also launched its new apprenticeship "hire to train" programme which is proving to be very popular with both corporates and individuals alike.
The Group is also pleased to report that the Department for Education has advised that funding has been increased further, due to the successful delivery of student courses through the first funding round. This increase entails a further £1.65 million in funding for training courses to be delivered between February and September of this year. This is a credit to the team within Northcoders who, despite increased Covid restrictions, managed to award 294 training programmes at short notice on behalf of the Department for Education in the six months ending January 2022.
The Group will release its full year results for the period to 31 December 2021 on 26 April 2022.
Paul you are the best;)
I messed this up & have deleted my original post.
I would currently put the threat of war in Ukraine at the very top of the list. I am pretty certain that the underlying message coming from the White House to Russia, is 'please get on with your invasion, we are coming under increasing public pressure to deploy NATO assets and once in situ, the Ukrainians will want NATO assets to go into the Ukraine. It will be difficult for us to deny such a request at that point, so it would be convenient if you could invade before we can deploy, i.e. sooner rather than later'!
The idea that US stocks have reached the capitulation phase of the bear market is very wishful thinking. Declines may slow from here but the over valuation is still excessive in nearly all US stocks and many UK bubble sector stocks as well. As interest rates rise over the next year and QE stops, and it will not return while inflation remains high, the bubble stocks will continue to deflate. It is quite possible that the declines will be steady from here rather than dramatic, although when the mega caps start to deflate, the market response could then become very volatile for a time.
Am I going to cash? Of course not, my stocks are very under priced. If you are a long term value growth investor, you cannot be deterred by a bit of short to medium term market volatility. My Tesla short, which I have held for a couple of months now and is my only short position is doing nicely, but again, my Tesla short is a long term position.
Comments on today's Anexo recommendation from elsewhere was very interesting I thought!
The net tangible equity does appear to have grown at an average rate pa equivalent to c10% of the current MCap.
What I cannot understand is, why, with all that equity build up and a small dividend, the level of net debt just keeps on growing year after year.
Surely for a business like this, that is not based around the need for a high tangible asset base, any build up in tangible equity, would surely be in the form of cash. Yet quite the opposite is happening.
Any thoughts anyone?
The above, my first post, was so odd that I had a look at the full accounts.
Lease liabilities from IFRS 16 are about £14m - not really debt in my view, so long as the business remains a going concern that is. Net debt in the loan/overdraft etc sense is c£31m. But, this is still very stange given the huge tangible equity build up, why is there not a big pile of net cash, which there is not, there is actually only c£1.4m of cash and net debt of c£31m. Retained profits, a cumulative figure on the balance sheet is a whopping £99m, so where is it all?
The answer is in the trade payables and the trade receivables. Trade payables c£9m. Trade receivables c£160m and rising steadily - yikes! All these declared profits, have not yet been received.
Russ, you deserve to have your a... kicked for not spotting and highlighting this!
Wonderful thing a balance sheet, it tells you almost everything. And the most wonderful thing about the balance sheet is that about 95% of investors pay little attention to it, giving those who do look at the balance sheet properly, a clear and sustainable advantage as investors.
Isn't Bogdan Branislov your own handle on Telegraph...?
My wife tells me I laugh at my own jokes too often, so I empathise with finding your own comments so interesting :)
Expecting Value
Isn't Bogdan Branislov your own handle on Telegraph...?
You might have hit the nail on the head there ;-)
This is not a joke, Anexo is no laughing matter.
I don't like Anexo (LON:ANX) regardless of how much growth or profit it has as its niche exploitation of odd rental car and insurance markets looks like a regulator intervention or Sunday Times expose waiting to happen around price gouging or unnecessary insurance premium inflation (insurers like very predictable cost inflation that they can use to bump up premiums).
But I'd expect the receivables to be really slow coming through so large as insurers are usually very very slow to settle anything around car accidents. To some extent Anexo balance sheet is off balance sheet financing for insurers...which the insurer gets the consumer to pay for so its free...which brings me back to the regulator or CMA etc
I think Anexo have a business that should be run my a private credit house and not a listed equity vehicle. The blow up terminal risk is high...and the first whiff of it in the market will see 50% off the sp...on the way to zero/delisting as they will need capital for financing and that will only come private
The Anexo profits are not real, they are not being received.
The profits are real according to accounting method...they just wait for a long time for translation into cash?
Yea, 2 years worth of turnover, but why should that worry you, it will arrive in the end, course it will guv, course it will!
"The Anexo profits are not real, they are not being received."
The auditor does not share your view.
Look at the full Anexo accounts, the asset column is completeley dominated, as is the P&L, by trade recievables. But they don't have the money, it is not in their posession. This equated to c2 years of turnover for Anexo. But hey, the auditors are happy so why should you not be, whay should you worry about 2 years of unpaid invoices, I mean auditors never get it wrong do they!
Doug2b. A mega first post! Where does Bogdan Branislov come into it?? I know he posts frequently on the Questor column in the Daily Telegraph and has had an article about him on the DT but otherwise I wonder about him.
What about Bogdan do you wonder exactly?
Doug2b
Initially I wondered if he was real. Then after the DT article I assumed he is real. Then I became curious about his investment style. ISTR from the article that he is a retiree who holds a concentrated portfolio and has done very well. His comments seemed very rational to me and I began to look forward to knowing more about him. Maybe you can help me here??
Doug2b, Bogdan Branislov and Vladimir Pokrov on the LSE BB are one and the same, I have said that before obviously.
Why am I here on Stocko? Ideas, things that I might have overlooked, you can only cover so much ground yourself, so I sift for ideas, Stocko has had a few good ones of late - ScS, Plus500. Watkin Jones today was not quite there but was a sensible business to assess.
Also, I don't know any other active investors in real life if you know what I mean. I know people who put money in stocks but not active investors. It is good to talk to other investors, even if I don't agree with them.
The Rus-Ukr stand-off has been going on for 8 years.
Rus say Nato are just stoking tensions, NATO say Rus have mobilised 60 units. Either way, it has become so public now, it seems difficult for Russia to advance with the world fully engaged.
China and Taiwan, however? But with the Beijing Winter Olympics, it doesnt seem like China would consider it and ruin their own party.
My hunch is that these are still tail risks and rate rise induced rotations are a bigger risk but I have bought much for a while, so I'm on the lookout for some discounted quality in the next two weeks.
Rus say Nato are just stoking tensions, NATO say Rus have mobilised 60 units. Either way, it has become so public now, it seems difficult for Russia to advance with the world fully engaged.
Unfortunately, the reverse is also true. The more it gets built up, the harder it is for Putin to back down. It's not clear how this ends yet.
I suspect Putin really only wanted to deflect the Russian public away from the 1000+ covid deaths, like when Macron kept going on about fish and blocking HGV drivers while cases sky rocketed in France.
He may well say "I defused the situation as a grand keeper of peace" in a grand gesture - he has done that before.
There is a tradition of UN countries observing an Olympic Truce starting seven days before the games and ending seven days after the end of the games. The Games are scheduled to run from Feb 4th to 20th.
Also Chinese New Year is Feb 1st this year.
https://www.un.org/en/olympict...
As we saw in early 2020, when the pandemic hit, markets roughly halved, it was total carnage, then they recovered. People who held their nerve recovered all their losses.
The unusual deep V shaped bear market in 2020 was one of the worst lessons any new investors could learn. When a multi year bear market turns up at some point buy and hold regardless of price action is going to be a painful experience. I don't know if it's already started or it's years away but you can't assume there will always be a swift reversal. I lived through 2000-2003 and 2007-2009.
Back in 2007 on TMF several investors thought RBS and LLOY looked like good value. To see the damage a longer term bear market can do look at a 20yr chart of LLOY. Buy and hold would still have a major capital loss 14 years later. At least LLOY survived, hundreds of small caps disappeared in the above bear markets.
Unwise2
If I remember correctly on TMF there was one guy who insisted on putting everything he had into LLOY. I wonder where he is now?
Personally ISTR holding up to about £7-8 and bailing about £4. Mind you we made up for it in spades on the Prefs.
My Brother in Law held all the way down and is still sitting on a very large loss.
I think the person you are referring to regarding Lloyds Banking (LON:LLOY) on TMF used the name Jimsusan. I understand he also had some buy to let properties so he wasn't completely exposed to Lloyds. I have no idea where he is now I'm afraid.
Jimsusan - there's a blast from the past. I think he went radio silent before TMF closed down didn't he. He was always good for stirring up a controversy.
Yesterday was a bad day for the markets but I'm glad I don't hold Vela Technologies (LON:VELA) which is down -98% today. Ouch!!
Vela Technologies (LON:VELA): it's not 98% down...
"Vela Technologies PLC Reverse Split For VELA.L - Ratio 1-50"
Not sure Logical David but I think Vela Technologies (LON:VELA) was doing a 1-50 share consolidation this month that today has been cancelled. Don't think the price has actually collapsed.
Hi Paul, absolutely love the mkt thoughts section!
Can you take a look at Sureserve (LON:SUR)?
Is the mkt sleeping on this one?- long gone are the Lakehouse days of low margin, heavily indebted, construction and property services contractor.
Now a cash rich, buy and build, compliance and energy services business with recurring revenue and good revenue visibility backed by green investment commitments looking to acquire in a rapidly growing energy services mkt.
The current valuation doesn't stack up with Premier Technical Services (LON:PTSG) take out multiple, Smart Metering Systems (LON:SMS) vs the Providor part of the group or even where Marlowe (LON:MRL) trades?
In an sector which potentially lends itself very well to an acquisitive strategy, this has to be valued higher surely or will itself fall victim to a takeover?
Appreciate your thoughts
Morning Wolfy!
That's an interesting teaser on Sureserve (LON:SUR) - thanks, I'll try to have a look later.
Regards, Paul.
Does anyone have a view on Revolution Beauty (LON:REVB)?
Revolution Beauty (LON:REVB) IPO’ed in May 21 and is now 40% below the starting price. Net debt is -16m, so cash in the bank and currently has an Analyst Forecast price of 2.43p compared to 98p this morning. Revolution Beauty (LON:REVB) released interim results in Nov 21, which on the surface looked good (although I am not an expert so have likely missed something fundamental). First Bullet points from the results:
INTERIM RESULTS FOR THE SIX MONTH PERIOD ENDED 31 AUGUST 2021
Thanks,
Andy
I think you mean 243p TP?
Yes, I do, my mistake. Thanks ( can't change it now as my 1 hour allowance is over)
I hold Revolution Beauty (LON:REVB) and think they’ve got the potential to be a disrupter in the sector, but as a growth company likely to get beaten down at the moment!
Thanks Paul good read this morning.
I am retired and living off dividends so to me short term share price changes are irrelevant so long as gradually increasing dividends are maintained. If a company is paying £1 per share dividend, does it really matter whether the share price is £20 or £30 if you are not selling? Over the long term it is not unreasonable to expect some share price growth, but short term price movements is just "noise" in my view.
Fonix Mobile (LON:FNX) released a "comfortably ahead of expectations" this morning and look very reasonable on valuation grounds. Profit growing at 20% YoY. EBITDA and PBT are more or less the same so we can expect around £12m for the full year I think. That puts them on about 13* with net cash and a 4% dividend that they say they re expecting to increase.
Interesting to see CEO say he is expecting to announce significant developments on the international front later in the year too so that might add some interest in H2.
Another one that got hammered yesterday but recovering some ground on the back of the trading statement today and looks good value to me. (I hold)
Fonix Mobile (LON:FNX) ( I hold)
Is a very good example of what happened yesterday in the small cap world. The price got marked down around 10%, there were about 50 trades, nearly all small sells , presumably small investors' stop losses being triggered and then this morning an unscheduled 'comfortably ahead' trading update is released and the price recovers most of yesterdays losses.
Richard
I am not sure what Thg (LON:THG) would have to fall to before I would be tempted. 50p-75p? I would be interested in other views. In the current market I am not sure I would have the nerve, even if there was a clear 3-5 year pathway to profitability.
Gross margins are 43% and top line growth is >20% even post covid.
It's depreciation and amortisation are high because they just spent £1bn on new head offices, brought in 6 new warehouses, building two fully automated distribution centres, one in the US and one in Europe, also bought Dermastore for £251m which will all be amortised but provides strong cashflows, and Cult Beauty for £275m - this one was expensive.
It was falsely attacked by Numis who released fake stories about accounting irregularities on working capital and had to HAND THEMSELVES into the FCA - really quite staggering!
Link here - https://www.sharecast.com/amp/...
Thg (LON:THG) itself has handed evidence to the FCA of this short attack on the business: https://www.theguardian.com/bu...
There has clearly been some funny business going on here by city brokers.
Bloomberg even ran a fake story that THG were going to sell the beauty divisions which THG official spokespeople later denied and was included in the article but Bloomberg ran the story anyway: https://www.bloomberg.com/news...
The company as it stands is valued at 0.6x sales, below book value with 43% gross margins and strong growth in nutrition and beauty businesses; particularly in the US and Japan (the core business) and Ingenuity has no value at the current share price - I was always more interested in the rest anyway.
I bought a small 2% position in my portfolio at 550p originally. (people will say obviously too high in hindsight but a valuation I still think it is worth given the underlying business and growth when considering comparables)
I added to that yesterday at 124p.
Frankly, the orginal valuation wasn't crazy and still isn't when looking at comparables but I do think something funny has gone on and the more time has lapsed, it seems more and more likely.
People will always have their own claim on what they think they knew but we could sit on the sidelines all day and say everything is overvalued or buy cheap stocks and they only get cheaper because they are cheap for a reason....
High growth at a low price is the best of both worlds.
Thornabien Thg (LON:THG) was crazy price with some questionable businesses and accounting too as I pointed out in late 2020. Here's the bet I offered for 2021 against super dull and dead Lloyds Banking (LON:LLOY) - it was prompted by your cheerleading of Hut back then (which I assumed you owned around highs and not just 550p):
https://www.stockopedia.com/co...
What do we think for 2022? Does 'super high margin growth' Hut beat slow dull Jabba the Bank? Double or quits?
(Winning margin approx 100% with Lloyds +30% and Hut -70%!)
As I just pointed out, the 'questionable accounting' was a fake story which Numis researchers ran and had to hand themselves into the FCA - I don't think you can take any credit for that, it was a lucky and false turn of events.
As for the valuation, it was high but warranted given the 92% growth - revenues have more than doubled and gross margins only fell from 44.8% to 43% last year. Net is largely pointless at this stage when they have just invested billions more than their revenue base to grow into the future (as I also pointed out above and last year).
When a company with 43% margins and high top line growth of 20-40% is valued at lower multiples than say a BT or a Lloyd's with less than 5% growth, there is something wrong with the term 'value' - is there not?
I will still go for that bet, that THG will have better 5 year returns than Lloyd's.
And no, I bought at around 550p.
You are wrong on all your points.
1) The bet was 2021 and not 5 years
2) Questionable accounting /business model was my view as expressed back in the day and not riding the Numis stuff...i read some of Thg (LON:THG) reports and dug in. For example they do not adequately disclose the revenues from Ingenuity historically and it looks like there may be a bit of shell game going on with the repurposing of effectively internal IT spend to look as if its part of the super high growth exiting Ingenuity platform for external sale. Then actual cash flows that a business needs come from old world assets that require high capital cost.
3) Pay for future growth not past growth
4) High investment means nothing without return on invested capital
5) Private/venture companies often achieve very high top line growth by burning capital for it
6) Gross margin is irrelevant if the company is flawed
Your analysis seems to start with Thg (LON:THG) will be great...so buy at any price. IMO that's dangerous in public market companies.
But I'll take your 5 year bet...I would have declined a 2022 fyi....and remember the starting point is from way behind Lloyds Banking (LON:LLOY) given my amazing 2021 call ;) I believe Hut will have a continued high cost to achieve growth and its doubtful there is a high return generation off ramp to high free cash flow return
Essentially, your only criticism is all about Ingenuity.
However, Ingenuity wasn't even priced in to the share price at the time and it certainly isn't now.
Of the £2.2bn in revenue, it is almost all Nutrition and Beauty and they both have 40+% gross margins.
So to say Ingenuity had strange revenues doesn't cut the mustard I'm afraid.
The real issue investors had with Ingenuity was how it would be transfer price internally if Softbank took their option of 20% stake. That is a fair question but not one which justifies a 80% drop.
It has only fallen 80% because false news was circulated of accounting irregularities - for which Numis will likely face a big fine for as they seemingly purposefully lied.
High contribution from revenue streams and high gross margins are exactly the sign of future return on assets. Net margins in the short-term are completely irrelevant if you have just spent half your EV on new assets which will be amortised or depreciated each year.
All of your other points don't ring true and are centered on the concept that no one is buying from their core businesses of Myprotein, LookFantastic and Dermastore but they are and they are doing very well.
Errr no! But whatevs dude...slammed you 2021 being really dumb ;)
You mean got lucky that a false libellous story was run? A FALSE story.
It isn't over yet as it has been proven to be false, so let's see which is ahead in the next 6-12 months because none your other criticisms of the business actually make any sense.
Your darling Lloyd's is hardly doing well. I have plenty of stocks in my portfolio which completely outstripped its returns in 2021 and I'm sure THG will also bounce back and outperform it before long.
Ooooo....you had many stocks that did better than Lloyds Banking (LON:LLOY) ...I applaud your brilliance. I bought Lloyds and other banks at the bottom of the market. Not as they great or have been great in the past but as risks were very clearly mis-priced. Plus imo banks are in a position to be secular winners once a new credit cycle starts...I sold out of them (for a tidy profit over Thg (LON:THG) ;) ) once I realised the cycle was likely delayed.
TBC dumb in the phrase "slammed you 2021 being really dumb" was referencing me being such a dullard for saying Lloyds (deliberately chosen as so dull) would beat Hut
You are incapable of not going totally batsh1t if people don't agree with you. We are discussing a stock Thg (LON:THG) that has fallen over 80% peak to trough and you are calling me out as wrong. If a story is demonstrably false then why is the stock still down so much? Maybe there are other reasons? Selling some beauty products well or having a few prestige clubs for northern celebs/footballers doesn't place you as the next Amazon (a stock you referenced in the context of Hut back in the day and got really upset with me when I pushed back on that). (Answer: the stock didn't deliver to its high expectations and ridiculous valuation).
Hut may prove itself out over time. You offer nothing but faith as an argument.
You are being very silly. I no longer want to play with you on Hut and I will take away my ball. I scored a goal and you make up any old nonsense to cancel it.
But it is fun to have a pop at your hysterical banalysis...so I'll be back....
I wrote some long comment's in yesterday's SCVR report on Thg (LON:THG)
Thornabian has written more bull-case analysis.
Over time, I've appreciated that stock values are irrational most of the time. Story plays an important part. See examples like Best Of The Best (LON:BOTB) . That is an example of investors following a Positive Story, and extrapolating short-term results to the moon.
However, the reverse happens too. Negative Story. Where every Tom, Dick, Harry points at a company and says "its nuts, there are so many things wrong with it, why would anyone want to buy". Tesla had that when it was punished to $300-$400? Who remembers Musk's 420 tweet? How we laugh now at Musk potentially taking Tesla private at $420. Facebook too, trading at $20 at one point. What did both have in common? Yes, real problems. But short term problems. Missed profit/revenue expectations. But those were short term targets. Crazy C-suite blunders (Musk, Zuckerberg). But those blunders not repeated.
I see parallels to THG now. Yes, they have some problems. But they are all fixable IMO. They have missed profit forecast. But that was this quarters/years, not the future years. The CEO and his mother have had moments of insanity. But will these continue? The newspapers are full of negative things on THG at the moment, but that is to be expected. The media loves to be a bully, piling in on the weakest company or politician at any point in time. But then they move on when there is a new target, and THG will be forgotten in a few months time.
Just as one should not get swept away with the Positive Story stocks and think any price is a good price because it can only go to infinity, neither should one get swept away with the Negative Story stocks and think they are investible.
(I hold)
Completely agree.
And you make a very good point which a lot of people forget because they ignore the business and only look at the price or the price vs balance sheet alone, but that does not tell you future return on those assets.
Tesla is a good example when it also halved from ~400 to ~180 and the doomsters (even me at the time I must admit) thought Tesla was finished...
There is also the famous interviews with Bezos in 1997 and 1999 when he tells of how Wall Street analysts told him his business was a glorified book shop and the share price kept falling but he explains how he could see everything he was building internally to set it up for the future.
They couldn't understand how $0.3 per sq ft was relevant vs $7 per sq ft of prime real estate. At the time Amazon only had 3000 employees and 4m sq ft of distribution space (about the same as THG now coincidentally) and was valued at $30bn but proceeded to lose 90% of its value in the dotcom bubble crash. Even if you invested $1000 at $30bn dotcom peak, you would have $15,500 today....not a bad return.
Not saying THG is Amazon but I do like what the business are doing and also if I own 2% of my portfolio in THG and it does 5x in 5 years time because of a reprice, then I make a lot more than buying something at say 5% of my portfolio and it only making say 5% per year or any variations of that.
Same can be said of many companies e.g. oil companies are cheap because they have diminishing returns on assets as disruptors taper their cash cows. (EVs)
True. The trick, of course, is to distinguish those that are affected by Negative Story (and will recover), and those that are truly in Terminal Decline and will be $0 at some point.
No easy task! :)
For sure and diversity is key for that.
I had a couple of really good ones last year which is expected as the market was quite hot anyway, and one this year with $ATVI which I bought in Jan on the big employee issue sell-off.
10x EV/EBITDA for the world's best gaming content seemed like a bargain to me, even with employee issues - and Microsoft seemed to agree.
I do buy some boring stuff too :) like when Rio Tinto hit 11% dividend yield, even if the share price falls, it's not a bad steady return even if it gets cut a bit on commodity price cooling. Etc. Etc.
Is this not usually what happens, once the apparent clouds have cleared (i.e. coming to the end of the pandemic), this is precisely when we would expect to see a market correction/crash?
For years we have had this twisted logic of bad (economic) news being good news (for markets), and people are now surprised that when the outlook looks brighter that markets should fall? I have to say I disagree with the suggestion that US base rates of 1%+ by end of the year would "not be a big deal", I think given the conditions markets would crash in that instance. This reflects how dislocated things are within a historical context. All just my opinion of course, it will be an interesting year for economists, of that I'm sure.
I must admit to looking at all this through the prism of US markets, since (unfortunately, and unjustly imo) UK markets seem to be inexorably tied to downside US market movements. I have to face the reality of this that I am confronted with, and adjust accordingly. No use complaining about it, it only seems to be getting worse in any case. I plan to continue to keep powder dry for lower levels.
Yes 0.75% rate rise might not sound much but is huge in bond market terms (the biggest and more influential market, which effectively sets price for rest of the market). Debt levels are now so high (across consumers, governments and corporates) that such a move would lead to a more than doubling of interest payments.
For future growth in businesses needing to borrow to grow in the near-term - sure.
However, the discounting affect from 1% on future earnings is actually really small. It is better to have a business growing at 20% CAGR with a 30% higher valuation than a business which only grows 5% CAGR - this is a tricky exercise to do as there are multiple variables, which is probably why investors spend their whole lives arguing about it.
Businesses with very strong cashflows or long-term locked in finance are in a good position here with a depressed valuations and markets in panic stations.
We should also note the Macro picture of Govt debt from covid being very long term (many 30+Yr debt was issued) at historically low rates and borrowing is actually coming in much lower as tax revenue from growth exceeds forecasts.
UK £10bn less borrowing than expected, opening the door to tax cuts and a Conservative Govt now desperate to impress and keep the talk away from parties; which will provide stimulus.
Thank you so much for your pre-amble Paul, it has restored my sanity after yesterday.
Amongst the carnage of my portfolio, it was good to see Ergomed (LON:ERGO) report very strong numbers today (I hold). I have been buying the dip on this company ahead of results. I was extremely nervous given the high PE, and any sign of slowing growth or higher costs would be severely punished. This has the hallmarks of a company that is tremedously well managed, the CEO and CFO or very experienced, and it seems to have a lot of runway ahead in terms of geographic expansion and services (with growing cash pile for M&A). This is one that I will continue to add to if the market hits them hard in the weeks ahead.
Thank you for your analysis Paul. I really needed to read this today!
Paul, may I ask which provider(s) you use for your spread bet accounts please?
Also, would you be able to look at £SUR Surserve today at all?
surely the biggest current negative factor of those listed is Ukraine. The huge impact of a misstep here makes the negative case scenario a large negative number under most probability assessments.
I'm still attempting to figure out if my owned stocks are overpriced? How do I calculate the intrinsic value using the datasets that stockopedia provide?
Depends on your strategy Lee, Value or Growth...I like the Naked Traders way of value, very simple but will exclude a great many companies at a glance. I am sure others may have options for you. Best of Luck to you.
Hi Lee. I do it in my spreadsheet. It is based on a time weighted average of the following two share prices so as to calculate my expected share price in 12 months from now:
My first year forecast PE ratio X my first year EPS = Share price based on first forecast year
My second year forecast PE ratio X my second year EPS = Share price based on second forecast year
Morning all,
Great stuff this morning Paul!
Looks like Microlise (LON:SAAS) could be a short opportunity...
Just read this with my morning tea. So glad I logged in this morning quite reassuring. I had plans to enter the market with some new buys yesterday and glad I didn’t. One of my biggest holdings is £TAY (Taylor Wimpey) with its price drop I’m very tempted to buy again, any thoughts?
All house builders looks like a good price to me. plenty of cash and dividend of 7-9%.
I have all of them and therefore can not buy more but its good entry for others.
high interest rate, cladding, windfall tax and over priced houses are issues causing the drop.
Between Barratt Developments P L C (LON:BDEV) and Vistry (LON:VTY) , does anyone have some interesting views why to choose one over the other?
Both are on my watchlist, both are acceptable buys for me having done my research, and both are at prices which I am thinking of pressing the buy button this week.
I’ve no depth of knowledge of £vty or £bdev but by way of a (possibly not very interesting ) systematic tiebreak a comparison of the two on Stocko gives Barratt as the winner. Also, Barratt passes 10 long screens whilst Vistry passes 5.
Hello Mr Beak
How exposed do you think Taylor Wimpey (LON:TW.) is to the cladding issue.? I anticipate the government will be much more proactive approach in the near future to the building companies' responsibilities for cladding replacement which is currently described as 'voluntary'.
"We will manage new business volumes to ensure the Group remains well capitalised throughout but before we return to normalised origination levels it is anticipated that there will be a temporary reduction in the overall size of the Group's loan book. Although these factors will continue to have a negative impact on capital generation and profitability in the near-term, it is absolutely necessary that we invest and manage the business appropriately for the future success of the Group.
The Board is confident that this investment coupled with the improvements in culture, governance and controls, and technology will allow the Group to overcome the current challenges"
[SP=23.8 Cap=60m]Oxford Biodynamics (LON:OBD) FY results released this morning. Revenues fell to £0.3m and the operating loss increased to £7.5m. A tough year with a lot of work continuing in the foundations but not a lot to show for it above ground yet. Management are confident 2022 will see rewards for the hard work come through.
The EpiSwitch CiRT (Checkpoint Inhibitor Response Test) which we are reminded will be launched imminently following completion of validation testing, could be a real game changer for patients and OBD. The test is the only smart blood test the specifically reports a patients likely response to immune checkpoint inhibitor (ICI) monotherapy and ensures the patient can make an informed decision on whether to start on an ICI treatment or consider other options without any lost time. The test has been presold since late 2021 and evidence of its use and utility will be fed into ongoing interactions with US healthcare payors. This is potentially a very large market if they can get this right.
Full release here
Management present at a webinar at 1pm today. Register here
Im am u lucky holder of Oxford Biodynamics (LON:OBD) and was convinced that two institutional shareholders (Vulpes and Armistice) knew what they were doing. Sadly, it seems like while the technology is good, management are incompetent in making any commercial progress.
Delay after delay for their covid test (CST) and cancer treatment test (CIRT).
The valuation is definitely bombed out, and I can see either shareholder taking it private with a cheeky small premium and keeping future upside to themselves. But also the company is rapidly cash burning and unable to even get the product across the finish line, and start generating revenues.
(I hold)
Interesting that the Chief Scientific Officer of £OBD has bought roughly £30k of shares today. He does have already a big stake, so this barely signifies additional conviction, but he hasn't bought for a long time.
Significant, seeing how the key drop today was due to news of delays in producing validation data for CIRT, their crown jewel, which is holding back sales starting. One would expect the Chief Scientific Officer to have the best feel out of the C-suite whether the validation results are near, and whether they will be good.
The proof will come if the rest of the C-suite and/or board buy, which they have been doing over the past year. Also if Vulpes, largest shareholder and 10+ years, dip their hands into their pockets again and raise their stake from 15%.
At the current prices, it is almost half of the last fundraising round in October 21.
Well, the CEO doesn't hold any shares at all. I queried that during today's presentation. He replied that as he is living in the US, he finds it very difficult to get hold of any stock but the shares are a steal...Make of that what you will. Is it difficult to buy AIM shares if you are living in the States? Maybe it is.
Really good stuff Paul, thank you. Although I find most of what you say reinforces my belief in my investing style, I find the fact that you leverage puzzling. I'm a fan boy, I admit, of Warren Buffet & Charlie Munger and a few others who share the same methods and principals to selecting companies. 2 Mar 2018 — “There's only three ways that a smart person can go broke…'liquor, ladies, and leverage.” -Warren Buffett. How do you rationalise using leverage?
Morning MarkB,
How do you rationalise using leverage?
I don't want to get into that right now. Some other time.
P.
I am reminded of the old George Best anecdote. He was in a Hotel room, drunk, with the Miss UK, beauty contest winner, and pound notes spread out on the bed. A porter comes to his room, and as he's leaving he says: 'George, where did it all go wrong!?'
Paul, you should ask Ed for a raise - these morning preambles are worth the price of the Stocko subscription alone. Many thanks for your continued efforts!
I don't know what will happen short term but IMO this looks like an excellent time to take risk. We are highly unlikely to fall into a structural recession now at a point when we haven't really recovered from covid hit. Things are very out of whack and not really a steady state trend in place so its possible we see some volatile numbers in economic series including some negatives (perhaps sharp at times). Nevertheless, the underlying trend is likely to be recovery and building activity.
However, its unlikely to be an excellent time for meme-ish and story stocks. I think PIs are quite exposed to them and they could continue to disappoint. Self propelled growth and cash-flow generation is where to be IMO.
I totally agree with all of that Mojo, thanks for posting.
Story stocks are best avoided altogether in my opinion, but in a roaring bull market there can be fantastic speculative gains to be made by traders, as we've seen. But the mood now has totally changed, and story stocks are probably the worst place to be right now.
I think balance sheets & cashflows are now more important than during the boom. That's because companies coming to the market now, asking for more money, could have the door slammed in their face. Placings might only happen at deep discounts, if at all, for cash-strapped companies. Hence we need to be much more vigilant about balance sheet strength. We can't just assume every company will be able to muddle through.
I'm also wondering about fund managers possibly facing redemptions, hence forcing them to trim positions in the market. That can be a horrible headwind in bear markets. People do tend to take money out of under-performing funds, and the performance stats for lots of funds are likely to look grim, after big falls in the autumn, and wider sell-off this January.
Or, everything could settle down and recover, we don't know!
Regards, Paul.
Agreed Paul. Particularly volatility causing down in small and micro caps
Excellent work Scott! Love the intro. For once in my life I'm going decline this opportunity to sell/buy and pointlessly muck about. Doing nothing is going to be my plan of action. Lets hope we've got it right!
May I throw Sureserve (LON:SUR) into the hat this morning.
Revenue up 24%
Operating Profit up 40%
Profit before tax 76%
EPS 7.1p vice 4.0
Net Cash 16.5m vice 9.8m
167 contract wins in the year worth 417m
Does this sound like a company that deserve to dive over 10% yesterday?
One of only 4 on the Jim Slater screen.
Thank you Paul for your thoughtful commentary. I am not geared. I have been through each of my 27 holdings many of which have no debt and I am sitting tight.
My main concern is liquidity leaving the London Market which is a worry.
A positive update from Ekf Diagnostics Holdings (LON:EKF) - although I suspect most share prices are currently determined more by the general market sentiment out there than any operational considerations:
"EKF Diagnostics Holdings plc (AIM: EKF), the AIM listed point-of-care, central lab devices and chemistry reagents business, confirms that continued strong trading will result in its performance for the financial year ended 31 December 2021, including adjusted EBITDA, being ahead of already upgraded market expectations."
https://www.investegate.co.uk/...
IF
If you can keep your head when all about you
Are losing theirs and blaming it on you,
If you can trust yourself when all men doubt you,
But make allowance for their doubting too;
If you can wait and not be tired by waiting,
Or being lied about, don’t deal in lies,
Or being hated, don’t give way to hating,
And yet don’t look too good, nor talk too wise:
If you can dream—and not make dreams your master;
If you can think—and not make thoughts your aim;
If you can meet with Triumph and Disaster
And treat those two impostors just the same;
If you can bear to hear the truth you’ve spoken
Twisted by knaves to make a trap for fools,
Or watch the things you gave your life to, broken,
And stoop and build ’em up with worn-out tools:
If you can make one heap of all your winnings
And risk it on one turn of pitch-and-toss,
And lose, and start again at your beginnings
And never breathe a word about your loss;
If you can force your heart and nerve and sinew
To serve your turn long after they are gone,
And so hold on when there is nothing in you
Except the Will which says to them: ‘Hold on!’
If you can talk with crowds and keep your virtue,
Or walk with Kings—nor lose the common touch,
If neither foes nor loving friends can hurt you,
If all men count with you, but none too much;
If you can fill the unforgiving minute
With sixty seconds’ worth of distance run,
Yours is the Earth and everything that’s in it,
I've got The Desiderata next to my bathroom loo, to read every morning!!!!
As the author, Rudyard Kipling deserves to be acknowledged for this.
Whenever people start quoting "If" I tend to think Oh dear, things really are getting bad.
Excellent analysis Paul. Im a lot happier after reading that with my first cup of tea of the morning !
Me to