Small Cap Value Report (Tue 25 July 2023) - QUIZ, TSTL, RCH, WIX, STEM, PIER, FA., YU., ECEL, TYMN

Good morning from Paul & Graham.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
I've re-jigged our agenda, with very brief comments on things we've not covered (which should explain why not covered) - let me know if this is helpful or not -

Summaries of main sections below
Quiz (LON:QUIZ) - 10.15p (£13m) - Final Results - Paul - AMBER
I review (reader requests) FY 3/2023 results, which looks quite good. Although current trading section concerns me, and looks like a £3m shortfall on profit vs LY. I struggle to see how that can be fully recouped in the rest of the year, so risk of a profit warning looks quite high. Balance sheet is strong though, and there should now be tailwinds from freight & forex. I'll stick at AMBER for now.
Tristel (LON:TSTL) - 355p (pre-market) £168m - Trading Update - Paul - AMBER
An encouraging update, with buoyant demand, but greater than expected profit largely recycled into increased overheads. All eyes will now be on the US launch, after FDA approval in June. Valuation is demanding, so it needs to deliver considerable growth to justify the price.
Reach (LON:RCH) - up 9% to 74.5p (£244m) - Half-year Report (in line)- Graham - GREEN
Full year profits are expected in line: the consensus forecast for adjusted operating profit is an incredible £94.9m. I remind myself and readers of the pension deficit and the legal issues surrounding this company. It could be an interesting time to take a punt on this one.
Wickes (LON:WIX)
SThree (LON:STEM) - up 4% to 364p (£490m) - Results for H1 (in line) - Graham - GREEN
My favourite recruitment stock issues H1 results and confirms that it’s trading in line with full-year expectations. It’s tough for the company to show growth this year, as 2022 saw a bonanza in post-Covid recruitment. But the overall story here is very impressive, in my view.
Brighton Pier (LON:PIER) - down 28% to 41p (£15m) - Trading Update (profit warning) - Paul - AMBER/GREEN
This profit warning looks quite mild to me, and Cenkos confirms this with a modest downgrade to forecasts. Still expecting to be profitable in all 4 divisions. Tiny market cap now, so I see potential speculative upside, for special situations investors. Debt looks manageable, and Luke Johnson is the biggest shareholder, so something could happen maybe?
Quick Comments -
Fireangel Safety Technology (LON:FA.)
Down 28% to 3.1p (£9m) - Trading Update - Paul - RED
Another heavy loss for H1, and the recent equity fundraise which I mentioned on 7 June 2023 doesn’t seem to have been enough - it still has hefty net debt, and is over-stocked due to disappointing sales. I’m keeping my negative view of this one, and think there’s a very high chance of a zero outcome for shareholders. New management will need a miracle, and another placing, to sort this out, which doesn’t look likely at this stage unfortunately. I would resist the temptation to speculate (or average down) on this one, as risk:reward looks awful.
Yu (LON:YU.)
Up 6% to 790p (£132m) - Trading Update - Paul - AMBER/RED
Yü Group PLC (AIM: YU.), the independent supplier of gas, electricity, meter asset owner and installer of smart meters to the UK corporate sector, is pleased to provide an update on trading for the six months ended 30 June 2023.
A very nice update today, with the key part saying -
As a result of the accelerating revenue profile of the Group and significantly increased EBITDA margin expected to be achieved in FY 23, the Group expects to report results substantially ahead of current market expectations.
Paul’s opinion - there’s no denying that the figures here look fantastic (and with an ahead of expectations update today on top) -
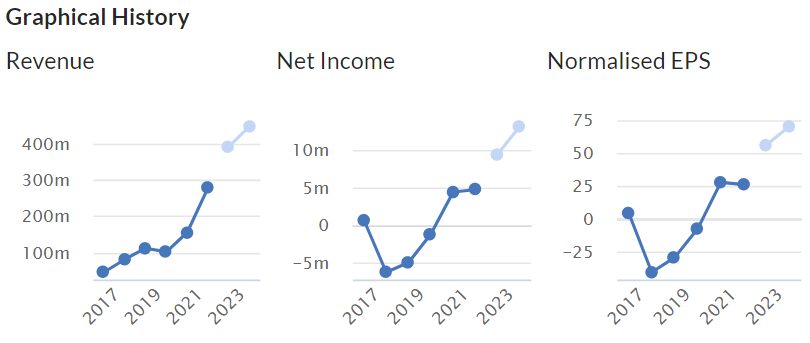
So maybe shareholders have found an amazing growth business?
Or, perhaps YU is just making bonanza profits due to the energy crisis, that won’t be sustainable?
That’s up to you to decide!
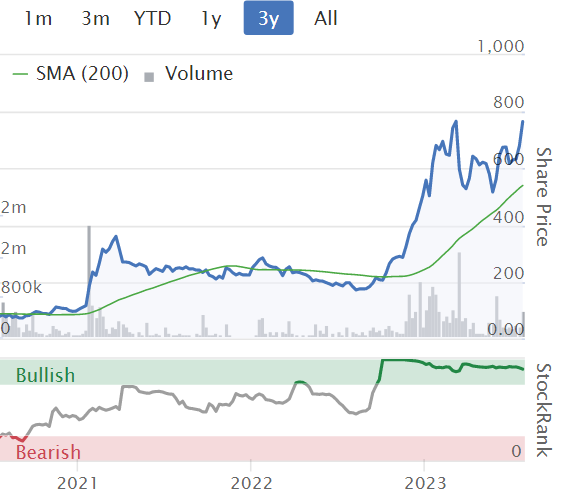
I went through the 2022 accounts here, and see a fair bit of risk, so it’s definitely not for me. But it’s been a great punt (so far) for risk-takers who backed it, thanks to the energy crisis. A 4-bagger in a year, is a remarkable outcome, and you could sell a quarter now, and run the balance for free! Very nice indeed.
This one reminds me a bit of all those covid multibagger shares back in 2020, most of which have come all the way back down again. So it’s always worth remembering to top slice, selling into the upward momentum, rather than watching it fizzle out, where a company hits a bonanza of trading due to external factors, that then reverses.
Eurocell (LON:ECEL)
Up 1% to 115p (£128m) - Trading Update - Paul - AMBER/GREEN
Eurocell plc, the market leading, vertically integrated UK manufacturer, recycler and distributor of innovative window, door and roofline PVC products, provides the following update for the six months ended 30 June 2023.
Trading Update - In Line with Expectations
H1 sales down -2% vs strong comps.
Volumes 6% lower, so clearly some price rises have been put through to partially offset.
More staff made redundant to save £4m p.a. (after £5m saved in 2022 redundancies).
Outlook -
As previously highlighted, for 2023 we anticipate a heavy weighting towards H2, with sales returning to a more normal seasonality and profits in the second half benefiting from lower input prices (including raw materials and hedged electricity) and operational cost savings already implemented.
Taking the above factors into account, our expectations for the full year remain unchanged.
Net debt - only £15m, so not a worry.
ECEL has an excellent balance sheet, so is sturdy enough to cope fine in the current downturn I reckon.
Paul’s opinion - broker forecasts have come down in several stages already, and given the poor macro environment, it wouldn’t surprise me to have more forecast downgrades at ECEL and other companies in the building products sector.
So investors here need to have the stomach to endure the risk of another profit warning.
Then at some stage, the market starts to focus on the recovery potential, and the shares re-rate upwards again.
I remain bullish medium to long-term on this nicely financed company, but am half-expecting more disappointments in the shorter term. Hence I am watching from the sidelines, but I’d like to be in it for the medium term recovery, as with so many other cyclical shares.
So I think AMBER/GREEN seems best at the moment - i.e. some short term worries, but fundamentally a good business longer term.
Tyman (LON:TYMN)
Up 6% to 302p (£594m) - Interim Results - Paul - AMBER/GREEN
I’m almost out of time, but just wanted to flag this for readers to take a closer look. The chart it making a new 12-month high, very unusual right now, and a good signal something interesting is happening (or a speculative bubble!)
How about this for an unclear self-description - surely this could have been simplified? -
Tyman (TYMN: LSE) is a leading international supplier of engineered fenestration components and access solutions to the construction industry. The company designs and manufactures products that enhance the comfort, sustainability, security, safety and aesthetics of residential homes and commercial buildings. Tyman's portfolio of leading brands serve their markets through three divisions: Tyman North America, Tyman UK and Ireland and Tyman International. Headquartered in London, the Group employs approximately 3,400 people with facilities in 16 countries worldwide.
H1 results don’t look great, with revenue down 8% to £330m, and adj PBT down 25% to £34.2m. Adj EPS down 24% to 13.3p. Clearly that didn’t come as a shock, because the share price is up 6%.
Outlook comments are probably driving that, with this being the key bit -
As a result, we expect full year adjusted operating profit to be at the top end of market expectations...
Balance sheet has £433m intangibles, bringing NAV of £519m down to NTAV of £87m.
Working capital is healthy, but financed by a fair bit of long-term debt, of £162m (partially offset by £79m cash), so probably OK. But the debt is going to cost a lot more now, so note that finance costs are quite hefty - fine when money was free, but borrowings are a lot more costly now.
Paul’s opinion - moderately positive, at a quick glance. A PER of about 10, divi yield of 4.7%. Upbeat-sounding outlook comments today, and a cyclical recovery to factor in at some later stage.
Worth a fresh look I think! Or, we could look at smaller things like WIX and ECEL that haven’t yet strongly recovered - there might be more share price upside potential for them, who knows?
Paul’s Section:
Quiz (LON:QUIZ)
10.15p (£13m) - Final Results - Paul - AMBER
QUIZ, the omni-channel fashion brand, announces its final audited results for the year ended 31 March 2023 ("FY 2023").
Quiz focuses on special occasionwear, and still has a network of physical stores, as well as a well-developed online offering. It jettisoned the problem shop leases in a CVA in 2020, moving largely onto flexible turnover rent leases (although note 11 shows that rents are now about half fixed, and half turnover-related).
Management are experienced rag traders, and still own stakes which give them effective control.
My earlier comments so far in 2023 have been these two -
17 Jan 2023 - GREEN - 16p - “at least in line” TU for FY 3/2023. £9.2m cash. Thumbs up.
17 Apr 2023 - AMBER - 11.7p - £2.0m PBT expected FY 3/2023. £6.2m net cash. Cautious outlook, and softer recent trading.
Results for FY 3/2023 were published on 5 July 2023, and several readers have asked me to review them, which we didn’t have time for at the time, so here goes.
Key numbers -
Revenue £91.7m (up 17%) - a good recovery, driven by the first year with no covid disruption.
Gross profit of £56.5m an impressive 61.6% gross margin - a key strength.
Profit before tax £2.3m (up 192%) - not bad in a really tough sector, but nothing like the heyday when Quiz floated, when it was achieving profit of c.4x this level - another very well-timed float (for the sellers!), in mid-2017.
Clean, simple numbers, with no adjustments, so very easy to understand.
EPS 1.64p (flat against LY, which was boosted by a tax rebate), PER 6.2x
Directors pay looks OK, not excessive, at £697k (note 4). Also note share based payments are very modest at only c.£50k p.a.
No dividends.
Balance sheet - looks healthy. NAV £20.9m. Deduct £2.7m intangible assets, and NTAV becomes £18.2m - which is plenty for the size of business. This includes cash of £7.6m, less £1.4m in bank borrowings, so net cash of £6.2m.
With revenues of c.£92m, I would expect the cash figure to move around a fair bit, so there’s nothing to be gained from over-analysing movements in cash, in my view. It’s in a healthy overall position.
Cashflow statement - looks good. Net operating cash generation was £5.9m, but boosted by a £417k tax refund, and of course this needs to be adjusted for £1.8m lease payments further down. Capex shot up, from £290k LY, to £1,965k this time.
Overall, this remains a reasonably cash generative business, so I think it should be able to pay divis at some stage. A 5% yield would cost £650k pa, which I think the company could afford, so that would be a good question to ask management - why no divis, and when will they start rewarding shareholders?
Outlook - soft recent trading - Q1 (3m to June 2023) saw a 15% decrease on LY - blamed on macro factors, and strong LY comps.
3 new stores opened since year end. Bank facilities renewed to June 2024, and increased to £4.0m (prev. £3.5m). Net cash £3.7m recently, at 4 July 2023.
During H2 the trading environment is expected to remain challenging, albeit the Group has softer comparatives in the second half of the financial year. Reflecting the uncertainty with regards to consumer demand and inflationary cost pressures, the Board currently anticipates that profit before tax for current year will be similar that generated in the past year.
Longer term the Board remains confident the Group will deliver sustainable and profitable growth
So it’s guiding for about £2.3m profit this year FY 3/2024, which I’d say would be a reasonable outcome, given tough macro & consumer sentiment. Plus of course very tough online competition, in particular from the aggressive Chinese direct to consumer websites, especially Shein.
Costs are expected to increase, including utilities (fix ending), and wages.
Paul’s opinion - Quiz is a resilient business that has outlasted many of its now defunct competition. So there’s less competition for its physical stores, and the customer returns rate is low for physical stores (whereas online is plagued by high returns, and all the costs of dealing with those).
My hunch is that the risk of a profit warning could be medium-high here. The reason being that FY 3/2024 has started badly, with revenues down £4.1m in Q1 alone. At a gross margin of c.62%, that’s £2.5m reduced gross profit. Overheads will be increasing, so the total profit squeeze in Q1 alone could be c.£3m. I find it difficult to believe that Quiz can make that up in the rest of the year. So I’d be expecting a profit warning at some stage, and maybe a result around breakeven for FY 3/2024. For that reason, I’m not keen to buy back in here.
On the upside, the balance sheet strength, and nice cash position, means risk is limited.
There should also be upside from reduced freight costs, and the recovery in sterling making input prices cheaper. So expect good gross margins to continue, or increase.
Overall, it’s got to remain at AMBER I think.
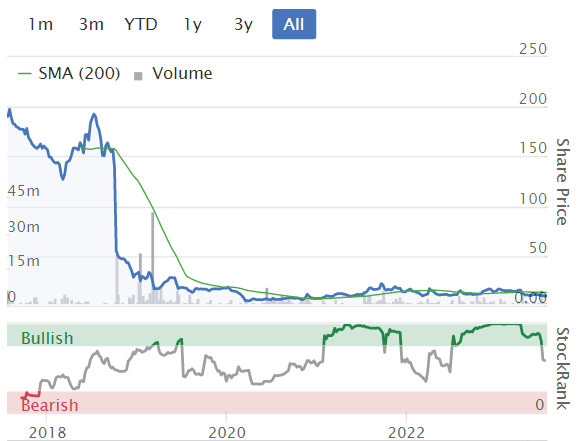
Note the StockRank is upper-medium, propped up by strong value scores.
Tristel (LON:TSTL)
355p (pre-market) £168m - Trading Update - Paul - AMBER
Tristel plc (AIM: TSTL), the manufacturer of infection prevention products, provides a trading update for the year ended 30 June 2023, ahead of its Open Day for shareholders being held today.
“Very robust” demand in “all key geographical markets”
FY 6/2023 revenues £36.0m, up 16% on LY, and ahead of market consensus.
Adj PBT “slightly ahead of consensus forecasts of £6m”
Cash £9.5m (up £0.6m vs a year ago)
Reminds us that it got FDA approval in June 2023, has begun manufacturing & marketing
Management sound excited -
"Looking forward to the years ahead, I am confident that Tristel will truly become a leading global player in the infection prevention industry. We now have access to the world's largest ultrasound market for our high-level medical device decontamination products and we have an exciting pipeline of new product innovations supported by a strong balance sheet. We are very excited about the prospects for further growth and the outlook is positive."
Broker update - many thanks to Finncap, which issues an update note. Profit expectations haven’t changed, because it looks as if Tristel is recycling the extra gross profit into increased overheads.
Latest forecasts are 9.9p adj EPS for FY 12/2023, and 12.4p for FY 12/2024.
PERs are 36x, and 28.6x
Paul’s opinion - same as usual - a nice company, but valuation seems fully up with events.
The USA expansion is finally happening, so if that takes off, then the company could grow into the valuation.
Good demand in all major markets is clearly a positive announced today.
As I don’t know whether its products will take off in USA or not, then I have to stay neutral, AMBER. That’s the deciding factor, and if it’s good news, I could see this share possibly recovering to previous highs. If the sales in USA disappoint, then the shares would probably lurch down. We’ll have to wait and see what happens!
I imagine today’s news should give TSTL shares a maybe 5-10% boost today, at a pre-8am guess (for fun!).
Wickes (LON:WIX)
Up 6% to 135p (£350m) - Trading Statement - Paul - GREEN
Wickes operates from its network of 230 right-sized stores, which support nationwide fulfilment from convenient locations throughout the United Kingdom, and through its digital channels including its website, TradePro mobile app for trade members, and Wickes DIY app. These digital channels allow customers to research and order an extended range of Wickes products and services, arrange virtual and in-person design consultations, and organise convenient home delivery or click-and-collect.
This sounds reassuring -
Improved second quarter drives positive first half LFL performance; full year expectations maintained
Revised capital allocation policy supports a maintained dividend and £25m share buyback programme
Full year guidance -
On a Pre-IAS38 Adjusted PBT basis, the Company is comfortable with the market consensus for FY2023, being a range of £54.5-57.0m.
Q2 LfL sales improved to +3.0% (was -1.8% in Q1), still well below inflation though.
H1 LfL sales were +0.7%
I can’t see any benefit from the company splitting out “core” and “DIFM” (do it for me) sales figures.
Inflation - it’s not entirely clear if this is talking about input cost inflation, or selling price inflation? Probably selling prices I would guess -
Inflation continues to slow, in line with our expectations, falling from 9% in the first quarter to 4% in the second. Wickes continues to retain its strong price position relative to the sector.
Cost inflation - sounds reassuring -
Costs remain well controlled, with savings flowing through as expected in distribution, logistics and store operations.
It doesn’t say anything about gross margin, which is surprising. I would imagine that importing a large quantity of bulky items would have seen big benefits on margin through reduced sea container freight.
IT spending - big upgrades are planned, and it says this will mostly be expensed through the P&L, rather than capitalised -
IT project investment is anticipated to be c.£17m in FY2023 and grow to c.£25m per year from FY2025…
The impact of this switch from capex to opex for some investment costs will have no effect on future cash flow. For four years PBT will be reduced until the higher IT opex is fully offset by lower IT amortisation costs. We estimate the impact on PBT to be £8-10m in FY2023, £6-11m in FY2024, £4-7m in FY2025 and £1-3m in FY2026;
That’s obviously going to result in broker forecasts dropping, or they might have already factored this in? I can’t find any broker research unfortunately, so am in the dark on this point.
Capital allocation - various points made, including saying that it won’t need to use its RCF, expects to be in net cash throughout the year. More scope for paying divis, by adopting a broader range of dividend cover from 1.5x to 2.5x adj EPS (previously 2.5x cover).
Dividends - maintaining 10.9p total divis for FY 12/2023, giving a sparkling 8.1% yield.
Intention to hold the payout at 10.9p until cover returns to normal. There’s obviously some risk there, that a downturn in trading could scupper future divis, but they say they’re confident.
Share buyback of £25m announced today - that’s a lot, coming on top of a generous yield, and for a £350m market cap that implies buying back about 7% of the existing shares.
Paul’s opinion - I think this is really encouraging, and the big yield + meaningful buybacks, reinforces that this is a decent business, well financed, and whose shares seem cheap.
It’s one of my favourite value shares, and that remains the case, so a thumbs up.
Let’s hope the diversity & inclusion manager keeps his trap shut in future! Most people don’t want companies to broadcast their virtue-signalling. Just treat everyone fairly, and then there aren’t any problems either way. And never, ever, insult your customers! (even if it is taken out of context). So I hope WIX has learned from its recent communications debacle.
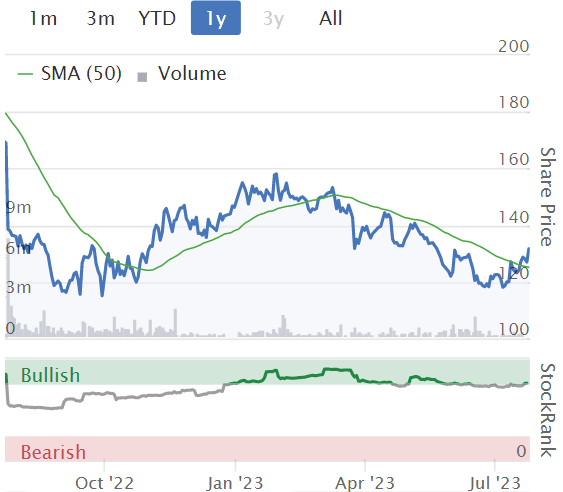
Good fundamentals, a cheap valuation, generous divis/buybacks, and a chart that's looking nice too - lots to like here!
Brighton Pier (LON:PIER)
Down 28% to 41p (£15m) - Trading Update (profit warning) - Paul - AMBER/GREEN
Brighton Pier Group PLC, a diversified UK leisure and entertainment business, provides the following trading update for the first half of its present financial year (26 week period ended 25 June 2023).
Profit warning -
The combined effect of these lower sales with the inflationary cost pressures are expected to result in earnings after tax below market expectations….
all four of the Group's divisions will remain profitable for the full year despite the challenges…
The Board's short to medium term outlook remains cautious.
Q1 was in line, but Q2 “more difficult”, blaming consumer confidence, and decline in disposable incomes.
H1 sales c.£16.2m
Operating margins hit by higher costs (esp. food/drink, and staff costs).
Reduced footfall.
Recent trading in July 2023 hit by poor weather, train strikes, and hotel fire opposite the entrance to Brighton Pier (1 week’s disruption).
Broker update - this is the bit where we often see a huge drop in forecasts. However in this case, I’m pleasantly surprised by how little Cenkos’s analyst Peter Renton (many thanks!) has cut the FY 6/2023 numbers by. He’s saying £5.5m adj EBITDA, down £1.0m on previous forecast, and a still-profitable adj PBT of £0.8m. Assuming that's realistic, then it's not a disaster by any means.
Paul’s opinion - I wouldn’t reject PIER out of hand at all. The balance sheet isn’t bad, and PIER de-geared a fair bit during the pandemic. This profit warning today isn’t a calamity, just a little worse than expected - hardly surprising in the current circumstances. Performance could improve once the squeeze on disposable incomes ends.
Hence I think the big reduction in share price could bring this share into buying range, for patient investors who are prepared to wait for a macro recovery.
Or a takeover bid - Brighton Pier is a fairly nice trophy asset, and with the whole group only valued at £15m now, someone might try to snap it up. Luke Johnson owns 27% I see.
As a special situation, I think this share is now looking quite interesting, with speculative upside potential. Liquidity and a wide spread are probably the main impediments to getting involved in this share.
Graham’s Section:
Reach (LON:RCH)
Share price: 74.5p (+9%)
Market cap £244m
This is the tremendously “cheap” newspaper publisher. The market has decided that it’s a value trap, but maybe it’s a cigar butt with a few last flavoursome puffs to give?
It had quite the spike during the Covid rally, and is now back in the doldrums:

Today we have interim results. The main point is that full-year profits are still expected to be in line.
Revenues declined 6% to £279m with the only bright spot being print circulation revenue, i.e. newspaper sales. This is still the largest driver of revenue and it increased by a few percentage points.
Strangely, this occurred despite newspaper volumes actually falling by 18%. Reach increased the price of newspapers so much last year that it is able to deliver nominal revenue growth even as volumes declined. It also sold one-off specials, e.g. celebrating Wrexham’s promotion to League Two.
Digital revenue on the other hand fell by over £10m to £61m. Facebook made a decision to de-prioritise news content and of course there is nothing Reach can do about that. Just another reminder that many small companies live or die depending on the decisions of the tech giants! They are trying to grow more revenues where they are in control of the relationship with the reader, but they still have a long way to go on that front.
Operating profit fell by a significant percentage whether we are looking at “adjusted” operating profit (£36m, down from £47m) or the actual result (£11m, down from £34.5m).
Adjustments are made up of:
Provision for historical legal issues £6m. Reach now has £45m set aside in these provisions. I think it is reasonable to adjust these out, as this problem must surely conclude soon?
Restructuring charges in respect of cost reduction measures £10m. Restructuring looks like it could be an ongoing story here (£5m restructuring charges last year) so I would not adjust out all of these costs.
Pension administrative expenses £2.6m. These are an ongoing cost so I would not adjust them out.
Other items £5.6m, mostly to do with the “historical legal issues”. I would adjust most of these out.
All told, the company treats £24m of costs as adjusting items. For me a more reasonable figure is £10m.
I would therefore be happy to say the underlying operating profit is around £21m (£11m actual operating profit plus £10m of adjustments).
This is a matter of opinion, of course. It depends on your view on what will happen in future periods - will restructuring costs go away? Will the company need a lot more provisions in relation to phone hacking? I’m just giving my opinion on what seems reasonable to me.
Based on my view that underlying operating profit was around £21m during a difficult H1 period, the shares undoubtedly look cheap in relation to current earnings.
Outlook - H2 will be stronger as newspaper prices increased during H2 of last year, so those increases are still being annualised. In digital, there will also be “less demanding second half comparatives”.
Operating costs should be down 5-6% with savings from cost reduction measures being weighted to the second half.
The High Court trial around historical legal issues has concluded.
Market expectations are for adjusted operating profit of an incredible £94.9m.
Net debt - currently just £3.5m, and it’s expected that there will be a “small net debt position” at year end. There are also some leases (not too big). The company has access to a £120m RCF which should mean there are no liquidity issues for the time being.
Balance sheet - net assets of over £600m, but net assets are negative if you strip out intangibles. That’s unfortunate because it means that the company doesn’t have assets set aside, e.g. to pay its legal provisions. It will have to borrow to settle these liabilities.
Pension deficits need to be considered. Work is being carried out on a new valuation of these deficits (this is done every three years). There are some very scary numbers in this section - one of the pension schemes is said to have had a deficit of £476m in December 2016!
But I think this is the key paragraph for the time being:
At the prior year end, the funding deficits in all schemes were expected to be removed before or around 2029 by a combination of the contributions and asset returns. Contributions (which include funding for pension administrative expenses) are payable monthly. Contributions per the current schedule of contributions are £55.8m pa in 2023 to 2025, £56.7m in 2026, £54.7m in 2027 and £8.6m pa in 2028 and 2029.
I’ll ignore the time value of money for just a moment and add up all of the contributions for 2023 to 2027. They give us total contributions of £280m. Or we can round it up to £300m if we include the contributions to 2029.
Perhaps the most reasonable course of action, as investors, is to simply add up all of these scheduled contributions to the Reach market cap? Based on the latest share price, that gives an “enterprise value” (market cap plus pension contributions) of £540m.
Graham’s view
Maybe I just woke up in a good mood this morning, but I think I’ll give the stock the thumbs up today. The company’s brands are household names and it has a good track record of generating the cash needed to pay for its many liabilities.
I also think it’s possible that the upcoming valuation of the pension deficit could bring good news, with higher interest rate assumptions.
Not much has changed since I looked at the stock in May but the shares are a little cheaper now, and I think it’s possible we are reaching an inflection point where the pension deficit and the legal issues might become less troubling. In a year or two, the company might have settled its legal costs and paid another £100m+ into its pension deficit. What would investors worry about then?
This is a high-risk stock and resembles a “punt” more than a solid investment. But it’s intriguing.
SThree (LON:STEM)
Share price: 364p (+4%)
Market cap: £490m
SThree plc ('SThree' or the 'Group'), the only global pure-play specialist staffing business focused on roles in Science, Technology, Engineering and Mathematics (STEM), today announces its financial results for the six months ended 31 May 2023.
We already had the H1 trading update and reported on it last month.
The main points from H1 are:
Like-for-like net fees down 2% (£209m)
Like-for-like operating profit down 22% (£38m)
Like-for-like PBT down 20% (£38.5m)
The post-Covid conditions of 2022 are seen as a difficult comparative: fees rose 25% last year. So it was always going to be tough to match that.
If you take a step back from the year-on-year comparisons, the overall trajectory here has been excellent:
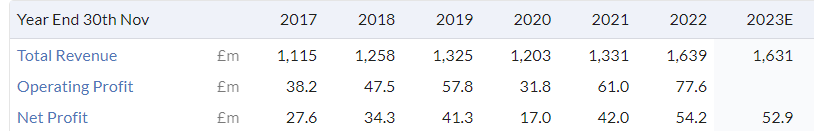
I also believe that SThree has in a sense allowed its net fees to decline, as it has been focusing its investment in the steady income provided by contract recruitment. This has steadily risen and is now responsible for 81% of net fees.
Permanent recruitment revenue (now only responsible for a fraction of total revenues) fell by 19% during the period, reflecting the post-Covid decline in demand from the Life Sciences sector, but also I believe reflecting SThree’s preference to invest in contract recruitment.
They have net cash of £72m: in my experience they have always had a strong balance sheet, but this must be a record when it comes to the company cash balance.
Outlook: trading is in line with market expectations.
Macro conditions continue to be varied as we enter the second half, however contract extensions remain strong as our customers seek to retain scarce skills to ensure they do not jeopardise future growth prospects. Furthermore, in June we saw a modest improvement in new placement activity, which itself was slightly ahead of the second quarter average. It is too early to know whether this is an improving trend, but we will continue to monitor and respond to activity levels over the coming months.
2024 ambitions: the company has a range of financial and non-financial KPIs. From a financial point of view, the goal of a 21% operating profit margin in the medium-term seems just out of reach for the company. They achieved 18.3% in H1 but say that the economic headwinds will “dampen margin progression in the short term”. 18% is still a reasonable level, so I doubt that investors will be too upset by this!
Graham’s view
I gave six reasons to like SThree shares last month, and nothing has changed. We can see that there is some pressure on profitability, which is not really a surprise given that revenue growth has paused.
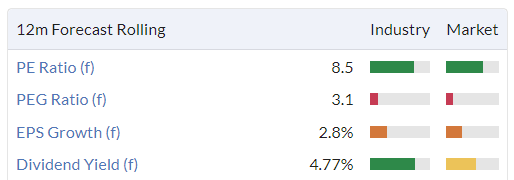
Stockopedia tools show that the overall trend for EPS estimates is ok:

I am therefore maintaining my Green view on these shares. I’m not a recruitment specialist by any means, but this is my favourite recruitment stock. It earns good returns, is reasonably priced, and is shareholder-friendly, paying regular dividends for very many years. What else can we ask for?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Looks like the US regional banking crisis is still being worked through. PacWest Bancorp (NSQ:PACW) trading just halted, pending talks of being acquired by the much smaller bank Banc of California (NYQ:BANC), also trading just halted - could be interesting this week as the regional banks announce their half year numbers. I can't see that the problems will have just disappeared.
I did see some interesting stats. that UK banks have been by far the best in the world on passing interest rate increases on savings to depositors. Maybe the government have added some value. US is much worse. Obviously, it doesn't make the UK mainstream news as its good news!
Really, some banks such as Close Brothers, Paragon, Aldermore and a few others, offer good rates but the High Street banks give you next to nothing, even on their savings accounts.
Spoiler alert!
Polite viewpoint personally and not aimed at anyone.
I read the SCVR for education purposes, good advice, guru insights, wisdom and to try to understand the alchemy of public accounting - good job and a good read inc the posters.
However ... updates from sub 50m companies Quiz 13m, FA (good ticker) 9m, Pier (is this a bit of wood in the ocean with a coin machine), etc.
There is' bottom fishing' and er ... maybe 'deep diving' for the next Meg 2 stock (but it is a shark pool and I'm not Statham).
No haters - posting in honesty - maybe 50m base, 100m my preference. If they break a certain financial level the fair dues lets have a look - but cash is king - must be making it and keeping it or why should we invest.
I like the breadth of coverage, especially at the smaller end. Just scroll past if you’re not interested…
What a tiresome post, I really don't appreciate this one bit. It's demoralising & undermining to read things like that, when we're busting a gut to cover as many companies as we can, to provide something of interest to everyone, not just you.
We cover 550 companies between £10m-1,000m market caps. There should be plenty to choose from for everyone, within that extensive coverage.
The market cap of every company is stated at the top of each section, so if it's too low for you, just move on to the next section.
I only covered QUIZ because a load of readers asked me to, repeatedly!
The tiny market cap stuff we often tear to pieces, and explain why they are best avoided. That's the reason we mention them, to flag up the problems.
If this topic comes up again, I'm just going to totally ignore it. Drives me up the wall.
Graham many thanks for your SThree (LON:STEM) comments, here is the analyst presentation from earlier today video & podcast. I like is the insight into trends, Engineering recruitment is +17%; Life Sciences -21% and Technology flat +1%. As for the geographical split the USA is -11% whereas Germany is only -1% and Netherlands +3%. They cite that the US was the greatest beneficiary from the lockdown other countries didn't upscale as much.
Biggest turnover of shares in RBG Holdings (LON:RBGP) entire listed history today
Number seems to coincide with a certain ex CEOs shareholding
Will be interesting to see if the underlying business is actually performing ok and whether the share price decline is solely down to a disgruntled seller- i've always thought the businesses (ex lionfish) are actually quite boring
Wouldn't be surprised to see an update coming this week if m'ment are savvy and have been waiting for the clear out
Good Afternoon Paul and Graham,
A great deal of quality work you have both produced today. A big thank you from me and I am sure all of the Stocko subscribers.
Hi Helvellyn,
How kind, thank you - we do appreciate feedback, especially when it's positive! :-)
I know everyone is worried about macro, but I'm genuinely excited about all the interesting companies we find almost every day, at attractive valuations. It's so rare to have such rich pickings sitting there on a plate for small cap investors. This market feels like a coiled spring to me.
Regards, Paul.
We had some bid excitement on Gresham House (LON:GHE) recently. I do wonder if the same may be going on at Mercia Asset Management (LON:MERC)?
I really like(d) Mercia and set out a case here in the past here- https://www.stockopedia.com/co...
But I cooled and have been a seller incrementally over last 2-3 mths such that I hold about 40% of my original stake. Selling decent size chunks to market has been easy. Much easier than at times in the past it seems. Maybe just someone hungry to buy more? Maybe a stalker? I'm not expert enough to tell.
Its still got a lot going for it including a deep discount to NAV with a 3rd party asset manager that makes a tidy profit and gives a sustainable 3.5% dividend payout (even though market cap is dominated by proprietary non yielding balance sheet investments (ie asset mgt kicking out tidy cash!). However, I never buy or hold purely on value...
I've never really liked the 20:20 corporate strategy. 20% earnings (which are significantly a function of value realisation in balance sheet holdings) and 20% AUM growth per annum over 3 years. The acquisition of Frontier Development Capital bringing c.£415m AUM for a c.£9.5m purchase price looks like a neat move at face value...but my sneaking suspicion is that this was opportunistic to reach corporate targets set after the covid snafu (so basement values) but before the inflation/rates follow on snafu and I can't help feel that FDC is not an ideal acquisition given the sort of debt and property lending its involved in. There's great value creation opportunity in developing greater mezzanine debt capability at Mercia...but you don't but FDC for that.
Then there are some of the large balance sheet investments. I think they should have realised an exit on some of them but haven't. It makes me think that further value from them might be hard (I do believe that Mercia hold assets conservatively and have generally been excellent at managing poorer holdings effectively...kudos). Something like nDreams (biggest holding) a growing VR games maker may go on to create much more value...but its just too long in the tooth as a holding and something should have happened by now if it were a desirable asset is my niggle (and the IPO route doesn't look possible anymore). There are others.
Anyway, Mercia will probably bounce from here...and I have suspicion they could be a takeover target. But as value abounds in UK and I look for durable long term growth I feel less inclined to Mercia. I also see a growing downside risk whereby a big investment proves to be a damp squib and that keeps the valuation low and sentiment poor. In extreme we could see NAV moving down towards share price.
Seems like the whole Wickes (LON:WIX) fiasco might have been a great buying opportunity :)
Wickes (LON:WIX)
In hindsight perhaps yes - but we really didn't know that the pack up your workbench and shop elswhere in a huff possy would be non material at the time. It certainly made it no go territory for me short term while that bod was happy to insult more than 50% of their (singular) customer base and peeps would be protesting to an unknown degree. Perhaps if there is knock on effect there wasnt enough time in the period referenced to matter? they were silent ref july trading as far as i can see .
Well it's game over for Trackwise Designs (LON:TWD) as they appoint administrators. Sad that again another highly promising British technology bites the dust. A painful lesson learned as I'm sure there'll be nothing for shareholders and also got stung by Applied Graphene Materials (AGM). What is it with our inability to turn these great ideas into world-beating and wealth generating businesses? Pieces, in both cases, bound to be picked up for a fraction of their true worth, likely by overseas companies, who'll make the most of their good fortune.
Can't say that we weren't warned but landing just one of the contracts in their supposedly huge pipeline would have seen them fly.
That's sad news re Trackwise Designs (LON:TWD) - fleetingly it caught my imagination here, but I think it was Graham's comments that then put me off, and the obviously inadequate financing.
To answer your question, I think the big problem with UK tech, is that it's not properly financed. TWD is a typical case, where the original business plan had nowhere near enough cash for contingencies, so they had their back against the wall fighting to raise more funding when the inevitable delays & problems occurred.
If that had been in the USA, investors would have nonchalantly thrown $100m at them, and just said get on with it.
I agree that Trackwise Designs (LON:TWD) is one of those where the potential was enormous - in this case flexible PCBs needed by EV OEMs:
but the finance let them down - they poured a lot of money into the new facility at Stonehouse (Gloucs.) pictured above and were then let down by their first EV customer.
I poured a lot of time into following this one but mercifully never pressed the buy button as the price always seemed ahead of events.
Of course, if you believe the SR you would have been expecting eps 5p and target price 315p - not bad for something trading at 0.18p pre suspension. Those were finnCap's figures which were withdrawn last September due to the uncertainties that had arisen with the first EV OEM contract. As I mentioned then:
The last time I moaned to Stocko about this (on a different share) I was told that it would not be removed but that "As we go forward, we plan to handle stale estimates differently, for example, by highlighting them in a different colour - eg. a light shade of amber. Removing them completely may be jarring for users".
Still waiting for your light shade of amber Stocko!
Anyone have access to Liberum's note on Yu (LON:YU.) post the update today? What are the EPS numbers? tia
It’s not expensive to sign up for Research Tree you know, can even get a discount off Robbie Burns at his site!
Had to laugh at this in The Telegraph today
The bosses of a bunch of bloated, debt ridden, dividend paying non growth FTSE100 companies want the same pay as bosses of many of the best companies in the world. Got to admire their chutzpah!
"Low executive pay is the biggest obstacle to boosting the City of London, FTSE bosses have said.
A new survey of 150 directors at London-listed companies found that lower pay for City chiefs compared to rival financial centres was holding back the London Stock Exchange (LSE) as a listing venue.
The research, carried out by investment bank Numis, adds to growing complaints in the Square Mile that Britain is being held back by a campaign against high pay.
Julia Hoggett, chief executive of the LSE, has said a pay disparity between UK chief executives versus their US counterparts has “not received enough attention” and called for a level playing field to stem an exodus of companies.
Chief executives of S&P 500 companies in the US make on average $10m more than FTSE 100 counterparts, according to data from Equilar and Deloitte published earlier this year."
.
Wolf, couldn't Numis (LON:NUM) be one of that bunch too? It was one of my kennel-pack until I gave up and here is why:
Hoping this does not offend (any other Stocko member),
Silver
Wickes (LON:WIX)
Let’s hope the diversity & inclusion manager keeps his trap shut in future!
Thats presuming they are still currently using the he/him/his pronouns ! - its probably doing the wrong thing to even presume they would be the same as last week nowadays.
I may be too cynical, but where the market seems to welcome the Trading Update from Alpha International (LON:ALPH) I tend to see a busy attempt to skim over a profit warning. There is no mention of "profit", no Net Profit , no Profit before Tax, not even an "Underlying Profit" or even a dreamland EBITDA. Nada , zilch. Almost everything is about Revenue, Operating Income, and meeting (unstated!) expectations
But there is an "accelerated investment programme and maintaining strong underlying profit margins". I tend to immediately translate this to"higher costs and lower actual margins". I do actually approve very much of higher investment in a growing business but it looks like APHA does not want to risk such a straightforward admission.
"The business is on track to deliver another strong year of revenue and underlying profit growth in line with meeting (unstated) expectations"
Alongside this it is admitted that "macro uncertainty has resulted in a noticeably more conservative approach to forecasting and hedging". Also,"revenue from spot contracts (which are...lower-margin) increased by 50%". Toronto did not grow but has "resumed its growth trajectory". The "Portfolio Managers (in June) are "achieving their new business quotas" - which of course are not stated.
I believe that this is in no way a bad company and it is achieving growth in most areas but there seems to more than a hint of embarrassed attempt to avoid being too clear about the actual earnings.
The share price has now fallen back on Alpha International (LON:ALPH) my broker has it flat on the day. So the market seems to have have it's opinion.
hVIVO (LON:HVO) Another nice £13m contract. looks undervalued to me on a cash adjusted PER of just 10 which, for a CRO and the global leader in its niche looks miserly now.
It does look good David doesnt it. Must be a chance of a beat as the year end draws closer? Full '23 revenue visibility in April update, Liberum thought they had until September to sign new contracts and recognise revenue in the same financial year.
Agree. Mo talks about under promising and over delivering so I am hoping for a beat. I’ve noticed they’ve stopped doing RNS for contracts sub £10m as well so that suggests materiality threshold is going up too
Eurozone, especially Germany, looks ropey to say the least.
UK PMI
Bullish!!
Paul, your Quiz (LON:QUIZ) dividend question was I think answered in the July 22 investormeetcompany presentation last summer, in Question 2. Basically they said they needed to see a sustainably higher level of profitability. That was a year ago and they obviously passed on this in the most recent results announcement, so could be a couple of years away absent any likely profit growth this year.
Morning M48,
Great, thanks for the additional colour on Quiz (LON:QUIZ) re divis.
Regards, Paul.
Reach (LON:RCH) . Seems to be a race between their pensioners dying off to reduce the pension fund and pensioners dying off who are buying their papers.
I take your point about newspaper buyers declining in number. However, a point that I've been pondering, is whether (and how many) people start buying newspapers when they retire? It's actually a nice daily ritual, to get moving & keep fit, to walk to the shops every day, pick up a paper, have a coffee, etc. Hence there must be a certain number of new newspaper buyers coming in as well - almost certainly not enough to offset those who become too old to buy any more papers, or die off as you say.
We may not need to buy a newspaper, as we can get our news online. But sometimes it's a nice little ritual to buy the Sunday Times, or whatever, and spread out the sections. Do some people also perhaps emulate what their parents/grandparents did, as they get older, maybe for nostalgic reasons? (e.g. buying the Radio Times at Christmas, and putting rings around programmes)?
The surprising resilience of demand in the face of big cover price rises does suggest to me that some newpapers could be around for a lot longer than people think. I remember going to an AGM of Trinity Mirror (now Reach) in May 2012. I distinctly remember the then Chairman stating that newspapers had a remaining lifetime of 10 years. Well here we are, 11 years later, and TNI remains a cash machine, spewing out large profits still!
One final point, is why don't newspapers enlarge their fonts? That would both make it easier for older people to read (I struggle with them at 55!), and mean that they can spread out less content in the same space, saving money on editorial costs.
Even if all the articles are written by AI, I'm sure the tabloids in particular would be far more factually accurate than the made-up garbage they tend to publish now!
Regards, Paul.
If I was going to read any paper published by Reach (LON:RCH) , then it would need to be a physical copy - trying to read anything they produce online is awful with the number of ads distorting the format.
Agree in the absolute. On line is an atrocious user 'experience', so bad that that there is no way I would ever consider the physical option either. Their plans, ambitions or whatever must be hindered through the low grade on line offering - what serious advertiser would wish to commit to such a poor platform? Clearly many do. But how many do not once they have seen it? The unknown unknown conundrum.
I stopped buying newspapers, when I retired, good to read on the train but not at home. I see most younger people, get their news from social media sites, such as tiktok, which is a concern.
My local shop, which used to have lots of newspapers, has hardly any now.
Lots of complaints about AI, getting the information all wrong.
Reach (LON:RCH) sites are awful, so full of adverts, I would not want to use them, on a regular basis.
.."Reach (LON:RCH) sites are awful, so full of adverts, I would not want to use them, on a regular basis..."
All the more reason why RCH should introduce a premium service with reduced/no ads as an alternative way of 'monetising' their readership.
It may just be me, but the blatant political slant and number of sloppy errors seems to have got worse recently. Consequently i stopped buying papers.
It may just be me, but the blatant political slant and number of sloppy errors seems to have got worse recently.
I thought you were talking about the SCVRs fleetingly then LOL! ;-)
SThree (LON:STEM)
Not much to comment on since it’s an in-line report, but the relative resilience of the name’s fee income, derived from it’s >80% focus on contract revenues, shines in the numbers. Shares look good value to me around these levels. Compare where they were just a couple of months ago near 475, when doom and gloom had already fully descended and without the news deteriorating in any meaningful way since. I’ve been topping up in the range 330-350 and would continue to do so today if the position wasn’t by now outsized.
Alpha International (LON:ALPH)
Still just squeezing under the £1bn threshold, I was interested to note that while trading on an underlying PER of 30x for FY23, the extra income from interest receipts on customer cash held by the firm brings the reported PER down to only 12x. This for one of the best performing and most admired companies on the UK market. The reason being that, extremely prudently, the group does not treat the interest income as core earnings.
But this is real money flowing into the firm. It’s almost as though the company is carrying out a substantial equity raise each quarter that results in no dilution and no discount. High interest rates may not last forever, but this extra revenue allows for a lot of investment that counters the macro trend, keeping the business on target. Shares have tracked sideways since the peak of the growth bubble, itself a bullish sign, and the long term trend line is resolutely upwards. I take reassurance from these technicals.
Interested to hear the views of others in the light of this recently disclosed extra value in an otherwise apparently expensive name. This is one of the first shares I bought when I switched to investing in public markets. I doubled the position in the pandemic sell-off. Otherwise, I’ve just let it run.
Brighton Pier (LON:PIER) has dropped like a stone today (currently down 28%) following a poor trading update as a result of poor weather etc. I note that Graham previously gave it an AMBER but think I will stay clear unless anyone thinks there is mileage at this price?
I have just taken a punt on it. Some good assets, LJ is no fool (despite the Patisserie Valerie disaster) and in my opinion something will happen to either dramatically grow it size wise or a takeover.
What is Luke Johnson's track record?
Best known Pizza Express. He had made £120m personally since the 1980's.
newsfile.refinitiv.com/getnewsfile/v1/story?guid=urn:newsml:reuters.com:20230725:nRSY0243Ha&default-theme=true
Reach (LON:RCH)
I have just noticed one of todays top risers is Reach ( the old Trinity Group newspaper ??) up 16% !!
Because I have not had time to read its Interims for 2024 I cannot offer any tempters to Paul or Graham as to why they might like to take a look at it this morning but has anyone got any views?
I've held a little stake in Reach (LON:RCH) for a while.
I'm firmly of the view that this will the leader of a declining industry that has some cash to throw off eventually.
Pensions will be revalued positively with interest rates massively increasing, recurring revenues and assets that can be sold.
Whilst you wait, I locked into I think a 12% divi (from memory)?
It's not going bust and lots of positive noises in the medium term.
Reach (LON:RCH) had been walked down consistently over last 6 weeks on anticipation that the trading updates would consistently underperform expectations. They didn’t and the price has been walked back up again as shorts close and people buy back in for the dividend.
Nothing meaningfully changed in its interims.
Comprehensive update from Wickes (LON:WIX) . Comfortable with current forecasts, inflation falling. Detailed capital allocation update. All in all reads quite positively, but need to delve into the detail. The shares like most UK stocks are cheap. Much prefer Howden Joinery (LON:HWDN) which I hold, but every stock has a price, have taken a small opening position.
Paul/Graham any thoughts.
HY update from Diaceutics (LON:DXRX) did not disappoint.
This family biz in the med tech sector seems to fly under the radar.
Rev + 32%, Order book up 43% since December.
Cash £17.9m and no debt even though it is investing for growth as sees company in a sweet spot.
FY2022 rev they traded at just over breakeven, so there was no cash burn.
21 of the largest 30 pharma companies are clients.
Platform biz transitioning to Saas model. Recurring revs now 47%, 37%
Recurring revenue now represents 83% or £20.0 million of the future order book
Gross margin 86%
Been persistent selling so share price beaten up.
I think there is a perception that med tech companies will suffer due to inflationary pressure as pharma look at their costs but these med tech companies actually save pharma money getting their drugs to market more quickly or helping them to get the right drugs to the right people and more quickly as is the case with DXRX.
DXRX specialise in precision medicine, so getting the right drugs to the right people. They do a lot in oncology where they say only 33% of cancer patients get the right drug for their particular cancer and also their own physiology.
I think another main concern is AI will take over med tech companies. I have several positions in this structural growth sector and have asked management about this. They all say that you can't just create a med tech company using AI. It takes them years to gain the confidence and trust of large pharma. They have been using AI for years to assist their operations to function better and more quickly.
Happy holder of DXRX.
Investegate | Company Announcement
Seemingly strong update from Altitude (LON:ALT) this morning with a bit more detail given on Adjacent Market Programmes, and an early 5% SP rise - hope Graham gets this one on his list to build on his prior analysis.
Very nice update fromYu (LON:YU.) expects results substantially ahead of forecasts. (Same as May t update)
Broker upgrades EPS 20% this year 33% next
Been my best share by a country mile in the last year, but still looks decent value on PE of 10x
Market cap is crazy! Quite a few sellers this morning too which I find odd. Thanks for sharing broker upgrades.
Not sure how to understand the £Yu business model, they seem to be offering commoditised services in fiercely competitive markets, yet are growing spectacularly with fantastic returns on equity. Is this just a result of the extraordinary volatility in energy markets or is there some secret sauce that I'm missing ? Competitors like Inspired (LON:INSE) don't seem to have benefitted in the same way
What are EPS forecasts please?
Alumasc (LON:ALU) Bolt-on acquistion announced today, which appears both a good fit and acquired on reasonable terms. I hold.
It seems very low risk, given the @ALU management are very familiar with the target's product range.
Alumasc (LON:ALU) (I hold)
Note from FinnCap says the purchase allows Alumasc (LON:ALU) to access to sales direct to contractors (which is ARP Group's strength), whereas Alumasc (LON:ALU) sell through merchants. Looks like an intelligent purchase of a complimentary business. There's been no change to forecasts on the notes as they state it will take up to 3 months to formalise the deal and get regulatory approval.
Like many companies it currently looks cheap P/E 6.2 (with a 32% discount to peers), whilst we await sentiment on interest rates to improve.
Agreed- I use a screen to show companies where P/E is less than Div Yield. Alumasc (LON:ALU) was one that appeared. Looks a good medium term holding to me.
Morning all, I spent an interesting hour or two reading over yesterdays debate ... as usual, we always find ourselves in interesting times. Complicated times too...so it's unusually hard to forecast, and forecasting is unusually hard!
Seems to me the UK may be the blue print... since a fiscally adventurous government had its wings clipped rather quickly...the markets, currency and government bonds said NO. The rest is history....a little less fiscal adventurism please. The other aspect here is confidence...and markets lost confidence...and therefore a policy compromise was achieved.
It also strikes me that the trot around the debt ceiling in the US...which always gets lifted ...is tied up in the same issues. I, nor anyone else for that matter, have no idea how confidence is maintained but it will become very obvious if it has been lost for some reason. We can speculate what may cause it. The next outcome however may well be a weaker $ , higher rates and less fiscal adventurism please.
So what ? Well we had a lot of monetary policy since 2008 directed towards growth with little effect. Now we drive monetary policy the other way to attempt to control inflation. And the debate yesterday I assume centres on when or will this even work. We don't know... Warren Mosler has helped explain some of the why it hasn't worked yet. ( Economy remains stronger). At the moment we are enjoying a reprieve from inflationary pressure. The deflationists say it's all going wrong... cuts and QE will return. For this to play out I believe we must see negative month on month CPI prints...so we see. An initial positive reaction may turn out negative if the market decides we have taken a turn down. As I have mentioned previously, if we muddle along in the US at 0.2% month on month - CPI will turn up. Will this shake confidence in US bonds? Only time will tell. A rise though to 0.3 or 0.4% would be taken badly.
The reason I find this moment so interesting is that while staying at 0.2% is no doubt positive .... a move up or down could lead to more difficult conditions. So it does feel as though more tricky times are ahead....although not necessarily negative.
I am fully invested, I think UK equities are very cheap. I "hope" the UK government maintains confidence. For me, you can build some resilience into portfolios by owning short term government bonds. You can raise cash levels and invest in cash like instruments. It's always nice to have some firepower. It's only personal but im not interested in areas that did very well under ZIRP.
Whilst I consider my portfolio defensive...it is not universally so. Uranium is speculative for sure. So is Silver. So is energy. One of my largest holdings is Sherborne Investors (Guernsey) C (LON:SIGC) and Navient (NSQ:NAVI) its only investment is a $ revenue $ share price business. If the $ continues to weaken then this does take a little shine off this position for sure. My point is my positioning isn't static and risks within portfolio change. Thus far I have not had to worry about the $ at all but it lurks as a risk im exposed to. Constantly re-evaluating your risks is key to success.
If you ever feel blocked the easiest thing in the world to do is take a little off everything. Wait a few days and see how you feel. If it feels like you made a good move you probably have your answer. The move from China over night should push markets more towards value today....a trend which has run well since the better CPI readings this month. For now Goldilocks is really enjoying herself.
It's a great time to be investing but that doesn't mean risk free. As always best of luck out there.
May I ask what instrument you use for buying short term government bonds?
I bought the bonds themselves - I’m less keen on etfs / funds because I like the redemption. In my SIPP I can’t do that - the Gen Accident Prefs are a poor substitute but probably ok if we turn down. There are money mkt funds you can use now but I don’t know them well afraid.
Thank you
Great stuff RD you seem pretty mustard on the macro any chance of a weekly ramble like the above , personally these days I'm more interested in investment trusts with the odd share gamble. The points you make though are very interesting on the big picture.
Regards Andy
Hope you cover Yu (LON:YU.) update today. Strong numbers and confident outlook:
"As a result of the accelerating revenue profile of the Group and significantly increased EBITDA margin expected to be achieved in FY 23, the Group expects to report results substantially ahead of current market expectations."
Hargreaves Services
Very interesting RNS about its renewables being valued at 27 million whilst in the books at 6 million with plans to realise value which I presume means sell and return to shareholders .
I remember mentioning this about 12 months ago and highlighting the unseen value, especially pivotal was the fact they had planning and start dates .
Whilst the UK government, opposition , politicians and powers that be all bang the drum on renewables the very sad fact is that it is very hard and slow to actually get planning approved and the current time to start is over 5 years .
The RSPB is top of the food chain in terms of first hurdle to pass and “bird surveys” can take 2 years and they have no interest in energy consumption only birds .
I am experiencing this with sone land I have near Edinburgh that Foresight wanted to develop, they could not go ahead because 2nd dire survey revealed a few Canadian geese for a few weeks a year touched down for a rest. There is nothing unique about this piece of land and they are free to land anywhere else in that area .
What is bonkers was that as landowner and the fact the bird was not protected in any way shape or form was that we have the right to shoot them there but not plant a tree there . We are now in our second year of bird surveys and RSPB have requested reports for the past 8 years despite us only having the land 3 years .
In short the “we have plans to build renewables” is political clap trap that is not backed up with on the ground practicality and planning processes to support it .
So for Hargreaves to have sites with planning , actually generating .and others with start dates is very positive.
The 27 million valuation looks understated to me and I think realisation if they sell will be higher provided they sell openly to the highest bidder .
Have to admit I thought the value would be higher at Hargreaves .
Even more annoying is the whole ludicrous nonsense on the wind power , when the wind is blowing we as a country don’t take the energy because the fossil fuel stations and nuclear can’t just switch off like the wind switches up , but guess what we still pay the wind farms for the power they generate but it isn’t used and can’t be stored
It is such an interesting area but the more you learn the more you realise what a lot of wind it is
Nice post Planetx. In trying to find stocks of interest to me in my process the foremost filter has become recognising the challenges we face arising from a fossil fuel era which has been allowed to expand without any form of challenge. That our bills are charged at the most expensive form of fuel being used is a further example. It has also allowed small segmentsof global society to have disproportionate influence on global decisions. Not to mention the fact that these are finite resources produced over millions of years and spent within a few hundred. The whole system needs overhaul but the challenges of doing so even now seem so high. I just wonder if the markets are capable of delivering it and whether private finance isn't a more effective conduit in these circumstances. Of course these circumstances do raise huge opportunities for us investors across hydrogen, renewables, battery to name a few. I think the form of capitalism we see today will be very different from that practised in 50 years time. But Adam Smith wouldn't necessarily have imagined how we practise economics today when he wrote "Wealth of Nations".
Some here will accuse me of trying to make a political statement. I am not. I am trying to think differently, the hydrocarbon age can't and won't last. I as a small investor have to try and work my way through that because the oft stated "it's different this time" is likely for once actually true. Just saying..............
No issue with your investment view but a statement like “The hydrocarbon age can’t and won’t last” has a certainty and inevitability to it that fails to recognise how complicated this subject is.
RD I accept it is complicated and of course trying to make the point in a limited dialogue requires simplicity. But in the end I stand by my wording. Hydrocarbons are finite. So at some point be it 5, 10 50 100 or more years we will run out. The other side of the coin is carbon levels in the atmosphere are higher than they have been in the history of man's time of earth and we are starting to see the impact of putting more out there. Hence my view that the outcome is inevitable unless we do something and there is the investment opportunity. I hope that clarifies my position it is not intended to persuade anyone who doesn't agree just my view.
Hi Camtab,
You are correct in what you say about finite hydrocarbon reserves and timescales.
The latest predictions are that the world will have exhausted all the known reserves of oil by 2050, gas by 2054 and coal by 2090.
David.
My morning smallcap tweet: Pier pressure
Brighton Pier (LON:PIER) ITM Power (LON:ITM) Trackwise Designs (LON:TWD) Proton Motor Power Systems (LON:PPS) Fireangel Safety Technology (LON:FA.) Aeorema Communications (LON:AEO) hVIVO (LON:HVO) Yu (LON:YU.) Northcoders (LON:CODE) Actual Experience (LON:ACT) Tristel (LON:TSTL) Hargreaves Services (LON:HSP) Fadel Partners (LON:FADL), Reach (LON:RCH), Microlise (LON:SAAS), Diaceutics (LON:DXRX), Pebble (LON:PEBB), Eurocell (LON:ECEL)
◄Brighton Pier (PIER)► warns H1-June rev only £16.2m and post-tax below market expectations after weak Q2. July also weak - blames weather, train strikes. [SP=58.92 Cap=21m]
◄ITM Power (ITM)► FY audited results delayed to 17 Au. Blames auditors. Confirms guidance. [SP=98.58 Cap=605m]
◄Trackwise Designs (TWD)► terminates contract with UK EV OEM (see June 30) due to failure to honour contract terms. [SP=NA Cap=NA]
◄Proton Motor Power Systems (PPS)► order for a standalone fuel cell system based on a 50kW container solution for deluvery in FY24. No £££. [SP=8.5 Cap=132m]
◄FireAngel Safety Technology (FA.)► brief flames of hope extinguished as it warns H1 rev down 17% and pretax loss £3.7m, £2m worse (including £1.1m losses on hedging contracts). Blames continued weak trading. [SP=4.32 Cap=13m]
◄Aeorema Communications (AEO)► guides FY-June rev up 62% and pretax £950k+ (£844k). In line? Outlook: strong momentum. [SP=78.5 Cap=7m]
◄hVIVO (HVO)► £13.1m contract to develop an influenza B virus challenge model. Rev recognised throughout 2023 and 2024. [SP=15.46 Cap=105m]
◄Yü (YU.)► guides FY-Dec rev above exp and significantly increased EBITDA margin. Co now targets £500m revenue with 5%+ sustainable EBITDA margin in the short to medium term. [SP=750 Cap=125m]
◄Northcoders (CODE)► £4.5m contract. Guides FY-Dec comfortably in line with management expectations. [SP=218 Cap=17m]
◄Actual Experience (ACT)► wins second order (£135k) for its Digital Workplace Management Platform [SP=0.5 Cap=1m]
◄Tristel (TSTL)► guides FY-June ahead of both analyst expectations and co's growth targets. [SP=354.5 Cap=168m]
◄Hargreaves Services (HSP)►independent valuation of renewable energy land assets of £21.6m-23.1m. [SP=448.91 Cap=146m]. I hold.
◄Fadel Partners (FADL)► guides FY-Dec rev in line, H2 weighted. Profit not mentioned. [SP=147 Cap=30m]
In line: RCH, SAAS, DXRX, PEBB, ECEL
A fascinating announcement from animal feed group Wynnstay (LON:WYN) this morning.
Apparently they are involved in a project called "Dancing With Daffodils" which will help to reduce the quantity of methane produced by ruminant cattle.
They are also "developing a precision on-farm gas
analyser to monitor in real-time individual ruminant emissions of methane,
hydrogen, carbon dioxide and ammonia."
I wonder if they have considered using corks?
Interesting indeed from Wynnstay (LON:WYN) , they do however have a pretty significant competitor in this space from DSM-Firmenich AG (AMS:DSFIR) ‘s Bovaer which is at a more advanced stage in terms of being brought to market.
WANdisco (LON:WAND) suspension lifted!
And down 96% as at 2.30pm.
Hence the elf'n'safety advice not to stand under something that is suspended.
It will be interesting to see if they have any customers left. I was one of the sceptics on LON:WAND and it helped knowing the specific industry. I would venture they are a punt at this price as WANDs only way back as a credible technology is if it gets bought out - I assume at a premium. Was the fund raising to stop someone else acquiring through a fire sale? Maybe. Am I going to buy it? Not right now for sure!!
Weak pre close trading update from City of London Investment (LON:CLIG) today. Unchanged dividend, EPS at 29.8p versus 36.4p last year, below expectations. Weak business outflows. I hold, although I halved my stake in the last few months in anticipation of choppy waters. I would expect a further correction down today. I can't see these being worth much more than £3.60 at this stage.
I have sold out of City of London Investment (LON:CLIG) within my Mum's holdings, I had held for a long while (ok a brief sell/buy over the Covid Spring 2020), the main issue for me was the drop in earnings meaning that the dividend was not covered and at what point does the dividend get dropped if the earnings are not turned around or is debt just going to go up which doesn't make sense in the current world?
The acquisition was meant to help that, but seems to be a continued slow blead, I appreciate that the overall markets have not helped but still strength in greater diversity?
Remains on the watch list but not at the top...
Good luck
Tommy
Can you take a look at SThree (LON:STEM) interim results?
Morning All,
Excellent update from £YU this morning. Strong revenue growth, H1 cash 36.6M, improving bad debt metrics and growing roll out of smart meters.
Market cap looks way too low!
I hold.
Yu (LON:YU.)