Small Cap Value Report (Tue 26 Mar 2024) - RBG, CHRT, JNEO, 888, ASC, GOOD, LUCE, BAG

Good morning, it's Paul & Graham here as usual!
Sorry we've run out of time, so have to leave it there for today.
Revolution Bars (LON:RBG)
Ominous news from Sky last night. Its says this struggling chain of bars & pubs is talking to investors about an emergency fundraise, wants to close a quarter of its sites (maybe a CVA or pre-pack administration I wonder?), and has also put itself up for sale. Clearly that doesn't bode well for existing equity.
RBG has itself just issued a statement confirming the speculation, which says -
Revolution Bars Group PLC notes recent press speculation. Following a period of external challenges which have impacted the Company's business and trading performance, the Board is actively exploring all the strategic options available to it to improve the future prospects of the Group. These include a restructuring plan for certain parts of the Group, a sale of all or part of the Group and any other avenue to maximise returns for stakeholders. The Company also confirms it is currently engaged with key shareholders and other investors including Luke Johnson in respect of a fundraising.
The Company continues to trade in line with management's expectations.
The Company is not in talks with, nor in receipt of an approach from, any potential offeror relating to an acquisition of the issued and to be issued share capital of the Company.
We've been flagging RBG shares here as high risk for a while, eg
26/7/2023 - AMBER - In line trading for FY 6/2023. Special situation, only for risk-takers.
18/10/2023 - AMBER/RED - Flagged "material uncertainty" going concern statement, high risk.
5/1/2024 - AMBER/RED - High risk special situation.
I previously liked RBG as a value/turnaround situation, but as the facts have deteriorated, we changed our minds here and became more negative. Many bars groups are struggling because younger people are spending less on alcohol (a higher percentage are teetotal than previous generations), plus the experiential leisure groups like XP Factory (LON:XPF) are taking away some market share.
The latest incarnation of the former Luminar/Deltic nightclubs business,now called Rekom, went bust yet again in early 2024. Plus of course the labour-intensity means living wage increases are hurting disproportionately, not to mention soaring energy costs, on top of the pandemic chaos. No wonder many bars are struggling, there are just far too many, and the industry needs a permanent cull of the excessive number of struggling hospitality sites, to leave more business for those that remain.
I'm worried existing equity at RBG may have little to no value, and the same could well be the case at Nightcap (LON:NGHT) .
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Ludicrously busy today, so please don't expect us to cover all of these! We'll home in on the most significant, and the ones subscribers are looking at most (as shown on the home page most viewed widget) -
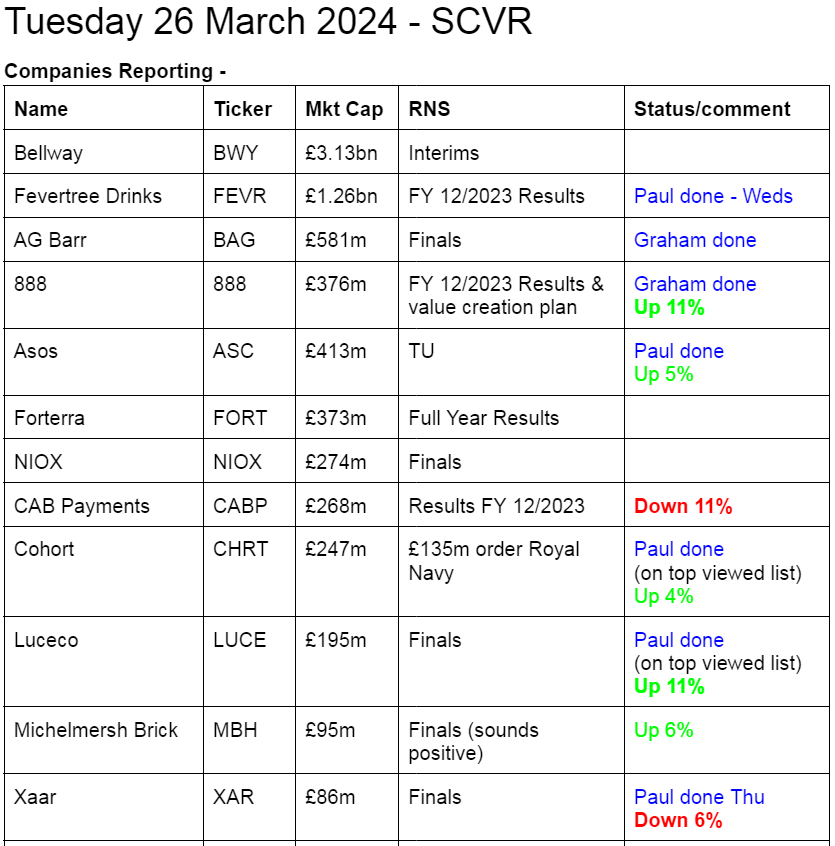
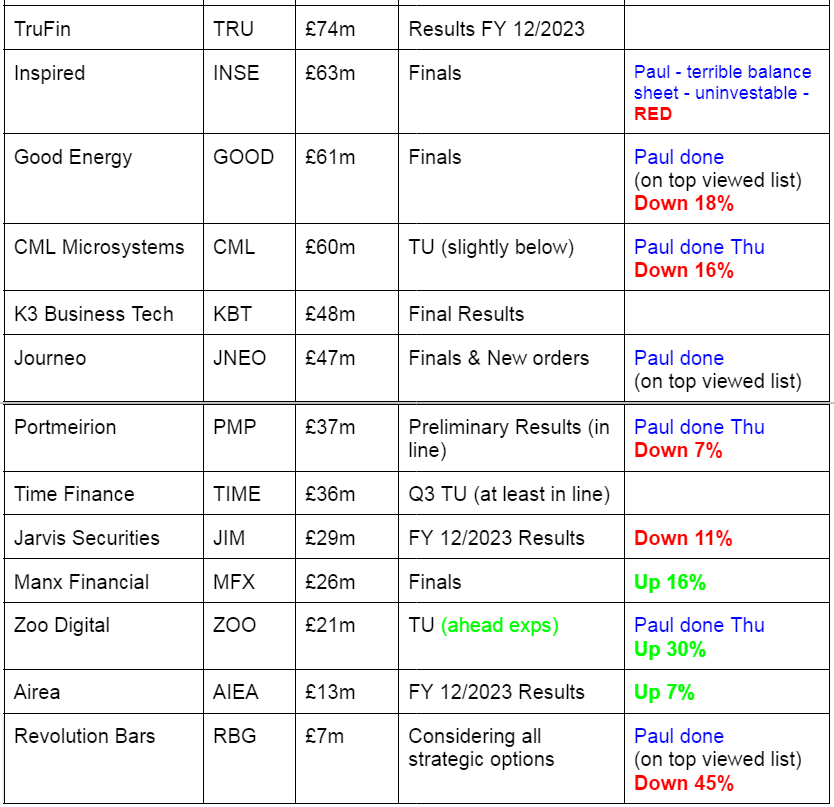
Summaries of main sections
Cohort (LON:CHRT) - 594p (pre market) £247m - Contract Win - Paul - GREEN
Good news with another decent-sized long-term contract win, to protect Royal Navy ships, presumably from drones and the like. Forecasts are raised c.10%, with potentially more upside. I was already positive on CHRT, increasingly so after today's good news. It has good visibility from an order book now over £0.5bn, has a strong balance sheet, and shares look reasonably priced. So I remain bullish. (I have a de minimis personal position personally).
Journeo (LON:JNEO) - 284p (pre-market) £47m - Final Results - Paul - GREEN
Very strong 2023 results, fuelled mainly from acquisitions which bizarrely seem to have cost nothing (in cash terms). Confident (in line) outlook for 2024. Overall, this looks very good, so I'll stick with GREEN.
888 Holdings (LON:888) - up 1% to 84.8p (£380m) - FY2023 Results - Graham holds 888 - AMBER/RED
These results aren’t pretty but aren’t completely awful either, allowing stale bulls like myself to dream of success. The new management team wants to change the name to “evoke plc” and they claim that they can get the leverage multiple below 3.5x by the end of 2026.
ASOS (LON:ASC) - up 10% to 380p (£454m) - H1 Trading Update - Paul - AMBER/RED
A typical update from Asos, which tries to sound positive, but with little substance to it. Guidance unchanged, which is for continuing losses before tax remember (but they only talk about EBITDA). I remain highly sceptical about the company fundamentals, including a £500m 2026 bond that it might struggle to refinance, but anything could happen as it might have strategic value to an acquirer (Frasers (LON:FRAS) now controls 27%).
Good Energy (LON:GOOD) - down 20% to 270p (£49m) - FY 12/2023 Results (unaudited) - Paul - AMBER
A quick review of these complicated accounts convinces me that there are too many moving parts, and hence way too much guesswork involved in trying to ascertain what the future might hold for this energy supplier. Other parts of the business are not financially significant. Balance sheet is pretty good, but not as strong as I previously thought. So it's not for me, as nobody knows what normalised profits (if any) these smaller energy suppliers will make once everything gets back to normal.
Luceco (LON:LUCE) - up 11% to 134p (£216m) - Final Results [slightly ahead] - Paul - GREEN
Superbly clear presentation of good results (slightly ahead exps). Reassuring outlook. Sound balance sheet. I remain positive on this share - it's a good business, owner-managed, at a reasonable valuation. Cyclical recovery upside, and you're only being asked to pay about 12x earnings in a fairly tough earnings environment, which could end up looking a bargain in a future economic recovery.
A G Barr (LON:BAG) - up 7% to 548p (£614m) - Final Results - Graham - GREEN
This old soft drinks maker announces good results for 2023/2024, as expected. A confident outlook statement should, I think, give investors some confidence that the margin rebuild plan can succeed. Bolt-on acquisitions are performing well and BAG remains cash-rich.
Paul’s Section:
Cohort (LON:CHRT)
594p (pre market) £247m - Contract Win - Paul - GREEN
Cohort, the Independent Technology Group…
CHRT is a collection of six largely autonomous defence-related businesses.
We’ve commented favourably on it before, including most recently a GREEN view of its last interim results, published on 13/12/2023.
Today’s news is a particularly large “at least £135m” contract with the Royal Navy for “electronic warfare countermeasures”, including a “trainable decoy launcher system”.
Work on this contract “will commence immediately”, expected to be for 10+ years, with options to extend.
This is the best bit -
Together with other recent order wins, the contract is expected to materially enhance the Group's earnings.
Also potential for export orders -
"It represents a real vote of confidence in Ancilia, a fully UK designed and built solution, for which we see encouraging export prospects.
"Over the life of the project, we estimate it will sustain employment for 150 skilled and professional people in North Devon, and export success could see this increase further still."
Have brokers raised forecasts today? -
The only note I can find is from commissioned researchers Equity Development. It flags that the already large order book is now over £0.5bn.
EPS forecast for FY 4/2025 is raised by 10% to 40.3p
Last year actual adj EPS was 36.4p, and a similar figure of 36.2p is forecast for FY 4/2024.
At 594p per share I make that 16.4x 4/2024 forecast, and 14.7x 4/2025. Note there’s also further upside for future years, as the full contract kicks in.
Paul’s opinion - I already liked CHRT shares, offering good visibility from a large order book, strong balance sheet, and reasonable valuation. Today’s news enhances that, and I imagine we might see shares continue rising.
Hence I’m happy to stick at GREEN.
Journeo (LON:JNEO)
284p (pre-market) £47m - Final Results - Paul - GREEN
£1.1m Orders - a separate RNS for a £1.1m contract win seems a bit over-the-top, given that it’s not particularly material to the £48m forecast revenues for FY 12/2024 -
Journeo plc (AIM: JNEO), a leading provider of information systems and technical services to transport operators and local authorities is pleased to announce that, further to its announcement on 11 March, it has received additional purchase orders totalling £1.1m to supply and install important safety systems on Arriva buses within the Transport for London (TfL) fleet.
The product sounds very interesting though - cameras to replace mirrors, to enhance safety. Great idea, and let’s hope these are installed on all the HGVs on the road, so we don’t get any more tragedies involving left-turning vehicles crushing cyclists that the drivers can’t see.
So I’d be interested in hearing more about this product.
This is for 150 buses, suggesting it’s a useful £7.3k per bus. I imagine there could be plenty more contracts available with other bus operators too?
No change to forecasts from this deal though -
The revenues are included in management's expectations of performance for the current financial year and add to the Company's strong order book, providing further future revenue visibility.
Final Results for the year ended 31 December 2023.
Journeo plc (AIM: JNEO), the information systems and transport technical services group, is pleased to announce its final results for the year ended 31 December 2023.
Figures look wonderful - helped by what seem to have been inspired acquisitions (Infotec & MultiQ) -
Revenue up 118% to £46.1m (20% organic)
Adj PBT up 325% to £4.0m
Statutory PBT reassuringly close behind at £3.7m
Adj EPS is up 92% to 19.8p (PER of 14.3x last night’s closing share price of 284p)
I like the mention of growing recurring revenues, and this -
The increasing barriers to entry into our sector are helping us to establish defendable market positions.
Seeking out further acquisitions “in adjacent markets” - good, as the track record on acquisitions so far appears terrific, so I’m happy to hear companies that are good at acquisitions doing more of them, providing they stick to a financially disciplined approach and do their due diligence carefully.
Outlook and the commentary generally, sound confident - eg
We entered 2024 with a strong order book, a growing sales opportunity pipeline, and reduced reliance on third-party technology. This gives us the confidence that we will continue to deliver on market expectations.
Broker update - thanks go to Cavendish for an update note. It says 2023 results are in line with recently upgraded forecasts.
FY 12/2024 forecast is for only modest growth, a 10% uplift in adj PBT to £4.4m, and adj EPS of 22.1p, so hopefully there’s upside on those forecasts, which I think would be needed to propel the shares sustainably higher.
Balance sheet - my usual quick checks here show NTAV of £6.0m - adequate, but not strong. There’s not much in fixed assets though, so it doesn’t need a huge NTAV. Receivables seem high at £12.2m, which is worth querying if you speak to management or go on a webinar. Note that the £8.1m cash pile has come from customers paying up-front, with deferred revenue of £5.8m (current liabilities) and £2.8m (non-current). So another key question for management is the expected movement in these creditor figures - if they are likely to permanently renew, then the cash balance should remain high. If they are expected to unwind, then the cash balance would correspondingly fall. That’s a key question, as it would determine how much cash is available for acquisitions.
Overall I only have those queries, other than that the balance sheet looks OK.
Cashflow statement - negligible free cash generation, with the increased cash coming from the cash within acquisitions - this looks a very odd situation, where the acquired companies seem to have been paid for using their own cash piles! I’ve been looking for the cash outflow to make the two acquisitions, but it’s the other way around - there’s a net £3.0m inflow from acquisitions! So these two companies that have helped transform group performance seem to have been acquired for nothing! How on earth was that possible?! Is there a catch, why did the vendors agree to such a deal?! As it turns out, the £7.1m cash raised from fresh equity wasn’t needed. That’s what the cashflow statement is telling me anyway.
If management can pull off more deals like this, then shareholders will be celebrating some more.
Going concern statement is clean, with no issues there.
Major customers - note 3 points out that the 2 largest customers accounted for 17% and 11% of group revenues, so there is risk from big client concentration, and lumpiness of orders, something to bear in mind. There could be occasional lean year in future, which you get sometimes from lumpy order type companies. For that reason I wouldn’t be chasing the share price too high, although that doesn’t seem to be an immediate worry judging from the upbeat remarks about orders.
Paul’s opinion - yes I think this looks very good, I can see why many readers are positive on JNEO. We were late to the party here at the SCVR, my last two comments (both in Feb 2024) were green. I’m happy with the numbers today, so will stick with GREEN. People tell me there are lots of opportunities in public transport, with public funds going into improvements. JNEO management seem particularly good at acquisitions, so if they can pull off more blockbuster deals, the excitement could continue.
Shares have had a great run, so it looks as if a bit of profit-taking might be going on today.

ASOS (LON:ASC)
Up 10% to 380p (£454m) - H1 Trading Update - Paul - AMBER/RED
Struggling online fashion retailer. Mike Ashley’s Frasers (LON:FRAS) now controls 27.1% (at 20/3/2024).
The market likes today’s update for H1 of FY 8/2024.
Big fall in revenues, down 18%, but strategy is now trying to make a profit, rather than gangbuster sales growth in the past.
“Ahead on plan” to reduce inventories to c.£600m by year-end. Was £1,078m 8/2022, then £768m at 8/2023. As sales are down 18% in H1 8/2024, then inventories should naturally reduce 18% to £630m, so its £600m target is not demanding.
Free cash outflow of £(20)m in H1, but it says this is dramatically better than prior year, and H1 typically sees large seasonal outflows. Hmmm, I’m not convinced.
“Robust cash balance” of more than £330m, which is actually down from £353m at the start of H1. It also conveniently forgets to mention the £673m of gross interest-bearing debt at the start of H1 (including £464m convertible bond, and £185m term loan).
Outlook -
Full-year guidance is unchanged, including: 5-15% sales decline, positive adjusted EBITDA, inventory back to pre-COVID levels, and positive cash generation, reducing net debt.
Bear in mind the large depreciation changes on its expensive warehouses, and capitalised IT costs, so positive EBITDA could easily still be a hefty PBT loss.
Paul’s opinion - unchanged - it’s a lousy business that never generated any free cashflow, with modest operating cashflow completely consumed by capex (building more warehouses, and capitalising a load of internal IT costs). Therefore I don’t see how the 2026 convertible loan could be refinanced. Its 0.8% pa coupon is pie-in-the-sky now, so even if it can be refinanced, the interest cost would be multiples of existing costs.
Why is Mike Ashley hoovering up shares then? Who knows, his strategy is perplexing. It might involve trying to bully suppliers and bond holders into discounts, but that failed to work at Matches.com according to recent press reports.
Hence I see little to no value in Asos shares as a standalone company, but it could possibly have significant strategic value to an acquirer maybe?
There’s nothing in today’s update to make me want to buy the shares, I think it’s heavily PR-d and quite misleading in parts (especially only mentioning gross cash, and ignoring the substantial net debt). The published accounts from Asos always strike me as a lot worse than the positive noises made from cherry-picked positives in its trading updates.
Meanwhile the Chinese continue to exploit the loophole allowing them to sell direct to consumers, putting further pressure on Asos’s margins.
Why get involved in this share, other than as a punt on somebody bidding for it, for strategic value? Our colour-coding system is based on the fundamentals, not takeover speculation, so I have to stick with AMBER/RED, and that’s probably being generous.
Over the last 20 years we've seen almost the full life cycle of online fashion - astonishing really -

Good Energy (LON:GOOD)
Down 20% to 270p (£49m) - FY 12/2023 Results (unaudited) - Paul - AMBER
A sharp 20% drop in share price today, although that’s only giving up a recent price spike, so the market perception hasn’t actually changed much over the last 6 weeks or so.
I reviewed GOOD here on 12/2/2024 and it’s coming back to me now, re-reading my notes. Its main business (the only profitable part) is electricity supply, where it had a stunningly profitable H1, but was forecast and has given back most of those bonanza H1 profits in H2 losses.
I concluded that the other parts of the business were too small to focus any time on. Overall, I concluded the shares are impossible to value, due to the wild gyrations in profitability. Although I leaned positively due to balance sheet strength, concluding amber/green in Feb 2024 at 254p per share. It’s slightly higher now, even after today’s sharp fall.
Some numbers for FY 12/2023 -
Revenues £255m (up 2.4%)
PBT £5.7m (up on underlying £1.4m in 2022) - only a small profit margin of just over 2%.
EPS seems to have fallen, but it’s presented badly in the RNS, due to a one-off profit in 2022. Canaccord presents the numbers better in its update note today (very helpful, thank you). It has adj EPS going up 12% to 17.1p, but hindered by a much larger tax charge in 2023.
These figures are very difficult to make sense of, with a very low overall margin, loss-making bits within the group, differing tax rates year to year, gyrating H1 vs H2 profits/losses, it’s almost incomprehensible actually, in terms of figuring out any trends, or what the future performance is likely to be.
Outlook -
The Board has confidence in Good Energy's strategic direction and future prospects. In the short term, trading has commenced in line with management's expectations. Further ahead, as a trusted brand with an array of high quality services under one roof, Good Energy is well positioned as a premium specialist in the rapidly growing microgeneration market. We have a proven track record of delivering on our strategy and we look forward to creating further value in 2024 and beyond.
Balance sheet - NAV is £42.0m, slightly up on £39.0m a year earlier.
Taking off the £5.7m intangible assets, NTAV is £36.3m. This includes £10.6m valuation an investment in associate (ZapMap, I think), so be prudent I would write off this figure too, getting to my adjusted NTAV of £25.7m, which is not as good as I expected.
Note there is a “corporate bond” of 5.0m, mostly not repayable in 2024 (see note 5 in the RNS).
Cash generation is very strong, but note that half came from favourable working capital movements (receivables growing £22.3m vs payables growing less at £11.2m)
Paul’s opinion - this business seems like a black box to me - ie I have no way of ascertaining what level of profit it is likely to make (if any) in future. I feel that about the whole sector of energy supply. Figures being reported now are hugely affected by the energy crisis, and it’s anybody’s guess where profits are likely to settle down.
Therefore I remain of the view that it’s just not an area I want to get involved in.
The balance sheet isn’t as strong as I’d imagined, it’s still decent though, but overall I’m going to shift down from amber/green last time to AMBER now. There’s far too much guesswork in trying to form a view on how companies in this sector might perform longer term, as it relies on so many factors outside their control. They only have to screw up their hedging arrangements in some unforeseen way, for potentially major problems to surface. Also the accounting in very complicated - problems in that area caused Yu (LON:YU.) shares to collapse in 2018 for example.
It’s not for me, I want simpler things to invest in. AMBER.

Luceco (LON:LUCE)
Up 11% to 134p (£216m) - Final Results - Paul - GREEN
Luceco plc, the supplier of wiring accessories, EV chargers, LED lighting, and portable power products, today announces its audited results for the year ended 31 December 2023 ("2023" or "the year").
Company’s headlines -
Profitability at the upper end of expectations despite challenging markets.
Continued growth and strong cash generation.
I covered its FY 12/2023 trading update on 30/1/2024, concluding favourably and increasing from amber/green to GREEN. Based on: slight beat after a good Q4, Good cashflow reduced net debt a lot, reasonable valuation (138p at the time), and possible upside from operational gearing in an economic recovery.
This is one of the best presentations of key results information below that I’ve ever seen - comprehensive rather than cherry-picky - please would other companies use this as a template! -
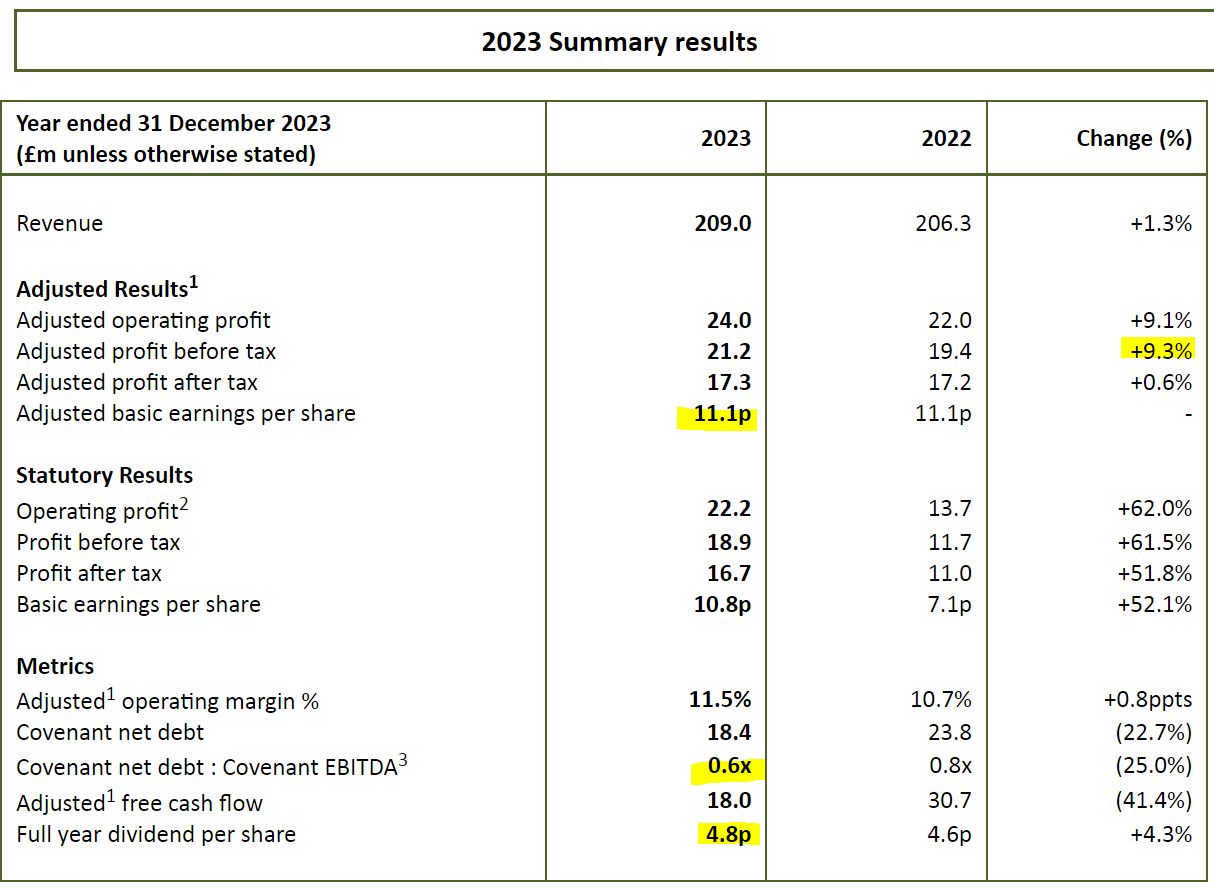
We can quickly calculate that the PER is reasonable at 12.1x
Net debt is fine at 0.6x EBITDA, with a nice 23% reduction in the amount.
Dividend yield is 3.6%, and it’s well covered by earnings at 2.3x
Adjustments are much smaller than last year, which is good.
Operating margin is quite good, and has improved.
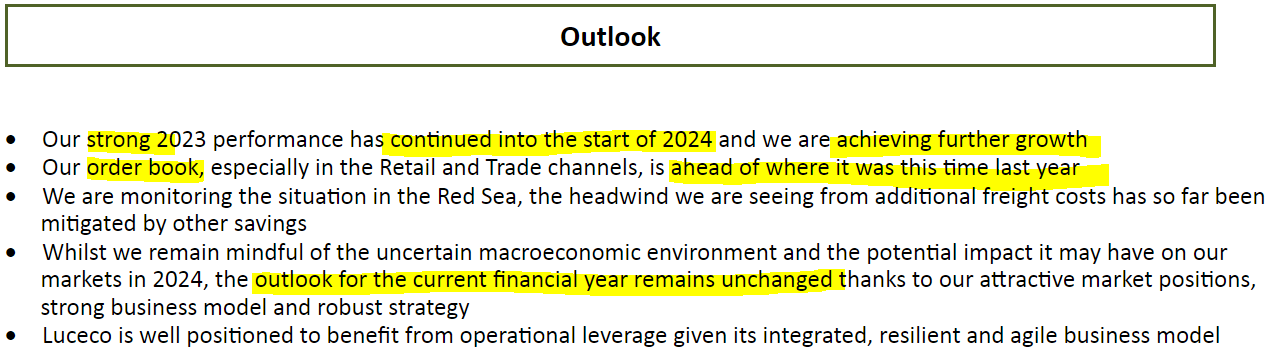
Outlook - is similarly well-presented, and reassuring -
Balance sheet - is strong, with £93.8m NAV, and £53.7m NTAV.
Working capital is healthy, at a current ratio of 2.0x (anything over about 1.3x is good)
Long-term gross debt of £22.3m is fine, and down usefully from £28.4m LY.
Inventories have usefully reduced, as the company promised they would.
Overall, I have no concerns at all here.
Cashflow statement - looks a very healthy business, that can easily fund reasonable divis, debt reduction, bolt on acquisitions, all without breaking into a sweat!
Paul’s opinion - this is a very simple share to research, with the numbers being really straightforward and no funnies anywhere in there.
I continue to like this share, it looks a decent quality business, reasonably priced. I could see shareholders doing well on this, in the next economic cycle. Worth considering as something to tuck away and forget for a while, I imagine.
It’s owner-managed by John Hornby. I’d like to get him on for a podcast actually, so if any LUCE advisers are reading this, please do reach out.
Overall then it’s another GREEN from me.
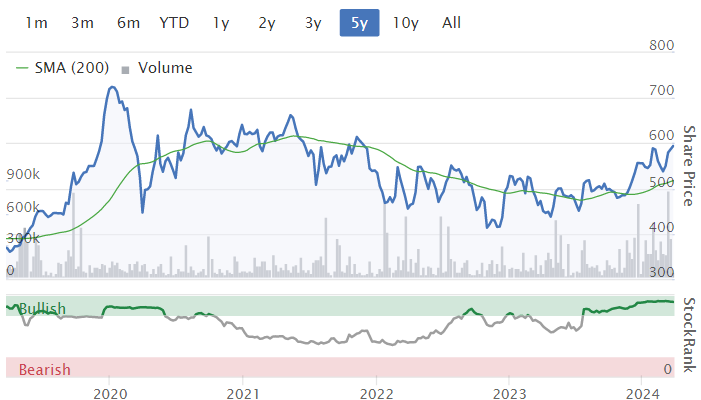
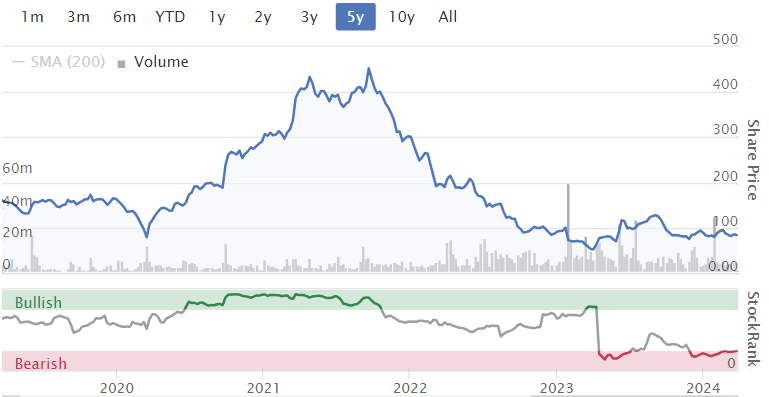
Long-term, the chart is not so great, and includes a bonkers pandemic boom & bust -

Graham’s Section:
888 Holdings (LON:888)
Share price: 84.8p (+1%)
Market cap: £380m
(Graham has a long position in 888.)
888 (LSE: 888), one of the world's leading betting and gaming companies with internationally renowned brands including William Hill, 888 and Mr Green, today announces its audited financial results for the year ended 31 December 2023…
This is a highly leveraged gambling company.
When I first invested in it, it had a wonderful balance sheet. But it used that balance sheet strength to buy William Hill (in mid-2022). My error was in failing to sell out despite the extraordinary financial risk the company had taken on.
I’ve now accepted that it will either be a zero or a multi-bagger from the current level, depending on whether or not it solves the debt problem:
Today’s full-year results for 2023 are as follows:
Revenue down 8% to £1.7 billion (pro-forma or like-for-like basis, taking away the timing effect of mid-year acquisitions and disposals).
Pro forma adjusted EBITDA down 1% to £308m.
Adjusted net income £48m (last year: £64m).
Actual net loss £56m (last year: loss of £121m).
I think there are a few sources of hope in these numbers. For example, “Adjusted EBITDA” might not be worth much when you’re trying to value a secure, profitable company, but where it has a real value is in assessing the ability of a company to survive a high debt load in the short-term. Which is pretty much the main question hanging over 888.
888’s adjusted EBITDA of £308m (down only 1% like-for-like) seems quite good to me, given the 8% fall in like-for-like revenues.
Again taking a rose-tinted view, the company was still loss-making in 2023 but it’s a much smaller loss than 2022.
Net debt fell slightly to £1.7 billion, with the help of some favourable exchange rate movements.
Net debt to EBITDA was stable at 5.6x, but this is a level that is not sustainable in the long run and needs to be reduced.
“Value Creation Plan”
Lots of parts to this plan, here are some of the big ones:
New CEO (since Oct 2023), and 7 out of 10 positions in the executive team are new appointments.
New group operating model, includes £30m of additional annual cost savings.
Geographies will be split up into “Core” markets (UK, Italy, Spain and Denmark) where 888 is a market leader, and “Optimise” markets, where 888 is not trying to be a market leader but does want to optimise the return on its investments. As previously announced, 888 could leave the US market.
New name: Evoke plc (if shareholders approve).
New targets: 5-9% revenue growth p.a., adjusted EBITDA margin to increase 100 basis points p.a., and most importantly leverage to get below 3.5.x by the end of 2026.
Outlook
Q1 revenue £420-430m
Positive outlook for full-year revenue “consistent with medium-term targets”
Unchanged adj. EBITDA guidance for 2024: approximately £340m.
Graham’s view
These results aren’t pretty, and even my rose-tinted glasses can’t avoid that.
There are £49m of “integration and transformation costs” which have been treated as exceptional. Can we trust that this number will be going to zero very soon? I’m not sure.
The CFO’s summarised cash flow statement seems like critical information to me. The key elements of this are as follows.
Cash generated from operations before working capital: £233m (up from £140m)
Negative working capital movements £82m (last year: negative £170m)
Summing these together, net cash generated from operating activities was £151m (last year: negative £30m).
The company could really use a year when working capital movements were flat or were even positive for once.
Unfortunately, for the last two years, these working capital movements have been relentlessly negative. Receivables have increased, customer deposits have fallen, and the company has reduced outstanding payables. All of which serves to suck cash out of the company.
Moving on further down the CFO’s cash flow statement, we have a few very important items:
Capex is a negative cash flow of £68m this year, £77m last year.
Net interest paid £138m this year, £76m last year.
Net interest paid doesn’t tell the whole story, as the interest that was actually charged on the company’s borrowings over the year was £176m (there is often a mismatch between the time interest is charged and interest is paid).
Between capex and the interest bill, it seems that the company is facing regular outflows of about £250m. This depends on interest rates, as most of the debt is at floating rates. The first maturity will be in 2026 (£350m coming due).
I still think it’s possible that this company will pull through. Indeed, if £50m of “integration and transformation costs” can disappear soon, if £30m of additional cost savings are found, if interest rates don’t rise further (or fall), and if we can start to see like-for-like revenue growth, then I would expect this stock to be a multibagger. But that is a lot of “ifs”!
It does have the potential to generate serious amounts of cash, I think, but the last two years have been chaotic. Between the William Hill acquisition, the old management team getting evicted, enormous cost savings being sought, and the impact of new gambling legislation, the company has seen tremendous turmoil.
Investors in the 2028 bond haven’t started to dump it yet.
I’m going to remain AMBER/RED on this one. It might turn out to be worthless, or it might be worth a lot. As it’s only a very small fraction of my personal portfolio, I haven’t felt obliged to sell out of it yet. Someone without my rose-tinted glasses might view it simply as RED.
A G Barr (LON:BAG)
Share price: 548p (+7%)
Market cap: £614m
A.G. BARR, the branded multi-beverage business with a portfolio of market-leading UK brands, including IRN-BRU, Rubicon, FUNKIN and Boost, today announces its results for the year ended 28 January 2024.
This has been on my best ideas list for two years running, so I’m psychologically invested in the outcome here!
We covered the company’s ahead of expectations trading update in January.
Now we get confirmation of a good year for the company:
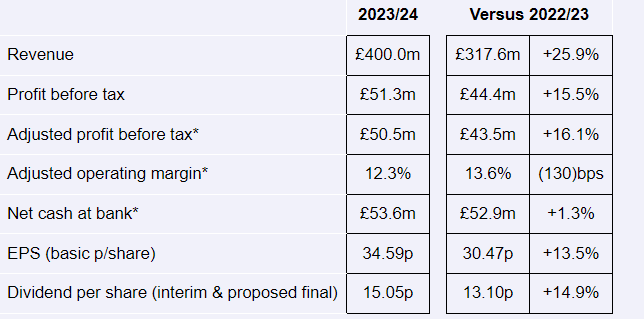
The numbers above are slightly misleading as they do include an acquisition.
On a like-for-like basis, revenues were up 8%.
The growth in net cash is especially pleasing as the company is paying dividends and also bought the Rio drinks brand for £12m during the year. The company acknowledges that it could borrow if it wished, but “in the near term, we value the financial flexibility that a positive cash position provides”.
Outlook is good:
Having seen continued positive brand momentum in the early weeks of the new financial year, we remain confident in our strategy and the continued delivery of revenue and profit growth in the year ahead.
Profit margins
I’ve been banking on this company rebuilding its profit margins; the Chair says: “margin rebuild plan well underway” - good!
You may be wondering how this can be true, given that BAG’s adjusted operating margin (in the table above) actually fell during the year. The reasons for this are to do with acquisitions. In the company’s words:
At 12.3%, adjusted operating margin* was 130 basis points below the prior period (2022/23 : 13.6%). This was an improvement upon our expectations from earlier in the year and largely a consequence of the successful acceleration of Boost and Rio production in-sourcing. This provides further confidence that our margin rebuild programme will deliver as planned over the next two years.
So the company is more than happy with the profit margin result for 2023/24, while still aiming for a significant improvement over the next few years. Refreshed production facilities at Cumbernauld should have a big part to play in this.
I should also mention that BAG shareholders were provided with plenty of warning that the Boost acquisition would reduce margins, so the result for 2023/2024 doesn’t come as a surprise. Reduced margins in the short-term are a small price to pay for acquisitions that should provide attractive long-term contributions to total group profitability!
Industry comments: the UK soft drinks market contracted in volume terms by 2.9%, while increasing in value by 8.3%. Hopefully this year will be better, but these numbers tell a story of a consumer who is hurting. BAG reports both volume and value market share gains during the period.
Interest income enjoyed an uplift to £1.4m (previous year: £0.5m) as rates increased.
CEO transition: the outgoing CEO will be available until the end of July to help Euan Sutherland take over smoothly.
Adjusting items: I should mention that these are beautifully clean accounts. The only adjustment is a £0.8m credit relating to an earn-out payment that will not have to be paid. This £0.8m credit is deducted from the PBT figure, so that adjusted PBT is lower than actual PBT! I don’t get to say that very often.
Graham’s view
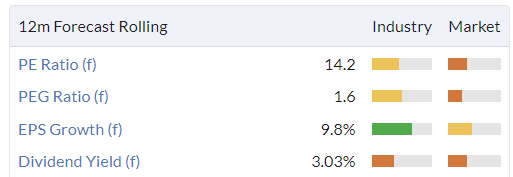
I remain positive on this one. It’s not cheap in terms of the earnings multiple but we are talking about a company with an excellent, very consistent track record of profitability, a strong net cash position, well-known consumer brands, and good prospects to rebuild its margins.
The macro environment might remain challenging, as consumers might continue to feel the pinch, but that will impact most companies, and I think BAG has proven itself better able to handle adversity than most.
At the moment, my main concern is the new CEO. But as I’ve just said, I reckon that BAG has greater resilience than most companies and that would include the likes of the Co-operative Group, Saga and Superdry.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Here we go again! At the end of yesterday's SCVR ken mitchell posted:
Yet again SKY are the first to know. How is it that time and again they know ahead of an announcement the next day confirming they got it right? It’s Revolution Bars (LON:RBG) this time.
Today a large cap (excuse posting here) but after market close we have on twitter/X:
Full marks to DS Smith (LON:SMDS) for getting an RNS out at 17 30. The offer is worth 415p (close today 359.8p) and "The Board acknowledges the strategic merits and potential for value creation through a combination with International Paper. Accordingly, the Board is progressing its discussions with International Paper regarding the Proposal".
Avingtrans
Huge director sale by CFO has really pissed on my chip bitty .
Drops this down from my biggest conviction share 10/10 to a less confident holding .
Think I’ll be reducing a bit , don’t like one of the main business protagonists banking a chunk of cash like this .
Maybe something to do with tax planning but really doesn’t give me a warm and fluffy feeling .
Avingtrans
Huge director sale by CFO has really pissed on my chip bitty .
CFO has only sold 5000 shares. Not enough even to buy a new car. Big sale of 110000 is by a divisional MD and, I think, non-board member. Sales by CFOs tend not to worry me anyway as they're a cautious bunch who don't think like investors. I pay a lot more attention to purchases.
Avingtans (rumour spreading )
Amend above . CFO only sold 1% of his holding
It was Austin Adams that ditched a huge holding (over 100,000)
He’s MD of the engineering division .
Could this mean the possible sale of the engineering division is getting close ??
Putting 2 and 2 together and coming up with 5.
My chip butty is tasting a bit better after re reading the RNS .
Avingtrans (LON:AVG)
planetX
I can't believe they would sell the Engineering Division as a single entity, however I expect a sale of one of its companies, Booths Industries has been touted as the likely first cab off the rank, although it will only be sold if the price is right.
As you have discovered and BnB indicated Austen Adams is not a member of the Board. Also the sale by Stephen King, CFO is beer money (buys a lot of beer though even at today's prices) and he retains 1.2% of the company.
Directors and their interests
As at 26 February 2024,the Directors interests in the share capital of the Company were as follows:
Ordinary shares of 5p each
Number of shares
Percentage of issued share capital owned
Really surprised by the negative share price reaction to Time Finance (LON:TIME) upgrading their profit forecasts for FY May24... I've lost track of how many profit upgrades they've announced over the last 12 months... EPS keeps being upgraded by brokers too (stocko will probably update tomorrow).
PBT of £4.2m for 9m YTD, when HY was £2.7m, means that we should get upwards of 4.6p EPS as Q4 PBT should be higher than Q3 given the growing loan book. Consensus showing on Stocko, before today's announcement, was 4.6p. Current price is around 8x PE (May24) so if you can believe that the growth flywheel is firmly in place for FY25, then that's a bargain.
Like I wrote in my substack post about Time Finance in Feb, they have a very strong growth flywheel in motion, and that momentum looks likely to carry them into continued growth for FY25.
The only big question is - the growth of loans they are making, are they having to relax credit underwriting too much? And therefore will we see big increases of bad debt to come? Only c£36m of NTAV to back more than £190m of lending book... a 10% write-off will wipe out more than half their NTAV and likely result in ruin for shareholders. Unlikely, IMO. But a tail risk?
I still think that two scenarios are possible. Either the shares re-rate to value this properly as a growth flywheel with momentum. In which case I think 50p-60p is fair. Or Arena, the largest shareholder, will make a low-ball bid (maybe around 50p, 25% premium) to take full control and capture all the upside to themselves. As they can then provide all the wholesale capital needed for Time to continue growing its loan books.
(I hold in the Boon Fund)
Why does it keep winning business? I don't see a USP so could it be buying higher risk debt? I don't hold as I don't understand it's success re competition
That is the big unknown risk with Time Finance (LON:TIME) .
Have they discovered a sweet spot in the lending universe to SMEs? Or are they taking on more risks than they are aware of and bad debts soar?
So far, their bad debt rates have been very benign. I would say this isn't that new a strategy; they have been aggressively growing their own-book since start of 2022. And so therefore, the loan book growth in the 2022 year, looks to be good credit quality, given the latest bad debt numbers.
Time Finance (LON:TIME)
Hi Boon
I agree, an impressive update today.
The only negative I could see was the slight drop in PBT margin for Q3 to 15.0%, but one 3-month period doesn't really tell us much.
For context it was:
Other than that, there wasn't much not to like.
A
abtan - maybe more bad debt being crystallised in Q3? I'm hoping not! Time Finance (LON:TIME)
"Pizza chain Papa Johns has said it will close nearly a tenth of its UK restaurants - all of which it says are "underperforming".
The closures follow a review of the business which identified sites that were "no longer financially viable".
The chain, which has 450 restaurants plus others in service stations and holiday parks, will close 43 sites but has not said how many jobs will be hit."
Source BBC: https://www.bbc.co.uk/news/bus...
Thanks Auto. I spotted that too, and did some googling. Turns out Papa John's is doing an outstanding special offer at the moment, any large pizza for £10 (reduced from £23 I think).
It seems to be US-listed group which Stocko has valued at a fwd PER of 24.1x, which seems astonishingly high for a hospitality business which seems to be struggling not just in the UK, overall its broker forecasts are in a downward trend.
It won't be cheap to exit its under-performing UK site leases, but probably immaterial to the overall group, I imagine.
I had pizza last night, so won't be mystery shopping Papa John's Bournemouth branch this week.
I wouldn't read too much into the 50% discount at Papa Johns - its normal and I suspect there just to catch out the inebriated. I ordered 4 pizzas online for a kids party 2 years ago and was floored by the £80 bill!!! -then realised there a 50% off code on their home page.
Good for Domino's Pizza (LON:DOM) ?
These direct-delivery-to-consumer pizza chains are having their lunch eaten (no pun intended!) by the food delivery apps and their plethora of independent pizza shops.
Pizza delivery is an operationally geared business - fixed rents, fixed energy usage (ovens), fixed staff costs, fixed delivery driver wages. Hence why they always use sophisticated deep discounting during off-peak days/times.
So even a modest site-level reduction in volumes, can cause havoc to the thin margins/profits.
Great news indeed for the relatively new but experienced management team at Domino's Pizza (LON:DOM) , they are as I understand it Boon working WITH the food delivery apps to generate additional orders but delivering using Domino’s own drivers.
Domino’s have also listened to your point re operational gearing and are considering the addition of another brand to their existing distribution infrastructure ;) I hold.
MS International
Pretty friendless at the moment now heading south below the 800p barrier .
Lots of holders on here .
Think this is just a drift due to lack of news and a management team that are more concerned with running their company than keeping the stock market warm with hot chocolates and marshmallows .
Probably a good thing in the long term and a good management team running their company well is hopefully what they are .
MSI haven't ever worried about updating the market or using brokers. No change. Progress comes from the rare interactions they choose to make. As a long term holder I can only say it has worked so far but no one can read the future. I continue to think this will end in either a reorganisation and sale of the diverse parts of the business or a complete takeover.
I wish MS International (LON:MSI) put out broker notes for PIs on Research Tree. When SP starts drifting you can’t help but think those ‘in the know’ are selling for a reason or if it’s just nervous selling from PIs because of lack of visibility. Other than that it seems a solid business (I hold - nervously)
I find it helps to go back and read over the latest communication from the company when you start to worry. In the case of #MSI there was a spate of announcements a few months ago about a number of contracts received and in particular one which had been expected in the previous period, which has now fallen into this year, so my expectation is that they are likely to be reporting very healthy activity. I could always be wrong of course.
I think possibly also this is a strange time of year when some investors take profits in companies whose share price has risen substantially so that they can benefit from their capital gains allowance before the end of the tax year. Perhaps they then buy back their shares in the new tax year. This may be a factor here as #MSI has risen over 50% this tax year and is quite illiquid so it won't take much selling to move the price.
MS International (LON:MSI) murrb - fwiw I think you are right. It's always worth re-reading the recent reports. Regularly.
MSI shareholders are in 2 distinct groups >80% directors and long term shareholders, sitting on gains of 4x or more, who are not selling, but also not buying. The remaining <20%, and it might be a lot less, are more recent shareholders who have bought at much higher prices and will be more likely to sell as the price drifts downwards. It's the shorter term shareholders who now set the price - until the results are due in June.
In 2023 the price fell around 40% in the 6 months from January to June. I suspect that some holders have also been selling this year with the intent of buying back in May if the pattern repeats itself. So far its only fallen 12%. I don't see it falling 40% this year, as the promised US Navy contracts all landed in the last few months. But it might well have further down to drift. I'd not be surprised to see 750p under consistent selling and not much buying.
Of course - there is always the possibility that MSI release another rns - which keeps me from trading in and out. That and the knowledge that over many years I've proven myself to be extremly bad at timing and trading. Just not my thing.
It's alway impossible to forecast MSI figures. Expect the unexpected is probably sensible? Few companies actually increase revenues and profits in a streight line. Bumps are to be expected?
Even to interpret the figures we do have takes a lot of backgroud research and digging. H1 defence figures were largely due to taking the £22m revenue on the first deliveries of the land-based system. There appear to have been few if any other defence deliveries in H1. I expect more in H2 accompanied by an increasing baseload of support, maintenance, spares and training. I'd also like to see a slight improvement in Forging operating profits, Superstructures maintained and branding moving to breakeven or just above.
Even though I see a range of possible outcomes, I do like to maintain my own forecasts, so I can see where I went wrong and hold myself to account. Or not. Fwiw I'm current expecting around 80p eps as the - most likely outcome - for the FY, but it could easily be significantly above, and it could be significantly below.
cheers
Mark (long term holder)
IG Design (LON:IGR)
Market cap £104m
Price 115p
Not a growth stock , but:
1. Trades at less than half of its NTAV.
2. Trades on a laughable EV/FCF of 1.93X.
3. Estimated 2026 dividend at 8p.
4. Estimated 2026 Net Cash Balance at £79m.
Company’s goal is to achieve the pre-Covid operating margin of 8% by 2025 but current forecasts I have provided are based on 5%.
Too cheap to ignore and I will start adding this to my portfolio.
All the best
Something needs to happen at IG Design (LON:IGR)
Its results back in Nov sounded good and the market liked them, but the price continues to drift lower.
Brokers seem to have targets of 250-275p ish and if they can deliver their plans then this is achievable in my eyes, although I have been tempted to bail more recently in favour of other opportunities and my growing frustration with the small cap space.
Think I will hold on and se what the next results bring.
Journeo (LON:JNEO) yes lovely results.
Paul - I need to double check but I seem to remember £6m of the £8m is net own cash. And yes, they have done some great deals. The scale they’ve now built and global market leading presence is key to future growth.
I like the increasing %age of recurring revenues and I suspect the 23p eps forecast is set soft to beat. Business momentum appears to be strong. So it’s still only on 12* PER which does not appear expensive to my lens. I see brokers have moved target prices closer to 385p so around 15-16* which feels about right to me. Over the next 3-5 years though I can see them growing strongly. In the US they have a lot of opportunity with the Infotec New York train deal of 500 trains is only 1/4 of the trains coming up for tender so you could easily see them doubling their existing wins there for example.
Anyway nice to see - looks like a good GARP stock to me
I sold out of Journeo (LON:JNEO) today as I thought it was a small miss on forecast EPS (actual 17.96p vs forecast 19.8) and Net Profit (actual 2.97m vs forecast £3.2m). Happy to be corrected if I’ve got this wrong. The other thing that was bothering me have been the recent RNS’ announcing contract wins that turn out to already be in management forecasts. Maybe they just want to shine a spotlight a bit more on the company, but would have preferred to hear about news adding to the forecasts and then not come short as today.
Hi LeicesterPete
Journeo (LON:JNEO) results bang in-line. Adj eps of 19.8p which was as per previously upgraded forecasts. SO they beat previous forecasts and traded in line with pre results update. Cavendish note confirms this (see Research Tree)
They tend to announce every new contract over £1m. I think this is a hangover from being a much smaller unit - I actually like it because (1) it tells me they are winning business regularly and gives me greater confidence in the numbers and (2) they tell me its in the forecast so I have no need to adjust my numbers.
The only downside is it could be a rod for their own back - ie if they stop doing this without first communicating to the market then people may inversely worry when they don’t announce them!
Anyway - each to their own. Hope you made decent money on it. I’m more in line with the brokers at closer to a 400p target. Look at the PEG ratio - look at the growth and the fact that this years earnings have clearly been conservatively set. Therefore personally I expect a beat but maybe I’m wrong. I think they are really only just scratching the surface of the potential market and I back management having see what they’ve built so far and how good the acquisitions have been.
Please forgive this intrusion, but I just wanted to update on the fund raise for our favourite charity Zane. For those who are not aware, I’m trying to encourage as many people as possible to read a novel I’ve written, called Pigs Get Slaughtered. It’s a crime novel and tells the story from the perspective of a UK private investor. I’m sure there are many aspects that readers here will immediately recognize and the book has been well received so far. For the month of March, I’m going to donate all the royalties to the Zane charity and so far we’re at £78-00. The e-book is only £4-99 and a little over £2 for each sale will go to the charity. With one week left, I’m sure we can get over the hundred mark with your help. If you’d be interested, please check out the book at the following links. Many thanks.
Book: https://mybook.to/PigsGetSlaughtered
Audiobook:
https://play.google.com/store/...?
https://www.audiobooks.com/aud...
https://www.barnesandnoble.com...
About quarter of the way though after purchasing the "real-thing" through Amazon.
Enjoying it so far - well done on your first foray into publishing/writing - I hope you carry on.
Kevin, I’m glad you’re enjoying it. It really helps to get positive feedback. All the best.
Three portfolio companies reporting this morning. Have briefly read the salient points but need to revisit the full texts:
Michelmersh Brick Holdings (LON:MBH) surprisingly positive results given the parlous state of the demand for bricks and in stark contrast to this morning's prelims from Forterra (LON:FORT) . Net cash of £11, profit before tax, basic EPS and dividend all increased. Small differences between statutory and adjusted results. Admittedly Michelmersh Brick Holdings (LON:MBH) is smaller than Forterra and Ibstock, but I fail to understand why it is trading at such a discounted multiple.
Journeo (LON:JNEO) As far as I can see an excellent set of results with a substantial road for growth. Unlike many IT related companies Journeo (LON:JNEO) products and their applications are for the layman, easy to understand and there for all to see at railway terminals, airports and on the bus networks.
Flowtech Fluidpower (LON:FLO) One my problem children. A lot of detail in the prelims, but on a quick scan, the tanker appears to be turning , albeit slowly. Certainly a lot of change, which, fingers crossed will deliver the hoped for improvements. Management, especially Roger McDowell, non executive chair are starting to eat their own cooking, having bought shares during the year, see below.
How the market will react to the above, I have no idea, but happy on the basis of what I have read to continue to hold, although tempted to add to to Michelmersh Brick Holdings (LON:MBH) AND Journeo (LON:JNEO) . Incidentally Frank Hanna leaves the former today to take up the post of CEO at Brickability (LON:BRCK) that I also hold.
"Flowtech Fluidpower plc has been notified of the following purchases of ordinary shares in the Company by PDMRs and/or Persons Closely Associated with them (PCAs) on 30 August 2023:
Ordinary Shares
Purchased
Resultant Number of
Ordinary Shares
Resultant Percentage
Holding in the Company
Roger McDowell, Chairman
300,000
1,050,000
1.71%
Mike England, Chief Executive
60,470
60,470
0.01%
Annabel Brooke, PCA of
Jamie Brooke, Non-executive Director
115,000
210,000*
0.34%*
Michelmersh Brick Holdings (LON:MBH) looks very good and would also like to understand how they've managed to increase profits last year, while peers such as Forterra (LON:FORT) have seen a sharp fall in earnings. Is this outperformance sustainable?
One of the reasons that Michelmersh Brick Holdings (LON:MBH) has managed to outperform its peer group is because it makes bespoke/premium products unlike Forterra that generally services the volume housebuilders.
Nice balanced summaries, thanks Jonno. We welcome posts like this from subscribers, especially on mega busy days like today, and it can help us home in on the priority companies for us to look at too.
Best wishes, Paul.
I think that Michelmersh Brick Holdings (LON:MBH) is a very well run company, but I would make a couple of points:
The company openly stated that it entered the last financial year with a very strong order book, which was likely to produce a good result. In the event, volumes didn't rise but were maintained. Prices rose and costs were trimmed.
I draw your attention to the below excerpt:
Despite the reduction in despatches in the fourth
quarter, we took the decision to both, maintain normal production
volumes as we targeted maximum operational leverage from our broader
manufacturing base, and invest in the appropriate inventory levels to
support our FY24 expectations and to provide our loyal customer base
with a consistent supply of our product portfolio.
My reading of this is that orders are now below normal and inventory is rising. I would expect this to result in a short dip in results, before normal service is resumed. Just my opinion.
I think your last para might be correct. if there is a recovery in '25 FORT (I hold)has spanking new kit for the mass market. If not things will be v bad for a while.
Michelmersh Brick Holdings (LON:MBH)
Hi GreyInvestor
I completely agree with your cautious sentiment here and coincidentally the paragraph that you have quoted was the exact one that caught my attention the most.
So demand is down, but they're going to keep producing anyway? Seems odd.
I should probably add that I sold out a few weeks ago after reviewing the latest DBT data, which highlighted the material drop in brick deliveries over the last few months:
(https://www.data.gov.uk/datase...)
---
I'm aware that Michelmersh Brick Holdings (LON:MBH) charges a premium for their products (albeit a greatly reduced one after the last few years), implying resilient demand, but I still remain wary that there's a profit warning around the corner.
I also noted the absence of any real outlook for FY24, with focus instead on the long term need for more housing.
It would have been useful if there were some numbers behind the order book as well.
---
Finally, it looks like the PBT margin on Fabspeed dropped from c8% in FY22 to c3% in FY23.
I saw it as a good sign that the company specifically explained the weak performance here when they didn't really need to - I always like honesty.
---
Hopefully the outlook for the next 12 months becomes clearer soon.
A
Cheers Paul, as Paul Hill said good luck with today's workload. My head is spinning after briefly reading the results for companies I hold.
All the best.
Hi Jonno,
Flowtech Fluidpower (LON:FLO) I'm coming at this one with fresh eyes and have been buying this morning. It's cheap with a single digit rating and double digit free cash flow yield. But if new management can execute (and judging by the multitude of director purchases they are backing themselves) and improve margins then this has the scope to do really really well.
I think a lot of people have got old and bored waiting for this one but therein lies the opportunity maybe...
Hi Burnt Onions
I agree, but more so with your observations that the majority of holders have got bored or frustrated waiting and have sold. Clearly something needed to change and in large part thanks to Richard Staveley at Rockwood Strategic (LON:RKW) and Christopher Mills who were I believe instrumental in the appointment of Mike England as CEO last year, the ship is starting to turn.
The share price has flatlined between 78p and 82p for an extended period, so hopefully with a little more optimism and anticipated fall in interest rates one can look forward to it appreciating. The director share purchases referred to in my earlier post were made at 82.6p
The dividend has been increased by 5%, which I believe is an encouraging sign and debt is coming down. Liberum forecast net debt falling to 11m, excluding leases for FY24.
All the best
Flowtech
I’m well known as a fan of Staveley / Rockwood / Mills.
I don’t really rate Flowtech, it’s been one of their “turnarounds” for several years and they haven’t turned much around .
The issue I have is Flowtech is simply a distributor with no IP or own brand value .
So it is doomed to remain a middleman making a 1.5 mark up and 30% margin if they are lucky . Chuck in the overheads and it’s a mediocre company .
Think they got this wrong and are trying to grind out a result .
If they were building a company with IP and profit maybe cut them some slack .
Think there only plan now is to trim sone costs, maintain margin then try to sell it as a “turnaround success” and dump it on to a trade buyer / private equity .
Maybe a bit of upside but I see it as an unrenarkable third party distributor .
Bit like Titon who put out another rubbish trading update today but they have good IP and freehold and cash and that’s a new play for Rockwood .
So Fluidpower Rockwood have not worked any wonders .
Flowtech Fluidpower (LON:FLO)
I hear you Planetx but my understanding of it is the turnaround only really commenced a few months ago, a gross margin improvement of 273bps from 2H23 v 1H23, that's a pretty rapid improvement and reading the results there is plenty more self help to come.
The new CEO is a former COO of a FTSE 100 company, he is a heavyweight and has been in the job for less than a year. His LTIPS don't activate until the share price is over £2 and some at £3. He didn't need to take this job, it was a huge coup for Flowtech, he clearly sees opportunity here.
Avingtrans Chairman (I know you're a fan) has also been buying plenty of shares.
I think watch this space, this is hopefully the beginning of a 24 month doubler, just my opinion...
Hi planetX
We are going to agree to disagree regarding Flowtech Fluidpower (LON:FLO) and its potential to turn the corner. The new CEO, Mike England has been in place for less than a year and has certainly made an impact. The outcome of the various operational changes will take time to have effect, my view is that one needs to judge a new management once they have had sufficient time in post. For me that is 2 to 3 years. It takes time to turn around a business that has lost its way.
Flowtech Fluidpower (LON:FLO) needs to increase stock turn and its operating margins. The aspiration is to improve the latter to mid-teens, which judging from the operating margins achieved in its European operations should over time be doable.
Although revenue in the Benelux and Ireland is much smaller than GB, £32.6m versus £79.5m, operating margins are much higher.
Current operating operating margins in Benelux and Ireland are 15% and 11.4% respectively versus 9.3% for GB. If the operating margins for the latter can be increased in line with those of Europe (including Ireland) then earnings and the share price will follow, subject to no significant drop in revenue.
The business has a target of achieving a mid-teens operating margin across the board. On the basis of today's results I am prepared to give the management team time to see if they can achieve this. As always time will tell.
Our geographical segments at a glance
Great Britain ("GB")
Benelux
Ireland
2023
unaudited
2022
audited
Change
2023
unaudited
2022
audited
Change
2023
unaudited
2022
audited
Change
Revenue (£m)
79.5
84.9
(5.4)
10.6
10.4
0.2
22.0
19.6
2.4
Underlying operating profit (£m)
7.2
9.8
(2.6)
1.6
1.3
0.3
2.5
1.9
0.6
Underlying operating margin
9.3%
11.5%
(2.2)
15.0%
13.0%
2.0
11.4%
9.9%
1.5
Underlying profit before tax (£m)
7.0
9.6
(2.6)
1.6
1.3
0.3
2.5
1.9
0.6
Jonno
Ref - Flowtech
You could be right however my point is Rockwood have been incumbent for a long time and have been touting this as a turnaround so they were active with the previous management .
So actually I don’t see this as a new turnaround but one that has faltered .
Even with the standard practice that any turnaround CEO will bring
- cut costs
- increase margin
- reduce stock
- improve stock turn .
It’s still going to be a middle man distributor company that makes a few quid but creates nothing of true long term value .
So I’m not a fan .
Can see why you are a believer .
planetX
I fully agree that the turnaround, if and when it gathers pace will have been a long time coming. Rockwood/Harwood clearly lost patience with the previous incumbents and the current management team is new, so fingers crossed!
All the best
I thought the value that Flowtech Fluidpower (LON:FLO) had was that they had literally any part you need. Because when a part fails on one of the pipes/fluid systems (you can tell I'm not technical in this area!), it usually is quite critical and needs to be fixed quickly?
So they had pretty much any part you might need... and they could get it delivered / available very quickly...
Whereas manufacturers didn't want to create their own network of stock and urgent delivery across multiple countries?
So therefore - I can very much see a need for a "platform" as this is, where you can find any part you need, and assured it will be delivered as quick as it can.
Would it be a stretch to call this the Amazon for the "flow solutions repairing industry"?
Hi Burnt Onions, if you don't mind I can add some seasoning to reasoning re Flowtech Fluidpower (LON:FLO) , it's history from my Sold Co's spreadsheet; I just hate these long, long declines and try to seize every opportunity to avoid them, and wishing I could set Stop Losses with confidence.
The attraction for Good Energy (LON:GOOD) was the forecast of 9.5p eps and then 18.3p for end 2024, 33.2p to end 2025 and 69.2p 2026.
A quick glance at the Results today was enough to give serious doubts about that so I escaped (at least for now) just in time for a 14p profit.
There are SO many small companies reporting today but I hope Paul might somehow find time to cover Good Energy (LON:GOOD).
The preliminary results are to be presented on Investor Meet at 1 pm today.
Thanks for the Good Energy (LON:GOOD) Update Paul. Enough reasons there not to regret the hasty decision to sell on just a quick scan of the Results. A key reason for getting out asap was because the share had risen so strongly ahead of Results, so even a slight disappointment was likely to see the share price take a hit.
The share was down over 60p today BUT that was only the pre Results fast gains unwinding. The share is now back to where it was Monday last week. The clever investors were those who bought a week ago for a quick profit and who took that profit yesterday, unlike me who ended up with just 14p of profit left……..and had I delayed the sale by another couple of minutes the share was down from the 298p I got to the mid 260s.
Luceco (LON:LUCE) full year results snapshot. In line with expectations, if not a very small beat. Nice to see them returning to growth, even if it is just 1.3% for revenue. Clearly getting back on top of margins and the issue of destocking appears to be over. They offer signs of improvement for segments that have shown weakness, so I think they may do quite well over the next few years.
I'll be watching their webcast at 9.30am, here's the link for those that want to watch & haven't seen it:
https://stream.brrmedia.co.uk/...
I hold.
I thought the webcast was encouraging, there were a number of points made, which I think should result in upgrades over the next few days. Some notes I made
Yes I agree, it gave me confidence. I like that the CEO was very realistic as well in answering questions, he wasn't promising stellar growth in the near future, but laid out their prospects sensibly.
Their further moves into EV and home energy management sound like a promising growth avenue. It puts me at ease that they are seeking out alternative countries for manufacturing as well, Vietnam & Mexico were mentioned. I don't think they will ever leave China completely, but having alternatives to fall back on is good in my opinion.
Edit - You must have updated your post while I was writing my response haha. Yes all great points, thanks for writing them all up. Lot's of positives if they can execute and market conditions shift in their favour.
Yes, I was having many problems with the bulleting feature on Stockpedia, it doesn't work very well !
I think some upgrades are coming out as the price is rising
Looks like people selling the news on Good Energy (LON:GOOD) should have guessed really as the sp was climbing up into the results today.
I thought it all reads quite well, must have missed something.. not on the list for today for a report so be good to read others views on it
My key question that jumps out of the update, unlike YU, how sustainable is the revenue?! It's very low margin, yes it has generated some nice cash, but it states "revenue and costs will be significantly lower next year". Will leverage stay the same? If not the small PBT number will be reduced.
I think it's important to distinguish between the legacy supply business which is subject to the wipzaws of energy price movements and the fast growing energy services business (40% expected in FY24).
The strategic pivot to the energy services business - solar, heat pumps etc focussed on higher margin installations - is the key to the investment case.
True, but that is currently only £3m revenue with a -£3m operating loss. That will take time to become meaningful and with their high admin expenses it does put a question mark over the short term. Plenty of cash though even when you excl. customer deposits.
The Energy Services number from today's Canaccord note are Revenue FY23 = £8.5m, FY24 = £38.6m and FY25 = £51.9m with of £1.5m, £1.5m then £5.6m in FY25.
For me a key risk is the energy services ramp which depends on successful integration and growth of recent acquisitions. There is currently a long wait for heat pump surveys so I suspect there's a battle on to recruit and train people.
Hopefully we'll learn more at 1pm.
If there is anything guaranteed to send a share price down it's an investor presentation, and I have Good Energy (LON:GOOD) at 1 and XP Factory (LON:XPF) at 2........
here we go..
Hope it went well.I'll try to listen in on the recording as the investor meet meetings can be pretty interesting.I hold too, but not a market timer or trader for the most part (as i find it too hard) and 'hope' for a decent overall few year hold and the business thrives, as there's so many profit warnings around nowadays.I'm hoping their solar installation business really takes off and no doubt if it does i'll miss the gains without being invested all the time, even if i'm sat down reading RNSes everyday.I'm not skillful enough.I missed Yu (LON:YU.) around £1 but remember someone who bought in soon after the initial huge profit warning more than a few years back and waited a couple of years when noone was interested and wish i did the same now. Here's hoping!
They were both good, both forward thinking companies, I'm going to keep holding both of them, slow burners hopefully. XP Factory (LON:XPF) Good Energy (LON:GOOD)
If you look at the broker note for Good Energy (LON:GOOD) you can see it has resulted in a downgrade of 20% of the next 2 years EPS forecasts. That’s quite a large drop with it now trading on a 1 year forward PER of about 12 before this mornings drop took it to 9. That’s quite high for this type of business so I can see why it has come down personally. My worry would be how accurate those numbers are. The company unhelpfully just said revenues and costs materially down in 2024 but didn’t really tell us how margin is holding up and whether there is any lag impact in costs vs revenues that might increase/decrease margins in short term.
I struggle with this company. Have watched it for a while (missed Yu (LON:YU.) at 380p unfortunately) but just can’t quite work out the business model and how operationally geared it is to energy prices. I guess that uncertainty holds the price back ultimately.
Good Energy
2022 included a one off £7.8m valuation uplift related to Zapmap. So not to be repeated.
Reported profit after tax for the period (2023)of £2.9m, 2022 was £8.6m.
So profit after tax for 2022 without the Zap map £0.8m. Making 2023 £2.9m not look so bad.
Reuters: ASOS (LON:ASC)
* ASOS PLC - TRADING STATEMENT FOR THE 26 WEEKS TO 3 MARCH
2024
* ASOS PLC: STRONG CASH PERFORMANCE FROM PLANNED INVENTORY REDUCTION; REITERATING GUIDANCE
* ASOS PLC: SALES DECLINED BY C.18%, BROADLY IN-LINE WITH GUIDANCE THAT P4 FY23 TRENDS WERE EXPECTED TO CONTINUE THROUGH H1 FY24
* ASOS PLC: AHEAD ON PLAN TO IMPROVE STOCK EFFICIENCY AND REDUCE INVENTORY TO C.£600M BY YEAR END
* ASOS PLC: 26 WEEKS FREE CASH FLOW IMPROVED BY C.£240M DUE TO IMPROVEMENTS IN UNDERLYING PROFITABILITY AND CLEARANCE OF AGED STOCK
Frasers have accumulated 20% of the equity. Time to pounce?
A Stocko favourite, more than 25% upgrade to SP target on yesterday’s close.
Bank of Georgia BGEO.L : Peel Hunt raises target price to 6,000p from 4,550p
Still looks very light to me JimMcLad on Bank of Georgia (LON:BGEO) - another broker is 6750p. Looking at the new forecasts I can’t help but think Armeniabank is not in the forecasts fully. EPS is around £11 for this year so we are still talking a PER of 4 currently, which just looks wrong to me. Armeniabank was bought on a very low PER and is earnings accretive in year 1 but it just doesn’t look fully factored in to the forecasts so I wonder if this is being deliberately held back. I guess we will see - I’m in no hurry on this one, plan on holding next couple of years - would think a PER of 8 is more appropriate particularly now given the regional diversification and that equates to a circa £90 share price!
Davidjhill
Bank of Georgia (LON:BGEO)
Nothing I can add to your analysis and am also very happy to hold (and receive the generous divis). I’ll set my Stocko alert at £90 and request a further update from you then 8-)
Bank of Georgia (LON:BGEO) what great performance! And that dividend growth is superb! It's almost enough to make me break my "never invest in banks" rule. I'll stay strong and poor for now but my congratulations to holders with my best wishes for the future.
It does really show the benefits of finding a good company with progressive dividend policy. I think Bank of Georgia (LON:BGEO) now yields something like 30% on my original investment which is phenomenal. If only they were all like that :D
Fevertree Drinks (LON:FEVR) interesting read on the FY24 outlook with significant gross margin improvement (600bps) linked to easing inflationary pressures (glass etc). Should flow directly to profit plus additional benefit of any price increases taken to offset inflation in FY22/23 .
Absolutely! Looking crudely at the Fevertree numbers. Management expect revenue to grow roughly 10% in 2024 and Gross Profit to improve by 6%, so from last year’s 32% to 38%. Assuming continued growth in admin expenses and 25% tax that would mean net profit of roughly £40m. Roll forward another year and assume a further 10% increase in revenues plus GP at 40% (CFO mentioned on today’s call he expects GP improving in 2% increments after this year) and that brings us roughly to £55m in 2025. Assuming fixed share count that takes us to a P/E of 34x in 2024 and 25x in 2025, post today’s rise. Assuming £500m of revenues by 2026 and a further 2% GP uplift takes us to near 20x. Of course the really exciting scenario is them being able to crack £750m revenues (which based on 10% growth would be roughly in 2030/31). Assuming GP of 40% and all else equal you are at net profit of c. £125m or forward PE of 11x. Given the cash generative nature of the business you could afford 50p in dividend by then and enjoy an Operating FCF yield of 13%. Obviously this does not factor in time value of money.
In conclusion what am I saying. Well as a current holder I’m happy to roll the dice and keep holding here. I think they’ve built an excellent brand with adjacent category optionality plus growth optionally (US / Asia). Business has shown it can weather tough inflation and weak consumer spending, whilst holding off / besting some deep pocketed competitors
(Schweppes). Assuming they can pull off the margin improvement and keep growing I can’t see why the SP can’t get back to £20 eventually. Would imagine £15 would be the floor in any offer situation, should a trade or financial buyer emerge
Zotefoams (LON:ZTF)
With the ReZource project seemingly close to a point of success or failure, I was intrigued by last night’s RNS noting that Neil Court-Johnson, who is leading the project I believe, sold his 29261 ZTF shares on Friday (he only bought these on 12/12/23) There are, of course, several possible reasons for the sale but seems a little odd,
The SP moved up 7.4% yesterday so maybe he’s bought them back again. Who knows?
(I hold)
Zotefoams (LON:ZTF)
Further down the form it says Acquisition...so a bit unclear what has happened.
Nature of the transaction: Acquisition of ordinary shares
following Person Discharging Managerial Responsibilities (PDMR) disposed of a number of ordinary shares
Edit, replacement RNS:
The following amendment has been made to the 'Notification of Transactions of Directors/PDMRs' announcement released on 25 March 2024 at 17:58 under RNS No 2285I.
The dealing notification form incorrectly referred to an acquisition of shares. It should have referred to a disposal of shares.
Zotefoams (LON:ZTF) Hi laurie, yes, a bit confusing but I believe there was a sale of 29261 shares at 17:15 on Friday. (With it being the exact same number of shares purchased in December it would be odd for him to buy the exact same quantity again) Maybe it was somehow deemed as an unsafe purchase in the first place. Speculation of course.
Correction now published, it’s a disposal.
How bizarre. And Zotefoams (LON:ZTF) had to also issue a correction when he bought back in December - you'd have thought they might have put an extra review step in. Not a great look to sell so soon. At least he's declaring his trading activity though.
Not in the tables just produced in SCVR, but as Paul Hill stated in earlier comment, Paul and Graham have a very busy day and surely won't be able to cover everything.
Full year results in for Jarvis Securities (LON:JIM) (YE 31.12.2023)
eps 8.9p, SP 68.5p, trailing PE of 7.7
PBT 5.2M, market cap £30.64
Last quarterly dividend was 1.75p, which if maintained for next three quarters would be 10.2pc dividend for 2024.
Skilled person review is ongoing.......
https://www.londonstockexchang...
Is the lack of conclusion on the skilled person review the reason Jarvis Securities (LON:JIM) shares are massively down do you think? I don't hold but am watching from the sidelines
I'm massively reassured by the fact that there have been no published sales by directors or major holders since the process started. In fact a non-exec purchased over £27000 worth at £1.38p or thereabouts. There are plenty of nervous posters and those who would like to hold at a lower price making all sorts of claims but if I recall the company aren't allowed to discuss the process. So a buying opportunity if you have a stomach for risk. I hold.
A skilled person review is usually performed when a regulator is concerned by the performance or controls in a particular function - the regulator then stipulates that a “skilled person” is appointed to manage that function, do an in depth review and usually fix the controls and get it functioning to the required standard. The latter can take quite a long time particularly if you need to improve IT, hire appropriately skilled staff and train them etc.
So it is usually limited to a certain function of the regulated entity and can go on for a good while.
I have no professional knowledge of this area, but I trust and appreciate your comments David that it can go on for a good while. Jarvis announced in September 2022 that they needed the skilled person. In July 2023, Jarvis Securities (LON:JIM) announced should be concluded in Q4 2023. Today's announcement indicates it's going to carry on for a good while longer:
"We continue to progress through the skilled person review. We were expecting the skilled person to have provided their draft report for Phase 1c by 28 February 2024. This has been delayed, with the draft report now expected by the end of April 2024. During Q2, we expect the skilled person to start its phase 2 review and assurance report on the remediation work we have undertaken to date".
This text reminds me of one of the many scenes between Sir Humphrey Appleby and the Right Honourable Jim Hacker, where Humpy tries to drag out all reviews for the maximum possible time.
My morning smallcap tweet: An accident not waiting to happen
Revolution Bars (LON:RBG) Trufin (LON:TRU) Kromek (LON:KMK) Zoo Digital (LON:ZOO) Cohort (LON:CHRT) Journeo (LON:JNEO) £BATM CML Microsystems (LON:CML) Titon Holdings (LON:TON) Cizzle Biotechnology Holdings (LON:CIZ) Time Finance (LON:TIME) Tharisa (LON:THS) Michelmersh Brick Holdings (LON:MBH), Wynnstay (LON:WYN), Kooth (LON:KOO), Portmeirion (LON:PMP)
◄Revolution Bars (RBG)► turnaround failing. Responds to Sky news report - co "exploring all the strategic options available". Fundraise talks. Trading in line. [SP=2.86 Cap=7m]
◄TruFin (TRU)► contract signed for sale of IP and assets relating to Playstack's augmented reality and gamification AdTech platform. Price $300k + $1.7m in VCIG shares. [SP=70 Cap=74m]
◄Kromek (KMK)► gets $2.1m security screening order. Delivery starts in FY24 and completes H1 FY25. [SP=5.6 Cap=36m]
◄ZOO Digital (ZOO)► feeding hungry shareholders' mouths with good news. Will beat FY24 mkt exp with rev $40m+ and a smaller EBITDA loss. Rev F/C $37.6m. Cites "further clarity on timing of projects and is now receiving orders relating to work on feature films and TV shows that have been completed following the industry strikes". [SP=24 Cap=24m]
◄Cohort (CHRT)► wins £135m ten year Royal Navy countermeasures contract. [SP=590 Cap=245m]
◄Journeo (JNEO)► FY-Dec. Also wins £1.1m of orders to supply and install safety systems on London Arriva buses. [SP=282 Cap=46m]. I hold.
◄BATM Advanced Communications (BATM)► wins $2.3m cyber security orders. Delivery to commence immediately. [SP=NA Cap=NA]
◄CML Microsystems (CML)► guides FY-Mar rev only broadly in line at 'close to' £23m. EBITDA c. £6.4m, marginally below expectations. Blames weak core biz sales, will last into this FY. [SP=370.6 Cap=60m]. I hold.
◄Titon (TON)► AGM stmt mixed. Weak UK and Europe Q1 rev continued into Q2. Profit hit mitigated by overhead cuts and by pursuing margin enhancing opportunities. Korea loss will be greater than expected for the remainder of FY24. [SP=75 Cap=8m]
◄Cizzle Biotechnology (CIZ)► £0.62m placing at 2p, a 22% discount, "primarily to enter the scale-up and manufacturing phase for the main components of the proposed commercial test for CIZ1B" ie to keep the lights on. [SP=2.55 Cap=9m]
◄Time Finance (TIME)► Q3. Guides FY at least in line with market expectations. [SP=39.57 Cap=37m]
◄Tharisa (THS)► $5m max buyback. [SP=55.5 Cap=4129m]
◄Michelmersh Brick (MBH)► FY-Dec rev up 13% (1.3% organic) and pretax £12.5m up 9%, ahead of mkt exp. Outlook good. [SP=102 Cap=96m]
In line: WYN, KOO, PMP
Cohort (LON:CHRT) "Major £135m contract award" - new research report: https://www.equitydevelopment....
Cohort announces that its subsidiary SEA (Systems Engineering and Assessment Ltd.) has been awarded a major contract by the UK’s Ministry of Defence to provide Electronic Warfare Counter Measures (Increment 1a) (EWCM 1a) to the Royal Navy with a total value of at least £135m. This includes provision and support of SEA’s Trainable Decoy Launcher System, Ancilia.
At the FY 24 interim results Cohort had commented on an overall “increased tempo” of order intake. The Group reported a closing order book of £354m: we note that this latest contract takes the closing order book above the £0.5bn mark at £513.6m.
We have raised our FY25 revenue outlook by 2.5% (£5.0m). Thereafter we estimate a contribution from the SEA EWCM contract of c.£15.0m annually. Our FY25 E (adj.) EBITDA estimate is raised by £2.0m, +10%, with an estimated subsequent incremental annual c.£5.0m contribution. Our FY25 EPS outlook is raised from 36.7p to 41.8p. Accordingly, and in the light of additional recent contract wins (e.g. the 19 March Chess Australian Navy contract) our Fair Value is raised to 725p.
Cohort (LON:CHRT) Contract win.
"Together with other recent order wins, the contract is expected to materially enhance the Group's earnings."
Wynnstay (LON:WYN) Agm statement.
"The spring months represent our busiest period and, at this point in time, the Board's expectations for the full year remain unchanged." No figures.
Kenmare Resources (LON:KMR) There is a webinar for private investors at 12.30pm today. Michael Carvill, Managing Director of Kenmare Resources and Jeremy Dibb, Director of Corporate Development and Investor Relations will present the FY23 results to 31st December which were announced on 20th March.
Register here
Best of luck today Paul & Graham. I suspect you might be very, very busy.
indeed I don't think I've ever seen quite so many trading updates, H1 results &/or prelims all land on 1 day!
Exhausting just to read them - never mind analyse & comment sensibly on the figures/commentary.
I know, I'm tearing my hair out here!!! We'll do our best.