Small Cap Value Report (Tue 27 Aug 2024) - IGP, PLUS, FLO, BELL

Good morning from Paul & Graham, suitably refreshed from the long weekend!
Summary spreadsheet - for those of you who find this useful, I've got it up-to-date and there's a new link in the explanatory notes below, flagged as being the live version (which you might want to bookmark if you use it regularly). The idea is you can quickly look up any share we've covered here, using CTRL+F and the ticker.
I'm delighted to say we have already achieved our goal of covering more shares than in 2023. So far the tally is 610 unique companies in 2024! Some are only quick comments of course, but even so, that's a good proportion of the whole market that we're reviewing at least once in 2024 to date. I hope some of you find it useful anyway.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 26/8/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Very quiet for news again today, so looks like many CEO/CFOs have taken the week off!
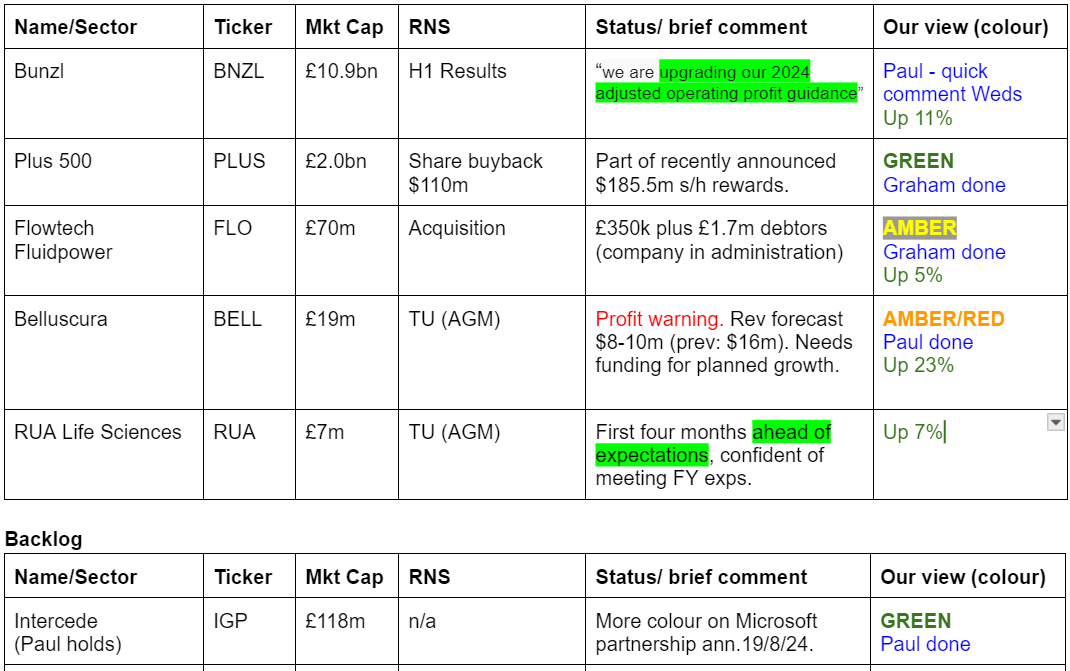
Summaries
Intercede (LON:IGP) (Paul holds) - 201p (£118m) - More colour on Microsoft partnership - Paul - GREEN
I try to better explain the Microsoft partnership deal announced on 19/8/2024.
Flowtech Fluidpower (LON:FLO) - up 6% to 118p (£75m) - Acquisition - Graham - AMBER
This looks to be a great bit of business by Flowtech as they acquire a small pneumatics company out of administration for a very cheap price (£350k for the business, and also separately buying its receivables). The skilled workforce are welcomed into the Flowtech group who will now seek to restore it to profitability in its first full year of ownership. Flowtech as a whole remains on the road to recovery and I can’t budge from a neutral stance just yet.
Belluscura (LON:BELL)
Up 50% to 16.5p (£28m) - AGM Trading Update [profit warning] - Paul - BLACK/ On fundamentals: AMBER/RED
Today's update tells us revenues are accelerating, but then considerably slashes the FY 12/2024 forecast. It's clearly desperate for more funding for both ongoing losses, and the necessary inventory build for higher sales, but tries to gloss over that reality. Punters might get lucky here, but for me the risks are still way too high. We can look at it fresh once the badly needed fundraising (more dilution with CLN's?) has been done. Bizarre to see a blue sky share rise 50% on a profit warning, but that's what has just happened.
Paul’s Section:
Intercede (LON:IGP) (Paul holds)
201p (£118m) - More colour on Microsoft partnership- Paul - GREEN
IGP issued an RNS last Monday 19/8/2024 re a partnership with Microsoft, which I reviewed here, concluding -
"Today's partnership with Microsoft sounds impressive, but doesn't alter the broker forecasts. Hence at this stage I don't know what the financial significance or structure of this deal is likely to be. I've reached out to the company asking for more colour, so at this stage all we can do is discuss amongst ourselves in the comments below - sector experts please help guide us!" [SCVR 19/8/2024]
Please bear in mind that I’m definitely not a tech analyst, so I don’t understand the technical details. However, this is the gist of things as I understand it -
Microsoft Entra ID is widely used for access to computer systems, including some existing IGP clients.
IGP’s existing PKI-based (high security) credential management system works with Entra already, but FIDO passkeys don’t.
Strong customer demand has led Microsoft to work with a small number of companies (including IGP) to make FIDO2 work with Entra ID.
Intercede’s MyID product suite will therefore be able to pass data between the two platforms.
Existing clients, and pipeline prospects are keen to use this new functionality apparently, in some sectors (esp Govt) driven by regulation.
There was a short comment from Cavendish on 19/8/2024, which I hope they don’t mind me mentioning here -
“Intercede (IGP): CORP Microsoft partnership Intercede has announced a strategic partnership with Microsoft, bringing FIDO passkey management to the enterprise. The and access management system, to allow administrators to create and register FIDO passkeys on devices. Importantly, this enables enterprise compliance with government security legislation (FIPS 201/SP 800-63). Full availability of the provisioning API will be available in the next release of MyID CMS, v12.12, in the next two weeks. While there are no changes to forecasts, the partnership reiterates the world-class quality and reach of Intercede’s technology. We place our target price under review.”
Paul’s view - this sounds encouraging, and I imagine would strengthen IGP’s position with its existing, and new clients. It's not clear yet what financial effect this will have.
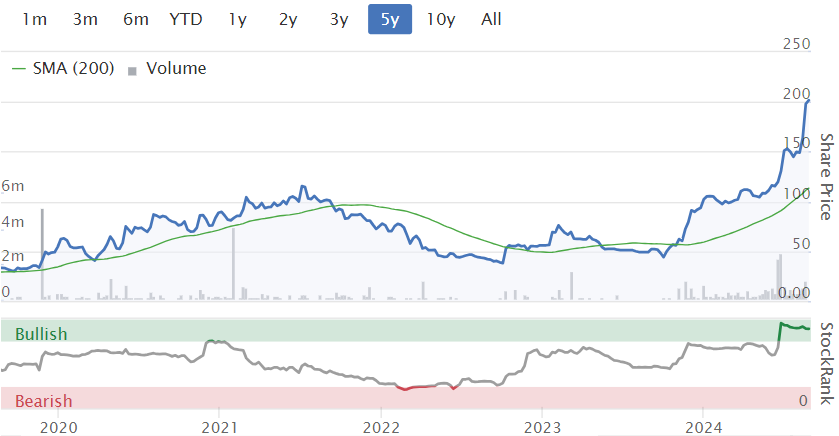
Belluscura (LON:BELL)
Up 50% to 16.5p (£28m) - AGM Trading Update - Paul - AMBER/RED
Belluscura plc (AIM: BELL), a leading medical device developer focused on lightweight and portable oxygen enrichment technology…
I’ve got to take a look at this, as a 50% share price rise after a profit warning signals there’s something else going on maybe?
BELL is a jam tomorrow share, with historical heavy losses and negligible revenues. The story is that demand is now taking off for its special machines, which it claims are lightweight & more effective by weight where portability matters.
Sales in June 2024: $521k
Sales in July 2024: $708k (both are record highs)
“Expects strong sales to continue…”
Upcoming release of new patented DISCOV-R device.
Paul - note the July record sales only annualises to £6.4m, does that qualify as “strong sales”?
Reduced sales & EBITDA guidance - this is a significant profit warning -
“The Board anticipates that revenue for FY24 will be approximately $8 to $10 million (2023: $825,409) depending on timing of the full commercial launch of the DISCOV-R. and that the Company will be EBITDA positive for Q1 FY25. The Company expects annualised run rate revenue of $14 million to $16 million by the end of year.”
Liquidity - this is almost comical. It gives us no facts or figures at all, but implies it needs to raise more cash -
“As reported in the 2023 Annual Report to support expansion plans for future development the Group regularly reviews its financing arrangements and cash flows to ensure there is sufficient funding in place for working capital…
the Company is currently evaluating debt and credit facilities and other options to meet the preliminary high customer demand for the DISCOV-R™.”
Outlook - again, vague -
“Whilst it has taken time to bring both products to market, and we are grateful for the patience of our shareholders, we now have two leading lightweight portable oxygen enrichment concentrators that meet the stringent requirements of the FDA and we look forward to the full commercial launch of DISCOV-R™ later in the year.
The Board looks forward to the remainder of 2024 and into 2025 with a real sense of confidence”
Broker update - Dowgate kindly updates us via Research Tree. It is indeed a profit warning, with a substantial cut in forecast revenues for FY 12/2024 from $16m, to only $9m.
The EBITDA loss for 2024 was expected to be $1.5m, now a lot worse at c.$4.5m.
Dowgate confirms that BELL needs to raise fresh funding (“ramp-up continues to be restrained by the company’s limited financing”). I’d be surprised if it can meet its needs using debt alone, so another equity placing looks inevitable, on unknown terms of course, that’s the big risk here.
Paul’s opinion - I’m only looking at the numbers. It’s up to you to do the deeper research, and form a view on the potential for the products, which I have no view on.
As things stand now, BELL is clearly financially distressed, and badly needs more cash - probably from a mixture of debt and equity. Note that it has been raising scraps of cash along the way with convertible loans, so make sure you factor in that dilution if those loans are converted into equity. My guess would be more dilution from further convertible loan issues in the next few months. And/or an equity placing if they can find anyone to put the cash in. It’s obvious BELL is desperate for more cash, which it needs to fund losses, and to finance the hefty inventories and receivables that would be required to ramp up production & sales.
Take all that into account, and the current £28m market cap with 168m shares in issue is likely to change a lot when all the dilution coming is taken into account.
Good luck with it, but I’m sticking at AMBER/RED to flag the current situation, which looks high risk. Things will of course change in future.
I’ll happily move up to amber (or higher) in future, but only once it’s properly refinanced, and there’s a clearer path to profitability.
Today is a nasty profit warning too - it’s missed 2024 targets by a mile, and guidance is greatly reduced. Plus it doesn’t have the cash needed to ramp up production. So why on earth would anyone be buying the shares today? That strikes me as suspicious - share price manipulation perhaps? I'll be surprised if today's bounce in share price sticks. Bizarre, but there we go, maybe investors had already dismissed the previous forecasts, and are pleased to see revenues growing? Occasionally, punts like this do work, but it’s very rare. Rising revenues is a good sign though, even if it's well behind plan, assuming of course that sales invoices turn into cash.
Graham’s Short Sections:
Plus500 (LON:PLUS)
£26.40 (£2.0bn / US$2.6bn) - Share Buyback - Graham - GREEN
We already covered the interim results from Plus500 earlier this month.
Today we learn that the announced $110m share buyback is starting today. There will also be dividends of $75.5m, for total shareholder rewards of $185.5m.
Plus500 takes the opportunity to underscore its investment case for us once again:
This larger Share Buyback Programme, which follows on from the $100.0m buyback programme announced in February 2024 and completed in August 2024, highlights the Board's continued confidence in the future prospects of Plus500. It also reflects the Group's robust financial position, cash generative business model and ongoing ability to deliver strong shareholder returns over the medium-term. This confidence is supported by the significant operational and financial momentum Plus500 has achieved in recent years, including during H1 2024, as reflected in the H1 2024 Interim Results.
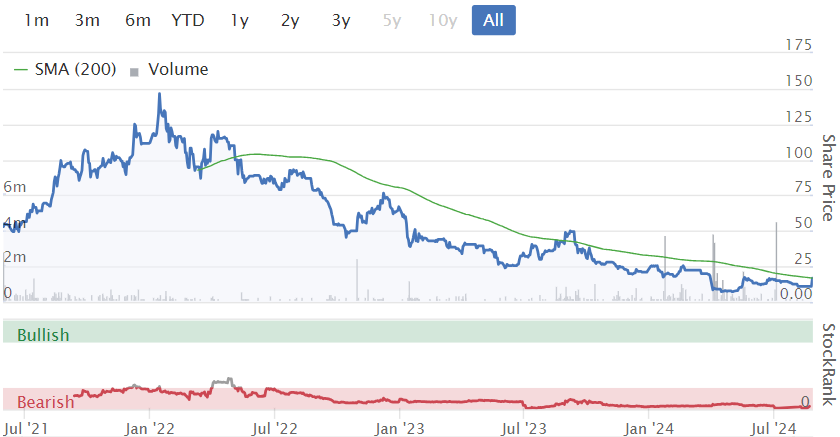
Graham’s view - a truly remarkable amount of cash has been returned to shareholders by Plus. This year we are heading for $210m of buybacks alone, and I think it’s right that the share price has responded to this:
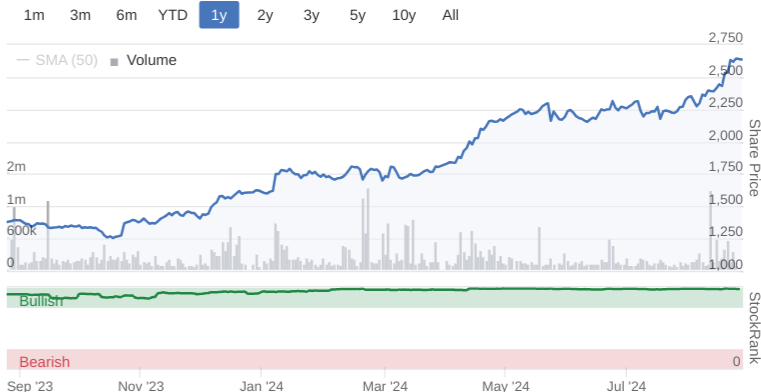
At the current share price, the PER is still only 10x and that’s making no adjustment for over $1 billion of the company’s own funds. At this level, I think it makes perfect sense to keep reducing the share count.
The remaining funds will still leave plenty of flexibility for growth, and the company is contemplating “inorganic growth initiatives”, something it has very rarely dabbled in before (I think the last one was a strategic $30m acquisition in 2021, when it bought a US-based futures trading platform). So watch out for M&A to complement organic growth moving forward.
Now enjoying unprecedented diversification across products and geographies, I have little choice but to keep my positive stance on PLUS. I still prefer the risk management approaches of the more traditional platforms, such as IG group (LON:IGG) (where I’m a shareholder) and CMC Markets (LON:CMCX), but I respect what PLUS is achieving for its shareholders.
Flowtech Fluidpower (LON:FLO)
Up 6% to 118p (£75m) - Acquisition - Graham - AMBER
This sounds like a nice bit of business - a small acquisition, keenly priced.
The acquired business: appears highly complementary to Flowtech. “Thorite is a leading UK provider of pneumatics, compressed air, vacuum and fluid handling products and systems and has traded since 1850. It operates from seven sales and service centres across the UK.” I always sit up and take notice when a business has been trading since the 19th century!
FY March 2023 figures: Thorite generated £21m of revenues, with negligible operating profit.
In the prior year, according to the accounts at Companies House, Thorite generated £350k of operating profits despite revenues being lower.
But in FY March 2023, the company struggled to maintain profits, with the directors referring to post-Covid supply chain issues, extra staff costs “due to planned growth that didn’t fully materialise”, depreciation and higher IT costs as the company moved to an expensive new ERP system. As of the FY March 2023 report, this expensive system had yet to be implemented, “and a lot of staff time is being spent on the project”.
Ominously, they also noted that “price escalation due to supply chain shortages make customer relations more challenging”.
Fortunes must not have improved, as the company has ended up in the hands of administrators.
All of which brings us to:
The price: Flowtech are paying just £350k for “all the plant and machinery, vehicles, stocks, and intangible assets”. This seems like an incredible price for a company that generated revenues of £20m+ and an operating profit of £350k only a few years ago.
Working capital: Flowtech are also paying off Thorite’s debtor financing facility (for £1.7m) and in return, they get ownership of the unpaid bills from Thorite’s customers (£2.6m). Any profits on this deal will be shared with the administrator.
Can Thorite be returned to profitability? Flowtech thinks so:
Through a combination of the strategic benefits and synergies already identified, the Board expects profitability to be restored in the first full year of ownership with the associated benefits to Group earnings.
Graham’s view
This strikes me as a perfect example of the benefits of buying companies out of administration: you get great pricing. In the context of listed companies doing deals, I rarely see a purchase out of administration that ends up causing much damage to the buyer - even if the business fails again a few years later or needs to be shut down, the upfront price was usually so low that it doesn’t matter.
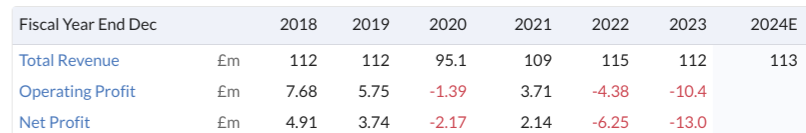
Flowtech’s entire existing revenues are £113m, so this very cheap acquisition is going to make a material difference to its top line. As for the more important bottom line, it’s too soon to tell but what a wonderful price to pay for the possibility that Thorite’s fortunes might improve. As part of a large group of similar businesses who face similar challenges, I would have to think that its prospects are decent. Flowtech as a whole remains on the road to recovery:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
Intercede (LON:IGP) - "Microsoft Entra ID" - This is basically active directory security renamed Microsoft Entra ID in the cloud.
Companies use Active directory on site and manage themselves but when they move to the cloud they are forced to use Microsoft Entra ID.
Moving to the cloud is more expensive. So although this is good news its only dependent on firms that use the cloud. I think a lot of firms get dragged into the expensive cloud migrations as a Fear of missing out. You can scale up and down servers when you want, rather than upgrading servers and infrastructure cose.
It depends on the organisation. Big firms like netfix it makes sense but smaller firms its more expensive. It could take 10 years for the majority of firms to move fully into the cloud and use Microsoft Entra ID.
Intercede (LON:IGP) How can you split out the true value of these bitty renewals or sales?
"Partners" resell on behalf of Intercede, whats their cut? Be great in the accounts if there was some lvalue to show the skimmed off amount. Different partners,different discounts
Selling software is so difficult to value
The amounts are the net amount to Intercede (LON:IGP) .
Hello Paul
Just a brief note to say that I listened to your podcast today for the first time and thoroughly enjoyed it.
It made a one hour car journey feel like only a few minutes !
Very easy to understand and follow, good humoured and informative - not only about the companies you cover but also your views on the macro economic situation.
I will now become a regular listener
Thanks again
Thanks Lochinver, nice feedback, I appreciate it :-)
There is an interesting article from Sunday on the problems (and Olympic marketing success) for Nike on Sky News headlined "Has the Nike trainer bubble burst?" https://news.sky.com/story/has...
Seems relevant for Zotefoams (LON:ZTF) whose Nike contract makes up around a third of revenues and (I would guess) a much higher percent of profit. (No position in either stock).
Worth noting only about 1% of Nike (NYQ:NKE) shoes utilise the Zotefoams (LON:ZTF) tech. The highest end running shoes only. So unlikely to be effected in the same way as more generic nike trainers.
Ben
Thanks and that is a very good point.
It is worth pointing out that the Sky News article does in particular mention that Nike has struggled in performance running shoes (a market it has long dominated) and mentions competition from HOKA's thick foam soles and ON's "cushioning system technology" which the article says "has proved popular with casuals and professionals alike". I don't know anything in detail about these shoes (whether they are competition to Zotefoams (LON:ZTF) 's technology that goes into the 1% of Nike performance shoes) but from the article they sound like high performance shoes.
https://www.on.com/en-gb/explo...
BNZL 3470p + 8% Since no-one else has mentioned it, I thought I might as well.
Obviously the mkt liked the H1 report. "British business supplies distributor Bunzl BNZL.L
raised its annual adjusted operating profit forecast on Tuesday, as it
benefits from acquisitions and demand for its own brand stays strong." https://www.stockopedia.com/sh...
Revenues were down 0.4% on constant exchange rate, statutory operating profits down 2.8%, and PBT down 11.9%.
I've held shares since Dec 2021 at 2945p. It's been a volatile share, going up and down and nowhere, although it has know shown something of a performance for me.
I was attracted by the quality and growth of the company. Revenues had been growing at 5.4% pa over the last 5 years, and net profits by 10% pa. Stocko gives it a Q score of 88, suggesting good quality. It has an average ROCE of 14.3% and a ROE of 20.6%. This is high. Interest cover is 8, which is reassuring.
Fwd PE is 16.4, which is obviously not cheap, but I think it acceptable for what I perceive as a good quality company. P/FCF is 12.9, which is pretty good. I'd consider paying up to 20, for example.
So yeah, onwards and upwards. Fingers crossed.
(Bonus content and minor plug: you can check out my thoughts on the Macfarlane (LON:MACF) earlier today . tl;dr : I think it will benefit from its increasing scale, its disciplined acquisition strategy and it is on an attractive valuation).
Bunzl appear to be the absolute masters at making bolt on acquisitions - they make dozens and dozens of them and have been doing it for years . From my experience as an FD in similar businesses, that is really not an easy art to get right. So well done to them. They should publish a book on how they successfully do it !
And I can see why you see parallels with Macfarlane. Personally I’m not totally convinced by them. I know historically they have done well, but no growth forecast from 2022 to 2025. Great to see them improve margin mix through clever acquisition but it would be great to see some organic growth as well
Jet2 (LON:JET2)
The shares appear to have gained some friends today; up 4.6% on reasonably good volume for the summer 'doldrums'. Any reason why or is it just the market being its usual whimsical self?
Perhaps its all those millionaires leaving and booking economy class to save a few bob, as opposed to BA first or business class.
easyJet (LON:EZJ) Up 6.6% today too, good day for tour operators
Best places to move to ?
Given the state of the nation and my dislike of all things Keir Starmer and the nonsensical snowflake times we live in not sure how much more of this I can take.
Whilst I have a naughty headmistress style liking for Andrea Rayner .
Anyway what other places in the world would we consider relocating to ?
Top of ny list is Java / Sumba which I really have fallen in love with and not a snowflake, or someone telling you what you cant say .
The UK is becoming the Royston Vasey for budinesses and entrroeneurs “we dont want your sort round hete”
Sorry loads of typos as usual
I’ve looked at New Zealand but you need to have loads of money and be at least 66 next was Italy which is much more doable but you would need to speak the language some of my family have Irish connections which looks the easiest if you are leaving the sinking ship
@ sjones33449, you may want to look at the Irish tax system. Graham can advise better than I, but I believe they tax dividends at 52% and there is zero allowance for them. So, if you have, say, £10k in dividend income, the Irish tax authorities take £5,200 of it.
The top rate of tax, 40%, also kicks in at 42k Euro, circa £35k.
Hi planetx, where in Java would you consider?
Flowtech Fluidpower (LON:FLO)
Graham thank for your analysis of the acquisition of Thorite. At the risk of making you blush, your narrative echoes my views, but I do have a reasonable holding, so room for confirmation bias however hard one tries to avoid it!
Anyway we shall see. If Flowtech Fluidpower (LON:FLO) continues to trade in line with market expectations I would anticipate the share price nudging gently upwards, but that of course is a little crystal ball gazing.
Larger housebuilders have pulled back by up to 6% today - Barratt Developments (LON:BDEV)
This follows fires in two East London residential blocks at the weekend, which have brought cladding retrofit delays back in focus for the media and politicians
Capital
More smart money going there
Scott L. Barbee
Aegis financial. Just took 5%
Contrarian value investor .
Nice tight spread on capital at the moment
Seems to be bouncing between 85 and 87 think its goong to head up soon
Looking at the US dollar basket (the US dollar against a basket of currency's) it's back where it was in April 2022. So maybe a weak dollar.
The resale value of 2nd hand luxury watches have dropped over the past 9 quarters (see below).
In turn, impacting prices of new time pieces (eg Watches of Switzerland (LON:WOSG) , alongside providing a headwind to UK pawnbrokers (eg H & T (LON:HAT) & Ramsdens Holdings (LON:RFX) who sell such jewellery in their stores.
I’m surprised this has impacted on H&T as much as you suggest. I doubt whether they sell many Patek’s or any other luxury watches, which are the only ones really affected by the fall in values at this luxury end of the market. On the other hand, I am surprised they have not benefitted from gold hitting an all time high, which does affect them and should have given their share price a lift.
H & T (LON:HAT) were impacted a few quarters ago. They said they had reduced stock levels due to volatility in the second hand watch market. Last report imported that second watch values now improving though.
Hi Paul,
I am more sanguine about Ramsdens Holdings (LON:RFX) due to its diverse revenue streams, split roughly 25% from each of FX, jewellery including high end watches, pawn broking and gold buying/selling. The latter is currently very strong and at the recent update was supported by good trading in pawn broking and second hand jewellery with FX broadly in line.
Like many UK small caps the shares are cheap trading at around a PE of 8.5 and yield of 5% or thereabouts with cash on the balance sheet. I have a reasonable holding.
As far as H & T (LON:HAT) is concerned the shares are a little cheaper than Ramsdens, but carry a reasonable amount of debt. Furthermore the recent trading update was somewhat disingenuous leaving one needing to read the broker update to fully realise that it was a profit warning. For me the integrity of management is non negotiable so the company is uninvestable as far as I am concerned.
Being predominantly a value style investor Watches of Switzerland (LON:WOSG) has never really appealed, although I appreciate that some investors more astute than me have very successfully invested in the shares. As always there are many ways to make or lose money in the stock market.
All the best
So it's time to buy a watch
Especially if you have time on your hands…
I read recently that easyJet (LON:EZJ) was due to be demoted from the FTSE 100 due to it's recent share price slump. Paradoxically, the share price has risen since I've read the article.
Does anyone know what the cut-off date and the market cap is for the final determination?
Thank you in advance.
First Friday September. No Market cap limit- largest 100.
Filtronic (LON:FTC) ticking up nicely.
Some interesting tweets; they’ve indicated they have got a big announcement coming up - significant expansion of their R&D and production facilities at NETPark as they look to expand their capacity for secured 2025/26 orders. It’s likely they will take several tens of thousands sq ft of new bespoke premises developed by Kier group.
More interestingly, NETPark have secured a big blue-chip global defence and aerospace giant, who are keen to HQ in a space-oriented environment, for occupancy of a new 140,000 sq ft facility (development to start at the beginning on New Year 2025) - none other than Lockheed Martin.
So Lockheed Martin and Filtronic next door to each other…does not take an awful lot of guesswork to work out where FTC shares are heading...
I hold and whilst I'm not a chartist, I looked at the chart of Filtronic (LON:FTC) and it looked like it was going to break out, tight trading and I think it might be testing highs soon. I did not know about Lockeed Martin - my hope has always been that Filtronic (LON:FTC) become the major supplier for comms in space, both short and long distance, apdapting exisiting technologies and not just end up being eaten up by Starlink/SpaceX - I hope they have long lunches together!
Filtronic
Doesnt half bounce around .
My biggest holding by some distance now .
Has tested 80p once before briefly only to shit its pants (is that a market term) down to 60p a few weeks later in the market armageddon that came and went in 24 hours .
Cant see it breaking 80p yet and reckon its going to need both a while longer and a bit of bull market bravado or a big bit of news .
Trifast
Share incentive plan announced .
Options based on market price which is good .
However really flawed as trigger point is solely share price and not any other performance criteria .
You might argue thats the only thing that matters however management cant actually control share price whereas they are responsible for ACTUAL business milestones such as
- cash
- stock turn
- profit
Id much prefer to see actual business performance hurdles not just share price hurdles .
The share price triggers set are far too low .
Think hatwood and Rockwood are giving their management team (and cronies) a bit of a tap in at the expense of shareholders .. Thats a bit poor really and im a huge Rockwood fan but thats a little bit naughty .
I share your thoughts on Trifast (LON:TRI) newly announced Directors incentive plan.
I would have expected criteria to at least require that the share price is above a given threshold for a period of time (say 30 days) in order it qualifies as being met.
I agree that the thresholds lack ambition.
I do note that an LTIP announced last year had more stretching goals with a significant uplift in operating margin required to pay-out fully in late 2026.
It seems management should have all the incentive they should need now to deliver very recent results!
What's the community view on the strength of Sterling? £=$1.32 now. Does that indicate confidence in the UK economy or weakness in the US? tia
Its great news as I had to buy 140,000 USD this morning .
Not sure, but I've been buying US stocks in the last fortnight to take advantage of the stronger £.
Which US stocks? Thx
I'm looking long term here, at least 5 years. I have invested in the small drop recently 3 weeks or so ago and picked up some NVIDIA (NSQ:NVDA) for obvious reasons and also some Advanced Micro Devices (NSQ:AMD) for the same. I've always wanted some Berkshire Hathaway (NYQ:BRK.B) so I see this as a good exposure to the US, an 'EFT plus' if you like. Rocket Lab USA (NAQ:RKLB) is also something that could be a very big player on the space scene as they have a massive backlog, apart from SpaceX have no real competitors in the delivery of smaller payloads into space and will be sending bigger payloads soon which will see a real boost to already great profits. These are staying in the kids ISAs and provides some US exposure which as a family were lacking and I don't plan to trade them at all (usual caveats apply). I did pick up some Ford Motor Co (NYQ:F) as a trade - just looked too cheap, always seems to though and might get sold soon for a 20% short term gain.
Surely you're getting less for your money with a stronger £?
Sorry, I'm full of cold or covid and am on holiday mode (but back to work today), but unless I'm missing something if I invest £1000 when the fx is 1.2 I get $1200. If it's 1.3 I get $1300. At at static share price of $50, I will either be able to purchase 24 or 26 shares, so a stronger £ makes it better for me?
Funnily enough I did read an article a week or so before I bought here, as I thought I'd missed the boat some point in June. found the article
In any event, looking at my records I bought on August 6/7 when there was a day of market armageddon and Ford a few days later.
I have separately been buying currency on my Caxton card mainly Euro, dollar and 'other' holiday destination currencies.
Market is pricing in US interest rate cut. As per Bloomberg this morning USD will most likely weaken more
Time Finance (LON:TIME) , the AIM listed independent specialist finance provider, is pleased to announce that it has been approved as an accredited lending partner under the UK Government's Growth Guarantee Scheme ("GGS") which is administered by the British Business Bank and was launched on 1 July 2024. GGS is the successor scheme to the Recovery Loan Scheme ("RLS") and Coronavirus Business Interruption Scheme ("CBILS") of which the Group was also an accredited lender.
Growth Guarantee Scheme Accreditation
The British Business Bank has approved Time Vendor Finance Ltd and Time Hard Asset Finance Limited, wholly-owned subsidiaries of the Company, for accreditation as participating lenders under the scheme.
The GGS accreditation provides an additional channel for the Group to deliver support to the UK's smaller businesses, adding to the Group's current lending activities alongside Asset Finance, Loan Finance and Invoice Finance. The scheme accreditation provides the added benefit of a government-backed guarantee to loans provided by the Group, the scheme covers 70% of any outstanding balance, post a recovery process.
The Group intends to be an active lender for the duration of the Growth Guarantee Scheme.
[I hold]
Pimlico... Can you add some extra insight/comment on top of just copy+pasting the RNS?
I get you're excited about this RNS as a shareholder (so am I) but comments should be about adding value...
Mello will be hosting two physical events this Autumn and all Stockopedia subscribers are welcome and will meet hundreds of like minded investors. The tickets will be available on launch day this Thursday but any comments or requests are gratefully received on this thread Stockopedia | Mello 10th Anniversary with two special events... | By carmensfella
Love the podcasts Paul. To me you're front row box office - fab delivery.
Indeed I was listening to this weekend's in my car with my wife, whilst returning from holiday in Keswick, Lake District. And although Anne's not financially trained, she now also plans to listen to your stock roundups every week.
Ever thought of perhaps contacting Gary Lineker to see whether he'd like to add another show on smallcap investing to his "The Rest Is.." series. You'd be a natural alongside Ed.
Hope you were not camping!
Re. comments on Friday on the potential sale by Ocean Wilsons Holdings (LON:OCN) of Wilsons Holdings (in which they hold 57%) and this being a catalyst for a re-rating - the share price predictably shot up 14% on Friday as a result, which I missed the boat on, but it occurred to me that another, lower risk, way to play this could be via Hansa Investment (LON:HANA). This Investment trust sits at a discount to NAV of about 40% which will appeal to value lovers, and it stands as a somewhat unusual beast in the investment trust sector in holding between 25% to 30% of its entire assets in Ocean Wilsons. It could be a nice way in to this and sitting on such a hefty discount you could get a nice double whammy of the proceeds of any sale combined with a narrowing of the massive discount due to increased interest and publicity raised by the sale process.
Just throwing this out there as an idea...
BIACS
Perhaps Labour's mooted increase in capital gains tax is going to encourage investors to spread bet their long positions rather than hold them through normal stockbrokers. Particularly in the case of wealthier investors, who are unable to shield all of their portfolios in ISA's and SIPP, and are financially savvy enough to realise the benefits of saving a possible 45% capital gains charge (so perhaps more relevant for IG group (LON:IGG) than Plus500 (LON:PLUS) . On the other hand spreadbetting firms are a natural target for a Labour government, both from a anti-gambling protective standpoint and especially if they need to close this loophole for avoiding tax
Is there anything else they would like to shut down in the name of 'collecting tax' i.e. putting their hands in your pocket. They've come in using hackneyed terms of ' clearing up the mess' etc., but actually they are just undermining everything they said to get into Govt. At least Blair trod carefully in the early days recognising you need the power of capitalism to be on your side.
Sorry, couldn't help responding as I think a lot of people are being sucked into a day dream fantasy of who they are dealing with (and that's not saying the last lot did a great job either)..
Frankly, it doesn't matter what flavour of government, they all leave a bitter aftertaste and are majorly useless at running the economy. My taxes go to prop up incompetence and that's only getting worse.
It was pretty obvious to every single person in the country we were in a mess and something was going to have to give re tax and/or spend . Apart from Reeves and Starmer it seems. It'd be nice if just once they were honest with us before the election. They'd have still won but at least kept some integrity.
I've heard rumours about a lifetime isa limit as well. Anyone think that's likely?
Limit to contributions or the investment pot accumulated please ?
Many thanks indeed
In terms of Keir Starmer's gloomy message today, I've been looking at the numbers. Unfortunately, I think that the only thing that will close the so called "black hole" is cutting higher rate pension tax relief to a flat 30%. Higher rate tax relief currently costs nearly c£30bn per year and total pension relief nearly £50bn. They may also bring back the lifetime limit. I can see them also moving CGT for higher earners to 30% as well. This would align investment tax relief with VCTs all at 30%. I think this was probably their plan all along and is probably not deemed totally unreasonable. It might even give them some leeway for additional ISAs etc. to offset.
Lifting corporation tax above 25% would be suicidal for the UK as multi-nationals would just leave.
Inheritance tax may get changed as well but it has a fairly negligible impact, unless they really went in hard.
On CGT by the way, everyone seems to have forgotten that £100k of salary is not the same as a £100k capital gain (for example, if you purchased the asset 10 years ago). There is no indexation, so the capital gain is not real in an inflationary environment and you shouldn't be taxed at your highest marginal rate. Bringing back indexation relief is the fair thing to do for anything held over 2 years. Presumably this was the reason why capital gains had an annual exempt amount and were charged at a lower rate, but people seem to have forgotten. This never seems to get any press comment, but wealth managers need to start reminding politicians!
In the meantime, everyone has until 30 October to worry about where the "tax and spend" plans are going to hit them. Not great for the economy and consumer confidence, that's for sure!
Inheritance tax may get changed as well but it has a fairly negligible impact, unless they really went in hard.
Hi topvest
Agree with most of that. One area small cap investors may want to keep an eye on, however, is BPR relief for IHT on AIM qualifying shares. The relief was originally brought in (by Labour, in 1976) as a means to allow family controlled firms to be passed on without being broken up or sold off. Later the relief was extended to unquoted investments. Somewhere along the line AIM got included in that, as a way of encouraging investment in high risk investments.
Fast forward to today, though, and it's perfectly possible to create a low risk portfolio of very large AIM stocks to avoid IHT, and a whole wealth management business has sprung up to support it. Last year 64 estates used BPR on AIM stocks to pass on £800 million - whatever the original purpose was, that clearly wasn't what was intended and is certainly sufficient to keep the Treasury interested.
Quite what Reeves will do, however, is uncertain. Blocking the relief immediately and retrospectively is possible - there is past form for governments doing this where reliefs are being used to avoid taxation beyond their original purpose.
I've been reviewing my AIM holdings and quite a few count one or more of the BPR portfolio wealth managers among their major shareholders. In the event BPR on AIM stocks is blocked you can imagine a fire sale occurring - although many of these stocks look quite cheap anyway.
I can't say I'm inclined to sell in advance of this as a possibility, but I certainly intend to have some cash in hand in the event there is a localised AIM panic at the end of October.
One further thought is that a number of family controlled firms moved to AIM specifically to allow their family shareholders to pass on their shares to the next generation. Quite what those will do in the event the relief is removed is an interesting question - taking the companies private may be the only way they can protect that relief. The same might apply to founder controlled companies where the founders are of an age to consider inheritance matters.
As always, the rule is to not let the tax tail wag the investment dog, but it's one to keep in mind, I feel.
timarr
Sorry Tim should have looked further up the thread doh.
The really big hole is unfunded government final salary pension scheme growing exponentially, which is largely funded by taxpayers you have funded a large proportion of their own pensions. The sword needs to fall on high earning senior government posts (which grow by the day) who if they were in private sector would have to fund a much greater proportion of their own pensions. Any tax changes which impact investing for the future will impact the economic growth of the country and sends out the wrong message for inward investment.
Bravo - hit the nail on the head .
I'm not sure that a lot of public sector schemes are unfunded. I had a short stint in the Local Government and given that most people don't have jobs for life, then what you are seeing is that many people are working less in these schemes, say 5-8 years rather than doing a whole 40 years + and forward looking the actual costs come down. It was a few years ago though.
No easy answers Topvest I think over half the total pension tax relief goes to db schemes in relation to public sector which will upset their core voters if cut, also I'm pretty sure it will be a nightmare for payrolls using salary sacrifice to administer. Its one of those I think would already have been done if it was simple to implement but I agree with everything you say.
somewhat likely - yes
Pretty likely that if this is implemented it will be like the pensions LTA threshold (the recently abolished one :). Any amount over (say) 1,073,000 is taxable. Crucially (for some readers here) on the date the rule is added, if you had more, that amount would be protected.
As others have noted above, stuff like this will benefit the spreadbet cos.
There may be a v. marginal movement of capital (there are only 4k-5k isa millionaires) into other tax privileged investments like EIS/SEIS funds / primary residences / gold.
Both pensions and ISAs are equivalent: in a pension you pay tax when you take the pension and in an Isa you have paid tax on the money paid in. The trick is to make sure the marginal tax rate you pay is less than the marginal tax rate when you did not pay.
If I was the chancellor I would look for valuable things that cannot be moved abroad that are owned by people who do not live/vote here.
I am long regulation. No matter what govt is in power, things do not get simpler. Contracts do not get shorter. If anyone knows of a co that is a proxy for growing regulation, please tell me.
If anyone knows of a co that is a proxy for growing regulation, please tell me
RELX and Accenture would be my picks.
As Timmar said on here a while back you can only tax things that can't leave the country.
Would be worth hearing his view on possible tax future if he's lurking.
Land value tax...
In my humble opinion you should take more time to judge them.
Great post. Completely agree. I do a lot of work with a left wing social enterprise and they decry the “right wing” tendencies of the Labour government. If you’re upsetting both sides then you’re probably getting the balance about right.
You never know they might just be employing the modern capitalist idea of kitchen sinking. Is obviously useful to counter the ingrained idea that Labour always wrecks the economy, can then paint a better picture plus it's a reason to avoid big spending those further left would want. That's the positive view!
Good morning Paul.
Really enjoy your weekly podcasts, and value your company and sector insights. But it does frustrate me and dissapoint me that you are being so judgemental so quickly about the new government and senior ministers. Irrespective of our individual politics we need to recognise what they have inherited. Country and economy governance since 2016 have been rudderless and self-centred. The new lot don't have a magic wand, but its clear they have long-term plans and a strong work-ethic. Give them a chance.
In my humble opinion you should take more time to judge them.
Back to your day-job.....thanks for your bullishness on Intercede. I'm up 36% and counting.
Hi Andrew
I can see you're new to Stockopedia so just to give you a heads up, Stockopedia is not a platform for people to express their political inclinations, if it was then it would rapidly descend into a pit of chaos and disarray.
However Paul's personal podcast is a platform for him to discuss whatever he wants and you have a choice to either listen or not, disagree or not, that's entirely up to you and we are all super grateful to Paul for taking the time to do this excellent unpaid undertaking (which sounds like you are too).
But please no politics here, just useful stock information observations and ideas, thank you.
Point taken however politics ( Tax increases ) have a significant impact on investments which is what this forum is all about.
I can understand that Andrew would think this is the place to respond to Paul's personal podcasts. No one seems to object when this platform is used to thank him for them. (I really must take time to listen to them)
But Paul did say wait till the budget, which IS taking more time to judge them, particularly RR. Still no politics here I hope.
I think Cockney Rebel sums up neatly what the New Intake has and will cost the UK.
Flowtech Fluidpower
Possible nice acquisition looks cheap on paper
However acquisitions are tough and at best 50/50 it will all go to plan .
Arguably copper bottomed due to the assets acquired at big discount .
Be a good test of management .
Flowtech Fluidpower (LON:FLO)
On initial reading management appear to have acquired the Thomas Wright/Thorite Group Limited ("Thorite") for a very good price. Gross assets of £8.8m for £350,000
plus repayment of debt of £1.7m, just over £2m in total. There is also the potential for a share of any monies recovered by the administrators above £1.7m., presumably on a 50:50 basis.
So fair play to Mike England and his team for spotting the opportunity. They now as you say have to integrate well.
"BASIS OF THE TRANSACTION
Under the terms of the Acquisition, Flowtech will acquire all the plant and machinery, vehicles, stocks, and intangible assets of Thorite for a total cash consideration of £350,000 which will be funded from the Group's existing bank facilities.
Flowtech has also repaid Thorite's outstanding debtor finance facility of c.£1.7m in return for an assignment to the Group of a debtor book totalling c.£2.6m; this has also been funded from the Group's bank facilities. A sharing arrangement relating to the excess of debtor book recoveries over and above the c.£1.7m paid has been agreed with the Administrator of Thorite.
In the audited accounts for the year ended 31 March 2023, Thorite generated revenue of £21.2m and delivered an operating profit of £79,000. The gross value of asset classes being acquired at the same date was £8.8m, inclusive of £3.8m in respect of the debtor book at that point in time. Thorite has since experienced cash flow challenges and incurred operating losses due to a combination of internal issues and market headwinds. Thorite's operating losses in the year to 31 March 2024 are estimated at £1.2m.
Through a combination of the strategic benefits and synergies already identified, the Board expects profitability to be restored in the first full year of ownership with the associated benefits to Group earnings."
Jonno
Think
- theyve paid 350k
- theyve paid off 1.7m debts
BUT
- have acquired customers owing 2.6m
SO
- flowtech will get those monies in and goes to them
If they colkected all 2.6m
Then 50% of the difference (2.6 - 1.7) 0.9m ie 450 k payable to administrators
IF
This happens
Flowtech have actually
- paid 3.50 plus 1.7 ie 2.05m milion
And received 2.6 minus 450k ie 2.15 million
So they actually make 100k
Lovely short term bit of deal making , but warning these things do need a real determined and good management ,
Administrators will be happy as theyve saved the jobs
Flowtech have basically been paid 100k to take 20 million turnover and 8m assets .
Hi planetX
Whichever way one looks at it, it appears a very good piece of business provided of course Mike England and his team can integrate well. So far they appear to have progressed the turn around well, but early days. Time will tell.
As you may have guessed I hold and bought a fair few for my daughter's ISA at 80p.
Jonno
I held in the past
I dont really rate it though as they are “just” a middle man distributor destined to be working on 1.5 mark up and making 5-10% depending on wind direction .
I spent years being a distributor of other peoples brands and in reality you dont build anything of value .
The issue is that the CEO past present and future do not want to build a lasting business of long term value they only want to “oversee a turnaround” and then move on to their next career move
Flowtech really needs the mindset of an owner but in this case its harwood and their turnaround CEO / team trying to squeeze out the juice and get it flogged off .
They will succeed I think and youll double your money in 3 years .
Think im talking myself into it .
Damn .
Diaceutics (LON:DXRX), a company specialising in Precision Medicine, RNS today announces the launch of Enhanced rare-disease offering and a contract to support the commercialisation of a rare disease therapy (no value given).
This follows a significant contract win on 19th August for £4.3m to end 2025 and potential to extend.
I wrote a comment on 19th August in SVCR giving a quick overview of Diaceutics (LON:DXRX).
Some perceive the med tech sector as a bit of a black box and hard to understand so here is a link to an excellent podcast with the Chairman /Founder and 18% shareholder Peter Keeling. Please bear in mind it was published in March 2023 so it is not up to date. There have been lots of developments since then. The podcast mentions 180 labs (now around 1000). Daily Signal (the central product) which provides alerts to pharma and biotech of patients who would benefit from their drugs is able to provide data which is 3 or 4 days old (Signal is now daily).
Peter Keeling of Diaceutics - In the Company of Mavericks | Podcast on Spotify
I hold
My morning smallcap tweet: Old MacDonald had a pharm, EBITDA
Allergy Therapeutics (LON:AGY) Faron Pharmaceuticals Oy (LON:FARN) Rua Life Sciences (LON:RUA) Shield Therapeutics (LON:STX) Malvern International (LON:MLVN) Narf Industries (LON:NARF) Belluscura (LON:BELL) Cambria Africa (LON:CMB) Diaceutics (LON:DXRX) Time Finance (LON:TIME) St James's Place (LON:STJ)
◄Allergy Therapeutics (AGY)► instos agree to further £5m loan so co has enough cash to late Sept. Co continues to explore further funding options . [SP=4.69 Cap=222m]
◄Faron Pharmaceuticals (FARN)► FDA has granted Fast Track Designation for bexmarilimab for the treatment of relapsed or refractory myelodysplastic syndrome. [SP=173 Cap=181m]
◄RUA Life Sciences (RUA)► AGM stmt - first 4 months trading ahead of management expectations with rev c.£800k. Guides FY-Mar in line. [SP=10.9 Cap=7m]
◄Shield Therapeutics (STX)► Health Canada has approved ACCRUFeR for the treatment of adults with iron deficiency anemia. [SP=3.8 Cap=30m]
◄Malvern International (MLVN)► guides H1-June rev (ex comissions) up c.22% but profit flat due to investment in people, travel and marketing activities. [SP=17 Cap=5m]
◄Narf Industries (NARF)► wins $1.3m U.S. Air Force SaaS contract for AI powered social engineering threat intelligence solution. Blizzard of levaraged synergy blah follows. [SP=0.9 Cap=14m]
◄Belluscura (BELL)► AGM stmt - record sales in July of $708k. Guides FY24 rev $8-10m "depending on timing of the full commercial launch of the DISCOV-R". [SP=10.95 Cap=18m]
◄Cambria Africa (CMB)► intends to return 1c (c.0.77p) and delist. It remains suspended. [SP=0.21 Cap=1m]
◄Diaceutics (DXRX)► significant enhancement of lab network which has facilitated a new rare-disease contract win. [SP=129.19 Cap=109m]
◄Time Finance (TIME)► becomes an accredited lending partner under the UK Government's Growth Guarantee Scheme. [SP=52.9 Cap=49m]
◄St. James's Place (STJ)► £32.9m max buyback. [SP=720.5 Cap=3953m]
Good news for IP (LON:IPO) and Chrysalis Investments (LON:CHRY) holders over this weekend as Sky News report Visa are in talks to purchase fraud detection company Featurespace, which is 20% and 10% respectively. Chrysalis Investments (LON:CHRY) marked up their investment almost to the proposed £700m transaction price in June but the value of IP (LON:IPO) holding should almost double and significant cash windfalls for both, which both companies sitting at 50%+ discounts to NAV. I hold both.
IP (LON:IPO) and @ CHRY Should an RNS not appear soon about this?
Facilities by ADF (LON:ADF)
I would like to add a couple of footnotes to Paul’s excellent analysis on Friday of the major acquisition, institutional placing and retail offer by Facilities by ADF (I hold).
Paul quotes forecast eps numbers of 5.8p for calendar 2024 and 8.8p for 2025, which are Stocko’s figures. I have now had the chance to read Cavendish’s comprehensive 15 page note (thank you Research-Tree!) and I believe these Stocko figures are before adjusting for the benefit of the acquisition. The new forecasts for eps are 5.7p for 2024 and 9.7p for 2025. The 2024 figure vindicates Paul’s view that ADF would struggle to hit the original forecast given its first half performance, since the forecast eps is edged down despite including two months’ contribution from an earnings-accretive acquisition. Incidentally, the acquisition is expected to close on 10 September so the actual contribution should be nearer four months. So it does look as though the company and the broker have sneaked out an earnings downgrade for the pre-acquisition business under cover of the deal. But the good news is that expected earnings per share for 2025 are now 9.7p rather than 8.8p.
Paul’s note also asks who the Selling Shareholders are (in the ADF placing, not the vendors of the company being acquired) and why they are selling, given the apparently modest valuation. Andrew Dixon (the AD of ADF) founded ADF in 1992 and Stephen Haines joined a few years later; the other two are their wife and partner respectively. They had stepped back from running the business some years before the January 2022 IPO (current CEO appointed 2016) and only cashed in a modest amount at the IPO, allowing the bulk of the IPO proceeds to go to the company to fund growth (and, I suppose, also de-risk their investment to a degree). Now they are into their sixties and two and a half years on from the IPO, it doesn’t seem unreasonable that they would prefer not to have so much of their net worth tied up in a business they no longer run, particularly after the twin setbacks to the business in recent years of covid lockdowns and the Hollywood writers and actors strikes.
Paul also asks why the Autotrak vendors are selling and the Cavendish note indicates that this is a retirement sale. The two main vendors (husband and wife in their early sixties) will step back whilst the other two vendors (their son and a more recently appointed director-shareholder) will remain running the business.
Hi Paul, says we need to request access to the spreadsheet? All the other links the sheets open fine
It opens directly for me.
Yes looks like it's working fine now, thanks. (And thanks Paul, a useful resource!)
Apologies Scotty020 and others, I got the sharing settings wrong, quickly flagged by a deluge of emails from Google Sheets asking for access. So I fixed it promptly, and should all be working now. My mistake, sorry! P.