Small Cap Value Report (Tue 27 Sept 2022) - SAGA, BIFF, SUS, DBOX, SMV

Good morning from Paul & Graham.
Agenda -
Paul's Section:
Saga (LON:SAGA) (I hold) - rather lacklustre H1 figures. It's moved back into profit, but only £14m in H1, and full year guidance is reduced again, from £35-50m previously, to £20-30m now. Debt is high, as expected, but covenants & liquidity are fine, and the going concern note is positive. Overall, it's a bit flat, but what do you expect when the share price has dropped by about two thirds in the last year?! There's nothing of concern in the numbers, but it's not madly exciting either. I'm happy to continue holding (well, happy is probably overstating it!), as shares should recover in due course. More detail below.
Graham's Section:
Biffa (LON:BIFF) (£1,248m) (+28%) [no section below] - the offer for waste management company Biffa has finally been announced, having originally been notified back in early June. Unfortunately, the price is 8% lower than the original proposal: 410p (plus a 4.7p dividend), instead of 445p.. Only 14.4% of Biffa shares have been pledged to vote in favour of the deal, so there is no guarantee that it will go ahead, although the latest share price of 408p suggests there is confidence that it will happen.
The reason given for the lower offer price is the “weakening economic environment”, and I think Biffa shareholders can feel disgruntled on two counts. Firstly, the most recent results - FY March 2022 - saw record revenues, helped by a post-Covid recovery with seemingly good momentum (adjusted operating profits £97m), although of course the last six months have been difficult. Secondly, the pound has depreciated against the dollar by 14% since early June, when the possible deal with this United States-based investor was first revealed. In dollar terms, this offer is much cheaper than the original June proposal (roughly $4.43 per share instead of $5.56 per share). But it looks like Biffa’s shareholders are happy to offload it and aren’t overly fussy about the exact price of the deal. (no section below)
S&U (LON:SUS) (£254m) - strong interim results from this motor lender and property bridging lender, with a long history of management and ownership by the Coombs family. Growth in property bridging continues at a terrific pace, while collections in non-prime motor lending are surprisingly positive. While I’m as nervous about the economic situation as anybody else, I don’t think the market is giving this company enough credit for its superb track record, modest leverage compared to many other lenders, and high loan loss provisioning. I believe that S&U is undervalued.
Digitalbox (LON:DBOX) (£11m) (+5%) [no section below] - Digitalbox owns a collection of websites - Entertainment Daily, The Daily Mash and The Tab, and should soon own TVguide.co.uk (acquisition set to complete during H2). The outlook here is broadly in line with expectations, and so the feared profit warning has not yet materialised. As promised in the prior trading update, H1 revenues come in at around £1.9m, up 40% compared to last year. Adjusted operating profit and cash generated from operations are both in the region of £0.7m. Additionally, the company has a cash balance of £2.4m.
Entertainment Daily has performed particularly well, with traffic up 46% on last year. The situation at The Daily Mash is more complicated and its goodwill/intangible assets have been written off. I’m more keen on this share now than I was in August: the price/sales multiple (ex cash) has reduced to 2.2x. Additionally, the profitability of The Tab lends credence to the company’s acquisition model, and increased gross margins (87%) suggest improved operating efficiency. I’m now leaning towards a bullish view on this one, though I expect it to face a difficult headwind in the short-term as corporate advertising budgets come under pressure.
Smoove (LON:SMV) (£28m) (-10%) [no section below] - this company’s eConveyancer website is doing well in terms of activity levels but business is strong in the lower-margin remortgage segment, not in higher-margin purchases and sales. This means that Smoove’s gross profit has not improved in the financial year so far (the financial year beginning in April). Net cash at the end of August was just shy of £17m, versus £20m at the end of March. The company reassures that cash burn is “moderating”. The outlook statement points to stamp duty changes driving the first-time buyer segment, and claims that the group will, over time, become less reliant on eConveyancer. Unfortunately, whatever positivity I gleaned from this company’s full-year results appears to be more muted now. The cash burn is still too high for my liking and I can see the share price drifting towards that still-sinking £17m anchor.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Saga (LON:SAGA) (I hold)
109p (down 19% at 08:22)
Market cap £153m
Saga plc (Saga or the Group), the UK's specialist in products and services for people over 50, announces its interim results for the six months ended 31 July 2022.
I’ve still got lots of detail to plough through, but have got the gist of the main points, so here’s my initial review -
H1 revenues up 65% (recovery from pandemic) to £258m
Underlying profit before tax in H1 of £14.0m (vs a small loss in H1 LY)
Full year profit guidance was £35-50m, this is now reduced to £20-30m - disappointing, but not a disaster.
Ocean cruise business is on target for this year & next year.
Insurance division “challenging”.
Liquidity is ample, with £179m available cash, plus a £50m undrawn RCF.
Net debt is high at £721m, but remember that it also owns 2 nearly new cruise ships, with a book value of £612m (tested for impairment, which wasn’t necessary).
Debt maturity - the next event is repayment (or refinancing) of the £150m bond, in 2024. SAGA already has enough cash in the bank to repay this in full, so not a concern to me.
No dividends, focused on debt reduction, as expected.
Big goodwill write-off, so statutory loss before tax is £(257)m.
Going concern statement is fine, concluding -
In both the base case and RWC scenarios modelled, the Group expects to operate within covenants in the ship debt and to maintain sufficient liquidity until at least March 2024, with no reliance placed on the availability of funds under the RCF.
When I last looked at the covenants for the ship loans, it basically required that SAGA overall trades ahead of breakeven, which it is.
Balance sheet is large & complicated! NAV is £397m, less intangibles of £496m, gives negative NTAV of £(99)m - room for improvement there, which should gradually improve from retained profits & cashflows in the coming years.
My opinion -
Overall, these figures don’t look too bad to me, in the context of what the share price has done in the last year, which hardly suggested that a sparkling result was likely -

The recovery in profits is slower than expected, which is why the share price performance has been so poor - brokers have been guiding down expected profits, and there’s another reduction today, not yet reflected in the graph below -
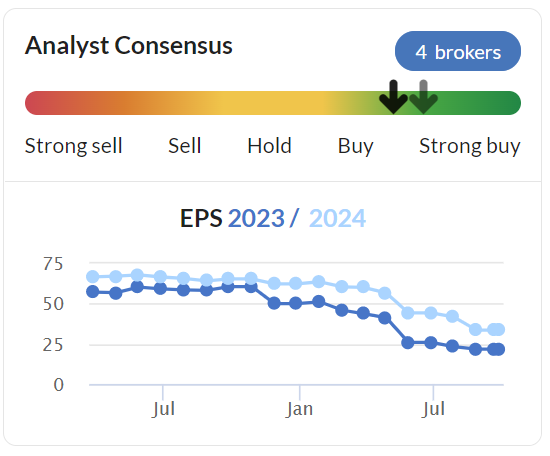
So clearly SAGA is not performing particularly well, but it is profitable again. Travel should gradually rebuild. The commentary says that the cruise ships are performing well, but travel overall made a loss of £11.6m in H1, which doesn’t impress me at all. There should be decent upside on that, and the commentary sounds upbeat about bookings, although with some inflationary impact, and having to offer early booking discounts.
I don’t have any worries about solvency or liquidity. Yes, SAGA has a lot of debt, but it’s well structured, with quite long maturities, and it’s also sitting on a big cash pile, and should be nicely cash generative. Note that I’m pretty sure debt costs are fixed, so there shouldn’t be an issue with rising interest rates. Covenants only apply to the ship loans, not the bonds, so that’s all pretty secure.
To conclude then, I’m obviously disappointed that this year has only seen a modest recovery in trading, so I see SAGA shares as work in progress. There’s nothing that particularly concerns me, so I’m happy to continue holding, and might add to my position if the share price continues falling, as there’s nothing of concern in these numbers - it’s just all a bit flat, so nothing to get excited about either. The market cap is now looking temptingly low, I think the valuation is looking appealing.
Graham’s Section:
S&U (LON:SUS)
Share price: £20.85 (+2.7%)
Market cap: £254m
This is a family-owned and operated financial business, in two parts: a non-prime car lender, and a property bridging finance lender.
Key bullet points from today’s interim results:
- Revenue +15% to £49.4
- PBT +5% to £20.9m
- Net Receivables at the end of the period +21% to £370m (this is the size of the lending book, and is a more forward-looking indicator).
The interim dividend goes from 33p to 35p - the company is rightfully proud of its dividend record, with a stream of dividends stretching back for decades.
Divisional performance
In car lending, the collection rate improves to 94.3% of due (up from 92.4% in H1 last year), described as “well above both budget and last year”. Net receivables finished the period up by 12.5%.
When it comes to credit risk, the Chairman points to “nearly a quarter of a century’s data and a broader range in our panel of credit reference agencies” as supporting collections.
On credit risk, the company “constantly studies customer payment patterns and refines the data surrounding them. It can then adjust affordability calculations and extrapolate future cost of living trends with some accuracy. This not only reinforces future credit quality but provides greater efficiency in identifying good future customers.”
In property bridging, net receivables finished the period up by 56%. This is still a new-ish venture and it’s exciting to see how quickly S&U is growing it. But S&U will still be considered a boring financial stock by many people!
The bridging company has created a new “Bridge-to-Let Loan”, that is “designed to appeal to smaller developers and refurbishers seeking security for their project refinancing”.
The bridging pipeline “has remained consistently above budget, although seasonal factors, higher interest rates and a slightly slowing residential market has shown a recent return to budget.”
Funding
The last time I covered this stock, my only balance sheet concern was that the company had used up most of its banking facilities. Sure enough, the company today announces that it has opened a new £30m facility with its banking partners.
Balance sheet equity creeps higher to £212.5m (from £206.7m six months ago).
My view
Perhaps encouraged by the strength of its collections experience in motor lending, and by the success of its property bridging venture, the company appears to be taking a bolder stance. Gearing according to the company’s calculations increases to 73% (vs. 61% a year ago).
According to my own calculations, the company’s balance sheet leverage (debt/assets) has increased to 43% (vs. 39% a year ago).
Personally, I think these metrics are still within a reasonable range. Other lenders would take far more risk without any shame.
It’s also worth pointing out that that £370m lending book is stated after some hefty loan loss provisions. The total amounts receivable from customers, before provisions, are £374m in motor lending and £91m in property bridging, i.e. £465m in total. But then £95m of provisions are recorded, so the lending book is only stated at £370m.
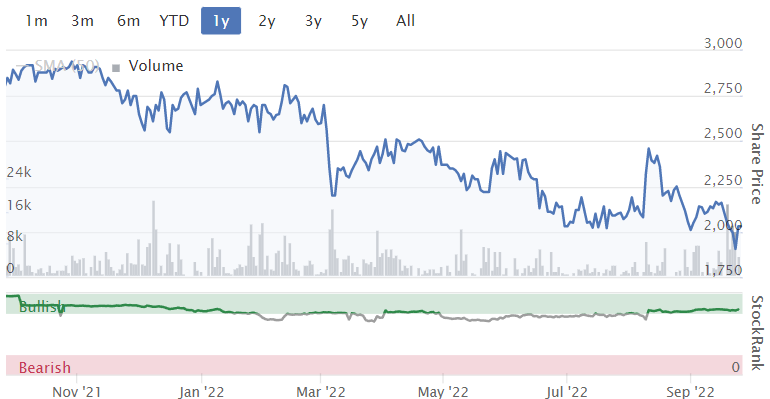
If £95m of provisions seems a bit big, then you can see how an argument for investing in S&U stock could be crafted. Let’s suppose that true balance sheet equity, after a more realistic (hopefully smaller) loan loss provision, is actually £230m. In that case, the stock is “really” trading at just a 10% premium to book value. Not bad, given the long history of high ROCE and ROE!
So yes, I do believe that these shares are undervalued:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

117 comments
Hi Paul,
I hold SAGA shares ( Saga (LON:SAGA)) and read your view on SAGA. I read then FT article "Saga cuts forecasts as inflation drives up cost of claims". FT article states "Euan Sutherland, chief executive, attributed the cut to the forecasts to the effect on Saga’s insurance underwriting business of the “underlying inflationary environment around insurance claims”.".
Please can you provide your opinion on SAGA's insurance business? Would it continue to be a drag on SAGA considering reduced competition in insurance sector while claims rise? Or in your opinion, it's not something to worry about.
Thanks.
Been using Stockopedia for a couple of years now after a long career as an FD ( never CFO….) in medium sized uk manufacturers, often PE owned. Didnt expect to be fifteen percent and many thousands of pounds down in that time.
Thought I knew a lot about this game - SCVR taught me I was wrong about that. Have learned so much, and have subsequently taken actions that have prevented those losses being at least double . For that I am grateful for stocko.
We seem to be in a period of constant crisis - I cannot recall anyone predicting this three years ago. So who knows what the future holds. If I was in it for the short term I would have adopted the traders’ tactic of stop losses and constant dealing. Not for me.
I have always been an independant thinker so there has been no need for the daily general reminders to DYOR. It would be unthinkable for me to risk my and my families money based purely on others’ thoughts. And i find it almost inconceivable to think others would do so. I like to take SCVR thoughts and put it through my own scrambler , based on over 35 years experience out in the field.
Great to see such an active SCVR discussion board (whatever the reason).
Due a dead cat bounce.....not today by the looks of it. America heading down again.
https://www.thetimes.co.uk/art...
Have we all forgotten about high StockRanks & high Momentum numbers?
Personally I would not have bought SAGA anytime this year. The general trend has been down. A simple 10% stop loss would save loosing any more money. With a StockRank of 32 and a Momentum of just 18 & down a massive 24.55% today is a complete disaster.
Meanwhile over the other side of the pond in the US the value of shares have been helped with falling £, & the dividends have been increasing as well.
Best share this year so far TGA, with a 43% dividend yield. StockRank 99 Momentum 98.
Mmm Lightningtiger. Well Thungela Resources (LON:TGA) is doing a lot for climate change, though it can best be described as playing an important part in the transition period to net zero and / or reducing Putin's gas and oil profit margins by a very small %. Oh and I missed the opportunity too, though of course I wouldn't have invested in it on moral grounds!
I trade Thungela Resources (LON:TGA) so I can stay afloat - pretty much like the world economy.
During a recession and an early stage bear market, I wouldn't risk my hard earned cash on any stocks right now except for energy and mining stocks. Missed out on the TGA rise which is a shame, but that is one heck of a dividend yield.
I think both Trinity Exploration and Production (LON:TRIN), Jadestone Energy(JSE) are good plays. Both have zero debt, strong cash balances, increased EPS for 2023E and are currently engaging in share buy backs. I'm watching Afentra (LON:AET) as that is good also. I've completed a trade on Sylvania Platinum (LON:SLP) with 20 percent profit and will look to buy back after a deeper pullback.
So far this year, I'm up 20 percent overall so I'm happy. Pity I didn't short the DOW in the last rally. I was shorting it but always tended to short it too soon, and eventually gave up.
Always thought Sylvania Platinum (LON:SLP) was just catalytic converters play but platinum is used in many other things and a byproduct is iridium in an awful lot of other things and scarce resource which is getting scarcer (or stockpiled) and harder to dig up by the day. Wan't to know how can buy/hold/invest/benefit from gold - but other than stashing it under a concrete slab aka John Wick don't know the answer.
Hi GarryC,
That's my understand also, that it's just a catalytic converter play. So wasn't trading it based on expected future demand of PGM's because I can't be certain, but on its chart pattern(rectangle), and swing trading as opposed to buy and hold.
I thought the best way to invest in gold is in buying gold stocks?
Clearly a big difference of opinion on Saga (LON:SAGA) today! I hold but it is sitting in my rubbish bin (the opposite of the coffee can concept!) along with Hostmore (LON:MORE) Boohoo (LON:BOO), Unbound (LON:UBG), Vertu Motors (LON:VTU) . These were always a speculative part of my portfolio so will have to forget about them until either go bust or recover - eventually (10 years!). Of much greater concern to my portfolio is the impact that the increase in gilt yields is having on REIT. The likes of Warehouse Reit (LON:WHR) ,Supermarket Income REIT (LON:SUPR) ,abrdn European Logistics Income (LON:ASLI) , Renewables Infrastructure (LON:TRIG) , Impact Healthcare REIT (LON:IHR) , etc are all suffering big falls in the last few days. It seems they are now no longer bond proxies when gilt yields are not far from 5% and some, but not all, have significant debt positions. Maybe no more SCVR reviews +DYOR and a switch to boring old gilts but then there is the twin spectre of inflation and the IMF!!
I too have suffered similarly as various things have sold off in the last few days, log on this afternoon as my head was in work, made redundant at 5pm last night hence focus elsewhere and go argh.
Impact Healthcare REIT (LON:IHR) was the last remaining 5% holding in my mum's portfolio everything else trimmed to 1-2% or sold, and it was like BEEP 20% down in 3 days so now trimmed to 2% today, take the loss, well between loss on sale (as took part in all the options over the last few years) and dividends probably slightly ahead in just over two years, though it feels beep how much capital down, that is three years worth of income since Sept 21.
But channelling my inner Linford C, I am still probably up from the depths of Covid, we are not looking at a big debt, and still >50% in cash. As mum now 80, we can play the sensible game, loss of income from the ISA for a few months or 20% loss of capital, use some of the rainy day account for now.
Add in the likes of NextEnergy Solar Fund (LON:NESF) and Foresight Solar Fund (LON:FSFL) and JLEN Environmental Assets (LON:JLEN) similar income holds, are also battered, but they were smaller positions so more likely that I will take from a 1-2% to 2-3% over the coming weeks looking to build a future income better than before, whilst accepting it might not be the bottom, or this bottom, or the next bottom, or cash if it all goes south...
Has anyone got a Tardis on eBay that I can put a bid in on?
Tommy
ps. Surprisingly now that I am redundant, unemployed or whatever the phrase is today feels a lot better than the last couple of weeks!
Hello Tommy. 'Ready for the next new opportunity/in between jobs/rethinking my future'. Some ideas for choice. You have my sympathy and very best wishes. PS Hope the pay off is enough for a good night out.
Sorry to hear about your employment situation TommyH. Hope things improve.
I too have been put 'at risk' 30 day notice thingy. Seems a theme. So resources moving around employers would be good for recruiters maybe.
Good luck Tommy. I hope it all works out OK.
ACounsell there was a very interesting article in this weekend FT about about I.T's and how they are all pretty much down on NAV across the board. The article was by David Stevenson.
Look it up, but his last paragraph is as follows
'I think were probably not quiet at the point of capitulation for investment trusts, but we may not be far off. If some of the discounts widen even further, I think the upside could be worth the risk'.
Hope this helps
Paul
Hi ACounsell,
Thanks for flagging up that some REITS have crashed in recent days, I hadn't spotted that. Warehouse Reit (LON:WHR) is one of the few that we've covered here in the SCVRs, purely because a shrewd friend told me about it over lunch quite a few years ago, and with warehouses at the time providing nice yields (about 7% from memory) in a zero interest rate environment, and being valued at below rebuild cost, they looked so good. I was kicking myself for not buying at about 100p per share, and watched as they slowly, gradually rose to about 160p.
Then suddenly, bang! All those gains gone in just a few weeks. Incredible.
With interest rates, and bond yields, shooting up so much, so fast, this all looks highly destabilising.
It's looking increasingly obvious, by the day, that the Fed has adopted a strategy that could be disastrous, especially for other countries now being dragged along in its wake. With so many (arguably over-priced) assets now crashing - shares, bonds, property, you name it, this could trigger another banking crisis like 2008 - with forced liquidations, deleveraging, banks not knowing which ones have the bad debts hence a reluctance to lend to each other.
Maybe we're not far away from a policy reversal, and slashing interest rates again, with more QE to stop the whole system shaking itself to pieces again? Trouble is, no other country can do that, as it would invite a run on their currency. QE only works if everyone does it at the same time.
So yes, very worrying indeed, recent developments.
Regards, Paul.
Oxford Metrics (LON:OMG) - Profit warning today, amazing isn't it that despite sale of part business not long ago which was reported on by Paul and company holding I believe 67 million in cash at the time and more than 1/2 of Market Cap (probably even more % now) that share price has declined since that news (after initial uplift on news) up to today's announcement. Now we know why perhaps. If Paul could find time to comment on todays update would be appreciated, a lot of commentary/brokers at the time of sale thought £1.50 was fair value, now not far of half this price!
Investing is tough. Roller coaster is why profits on average are high. Few can stomach the downturns. The analysis by Paul and Graham is good. You must be both diversified and low risk to cope with these types of periods.
I'm 70% down on Saga. Another great investment idea highlighted by the Small Cap Value Report! Boohoo, Revolution Bars, Hostmore etc. On it goes. Disastrous.
I could add the those, Stocks123456, but the SCVR is still a great classroom!
Stocks123456, best advice is to grow up or use a stop loss. Preferably both.
Im not sure we've had the capitulation phase yet but we must be moving towards the anger and depression phase.
Timeless human emotions.
Love it gringo!
Dont want to be anything but constructive (I tend to be a bit of a bear !!) but I think that it might be too soon to dismiss the possibility of several years of pretty choppy waters. The FTSE 100 is only 10% off the peak, the AIM markets are well down on that (maybe 37%). I watched an interesting video from Aswath Damodaran this morning on the effects of inflation and the equity flow from risky assets. I have noticed this in my own behaviour - I now pay much more attention to the spread - I dont want to be trapped in an asset where I am 5% down before even starting.
Lets hope so gringo. I'm with Paul and SCVR team, they don't tip and always state this.
Nice chart Gringo!
Love this chart. Very good. Personally I think the major markets are still in Denial.
Stocks123456, best advice is to grow up or use a stop loss. Preferably both.
IMHO they are making a good point. The SCVR coverage is overweight poor quality consumer facing shares. I could add another half dozen such dreadful companies to the list easily, but we all know what they are...
Simoan, do you mind if I ask what do you think can be done about it? G.
Simoan, do you mind if I ask what do you think can be done about it? G.
FWIW I am not trying to change the SCVR coverage and you and Paul should cover companies that interest and motivate you. However, often decent quality companies putting out results or trading updates are overlooked in favour of some high risk special situation. Today is a perfect example with results from decent companies such as K3 Capital (LON:K3C) Medica (LON:MGP) and A G Barr (LON:BAG) being overlooked in favour of the basket case that is £SAGA
All the best, Si
Hi Si, that is fair enough. Unfortunately, we are in results season and it's easy to get overwhelmed with the volume of news that is released every morning, and to get bogged down reading one or two particularly long and complex results statements. But the process is always improving. Thanks for the feedback. G
A fair point, though difficult to pick and choose at times especially during busy periods. I supported request for K3 Capital (LON:K3C) too.
Graham, you and Paul are both excellent analysts. You are perhaps a little more dispassionate than Paul but you are both honest and I value your work. As I understand it the underlying thesis of the SCVR is that small UK-based companies have the possibility of growing much faster than big international companies but they aren't covered very well by other analysts, so it's worthwhile having specialised analysis of them here. But we have a problem. The macro events of the last few years have, one after another, knocked back the chances that small UK companies are going to be good investments. It's quite possible that UK smallcaps is going to be just about the worst investment sector in the world for at least a year or two. And I agree with Simoan that there is too much focus on 'poor quality consumer facing shares'. If the SCVR continues I suggest that it re-focuses. Someone on Stocko recently published a list of UK manufacturing companies with a high proportion of earnings from overseas. Might that be one possible shift in focus?
Agree have no interest in fashion or restaurants for the long foreseeable future, or ten pin bowling lol. Commodities, energy, financials maybe and USD earnings.
The SCVR provides a huge valuable resource of past articles to go back and see what the view was then and how panned out to today.
There will be cigar butts out there and the SCVR is tasked with finding them - just put them on a watchlist with an alert rather than putting in the cash. Sad but it's investing in a shark pool where you are the food.
But these are only ideas for us all to Do Our Own Research with and take ownership of. This is from someone who also owns ( or has owned) Boohoo, Revolution Bars and Hostmore and didn't do enough research or set a stop loss with. I really value the comments from knowledgeable readers, especially with todays Saga (LON:SAGA) Saga.
That's not to say I don't value Paul's ( or Graham's) work of course, which I think is absolutely brilliant. The level of detail is unsurpassed in my opinion.
Correct and I admire people like you.
Everyone should do their own research first and do not blame others for losses incurred. But I have to say that people writing these reports should be more careful and study the accounts in more detail. One disadvantage they have though ( a very big indeed ) is that they should write their reports in a couple of hours ( covering 5-10 companies!! ) , while we have all the time in the world to study them in more detail and also look at Mr. Market’s reaction.
Sorry stocks123456 that you lost money but I’m fully backing Paul and the SCVR here.
We all make our own investment decisions and try to make use of the available information at the time. It’s unfortunate things haven’t worked out but no one can predict the future and sometimes things go wrong. In a different environment, the companies might’ve performed well.
This year, most of us have lost out in some way. Best to learn from it and hope for improved performance in future.
Cheers,
My view when I act on a tip that has turned out to be duff is that I was the one that pressed the buy button.
PS Maybe in a bear market you should change your user name to Stocks654321. :)
but, you do 'do your own research'?
I rely on peoples opinions not DYOR - hence rely on Stocko quick assessments. There is no blame game here. We are responsible for pressing the button. There will be 'oh but he said etc' - I dumped IC on a Mr T's studies but my fault - there are no guarantees. He's had a hard time I think with reputation as well.
My biggest duds are Boohoo (LON:BOO) and THG (LON:THG) - but as noted above it's discipline and obeying your stop loss rules not dreams. Sell your losers in good time - not keep in hope they recover - sell and buy again on the up if have the same conviction - but who does that - not me lol.
The SCVR merely highlights ideas which may be worthy of further research - I looked at all those companies and ruled them out for one reason or another.
Stocks123456
People were not saying "disastrous" when the market boomed on the back of the vaccine in 2020.
I've made money out of several of those names but I don't own any of them now and my portfolio is up over the last few years on the back of finding stocks in the SCVR.
Its just a very bad time if you are a buy and hold investor ( which I am not ). Maybe in a few years time I will wish I hadn't sold out? Who knows?
Small caps are not 'where it's at' just now ... and I don't think they will again be 'where it's at' for another two or three years. Small caps in general are not going to deliver good returns or be a good place to invest at acceptable risk for a few years ahead, I believe ... although their day will surely come again in, probably, just a a very few years' time.
That renders SCVR (as it is now) a bit of a side-show, I think. I believe now might be the time to 'reinvent' (or, at least, realign) Stocko's premier blog. The way I see it 'how to make smart investment decisions on the way into and out of a stock market crash' is the central problem that most of us face.
And I'd like to see SCVR refocused on that.
Read the small print. DYOR
I wonder whether anyone would care read something into the announcement late yesterday of Edward Bramson (activist investor) taking a 3.63% stake in £MORE. Where does he see value and what might be his plans? I sold out a while ago but does the current price represent an opportunity?
I did report late last night that the boys seem to be back in town.
It’s not only Branson but his partner is actively involved now in the running of Hostmore plc and has been buying shares since. I believe that we will see a lot of changes ( management, shareholders list , share price ) by the end of the year. Worth an investment at these levels.
Now I understand your comment. Too cryptic for me!
Interesting development, and remember Bramson was the one who started all this by pushing for the winding up of the Electra private equity fund, which of course held TGI. He therefore must be pretty familiar with the company and thinks there is a way to extract value. He has a pretty good good track record with small companies (less so when trying to take on the like of Barclays where we had to accept defeat).
I read the smart money will move into restaurant shares at the point of peak pessimism. Good chains will flourish in the bounceback. Because will will bounceback right???
S&U (LON:SUS)
I hold. Investor Meet Company presentation at 12.30 today.
Hi Paul,
Will you be reviewing Animalcare (LON:ANCR) Interims released today. You made comment when they provided a trading update in July. Cheers.
Interesting and reassuring interim results this morning from £NAH.
They are progressing well with their strategy of building up a book of WIP (work in progress) within their law firm and are balancing investment in cases with cash flow sensibly. Once the book reaches maturity (FY24), it should generate £2-3m per year in profits, which when added to the c. £3-4m+ profits from their other main division (provides Critical Care assessment and expert witness services), the group should be earning in excess of £5m per year. That's against a market cap of c.15m (EV of £29m). I hold.
Allenby Capital (House Broker) have a good note out on NAHL (LON:NAH)
https://wp-allenby-2020.s3.eu-...
Has EPS reaching 7p by end of FY24 and 11.p by FY25 (currently 34p/share)
NAHL (LON:NAH) hasn't paid a dividend since 2019 and isn't promising to do so anytime soon.
I hold.
Silver
I recently read a comment (not here) that NAHL's board of directors were more interested in preserving/increasing their meal ticket rather than doing honest work paying investors a dividend. I look foward as a shareholder to being proved wrong.
I'm not sure that's fair. Management aren't paid extortionately and have performed really well since Covid. They aren't paying a dividend because they are focusing on paying down debt and reinvesting in their book of WIP. Once that reaches maturity, I would expect them to pay a dividend, but not before.
(I hold) Paying a dividend at this stage of the turnaround would not be a wise allocation of the companies capital. in previous years (and under previous management) the company used debt in order to sustain and pay what was an unsustainable dividend, saddling the business with more debt and damaging the balance sheet.
By funnelling all free cash flow now into paying down debt and investing in the book of WIP in NAL, the company is both reducing risk and transferring equity back from the banks to the shareholders (in a very tax efficient way). As well as ensuring a more sustainable and profitable business moving forward.
It may not feel like it but the company has returned £1m in cash to shareholders this half through debt repayment, and its likely to pay a similar amount in the 2nd half. As NAL begins to throw off more cash next year and ongoing the cash returned to shareholders will increase sharply from current levels.
If this is the case then we should be seeing an uptick in the current share price. It still looks like jam tomorrow to me having bought and held since 2016.
Saga (LON:SAGA)
The post-pandemic boom in travel and cruising helped over-50s specialists Saga post a 600 per cent increase in underlying profit for the first half of the year.
Saga announced almost £260m in revenue up until July 2022, a 65 per cent increase on the previous year, while its £14m underlying profit brought it back in the black, after a £2.8m loss in 2021.
https://www.cityam.com/over-50s-specialist-saga-has-600-per-cent-increase-in-underlying-profit-in-covid-revival/
Most mornings I love investing in Small UK Companies. This morning is not "most". Pressure Technologies who are fast becoming serial disappointers in my mind have announced their final results. We have to remember why we invested in the first place....mmmm.....well they restored their bal sheet in a placing back in Dec 2020. They produce valves, cylinders for the oil and gas industry (not so good), defence (i would have thought good) and hydrogen (increasingly) industries. In my mind demand for hydrogen growing and defence growing, oil and gas not going away quickly, should be revenue enhancing. Clients are high quality. Been in the business a long time. Turnaround situation. Well apparently no steering wheel!! Excuses - well unexpected customer delays, supply chain disruption, unplanned outage of key equipment. So that would be supply and demand! And the good bit is they won't meet their banking covenants and their revolving credit with Lloyds is fully drawn. Anybody want to guess at what is going to happen here? Ouch. But don't worry 2023 promises to be a much better year. Shares down 40% as I splutter.
You have my sympathies, Camtab. The destruction of shareholder value at Pressure Technologies (LON:PRES) since around 2014 has been quite shocking. Shares back then were trading in the low to mid 600s and all seemed promising. A series of poor and overpriced acquisitions and diversification of the business (including the usual US disaster) saw a sharp reversal and it has been pretty much one way traffic ever since. I finally lost patience and bailed out (far too late and at a significant loss) last November, because I saw little prospect of recovery. Shares were then trading around 77p. Look where they are now.
Saga (LON:SAGA) rights issue must be coming at some point. They now have wafer thin profits and a huge £700m net debt. With the insurance business deteriorating due to the inflationary environment and the cruise biz facing into a recession they are walking the plank towards an inevitable equity raise.
I think if you look more carefully at SAGA's numbers, there's no reason for an equity raise at all. It has ample liquidity, and has £179m available cash - plus an undrawn £50m bank facility - which is more than enough to pay off in full the next bond maturity in 2024 (the bonds don't have any financial covenants, incidentally).
Remember that most of the debt is funding 2 nearly new cruise ships, which have a book value (tested for impairment) of £612m. So it's long-term asset funding (no problem with that), and repayments have resumed after a 2 year pause during the pandemic.
Profits are not falling, they're on an improving trend.
So I think you're scaremongering - there's clearly no need for an equity raise.
Their 3x Net Debt / EBITDA covenant (ex-cruise) says otherwise. If insurance is deteriorating (as it is) then this covenant is at significant risk of breaching particularly when they’ve already said that insurance reserve releases can no longer be relied upon. An equity raise is a very significant risk for shareholders.
There isn't any bank debt at SAGA. The RCF is undrawn, as it's sitting on a £179m cash pile, and the going concern statement says it doesn't need to draw down on the RCF, even in a downside future scenario.
Hence the covenant on the RCF doesn't matter, it's a red herring for this reason. Management are very cautious re liquidity, which is why they did an equity raise, and an (arguably unnecessary) additional bond raise (no covenants) in order to pay off all the bank debt.
Nebraska 1977 is not scaremongering.
He is giving an honest opinion based on the financial accounts of Saga.
This company will need a fundraise , maybe not this year , but definitely sometime between 2023-2024.
"This company will need a fundraise , maybe not this year , but definitely sometime between 2023-2024."
Why? SAGA doesn't need to raise any fresh funds. It has a £179m cash pile, no bank debt, and the 2024 bond maturity is £150m - so the cash to pay that off is already in the bank.
Also bear in mind that there's a big depreciation charge on the ships, which means that cashflows should be good, even at modest levels of profitability.
So as things stand, there is absolutely zero need for an equity raise.
If trading falls off a cliff in future, and SAGA starts generating big losses, then yes it might need to raise equity, like any other company where trading goes horribly wrong. But there's no sign of that.
I think if you're going to claim that a company needs a fundraise, then you need to back it up with facts & figures. Just making an assertion, with no supporting evidence, doesn't persuade me that you're correct.
The going concern statement today talks us through a downside scenario, and says there's ample liquidity, with no need to draw down on the RCF at all. So why would it need to raise fresh equity, if it's not even using the bank facility?
Regards, Paul.
Exactly you said it :
“As things stand”.
Enjoy your day.
Saga (LON:SAGA)
"Also bear in mind that there's a big depreciation charge on the ships, which means that cashflows should be good, even at modest levels of profitability."
Yes but the cashflow is used to paydown the debt on the ships and at the same time the ships become worth less older and closer to the point they will need to be replaced at which time upfront cash wad will need to be found for new ships . Note saga has already been granted extension ref loan repayments so payments in near future are higher to catch up amounts they previously "deferred". So there is no pot of excess cashflow imho ref the repeciation charge not being matched by specific cash charge.
What you cant argue is yet again with another worsening of near term expectations compared to before the safety net that was here is less now and the market is worrying that come 2024 or 2025 the spare kitty that is in then bank now may be gone - if they need to pay off that bond from cash.
Practicably that was my worry with last update that sharprice would tank in advance of any imminent issues with debt - the elephant is still there and we are getting closer to the date where they may not have said cash buffer of £150 mill.
I would agree they do have time to turn things around in the meantime - but to me the market pounding the shareprice is fairly natural and expected reaction to the worsening overall outlook.
Hi rmillaree
If I am not mistaken we did agree in the past and when Saga’s price was around £2 that this was a very risky investment due to its high debt.
What Paul is missing here is that he assumes that the cash the company is holding will be the same when the first bond matures in 2024. But , the company is not generating any cash.
Also , by paying out this bond , the company will be left with no cash at all. Will they pay the bond or opt for a share swap or a fundraise. Will they go for another bond ( but the rates of 3.5% are a thing of the past- they will be lucky to get 7-8%). And if they do pay it , how will they pay the one in 2026? Remember this company’s revenues are decreasing all the time and generate no cash.
Mr. Market has spoken today and has answered all my previous and current concerns. The company will need a fundraise sometime in the next couple of years.
There is perhaps also a circular argument on the ship debt.
What would be the market value of those ships in the current climate. Let's assume Saga failed and they lender took the ships back and sold them, how many cruise companies would be in a strong position to buy them?
As such I think the last thing the ship finance lenders want are the ships back. They will restructure if need be.
I have to say I am disappointed with Saga. This was one I was very bullish on. It looks like a long term hold to recover my position at best.
I've watched Saga for about a year now and I don't see an improving business. In an environment where loads of good, debt-free, dividend-paying companies are at rock bottom prices, I see no attraction whatsoever in Saga. I see the possibility of problems going into a recession and will avoid. In my view, all it would take is a slight deterioration and another raise becomes a strong possibility.
Saga (LON:SAGA) All of Saga's debt is at fixed rates, except the undrawn RCF facility which is charged at a margin over SONIA (Bank rate). The £150m 2024 bond pays 3.375% and the £250m 2026 bond pays 5.5%. The debt on the ships is backed by an Export Credit Guarantee and is fixed and payable in equal amounts over 20 years. See the interim report towards the end.
They appear to have ample cash resources borrowed at good rates with no repayment due till the repayment of the £150m May 2024 bond, which they should be able to pay from cash .
They also have some fuel hedging but I have not seen any details.
Presumably we can question them more at their presentation tomorrow.
I need to check the prospectus for exact clarification on which ones, but there are covenants in the bonds. It's simply not the case that any lowly rated issuer could get away with no covenants. I think they might be leverage and interest cover, but possibly others too. No equity holder should be under any illusion though that bondholders won't be speaking their mind to management on matters. A company like Saga knows they will likely need the bond market going forwards. I would be suggesting them to do a liability management excercise on both bonds and roll them both up into a longer dated higher coupon deal, but get breathing space on maturity. Banks would like that too. Or buying back debt would generate a b/s gain for the company is a well travelled approach if the cash is truly being held for the 24 maturity. They won't though be thinking only about the 24 maturity in isolation. They have to have a plan for the 26 bond too. There are plenty of approaches to use here but the bottom line is bondholders might force an equity raise if there are negotiations.
Saga (LON:SAGA) looks like the big one today.
K3 Capital (LON:K3C)
In July 2021, the Group completed the acquisitions of Knight CF and Knight R&D following a successful fundraise. These acquisitions have provided sector specific expertise to our existing corporate finance and R&D tax offerings, as well as paving the way for the development of transaction services to the Business Sales division, following the acquisition of Knight Transaction Services. From today’s RNS
I’m confused. What is the relationship between these acquisitions and K3C? Knight Corporate Finance, for instance, was incorporated in November of 2020 and bought by K3C in mid 2021. According to the accounts filed at Companies House, before K3C directors were added to the board, there were two directors, no employees, and 68k of assets (unspecified). https://find-and-update.company-information.service.gov.uk/company/13029720/filing-history
This is from the placing announcement for the acquisition:
Proposed Placing to raise £10 million for the Company
K3 Capital Group plc, a multi-disciplinary professional services firm providing advisory services to SMEs, today announces the proposed acquisitions of Knight Corporate Finance Group Limited ("KCFG") and Knight R&D Limited ("KRD") (together, the "Acquisitions"), together with a proposed placing of new ordinary shares of 1 penny each in the capital of the Company ("Ordinary Shares") to raise gross proceeds for the Company of approximately £10.0 million through the issue of up to 2,941,934 new Ordinary Shares (the "Placing Shares") at an issue price of 340 pence (the "Placing Price") (the "Placing").
KCFG is a specialist M&A advisory firm within the telecoms and tech sector, and KRD is a specialist research and development ("R&D) tax advisory firm servicing UK SMEs. The Acquisitions are in line with K3's strategy to acquire complementary and value accretive businesses to build out its existing SME focussed service lines. The proceeds of the Placing will be used in part to fund the Acquisitions and to satisfy an element of fees payable in relation to the Placing and the Acquisitions.
RNS, 7th July 2021
Has anyone looked into this deeply enough to satisfy themselves that what appears to be happening here is not what is actually happening?
Interesting find but seems at odds with what K3 Capital (LON:K3C) declared at the time of the acquisitions:
KCFG is a specialist M&A advisory firm within the telecoms and
technology sectors with consistent growth of revenue and EBITDA over recent
years.
o For the financial year ended 31 March 2021, KCFG generated revenue of
£1.71 million and normalised* EBITDA of £0.78 million, representing an
EBITDA margin of c.45%.
o Consideration of up to £8.6 million, comprising:
§ Initial consideration of £3.3 million on a debt free, cash free basis (to
be satisfied as to £2.2 million in cash and £1.1 million by the issue of new
Ordinary Shares at the Placing Price ("KCFG Consideration Shares")); and
§ Deferred consideration expected to be approximately £1.1 million (capped
at £2.25 million) payable as to 60% cash and 40% new Ordinary Shares for the
financial year ending 31 May 2022 ("Earn Out Year 1"), 70% cash and 30% new
Ordinary shares for the financial year ending 31 May 2023 ("Earn Out Year 2"),
80% cash and 20% new Ordinary shares for the financial year ending 31 May 2024
("Earn Out Year 3"), and 90% cash and 10% new Ordinary shares for the
financial year ending 31 May 2025 ("Earn Out Year 4"), in each case contingent
upon the future EBITDA performance.
§ Further earn-out equal to three times the EBITDA of Knight Transaction
Services Limited ("KTS"), a subsidiary of KCFG, for the financial year ending
31 May 2026 (capped at £3.0 million) ("TS earn out").
KRD is a specialist R&D tax advisory firm servicing UK SMEs,
with consistent levels of revenue and EBITDA growth over recent years and an
impressive EBITDA margin.
o For the financial year ended 30 September 2020, KRD generated revenue of
£3.16 million and EBITDA of £1.98 million representing an EBITDA margin of
63%.
o Consideration of up to £16.3 million, comprising:
§ Initial consideration of £9.328 million on a debt free, cash free basis
(to be satisfied as to £7.296 million in cash and £2.032 million by the
issue of new Ordinary Shares at the Placing Price ("KRD Consideration
Shares"); and
§ Deferred consideration expected to be approximately £4.0 million (capped
at £7.0 million) payable as to 60% cash and 40% new Ordinary Shares
contingent upon the future EBITDA performance, payable over 4 years
So I can't answer your question - what do you think has happened? And does anyone else have a view?
cheers
Francis
Sounds like a question for the Investor meet meeting on Friday at 11
https://www.investormeetcompan...
Re £K£C and Friday's IMC meeting, and questions, good point, Doug2500
Fair point, it does seem confusing. As already mentioned, the question can be posed at the investor meet company webinar and may be posted in advance.
Another supply chain profit warning today, from Oxford Metrics (LON:OMG).
Looks interesting, I think - they have around £20 million in cash (from interims) plus £54 million to come from the sale of Yotta, so the EV is only about £42 million with earnings (say) of 2p. The real interest is in the opportunity for Vicon, which ought to be in a sweet spot for all that lovely Metaverse growth Zuckerberg is betting the ranch on at Meta.
More generally, I wonder if these supply chain related warnings are really an opportunity. If orders are really only delayed and don't get cancelled presumably they are, if we care to look through the current economic chaos?
timarr
More generally, I wonder if these supply chain related warnings are really an opportunity. If orders are really only delayed and don't get cancelled presumably they are, if we care to look through the current economic chaos?
The problem is that small companies which buy relatively small volumes of components are at a significant disadvantage in sourcing those in short supply. There is a pecking order and any components with limited availability will go to much larger manufacturers. So whilst more generally component availability may be getting better for some, that does not necessarily mean everyone is in the same boat. Yesterday, Concurrent Technologies (LON:CNC) were unable to indicate a likely timescale for an end to their component supply problem. With Oxford Metrics (LON:OMG) it's not clear what type of component is in short supply. I like both companies but don't see any rush to get involved, although given their technology, I'd put Oxford Metrics (LON:OMG) down as a likely take-out candidate for an overseas buyer.
All the best, Si
Hi Si
The problem is that small companies which buy relatively small volumes of components are at a significant disadvantage in sourcing those in short supply.
Couldn't agree more. I hold both Oxford Metrics (LON:OMG) and Concurrent Technologies (LON:CNC) as well as Gooch & Housego (LON:GHH) and Treatt (LON:TET) who have all reported similar problems recently. With smaller companies I take the view that there's a limited amount they can do to avoid these market wide issues when they happen and that, as long as the management remain apparently competant and trustworthy and the longer term vision remains intact I'd rather stick with them rather than jump overboard.
But holding anything in this market is painful, let alone buying into it, which I've been doing for a couple of months now. Arguably that's an act of blind faith, of course, as things could easily get worse before they get better.
And yes, Oxford Metrics (LON:OMG) post-Yotta looks like an obvious target.
timarr
Timarr, I agree, when the management says that orders are delayed, it's difficult to deal with. They may have decided that it's better to say "delayed" than "cancelled". They may be over optimistic or deluded or mistaken or dishonest. Or they could actually be right. One thing that we can do is to look at the forecasts. When the forecasts change following the RNS, then if the management really believe that the orders are only delayed, then this might be supported by FY2 forecasts being revised upwards at the same time as FY1 forecasts being revised downwards. If FY2 forecasts are not revised upwards at the same time as FY1 forecasts are revised downwards, then this suggests to me that the orders are more likely to be cancelled, rather than just delayed.
If anyone is looking for buying ideas, I think Cenkos Securities (LON:CNKS) looks attractive and I bought yesterday at 41.6p. This is about NAV per share price and over the last 5 years the 40p mark has been about a floor for the share. In the current market brokers like £CNKS will have a poor outlook so you're basically buying to sit and wait for markets to turn and in the meantime benefit from divis and share buybacks that the company has previously been generous on. I think its glory days in the mid 2010s are behind it but in 2021 it was as high as 90p and I am not going to turn my nose up at a share that offers potentially 100% upside over next 2-3 years with very little downside risk!
Billington Holdings (LON:BILN) . Worth a look at the IMC presentation this afternoon. I really like the hard as nails management team and results today delivered a big upgrade (Finncap note out) and played out just as they have said it would in the last 2 presentations. Weaker margin contracts being worked through (retail distribution centres and pre-steel price rise contracts) and now strong orders in hand with much better margins . In April they said energy price s fixed till mid 2023 (gas) early 24 (electricity) which offered them a big competitive advantage. Their safety solutions business going very well. Cash a bit weak end of period ( payment timing and margin enhancing stockpiling of raw material) but has recovered post period. Finncap have 2023 5.8x PE, 5.3% yield, mid-teens ROCE and FCF yield with more improvement to come in line with management guidance for margin. Strong balance sheet. Top-line coming from energy from waste plants, gigafactories, data centres, retail distribution and some signs of a return to some commercial property
Bilington Holdings Billington Holdings (LON:BILN) - structural steel - has posted interim results:
PbT + 71%
Adjusted PbT +93%
EPS + 71%
Very positive forward loking Chairman's statement including:
"I now expect the Group to deliver profits for the full year and for FY23, ahead of previous Board expectations."
Not much followed here, but could be worth a look. Up 12% this morning at 8.30. Market Cap £24mn. I hold.
Richard
S&U (LON:SUS) - S&U PLC.
Really good interim results today from the motor and property bridging finance company. A highly skilled and shareholder aligned management team that is definitely worth backing in my view:
Revenue £49.4m (H1:2021 £42.8m)
Profit before tax: £20.9m (H1 2021: £19.9m)
Earnings Per Share: 140.7p per share (H1 2021: 133.1p)
Net Group Receivables: £370.1m (31 July 2021: £306.4m)
Advantage Finance Collection rate: 94.3% of due (H1 2021: 92.4%)
A slightly more cautious tone struck in the outlook, more due to the potential impact on its customers from casino economics followed in the UK, than the underlying quality of this business.
"Current trading in both of S&U's businesses is very encouraging. We are
of course aware that we live in troubled times. Current economic and political
conditions pose potential challenges to overcome, but also opportunities to
grasp. As Franklin D. Roosevelt declared at the outset of a much more profound
recession 90 years ago, "all we have to fear is fear itself." Whilst rightly
more cautious in a less promising economic climate, S&U is equipped with
the ambition, experience and determination to prosper."
Graham, you have covered this before - please can you take a look today?
Hi Oldschool, thanks for the early comment. I covered S&U - hope I did alright! Cheers, G.
A further vote for K3 Capital (LON:K3C) on initial reading the prelims look very encouraging. One of the few shares I hold that is still in positive territory for the year.
Hi
Gresham House Energy Storage Fund (LON:GRID) half yr results 2022 (Jun 30th). Extract from report ....
Performance highlights in H1 2022
Net Asset Value (NAV) up 53.5% to £785.4mn (31 December 2021:
£511.7mn)
NAV total return of 27.2% with NAV per share rising to 145.11p (31
Dec 2021 :116.86p)
Share price total return of 23.3% vs FTSE All Share Index total
return of -4.6% in H1 22. Since IPO, returns have been 86.9% and 15.8%
respectively
Dividends of 3.5p per share paid in H1 22, with Operational Dividend
Cover at 1.18x
Underlying Operational Portfolio Revenue rose 20.6% to £30.1mn (H1
21: £24.9mn) and EBITDA stood at £22.7mn (H1 21: £22.4mn)
Weighted average discount rate of 10.79% for assets valued on a
discounted cash flow basis (31 December 2021: 10.77%)
Glossy report is here for those interested ...
https://www.rns-pdf.londonstoc...
I hold.
Regards
Howard
Hi again
For any interested in Gresham House Energy Storage Fund (LON:GRID)
This is the investor presentation they did earlier today.
You might need to register your name and email then you are free to view the presentation & Q&A its just over 1 hour.
If this link does not work go to their website and look in the Investors section
https://greshamhouse.zoom.us/r...
Regards
Howard
Good morning all,
Very good finals from K3 Capital (LON:K3C), and a very encouraging outlook statement. Revenue for Q1 "significantly ahead " of last year. 8.1p divi to be paid, ex div early October.
Will you be covering Paul or Graham?
Regards.
I second this request. Adjusted EPS 20.64 puts K3 Capital (LON:K3C) on an undemanding PE of 11 with over 5% dividend and if Q12023 performance sustains, growth of 27% in 2023. (I hold)
Cheers
Francis
I'm sorry we didn't get around to K3C today, but perhaps it will get some coverage in a catch-up report later in the week. Thanks. G
Yes please Graham re K3 Capital (LON:K3C) although I may be biassed suggest rather more interest than Digitalbox (LON:DBOX) or perhaps not. Don't see any comments today elsewhere from readers/contributors on the latter.
Thoughts on Saga please Paul. Thanks.
looked to me in simple terms like the travel side of the business was doing well, as expected, but payouts on insurance claims are up for to inflation.
the impairment on insurance goodwill want obvious to me though, is this just uninflating a previous unreasonable expectation? Can anyone else explain please?
Saga (LON:SAGA)
the impairment on insurance goodwill want obvious to me though, is this just uninflating a previous unreasonable expectation? Can anyone else explain please?
Most often goodwill represents a real sum of money paid (or similar) in the past for acquiring a business or brand , this may not necessarily be the case - so one would have to go looking back to find out if this was specifically money splashed out sometime in the past. Perhaps its book entry if they merged insurance with someone else like the aa? - the default amount that goes to goodwill is the excess paid over the value of the assets been acquired when new "brand" or "business" is bought.
Its very common - almost the default that many years later the goodwill left on the balance sheet will bear little relation to the actual goodwill value if the business were to sell their "brand" - the acounting adjustments are often just random knee jerk reactions based on sketchy accounting rules - this one does kinda make sense though if insurance is expected to be pants.
Example of this in action is probably nike with goodwill of only $240 million dollars - clearly then brand is worth billions and current owners could easily sell brand/business for billions tomorrow on top of asset value - as its presumably mostly been organic growth for Nike - they havent spent money on goodwill therefore there is little on the balance shet. Thios may be a bit oversimplistic Nike may have presviously splashed teh cahs and written of huge sums but thats probably pretty unlikely.
Generally with historical goodwill its best to completely ignore - and replace with your own valuation of what a business/brand/combo of teh two could be worh if sold. This being the case w/offs of the goodwill you have been ignoring anyway are no big deal.
Saga (LON:SAGA) ( I hold)
Guidance down from £35-50m to £20-30m. On 82m shares that's about 24p of earnings. Another big downgrade. I doubt market will have much belief in their credibility so hard to know where the price will bottom.
How did you get to 24p? Stockopedia had brokers at 21p before today and isn't £20m-£30m essentially double H1 (i.e. making £28m pre-tax profit and maybe 12p underlying EPS?). EPS calculations complicated by their tax charge which looks high in H1 and I don't understand the tonnage tax regime!
'In both the current and prior years, the difference between the Group's tax effective rate and the standard rate of corporation tax of 19%, is mainly due to the Group's Ocean Cruise business entering the tonnage tax regime on 1 February 2020.'
Saga (LON:SAGA)
EPS calculations complicated by their tax charge which looks high in H1 and I don't understand the tonnage tax regime!
Per google seems pretty simples - you take a gamble that may result in you paying higher or lower corporation tax than you would otherwise pay. Saga board being saga board have probabaly made the worst option out of the two available if this entry is bumping up tax. Obviously with covid boards expectations of how calcs would work in their favour medium term pre covid have likely ended up not working out as planned. Just another woeful saga for saga if they are paying coporation tax on chunky fixed sums whilst making little to no profits. Unlike tax normally looks like this extra tyax may simply be extra cash cost rather than normal swings and roundabouts of timing and or tax rates going up and doown.
per our friend google.
Tonnage tax is a form of Corporation Tax for working out the tax you owe on your profits. You can choose to pay tonnage tax on a fixed notional profit, instead of your actual profits from your shipping activities. This is based on the net tonnage of your ships.
You can elect to use tonnage tax but you must sign up for a minimum of 10 years.
Very helpful, thank you.
So if I have read that correctly, at the moment Saga (LON:SAGA) are paying a high rate of tax (especially as the cruise ships and travel business is still unprofitable) but hopefully at some point that will hopefully become a lower tax rate in future years providing the ships become decently profitable.
Saga (LON:SAGA)
I dont really know the details i just cut and pasted that info from google - makes sense though if they do make higher profits before they can change methods - IF they are on fixed method now then higher profits whilst on this method may come with lower effective rate of tax all other things being equal. Lot of ifs and buts here though.
Hi, taking mid points its -10p eps by my calcs. Seems to be at fair value now with limited upside but doubt the market will see it that way unfortunately.
Another big portfolio kick on this , just glad it's a longer term sipp hold but a kick nonetheless. EV still around £850m so even if the cruise ships do 80m and insurance and travel 100m(?) if things ever normalise you can understand how £1 a share is where it will end up even in an OK stock market
Hurts writing this as I also subscribed to the published rationale on here it could be worth many multiples of the share price in the past. Never back Euan - knew this but still did it
On the plus side, travel is now approaching profitability again and could change the fortunes of the company in the next financial year. As you can see below there is a declining trend in insurance (pre-pandemic half year insurance PBT was around £70m+ I think) and presumably this will get worse with lower margins expected in future on motor and home during 2023/24.
I suppose key questions might be 'how bad can it get' in insurance and what might be a more normal level of profitability in future years from 2023/24 when home and motor insurance margins are compressed? Would love to hear from anyone who has a stab!
Note my shorthand H123 = July 2022 (i.e. today's results) and H122 = July 2021
Will also be keen to hear Paul's balance sheet commentary today.
I did post of advfn yesterday that one way or another the share price will be very volatile at these levels where you have debt of 6x equity value. Just a bit gutted it was volatile to the downside . If things do normalise (whatever that looks like) and they continue to service and pay down debt and have 2 decently profitable business streams and a few other smaller ones it does represent long term value for sure plus I always felt a PE house could swoop in again at these levels and sort it out , restructure , split the two arms and realise some value perhaps. And I understand Paul's point that the mortgages on the ships aren't as bad a normal bank debt and are asset backed so keen to see balance sheet view and maybe if you "ignore" that debt if the cruise ship asset could ever be realised then that is the argument a SP in the mid £s is achievable still
How can you ignore a debt that you pay interest on?
It’s like saying that I have a mortgage but I haven’t got a debt. By the time they pay off the ships , new ones will be needed.
For me this is still a very risky investment; even after losing about 80% of its share value.
You get an asset you can use that is depreciated over its life.
"By the time they pay of the ships, new ones will be needed". Um yeah, it's why EBITDA is a thing.
Thanks you have made my day!
Re Saga (LON:SAGA) this is a light response to all the comments above.
Clearly the insurance side is being hit by high charges for repairs as well as many other things.
I an insured with NFU Mutual and my quote has just gone up by 15%.
In the same week, I passed a car coming the other way on a main road, a small piece of stone flew up and cracked my windscreen. Replacement needed. Charge for the windscreen from the main dealer £400 + VAT + fitting; charge, and for the camera realignment (didn't know I had one!) 140 + VAT at the main dealer.
The local guy from National Windscreen who handled the whole thing for the insurance company said that he could buy the windscreen direct for £140 vs the 400) and he was planning to buy his own realignment kit for £20k, and the job would have taken him 10 mins. He had to buy the windscreen form the place I bought the car or I couldn't have got the camera realigned.
Costs build up, don't they, especially when you add on several levels of middlemen?