Small Cap Value Report (Tue 28 Mar 2023) - ALT, UBG, XAR, MRL

Good morning, it's Paul & Graham here!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
SCVR Agenda - Tuesday 28 March 2023
Main Sections
(summaries here, main sections further down)
Altitude (LON:ALT)
Trading Update (ahead) - 47.5p (up 17% at 08:34) - market cap £34m - Graham - GREEN
FY 2023 adj. EBITDA is ahead and broker estimates for 2024/2025 increase. A speculative but promising share. Based on last night’s close, FY March 2024 price/sales ratio is only 1.1x.
Xaar (LON:XAR)
Finals - up 5% to 189.8p (market cap £149m) - Graham - AMBER
Weak 2023 estimates and nobody wants to forecast 2024. Chinese demand, margins too unpredictable. A shame that the company can’t generate better performance with its proprietary technology.
Marlowe (LON:MRL)
Trading Update - down 4% to 480p (market cap £460m) - Paul - AMBER
In line with expectations for FY 3/2023, and the tone of today's update sounds positive. Although on closer inspection, I dislike the very weak, overly indebted balance sheet, and poor cash generation. Looks like they've been in too much of a rush to do too many acquisitions, so it's not for me.
Quick Comments -
Unbound (LON:UBG) - Possible offer - 7.75p (up 87% at 09:00) - market cap £ 5m - Paul - RED
This footwear company was a disastrous demerger from Electra Private Equity. It today discloses an approach for a possible takeover bid at 10.5p cash, plus rights to any recovery from an insurance claim. The possible bidder is called WoolOvers, which seems strangely appropriate! Certainly I feel the wool was pulled over my eyes with this share. Let’s hope the deal goes ahead, and we don’t hear from this lot again. The market’s not convinced it will go ahead, judging by the 7.75p share price now. It would be tempting to grab the money and run, rather than waiting to see if the bid actually happens
Companies Reporting -
Paul's Section:
Marlowe (LON:MRL)
480p (down 4% at 09:14)
Market cap £460m
Trading Update (and Capital Markets Day)
Marlowe plc ("Marlowe" or the "Group"), the leader in business-critical services and software which assure regulatory compliance
I can’t remember anything about Marlowe, as it’s not something I’ve written much about before, apart from when it was trying to buy Restore (LON:RST) - a deal which seems to have fallen through.
Marlowe is doing a capital markets day to explain the company and its strategy. These can sometimes be a precursor to an equity fundraise.
Trading update -
FY 3/2023 in line with market expectations.
Revenue expected to be £475m (up 50%)
“High single digit” organic revenue growth.
Accelerating momentum, expected to continue into FY 3/2024.
On track to achieve £500m revenue, and £100m adj EBITDA in FY 3/2024.
Net bank debt c.£170m at 3/2023 year end.
Expects increasing free cashflow in future.
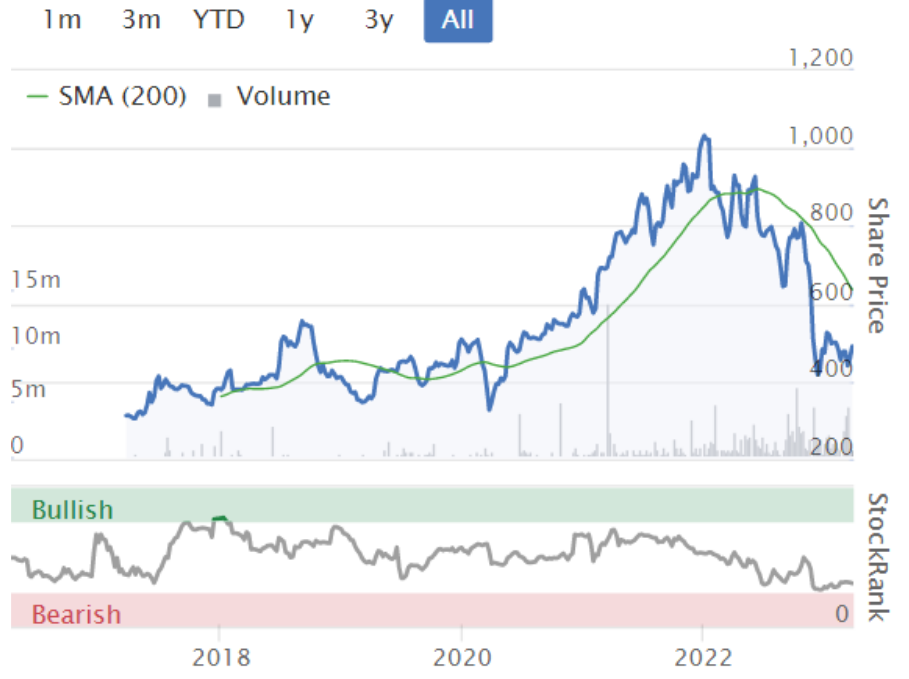
That all sounds quite positive, so I’m not sure why the share price has fallen right back almost to where it floated in 2016, after peaking in Jan 2022 -
.
Valuation on a forward PER of 10.3 looks attractive.
It doesn’t seem to pay divis, and the historic track record seems poor, reviewing its StockReport. Also the StockRank is low at 30.
Looking at the last published accounts (interims to Sept 2022) almost all the profit seems to come from adjustments, with statutory profit being negligible.
85% of revenues are said to be recurring.
Balance sheet - this is problematic. NAV is £448m, but that includes a gigantic £645m intangible assets. Whip that off, and NTAV is negative, at £(197)m. We can be generous I think and also remove deferred tax (which is often related to goodwill), which reduces the deficit on NTAV to £(145)m. Still very weak, although software companies don’t need a lot of net assets. I’d prefer to see it repay the heavy debt burden though, if that is possible.
Companies with a lot of debt are not attractive to me, given that interest costs are rising, and banks are probably getting more nervous about extending & renewing large facilities.
It’s clear from Marlowe’s balance sheet that it is heavily dependent on its bank facilities, so that would need careful scrutiny for anyone thinking about buying or holding this share. It could all be fine, but it needs checking.
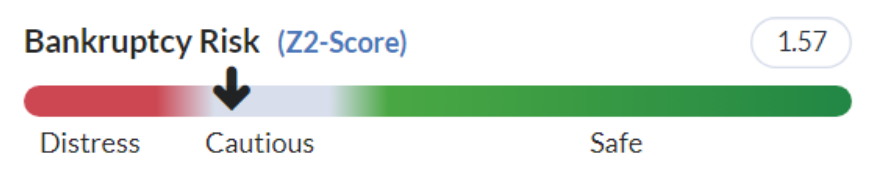
This is reflected in a Z-score (a historically proven warning system re risk of company solvency) that sounds a caution alert -
Cashflow statement - where’s the cash generation? I don’t see any meaningful cash generated in H1 this year, nor the whole of last year.
The stand out line is acquisitions of other companies - £37.1m cash outflow in H1 of this year, and a staggering £316m last year - nearly all of which was fuelled by increasing bank borrowings.
Acquisitions - you only have to skim the RNS to see that Marlowe has been highly acquisitive, some of them quite big.
My opinion - I can’t reconcile talk of £100m EBITDA next year, with an almost complete lack of cash generation in H1 FY 3/2023, and the whole of the prior year.
It looks to me as if Marlowe has rushed into too many acquisitions, overloading itself with debt and goodwill on the balance sheet.
Although it does look cheap on a PER basis. So if future performance improves, and starts generating cash to pay down debt, then it could be interesting.
Overall then I've got to be AMBER. Although I'm leaning towards RED, given the balance sheet risk, high debt, and poor cash generation.
Graham’s Section:
Altitude (LON:ALT)
Share price: 41p (pre-market)
Market cap: £29m
As we’ve discussed before, US-based Altitude has two major sources of revenue:
“Services” - connecting suppliers and distributors in the promotional products industry.
“Merchanting” - the sale of promotional products by Altitude itself.
Today’s update informs us of “multiple new significant contracts” relating to the second activity:
These multi-year New Major Contracts will generate an expected total combined gross revenue value of c.$30m, including $8m signed and subject to State clearance, throughout their 5-year terms. All New Major Contracts are expected to begin generating revenue for the Group in the first half of the next financial year ending March 2024 ("FY24").
Additionally:
A number of other major contracts of material value to the Group are in late-stage legal negotiations.
The new contracts sit within what Altitude calls its “adjacent market programme”. There is an explanation of what this is on Youtube at this link, in which CEO Nichole Stella refers to opportunities in the education sector - this may explain why some of the new contracts are subject to State clearance.
Year-end trading update: this section is short but sweet.
The Group has had a strong close to the year and the Board are pleased to announce that FY23 Adj EBITDA will be ahead of market expectations. Furthermore, as a result of the New Major Contracts, trading in FY24 is expected to start strongly and the Board are very confident in improving on Altitude's record profitability.
Estimates
Zeus upgrade their revenue forecasts by 6.6% (FY March 2024) and 14.8% (FY March 2025), to £26.1m and £35.6m respectively.
The adjusted PBT forecast for FY March 2024 moves from £1.1m to £1.3m.
The adjusted PBT forecast for FY March 2025 moves from £1.7m to £2.2m.
My view
I tentatively gave this stock the thumbs up last time, and the market cap hasn’t increased since (although I’m sure it will when the market opens this morning). Therefore, I’m going to retain my positive view on it.
Personally, I would prefer to see more growth from the Services side of the business, as that strikes me as a higher-quality source of revenue (it’s platform revenue, not direct sales revenue). However, I won’t say no to Merchanting revenue.
Altitude has not yet generated material profits so for now it is inevitably on the speculative end of the spectrum and has to be valued based on its growth prospects over the next few years, its price to sales ratio and the quality of its revenues.
Xaar (LON:XAR)
Share price: 189.8p (+5%)
Market cap: £149m
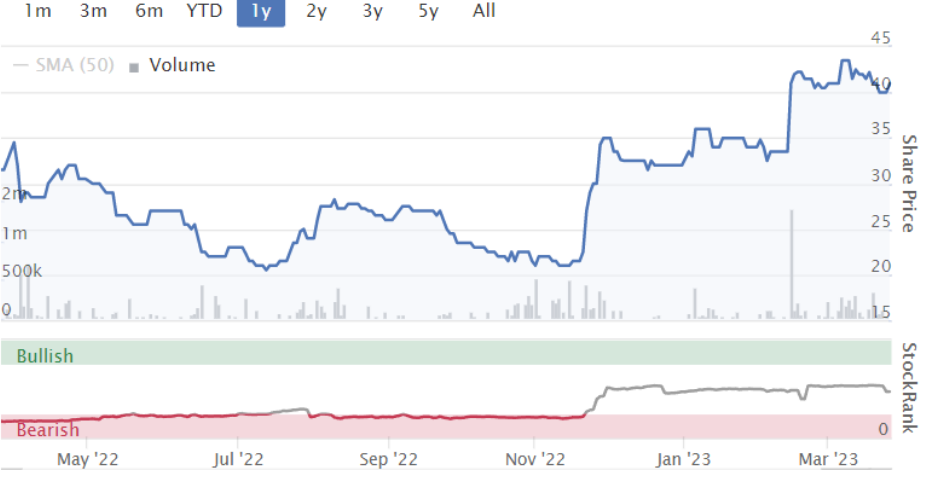
We last covered Xaar, the inkjet technology company, at the time of its trading update in January. A profit warning that day caused the shares to fall by 13%. They have held steady since then:
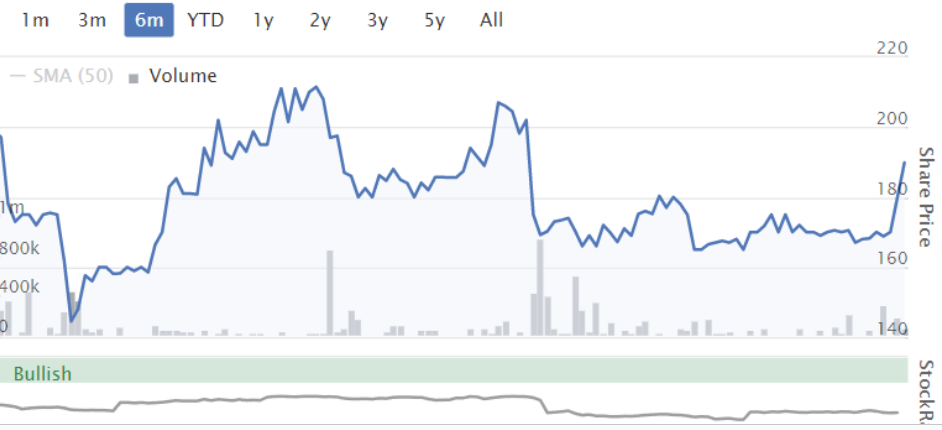
Today’s full-year results for 2022 are as follows:
Revenues +23% to £73m (+8% organically), slightly below expectations.
Gross margin 39% (up from 34%)
Adjusted PBT £3m is ahead of expectations
PBT £1m
The once-mighty cash balance reduces to £8.5m.
FY 2023 estimates are unchanged, although Gareth Evans at Progressive has taken a “cautious” approach and reduced his cash flow estimates.
CEO comment:
We have transformed and re-energised Xaar as demonstrated by our good performance and further strategic progress with positive contributions from across the Group. We have delivered strong profitable revenue growth and the important milestone of achieving full year profitability which represents great progress against our plan.
The company has launched a new printhead, Aquinox, and it says that this product “opens new markets to Xaar with its water-based capability”.
Let’s see what the company has to say about China, which is such a volatile source of demand:
Reduced revenue in China has impacted our Ceramics sector printhead sales, however, we are confident in returning to previous levels of trade with our customers in the region as COVID-19 restrictions continue to be lifted. Our commercial and technology proposition remains compelling, and we have retained market share in the region.
That sounds positive, but later on in today’s statement they strike a more cautious tone, saying “it remains unclear when normal levels of business will return”.
Acquisitions - the two acquired companies are trading “ahead of our initial expectations”.
My view
I remain intrigued by this share but I have two major question marks:
The demand from China seems beyond anyone’s ability to forecast.
The company has used up the majority of its cash balance and now needs to see the financial returns from its investments, to prove that the money has been put to good use.
2023 estimates have already been slashed to just £2m of PBT (£2.5m adj. PBT), and nobody is brave enough to make estimates for 2024 yet.
I’m on the fence between Amber and Red - I’ll go for Amber even though I don’t have any faith that 2024 will be the year that sees a proper financial turnaround.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
Is it my impression or many UK domestic stocks are having a very hard March? I'm seeing so many stocks bleeding?
Jadestone Energy (LON:JSE)
Average production in 2022 was 11,487 Boe/D. This will almost instantly nearly double to 21,000 Boe/D imminently as Montara progress to a full restart in the coming few weeks. Last week's RNS confirmed restart of the 1st well out of about 7. At current $78 Brent that works out to $0.6 billion annual revenues with Brent projected to rise going forwards. Not bad for a MC of £300 million, EV of £176m, zero debt, about 120 million in cash. Double impact of imminent catalyst of full Montara restart and price at year lows(strongly bounced off this level 3 times in the past). I have a price target of around 100p+ from current year lows of 65p.
Thank you Guybrush, checking it out now.
Just thought I'd flag up CMC Markets (LON:CMCX) sneaking out a profit warning at 3:51pm yesterday...
When will Management realise it only ends up in all trust being lost and always results in the share price being punished even more...?
I don't disagree but what I would say is that the MAR rules state that a company must release material news immediately it becomes aware of it. Thus if a client say cancelled a material contract at 3pm the company is obligated to announce it the same afternoon and not wait until 7am the following day. Obviously this was intended to stop companies sitting on news and/or leaky ships but can also be manipulated. Accounts being a classic example in that who is to say when "immediate" is etc. So it could be an attempt to sneak out a profit warning or it could be that the company had a board review that day where the numbers were discussed and then released. Hard to tell definitively either way of course.
Thanks David, hadn't realised that.
However the wording of this particular RNS implies this wasn't as a result of some sudden material news, but was down to general trading over the last couple of months, which presumably they should've been aware for some time now:
"February and March posed a more challenging environment with lower equity volumes and a higher proportion of lower margin institutional trading activity."
Agreed - thats why I say it's a bit open to manipulation. Depends on when they get their management numbers / when the board review is scheduled / whether they think they need to re-check the figures etc etc. Hence a late in the day update always looks suspiciously timed even though it may not be.
CMC Markets (LON:CMCX)
So it could be an attempt to sneak out a profit warning or it could be that the company had a board review that day where the numbers were discussed and then released. Hard to tell definitively either way of course.
Of course, these late announcements are never missed by the markets. Given that CMC have done this before, with the same result, in this case it looks like policy rather than subterfuge.
timarr
I also bet there are a lot of companies that could release RNSs earlier but don't.
hVIVO (LON:HVO)
Anyone willing to offer any thoughts on the huge fall over the course of March. For my part I felt it was way overvalued in the 20s comparing it to better established CROs in the normally pricier US with more stable revenues, so a dip was due. But it’s almost halved. And it’s looking sensible value to me today, albeit not much cheaper than industry-leading comparators for a mere niche-leader.
My basic hVIVO (LON:HVO) chart that I had made a while back. This was drawn before the channel breakout.
Chart
It's seems to be dipping to retest the lower channel trend line. Continuing to watch to see if it breaks below or turns
I don’t trade technicals but I can see that if it falls much further it will hit the 200d MA almost at the point it hits the lower band. That ought to provide a good test of support.
looks way undervalued to me BnB. I have a target in the mid 30's for it
In human challenge studies it is the global leader - in pharma and biotech they all want to use human challenge studies as it is reduces their risk. Thus whilst they may be a niche they deserve a premium given the moat surrounding this activity and the companies they work with. Visibility of revenue is very strong - this year is basically covered and margins are improving as they scale. So I see a 2 year forward revenue of £70m with margins around 18-20% and net cash of £30m+ and growing. For me that will be worth £250-300m to a CRO buyer.
There will be some sort of corporate event to realise this at some stage but probably depends on market.
Fall appears to be liquidity and market related. It went up quite a bit as people realised it was a much better business than they thought and that hotter money has drifted out. Mo Khan says he wants to under promise and over deliver so I am hoping he sticks to that.
Thank David. I remembered you were an enthusiastic proponent. I do like the CRO segment as it facilitates investment in drug development without the binary nature of pharma trials.
I like the business and I do think it is misunderstood by investors. It has a bigger moat than people appreciate and usually a global leader commands a premium, but in this case a discount for some reason!
It's a frustrating hold but the market is also pretty woeful and I suspect there are quite a few weak retail hands in the share register. All Mo can do is keep delivering and value will out at some stage.
Profit taking and the banking crises most likely. It did rally from 9.6p to 23p in about 5 weeks. Its only just come out of a long term downtrend and after that usually comes a period of sideways movement. From the stockreports, the fundamentals look poor: very expensive and low quality. Is there a wonderdrug that is on the verge of approval imminent? Otherwise I don't see anything special to make me want to buy.
Hi Guybrush - I'm not sure you understand what the company does if you are wondering that. This is not a pharma in the business of drug discovery or sales, it is a CRO that is the only company globally that does human challenge studies. So it sells picks and shovels to pharma and biotech - it does not run clinical risk and is highly profitable. Its client list is pretty much all of the major pharma. It provides major benefits to them in reduced time to market, reduced risk of failed clinical trials and cost savings.
The company has a net cash position of £30m and is on track to be producing profits of around £12m in the coming 12-24 months. It has almost 100% forward revenue visibility (contracted) for this year and much of next which compared to most businesses is very high quality.
A CRO will sell for 20* so hVIVO (LON:HVO) could happily get taken out north of £250m or 2.5* the current share price and that would not be unreasonable.
You need to look a bit closer than a cursory glance - I suggest looking at the research notes out and also the IMC presentations Mo Khan has done if you want to understand this a bit better.
Thanks for the info davidjhill.
This is a new company to me and I have done no research other than a glance at the stockreports, so apologies if I have misrepresented the company. However, from experince, the Stockreports has provided an excellant INITIAL filter for research, but obviously it is backward looking not forwards(not including analyst projections), so it won't capture any future potentially beneficial changes to the fundamentals. For that yes, deeper research is required.
On a price to sales basis a target in the 30s does look viable but this requires the operating leverage of improving margins to kick in without unforeseen complications. I think a target in the mid-20s splitting the difference between today’s valuation and the blue sky level better accounts for the risks in the model. In other words, still good potential upside and I’ve been watching via alerts on my software for a dip back into this lower band.
So we agree on hVIVO (LON:HVO) and I’ve an order in since 11am at 14p. Who knows how much, if any, will get dealt?
Agreed BnB - I know Mo targets margins in the 20% range over next couple of years. That would put it in similar quality category to Amryt pharma which recently got taken out at almost double.
I think mid 20's to mid 30's is reasonable. There are two other businesses that are hidden in the hVIVO (LON:HVO) balance sheet that will get divested once market conditions turn round (whenever that may be) that should add decent upside. I include them at zero in my calcs for now but am mindful there is a plan to realise value from them when conditions are right.
Yes, and CROs have been selling off across the board this year on expectations of a cyclical downturn - see IQVIA, Medpace, Ergomed, which accounts for a dose of reality setting into the share price.
I don't know Hvivo but when I look at the stock report, my uninformed view is that this is a long term gamble - no idea about the short term. I can't see any moat or severe barriers to entry. So when I hear someone say they are the only company doing something - my first question is - is their product / service proprietary (ie. IP) or protected through their brand / reputation - or can anyone take them on. I don't know the answer to this - but I think its an important consideration. The worry is that if they have found a very profitable niche, that then would likely attract competition within a sector that is very capex and investment heavy - what is the likelihood in 3 - 5 years that there is still no competition?
Also you say they are highly profitable. However according to the stock report they have been a perennial loss maker! The stock report for their profitability section is horrendous - these numbers suggest they have been selling £10 notes for £9 - not hard to grow a business if you operate on negative margins and are selling at a loss! Also in terms of the 'true profitability', is there a worry that this will be one those companies that incur a lot of regular annual capex in order to keep growing - or do you expect them to be very cashflow generative in the future - again a worthwhile consideration imo.
I do also wonder about the £30m net cash position you mention. As the company appears to have not made any real profit - in fact years of quite high loses. So where has the cash pile come from. I can see they have also heavily diluted share holders - about 10x in 4/5 years! So am I correct in thinking the cash position is actually just investors' money? Also metrics like book value and eps normalised look unimpressive, and although not necessarily indicative of a poorly run company, it also may be something to be weary of.
As I said, I am not knowledgeable on this stock and these are my thoughts after just a cursory 5 minute glance. However the stock report looks fairly hideous to my eyes. Years of building a business on negative margins, negative ROE and ROCE - screams warning bells imo.
Ps. I am usually wrong though. But this is a very open minded discussion board where I think most people want to hear bear views if they have them. So just throwing it out there for further discussion.
Good luck to all holders and I hope this one works out well for you.
cheers
Matt
Hi Matt - the problem is that you are coming to a turnaround story of two businesses combined by new management and investors and then looking firmly in the past, which is exactly what I'd expect from someone taking a 5 min cursory glance at a bunch of outdated information, that is now completely irrelevant. Like all investments, if you do that you will miss the change in the business. You have to look at more than one piece of outdated information to understand and assess the business.
This a complicated story to go through the history of so I'm not going into that here but I suggest if you have any genuine interest to go and watch a couple of the latest IMC presentations Mo Khan did (or maybe the capital markets presentation) which will give you a much better context.
The business is profitable at all levels and generating increasing cashflow. Post publication of the results they are going to be paying dividends from operating cashflow. It has contracted revenue for the year with over 97% visibility. It has margins of 14-17% and these are growing because the business now has scale. Medium term target is 20%. So no, they are not selling £10 notes for £9. They are now strongly profitable at all levels including FCF, which is what I care most about.
hVIVO (LON:HVO) actually has a pretty strong moat - I've described this before so I'm not going to repeat but check out previous comments on that. It's also in the presentations.
hVIVO (LON:HVO)
Thanks for your knowledgeable input David. Does it have bed capacity for further growth if it is maxed out this FY do you know?
Hi AcornInvestor
I believe Mo said they have current capacity to support £70m p/a of revenues versus circa £55-60m now. However, revenue growth that exceeds the £70m would have a good few months notice so they don't need to expend capital upfront without contracted revenue.
Note also that they operate a hub and spoke model. The hub is very expensive to replicate, the spokes can be added quickly and cheaply (months I think). Capacity increase is a new spoke so relatively inexpensive.
hVIVO (LON:HVO)
Anyone willing to offer any thoughts on the huge fall over the course of March. For my part I felt it was way overvalued in the 20s comparing it to better established CROs in the normally pricier US with more stable revenues, so a dip was due. But it’s almost halved. And it’s looking sensible value to me today, albeit not much cheaper than industry-leading comparators for a mere niche-leader.
I know it's just me being old fashioned, but why on earth does it take a £100m market cap company with a December year end until the first week of June to release its results? I imagine many holders have just got bored waiting for the FY22 results announcement :)
All the best, Si
You are definitely old fashioned :)
The market’s not convinced it will go ahead, judging by the 7.75p share price now. It would be tempting to grab the money and run, rather than waiting to see if the bid actually happens.
Unfortunately after 95%+ decline in my thankfully small holding in Unbound (LON:UBG) even after today’s 80%+ increase it would cost nearly as much in commission to sell. So I will hold and hope that it goes ahead so at least I can get out without throwing any more good money after bad! However, I’m with the market having looked at Woolovers web site - doesn’t seem a terribly good fit with their ‘green’ and ‘sustainability’ philosophy. I’m reconciled to losing the lot but it won’t break the bank!!
Journeo (LON:JNEO) Increasingly liking what I am continuing to see here. As expected EPS was 10p with no debt (though it does look like they use an RCF type facility for day to day cashflow management) and the SaaS business growing considerably (+150% in connections to 10,000).
BUT the step change in the business following the acquisition of Infotec this year is material pushing expected EPS closer to 18p and net cash of around £5m. Given the momentum in the business (another material contract announced today) and growing airport demand I feel as though the risk is to the upside on earnings. Accounts look pretty clean too. Although the recently announced contract wins were anticipated the number of them coming through does seem as though management have a good handle on their pipeline and that we can therefore trust guidance.
Nonetheless - hardly an exacting valuation sitting on a PE of 9* for this year and 30p+ in cash. Strip that out and its on 7*
On a general theme at present and to quote some examples OMG, CAPD, AGFX, all have excellent fundamentals and balance sheet, and despite results which were positively received and commented on, the share prices have gone into reverse. Obviously its not just these shares, and I read an interesting article by Robbie Burns about profit taking and then stops getting hit which leads to adverse movements to the downside. I have generally bought shares with a coffee can approach but must admit its not doing me any good. I have held some shares a lot of years now and wish on many occasions had now taken profits how ever little as its not working, as even with companies whose profits, fundamentals have improved over the course of time their share price certainly hasn't. Are fellow investors finding similarly frustrating?
Yes, in a word! Actually thinking of selling everything and coming back when markets improve, or the war in Ukraine ends. Risky strategy but sick of the constant drip down every day
Hi JohnDoe - Think you are invested in a few shares that I hold also, similar thinking here but wish I had done it at the possible outbreak. Could guarantee the moment I sell out the shares they would get taken over with a premium bid though!. I can't understand why some have not been subject to bids already. NXR for example which has looked cheap as chips for years held back possibly by pension deficit a problem though which has decreased, but again although profits, outlook good share price is far lower from its peak. Sentiments appreciated I too are sick of the constant drip down by 2 to 10% even when only a few shares are traded, its never the reverse way around, and personally getting fed up with the way the market is being manipulated to Investors detriment.
Norcros (LON:NXR) is a poor example, proffittpar, a quick check in my Sold Stocks spreadsheet says I sold in 2021, not so long ago, at 331 pence/share. Right now, many stocks are in the doldrums and as JohnDoe insinuates it is all pretty depressing.
Hi Silver Moon - yes you are quite right the share price was at this level and although in profit then, it is a long term hold for me and I thought it was still cheap at this point in time hence a decision not to sell, in hindsight a poor one. One of my problems is deciding exit point as when I do share price normally keeps going up rather than down but should stick to the old adage maybe, its never wrong to take a profit.
Long term holds, proffittpar, are best not neglected in that a selling point is easily missed. My Norcros (LON:NXR) was a two-year hold, most of the holds I have kept for longer were, sorry, are there because they never showed me a gain and I'm still waiting for that delicious moment. Today I look at my peakers: Anglo Asian Mining (LON:AAZ) BAE Systems (LON:BA.) Shanta Gold (LON:SHG) Moneysupermarket.Com (LON:MONY) and decide to watch the BAE Systems (LON:BA.) closely since I'm in profit there and if it twitches, will sell.
I think that's the problem at the moment, there are so many shares that are underwater that as soon as one sees a holding actually in profit, one's instinct is to sell it before it goes the same way as the others!
JohnDoe, Profittpar,
Thanks for sharing your thoughts. I've actually found it quite cathartic reading both these posts as I've been having similar thoughts and it's a real mental test at the moment. My portfolio is only relatively small but the constant red on the screen can be hard to take everyday.
If it's any help, I've been reading articles and watching videos of/by Terry Smith who is a famous investor and even he openly admits he's not smart enough to time the market. I'm trying to take comfort in the fact I have a discilplined process and try (mostly badly!) to pick good companies, with no debt and that actually make money and that overtime this will play out as successful.
All the best with whatever you decide,
Rich
Hi Rich, my main investment policy is of a similar ilk with a strict screening process and criteria using Stockopedia and the valued commentary provided by Paul & Graham with a bit of intuition, dyor of my own. A few small punts in "jam tomorrow" stocks of my own choice, the jam gets further away each day. Paul is right that not many do produce. Despite the frustration I do intend to hold most and not change my policy and keep the faith that in the long term the well run companies will bear fruit. All the best too.
Yes seeing a similar pattern. Argentex (LON:AGFX) I hold, think that is to do with the banking sector, I'm considering topping up. I did sell some of my shares after the recent bounce, such as SCS (LON:SCS), wish I had sold some more. I have found many stocks go wrong, after a good few years, coffee can did not for me. Robbie Burns approach in this market, works better.
Hi Rusty Argentex (LON:AGFX) is one of few shares on my radar currently. Looks decent value
Hi Rusty, agree entirely with your comments that Robbies approach works better at least during market volatility in recent years. Argentex reached nearly £1.40 and still looked relatively good value but a decline of 20% since then even with companies in similar sector providing good results. Reading between the lines a few investors have been extremely annoyed that their stop losses have been taken out at a low price which is maybe the reason why the share price has fallen so significantly for no apparent reason rather than Banking sector which surely can't affect every share.
Any update on 888 Holdings (LON:888)following a record William Hill fine today from gambling commission. Having worked in industry at (Entain (LON:ENT) for a number of years always viewed this as a basket case but the market cap quite low now, debt is killing them. Be good to get Paul/Grahams eyes on it
888 Holdings (LON:888)
its clear any investment here is a 100% crapshot - could easily lose your shirt. Flipside is if they trade well and pay down debt could be easily be multibagger, Probably best left to those who like a gamble and dong mind losing their shirt in the process.
It would be nice to be put out of my Unbound (LON:UBG) misery.
paul, can I just say, the idea of splitting the PODCAST into 2 session 45 min each is absolutely BRILLIANT. Thanks for the effort you put in making them. Much appreciated. Big thumb up.
I'd be grateful for observations on Eleco's finals today Paul and Graham (we hold) as it transitions to a SAAS business. The results seem to have been received with equanimity so far with ARR up 14% TRR 10% PBT 2.9m (down after a non core disposal) and EPS 2.9p (also down) CEO says H1 lower but H2 to accelerate to revenue growth in 2023. Total divs (paid and forecast) 1.28p (2021 .60). Woke comments and their awards follow which are nice to read, they have an ESG committee and are certified as a great place to work. Whats not to like?
Nanoco (LON:NANO) interims in line, however the letter sent from a shareholders group with some pretty serious aligations yesterday might make the analyst call & IMC presentation tomorrow a bit more interesting! Some big questions being asked - rejected by the board of course!
I am also interested in S&U (LON:SUS)
S&U (LON:SUS) are on Investor Meet Company today at lunchtime.
Eenergy (LON:EAAS) released results today.
Given the improved results, outlook and the focus on this sector I think this is worth a look.
My morning smallcap tweet: Unbound approach looks a shoe-in
Journeo (LON:JNEO) £QED Unbound (LON:UBG) Altitude (LON:ALT) Verditek (LON:VDTK) Sabien Technology (LON:SNT) Eleco (LON:ELCO) Bango (LON:BGO), Digitalbox (LON:DBOX), Personal group (LON:PGH), essensys (LON:ESYS), Xaar (LON:XAR)
◄Journeo (JNEO)► wins £1.6m of contracts.C.£1m will be recognised this FY and is included in management expectations. [SP=155.88 Cap=25m]
◄Quadrise (QED)► name change from Quadrise Fuels (QFI). It's non-stop value enhancement here! [SP=NA Cap=NA]
◄Unbound (UBG)► the footwear calamity gets an approach at 10.5p + 1 contingent value right. Cash would be 163% premium. Board minded to recommend if WoolOvers (a play on pullovers I guess} makes a firm offer. [SP=4.08 Cap=3m]. I hold.
◄Altitude (ALT)► wins c.$30m 5 yr contracts, including $8m signed and subject to State clearance. Rev to start in H1 FY24. Guides FY23 Adj EBITDA ahead of market expectations. [SP=41 Cap=29m]
◄Verditek (VDTK)► €168k order to be delivered in the next 12 weeks. It's the first production order following the development phase from this customer. [SP=0.94 Cap=4m]
◄Sabien Technology (SNT)► £422k order for M2G business. [SP=9 Cap=2m]
◄Eleco (ELCO)► FY-Dec rev in line and pretax slightly ahead of market expectations at £2.9m. Outlook in line. [SP=77 Cap=64m]
◄Bango (BGO)► FY-Dec adj EBITDA $5m ($6.1m), ahead of market expectations pf $4.13m. Current trading good, now expects to exit 2023 with $10m of ARR cf $7m guided. [SP=232 Cap=179m]
In line: DBOX, PGH, ESYS, XAR
QED made me chuckle !