Small Cap Value Report ( Tue 29 Aug 2023) - VLE, PTRO, DAL, LIO, BVC

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Very thin pickings today, I'm afraid -
Summaries
Dalata Hotel (LON:DAL) - 374p (unchanged) (£787m/€900m) - Half Year Report - Graham - GREEN
Strong results from this Irish/UK hotel chain with significant improvements in revenues, room rates and occupancy. A comparison with pre-Covid margins suggests that we are fully back to normal here. This is a dividend payer once again and I think it deserves a second look.
Pelatro (LON:PTRO) - Down 79% to 0.668p (£0.6m) - Delisting - Paul - RED
Nanocap software company announces it is to delist. I run through the issues below, and a checklist of warning signs that might indicate a delisting is likely at many other tiny listed companies. Expect a continued mass exodus.
Liontrust Asset Management (LON:LIO) - up 2% to 670.95p (£435m) - Offer for GAM - Graham - GREEN
These shares are up 10% over the past week as news has emerged that the proposed acquisition of Swiss fund manager GAM has met with rejection by GAM shareholders. GAM’s largest shareholder had pledged to support it, but it seems that few other GAM shareholders were keen on the deal (which did seem to be extraordinarily cheap relative to the amount of assets that would be taken over).
I took a neutral view on the planned deal, thinking that the expected synergies and the bump in AUM (from around £30bn to around £50bn) might ultimately benefit Liontrust shareholders. In the short term, however, there would likely be a great deal of complexity, risk and one-off costs of integration. All of those issues are now off the table and the Liontrust investment thesis can go back to being a simple one of cheapness and equity market recovery.
The Liontrust CEO has made a statement admitting defeat, defending the offer made to GAM, and reiterating Liontrust’s strategy to (among other things) diversify its product range.
This isn’t my top share pick in the fund management sector but I continue to view it as very cheap. The StockReport puts it on a PER of 8x with a dividend yield of nearly 11%. [no section below]
Batm Advanced Communications (LON:BVC) - Up 3% to 26.8p (£116m) - Interim Results - Paul - AMBER/RED
There's a good increase in profit, and a perky outlook statement. Although I question whether these figures justify a valuation anywhere near £116m. Bulls are obviously optimistic about the future, and think the big forecast profit increases for 2024 & 2025 might be achievable. A strange, apparently strong balance sheet, but why no divis, if it's rolling in cash? I'm not keen.
Paul’s Section:
£PTRO
Down 79% to 0.668p (£0.6m) - Paul - RED
Proposes cancelling its AIM listing.
This comment is just to close the file on this minnow, which offers marketing software to telcos. We haven’t covered it here since 2019, when it looked half-decent, but performance since the pandemic has badly deteriorated, so it wasn't worth covering here.
The shareholding structure shows that 2 dominant holders control nearly half the company, which heightens the risk of a delisting.
It mentions other reasons for delisting, many of which apply to other nanocaps, so I expect we’ll see many more delistings -
Considerable cost,
Management time,
Legal & regulatory burdens,
Inability to access capital.
Hence it sees these costs as being disproportionate to the benefits of a listing.
Once it delists, a matched bargain facility will be provided to enable shareholders to possibly buy or sell.
Paul’s opinion - I see it as a positive thing that tiny companies which have failed to live up to expectations exit the UK stock market. Many shouldn’t have listed in the first place. A smaller market, but with better quality companies, is what I hope we end up with after the current bear market ends.
The key thing is that we don’t end up holding shares which decide to delist, as they typically crash 50%+ on the announcement. The warning signs (off the top of my head) are -
Tiny market cap - anything below £10m must be a high delisting risk.
Poor financial performance.
Shortage of cash - maintaining a listing costs hundreds of £k’s each year, and is a big hassle. Tiny, loss-making companies can’t afford these costs, especially if they’re running low on cash.
Dominant major shareholders - if a handful of holders own over 50%, then there’s not a lot of point in having a listing, and they often decide to take it private, leaving small shareholders high & dry, and nursing a big loss.
A stale story that nobody’s interested in any more.
Few shares traded.
Lack of access to funding - poorly performing companies are probably finding it difficult to impossible to raise fresh funds from the stock market, in this bear market.
So it’s worth reviewing our portfolios to see if we hold anything that ticks those boxes. As small shareholders, we can exit - but it might involve having to take a haircut on price, and sell in tranches over a few days/weeks. The institutions can’t sell, they’re completely stuck in many embarrassingly poor companies. Hence we have a big advantage, so I’m being much more ruthless about dumping my mistakes these days. It’s such a relief getting mistakes off the screen too, so you don’t have to worry any more. Even if it’s just a few hundred quid, it’s worth salvaging something I think.
Some investors are able to hold shares in private companies, and I have heard of delisted companies subsequently doing well, occasionally. If any readers have any insights into delisted companies that you have held, then I'd be interested to hear of your experiences in the comment section below.
Batm Advanced Communications (LON:BVC)
Up 3% to 26.8p (£116m) - Interim Results - Paul - AMBER/RED
We’ve not looked at this Israeli group so far in 2023. Looking at our previous notes, it did well in the pandemic, and boosted profits from a disposal. Shares have done a big round-trip in the pandemic, and previously went nowhere for years -
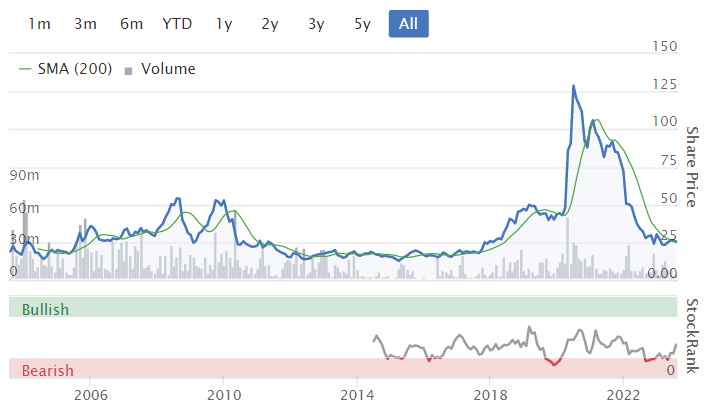
This share has been listed in the main UK market for many years, which helps reduce my anxiety about overseas small caps listed in London (many of which go badly wrong). Dividends have been very sparse over the years - which seems odd, given the large cash pile.
BATM (LSE: BVC; TASE: BVC), a leading provider of real-time technologies for networking solutions and medical laboratory systems, announces its interim results for the six months ended 30 June 2023.
Key numbers for H1 -
Revenue $60.2m (up 5%)
Profit before tax $2.3m (up 130% - very nice) - NB this is adjusted, and excludes goodwill amortisation and share based payments. Statutory PBT is only $0.7m.
Basic EPS $0.39 (up 225%)
Dividends - were paid last year, but seem to have stopped. Why no divis this year, given how strong the balance sheet appears?
Outlook - is in line with expectations -
"Looking ahead, we have entered the second half of the year in a better position than at the same point last year, with sustained revenue momentum and a higher backlog. We expect to deliver year-on-year growth in Networking, with increased revenues from both carrier ethernet and Edgility. Our cyber business revenues are expected to be higher in the second half than in H1 as we ramp up delivery of our large contract won earlier this year. Our Bio-Medical division is also expected to continue to increase sales. As a result, we expect to report year-on-year growth for 2023, in line with market expectations."
The Group continues to have a strong balance sheet as well as property and valuable IP. Accordingly, the Board remains confident in the Group's prospects and looks forward to reporting on its progress.
Balance sheet - looks a bit strange to me.
NAV is $116m. I always deduct intangible assets, which total $19m here. Also there’s a $16m investment in a JV and associate, which it’s safest to write off. That gets me to NTAV of $81m, which seems very strong.
This includes $33.7m cash, plus $8.2m “short term investment in deposits and other securities”, which sounds like it’s near-cash. So that’s $41.9m cash. Yet it also has $5.6m in “short term bank credit”. Why? Surely if it’s sitting on so much cash, there wouldn’t be any need to have bank credit showing as a liability.
Receivables $34m, and inventories of $37m both look quite high, compared with revenues in H1 were $60m.
Shareholding structure - is dominated by Lombard Odier on 28.9%, and the founder (who recently retired) Zvi Marom, holding 22.2%. Possible delisting risk there, if the 2 big holders decide to take it private? It would be interesting to hear Lombard Odier’s take on things, and why they hold such a large position, and seem to have added to it in Dec 2022.

Valuation - many thanks to Shore Capital, for publishing an update note today on Research Tree.
Shore forecasts revenue of $131.6m, and adj PBT $3.4m for FY 12/2023.
Given that it has already done $2.3m in H1, and the outlook sounds perky about H2, it looks to me as if a beat against market expectations could be in the pipeline possibly?
The PER works out at a sky high 82x for 2023 forecasts, so it really does need to thrash that forecast.
Big rises in profit to $6.9m, and $16.1m in 2024 and 2025 are forecast. How realistic is such a massive jump in profitability? Are you happy paying up-front for it?
Paul’s opinion - the valuation looks punchy to me, and I’m not happy with the lack of divis for a company that claims to be so cash-rich.
So I think bulls would need to understand, and be very positive, about its products and future prospects. I’ve not looked into that. Just based on these numbers, I’m struggling to justify the valuation.
Overall, I see this share mildly negatively, so I’ll go AMBER/RED. If it does deliver on the big jump in forecast profits for 2024 & 2025, and does something useful with the cash pile, then I’d see it more positively, so we’ll keep an open mind.
Graham’s Section:
Volvere (LON:VLE)
Share price: 1052p (-12%)
Market cap: £26m
(Graham has a long position in Volvere)
This RNS has come as a complete shock to me and I’m sure to many others:
Volvere plc (AIM: VLE), the growth and turnaround investment company, announces with great sadness that its Chief Executive, Jonathan Lander, died peacefully after a short illness fought with much courage, on 28 August 2023, surrounded by his family.
I only met Jonathan Lander in person on a few occasions - at a couple of AGMs, and at a Mello presentation. But I’ve been studying his work for many years. Of course I would not have made Volvere the largest holding in my personal portfolio, and left it there, if I did not rate Mr. Lander extremely highly, both in terms of his intelligence and his integrity.
In every interaction I had with him, he was generous with his time and a pleasure to deal with. I believe that like us, he viewed investing as something that was not just a career but also something that was fun and interesting. I would always learn something new when he spoke. In many ways I would say that he was a credit to the financial industry and to the City.
Besides his personal qualities, Jonathan and his brother built a company with a tremendous long-term track record. He achieved truly astonishing success and it was well-deserved. He had all of the personal characteristics needed: patience, analytical skills, and unquestionable trustworthiness.
I can’t believe that I won’t get to hear him speak again. My sincere condolences to his brother Nick and to all of his family and friends.
Nick Lander, COO:
"As shareholders and staff will understand, it is with almost unimaginable personal grief and the heaviest of hearts that I write this. Jonathan was not only my business partner for more than 23 years but also my brother and best friend. He was a rare blend of so many qualities - visionary and challenging but always fair. His leadership of the Group was focused on enabling those around him, and throughout the Group's businesses, to achieve their personal and collective potential. This ensured that our shareholders, employees, and our former employees achieved the returns and rewards that they have over such a long period…
"Jonathan leaves in place a strong team with extensive, loyal service to the Group. I know that, in this moment of great loss, the Volvere team will do what Jonathan would expect - to support each other and preserve his legacy.
"For me, this moment is about remembering Jonathan and all that we tackled together - always with a sense of fun - both as brothers and colleagues. His wife and three children, as well as our parents are, and will continue to be, in our thoughts and prayers."
I don’t feel that it would be appropriate to comment further at this time. Rest in Peace.
Dalata Hotel (LON:DAL)
Share price: 374p (unch)
Market cap: £787m (c. €900m)
Dalata Hotel Group plc (‘Dalata’ or the ‘Group’), the largest hotel operator in Ireland, with a growing presence in the United Kingdom and continental Europe, announces its results for the six-month period ended 30 June 2023.
It’s nice to see this hotel group performing well: revenues are up 29%, although there is no increase in PBT (€50.4 million in H1 this year, vs. €52m in H1 last year). Having checked the footnotes, I think the primary reason for this is that last year’s results benefited from more positive property revaluations going through the P&L:

Operationally, occupancy is up from 70% to 78% (using rounded figures) and the average room rate is up 10%, which is reasonable given inflation.
The combination of higher occupancy and higher prices means a 23% increase in revenue per available room. Excellent!
Dividend: we have a 4 cent dividend per share, the first one since pre-Covid.
Gearing: sounds low with 11% LTV (using net debt).
Gross borrowings on the balance sheet are €265m, plus another €657m of lease liabilities (these are measured at their present value). So the balance sheet paints a slightly different picture than the 11% LTV quoted by the company. About 55% of the company’s assets are financed by equity, with the rest being mostly financed by leases and financial debt.
Overall, the company seems to be financed in a conservative way. Rate risk on their outstanding term loan is hedged until October next year. Importantly, most (31) of their 52 hotels are owned outright.
Balance sheet equity is €1,347 million (£1.15 billion), nearly all of it tangible, offering a good premium over the market cap. They have gained from the further revaluation of properties over the past six months, and of course readers may differ on whether hotels have increased in value over this time!
Properties: they have added two London hotels so far this year, and Maldron Hotel Shoreditch will be ready in Q2 2024.
Outlook: after a “very successful start”, they are “optimistic” for the remainder of the year.
Gas/electric is 80% fixed until December 2024, with a cost reduction expected in H2 vs. H1.
On travel numbers:
Recovery of international travel, including resurgent UK Airport traffic statistics and record numbers at Dublin Airport, provides a positive backdrop for the markets in which we operate. While we continue to monitor potential slowdowns in demand as a result of high inflation levels, we are not seeing any such indicators.
CEO comment is very positive, describing performance as “exceptional” and pointing out that the “EBITDAR” margin (EBITDA also excluding interest on lease liabilities) has improved by 1% compared to 2019.
Graham’s view
We don’t discuss this one very often (last mentioned August 2022) but as a customer I’m a fan of the Clayton brand. I haven’t stayed in a Maldron but the reviews I’ve seen of hotels under that brand are also very positive.
As an investment, I continue to think that this looks interesting. It’s still not particularly expensive either on earnings or in relation to the balance sheet (true balance sheet value is of course highly uncertain).
Stockopedia’s computers have noticed some attractions:
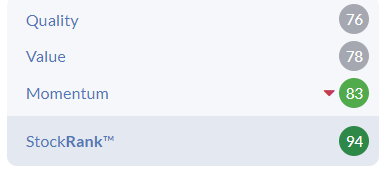
It’s now paying a dividend again, in a strong sign of a return to post-Covid financial stability.
Trading at a PER of about 10x, without excessive leverage, and with interest rate and gas/electricity price risks seeming carefully managed, I’ll take a positive view on this.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Greggs (LON:GRG) has exactly the same issue as 4imprint (LON:FOUR) because the results have a date of 31.12.22 and not 1.1.23, the system is not picking these up. Wickes (LON:WIX) is the same.
I understand these have been reported to Stockopedia months ago but still have not been sorted.
Braemar (LON:BMS)
Belvoir (LON:BLV) (I hold)
For any interested, here is a short video from the CEO of Belvoir that was published today.
Around minute 3:00 it sounds like he confirms that the business is probably slightly ahead of management expectations.
At the very least it doesn't sound like there's a profit warning on its way.
A
Dalata Hotel (LON:DAL)
Thanks to Graham and other commentators on their thoughts here.
I hold and must admit to remaining baffled by the seemingly low valuation.
Share Price Floor
Tangible Assets = c.€1.3b-€1.4b
Cash Generation
I don't know Dalata Hotel (LON:DAL) well. I looked briefly yesterday and it seems fairly obvious imo that the valuation would be modest given our current environment. Its growing assets, cash flow AND liabilities. Implicit in the price of much of UK and Europe stock prices is lack of confidence in the outlook. The combo of growing liabilities to be met by volume and price of hotel rooms sold in environment that fears an 'inevitable' slow down to crisis isn't going to get generously priced due to feared procyclical effects. Handwaving, I'd say the current price (11x forecast earnings and not huge discount to asset value and it being smaller, less global and less well established than something like Intercontinental Hotels (LON:IHG) ) in fact reflects rather positive relative glow for the company and a degree of belief in their growth model...
So may be a great buying opportunity as you say...lots of good reasons...although I always feel the property value argument is a little cake and eat it as when that counts as a backstop the times are already probably a bit tougher and the value realisation may be over a barrel...whereas as if a sale and leaseback sort of thing is struck then its probably at a time when things are going pretty well in a general market sense and price already reflects that.
Dalata Hotel (LON:DAL)
Thanks for the response Mojo.
Understood regarding the weak outlook.
I'm not sure I understand the rationale in looking at the liabilities - which I presume relates to the increasing leasing costs - when cash generation is so high, non-lease debt is minimal and there are a lot of tangible assets on the balance sheet.
Incidentally on the call yesterday the company emphasised their desire to do more leasing going forward rather than buying buildings outright.
Let's see what happens. Fingers crossed.
A
abtan-I also hold and have for 2 years or so. The spread is wide- but to buy I just use a limit price just above bid. Seems to work more often than not. It does look very lowly priced by the market.
Anyone know why Castings CGS has been declining recently?
I’m hoping its just a pullback to a level of support which is where I had my alert set and subsequently bought in. No news that I can see, excellent fundamentals.
Thanks LeicesterPete, I'm hoping that too! Had a good trawl around the bulletin boards and couldn't see any recent comment.
On a positive note, the "Tags" for each article seems to be working now. I check each report at the weekend, and lately I've not had to re-input tags which disappeared. Keep your fingers crossed that it's a permanent fix :-)
Microcaps delistings
This is a really interesting scenario.
I have a big holding in a microcap and I actually suggested to them a few ago that they should delist as from a company performance their listing was totally pointless .
Delisting would save then circa 150k a year on feee (I thought it was higher)
It would give the CEO much greater flexibility and agility which is key for a business their size .
This company is in a tough spot at the moment but the long term business case is excellent and they are stacked with cash close to market cap and assets above market cap .
What I was really surprised at was it seemed quite difficult as the Rules prevented to majority founder having an active vote .
Meaning that the 75% required excluded his votes so it would be down to the 2nd to 5th shareholders to vote .
Given the company is stacked with cash it seemed easy enough to introduce a trading mechanism that would satisfy all shareholders so either
- take it private and keep your shares and “own” a share of a private company which is in an improved position with better flexibility and an annualised cost saving of 150k , plus have a defined cash reserve set to one side to allow shareholders chance to exit at a pre agreed pricing mechanism cash funds allowing
Or
- vote against and maintain a pointless totally illiquid shareholding in a value trap in a market that is totally disfunctional and waste 150k a year
From my perspective total no brainer and I would be happier in a private company with a clearly defined mechanism for selling as opposed to locked in a totally illiquid value trap whose agility is killed by AIM regulations .
This case may be isolated as I am 100% comfortable with the intentions and honour of the majority shareholder and founder and I know he wants to do well for his shareholders and not himself .
I’m not at liberty to name the company
Talk of Pelatro (LON:PTRO) here today jogged my memory of a very impressive presentation by the CEO and I found it here:
That was at the end of 2018. Mercifully I did not buy as a result of just watching that but decided to sit back and look for signs of the stellar take-off. The rest is history:
Coincidentally I reported the data issues with 4imprint (LON:FOUR) at the weekend. After a bit of to and fro I got them to see that they are showing the last reported figures as the estimates for this year! Which also means that we can't see any forecasts for FY25 because the columns are wrong. They said that they would look into the problem.
The actual results are not the same those 2023 estimates, both estimates (revenue and profits) are under the actual results. If they are not showing the results, then the Stockopedia rankings, have not been updated for ages?
I ended up holding shares in a company that delisted. I thought I had instructed the broker to sell, but hadn't. After a few months I got a letter from the company making a low ball offer for the shares, but I turned it down then got another offer, I turned that down and then a third offer which gave me a 20% profit. So I took that.
Dalata Hotel (LON:DAL) I work in Dublin fairly often and live about 3 hours away, and have stayed in their hotels. They always do the job and I am a repeat customer.
However, the cost of a hotel night in Dublin at the moment is seen by my friends as being unaffordable, and many have stopped staying overnight for concerts etc.
Demand might keep the prices and occupancy rates high, but I do wonder if the high rates + cost of living costs continues and brings some reduction over the next couple of years.
A friend of mine tells me that a lot of hotel rooms in Dublin are being used for Ukrainian refugees. So room shortages and therefore high room prices. I was going for on business and some friends wanted to come- cost put them off.
The Ithaca Energy (LON:ITH) dividend yield is not 11% but about 14% ITH goes ex dividend this Thursday. It’s announced in dollars but once converted to £ it’s about 10.5p. What’s more they intend to pay another dividend the same size later this year to give a 14% yield (and that yield excludes the similar dividend paid in March).
The site below is excellent for dividends including ex dividend dates, the latest dividend and the yield from that dividend as well as pay dates and several other headings well . Even the MORE heading is good for quarterly and monthly dividend payers and dividend cuts. It’s updated every day and is much more reliable for dividend yields than Stockopedia. Also key in the code for any share (e.g Ithaca Energy (LON:ITH) ) to access the dividend history for that share. The link is to the general ex dividend dates section which of course includes every UK share or Investment Trust going ex dividend this Thursday,
https://www.dividenddata.co.uk...
Ithaca only came to the Market last November. Their recent Results looked good bearing in mind the windfall tax and North Sea Oil policies of both Cons and Labour. The share is down around 35% over 1 year and is almost at the lowest it has been.
Ithaca looks cheap. PE4 and Stockopedia 96 rating for value. I bought today.
Ken, the tiny free float is putting me off. I suppose a big fund raise followed by a buying spree might be an alternative to a de-listing. Is this a possibility?
Silver, agree with you re-Ithaca Energy (LON:ITH) massive shareholding by DKL. 89%. Why did they float? Do they need the official position/standing for partnerships internationally? The divi at 20% for this year is very tempting though and 15% forecast for next year too.
Thanks for the replies Silver Moon and sevenccc. I agree that the 89% held by DKL. is a negative but don’t understand why they would need a big fund raise as an alternative to delisting. Perhaps you or sevenccc could further explain? I.e I can’t fathom why they need a big fund raising, nor why it’s an alternative to delisting as why delist so soon after floating? I realise I might be missing something obvious.
Some important data about Dalata Hotel (LON:DAL), looking at its marketcap I couldn't believe how illiquid this share is: over 10% spread and average daily volume: 1500.
Graham said the price is unchanged today, which is true, because there was no trades at all. So keep on eye these things if you are planning to do more researches - for me these are enough informations to avoid it.
Great point DonQ. The shares are actually dual-listed and should be more liquid on Euronext Dublin (up 9% there today). G
The spread is crazy wide,I bought a while back and plan to hold. Hopefully they will do something to improve the liquidity. I have emailed IR pointing this issue out.
On Liontrust Asset Management (LON:LIO) Graham what do you think of the position re. the £9m secured debt facility? Basically, if GAM doesn't get securely refinanced with CHF 25m later in the month, then I am now wondering whether Liontrust are still in a position to pick up some of the business at a later date. The CHF 25m is only enough to repay Liontrust, but only about a quarter of the funding required. Just a thought given all the fund managers at GAM are behind Liontrust. I am not totally convinced that it's all over!
EDIT
See GAMs announcement - looks like the other party is confident of sufficient funding being forthcoming, so maybe its more whether the GAM investment managers may defect?
http://newsfile.refinitiv.com/...
Pelatro (LON:PTRO)
Great play by the directors...bravo! Bravo!
List with a supposedly rapidly growing business operated in India and with clients in mainly frontier and developing markets with generous payment terms giving rise to large receivables (often not yet billed) and the pressure on cash flows that brings. Post IPO tap shareholder a few times including just a few weeks before the decision to delist. Note the new investors seem to be 4 individuals based in Middle East...again all a bit obscure...and rather fortuitous that these charitable fellows are willing to lend a hand...
Then sink the share price and take ownership of the generously funded speculative business at very little cost. They are going to pay to take the stump holdings off of you...so they think there's something useful left.
Along the way the directors decided to pay themselves in kind...very kindly billing fancy motors to the company. Supposedly normal in India for tax reasons etc (I don't know...but its a UK company so what counts is normal here).
If you bought this at any point in its journey (and you're not a short term trader sort) then you need to reality check your analytical work and the amount you do before committing to buy.
I'm not a fan of idea that investors need to be protected from every dodgy/rubbish failed company...but there is always a case for regulators and stock exchanges to look at cases where it looks like rules could have been broken, accounting/reporting has been misleading and some element of insider trading may have taken place...
Pelatro does and has always smelled funny
PS brokers and promoters who handled this company should be made to do some sort of walk of shame. We know these guys are not to be trusted (just a fact rather than a slur!)...but there's flaky and then there's extremely eye watering dodgy
Agree 100% with came across this article Re Mr Menon
https://www.forbesindia.com/ar...
Centrica
I know this site mainly discuss the small caps but the share price of CNA nicely shows the strength of momentum both ways. It peaked at nearly 400 in 2013 and drifted downward to nearly 30 during Covid. Trying to catch a falling knife for 7 years was a disaster for investing.
Since 2020 It has gone up relentlessly and continues . Distrust and Disbelief has proved unwealthy!
Stocko rating is the icing of the cake: 99, 99, 77,95
Centrica (LON:CNA) is a perfect example of avoiding downtrends and buying only when an uptrend/earnings increase begins.
Why anyone would want to carry on holding since 2014 is beyond me but there you go (probably spend all their time moaning on ADVFN) theyd have been down over 90% at the lows. Much better to go nowhere near it, leaving fund managers to pull their hair out. At a very basic level price follows earnings, as forecasts since 2014 show.
EPS forecasts started to fall 2014 and continued falling for 7 years. Started to rise again beginning of 2022, by which time the chart was already in a stage 2 pattern and up 100% from the low. From there you get into an upgrade cycle, investors/funds buy more, traders move in, PE rating increases, momentum traders join in. Theres so many battered share prices out there- provided US markets dont fall off a cliff and macro improves- I can see more of these emerging in the next 12 months.
Has anyone else noticed that at least 4 companies whose year end falls on 1st January 2023 have not been updated despite results having been announced in March and April ; Greggs (LON:GRG), National World (LON:NWOR), Wickes Group (LON:WIX), and HSS Hire Group (LON:HSS). In addition, some forecast information for these companies shows figures for 2022. I have sent several messages reporting this but nothing seems to happen. I rely on Stockopedia for basic information to identify possible investments for further research and correct and up-to-date information is a necessity.
Hi Kanddas. I complained to Stockopedia about the same problem with 4Imprint over 7 weeks ago. But the error is not corrected yet. Stocko subscribers like me are left unable to analyse the shares which are suffering from data errors. Stocko blame Refinitiv for the problem. My take on it is that Refinitiv is a massive company which is in a monopoply / oligopoly position and they really could not care less about these data errors. Reading between the lines, Stocko are struggling to get anywhere with Refinitiv with this problem because both Stocko and Refinitiv both know that Refinitiv could easily say to Stocko "If you don't like it, then you can lump it!" It's hard to see a way forward with this. Maybe Stocko should suggest to Refinitiv that Refinitiv could pay £200 to charity for every data error which Stocko subscribers have brought to their attention? The fact is that Refinitiv should not be making these mistakes, and Stocko subscribers should not have to keep pointing the mistakes out.
Just looked at 4imprint (LON:FOUR) last annual results on Stockopedia were 1.1.22, yet in the accounts, they have interim at 31.12.22 and an interim at 1.7.23, so is this a Refinitiv mistake?
Who do Sharepad use because they don't seem to have so many problems.
I get the impression that Stockopedia are short staffed, queries are taking ages to be answered or fixed.
Every time I complain to Stockopedia about data errors such as this, they tell me that the problem is caused by Refinitiv and I believe them.
But Stockopedia are choosing to use Refininitiv. So ultimately, all data issues are Stockopedia's responsibility.
I remember Ed once saying that Stocko raised more queries with Refinitiv than anyone else. However there is more that Stocko could do to help itself. On July 28th I sent this via the green button:
"Experian declares dvidends in $ but on request pays in £ with the conversion rate being announced a couple of weeks beforehand. On your page https://www.stockopedia.com/share-prices/experian-LON:EXPN/dividends
You show the $ rate for all except the 3/2/23 payment where you show the stirling amount making your graph ridiculous as it takes 1p = $1 !!!
Can you replace the amount with 17c and then all will be well. All you need do is take it from here https://www.investegate.co.uk/announcement/rns/experian--expn/first-interim-dividend/7435435 - please don't refer it to Refinitiv or I suspect you will be waiting weeks".
Here we are A MONTH LATER AND NOTHING HAS BEEN DONE yet what I asked for was just one figure to be changed, clearly there in the referenced RNS. I don't think Stocko has sufficient capacity to keep everything up to date.
Some of the errors are nothing to do with Refinitiv, it seems shares splits can really muck up their figures. Yes some of the issues are due to Refinitiv but not all.
Really the Stockopedia figures should be updated, within a few days of the results, some are over 6 months overdue. This not only affects that stock but every other stock.
Maybe they should have a warning, if overdue?
I did follow up on these stocks and 4imprint (LON:FOUR) and this is the reply from the Helpdesk: "We are aware of this issue. Essentially, there were some changes on Refinitiv's end that the code base hadn't accounted for.
Unfortunately, the required changes on our side to get these to match up again are a bit more complex than we had originally anticipated. We have had several meetings internally to discuss the best approach here though, and this is being prioritised over other work.
We hope to have a promising update for you in the coming weeks."
Many thanks to the 5 subscribers who responded on Friday to my post about Averaging Down and in particular Simoan with 73 Likes and Wolf of Small Street with 19 Likes.
Primarily I am an Investor but I do trade sometimes when I see a Share is oversold as happened last Friday when I held Watches of Switzerland (LON:WOSG) for only 5 hours.
I used to be overley cautious but now I have built up my pot I tend to take more risk which in the current market has not been very clever.
Over the weekend I re read parts of Mark Minervini's book Trade Like a Stock Market Wizard which I highly reccomend and he says "never let a loss grow larger than your average gain"
Brilliant advice but quite hard to do unless you are ruthless in abiding with the rule.
Likewise, see myself as a long term investor but happy to complement this with some short term trading when opportunities present themselves - at the very least this should help diversify your returns, since very short term trading should be largely uncorrelated to longer term market trends.
For instance, picked up some Watches of Switzerland (LON:WOSG) on Friday and sold today for 10% gain - that's basically 2 years worth of dividends you'd get on a typical FTSE 100 share, which I don't think is bad.
I used to be overley cautious but now I have built up my pot I tend to take more risk which in the current market has not been very clever.
To me, this is counter intuitive. I took on risk for many years to generate a pot big enough to retire early and comfortably live off for the rest of my life. As such, I have spent the last two to three years substantially dialling down my portfolio risk (if we assume the meaning of risk is the risk of permanent capital loss rather than the slightly ridiculous definition used by the Stockopedia "Risk Rating").
Anyway, good luck with whatever you decide to do but it seems from your last couple of posts that you maybe need to decide what type of investor you are and define what your ultimate financial goal is and plan how best to get there whilst minimising risk.
BTW Horrible news about the CEO of Volvere (LON:VLE) today. Another jolt to remind us to get on with life because you don't know what lies just around the corner.
All the best, Si
Any gamers here have a view on Frontier Developments (LON:FDEV) ? Price in free fall recently. Stocko valuation metric is good. Also passes 2 long screens. Is there a big seller or just worries about future games success?
I'm no gamer and no expert on company but, from what little I've gleaned, I think that gamers think their latest two big games (that they'd alot of hopes resting on) are not good at all. Their F1 management game has been plagued by problems, poor sales, and need to continually update it as a result and their Games Workshop game has been in testing with gamers and reviews are v poor and thus launch has been delayed. They've taken on huge number of new staff in recent years (doubling staff count from memory in just last few years) and I think market is bit worried about cash burn as a result. As with alot of games developers, they tend to capitalise alot of dev costs, so if this run of poor games continues then there could be some ugly writedowns. They face usual games developer problems, they're reliant on their few releases being hits. They tried 3rd party gaming publishing and that was a flop & they had to close that down recently plus new CEO has taken over at worst possible time with long term founder stepping back. The CEO has been at company a long time and was integral to development of recent new games that haven't worked so that hasn't helped sentiment either. I don't follow the company that closely but they must have some valuable residual IP & they've got a good back catalogue of games that were successful & still provide steady sales.
Not a gamer but I've been watching the precipitous fall in Frontier Developments (LON:FDEV) with interest too. I hate bottom fishing and I'm acutely aware of the "never catch a falling knife" adage. Nonetheless, this is an astonishing plummet for a stock that was 10x the current price just a couple of years ago with virtually no dilution. Revenue is forecast to be £108m next year which is triple what it was doing around 2017 and 2018. But as the saying goes, revenue is vanity and profits are sanity.
My feeling is that this is simply a dramatic re-rating for a business that is now loss making and forecast to make an adjusted EBITDA loss of £5-10 million next year.
When even your adjusted bullshit measures of profitability are negative, the current market will be brutal.
I wonder however if this is a value opportunity for a medium term play - it's still founder led by the widely respected David Braben who holds 32% and the upcoming Warhammer releases and other quality titles could support a turnaround when wider sentiment improves.
I'd also love to hear from anyone with any insightful views on this one. I'm tempted to start a position at these levels.
revenue is vanity and profits are sanity
My ex boss used to add
Only cash is reality
I used to listen to him and his mates tell war stories from the early 70s about the lights going out and planting enough veg to be largely self sufficient and praying they would be able to pay that weeks wages.
Altogether too many (small) businesses are failing not because the business is a bad model or badly managed but because the owners have never known a time when they could not easily access working capital as needed.
Hence my deep appreciation for the green label = ... and reasonably well financed ...
“Talk is cheap cash buys houses”
Frontier Developments (LON:FDEV) FDEV (I Hold – Opened a medium size position last Friday)
Lot of negatives here - FY23 and FY24 are going to look terrible compared to the previous years. I reckon FY23 will record a loss of £12M and FY24 slightly lower. They have enough cash to cover the loss for 2 years. A new CEO. Foundry model was a disaster. Good they stopped it and fired all the contractors. Full year report in September should give current employee headcount. F1 Manager 2023 – metacritic reviews are not great. No need for upgrade from F1 2022 as no big changes. Also lot more bugs on some of the releases last year.
Despite all this issue, one of the main reasons for opening a position here is 9% holding by Tencent. Tencent has roughly similar size holding in 16 UK companies (Predominantly gaming, full list provided in their fact sheet) and also has stakes in Ubisoft, Activision and Epic. Tencent gaming has been trying to become the mega sport launchers (like EA for FIFA, 2K for NBA). FDEV acquisition can help them to do so with one of the biggest sports through F1 manager. I held SUMO in the past which was acquired by Tencent for £900M. Portfolio of games from FDEV are superior (in my opinion) compared to SUMO and with the marketcap of sub £140M I think it should be in their radar for consideration. When Tencent acquired SUMO, FDEV was at £1.4B market cap and now trading at one tenth of that. Tencent may or may not buy FDEV but i like the risk reward here.
Good luck to holders.
Cheers
Nesh
Swedbank sold a few on the 18th. Wonder if they're liquidating Frontier Developments (LON:FDEV)
Frontier Developments (LON:FDEV)
Not sure I would want to buy shares in a company based on a chance of a take over.
Are the stocko metrics correct giving it a quality rank of 96? Stocko has it's forecast down to make a profit next year but if you look at Zeus's last report they have FDEV not making a profit until 2025.
Current big game out is their F1 game, full of bugs and missed revenue targets.
Next big game out is Warhammer-Realms of Ruin due out on 17/11/2023. Obviously Warhammer is very popular but it does seem people who have played the beta/alpha are not overly impressed, especially with the price tag of it. If it doesn't live up to their hype then sales forecasts are going to disappoint.
The last holdings RNS was showing Swedbank Robur Fonder AB reducing it's holding to 6.9%, will they be selling more to 0%?
Technically it looks poor apart from it is now priced at 330p, just above major support which is where I'd buy at if interested.
Frontier Developments (LON:FDEV)
This is what Zeus said in June-
"Forecast downgrade: We are disappointed that the company did not at least modestly outperform consensus expectations and provide a more upbeat outlook, since we thought guidance was conservative and included the proverbial kitchen sink. We lower our estimates to be in line with company expectations, but we see potential for outperformance given our confidence in FDEV’s strategy and track record of producing high quality games."
The charts an abomination. Someone's aggressively selling. Results in Sept, its a brave man who holds into them without something changing
The charts an abomination. Someone's aggressively selling. Results in Sept, its a brave man who holds into them without something changing .
Hence why I’m not buying. Especially since Zeus predict no profit until 2025!
Another financial services acquisition by Belvoir (LON:BLV) . According to CEO, Dominic Gonsalves, the price paid reflects the current depressed state of the housing market. I hold.
"Belvoir Group PLC (AIM: BLV), a leading UK property franchise and financial services Group, is pleased to announce that, in line with its continued growth strategy, it has acquired MAB (South West) Ltd ("MAB SW"), a financial services business for a cash consideration of £1.0m. This follows the earlier acquisition of BMA Bristol Limited ("BMA") in June 2023 for £1.1m in cash (together, the "Acquisitions").
Background
BMA and MAB SW both trade as the Mortgage Advice Bureau and are appointed representative firms of Mortgage Advice Bureau, the wholly owned subsidiary of AIM-listed Mortgage Advice Bureau (Holdings) plc ("MAB"), one of the UK's leading networks for mortgage intermediaries.
The Acquisitions provide mortgage and related financial services to clients through a combined network of 41 highly motivated advisers, all of whom are self-employed with MAB providing training, support, compliance, website and national marketing via the wider MAB brand. With BMA based in Bristol and MAB SW based in Plymouth, the Group has extended its reach across the South-West.
Further details of the Acquisitions
Belvoir has acquired the entire issued share capital of BMA and MAB SW, through its subsidiary Brook Financial Services Ltd ("Brook"), for a total net consideration of £2.1m, settled in cash from existing cash reserves. Tim Wood, Brook's Financial Services Director, will manage both businesses, overseen by Michelle Brook, Managing Director of Brook and Executive Director of the Belvoir Group PLC Board.
Financial information
In the year to 30 September 2022 MAB SW had revenue of £1.5m, pre-tax profits of £0.1m and net assets of £0.2m. In the year to 31 December 2022 BMA had revenue of £1.8m, pre-tax profits of £0.3m and net assets of £0.1m. The Acquisitions are expected to be immediately earnings accretive adding around £0.6m p.a. to Group profit before tax."
Just a quick correction about the CEO of Belvoir (LON:BLV): Dorian, not Dominic. ☺
Good spot Don. Embarrassing for me as I have met Dorian on at least two occasions.
Belvoir (LON:BLV). I hold but downsized during Covid and foolishly didn't reinvest when I should have done. Maybe not too late. I really like the sensible management style here, not trying to race but making good pragmatic acquisitions. Seems to me that they have now built a good reputation for integration. Nice divi too.
Mark
Terrible news from Volvere (LON:VLE) that co founder Jonathan Lander has died at age 55. We have lost a good one.... sincere condolences to the family.
Nick Lander has taken over responsibility for Volvere (LON:VLE) and further appointments will be made. Volvere (LON:VLE) is awash with cash and available for sale investments £20.4m.... which compares to a mkt cap at the close of £27m. This attributes very little value to Shire Foods where Nick has always been the operational guy. The company has been buying back stock and clearly could do more should the shares weaken materially. A little early to speculate too much what might happen here, but the discount to NAV should provide support and the business is in good shape.
Great weekend podcast Paul - thanks.
I've historically avoided large contractors but will look again at Costain.
One issue that keeps coming into my mind (perhaps other readers too?) is the value in small cap versus some of the large(r) caps.
All readers know there is abounding value in plain sight in smaller caps but what of the argument that there are also large caps offering equally enticing value, absent the small cap liquidity issues/risk?
So, are small caps priced so that they have a sufficient large liquidity premium (i.e. valuations at a discount to large cap peers) to the extent a look-across is possible?
Its a point I've been pondering, conscious that sales of very small volumes in individual companies can shunt down the small cap prices or conversely is that another source of opportunity for the brave?
Interesting announcement from hVIVO (LON:HVO) this morning:
“hVIVO plc (AIM & Euronext: HVO), the world leader in testing infectious and respiratory disease products using human challenge clinical trials, announces its plans for a new consolidated facility at the fast-growing life sciences hub in Canary Wharf, London. The expansion, largely funded by hVIVO clients, comes in response to the Company's growing orderbook and increasing demand for its human challenge trial services.”
Good to see expansion is to be part funded by clients. This bodes well for the future, indicating increased need for the company’s services , at reduced costs. (I hold)
Yes an interesting announcement. Clearly clients are keen that there is sufficient capacity at hVIVO (LON:HVO) to avoid waiting for available slots, which bodes well for contract wins and revenue growth in the short to medium term. Otherwise they wouldn’t have predominantly funded the expansion in my view.
My morning smallcap tweet: Despicable Fee
Minoan (LON:MIN) RM (LON:RM.) Literacy Capital (LON:BOOK) Faron Pharmaceuticals Oy (LON:FARN) Grafenia (LON:GRA) Volvere (LON:VLE) Polarean Imaging (LON:POLX) Fusion Antibodies (LON:FAB) Pelatro (LON:PTRO) hVIVO (LON:HVO) OptiBiotix Health (LON:OPTI) Argo Blockchain (LON:ARB)
◄Minoan (MIN)► repays half of £1.4m loan to DAGG by issuing shares at 1p, an 11% premium. Balance extended to Dec 24 for a £175k fee, an astonishing 25%. [SP=0.87 Cap=7m]
◄RM (RM.)► extends covenant waiver to Nov 30 test. [SP=62.54 Cap=52m]
◄Literacy Capital (BOOK)► June book value (geddit?) 488.5p /sh up 21.2p since Mar. [SP=484 Cap=294m]
◄Faron Pharmaceuticals (FARN)► gets FDA Orphan Drug Designation for Bexmarilimab in Acute Myeloid Leukemia. [SP=262 Cap=179m]
◄Grafenia (GRA)► £23m placing at 8.5p, a 17% discount, to buy back bonds, pay deferred considerations and fund future acquisitions. Trading in line. [SP=9.52 Cap=12m]
◄Volvere (VLE)► CEO Jonathan Lander has died. Nick Lander (COO) will assume Jonathan's responsibilities. [SP=1205 Cap=28m]. I hold.
◄Polarean Imaging (POLX)► US Medicare & Medicaid issues reimbursement code for XENOVIEW. Payment level TBD. [SP=15.12 Cap=33m]. I hold.
◄Fusion Antibodies (FAB)► first order for AI/ML-Ab (pronounced AIM-Lab would you believe) services. No £££. [SP=6 Cap=4m]
◄Pelatro (PTRO)► proposes delisting. Blames usual suspects. [SP=3 Cap=3m]
◄hVIVO (HVO)► plans for a larger consolidated facility, largely funded by clients,. [SP=17.5 Cap=119m]
◄OptiBiotix Health (OPTI)► general update including £116K order for SlimBiome. [SP=27.95 Cap=25m]
◄Argo Blockchain (ARB)► H1-June - more value destruction by burning electricity. $18.8m loss on $24m rev. [SP=8.86 Cap=59m]
An in line trading update hidden in Somero Enterprises (LON:SOM) board change announcement this morning.
"As reported in the 24 July 2023 trading update, the Board is confident that the results for the full year will be in line with market expectations. The Company will announce its interim results on the 31 August 2023."
The current President is stepping down from the role, being taken over by the current CEO, who previously held the dual role for 25 years. So hopefully not too much of an issue? (I hold SOM).
hi Phil P
re Somero Enterprises (LON:SOM)
The current President is stepping down from the role, being taken over
by the current CEO, who previously held the dual role for 25 years. So
hopefully not too much of an issue?
I wouldn't be so sure, for the following reasons;
1. The President (John Yuncza - aged 52 ) had already 'stepped down' rather abruptly on the day before the RNS announcement with no reason given for his departure.
2. The current CEO (Jack Cooney - aged 77) is taking on the interim dual role of CEO / President. Quite demanding at 77 perhaps?
3. The non-Exec Chairman is a sprightly 89 years of age so the board is looking rather aged.
4. The company have been quizzed on previous results presentations regarding succession planning and have always said they regularly have the topic under review. Given they are only now commencing a search for a replacement President this departure looks rather sudden.
5. Reading between the lines it rather looked like Mr Yuncza was the man being groomed for the top job having joined as CFO in 2015. If that was indeed the intention then something appears to have gone badly wrong.
I hold.
Snazzy