Small Cap Value Report (Tue 29 June 2021) - D4T4, TAST, MER, APP, CSSG, ELTA, VARE

Good morning, it's Paul & Jack here with Tuesday's SCVR
Timing - today's report is now finished (15:07)
Agenda -
Paul's Section:
D4t4 Solutions (LON:D4T4) (I hold) - a quick review of its FY 03/2021 results. Numbers look in line, or ahead, depending on which forecast you're using. Very strong balance sheet. Difficult to value. Certainly not cheap on a PER basis, but the software seems to have great potential.
Tasty (LON:TAST) (I hold) - trading update from this minnow casual dining chain. Trading well since re-opening, but no figures given. Reminds us of the many headwinds the sector is facing as things normalise.
Electra Private Equity (LON:ELTA) (I hold) - my notes from today's Capital Markets Day (online). Comprehensive information provided about the forthcoming float of (TGI) Fridays restaurant chain. Looks a really good business to me, and I think ELTA shares remain a cheap way in.
Various Eateries (LON:VARE) - my brief notes from an online results presentation today. Interesting company, and good concepts, but impossible to value at this stage.
Jack's Section:
Mears (LON:MER) - a solid update from this housing services provider, but financial and business risks remain so it's hard to see a great deal of long term upside.
Appreciate (LON:APP) - disappointing results and short term outlook statement but management appears to be creating a more focused operation that is investing for future growth, so could be worth researching on share price weakness.
Croma Security Solutions (LON:CSSG) - micro cap, so liquidity must be considered. Good trading momentum though and nearly half of market cap in net cash.
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
Paul’s Section
D4t4 Solutions (LON:D4T4)
(I hold)
395p (yesterday’s close) - mkt cap £160m
Preliminary results & board changes
D4t4 Solutions Plc (AIM: D4T4, "the Group", "D4t4"), the data solutions provider, announces its preliminary results for the year ended 31 March 2021.
I last reported on D4T4 here on 1 April 2021, with its “comfortably ahead” trading update for FY 03/2021. That led to a rise in broker consensus forecast, which Stockopedia is showing as 9.65p. Actual fully diluted adjusted EPS has come out at 9.52p, down 15% on last year.
There’s a broker update from Finncap out this morning, which shows the 9.5p adj EPS as being a 14% beat against its own forecast.
Revenue is as expected, at £22.8m.
Adjusted profit before tax is £4.45m (down 12% on last year).
Not madly exciting then, with profit being down on last year, but the context is a poor H1 (loss-making), with the shortfall being recouped in H2, which has happened before with D4T4. Although it’s increasing annual recurring revenues nicely, it also seems to still be heavily dependent on H2 contract wins, as in the past.
Divis - small, and not really what this share is about, it’s a future growth company.
Current trading - in line with expectations.
Directors - both the founders are retiring, and a new CFO is being sought. I don’t know whether that’s significant or not.
Outlook -
The Board remains highly confident in the Group's strategy; our underlying business is delivering against our key KPI's and performing well, and D4t4 is well positioned in its key markets. The current revenue visibility, order book and pipeline of opportunities all bode well for the future.
Valuation - this is the tricky bit! D4T4 has big name clients, and impressive software. Plus the company is making positive noises about its new fraud prevention platform.
Finncap’s latest note this morning shows a 29% drop against its previous FY 03/2022 EPS forecast of 8.0p. This is reduced to 5.7p, but rising to forecast 9.8p adj EPS for the following year, FY 03/2023.
At 395p per share, that produces a current year PER of 69, dropping to 40 times. Clearly not a share for value investors then!
However, it’s a growth company, and seems to have very impressive software, so investors need to be comfortable with it spending more to roll-out the new product, suppressing short term profitability (which is what has driven the forecast fall today).
What should it be valued at? I don’t know, but it’s starting to look fully valued to me.
Balance sheet - very strong, with plenty of cash, so no concerns here at all.
My opinion - I’m intrigued by the potential for expansion, as D4T4’s software seems to be impressive, and helps companies improve their profitability by processing their data better. Therefore, I think the share price is probably being chased up by investors who like the story more than the short term numbers.
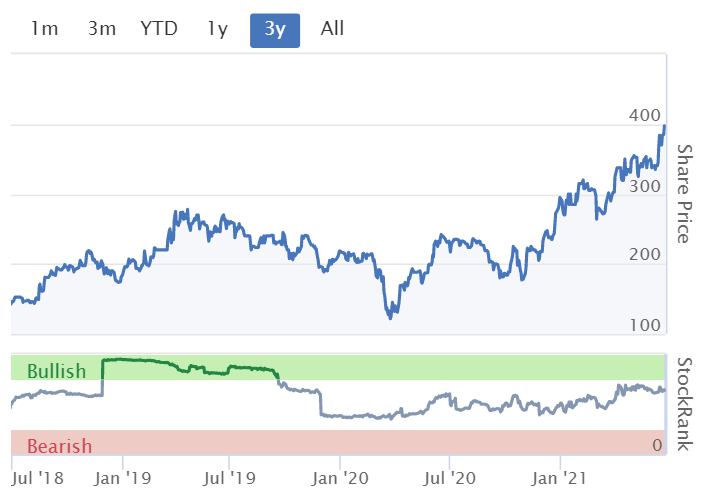
Taking a longer term view, the track record is not madly impressive given the high valuation -

.
Overall, I think I’ll run with this one. It’s difficult to value, and probably needs another out-perform trading update to justify any further rise in share price, but who knows?
Companies with great products, and huge potential markets, can be valued very aggressively in bull markets.
.
.
Tasty (LON:TAST)
(I hold)
6.0p (unchanged) - mkt cap £8.5m
Too small & illiquid really, but Jack thought it might have interesting read-across for other hospitality sector stocks. Also I (Paul) have a small holding here, so looked at it for my own purposes anyway.
TAST operates the Wildwood chain of (mostly) pizza & pasta casual dining restaurants. Also a handful of “dim t” restaurants.
Today we are told -
- 49 out of 54 restaurants are fully open, with social distancing measures
- Takeaway & delivery performed well in lockdown, and after sites re-opened
- Last 6 weeks (indoor dining allowed) - “strong like-for-like growth” (but no figures provided)
- Encouraged by strength of recent trading, despite restrictions - pent-up demand
- Outlook - TAST believes trade will “remain robust” over the summer
- Challenges - supply chain disruption, staffing, wage inflation, business rates resuming, furlough & VAT support phasing out
- Leases - consensual agreements reached on 80% of the sites. Continuing to negotiate with remaining landlords & creditors
My opinion - sounds generally positive, but with no figures provided, and nothing said about liquidity, it’s difficult to forecast where this company is going.
Evidence is mounting that people are keen to eat out again, although this update is a reminder that the sector faces serious headwinds. Set against that, demand seems strong, and a lot of competition has disappeared.
I’m surprised TAST hasn’t done a CVA, as that was mooted a while back. It would be a good way to clear the rent arrears & dispose of moribund sites. That’s what Revolution Bars (LON:RBG) (I hold) did last year - renegotiated with most landlords, then did a CVA to sort out the remaining sites where landlords wouldn’t co-operate.
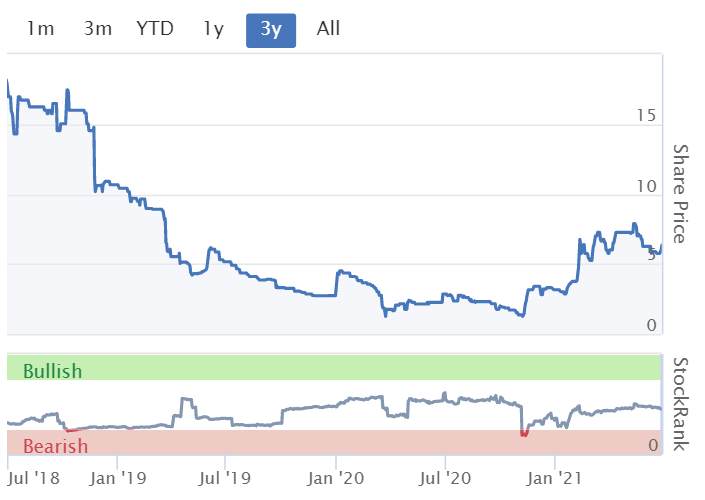
The 3-year chart below is a reminder that the pandemic was the cherry on top of an already-rancid cake.
.
.
Electra Private Equity (LON:ELTA)
(I hold)
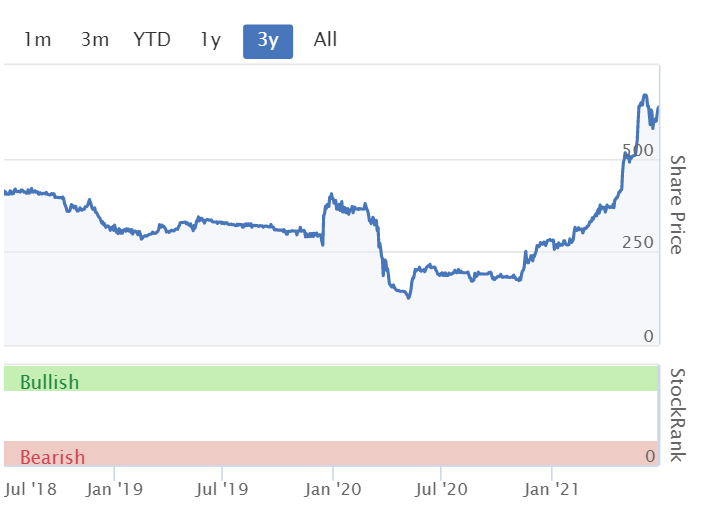
637p - mkt cap £248m
This is a very interesting special situation, here is my archive of comments on it, or if you’re short of time, my most recent stab at a valuation of the 2 investments owned by Electra, namely TGI Fridays (UK franchise, restaurant chain) and Hotter Shoes (Saga for feet!). These are both set to become separately listed shares later this year.
I get to 803-1187p per Electra share valuation range, so still potentially good upside from the current price of 637p. Hence why I have not sold any of my shares despite a fairly nifty 50% gain in a couple of months. I’m keen to continue holding Fridays, and Hotter shares longer term actually. Both seem to have good prospects, and strong management, having used the pandemic to comprehensively restructure.
Capital Markets Day - held online today. Here is the full slide deck (pdf download link, very comprehensive). Or if that doesn’t work, try this page on their IR website.
I urge people to take a look, as I think the Fridays float looks set to be a success, there seems good expansion potential too with a newly launched cocktail bar brand called 63rd+1st, referencing a Manhattan address where Fridays was launched.
Because of the way the float is being done (issuing shares to ELTA shareholders), there could be some initial indigestion as some ELTA holders are bound to sell their newly issued Fridays shares. That’s an unknown factor. This is scheduled to happen in late Sept 2021.
Management read through the slides quite rapidly, I jotted down some key points only, as follows -
- Pre-pandemic, Fridays did £25.6m EBITDA from 87 sites
- Price rises & (something else, I forgot) will significantly add to future profitability, plus cost cutting, rent re-negotiations, etc. Current estimate is £30-40m EBITDA pa post pandemic
- Pent-up demand now in evidence
- Online ordering & takeaway is now 8% of revenues, from nothing - hence future profitability should be higher than before. Likely to continue post pandemic, established now
- Competitors - c.598 competing sites have closed, about 10% of the total casual dining market
- Italian pizza chains worst performing, with 18% of sites have closed - all new sites for 63rd+1st new format rollout were previously Italian themed restaurants, so kitchens already fitted out, saves capex on new sites
- Fridays sites - typically £1.2m to £2.0m fitout capex per site.
- 63rd+1st new format will be typically £650k capex, and payback in just 2 years (wow!)
- New site deals are typically nil premium, low rents, 6m to 2yrs rent-free - attractive terms
- Drive-through format for Fridays - deal pending with a licensed operator
- Other acquisition opportunities - e.g. launch new franchises, looking at expanding Fridays into Europe
- Staff - we hire on personality and sense of humour, not skills
- Dark kitchen (delivery) format launched called “JailBreak”, generating more revenue from existing sites
- As previously announced by ELTA, current trading is +12.5% LFL (vs 2019) - i.e. good! Scope for further growth once 19 July lifting of restrictions
- Seasonality - very low - business is spread almost evenly throughout the year, each quarter being in the 24-27% range of full year. An important competitive advantage
- Franchise fee payable to US owner of brand is c.4% of revenues (Slide 51)
- Franchise agreements have been renewed on more flexible terms, very good relationship with brand owner
- Current trading restrictions re social distancing has reduced capacity by c.30% - soon to be lifted we hope
- VAT - currently 5% until Sept 21, then 12.5% until March 22, then back to 20%
- Industry data suggests about 60% of competition intend to raise prices when support schemes end
- 5 problem (i.e. loss-making) sites. 2 of these leases expire in 2023
- Management have background in hotels, so know they need to manage demand to fill space - i.e. offering deals to get people in at quiet times
- Maintenance capex is modest at 1.25% to 1.75% of revenues per annum. Sites are well invested, with no major refurbs needed yet
Next came Q&A:
Q1. Why didn’t you do a trade sale of Fridays as originally intended?
A1. The M&A market is currently dominated by distressed situations. Can achieve a better result for ELTA shareholders through a stock market listing (I agree)
Q2. Staffing costs rising?
A2. Yes, some inflation factored into their financial model. Kitchen pay in particular has gone up.
Q3. Staffing vacancies a problem?
A3. 800 new staff have been recruited since May, so people are out there.
Q4. Can ELTA shareholders have a cash option instead of Fridays shares?
A4. Not directly, but will be able to sell in the market. Advisers intend to establish a strong market post-demerger
Q5. How is the new format 63rd+1st trading from first site in Cobham?
A5. Pleased so far. Glasgow site will be next. So far 63rd+1st is doing what we expected. See it as Fridays for grown-ups - focused more on cocktails, less on food.
.
As I say, there's tons more information in the slide deck, so do take a look.
.
.
Various Eateries (LON:VARE)
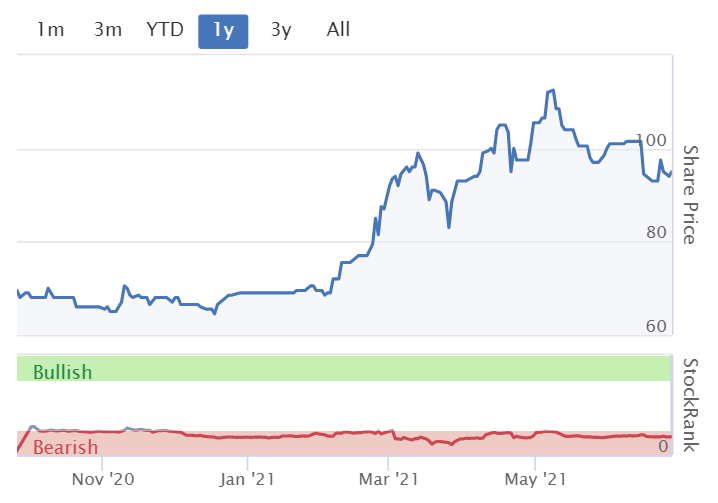
97p (up 3% today) - mkt cap £86m
This is a recently floated chain of upmarket bar/club/restaurants, the main brands being Coppa Club, and Tavolino. Its website is here, for more info.
The main attraction of the shares is that the founder & major shareholders is Hugh Osmond, founder of Punch Taverns, and Pizza Express fame.
The main downside of that, is that the valuation look very stretched, as investors are paying up for being a back seat passenger in Mr Osmond’s venture, and his track record.
I was invited to join an investor presentation today, and as usual I only jotted down a few key points, which I’m happy to share with you here -
Current trading very strong, LFL (vs 2019) are:
+11.3% (12 April - 16 May - outside space only)
+28.3% (17 May - 20 June - indoor trading allowed, with social distancing
These figures include the benefit of reduced VAT, but are still good.
- Tower Bridge site (with the riverside igloos) trading “phenomenalyl well” - despite no tourists, and many office staff not having returned yet
- Coppa Club concept is to fill the space all day, people having meetings, working there, as well as just meals. Seeing this happening in practice.
- Expecting stronger sales still, when office staff come back
- Furlough scheme - 1.7m people still furloughed, estimated 0.8m in hospitality sector. This is causing distortion of labour market. European workers can claim furlough in UK, and go home to relax, or earn a second income overseas, which many have done, allowed within the rules. When furlough scheme ends, this distortion should be removed.
- Moratorium on evictions - a day of reckoning will arrive. Expecting a “tsunami” of evictions & hence new sites available from early 2022.
- Change of use - planning rules have been relaxed, meaning that councils now classify retail and hospitality use as the same. This will allow a much easier reclassification of use, which previously was problematic. E.g. a hairdressers can now become a cafe easily.
- New sites - have cash on hand for 10 new sites. Would raise equity possibly for further expansion (Paul - makes sense when share price this high!)
- Forget London - too many operators are competing for sites. Very little competition for good sites outside of London.
- Too early to issue financial guidance.
My opinion - it was great to hear management talk about the business. This share looks a lot more interesting than I previously realised. However, for me, the current valuation looks too high, and with no forecasts, it’s currently impossible to value accurately.
.
.
Jack’s section
Mears (LON:MER)
Share price: 184p (pre-open)
Shares in issue: 110,881,897
Market cap: £204m
Mears (LON:MER) is a housing services provider. It provides local authorities and housing associations with housing related and domestic care services. It’s the UK leader in the former and has a growing share in the fragmented market of the latter.
This is a tricky area - typically low margin and sometimes requiring capex. Mears also has to deal with long-term contracts, which can be a risk.
The group has struggled to consistently grow revenue:

And the high cost of sales (80.6% of revenue in FY20) means net profit has remained broadly flat, even swinging to a loss in the most recent financial year (before extraordinary items).

On the point of extraordinary items, there have been a lot of these. Approximately one every other year for the past ten years, including a massive £88.3m loss in FY19. Mears has recently disposed of part of its Domiciliary care business, sold for only £7.5m.
The group does offer value (with a Value Rank of 88), but the financial health scores are creaking and the share price has not gone anywhere in a hurry over the years, so it’s got the potential to be a value trap.

AGM update
Trading at Mears in the calendar year to date has remained in line with management's expectations... the board re-iterates its previously provided guidance for the full financial year ended 31 December 2021 ("FY2021"), as being in line with current market forecasts.
Those are:
- Consensus FY21 forecasts of £771-811m revenues ranging from £771m - £811m, and
- Adjusted profit before tax in the range of £21.3m - £25.4m
The group says that the ‘return to normal payment mechanisms’ across its contract portfolio is now largely complete with activity levels increasing. Group revenues for H1 are expected to be in excess of £430m, with adjusted profit before tax (before exceptionals and amortisation) in the region of £11.0m.
Improving trends in working capital and net debt have continued, with average daily net debt anticipated to be approximately £20m. This is down from the £97m reported in FY2020, which is encouraging, and Mears expects to return to dividend payments shortly.
Conclusion
The group trades at just 0.25 trailing twelve month (TTM) sales and 2.1x TTM free cash flow, so there’s the possibility that, if the group is managed well with an effective strategy, the shares could rerate.
But it looks like a tough industry that is expensive to operate in. I don’t see why you would assign Mears a particularly high multiple and the group’s track record suggests a company that works very hard but struggles to translate that effort into profits for shareholders.
The dividend was cut steeply in FY19, before Covid, which suggests either that the business model is prone to shocks or some financial risk. Mears does have a pension fund and quite high capital lease obligations, so even with the apparent value on offer, I think there are probably more attractive investment propositions out there to spend time on.
The StockRank has been improving recently though, and the narrative sounds stable if not spectacular, so if conditions remain favourable with economies opening up there could always be a rerating in the shorter term.
Appreciate (LON:APP)
Share price: 35.4p (-10.4%)
Shares in issue: 186,347,228
Market cap: £66m
Appreciate (LON:APP) is a financial services business that provides gifting and reward products. It sells these products via digital channels, its direct sales force, and a network of agents. Products include Love2shop gift vouchers, single store gift cards, and VIP travel experiences.
There are signs of potential quality here. Good cash conversion, high levels of free cash flow, a net cash position, and previously encouraging returns on investment figures. But these profitability metrics have been declining recently and the group is simplifying its operations at pace.

It says it wants to create ‘wow’ moments for its customers (both corporate and retail) but, with shares down 17% as of writing, it looks like the wrong kind of wow today.
Highlights:
- Revenue -5.2% to £106.8m,
- Group billings -3.2% to £406.5m following the early impact of the initial lockdown and ceasing of hamper packing,
- Unaudited, non-recurring losses relating to the wind down of the hamper packing business of £1.1m
- Operating profit down from £6.4m to £0.8m,
- Profit before tax down from £7.7m to £1.3m,
- Earnings per share down from 2.96p to 0.46p,
- Year end free cash up from £29.6m to £31.4m,
- Final dividend of 0.6p recommended, making for 1p of total dividends per share.
The falls come from reduced profitability in Corporate and a loss of business over lockdowns in Consumer (some of which is deferred).
Corporate billings rose by 1.8% to £201.3m and revenue increased by 6.8% to £53.7m, although net profit fell from £6.6m to £2.6m due to lower margin business (namely the free school meals initiative) and higher administration costs.
I wonder why the company took on this school meals work if it’s at such a lower margin? And why were there higher admin costs?
Consumer billings -7.6% to £205.3m due to lockdowns and reduction in Christmas Savers. Revenue down from £62.4m to £53.1m. Segmental profit consequently falls from £5.3m to just £0.5m, with a £1.1m hit (non-recurring) also coming from the closure of Appreciate’s hamper business.
Unfortunately, some of these trends are not limited to FY20. The group’s current trading and outlook:
Trading in the first 12 weeks of the current financial year has been slower than anticipated and continued to be impacted by the pandemic, as customer buying and spending patterns take time to return to normal levels...
…the Christmas Savings' order book has been held back by COVID‐19 restrictions impacting face‐to‐face agent activity during the crucial renewal and recruitment period, combined with higher levels of unspent paper vouchers (up by £6.4m compared to last year) due to shopping restrictions, which customers appear to intend to use towards Christmas 2021, rather than starting a new savings plan. Whilst initiatives to recruit Christmas savings' customers continue, the order book is now predicted to be c.14% down following the continued COVID uncertainty, having quoted c.11% lower in April.
Billings are considerably higher than the same period last year but remain 8.6% down on 2019.
Conclusion
Unwelcome news for shareholders, but I wonder if this is just a continuation of temporary Covid disruption, but with the nature of Appreciate’s businesses meaning softer trading has continued for now while other businesses see signs of recovery?
After a quiet Christmas period, unspent paper vouchers are £6.4m higher compared to last year and ‘some’ customers intend to use them towards Christmas 2021, rather than starting a new savings plan (why wouldn’t all of them be doing this?)
That said, I don’t see why gifting products would be fatally affected by the pandemic even if the effects linger longer here than for most. These results probably aren’t as bad as expected given the initial share price drop. Hundreds of companies have suffered similar disruption.
But then again, a falling order book does not bode particularly well for now. The fear is that this marks something more significant than temporary disruption. The group comments:
In response to this reduced predicted order book for 2021, a number of initiatives are underway to encourage customers to save and incentivise agents. We held a virtual event to engage agents in May and introduced a regular prize draw to encourage customers to add to their savings' plans. We also introduced new agency commission structure in 2020 to support plans.
Appreciate has a good cash position of £31.4m. Digital Billings grew an impressive 287% to £68.5m and it has invested heavily here, to the tune of about £6m over the past two years. There are other longer term growth initiatives underway.
There are signs of quality in the underlying business, but management must now unearth that so that shareholders benefit.
Reading up on the story, Appreciate is clearly a company in transition. It is simplifying its operations with the sale of its brand engagement subsidiary, the end of its hamper business, and the wind down of the contract packing and Republic of Ireland businesses. There are several non-recurring costs this year that will not be repeated in future.
Turnarounds are easier said than done, and the more complex a problem is, the greater the scope for slippage, additional costs, and further complications.
But it could be that, underneath the Covid disruption and unfavourable shorter term dynamics, a fundamentally simpler and stronger enterprise is emerging. There are points of interest here, and this one could be worth cautiously getting to know a little better, although there’s no doubt sentiment is against Appreciate and the short-term outlook is rocky.
Croma Security Solutions (LON:CSSG)
Share price: 81.25p (+3.5%)
Shares in issue: 14,902,486
Market cap: £12.1m
This is a tiddler but is notable for yesterday’s strong share price reaction to its trading update - flagged by EffortlessCool. Trailing twelve month revenue is £31.5m, so it’s possible that this is a more valuable and larger enterprise than the market cap lets on.
For now, however, liquidity is obviously a key consideration. You can reliably buy less than £2,000 worth of stock and if you decided you needed to get out in a hurry, I wouldn’t bank on being able to do it. The group does have some notable shareholders for a micro cap, namely Canaccord and Liontrust. Directors also own a good chunk of stock - the top shareholder is group CEO Roberto Fiorentino.
This is a small outfit run by ex-military professionals with five divisions (at least according to its website. The RNS refers to two divisions):
- Croma Vigilant - keyholding, security guards, and mobile patrols as well as more specialist security throughout the UK,
- Croma Proception - reception, concierge, and security,
- Croma Systems - security consultants for families, businesses, and assets,
- Croma Biometrics - identity management and software,
- Croma Locksmiths - locksmith services across eight outlets in the south of England.
Trading statement for the 12 months to 30 June 2021
Robust Trading
Both divisions have traded well since the start of the year and the impact of Covid-19 has been more than offset by strong performances elsewhere in the group. The board now anticipates a better result than previously expected, with FY EBITDA of at least £1.85m (2020: £1.75m). Taking the group’s net cash figure of £5.5m below and using that for the EV calculation, that looks like striking value on the face of it (EV/EBITDA of c3.85x).
Croma Systems (which includes the lockdown-affected locksmith stores) is expected to deliver an increases in sales and profits against the prior year.
Croma Vigilant, the largest division, is also expected to perform well against the prior year. This division has benefitted from the increased need for manned guarding and Proception services.
Balance sheet - no debt (excluding lease liabilities) with net cash of £5.5m. That’s highly significant given the market cap, as is the level of annual revenue.
Conclusion
Trading momentum is positive and if this is a viable business, then the shares are likely mispriced at current levels on account of the material net cash holding. Croma has struggled to increase net profits in line with revenue growth though.
Despite that, the group looks strongly cash generative so perhaps profits are understated.
With such a small market cap, corporate governance and depth of management are key considerations. Is there enough quality at the top to get Croma up to the next level in terms of scale? A quick look at indeed shows some mixed reviews from employees. By itself, not enough to come to any kind of conclusion, but it’s enough to suggest this is an area to investigate further. As noted above, it’s good to see some institutions present.
There’s probably potential here, but also clear risks primarily around liquidity - if there is ever a profit warning and you want to get out, it’s going to be tricky. This must partially explain the cheap valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Given the 12% drop in D4T4 share price could you do a follow-up to your report above? That would be very helpful
Appreciate (LON:APP) - I've also taken a quick look at its results today, and am distinctly underwhelmed. If this business didn't exist, would it be invented? Probably not. I can't see much point to it.
Incidentally, I was asked at random to contribute to an ONS consumer survey, and they sent me a £10 card from Love2Shop as a thank you. I spotted that it was one of APP's products, so tried it out.
I found the sign up process clunky (e.g. it had a very poor facility for entering your address), and intrusive (it required my date of birth and phone number, which I would rather not give out).
The card sat on my desk for a while. I retrieved it today, logged in, and found it had expired in Jan 2021! So I've lost the £10. This leaves a sour taste, so my perception of Love2Shop is now very negative. That must happen to plenty of people, and maybe that's where the profits come from (expired cards)?
All in all, it strikes me as a pretty rubbish business model. Hence not something I would invest in. Sorry about that.
Regards, Paul.
Re £ELTA and Fridays - after reading their slide deck, some Marketing caution FWIW.
Fridays 3 key occasions are to be : Family Dinner (4+ people from, Date Night (30-50s) Girls Night (30-50s) but the deck says current Fridays crowd are 47% 18-30. The archetype Maria is in her 30s ("but there are many Maria's in their 30s, 40s and 50s). Maybe but is Mandy aged 24 going to go to the same place as Maria, a young 48.
The brand decor in the back looks like Cheers.....a show closed in 1993. I also think that 'Brand USA' is a lot less cool than it was (or at least has moved on a lot). I think the decor and menu looks very dated and 'old' for a UK urban brand- and I am 55!
It also says that American themed restaurants have been hardest hit (29% net closure) and it has 32% of current estate in shopping centres. That could be a contrarian opportunity but (buying from PE) .......
Also the newly assembled Mgt team look fine but are not steeped in Foodservice. Hotels and consumer facing gambling/leisure sites are not F&B centric.
Whilst I buy into a big recovery in eat-in casual dining and a positive story for brands ready to expand (I hold Fulham Shore (LON:FUL)), I don't see a big potential for Fridays.
Good luck :)
All very interesting Zipmanpeter, but I'll follow the money thanks! Fridays is highly profitable, and performing well. This is what tells me customers like the format, which is what matters.
Re Fridays. Can someone tell me what the menu looks like? Does "American themed" mean that it is burgers, fried chicken and some Mexican food? The web site doesn't help. I just want to try to understand its positioning in a competitive market.
Richard
Here you are.
https://uk.menuwithprice.com/t...
Heart burn to go …..
Gus.
Re Fridays, add in a sprinkling of Cajun and that's it. Though I would like to say that it's Tex-Mex as opposed to real Mexican food.
Huge thanks for the swift and superb write-up on Electra Private Equity (LON:ELTA) , Paul.
I hold.
Appreciate was one of Lord Lee's holdings. Not sure if he still holds, but worth a look, as he tends to favour a company where Directors have considerable skin in the game.
I would appreciate Paul's thoughts on React (LON:REAT) (I hold) which has published interims today. The EPS are unchanged but the adjusted show significant improvement. The company presented at Mello a few months ago, and I remember Paul being dismissive of it. From memory that was for two reasons. First the CEO sold it too hard (my words not Paul's) and secondly one could not have very high expectations of a mere cleaning company. I hope I have not misrepresented Paul's views in this summary. I would be very interested in whether his views have been modified by these results (which the market doesn't quite love).
Hi OsullivanB,
I've had a quick look at interim numbers from React (LON:REAT) and cannot understand why the market cap is anywhere near £15m. It seems considerably over-valued. Like lots of shares in the last 8 months, it seems to have caught the imagination of punters, who've chased the price up, and now people look to be (very sensibly I think) banking their profits.
A specialised cleaning business just doesn't interest me. It should be valued on a very modest multiple (e.g. recent acquisition done on 4.75x EBITDA). I can't see any reason why you would value the whole business any higher than that.
What kind of defensible moat would a cleaning business have?
It was a nice speculation for people who spotted the covid angle when it was 1p, but that story seems stale now. It's tripled in price, and banking profits seems entirely logical to me, because so many things have peaked and are beginning to sell off now. Why hold something so small & illiquid too? You get stuck in them, hence why I avoid this type of thing these days.
Sorry about that.
Regards, Paul.
Thank you, Paul.
Well, there's the bear case for React React (LON:REAT), in response to my more bullish presentation below! I dismissed BOTB ages ago as 'that gimmicky prize company' and I think to do likewise with a cleaning company is also a mistake. It's always good to get both sides of the coin though. The price is about right for now , but I think it will be buttering its bread in a year or two when a lot of other tiddlers are still chasing jam tomorrow.
Half year results from React React (LON:REAT), which will be too small to garner coverage here, but a recent Mello presentation interested me enough to breach my own rules on size and take a small position. Very speculative, but possibly will surprise nicely if I forget about my modest investment for 3-5 years.
Figures look encouraging despite some short term 'softening' that seems to be in line with what happened when lockdown eased last year.
React operates at the more 'challenging' and thus high margin end of the cleaning business - from road accidents to detention cells and squats. Business through the pandemic has 'been swings and roundabouts' with covid work making up for other losses. It recently doubled in size through acquisition of a more regular contract cleaning business, Fidelis, and clearly has it's eye on further acquisitions at modest p/e ratios, along with cross-selling and organic growth.
Todays figures have them just in profit without any input from their acquisition, strip out exceptionals (that do look like proper one-off costs) and there is a decent margin. Add in contribution next time from Fidelis, plus some growth in both businesses, and the forward PER or EV/EBITDA does not look overly challenging.
It appealed to me because management really seemed to know their trade, and have sorted out some previous problems. There's a little bit of market differentiation, room for consolidation in the sector, plus the capacity to rinse and repeat on deals like Fidelis. DYOR, but I liked it as 'sensible punt.'
Hi all. Anyone got thoughts on £indv ? Currently trading at 145p
Jeffries raised price target to 220p and it’s rated strong buy by 3 brokers. Price has recently pulled back from 165p but still in an uptrend.
Low PE and huge cash stockpile.
As far as I can see it’s settled all it’s law suits (or they were dropped) in which case it looks like good value. Am I missing something?
That should be Indivior (LON:INDV)
Wasn't the other big issue with Indivior (LON:INDV) the generic competition to its blockbuster drug?
Hi Paul - where is the Various Eateries (LON:VARE) presentation being held today or is it just broker led roadshow meetings you've been invited to?
The Various Eateries (LON:VARE) presentation was just an invite thing, which I sometimes get from brokers. It was mainly presenting the information in the recent interim results here
I jotted down some key points, so will post that in the main article shortly.
Also a very good presentation about Fridays from Electra Private Equity (LON:ELTA) (I hold) which I'll also write up.
Regards, Paul.
keen to hear your thoughts on various eateries, like their product, management have great cv's but the valuation looks very steamy
Here are my SCVR heat maps for today (prices as at ~9am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
I realise it is likely just me, but I can't get my head around the valuation of D4T4. This is a software company going through a difficult transition from one-off licenses to a recurring revenue model, and the latter are not growing that quickly (11% in FY21), and it's on a PER of nearly 60. Looks like something the momentum brigade have stuck their teeth into. On any rational valuation basis, it is ludicrously overvalued.
All the best, Si
It's really on a fwd PE of 40 and cash adjusted 35 so not particularly richly valued compared with peers in similar group focused on data. Particularly as it is seen to have a world class product and a blue chip client list to boot and is expanding quite rapidly in both US and now AsiaPac region. Tenant clients like HSBC clearly add lots of credibility to the AsPac expansion.
It's not really going through a "difficult" transition either. The ARR is moving as planned - up over 11% YoY and that really just adds stability to earnings and will command a premium in valuation as it significantly smooths any lumpiness. People always used to panic at the H1 and H2 split - lost count of the times people have written on here how H2 looks like a stretch and really there's a profit warning, when clearly each time management was correct in their forecasts. A heavier weighting to ARR should alleviate that angst.
I currently hold but feels like around fair value for now, though if market conditions change ratings may fall back in the short term. This would not be considered richly valued in the US. It is a growth stock just around the uptick of its J curve and is a really a play on the next 5 years where they are expected to have some pretty dynamic growth. Probably up with events for now - I can't see UK investors bidding it up much further until some of that growth comes through.
I currently hold but feels like around fair value for now, though if market conditions change ratings may fall back in the short term. This would not be considered richly valued in the US.
I think "fair value" is pushing it tbh. Only time will tell if it grows enough to justify the current rating, but why take the chance? Obviously your hopes are very high. It completely fails my "Microsoft test" - if I'm going to buy a company in this area on this kind of rating, why would I not just buy Microsoft?
Anyway, good luck with it. Looks like dead money to me...
All the best, Si
well everyone has an opinion. FinnCap think it should trade comparably against peers at roughly 6* EV/Sales or 30* EBITDA so that suggests north of 450p so clearly your ludicrously overvalued remark, my fair value remark and analysts 30% undervalued remark is what makes a market.
I bought in the low 100's so I'm not complaining at 300% returns but I am now at a crossroads. From a personal perspective I think 400p is around fair value but longer term I can see considerable upside. If it bounces back I may take profits and look to buy back in a year, as I do see the next 12 months consolidating and there may be better returns elsewhere in that 12-18 month timeframe.
FinnCap think it should trade comparably against peers at roughly 6* EV/Sales or 30* EBITDA so that suggests north of 450p so clearly your ludicrously overvalued remark, my fair value remark and analysts 30% undervalued remark is what makes a market.
Just back got from A&E after reading that Finncap valuation method which split my sides from laughing so hard. I must have missed the Stockopedia screen for that one! I particularly like the random large multiple of EBITDA element - two made up numbers multiplied together to create an even larger and more meaningless number! Wish I was a rocket scientist and could get a job at Finncap...
I bought in the low 100's so I'm not complaining at 300% returns but I am now at a crossroads. From a personal perspective I think 400p is around fair value but longer term I can see considerable upside. If it bounces back I may take profits and look to buy back in a year, as I do see the next 12 months consolidating and there may be better returns elsewhere in that 12-18 month timeframe.
Well, I'm very happy for you. I'm not sure why you felt the need to add this and don't understand why others do it either. We're here to discuss shares not enter some kind of p***ing contest!
Si
Personally I prefer to hold Gb (LON:GBG) over D4t4 Solutions (LON:D4T4) as the valuation seems more reasonable and the recent insider buying gives the USA growth story some conviction. It’s not a complete overlap of services or direct competition. Gb (LON:GBG) is more diversified both geographically and through its products and services.
Take care,
S.
As if by magic, a few minutes ago another three large inside buys from the CEO, CFO and group MD.
Me too !
Excellent piece by John Authers of Bloomberg today. What could possibly go wrong? https://www.bloomberg.com/opin...
Yes it was a great letter that I need to re-read. The trouble is the scary answer is "everything could go wrong". But when?
Novacyt Sa (LON:NCYT) announced a saliva based COVID test kit today. Ie No awkward swaps if my understanding is correct. It is quite rare for such a user friendly test to have such a high efficacy rate if their RNS claim is to be believed. I think this is quite a breakthrough (I hold).
My morning smallcap tweet: SYME tries to pull a different rabbit from hat
Trakm8 Holdings (LON:TRAK) Appreciate (LON:APP) Supply@Me Capital (LON:SYME) Record (LON:REC) Avacta (LON:AVCT) James Fisher and Sons (LON:FSJ) Proactis Holdings (LON:PHD) Midatech Pharma (LON:MTPH) Tasty (LON:TAST) Novacyt SA (LON:NCYT) Gaming Realms (LON:GMR) NAHL (LON:NAH), Mears (LON:MER)
Trakm8 (TRAK) FY adj EPS 0.07p down 75%. Outlook: with no further lockdowns or unmanageable supply chain issues co expects to return to pre-Covid-19 revenues and deliver a profit. [SP=18 Cap=9m]
Appreciate (APP) FY(Mar). recent trading slower than expected, hit by the pandemic. Xmas savings order book is now predicted to be c.14% down following the continued COVID uncertainty, having quoted c.11% lower in April. [SP=39.32 Cap=73m]
Supply @ME Capital (SYME) Term Sheet with Italian Banking Group and the Fintech Bank which envisages: "signing of a commercial agreement to manage both the origination of new Client companies and a multi-annual inventory funding plan; and the execution of a first inventory monetisation transaction involving a portfolio of Italian Client Companies." SYME will acquire up to 10% of the Fintech Bank. Names are confidential for now. [SP=0.36 Cap=121m]. I'm short
Record (REC) strategic partnership with UBS Global Wealth Management for its newly launched Record Emerging Market Sustainable Finance Fund. "Record will leverage every component of its strategy..." Ugh. [SP=96 Cap=191m]
Avacta (AVCT) lateral flow test detects the Delta variant of covid in a small study outperforming two lateral flow antigen tests that are commercially available in Europe. I'm sceptical of test claims given very poor test performance in mass use. [SP=183 Cap=464m]. I'm short.
James Fisher (FSJ) guides FY U/L op profit up despite weakness in Marine Support. [SP=912 Cap=460m]
Proactis (PHD) confirms no customer systems compromised and "only a very small amount of low level internal and non-commercially sensitive data,..was accessed by the perpetrators" in recent hack. [SP=74.04 Cap=71m]
Midatech Pharma (MTPH) £10m placing at 28.5p, a 12% discount, for drug development. [SP=32.8 Cap=21m]
Tasty (TAST) believes trade will remain robust throughout the summer months. [SP=5.99 Cap=8m]
Novacyt (NCYT) to launch two PathFlow covid lateral flow tests: professional and self-test The Company will initially target private market opportunities. [SP=346.1 Cap=282m]
Gaming Realms (GMR) as expected has launched Slingo Originals content in Michigan. [SP=32.5 Cap=94m]
NAHL (NAH) Lead volumes continue to grow month on month across the Group's PI business and in expert witness services in Critical Care. In case management services, leads remain subdued due to reduced accident numbers in Q1. Pleased with the level of interest received to acquire its Residential Property business. [SP=47 Cap=22m]. I hold.
In line: Mears (LON:MER)
Than ks as always......and D4t4 Solutions (LON:D4T4) ?
could you have a look at Record (LON:REC) . they announced a partnership with UBS this morning and their share price has been on a tear recently. potential for further upside? with more and more green countries for travel opening i think their currency services will gain more clients so as a trade idea im considering this one
could you have a look at Record (LON:REC) . they announced a partnership with UBS this morning and their share price has been on a tear recently. potential for further upside?
There are no numbers attached to this so it's not possible to determine what the impact on Record (LON:REC) will be and whether it's material.
However, the announcement is for an ESG fund investing in emerging market currencies. Heaven knows how that's supposed to work, but as sustainability is the biggest growth area in fund management it probably makes for a good story. If nothing else it shows intent.
https://www.investegate.co.uk/...
timarr
I’m also intrigued by the £REC announcement, The fund seems to be for UBS private clients so that saves the rest of us having to think too much about whether this is a sensible idea:
Record will leverage every component of its strategy to increase its contribution to sustainable finance by investing over longer time horizons, in illiquid currencies, and in currencies with elevated volatilities, or in periods of drawdowns.
what is know, I think is thatUBS will seed the fund with $750m and at 0.5% fees per annum this could increase turnover. I feel this is an early development to leverage their currency skills ( I hold).
I have held Record (LON:REC) for just over a year and at 85% up, I am more than happy, however, its the one share, I have no real idea what they do.
I bought them because they hit all my "Stocko mechanical" criteria, and thought reluctant to buy them as I didn't understand the business, they wouldn't move from my entry criteria.
When people ask me, the best I jokingly say is they sound like a legalised money laundering outfit, but can someone educate me, in simple terms please.
Thanks in advance.
GB - Record (LON:REC) manage currency for institutional investors (eg. pension funds, fund managers). Often these clients want to hedge currency exposures where they have invested overseas. They can also be more proactive and speculate in currencies (higher fees for Record). Now they are engaging with UBS to launch a fund targeting private investors (fees will be a lot higher).
In the past they made a lot of money out of the carry trade, but this disappeared with interest rates around the world heading to zero. (Carry trade - selling a currency with a low interest rate (this was the Japanese yen), and buying a high yielding currency - making a turn on the interest rate divergence and crossing your fingers that the currency equivalence doesn't unwind too quickly - which of course it ultimately does).
Record has been very consistent in its earnings in recent years and at c30p seemed a safe place to park some funds. The price has been particularly strong lately, but not on profit improvements. I suspect it's been driven by a new CEO taking the company in a new direction - time will tell how it works out.
Good morning Paul & Jack, would love your thoughts on D4t4 Solutions (LON:D4T4) (I hold) if you get chance. A company with interesting technology and hopefully lots of potential for the future. Thank you.
Hi, any chance you could have a look at React (LON:REAT) ? They have published their half year report today. Revenue is up 20%, net profit is up 46% and margin has improved 7%. The acquisition of Fildis hasn't been included in the report as its too new, but has been trading strongly.
Andy Sav - note on React (LON:REAT) here which is quite useful. I hold.
Price de-hyping underway in React (LON:REAT) ... will be interesting to see whether the PI puke gathers more momentum through day as people 'lock in' a profit or whether there is a positive restorative bid. No idea but chance of a snowball for sure partly as the update can be read as a soft warning on current trading
Yes, think you are right! Down 9% at 8:40. Interesting to see how this plays out. I'm going to hang in there, its a long term holding for me. I like their approach to growth via consolidation in a fragmented market. If they can reach a certain size, then bigger contracts should follow
The React (LON:REAT) results today [I hold] were a bit of a curate's egg when it was priced for perfection, hence it is down heavily this morning.
This extract from the outlook is the problem:
"... however the start of H2 by contrast has experienced some softness in the reactive business as the country stutters towards the end of lockdown. Whilst COVID-19 decontamination work has been reducing, the more typical reactive emergency cleaning work has been slow to pick up".
However, things may now be normalising:
"A similar pattern emerged last year as the country went from full lockdown into a more relaxed period during the summer of 2020. Then as we believe now, REACT had two soft months, which rapidly returned to some form of normality. Ironically as we pen this report we have experienced the first few weeks of high demand returning, including a re-emergence of COVID-19 decontaminations".
Otherwise, the outlook is favourable:
"H2 has started well. Fidelis (acquired at the end of March 2021) reported record trading months in April and May to continue their solid track record of growth. With long-term contracts of between 3-7 years in length driving strong recurring income, this bodes well for H2 and the year(s) beyond".
"The contract maintenance business has continued well, with little or no impact from the issues surrounding the pandemic".
Whilst the growth story remains intact, this is a long term hold for me, so these ups and downs are just bumps in the road.
Appreciated :) I'll take a read
Paul & Jack - if you get time today I would appreciate any view you have on Appreciate (LON:APP) . Results for FY21 were always going to be disappointing but the outlook for this financial year is worse than I expected and they don't say anything about whether the trend improved with shops reopening which is a worry.
That said, there is potentially good upside here if they can return to pre pandemic levels of business as they did not increase the number of shares through fundraising during the pandemic and historically the share has done well when interest rates rise as they make money from the large amount of customers' cash they hold. So this could be a good hedge against continued inflation.
Just to say thanks for the coverage of £APP. Very helpful for when I go back over the RNS when I have more time this evening. I sold at 34p today - still in profit for the year and will revisit at half-year report or if this falls into the 20s.