Small Cap Value Report (Tue 3 Mar 2020) - RBG, VTU, GETB

Good morning, it's Paul here, with Tuesday's SCVR.
Estimated timings - mostly done by 1pm official finish time, but I've got nothing else planned for the afternoon, so will probably keep adding sections until about 7pm.
Edit at 19:"7 - sorry, it took much longer than expected, but today's report is now finished.
I'm going to start with my views on the current coronavirus situation. Sorry if this is not very well-structured, but there's so much to cover;
Coronavirus thoughts
It seems to me that (to mangle a phrase from Churchill) we're not even at the end of the beginning. Coronavirus is clearly spreading internationally, and is highly contagious. Therefore, the most logical stance to take, is to assume that it's likely to become a pandemic. Hopefully not, and there are of course other possible scenarios - e.g. that containment measures slow it down, or even gradually eradicate it, as people either recover or die (it is binary, after all). My sources in the pharmaceutical sector tell me that hopes for a vaccination, let alone cure, are premature. After all, they've never managed to develop a cure, or vaccine for the common cold, after trying for more than 50 years. But who knows, there must be lots of scientists working on this, and they could get lucky. Even then, testing would take the best part of a year before it could be widely distributed.
I monitor this website (from a good source, which I've checked out) every morning, and note that;
Reported cases in China seem to be reducing now. The number of people reported as having recovered, is rising strongly now. That's great, but bear in mind that many cases (elderly & already sick) are severe & require hospitalisation. The number of cases could be under-estimated, if people who have mild symptoms don't need medical help. We saw from some of the social media coverage just how bad the situation was in the early stages of the virus outbreak, as so many people needed hospitalisation in China. Remember the new hospital they built in 8 days? How could that be done here in the UK? It was reported on last night's TV news that we only have 2 hospital beds per 1,000 people, well below other developed countries (e.g. France & Germany), therefore the worry is clearly that if people become sick from coronavirus & require hospitalisation, then how could the NHS possibly cope? Remember that mortality rates might not be that high, but severe cases who need hospitalisation, is considerably higher than the mortality rate. How could open, Western societies deal with trying to lock-down entire cities? It just wouldn't work. Would we tolerate the army on the streets enforcing lock-downs? It's almost inconceivable here, but not in China. My point being that the extreme measures taken by China to stop the spread (shutting down the economy in large areas) couldn't be done effectively, in open, democratic societies.
From looking at US websites, and the very powerful rally in US shares currently underway, I get the feeling that they could be seriously under-estimating the risks. Therefore, I'd expect to see another big sell-off in the US, when coronavirus really hits them, as it's bound to. I think the very recent, powerful rally in large caps (especially in USA) is probably a selling opportunity. Remember that, in falling markets, powerful rallies are the norm, but they fizzle out and then another, larger sell-off occurs. It looks that way to me right now, and reminds me of 2008 actually. There were big rallies then too, before repeated new waves of selling, as people realised the situation was getting a lot worse, not better. The parallels to today look striking. But we don't know, it's a fluid situation. Hopefully this article might look ridiculous and alarmist in future, if they get on top of things. We can only base our views on the information we have right now, with the future very uncertain.
In terms of the markets, there are really 2 issues on my mind;
1. The temporary but still serious potential impact on company profits. Supply shortages from China haven't really kicked in yet, but March & April is likely to see many profit warnings from companies that either import finished goods from China (think lots of non-food retailers), or make stuff using some components sourced from China. I'm expecting to see many surprises, from companies that I didn't know were reliant on China - it's the workshop of the world, on which many sectors are highly dependent. Because of this, I think it's too early to be buying the dip. I'd rather buy after profit warnings, which in many cases look inevitable.
2. Whether the panic and worry of coronavirus spreading widely, could be a trigger for not only a recession worldwide, but also a credit crunch. Many companies are highly geared, because credit is so cheap. But if earnings crash, then covenant breaches could make debt repayable on demand. So in a bad case scenario, coronavirus could conceivably be the trigger for a credit crunch - i.e. withdrawal of credit, causing banks to retrench in order to lower their risk, with the knock-on impact on geared companies which might be forced into refinancing at the worst possible time (and hence bad terms - e.g. emergency placings at a big discount), or even insolvency.
I'm almost fanatical about balance sheets, and I think we're entering a market phase where highly geared companies could be severely punished. People who ignore balance sheet risk in a bull market, could be about to be taught a painful lesson, in my view. Risk is badly mis-priced already in my view. Hence it's a ticking time-bomb for both equity and credit markets. We could very easily see another major dislocation, as happened in 2008-9. It doesn't really matter than interest rates are ultra-low, if banks are not willing to lend - which is what happens in a recession. Although having said that, banks are more inclined to be lenient, if the interest charges are modest, and a company can at least afford to service those interest charges. Hence the situation doesn't get any worse for the bank, so it can justify leniency on repayment of capital.
Whereas in the downturn of 1990-93, I remember that the banks were absolutely brutal in putting so many companies into receivership, because interest rates were far too high (that numpty John Major took us into the ERM at far too high a level, so cripplingly high interest rates were maintained to defend sterling, unsuccessfully as it turned out) . The result of which was that compounding interest, at high rates, saw banks' problems get bigger by the day, so they pulled the plug on many decent but highly geared companies, thus actually just crystallising a bad debt for the bank. The only beneficiaries were the insolvency practitioners, whose fees often mopped up a lot of the recoveries from fire sales of assets at the worst possible time in the cycle. Anyway that was then, and this is now, where low interest rates mean banks are not likely to be so brutal this time. They can force companies to raise more equity though, and that could mean severe dilution for existing shareholders.
Stocks/sectors -
Transport - still the most vulnerable. Some airlines are already reporting bookings down c.20%. Holiday companies are also looking extremely vulnerable - why on earth would you book a summer holiday abroad, knowing that if just 1 person in your hotel is even suspected of having coronavirus then your hotel becomes a luxury prison, with local police stopping people from leaving? Then apparently you need to get a doctor's certificate within 24 hours of your flight, so if you can't get that organised, then you can't fly home. I reckon airline bookings are likely to drop much further than 20%. I've already told my social secretary not to book any holidays or short breaks for the foreseeable future. But at some point, that risk & cost will be priced in, and investors will inevitably look to anticipate the recovery. I closed my short on International Consolidated Airlines Sa (LON:IAG) and am now wondering whether to go long. But the share price has only corrected back down to where it was last summer. Is it really that cheap, now that we have no idea what earnings are going to be?
The TV reports on this kind of thing are very powerful. I expect "staycations" to become much more prevalent this year, across the world. Let's hope it's a hot summer. As for cruise lines, who on earth would want to book a cruise, after we saw that the lock down measures taken on the Carnival Princess resulted in hundreds of people becoming ill and even dying (old people are concentrated on cruise ships, after all) due to being quarantined. So expect a class action against Carnival (LON:CCL) for that, in due course. I remain short of CCL. Cruise lines & airlines rely on the cash paid up-front by customers, to finance their businesses. If bookings dry up, then many are vulnerable to insolvency. That said, customers could get some cracking deals in a few weeks or months, if you're prepared to take the risk.
Hotels - well that depends, as so far a lot of places haven't really been affected much, or hardly at all, by the virus. But what happens when it becomes more prevalent, as seems highly likely, based on the information & trends we currently have? Personally I wouldn't even entertain buying or holding any hotel companies' shares right now. The outlook is far too uncertain.
Bars - this is a bit more tricky. I was in the City last Friday, meeting management of Revolution Bars (LON:RBG) (I'm long). It was an excellent meeting, to run through the presentation slide deck for recent interim results. With coronavirus at the forefront of my mind, as I stretched out for a handshake, I did a double-take, and quipped, "Actually let's do a fist-bump instead of a handshake!". Whereupon, the softly-spoken, very calm and rather serious CFO clonked his large fist on mine, causing me to say, "Ouch - you were obviously a boxer in your day!". The CEO then quipped, "They don't call him Mad Mike for nothing!". It was a great icebreaker (and nearly a bone breaker too!).
Forget all the IFRS 16 nonsense, that's irrelevant. The key thing is that the business is recovering - underlying interim profit was up. LFL sales are recovering, with an improving trend - knocked back a bit by the flooding/storms in last 2 weekends of February, but the underlying trend is that they're now at a current run rate of about +3% LFLs. Costs are being well controlled, with increased wages cost in particular being mitigated with better staff scheduling & productivity (e.g. simplifying & speeding up the time to make cocktails). Amazingly they've managed to save £70k by finding a new supplier of goats cheese! Almost all the loss-making sites have now been disposed of through a deal with their largest landlord. Net debt is coming down (although note that the interim period end is a seasonal high for cash), but they're still on track to meet the forecast year end (FY 06/2020) reduced net debt figure, despite paying out about £.5m in order to exit the leases on loss-making sites. Still highly cash generative now that expansion capex is on hold, and new site roll-outs going to restart next FY 06/2021 - but looking only for large, city centre sites, so probably just 2 big new sites each year. Sounding out opinion on whether investors want dividends to resume. The turnaround is happening, it's not a hope, it's a fact. Therefore RBG shares look dirt cheap in my view.
Oh by the way, I asked about why receivables and trade creditors are both high? It's because volume-based rebates (prevalent in the bars sector) are shown as receivables, when they are billed to the main drinks suppliers. Therefore most of the receivables figure really should be netted off against trade creditors. I specifically asked if the creditors were being stretched in order to suppress net debt? The CFO (who I trust, because he's got a track record of giving me truthful answers to my questions at previous meetings) emphatically confirmed that RBG pays its suppliers on the agreed terms. Average payment terms are 40 days. Therefore, in my opinion, anyone who says that the balance sheet is stretched, is just plain wrong. Maybe they're confused by IFRS 16, which wrongly classifies future years' rentals as debt. When actually rents are future years' operating costs, which should not be on the balance sheet at all.
Is coronavirus a threat to bars/restaurants generally? Clearly yes, to some extent. A few months lost trading would be very expensive - with rent & rates having to be paid, with little revenue coming in, then it wouldn't take long for the more highly geared operators to go under. That said, would people stop meeting in bars? Some maybe, but many would just carry on, and take better hygiene measures such as washing hands, and using hand sanitiser, etc.
I think in the UK we're renowned for our stoicism. We've seen that with terrorist attacks - people generally don't change their habits or behaviour at all, after the initial shock has worn off. This was evidenced by a conversation I overheard in the Lord Aberconway, just after my meeting at FinnCap's offices to see RBG management. Thankfully there were 4 real cockney geezers in the pub. I say thankfully, because I didn't want to be the only person drinking peroni at 11am (I had a 1.5 hour gap between the meeting, and a lunch appointment at Paddington). I was struggling to contain my laughter at their conversation & probably the most extreme cockney accents I've ever heard. Anyway, the geezers started talking about coronavirus. I jotted down some notes to help me remember, given that it seemed highly unlikely this would be my only peroni of the day (well, it was Friday, and the market was in freefall). Their main comments were, "Well, it's just like a bad cold, innit?!", and, "If you're gonna get it, you're gonna get it!".
Cross-referencing that with the fact that RBG's core customers are aged 18-25 (about 10 years older in their smaller, "de Cuba" brand - which incidentally is trading very well - as you can see from the slides) - and of course at that age people feel invincible. Given that young people seem least affected by the virus (mild symptoms mostly), I see it as unlikely that they'll give up their Fri & Sat nights out. That is RBG's core business, where they make their profit. So it doesn't matter if their bars are empty during the week (which many are already), as long as the big Fri & Sat nights out continue to some extent, then they should be fine. There's a good geographic spread too, so even in an extreme case where some cities/towns are put into lockdown, then it would only partially impact the overall business.
The way I look at things, is to ask what would a share price be, if coronavirus had not happened? With nicely improving fundamentals, and more refurbs coming through (which are boosting LFL sales & have a great payback time of just over 2 years), then I reckon RBG would by now be around 100-120p. The fact that its shares are actually 60p to buy, says that they're cheap. Very cheap. That said, anyone buying now has to be clear that, if things get a lot worse in the UK with coronavirus (which seems likely to me), then the share price of RBG and many other shares, could get cheaper still, purely on sentiment & panic selling. The big problem with small caps, is that when people are panic selling, even if it's only a small number of shares, then the bid side can dry up completely - i.e. you can't sell in any size. Therein lies someone else's opportunity. But we need cash on hand, to be able to take such opportunities.
The other thing I noticed on Friday 27 Feb, in London, hardly anyone was wearing a face mask. In fact, after scanning what must have been many hundreds of faces during the day, I only saw a youngish man wearing what looked like a cycling mask (the black ones), and an oriental-looking woman wearing a paper face mask - which is common anyway, orientals often wore face masks in London before coronavirus. I'm still in London, and am looking out for face masks. I've got a small supply of my own, but feel that there is unspoken social pressure not to wear one. Mind you, going on the tube, I'm tempted to wear one now, given the appalling lack of hygiene shown by many. People are coughing & spluttering, with just a half-hearted attempt at putting their hand near their mouth - which is no good at all, without a handkerchief, which hardly anyone seems to carry these days. At Finncap's offices, someone from another company got into the lift with me, a youngish chap probably in his early thirties, and the second the door had closed he coughed heavily, twice, without covering his mouth. How un-self-aware can someone be? I was about to say something, then stopped myself, because in a confined space there would have been no escape route if he turned nasty. Just as I was weighing up risk:reward, he'd already exited the lift. Pity I didn't at least give him a perturbed glare, but he probably wouldn't have realised why, even if I had.
Why are the TV ads not inundated with Govt warnings, about always keeping clean tissues to hand, always covering your mouth if you need to cough or sneeze, frequent hand-washing & using hand sanitisers, etc.? People need to be taught these basics, as these common-sense measures which older generations had drummed into them back in the day (probably learned from the Spanish Flu epidemic just after WWI), but have since been forgotten. It's a bit like the foolish people who don't vaccinate their kids. They don't perceive a threat from these diseases, because they've been (temporarily) eradicated with mass vaccinations. So the diseases are now coming back again. We seem to need to unlearn, and then re-learn so many things. It's just like that in financial markets too - the same patterns of boom & bust play out in exactly the same way, every few years.
Mum mentioned to me that she was brought up with the slogan, "Coughs and sneezes spread diseases", and that she was always made to wash her hands before sitting down to eat. Now, people like a little wet towel to wash their hands at the end of the meal! Beforehand they're cheerfully handling a bread roll with their unwashed hands that were recently holding on to a handrail on a tube train that's probably covered in germs.
As an 83-year old asthmatic, I decided to put Mum in lock-down in her flat, about a week ago. But she's completely ignored me, claiming that she's more likely to die of deep vein thrombosis if she never goes out for a walk. So her daily trip out by free bus, to potter around, have a coffee at Pret, and drop off a small bag of clutter at the charity shop, are continuing to this day. She nonchalantly told me that, "If I catch it, I'll definitely croak it!". But Hitler didn't get her, nor did pneumonia or a heart attack a couple of years ago, so she's pretty relaxed about the situation overall.
Indices - are so volatile, that you can be right about the direction, but get stopped out, or suffer huge losses, if there's a big rally in between. I somehow managed to lose money on my Dow short hedges, during a 4,000 point fall! Timing is everything I'm afraid, and market timing is one of my weaknesses. It's so irritating to be completely right about the big picture, but manage to screw it up in terms of actions.
China supply chains - I'm less worried about this now. Of all the problems right now, this seems the likeliest to be fixed, as Chinese factories are going back to work, albeit slowly. Also, companies can mitigate, and potentially shift production elsewhere. We're far too dependent on China, in my view. So maybe one of the positives that might emerge from this crisis, is that companies might recognise that having a more distributed global supply chain is necessary. Although in the short term, expect lots more profit warnings, as UK inventories begin to run out, even if only temporarily.
Of the small caps I follow, Norcros (LON:NXR) stands out as having fallen a lot recently. It sources a lot of product from China, so is bound to see some disruption. Is it a bargain after having dropped by about a third? Possibly. Although with so many similar shares, it's only given up the gains from the big autumn/winter stock market rally. So we're really just back to where it was last summer. Does that make it such a bargain then? Arguably not really.
Online businesses - these should be some of the beneficiaries. After all, if people are nervous about going to the supermarket, or shopping the High Street at the weekend, then online shopping is the obvious answer. In my own portfolio, I see that Sosandar (LON:SOS) (I'm long) has sold off a bit in the recent, general panic. That doesn't make sense, as they should benefit from more home shopping. Also their balance sheet is cashed-up after a well-timed recent fundraising. Similarly, I see no reason for Best Of The Best (LON:BOTB) (I'm long) to have sold off. If people are bored at home on lock-down, then what better way to spend a bit of their now surplus-to-requirements holiday money by playing online spot-the-ball in the hope of winning a supercar?!
EDIT: Conclusion - pulling all this together, my current view (subject to change at any time, as the situation develops) is that the market doesn't seem to have adequately priced-in the increased risks of profit warnings, and the increased risk of a recession. Therefore, I am not actively looking to buy in the market just yet. However, I am building up a list of small caps that look attractively cheap, and at some point I'll push the buy button. Am just not sure that now is the right time. I don't see this as being a likely V-shaped recovery. It feels to me as if there could be (at least) another big leg down in the major indices. The reason being that the starting point (especially for the US market) was far too high - with stocks pumped up on steroids of cheap money, and a mindset of buying every dip (which so far has been a brilliant money-making strategy). But when that stops working, who knows how much downside there could be for US stocks? A lot, I think. The same could be said for more speculative, fashionable, UK stocks. Many look wildly over-priced to me still. End of edit.
Right, sorry if the above lengthy ramble has seemed OTT to some readers, but people seem to like me commenting on the major topic of the day, judging from the thumbs ups. I'll cover small cap trading updates & results below, in addition to the above.
Apologies, I nodded off on the sofa, after lunch. One of the dangers of being over 50, and working from home! Re-starting now, at 15:14. I see the Fed has just dropped interest rates by 0.5%, in a knee-jerk reaction. You can't stop a virus with interest rates. So that looks a flash in the pan to me. On to company news:
Vertu Motors (LON:VTU)
Share price: 32.0p
No. shares: 369.2m
Market cap: £118.1m
Vertu Motors, the UK automotive retailer with a network of 133 sales and aftersales outlets announces the following update with regards to the five-month period to 31 January 2020 (the "Period") ahead of its preliminary results for the year ended 29 February 2020.
Key points;
In line with expectations for the full year (which had previously been lowered, see below)
There's a lot of detail in the announcement, which I won't re-hash here. My overall impression is positive - the group seems to be making common sense moves to focus on margins, given that volumes are down. The after-sales (servicing) division seems to be trading well.
There are a couple of negative points flagged;
1) Commissions arrangements for financing are under review by the FCA (already known factor), and
2) Manufacturers taking parts stocking in-house is likely to be a £0.9m hit to profits for VTU in FY 02/2021 (and beyond, presumably beyond). To put that into perspective, it looks to be around 4-5% of profits - so a dent, rather than a write-off!
Broker updates - there are 2 good quality broker updates available today on Research Tree - thanks for those (Liberum & Zeus) as it saves us so much time, and keeps private investors properly informed.
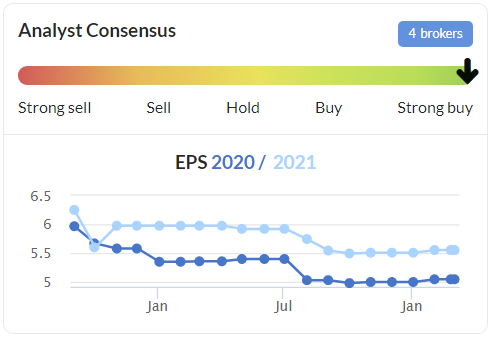
FY 02/2020 forecasts are obviously unchanged, as it's an in line update, at 5.0p EPS - a PER of only 6.4
FY 02/2021 forecasts are cut by nearly 10%, to 5.1p - still up on the current year - a PER of 6.3
Given the asset-backed (freehold property) balance sheet, then I see this as good value - assuming that forecasts don't get cut again of course. A drop to 4.0p EPS would raise the PER to 8, and a drop to 3.0p EPS would raise the PER to 10.7 - not such a bargain if earnings forecasts do fall again.
My opinion - this share looks excellent value. I'm impressed with how well profitability is holding up, in a tough sector where others are faring far worse (e.g. Pendragon (LON:PDG) ).
I'm uneasy with the FCA investigation, so it would be wise to read up on this, and try to assess what the damage might be, if the FCA levies fines.
I've checked the last reported balance sheet, and it's excellent, with lots of freehold property. Therefore the bank facilities should be safe (banks love freehold property as security against lending, as it de-risks things for the bank). The share price is currently well below NTAV.
The 5.6% dividend yield is 3 times covered, and together with a strong balance sheet, I think the yield looks fairly safe.
Overall then I like this share at the current level. It looks excellent value, and is nicely asset-backed too. Who's got the balls to by it though, given current nervous market conditions?!
As regards coronavirus, if people are cancelling their summer holiday plans, then who knows they might decide to treat themselves to a new car instead? Hence it could work out to be a net positive, possibly?
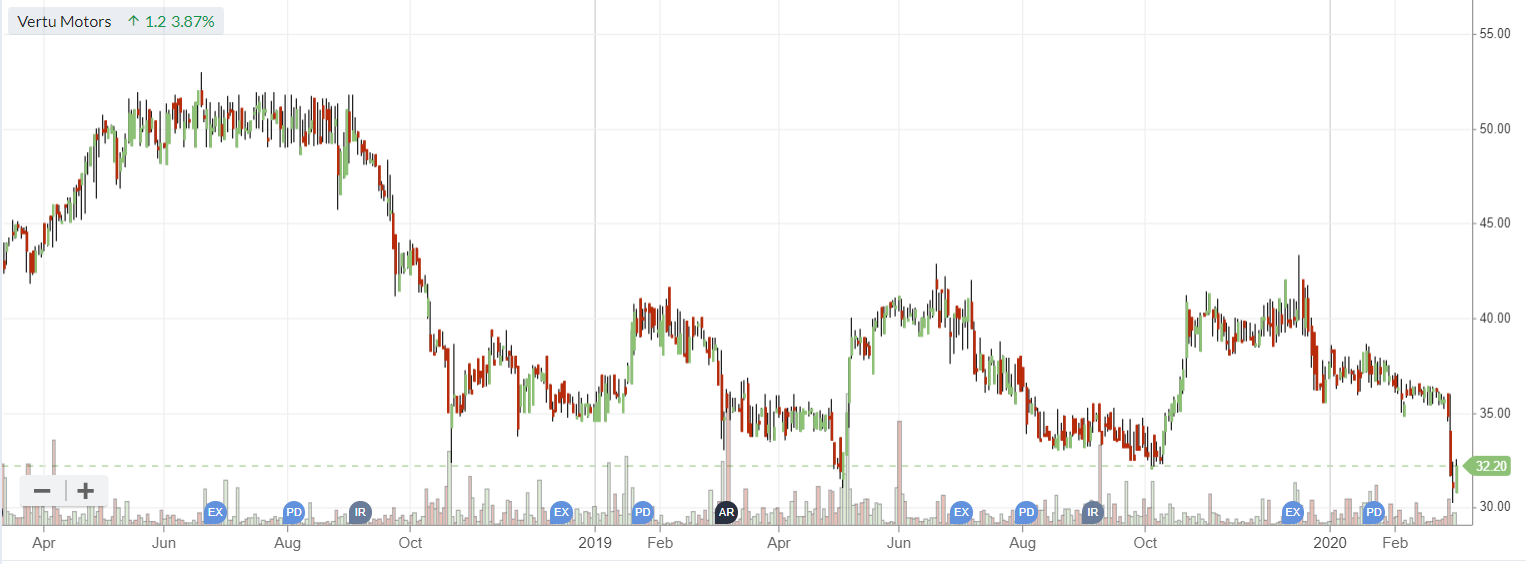
Looking at the 2-year chart, buying at the current level of just over 30p would have enabled us to make a 30-40% profit several times, and collect some divis along the way. Therefore this could be a nice trading idea? Or one for income seekers with a good, and well-covered yield.
.
Getbusy (LON:GETB)
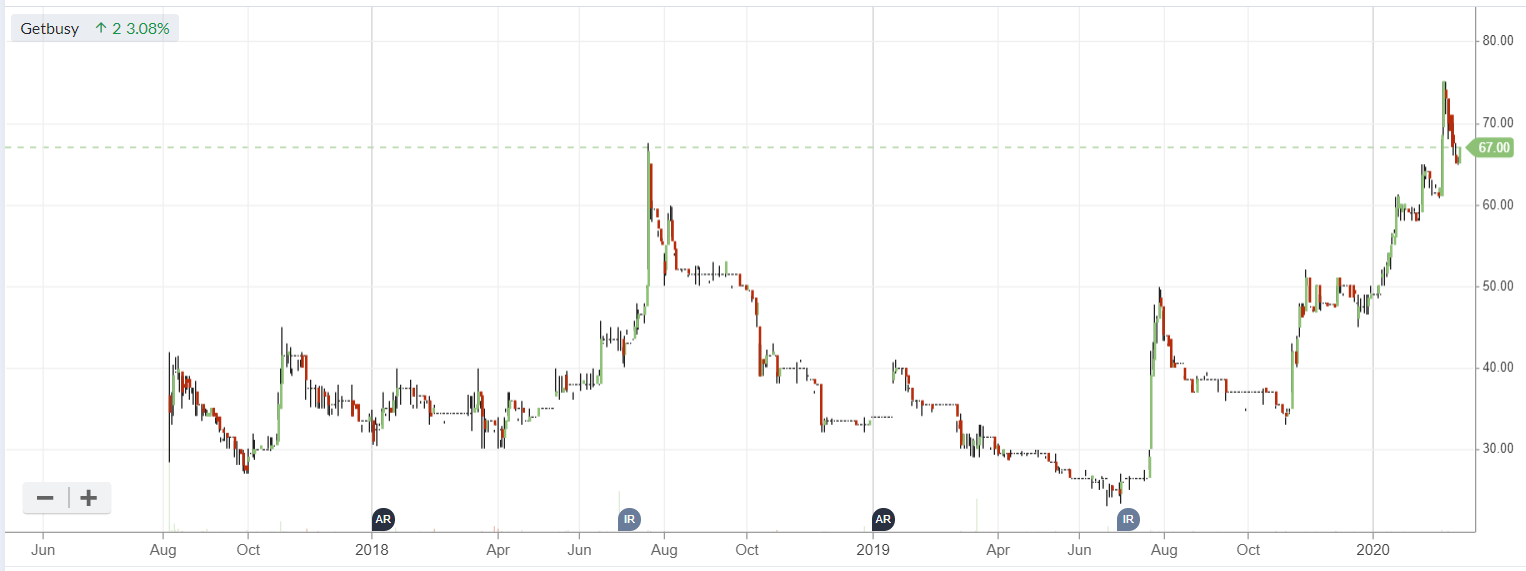
Share price: 66p (up 1.5% today, at market close)
No. shares: 48.4m
Market cap: £31.9m
GetBusy plc ("GetBusy", the "Company" or the "Group") (AIM: GETB), a developer of document management and communication software products, announces its audited results for the year ended 31 December 2019.
A pal of mine is very keen on this one, and I've been meaning to look at it properly for a while now.
It looks small, but complicated, at first glance! For this reason;
"Within our product portfolio we have an established brand that is well-respected and highly profitable, a rapidly growing and very scalable SaaS product that has clear product market fit and a new entrant that is seeking to carve out a lucrative niche in a sector that is undergoing disruption. This unique combination of products is a key enabler of our aim to be a long-term sustainable growth business."
There's a useful slide pack here - follow link then click on "full year presentation".
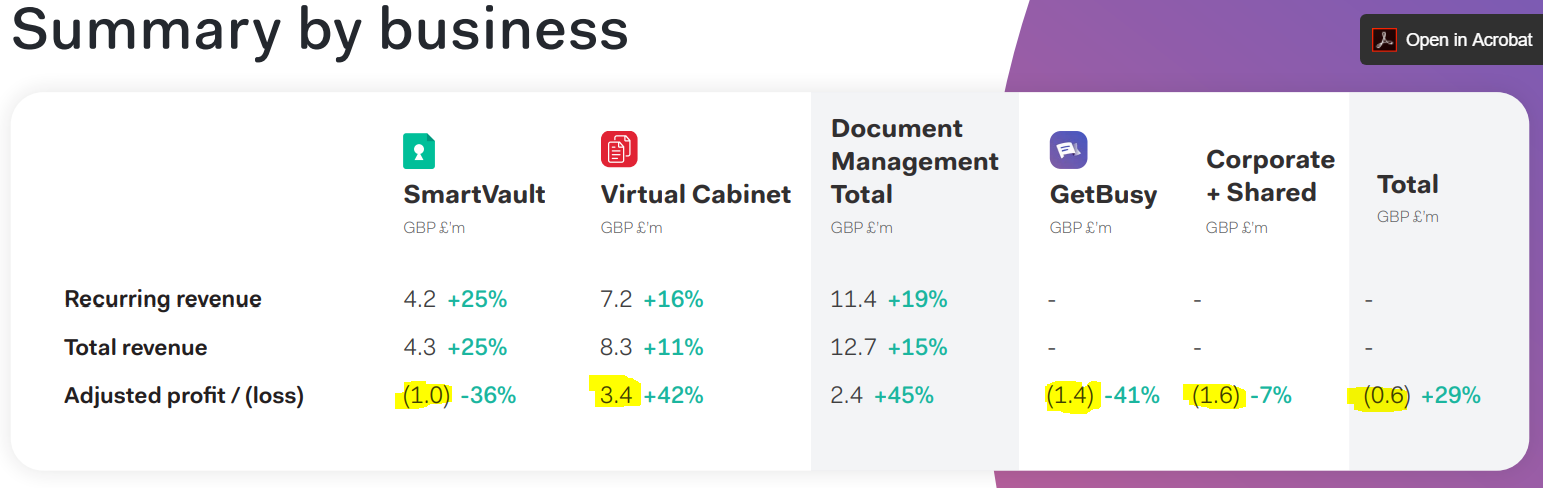
Slide 6, copied below, helpfully shows the breakdown of its various product divisions. I've highlighted the adjusted profit figures. What this is trying to show, is that the overall adjusted loss of -£0.6m is caused by 2 loss-making divisions, which mask the profitability of the Virtual Cabinet product. That's interesting, but personally I would tend to allocate most of the £1.6m central costs to the core business. So I prefer to look at it as a core business making £1.8m profit, with 2 loss-making ventures that lose £2.4m p.a.. Even so, that's still a lot better than all 3 divisions losing money. The implication being that the 2 loss-making divisions could be jettisoned if needs be, leaving a core, profitable business. So that's fine, I'm happy with this.
Another stand-out feature is that revenue is nearly all recurring, which is a very positive thing.
Overall losses of -£0.6m are modest, which is another plus point, compared with many other similar businesses which burn cash like it's going out of fashion.
.
.
Slides 11-13 show that the group seems to be mainly dependent on the accountancy sector for its revenues. That's great, it looks like it's cracked that niche. But will it be able to duplicate that success in other sectors? Maybe, but it could be costly & take time. That said, it can be a good thing for small tech companies to crack one niche first, then go for wider expansion later, once the running costs are covered by the core business's recurring revenues.
Slide 26 - Churn rates are very low, and improving (but shown monthly, instead of the more usual yearly). Even so, multiplying by 12 still leaves them low.
Slide 28 - shows cashflow. It's probably going to need more cash. Ah, I've just realised that it raised £2m in a placing in Dec 2019, but the proceeds did not hit the balance sheet until early 2020. Therefore we need to manually adjust the 31 Dec 2019 cash balance of £1.7m for the increased cash of say £1.8m net. Therefore it should now have £3.5m in cash, which is probably enough for now.
As always, presentation slides make me want to rush out and buy the share! That's what they're designed to do, after all.
Looking at the accounts next, can I find any funnies?
Capitalising development spending - very modest, I'm pleased to say;
On an IFRS basis, we have capitalised £0.3m of development costs in 2019, which relates solely to work carried out on Virtual Cabinet and SmartVault. Capitalised amounts in 2019 relate, amongst other things, to the migration of SmartVault to AWS, the development of the VC Go suite of mobility apps and the creation of key integrations for SmartVault. No costs related to the development of GetBusy have been capitalised as there is insufficient certainty over the commercial viability of that product at this stage.
R&D tax relief - not claimed yet, nor accrued for. So could be an upside surprise here of about £0.6m.
Outlook - sounds encouraging in parts;
We expect SmartVault's growth to continue to be strong, underpinned by a very encouraging start to the new year and investment in product development and customer acquisition that will be at a higher run-rate than in 2019. Improvements in Virtual Cabinet's operating margin will be driven by strong operating leverage and more modest recurring revenue growth. We are not forecasting any material revenue for the GetBusy product at such an early stage, although we remain encouraged by the initial progress thus far.
Profit figures - I'm not comfortable with the adjusted profit/(loss) numbers. To my mind, the statutory loss of -£1.2m in 2019 and a similar figure in 2018, is a more sensible & prudent way to look at things. A £-1.2m loss if fine for a growing tech business, I don't have a problem with that level of annual losses.
Balance sheet - is weak;
NAV: negative, at -£2.9m. Subtract modest intangibles of £650k, and NTAV is £-3.6m. Recurring revenue businesses can operate OK with a negative balance sheet, however, I would prefer to see NTAV decently positive. Note that the £2m placing in Dec 2019 would improve these figures by say £1.8m net of fees.
Current ratio: very poor, at just 0.46 . The reason is that there is a large creditor of £4.2m for deferred revenue. This is the book entry for cash that has been paid up-front by customers. Therefore the business is partly being funded by customers paying up-front. As it's about a third of annual revenues, this is not customers paying monthly, there must be lots who pay annually, up-front. Again, this will have improved somewhat post year-end, with the placing.
My opinion - this looks potentially interesting. My main worry is that the group seems to be trying to do lots of things at once, on a very limited budget. Trying to expand 3 products, internationally, on a shoestring, is a tall order. That said, I'm impressed at what they've achieved so far.
I'm not looking to buy anything right now, but this one is going on my watchlist, as something that I need to research further, and possibly buy on any pullback. I doubt there is any need to chase the price up, in current markets.
That's all I can manage today. Thank you for the positive comments, and unusually large number of thumbs up, so clearly readers like me covering current macro topics. I didn't think there was much point in ploughing through loads of boring company updates, when the market is so vilatile & fear-driven right now.
See you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

103 comments
Additional thoughts on coronavirus. Please remember that it is likely that coronavirus is will show a similar periodicity to another respiratory virus, influenza. In the US and in countries in Europe this means that cases are likely to decline significantly as summer approaches (probably starting in April) as the weather warms up. The relationship between the duration of viability of viruses in the air and temperature is reasonably well established and this may help explain why such viral infections are often much less frequent in the summer. When I used to produce viruses (bacteriophages actually) while I was working in the Public Health Laboratory Service, they were always stored in the cold room, otherwise viability would have been lost quite rapidly because of this temperature sensitivity. Unfortunately coronavirus is likely to re-emerge in the autumn before a vaccine is ready so the problem is likely to recur then. I will leave it up to others to explain possible impact of the waxing and waning of these coronavirus infections on share prices.
Coronavirus: I was brought up on that saying, just as your mum was. Apparently, 35% of people (and mostly the Younger Generation lol) are incredibly blase about it, as per the man in the lift you shared.
Tomb Sweeping Day in China falls on April 4th this year and is traditionally an event when Chinese abroad return home to celebrate their ancestors, particularly if they haven't been there for the lunar new year. I read today that the authorities are concerned they may bring the virus back with them, and expect cases to rise again.
I really value your thoughts and opinions so please keep them coming.
All the best,
Daphne
Hi Paul,
That was another mammoth effort again today and you've evoked a lot of great comment threads.
VMT's
James
Re facemasks it depends what you mean, the N95 is probably what health workers are wearing when they test people for Coronavisa in the UK, there is a N99 version as well I believe which is even finer.
" An N95 respirator is a respiratory protective device designed to achieve a very close facial fit and very efficient filtration of airborne particles.
The ‘N95’ designation means that when subjected to careful testing, the respirator blocks at least 95 percent of very small (0.3 micron) test particles."
In one test I read it was quite effective.
The U.S. Fed made a surprise 0.5% interest cut today. There was 600 point rally on the Dow that lasted all of 5 minutes - it is currently trading even lower.
This is a really bad sign. In the past, rate cuts have always been followed by a sustained market rally. This show that Central Banks no longer able to control events.
However, it is not really surprising as Covid-19 is not a problem that can be solved by economic stimulus. China illustrates that a highly aggressive strategy could contain Covid-19 but as others have pointed out similar actions will be very difficult in pursue in free societies. But the real issue for markets is that such containment strategies come at a huge economic cost, especially in terms of lower productivity.
Thus, even in the virus is brought under control, there is no good news for markets.
Big, early cut in rates in the USA (as opposed to 'too little, too late'). Market seems un-impressed. I try not to assume that the market's reaction will be logical to such exogenous factors and find explanations of the market's reaction to such things often overly-simplistic. But could this be a sign that the state of denial that the markets were in yesterday has reversed? That monetary policy is not going to be a particularly effective tool against market fear - especially when the starting point was, by some measures, historically expensive?
Souhern hemisphere winter is nowhere near as cold as it is in Northern hemisphere. Austrralla far too far away from the Antarctic so very low temperatures are rare. Occasional ground frosts in cities like Melbourne and Sydney but hardly ever an air frost. Obviously that's on low ground. They ski in the mountains. Southern tip of Chile is similar to UK winter. Also coronavirus is in hotter Countries already,
e.g Singapore has 110 cases.
One fact about coronavirus so far getting ignored is that the death rate for the under 60s seems to be very low., So why the need to close schools, factories, sporting events etc. Seems way over the top unless coronavirus gets worse. Otherwise why treat it any differently to flu?
Because 'young' people still host and pass the virus on to people in the at-risk category.
And along this train of thought, if considered as a weapon being used against an ageing population and it's impacts on the world economy, Coronavirus appears at this stage to be highly effective (i.e. symptom-less, high rate of infection, mortality rates amongst the general pop vs. the elderly etc).
but that's enough tin-foil-hat for today..
Paul great report today, thanks. I totally agree about airlines, some countries tourist numbers are already down around 40% and with more restrictions coming I can see that getting worse. It's not just about getting the virus but it's whether you can get home and even if you can you may need to do 14 days in isolation or even worse infect people at work. Even China is imposing quarantine on visitors of certain countries now.
You hear all too few genuine Cockney accents nowadays.
Love your market views! Also i was in Rev De Cuba the other week experiencing happy hr on cocktails, all made pretty fast in a very busy bar!
Hi Paul, I do enjoy the SCVR when you or Graham write a report such as this. It’s super relevant and really interesting. Thanks
With regards coronavirus, I found this update very interesting from Worldmeters:
Bruce Aylward, World Health Organization Joint Mission to China:
"I think the key learning from China is speed — it’s all about the speed. The faster you can find the cases, isolate the cases, and track their close contacts, the more successful you’re going to be. [...]
People keep saying [the cases are the] tip of the iceberg. But we couldn’t find that. We found there’s a lot of people who are cases, a lot of close contacts — but not a lot of asymptomatic circulation of this virus in the bigger population. And that’s different from flu. [...]
China got patients in treatment early and have highly sophisticated health care treatment procedures. They are really good at keeping people alive with this disease. They have a survival rate (with a mortality rate of just under 1% outside of Hubei province) for this disease I would not extrapolate to the rest of the world. What you’ve seen in Italy and Iran is that a lot of people are dying.
Panic and hysteria are not appropriate. This is a disease that is in the cases and their close contacts. It’s not a hidden enemy lurking behind bushes. Get organized, get educated, and get working."
Source: Vox Interview
Last night I watched on iPlayer a program from a couple of years ago on BBC4 called Contagion. They conducted an experiment to simulate what could happen in a pandemic and to aid future planning for such an event. This experiment co-incidentally started in Haslemere which was also the first case in the U.K. where the patient had not contracted covid-19 after travelling abroad. Fascinating insight into the maths and ‘super spreaders’, I would highly recommend watching.
Great update (as usual) from Paul on Coronavirus.
One thing to add is that the deadly Spanish flu epidemic that killed between 50 and 100 million, 100 years ago, started as a mild outbreak in early 2018, then died out before coming back with a vengeance in the Autumn of 1918. And the highest death rate was for the young and not the elderly.
It could be that something similar on the cards again?
Agree strongly re high risk market warnings. The big gains in the US last night and in Europe so far today could be a DCB. Though if Coronavirus news improves soon, a bear market might be delayed, and could be triggered after a big temporary rally, by almost anything, with return of Coronavirus (IF it goes away for a while) a near certain trigger.
I’ ve avoided (with the odd exception) shares on high ratings for ages as so many seem so expensive. Surely it’s these, rather than shares already at bargain basement prices that are most at risk?
The following few examples are off topic for a small cap bb, but seem worth highlighting, as while they are back to sometimes multi year lows, now or on down market days could prove a very good time to include them if, like me, preferring a diverse portfolio and also shares big and small and not just UK, but via bargain priced Investment Trusts, all round the world.
e.g AVIVA. 350p and yesterday went below 5 year low. Results Thursday. Dividend likely to be held, and is over 8%.
LEGAL AND GENERAL 262p. Has been lower. They report tomorrow and dividend increase likely. Dividend yield over 7%.
HENDERSON FAR EAST INCOME INVESTMENT TRUST 322p Dividend 6%.
EVRAZ 328p. This goes ex a 31p dividend this Thursday. That dividend alone is over 9%! But riskier than above 3 as profits down and risk that share being supported by that yield, but could drop more than the dividend on Thursday and after.
RIO TINTO £38. Goes ex a £1.77 dividend on a Thursday. That dividend alone is nearly 5%.
IG. £7. NOT near any low. Attraction is that it looks largely Coronavirus proof and market volatility is good for trade. AND note both PLUS and CMC have issued better than expected updates. IG is the best quality of the 3 and report in around a fortnight. Dividend around 6%. I’ve held since share price dip to £4.90p and their promise that the then 9% dividend would be held. Share now £2 higher. Explaining this as it shows that good upside for quality big Company and FTSE100 dividend paying shares if bought when few want to know.......as is the case for the other examples here! And add on those big dividends (very useful in market dips) and the gains can become impressive.
MARKS AND SPENCER. 165p.
I bought today. Share is at 32 year low!! A share with good recovery potential while others in the sector go to the wall, so less competition. Such a share should not fall too much further however severe a bear market. The bad news is priced in and recovery clearly isn’t, otherwise thecshare price would not be at 32 year low!
Marks are closing unprofitable stores and are about to go with Which Best Buy Ocado for their online food sales. Ocado are ditching Waitrose. OK clothing range seems dire... but surely that’s priced in, and long overdue improvement isn’t?
OIL sector bombed out, both big and small shares. E.g Shell and BP both yielding 8% Pharos, , formerly
Soco, is down about 85% from peak. Others are similarly cheap.
SYLVANER PLATINUM 59p. Had come back a lot in recent dip. Simon Thompson is very keen. Some rubbish all Investors Chronicle tips and some of their writers are very inexperienced, but Simon T (apart from not realising that those small AIM Companies like Naibu and Camkids were frauds) has a super record with his bargain shares portfolio. And he shares Paul’s forensic balance sheet skills too.
Finally 2 small companies that are appropriate for this bb.
ZYTRONIC. 143p. See the last two updates from Paul when he considered ZYT overall good value at much higher price than now. Cash worth 82p a share. Dividend cut likely. Broker thinks to 11.4p. That still gives 8% dividend yield.
SOSANDER. 16p. I bought back today the half I had sold at 30p after their decent trading update.
Should with hindsight have sold the lot, but if next news OK then could the halving of the share price be overdone?
I hold all the above shares, except (hoping for better buy opportunity) Henderson aFar East.
Hope being often off topic OK as a one off.
Great post Ken . Looking at MKS myself
"And he shares Paul’s forensic balance sheet skills too."
I don't think he does as can be seen with the different views on Globo, ST could not see it at all. Paul was highlighting all the issues. ST apart from his bargain shares does not publish any performance figures?
My concern with Aviva (LON:AV.) and Legal & General (LON:LGEN) is exposure to Coronavirus.
"My concern with Aviva (LON:AV.) and Legal & General (LON:LGEN) is exposure to Coronavirus."
And i'd expect the insurance industry is going to get clobbered by all the natural disasters so far this year , fires and floods etc (not been a great start to the year so far)
virus related illnesses are often excluded and insurers have reinsurance treaties to limit losses
Excluded by what policies do you mean?
Yes they may have Reinsurance and Excess of Loss policies but they will still bear losses and their renewal premiums no doubt will increase.
it depends what cover is being provided. It it is All Risks travel or medical insurance then obviously virus issues will be covered , but unless the virus causes multiple deaths I don’t see that life insurers will have too much exposure. And I am fairly sure this will all be over when the warm weather eventually arrives. Let’s hope we have a great spring !!
The renewal premiums may well increase but in a highly competitive reinsurance market,I suspect by not that much to cause investors any great concern.
I do hold Aviva but have been a long term shareholder and have no intention of selling .
We will have to watch the numbers in Iran as it warms up, hot countries have not been badly affected so far.
Both Aviva and LGEN have a huge range of insurance offerings including pensions and annuities. For annuities, high death rates from Coronavirus or other reasons means higher profits.
On a more general point, for big shares like LGEN and AVIVA, it's worth remembering that known negatives and positives get priced in to the share price. It's the likes of surprise profits warnings and profits upgrades that are not priced. in. i.e if we've thought of negatives so has the market.
A big mistake I used to make was to decide against a share because of a specific negative that put me off or a big positive that persuaded me to buy. . There are negatives and positives for every share I hold and there always will be.
And remember Aviva is at a multi year low. So a lot of known negatives look priced in.
Anyway both AVIVA and LGEN report this week, so decisions can always be taken after that and presumably both likely to comment on possible Coronavirus effects on their businesses.
Finally re the recent floods. Terrible for those suffering from them but the number of houses flooded compared with the number of houses in the UK as a whole are tiny. And anyway insurance companies expect to pay out for claims and adjust their premiums accordingly.
Yes some good points, I had not thought about annuities, I was thinking more about travel insurance and early deaths, had not thought about the floods. I do hold some Aviva (LON:AV.) in my SIPP more for income. I will keep an eye on Legal & General (LON:LGEN), I missed it last year. Yes best time to buy insurance companies is when they have had some big losses.
Thanks for your post, Ken. I'm sure it can be admissable, as you do mention two small-cap shares! I think it is important to realise that many here do follow diversified strategies, with large-cap, small-cap and investment trusts, especially for foreign themes. I hold, and have done for some while, the first three in your list and think that Legal & General (LON:LGEN) in particular is one for the pension. They have evolved over recent years to be, amongst other things, a serious developer of real estate to support their annuity payments, so they have more control than most of their own costs. Our parents' generation said, "Never sell Shell". I tell our children "Never sell LGen". 14% compound growth in DPS over the last decade, and if tomorrow's results go down with the market, I'll buy more. I think its internal asset management has turned into a Buffettesque Moat.
But I'll look at Zytronic at that price.
My small-cap rejoinder for these psychologically difficult days is Somero Enterprises Inc (LON:SOM), for a company that is plugging away, expertise in-house, cash-generative, debt-free (sympathy with Paul's balance-sheet concerns), operating a niche within a long-term growth industry, earning in $ to balance a UK post-Brexit slide. Forecast P/E around 8, div 7%+.
And if it weren't financial again, try Chesnara (LON:CSN), which is still small-cap. It may not be Legal & General (LON:LGEN), but I don't see any reason for a 13% drop in two weeks, to an imminent yield of over 7.5%.
Thanks JTG.
I hold Somero. Pleased with dividend increase from LGEN today.
Thanks for the Chesnara prompt. I regretted not buying many years ago and haven’t looked for ages.
Presumably the 13% recent fall is partly Coronavirus. Their results were late March last year so might wait for those for any Coronavirus comment and possible negative effect on their otherwise progressive dividend policy. Focus seems to be more on pensions business rather than annuities? If that’s correct a possible negative if Coronavirus deaths increase a lot.
Agree with your LGEN comments. I’ve held since that astonishing buy opportunity immediately after the Brexit vote, and a (more astute) friend has held since they fell to 60p, and now gets over 40% in (growing) annual dividends. Might be a better buy opportunity for anyone tempted if, as seems likely, more general market falls ahead. But that big dividend and confirmation today of no change in progressive dividend policy, should limit he downside
Thanks for your thoughts Paul on Covid-19. One thing which is missing from most of the media commentary I've seen is the impact on shipping. Just now there is a significant shortage of Containers (stuck in congested Ports in China), and the shipping lines are cancelling sailings as a result. Whilst things seem to be improving slowly in China ports, there is significant potential for similar problems in other hubs around the world (HK, Singapore, European and US hubs) in due course. A Supply Chain is only as good as it's weakest link. Factories operational in China, doesn't mean the problem is solved.
Very good point, Dave, thanks for flagging. Even if China factories get back to full speed, and catch up on backlogs, then actually getting the goods shipped to end markets could add a further delay (and increase the cost of shipping). Therefore, we could be looking at summer, perhaps, before supply chains get back to normal. Possibly even autumn, who knows?
I think the biggest benefit of wearing a mask is probably stopping you touching your mouth with your hands, that may have touched an infected surface.
They must also have some benefit in reducing the infection risk to others if you wear one when infected and likely to cough.
Plus, wearing a mask will probably guarantee you a double seat on the train ;-)
Viruses are apparently quite fragile outside of the body, and ultra violet rays in sunlight can easily damage them. So perhaps not just heat but growing daylight hours can help ameliorate transmission, but perhaps dark poorly lit places should be avoided (London Underground!).
Paul, might here be a chance that Sosandar may have supply issues if they manufacture or buy from China,/far east, hence the fall in price.
Sosandar (LON:SOS). Most of their mfg is done in Bangladesh I understand. However I think a fair amount of the cloth to make this is sourced from China. Product is air freighted to Manchester so they don't have the problem with congested ports and missing containers. Its never simple but that international trade for you
Re Sosandar (LON:SOS)
Forgive the repetition ( posted this a few weeks ago) but this is what their PR agency told me on the 5th February:
Sosandar isn’t seeing any disruption in its manufacturing – the Company has less than 5% of its manufacturing in China, and the manufacturing in the region is knitwear so isn’t being produced until much later in the year.
Cheers
Francis
I asked Sosandar (LON:SOS) mgt about China risk (and posted about it here previously). They said very little exposure, with the 5% figure also mentioned to me, and could easily be relocated to another country if needed.
However, a point I thought about earlier, is that a great deal of fabric is made in China these days. So manufacturers in other countries could possibly struggle to secure the fabrics they need, maybe?
Hi Paul, good point Re Sosandar (LON:SOS)
However, I'd like to think they would have told me this in their reply to my question which was worded as follows:
I’m an investor in Sosandar and wanted to know what proportion of your stock is currently manufactured in China and what if any interruption you envisage as a consequence of the CoronaVirus?
cheers
Francis
In a previous incarnation of self I was a farmer in Australia in an area that we could grow cotton. The cotton crop was a very important part of the local economy and very profitable to grow.
To put it into perspective though, I believe there is at least one Chinese cotton mill alone that processes more cotton than the entire Aussie annual production!
Their wool mills similarly process vast quantities of world production.
My point being, supply chain issues could arise.
Anther angle to think of is what % of final cost is fabric in a final garment and how much fabric do you need to source .
For this reason I am more positive about smaller & more premium priced fashion suppliers eg Sosandar (LON:SOS) then price driven, big volume sellers sellers eg Boohoo (LON:BOO) and Primark plus the supermarket brands. The former can be more agile and can absorb any cost hit better. The latter may even be forced to put prices up.
This also plays into the growing awareness of the environmental cost of throwaway fashion - so consumers can justify a change in habit away from 'newness' to 're-usability' of clothes. Obviously, this is at the margin but I think will be a cumulative trend
However, personally, I expect the specific 'Corona' induced supply chain issues to iron out within 6 months but with a bit of an inflationary bump (via lots of youngish Chinese workers sniffling but doing overtime and the switching of some sourcing to 3rd countries!).
Great column Paul. I like the sound of your Mum (especially given what she has had to put up with!) ;-)
LOL, what do you mean her asthma, or me!! ;-)
Amazing Paul how do you (and Graham) do it day in day out almost every day day, all before 1:00. And its cogent, lucid and sensible. Big thanks.
Thanks Purpleski, we try our best! :-)
Great reflections, Paul. Our focus here is solely on coronavirus - but the US political situation should not be totally ignored. I would be surprised if the market in general would not much prefer a Trump-Biden choice than a Trump-Sanders choice. Since the weekend, Biden’s chances have improved (as has the market recovered along with soothing words from Central Banks). Today is Super Tuesday and afterwards, we will have a much better idea of where the Democratic race is.
I am not saying the market is being largely driven by coronavirus - but as ever there are always other factors too.
Large numbers of Chinese are in the habit of wearing masks because of the pollution, so they are habituated to it.
I am not competent to compare molecule size of particulates in pollution compared to viral droplets. But suspect the nature of the protection of masks for pollution is probably better than diseases.
A Chinese lady I know wore a mask on a bus yesterday, and was queried by the bus driver (in a polite way) but in a rather unusual aside, as if she was scaring passengers, as people wouldn't sit beside her. She said she was protecting them, and was rather glad in the event no-one unmasked sat beside her.
It does attention to oneself and arguably some English people would rather die than stand out from the crowd :-)
Yes in Asia masks are commonly worn on public transport and when serving food etc. N95 masks are meant to be better than surgical masks but are not so comfortable and make breathing more difficult, N95 is mainly for pollution. However one study in the US of health workers who treated flu patients found there was not much difference in infection between the 2.
I did just see this "China: Travelers from the virus hotspots of South Korea, Japan, Iran, and Italy arriving in the capital will have to be isolated and placed in a 14-day quarantine, a Beijing official said."
That reminds me of a funny moment in a recent interview I heard online with Toby Young. He took his daughter into A&E, after one of her fingernails was somehow torn off. They waited many hours, so Toby stopped a Doctor, and said, "I'm worried that the Chinese man sitting over there might have coronavirus, shouldn't he be quarantined?". The Doctor became furious, and accused Young of racism, for singling out a Chinese-looking man.
Young then quietly pointed out that the reason he suspected the Chinese man might have coronavirus was not racism, but was because he had walked into A&E and loudly told the receptionist that "I think I might have coronavirus".
Classic!
Hi Paul,
Thanks for all your excellent work. I wondered if you had any thoughts on Getbusy which reported this morning? I see that they are changing the p/l measure they use which I think has been spoken about before?
It still looks an interesting business in an area that is definitely not subject to Coronavirus!
Hi MH1, OK I'll look at Getbusy (LON:GETB) next.
I enjoy your comments on current events that effect the market. I always look forward to reading them as it often gives me some different points of view on what's going on.
One thought paul. Spring is just around the corner for europe and that normally sees off most of the flu type illnesses that are around.
Could this possibly have an effect?
Good point, Andrew. I've not heard anything about that, and am not a medical person myself, so don't know. Some suggestions are that coronavirus could come in waves. Given that we also have no deal Brexit risk, which is likely to get investors in a lather again this autumn, I can imagine that another wave of coronavirus at the same time could make things very difficult again, who knows? Given that the outlook seems difficult, I think we need to be very careful not to overpay for shares, as risk doesn't seem adequately baked into prices yet, in my view.
I am a Dr and consider myself very uptodate with coronavirus
In short - we have no idea whether warmer weather will make any difference. Remembering the swine flu of 2009 - that happened in the summer.
I think the main impact of the weather would be that come summer, normal seasonal flu cases would be taking up less beds, so the hospitals would be marginally more able to cope. The emphasis there is on marginally.....
By far the biggest problem as I see it is that one can be carrying - and spreading - the virus yet be, at least for a while, entirely symptom-free. This seems to be the big difference between this and a superficially far more dangerous virus, such as ebola. It's a bit like having a trojan hiding in your computer, ready to wreak havoc at the appropriate moment, but invisible until then.
It's therefore very difficult to see how the spread of the virus can be contained at all in any meaningful sense. By the time someone's displaying symptoms they may already have infected hundreds or thousands of other people, and each of those people will be doing the same. How many of us now sat at our keyboards are carrying it, and infecting our friends and families in blissful ignorance?
It's simply not realistic for people to isolate themselves from others to the extent required unless they're prepared to give up anything like a normal life entirely, which they aren't. I suspect the net result is that far more people will be infected than has been forecast, and the economic social and damage will be far more serious.
Thanks danyou, good to hear from a medical expert.
Something that occurred to me, is maybe warmer weather in the Northern hemisphere might ease things here, but presumably cooler weather in the Southern hemisphere could lead to infections rising there instead, and then coming back again when the Northern hemisphere moves into autumn/winter again?
Yes that is true but most of the cases are in colder climates, must be over 90%, South Korea has so many cases but Thailand has very few cases even though it had no restriction on Chinese tourists, last year Thailand had over 10m Chinese tourists and with Chinese New Year there were still plenty visiting this year.
Great article , The panic and hysteria is contagious . Just heard about a mobile hairdresser who has had a lot of cancellations as she has recently returned from Venice - real grass -root level but this highlights the mind set . I too keep getting wrong footed on trading the indices - will sit on the sidelines looking for long term value. My Missus keeps talking about wearing masks ...but erm .... er thats a different story..
As regards Revolution Bars (LON:RBG) I think most young people will still go out but if they were to lose just 5% of their customers it could make a hole in their profits. With the general concern it seems unwise to open new holdings at present which, of course, will make stockmarket falls self-fulfilling. Personally, even at the risky 75 years of age my main worry is whether the football I attend will be cancelled and there is absolutely no way I am not going to get on a plane to go on holiday.
Got sent this today - interesting view point on the recent day's rally.
As John Rosier said in today’s Johns investment chronicle, the ‘5.1% jump in the Dow Jones yesterday was only bettered on 10 days in the last 80 years! The ten others were Oct 20 and 21 1987, July 24 and 29 2002, Oct 10 & 28 2008, Nov 13 & 21 2008 and March 10 & 23 in 2009. In all cases except the most recent markets went lower over the next few months but were significantly higher a year later. I don’t see why the current episode should be any different.’ https://johnsinvestmentchronicle.com/
John Autheers on Bloomberg this morning. I have quoted in full as the link doesn't work
This Tigger Market Owes Much to the Buck
Bouncing’s what Tiggers do best, as we all know. And after a big fall, we can all expect a stock market to stage a Tigger. That is certainly what happened Monday, as the S&P 500 gained more than 4% for its third best day in the last 10 years:
Note that all the previous big positive days come soon after big negative days. There is little reason in itself to be excited by a market like this. The scale of the bounce has much to do with the scale of the drop before it. In evidence, I can cite that the best day for the S&P since the war was Oct. 13, 2008, in the aftermath of the Lehman collapse, when the index gained 11.6%. It foretold nothing much about the future. Anyone who bought at the end of that day still had to endure another 27% selloff before the index finally hit rock bottom five months later.
But beyond customary caution about trading bounces after a large fall, we also need to look at how the currency helped Tigger on this occasion. A chunk of U.S. stocks’ great day was driven by the weak dollar, which makes things feel better for Americans but not people from overseas. This is that same chart, this time denominated in euros:
Still a good day, plainly, but no longer so remarkable. The currency’s weakness is central to Monday’s events in more than one way. Beyond flattering the S&P’s percentage gain, the lower dollar is also an artifact of dramatic moves in rates, which in turn are driven by some dramatic and very optimistic assumptions about what central banks can do, and how much they can co-ordinate. Every decade or so there seems to be a reason for central bankers to club together. Most famously and explicitly, the Plaza Accord of 1985 weakened a dollar that many found cripplingly strong, while the G-20’s London agreement in 2009 was billed by Gordon Brown, Britain’s premier at the time, as saving the world. More recently, the rather more implicit Shanghai Accord in early 2016, following two disorderly devaluations for the Chinese currency, eased the pressure on Beijing. The dollar weakened, as the Federal Reserve held off on planned rate rises until the end of the year.
Monday’s excitement has been driven primarily by news that the G-7’s finance ministers and central bankers will convene Tuesday to discuss measures to counter the economic effects of the coronavirus, in combination with hints from a succession of central bankers that they are ready to ease monetary policy if necessary. U.S. interest rates are higher than in much of the developed world, and so almost any action would involve a weaker dollar. That explains a remarkably sharp reversal for the dollar, which Monday dropped below its 200-day moving average, having apparently broken decisively upward only a month earlier:
The dollar’s decline has in turn been driven by the fall in U.S. rates. Generally, all else equal, higher interest rates will strengthen a currency as they attract funds. Since election day in 2016, the excess of U.S. Treasury yields over equivalent German bunds has ballooned to remarkable levels, helped both by negative rates in the euro zone, and steadily rising policy rates in the U.S in 2017 and 2018. That differential reached 2.8 percentage points at one stage. Following the slide of the last week, that gap has dropped to 1.8 percentage points. That brings it back almost exactly to where it was on election day — and the dollar-euro exchange rate is also back to its election day level:
In this chart, note that we would usually expect the two lines to move roughly in alignment. Instead, the dollar stayed fairly weak as the differential in its favor widened, and then kept crawling upward as the gap narrowed. It is only in the last week that both have behaved as theory would dictate and fallen together.
Why? In part, it is down to the vagaries of trading. Investors have given up on carry trades, which generally involved borrowing in euros and investing in dollar-denominated assets such as the S&P 500. That means net selling of dollars and buying of euros. Pure psychology has a role — such a sharp move in differentials commanded attention. There is also still a lot of speculative money betting on a strong dollar. That makes betting against the U.S. currency very attractive for those who believe that the Fed will cut early and aggressively.
Finally, the weaker dollar reflects a belief that G-7 policymakers can deliver a meaningful package. Other central banks will be much more comfortable about loosening policy if they are assured that the Fed will ease even more; and so, bet on a weaker dollar. And coordinated fiscal measures — to make public investments that mitigate the economic effects of the virus, if not the human ones — would mean less need for the dollar as a shelter.
The question is whether this has gone too far, too fast. Again, 2008 provides disquieting evidence that markets can get over-excited about politicians’ ability to get their act together. The stock market was higher at the end of the week after the Lehman bankruptcy than it was at the beginning, because of excitement that Congress was about to bail out the banks. Those hopes proved premature.
The coronavirus may indeed provide a convenient political excuse to switch toward fiscal expansion. Many economies could use it, and low rates make it more affordable. But fiscal expansion in the euro zone is politically and constitutionally difficult, while in the U.S. it is made far harder by the huge increase in the deficit that accompanied the 2018 tax cut. The deals of 1985 and 2009 were a long time in the making. Nothing that ambitious can come any time soon. The fact that Plaza and London and Shanghai have been widely cited in the last 24 hours does therefore suggest that there is now a lot of room for disappointment.
Paul. Masks are of no use in stopping you catch the disease. They cannot prevent the virus entering your body. There will be gaps around the mask through which the virus can enter and the virus can also enter through your eyes. Masks are only of use in stopping someone who already has the disease passing it onto other people, by keeping the viruses inside. Even then you must change the mask frequently and dispose of it in the correct manner.
That doesn't make sense to me. If the gaps around the mask let in germs, then surely they would also let out germs?
I'm sure that masks don't guarantee anything, but they must reduce the risk, surely? Which is a good thing. Why else would the Chinese be insisting on people wearing masks, if they don't work at all? And why do medical staff almost always wear them, if they don't work?
There are always gaps around the masks unless they are the masks and body suits that make you look like a beetle so you are correct about masks letting germs in and out. It means that most masks are of limited effect in stopping you getting the illness. The benefit seems to be mainly psychological. They are of more use in helping to prevent an infected person infecting others. I guess that is why the Chinese insist on their people wearing masks. To stop those who might be infected passing their illness to others. They might insist on everyone wearing them because they are not confident that they know everyone who has it.
Medical staff wear masks to prevent their germs affecting the patients, not the other way around.
The WHO guidelines for the public are:
Listening to an 'expert' on TV, he confirmed the masks are no use, as the virus is so small it passes through the mask, you can get 10,000 virus lined up in 1mm of space, the masks don't filter particles this small.
Masks are no use. From what I see on the tube is - the people wearing the masks look absolutely terrified. A cough or sneeze in the carriage only increases the look of terror in their eyes.
Old fashioned hand washing is the only answer* - it not only prevents spread but also helps individuals from picking up the virus because you are likely to touch something or someone infected with your hands... washing your hands in soap kills viruses.*
Also worth mentioning that hand sanitisers are of limited affect and are not as good as soap and water. They should only be used twice before resorting to a hand wash.
* Hand-washing should be done for 20 seconds and hands dried thoroughly.
**Soap kills viruses by breaking down the fat compounds in viruses.
If you get a chance, following its trading update, Vertu Motors (LON:VTU) please today Paul, thank you.
Morning MrContrarian,
Great snapshot as ever. I understand your negative view on XP Power (LON:XPP) but actually going short seems brave to me. Is it just a negative view of the company's prospects or do you suspect foul play, or lack of cash?
Doug (who's long)
I though it was likely to be hit by component shortages at some point and/or delayed orders due to customer production hold-ups.
I clearly made a mistake not closing my short at the open when it was up only 50p.
I'm (pleasantly) surprised myself by the market's reaction this morning. Given XP Power (LON:XPP) 's current valuation I didn't expect a rise this morning, in fact I expected a nasty fall. From a long term point of view I'm happy to hold but I thought today, and maybe the short term, would be worse.
And this is why I don't do much trading, but more long term holding.
Greggs has warned that, despite record profits last year, storms that hit the UK last month have caused a “significant” slowdown in sales.
The group warned that the potential impact of coronavirus meant that the outlook for 2020 was “uncertain”.
Greggs (LON:GRG) So why are the shares up 5% today?
There was a very positive trading update today - sales up 13% and pre-tax profits up > 20%. Mention was made, though, of worries about the coronavirus and problems caused by flooding.
Greggs (LON:GRG) I see thanks, did not seem to make sense from Susan's comments.
So, not to give an opinion on ‘you know who’ and having just finished reading the philosophers stone to my children, it remains the villan and the threat to portfolios.
https://www.sciencemag.org/news/2020/03/china-s-aggressive-measures-have-slowed-coronavirus-they-may-not-work-other-countries
This report by ‘WHO’ is worth reading. It details how China contained the spread of of the virus, with the intention of slowing it down, the worst possible outcome being the uncontrolled infection rate. Now controlled is the relevant word and quite incredible how this was achieved over 50-80 million people. Maybe scary id the right word if you are not a staunch communist.
Anyway, this isn't about my opinion about what may or may not happen but it begs the obvious question ‘can the rest if the world act as China’ . So probably not, and if not, then what is the forecast for infection rates (and supply & the economy & business etcetc).
The initial comments a few weeks ago from many were to compare it to the death rate of the flu, that was missing the point, supply chain & effect of quarantine. The point i think now is does the world have to follow the china model and what if it cannot?
Hi John,
It's certainly something I considered when I originally read that China had begun to demonstrate some success in curtailing the spread. If we accept the hypothesis that this information is correct (arguable), can we honestly believe the rest of the world would be able to handle the situation in a like manner? I would say liberal democracies generally aren't falling over themselves to sign up to martial law.
But then I counter this by knowing that one of the positive aspects of the alarmist media sentiment is that people are taking this very seriously (deservedly so), and that a unified community response (something not unique to China) coupled with high calibre medial professionals (something Europe can surely claim) gives me hope that the rate of new cases can be managed until the warmer months are upon us.
In the spanish flu outbreak in 1918/19 there were three waves and it was the second that was the most lethal. Given how infectious it is, Coronavirus is likely to come back until either a large percentage of the population have had it or we have a good vaccine.
.
Robert Walters (LON:RWA) has gone under the £400m market cap mark today on virtue of its share price fall.
With 41% of its fee income derived in Asia, you can't blame the markets for not liking it and the company seem to be setting up for a drop in profits for this coming year. The previous year may have provided soft comparators which included Hong Kong, Brexit, gilet jaunes, but the coronavirus is impossible to quantify at this stage.
I have a long position here, personally I like the performance of the company and longer term I do see more direct bank intervention.... buying bonds isn't enough and to put money in the hands of the people jobs have to be created.
Their cash pile certainly allows them to weather a rough period and maybe to acquire weaker companies. Anyone else got any thoughts?
Robert Walters (LON:RWA)
I previously held but sold last year when their UK numbers deteriorated
Reading through their results, message remains the same, international doing well, UK is a drag on revenue. Of course the HK protests and now the virus will now be a headwind. Strong balance sheet, net cash, so shouldn't go bust in a downturn.
RWA is run by the founder. I've worked with one of their Asian offices, it was a good operation.
Long term, I would like to hold again as I have a view this is a well run business, but not until the economic impact of the virus is clearer, as recruitment is cyclical and if there is a downturn, recruitment slows down significantly. So I'll wait for that. Need the real world impact of the virus to feed through the chain a bit further.
Live (LON:LVCG) I have been super bearish on this company since September 2019 (share price has fallen 70% since then). Basically they bleat on about revenue and totally ignore everything else so real profitability is a long ways off, loans frequently having to be re-negotiated, bills being paid off by share payments, Directors not getting full pay etc., Personal property being rented out to the company until giving it 'free' to the company because the company cannot pay the rent. It's a sorry history.
Today they continue the same theme in their RNS. all about claimed forward revenue (although again history says these plans do not always come to fruition). Claims that the year to date; or shall I say Year to Virus/Market fall is all hunky dory and effectively claiming COVID-19 is not a problem for them. Unbelievable.
Underlying all of this I do think there is a real business here; but perhaps its best they go bankrupt and someone picks up the assets for next to nothing. Current management are good at sales but total inability to manage the business.
No doubt today there will be a spike in the share price offering realists the opportunity to bail out.
my thoughts are where is the report ?
Hmm, lots of red thumbs for that comment.
Has anyone thought that as a relatively new member, maybe caper4 is unaware that Paul puts up a placeholder so that people can comment on news and then writes the article during the day?
The placeholder often explains that, but today's does not.
Hmm. I’m wondering if 30 red thumbs in 32 minutes (at the time of writing) is a record of some sort.
Perhaps the uncertainty is making us unusually grumpy.
Surely the record is an hour without mentioning you-know-what? I mean, this is the SCVR (Speculative CoronoVirus Report), no? :-)
But if I can digress onto something to do with small caps instead,I noticed that Barkby (LON:BARK) has made another acquisition. It's a curious beast - it looks like an old fashioned conglomerate: commercial property development, pubs and coffee shops, a used car dealership, coffee cup packaging and, err, digital health.
It recently arrived on AIM via a reverse takeover:
https://www.investegate.co.uk/...
Can't say I'm immediately attracted but it's a curiosity, will be interesting to look at the first set of results for the new entity.
timarr
Thanks for this note on Barkby (OFEX:BARK), Tim. As you say, a curiosity. I don't think we can be in a bear market yet. The Stockopedia computers have come up with a NAV of £1.5 million. The admission document gives only half a million, AFTER placing proceeds of 5 million. Either way a market cap of 13 million is putting quite a lot of value on the skills and expertise of the directors.
thanks for the clarification
Yes I agree Gromley but I think it is tone of the comment?
Yes I agree Gromley but I think it is tone of the comment?
This is just perception though, isn't it. Maybe the poster is not a big user of social media. If you want to misinterpret the tone of a message, you should see the emails I get from my 80 year old mother! :-)
On another note (and I must firstly apologise for discussing shares in the Speculative CoronaVirus Report comments section) I see that the FD of Tristel (LON:TSTL) has exercised 157,000 options at a cost of 1p each and sold the lot for £4.31. She only holds 45,000 shares. I used to hold Tristel (LON:TSTL) but became disillusioned by the directors behaviour with regard to share options. If you hold, make of it what you will, but it makes me uneasy.
All the best, Si
Yes it is a perception so that is why you have to be very careful with “social/interactive media” how and what you write.
Likewise I don’t whether the Speculative Corona Virus Report Comment was tongue in cheek but COVID19 is likely to be the biggest thing that impact companies of all sizes since 2008/9 or if you believe some people before that. So I Paul’s thoughts and commenters on COVID19 are completely relevant.
Likewise I don’t whether the Speculative Corona Virus Report Comment was tongue in cheek but COVID19 is likely to be the biggest thing that impact companies of all sizes since 2008/9 or if you believe some people before that. So I Paul’s thoughts and commenters on COVID19 are completely relevant.
Of course it was tongue in cheek but it was timarr what started it...
I'm glad you find the mass speculation about this virus thing interesting. I would think even people new to investing can identify which companies are likely to be hit and take appropriate action - you don't need to be a seasoned investor it is so bleeding obvious.
Meanwhile people are speculating wildly and drawing conclusions using dodgy data about this virus thing, even though I admit it may be the best data available. If you have bad data it is difficult to draw any meaningful conclusions (crap in, crap out etc.) although it seems a great way to increase the noise in this comments section... All I see is otherwise intelligent people deluding themselves.
I felt sorry for Graham yesterday. He puts great effort into analysing and writing about the small caps releasing news and only four posts (well done Frugaltree, abtan, shanklin100 and zipstuck) out of 65 (to date) commented on the companies he covered.
Si
"I'm glad you find the mass speculation about this virus thing interesting"
Mass speculation is the activity many on here are carrying out....which includes speculating on factors which effect our specific speculations. Often using dodgy/incomplete data eg accounts of AiM companies. Such is the nature of stock speculation, attempting to make profitable decisions based on incomplete/inaccurate data in an uncertain environment. So yes, by definition many people are likely to be interested.
For those that aren't there is always the scroll wheel.
Just saying I agree with Simoan's comments re COVID19, having to post since I can't get the Thumbs Up button to work.
Caper4
I see you only joined 13 days ago so you probably don’t know the protocols here at Stockopedia (I am a member not owner BTW!!) but we are polite, tolerant, dont go in for personal abuse and have constructive discussions about stocks (and try to stay away from politics - that will make Paul laugh coming from me).
Paul posts his report usually by 13:00 and sometimes before and sometimes after. Whatever the hour they are always worth reading. I have read every one (and Graham’s which are equally as good) since I joined in May 2012.
Please give Paul a break why did you think it should be there by 08:00.
Paul/Ed maybe there should be three or four line header above the title explaining the report to new people and explaining the timings.
KR
Michael.
thanks. I meant no offence . It would be good if there was a smiley
Hi Caper4,
Sorry you got your head bitten off below! :-)
Welcome to Stockopedia.
A reader below suggest that I put in a standard heading for the placeholder reports, which is actually a great idea. Then new members such as yourself know what the timescales are for each report.
Best wishes, Paul.
Thanks Paul. Very impressed with this site and I look forward to being an active member over the next few years. Thanks for your very interesting report today.
I thought Ed could hard code it in to the page say above your photo, top right, or above the title. That way you dont have to remember to paste it in each time!
Best wishes
Michael.
Good idea, thanks Michael. Although it would be quite easy for me to copy paste in some standard wording.
My morning smallcap tweet:
Iconic Labs (LON:ICON) Boku Inc (LON:BOKU) Braemar Shipping Services (LON:BMS) XP Power (LON:XPP) CMC Markets (LON:CMCX) Begbies Traynor (LON:BEG) Live (LON:LVCG) Norman Broadbent (LON:NBB), Vertu Motors (LON:VTU), SkinBioTherapeutics (LON:SBTX)
Iconic Labs (ICON) early signs of growth, co sets a target to at least cover all general and administrative costs during H2.
Boku (BOKU) Total Payment Volumes for Jan & Feb up 30%, slightly above mgmt plan. Higher growth in covir-19 regions. Confident of meeting FY market expectations.
Braemar Shipping (BMS) H2 approximately in line with market expectations. Wavespec had delays on the LNG storage technology and further delays with current projects tied to China. Outlook - shipping markets have seen significant falls in charter rates in 2020. Braemar expects covir-19 will have an effect on earnings in recent Q.
XP Power (XPP) FY rev up 2% (in line), orders up 8%. Adj EPS -16% cf F/C -12%. Outlook optimistic but "we are affected by certain external events, such as the impact the outbreak of the COVID-19 virus had on our supply chain. This introduces some caution into our outlook, but we remain encouraged by our healthy order book.” I'm short.
CMC Markets (CMCX) guides FY net operating income ahead of market consensus of £200.6m.
Begbies Traynor (BEG) guides FY at least in line with expectations.
Live Company Group (LVCG) is encouraged with Bricklive progress. "Coronavirus has had a direct effect on operations in China and Asia, this has already been accounted for within our revenue targets. The majority of our activities in this region will occur in the second half of 2020 and the Board does not currently believe the Coronavirus will impact the overall performance of the Group,"
Norman Broadbent (NBB) opens Chester office to meet increased client demand.
In line: Vertu Motors (LON:VTU) SkinBioTherapeutics (LON:SBTX)
Hi Paul. Kudos on spotting the seriousness of covid-19 early on. I would appreciate your thoughts on how Revolution Bars (LON:RBG) will cope if 'social distancing' is encouraged, particularly if this outbreak persists into next year (when a vaccine is released). Thanks
Begbies Traynor (LON:BEG)
Nice trading update:-
"...... leaves us confident of delivering results at least in line with expectations for the year as a whole."
No mention of coronavirus, Brexit, etc,etc which is why I hold.
Phil