Small Cap Value Report (Tue 3 May 2022) - CARD, OOUT, IUG, QRT

Good morning! Paul & Jack here with Tuesday's SCVR. Welcome back Jack! Today's report is now finished.
Agenda -
Paul's Section:
Card Factory (LON:CARD) - FY 1/2022 figures are out. Real profits are a small fraction of the inflated EBITDA & cashflow numbers. Balance sheet still very weak, and the company is completely dependent on bank facilities - recently renewed, so not an immediate worry. I don't see any attraction to this share, unless you believe it can significantly increase sales.
Intelligent Ultrasound (LON:IUG) - my first look at this heavily loss-making niche medical equipment maker. High gross margins, and strong revenue growth in 2021 results caught my eye. But admin costs look way too high, and it's running out of cash, flagging up the need for another fundraising in the going concern statement. So probably not the right time to buy, as it's so speculative, but could be an interesting company to watch for signs of accelerating order intake in future, maybe?
Quarto Inc (LON:QRT) - see the reader comments section, where we have a discussion about this book publisher which is demonstrating a strong turnaround. Many thanks to mjfgs and jimrog64 for flagging up this share, and apologies we didn't spot the turnaround (after 8 years of writing about it, we gave up coverage right at the low. Typical!) [No section in the main report - see reader comments section only]
Jack's section:
Ocean Outdoor (LON:OOUT) - digital out-of-home advertising specialist (DOOH) currently looking to sell itself due to ‘technical trading challenges’ with the share price. Business is recovering nicely as economies open back up, but a lot of this recovery is priced in. I’m happy to watch from the sidelines as Ocean’s largest shareholder weighs up whether or not to bid for the company.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Card Factory (LON:CARD)
64p (up 9% at 08:35)
Market cap £218m
Card Factory, the UK's leading specialist retailer of greeting cards, gifts, wrap and bags, announces its preliminary results for the year ended 31 January 2022 ('FY22').
I’ve been looking forward to seeing some numbers from CARD, because its big news recently was the renegotiation of bank facilities, and seemingly avoiding having to do a dilutive equity fundraise - very good news, as the risk of dilution previously looked high, given the balance sheet weakness.
I reviewed CARD’s refinancing arrangements here on 21 April.
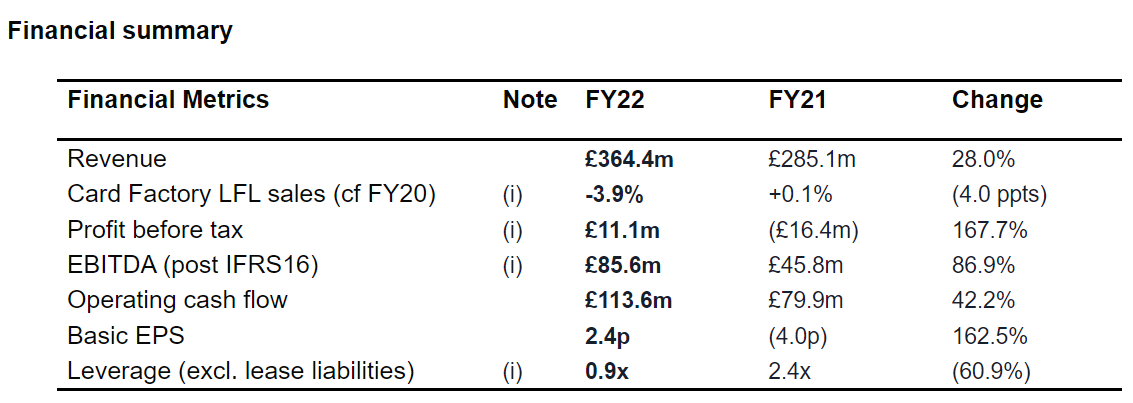
The financial highlights section has some apparently huge cashflow & EBITDA figures, but these are stated post IFRS 16, an accounting standard that has turned these metrics into complete nonsense, for multi-site businesses. So these numbers need to be ignored, otherwise they mislead us into over-paying for the shares. This is not genuine cashflow at all, because the highlights numbers exclude £57.8m in rents, which are shown further down the cashflow statement in 2 entries (£54.5m and £3.3m).
Look at how small profit before tax is, compared with EBITDA -
.
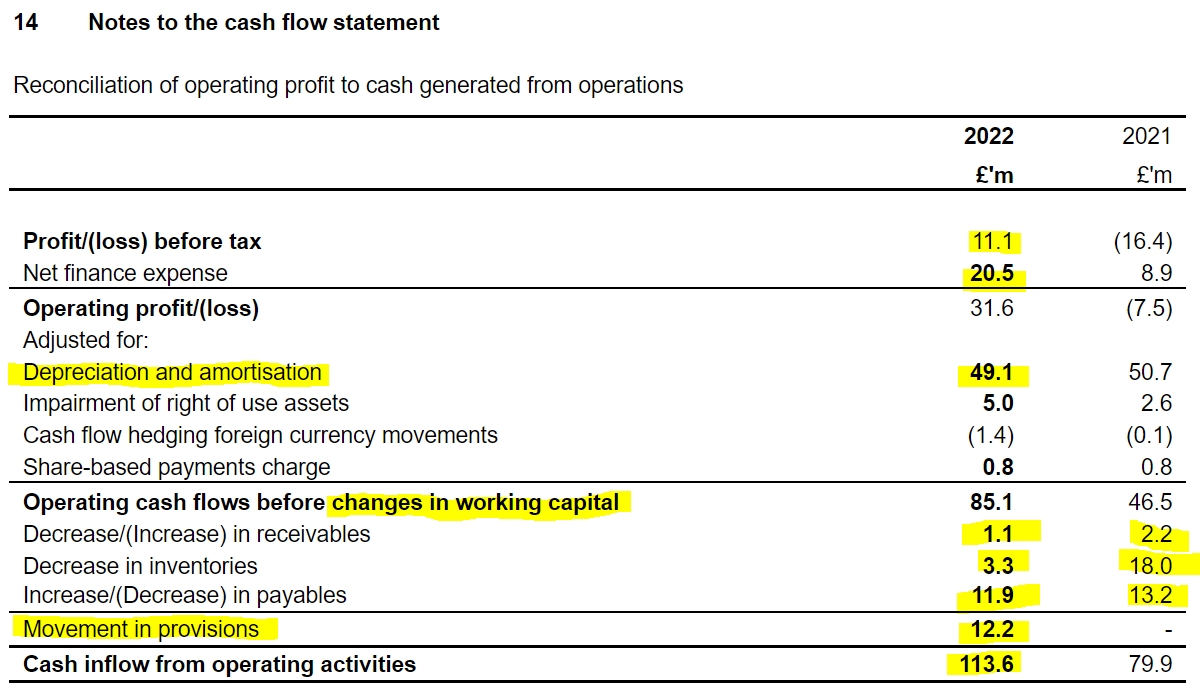
To demonstrate the point further about how £85.6m in EBITDA turns into only £11.1m in profit before tax, there’s a useful reconciliation in note 14 -
.
Note - the substantial net finance expense, because the business remains highly indebted, with the half year and full year balance sheets showing a favourable lull in bank debt, which is higher at other times in between -
It should be noted that Net Debt at the half and full year period ends is lower than intra-year peaks, reflecting usual trading patterns and working capital movements.
Given this, I think the company should report average daily net debt, which would be a more realistic figure. I don’t see that number disclosed anywhere.
The huge depreciation charge above of £49.1m mainly relates to rents, under the ridiculous IFRS 16 rules. Only £8.8m of that figure is actual depreciation (on fixed assets).
Also note at the bottom of the reconciliation above, there are favourable working capital movements in both years. Over the two year period, inventories have been run down by £21.3m, and trade payables increased by £25.1m, which is where a lot of the debt reduction has come from - squeezing working capital. Those are sensible actions to take, when you have too much debt, but can the business continue squeezing its working capital, or might it need to let things increase again? Low inventories could mean shortages at peak times, especially if product intake from the Far East is delayed on ships. Many companies are increasing inventories at the moment, to ensure no shortages occur.
LFL sales are only down -3.9% compared with pre-pandemic, which seems very good. This has been achieved mainly through increasing the average spend per customer, up 22%, largely offsetting transaction volumes down 23%.
This is impressive, and means there could be good upside on future sales, if customer footfall returns to pre-pandemic levels.
Some price rises are being implemented, although I can’t find any reference to the average price rise. Given that CARD prices are low, and average basket size is small, then I imagine CARD should be able to cope better than most in the higher inflation environment we currently have.
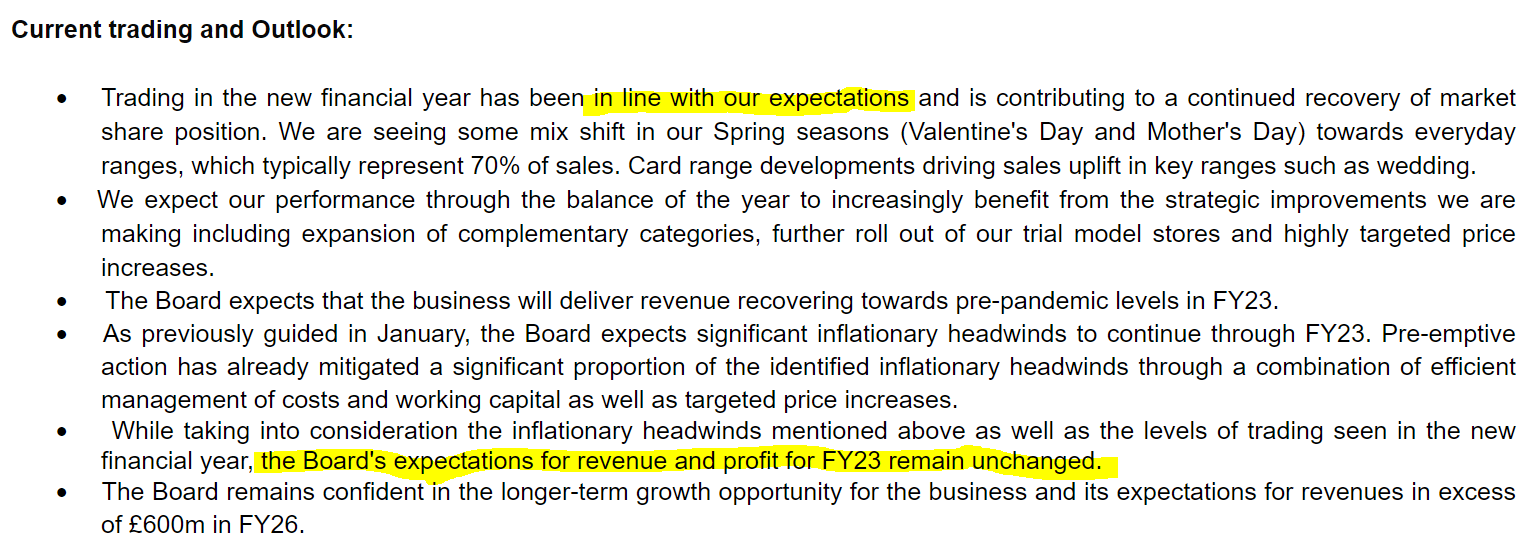
Current trading & outlook - this is a bit waffly, with no numbers, but it’s in line with expectations anyway -
Balance sheet - NAV is £219.6m, but this is dominated by a huge £320.7m intangibles (mainly goodwill), which needs to be removed. That takes NTAV into negative territory, at £(101.1)m.
Cash of £38.3m is more than offset by gross bank borrowings of £111.0m, giving net bank debt of £72.7m. Net debt has come down a lot, but much of that is due to stretching working capital (running down inventories, and taking more credit from suppliers). Those tend to be one-offs, and can’t be repeated year after year, or might even reverse somewhat in future years.
Capex has been very modest, so there might be a backlog of store refurbishments needed now?
Online - is still only a very small part for the business. My concern remains that CARD has missed the boat, and now has highly profitable online competitors which dominate the space, e.g. Moonpig (LON:MOON) . CARD has a lot of catching up to do, if it can catch up at all?
Going concern - this is surprisingly good, saying the business would still have financing headroom, even in severe forecasts. I’m struggling to see how that would be credible, but the auditors must have reviewed the forecasts and be happy with them.
My opinion - there’s nothing in these numbers to excite me. It only made £11.1m profit before tax (PBT), and as we know businesses are facing lots of cost headwinds now.
The balance sheet is weak, with bank debt reduction having come more from squeezing working capital than from profits.
I still think bank debt is much too high, especially at seasonal peaks (no figures provided, but it does say these are higher than half year and full year end net debt balances). Hence the business is still completely reliant on bank support, and has been very lucky to have had such accommodating bank managers over the last couple of years. The revised bank facilities require further staged reductions in facilities, therefore I doubt there’s likely to be any cash available for dividends for several years, which is a condition of one of the bank loans anyway.
I think the bull case requires faith that sales could be considerably increased, to produce operationally geared improvements in profits.
As things stand, the valuation if anything looks expensive to me, so I can’t get excited about CARD shares. Shareholders here took a lot of risk in the last couple of years, for not much upside. So risk:reward wasn't good in my view. Although now the dilution risk has gone away, with the recent bank refinancing, then risk:reward has improved.
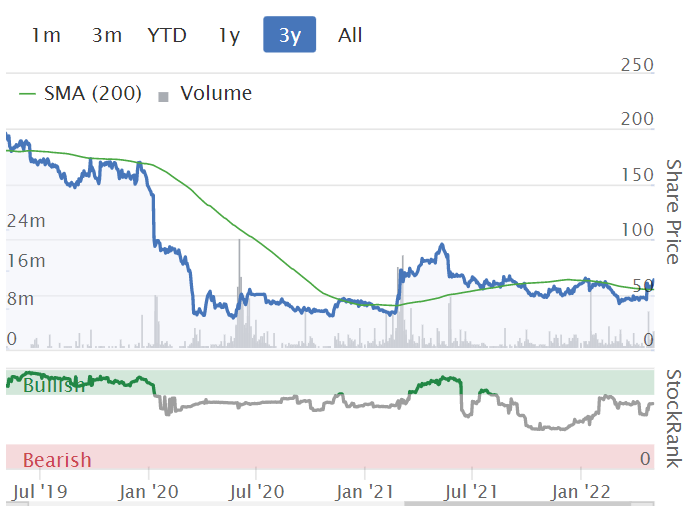
It's surprising that the share price is up 9% in early trading today, but maybe people have latched onto the apparently huge cashflows (which are not real!).
.
.
Intelligent Ultrasound (LON:IUG)
14.5p (up c.2%, at 12:16)
Market cap £41m
I’ve not looked at this share before, because it’s a serial loss-making, cash burner.
However, today’s results show a decent increase in revenues, and upbeat outlook comments, which caught my eye on a slow news day. Has the company reached an inflection point I wonder?
Occasionally jam tomorrow companies do come good. It’s so important to be ready to change your mind when the positive signals start to come through. A good recent example is Audioboom (LON:BOOM) , which I’ve followed for years, being resolutely sceptical, given years of abject failure. I missed a couple of positive trading updates, and by the time I’d twigged here (autumn last year) that things were turning positive, I’d missed a multibagger!
Intelligent Ultrasound Group plc (AIM: IUG), the 'classroom to clinic' ultrasound company, specialising in artificial intelligence (AI) software and simulation, announces its unaudited preliminary results for the year ended 31 December 2021, showing a positive year of simulation revenue growth, a small reduction in operating losses and encouraging progress in the clinical AI portfolio, despite the restrictions of the pandemic.
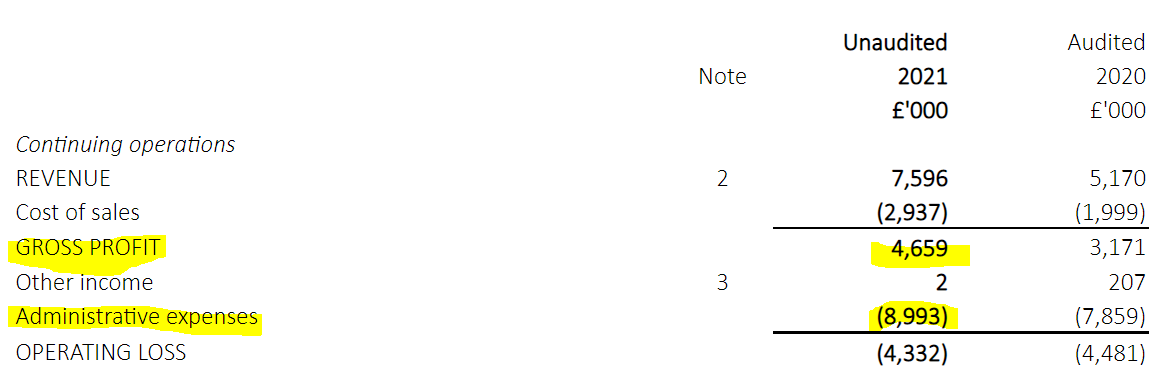
FY 12/2021 results show revenues up 47% to £7.6m - a good outcome, because revenue had previously flat-lined around £5-6m for 2018-2020, although the pandemic hit in 2020 might have obscured an underlying growth rate. That seems to be the case given a strong surge in 2021 revenues. The trouble is we don’t know whether growth in 2021 was catching up from the pandemic, or the start of a stronger long-term growth trend. Hence it’s very difficult to assess what the future might hold.
Profitability - it’s never made a profit, and the loss after tax (to take into account R&D tax credits, which is legitimate for this type of company) was £(3.6)m , slightly worse than 2020 loss of £(3.3)m.
As soon as I see repeated losses, I ignore everything else, and go into loss-making company mode, immediately focusing on the cash position & cash burn as the most important issue. Especially right now, in a small caps bear market, when fresh funding may not be available on reasonable terms.
Cash - has fallen to £4.95m, from £8.77m a year ago. If that trend continues, then it’s going to run out of cash in early 2023.
Going concern statement - confirms that another fundraising will be needed, creating a “material uncertainty”. That’s enough to repel me, because the funding window has been slammed shut, and fund managers are probably now seeing customer redemptions, rather than fresh investments coming in. That limits their scope to provide fresh funding to speculative companies. So my worry is that IUG is running out of cash at the worst possible time.
Overheads - looking at the P&L, I like the high gross margin. This means strong operational gearing, if sales can be further cranked up.
Looking at the top section of the P&L (below), you can see that administrative overheads are far too high for the size of company. In fact, revenue would need to double, to double gross profit, which would be necessary just to reach breakeven. That’s assuming no further increase in overheads, which in practice is not how things tend to work. If revenues were to double, then admin costs would probably increase somewhat too, although a lower percentage. Hence in practice I think revenues would need to more than double just to reach breakeven.
.
Are revenues likely to double? - who knows, we can’t predict the future.
I’d want to see signs of demand really taking off, to convince me to have a punt on this. So let’s take a look at the outlook comments for signs of stellar growth kicking in.
Outlook - this sounds positive, but probably not positive enough, given the rapidly reducing cash pile -
Outlook
With a growing range of both AI and simulation related products, a scalable operational base and pandemic related restrictions around the world relaxing, we have had a strong start to 2022. We have had a high number of NHS financial year-end orders in the first quarter, and we therefore expect revenue for 2022 to be ahead of current market expectations.
We are focussed on growing sales in both the more established simulation market and the newer, potentially higher growth AI imaging market, but will continue to monitor cash and overheads against this anticipated sales growth curve and any future investment of new AI products and expansion of our sales networks. We remain excited about the potential of our 'Classroom to Clinic' business.
My opinion - I’m only reviewing the figures remember, not trying to make a detailed study of IUG’s products & competitors. Although the high gross margins, and installed base of 650 medical establishments, suggests that IUG has something of value, and with pricing power. It’s sold internationally too, not just in the UK.
The arrangement with GE sounds interesting, and I wonder if GE might be a potential bidder for IUG possibly?
As a standalone company though, it strikes me that IUG may be trying to do too much, with inadequate funding. Hence, as the going concern statement suggests, another fundraising will be needed, creating a “material uncertainty”. I’m never keen on investing in anything that needs more funding. That’s risky enough in a bull market, but can lead to horrendous dilution in a bear market, when institutions just name the price for their support, which can often be half the current market price. Even if PIs get a look in via an open offer, it doesn’t really matter, because the share price is likely to drop around half anyway. That then almost forces us to buy more, to maintain our position. Why take the risk?
Upside could come from major order intake. If that were to happen, then traders could jump on this share, and bid it up to a much higher market cap.
All in all then, it’s not for me at this stage, but it’s worth keeping an eye on the RNS, for signs of any game-changing order intake, which would be the time to buy on the opening bell.
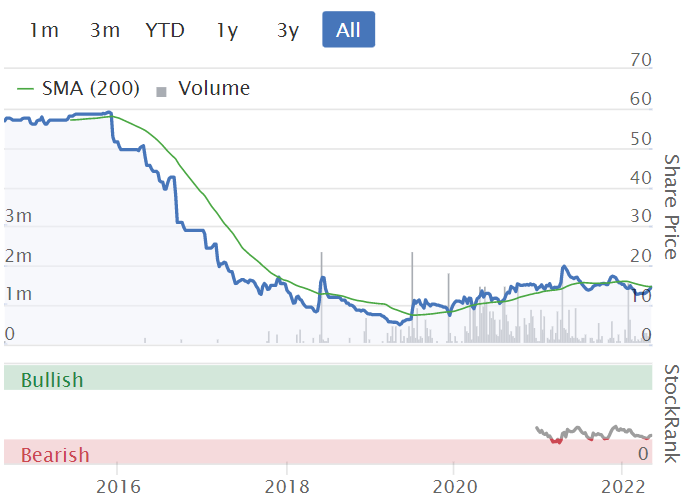
By the way, I've already raised a green blob with Stockopedia HQ, because the forecast info is clearly not right.
.
.
Jack's section
Ocean Outdoor (LON:OOUT)
Share price: $10.11
Shares in issue: 53,930,223
Market cap: £438.23m
Full year results to 31 December 2021
Ocean Outdoor is an operator of premium Digital Out-of-Home ("DOOH") advertising in the UK, the Netherlands, the Nordics and Germany. Its portfolio of advertising locations stretches across 351 cities across Europe, including the famous Piccadilly Lights in London.
I’m not sure of the operating history here - it looks like the group has grown revenue from a standing start back in 2018, with variable levels of profitability.

In fact, there have been some pretty eye-watering losses. Is this some kind of roll up perhaps, with one off costs impacting the bottom line? The 2020 income statement is dominated by a £139m unusual expense but if we strip that out then the company would still have lost £41m on an underlying basis.
I’m also unsure why the share price is in USD when the reporting currency is GBP and the UK looks like the group’s largest region. It looks like liquidity could be an issue here, with an unusually large 296bps spread for shares in a £617m enterprise.
That’s why management continues to conduct a strategic review:
In November 2021, we announced the initiation of a strategic review to evaluate potential strategic and financial alternatives to maximise shareholder value. This decision was taken after the Board and management felt that the Company was undervalued, with the share price continuing to face technical trading challenges unrelated to Ocean's strong business fundamentals and intrinsic value. At this current time, the Board is evaluating a potential sale to its largest shareholder, Atairos, which may or may not lead to a transaction. Whilst there can be no certainty that a formal offer will be made, discussions continue and Atairos have presented a proposal to the Board which is being considered.
I am interested to see how this develops. As OOUT’s largest shareholder, Altairos must have a good degree of insight into the business. If anybody understands whether or not Ocean Outdoor is undervalued, it would be its largest shareholder. But what would it signal to the market if a deal does not go ahead?
Full year figures:
- Revenue +43.3% to £124.4m,
- Gross profit +87.9% to £42.1m,
- Loss before tax down from -£156.5m to -£30.3m,
When there are big losses on the income statement like this, it helps to check the cash flow statement to see whether or not the group is cash generative. There’s a hierarchy of losses and one-off non-cash charges (which happened last year) are perhaps the least serious offender, although they do introduce a large dollop of subjectivity into the accounts.
Here we see that OOUTT generated cash from operations of £47.1m (FY20: £32.1m), so that allays some of the more immediate concerns. In this instance, there are no unusual expenses - just a large amount of depreciation and amortisation, about £67m compared to just £4.6m of capex. How expensive is an estate of billboards and advertising screens to maintain on an ongoing basis, I wonder?
In terms of operations, contracts have been won and maintained in the UK. Contracts won include with the Canary Wharf Group (a long-term contract value of £30m) and Edinburgh's St James Quarter (contract for £25m). New retail and key roadside contracts have been won in the Netherlands, and new screens are up in Denmark, Norway, and Sweden (Nordics).
Conclusion
2021 has been a year of recovery for the out of home advertising sector, reflected in a significant rise in revenues and profits for OOUTT, which has invested in differentiating itself with prime retail locations and digital technology. It appears to be leading the market, at least in the UK.
Operationally, this has correlated strongly with the Covid recovery, but I would argue that the window in which the share price was low enough for investors to make good money was small.

The group is forecast to grow and I can imagine there are exciting developments and innovations to come for the digital OOH advertising market that could see it add increasing value to its customers. There are also a lot of costs to running the business at present though, which makes me wonder about how profitable such an enterprise can become.
The gross margin appears to have recovered in H2 but it has been volatile so far, including before Covid.

A price to sales of nearly 5x and a forecast PER of 23.2x doesn’t strike me as cheap, although I note a PEG of 0.4x. I’m happy to wait for now, particularly as the group’s largest shareholder weighs up whether or not to make a bid.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
The Annual Report of Ekf Diagnostics Holdings (LON:EKF) contains a statement that EKF intends to distribute its holding in Verici Dx (LON:VRCI) in specie to EKF shareholders.
"Investments
At year-end, the Company continues to hold 1.39% of the issued share capital of Renalytix plc, a developer of artificial intelligence enabled acute kidney injury products, and 1.89% of Verici Dx plc, a developer of advanced clinical diagnostics for organ transplant. The market value of these investments increased by £1.1m during the year. Post year end the Company invested a further £2.5m in Verici alongside other existing and new investors participating in a placing of new ordinary shares. Further to the investment, the Company holds 5.8% of Verici DX plc. EKF intends that its holding in Verici will be distributed to its own underlying shareholders as soon as reasonably practicable and subject to appropriate arrangements to maintain an orderly market in Verici’s shares following such distribution."
Anyone any thoughts on why the SP of Atalaya Mining (LON:ATYM) is sinking progressively into its own mine workings? Yes, its costs will be rising but since its products are still in high demand, so will the price it receives? Or am I missing something? I often do!
USD strength.
Yanggu Xiangguang Copper Co, Ltd. sold a chunk (through no fault of Atalaya, Yanggu needed capital) a few weeks back and it had a negative effect on the share price, although it did bounce back the same day I think it rocked confidence.
I think its latest RNS hinted at higher energy prices for converting the copper, some kind of transport strike (from memory) and lower output than expected which started a sell off. I note that shares such as £THS are also off a high ATM.
I sold out just after the RNS...thinking it would come down a bit. Energy prices swung it for me.
Its a good story, the new mining rights, the solar farm etc...but I feel along with many shares its taking a fall...maybe some to go...
I have watched Atalaya Mining (LON:ATYM) drift and it has gone past my manual stop loss of 10% so sold out today, like the company think a good long term story, but considering it is £5 to buy/sell I am happy to watch it drift some more, maybe it will bounce, but like a lot of things I am staying heavy cash right now rather than watching another day of red screens.
Tommy
Thanks a lot to all for comments on Atalaya Mining (LON:ATYM) which make a lot of sense, and should have picked up for myself. Have been taking my eye off the ball for personal hurt reasons for a little while so especially grateful for helpful (though not profitable) comments from you guys on the reasons why.
Card Factory (LON:CARD)
Very unhelpful that card didn't spell out what expectations are ref year just starting if they are on track. I was worried January that they might have been saying they expected the full £30 mill to drop through to the bottom line - thankfully thats not the case - although if expectations were being revised down in january by less than that figure why they didnt just spell it out i dont know. All a bit ridiculous you can reference something that you don't quote - makes about as much sense as what comes out the mouths of amber heards lawyers (they dont strike me as being the brightest bunch - with one hilariously objecting to a question they forgot they had just asked !)
Anyway we can fill in the blanks sort of if the reduction showing up on stocky of 3.4p is on the money that equates to expected profit reduction in january of £11.7 mill from prior expectation with thankfully no worsening today. Much better than the £30 mill they flagged up January. Again annoying that what the say in the updates is really not telling us the whole story clearly. It all seems a little odd that they would be so blunt in january when they were facing refinancing issues ! that strikes me as being odd. Obviously those in the know may have got wind of broker notes once the dust settled but does it need to be that hard - answer = no !
To be fair to card i quite liked the upfrontness of the fact that trading would be tricky - so at least they have sat on an obviously deteriorating situatoion whilst saying nowt.
Is 6p expected eps enough to get excited about - i guess the obvious answer is no - although i expecty this one may come good (some may say that has already happened with share doubling from its low point !! - will done to holders with big kahuna's) if they can concentrate on paying down debt and being miserly with the rest of the cash.
Quarto Inc (LON:QRT) As it's relatively quiet I'd be grateful for anyone's thoughts re this company. Mkt cap of c£71m, no broker coverage as far as I can tell.
It first came to my attention as a consequence of the Director CK Lau buying shares almost daily (he now owns just over 50% from about 28% pre-pandemic). Seems to score highly on Stockopedia and qualifies for 3 screens. To a non finance-minded amateur like me, the fundamentals look attractive too. Their website is worth a look to get more of an idea of what they do.
Q 93
V 87
M 95
Stockrank 99
Grateful for any thoughts!
mjfgs - thanks for commeting on £Quarto Inc. Like many others at the moment, I am looking at a poor performance from many holdings in my portfolio. In the last couple of years, I added a number of stocks which were subject to a lot of discussions here and elsewhere - most are well down from my entry point. £Quarto Inc has really highlighted the value of DYOR. This is the one stock which I added which has had virtually zero commentary, but which met criteria that I try to use for my selections, and looked from my own research to be a great investment. These are 1. High Stock rank - £Quarto has stayed at 99 since early last year. 2 Director buys. 3. Some understanding of the industry/sector. This is now my best performer in the last couple of years- and has nearly doubled since I bought in last year. I think it has further to go and appears to be a on a steady climb. Management have turned this company round, significantly reduced debt, and appear to be growing things nicely. There has been a lot of discussion about £Bloomsbury as the publisher to invest it. Prospects look decent for the industry as a whole this year, and I think that both will do well, but pleased that I opted for £Quarto!
I also hold Quarto Inc (LON:QRT) I also noted the turn around plan from approx 2016. The company specializes in books with lots of pictures. So lots of Gardening and cookery books. CK Lau by far the biggest share holder also owns a Chinese printing from called 1010 printing.
Hi Lgarvey,
CK Lau by far the biggest share holder also owns a Chinese printing from called 1010 printing.
Interesting. In such a situation, I think it would be very important to scrutinise the Related Party disclosures in the Annual Report. I'm certainly not alleging any wrongdoing at all, but am just flagging the risk that an overseas controlling shareholder in the same sector, would have a lot of flexibility to move profits around the group, by adjusting prices charged for intragroup purchases.
There were vague allegations of this made by Tom Bower, in one of his hatchet job books (on Philip Green) about Arcadia & BHS, that their miraculous turnaround could have been at least helped by having a friendly supplier in the Far East indirectly linked to the major shareholder, that supplied product at cost price (or maybe even below?), thus driving a big rise in Arcadia profits, and hence the value of the business. Which could then be sold for an inflated valuation, at a high PER. Thus creating a big UK-based asset for someone looking to extract value from the Far East by the back door.
Regards, Paul.
The main issue with Quarto is they're not subject to the UK takeover code so minority shareholders don't have the same protections (75% to delist) . The CEO has been very keen to get over 50%. Hopefully that's just so he can consolidate their results into his company. Alternatively, at over 50% , he could delist and try to squeeze out the minority shareholders.
Thanks. Good point about the takeover issue.
Many thanks to mjfgs & jimrog64 for flagging up Quarto Inc (LON:QRT)
If you look at our archive, it was one of the shares we followed closely, writing about it 24 times from 2013 to 2020! I even remember doing an audio interview with the former CEO as we thought it looked potentially interesting. Although the accounting treatment of advances to authors always struck me as a bit suspect.
Sod's Law being what it is, I think we finally lost interest at the company going nowhere, struggling to maintain divis & with too much bank debt, etc., just at the point that a turnaround began!!!
I wish somebody had flagged up earlier that a turnaround was underway, as we can't cover everything, and plenty of things will inevitably slip through the net, especially on busy news days.
Taking a quick look at the FY 12/2021 results (published on 17 March 2022, I'm impressed with the figures, they look good.
Outlook comments mention higher shipping costs though -
Quarto is in a good financial position and has a strong list of new titles for publication in 2022. The sizeable backlist continues to perform well and we are confident in our sales teams ability to navigate the changing market. The volatile state of the shipping market will continue to present challenges and we expect that this will have a significant increase in shipping costs.
As you say, the shareholding structure is not ideal, with the biggest shareholder owning 50%, and the next 2 largest combined owning 30%, so private investors are very much along for the ride. It looks like the biggest shareholder provided loans, suggesting it was financially distressed previously.
Anyway, it looks like things have worked out very well so far, so well done to holders & for doing your own research!
Do flag up any similar situations you come across, as we love turnarounds here at the SCVR, and sorry we missed this one.
Best wishes, Paul.
Thanks Paul. I don't comment often on here as I usually don' t think that I have the expertise. I still consider myself to be a novice and only started investing at all a couple of years ago. I guess the lesson for me is to be more confident about bringing things to the discussion when there seems to be a well argued case and relevant information/ reports.
Often compile a well worded considered and informative point of view - then bottle it as - the first wine takes over and have not actually done much DYOR.
The post on Serica Energy (LON:SQZ) by Mr Cooper with a reply by Mr Pavey was highly informative on both the company and DYOR - the information is there on company websites and RNS - just need to read and correlate it, form an opinion, and hopefully beat Mr Market (busy eating other fish).
Hi jimrog64,
I guess the lesson for me is to be more confident about bringing things to the discussion when there seems to be a well argued case and relevant information/ reports.
Yes definitely! :-)
I like ploughing through the figures, but successful investing is about far more than that. I know lots of very successful investors who have their own approach, which often just relies on shrewd common sense - e.g. seeing a product taking off, Directors buying repeatedly, etc. It's what makes investing so fascinating - you never know what's going to happen, and the market makes a mockery of experts every day!
Best wishes, Paul.
I remember a few years ago Paul I think did a review of the economy based on how many skips he'd see in his street. I think we can digitize it now with the number of posts on here is a reflection of where people think the markets are going to go.
Paul/Jack - hope you aren't feeling disillusioned with it but I think a lot of us are just feeling a bit down at the moment on the market and don't have too many things we want to shout about.
On a similar note, what are people doing at the moment. I am sitting on about 15% cash at the moment and am getting a bit itchy but feel we could have a lot more downturn yet on interest rates and potential recession that I'm sitting on it. Hate to see inflation eroding it but am scared the markets might erode it even more. I feel a lot of my shares (I am biased) are cheap on the historical metrics (P/E P/FCF etc) and so I'm holding tight and watching so many of them buying back shares. Still doesn't make me feel like putting more in though
Personally I remain 100% deployed in the equity side of my portfolio.
Added significantly to Lloyds Bank and Shell today and sold all my holdings in £NAHL after spotting all of the reviews on trustpilot coming in for their law firm are negative and this is the new strategic focus of their business.
Very happy in particular to be owning more Lloyds who should stand to benefit from increased interest rates and conservatively risk managed in terms of their cash balance. If there's one thing I wouldn't like to be owning at the moment it's a variable rate mortage, but if I did I'd be doing everything I could to make the monthly payments.
Hi
Curious about your comment on negative Trustpilot reviews. I've Googled them and £NAHL are 83% excellent, NAL 66% excellent. Am I missing something?
I actually don't trust "trustpilot" I was looking at a local car rental company here in Spain and every website was really negative about the extra charges they added and trustpilot was like 90% positive. Looked like so many of the reviews were made up.
Late to this but thought I would add what I know. Trustpilot actively encourages positive reviews. It's quite hard to add a negative review.
I don't agree, I have left negative reviews, sometimes its the only way to get the company to respond.
Plenty of negative reviews, here are some: https://uk.trustpilot.com/revi...
Many others with worse reviews than that.
I may do one, phone charge going up from 4p to 15p, what a joke.
Here is another: https://uk.trustpilot.com/revi...
Yes, quiet around here isn't it? Hey, ho.
I have no idea what's going to happen. I agree that it doesn't look good - but does it ever? And when/if it does look good - would I have so many opportunities to choose from?
I understand why investors are running away. Perhaps its the contrarian in me, but all the reading I've been doing tends to point towards times like this being when the most gains are made.
What am I doing? Probably the reverse of most. Right now I'm sitting on my hands. But what I have done is prune down my holdings by around 50%. My portfolio i now around 20 small cap UK shares, more concentrated than its ever been with over 50% in my top 5 holdings - and the funds released by the pruning have been reinvested in my highest conviction holdings - and, as usual, I am fully invested. Zero cash, the odd small sale to provide me something to live off, and if I want to buy something - then I have to decide what if anything to sell. Something I find to be a useful discipline. And reduces the amount of tinkering I do.
As I said - I have no view on whether the macro evironment will get better or worse. Could do either - or just blunder on with one thing after another. Which is what seems to have happened in the last few years. Either way I have no aptitude for timing. My response has been to pay less attention to the macro-evironment. Try not to be terrified by the news on a daily basis and focus much more upon the management in particular. And also the cash (or cashflow), product and product/development, market opportunity and margins of the small cap - mainly Value And Growth stocks I select.
That's not to say I am getting it all right (yet) - just that I am working a lot harder and I look on the current environment as a challenge. And also an opportunity to ferret out which of the host of apparent bargains will actually turnout to be cheap in hindsight. Quite exciting in a way and its certainly going to be interesting times,
Cheers
Mark
Mark,
Are you willing to share your highest conviction holdings and your reasons?
Are you willing to share your highest conviction holdings and your reasons?
Of course. How kind of you to ask :-)
Though it turns out to be easier said than done. The reasons, not the sharing. I'll try to provide something tomorrow as I failed this evening.
I didn't name then on my post as the OP asked about approach and in my experience a list of shares tends to distract from a discussion of approach,
cheers
Mark
Warning Long Post!
Are you willing to share your highest conviction holdings and your reasons?
FREng: Of course. How kind of you to ask :-)
Sorry it’s taken me a while to do this. Listing them is not a problem – but including the reasons - turns out to be much easier said than done. Still its good discipline so I’ll give it a try.
I didn’t previously list the shares as the OP asked about approach. It’s my experience that a list of shares tends to detract from a discussion of approach. Likely more so in this case as these companies are not conventional picks. Quite the reverse, normally for one reason or another, quite often buried in the history they tend to be – Marmite – love them or hate them shares. Except most are so small and illiquid it’s hate them or hate them a little less. These should carry a health warning up front. But that’s one of the few places as a private investor my research can have an edge? When there isn’t any public research – or the history gets in the way of current progress?
Without further obfuscation here is the list of my largest 5 holdings by current value – accounting for around 50% of my portfolio.
Ms International (LON:MSI)
Anglo Pacific (LON:APF)
Macfarlane (LON:MACF)
Zytronic (LON:ZYT)
Vianet (LON:VNET)
Though whether they are also my highest conviction holdings is an interesting question. Not necessarily. You might think so, but the market fluctuates and prices go up and down. My assessment of conviction is not the same as my assessment of reward versus risk – which is another factor.
The reasons. Well they all – to a large extent but not exclusively – share characteristics of management, quality product, product development, margins, cash (or cashflow) and growth market/opportunity.
In addition they all have an additional characteristic – which is one or more factor or asset that are neglected, overlooked, undervalued or mis-priced by the market. Or if not currently mispriced a basis upon which I expect the price to rise significantly in the future.
Here is the briefest I can make it.
Ms International (LON:MSI) £47m mcap – engineering microcap based in Doncaster. Long time management, also the largest shareholders, have maintained R&D. The defence division has recently won a long term contract with the US DOD to roll out its GWS (Gun Weapon System) across the USN and Coastguard Fleet. Doesn’t get much more coals-to-Newcastle does it? Hard to assess the long term benefit of this but it seems seriously under appreciated to me despite the recent strength in share price.
Anglo Pacific (LON:APF) - £385m mcap – until quite recently a largely neglected – for understandable reasons - traditional and cyclical coal royalty company. The company has been in transition towards a portfolio of energy transition minerals and I bought for exposure to the portfolio of Cobalt, Vanadium, Copper, Uranium and some precious metal and non-precious minerals. The enormous extent of the windfall income coming from the remaining metallurgical coal royalty as it winds down is not yet fully appreciated – the company should be net cash by H2 and able to fund an existing deal for a royalty on a Nickel mine in development by Brazilian Nickel. The value of this asset is undervalued as the royalty can be stepped up with further payments on an agreed schedule and the structural deficit of Nickel is forecast for some years yet making it extremely good value. A deal that would not be available today. I still want exposure to these minerals – but I will likely reduce the size of this holding should I be lucky enough that the extent of the current cash windfall and the value of the Nickel royalty is at least partly in the share price.
Macfarlane (LON:MACF) - £190m – starting to get some coverage, around here at least. According to the stock report this company qualifies for three screens – one of which is the neglected firms screen. I agree with that. ROCE and operating margin and consistently high for packaging distributor indicating it has some price setting ability not held by its peers. The extraordinary ability of the long time management to acquire, integrate and grow business in the fragmented regional packaging segment is not currently reflected in the company valuation.
Zytronic (LON:ZYT) £19m mcap – another microcap. A former high flying developer and manufacturer of bespoke touch screens for the ATM market. Rather than chase dwindling contracts and margins, or spend its cash on acquiring other businesses long time management has stuck to what it does best and developed its technology for new growth markets. It has launched new (award winning) ‘touchless’ touchscreens and moved up the value chain to supply hardware/firmware and encypted controllers (touchscreen pin pad) and software with standard interfaces. During the pandemic lockdown the company reduced its cost base and invested extensively in its production facilities. Used part of its enormous cashpile to buy back shares via a tender offer. As the full number of shares were not tendered shareholders have given permission for buy backs to continue which sets a floor under the current share price. Subtracting the still enormous cashpile the EV is only £9m. At the recent AGM statement H1 revenue at 5 months was up 25% yoy and order intake up 45% yoy. I anticipate buybacks will continue until the H1 results and H2 outlook statement when the shares will likely re-rate - should I be so lucky. This is likely my highest conviction share – by a whisker from MSI.
Vianet (LON:VNET) - £26m mcap – and another microcap turnaround. Primarily known for its origins in digital flow monitoring and its Brulines beer flow monitoring operation which has been the cash cow funding devlopments, Vianet has been transforming its business in recent year. Vianet has outsourced its manufacturing operations and developed a data management and analytics platform (cloud based of course) with contactless payment services which manages connection to multiple devices in its smartzone hubs (typically hospitality venues – like the AMC cinema chain in the US) and to single devices in its smartmachine division (typically vending machines or remote assets). Once a connection is established the recurring revenue from data management, analytics and contactless payment services is quite sticky and high margin. Smartmachine division growth in connections is currently running at 20% annually and I anticipate this rate will increase as new contracts are signed – and subject to availability of semiconductor components for the connections. Of these shares this one is perhaps the most questionable, Vianet has quite a long history of not quite making the growth opportunity. The company is not highly valued – by pre-pandemic figures and this time it has the technology, platform and sales team in place – whether it can capitalise on this growing market opportunity remains to be seen.
That’s more than enough from me. I should quit whilst I am ahead. I hope. Just as well you didn’t ask about the next 5 shares – which takes me to 80% of the portfolio – they are even more fascinating :-)
Whilst writing this I’ve just realised another shared characteristic – with the exception of APF – they are all Northern based. Stockton, Newcastle, Doncaster and Glasgow. Not my bias as I am Somerset born and bred, living in darkest, deepest West Sussex. The next 5 shares also share the same bias being based in Stoke, Osset, Barrow, Darlington and finally Cambridge, one not based in the North. How intriguing.
cheers
Mark (CEng MIET - on extended career break)
That’s a terrific post Mark - thanks for making the effort. I hold £Apf and have previously held £vnet and £zyt - if you ever get the urge, I would love to read about the next 5.
Cheers
Simon
Also I always like to remind myself of the famous Buffer quote "be fearful when others are greedy and greedy when others are fearful" which keeps me optimistic in difficult investing times :)
After being a net seller of stocks for at least the last year prior to Q1 2022. Buffet bought $51B of equities in Q1. Not saying you should buy blindly but it's a nice data point.
Has Buffet not been hoarding cash for years whiole the stockmarket has been flying ?
He made some ill time buys prior to Covid. He bought shares of all the major American airlines save JetBlue which he liquidated at some point in 2020.
The irony is he had been saying for years that as far as investors were concern they would have been best served if someone had shot down the Wright's brothers first plane flight. Needless to say he sold at a massive loss.
Overall while he was deploying small amounts of cash by Berkshire standard it was easily surpassed by the accumulation of cash generated by the businesses.
My only question to this though are people fearful yet or is the worst to come. Whilst I see a lot of despondence and losses I don't feel we're at the panic stage yet.
The meme stock crowd is certainly in a panic. This is obviously an anecdotal evidence but some investors that were all in on growth stocks are now talking about having a balanced portfolio. Personally I have been incrementally building positions in some names since January and will continue to do so for the foreseeable future. I may not be able to time the bottom but there is value to be had currently/
Hi Brookeda,
Paul/Jack - hope you aren't feeling disillusioned with it but I think a lot of us are just feeling a bit down at the moment on the market and don't have too many things we want to shout about.
We're all human, so of course it's very painful to see our portfolios decline, but that's what markets do sometimes.
Our job here is to crunch the numbers, review company updates, but it's obviously then up to readers to decide how to finesse things, timing your buys & sells according to your own assessment, outlook, and risk tolerance.
I've been through a few market cycles, and the way I see bear markets is that they lay the foundations for super-sized future profits. So many people end up getting despondent & selling at irrationally low prices, that they're handing us the future multi-baggers on a plate.
Maybe we're not quite at that point yet, but it's coming. We're probably at the stage of the market scrubbing off excessive valuations, esp on the tech bubble - some staggering falls in the US, but on stuff that was wildly over-valued (and plenty still is).
At some point though, inflation is likely to peak, Govts are likely to be forced to backtrack I reckon, and turn on the spending & cheap money taps, and then off we go again. Absolutely no idea when that happens though, my crystal ball is not working at all well at the moment!
Supply chains should sort themselves out, as consumers spend more money on services instead of stuff, and several companies have already said that supply chains are beginning to ease. There again, there seem to be other problems building, e.g. shortages of key foodstuffs due to Ukraine. Who knows where it all goes?
As regards equities, if 2022 earnings are hit badly, as plunging share prices seem to be telling us, the logical progression is that 2023+ earnings tend to recover. Hence shares would once again start the positive cycle of beating forecasts, and PER expansion gets going again.
It's all about timescales isn't it? Patient investors buying fundamentally good companies, at bombed out valuations, are likely to do very well with a say 5-year timeframe, if we pick well.
There's tons of money on the sidelines too. I'm struggling to remember when so many of my more successful investor friends are holding lots of cash, which they are now. That's another reason why there could be a big move up at some stage, I just don't know when.
Basically, if we've picked sound companies, then there's almost certainly more upside than downside, taking a longer term view. In the meantime, there could well be lots of profit warnings, and more short-term downside. Nobody knows.
Regards, Paul.
Theres certainly been a reset in tech valuations in the US since Oct 2021, especially the jam tomorrow stocks. Was very much needed.
Who knows where the bottom is, but it's getting closer. There's some nice looking opportunities on low or sensible valuations, which with a little patience should be very profitable.
Am 40% cash ATM, and am not really seeing a lot to decrease that...in fact am thinking of heading further into cash.
I am looking at a set of scales and the bad news side just fully outweighs the good going forwards ATM.
If the Ukraine war were to end I do feel that's a tipping point...but as things stand, looking out 6 months, where is the good NEWS going to come from to balance things up?
Yes I am looking but am not going to buy if I think its got further to go and there lies my problem...
Good write-up on £CARD. IFRS 16 is a complete shambles and no doubt in a few years time the accounting profession will realize they have made a huge error and get rid of it.
Holding shares has been pretty miserable for the last few months but two of my holdings - Hargreaves Services Hargreaves Services (LON:HSP) and Eneraqua £ETP have both issued very positive statements this morning -in fact they both merit a mention in Mr Contrarian's smallcap tweet this morning .
Hargreaves are forecasting a benefit of up to £6.25 million on the bottom line through the current year and the first quarter of next via their German Joint Venture - strong commodity prices for pig iron and zinc are the source . Long may it last but they have also issued a cautionary statement that they do not know how long it will go on beyond the forecast.
Eneraqua is much more interesting -the company joined AIM in November , having been found 10 years ago. They are in a strong period of sustained growth based on the company's patented Control Flow HL 2024 technology -a family of products that maintain an accurate flow rate of water in a system regardless of fluctuations in pressure . The main thrust has been in the UK energy market but todays announcement is entitled "Zero carbon irrigation contract win marks entry into Agritech sector " having won a £0.9m contract to supply systems to 340 horticultural farms to the State Government of Uttarakhand in India . This will be the first major initiative of its kind in India.
More importantly it only has a PE of 9.8, ROC of 22.4%, and an operating margin of over 10% , cash flow positive and has no debt . According to Stocko Analysts Forecasts are 425 (67.32% above the current share price ) - not many of those around at the moment .
Worth a look
Hi fred9566,
Thanks for that. I used to follow Hargreaves Services (LON:HSP) quite closely, but found that it would take half a day to work out what was going on, as it's more of a special situation - a while back, its coal operations were in wind-down, management pivoted to engineering services, plus it had longer-term value from redundant, but large, land ownership which it was developing for housing. All in all, quite a complicated basket of things to analyse, so we dropped it from the coverage here due to time constraints.
I see HSP has been a rare small cap out-performer, up about 50% this year to date, so well done to holders.
Eneraqua Technologies (LON:ETP) is a new one to me. Being a recent float (which nearly always means over-priced), and having consensus forecasts that show exponential growth (rarely achieved) makes me a bit wary. I might watch from the sidelines, to see the company establish a longer track record of profitability. Thanks for flagging it up though.
Regards, Paul.
[edit] Mccoll's Retail (LON:MCLS) FY21 won't be published before end May, delay reflects the need for a conclusion to discussions with key stakeholders around a potential financing solution for the business, in order to finalise the Company's FY21 audited financial statements. Shares will be suspended on June 1.
Totally (LON:TLY) three contract extensions.
Hargreaves Services (LON:HSP) Trading update inline with market expectations.
There was a flash crash yesterday caused by a Citygroup trader.