Small Cap Value Report (Tue 30 April 2024) - MCB, MTRO, IGR, CRPR, CARD, RBGP, NAR, S247, TRT, SYS

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech). We might cover companies outside this range if they are big % movers on the day.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting -
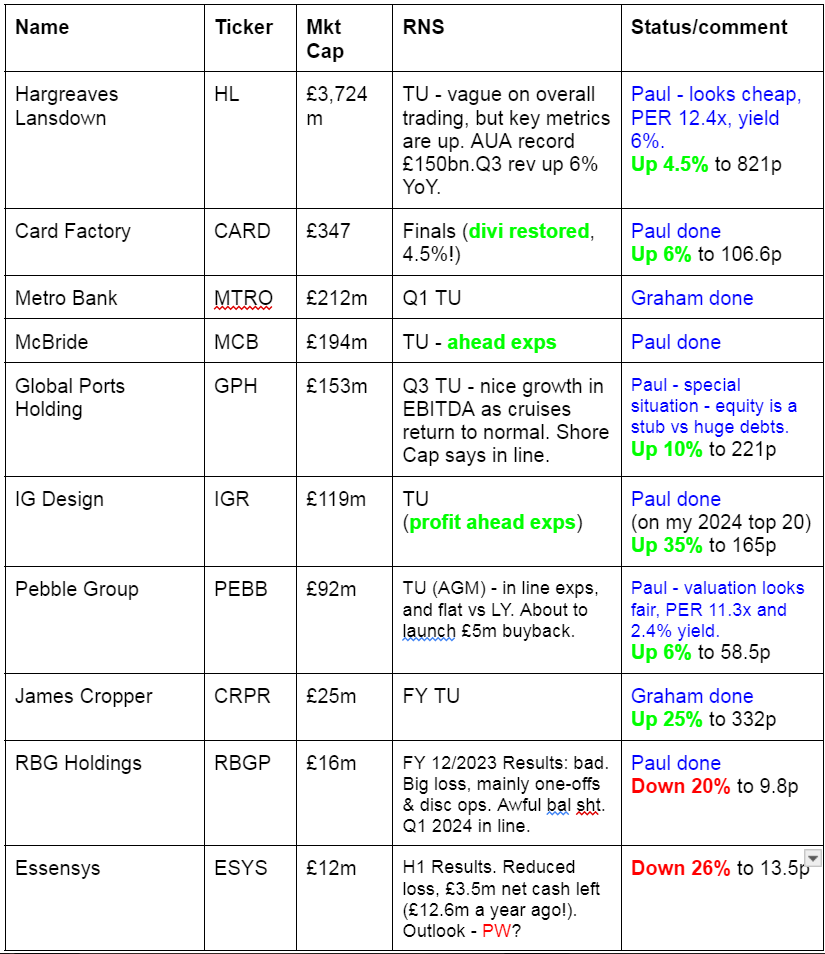
Other mid-morning movers (with news) -
Northamber (LON:NAR) - up 14% to 40p (£11m) - Acquisition - Paul - AMBER
At last something is happening at this stagnant share (a distributor audio-visual equipment, and IT) that usually makes a small loss most years. Strong balance sheet is a plus, but 63% shareholder seems to do as he pleases. So high de-listing risk. Could things change now? Today it announces a relatively large acquisition, for c.£3m cash up-front, plus a few shares, and possible earn-outs.
Smarttech247 (LON:S247) - up 10% to 22p (£26m) - Interim Results - Paul - AMBER/GREEN
I looked briefly at this cyber-security company yesterday on the latest in a flurry of contract wins, which look impressive. H1 results show another loss, E601k LBT, but it has adequate net cash of E4.5m. Negative cashflow due to capitalising dev spend. Multiple contract wins is the main attraction, as these H1 numbers are not great by any means, so it's dangling a carrot of jam tomorrow. Hence shares impossible to value at this stage. Exec Chairman holds 70% unfortunately, so outside investors are just along for the ride, with no power or influence. Could be a reasonable punt maybe?
Transense Technologies (LON:TRT) - up 9% to 102p (£15m) - Joins Airbus Project - Paul - AMBER
As the notes to editors section points out, TRT's profit comes from "residual royalty income" that expires in 2030. So it doesn't make sense to value the share on a PER basis. Today's announcement says it will be involved in a research project with Airbus for landing gear development. No indications of how much of the £38m funding will flow through to TRT. Probably very little, would be my guess. I see very little prospect of TRT scaling up into a viable long-term business, having followed it for many years (it listed 25 years ago!).
SysGroup (LON:SYS) - up 16% to 35.5p - Trading Update - Paul - AMBER/RED
Over the top commentary of the day award - goes to the Exec Chair of SYS, who claims to have "totally transformed" things since he joined 9 months ago. Expects £2m adj EBITDA for FY 3/2024, but it already reported £1.6m in H1. Net debt of £3.4m unchanged from 6-months earlier. Last balance sheet is weak, at NTAV £(7)m, and it has to pay £1.8m in contingent consideration shortly. It had to pay an eye-watering £1.5m to get rid of previous CEO. Lots of talk of AI & machine learning in the commentary. Paul's view - sounds a bit rampy to me, with no real profits yet, so I reserve judgement until seeing the full numbers. For now though, I think it probably needs another placing, so will go AMBER/RED.
Summaries of main sections
McBride (LON:MCB) - 111p (£193m) - Trading Update [ahead exps] - Paul - AMBER/GREEN
Another ahead of expectations trading update, from this remarkable turnaround. I can't quite get my forecast figures to work below. Useful reduction in net debt, which is still substantial (but no longer an emergency), and don't forget the pension deficit consumes £4m pa in cash from the company. Overall, I like it, but wonder if supermarket customers might put the margin squeeze back on in future?
Metro Bank Holdings (LON:MTRO) - unchanged at 34.6p (£233m) - First Quarter Trading Update - Graham - AMBER/GREEN
I’m upgrading my view on this one as today’s update shows the bank winning low-cost deposits and adjusting its lending to focus on specialist areas. Metro is very well capitalised after last year’s fundraising efforts and trades at very cheap valuation multiples, but now it needs to prove that it can be profitable.
IG Design (LON:IGR) - up up 30% to 157p (£153m) - Trading Update - Paul - GREEN
An excellent ahead of expectations update today, but why did the company leave us in the dark on trading for 5 months?! I think today's rebound looks fully justified, as I crunch the numbers below. Strong balance sheet, so divis should be on the cards soon too. Looks good value still, so a continuing thumbs up from me.
James Cropper (LON:CRPR) - up 32% to 350p (£33m) - Full Year Trading Update - Graham - AMBER
The market is hugely relieved by this update as it suggests that the bad news flow from CRPR may have ended with profitability now set to slightly beat the hugely downgraded expectations. The company is discussing covenants with its bankers so it’s not yet completely in the clear.
Card Factory (LON:CARD) - up 7% to 107p (£372m) - FY 1/2024 Results - Paul - GREEN
Results look good, and the best bit is the 4.5p divi announced. So shareholders now receive an income whilst they wait for the Teleios overhang to clear. Balance sheet now sorted, with bank debt paid down to modest levels. Free cashflow isn't as good as I had expected, but I think it supports a potential doubling of the divis over time. It's good, and it's cheap, so has to be maintained at GREEN.
RBG Holdings (LON:RBGP) (Paul holds) - down 20% to 9.75p (£13m) - FY 12/2023 Results - Paul - AMBER/GREEN
Terrible 2023 results, and a diabolical balance sheet. However, turnaround actions have dealt with the main problems, and bank facilities renewed on reasonable terms. So I think there's a potentially good turnaround, possible multibagger here. It is higher risk though, not for widows or orphans.
Paul’s Section:
McBride (LON:MCB)
111p (£193m) - Trading Update [ahead exps] - Paul - AMBER/GREEN
McBride plc (the "Group"), the leading European manufacturer and supplier of private label and contract manufactured products for the domestic household and professional cleaning and hygiene markets, today provides a trading update.
It’s two months away from the current year end, FY 6/2024.
This has been a stunningly good turnaround, well done to bulls!
It’s more good news today -
Continuing trading momentum from operational delivery and strong demand levels.
Financial performance ahead of our expectations.
March & April trading ahead of expectations.
9m to 3/2024 - revenues up 8.2%, mostly from volume growth of +6.5%
Input costs - a bit mixed -
Input costs for chemicals and packaging remain at similar levels as at our last update in February 2024, with employment, general supplies and financing costs continuing to apply inflationary pressures. There are early signals that certain materials will see price rises as we progress into the second half of 2024, primarily in the more sustainable materials categories. Additionally, the Group continues to monitor and manage potential supply chain risks caused by heightened geopolitical tensions.
Upwardly revised guidance -
As a result of continuing strong trading performance, the Group now anticipates that adjusted operating profit will be c.10% ahead of current market expectations* and that net debt / adjusted EBITDA will be close to 1.6x by 30 June 2024.
* Group-compiled consensus of broker forecasts for FY24:
· Adjusted Operating Profit £61.0m
· Net Debt £132.0m
I can’t find any broker notes unfortunately. Stockopedia shows broker consensus as 19.6p for FY 6/2024, so I would assume that’s now heading usefully higher. Pity they’ve joined the new fashion for quoting operating profit, which of course ignored the large finance costs associated with its still heavy (but coming down nicely) bank debt.
It made £30.5m adj operating profit in H1, so H2 is now guided to be exactly the same, resulting in £61.0m for FY 6/2024.
Net debt has fallen from £145.7m at 31/12/2023, to £132.0m now, which is excellent progress. As I mentioned last time, net debt is no longer an emergency. It’s high, but coming down, and since EBITDA has risen so much, it’s looking manageable now.
Don’t forget there’s also a pension deficit to adjust for in your valuation calculations (£4m pa deficit repair cash costs currently, based on a 2021 actuarial deficit of £48.4m).
Adj PBT was £22.4m in H1, so double that for FY 6/2024, to £45m. Take off assumed tax of 25% (it was 27% in H1), gets PAT of £34m. Divide by 174m shares, and I get 19.5p adj EPS. Strange, as the existing consensus is 19.6p, so why isn’t my figure any higher when they’ve just reported op pr 10% up?
Paul’s opinion - I was slow on the uptake for this turnaround last year, but we gradually turned more positive as the trading updates improved. We were amber/green last time, on 27/2/2024. With continuing positive trading, ahead exps announced today, I’m happy to stick with AMBER/GREEN, although it was close re going fully green. We can’t ignore debt & pension deficit, hence my slight caution on valuation.
The forward PER is only 6.3x, and debt is now steadily reducing not just in absolute terms, but also relative to the value of equity. Market cap of £193m (pre-market) compares with £132m net debt. Expect that gap to widen in a good way for equity holders, as equity I think seems likely to continue rising, and over time, net debt is coming down usefully.
I still have reservations about how high the margins can go here, and whether this current boom in trading is necessarily sustainable though. Supermarket customers are likely to get to work on squeezing its margins back down again, once macro conditions have normalised. So far, so good though! Next step maybe 120-150p/share? Looks plausible to me.
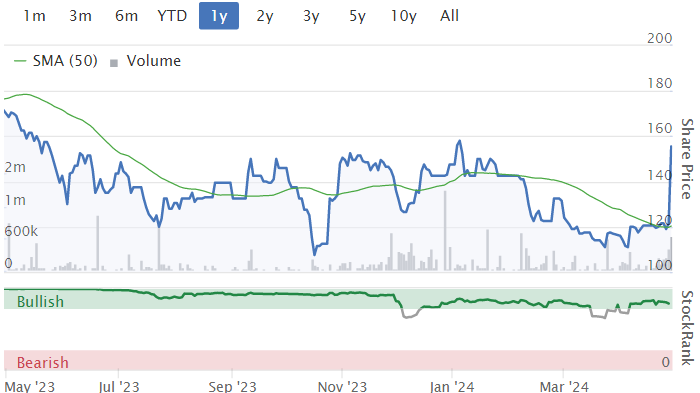
Stunning turnaround -
IG Design (LON:IGR)
Up 30% to 157p (£153m) - Trading Update - Paul - GREEN
IG Design Group plc, one of the world's leading designers, innovators and manufacturers across various celebration and creative categories, provides an update on its financial performance for the year ended 31 March 2024.
IGR shares have been drifting down, probably due to the news blackout from the company. Management really need to address this issue, it’s left a yawning gap in reporting to investors - last updated on trading five months ago, on 28/11/2023. That’s ridiculous. A much more prompt reporting cycle is needed. Shareholders own the business, they want to know how things are going at regular intervals, not be left in the dark for 5 months!
When people see the share price drifting down, a lot of traders (as opposed to long-term investors) assume that insiders must know something, and are selling. Also, stop losses kick in, and people end up drifting away. Sometimes a falling share price is an indicator of poor trading, but sometimes (as in this case) it isn’t. Hence why clear, and frequent trading updates from companies are essential.
Anyway, all is forgiven with a 30% share price rise this morning on good news - and how marvellous to see a company using a meaningful reporting measure, of adj PBT -
The Group has continued to make good progress on its turnaround journey of improving operational efficiency and simplifying the business. These initiatives have resulted in significant growth in profit and margin for the year.
The Group expects to deliver adjusted profit before tax of $25.9m (FY23: $9.2m), which is ahead of market expectations. The Group's adjusted operating profit margin is expected to be c3.8% which is a further recovery of 200 bps on the previous year.
Revenue - is down 10% on LY to $800m, but I don’t care about revenues, this share is all about improving margins, which they’ve successfully achieved. It’s the sort of business where you want the company to be turning away low/zero margin business, and just focusing on profitable customers.
Financial position - was already good, with me flagging here on my top 20 share ideas for 2024 that IGR had NTAV of $286m, and that its bank debt was only for seasonal spikes in working capital (which is exactly what banks like lending for, as the risk of default is very low). Hence a strongly asset-backed situation is a good place to be, waiting for a turnaround, as the downside risk is only moderate even if the turnaround fails to make much progress. In other words, positive risk:reward, which is what we try to look for.
This is excellent, what it says today -
The Group closed the year with a net cash balance of $95 million (FY23: $50m), a $45m year-on-year increase which is well ahead of market expectation. The Group was average cash positive for the year despite its traditional seasonal cycle of working capital movements. This improved cash position was driven by increased profitability and continued improvements in working capital management throughout the Group.
Moving forward, the cash position of the Group is expected to continue strengthening due to its financial performance and sale of freehold sites following footprint consolidation in the DG Americas division.
Wonderful to see CARD joining the currently small group of companies which mention their average cash/debt position. This needs to become standard reporting for all companies, as year end snapshots of cash/debt are so easily window-dressed. It’s the average throughout the year that matters, but is rarely disclosed by most companies.
Historic issue re a potential liability of $5.5m is unwelcome news, but is easily drowned out today by the positive trading update.
Outlook -
The financial performance delivered in the year has been ahead of expectations and reflects the Board's aspiration to return to pre-Covid adjusted operating profit margins of 4.5% by 31 March 2025.
The increase in profitability came from both divisions, with the DG Americas division growing 132% (c$4m) and DG International growing 61% (c$12m). Whilst the Board expects momentum to continue into the year ahead; more of the profit growth should come from the DG Americas division. Management initiatives to underpin this track in line with expectations.
The Board is pleased with the operational progress and financial performance of the Group. As highlighted in our interim results, there remains caution in consumer shopping behaviour which holds down demand in certain markets and product categories. That said, actions taken over the past two years provide confidence in the delivery of the expectations for the year ahead, with the Group on track to deliver on its margin target for 31 March 2025.
That’s good news - indicating a margin improvement from 3.8% to 4.5% this year, FY 3/2025. That should translate to another decent rise in profit & EPS this year.
Valuation - Progressive has put out a note, commissioned by the company of course, so this is effectively the company’s forecast.
It shows 12.6c (10.05p) for FY 3/2024, which is now nailed down on the update provided today, so no guesswork there (subject to any audit adjs of course).
FY 3/2025 shows another big leap up, to 23.4c (18.7p).
I would value this share on maybe 10-12x FY25 earnings, not an aggressive valuation given the strong balance sheet, giving me a target share price of 187-224p.
It closed last night at 122p, so was ludicrously cheap with hindsight (but we didn’t know how the company was trading). At the time of writing (09:10) it’s up 28% to 155p - I think this rise looks fully justified, and once some profit-taking has happened, I could see IGR shares reaching 200p+ in due course (nice and vague on timing there, as obviously I have no idea when the market will re-price it fully).
Paul’s opinion - looks good to me. Not the most exciting company in the world, selling low margin products. It was badly hit by unexpected commodity price rises in the energy crisis, and supply chain problems. A big issue with IGR is that its products for Christmas, and other key times (eg Easter) become almost worthless if they’re late. So supply chain and warehouse/distribution management are critically important. Hence if talking to management I would want to know what key lessons, and changes, have been made as a result to prevent any similar supply chain problems in future causing another big upset.
However, as turnaround go, this one is now looking very convincing. Hence I see the share price rise today as fully justified, and there could be more fuel in the tank to take it back up to 200p+ the way I see things.
Both Graham and I were green on IGR shares late last year, and with news today that the turnaround is gathering strength, and shares still good value, I’m very comfortable reiterating GREEN today.
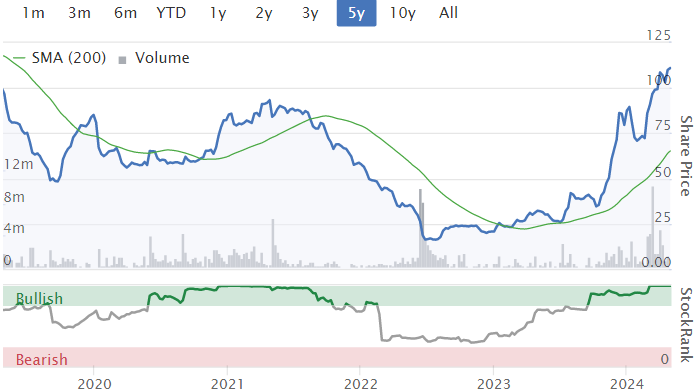
Lovely rebound today -
Card Factory (LON:CARD)
Up 7% to 107p (£372m) - FY 1/2024 Results - Paul - GREEN
cardfactory, the UK's leading specialist retailer of greeting cards, gifts and celebration essentials, announces its preliminary results for the year ended 31 January 2024 ("FY24").
The story here in a nutshell is that CARD was having problems before the pandemic, which then almost finished it off due to an over-geared weak balance sheet. However, the bank remained supportive, giving it time to trade out of difficulties, delivering an impressive turnaround under new management. Shares did very well, c.tripling in 2023 from late 2022’s lows, but momentum and investor excitement seems to have gone more flat lately. Not helped by major shareholder Teleios clumsily disposing of a large stake in dribs & drabs (and still holding 11%).
What are the numbers like then?
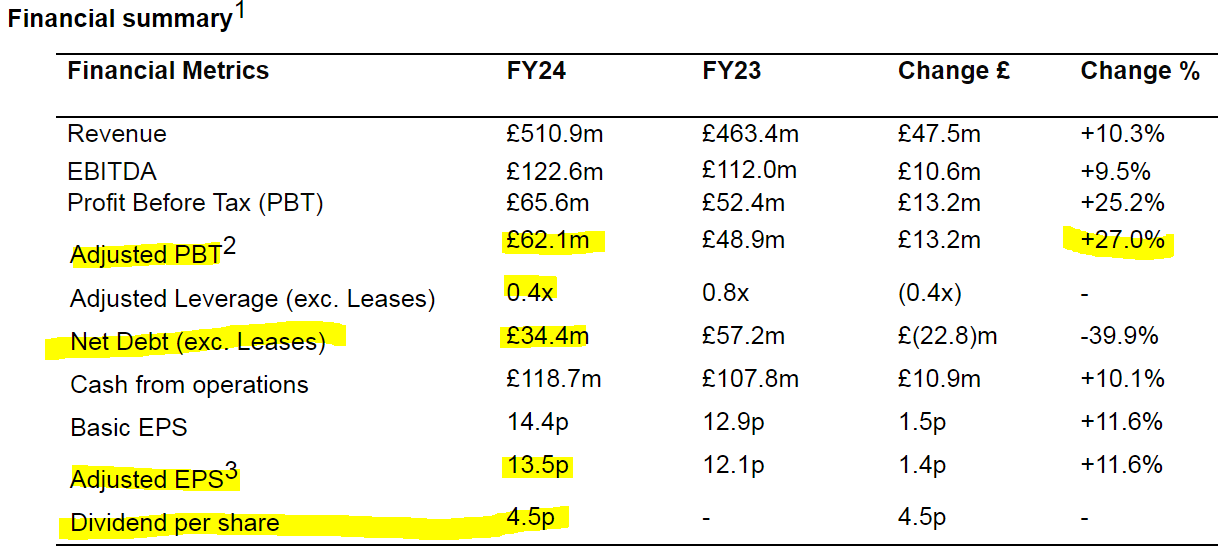
Highlights below look pretty good to me - main points being:
Healthy adj PBT margin of 12.2% - sign of a decent quality business.
Adj PBT growth of 27% also impressive (I’m fine with the adjustments)
Large reduction in net bank debt, now not even remotely a problem.
Adj EPS of 13.5p is slightly below the 13.7p broker consensus forecast on the StockReport
Biggest news is the return of divis, at a generous 4.5p (yield of 4.2%), and given the stronger finances & cash generation, I expect these payouts to rise in future.
Note that a much higher tax charge is the reason why EPS has grown more slowly than PBT.
To save me typing, here’s the outlook - not madly exciting, but OK I’d say -
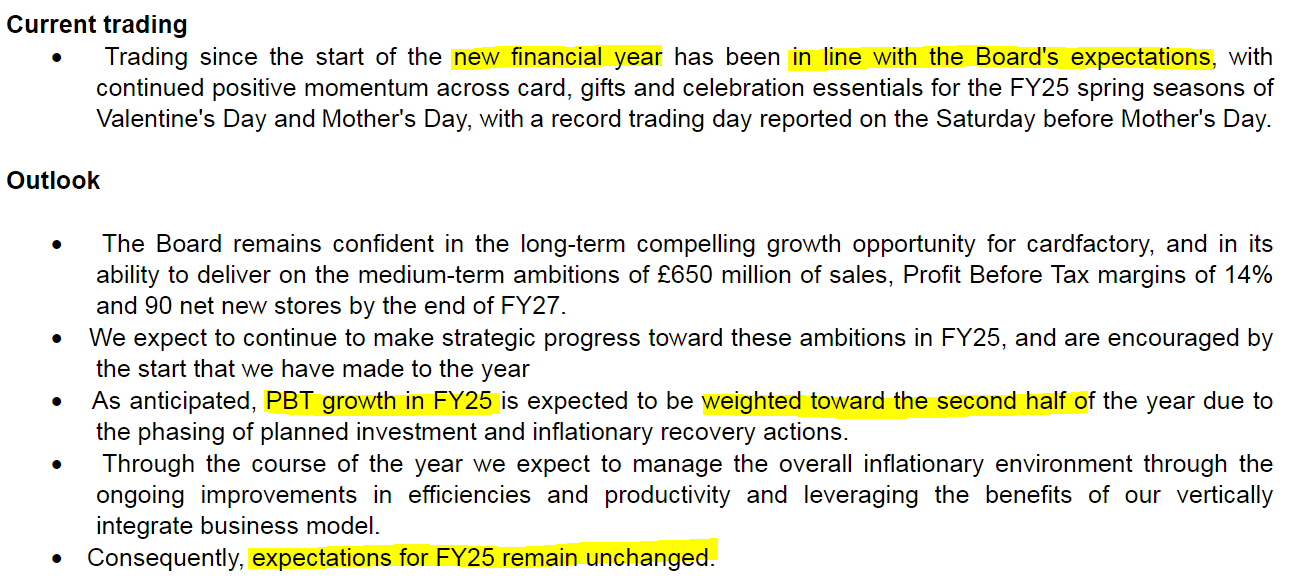
The aspiration above, if achieved, works out at about 46% higher profit than FY 3/2024, over the next 3 years. That’s good, but not exciting, and suggests to me that the lion’s share of recovering earnings has already been achieved. So steady profit growth from now on, not stellar growth. That’s fine for a low PER stock.
Balance sheet - much improved in recent years. NTAV is now only negative £(15.6)m. That’s not a problem at all for such a cash generative business, and should swing into positive this year.
Lease liabilities are not a problem, being almost the same number as Right of Use Assets. The commentary says leases are short (average 5 years) and with 3-year break clauses, and that rents drop 20% on renewal. Due to the mess that is IFRS 16, this filters through more slowly in reduced depreciation charges relating to leases.
Cashflow statement - is OK, with the main focus on debt reduction. As that’s now down to a sensible level, the focus can change more to paying divis.
If I re-jig the cashflow to better reflect reality, its free cashflow the way I work it out isn’t actually that brilliant, at £27m. I was expecting it to be better than that.
Paul’s opinion - I was expecting to be a bit more positive on these numbers than I am. The PER is cheap at 7.9x, and with EPS likely to increase almost 50% in the next 3 years (if they achieve target) then there would be probably upside on the current share price.
Debt is no longer an issue at all, which has allowed it to start paying divis. The 4.2% yield on today’s 4.5p divi (earmarked as a delayed interim + final in the commentary) has upside scope. My figures suggest it could possibly double (over time) the divis, so the dividend paying capacity looks good. I’ve worked that out on my free cashflow calculations. So this share could once again become a high yielder income share.
The main downside with CARD is I think its almost complete failure to do anything successful online, when Moonpig (LON:MOON) has demonstrated what a high margin, lucrative market that is.
Bottom line though, is that CARD has done a terrific turnaround, and is now probably worth about 130-150p I reckon. Sooner or later than Teleios overhang should clear, and remove the cap on the current share price. From now on you’ll get divis too whilst you wait. So I’ll maintain my previous GREEN opinion.
RBG Holdings (LON:RBGP) (Paul holds)
Down 20% to 9.75p (£13m) - FY 12/2023 Results - Paul - AMBER/GREEN
This is a special situation/possible turnaround, with management clearing up the mess created by Nicola Foulston, the disgraced former CEO.
Looking at the 2023 figures, this looks like a company that is about to go bust! Awful losses, and a diabolical balance sheet.
However, the reason I recently bought some at around this price, is because the problem areas have been disposed of, realising a bit of cash. Plus it’s done a small placing, and HSBC has given it leeway with renewed & modified borrowing facilities on quite good terms.
The core businesses are long-standing, and successful legal practices, which should be able to generate cash to get bank borrowings down to a more sensible level. There won’t be any divis for the foreseeable future.
The main remaining problem is surplus leased property, with 2 big central London offices costing a combined £4m pa. They’re aiming to sublet, or surrender leases, targeting £1-2m pa savings.
Adj EBITDA margin is 12% now, which they said in the IMC webinar today has scope to be raised to “mid to high twenties”. Well if that happens, then this share would be a multibagger (that’s why I’ve bought some). Needs a recovery in equity and property markets to drive recovery faster.
Paul’s opinion - hideous numbers, but entirely due to one-offs that are now resolved. Bank has given it time to recover. Current trading in line. I think there’s a good chance that the bank to basics strategy should work over several years. There’s some risk, but renewed bank facilities and recent fundraisings mean cash headroom should be OK. There’s no scope for any more mistakes, or a trading downturn though, so this is higher risk.
On balance I think it’s quite appealing, for more risk-tolerant investors like me. I like turnarounds where the heavy lifting has already been done, and all you have to do is wait.
EDIT: note the going concern statement is clean (these have to be signed off by the auditors remember), key excepts being -
The financial projections performed form part of a three-year plan which shows positive earnings and cash flow generation and projected compliance with banking covenants at each testing date.
The Board confirm that they have a reasonable expectation that the Group has adequate resources to continue in operational existence for at least 12 months from the date of signing the financial statements.
Therefore I don't see any risk of it going bust, based on the facts as they stand today.
A disaster so far, but could the worm turn? Note share count has risen from c.80m to 129m now, so some dilution.

Graham’s Section:
Metro Bank Holdings (LON:MTRO)
Unchanged at 34.6p (£233m) - First Quarter Trading Update - Graham - AMBER/GREEN
This is probably the only mainstream bank which I cover from time to time. In November, when the Q3 update was announced, I reiterated a neutral stance, arguing that the bank’s fundraising package had treated its existing equity investors well. That package saw the creation of 500 million new shares, which meant 300% dilution, but it could have been a lot worse!
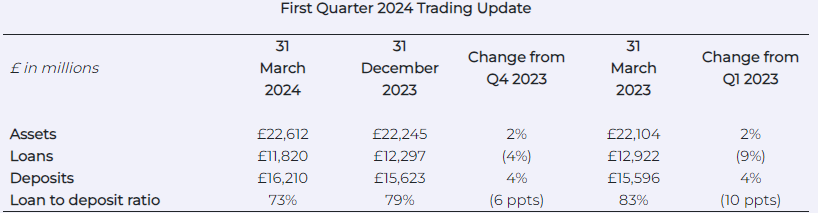
Today we have a Q1 update, with the following table:
Key points:
Deposits up £0.6 billion to £16.2 billion, “reflecting the continued success of the deposit campaign launched in the fourth quarter”.
Lending falls 4% to £11.8 billion “as the bank strategically repositions its balance sheet towards higher yielding Specialist Mortgages and SME/ Commercial lending”.
The lower loan-to-deposit ratio (73% now vs. 83% a year ago) implies quite a big change in the business over this time. But lending should pick up again as Metro builds on its new areas of lending focus. See the CEO comment:
“Following the successful deposit campaign launched in Q4, we have implemented our plans to reduce cost of deposits and optimise our elevated liquidity position... Lending activity levels are in line with expectations and the pivot to higher margin commercial and residential lending progresses, with lending balances reflecting the time lag between committing facilities and subsequent draw down…
Based on performance in the first quarter we remain confident that financial results will continue to improve throughout 2024 as we optimise funding, deliver on cost savings, continue our asset rotation and benefit from lower yielding fixed rate treasury and mortgage maturities.”
Graham’s view
Getting up to speed with Metro Bank’s most recent financial metrics, this is what I’ve found:
Balance sheet equity improved from £956m (Dec 2022) to £1,134m (Dec 2023), with only a slight change in total assets over that time.
The CET1 Ratio (a crucial measurement of bank safety) increased from 10.3% (Dec 2022) to 13.1% (Dec 2023). This would be considered a very normal and safe CET1 Ratio.
Including risky bonds and other sources of capital in the calculation, Metro’s total funding increased from 16.7% to 22% (see page 7 of the 2023 annual results presentation). Again, this should be plenty of funding to satisfy regulators.
I’m sorely tempted to give this one the thumbs up. It has raised the new equity and debt it needed to grow and to shore up its finances. It is winning low-cost deposits which are needed for profitability. And the new lending strategy (focused on Specialist Mortgages and SME/ Commercial lending) sounds promising.
So what’s the catch? I suppose the track record doesn’t inspire confidence:
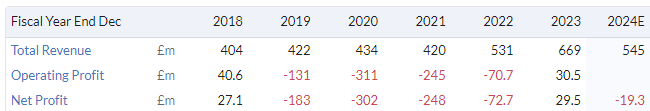
Given the history here, and the general lack of interest in UK financial stocks, Metro trades at an extraordinary discount to book:
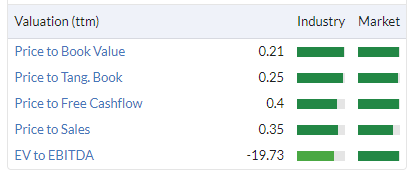
Since I think that Metro’s financial position is probably sound (you can never be 100% sure!), and since it is trading at such cheap multiples, I feel obliged to go AMBER/GREEN on this one.
I would probably come away with the same view if I studied the likes of Barclays (LON:BARC) and Lloyds Banking (LON:LLOY): they aren’t nearly as cheap as Metro when it comes to their value metrics, but they do have excellent track records of profitability and dividends.
James Cropper (LON:CRPR)
Up 32% to 350p (£33m) - Full Year Trading Update - Graham - AMBER
James Cropper PLC (AIM: CRPR), the Advanced Materials and Paper & Packaging group, is pleased to issue an unaudited trading update for the 52 week period to 30 March 2024 ("FY2024").
The headline is that FY2024 profitability is set to be “slightly ahead of expectations”.
Furthermore, “the outlook for FY2025 is encouraging, with a return to growth expected across both the Advanced Materials and Paper & Packaging businesses for the full year”.
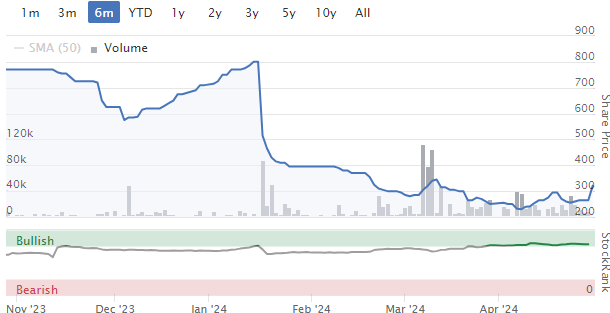
We last looked at this stock in January when Paul studied its “bombshell” profit warning.
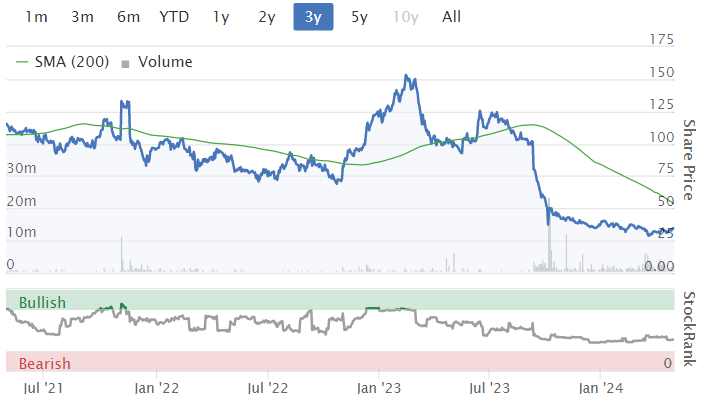
Therefore, while the stock price is up today, I should point out that the overall trajectory has been lower:
Let’s dig into the performance at each of James Cropper’s divisions.
Advanced Materials
The Advanced Materials business saw a year-on-year contraction in revenue, primarily reflecting the slowdown in fuel cell market demand.
For more info on James Cropper’s hydrogen fuel cell business, see here.
Excluding that business, Advanced Materials “was underpinned by growth in the aerospace and automotive sectors”.
The mid-term outlook “remains strong”. A new MD is joining at the end of July.
Paper and Packaging
Within the Paper & Packaging business, supply chain destocking compounded by the impact of high inflation on consumer confidence continued to be felt through the second half of the year.
This bit is more positive…
The future project pipeline is encouraging and forward indicators, such as order intake, point to early signs of market recovery throughout FY2025.
Net debt finished the financial year “better than expected” due to lower working capital and capex.
But beware, the company also says “it is currently seeking temporary covenant adjustments on its UK banking facility to ensure sufficient headroom is retained. Discussions with banks have commenced and a further update will be provided in due course.”
This does not mean that there has been a breach of covenants, but it does mean that the company is not entirely comfortable with the covenants for FY March 2025.
CEO's comment doesn’t contain any specific information.
Estimates from Shore Capital suggest that the company finished FY March 2024 with £16.5m of net debt. They see adj. PBT of only £0.6m for that year (previous forecast: £0.5m), and are waiting until July before they will publish forecasts for FY March 2025.
Graham’s view
Historically this company did generate small but consistent profits each year, although it never generated hugely attractive quality metrics, to my eyes.
Last year was unusual: a serious wobble in terms of profitability, not revealed until late in the year.
And it does seem to have an issue with its debt. Although that issue is unlikely to be fatal, it does mean I would want to treat these shares with additional caution.
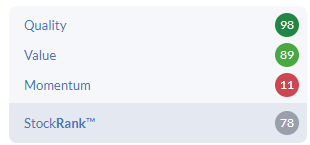
Overall, I see this share as perfectly average, with a few (hopefully temporary) problems that I expect it to sort out.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Another intersting blog post by Woodford https://www.woodfordviews.com/... Some fair points about the relatively limited impact of rate cuts on household budgets versus other positive tailwinds in 24/25. I think Paul has also rightly been mentioning a number of these a few months back, but its interesting to see the estimated size of them versus the interest rate impact.
Fantastic article many thanks for sharing
Interesting in the notes, Card Factory (LON:CARD) shows £17m book value of freehold property, that’s half their £34m net debt (excluding leases). Nice to have in the back pocket. As long as they don’t do a daft acquisition, soon this could really throw off a fair bit of cash.
Northamber (LON:NAR) The acquisition of Tempura communications is potentially very positive. I know Tempura and the owner Matthew Light as we buy AV equipment from them, though had no idea he was selling. The main distributor for Heckler Design in the UK as well as Yealink. I do not hold as Northamber appeared to be drifting but will re-look at it once the acquisition is completed.
Transense
Have to disagree with Paul’s summation which seems to include a negative view because he owned it years ago !
I’ve had a very close loo at the business and the two remaining divisions and have done some deep product and sector research .
It’s not always correct to write off a jam tomorriw serial disappointed .
Take a look at Filtronic which you could say the same things about .
I am biased but I have also done the hard yards and sawsense has a long runway , the tyre monitoring technology is an open goal and they just have to tap the ball in , there have been some key changes in binning out underperforming non commercial men in white coat types and replacing with sales .
The tyre monitoring division is a total open goal and I think watch the RNS in next 6 months to prove me right .
From shares magazine:
With a ‘buy’ rating on Card Factory and a 175p price target, Liberum Capital remains ‘very favourable on the outlook and Card Factory’s disruptive, value-focused market position where the new strategy remains on track to deliver exciting medium-term ambitions.’
Hi Paul - Re Card Factory (LON:CARD) - you mention " Moonpig (LON:MOON) has demonstrated what a high margin, lucrative market that is." Just comparing the 2 from the Stocko reports, Card has a target margin of 14% v Moon 18%. In very simple terms that's a "bricks v clicks" comparison. I would argue that Card need to defend their bricks offering, particularly in the UK, as more retailers report people physically shopping in store (e.g. Sainsburys re-iterated this point this/last week). If Card get their higher margin lines moving (i.e. gifts v cards) then I can easily seeing them reaching 18%+. Ergo - is there any point in Card trying to take on a well established online operator when it is well positioned on the high street? I see Card as "the Greggs of gifting" - why upset the applecart?
Agree with this. Gulf Keystone Petroleum (LON:GKP) very good value in the long run. Just have to hold our nerve until all interested parties agree to reopen the supply. I hold. A dividend King again in due course.
On McBride (LON:MCB) there is one other big threat to continued growth - return to normal demand for own-brand products.
They have benefitted in the last year because of a huge surge in demand for supermarket/pharmacy own-brand products, which are cheaper than branded goods from the FMCG giants.
But as the inflation shock eases, and wages catch up, then wouldn't many of those shoppers who traded down, now have money to trade back up? The FMCG companies are also quite cash rich, so would probably be aggressive in pricing, promotions, marketing to capture back lost market share to own-brand products.
Meanwhile, margins will probably come down, as supermarkets start to gain the upper hand again, and squeeze suppliers, like Paul says.
Still, McBride has gotten a really valuable lifeline in the past year, and balance sheet wise is in a better position...
McBride (LON:MCB)
then wouldn't many of those shoppers who traded down, now have money to trade back up?
good question i certainly wouldnt presume that when people have started saving money and they may have realised the quality may near identical on the cheaper item that they would be in any hurry to swap back. Some reversion to the mean for sure (not all cheaper stuff will be the same quality) but i wouldnt presume those that have gone to the other side wil all go back.
I remember not accepting any tomato soup other than heinz back in the day , that was until i was 18 and started buying it myself out of my own limited funds - i then realised the cheap stuff is tolerable and i have never gone back - other than the odd treat for old times sake.
I think its sensible caution though to suspect better margins may not last forever - in that regard its a tricky one to see how this will pan out.
Facilities by ADF (LON:ADF) following up on messages posted on Friday after their results, in a bullish presentation on the IMC platform this morning, management confirmed that there would be a final dividend at 0.9p, matching last year and delivering a full year increase. FD had to struggle to find the pay date (19 July). I still can't see it in the RNS. Shares up over 6% as I type.
Great write-up by Matrin Fitton on IG Design (LON:IGR) :
https://martinflitton1.wixsite.com/privatepunter/post/igr-on-the-recovery-road-30-04-23
Gulf Keystone Petroleum (LON:GKP)
Price 113.5p
Market Cap £252m
At some point this year the pipeline from Iraq to Turkey will open again (all parties involved ; Kurdish government ,Iraqi government and the Turkish government will find a solution at the end as they are all losing billions of revenue pa).
OPEC has recently urged all involved to find a solution as soon as possible.
Gulf Keystone Petroleum (LON:GKP) has managed not to burn any cash, while the pipeline shut by selling oil locally.
The oil field has at least another 28 years life. Also nearby oil fields can be developed,
Estimated FCF will be over £100m as soon as the pipeline reopens and dividends can easily match half of current market cap!
Estimated 2026 cash about the same as the current market cap as well with an EV/FCF of less than 1!
All the best
Assuming the pipeline starts pumping again, how much will they be able to realistically pump, given that they have agreed with OPEC to cut output? Or will they reduce volumes elsewhere?
OPEC cuts are usually announced to stabilise prices and have no impact on the numbers I have provided. The issue here is the pipeline opening and the flow of oil from Iraq to Turkey.
Here's 1Spatial (LON:SPA) FY24 results webinar video & podcast. The focus for FY25 is developing business with the utility networks in the UK, especially their first adopter UK PowerNetworks, and in the US further building the go-to-market. This strategy is covered in the presentation. FY26 should see the fruits of their labours. If this interests it's worth looking at the 1Streetworks CMD too, Andy Fennel, MD of Roads is particularly impressive and relatively new at SPA.
Sad news, I've just found out that Revolution Bournemouth (my local) is permanently closing. Such as pity, as the staff there are lovely, and really good hosts.
Trouble is, the format has just had its day I think, and there's far too much competition now, esp with a newish "Popworld" nearby.
Even £2.99 hot food offers, and £2.50 pints of Amstel didn't seem to attract many punters. Only ever busy on Fri & Sat nights, and student nights (who trash the place).
This is the second big restructure in only a few years. So doubt I'll be revisiting this share, even assuming all the conditional aspects of the restructure go through. Although Peach Pubs and the De Cuba offerings seem better. Incredibly difficult even for the large chains to make much profit these days out of pubs - mainly because wages costs have soared over the last 2 years, whilst customers find other things to do with their money.
I last mystery shopped Revs this weekend just gone, and enjoyed the live band, a Bon Jovi tribute group - little did we know that Revs literally was Livin' on a Prayer :-(
https://youtube.com/shorts/9bU...
Revolution Richmond in Surrey was quite nice, smartly kitted out inside and right on the river, although admittedly did have a bouncer on the door.Haven't visited for ages since i moved.Prime location too.Just checked the local rag and apparently it got shut down permenantly during covid.Wonder who took it over.Probably another All Bar One or another Ivy restaurant or some very posh flats.However, Revolution Brighton looked a dive from the outside as i couldn't get in without an id, despite sporting a very fashionable salt n pepper beard.
Hi Paul - just looking at your top 20 spreadsheet and a mightily impressive 20% YTD return - well done on those picks!! You are beating me alas - I’m only around 15% YTD - maybe I should give up and just buy your top 20 :-) or try harder - I’ve still got 8 months to make up ground……. To be fair we have some overlap but the biggest difference in performance was in me not spotting the CMC Markets (LON:CMCX) opportunity, which I am kicking myself on. Suspect that has further to run medium term but hoping for a bit of a pullback.
Poolbeg Pharma (LON:POLB) and so Amrit 2.0 begins. First orphan drug option signed. Interesting.
@RNK, does anyone know why the Rank share price has gone up a lot over the last two days (on massive volume yesterday), I cannot find any news/reason for it?
Rank (LON:RNK)
Just saw the RNS that Guoline has increased their stake in Rank (LON:RNK) from 57% to 60%.
How can a shareholder have a more than 30% shareholding, and is allowed to increase their stake?
Does this mean they now need to make an offer for the rest of the company, at the price they paid? (I don't think they bought any shares in recent history)
The rule used to be (and probably still is) that you are restricted about how fast you can move from 30% to 50% without triggering a mandatory bid under the Takeover Code (can't remember the exact detail now) but once you are over 50% you are unrestricted - presumably on the basis that you already have voting control.
Thanks sherriff
Thanks Boon
From Hong kong, Singapore, Hawaii, Malasia and London listings around a certain 80 year old Mr Tan Sri Quek Leng Chan (head honcho) and family then who knows what is a trade here. Only looked up as thought Rank (LON:RNK) was familiar but looks like a movie script. For me will pursue less risk assets like junior gold miners lol.
I think Stockopedia & the SCVR are superb. I have one small comment. I would love to see a specialist commodities analyst provide a monthly review of the sector. My recent biggest winners have all been in this space. Gulf Marine Services (LON:GMS) is up nearly 400% in the last year, Paul had brilliant success with Plexus Holdings (LON:POS) and my largest investment winner to date has been Valeura Energy (TSE:VLE), a 10 bagger in 18 months since Oct '22. Valeura is a Canadian O & G co with oil assets in the Gulf of Thailand and, even after such a big rise, is still on a forward EV/FCF of @ 1. This shows how cheap and unloved the sector is, a great contrarian play imo. These are real assets producing real cashflows. The energy transition is one of the biggest investment themes of our lifetimes, and is throwing up some great investment opportunities imo as overlooked sectors, such as O & G, come to life again as the importance of energy security is realised by societies and govts. There are also great opportunities in the mining space. Gold is hitting all time highs, copper is much in demand for electrification, tin is needed for solder & solar panels, lithium for EV's etc. Real assets that provide volatility hedges, and build and power our world. Commodities or ESG ? Long term I know which one I'd pick to create most value & thus shareholder returns.
If only there were more posts and posters on other threads including on commodities your wish would already be granted. I’ve read that a lot of Stockopedia subscribers are unaware that there are a wide range of investment threads here, and only read this one.
Here’s a link to a Mining thread I started:-
https://www.stockopedia.com/co...
As with most of the other threads here, including ones started by and run by Stockopedia staff writers, there are very few follow up posts and replies. And the Mining thread above is a good example….just a few good posts and posters on a limited range of Mining shares. It could be so much more useful if only people realised that these other threads existed and posted on a much wider range of commodity shares there. Or someone start a new thread that might get more seen.
For evidence to back this up. I‘ve written posts on some of these threads that went on to get no replies and only a couple of up ticks. So occasionally if thinking far more might be interested, I’ve pasted it on to this bb and got over 100 up ticks and excellent replies too.
Don’t know what the solution is, if there is one.
I click “discuss” and then “all posts” and it brings up this page showing all the other threads, with those with the most recent post at the top.
https://www.stockopedia.com/di...
Hi Ken, it must be relatively simple to create a menu for posts. Eg: 1. SCVR .2. Mid & Large Caps. 3. Commodities & Mining . 4. ETFs 5. Investment Trusts. 5. US Equities.
Perhaps a redesign to have the above tabs at the top of the page
Morning All,
Just Introducing Strip Tinning Holdings (LON:STG) to the community, if only to put it on Paul and Graham's radar for the future.
It was a 2022 float and, surprise surprise, it listed at 185p and is now 45p. For one reason or another (a personal connection) I was invited to participate in the float but declined on the grounds both of valuation and management sell down.
It's facilities are 5 mins from my home so I decided to follow things from a short distance. It raised £5.1m in a placing and retail offer (plus some EIS qualifying CLN's) in January, ostensibly to support the company's "emerging EV business", for these purposes we're talking components for EV battery packs.
Anyway FY results this morning scraped a tiny adjusted profit amid talk (per a Singer note) of a significant "growth inflection point", and accompanying TP of 75p. It does seem to be picking up contracts of late (one of £12.3m and another of £6.3m / both lifetime), or "nominations" as they are called. These seem to be for the ("tunnaround") glazing side of the business.
An AIM listed nano cap at £8.6m mk cap so all the uaual caveats apply. It has a new CEO in what looks like planned succession.
https://www.striptinning.com/
This is really just to introduce the company and see if there are followers with any views. Perhaps one to keep an eye on, should the nominations keep coming.
w
The most useful metric has been left out of the Metro Bank Holdings (LON:MTRO) update - the net interest margin KPI for the quarter!
They hint that it has improved? Through lower costs of deposits/funds. But it is not explicit.
For me, if the NIM stays as it is, they will be roughly break-even, and struggle to get to meaningful profitability. This is why I sold out last summer; NIM had stopped growing. All the other lenders are also reporting a stabilisation of NIM, with some decreases even, rather than continued increases.
They need one of three things to happen for healthy profitability:
However, none of the three seems to be done at the moment? Which leads me to think they could continue to eek out break-even or small profitability, but nothing more.
Re: Metro Bank Holdings (LON:MTRO) Net Interest Margin KPI:
"Underlying net interest income increased by 2% to £411.9 million (2022: £404.2 million) driven by
improvements in net interest margin (NIM) which is up 6bps to 1.98% for the year (2022: 1.92%) reflecting improved yields on new lending and treasury investments offset by the impact of increased cost of deposits in the fourth quarter following the successful deposit campaign."
Yes - NIM is covered in detail in the Metro Bank Holdings (LON:MTRO) FY23 results... but I was hoping they might have updated on it in the Q1 trading update.
Quite a bullish (from management) trading update from James Cropper (LON:CRPR) today.
As I was expecting, they need a covenant holiday from their banks, and discussions are underway. Normally, a statement like that will cause the SP to plummet, given that there's a heightened risk of an equity fundraising to satisfy the bank, or some other onerous demands from the bank in exchange for a covenant waiver.
But it seems like the market is focusing more on the positive outlooks by the company, albeit more mid-term. Or the SP was too depressed assuming the worst.
Nothing in the trading statement, for me, is real traction that both businesses are back on the growth pathway though. Just some optimism, and hints of leading indicators.
The Advanced Materials division is really a very good business. They blotted their copybook for the first time last financial year in the hydrogen market but the core AM turnover is targeted at aerospace, medical, defence and industrial sectors and should be growing strongly now that headwinds have abated in some of the target markets and in some cases have very much turned about. If they can quickly address the problems in hydrogen, was about 20% of the AM turnover, and sell the paper division(never going to happen) then this has got a lot of upside.
The restaurant sector is a tough one at present:
"Premier Inn owner Whitbread is to cut 1,500 jobs as it closes restaurants and expands its hotel business.
It plans to cut its number of branded restaurants by more than 200 in favour of building more hotel rooms.
The job cuts, which are subject to consultation, will come from a total UK workforce of 37,000 employees.
The group's restaurant brands including Brewers Fayre and Beefeater.
It plans to sell 126 of its less profitable restaurants, with 21 sales already having been agreed.
It will also close 112 restaurants and convert the space into new hotel rooms.
Whitbread said the changes would add more than 3,500 hotel rooms across its estate."
Source: BBC https://www.bbc.co.uk/news/art...
Along with Serco (LON:SRP) should be massive demand this summer.
Tortilla Mexican Grill (LON:MEX) Like Paul I am a fan and recent buyer. But today in Richmond my basic veggie cost £8.60 up from £7.40 in a month. It was £5.50 during Covid. With Greggs and Dominoes in pizza/wrap wars at £4.50 I am not sure how many will see £9 as cheap even with the base wage increase. The mid value operators are going to find life tough. I wonder where the MEX franchise locations will be? Whitbread are ahead of the game on this one.
Card Factory (LON:CARD) As a shareholder this has taken some patience as the share price has been range bound now pretty much since the start of 2023. The elephant in the room seems to be the overhang from the Teleois shareholding. This now looks to be c10.99% according to Stockopedia with 2.1m shares sold. If they continue to drip feed their shares out it’s going to be tricky for the shares to rerate
Todays 4.5p dividend does gives me some reward for remaining a shareholder in the meantime
Card Factory (LON:CARD) I agree it is testing AstonGirl - surprised it is not up more today
Given it looks like it will make circa 15p eps this year and reduce debt further this really should be on 10* at least in my view - particularly given its cash conversion of 96%
Debt reduction and refinanced RCF should add £2m to the bottom line and medium term target of 20p EPS confirmed (so that’s usually 3 years)
Now a 4%+ dividend payer again so that should help. Teleois position not entirely clear. The occasional sale into the market just reinforces peoples views of an overhang. They would be better either selling the lot at some point. Would probably get a much better price but who knows what pressures to sell they are under.
I have to hope that today's Card Factory (LON:CARD) results (including refinancing/dividend list story) plus presentation colour in due course allow someone (e.g. Schroders who seem to like this sort of space and who I don't see on the register) to take a block of shares. Might not be today or tomorrow or the day after but the forward pe multiple/growth potential online must surely be attracting some interest. Like you say, now you get paid a divi to wait.
It has been a very long time since Teleois updated us on their holding. When would they next be obliged to update the market, when they move below 5%?
This worries me slightly that there is still a long way to go until their holding is cleared (provided they want it all gone) and I agree that this one could be a grind before we see a genuine re-rate. However, with online improving in H2, a decent divi, and strong start to the year it seems safe to assume the SP wont fall back below 100p on Card Factory (LON:CARD). Breaking out beyond the resistance around 114p will be a challenge though. So bouncing between those values is most likely for the near term one would expect.
No BenHazz - they need to update any time they trade shares in Card Factory (LON:CARD) until such time as they fall below 3%.
So we can see from this that there is very little activity. The problem is that people “suppose” Teleois are selling their entire stake because they have sold some at different intervals. That may or may not be true, we dont know, but that doesn’t really matter as the perception is of an overhang so unless they come out and say “we are a long term stakeholder” or sell below 3% that perception will remain. I can’t see how the lack of clarity from them helps their position economically given its impact on the share price. You’d think they would have a strategy but maybe they don’t.
I thought it was required to update the market at 1% intervals above 3% threshold ie. moving down from 5% would only require the update once it crossed the 4% mark - anything around 4.1-4.9% could be actioned without reporting in order to avoid over-reporting as blocks could take a couple of days to clear.
Thanks for the clarification David, much appreciated. So would it be safe to assume that if by the end of next week there is no RNS then Teleios are in fact , not selling. I agree, they need to update the market!
I just don't know BenHazz - I thought they had finished a while back as they hadn't sold any for ages and then an RNS popped up, so long and short of it I'm not sure we can assume anything with Teleois. Therefore the market will continue to assume overhang irrespective of their intentions I suspect.
Thought the webinar that has just finished was excellent. Really nice that analysts and investors are in the same meeting and it was possible to see/hear the analysts ask questions and get the same answer !
Mgmt seemed very relaxed and not afraid of details, whilst not appearing to over exaggerate the future.
A mixture of debt reduction, increased dividend, a very solid balance sheet and a nimble approach to store openings and closings gives me a warm feeling going forward.
I can see funds now buying in, and a potential bid from PE given the strong cash flows.
Camaccord Wimding down which fund ?
Anyone know which fund Camaccord winding down .
Have noticed some unusually high liquidity and huge trades in a few of my holdings and common theme is Camaccord
Though might be just some increased liquidity but seems more than that .
Odey Asset Management have transferred the Odey Opportunity Fund together with its manager, Geoffery Marson to Canaccord Genuity Dynamic Fund. It may be that Geoffery is rebalancing his portfolio post transfer?
I would be interested to know what equities you are seeing increased liquidity in if you are happy to share.
IG Design (LON:IGR)
I mentioned them in a recent SCVR as one of Paul's 2024 picks which had drifted 20% since Jan. Great update today. Canaccord:
"IGR’s FY24E TU highlights a better-than-expected financial outcome and confirms another year of progress in rebuilding margins and profitability. Whilst the 10% revenue decline was in line with expectations, margin recovery was better-than-expected with FY24E EBIT margins increasing by c.200bps yoy to 3.8% (CGe 3.4%), delivering adjusted PBT of c.$25.9m (CGe $20.5m), growth of c.182% yoy and c.27% ahead of our $20.5m forecast. YE net cash of c.$95m (CGe $75m) is also better than expected. The strong FY24E outcome gives management confidence that it can return the Group to prepandemic margins in FY25E. We see today’s update as a potential inflection point that should give the market confidence in the deliverability of future forecasts. We believe the market should now focus on the near-term strategic growth ambitions presented by management, which include an aspiration to achieve c.$900m in revenues, EBIT margins north of 6%, and adj. PBT of c.$50m by the end of FY27E, +c.40% compared to IGR's previous record adj. PBT of c.$35.8m in FY19. The FY24E margin beat prompts meaningful FY24E profit upgrades, albeit FY25E P&L forecasts are unchanged at this stage with cash forecasts increased."
And another excellent pick from Yiannos1 as well ( although suspect that his subscription may have run out now / soon )... many thanks to him and to you eParo for flagging... team game as Paul says
I wish Yiannos1 would stay as a subscriber but just be more measured in some of his comments which are otherwise often very insightful
Good update today from IG Design (LON:IGR) and I've decided to buy in on this news having been waiting for signs of a turnaround in the US. However, one thing I'm nervous about with IG Design (LON:IGR) is international revenue has gone from +8% at the half year to flat at the full year. I take Paul's point that margins matter more than revenue but I think margins have been better in international so falling revenue here might be a concern. Something to keep an eye on for now.
Transense
Bit of a vague RNS about “joining a 34 million project with Airbus to put their sawsense technology in some landing gear .
I know they are very limited by Airbus on what they are allowed to say .
Price has come off last few weeks as Cammaccord have been selling down as they are closing that fund . They are down to 1.35% now so that will be cleared soon .
I met the CEO few weeks back he’s very grounded and understand the importance of selling things for more than you pay plus he had a good track record building and selling his own businesses .
Things are definitely happening and market cap is underpinned by a pretty much guaranteed income stream from a current license agreement
It’s now or never really if it’s going to happen at Transense it’s got to be in the next 6 months for them to show the two remaining parts of the business can be commercialised .
My morning smallcap tweet: Full fathom five thy sucker stock lies
SysGroup (LON:SYS) Cloudcoco (LON:CLCO) Pebble (LON:PEBB) Shield Therapeutics (LON:STX) Software Circle (LON:SFT) Transense Technologies (LON:TRT) Fusion Antibodies (LON:FAB) Sorted group (LON:SORT) McBride (LON:MCB) IG Design (LON:IGR) James Cropper (LON:CRPR), £RGBP
◄SysGroup (SYS)► guides FY-Mar rev up 5% and adj EBITDA c.£2m. In line? "Evidence is becoming indisputable that adoption of AI is no longer an option for businesses." Chmn needs some AI help maybe to improve that sentence for him. [SP=30.79 Cap=16m]
◄Cloudcoco (CLCO)► FY-Sept out. Unsuspended. Loan notes (£5.85m inc int) extended to Aug 2026 from Oct 2024. Fee £550k. CEO scarpers. Outlook "confident of making continued steady strategic and commercial progress". [SP=0.73 Cap=5m]
◄Pebble (PEBB)► £5m max buyback. Trading in line. [SP=56 Cap=94m]
◄Shield Therapeutics (STX)► FY-Dec results delayed to 'before 10 May'. Blames additional time to finalise the translation of presentational currency from GBP to USD. You wouldn't think that the spreadsheet was invented 45 years ago. Reiterates guidance. FY24 Q1 prescriptions up 1% over prev Q. [SP=1.32 Cap=10m]
◄Software Circle (SFT)► guides FY-Mar rev up 38% and adj EBITDA £1.7m (£0.4m). In line? Outlook cautiously optimistic. [SP=18.5 Cap=70m]
◄Transense Technologies (TRT)► has formally joined a project with Airbus to provide SAWsense technology and support the development of next generation landing-systems technology. [SP=93 Cap=14m]
◄Fusion Antibodies (FAB)► guides FY-Mar rev £1.14m (£2.9m). Blames "adverse investment conditions, although improving, continued to impede certain clients placing orders, with some pipeline projects yet to convert and some being received later than anticipated." Claims significant increase in sales pipeline opportunities during H2. "We remain optimistic for our prospects." [SP=3.6 Cap=3m]
◄Sorted (SORT)► gets £2m R&D tax credit. [SP=78 Cap=6m]
◄McBride (MCB)► guides FY24 adj op profit c.10% ahead of market expectations of £61m. Mar-Apr trading ahead of mgmt expectations. [SP=111 Cap=193m]
◄IG Design (IGR)► guides FY-Mar rev down 10% (in line) but adj pretax $25.9m ($9.2m), ahead of market expectations. [SP=122.4 Cap=121m]
◄James Cropper (CRPR)► guides FY-Mar rev in line and slightly ahead of its expectations. [SP=270 Cap=26m]
In line: RGBP
Card Factory?
I would really love your thoughts on Eenergy (LON:EAAS) Results out today. They look good to me in a sector that seems to be well placed for continued growth.
Simon Thompson re-stated his 'bargain buy' case for Eenergy (LON:EAAS) today in Investors Chronicle - it's behind a paywall unfortunately but it backs up Pauls instinct in the last SCVR 'quick note' that there may be more to this than meets the eye: 'initial inkling is that there might be an interesting punt here? So it's worth a closer look I suspect.'
There is something interesting happening, its positive and worth noting.
In the last month the FTSE100 has picked up, at a time the S&P 500 has given back prior gains. At the end of March the S&P was up 10% for the year...and the FTSE 100 languishing at 2.8%. Since then, the S&P has lost 2.6% whilst the FTSE100 has gained a similar amount. Of course the S&P500 remains ahead YTD with a gain of 7% versus just over 5% for the FTSE.... The midcap and small cap indices are also picking up but lagging. Aim is worst.
Within the FTSE 100 it is clear that Banks, Resources (incl Oil) and cyclical value sectors are improving. Not those that are deemed interest rate sensitive. 12 months ago it was very popular to believe a recession is imminent and rates way too high. There may well be scope to cut...more in Europe than the US but nothing like expected. The economy was weaker in Europe suffering from a stunted recovery in China and the war in Ukraine. Recent data is far from universally positive but ISM manufacturing data is improving. Chinese reported GDP was higher than forecast... which seemed to serve as the catalyst for better FTSE 100 performance.
Its one month so lets not get too excited... what is clear is a broad improvement in economic data has resulted in better UK index performance. We rely on the Fed to thread the needle policy wise and therefore pray for CPI data that plays ball. Sadly Im not sure these prayers will be answered since the base effects are against us later this year. Never the less the idea that the UK could continue to decouple from the US but positively is not dead and buried.
It's a bumpy road ahead for sure... but the last month passed smoothly, Im hoping this can continue.
Good luck all.
On this theme I wonder if anyone with an analytical eye is able to track the TUs, measuring the number of companies reporting below, meeting or ahead of market expectations from say the beginning of April.
Check out Factset.US companies and research entities usually report this kind of data quarterly.I haven't searched for UK ones as there aren't so many eyes on the indicies here but i'd be surprised if there might not be some free data floating somewhere around google.
EY tracks UK profit warnings on a quarterly basis here: https://www.ey.com/en_uk/strat...
Eenergy (LON:EAAS) - "Balance sheet transformed, pipeline building" (link to research note here: https://www.equitydevelopment....)
eEnergy’s FY23 results are in line with expectations, having been well flagged in the March update. Recent months have seen the balance sheet transformed by the disposal of Energy Management and growth capacity materially enhanced by a £40m project funding facility with NatWest.
H1’24 results are likely to be softer than expected but last week’s c. £5.2m contract win with Spire Healthcare – one of the Group’s largest to date – gives us confidence in pipeline conversion and a meaningful step-up in revenue and profitability from H2.
eEnergy is now well capitalised, with an excellent track record of growth (three-year CAGR of 58% within Energy Services). We expect this to continue, driven by an ambitious management team with a focused strategy to capitalise on a highly attractive market with significant scale.
Our Fair Value estimate of 13p per share represents an EV/EBITDA rating of c.8.5x our FY26 forecast. This is in line with the current FY1 EV/EBITDA rating of the peer group. Note that our forecasts do not include the potential benefit of deferred consideration from the EM disposal, which management estimates at between £8m and £10m over the next two years.
Hargreaves Lansdown (LON:HL.) - trading update reports good momentum in the business. All measures appear positive except a very slight reduction in retention rates. Record AUM of nearly £150bn and revenue up 6% despite lower net interest margin. Higher trading volumes evident and more overseas trading going on.
As an investor with holdings in HL. and also being a client of theirs, I've noticed that their fees appear relatively high compared to other portfolios I manage. Additionally, I haven't seen substantial differentiation in their services to justify these costs. In fact, over time, I've observed a reduction in features on my dashboard rather than meaningful additions. This raises concerns for me regarding the potential for long-term growth in my investment with them. They flag service as being good but that is not what I have experienced over the years - granted that may have changed recently, and time will tell.
Hargreaves Lansdown (LON:HL.)
No mention of the court case.
https://www.reuters.com/busine...
The amount claimed is material and its costs have been funded.
Would have liked a 'nothing to see here' or at least a 'we are aware and it is under review'
As a customer of Hargreaves Lansdown (LON:HL.) I don't have an issue with their service - and in fact they get a lot of flak for high costs, which to be honest really relate to their costs associated with unit-trusts. Holding ETF's, Inv Trusts or direct share holdings in a SIPP and/or an ISA are not too costly - whilst you might be able to save £5 per trade elsewhere I am sure you'll pay for it in the spread. Their Active Savings seems fairly competitive with some good rates.
I am however, quite worried by the overhanging outfall related to Woodford and also see that there is a large number of shorts on the stock. Do others know something we don't.
I really do hope they can recover some of their previous shine and wish holders well, but the risks around the above have caused me to sell out today following the small rise on the SP.
I feel there are so many other great brokers and/or investment houses on equally bombed out valuations that don't have the same risks hanging over them that I feel they are probably more up my street. Graham has highlighted many her win the past few weeks.
Card Factory (LON:CARD) results look very good.
Revenue up 10%
Profit before Tax up 25%
Even online was up a massive 0.4%, ok, maybe gloss over this one.
But probably more importantly, the dividends are reinstated at a not to shabby 4.5%, based on last night closing price.
One for the experts?
Thanks to the people that recommended this share on the scvr reports and comments - very happy :)
I was slightly more impressed by the 2nd-half on-line growth which appears to be reflecting their focus/investment and I would hope offers an area of sizeable growth moving forward.
"Encouraging H2 performance with +11.4% LFL sales growth, reflecting the impact of ongoing investment in online capability, platform performance and customer experience. This positive traction has continued into FY25 resulting in five consecutive months of sales growth."
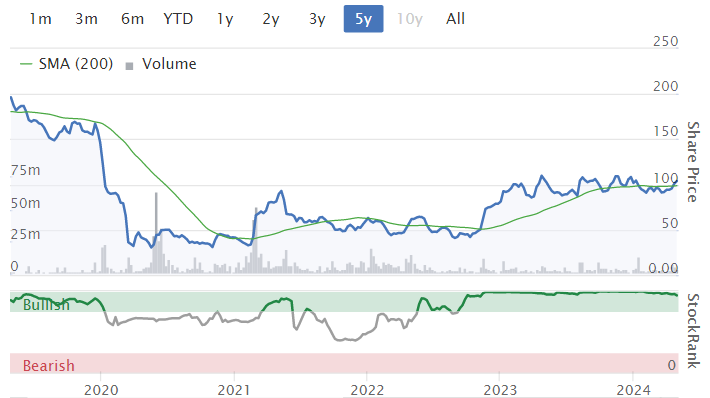
Card Factory (LON:CARD) say that ”expectations for FY25 remain unchanged” but none of the retail friendly brokers on research tree cover the company. I’ve written to the company on this point before and was ignored. If every holder on here asked, it would be interesting to see if we could make a difference.
At the TU expectations for 2024 were up to 62m so they are very slightly ahead of top end at 62.1m adj PBT.
Debt down a lot as well
CARD will be on Edison site soon