Small Cap Value Report (Tue 30 July 2024) - SOM, BAG, FOXT, GMR, FTC Movers: STJ, DGE

Good morning, it's Paul & Graham here as usual!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
I'll try to get SOM up before 8am (just about, it was up at 07:59)!
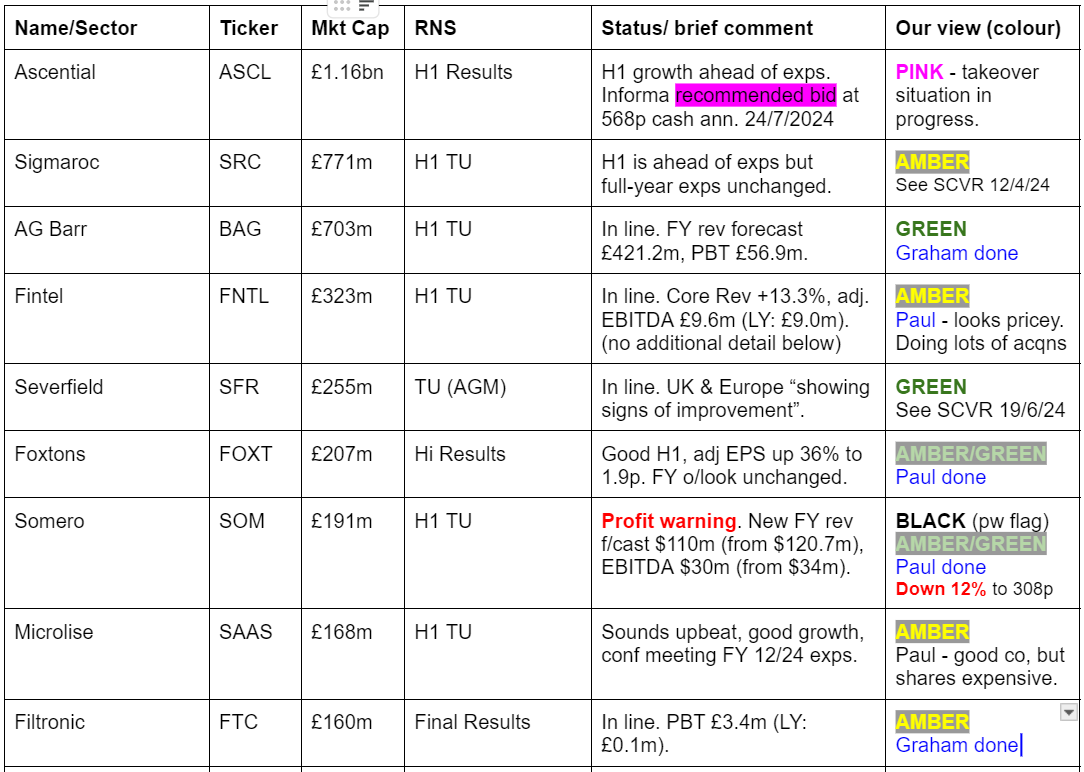
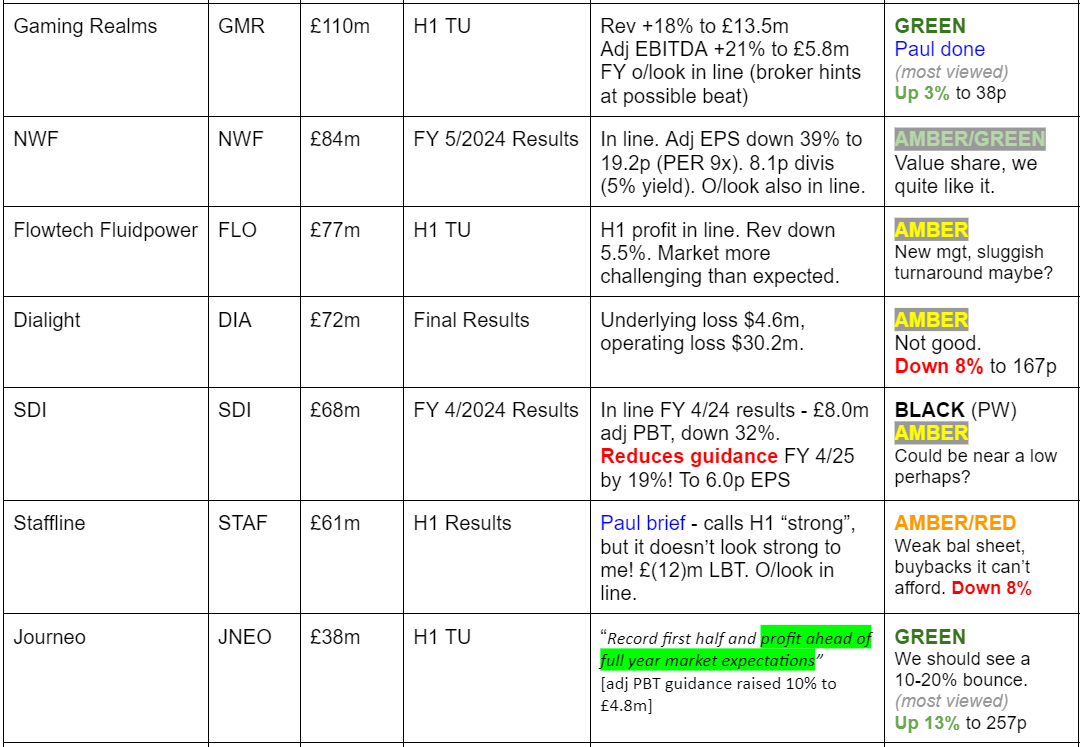
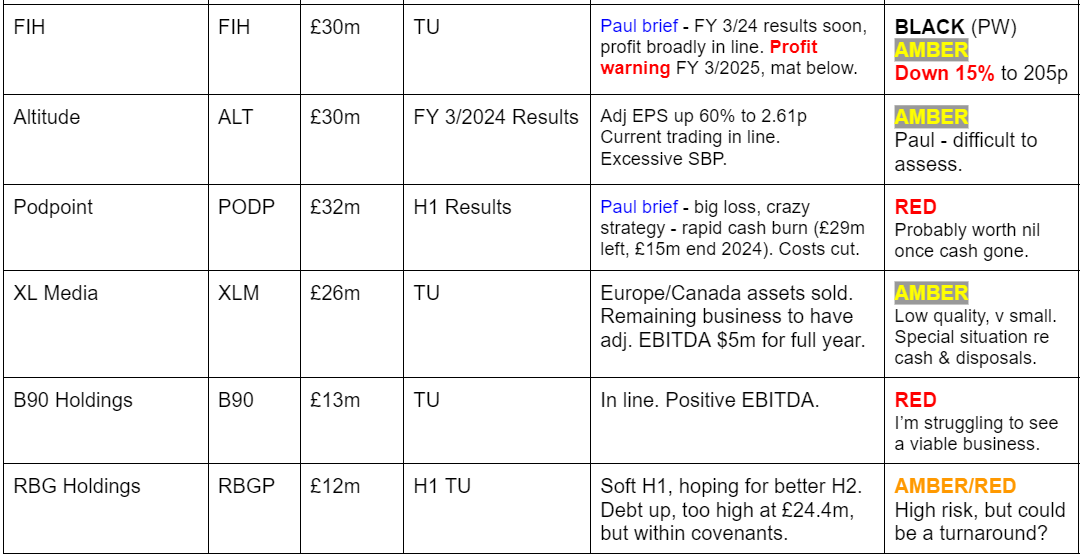
Other mid-morning movers (with news)
St James's Place (LON:STJ) - up 20% to 670p (£3.67bn) - H1 Results - Paul - No view.
A very positive market reaction to this mid cap fund manager’s H1 results and strategy update. This share is up 60% just in the last 3-4 months, but the StockReport still showed a low forward PER of 7.8x as of last night.
It reports a net funds inflow in H1, and a positive market return on funds invested. Total AuM a record £182bn. Plans to cut costs.
Bullish sounding outlook -
“While near-term profit growth will reflect the structural impact of transitioning to our new simpler and more comparable charging structure as announced last October, we expect to see the Underlying cash result accelerate in 2027 and beyond, doubling between 2023 and 2030. Importantly, much of this rapid growth is highly predictable because of those changes that we are making to our charges.”
Paul’s view - no colour, as I haven’t properly researched it, but there are certainly interesting elements here, and it could be worth further research. We’ve been anticipating a recovery in this sector, and it now seems to be happening, selectively.
Diageo (LON:DGE) - down 8% to 2,339p (£52bn) - FY 6/2024 Results - Paul - No view.
Amazingly quick reporting of FY 6/2024 preliminary numbers. Why do the tiny companies we cover take months to report, when this drinks giant can do it in 30 days?! DGE shares have been in a nasty downtrend for 2 1/2 years being roughly back down to the pandemic lows.
Figures today have clearly disappointed, as it’s down 8%. Debt looks high at 3.0x, so it’s surprising to see it doing share buybacks (fuelled by debt). The StockReport shows earnings forecasts in almost continuous decline, a fwd PER of 17x, lots of debt, and an unremarkable 3.2% dividend yield.
Paul’s view - it still looks overvalued to me, despite the big drop in share price. Where’s the profit growth? There doesn’t seem to be any. Negative NTAV, and a huge pile of debt c.$20bn, definitely not my cup of tea! Although the business clearly has some attractions, as a portfolio of quality brands, with a high operating profit margin. Is that enough though? Markets want growth, and this business is effectively shrinking, when you take into account inflation - flat revenues over 6 years is going backwards significantly in real terms.
Summaries
Somero Enterprises (LON:SOM) - down 14% to 305p (08:07) £166m - Trading Update - Paul - BLACK (profit warning flag). AMBER/GREEN (on fundamentals)
Various factors have caused H1 to be soft, but a recovery is expected in H2. Disappointing, not a disaster, is my conclusion. With a strong balance sheet, and a modest PER on lowered forecasts, I think the value is now looking quite attractive. Probably not a time to be panic selling in my view, but that's your call.
A G Barr (LON:BAG) - up 0.6% to 634p (£710m) - Trading Statement - Graham - GREEN
An in-line H1 update from this soft drinks group. There is positive momentum with revenue growth and solid profit margins combining to give forecast EPS growth of c. 13% this year. The soft drinks industry faces some macro challenges but I remain a fan of BAG. PER is around 16x. Cash c. £60m forecast.
Foxtons (LON:FOXT) - up 1% to 68p (£206m) - H1 Results - Paul - AMBER/GREEN
Good H1 results, with profit up strongly. Reiterates full year forecasts, but broker suggests it could beat rather than just meet. Adequate balance sheet. We were green in April 2024, but it's risen c.30% since then. I still like the share, but price maybe up with events for now, so moderating slightly to AMBER/GREEN.
Gaming Realms (LON:GMR) - up 7% to 40p (£117m) - H1 Trading Update - Paul - GREEN
Continuing strong organic growth from its core Slingo game. Broker forecast unchanged, but looks set up to beat rather than just meet. I find the valuation still appealingly good value, with considerable further upside possible. It's net cash too. Lots to like here, one of my favourite GARP shares, looks like I forgot to include it in my top 20 share ideas this year.
Filtronic (LON:FTC) - down 1% to 72p (£157m) - Final Results - Graham - AMBER
Excellent results from this component manufacturer, as expected, and brokers have left their FY May 2025 forecasts unchanged, predicting continued improvements in revenues and profitability. I applaud shareholders who have held this through its bull run, but personally I would see it as fully valued here.
Paul’s Section:
Gaming Realms (LON:GMR)
Up 7% to 40p (£117m) - H1 Trading Update - Paul - GREEN
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile-focused gaming content, announces a pre-close trading update for the half-year ending 30 June 2024 ("H1 2024" or "the Period").
Decent growth here -
“H1 2024 Revenue and EBITDA growth of 18% and 21% respectively, driven by growth in content licensing and market expansion”
H1 revenue £13.5m
Adj EBITDA £5.8m (*EBITDA before share based payments)
It doesn’t mention what actual profit is (PBT)! Probably because adj PBT is only about half the misleading EBITDA number.
Outlook - sounds encouraging -
“The strong momentum experienced during this period provides the Board with the belief that the Company is on track to meet its full-year targets, as it continues to expand into new markets and launch new games with existing partners.”
What are the targets?
Canaccord helps us out with a note, leaving forecasts unchanged, but describing them as “well underpinned”, which implies to me the most likely move could be a beat against forecasts, it’s always nice to hold shares in that position.
Canaccord has 2.3p estimate for FY 12/2024, rising to 3.0p next year.
What PER to apply? If unprompted, looking at these figures without knowing the company, I would say a PER of 20-30x would be justified. That takes me to a valuation of 46p - 90p, using 2024 & 2025 forecasts within my 20-30 PER range. The actual share price is 40p, suggesting to me that this share could have attractive upside.
Paul’s opinion - I’ve been a bull on this share for a while, due to its tendency to report decent organic growth, at an attractively cheap valuation. That is coming from a core product (Slingo) that customers like, and keep buying more of it, alongside plenty of new customers, globally. So a very simple, and attractive business model. I can’t think of any negatives, leave a comment if I’ve overlooked any concerns.
Cash is piling up nicely too, so I think we need divis, or a credible use for the cash. Bolt on acquisitions might make sense, if management are experienced in successful acquisitions in their previous lives?
It has to be another GREEN from me, as before, multiple times.
Foxtons (LON:FOXT)
Up 1% to 68p (£206m) - H1 Results - Paul - AMBER/GREEN
Foxtons Group plc (LSE:FOXT), London's leading estate agency…
Just a very quick look at H1 results. I’m impressed, there’s good progress being made here, with both adj operating profit and PBT up 24%. Adj EPS is up 36% to 1.9p.
The strategy here has been to grow the less cyclical lettings income, with an impressive 70% of revenue now non-cyclical & recurring streams.
I like the turnaround strategy here from newish (2 years) CEO Guy Gittins, which seems a no-nonsense back to basics approach.
Outlook comments reassure -
“Through continued market outperformance, the Group's expectations for the full year remain unchanged and the Group is on-track to deliver its medium-term target of £25m to £30m adjusted operating profit.”
"Momentum can be felt across every aspect of the business and I am very excited about the second half and beyond as we work hard to deliver excellent results for the property owners of London and our shareholders."
Broker update - an interesting note from Singers is most welcome, thank you.
It has an unchanged 4.2p forecast for FY 12/2024, but makes it clear in the commentary that this could be upgraded. That’s a very good increase on actuals of 3.0p in 2022, and 2.8p in 2023.
If I assume that it does 4.5p in 2024, then the PER is c.15x, which looks about right to me.
Although more acquisitions of lettings books could drive inorganic growth further, so I don’t see forecasts as either a ceiling, nor wishful thinking.
Balance sheet - still has some odd, legacy items on there. Maybe Gittins could have a clean up of the balance sheet? In most respects though, it looks an OK balance sheet. Modest net debt is easily supported by earnings & cashflows. Lease liabilities are obviously quite large, from its network of physical offices, but as long as they’re all earning their keep, then that shouldn’t be an issue.
Overall then, the balance sheet is adequate, not strong.
Paul’s view - keeping this brief, Graham was GREEN last time on 18/4/2024 at 53p. We’re now 28% higher at 68p, and with the valuation now looking more up with events, rather than outright cheap, I’m going to stay positive, but moderate a little to AMBER/GREEN due to the big share price rise. Things like this often continue rising once they have momentum though, and with macro now moving in the right direction, I think staying positive seems the right call.
Somero Enterprises (LON:SOM)
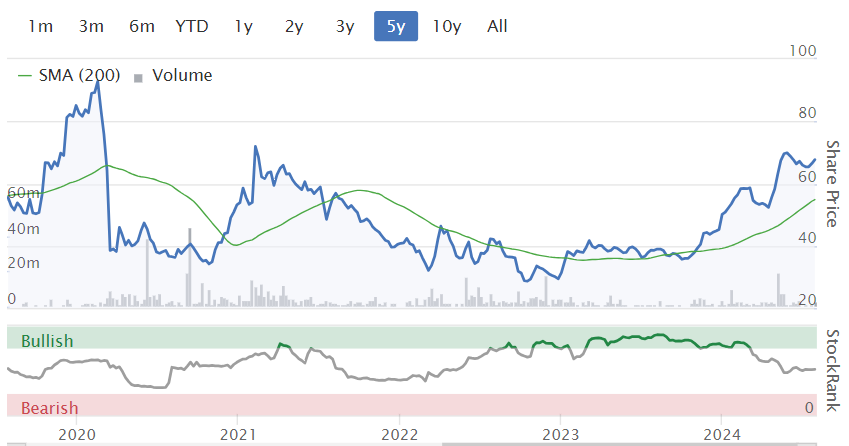
Down 14% to 305p (08:07) £166m - Trading Update - Paul - AMBER/GREEN
Somero is a vendor & servicer of laser-guided concrete laying equipment, mainly in the US. It’s been listed on AIM for many years, and has traditionally been cash generative & generous with divis.
H1 this year has been tough, resulting in a profit warning today -
“trading in North America continues to be impeded by project start delays and pauses caused by elevated interest rates, labor shortages and concrete rationing, as previously reported in the 20 June 2023 announcement. This has been coupled with significant inclement weather in H1 2024. As a result, H1 2024 trading in North America is expected to end below the comparable H1 2023 period.”
Improvement in H2 is expected -
“The Company anticipates an improvement in H2 2024 over H1 2024 driven by a combination of new product revenue growth, including the launch of a third new machine, and an expectation of improved weather conditions.”
Outlook -
"Despite the impact of persistent challenges and poor weather conditions on trading in the first half, the non-residential construction market remains fundamentally sound. Importantly, the long-term growth drivers remain intact and we are working hard to expand our product offering and build our presence internationally to capitalize. As those factors outside our control abate, we would expect performance to improve. In the meantime, Somero is built to withstand challenging conditions. We have a solid track record of adapting to changing conditions and then emerging strongly."
Cost cutting - workforce is being reduced by 15%, alongside other “strict cost controls”, to “partly offset” the impact on profit.
Revised guidance - very clear here -
“In consideration of the aforementioned factors, the Company now expects FY 2024 revenues of approximately US$ 110.0m (compared to the previous market consensus estimate of US$ 120.7m), EBITDA of approximately US$ 30.0m (compared to the previous market consensus estimate of US$ 34.0m), and year-end cash of approximately US$ 27.0m (compared to the previous market consensus estimate of US$ 31.7m). “
Paul’s opinion - I’ll add more detail to this section in a little while, once I’ve read the broker update. Initial reaction is that this is disappointing, but not a disaster. However, with the trajectory of earnings now in a downward trend, the share price is likely to take a significant hit today (written just before 8am). Assume the brace position, holders, if you're not trying to sell on the opening bell (probably futile).
EDIT: Many thanks to Cavendish for updated numbers. New vs old forecasts are shown for FY 12/2024. What strikes me, is that a 9% drop in revenue has only caused a 13% fall in adj PBT and EPS - I would normally expect to see a much larger, operationally geared impact on profit. So clearly the rapid cost-cutting response has softened the blow, albeit at the expense of employees - cutting 15% of the workforce is quite a savage thing to do, and is bound to have an effect on morale, and maybe on operations as demand returns?
On valuation, the new FY 12/2024 forecast is 37.6 US cents, so 29.2p. The share price is currently (08:14) 300/310p bid/offer, so taking the mid-price that's now a PER of only 10.4x - given that Somero is also comfortable for cash, this looks a modest valuation. So my conclusion is that the shares now look quite attractively cheap, and I'd be surprised if there's much further downside below 305p. Given that the factors behind the profit warning look temporary, I'd be inclined to look at this favourably as a potential purchase if it continues falling below 300p. I think I'll go up to AMBER/GREEN, based on the now quite attractive valuation. The factors which caused this profit warning could reverse in future, leading to growing demand in H2 and maybe in 2025. If that doesn't happen, then I would be worried, as that could indicate SOM might be suffering competitive pressures, something we've questioned here before.
Graham's Section:
A G Barr (LON:BAG)
Up 0.6% to 634p (£710m) - Trading Statement - Graham - GREEN
A.G. BARR p.l.c., the branded multi-beverage business with a portfolio of market-leading UK brands, today announces a trading update for the 26 weeks ended 27 July 2024.
The owner of IRN-BRU and other soft drinks and brands has issued an update for H1.
H1 revenue growth is 5% to c. £221m, within which soft drinks revenue growth is 7%.
The Boost acquisition is being integrated as planned, with “margin realignment” underway as production is insourced (Boost has negatively affected BAG’s margins in the short-term).
Each of the main brands seems to be doing fine. Rubicon is the stand-out performer, growing at double digits, while IRN-BRU is enjoying volume growth and market share gains.
Comment from CEO Euan Sutherland:
"I am pleased to report overall H1 revenue growth of c.5% with Soft Drinks growth of c.7%, against strong prior year comparatives. The strategic margin rebuild programmes are on plan, guidance on revenue and margin remains unchanged, and we are on track to meet FY expectations...
Our four power brands - IRN-BRU, Rubicon, Boost and FUNKIN - have clear paths to long term growth…
We have a clear and focussed UK based growth strategy with simple KPIs of Net Revenue, Operating Margin and ROCE."
Outlook: in line. The company is “committed to improving our profit margins”, with positive earnings momentum for H2 and beyond.
Estimates: Shore Capital have left their forecasts unchanged, expecting FY Jan 2025 PBT of £57m and EPS of 38.1p.
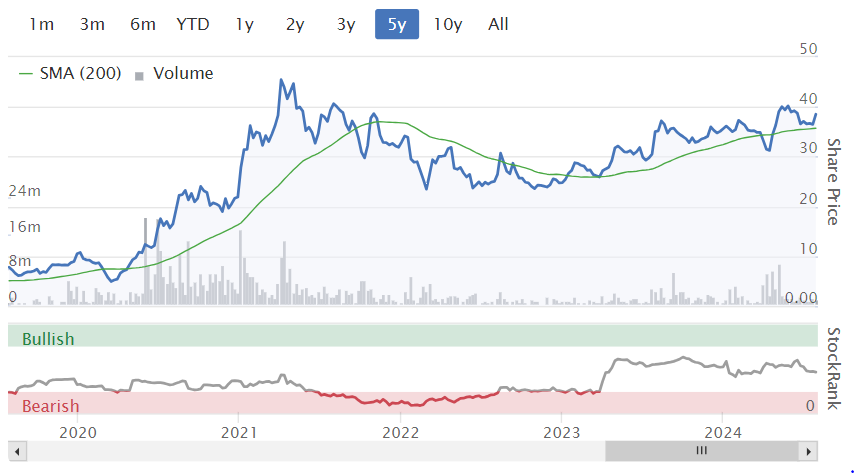
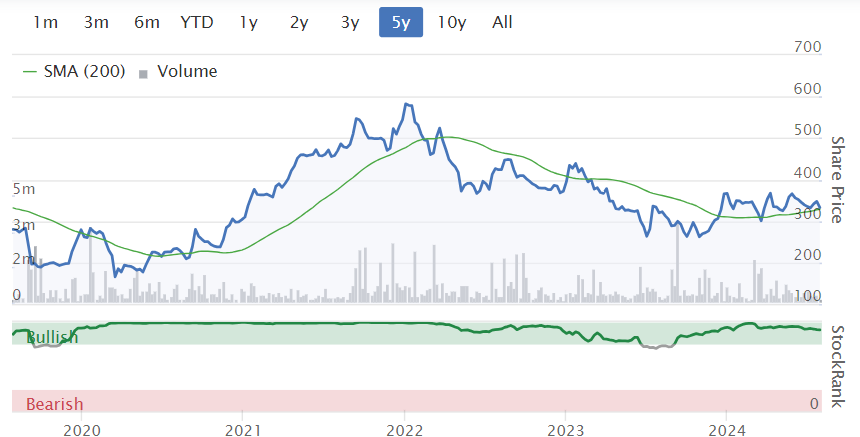
Graham’s view: I’m pleased to see that the BAG share price has picked up some momentum:

This is a stock I’ve been stubbornly bullish on due to its high cash balance, well-known brands, and (hopefully) an ability to rebuild profit margins as economic conditions improve.
It hasn’t been plain sailing and it’s not going to be, either. A deposit return scheme seems likely to be introduced at some point, although it has been delayed for now. So perhaps BAG can continue to trade without worrying about that for a few more years.
At this stage, I’m not sure if I will want to leave this on my best ideas list for 2025, as the introduction of new management here has made me a little nervous.
Fortunately, profits are still moving in the right direction, and this means that the PER remains at a level which I would see as attractive - and this is before making any adjustment for the company’s strong balance sheet and cash position. So for now I’m going to leave my positive stance on this one unchanged.

Filtronic (LON:FTC)
Down 1% to 72p (£157m) - Final Results - Graham - AMBER
Filtronic plc (AIM: FTC), the designer and manufacturer of products for the aerospace, defence, space and telecommunications infrastructure markets, announces its full year results for the 12 months ended 31 May 2024.
We have a very impressive full-year results table, with significant improvements in every metric.
Revenues are up 56%, operating profit has jumped from around breakeven to a more meaningful figure (£3.4m), and the company’s cash balance has expanded:

For context, here is the share price performance over the past year, a multi-bagging performance:

A review of the news:
5-year strategic partnership with SpaceX. In the new financial year, a follow-on contract with SpaceX has been signed with $9m value.
£3.2m contract from European Space Agency, £4.5m from BAE Maritime Services, £2m from QinetiQ.
King’s Award for Enterprise in Innovation.
Excerpt from the Chairman comment:
The success in FY2024 has given us a very strong basis for our business as we look ahead into FY2025. We continue to prove that we have the technology, products and skills to compete internationally with the best.
Contract wins in FY2024 require us to expand the Group's engineering and manufacturing operations into our growing sales orderbook. At the same time as we develop our electronic communications products and technology in the low earth orbit space sector, we have ambitions to do more in the defence, aerospace and security sectors…
Whilst we wait to see what the new government's UK industrial strategy will look like, we remain confident that in the critical technology areas, including sovereign semiconductor packaging capability, we have a meaningful role to play.
Dividend: an interesting choice to retain cash within the business instead of paying a dividend “after continued dialogue with investors”. Seems reasonable, as hopefully this is just the beginning of the good results for Filtronic, and the cash will be better spent funding growth.
Outlook:
The demand drivers for our business, as I have outlined above, remain strong and the markets we serve are robust. We have increasing confidence in our ability to deliver further growth in the year ahead, but we recognise the need to work fast and not be complacent. We will be matching our resources with the enlarged business that we are now operating, investing in key areas including exceptional and experienced engineering and manufacturing talent, developing opportunities with those in the early stages of their career and leveraging strong commercial relationship builders to deliver greater customer focus and support…
The new CEO expands on the outlook, emphasising the opportunity with SpaceX, a new manufacturing facility in Sedgefield, and the overall scaling up of the business.
Graham’s view
Like Paul, I’m going to have to stick with an AMBER stance on this one, as I don’t have the industry expertise to express a view on whether Filtronic can follow through with its growth ambitions.
Quantitatively, there doesn’t seem to be much value on offer at this market cap: the valuation dwarves the revenue figure, profits and cash.

The ValueRank is only 4:

In a value report, it’s difficult to be bullish in these circumstances.
Looking ahead, brokers are estimating full-year revenues of £36m for FY May 2025, converting to adj. PBT of £6.4m. It’s certainly a huge improvement compared to where the company was before.
I will respect the momentum here and stick to AMBER, as it’s dangerous to be bearish on well-funded, growing, profitable companies. But personally I don’t understand the investment case here, and the valuation would make me nervous.
(Paul adds: I've heard a couple of fund managers talk about Filtronic recently, and I think the bull case rests on a belief that the upside could be considerably larger than the current broker forecasts. I'm with you though Graham, as that's not something I can forecast, it would be pure guesswork for me to get involved now. Well done to the readers here who spotted this opportunity & left comments about it early on in the growth phase).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

95 comments
NWF (LON:NWF) FY24 management presentation video & podcast
A quieter year in line with expectations with some headwinds after a bumper 2023 with abnormal margins.
no scvp for weds yet or do i have pc problems?
SCVR - Perhaps it's a case this morning of you don't know what you're missing until it ain't there no more. AND It's absence might be connected to the tone of some posts later yesterday? A silent strike perhaps and also rather understandable
olympic games triathlon always a good excuse to down tools - viva la france - oh doh
Off topic but given we have been discussing the likes of Diageo (LON:DGE) I thought I would put in a shout for another large cap announcing its final results today - Games Workshop (LON:GAW. Obviously much was already flagged in the trading update. But still, what a classy operator it is. Revenues up 11%, gross margin approaching 70%, EBIT margin over 40% and net income margin over 30%. No debt to speak of, which will not impress efficient balance sheet devotees but makes for a derisked ownership experience. In fact management has temporarily depressed the dividend to build a larger cash buffer, commensurate with the daily working capital needs of being a larger business. Still you have an expected lumpy yield north of 4%. And a forward P/E of just over 20x. With its unique IP, global revenues, LT manager mindset, wonderful margins I have no doubts in my mind that this is one of the finest companies listed on the FTSE. Even following its strong bounce back from what were unwarranted lows the share price surely massively underprices the value on offer here. A core ‘coffee can’ hold for me. Actually largest holding. I remain baffled how apart from Sanford DeLand this gets so little love from institutions. I can only think that it is the company’s refusal to play PR games and some snobbishness towards the hobby and its customers. Their loss. The FTSE is not exactly over flowing with quality businesses
Hi Phill - Think your comments here illustrate the problems we investors face, It doest matter how good the company and how much you love it - if 'The Market' doesn't agree it wont move up. In similar vein - I would not go anywhere near St.James but look at the Mkt reaction today.
Thanks bohenie! The only solace I can offer is the old Benjamin Graham quote ‘In the short run the market is a voting machine but in the long run, it is a weighing machine’. I mean I don’t think it’s wrong. For example, in the LT no company that doesn’t cover its cost of capital (ahem Vodafone (LON:VOD, as an example, thinking of you) can produce a great return. So it really comes down to your time horizon and investing style. I would say that many investors both retail and instiutional, and by implication the market (the ultimate collection of investors) are ST in nature. They are essentially special situation investors. Constantly churning their portfolios and jumping on the next opportunity. And why not. It’s fun. But there is no ‘hiding’ in the LT. Dogs (I.e. most companies) will not become Swans. Although Swans can become Dogs. I guess if you feel you have a real lasting Swan and a patient temperament, fear not, your / its day will come…
If a drop in sales was a Diageo specific issue, then I would be worried. This looks more like a market challenge with global consumers tightening their belts .. have a look at Diageo competitors ,.. Pernod, Campari, Remi, Brown etc ... in terms of share price performance,, nearly all have performed worse. I personally think with the international spread, Diageo is a preferred play. For example, Diageo has one of the largest market share in India which is a difficult market to crack.
Games Workshop (LON:GAW) re institutional holders I know that Schroder UK Mid Cap Fund (LON:SCP) is a top 10 shareholder & has been for some years
I hold both: Games as it’s been a fabulous buy & hold for me since their first ‘Ahead of expectations’ back in 2015 and SCP as a lightly geared play on mid caps (on a reasonable discount)
Wondering if anyone had any thoughts on the Investor Meet presentation by Ondo Insurtech Plc a few hours ago.
Seems to me the Directors seem as mystified about the current share price as the questioner does.
Somero Enterprises (LON:SOM) I have held since 2016. Would I have been better in say the S&P probably but I like this company, though I think maybe I should have cut my losses .
I just want to comment on the job cuts that Paul remarks on:
“is bound to have an effect on morale, and maybe on operations as demand returns?”
This must be horrid for the employees concerned but I am not sure whether this will affect morale particularity. The impression I get is that being laid off is sort of an “occupational hazard” in the States, though that may sound callus and is the trade off for getting re-hired more quickly than you would in the UK or France and for a high standard of living (possibly depending on your definition of that).
US GDP per head $81,695
UK GDP per head $46,866.
S&P 12.8% CAGR
NASDAQ 17% CAGR
FTSE All Share 6.1% CAGR
Hope that this is not too off topic.
Regards
Michael.
Do we have any thoughts on Altitude (LON:ALT) today?
Hi Mdfraser11,
Yes I had a quick look at Altitude (LON:ALT) today, and added a very brief comment above.
Figures look good, with adj EPS up 60% to 2.61p, giving a PER of c.15x.
The problem I have with ALT, is trying to assess what its business model is, and what potential it has? The core business has been little more than ticking along, for many years, and doesn't seem to have delivered the big scale up, platform type stuff that we were promised years ago.
It seems to have branched out into products for Universities now, which seems to be going well, but doesn't strike me as exciting from an investor point of view.
Balance sheet looks OK I think, I was pleasantly surprised.
SBP - share based payments - are clearly excessive, but I suppose it's an American company, so mgt are delving deep into the till, thinking it's somehow OK. That upsets me.
Let us know your view!
Regards, Paul.
Just a quick thank you from me and no doubt everyone else on here who keenly follow you on a daily basis. Keep up the great work!
DGE Just wanted to add my thoughts about buybacks. Buybacks are often hailed as smart moves, especially across the pond. I think a great deal more scepticism and critical assessment is required.
DGE made the classic buyback mistake of buying under good business conditions at high valuations. The business falters, and the buybacks to nothing to prop up the price. You end up with a situation where you've taken on a lot of debt, with nothing to show for it. Even if you think that it makes sense to do a buyback aat what might be the bottom of the cycle, you don't have any money to do it anyway.
Boeing Co (NYQ:BA) is in that situation, I believe. Loads of buybacks, business takes a tumble, debt levels become perilous, and now they're after government bailout. BA is likely seen as strategic, so they'll probably get it, with too little cost to management and shareholders.
Ref Diageo (LON:DGE, Mark, time will tell if its buybacks were all about Director bonuses, certainly when buyingback at high valuations this must be the case but I'm not certain that shareholders will not benefit at low valuations. I would always prefer a special dividend at my time of life though.
Re. Diageo (LON:DGE) . I really think a lot of this comes down to your time horizon, investment style and risk tolerance. The share buybacks were in no doubt misguided with the benefit of hindsight. Executed above intrinsic value, which as Buffet says is the crucial test of whether they are value added or not. But I would perversely argue for a glass half full view. At a time of geopolitical instability, weak consumer sentiment, high interest rates (at least in recent memory) you have a company that is still able to generate meaningful positive cash flow, sufficient to service said debts, pay a reasonable dividend, not scrimp on marketing, not skimp on capex, etc. Why is that? Because they do have a portfolio of beloved brands. They do have a true global footprint with EM exposure. And they have sufficiently juicy margins which gives them a strong moat to ride out the rough times. I would humbly argue that the shock of Covid followed by a temporary boost from revenge spending followed by a de facto soft consumer environment (and the dreadful economic situation in China) mean that it’s just not possible to come to a view that Diageo is in some way ‘finished’. Famous last words but I would bet today’s valuation and super negative sentiment is likely to prove the nadir. And I will go further and say that I suspect there is a certain gentleman in Omaha looking at his vast cash pile and strongly mooting a once in a lifetime opportunity to get the world’s finest collection of spirits brands / Guinness on the cheap. For someone who thinks in decades and not quarters or even a few years it must be very tempting. I for one am very happy to have this as a core holding in my SIPP on the same basis
Hi Phil,
Interesting perspective on DGE, thanks.
The trouble is, it's not cheap! Just because the shares have fallen a lot, you've got a portfolio of brands that is now priced on a forward PER of about 17x, with about $20bn of debt - that's 5 years' worth of PAT!
There's no growth, yet inflation is eroding the value of money. So static revenue & profit is actually going backwards, quite significantly over the last 2 years.
3% yield is quite weak for a mature business.
Above all, have you tried Aldi or Lidl branded gin, etc.? Maybe consumers are realising that the branded stuff isn't actually better, it's just clever advertising that makes you imagine it's better.
I think there are much better long-term shareholdings than DGE, but time will tell!
Interesting debate, I've taken on board your views.
Best wishes, Paul.
Paul,
Really appreciate you taking the time to respond! Just want to thank you (and the rest of the team) for the amazing work that you do. Love the podcast btw. I know of no other site like this where there is such in-depth thoughtful content. And that goes for the wider community too.
I hear what you (and others) are saying. I just say again that a few years is not long enough to come to a definitive conclusion. Also I don’t believe that human nature has been conquered I.e. people want aspirational goods. Plus there is a big wide world out there. I happened to find myself passing through Dubai Duty free a month ago and was amazed at how fast the double packs of Johnie Walker Black (it has to be said encouraged by some keen promotional pricing) were flying off the shelves. Demand was driven by workers going back to India and I guess who wanted to impress their family and friends with a global brand. Unless we have a Great Depression or WW3 the middle classes are going to keep growing in EM and they will very likely move up the value chain too. Diageo offers a great way to play this trend. And through a basket approach. Unlike say, Burberry (LON:BRBY) you are not betting the bank on one brand or sub-category. They pretty much have it all including non-alcoholic elements like Seedlip, Guinness 0 and Tanqueray 0. They are the LVMH of booze. Many of these brands have survived WW2, they survived the stagflation of the 70s, etc, a longevity not be sniffed at. But you’re right. There are no guarantees. Time will tell if this is enough to return them to growth.
Thanks again and best wishes,
Phil
H & T (LON:HAT) just to flag the H1 results webinar 20.8.24, 12 noon. Register here.
I know Graham reviewed the TU for H1 given last week. IMHO they tend to understate their achievements, yes they're in line but that's for the EPS forecast to grow +17.5% to 57.2p. The pledge book +4% at £105m although growth is due to Maxcroft but organic growth expected H2, retail & fx doing what they expect and scrap margins improving. It's incredibly cheap with the economic backdrop on a PE of just 6.5 with a divi yield 5%.
Not sure about that - H & T (LON:HAT) overstated guidance last year and then were then forced to warn on profits (which was a bit silly as they performed strongly and didn't need to over promise in the first place). Also, organic growth was pretty flat in H1 this year, so they'll need growth to pick-up to meet FY guidance - not saying they won't, but something to keep an eye on. Agree that it looks very cheap.
Oh Greggs (LON:GRG) , why do you mock me so? This is one of my definite ones that got away.
Share price up 4%. Sales up 14% (LFL +7%), ordinary interim divvies up a honking 19%. PBT ex. exceptionals up 16%. Stocko Quality score 93, ROCE 18%, and operating cashflows have been compounding at a monsterous 18%pa.
I hate you! (tongue in cheek, of course).
Share price ain't cheap at a PE of 20, but crikey, what a quality business.
and there sausage rolls are not to bad either :)
When I was doing my Masters many many moons ago, I used to pop into Greggs tp get their sliced bread, which I then froze for sarnies. It was nice bread.
Back in 2016 I stopped off at Wirral services off the motorway, and bought something to eat at Greggs. There was quite a queue. It seemed to be the most popular eatery there. I liked their food, too. Just nice sarnies at a reasonable price.
Yeah we get it. Greggs is cheap fuel. But are the shares cheap fuel at £30?
Hi Paul, do you think that there is more to the Somero report than meets the eye? I think that they are being very short sighted in laying off experienced staff ahead of an expected upturn in profits.
Somero Enterprises (LON:SOM)
I think that they are being very short sighted in laying off experienced staff ahead of an expected upturn in profits.
i would trust them to know when to hire and fire staff better than me or you thats for sure. I suspect ther may be very few key long term employees laid off here - who knows though. Possibly more a reversal of hires the last 2-3 years to deal with uptick in sales that did happen.
Some companies restructure staff every two years just to get rid of the "dead wood".
i could do with being pensioned off for sure
Or those veterans with baggage.
Excellent point. It did occur to me that at times like this it's a good opportunity to get rid of some dead wood. From my own limited experience I have often found that when good staff are let go they disappear and are not reappointed. I like Somero and am reluctant to sell. Wishing I had done so at it's high point and buying back in now. I've never been any good at timing!
What shocked me a while ago, was when a friend who you might judge as "dead wood" because of his age, took early retirement, I asked why he was going. The answer was just the opposite of dead wood: he could see what needed to change, and was leaving because he couldn't see it happening anytime soon.
The dead wood was not him, but the younger guys who managed him, but lacked his experience and insights!
Hi rmillaree
Somero Enterprises (LON:SOM) run a very variable cost structure - they have always been very open about headcount changes in line with growth or falls. But they also pride themselves on training and quality. So I expect that the shorter tenure employees go first but will equally get picked up later as necessary.
The US labour laws are quite flexible here - usually a 2 week notice and not much in the way of redundancy. It’s a much more eat what you kill labour market than the UK and Europe in particular. There are good and bad points to that off.
But the dynamics they have battled with in H1 are genuine - particularly in the cement shortfall and inclement weather which does have a big impact on the start date of projects. So assuming these conditions revert to mean and coupled with a rates reduction environment I can see this as a bit of a low point in Somero Enterprises (LON:SOM) cycle.
What interests me about that is historically it was a more boom / bust cycle but that seems to have smoothed somewhat over the last 10 years and so the balance sheet can stay strong and the flexible cost base means the business can stay very profitable and cash generative even in more difficult times.
Share price has behaved as I expected based on the RNS. A drop to 300p followed by a gradual recovery to the 325p mark. Probably not going to go anywhere though until there are strong signs of a sales pick up so I guess you’ve got to determine whether the dividend on offer compensates for little capital growth in the short term.
Somero Enterprises (LON:SOM)
i think the main issue i have with somero now is i am not fully convinced they are able to grow their marketplace much biger than what it is - possibly anemic growth type situation. Thats probably being a bit harsh on them clearly 2012 and 2022 were pretty exceptional years so the fact they have gone backwards since then is possibly to be expected - as you say if they say they think sales will pickup this is hopefully the lowpoint - but i dont quite see the upside as being as rosy as it was back in the day (pre covid) when these could be picked up for 200p. I am probably a bit bitter that having sold out a couple of years ago for 470p they released an ahead of expectations update the next day and i could buy back in at the same price and never sold out later . So whilsty i think there may be better places for my cash i am not minded to sell now - who knows when things pick up i may even turn positive again - would be nice if one of their new fangled machines took off sales wise - just be careful what websites you click on when you do your research online to see how the "sky strip" is perfoming - looks like she is avaialble for hire at reasonable rates. Perhaps they need to give their products faces like thomas the engine or personas like then mr men and start selling the merchandise on tik tok.
Haha rmillaree - I will clean my web browser after searching then!!
I think you definitely have a point about Somero Enterprises (LON:SOM) market share/growth - they’ve stagnated in last couple of years for sure. Invested for growth but not really grown, though managements expectations of the market medium term seems undiminished. To be fair to them they generally do have a good level of direct engagement with clients so I’d give their views on market size and opportunity some credibility but they do need to start showing it.
Hi fithcolumn,
"Hi Paul, do you think that there is more to the Somero report than meets the eye? I think that they are being very short sighted in laying off experienced staff ahead of an expected upturn in profits."
I have no idea!
Outside investors have absolutely not a clue what is really going on within companies. I've been told this time & again. If you think you understand a company, the reality is you don't know a damn thing, as an outsider! Talk to people who work there, and you'll find out all sorts of dreadful things that have never been disclosed in RNSs!
That's my experience!
P.
PS not related to Somero I should add.
A very good reason why the single most important factor in investing is the quality and integrity of the management.
I hope it's also not related to all sorts of dreadful things going on inside Greggs also Paul, that would put me off my sausage roll
I wonder if Journeo (LON:JNEO) & Tracsis (LON:TRCS) would make sense as a combined entity?
I doubt it will ever happen, but two smallish companies together may have greater leverage or even opportunities in a large transport sector
Growth, value or income shares
Browsing my diary I came across an interesting finding. On 21 February in a Stocko webinar , Ed Croft discussing the investment themes , picked up three shares as an example not as a tip or favourite .
For growth he picked up Journeo 266p at the time, for Value it was Mears at 350 and for an income he picked up IG at 699.
The growth and value picks are more or less the same level but the income share is up 35% since that day.
A small lesson for me is:
Income investing pays better dividend!
IGG I've been a holder since 2018. The share price performance has been quite a drag on me, and only recently has it come good. It has mostly been underperfoming the index during that time, if I exclude divvies. I'm pleased to see it finally gaining some traction.
Its ROCE and operating margins have been high. It is trading on a P/FCF of 9, which is pretty cheap. I guess everyone is nervous about the company going ex-growth. Operating cashflow have actually been increasing at around 11%pa.
Mark, I've also held IG group (LON:IGG) since 2018 and whilst the SP performance has not been stellar (although it has recently been on a nice spurt), it has rewarded me with almost 34% in dividends during the time, so my question is why would you "exclude dividends"?
My sense is that the market was not enamoured with the previous CEO and perhaps the Tastytrade acquisition was questionably timed and priced.
It does appear that sentiment is turning more positive as Breon Corcoran starts to make his mark.
I suppose one concern would be that the £142.4m of interest income may come under threat from regulators or a lower interest rate environment.
Nonetheless it feels like a nice relatively safe, good value, income stock which I'm very happy to have held onto (I wish I could say the same of so many others where my intervention bias twitchy fingers got the better of me!)
Gaming Realms (LON:GMR) continues its march - a great quality growth stock at a very reasonable price.
Diageo (LON:DGE) Down 8% in early trading. Prelims were out. Net sales down 1.4%. Divvie increased by 5% though. Operating profits were up 8%, but I think that was due to last year's exceptionals. EPS before exceptions is down 9%, which paints a nastier picture.
I thought it worth a mention as one of Nick Train's favourites.
Historically, operating cashflow per share was declining slightly. I haven't done detailed calculations, but I don't think the current results change the picture much.
Also historically, reported EPS has been growing at 6.6%pa, and normalised at 9.8%pa. That sounds not to bad, but if I update the figures to EPS (before exceptionals) now of 180c against 2019 comparative of 163c (correct me if I'm wrong), that's a CAGR of 2%.
Their website takes you round the houses a bit, but a nice summary is here: https://www.diageo.com/~/media...
So, hmm, not too much to get excited about there then, I think, esp given the PE of 17. Stockopedia gives it a Momentum score of 19, which is a bit wan.
The shares are down over 5 years, despite them doing buybacks at around 2%pa. It was a policy that clearly didn't pay off. Their shares were at lofty valuations anyway, so it was a misguided one. The shares reached a peak of over 4000 back in Dec 2021, and now stands at 2341p. Over the last 10 years, shares have compounded at around 3%pa, which is a bit weak. It's difficult to estimate the long-term divvie yield, but it's somewhere around 3%. So that'd be a total return off around 6%pa for a decade.
Hi Mark, re Diageo (LON:DGE) I've been tracking it for a while as we all know it has a quality portfolio of brands but i'm turned off by the debt at 3x and coupled with the poor capital allocation decision of buy backs (funded by debt) makes me think there are better large cap opportunities elsewhere such as a St James Place or a Whitbread.
Edit - I've just seen Paul and I are on the same page on this one, not copying, honestly...
RBG Holdings (LON:RBGP) Pre-Close Trading Update - slight softening of revenues in H1 but with stronger H2 predicted - guidance is in line.
H1 2024 revenues of £18.4 million, down from £19.8 million in H1 2023, due to a quieter May and June - election blamed. Company expects a stronger second half with full-year trading to be broadly in line with market expectations.... and adds this handy footnote (thank-you RBG):
"The Company understands that market expectations for the financial year ended 31 December 2024 are revenues of £41.2m and Adj. EBITDA of £6.0m."
Annualised cost savings of approximately £3.0 million expected from 2025 onwards. Net debt £24.4 million, up from £21.0 million in 2023.
Not much to get excited about, but nothing to get too worried about either... PE is an undemanding 5.8 but reflects its poor past performance. I hold a few in the hope of a turnaround... but not sure there is enough momentum for my liking
RBG
Isnt RBG those clowns that a couole years ago gave the FD literally a million pounds of share options at zero cost with no hurdles or deliverables over and above getting to work on time ?
Sure it was
Its an iron maidem share on that basis alone .
“Run for the hills”
Any views on SDI Group PLC (LON: SDI) result will be highly appreciated (i hold).
Morning Paul,
Foxtons (LON:FOXT) reported a good set of interim results this morning, ahead on all metrics.
They don't feature in your list of companies reporting above. I'm always a bit bemused that there is so much discussion of housebuilders, building components suppliers, land banks and the like, yet very little coverage here and elsewhere of estate agents, who are the people involved in the buying and selling of the new properties.
I would have thought that once interest rates do start to come down, their share prices would go up quite quickly. As it is, their sales revenues are up 28%.
Property Franchise (LON:TPFG) TPFG has been covered well and has a more stable history than FOXT
rogerh,
You jumped the gun a bit here -
"They don't feature in your list of companies reporting above. I'm always a bit bemused that there is so much discussion of housebuilders, building components suppliers, land banks and the like, yet very little coverage here and elsewhere of estate agents"
We've covered FOXT 4 times in the last year, including today.
We've covered LSL 4 times in the last year too.
We even covered tiny WINK here on 10/7/2024.
And I haven't even touched on Belvoir, now part of Property Franchise (LON:TPFG) both of which we reported on extensively.
Maybe a bit of fact-checking might be in order before firing off an inaccurate post in future? Stuff like this really gets up my goat! No reply needed.
P.
Paul - Your response is warranted....but in his defence, how is he meant to do "a bit of fact-checking" through the posts and discussions on Stocko when search doesn't work??
I can't find my own (properly tagged) posts on certain stocks in Stocko - I have to scroll through all of posts in time order, which in this day & age is a little ludicrous.
You can search here on my spreadsheet for the last year.
Also, the Stockopedia search does work - you just have to scroll down.
From my perspective, you can probably imagine how infuriating it is to expend a lot of effort covering 24 companies today, and over 600 in the last year, to read a comment claiming we didn't write about something that we've actually extensively covered. I want to punch my screen, but have quite spindly hands, so it would hurt me more than the screen. And my backup screens have the wrong type of connectors in these days of HDMI leads, but there are about 4 in a cupboard, covered in bubble wrap. So a few more reader comments, and we might have to dip into that strategic reserve. I'm off for another G+T in the sun!!!
Paul,
Apologies if my post earlier today came out wrongly. When I posted it, Foxton’s wasn’t up in your list of companies reporting today and I was hoping to get your view of their results.
What I was actually meaning, albeit badly expressed, was that estate agents somehow don’t seem to me to be discussed in the same vein as housebuilders (Vistry, Gleeson, etc), buildings components suppliers (Eurocell et al), land banks (Harworth, Boot) i.e. as direct beneficiaries of interest rate reductions when these come and the property market recovers. It was a general market comment, not just pertaining to the exceptional SCVR.
Certainly you do a more than excellent job of covering so many stocks and it is very much appreciated!
I hope your goat may be a little assuaged.
Roger
Well thank you Roger. I've consulted my goat, and to be fair, he seems remarkably relaxed now. We were a little uptight earlier, sorry about that.
Lol good to see you thought through the consequences and possible cable related downside to punching your screen. May I suggest a hammer to spare your spindly hands?
Great work today.
Dont get me started!!
Hi Paul I think what Monty meant though was that you can't search for comments. If you remember that someone posted a great comment on, for example, NWF (LON:NWF) last week, you can't find it by searching "NWF". It will only come up if it was in the subject of a post.
Great work today. Am mulling over your comments on Filtronic (LON:FTC). Dave
Exactly this - no criticism of Paul intended, and to try and make that 100% clear I started my comment by stating his response was warranted.
If you are a Stocko author then your articles do come up in search (haphazardly with some very old ones high up).
If I want to find Yiannos1's comments on McBride, or see what PlanetX posted a few weeks back - I can't - other than to click on their name and trawl through ALL of their posts manually. Not all of us can read all of the SCVR every day due to other commitments - and it would be great to bring up all reader comments on a certain stock.
If you invest time in posting an article in the Discuss section then it simply vanishes into a black hole once it rolls off the opening screen. I've given up wasting my time on that.
The fact that Paul has to maintain a separate spreadsheet outside the Stocko environment so people can keep track of things should really be focusing minds on where Stocko deploys its development spend.
On the old site we had fantasy funds, which could be viewed by every subscriber. Roland had one for his long running portfolio. This all went with the new system. It would be useful if Stocko staff could at least have funds that everyone could view, such as NAPS. Some members have even stopped contributing or have left because of this. There was a good one on European stocks.
As for searching, it does not always work, the tagging system had issues with tags going missing. Then some authors did not use tags or not many. The search only works the stock, not anything else. Even if you do find it under the members posts, then when you click on it, it does not go to the post but the top of the page, you then have search again for it. Some stocks get tagged but l can't find them in the article or in the posts.
An American Fantasy Fund would be greatly appreciated by me ... I'm desperate to get my feet wet in the deeper US waters , but without a bulletin board / discussion thread such as the SCVR, I'm a bit scared to go off piste, screening on my own ... somehow UK Markets seem much easier to navigate when you're familiar with many of the brands and closer to the issues...
If Ed was to hire another resource, speaking from a personal perspective, I ( and I guess others, potential thumbs up ) would happily pay for the US Subscription if there was a similar brainstorming of US ideas ... frustrating when you know that many experts ( Yiannos1, BnB etc. we know who they are ) have multiple US holdings, but are probably lacking a forum in which to share their knowledge ( if they wish to ).
Just realised that this is yesterday's SCVR, so won't get many views, but very many thanks indeed to Paul, Graham and Roland. for all their very hard work.
SDISdiSDI (LON:SDI) IMC at 2pm today
Journeo (LON:JNEO) I hold
There is a lesson in here somewhere about trading the news flow as oppose to the price action (which was signalling there was something wrong).
I can only put the price action down to Downing selling into an illiquid market, thankfully I wasn't spooked into selling.
Net cash of £13m, free cash flow yield of 16% and an EV/EBITDA multiple of 4x with a long runway ahead of it.
This is a gem of a little company, Cavendish have upgraded and raised their price target to £4.70, I trust this management to deploy their firepower intelligently.
I likedJourneo (LON:JNEO) on fundamentals when I started using Stockopedia early this year. However, I was put off by the Stockreport's 'short screen' and high 'earnings manipulation'. I have tended to avoid companies if either of these are highlighted. From all, the positive comments this morning and green rating I wonder if anyone can comment on how these factors can be ignored?
Journeo (LON:JNEO)
However, I was put off by the Stockreport's 'short screen' and high 'earnings manipulation'. I have tended to avoid companies if either of these are highlighted
you often need to dig down to the balance sheet to see the realities. Many of these screens will flag up stuff that can practicably speaking "not be an issue" - but alwasy best to satisfy yourself. Note sometimes screens have valid issues - often with growing companies like journeo they are capitalsing costs which can result in less than 100% cash conversion ref profits and that (somewhat seinsbily) can raise flags.
I dont profess to be an expert onm the poor scores journeo has but i suspect the high growth may be raising some concerns - perhaps as growth moderates and they have better track record of higher numbers things will moderate.
Its all about the balance sheet so lets check that at year end
Cash £8 mill - trade receivables £12 mill - inventories £6.9 mill
whats owed out trade and other payables £10 mill - deferred revenue £8.6 mill - lease liabilities £1 mill - loans and other payables £0.3 mill
the rest of the stuff on the balance sheet isnt material too me
I would give this balance sheet a very solid 9/10 - very safe.
Main thing is they have a great cash pile - note that cash pile is now up to £12.8mill !!!
they have receivables that fully cover payables - note large receivables can be an issue in itself ref bad debt risk - but £10 mill on £50 mill turnover seems fine.
Liabilities of defered revenue is probably the best liability to have as thats just future sales waiting to be booked (they will have invoiced or been paid and/or have amounts in receivables)
In summary they look like they have chomping cash pile in reserve with the working capital taking care of itself (debtors/creditors) and their inventories are fully paid for practicably speaking. Compared to many growing companies who may have stretched working capital this balance sheet is rock solid at present.
I would say a sound balance sheet doesnt mean they arent pimping earnings - note assets (excl current asets) did increase by £5.4 mill - so alot of their profit has been invested in capital stuff that year. That makes sense based on acquisition and doublidingt of sales in a 2 year period - i would expect the asset numbers to be more stable 2024 and 2025 unless they have material acquisitions. so perhaps these red flags may wane soon?
Thank you rmillaree. Very helpful indeed.
Agreed. Downing started the run down and more recently Gervais Williams at PMI stuck the boot in when saying he liked the company, but was selling as he saw better value elsewhere..... .... JNEO is a gem of a small company playing in a active, growing and well funded market space. The opportunities are considerable.
No mention of Bodycote (LON:BOY) interims?
Bodycote (LON:BOY) Is just above 1bn market cap cut off for the SCR.
Quite right Dragon but why then are people discussing Diageo (LON:DGE) later on this morning which is massive compared to Bodycote (LON:BOY)
I assume the person was asking why it wasn't mentioned in the list of what is being covered. Which includes AG Barr, maybe that's why Paul mentioned Diageo.
Diageo is in the movers list. I look at those because a large % move means something interesting is happening.
Bodycote is down 2%, so didn't come up as a mover.
Graham and I have already reviewed 24 companies today, so I hope you don't mind, but we'll leave it there. It's sunny, and I have gin.
We quite like Bodycote though, so you tell us why you like it?
Cant say I am impressed with Bodycote (LON:BOY) interims
Journeo (LON:JNEO)
Cavendish has raised forecast adj. eps for current year from 22.1p to 23.5p and PT from 385 to 470 based on FY1 P/E of 19.8x for the peer group.
https://www.cavendish.com/rese...
JNEO up 10.75% at 08 15.
Journeo (LON:JNEO)
Cavendish has raised forecast adj. eps for current year from 22.1p to 23.5p and PT from 385 to 470 based on FY1 P/E of 19.8x for the peer group.
Happy to see my stake improve in price today but I really can’t see a PER at nearly 20x for a tiddler like JNEO. Perhaps 15x tops, and it would take plenty more execution to get there.
Journeo (LON:JNEO) but they have a lot of cash, about a 1/3 of market cap.
Edit. Journeo (LON:JNEO) discussion also on Wolfies excellent "Is the Scene Set for Summer Stage 2's? post
Journeo (LON:JNEO)
Happy to see my stake improve in price today but I really can’t see a PER at nearly 20x for a tiddler like JNEO. Perhaps 15x tops, and it would take plenty more execution to get there.
Presumably they are expecting further growth in profits to come with 20 p/e (or are they just glass firmly full?) - i dont tend to pay much attention to price targets but hey why not have a high one rather than a low one they at least seem to have the faith. Hopefully the saas type income streams and potential for decent operational gearing and acquisitions too means they are well set - personally i like to see some firm future numbers before i pin a higher valuation - pe of 12 * the 23.5p (ughh its adjusted eps) = 280 seems about right for now in absence of any guidance for next year. Happy to hang around for the ride based on todays news. If nothing else todays update has hopefully temporarily silenced the doubters (was that me?)
EDIT
Ok perfect timing here thanks to Cavendish we have some visibility on 2025 now (i have copied info below from other place further details there) - £5 mill adjusted pbt pencilled in for next year - main thing is that there is no dropoff in expecvtations despite the ny subway income drying up - i would expect estimates for next year to hopefully be reasonably conservative so all looks tickety boo here.
We have also upgraded our FY24E net cash forecast by 8% to £12.8m, reflecting the cash generation already experienced in the first half. As the pipeline continues to grow and grants revenue visibility, we have released our FY25E forecasts which show revenue increasing 4% YoY to £52m and adj PBT increasing 6% YoY to £5m. Journeo looks compelling on an FY25E adj P/E of 9.4x (6.3x ex-cash P/E) vs peers on 16.6x, with further upside being seen if the substantial £12.8m cash balances (35% of market cap) are deployed on additional organic or acquisition opportunities
Somero
USD earner and GBP to USD is headed up to 1.30 and maybe above .
Thats going to drag profits too .
Still a good company though .
I sold mine a good while ago as clearly the story was chamging.
Somero Enterprises (LON:SOM)
Were still running a buy-back programme as recently as last week when management must have known about trading conditions - presumably a vote of confidence?
If you've not met the management of DP Poland (LON:DPP) then why not tune into the webinar at 12.30pm today. Nils Gornall, CEO and Edward Kacyrz, CFO, will provide an introduction to the company and update on performance. Progress since this team took the reins almost 2 years ago has been impressive with LFL sales growth regularly greater than 15% and in the most recent quarter sales grew at 26.5% LFL.
Register here
Seems like a strong update from #SAAS this morning
Filtronic (LON:FTC) with very good results. The note from Cavendish says that Aerospace and Defence orders are up, but revenues are down, as delivery will be this year and revenues recognised then. Given that the low earth orbiting business is going great guns, it looks like next years estimates will need upgrades at some point.
Weather related P/W from Somero Enterprises (LON:SOM) .
In consideration of the aforementioned factors, the Company now expects FY 2024 revenues of approximately US$ 110.0m (compared to the previous market consensus estimate of US$ 120.7m), EBITDA of approximately US$ 30.0m (compared to the previous market consensus estimate of US$ 34.0m), and year-end cash of approximately US$ 27.0m (compared to the previous market consensus estimate of US$ 31.7m).
JNEO. A very positive TU today.
JNEO. A very positive TU today.
Certainly good to hear we are are a smidge above “in line with expectations”, but the cancellation of the US subway contract takes the shine off - and points to structural weakness in public transport use around the world’s more developed economies, where WFH is becoming entrenched. I’m not expecting a big reaction either way. But who knows what the market will do?
Pause of the U.S. subway contract was expected and well sign posted. Not ideal but no biggie in the grand scheme of things. WFH is already reversing with much less flexibility and more and more going in 5 days. Even Friday volumes are increasing. But actually the markets Journeo (LON:JNEO) are servicing are generally growing rather than shrinking and as they become a global player there is no shortage of contracts to go after. Also worth remembering that these things have a lifespan and need replacing so you have both a new and replacement market. Throw in the SaaS recurring revenue which should become an increasing proportion of revenues and that should provide a good smoothing effect.
Thanks for your thoughts David. As holders, always good to discuss bull and bear cases.
RE JNEO
WFH is already reversing with much less flexibility and more and more going in 5 days.
But not in the Civil Service where someone quoted in a Telegraph article said they are all twats. They only want to work Tuesdays, Wednesdays And Thursdays.
This is factually incorrect, but hey it's the Civil Service-hating Telegraph. What else would you expect? Anyway, we shouldn't be discussing politics on here Samsgrandad should we?
djack, I wasn't discussing politics, i was discussing JNEO and working from home. The Civil Service isn't political......is it?
If you were discussing Journeo (LON:JNEO) then there's no reason to make a spurious comment about Civil Servants, even if it was an attempt to be humorous. There are a number of companies and organisations in the UK where hybrid working is normal now. I doubt Journeo (LON:JNEO) products are affected by how often people commute, as they're operational whatever kind of travel that someone may do.
I didn't make any comment, I quoted someone whose comment I read in the paper. Do get over yourself.
The Telegraph made a typo, it really meant TWATs.
i suspect the issue with the NY subway is more to do with fear of being killed or attacked rather than lack of people having a need to travel.
Journeo (LON:JNEO)
Agreed update is reassuring
Per company
Revenue for the full year is expected to be approximately £50m, marginally ahead of current market expectations, with adjusted profit before tax expected to be £0.4m ahead at £4.8m.
Looks like they are ahead of expectations ?By £0.4 mill if my reading of the above is correct ???
Comparing the above to the £3.7 mill expected net profit per stocky seems a stretch to think they will deliver over £4.0mill post tax profit factoring in tax share options etc so smaller beat at the bottom line as should be expected.
I suspect the market result today may be not a lot - they are obviously expecting h2 profits to be down on h1 so that may take the shine off the 0.4 mill beat for those looking in externally - I think 2023 was similarly h1 weighted too . Comments ref large us subway contract seem to suggest that work may be somewhat on the back burner.going forward - I have seen comments elsewhere (not substantiated) that this contract was delivering very good profit element.
Overall though one can’t expect company like this not to take a pause for breath at some stage ref growth so as things stand looks like 2024 will be very decent progress over 2023 - will be interesting to see when first expectations for earnings turn up for 2025 - I suspect shareprice might remain subdued till that cat is out of the bag,