Small Cap Value Report (Tue 30 May 2023) - DWF, HTG, BOWL, LIKE

Good morning from Paul & Graham!
Weekend podcasts - I'm only publishing these on the main podcast platforms now, not on my own website. If you prefer a web-based version, this is the web page created by acast, the publisher I use for my podcasts, which you might want to bookmark, if interested. I must change that picture too for one with a smaller double chin!
My macro view is certainly getting more bearish, after the latest lurch higher in gilt yields, core inflation proving more stubborn than expected, and market expectations for peak interest rates being a lot higher than a week ago. One month's data is just that, but even so it strikes me that we might be inching closer to a recession. Who knows? It's difficult to see why small caps would start a bull market any time soon, given that people can earn a nice return, with little to no risk, from cash, or fixed interest instruments. So I think we should really be questioning valuations, that in some cases don't seem to adequately reflect the completely changed environment we now have. Mind you, once we're through this period of higher inflation, maybe interest rates might come back down again? All the more reason perhaps to lock in some higher yields on fixed interest stuff?
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections
DWF (LON:DWF) 66p (+6%) (£226m) - Full-year TU, misses FY 2023 estimates but forecasts for future years are unchanged - Graham - AMBER
This RNS leaves out most of the bad news, as investors have to find the broker note instead for profit and debt figures and how they relate to prior expectations. Estimates for future years are unchanged due to anticipated cost savings. Very cheap shares but debt is high.
Hunting (LON:HTG) - 232p (+15%) (£381m) - Major order, improved guidance - Graham - AMBER
Pleasant news of a 3-year order from Vedanta for Indian operations, total value $91m. Hunting’s EBITDA guidance gets raised once again. The very large, short-dated order book is now $575 million. Market cap should allow for more gains if this momentum continues.
Hollywood Bowl (LON:BOWL) - up 1% to 262p (£450m) - H1 results & in line outlook - Paul - GREEN
A high quality, high margin business, that continues to trade well - in line exps for FY 9/2023. Self-funding expansion & refurbs, plus decent divis too. Lots to like here, but nobody knows whether the boom in ten pin bowling is here to stay or not.
Likewise (LON:LIKE) - unch at 25p (£61m) - Trading Update (in line) - Paul - AMBER
A fast-growing competitor to Headlam (LON:HEAD) run by its former CEO. Reassures on trading today, in line with expectations. Good growth. Could be one to watch maybe?
Paul’s Section:
Hollywood Bowl (LON:BOWL)
Up 1% to 262p
Market cap £450m
Hollywood Bowl, the UK and Canada's largest ten-pin bowling operator, is pleased to announce its Interim Results for the six-month period ended 31 March 2023 ("H1 FY2023").
Company’s headline -
CONTINUED STRONG CUSTOMER DEMAND REFLECTING ATTRACTIVENESS OF OFFER AND GREAT VALUE FOR MONEY PROPOSITION
Key numbers for H1 -
Revenue £110.2m, up 10% vs LY, or +20.7% if the one-off VAT benefit to last year’s figure is adjusted out, to give a like-for-like (LFL) comparison.
LFL revenues (i.e. excluding new sites, and closures, if any) is up +3.5% - well below inflation, but the prior year comps are tough to beat as there was a bowling boom after the lockdowns ended (which still seems to be ongoing!)
Gross margin - note the very high gross margin of 82.8%, since a lot of revenues will have little to no direct cost of sales (playing games, as opposed to buying a physical object). Although this is down from 85.1% in H1 LY (last year).
Adj EBITDA (pre-IFRS 16) is a healthy £35.1m, up 13% vs H1 LY. Note that the margin on this measure has fallen from 33.95% LY, to 31.85% this time, but that’s still a very good margin I think, and it takes into account all central costs. So the individual site EBITDA margin would be even higher. I think EBITDA is actually a useful performance measure in the hospitality and retail sectors, and is widely used. That’s only for a half year remember, so this is a highly cash generative, high margin business.
Balance sheet - net cash is £44.1m (ignoring leases, because they are not debt, they are future operating costs from which profits will be generated).
NAV is £139m, which includes £89m intangible assets, quite a lot. That gives NTAV of £50m, which is only one-ninth of the market cap, so it’s not really an asset-backed investment.
The lease entries show an overall deficit of about £41m, which surprises me, as that implies the group has some loss-making sites where the notional asset value is well below the future rental payments. That would be a good question to ask management to explain.
Being a leisure business, the balance sheet has very little inventories and receivables. So it has negative (i.e. favourable) working capital. That means there’s a lovely cash pile sitting there, or £44.1m, with no bank debt, just an unused £25m facility.
The short version is, everything’s fine, this is a well-financed business, so I don’t see any solvency or dilution risk..
Although very high gross margin companies like this are sensitive to downturns. By my rough calculations, revenues would have to drop by about a third, to eliminate profits and reach breakeven, which is a very extreme scenario.
New sites, refurbs, and Canada - the commentary says all are performing well, at or above plan. BOWL is clearly in a sweet spot, generating loads of cash, which enables it to keep expanding & improving its offerings - a virtuous circle I’d say.
Outlook -
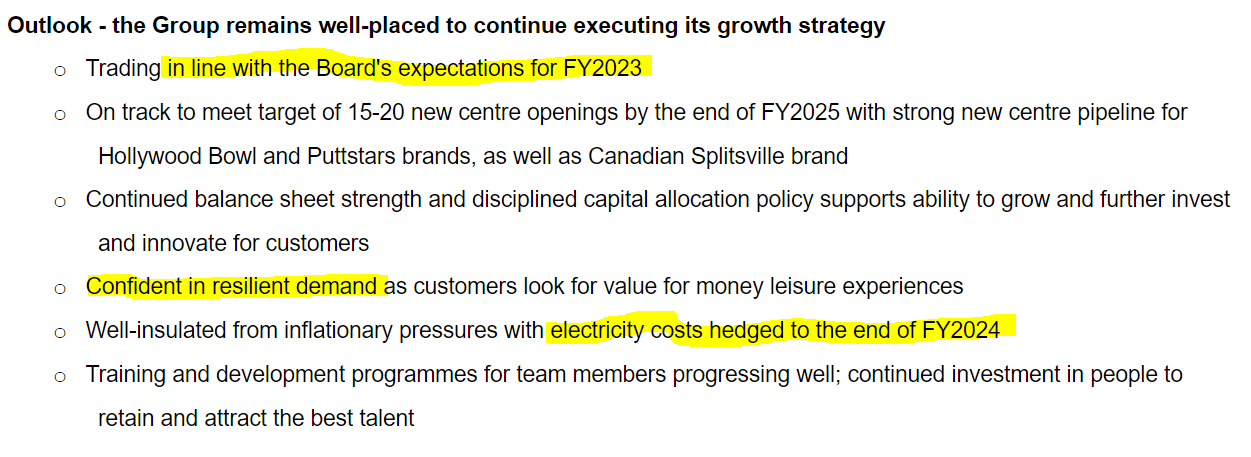
I can’t see any information on what the LFL sales growth (if any) has been since the half-year end of 31 March. If I’ve missed it (possible!) then do please leave a comment. I suspect sales growth might now be hard to come by, given strong comparatives. Not that it matters too much, because the company confirms that it’s trading in line with expectations for FY 9/2023.
The StockReport shows a broker consensus for this year of 18.7p EPS, so at 262p that’s a PER of 14.0x, or an earnings yield of 7.1% - I’d say that feels about the right valuation given current macro conditions.
Paul’s opinion - I can’t find fault in BOWL - it’s trading very well, generating tons of cash, which it’s using to self-fund growth, refurbs, international expansion, and pay a fairly decent divi yield forecast at 4.3%. That’s an impressive combination. So it has to be a thumbs up from me!
Obviously the big unknown is whether, and for how long, the current popularity in bowling is likely to last. Maybe it’s permanent? Remember though, that if demand really drops off, eg in a big recession, then that 83% gross margin, and a largely fixed overheads base, could generate high operational gearing on the downside. For that reason, I don’t think it’s necessarily a good idea to be chasing this share higher in such a wobbly macro environment.
I see BOWL shares qualify for a GARP (growth at reasonable price) screen - I've not looked at this one before, but it might be worth checking this to see if we can find other similar shares. This is a clickable link - I see this GARP screen only picks up companies with a >£200m mkt cap, but that can be easily amended to look for smaller companies, if you wish.
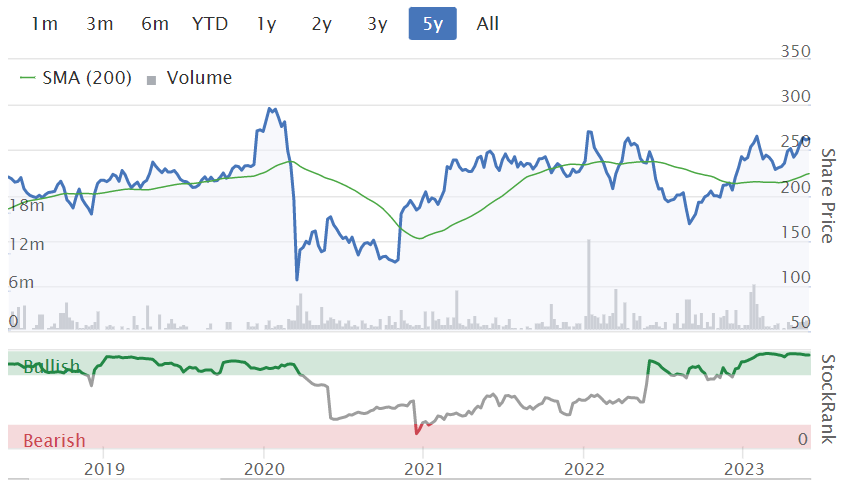
Healthy-looking chart, given that we're in a pretty horrible bear market for smaller companies - although it's quite surprising it still hasn't recovered to the pre-pandemic peak, given how well the business has performed since then. Although note the share count has risen from c.150m to almost 172m over the period of this chart, so some dilution -
Likewise (LON:LIKE)
Unch at 25p
Market cap £61m
Likewise Group plc (AIM:LIKE), the fast growing UK floor coverings distributor…
I remember previously researching Likewise, and was confused that it had 2 admission documents on its investor relations website. It turns out one was for an obscure Channel Islands listing, but it then moved to AIM in Aug 2021.
This group is run by Tony Brewer, who was a former, long-serving CEO of Headlam (LON:HEAD) (I hold). I had a get to know you phone call with him last year, and the business model is very simple - LIKE is expanding organically (opening new warehouses), and by acquisition, with the aim of becoming a major player in the UK floorcoverings distribution market - so it’s trying to eat the lunch (my words, not his!) of Headlam, and mop up independents too.
As you can see below revenue growth has been impressive, but it has yet to make a meaningful statutory profit (it did manage to squeeze out an adjusted profit in 2022) -
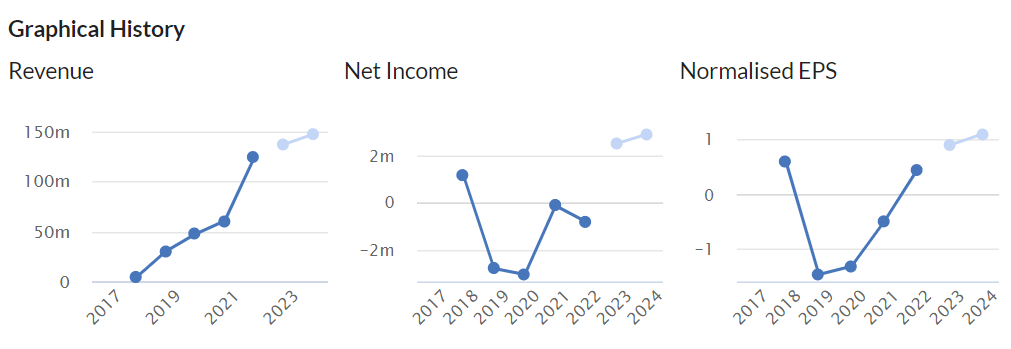
Today’s update sounds encouraging (given that HEAD has recently issued what sounded like a mild profit warning, and was unsure about consumer demand) -
…is pleased to announce that despite certain adverse comment regarding the New Build and Refurbishment Markets, that its businesses in both Residential and Commercial Flooring have continued to increase following the last announcement on 16 May 2023 and the Group continues to trade in line with current market expectations.
Year to date Group Revenue has now increased by 17.7% against the corresponding period last year and the Likewise Branded Businesses by 24.5% due to the ongoing investment in Sales and Marketing continuing to accelerate gains in market share.
Its medium-term target is to reach £200m revenues. Note that for comparison, HEAD did £664m in FY 12/2022.
The next update is on 29 June 2023.
Paul’s opinion - we’re in a nasty bear market for small caps, so I’m not prepared to pay up-front for future profit growth, when I can buy existing profits cheaply at HEAD (which I’ve done, taking a tiny opening position in it recently).
That said, I think LIKE looks credible, has a reasonably sound balance sheet (with some freehold property), and experienced management. Adding new capacity is pretty simple - it’s just more warehouses, with some simple racking in them, and more staff.
The plan is to keep adding more salespeople, who generate multiples of their salaries in gross profit.
As mentioned in my recent comments on HEAD, my worry is that LIKE and HEAD could just be in a race to the bottom on margins, to the detriment of both businesses.
It’s difficult to imagine what LIKE can do better than HEAD, other than undercut it on price, which doesn’t excite me as something to invest in.
Overall then, I’ll be neutral on LIKE for the time being, but will keep an eye on it. The obvious upside case, is that if it can scale up to the same size as Headlam, but without excessive dilution, then the shares could be a multibagger from the current £61m market cap. That won’t be easy to achieve though. Also, it's the type of share that would probably re-rate onto a more punchy valuation once the next bull market starts.
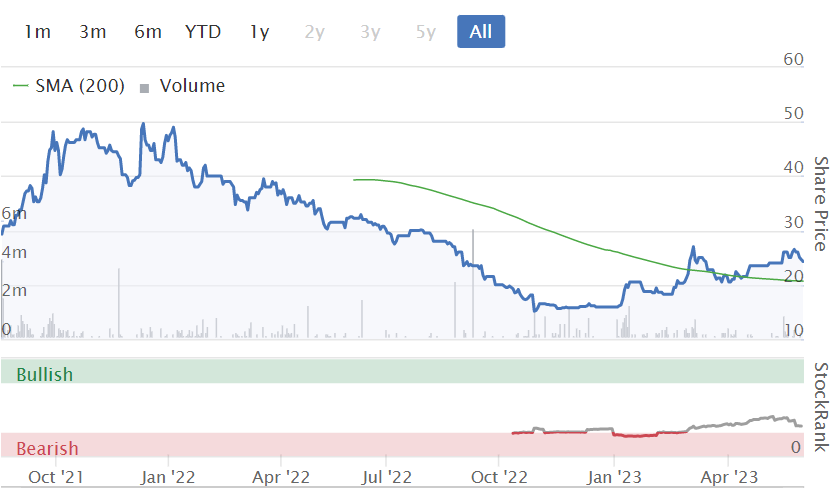
The chart is starting to look a bit healthier too. Although StockRank is not yet convinced!
Graham’s Section:
DWF (LON:DWF)
Share price: 66p (+6%)
Market cap: £226m
This professional services company issues a trading update for FY April 2023.
Key points:
Revenues c. £380m. The broker note tells us that this is 2% below forecast. Organic growth for the year was 5%.
The RNS does not tell us the profits for the year. The broker note says that adj. PBT was £44.1m, 4% below forecast.
“Lock-up days” (time taken to convert work done into cash) is 190 days. The broker note tells us that this is ten days longer than forecast, and that this results in year-end net debt of £98m, £9m higher than forecast.
I find it remarkable that the RNS doesn’t tell us that revenues were below forecast, doesn’t tell us that profits were below forecast (or even what those profits were), and doesn’t tell us that net debt is higher than forecast (or even what the net debt figure is).
The RNS does give us reassurances on medium-term guidance:
Highly confident in medium term guidance provided in July 2021, underpinned by the cost programme which is now expected to remove in excess of £15m of cost by end of FY24 (versus £10-12m reported in December 2022), helping to protect the business from broader inflationary cost pressures.
That bodes well for FY 2024/FY 2025, and forecasts are left unchanged for those years with “upside risk to profitability”.
It is thought that revenue growth will continue at a rate of 13% in the current financial year (but remember that this is not all organic growth).
CEO comment:
We have delivered consistently strong revenue growth and underlying organic growth, with the initial benefits of our cost control programme also coming through. Our transaction in Canada has also given us great momentum in North America, which is a geography that continues to be of high importance to our future growth story. In combination, this gives us a high degree of optimism as we begin FY24.
My view
These shares are strangely cheap, even in a bear market for UK small-caps.
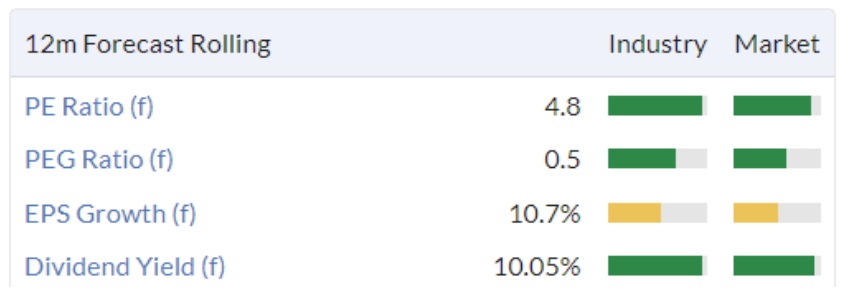
Almost anything with this sort of rating is worth investigating! If only to understand why it is so cheap.
Personally, I will stay away from it, because of my bias against the professional services sector (including law firms), which has been a minefield for investors. However, it’s possible that these shares are now simply too cheap relative to the size of the business. The price to sales ratio is materially below one.
Some of the concerns and quibbles investors might have could include:
Net debt of nearly half the market cap
Net debt higher than forecast, with cash locked up for six months - how confident can we be that all bills will be paid?
Organic revenue growth of 5% is less impressive when you consider the inflationary environment.
The RNS leaves out a lot of useful information - why can’t it say what the profits and net debt figures are, and how they relate to expectations?
I take a neutral view of this share, because a P/E rating this low is clearly already pricing in a lot of bad news. Managing the debt will be key.
Hunting (LON:HTG)
Share price: 232p (+15%)
Market cap: £381m
Today’s news provides a welcome boost to Hunting shares after a difficult start to 2023:
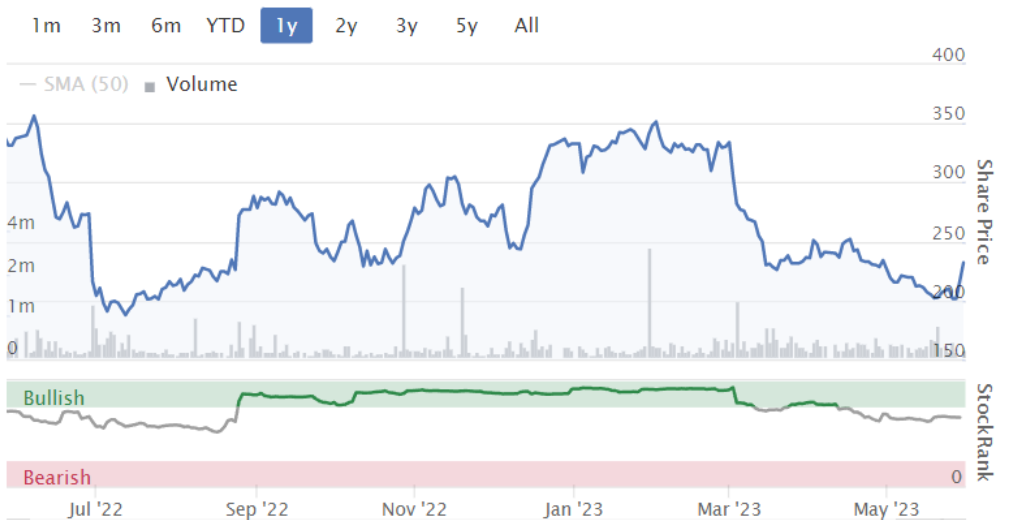
It has a new three-year contract covering 100 oil wells, which the company interprets as a sign that market sentiment remains “extremely strong” in the industry.
Hunting PLC (LSE: HTG), the international energy services group, today announces that its Asia Pacific operating segment has won a new, significant Oil Country Tubular Goods ("OCTG") contract that management estimates to be worth up to $91 million with Cairn Oil and Gas, Vedanta Limited, for its operations in Rajasthan, India.
New guidance - EBITDA for FY 2023 is now expected to be $92 - 94 million, versus prior guidance of $85 - 90 million. This follows another upgrade from $80 million that we commented on in December.
The order book goes to c. $575m, a very nice uplift from $500m six months ago.
Cash/debt - the company says there is no change to guidance for cash at year-end. The latest Zeus forecast suggests net cash of $41m at December 2023.
A word of warning, however - there are significant swings in working capital during the year in this industry and we should not treat this as we would an “average” figure.
CEO comment:
"Hunting's successful run of significant OCTG and Subsea orders since H2 2022 demonstrates that our technology and global footprint is well positioned to deliver significant growth in the medium term. US market activity remains stable and with the orders received for China, Guyana, Brazil and now India, Hunting continues to see a strong growth profile given our standing and recognition with major energy companies, coupled with the strong international market sentiment being reported in many regions."
My view
I’m neutral on this, leaning towards green as the value metrics are attractive, the cash position is not bad, and the earnings momentum has been impressive lately.
When I last commented on it, the market cap was £450m (vs. £380m today). As such the arguments for value are now slightly easier to make, with firm and rising EPS estimates helping to reassure that things are on track.
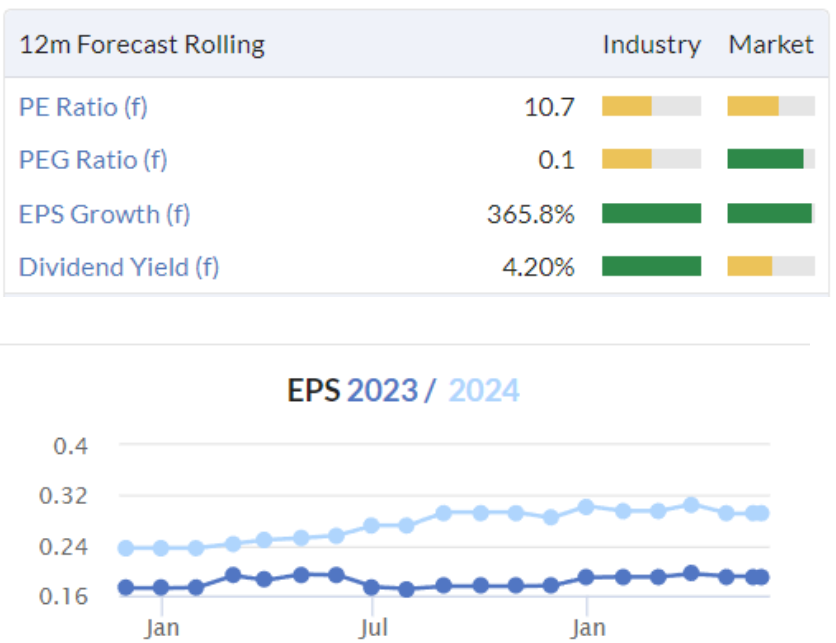
So if you like the oil services sector, this strikes me as a nice candidate for further research.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
ASOS (LON:ASC)
We live in interesting times - market cap now @ £350m - buy and hold looks dead.
The distrupters have become the distrupted.
Hey Paul!
Hate to bring this up here, but I couldn't resist mentioning something about your website woes. It seems like you've been dealing with some unexpected and quite frankly 'flacid' "performance aids" popping up all over the place. I mean, who would've thought your site would turn into a hotbed of unwanted "enhancement" ads? It's a real mood killer, isn't it?
Anyway, I stumbled upon a nifty little solution that might help you out... There's this site (https://10web.io/) you could consider migrating to, which could save you from further encounters with those sneaky hacked advertisements. Think of it as your secret little pill against the unwelcome advances of those pesky promos. It's like the ultimate shield for your web presence!
Now, I won't guarantee that it'll work like magic, but hey, it's worth a shot, right? I'm just tossing the idea out there, hoping it might put a spring back in your website's step.
Cheers, and stay strong in the face of those unwanted "boosts"! (Yes, this post is filled with Viagra euphemisms, soz).
On a similar vein, but re: audio. It’s a pain to lose a recording one hour in. When Tim Ferriss interviewed Arnold Scwarzenegger for his book. He used 2 digital audio recorders. The Austrian oak asked him why he used two devices. Tim replied, “Redundancy. You won’t want to do the same interview twice in case my main recorder fails to record.”
The “Oh, FFS!” was funny though…
I'd welcome views on the 2022 results from Spaceandpeople (LON:SAL) today. A tiny operating loss after a 38% increase in revenue, explained by an increase in staff costs, partly as an investment in growth. No Gov't COVID money in 2022 of course, and a large write-off of goodwill leading to an 11p EPS loss. Cashflow looks OK and the outlook comments are +ve but it appears a miss against expectations and the market appears unimpressed. I hold a few.
Terrible cash flow if you take out the increase of £1.3m in payables.
Also looming contract renewal with Network Rail, one of their largest physical space inventories. Worth checking to see how long their other supply side contracts are (shopping malls, etc) as I remember they were quite short contracts.
Spaceandpeople (LON:SAL)
Hi Paul I wondered if you were going to write something on XP Factory (LON:XPF)? I went home before the Melo Bash. I know you mentioned it on the podcast on Saturday (which was very good as usual). I was interested in the use of R&D tax credits and if you think they are important in the scheme of things. Not a holder but waiting to jump aboard at an opportune moment.
On another note, I dumped DX (Group) (LON:DX.) after speaking to somebody I know who works at a UPS delivery depot in Luton. They have very little work at the moment, there are drivers sat around with nothing to do, the drivers have been offered unpaid leave etc. It went mad during the pandemic apparently trying to keep up with the volume of parcels. I know also from listening to the Odd Lots podcast that a similar issue is going on in trucking in the US.
How do you know DX Group is in the same boat? My wife's workplace use them and she says they are very busy. DX are also opening new depots.
I don't. I didn't like the drift downwards though and I didn't have your inside information. Thanks for that, that is really useful and one reason why I posted as other views are interesting.
Going off the last set of results DX are doing well...
It would be great to get Paul's comments on XP Factory. I listened to a couple of presentations by the CEO post results. I don't know how much they pay Vox Markets for the 'interview' but Vox were so fulsome in their praise for XPF, they really ought to double it. I took note of a comment by a subscriber here that they actually lost circa £1m this year. I spent a long time over the bank holiday reading through what seemed a complicated set of accounts. I'm not good at that at all but they do indeed seem to have lost £1m. Surprise surprise, no mention of that in their presentations, just the old positive adjusted Ebitda stuff. I don't mind companies losing money but they should be upfront about it
Yep. I watched that and another one. I haven’t bought yet as I can seem to convince myself to. I like Vox as a source of companies to look at but it does seem licky sometimes.
XP Factory (LON:XPF) is doing a rapid roll-out of new sites, many of which were opened towards the end of 2022. So the historic numbers are irrelevant. To assess the shares, it's all about working out the future profits, once a full year of the new site openings is included. That's where the broker notes are more useful than poring over historic numbers which are already out-of-date.
Everyone here seems to have forgotten how the numbers work for companies that are doing a roll-out of new sites! It's all about each new site adding say £200k extra contribution (profit before central costs), which means losses turn into profits once critical mass has been reached. XPF has already reached critical mass, and the site economics are excellent. So the 2023 and beyond figures should show a business that's growing profits strongly. But obviously that won't have come through in historic numbers yet, as most of the Boom Battle Bars sites have only been opened recently.
Regards, Paul (I hold XPF)
Re XP Factory (LON:XPF). I am also eagerly awating Paul's write up but aso frustrated that Stockopedia have still not updated the strock report showing the the last set of results
Morning Paul - for Hollywood Bowl (LON:BOWL) you say :
"Balance sheet - net cash is £44.1m (ignoring leases, because they are not debt, they are future operating costs from which profits will be generated)."
This is correct of course, but then why does Stocko include leases in their net debt figure for all stocks ? Could you pester the relevant people to have this changed ?
I would like to second Truegent's comment. I was taking a look at TEG [already hold BOWL] but put off by 'apparent' 300% debt [probably why it does'nt come thro' my Zulu type sieves - max debt 70%] although looking at 22 nd mar accounts they had £10M cash. Only time I have not had a reply from Stoko, when I questioned the fact sheet. Accountant friend explained the new accounting system of reporting. However how many cos. is it now excluding from my sieves simply for this reason. Wonder if stoko can find a way to 'split' real debt from accounting tecniques. As Paul says leases ar'nt true debt but future operating costs. Hope Paul can intervene . Tony
hi Tony - I agree, it is annoying. Would be better to be split out. In Ten Entertainment (LON:TEG) case they are actually net cash outside of leases so it's not really 300% debt at all. I never could understand the IFRS rationale for chaining the rules to include in the net debt number, as it's bonkers really. Are future lease costs an important metric to have easy sight of? yes! but should they be lumped in to mask the actual net debt/cash of the business? No - absolutely not!
FYI, my spreadsheet summary of the SCVRs is now up-to-date.
Link not for sharing outside Stockopedia please! Thanks :-)
Good morning Paul.
I don’t know if you’ve got chance to speak to the management of Centralnic at mello the other day? I just wondered if you had managed to glean anything with regards to the business carrying cash and debt simultaneously?
Thank you so much, and humblest apologies if you have already mentioned it elsewhere.
Well done thepomisback, the same topic has been floating in my mind this morning while I hilled the spuds growing in the back yard!
I wonder more generally please Paul about how, if at all, your impression of CentralNic (LON:CNIC) has evolved or your analysis of 16th May changed since/ if, you were able to meet management at Mello? [I hold]
With many thanks,
TEIN
Morning!
Oh dear, sorry about this, but what with one thing and another I didn't get to Mello last Weds, so missed the opportunity to speak to CentralNic (LON:CNIC) management.
Regards, Paul.
Never mind Paul, none of us can do everything. I'm sure CentralNic (LON:CNIC) would respond to an interview request from you! They do seem pretty engaged with holders.
Did any other readers get any insight on CentralNic at Mello that are shareable here please?
Thanks, TEIN, [I hold]
Don’t worry Paul. I was really being a little lazy by asking rather than contacting them directly. Really grateful for all of your good work as always.
Hollywood Bowl (LON:BOWL) interims appear reasonably positive with Canadian operations trading ahead of expectations. Still can't see why it trades at a significant premium to Ten Entertainment (LON:TEG) despite its Canadian interests.
I hold Ten Entertainment (LON:TEG) so am clearly biased, but nonetheless!
Ten Entertainment (LON:TEG) has more debt according to Stockopedia figures.
Ten Entertainment (LON:TEG) does not have any debt, look at the accounts.
Not a single penny of debt.
Hi Rusty2,
Unfortunately, the StockReport figures include lease "debt". I have challenged this, but the data provider apparently says that this is the accounting standard's definition of debt, so that's what they have to provide.
So something to bear in mind, that multi-site businesses like retail & hospitality will show apparently high debt on the StockReport, because the IFRS 16 lease entries inflate "debt".
Bloody annoying. I wish they would scrap IFRS 16. If any accounting standard has to be adjusted out routinely by accounts users, then it's a lousy accounting standard!
Regards, Paul.
Could it be possible for the provider to give us both figures? The net debt inc leases and the net debt excluding leases. This would be a huge help. If that can't be done then it's important for us all to check the net debt from the last statement ourselves to get the true picture,
Stockopedia is meant to be providing us with useful information; it shouldn't be accepting ignorant (even if accurate given inane accounting standards) comments from 3rd party data providers.
Robbie's suggestion is a reasonable compromise. Importantly the real net debt figure (not the regulatory one) should be factored into Ranking calculations
The net debt should also include the "right-of-use assets" if it is going to include the leases. The right-of-use assets being the building being leased, the leases being the lease left on that building. One should negate the other, leaving 'net leases' (not an actual thing but you get my point) being £0 or close to it. I have contacted stocko about this and was told I was wrong but I do not think I am...
Sharepad allow Net debt - Total leases in historical numbers at least. I use it alongside IFRS junk figure. Unfortunately wont work on forecast figures when filtering for companies.
I dont see any reason why stocko couldnt show this, it cant be that difficult to calculate.
Entirely correct. Stockopedia should be something more than a passive pipeline for third party data. They can and should provide the option to present net debt excluding lease liabilities. That is clearly what their subscribers want.
I expect that, if pushed, Stockopedia will blame their data provider for this. That is their standard response to all data problems and errors, and there is probably some truth in it. But I have to ask whether Stockopedia really has any choice as to who their data provider is. It looks like suitable data providers are in an oligopoly and are totally unresponsive to customer requests from Stockopedia and probably other customers. Also I believe that it would be extremely difficult for Stockopedia to change their data providers, and Refinitiv are very well aware of this. So Stockopedia and their subscribers are stuck with Refinitiv who couldn't care less because they know that it's too hard for their customers to go elsewhere.
Paul, Yes I agree lease debt should excluded or split out, but this is what Stockopedia figures are based on. Even so Hollywood Bowl (LON:BOWL) seems to have more cash than Ten Entertainment (LON:TEG). It makes comparing stocks on Stockopedia is difficult, after all this is what Stockopedia is doing, so some of the data is flawed. Ten Entertainment (LON:TEG) is excluded from some of my screens because of the debt figure.
I don't subscribe to Sharepad but they do seem to be adjusting the figures to exclude leases.
For me, crazy valuation anomaly. Every time I walk past a bowling operator, they are busy.
Good Morning Guys,
Please could you take a look at Tremor International (LON:TRMR) if you get chance. Today’s update seems a bit mixed to me, but forward guidance looks positive.
Thanks.
Pretty impressive turnaround by Tremor International (LON:TRMR) share price today. It hints that the shares are oversold and have bottomed. TBC I'm not a short term or tea leaf reader sort of guy so take that 'wisdom' with a big pinch of salt.
I wouldn't recommend Tremor to anyone as a difficult company to understand and like and I have my doubts! (that is beyond the simple negative biased view many hold of Israeli cos)
That said, I believe they have a differentiated ad tech platform and I like CEO Ofer Drucker.
My history with the stock is buying on a price puke down towards and even below the 100. Selling most of it through 400-700 range when it had covid bounce...and then buying back some more as it fell to 400 and below but rather timidly as I do have a concern I am missing something...I don't think so, but the sp performance is so out of whack with 'fundamentals' I've taken it as a caution rather than my (more usual) opportunity perspective. Plus its an environment where one doesn't lack for fallen shares!
And TBH I probably wouldn't start a new participation now without the history I share above...as its a complex and fast moving company...but my involvement leads me to think I get it (delusion!?). IMO they are doing loads of the right things that will give it durable and profitable scale...I believe we will see much higher sp, many fold the current assuming no cheap take out (that frustratingly the big fund managers holding seem to be angling for...making liquidity for them but ensuring suboptimal price achievement)
Oxford Biodynamics (LON:OBD) have released their HY results today
There is a Webinar today at 2pm for investors. Register: https://us02web.zoom.us/webinar/register/3216841534960/WN_XzaMPjm_TE6YFtNcxVxC1g
Exciting situation over at Oxford Biodynamics (LON:OBD) - in both good and bad ways.
Good:
Bad:
Twist:
Tempted to buy some more now at 14p, as I do see the premium fundraising as a credible option, and the shares will pop upwards on that event. But also think these will drift downwards more, given the bearish market at the moment for anything loss-making and in need of fundraising...
Also think that maybe some of the major shareholders should put this company out of its public misery and take it private. IMHO it needs at least a £20-40m cash injection for the next 3 years to maximise CiRT sales as well as bring the prostate cancer test to market and maybe start R&D on more tests.
(I hold in the Boon Fund)
My morning smallcap tweet: Meat expectations
£BFSA DWF (LON:DWF) STM (LON:STM) Woodbois (LON:WBI) Rosslyn Data Technologies (LON:RDT) Hunting (LON:HTG) Home Reit (LON:HOME) Malvern International (LON:MLVN), Likewise (LON:LIKE), Sportech (LON:SPO)
◄BSF Enterprise (BFSA)► has made 2 further full-scale fillets of cultivated pork, as well as a cultivated pork strip, which were presented at a technical event. [SP=NA Cap=NA]
◄DWF (DWF)► guides FY-Apr rev c.£380m up 8%. "Highly confident in medium term guidance provided in July 2021." [SP=62 Cap=212m]
◄STM (STM)► new interest sharing policy with some of its pension members. Has obtained better interest from its banks and will boost pretax by £1m+. Higher returns will compensate for "lower than expected new business and some significant non-recurring costs". [SP=25.85 Cap=15m]
◄Woodbois (WBI)► cash crisis: GM to increase preemption powers and lower the nominal value of shares to allow a placing. [SP=0.5 Cap=12m]
◄Rosslyn Data Technologies (RDT)► wins two contracts worth £422k over a multi-year period. [SP=0.77 Cap=3m]
◄Hunting (HTG)► hikes FY23 EBITDA guidance to $92-$94m due to $91m 3 yr order. [SP=201.5 Cap=331m]
◄Home REIT (HOME)► update on Internal Investigation includes "existence of certain undisclosed potential outside business interests and undeclared potential conflicts of interest as between certain persons associated with the Investment Adviser and third parties". [SP=NA Cap=NA]
◄Malvern International (MLVN)► AGM stmt. Good numbers. In line? Co "confident for Malvern's prospects and expects to achieve growth in all divisions in 2023". [SP=17 Cap=4m]
In line: LIKE, SPO