Small Cap Value Report (Tue 31 Jan 2023) - CNIC, COG, BAG, MAB1, TPX, SOM

Good morning from Paul & Graham.
It's the last day of Dry January today, so I'm looking forward to celebrating a friend's birthday at the weekend. In the meantime, we've got lots of companies to report on, so I got up early today to try to catch up on 2 stragglers from yesterday - Porvair (LON:PRV) and CentralNic (LON:CNIC) [CNIC now done].
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
It's another huge list of announcements today. We'll not be able to cover all of these, but will try to report on the most interesting (above or below exps take priority). If updates are just in line with exps, then they're lower priority & might not be covered. Please do add your own comments on any companies, it's a team effort, especially on busy days! -
Paul’s Section:
CentralNic (LON:CNIC)
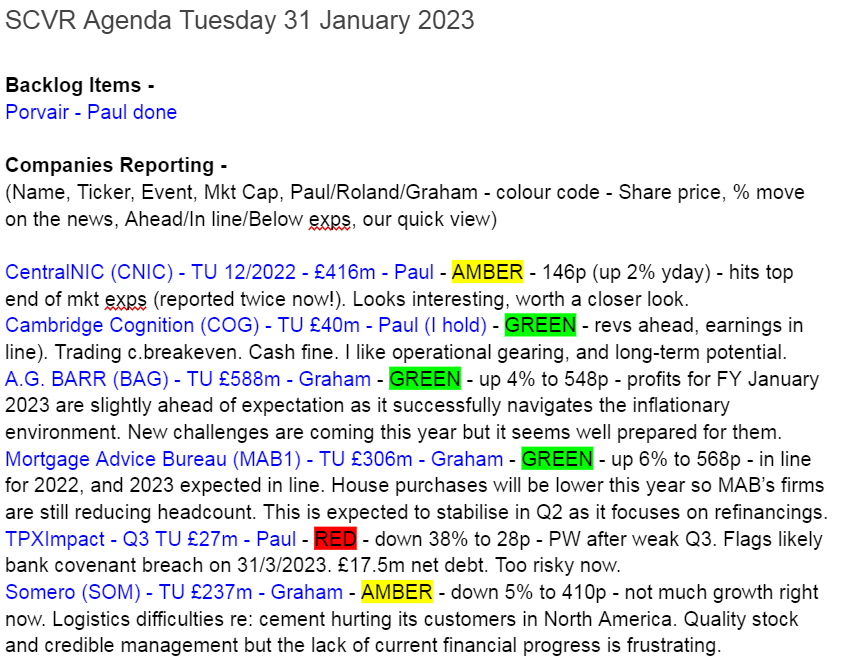
145p - mkt cap £416m
CentralNic Group plc (AIM: CNIC), the global internet platform company that generates recurring revenues selling online presence and marketing services, is pleased to announce its trading update for the full year 2022.
Continued positive trading momentum, with record revenue and EBITDA for 2022
These guidance numbers look impressive - it’s another ahead of expectations update on EBITDA -
The Company now expects to report record gross revenue of c.USD 728 million, and net revenue and Adjusted EBITDA1 of at least USD 177 million and USD 85 million respectively for the financial year 2022.
These represent increases of c.77%, c.33% and c.84% respectively versus the prior year, ahead of the recently upgraded market consensus2 for 2022.
Adjusted for acquisitions and FX, year-on-year organic growth3 for 2022 was c.60%. This outperformance has been driven largely by the growth of the Online Marketing segment, reflecting increased demand for our privacy-safe online customer acquisition services, and the resulting economies of scale and consequent operating leverage.
2 Analyst consensus of revenue and adjusted EBITDA for the financial year ending 31 December 2022 as of 29 January 2023 and last updated on 6 January 2023 is USD 708.5m (analyst range of USD 701m to USD 715m) and USD 82.7m (analyst range of USD 80m to USD 85.1m) respectively.
Bravo for the footnote! It makes things so much better for investors/commentators when companies spell out what the guidance actually is, instead of sending us on a wild goose chase trying to discover what the forecasts are.
In this case, the footnote shows that the company has hit the top end of the analysts’ range at c.$85m EBITDA.
This is not actually much different to the ahead of expectations update which I covered here on 12 Dec 2022, when it said “at least in line with the upper end of market expectations” for EBITDA, which at the time was $80.0 - $84.1m. So this does look a case of double-announcing in Dec 2022, and again in Jan 2023, the same slight beat against forecasts! Hence probably why the share price barely moved on yesterday’s news.
Next question, is EBITDA a meaningful number?
Sometimes it is, sometimes it isn’t, depending on how much is being capitalised, the size and type of costs that are going through the finance costs line on the P&L, etc.
The good news here, as I discovered when rummaging through the accounts here on 12 Dec 2022, is that CNIC does not seem to capitalise much into intangibles. So the EBITDA figure does indeed look credible.
My main reservation with CNIC’s finances, is that it’s taken on too much debt, which we’ve discussed before here. The balance sheet is very weak, with negative NTAV.
Net debt - however, the latest numbers on net debt actually look fine -
Cash increased to c.USD 95m as at 31 December 2022 from c.USD 56m as at 31 December 2021, whilst Net Debt4 decreased to c.USD 57m as at 31 December 2022 from c.USD 81m as at 31 December 2021. Adjusted operating cash conversion continued to be in excess of 100%.
So is debt such a worry now? Not really, no. Although when I see large gross cash, and large gross debt, I do worry that the cash might be a window-dressed, or seasonal spike, which could dissipate once the reporting date has passed. So I’d like to see CNIC use its cash pile to pay down some of the gross debt. It should (as all companies should) disclose average daily net cash/debt, to provide us with a more reliable number that reflects reality, which might be similar to the balance sheet snapshots, we don't know.
The balance sheet at Sept 2022 showed a deficit on NTAV of $(156)m, so not ideal, but it is a capital-light business model, with very little in fixed assets.
Diary date - results for FY 12/2022 are due out on 27 Feb 2023, along with an InvestorMeetCompany webinar on the same day at 13:00.
Board changes are announced, with a new CFO becoming a proper Director, so they must be happy with his performance to date.
My opinion - CNIC has a high StockRank of 89, and modest valuation metrics - a forward PER of only 8.8. Although it doesn’t have balance sheet strength, which is the missing bit for me.
That said, the previous worries on net debt don’t seem valid any more.
CNIC has demonstrated stunning growth, and high levels of profit now do look genuine. The big question is whether this profitability is sustainable or not? If you think it is, then the shares would be good value. I don’t know enough about it, so have to declare myself neutral for now, but as mentioned before, leaning more towards a positive view.
Some of the reader comments yesterday did call into question whether profits are sustainable, which concerns me somewhat, or whether it's a temporarily lucrative cigar butt type of business? the low PER suggests the market might think that currently. We’ve seen before with companies in this sector, that profits can suddenly disappear, then they reinvent themselves doing something different.
I think big Director selling is always something to look out for, when unsure about a business model. In this case all the recent Director buying at CNIC has been from one individual, offset by a couple of large sells from other Directors, so nothing conclusive either way here.
Definitely worthy of doing further digging on this one, I’d say. Or tempting to just buy a few as a punt maybe? I'm tempted!
Cambridge Cognition Holdings (LON:COG) (I hold)
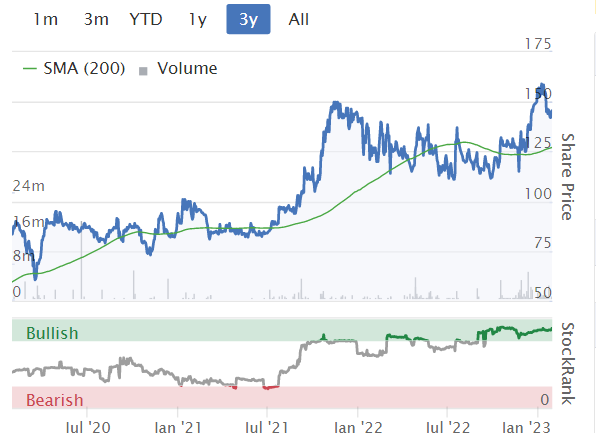
115p (up 1% at 08:38) - mkt cap £40m
I want to do this first because I hold a small position personally, and obviously want to check on my investment, before moving on to everything else.
Cambridge Cognition Holdings plc (AIM: COG), which develops and markets digital solutions to assess brain health, is pleased to announce a trading update for the year ended 31 December 2022.
Strong revenue growth (ahead of mkt exps), up 25% to £12.6m
(H1 revenues were £5.9m, so H2 is £6.7m)
Contracted order book up slightly Y-on-Y to £17.6m (but down from £18.6m in June 2022)
High visibility for 2023, with c.60% revenues already secured (hence little worry about profit warnings)
Trading around breakeven, with £0.2m PAT quoted (H1 was a whisker above breakeven PAT, so better in H2). FY 12/2021 PAT was higher, at £450k (being PBT £253k, plus tax credit of £197k)
Cash position healthy at £8.3m (up from £6.8m a year earlier), so no risk of dilution (unless money raised for more acquisitions)
Reminds us that 2 small acquisitions done, to broaden product/skills - no material effect on 2022 numbers. Note that trading losses from acquisitions mean that a move into the red is expected for 2023 (Dowgate forecasts £(1.0)m loss at adj PBT level).
Large & growing market.
Outlook -
With Cambridge Cognition's gold-standard cognitive assessments, Winterlight's leading vocal biomarker technology, and Clinpal's end-to-end virtual platform, the combined Company is well positioned for further considerable growth.
My opinion - this looks fine to me. The strong revenue growth is key, because it’s high gross margin (80% last year), so combine that with good revenue growth, and it’s giving us lovely operational gearing. Why is COG only trading at breakeven then? Because it’s been run on a shoestring in the past, and is now reinvesting additional gross profit into additional overheads to drive growth - so we have to trust that management is spending the money wisely. The CEO Matthew Stork has impressed me to date, with much improved financial performance & commercial focus since he came on board. I can tolerate the expected £1m loss in 2023.
COG has expertise & decades of key data, in a niche area that would be difficult to replicate. So high barriers to entry, which is proven by the 80% gross margin.
Cash is fine, so I’m not worried about dilution risk. Also, there’s still a fair bit of interest in the company in the stock market, with a market cap of £40m, so I don’t see delisting as a risk. Nigel Wray is the biggest, long-term holder, at 14.5%. So nobody completely dominates the company.
Overall, as a long-term holder, I’m happy with everything. I don’t really want the company run for short-term profit, when it has big market opportunities to go after. As long as it doesn't become a major loss-maker, then that's fine by me. The big potential upside is from the business scaling up, and being valued on a rich growth multiple in future bull markets, not on eking out a small profit, and putting it on a PER of 10-20.
This gets a tick on my portfolio sheet, and I’ll go back to sleep for another 6 months. Thumbs up from me as a long-term investment. Short term? Probably priced about right for now, but as market conditions become more bullish, then it might re-rate upwards with other growth companies, possibly?
The story here is good I think, and with no cash burn to worry about, and good visibility of high margin revenues, then we’re not having to take silly risks to enjoy the potential upside. i.e. risk:reward seems quite good to me, but that depends on what the future holds, which is currently unknown, as with every share.
Note that COG comes up on the Altman Z-score shorting screen. I would ignore this, as a false alarm, but it's important to always check this warning flag. The historic performance justified concern, but it's now fine, with plenty of cash, and capable of profits (but making a policy decision to operate at breakeven, by modestly reinvesting profits for expansion - which could be an excuse, but it's not here) -
Tpximpact Holdings (LON:TPX)
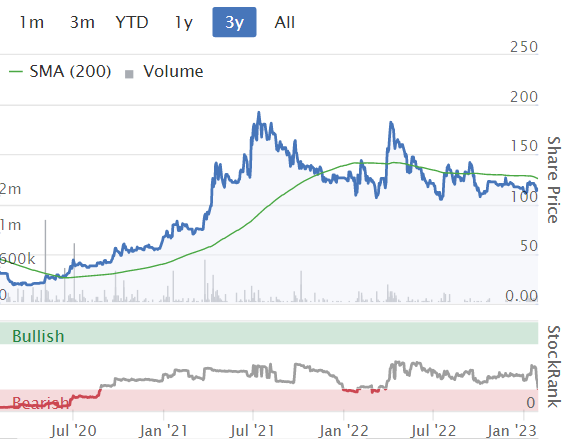
29p (down 36% at 09:17) - mkt cap £27m
Formerly called Panoply, then changed its name. Shares looked promising a while back, but it’s been a disaster since peaking at c.300p in May 2021, now down 90% from that high.
I covered its last profit warning here on 30 Sep 2022 in a fair bit of detail, with a strange disclosure of the founders admitting they didn’t have the right skill sets, and planning to step back into lesser roles. Very unusual indeed. Good visibility meant they indicated a better H2 was in the offing, so I toyed with the idea of this possibly being a recovery share, whilst flagging the balance sheet risk of an £18m bank loan, and negative NTAV.
Unfortunately recovery was not to be. More bombshells today -
TPXimpact Holdings PLC (AIM: TPX), the technology-enabled services company focused on digital transformation, announces its Q3 trading update for the three months ended 31 December 2022.
Trading below expectations. Full-year guidance revised.
Loads of detail is provided - way too much actually. I almost missed a lot of the detail, as if you scroll down, it turns out the top bit is only a summary.
Key points -
Q3 disappointing trading, but good order intake.
Net bank debt £17.5m at end Dec 2022 (and within bank covenants).
Key point re risk - “Unlikely to satisfy its debt covenants at 31 March 2023”, so in talks with bankers to seek a waiver. This obviously greatly increases risk. Although banks are usually supportive, unless they think a business is a total basket case. Plus of course this also greatly increases the risk of an emergency equity fundraise, which might be part of a refinancing package.
Revised guidance FY 3/2023 - revenue £80m (previously £90m), and adj EBITDA margin 2-3% (previously c.8%), so it’s a whacking great miss. Dowgate reckons this is just above breakeven at adj PBT level, at £0.2m (many thanks to them for an update note on Research Tree).
Guidance for FY 3/2024 - it’s only starting the budgeting process for FY 3/2024, which is madness - there should already be a budget in place, given that this financial year starts in just 2 months. This tells me there isn’t proper financial control here.
It’s hoping to get 10-15% LFL revenue growth in FY 3/2024, and has £56m of committed revenue visibility, which does reassure somewhat.
My opinion - I think this is now too risky for me. It could go either way, it’s a coin toss now - a strong recovery in share price, or a disastrous continuation of more bad news, with possible dilution, delisting, or even insolvency.
It wouldn’t matter if TPX had cash in the bank, but it’s got £17.5m net debt, not a good thing when performance has dipped to only breakeven (at PBT level).
It’s the lack of financial control over the budget that worries me the most, and that won’t impress the bank one bit, in my experience. Also previous guidance of a recovery in H2 hasn’t happened, which undermines the credibility of the fresh guidance today. I'm not keen on situations where bad news keeps getting worse.
It sounds like there are significant operational problems too, with shortages of suitably experienced staff mentioned.
This was on my spreadsheet as a speculative idea for 2023, but the facts have changed, so I’ll take the loss and close this position on my spreadsheet (as I would do in real life, if I held). As individuals with usually smallish positions, we have the luxury of being able to sell. Whereas the institutions don't have that option, and as Nigel Wray once replied to my question, "How do you get out of a micro cap that goes wrong", his reply being, "I don't, I just go down with the ship!"
Graham’s Section:
A G Barr (LON:BAG)
Share price: 527p (pre-market)
Market cap: £590m
This drinks company gives us a full-year update for FY January 2023. It is slightly ahead of expectations.
Revenues for the year are up 17% to £315m, or up 15% on a like-for-like basis (adjusting for slightly different year lengths, and the small acquisition Barr made recently. I discussed the acquisition here).
All divisions of the group contributed to the strong performance.
On inflation:
As anticipated, the inflationary backdrop across the UK continued across the second half of our financial year. We have remained focused on supporting our employees, customers and consumers alongside taking positive action to mitigate the inflationary cost pressures.
They evidently did enough to offset inflation, given that profits are coming in ahead of expectations. Well done to management for that.
Cash position: little information given, but it will be “robust” despite the acquisitions made. As I noted in December, the interim results showed cash of £61m, prior to the £20m acquisition of the Boost energy drinks company. There is another £12m of contingent consideration.
Outlook
The outlook statement is in line with expectations, although there will be a few challenges to navigate:
“Continued high inflation” (their words, not mine)
Deposit retention scheme in Scotland from August 2023 (you have to pay 20p when you buy a drink in a container, and you get it back when you return the container to a recycling point).
“Short term dilutive impact from the Boost acquisition” - they are referring to the impact of Boost on Barr’s operating margin. They have previously warned of this, and said that they expect their operating margin to recover in the medium term.
My view
To me, none of the challenges look beyond Barr’s ability to manage. They have already managed inflation very well, and I’d bet on them continuing to do so.
It’s true that the deposit retention scheme is a new challenge: These schemes are being rolled out all over the EU right now.
The way they work is that consumers will have to remember to dispose of their drink containers in a shop or other recycling centre. They can’t simply dispose of them at home, or they will lose their 20p deposit. So there’s an additional hassle which I suppose could turn off a few consumers at the margin. Hopefully not too many.
I included A.G. Barr in my list of top ten ideas for 2023 so it will come as little surprise that I retain a positive view on this company. Since I wrote that article, not much has changed except that we now have an “ahead of expectations” trading update for FY January 2023.

Mortgage Advice Bureau (Holdings) (LON:MAB1)
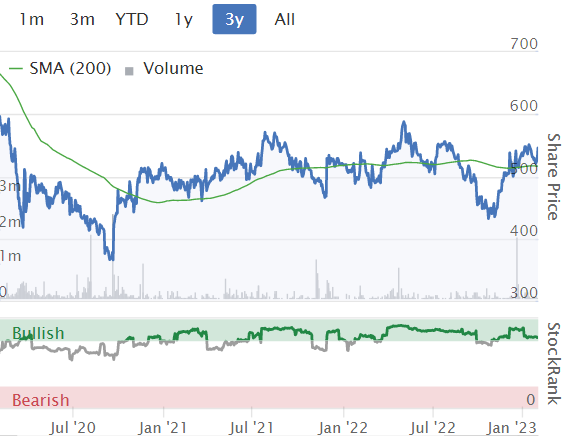
Share price: 568p (+6%)
Market cap: £324m
This stock was also included in my top ten ideas for value and growth in 2023. Here is its update for the full-year 2022, which is in line with expectations.
Highlights:
Revenues +22% to c. £230m, despite the short-term crisis in the mortgage market which occurred in September.
Organic revenue +10% after adjusting for the acquisition of Fluent Money.
Total number of advisers at year end up by 20% to 2,254 (including advisors at Fluent). No worries about productivity as revenue growing faster than the number of advisors.
We also get some comments on the mess that occurred in Q4, which resulted in recruitment being halted and cutbacks by some of MAB’s member firms (which led to a reduced outlook for 2023).
I think this mess has been cleaned up now. These comments are relevant to many other property-related stocks:
After the Chancellor's Autumn Statement, mortgage rates stabilised and then improved a little towards the year end. The number of mortgages available also started to increase and this trend has strengthened into 2023. Although markets expect further rises in the Bank of England base rate, we expect lending conditions will continue to improve throughout 2023.
Outlook
Current trading is in line with expectations. But there are some useful comments from the company for us to chew on.
Again, I think there is plenty of read-across from here to other property-related stocks and to lenders, as MAB are at the coalface of the mortgage market:
Current activity levels are below the levels seen this time last year. However, towards the very end of this month there have been early signs of increasing lead volumes and written business across the Group, which we anticipate will build steadily as borrowers gain confidence in a more stable macroeconomic and interest rate environment…
Although house purchase transactions will be lower this year, overall we expect a second-half weighted recovery. Re-financing opportunities from MAB's client bank are at a record level for 2023. In the wider market, 1.8 million borrowers' current mortgage deals will expire during 2023, providing further opportunity for MAB.
Mortgage refinancings are, as I understand it, less profitable than new business from first-time buyers. But they should still provide a steady flow of deals for MAB to advise on.
The headcount at MAB’s member firms will fall in Q1 but they expect this to stabilise in Q2 and then “build gradually” in H2.
My view
Again, there is little reason for me to change my view on this stock since I wrote about it last, as there is no change to expectations.
I half-hoped that advisor numbers might have stabilised already in Q1, but an expected stabilisation in Q2 is no bad thing.
Remember that this company employs the franchise model, so it can be mentioned in the same sentence as the likes of Property Franchise (LON:TPFG) and Belvoir (LON:BLV) (even though MAB is not an estate agent).
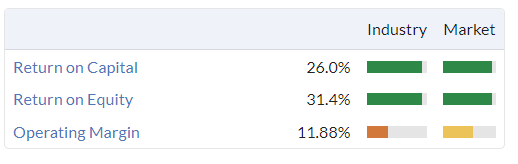
The high-quality characteristics keep me interested here:
Somero Enterprises (LON:SOM)
Share price: 400p (-7%)
Market cap: £223m
We have covered this American company many times, most recently in December.
Let’s see the important points from its full-year trading update for 2022. It is below expectations.
Record revenues $134m (last year: $133.3m, so not much of an improvement year-on-year)
The expectation for revenues was a little higher, at $138.8m. The shortfall reflects “the impact, albeit limited, of supply chain shortages in our North America market on our customers’ pace of work.”
Due to the lower than expected sales, adj. EBITDA is $46m, below guidance of $47.7m.
Year-end cash $34m.
As a reminder, this company makes screeding equipment for the construction industry. The typical bear argument against it says that cyclicality in the construction industry is going to hurt it, sooner or later.
North America: this is Somero’s biggest and most important market by far.
H2 2022 saw “a healthy and active underlying non-residential construction market”, though H2 was weaker than H1 and revenues were slightly lower than 2021. There was “inconsistent availability of concrete nationwide”, due to a shortage of cement and drivers.
These challenges persist in early 2023 though “underlying market conditions” are said to remain positive.
Europe: revenues rose 20% to a record high. It seems like there were fewer logistical difficulties. Also, Somero have shifted their international efforts to Europe and Australia (their Chinese venture, as I anticipated, did not work out as they hoped it would).
Australia: revenues rose 40% from a low base.
China: revenues fell 50% versus 2021 and are now close to zero.
Products: the core product offering remains responsible for the lion’s share of revenues, as revenues from newer products targeting new segments “grew modestly on a combined basis from 2021”, and remained small.
Outlook: confident, though there will be investments and costs in the short-term, in order to grow internationally and develop the new products:
With consideration to these factors, the Board expects 2023 will be a highly profitable year with healthy cash generation, revenues that are comparable to 2022, and EBITDA that reflects the planned investment to add strategic resources for future growth.
My view
I can understand that investors might be feeling some mild frustration here.
Adjusted EBITDA is lower than last year, with only mild revenue growth. And for 2023, not much (if any) revenue growth is expected, and adj. EBITDA is unlikely to make progress, either.
How to value an ex-growth company that makes equipment for a cyclical and volatile industry?
Well, I do consider Somero to be a better-quality company than that description would imply. And management have built up lots of credibility over the years, so I do think we can have some faith in their long-term growth initiatives.
Remember the quality metrics on offer here:

At a single-digit earnings multiple, I do think this stock is looking rather cheap currently, given its undoubted quality.
However, I’ll hold back on taking an outright positive view, since despite management’s credibility, I don’t feel able to predict with any certainty that its growth prospects will materialise. There is a risk that results could stagnate for the time being.
But this is a close call for me. It’s definitely worth continuing to research this one, if you are interested in it and have the time to do so. The prospective dividend yield (9%, according to Stocko) also justifies taking a closer look.
Paul's spreadsheets
(please don't publicise the links, these are intended for Stockopedia subscribers only!) - if you find these interesting, may I suggest bookmarking the links.
SCVR summary to quickly show shares we think are good (green). Also note the ahead exps & profit warning tabs (may not be complete - please let me know of anything I've missed, with a reader comment here).
My 2023 watchlists - I'll do a month end up date of this shortly. It's been a good month, as it has I think been for everyone in small caps!
Podcast mystery shares last weekend were: Best Of The Best (LON:BOTB) (I hold), and hVIVO (LON:HVO) (I hold) - as always, please be sure to DYOR, as I'm frequently wrong!! (because I can't predict the future).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
You have just doubled the life of the CTRL, C and V keys on my keyboard.
Porvair (LON:PRV) Another vote for a look if you get a quiet moment, Paul. I like the exposure to environmental factors and the track record of growth. But I found the outlook statement more cautious than other high quality industrials within my research universe and that, coupled with the lower returns and margin profile, kept me from jumping on the slump in the SP.
(LON:NWF) (I hold) issued a positive set of interim results today for period ended 31 November 2022.
Operating profit was split pretty evenly across the three divisions: Fuels – oil distribution (£2.6m), Food distribution (£2.1m) and Animal feeds (£2.1m).
This translated into £4.6m profit after tax for H1 which, for me, means its well on track to beat year end Stocko estimates of £9.0m.
The fuel and animal feeds business are much stronger in the winter months which is good for FY profits but means there was a £12.6m working capital outflow in H1. Excluding leases NWF still had a period end net cash position, albeit only £1m.
Management explained that £4m of that WC has flowed back in the first 2 months of H2 confirming this is a very cash generative business.
For H1 management reported 28% ROCE which wont harm NWFs strong stock rank ratings.
A key challenge for management has been negotiating volatile commodity prices. I think this makes it difficult to gauge underlying business growth although I was pleased with how management articulated its growth strategy, combining organic growth with industry consolidating acquisitions.
A downside to the share is its wide spread, even though the market cap is over £100m.
In summary, I think this is a well managed, high quality company that’s compounding profit growth nicely.
For those interested management have posted slides from this morning’s analyst/shareholder presentation. This includes analyst forecasts which is handy as there doesn’t seem to be anything posted on Research-Tree recently.
https://www.nwf.co.uk/application/files/3216/7515/6878/NWF_Half_Year_Results_presentation_final.pdf
Tpximpact Holdings (LON:TPX) This was discussed 4 months ago here with very helpful comments from mainlydown, and I commented that I had looked into the background of the new CEO, Bjorn Conway, with the result I put this company on my bargepole list. I am tempted to open a spreadbet account with IG just so I can do the next best thing to going short on this. It seems to me the situation can be summed up in this comment by mainlydown: 'There have been plenty of these types of groups in our market (see Be Heard and The Marketing Group) all of them have seen a similar fate....'
You mention that you might be going to cover Porvair. If you can manage that, this would be great. It seems an interesting company in a good niche. I'm not trying to hurry you. Just hope you haven't forgotten! I hold, but may buy more.
Morning nettle!
Yes, I like Porvair (LON:PRV) - it's always seemed too expensive, but seems to be looking more reasonable now. I did have a quick look at the results, and thought impressive. But the market seems to have taken a negative view of the outlook comments. Probably not urgent to cover today, seeing as we've got so many other things to look at, but I'll do my best to come back to it at some stage (maybe on Friday). But it's likely to be a thumbs up from me, unless I find anything horrible in the numbers/outlook, which is unlikely.
Regards, Paul.
Many thanks for this. You are a brick! And you write as you would talk, so one get some idea of a human-being doing the writing. Not always the case on the net.
on Cambridge Cognition Holdings (LON:COG)
"COG has expertise & decades of key data, in a niche area that would be difficult to replicate. So high barriers to entry, which is proven by the 80% gross margin."
Not so sure. I have read that you can scrape data, rent a neural network in the cloud and train it for a rapidly decreasing amount of money (still a lot but not 10s of millions anymore).
I would put it that this is a relatively new area, and there is a lot of low hanging fruit elsewhere. But unless COG has IP over the best sources of training data(*) , the moat is crossable pretty easily when someone decides they want to.
(*)this is interesting, I think Alamy (one of the larger image libraries) is suing a Co that used images scraped off the internet to train its AI - which included a lot of their images.
I wouldn't strongly disagree with this, but I would slightly disagree.
We've recently seen a lot of progress in training networks off data scraped from the internet (e.g. the recent wave of image generation models - which have been trained on a lot of online artwork, and the GPT-based models - trained off huge amounts of text - ChatGPT being the current popular one).
These have all worked amazingly well because the data they are being trained on is readily available and is either already classified in some way (images with tags and descriptions) or in the case of the large language models doesn't need to be classified as the model is learning the structure of language.
Getting access to high-quality data that has already been classified by an expert - then cleaning and normalising it is still a bit of a problem.
Cambridge Cognition (LON;COG)
I asked Matthew Stork CEO about the issue of IP protection a little while ago. He directed me to their IPO document which I seem to have difficulty attaching here and also the following:
Additionally COG use APIs to send and receive data to their clients. This means that the source code is not provided but a response is sent when a partner sends a request via an API to a service. As in all situations, software and systems are only as good as the people operating them. It is also important to note that the many of the employees of COG are specialised scientists who understand what the data actually means.
I tend to agree & hopefully CANTAB will become the default option in the sector.
You only have to look at the statistical software that is used in academia. SPSS was bought up by IBM years ago and even now has the look & feel of something predating Windows XP.
And yet i's reputation is so firmly established that it rolls on (no doubt spinning off obscene amounts of cash), and you see papers attributing simple statistical analyses to SPSS when you could run them in Excel.....
Once you get a foot in the door as the recognised standard nobody can be bothered to take the risk of straying from the familiar...if you are submitting a paper you just want to tick the box with as little effort as possible.
I really like and enjoy Stockopedia, especially the SCVR section, the ideas, information and exchange of views.
I do think an improvement could be made to the news section where the flow of RNS comes. The format is often different to that of the original RNS meaning it is hard to read a company's results easily or to tell if a large holder has bought/sold shares and what the change is. For clarity, I usually find I need to look at the original. Stockopedia - could you see if you can improve this?
Thanks
Michael
Yes that's a good point - the RNS are more or less unreadable if there is a table involved. Not sure why they need to reformat them. I usually end up going to the LSE to get the original RNS.
The RNS on Stockopedia always contains a link near the top to a printable version. I just cut and paste this into the address bar of a new tab or browser. Quick and foolproof.
Just hold a finger on it and a pop up opens inviting you to open it. Select that and the pdf just appears. Perfect formatting and ready to read.
I can open it but there is no pdf and the formatting is all wrong, especially if there column of figures on it.
If it is formatted correctly, why does it not show on Stockopedia correctly. This started last year, before never had this problem.
Thanks FREng, although I access Stocko via mobile and can't seem to see that option, unless I'm looking in the wrong place.
Michael, I totally agree with you, particularly with the buying and selling of shares it seems an issue. I often have to go to another site such as: https://uk.advfn.com/or https://www.investegate.co.uk/to look at the RNS properly formatted.
I would second the point you are raising, Michael. Although there are ways around the problem of the poor formatting of the RNS-based news section items, as others have kindly explained, ideally the problem would be resolved at source by Stockopedia. I imagine Stockopedia are aware of the problem, but have not been able to find a solution to date. As it is clearly a problem that a number of subscriber have identified, perhaps Paul or Graham would ask the relevent member of the Stockopedia team to provide an update for subscribers on this forum about what is the source of the problem with the unsatisfactory formatting and whether they think a solution can be found in the near term, or alternatively provide confirmation that the problem is too difficult for Stockopedia to resolve at this point.
Thanks Paul and Graham, in advance, if you are able to convey that request to the relevant person within Stockopedia. May I also echo the original poster in saying how much I enjoy SCVR and thank you both for the fantastic work you do in providing such insightful coverage of key news flow and company updates.
Michael - I find the easiest way to open the 'proper' RNS is to left click and highlight the link (that is supposed to be clickable but isn't) and then right click and chose from the menu to open, or in new tab thus:
How would you do that if you don't have a mouse? I use an ipad most of the time.
I eventually found that it is possible to do almost anything on a touchpad that could be done with a mouse. I am on a Windows 11 laptop. I don't even have any buttons at the bottom of my touchpad. The solution for me came when I found out that the bottom section of my touchpad contains two virtual buttons, left & right. I just pretend that the physical buttons are there, and it works, a bit like magic! (The touch pad was always programmed that way. I just had to learn how to use it.)
Sorry but I have an ipad, not touchpad, yes I can get some options to come up on the screen but not any use it seems.
Hello,
Just wanted to let all our news readers know that we have heard the feedback about having to copy and paste the URL link at the top of news announcements in order to open the correctly formatted document. From this, we have made a change to our systems to make this link clickable, so you won’t have to copy and paste it anymore. We’re still looking to improve the news document formatting, but we hope this change will make your life a bit easier for now.
Kind regards
Daniel
Thank you! This makes it so much less hassle to go direct to the source on the PC when required.
Seconded:-)! I usually go to investegate.co.uk if I need to read an RNS highlighted on stocko.
It would be nice if making RNS links easily readable was put into the pipeline of ongoing Stockopedia system improvements.
Yes this has been an issue for some time now, not sure when it started, was it the move to the cloud?
Some are illegible.
And colour highlighting lists of specigic words different colours the same way advfn do. Super useful.
Tpximpact Holdings (LON:TPX) Trading update is absolute mince.
Net debt ballooned to almost £18m. Debt covenants will be breached. Profit forecasts wiped out to zero.
Was watching for a potential turnaround here but it goes straight to the top of the bargepole list.
and yet the directors bought stacks of shares relatively recently in the 40's, very puzzling
Good results FY22 from Gemfields (LON:GEM) Gemfields this morning, £205m market cap, record revenue of $333m (£270m) cash of $104m & $55m due from recent auction, puts this on a low P/E.
Gemfields plc must be one of the most undervalued and ignored listed company in the LSE.
Surely one of these clever fund managers will one day discover this. Dividends will be over 20% and cash will be about the same as it’s market cap in the forthcoming financial year. ( special dividends and any buybacks not included! ).
Where do these figures come from? SP shows the forward dividend yield as 6.59%. Year end cash is 50% of market cap. Strong cash flows should improve these figures, assuming gem sales hold up (always a very volatile area of business, especially going into a recession). Personally I think the valuation looks attractive, but the figures don't look that out of line with the mining sector generally. I don't hold.
Try studying in detail their annual report , and their latest announcements about dividends, special dividends and buybacks.
Thanks
DAZZA64: Thanks for alerting us to Gemfields (LON:GEM) . A "Super Stock" with a StockRank of 96 , a PE of 5 and a 6% dividend is an unusual combination.
I notice that the Earnings Manipulation Risk (Beneish M-Score) is HIGH but on checking the components, GEM passes 7 of the 8 tests and fails just one - its sales growth rate is too high!
Paul, you might like to look at this, even though it's a mining share with a retail arm (Faberge) attached, which is a bit outside your usual territory.
If anyone wants a review on KMK interims , ED have published new note with FV retained at 26p/share. Free access here: https://www.equitydevelopment....
Useful - Thanks. LON:KMK (I hold) looks like it might be turning a corner and forecasts it will finally become profitable this fiscal. . 26p represents a more than doubling in value from the current price.
Strong FY updates from these 2 'picks and shovels' Life Science / software companies. I like the picks and shovels side of Life Sciences as it is not so dependent on drug approval and it is high margin, often with large contracted revenues. Both companies generate their own cash so can pay for their expansion and growth.
Cambridge Connition (LON: COG):
Rev £12.7m £10.1m +25% and ahead of expectations.
Order book up and well positioned post acquisitions in both high growth markets of virtual clinical trials and also voice biomarkers.
Dowgate upgrade FY 23 expectations by 6%
Investegate |Cambridge Cognition Announcements | Cambridge Cognition: Trading Update
Instem (LON:INS)
Impressive organic and inorganic growth at a reasonable price - PE 17
Rev £59m (£46m)+28%
H1 £27.8m so good H2 £31.2m as H1 price increases kick in
Slight miss £60.2 but highlighted already so good overall
Profit in line
More higher margin SaaS
Rec rev £34m +40%
Cash £13.7 ((15m) £5.3 acq costs
Strong order book
Investegate |Instem plc Announcements | Instem plc: Trading Update
I hold.
Hi, Instem (LON:INS)
I am not a holder, just becoming interested. Do you know if there was any indication that Instem was planning on changing auditor (to PK Littlejohn from Grant Thornton ) ....
"In accordance with Section 519 of the Companies Act 2006, the Company's previous auditor, Grant Thornton UK LLP, has deposited with the Company, a statement confirming that there are no circumstances connected with its
resignation which it considers should be brought to the attention of the
Company's members or creditors."
Doesn't really wash. It looks unplanned to me, hence the full year results won't be published until May. I would be keen on knowing this before becoming a holder.
Hi Peter Wyatt
Instem (LON:INS)
I have been invested since 2019. I saw a Progressive presentation by Phil Reason CEO also took the opportunity to speak to Phil one to one afterwards. Phil came across as a genuine, passionate and highly knowledgeable CEO and company man. He has been with Instem for over 20 years. I view him as a man of high integrity which is very important for me. I conducted further research and started investing. To date Instem have always done what they said. I added several times in the days leading up to this update as the SP pulled back and there is considerable growth on offer.
I do not know the reason for the auditor change and I am not concerned, but will ask Phil. Phil Reason owns more than 3% of the share capital of Instem.
Hope this is helpful.
Hi Michael,
Very helpful, Thank you.
My morning smallcap tweet: Priced to fail ratio
Tpximpact Holdings (LON:TPX) Morses Club (LON:MCL) RBG Holdings (LON:RBGP) Cambridge Cognition Holdings (LON:COG) Microlise (LON:SAAS) Filtronic (LON:FTC) Harworth (LON:HWG) Kromek (LON:KMK) Venture Life (LON:VLG) Sigmaroc (LON:SRC) MyCelx Technologies (LON:MYX) LifeSafe Holdings (LON:LIFS) accesso Technology (LON:ACSO) Myhealthchecked (LON:MHC) £TPFP Belvoir (LON:BLV) Somero Enterprises (LON:SOM) NWF (LON:NWF), XLMedia (LON:XLM), Mortgage Advice Bureau (Holdings) (LON:MAB1), Gusbourne (LON:GUS), Northcoders (LON:CODE), Ricardo (LON:RCDO), Instem (LON:INS), Tissue Regenix (LON:TRX), Renewi (LON:RWI)
◄TPXimpact (TPX)► warns Q3-Dec rev below mgmtm exp "reflecting external factors largely outside the Group's control". Likely to breach covenants in March. [SP=45.45 Cap=41m]
◄Morses "it's not a" Club (MCL)► lenders extend term-out clause to March. [SP=0.65 Cap=1m]
◄RBG Holdings (RBGP)► CEO sacked: "The Board has lost confidence". Failed LionFish unit for sale. Trading in line. [SP=66.03 Cap=63m]. I hold.
◄Cambridge Cognition (COG)► guides FY-Dec rev up 25%, ahead of market expectations. Earnings in line. The acquisition of Clinpal did not contribute materially to trading results. [SP=113 Cap=39m]
◄Microlise (SAAS)► guides FY-Dec rev up 5%. Adj EBITDA lightly ahead of market expectations. [SP=120 Cap=139m]
◄Filtronic (FTC)► $2m contract to be booked in calendar 2023. Warns FY23 below market expectations due to component shortages. [SP=12.5 Cap=27m]
◄Harworth (HWG)► guides ERPA NDV towards the lower end of forecatst. Blames "market-driven outward yield movements in the valuation of the Investment Portfolio and more mature industrial & logistics major development sites". [SP=119 Cap=384m]
◄Kromek (KMK)► £2.5m grants for two research programmes to further develop a low-dose molecular breast imaging. [SP=10 Cap=43m]
◄Venture Life (VLG)► guides FY-Dec rev up 34%, slightly ahead of market expectations. Adj EBITDA t least in line. [SP=39.11 Cap=49m]
◄SigmaRoc (SRC)► guides FY-Dec U/L EBITDA and EPS slightly ahead of current market consensus expectations of £99.5m and 7.7p. Outlook confident. [SP=57 Cap=364m]. I hold.
◄MYCELX Technologies (MYX)► guides FY-Dec rev c.$10m and loss c.$4m, above previous guidance due to strong Dec. [SP=33.94 Cap=10m]
◄LifeSafe (LIFS)► guides FY-Dec rev £3.9m, above previous expectation of £3.5-3.8m. EBITDA slightly ahead of market expectations. [SP=40 Cap=9m]
◄accesso Technology (ACSO)► guides FY-Dec rev at least $139m, ahead of its initial full year expectation. Current exp? [SP=808 Cap=335m]
◄MyHealthChecked (MHC)► guides FY-Dec rev up 34%, above management expectations. EBITDA over $2m ($2.7m) - in line? [SP=1.4 Cap=11m]
◄The Property Franchise Group (TPFP)► guides FY-Dec rev up 135. Profit head of market expectations. [SP=NA Cap=NA]
◄Belvoir (BLV)► guides FY-Dec slightly ahead of mgmt expectations but warns FY23 slightly below 2022 and is expected to return to an upward trend in 2024. [SP=189 Cap=70m]. I hold.
◄Somero (SOM)► warns FY-Dec rev $134m, below previous guidance of $ 138.8m. Adj EBITDA c.$46m, below previous guidance of $47.7m [SP=430 Cap=240m]. I hold.
◄NWF (NWF)► H1-Nov rev and operating profit significantly ahead of the prior year and mgmt expectations. Nevertheless guides FY in line. [SP=228.24 Cap=113m]
In line: XLM, MAB1, GUS, CODE, RCDO, INS, TRX, RWI
Surprisingly positive morning for some of my holdings.
Property franchisers Property Franchise (LON:TPFG) and Belvoir (LON:BLV) both update today - the former ahead of expectations and the latter slightly ahead of "management expectations" (which is nice, as long as they expected good results). Both look to be highly resilient to falls in housing sales, due to their lettings business.
Also Wickes (LON:WIX) in line having actually achieved the mythical fourth quarter weighting boost. Core business here continues to look strong despite the undoubted headwinds. And then there's A G Barr (LON:BAG) and the less small cap Pets at Home (LON:PETS) actually raising guidance.
I'm feeling a bit giddy, to be honest, will have to go and lie down.
timarr
The problem for Belvoir (LON:BLV) is where is the growth going to come from over the next 12 months? Potentially from some acquisitions but I can't see much to drive the share price. That's fine if you're taking a 2-3+ year timeframe but it's potentially a missed opportunity to deploy cash more effectively elsewhere.
The problem for Belvoir (LON:BLV) is where is the growth going to come from over the next 12 months?
Well, as you say, it depends on your timescale. Mine is (give or take) five years providing there are no management shenanigans, stupid misapplications of capital or bombshell black swans. Other peoples' will be different as they have different (and hopefully better) judgement than I have.
My personal experience is that most of my short-term buy decisions turn out to be largely random so, for me, the opportunity to "deploy cash more effectively elsewhere" tends to turn into "making less money than I would have if I didn't do anything". I have a very long list of good short term decisions that turned into terrible long term ones.
But everyone needs to find a process that works for themselves, it's the diversity here that keeps it interesting.
timarr
The RBG Holdings (LON:RBGP) board have sacked its CEO - "as a result of cultural concerns and the execution of the Group's strategy" - that was a bolt out of the blue!
Indeed, totally unexpected, I sold first thing. she only just bought tons of shares too, what happens to the 12% of the shares she holds ?
also some vague profit warnings in there i thought
It's become a bit of a bargepole stock now - just one to avoid
Thank you Paul, much appreciated on CNIC. It's back to monitor it for now rather than add to it, balance sheet weakness has caught me out on too many companies when growth stalls.
Slightly dissapointing update from Somero Enterprises (LON:SOM) . Revenues below guidance (134m Vs 138.8). Also, guidance for revenues next year is for revenues similar to this year. International growth was positive, but put's relatively poor performance in US down to supply issues...cement.
At this share price, it still seems good value, but expect it will take a hit today.
Any thoughts appreciated.
Somero
Great company, great products, great profits, low valuation, big dividend .
Macro headwinds cannot hide the above and if you are a trader by all means sell, if you are a long term investor one of the best shares on AIM .
Really nice company.
Agree. I won't be selling. It's a minor miss (very minor) in an environment plagued by an environment with headwinds of all kinds. I also think it's a little unrealistic to expect guidance to be so accurate - they were 3.5% out, with inflation running at 10% and lots of supply variables etc. Result looks sold to me, valuation still looks attractive.
worth holding for the dividend alone, great company
They also communicate honestly - within the first two paragraphs, they've said that it's record revenues, but they fall short of guidance - they haven't hidden that second bit in the small print.
Completely agree. It’s so refreshing to have a candid management who talk straight. Plenty to like when you look past the near term macro uncertainty. Very happy to continue holding personally.
Ripe for a likely takeover.
if anyone wants a chuckle head over to Love Hemp (OFEX:LIFE) and read yesterdays RNS which is a response to ex-MD Philip Smalls slurs (which have been copied to the Love Hemp LSE board for context) Seems a very un-professional RNS but I suppose what can one expect from a shamble company suspended from trading.