Small Cap Value Report (Tue 31 May 2022) - BOO, CAM, XPF, SYME

Good morning! Paul & Jack here with you as usual today.
Day 2 of our 3 day week - I could get used to this! (is that as predictable as neighbours shouting, "Can you do mine as well?!" when washing my car, with a look on their face as if they're the first person to have thought of saying that? Laughing is a social obligation, even though it's not funny).
Agenda -
Missguided (a large competitor to Boohoo (LON:BOO) [I hold]) has called in administrators, according to Sky News. I ponder what this might mean for the fast fashion, and eCommerce sector.
Camellia (LON:CAM) - rather late FY 12/2021 results from this sprawling international group, mainly focused on agricultural production. Modest profits, which nearly all come from part ownership of an associate. Outlook for 2022 is better. Strong balance sheet, but so what, if it generates so little profit? Lots of risks to consider too, so not of interest to me.
XP Factory (LON:XPF) - FY 12/2021 results are out today. Historic figures are of only passing interest, since a recent acquisition of competitive games themed bars is set to transform the original escape rooms concept. Looks potentially interesting, but expensive at this stage, with economics still unproven.
Supply@Me Capital (LON:SYME) - a brief look at this crock is enough to repel me. Based on the facts & figures to date, this looks highly likely to end up at zero. Bargepoles need to be dusted down!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Missguided - sadly for the staff and suppliers, and shareholders, this privately owned fast fashion business has called in administrators, Sky News reported last night here. Thanks to my friend Miles for flagging up the story.
Missguided is a big competitor to Boohoo (LON:BOO) (I hold), and based in the same area - so a competitor for key staff, as well as customers. It traded very well a few years ago, but has struggled against tough competition in recent years. It also appeared shambolically run, when a TV series was made about it - although to some extent, that’s the nature of the sector. Demure it is not -
Several press reports have said that Boohoo (LON:BOO) (I hold) is in talks to buy the brand in a pre-pack administration, which could help sentiment towards BOO shares, taking out a competitor. BOO has obviously a very disappointing share (along with the whole eCommerce sector) over the last year, but is still a formidable business, with many brands.
At this rate, I think a lot of also-ran competition is likely to disappear in the fast fashion space, perhaps leaving just BOO and Shein (unfair Chinese competition, which takes advantage of loopholes to avoid UK tax & regulations).
eCommerce generally has been so battered in the last year, I think there seem to be some obvious bargains there now. So maybe the sector could surprise later in 2022, or 2023, particularly if freight rates begin to moderate? One year’s dog, is quite often the surprise winner the following year. Time will tell.
I think you could see structural growth in online resume this year, once the distortions of the pandemic fully annualise, around now. Demand was undoubtedly pulled through early in 2020, then dropped back in 2021, hence it appeared that growth had stopped. I reckon we could see a return to more normal, long-term structural growth this year. That might surprise the market, and lead to eCommerce shares re-rating upwards. Who knows, it’s only my theory at this stage, but it makes sense to me anyway.
.
Camellia (LON:CAM)
5950p (last night’s close)
Market cap £164m
Normally I avoid all UK listed companies which operate overseas, because so many of them turn out to be dodgy. Why take the risk? However I do make the occasional exception, if such a company has been listed in the UK for a long time, and paid decent divis along the way, then it’s probably OK (e.g. Somero Enterprises (LON:SOM) - I hold). Obviously some countries are less risky than others, you can decide that for yourselves. Mind you, we get plenty of dodgy companies and management in the UK too - but they’re easier to spot, because when you live in a country, you know where to look.
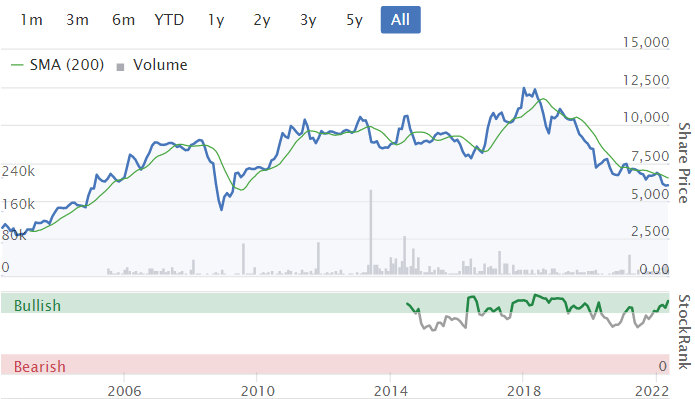
Anyway, Camellia caught my eye here in Dec 2021, when I reviewed it for the first time, and thought it looked potentially interesting - its an agricultural group (growing tea, avocados, etc), with a strong balance sheet, and a good dividend paying track record (although unremarkable yield of 2.4%).
Camellia acquired an English apple grower in mid-2021.
Revenue down 4.8% to £277m
Adj PBT down 45% to £8.8m - note that most of the profit comes from the share of profits in an associate company.
EPS 83.3p (based on unadjusted, statutory EPS) - PER of 71 times - so the market must be expecting future earnings to rise considerably, to justify the current valuation. Although you’ve also got asset backing with this type of share, so PER isn’t everything.
(adjustments are small this year, and look reasonable [relating mainly to non-trading items re acquisitions & disposals], boosting profit by £1.7m, vs ££8.2m boost LY)
Dividends - 102p final divi, making 146p for the year - a yield of 2.5% - OK, but you can get much better divis on other shares, so I wouldn’t say this is a compelling reason to buy/hold Camellia shares, unless you think future earnings & divis might rise substantially? Note that the divis are higher than EPS this year.
Outlook - sounds positive -
2022 has started well with good prices being achieved in the Kenya tea market and a strong opening for India and Bangladesh, albeit early in the season. The remaining crops are developing in line with our expectations for the stage of the growing cycle with volumes ahead of those of 2021. The impact of substantial rises in energy prices and in fertiliser costs is being felt across all our agriculture operations and we expect rising inflation to also lead to further increases in wages.
Overall however, we expect higher profits in the year ahead."
Balance sheet - one of the most complicated I’ve ever seen! Still, assuming all the figures are correct, then it’s very strong - NAV of £437.3m. That includes only £10.1m intangible assets. There’s also a £14.8m pension surplus, which would need looking into, to see if it’s actually a real world deficit, as they often are. There’s also a £8.6m pension deficit, presumably for a different scheme.
Working capital looks very healthy, with current assets of £181m (including £61.8m cash), vs current liabilities of £83.6m, giving a surplus of £97.4m net current assets - this means the group seems strongly financed, and has firepower for acquisitions possibly?
The trouble is, what’s the point in owning all these assets, if the group is only generating a tiny return from them?
My opinion - I’ve lost interest in Camellia, so will stop here. It’s a sprawling, complicated group, with 3 divisions, mainly agriculture, but also engineering & food services. It also owns investment properties, and part-ownership of a profitable associate.
The group is subject to all sorts of risks, including weather - crops failing, erratic selling prices of crops, inflation, legal claims (see note 4 - £16.1m legal expenses last year re litigation in E.African operations), developing country political risks, you name it, the list goes on & on.
So why invest in something so inherently unpredictable?
It’s not for me, as it would be nothing more than a punt. However, I do like the strong balance sheet, and given rising populations & shortages of food, maybe food producers might be a decent place to invest right now?
.
.
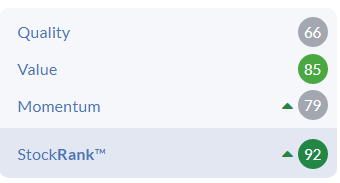
Note the StockRank system likes it -
.
XP Factory (LON:XPF)
26p (up 7% at 09:09)
Market cap £39m
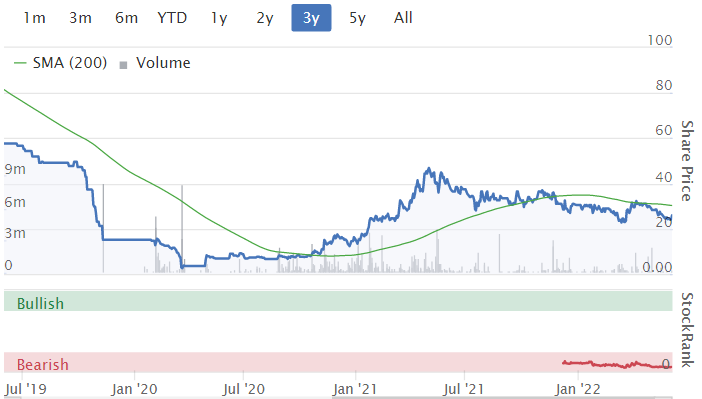
This company used to be called Escape Hunt, it listed in July 2016, as a start-up, developing escape room leisure experiences. Performance was very poor, and the share price collapsed by 90% from c.150p to 15p just before covid struck.
Naturally, escape rooms (people locked into a themed room, in close proximity, solving queues to escape) couldn’t have been a worse concept in a pandemic, and the shares dropped to just 3.5p at the spring 2000 low. They more than 10-bagged in the subsequent bounce.
I lost interest in this share about a year ago, as I couldn’t see anything much in the business model. Taking a fresh look at things today, the business model seems to have improved significantly, so I’ll take a closer look.
A placing at 30p raised £15m (before fees) in Nov 2021, mostly being used to fund the acquisition of Boom Battle Bars. I really like the concept here, it’s mainly franchised bars, with a simple food offering, but the main attraction is competitive games, like axe throwing, pool, shuffleboard, augmented reality darts, karaoke, etc.
Funnily enough Revolution Bars (LON:RBG) (I hold) is also trialling a similar games/drinks/food concept, centred around retro arcade games. I think this is the way to go, because drinking out has now become so expensive, why would anyone pay £6+ for a cocktail, just to sit and talk in a noisy environment? Also, singles feel awkward on their own. Much better to provide some kind of active entertainment via games, to make a night out more exciting, and unique experience, a bit like a night out ten pin bowling. Good for team building corporate customers, birthdays, and general socialising. Plus probably popular with students. There’s one opening soon in Bournemouth, so I’ll mystery shop it & post a video in due course.
Sites are being rolled out, and a franchise model allows more rapid expansion, and without capex needed from the group. Landlords are providing a lot of the capex anyway through reverse premiums, and of course there are many empty sites available, often off-pitch (so cheap), since this format is more of a destination, rather than needing to catch passing trade. So far so good, this looks promising.
Plus it says the Boom Battle Bar sites can be combined with an escape room, so a clear benefit of making the acquisition, to create larger hybrid leisure sites.
Downside risk, as with the escape rooms, is that there’s no moat - anyone can copy the concept very easily.
Trading update - issued on 26 Jan 2022, indicating positive adj EBITDA for H2, ahead of market expectations. Although it’s not clear whether that’s nonsense EBITDA (under IFRS 16), or more sensible EBITDA (pre-IFRS 16)?
Also, a £1.5m cash boost was received for a successful R&D tax credits application.
Boom Battle Bars only contributed about 1 month into the FY 12/2021 results.
Final Results - for FY 12/2021, so of limited use, due to lockdown in early part of 2021, and little contribution from recent acquisition. Plus heavily distorted by Govt support measures.
Revenue £7.0m (up 163%)
Adj EBITDA (pre-IFRS 16) was £0.5m in H2 (I’m happy to ignore H1, as sites would have been closed for most of it)
Equity fundraise of £16.1m (net of expenses), of which £9.9m paid to acquire Boom Battle Bars.
Cash remains healthy, £8.2m at 12/2021, and £6.9m by end April 2022.
XPF has passed the concept stage, and is now rolling out (via franchisees mainly) new sites rapidly. So there’s no point in over-analysing 2021 results. It’s the future that matters. So what we really need to know, is what are the site level economics? This list of points below is helpful, and sounds positive, but since it contains no figures I can’t do any analysis. What I need to know, is how much profit each site is going to make annualised, and what are the franchise fees which flow to XPF ? -

Outlook - this all sounds good, but I have to question whether these concepts (escape rooms & competitive gaming bars) have longevity, or might just be seeing a boom as a fad. Also, competitors are joining in, so before long we could have loads of these themed gaming bars all over the country?
The customer demand we have seen since Covid restrictions were lifted has been overwhelmingly positive and has reinforced our belief that businesses like ours serve an important role in bringing people together. With the Escape Room category becoming much more a part of the mainstream consumer psyche, and with competitive socialising being such a fast growing sub-sector within the leisure market, we feel that XP Factory is perfectly positioned through its operating brands Escape Hunt and Boom respectively.
With such a well-developed pipeline of sites, such encouraging demonstrable unit economics in both brands, and such a well-positioned business in terms of customer demand, we have reason to be highly optimistic about the future for XP Factory."...
With our current pipeline of over 40 potential sites in development, we anticipate having 27 venues trading by the end of 2022, spread across franchise and owned units. We believe that this footprint will enable us to become a pre-eminent player in the industry.
[Paul: it’s not clear whether this relates to just Boom, or Boom + existing escape rooms?]
This is a great time to be expanding, as we’ve also seen for restaurant & bars groups elsewhere -
The opportunity to exploit a property market which has been at its lowest point in a generation has enabled us to secure an enviable pipeline of sites, at materially lower rents than would have been achievable previously, and this, combined with the capital contributions on offer, should allow us to make very strong returns on the capital we employ.
Management don’t seem to have much personal shareholdings, unusual for an early stage company, and experience seems to be more in larger companies, than entrepreneurial.
Balance sheet - NAV is £21.8m, but once £22.0m intangible assets are written off, NTAV is slightly negative at £(0.2)m.
The £8.2m cash pile looks good, but that’s largely offset by current liabilities of £7.3m.
In long-term liabilities, a “Provisions” liability of £9.25m stands out, and note 21 explains this is almost all contingent consideration relating to the Boom acquisition. Although this seems to be payable in up to 25m shares, if targets are achieved, rather than cash.
There are 150.4m shares currently in issue, so we should work on the basis that could be diluted, with 25m more, which is 16.6% potential enlargement of the share count, plus more for share options. So make sure you take that into account in valuation terms.
My opinion - a very interesting concept I reckon, rapidly being rolled out, mainly via franchisees. We need to find out the terms of the franchise deals, and how much recurring revenues XPF is likely to earn from them. The franchise fees in 2021 were negligible.
Also, I don’t see any figures on site economics.
Hence at this stage, the business model is still unclear, and unproven. That said, if franchisees are lining up to open & pay for new sites, then that’s telling us something positive.
Adding in the c.20% dilution from deferred consideration & share options, the market cap is knocking on the door of £50m currently, which seems a lot for a concept that’s only starting to be rolled out, and is easily copied.
So it doesn’t attract me as a value investment. However, as a punt, I think this could be quite interesting, due to the rapid pace of expansion. Definitely one to keep an eye on, so it’s going on my watchlist. What do readers think? I’d love to hear from anyone who’s done more research on it.
I’m motivated to do some more research on it now, whereas in the past it looked a waste of time. There’s an update note from Shore Capital on Research Tree, so that’s my next port of call. Hopefully management will do webinars, so we can learn more about the business, and ask questions.
.
Supply@Me Capital (LON:SYME)
0.07p (down 8% at 11:36)
Market cap £26m
I’ve commented here before on this absolute crock. It’s barely worth wasting any time on it. But just for the record, FY 12/2021 results out today are dire -
Negligible revenue of £0.5m
Adj operating loss of £(4.4)m
Loss before tax of £(12.2)m
Balance sheet as at 31 Dec 2021 looks insolvent to me. NTAV of negative £(1.4)m, includes £7.9m in intangible assets. Write that off, and NTAV is negative £(9.3)m, so the company is dependent on creditors not calling in their debts.
It badly needs an equity refinancing just to survive, let alone prosper.
Looking through the RNS for 2022, a refinancing was announced on 27 April 2022.
It's an equity drawdown type arrangement with Venus Capital SA, providing potential new equity of £7.5m in tranches. I don’t know the detail of this, but we’ve seen similar arrangements in the past being made possible by forward selling shares in the market, hence the term death spiral. So this deal would need to be closely scrutinised. There are billions of warrants issued too.
My opinion - I strongly urge readers to steer clear of this share. It looks absolute rubbish to me, and likely to end up at zero.
An extreme optimist might imagine a successful business might miraculously appear out of nothing. Even if it does, then dilution means existing shareholders are not likely to own much of it.
As an aside, I find it’s worth looking at the advisers who promote this kind of junk, and make sure to always start off highly sceptical about anything else they promote.
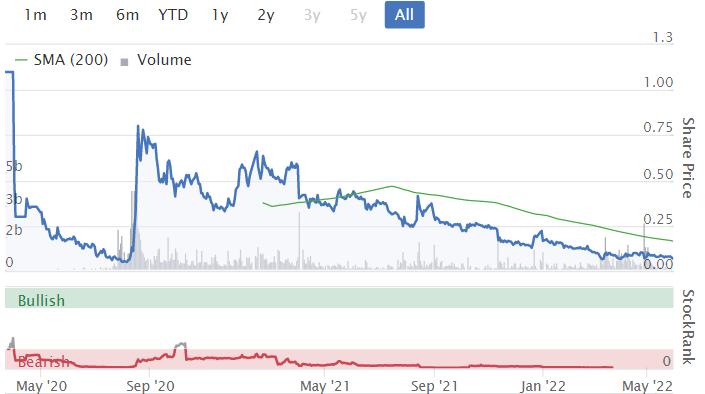
Stockopedia agrees, with a StockRank of a big fat ZERO!
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
@SYME is dreadful.
Everything about it. Even they don't appear to know what they do. Just jargon rich nonsense from the type of directors that just want to blow someone else's money to stroke their own egos.
Is it just me or are the companies featured that usually show up on the right hand side not showing up for others. I’m on iPad Pro.
Thx
Regards
Michael
HI Michael, mine are there, i'm on a mac laptop (catalina)
Not a small cap but couldn't help noticing the big fall in B&M European Value Retail SA (LON:BME) on what looked like reasonable results. Been on my watch list for a while and starting to look very tempting now.
Hi Bouden54,
I agree re B&M European Value Retail SA (LON:BME) - looks very attractive now, as a long-term buy & hold. PER about 10. I skimmed its results & outlook, and looks fine to me. Obviously some macro uncertainty, as you would expect.
The expansion since 2004 has been staggering. Still has further room to expand here, and overseas.
As a value retailer, it could benefit from people trading down right now.
Big thumbs up from me!
Regards, Paul.
I am a holder and I would very much like it everyone sells. I will probably not be able to buy until I get my next salary injection as I do not sell in a buyers market especially as I only buy companies that I would like to own outright. Please sell. Please reduce the price further and give me the opportunity to buy at an awesome price when I get some cash to allocate.
every market is made of buyers and sellers. The demand and supply dictate price.
Knowledge of what you own determines what price you know when something is cheap or something is expensive. This is how you make the market work for you. You determine price.
I own. I want to own more and I very much hope that everyone sells
Re Supply@Me Capital (LON:SYME) , when Paul Scott and Tom Winnifrith both describe a company as a crock on the same day, you know it's one to sell or avoid. I have never held.
Agreed! I held it in 2020 as I got interested in their tech stack, but they never managed to move beyond buzz word bingo and I got out with a small loss. Glad I did without being taught too big a lesson :-).
I was heavily berated by one poster for setting out the SELL case for #SYME back here:
https://www.stockopedia.com/content/small-cap-value-report-tue-16-feb-2021-bwng-nexs-clx-bltg-syme-virgin-wines-763299?order=createdAt&sort=desc&mode=threaded
I cannot for the life of me understand why there are still people out there on twitter etc who say that they are buying more shares!?!?!
The balance sheet is technically insolvent! It has less revenue than my local corner shop! They lost £12.5m last year! And to fund this disaster story they're now on their third death spiral financing.
SYME is the perfect example of why there needs to be better financial education in schools, no one should ever have fallen for this one!
XPF - alcohol and axe throwing - what could possibly go wrong ?
your comment got me thinking about adding to that archers and strongbow.... ;-)
Thanks for the detailed comments on XP Factory (LON:XPF) Paul. One aspect I noted is that the cash flow for the second half of the year (no restrictions on trading) seemed very strong though it was difficult to be sure of this. The central overheads/costs seem high though.
I hold (currently down c20%) so am hoping for a good trading update for H1 2022.
Paul, A very through XP Factory (LON:XPF) analysis, Thanks.
It’s difficult to predict how successful the recent Boom Battle Bar acquisition will be, but I have just averaged their Trip Advisor site ratings which are a creditable 4.3 out of 5. So promising so far.
Here’s an interesting comparison of todays S&P chart v’s 2010’s false H&S top (by Allstar charts). They are very similar. According to the author 4100 is a critical resistance. If held the S&P could rally as in 2010.
I thought it was interesting as it highlights why it is risky to be sitting completely in cash. It’s very hard (impossible) to know when the market is at a low.
The author also says that how to play the current climate varies wildly even within their own company. Some are waiting for more turning signs, some are buying oversold shares. Each to their own. Let’s hope 2010 repeats in 2022.
As Boo has been mentioned today it seems appropriate to mention that a director bought just over £1.1m in Superdry (LON:SDRY) yesterday. I don't hold any but with that size of a buy it is tempting. A few red flags would be the size of it's debts and the fact it has had a few loss making years. This could be a good turn around company and the size of the bod is not something to sniff at.
If by "director" you mean the former founder of £SDRY who has returned as CEO to try to rescue the ship, then yes - a strong vote of confidence.
Albeit he already had £28m+ worth of shares already, and probably a personal net worth much much higher, so what's another £1.1m....
He also bought close to £1m in Oct21 at 262p (vs latest purchase at 142p) so maybe not the best track record for timing.
Back in Jan 2018, it looked like he netted £17.8m from selling shares at 1780p...! So he clearly has some spare cash sloshing around to buy a million here or there.
Not only do I wash my car too, and own a heck of a lot of Boohoo shares - I also dont understand why anyone would pay to go to a gym and pay to have their car washed?! Why not just wash your car - it's a FREE GYM! (and you avoid the dreaded car wash scratches!) - ;-)
Simmsc - you are a bit of a sad git - but in good company!
lol I"m with sad git Simms . I used to PAY to go to the gym at lunch to run on the treadmill.. then I cancelled membership and just ran outside... so much better..... cars need washing? really?
CT Automotive (LON:CTA) full year 2021 analyst presentation & Q&A from last week. They IPO'd in December 2021. They supply interior components (the bits that move: armrests, air vents, cup holders) to the largest automotive manufacturers including Skoda and VW, to premium, Audi and Bently, and EV supplier Lucid. Demand is greater than supply, frustrated by supply chain issues, revenue was up 21% aEBITDA +700%. Gross margin 24.5%. The growth is expected to accelerate as manufacturing volumes recover with an improvement in supply chain issues. They are in line with expectations for full year 2022. Particularly interesting was the insight to the automotive market generally. Video & podcast.
Hi Paul
A rough sketch of the bull case for Camellia (LON:CAM) - I don't hold but I have been wondering.
1 They have been around a long time - as long as I can remember - they must be doing something right just to have survived.
2 A high PER and big discount to NAV are normal for an agricultural business - you have to own the land, so return on capital is always going to be low compared to an industrial business.
3 Owning a lot of land, even in far-flung parts of the world, is a good place to be if inflation is rising.
4 The past decade has not been kind - the share price is about back where it was in 2012. The next decade is going to be, at the very least, less unfavourable. In particular, tea prices have been rising, compared with flat for years.
So, if you are looking for some non-sterling earnings, protection from the inflationary storm which Mr Bailey says is upon us, and the prospect of some sort of turnaround, and are more concerned with a safe, steady yield than with growth, and are looking for alternatives to UK financials, I would have thought it was one to put on the list.
Maybe we should look back in a year's time and see which has prospered more, Boohoo (LON:BOO) or £CAM.
Have you been reading the tea leaves for the rising share price prediction for Camellia (LON:CAM) ? :)
CAM (Camelia) has a subsidiary KAKU (Kakuzi) with a separate listing which I held 2013-15 ish years until it doubled.
https://www.stockopedia.com/sh...
These are colonial relics along with Tiny Rowland's Lonrho, a trading house, now private.
There are other African agricultural stories such as ZAM (Zambeef).
Then there are the modern world developments such as AAF (Airtel Africa) and even VOD. Payments systems for people without bank accounts are the growth story.
On the basis of its asset backing and falling to a price where it makes sense to have an individual holding I have bought some CAM. Previously I only held it through Jupiter UK small caps fund.
Apologies this is probably my lack of understanding whilst working and trying to do this on top.
River and Mercantile (LON:RIV) have dropped and bounced today.
I thought that today was the day they went ex-dividend with the record date tomorrow, or was that last night and they are now ex-dividend?
Thanks
Tommy
RE: River and Mercantile (LON:RIV)
I thought that today was the day they went ex-dividend with the record date tomorrow, or was that last night and they are now ex-dividend?
Technically it's not a dividend, it's a capital return by way of a B share issue. The shares are trading ex-B share entitlement now. Technically the record date is tomorrow so if you sell now you should still get the B shares in a week or so. It takes a few days for the whole thing to sort itself out. The capital return happens first, then the share swap.
RIV is trading at about 62p a share so the total value there at the moment is 62p + 221.38p = 282.38p.
ASTO is trading at about 950p a share so the total value there is 70p + 221.38p = 291.38p (where 70p = 950p * 0.0739).
Doubt you'd get those prices in the market though. So the value is about the same, I'd guess, whichever way you go.
ASTO has fallen significantly in the last few days - it looks like holders selling and switching into RIV. But given the state of the market it's hard to know where this will land post-takeover.
timarr
Thank you Timarr
Apologies for using Dividend rather than B Share issuance.
Tommy
It is nice to hear from a man who washes his car himself even though well able to have it done by another, so it's Cheers from me.
Silver
"competition is likely to disappear in the fast fashion space, perhaps leaving just BOO and Shein (unfair Chinese competition, which takes advantage of loopholes to avoid UK tax & regulations)".
Out of interest, what taxes/regulations is Shein avoiding?
This gives a flavour of Shein's shadowy MO https://www.wired.com/story/fa...
Nice one Paul. I don't even laugh at the car comment anymore..... I noticed on the commute to work, there used to be at least 5-6 Boohoo posters, all replaced by Shein, with boohoo nowhere to be seen. I don't even see boohoo adverts on TV now....
Nano - if I were BooHoo I'd be advertising the other brand names I'd acquired. Boohoo is media dirt at the moment - so focusing on the acquired alternative brands makes more sense. FWIW I just bought some clothes from Debenhams and I am still getting smashed by tracker adverts for Debenhams daily on my phone....
Their other brands aren't the best in all honesty and struggle to see them squeezing any growth out of the likes of Burton, Oasis or Dorothy Perkins!
Fascinating paragraph in Zambeef Products (LON:ZAM) trading update today.
"As announced on 27 April 2022, the Group expects its results for the six-month period ended 31 March 2022 to be released by the end of June 2022. Accordingly, shareholders are advised to exercise caution when dealing in the Company's Securities until the publication of results. The shareholders are further advised that the information contained in this Trading Statement has not been reviewed nor reported on by the external auditors."
Strong results from XP Factory (LON:XPF) though there is a lot of "noise" in the numbers from buying out franchise holders and other corporate activities. Operating cashflow seems very positive along with the outlook.
I would be interested in Paul or Jack analyzing the XP Factory (LON:XPF) results.
XP Factory (LON:XPF)
OK I'll take a look, but pre-warn you I think the business model is a load of rubbish! ;-)
Just shows, initial preconceptions don't always hold true! Section on XP Factory (LON:XPF) now published above, and I think it looks potentially interesting.
Hi Paul, thanks for your write up on XPF. I don't hold, but it would be an interesting company to listen to perhaps, if they appeared on Mello Monday. Should Mello approach them or the other way around or both?
ps more evidence and potential business for BEG and similar businesses with Misguided sadly falling into administration.
ATB DH2.
XPF “I don’t see any figures on site economics”
Information on site economics was published as part of the equity raise to fund the Boom acquisition in November 2021.
https://www.stockopedia.com/sh...
The key takeaway for me is how important the owner operated sites are to the business model versus franchises. They also published a roll out plan in the same announcement. This seems to falling behind schedule for the all important owner operated sites as Edinburgh (due in Q1) is yet to open and there is no opening date for the Oxford St flagship yet (due Q2).
I think management are very capable based on how they brought Escape Hunt to profitability. So, I suspect these delays will only be a short term issue. However, the lack of confirmation around FY22 forecasts suggests to me that the delays could result in guidance being lowered for the year.
Thanks Cuddlesticks, that's tremendously useful!
A 10% revenue share looks a terrific deal for XP Factory (LON:XPF) - probably means franchisees are handing over the bulk of the profits, with no risk to XPF.
That gives me a lot more to go on, thanks again!
Regards, Paul.
Interesting little update from Tern (LON:TERN) (no position myself)
A fund raise for one of their portfolio of investments, FundamentalVR, sees the value of their holding rise from £3.6m to £6.3m. That’s quite an uplift for a tech company in current market conditions.
It may be that the long suffering Tern shareholders will be finally receiving some jam.
def some recent buying here
Have held some Tern (LON:TERN) for about 18 months on the basis they only need one of the companies to do well to get a good return. Its part of my "punt" fund and not certainly something I have as a major holding.
With this one it'll be worth nothing in 5 years time or I'll at least double my money. They have some interesting IP though and it'll be interesting if they can make it viable before selling it and therefore getting a good price for it.
The AGM statement from Tern (LON:TERN) is worth reading if you want insight ito its portfolio. It's a comprehennsive update. (I hold, as of today).