Small Cap Value Report (Tue 31 Oct 2023) - BEG, HEIQ, ELM, UPGS, D4T4, ESYS

Good morning from Paul & Graham!
Today's report is now finished.
Press reports say that the recent demise of Safestyle (double glazing), going into administration recently, has resulted in the administrator making 680 people redundant. A stark reminder that there's a human cost to failed investments. Let's hope they are re-employed if the operating business is sold to a new owner.
Graham's youtube link for today - covering UP Global Sourcing Holdings (LON:UPGS) , IG group (LON:IGG) and Elementis (LON:ELM)
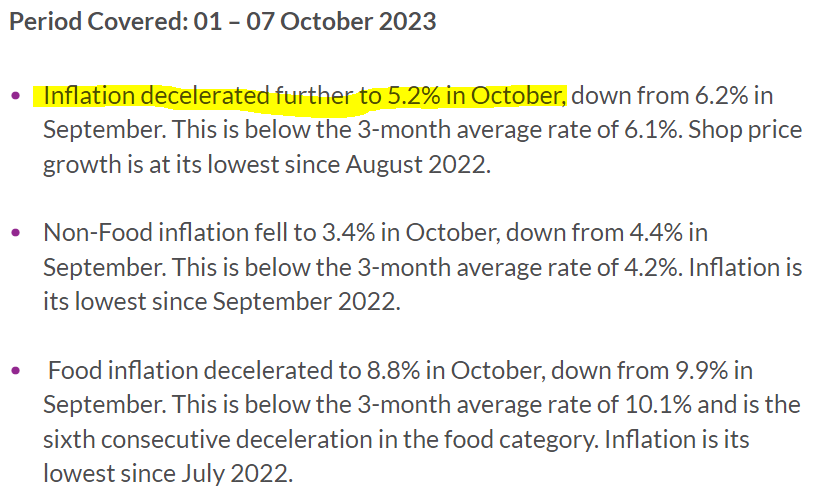
Inflation falling
Some positive-sounding data out today from the British Retail Consortium here, showing a sharp reduction in retail (shop prices) inflation - good news I think (but not sure what expectations were), and remember this is not the official ONS data that includes a wider spectrum of household costs beyond retail -
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Heiq (LON:HEIQ) - down 60% to 8.5p (£12m) - Late accounts published - Paul - RED
Restored from suspension today, after late accounts FY 12/2022 published yesterday, with H1 2023 accounts also filed. Hopeless numbers, with heavy losses. Going concern “material uncertainty”. I recall watching a webinar a while ago from HEIQ which was totally unconvincing, and completely put me off investing, thank goodness. All its grandiose promises have come to nothing. There’s another one imminent on IMC I believe, so maybe that might be a bit better, or failing that, might at least be entertaining? We were RED in Jan 2023, and remain at RED. [no further detail below]
Begbies Traynor (LON:BEG) - Up 1% to 116.7p (£184m) - Q3 Red Flag Report - Paul - AMBER/GREEN
Our quarterly dose of depression, courtesy of Begbies Red Flag Report, which I glance at below. It also seems a good time to review BEG shares, which have fallen recently, despite market conditions for insolvency practitioners improving, with a 25% increase in companies in financial trouble. Shares might be worth a fresh look maybe? Lowish forward PER, but little asset backing is the quick version.
Elementis (LON:ELM) - up 3% to 115.4p (£678m) - Trading update (in line) - Graham - AMBER
This specialty chemicals company has issued an in line trading update. Revenues are flat quarter-on-quarter and down year-on-year. Financial performance has been lacklustre but I’m intrigued by the possibility that we could see a takeover here in the near future.
UP Global Sourcing Holdings (LON:UPGS) (new ticker: ULTP) - up 5% to 120p (£107m) - Results for FY July 2023 (in line) - Graham - GREEN
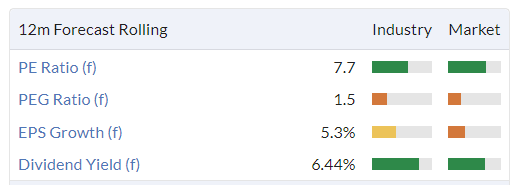
These results are in line with expectations and the outlook for FY July 2024 is also currently in line. At about 8x earnings, with modest debt, I remain positive on this stock. It owns a few decent household brands and seemingly hasn’t put a foot wrong in recent years.
D4t4 Solutions (LON:D4T4) - 155p (£62m) - H1 Trading Update - Paul - AMBER/GREEN
An in line update from this interesting software company, that never quite seems to deliver on its potential, although is habitually (albeit unpredictably) profitable. Plenty of cash, on a safe balance sheet. I like it, and think it could become a bid target maybe? But tough macro could make it difficult to convert the pipeline maybe?
essensys (LON:ESYS) - up 5% to 28.25p (£18m) - FY 7/2023 Results - Paul - RED
essensys plc (AIM:ESYS), the leading global provider of software and technology to the flexible workspace industry, announces its audited results for the financial year ended 31 July 2023.
These are shockingly bad figures. Revenue up 9% to £25.3m, but a huge loss before tax of £(15.5)m (last year also a loss, of £11.1m). Staggering cash burn, with net cash down to £7.9m, from £24.1m a year earlier. The commentary says that it has cut costs, which looks vital for survival to me. So it reckons it can move to positive cashflow next year, FY 7/2025.
Paul’s view - the strategy so far seems to have been reckless in the extreme, re cash burn. Let’s hope management has cut costs deeply enough, and quickly enough, to save it from going bust. We’ll keep an eye on it, and if the facts & figures improve, happy to amend my view on it. [no section below].
Paul's Section:
Begbies Traynor (LON:BEG)
Up 1% to 116.7p (£184m) - Q3 Red Flag Report - Paul - AMBER/GREEN
Many thanks to this listed insolvency practitioners, Begbies for its Q3 Red Flag Alert Report which is out - here.
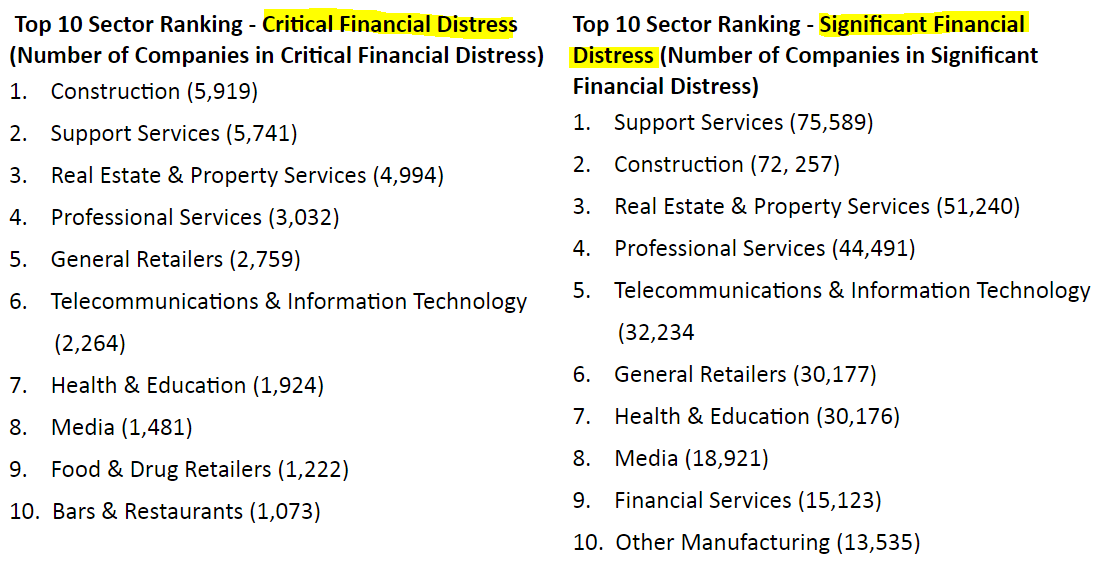
As no doubt we would all expect, financial distress at companies is worsening - up 25%.
It's a freely available, published report, so hopefully they won't mind me copying (with thanks) the top 10 most under pressure sectors, which ties in with the profit warnings we've seen in many small caps -
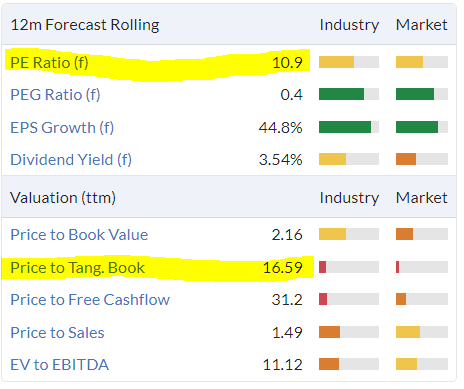
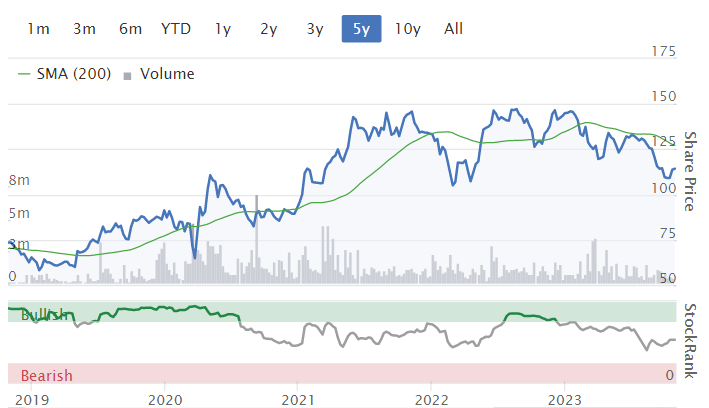
Looking at BEG shares, they've come down somewhat recently, which seems odd considering the macro picture appears to be worsening, due to aggressive interest rate hikes, thus improving the outlook for BEG. Could this be a time to take a fresh look at BEG shares I wonder? The valuation metrics are looking quite appealing again, so I think yes it might be worth a fresh look. Low forward PER of 10.9x. Although note there's no asset-backing to speak of.
As we've also mentioned before, both Graham and I don't particularly like the complicated accounts, with lots of adjustments.
D4t4 Solutions (LON:D4T4)
155p (£62m) - H1 Trading Update - Paul - AMBER/GREEN
D4t4 Solutions Plc (AIM: D4T4, "the Group", the "Company", "D4t4"), the AIM-listed data solutions provider, provides the following trading update for the six months to 30 September 2023.
A reminder that D4T4 is in the process of changing the group name to “Celebrus Technologies”, which is its lead product.
As a reminder, checking our previous notes here -
3/4/2023 - AMBER - down 16% to 190p on a profit warning caused by contract delays. Roland cautious, but Paul more upbeat. A quarter of mkt cap is net cash.
9/8/2023 - AMBER - up 8% to 210p - delayed contract now won. Strong pipeline. Vague outlook. Potentially interesting.
I’ve checked, but cannot see any price-sensitive news since then (unless shareholders are repelled by the new name?!), so I can only guess that the considerable fall in share price to 155p has been due to the general small caps market malaise? Could it be a buying opportunity, I wonder? Or is the price fall sensible caution over sector worries that customers might be less willing to commit to new software spending, which we’ve seen some signs of?
Here’s the latest news in yesterday’s H1 trading update -
This sounds OK, in the context of H1 being traditionally the slower half -
Results1 are expected to be in line with management expectations, with revenues of approximately £13.0 million (H1 FY23: £8.1 million) and adjusted profit before tax2 of approximately £0.2 million (H1 FY23: loss of £1.3 million).
2 Adjusted profit before tax is calculated before amortisation of intangibles, foreign exchange gains/losses, share based payment charges and one-off reorganisation costs.
It’s good when companies are open about unusual factors which benefit results, so I like this bit -
We have made progress as we continue to convert our improving sales pipeline, while the outcome was also assisted by the revenues related to the delays in contract signings at the previous year end, which were signed during this period.
Annualised recurring revenue has only increased a little in H1, from £16.7m at the start, to £17.4m. That’s about 54% of forecast revenues for FY 3/2024 - good, but not enough to make forecasts rock-solid. We’ve seen in the past that D4T4 is still heavily dependent on timing of individual contract wins/renewals for its profit outcome each year. That does introduce risk, and investor nerves, as we hold our breath and hope that the H2 weighting comes through each year as planned, which sometimes it does, and sometimes doesn’t. Hence the erratic profits, even before the pandemic -

Although I’m reassured it remained profitable, even in bad years, and throughout the pandemic, which together with a groaning cash pile, makes this seem erratic, but fundamentally safe, I reckon, if you’re prepared to accept shorter term volatility in performance and share price.
Cash - was £14.7m at Sept 2023, more than enough I’d say. Plus it’s now earning interest on that cash.
The last balance sheet looks fine, with about £17m on NTAV, including a £17.2m cash pile with no debt, so note the £2.5m reduction in cash pile in H1. About £850k cash outflow would be the 2.5p final divi from last year, paid in Aug 2023.
So even if D4T4 hit a poor patch of trading, which we have to consider for many companies in tough macro, there would not be any need for an emergency fundraise, or worries about covenants, etc., due to its healthy net cash position, and favourable working capital cycle (getting paid up front, see the deferred income line on the balance sheet to measure that).
Outlook - it says it has “continued to invest in Sales and Marketing” - does that mean higher spending? Sounds like it. The conclusion is -
These factors provide us with confidence of another year of progress and a full year performance in line with management expectations.
Paul’s opinion - a market cap of £62m (155p) doesn’t seem much for a software company that is always profitable, and seems to have considerable potential, and plenty of cash.
Could it be a bid target, I wonder? Wouldn’t surprise me. The shareholders are mostly well-known institutions, I can’t see any obvious blocking shareholders, like founder mgt, so a takeover deal would probably be easy to agree by a buyer prepared to pay a decent premium.
D4T4 always seems to be on the cusp of great things, but never quite gets there, in terms of stellar growth.
Today’s update isn’t madly exciting, but steady - which is fine by me, in tough macro. It must be hard to convert pipeline into sales right now.
I think AMBER/GREEN (mildly positive) feels about right to me, based on the facts, figures, and forecasts as they are today.
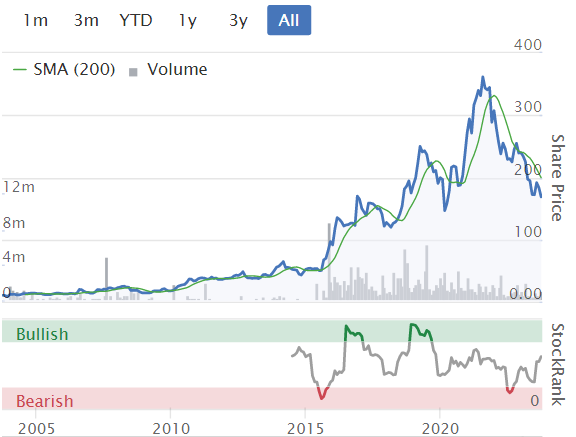
What do chartists think of the long-term chart?
Graham’s Section:
Elementis (LON:ELM)
Share price: 115.4p (+3%)
Market cap: £678m / $824m
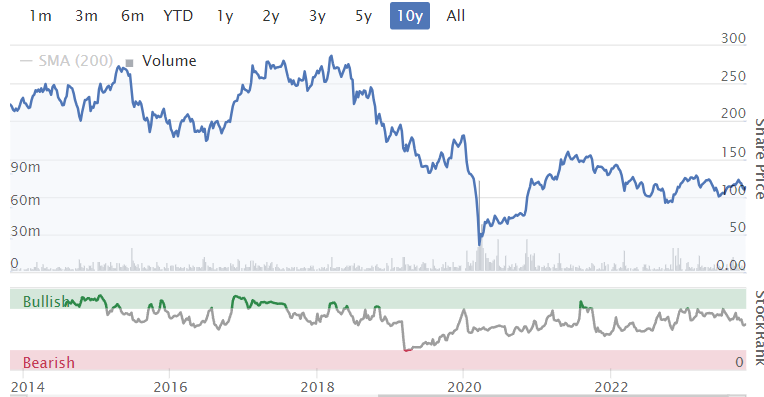
This chemicals company has had a very mixed share price performance in recent times. Profitability has been weak for the past several years:
Today we have a brief in line with expectations trading update for Q3.
Key points:
Q3 revenue is down 7% at constant currencies against last year, but is similar to Q1 and Q2 of the current year.
Personal care: “sequentially stable, but below a strong prior year period”.
Performance specialties: “resilient performance”, with volumes weak but benefits from pricing and product mix.
CEO comment:
Despite the industry and macroeconomic conditions remaining uncertain, we remain well positioned to take advantage of growth opportunities across our market segments.
Unfortunately the financial performance of this large business - expected revenues of $700m+ in the current year - has been lacklustre since demand was hit during the Covid era.
Interim results published in July showed an adjusted operating profit of $53m, but after-tax net income was a much more modest $27m.
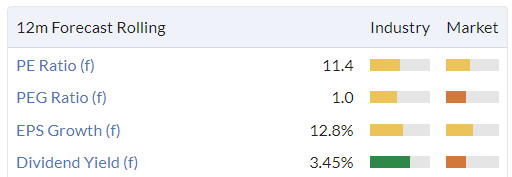
At this valuation, there are signs of possible value creeping in:
However, we also need to bear in mind that the company is carrying about $250m of net debt. So enterprise value (cost of equity plus debt) is $1 billion+.
Investor activism!
US fund managers Franklin Templeton have a 9.8% shareholding in Elementis under their “Small Cap Value” strategy.
Last month, they wrote a letter to the Elementis Chairman, urging him to arrange a sale of the entire company. Among other things, they said:
“the Company's capital allocation decisions have contributed to an extremely disappointing degradation in the share price” - pointing to large acquisitions in 2017 and 2018 which cost more than the current market cap of Elementis.
Return on capital has more than halved and the 17% operating margin target has not been met.
Elementis rejected takeovers at 130p and 160p, with management saying that fair value was 198-225p. But the share price remains far below that range.
In the end, they said:
We believe that the Company is not of a sufficient size to accomplish its targets. We contend it would benefit from being part of a larger organization to achieve economies of scale. The Company's revenue is half that of its next closest peer (and a quarter of the size of the peer median of $3B). However, as noted above, prior attempts to gain scale inorganically have yielded disastrous results.
Under these circumstances, a strategic merger seems necessary and, ultimately, inevitable.
Elementis did not say very much in response:
Our Board does not believe that Franklin's request to initiate an immediate sale of the Company is currently in the best interests of its shareholders given the substantial value still to be realised.
I’m not sure who I agree with: the fund managers are probably right that capital allocation has been poor and that the company should ultimately be sold to a larger peer. But they also seem rather impatient for the share price to go to fair value. A little bit of patience can go a long way.
Graham’s view
I’m tempted to turn positive on this one but I’d like to see a year or two of clean profits, and I’d also like to see more progress on debt reduction.
Of course, by the time that happens, the company might have already given in to a takeover offer. Or the share price might have already gone to where management said was fair value (198-225p).
Specialty chemicals is a sector that has treated many investors very well and maybe this one is worth looking at a bit more closely now, especially if shareholder pressure is making a takeover in the next year or two more likely.
This is also pretty much what I said in April - Elementis is worth a closer look.
UP Global Sourcing Holdings (LON:UPGS)
Share price: 120p (+5%)
Market cap: £107m
Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), announces its audited results for the financial year ended 31 July 2023
I’ve been positive on this one - e.g. last time we covered it here, in August.
Today’s results are in line with expectations.
Revenue +8% to £166m entirely through volume increases (not pricing).
Slight increase in gross margin from 24.9% to 25.7%, “driven by online sales growth and the fall in global shipping rates”.
Adjusted PBT +6% to £16.8m
Actual PBT +4% to £16m
With less than £1m of adjustments, these look like clean numbers to me.
Borrowings - as previously announced (see the July SCVR), net debt finished the financial year at £15m, a nice improvement from £24m at the end of the previous financial year.
Gross debt is £20m and includes a mix of overdraft, term loan and invoice discounting.
Dividend - the total dividend for the year is 7.38p (last year: 7.12p), of which 4.95p is the proposed final dividend.
New Ticker - UP Global Sourcing Holdings plc is no more. From now on, this will be Ultimate Products Plc. The new ticket is ULTP.
Outlook - in line with expectations for FY July 2024.
Net debt is continuing to reduce as the Group de-levers following the transformational Salter acquisition at the end of FY21. In the current environment of higher interest rates, the Group's low net bank debt/adjusted EBITDA ratio, combined with its interest rate hedges, provides both a competitive advantage and growing optionality in the use of free cash flow.
Estimates - with thanks to Equity Development, here are FY July 2024 forecasts:
Revenues +6% to £176.3m
Adjusted EPS unchanged at 15.4p
Reading through the ED report, I see that slower forecast EPS growth in FY 2024/FY 2025 is attributed to higher UK corporation tax and possibly higher taxes in Germany (where ULTP has been focusing recent efforts). Of course most other companies have also faced the headwind of higher corporation tax this year.
Graham’s view
With another update that’s in line with expectations, there is once again little reason to change your prior view on this one. I remain positive on the stock for the same reasons as before - good management track record, modest leverage, and a cheap valuation.
Anecdotally, I’ve just realised that I own a Salter weighing scales! And a very nice one it is, too! The other key owned brand is Beldray and the Russell Hobbs brand (for non-electrical products) remains on licence at Ultimate Products.
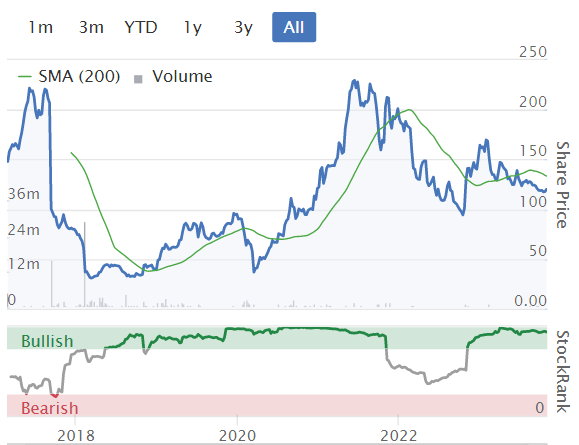
I fail to see what is the catch with this at 8x earnings:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
UPGS/Ultimate Products (LON:ULTP) again. Currently there is a stock report for ULTP (yay!), the discussions section on that page shows UPGS material, that might confuse people new to the company but that is how it is, retrospectively changing the names would be falsifying historical material. Searching for UPGS shows nothing.
If I go to a discussion for UPGS and click on the UPGS link I (after a pause) get the ULTP stock report. It would be tidier if UPGS were searchable, this would require Stockopedia to maintain extra entries for the old names which mapped onto the new names.
SDI (LON:SDI) I sold a modest holding a few weeks ago having watched the CEO in action, who I felt was less than impressive. I now see Pershing Square has popped up on the share register with a 6% + holding which I thought was odd give the type of business Ackman usually invests in and the relative market caps: Pershing Square Holdings (LON:PSH) : £5.61 B and SDI (LON:SDI) £106 m. Even a 100% holding hardly moves the needly on Pershing. I wonder what Ackman is up to?
Not Ackman. Its this https://www.pershing.com/uk/en...
Thanks .... makes more sense
D4t4 Solutions (LON:D4T4)
hi Paul - the business is 2nd half weighted but actually now that it has moved to an ARR model the visibility of full year revenues is actually not erratic. That’s because the contracts renew annually in H2 but are actually multi year contracts (no break clause). So you should now have very good visibility of a baseline annual revenue. Where it can get lumpy is if any large low margin contracts are included in forecasts - if they slip (like last year) you have an effect.
Cash outflow should reverse by year end so that’s 50 - 60p of net cash leaving the business valued at around 10* cash adjusted EPS. Looks far too cheap long term to me. Short term who knows of course given markets but if it stays here I suspect it will attract a bid at a big premium at some point.
D4t4 Solutions (LON:D4T4)
I agree it looks cheap but it would be good to have an understanding of progress with the fraud revenue line. Reading the recent RNSs gives me the impression they are trying just a bit too hard to convince shareholders of progress with the product. It's one thing to mention fraud contract wins of undisclosed value, another to get granular on the numbers. My assumption is that these remain immaterial until such time as the company chooses to segregate revenues for the different lines in its reporting.
Nevertheless, this is certainly the type of business that has been catching a bid of late. A pity that it is somewhat short of liquidity in the event of a blow-up.
Sopheon (LON:SPE) my first Takeover Bid this year.
Small position and I so nearly topped up 3 weeks ago.!
Latest FD to go with immediate effect, this time at Jarvis Securities:
https://www.investegate.co.uk/...
Thanks for posting. Has not moved share price which is at a 12 month low (93p). The announcement of next dividend is due by 09 November at latest. Hopefully the new FD will feel it wise to give shareholders an update to the ongoing skilled person review and current trading.
I feel better now and am hoping the new FD will curtail the CEO's excessive pay increases. Since 100 percent of the dividend is paid from cashflow I had to wonder where the profits were going. I hold.
I note that Zotefoams (LON:ZTF) has fallen back again today after initially rising on the RNS today about the Nike agreement.
When I contacted them today the CFO, Gary McGrath responded back to me. I thought I would share his response as it does indicated trading should be in line and surely too much can't change in a week!
I know SevernCCC previously mentioned they had been in touch to get a date for trading update of of November 7th and I think had a similar response.
Cheers,
Ben
Good work Ben, its a good look that the CFO responded so quickly. Thanks for sharing.
With regard to the Begbies Traynor (LON:BEG) report, it makes horrible reading just the first two lines from Paul's link above:
"There has been a marked increase in the number of businesses in 'critical' financial distress since Q2, up nearly 25% to 37,722 in Q3 2023.
· Almost 480,000 businesses across the UK in 'significant' financial distress, 8.7% higher than Q2 and 4.7% higher than the same period in 2022 (Q3 2022: 456,949)."
My only non expert insight would be how many of these are companies that have been kept afloat by crazy 0% interest policy that should have been exited years ago and the free Covid money that kept them afloat (the few businesses I am now in touch with basically said they did better out of covid than if they had been trading normally).
What I am suggesting is were the "'businesses in 'critical' financial distress'"/@"'significant' financial distress" below what one might normally expect in say 2015 to 2022.
Doesn't make the impact on the economy or employees any less today but at some point a clear out of these financially stretched companies has to happen doesn't it?
Regards
Michael
Finally got around to buying a chunk of Card Factory (LON:CARD) today. Been watching a while and seems to have a floor around 90p with no sellers there despite the overhang so I suspect the big seller is looking for higher. Coincides with 200 day MA so if I am right then as long as it holds then decent results should propel it higher (hopefully). If it goes below 85p then story probably changed so could be a good risk/reward.
expecting divi once the loan is paid off by end Jan too so prob announced May which I think will help.
anyone negative on this one? First buy I’ve made in quite a while so interested in views.
Card Factory (LON:CARD) I think Cockney Rebel has this as 30% of his portfolio.
The spread was large last time i looked.
I have a largish position and am happy to add on weakness. I think it is a compelling investment although of course time will tell.
Card Factory (LON:CARD)
Having watched Richard Crow's interview on Vox markets, the webinar of the recent interims on the the company website and read through the interims, I decided to open a position. No one gets it right every time, but Richard Crow is an astute stock picker and he wouldn't bet the house, well 30% thereof without doing his homework.
I have therefore started to build a position in my ISA, regularly buying smallish amounts on commission free trading that is offered around six times per month by Halifax. The absence of commission makes it cost effective to deal in smallish amounts using dividend income. I have bought 6/7 times between 91p and 96p and at present shall continue to do so.
Good numbers from Georgia Capital (LON:CGEO) Q3 trading update with NAV continuing to perform backed strongly by Bank of Georgia (LON:BGEO) . Interesting to see dividend income is now getting very large and gearing dropping quickly. Exposed to structural infrastructure like hospitals, banks, pharmacies, education and given the population and gdp growth of Georgia these should grow for many years to come.
Trading at 60% discount to NAV I get why the buyback is taking place but I’d also like a dividend from them. I think that would help the ownership register and tighten gap to NAV as much as buybacks personally.
Anyway had been drifting ahead of Q3 update but rebounded nicely this morning. Surprised no comments here.
Sopheon (LON:SPE) looks like a potential offer at £10, more than double current price.
The Bank of England continues with its QT plan. Over £650m bonds maturing in 2030's have been sold today.
Could anyone explain to a thicko like me why they are doing this, at this point in the cycle, and why in particular are they selling longer duration bonds?
Just seems idiotic and very expensive.
Can't explain as I agree - the obvious strategy to me would be not re-issue as bonds mature rather than sell off long term ones at below par.
https://on.ft.com/3Y7JqzD
You could try this ? It sort of says Technically it doesn't matter .... I think .....the dumb answer is Boe is fighting v hard and serious on inflation for fear of a £ crisis. And yes something could break but it hasn't yet...kind of ... excluding Trussgate... which was a tremor more than a break...
Could anyone explain to a thicko like me why they are doing this, at this point in the cycle, and why in particular are they selling longer duration bonds?
Just seems idiotic and very expensive.
The explanation I have heard is that unlike in the US, the UK Government debt is heavily weighted to the longer duration end, so they are not able to shrink the UKs balance sheet as quickly as they would like purely by allowing gilts to mature. I agree that it’s idiotic and the UK Treasury will have to make up the losses incurred somehow.
Yes that sounds plausible simoan, thanks. BoE tend to just follow the US by the looks of things. Amazing this isn't talked about in the media more, considering the cost.
Is it a real loss though ? Hasn’t the Treasury made an equal gain in the process ?
There's a great video on this link RD the b of e made billions during qe they are now losing billions during qt indemnified by the treasury issuing more gilts, I can't see any logic in it other than getting the gilts off b of e's balance sheet so they can maybe load it up again in next round of qe and the chart going to the moon won't look quite as bad.
Your way smarter than me in this investment game interested if you have any further thoughts.
Perfect Phoenix and Dont tell him Pike, thats what I was looking for
I like complicated things simplified. As the CEO in the film Margin Call says "Please, speak as you might to a young child or a golden retriever"
I once embarrassingly (what was I thinking) phoned Radio5 after the financial crash in 2008 because Mervyn King was on. Said I thought QE was a disgrace as it would screw the poorest and hugely benefit the richest. He sort of agreed and said it was only a short term measure during an emergency.
An interesting comment on the youtube video from Ramin when asked who'd be the winners and losers. How ironic if the poorest get screwed with QE then get screwed with QT
"Hi, gilt investors who hold to maturity are the winners as they may get a higher yield. There are other factors that keep yield in check e.g. fear and disinflation (a reduction in the rate of inflation) at the moment which push up bond prices and push down yield. But as bond investors tend to be wealthy people that would increase inequality. And if the indemnity payments trigger austerity that would again hurt the poorest people most. Thanks, Ramin"
No worries Wolf.
I always enjoy your charts and style of prose and thought I would like to offer you something for a change.
Great story re Merv the Swerve (that might have been the large Aussie Cricketeer with the porn tash) actually thinking about it.
Have a great evening gents
"Please, speak as you might to a young child or a golden retriever" .... that made me laugh. 35 years ago, I once made a pitch to a MD at one of our old - now long gone - merchant banks. After I had finished, the MD said "I didn't understand a word of that , but I suspect you didn't either".
Is it a real loss though ? Hasn’t the Treasury made an equal gain in the process ?
Yes. By selling they have crystallised a real loss and because the Treasury has indemnified the Asset Purchase Fund against losses, they will need to find the money down the back of the sofa.
Two ways to make up those losses Si tax rises (unlikely) or err sell more gilts to cover the losses you made on selling gilts, utter madness.
Well, the key assumption you're making when you say "this is idiotic and very expensive" is that long-dated gilt prices are at its lowest and can't keep going lower.
If you had that much conviction that long gilts are at the cheapest price they ever will be... are you backing it up by taking a massive position in long gilts, expecting the prices to go up?
The BoE have a strategy in place (QT) and rather than take a crystal ball view on prices/yields, they're drip feeding their sales over time. Perfectly sensible execution of a strategy IMO.
Who rattled your cage Boon? I was simply asking a question I didnt know the answer to. If you're going to use " " don't just make words up.
?si=ggJ3DEXbwc3f0-00
Hi Wolf,
This video may be helpful. This guy is very knowledgeable regarding bonds and explains things very clearly.
If you or anyone else views it I hope you find it useful.
Many thanks
Sorry Pike I've just done the same link without noticing you had already uploaded doh
No worries Phoenix. Hopefully it will be of some use to others. I look at a lot of his videos and find him a font of knowledge to laymen such as myself. Have a good afternoon.
Thanks Pike , agreed he's got some great video's the "portfolio matters" fellas weekly macro podcast is awesome also if you don't subscribe.
Think the answer is simply that they need financing to pay off thematuring bonds. Normally, Central Banks dont print all the time!!
Thing is though it looks like the bonds in question aren't maturing hence the colossal losses being incurred as they aren't being redeemed at par.
Hi Graham
Thanks for your thoughts on Elementis (LON:ELM) . The company has two prize assets, the only globally viable hectorite mine in Arizona and Talc mines in Finland. Hectorite is the component that provides 'flowability' to paints, cosmetics etc. I increased my holding in the company on the sale of its chromium business that was a drag on performance and management time. It also allowed a significant reduction in debt, albeit it remains on the high side.
I have also bought a holding in Odyssean Investment Trust (LON:OIT) for my daughter's ISA. Lead manager Stuart Widdowson together with Richard Staveley are close associates of the Christopher Mills. Odyssean Investment Trust (LON:OIT) has a significant holding in Elementis (LON:ELM) . It is the Trusts largest holding at 12% of NAV. Odyssean Investment Trust (LON:OIT) have joined Franklin in calling for the company to put itself up for sale.
Elementis (LON:ELM)
Many thanks for the helpful comment Jonno. Best wishes! G
Gear4music (G4M). A Richard Harpin announced a 10% stake. Interested if any views on this out there. Wealthy CEO of Homeserve who could clearly afford to buy Gear. Below the original IPO price, so the founder must be pretty frustrated.
I'm sure the £18 million he banked will help soothe any frustrations
Good thing the CEO at Gear4music (HOLDINGS) (LON:G4M) ignored me, as I told him not to sell any below £10/share. Bull markets eh! :-)
Haha, was this just before he sold Paul? To be fair the market ignored his sale in 2020 at 730p and price topped out 8 months later at £10 so it did hit your target.
Let us hope he can do something Ukjrb57. This has been one of my worst investments but I am hanging on as like the progress being made to improve profitability.
Heiq (LON:HEIQ) just notiing the CEO buys at the start of the year
Interesting, thanks tic_tac_toe.
I wish there was a UK small caps study for what statistical correlation (if any) there is between Director buying & selling, and subsequent share price performance? We've all got our own hunches, but has it ever been properly measured, I wonder?
I asked ChatGPT, but got one of the usual waffly, but clever-sounding replies that sat on the fence, not really saying anything!
From my gut experience, definitely feels like very little correlation between director buys, and subsequent share price performance.
However, I think there is a stronger correlation with Director Sells, and poor SP performance going forwards.
One also has to be careful, as there are some director employment contracts that force directors to buy regularly - and the disclosure of this is sometimes hard to find.
Also it is a question of what is a meaningful amount of a buy for it to be useful for a signal? Plenty of director buys in the thousands, or up to around £50k... but is that really substantial? Especially as some directors make £1m or more? Whereas a director earning say £200k and spending £100k on shares in the open market, that is somewhat of a statement.
Hi Boon
My understanding is that some plcs insist that Directors (and NEDs) hold a certain percentage of their base salary/fee in shares in the business, This can vary up to 100%. Probably more a Governance standard for larger plcs. St James's Place comes to mind as an example though I'd need to search back through the archive to find out what the holding requirement is. Can't believe they are the only ones. AIM companies on the other hand it is probably much lower and varies even more. Perhaps it's just more good practice than requirement.
has it ever been properly measured, I wonder?
This paper is quite old but does specifically address the UK market. You can guess the conclusion from the title "Some Insiders are Indeed Smart Investors"
Abstract
Not all insiders are the same; some are more effective than others in processing the information they have access to, and invest their own wealth accordingly. We used a database with transactions from the U.K. market to identify insiders with superior market timing abilities. For the period 1994 to 2006 we showed that informative insider trades can be identified ex-ante through certain characteristics of the transactions and the firm itself. Moreover we showed how outsiders could benefit from this information. We created a long-only portfolio strategy that generated an economically and statistically significant return. In addition, we showed that the insider transactions signal can be used to construct a satellite strategy that enhances the returns of a typical quant investment portfolio.
That's an interesting question. I've nothing to back it up but I'd say it's depends on previous track record and size. I'm sure Ian Wood was a key reason I bought and sold Wood group years ago. Robert Walters (LON:RWA) buys/sells seem quite well timed, as was Gear4music (HOLDINGS) (LON:G4M) etc
Any sale of £1million I'd probably be following them out the door. SDI (LON:SDI) sales were a big red flag.
Then you have the joke end of the scale like Audioboom (LON:BOOM) director chucking in £9k every couple of weeks. Pointless. He's the Cathy Wood of director buying. Someone buying a token £10k after a profit warning I see as a negative also, shows they aren't in a close period but if they thought it was a great price they'd surely be buying 100k+
There is a study here
https://timhanewich.medium.com...
on the S&P, which seems interesting.
My recollection is that I read somewhere (of course I can't remember where, but I dont think I'm making it up) that there is little correlation betwee sales and price declines (as sales are done for a multitude of reason - house purchase, tax planning, school fees, diversification see Jamie Dimon) but that there is some correlation in the case of purchases.
Regards
Michael
Everyone has the same reason when they buy. There are a variety of reasons to sell, for everyone.
I’d respectfully disagree…many companies formally require directors to acquire equity in certain circumstances eg Games Workshop (LON:GAW)
In other cases post unwelcome news it’s quite common for coordinated waves of director’s purchases to be made…often but not always relatively small…but it’s amazing how often investors view them as meaningful…when they are just presentational.
other purchases are simply new directors saying “thanks for the gig…hope this is enough of a gesture “
but in other cases it’s clearly likely that the director involved thinks the value on offer is compelling….now you just need to know whether they’re good investors….or not.
Not a small cap but Spectris (LON:SXS) may be signalling a small beat for the full year in this morning's Q3 RNS trading statement - top end of adjusted PBT market expectations. Very high quality business on historically low p/e. Compares very favourably with similar companies such as Renishaw (LON:RSW) , Diploma (LON:DPLM) and Smiths (LON:SMIN) .
Another one like Porvair (LON:PRV) in structural growth markets,
I bought a few this morning and will look to add more despite the macro situation if it gets cheaper.
Not a small cap, but interesting update from Spectris (LON:SXS) I think. I worked there during the 08-09 financial crisis and recollect, given customer purchasing is to a good degree linked to discretionary capex budgets, absolutely brutal impacts on orders and sales revenues. Given the talk of recession, and companies potentially tightening their belts merely in anticipation, I'd anticipated some softening. But the statement reads to me to be pretty bullish. It's a diversified business supplying multiple industries, a bit of a not very well known bellwether in my eyes. Probably a better quality business now, so I'd expect more resilience in the performance, but maybe we're going to escape a nasty recession after all.
Spectris (LON:SXS) - great insight from your experience there. The trading statement references softer trading in Asia from stock normalisation but buoyant conditions in the US.
Reference to 'order book visibility', book to bill of 0.97 and talk of further progress in 2024 are reassuring.
Spectris (LON:SXS) - what are the chances of another bid for Oxford Instruments (LON:OXIG? The last one was thwarted by the invasion of Ukraine - or at least that was the excuse. Target is much cheaper today yet has better fundamentals.
Brooks Macdonald (LON:BRK) - Tech investments pave way for staff cuts & margin upside (link to report & audio here: https://www.equitydevelopment....)
Brooks Macdonald has announced it intends to reduce staff complement by 55, around 10% of its workforce of just over 500. It expects to save £4m of costs per year from the changes, but it will incur restructuring costs of up to £3.0m, to be recognised in the current FY24.
We update our forecasts and valuation as a result of these changes, primarily:
While these adjustments offset each other to a degree, the increase in outer-year profits is the dominant driver of valuation and we increase our fundamental valuation from 3,000p per share to 3,050p per share (71% above the current share price). We also maintain our view that the ‘de-rating’ of investment/wealth managers, especially Brooks Macdonald, has been overdone.
On the subject of job losses (ref Safestyle UK (LON:SFE) below) I see that 2 companies in the financial services sector have announced redundancies today:
IG group (LON:IGG) c300 jobs which is 10% of their workforce
Brooks Macdonald (LON:BRK) c55 jobs
I suspect we will see many more of these going forward as things get tougher
To add another sector, the video game industry is also making big cuts. Team17 (LON:TM17) was reported to be axing circa 50 staff (from 300) and many of the large companies are doing so too.
Sorry, on my phone and can’t seem to edit my post - Team17 (LON:TM17) are actually making closer to 90 people redundant.
https://www.eurogamer.net/full...
No it’s odd. On the phone you can’t edit posts, which seems an oversight but if it was I think it would have rectified, as I would have thought only needs a small change to the code.
That said just turned my iPhone 10 into landscape mode the edit button appears and I have been able to add this.
Regards
Muchael
BBC report including Begbies data 38000 UK businesses in critical financial distress https://www.bbc.co.uk/news/bus...
Some companies in the past have made three or more rounds of redundancies before becoming lean enough to find another willing to take them over;-)
My morning smallcap tweet: Tricks or treats?
Barkby (LON:BARK) Velocys (LON:VLS) Zotefoams (LON:ZTF) Kromek (LON:KMK) Brooks Macdonald (LON:BRK) Real Good Food (LON:RGD) Newmark Security (LON:NWT) Esken (LON:ESKN), UP Global Sourcing Holdings (LON:UPGS)
◄Barkby (BARK)► JV with Meadow Partners to acquire and develop a portfolio of UK-based Roadside Real Estate assets funded by up to £100m of equity with an intention to add appropriate levels of leverage. Barkby will initially fund 3%. [SP=5.3 Cap=7m]
◄Velocys (VLS)► re convertibles: "It has become clear that any investment into the Company resulting from these discussions is unlikely to be on the same terms as the previously announced CLN, accordingly there will be no further extension to the CLN longstop date. There are no binding arrangements for funding at this stage". Desperate for cash before YE. [SP=0.97 Cap=16m]
◄Zotefoams (ZTF)► Nike supply extended to the recently launched Nike Ultrafly, the "pinnacle trail racing shoe". A snip at £230. They'll certainly see you coming. Nike did. [SP=277 Cap=135m]
◄Kromek (KMK)► wins three further orders totalling over $1m in the CBRN detection segment. [SP=4.5 Cap=27m]
◄Brooks Macdonald (BRK)► palns c.55 redubndancies saving c.£4m PA. [SP=1770 Cap=291m]
◄Real Good Food (RGD)► AGM stmt: after expected slow start to year it's trading well. H1 rev up 2%. EBITDA loss £0.7m (£2.3m loss). Remain on track to deliver circa £8m of price resets, efficiency gains and cost savings for FY24 with FY EBITDA c.£1m. Must be the 25th turnaround promised. [SP=1.35 Cap=1m]
◄Newmark Security (NWT)► AGM stmt - expects H2 weighting due to the timing of new contracts and orders. It has adequate financial resources in place to deliver on plans.. [SP=48.95 Cap=5m]
◄Esken (ESKN)► re:press speculation regarding sale of Esken Renewables. advanced discussions with Pioneer Point Partners. "The net proceeds would be used to: repay the committed funding drawn under the Group's facilities agreement with the specialty lender and associated costs; further contribute to the Group's defined benefit pension scheme; and provide additional working capital in the short term."
[edit] Sky News says it's £100m inc debt. [SP=2.7 Cap=28m]. I hold.
In line: UPGS
@IGG Is that a heavily concealed profit warning? Talking about continued soft Q2
"Beware the cost cutter " so the saying goes
But funnily in my experience the markets like to see cost-cutting as it reflects the management team taking steps to address costs proactively. We shall see in 5minutes.......
IG group (LON:IGG) I also noted the comment about Q2 continued softness, but at the same time I think that is so predictable that it is entirely factored in by most investors in the sector. I remember when some of the magnificent seven announced staffing cuts earlier in the year their share prices roared higher. Very different comparison to IG I know, but just showing it can be seen as a big positive. It seems the sentiment is balanced this morning with the SP pretty much flat. (I hold)
I don't think the saying applies to the on the day share price reaction....cutting staff is painful and companies do it under duress and normally late, when the damage is done. So it's unlikely that more good news follows .... if investors are waiting for trading top line to improve this isn't a positive...but there are other reasons to own the stock of course.....
Hard to say - could also be the acting CEO wanting to make his mark, or just frustration with the low share price and the hope that this will spark a bit of a rebound.
On the positive side they are still buying back shares on a daily basis.
UP Global Sourcing Holdings (LON:UPGS) - Strong sales growth, sustained profit margins and abundant free cash flow were key features of the (newly named) Ultimate Products FY2023 financial results. Moreover, the company combined significant advances with its brand portfolio with operational efficiency improvements, both in the UK and internationally.
The results confirmed the Company’s 15th August trading update, as sales advanced 8% and the EBITDA and pretax profit measures were £20.2m (+8%) and £16.8m (+6%) respectively. Net bank debt closed the year at £14.8m compared with £24.3m at end FY2022 and was lower earlier in the year. Robust underlying free cash flow is consistent with a proposed 7.4p full year dividend, in line with UP’s 50% pay-out policy.
Profitability benefited from a number of initiatives in FY2023, as well as a focus on continuous improvement. Importantly, last year’s sales growth was not driven by price inflation.
Given the company’s confidence that it will meet expectations in FY2024 and a visible growth trajectory, we reiterate our 250p fair value for the shares. Link to research report: https://www.equitydevelopment....
UP Global Sourcing Holdings (LON:UPGS) - solid results against tougher comparatives. Name change to Ultimate Products makes sense. Fantastic performance from Salter. Other brands struggled a bit except Petra and Kleeneze. Debt reduction is going well. Need to focus on international expansion with the new Paris showroom replacing Cologne (who visits there!). Further brand acquisitions likely now that the Salter debt has been reduced, I suspect. Nice dividend and ROCE as always.
I like the business model here of rejuvenating old brands, often paying virtually nothing for them. Obviously Salter was an exception, but that was a fantastic top tier brand. Also, when some area of the business is not doing well, then another seems to do well to take up the slack. This year it was air fryers and online sales after the overstocking by some retailers and supply disruptions in FY22 resulted in a general sales decline elsewhere.
This is one of my top holdings. I was a bit nervous about the rather late change of auditor, presumably over fees, but they have got the job done with no delays. This is a quality company and founder led. It's undervalued, particularly if it can crack the European market like it has in the UK.
Anyone else any thoughts?
I agree topvest. I've held for a long while (all the way up to £2.20...and down again!) and continue to be impressed by the progress the management team are making in growing revenues in a difficult climate and reducing the debt. They also have a good approach to reducing operating costs through robotic process automation which has been a consistent theme in their updates and seems to be helping drive down costs. They managed COVID superbly and are very straight forward and transparent in their communications.
I continue to believe that the business is worth significantly more (£1.50 plus) but get the sense that people feel it's a boring business - the sort I like! Going to buy a few more as likely the price will drop over the next few days...
UP Global Sourcing Holdings (LON:UPGS) - I like the business too. And own a full-sized position. If I have one criticism it is that the company has stuck to a policy of holding prices down in a market where most have been raising them without significant complaint from customers. Now there are two ways of looking at this.
On the one hand, this is a northern business, where prevails a deeply ingrained culture of delivering the best value to customers. More in Yorkshire than Lancashire, where UP is based, it is true. But you will hear shopkeepers and assistants across the north echo the refrain: "don't buy that one, this one is much cheaper". And of course we cannot ignore that UP caters to the stressed middle and lower economic tiers.
On the other hand, such a strategy speaks of low pricing power, also evident in the relatively low margins for a business with such good returns on capital. This argues against significant multiple expansion, no matter what the house brokers predict.
So I won't get too excited, but a happy holder so far.
UPDATE - just watched Graeme's vid and he makes pretty much the same point, with a little less insight into northern English ways(!!) but with the perhaps more apposite suggestion that the price restraint could be part of a bid to raise sales.
An interesting test for Stockopedia. Currently it cannot provide a price for ULTP as the data provider have presumably not got their act together. However when the name change occurs will all previous mentions/articles of UPGS be updated? If not, much historical info will get orphaned as not everyone will think to search for UPGS as well as ULTP.
Utterly useless:
So try ULTP
NOTHING. Now compare the very pricey Stocko with FREE Investegate:
Still no prices for ULTP.
Green button reply from Alex:
"Hi, Thanks for this. A price is now available. Please see the StockReport (link here).
We may need to refresh the search index. I will speak to the development team about this".
Hi,
Thanks for this.
I followed-up with the development team.
LON:ULTP is now available in the search tool, too.
Best,
Alex
Alex, Thanks. I wish the mcap was £11bn.
Why is all the news history lost on a name change?
UPGS is no longer accessible.
Why is all the news history lost on a name change?
I am generally supportive of Stockopedia but on this issue they have failed dismally. They have known about the inability of their system to link the news history after a name/ticker change of a company for over a year. Although not a regular issue, name changes do occur surprisingly frequently and Stockopedia always fails to update correctly. I can only conclude that not fixing this is a deliberate choice by the company, something that I find extremely disappointing.
Hey,
I appreciate the candid feedback.
I won't go into too much detail, but in terms of the technicalities, the news is lost because it is tagged in the database by a changeable ID, namely the RIC, which changes when the ticker changes...
In the case of LON:ULTP, the RIC was UPGS.L. It is now ULTP.L. The old news is tagged with UPGS.L and the StockReport with the new RIC has no means to access the news tagged with the old RIC.
The proper solution to this is to use an immutable ID - i.e. one that does not change even if the ticker/RIC does change. We have already rolled this solution out with the StockRank histories (see here) and can, of course, implement something similar for news.
I can not promise when this would happen, because there is a long backlog of data issues/product improvements we want to roll out, but I hope the above provides more clarity.
Best,
Alex
Thanks Alex. It's good to hear the cause and solution are known for this problem.
Unfortunately, there are other unresolved issues around a simple name change. I use your figure for volatility 1yr % in my screening. For UPGS it was around 55% for months but currently ULTP shows a staggering and highly unlikely 761%. Of course, this then changes the risk rating from "speculative" to "highly specualtive", a risk rating that I tend to avoid when looking for a new purchase.
Since the StockReport, the StockRanks and your risk ratings are your core product, I am surprised that such obvious anomalies have not been resolved
Hey,
Thanks for this. I feel I need to provide a little more context. We say it is a simple name change, but we have to understand what is happening from the ‘perspective’ of a computer.
In the real world, if I simply change my name from Alex to Alec, people would still recognise me by appearance. Likewise, if a company changes its name from Facebook to Meta, people still know it is still Facebook. This doesn’t necessarily happen in computing...
Software code doesn’t have real world context and computers think in very literal terms (i.e. ‘Yes’ or ‘No’). Either the RIC / ticker is exactly the same, in which case everything runs smoothly, or the ticker is completely different, in which case a new ticker is an entirely separate security. If AAA.L changed to AAB.L then, in the eyes of a computer, that is as significant as AAA.L changing to ZY1.L.
To complicate matters further, different pieces of the puzzle receive knowledge of the ticker change at different times. We use various Refinitiv products to construct our data. If one product thinks the RIC is AAA.L, whereas another product still uses ZY1.L, then you would literally have a situation where some bits of data are present, whereas others are not. Tickers can also be reassigned and recycled between securities, but I won’t get into that.
A lot of this is arguably a flaw of the RIC system. They were never designed to track stock information over time. RICs were first used by the old Quotron machines, which came in during the 1960s. They just gave you the latest price. Users would get a snapshot (price now) and not a time-series (price through time). The (changeable) RIC is unfortunately very much baked into the Refinitiv product offering, whereas constant identifiers are much more peripheral. Indeed, the industry only came up with a solution for identifier changes later, over time, presumably because those problems only become apparent over time. For instance, ISINs often stay the same when a ticker changes, but they were only introduced in 1981, well after RICs, and it took a while for them to be used as an industry standard. But then ISINs change too.
We are grappling with identifier changes and can move away from RICs where possible. Nothing we can not do over time. Just something that needs to be done with surgical precision, alongside various items of work in the backlog.
Alex
Of course you want your own immutable IDs (ISIN would probably do) tying yourself to a data suppliers ID is just making trouble for yourself.
Re Safestyle, yes agreed Paul sadly there’s a human cost to business failure - I recall that well from my days working in business recovery (insolvency) with PW in the 90s.
That said there’s usually a “next thing” for most staff sadly let go - without graveyards there can be no resurrections etc.
Another outcome is customer spend becoming available for Safestore’s competitors such as Eurocell (LON:ECEL). I hold.
Don't think you'll find that Safestyle UK (LON:SFE) was a competitor to Eurocell (LON:ECEL) . Eurocell don't sell double glazing, they supply extruded product to the fabricators to make the frames up so really need people like Safestyle for the construction of the window units, their sale and installation. Their website and AR both worth a look.
Are you sure? https://www.eurocell.co.uk/win...
I stand corrected. Too many years doing their AR when they weren't making. Surprised they've moved into install as they always talk about contracts with fabricators.
Ah actually the windows themselves are made by third party fabricators.
Their business model includes this for the Buildings Plastics division (Branch network): The Building Plastics division sells, through its network of branches, our manufactured foam products and entrance doors, along with a range of third-party related products, as well as windows fabricated by third parties using products manufactured by the Profiles division. Customers are mainly installers, small builders, roofing contractors and independent stockists.
The Eurocell branding in the link you provided seems to position it a little differently though. Not at all confusing! I didn't recall seeing any glass on the premises when we used to visit. I don't think they want to compete with their customers. I certainly thought they were more in the Howden type role as a facilitator and provider to the trade, though you can wander into their branches as a punter.