Small Cap Value Report (Tue 4 Jan 2022) - TAST, DX.

Good morning, and happy new year!
For anyone who missed it, I posted my personal portfolio review of 2021 here. Warts & all. A disastrous Q4 wiped out most of my gains for the year, but at least the figures were still positive overall, so it could have been worse. I definitely need a re-think on my portfolio management, but apart from Boohoo (LON:BOO) (I hold) the stock picking generally went quite well. Here it is again, if you've not already expended 39 minutes of your life listening to me waffling on!
The trouble is, I've always tried to shoot the lights out, in terms of chasing very high annual gains, using gearing, and portfolio concentration, which produces violent moves up & down in my portfolio.
However, my SIPP has been quietly chugging away at a fairly pedestrian +17% p.a. for the last 9 years since inception. Sounds boring, but it's actually compounded to +360% in just 9 years (with no new money added - I started it with a transfer in of existing pension policies). Do that for another decade (or even two), and it would produce a spectacular overall result. So maybe I should forget about gearing, and just go for steady, ungeared, lower risk returns over the long term? That's what the best investors do, after all (stating the obvious!)
Outlook for 2022 - We seem to be entering 2022 with covid reaching a climax in terms of case numbers, but with a mild variant - surely the ideal scenario to achieve herd immunity? The main issue now seems to be staff absences, which should be resolved in weeks rather than months.
US markets are once again hitting daily new highs. Sooner or later, I imagine that bullishness should rub off on UK small caps.
So personally, I'm going into 2022 feeling quite positive about my small cap positions. Providing companies can pass on cost increases to their customers, then business should be good. Supply chains sort themselves out over time, although I have no idea when.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Tasty (LON:TAST)
5.13p (pre market open) - mkt cap £7m
Too small, and very illiquid I’ve found in the past. However, it’s the first casual dining chain to report on Christmas trading, so there’s likely read across for others e.g. Restaurant (LON:RTN) , Fulham Shore (LON:FUL) , and Hostmore (LON:MORE) (I hold).
My summary of the announcement -
- Trading from Jul to Nov 2021 was “extremely encouraging”
- Dec 2021 trading was “disappointing… considerably weaker than anticipated” (normally the best month)
- Covid-related downturn in December - “deterred the larger Christmas bookings”
- 50 restaurants remain open (out of 54)
- 2 or 3 possible disposals
- “Adapted well”, and “navigated its way through” covid, staff shortages, and supply chain issues
- Outlook - challenges: ending of Govt support (reduced VAT, and business rates)
- Confident in brands (Wildwood & dim t)
- “Strong revenue stream” from takeaway & delivery
My opinion - this update seems reasonable in the circumstances. The challenges in Dec 2021 have been widely publicised, are impacting the whole sector, and shouldn’t surprise anyone.
Therefore I see this announcement as neutral, maybe even slightly positive, because the market is meant to look forwards, not dwell on temporary problems. Although that’s clearly not working at the moment! But it should do, in time, when Mr Market (UK small caps) switches from depression to optimism again.
Overall, I’m currently neutral on TAST. I did have a dabble in it when the price was really bombed out a while ago, but decided to exit in stages (difficult to sell) in 2021, as the upside seems quite limited & uncertain now, possibly.
The trouble is that TAST wasn’t performing at all well before the pandemic, so why should it suddenly become a good business in future?
There again, £7m market cap is not much, for a nicely fitted out chain of c.50 restaurants. Especially now deals have been done with landlords on some sites.
We’re not given any actual numbers in today’s update, so there’s not really much to go on.
In this sector, I think MORE (I hold) is the stand-out undervalued option, so I’ll stick with that.
We’re likely to see the 3 larger competitors mentioned above also complain that Dec 2021 trading was disappointing. It will be interesting to see if traders focus on that, or the improving outlook as the pandemic recedes? Or taking a bearish view, will investors worry about the possibility of another mutation causing renewed lockdown restrictions? Who knows? As we’ve seen over the last 21 months, re-opening trades in travel/leisure/hospitality can be unpredictable.
.
Dx (group) (LON:DX.)
30p (shares suspended) - mkt cap £172m
Background - Jack wrote up the FY 6/2021 results here on 8 Nov 2021, from this specialist logistics/delivery group. The figures showed a strong turnaround, back to profitability, after several years of major problems, and losses.
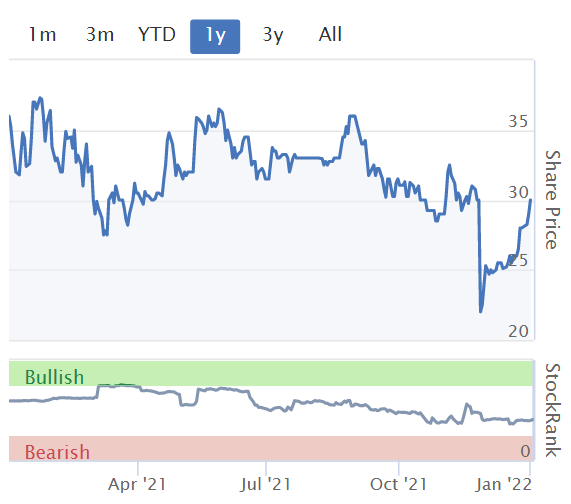
DX dropped a bombshell on 26 Nov 2021, which I covered here. A vague, and badly handled announcement indicated that a “corporate governance inquiry” would delay publication of the Annual Report, and would likely cause suspension of the shares. This hit the share price by c.30%. Although the announcement did say that trading remained in line with expectations.
Directors then bought c.£115k-worth of shares at 18.18p later that day, despite them being the only people who knew what this corporate governance inquiry actually related to! Which seems very wrong to me. According to posts on another bulletin board, Directors were telling people who rang them up, that the issue was nothing to worry about. Again, very wrong, if those bulletin boards comments are true.
It warned on 26 Nov 2021 that the shares were likely to be temporarily suspended on 2 Jan 2022.
Roll forward to today, the first trading day of 2022, and DX shares have indeed been suspended. We still don’t know what this issue is about! This is the latest news -
As detailed in the Company's announcement of 25 November 2021, the Company's Audit & Risk Committee recently raised a corporate governance inquiry relating to an internal investigation, which commenced during the financial year ended 3 July 2021. Whilst the inquiry is progressing steadily, it has yet to be concluded.
As stipulated by Rule 19 of the AIM Rules for Companies (the "AIM Rules"), the Company was required to publish its audited Annual Report by 2 January 2022. As it was not in a position to do so, trading in the Company's Ordinary Shares on AIM will be suspended with effect from 7.30 a.m. on 4 January 2022 pending publication of the Annual Report.
Suspension from trading will be lifted with the publication of the Annual Report.
My opinion - this has been appallingly handled by DX and its advisers, in my view.
However, we can’t ignore the fact that it now looks as if the spike down in share price to 18p appears to have been a buying opportunity, which the Directors took advantage of. We’ll find out for sure once the Annual Report is actually published, which is presumably when the company is going to reveal the facts as to what has happened.
This is all very unsatisfactory, and irregular. Well done to anyone who had the courage to buy the spike down, but for me personally, I’ve been bitten too many times jumping in when irregularities of some kind emerge. Remember Conviviality, and Patisserie Valerie, for example? Although in the case of DX, it doesn’t seem to involve false accounting, because they said trading was in line with expectations - but who believes company assurances, when something iffy seems to have been uncovered?
All of this completely puts me off going near this share, not that I’m interested in freight companies anyway.
The other issue with DX is that, as far as I am aware, it has never split out how much profit is made from the declining private, secure postal service for lawyers. That used to be highly lucrative, but is in structural decline, as legal documents are now often moved online. Do please leave a comment if this split of profitability has been disclosed more recently.
Not for me this one, but good luck to holders.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
£1.5m in a SIPP isn't a maximum amount allowed, more that an excess over £1.5m (your Lifetime Allowance) triggers a tax charge upon certain crystallisation events. After age 75 (!) there are no further charges/limits.
However, turning 75 is a crystallisation event. If I remember correct funds over the lifetime allowance at that point are taxed at 25% as long as taken as income, Or something like that.
timarr
M&c Saatchi (LON:SAA) Very big trades on this after hours @ £2 well above close of 167p.
I see what you mean….that comes in at over 15% of £SAA shares traded @ £2 in this afternoon’s session.
incidentally does anyone know when £scs are likely to update - will it be some time in Jan.
I want to have some cash at the ready
2020- 29th jan
2021- 27th jan
So expect on last weds of jan… 26th
to short it?
Hi Paul. As one ex FD to another my portfolio returns are in the same ballpark as yours and over a similar timeframe but I don't think 17% compounded is pedestrian. However unlike you I have kept away from opening a geared account although been tempted on many occasions. Many thanks for your insight and thoughts over the past 12 months and wish you a prosperous new year. Good luck with your new strategy!!!
Hi trader45,
Thanks for that. As I slept on things, and the generally negative tone of my portfolio review, I woke up this morning thinking a similar thing to you - that my +17% p.a. compounded since 2012 on my SIPP is actually quite good! It's turned £67k into about £310k. And the original £67k came from initial contributions by me of under £20k in the late 1990s.
So if I can achieve the same +17% p.a. for another 9 years, then my SIPP would hit £1.43m, which is within spitting distance of the maximum allowed of £1.5m (I applied to lock in a £1.5m limit with HMRC a few years ago).
Overall that would be a stunning outcome - turning £20k into £1.43m in about 35 years, or a typical working life.
It also shows the value of starting relatively early, and allowing compounding to work its magic, as so many books suggest.
So I'm definitely leaning more now towards taking my foot off the gearing pedal, and focusing on compounding at a reasonable pace, rather than trying to shoot the lights out with 100%'s gains in good years, and near death experiences in bad years.
For anyone who is confused by all this (see the other thread, this is not directed at you, trader45), it's just me baring my soul, and sharing my investing journey with others, which is interesting and stimulates debate. It's my money, so I'll do what I want with it - who says I have to be consistent, or just stick to one strategy? I'll do as I please, and don't see why I should be pigeon-holed into any investing category.
So some of my money is in long-term positions in the SIPP, and some is in an ISA, and some is in real shares, and probably too much is in spread bet accounts. Each to their own. But I've decided to reduce the weighting in the spread bet accounts, as it's creating way too much volatility.
As others have correctly said, and as I said in the video, there are lots of different strategies that people can try out, and find their own way of doing things. That was also the lesson of Free Capital (an excellent book) - that different people have formed their own unique ways of doing things. I'm certainly not pushing any one type of strategy, that's for everyone to decide for themselves.
Regards, Paul.
Spend it now Paul...before the govt forces you to invest it all only in some strategic ESG projects they deign as critical that earn a negative real rate so as they can inflate their debt away whilst creating necessary infrastructure...I'm joking...but only partially...
Hi Paul
£1.5m in a SIPP isn't a maximum amount allowed, more that an excess over £1.5m (your Lifetime Allowance) triggers a tax charge upon certain crystallisation events. After age 75 (!) there are no further charges/limits.
Ian
Hi brads13,
Thanks for clarifying re SIPP.
Regards, Paul.
my +17% p.a. compounded since 2012 on my SIPP is actually quite good! It's turned £67k into about £310k.
Hi Paul, this statement of yours has resulted in a lot of head scratching on this board, me included I wondered if my old brain was getting past it when I was unable to get the answer of £310K purely as an exercise in maths.
My way of working compound interest is: the principal is multiplied by (1+R/100)raised to the power of the number of years. 67000(1.17^9 ) This gives £275,262.82
Working backwards the 9th root of 310/67 = 1.186 so an interest rate of 18.6%
I'm guessing you used some approximation somewhere and you did better than 17%.
Have a great 2022.
Is anyone else having issues with Barclays Smart(hahaha)Investor re non payment of Coral Products (LON:CRU) interim dividend? A final and interim div both went ex div same day 11/11/21 with payments 30/11 and 3/12. Barclays don't seem to know what they are doing and tried to tell me the interim didn't even exist. I've complained of course.
Tell them that you will report the matter to the FCA. Then they will take notice of you and solve your issue as quick as possible.
Regards
Paul, on the issue of gearing. The investors featured in Guy Thomas’ book Free Capital seemed pretty split down the middle on gearing. Some would have nothing to do with gearing, others used some gearing in a measured way, one pushed it quite hard and lived precariously.
I prioritise my ISA and SIPP investments, which are obviously non-geared. But I do keep nearly 30% of my total funds in a SB account, partly to use the gearing, partly for tax reasons.
I am curious as to the proportion of your funds that you place in geared accounts and by how much your geared accounts are actually leveraged?
Hi doug2b,
I am curious as to the proportion of your funds that you place in geared accounts and by how much your geared accounts are actually leveraged?
I'm generally an open book, but there are limits to what I'm prepared to disclose publicly. So I think that level of granularity would be too much, sorry about that.
Regards, Paul.
Hi Paul
I am amazed you are able to sleep at all with the leverage, hedging and resultant volatility you describe.
I make quite enough investing mistakes without the excitement of having them magnified as you describe. Nowadays if any aspect of my admittedly fairly concentrated portfolio is keeping me awake at night, I just sell it down to the extent needed to stop my mind whirring about it all night.
Boredom, at least in this respect, suits me.
Good luck with your less leveraged future approach.
Martin
US markets are once again hitting daily new highs. Sooner or later, I imagine that bullishness should rub off on UK small caps.
Unfortunately it's still the mega caps pulling up the popular indexes. The Russell 2000 "small cap" index is lagging behind.
Yup. Market breadth in the US is horrendous. It seems like all flows are going just to the largest shares...
Somero Enterprises Inc (LON:SOM) Board appointments. CFO stepping up to president (Day to day running of operations etc), This was current CEO'S Jack Cooney's role but he is now focusing on his more high level strategy role. New CFO appointed internally.
I think there are interesting items around this: the new president is an accountant by training and will likely end up taking on the CEO role in the near term, given the CEOs age (73), unless one of the other directors takes on the role. The current CEO's background is in Engineering fwiw.
Looking at all of this change I belive the risk profile is creeping up a bit (unsure if it is skewing to the positive or negative). In that vein does anyone have any idea if any of the management team have any significant holdings? I can't see much evidence of this on the stock report.
I took it as a positive that the whole thing feels planned and appointments have been made internally, to people who've been in place for 3 years which is a decent testing period.
I’m not the biggest fan of CFO’s stepping up to CEO as the mindset shift can be quite tonight. However the stepping stone of President with the current President stepping up solely to CEO looks pretty sensible. The NED appointment looks rather strong .
This is now my biggest holding (almost be stealth) and one I’m happy to continue topping up. No debt, consistent cash generation and a market leading product is very nice.
Somero Enterprises Inc (LON:SOM) I agree. I've been following it since around 2015 and the age of the CEO has been a concern for a while so it's good to see their earlier recruitment paying off.
I suppose there is risk in any transition at this level but I firmly believe that if the product is good enough then it should sell itself. Apple is a great but not very relevant example of this. I only mention it as I was staggered recently when I saw the appreciation in market cap since Tim Cook took over, how many saw that coming I'm not sure.
Back to Som. I listened to the q&a on the Piworld podcast and if I recollect correctly I think around 20% of sales are from new customers with the remaining 80% from existing customers, upgrades, expanding etc. They really value these existing relationships and the focus is on stable supply of replacement parts, training and helping them succeed as businesses. So perhaps a steady hand at the rudder is what is needed controlling operational costs and capex. In my mind that's what a former CFOs skillset comprises of and I've been caught in the crosshairs of a few in my time.
On another potentially opposite and rampy note that I should keep to myself. I think that the screeding machines could benefit from a robotic or AI element. With the aim being that once you get them on a steady supply of wet concrete they finish the job for you. Something like a robo lawnmower. It has been at least a decade since I laid concrete but it sounds feasible to me.
Somero Enterprises Inc (LON:SOM) According to Sharepad, Cooney holds 615k shares (£3.3m) and Yuncza holds 131k (£700k)
Brilliant thanks for that.
dhannaway58156
I don’t feel concerned by these internal moves. You don’t mention the appointment of Anne Ellis as a new NED.
Ms. Ellis brings with her more than three decades of experience as an
engineer, senior business executive and as a Board member with a variety of
organizations. Ms. Ellis is recognized worldwide in the field of concrete for
her work with the American Concrete Institute (ACI) where she served as 90th
president, and with the National Ready Mixed Concrete and the Portland Cement
Association.
FWIW SOM moved from my waiting list to my portfolio this morning.
Yes I'm happy with the various moves as an existing Somero Enterprises Inc (LON:SOM) holder. Given the age of the CEO some succession planning was arguably overdue. The new NED is particularly impressive. https://anneellis.com/
Yes I'm happy with the various moves as an existing Somero Enterprises Inc (LON:SOM) holder. Given the age of the CEO some succession planning was arguably overdue. The new NED is particularly impressive. https://anneellis.com/
Come on AIM wakey wakey it's a new year its a new day
...However, my SIPP has been quietly chugging away at a fairly pedestrian +17% p.a. for the last 9 years since inception...
I've been reading the Terry Smith Book "Investing for Growth" over Christmas, whilst trying to correlate a CAGR figure for his fund over 10 years. Your video and comments over christmas have struck a cord. Here we "investing" hard, and going through the ups and downs of good / bad returns. I never thought I say it but a boring fund which buys good companies, not overpaid and then does nothing, and still makes 15-20% is almost a no brainer......Not as interesting though.
If I did for myself the same thing that I have done for the girls, then I would be a lot better off!
Their JISA's are through Fundsmith, so a monthly payment with occasional lump sums, and whilst I have not done the CAGR, the information that comes with each 6 monthly update gives a return %. And I think within KIDD it gives several years data.
But part of this is mental stimulation, learning, growth, stress, and lots of other emotions. As well as a lot of looking in the rear view mirror and "why did I not" "if only I had" and "well done great choice"
Then again the bulk of my pension is still with Fidelity rather than a SIPP so maybe I am doing this already without realising?
Tommy
Hi FuzzyHaha,
Re Terry Msith's funds -
I never thought I say it but a boring fund which buys good companies, not overpaid and then does nothing, and still makes 15-20% is almost a no brainer......Not as interesting though.
Good point. Although my worry is how much of that rate of return can be sustained long-term? Remember we've seen a serious re-rating of many good quality large caps in recent years. Stuff that used to be on PERs of say 10-15, have since re-rated to maybe 20-40, driven primarily by ultra low interest rates.
Can that be sustained long-term, let alone an even greater increase in PERs for high quality companies? We don't know, but I am a bit wary. If interest rates ever do normalise, then PERs could have a long way to fall for higher quality businesses.
Regards, Paul.
Terry Smith seems to be performing well on a longterm basis I feel.
Terry Smith hasn't really been tested long term. His fund opened post 2008 and as we know the US markets, where he is primarily invested, have done well at his chosen large cap end for the past decade. I haven't done the analysis but as Paul mentions these stocks have re-rated massively on a PE ratio basis in that time so a good chunk of the compound performance is Beta rather than outperformance.
Over the long term any de-rating of PE ratios could hit the portfolio quite hard. Primarily that is because it is a buy and very long term hold strategy so it benefits from overall PE re-ratings and will suffer from a reverse.
That's not to say his approach won't continue to do very well, and indeed it may pass the test of a PE de-rating environment, but that's an unknown as it hasn't happened since the funds were formed. The blip in March 2020 was quite savage for his funds before the big recovery though so that might give us some clues at least.
Overall I am quite positive on his style but it is a risk investors should have eyes open to.
Re Terry Smith, one wonders how much it's that he's been in the right area, rather than because of any amazing stock picking skill. I seem to recall some analysis which showed his fund was basically in line with a US quality/growth factored ETF, very much the area he's invested in.
HI Paul,
The book's been a really interesting read and a bit of an eye opener. Firstly I should say that I don't own any Fundsmith products , but am considering it. In his letter to shareholders Aug 21 the Fundsmith Equity fund has annualised 18.7% return and I think there's only been one year where their annual return was 2-3 %, but still beat MCSI.
https://www.fundsmith.co.uk/me...
His focus is almost solely on ROCE growth, not EPS growth. So for example share buy backs don't improve ROCE, merely EPS. If a board is incentivised by EPS, then share buybacks don't return value to shareholder.
Terry Smith started Fundsmith at the tail end of a very powerful value and commodity cycle in c.2006 (I can't remember when exactly but I met him as he was pitching it). His timing was spectacular. He and his approach is good. But how to normalise for the very long term? I'm not sure but its an issue to be aware of...
Hi Paul, FuzzHaha, TommyH :
Interesting. I guess if one is happy to trust Terry Smith with one's own capital ( I am) but concerned about US mega cap overvaluation (I am), then his investment trust for smaller companies - SSON - would be the way to go. Just over 3 years old, it's just reached a doubling of share price - from £10 to £20 - I make that a 24 % CAGR. I always thought having a smaller ca bias than the Fundsmith Equity OEIC would "let him off the leash" a bit. Granted, as per other posts, a general market rout / higher interest rate environment would sort the wheat from the chaff, but my instinct is that Terry's stuff would eventually prove to be the former in the main.
As an aside, the IT's remit allows investments in companies from £500M to £15 Bn market cap, so I guess not core business for this thread.
All the best
Geoff
Hi Geoff
Yes I hold Smithson Investment Trust (LON:SSON) too as well as Fundsmith. At least one of the two are parts of all the portfolios I manage (now 6 people).
I think the clear one for me is I have been happy in the past, I am happy right now, but at the same time I am not a forever person. I have sold out in the past and probably will again in the future.
Cheers
Tommy
Terry Smith's usual answer to that is along the lines of "If you think these companies are going to be in trouble, then heaven help you if you own the rest".
If that's what Terry Smith really thinks then he's fooling himself. The difference between these companies and the rest is that the rest aren't priced for perfection, with assumed bumper profits in future being discounted back to today at near zero interest rates. To sustain their valuation, they need both the bumper future profits and the near zero interest rates to remain intact.
In an era of unattractive bond yields, many of these companies have become "bond proxies". If rates make a meaningful move upwards, long duration bonds will hurt badly. Bond proxies, which are even longer duration, are likely to hurt worse.
The premium being paid for quality is now higher than at any time in history. I would respectfully suggest to Terry Smith that relative values tend to move in cycles, not one direction for ever.
An interesting perspective, but wouldn’t he argue that he is focused on ROCE, and the compounding effect of these companies reinvesting their profits will drive the share price in the longer term relative to the rest regardless of bond and interest rate market movements? Also, I guess he would argue that these companies are certainly not priced for perfection when he buys them. And there are plenty of growth companies in the USA that are priced for perfection to a much higher degree.
And for me that is a real issue. Investors were prepared to pay for 10 to 15 years profits and now it is 2 to 3 times that. So one of the major reasons for performance has been investors being prepared to wait longer for a return of their money. Completely makes sense in a miniscule interest rate environment. It is just a change of perspective driven by reduced interest rates and an increasing money flow. For all the stock picking in the world the real determinant of success will be how or if this unwinds. I recall explaining to a set of Trustees how we had performed in line with their expectations as the market was down 20% and we were down 18%, so we had indeed out performed the benchmark by 2%. I will always recall the red faced gentleman 3 places to the left of the chair stammering out "that's a fat lot of good"!! He had a point.
Hornby (LON:HRN) (I hold). Shares up 16% this morning on no news. Can anyone shed any light on the possible reason?
Hornby (LON:HRN) Likely as a result of a tip in the Mail on Sunday Midas column at the weekend....
Thanks for that - lots of (mostly) small trading going on today.
17 percent per annum for the last 9 years? Come on, man, you are either fishing for compliments or made a mistake in calculating. A 1000 pound investment then would be worth 360.000 pounds today. You can't be serious. If you are, I'll engage you immediately as my portfolio advisor.
17% per annum for 9 years would turn 1000 into just over 4000 -not 360,000
Correct. 360% compounded over 9 years equates to 15.3% per annum. Not 17% but still not to be sniffed at.
Suggesting that sustained 17% returns are "pedestrian" is odd, however.
Its a giant bull market in small and growth so everyone is a genius (no offence intended...just a statement of fact IMO). We need a sustained bear period to sort the wheat from the chaff and take all the averages down. I might find I'm chaff...the reveal should be exciting though
sorry, not 350000 but 35000. My comment still stands since a 10000 investment then would be worth 350000 today. Hard to believe.
Still wrong
i got up too early. After a cup of coffee, redid my calculations. The result would be 41.000 pounds. Awfully good, netter than I can do. Maybe because you are better at math than I am. Congrats and a happy new year.
Redid your calculations why not let the internet do the heavy lifting? https://www.thecalculatorsite....
Paul said he had about 67K in 2012 and its now over 300k putting the starter figure into the above at 17% p.a. and a period of 9 years brings up a future investment value of 306K.
Definitely still wrong
Why hard to believe? Doesn't seem too far fetched given we've been in a rampant bull market for most of the past 9 years. Many indices (especially in the US) have probably been in excess of this, and my own returns are also in this ballpark (and I wouldn't claim to be the world's best investor!)
dmcarver
"sorry, not 350000 but 35000. My comment still stands since a 10000 investment then would be worth 350000 today. Hard to believe."
You can't be serious. <<<he aint John McEnroe but he is serious :)
There is plenty of bods who have made that sized return consistently over the years - one big issue here is the survivorhsip bias in that there can be big variability here in returns between investors - it just take a few stocks to 5 or 10 bag as big holdings to make ones returns well above the average of the market - that doesnt mean the same person will deliver that return in the future or that they were a great stockpicker they may have just been lucky up to now with some of their larger stakes!
Having followed Paul's writing for nigh on 20 years if he says he has made that return i can vouch for that fact that the his comments will be done from a position of honesty and transparency - you may choose not to belive it but that doesnt mean it hasn't happened - don't disagree with your viewpoint of being slightly skeptical of anyone you don't know perosnally. Hopefully if you follow Paul's writing for a decent period of time you will understand the integrity at play with regard to the comments he posts - just look at the time and effort he has taken today to clarify the position with regard to SCS when really there isn't much need for him to dig so deep ref his perosnal trading.
I think you need to check your maths. You are about 355,000 out
not sure I follow the math here - a present value of £1000 compounding at 17% for 9 years gets me to a future value of £4108.40 What am I missing?
Nothing!
??????
Pleasantly surprised that Tasty (LON:TAST) is in the blue today despite a profit/trading warning. Goes to show either their shares were marked down too much in the last few weeks on omicron fears, or the market sentiment today is very, very bullish and lifting all boats.
Pleasantly surprised that Tasty (LON:TAST) is in the blue today despite a profit/trading warning. Goes to show either their shares were marked down too much in the last few weeks on omicron fears, or the market sentiment today is very, very bullish and lifting all boats.
Paul, I have a query on #SCS please if you don’t mind.
In your video review of 2021 (for which many thanks especially for being so candid about your own stock picking history and performance) did I hear correctly that you have exited from #SCS? I tried to find what you had said again once I had listened until the end but couldn’t find it.
I was quite surprised at this as you were bullish in the SCVR in early December, so I would be interested in hearing what changed your perspective?
Many thanks
Bristolian
Unless you were hearing a diferrent version to me, I thought Paul said he had reduced (but not eliminated ) his Scs (LON:SCS) position, because of worries that their next trading statement would reveal supply chain issues.
Hi Bristolian,
grumpy5 has clarified it correctly - I still hold Scs (LON:SCS) but decided to trim my position size in December. There are several reasons. I'm worried about supply chain problems for the whole sector. There have been recent articles in the press about customers of Sofology (owned by DFS) and ScS waiting a long time for deliveries.
Also, I pondered the ballooning order book at ScS, which suggests that they're not keeping up with demand, hence I am worried that H1 results to 31 Jan 2022 might look weak, since it is deliveries to customers that triggers order book numbers turning into revenues on the P&L.
My main upside worry is that someone might bid for SCS in the meantime, and I miss out on some of the upside from no longer having a large position in it. That said, I can't afford another big hit to my portfolio, after a really bad Q4, so I decided to trim the position size, so that if SCS does issue poor H1 results and the share price drops sharply, then it won't do me too much damage. And of course we can always add to the position size in future, at any time. Positions don't have to be set in stone, and probably like most people, I often add to, or reduce position sizes, whilst remaining invested in the company concerned.
So in a nutshell, I'm bullish long-term on SCS, and I continue to hold. However, I'm worried about the next set of interim numbers, and need to play it safe personally due to having absorbed such large losses holding through profit warnings at Boohoo (LON:BOO) and £JOUL (I hold).
Hope that clarifies.
The other thing to point out, is that the SCVRs are only my view on that particular day, and are always subject to change, even if only on a nuanced level. Sometimes it takes a while for news to sink in, and there's also unconscious bias, in that when we hold a share, we tend to see news as glass half full, but then you talk to other investors and in the subsequent weeks or months, you sometimes wane in enthusiasm, and it depends what the market as a whole is doing too.
Finally, I had a lot of SCS in a geared account, which went onto a humongous margin call in December, so I had to trim lots of positions. Also, I wanted cash to buy more of other things, so something had to be sold. There are various factors involved, as to why I decided to trim back on SCS. Something had to go basically, to meet the margin calls which arose in December.
Regards, Paul.
You have previously said SCS is better investment that DFS, and DFS shot up 6% just before the new year ?
Bit short term perhaps?
Thank you SO much for your explanation regarding #SCS Paul, I completely understand and appreciate your comments. All the best for 2022!
Bristolian
Were the Volex (LON:VLX) acquisitions new ones or just formalising ones that have already been announced?
already announced.
R
The latest Covid data out of South African, estimates that an astonishing 80% of the population have had Covid with the vast majority the Omicron variant. Very few have been hospitalised in the last few months and those are mainly the unvaccinated . Accordingly, the Government here have relaxed curfew restrictions and the feeling is that herd immunity is almost complete and that future Covid variants are unlikely to cause any major disruption.
Suspect it will soon be a similar situation in the U.K. and hence I share your optimism Paul for the share market in 2022.
Don't be so hasty
https://www.dailymail.co.uk/ne...
That's my worry too. The virus continues to mutate and evolve in parts of the world that do not enjoy effective immunisation. There seems to be a general assumption that all variants from now on will be mild, which seems unjustified.
It's summer in South Africa we shouldn't forget - that means more socialising outdoors so I think there's only so much read-across from their situation to us. Judging by how empty London was pre-Christmas I think a lot of people had a self-imposed lockdown of sorts in the run up to Christmas to protect their holidays from disruption, so I think in these next two weeks with schools returning in particular we'll see the proper impact of Omicron.
However, even if some restrictions are brought back I think these will be short-lived and probably targeted mostly at hospitality rather than retail (although will lead to lower footfall at retail) on the basis of how Delta was still declining even with retail open at the end of the last lockdown.
It'll be interesting to see what difference staff absences, and lower footfall in shops(as a result of self-imposed constraints) makes in the post-Christmas trading statements we'll see over the next few weeks.