Small Cap Value Report (Tue 4 July 2023) - HARL, CBOX, KOO, DUKE, KITW, KETL, RST, WINE

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
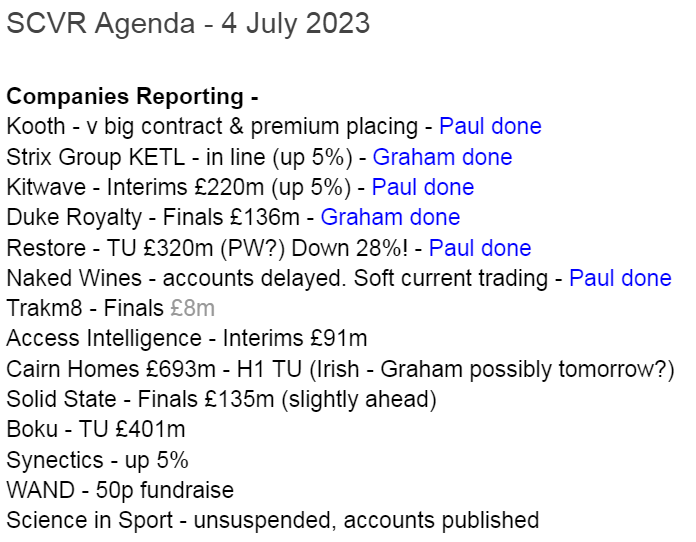
We're concentrating on the price-sensitive announcements first, as usual -
Summaries of main sections
Duke Royalty (LON:DUKE) - up 2% to 33.25p (£139m) - Final Results - Graham - GREEN
I remain positive on this one as I think the discount to book value offers investors some protection against a mishap in the portfolio. The company has performed well despite the economic difficulties of recent years and is worth a fresh look, in my view.
Kitwave (LON:KITW) - Up 4% to 325p (£227m) - Interim Results - Paul - GREEN
I have a good rummage through the interim results, and am impressed that this wholesaler still seems reasonably priced on fundamentals, despite shares being up 69% year to date. Balance sheet & debt aren't the best I've seen, but not a serious concern. Good current trading too. Canaccord ups forecast FY 10/2023 EPS from 25.9p to 29.0p today. EDIT: thanks to Stegga1000000 for flagging in the reader comments that large Director sales totalling £3.3m have just been announced, which is clearly negative for sentiment.
Strix (LON:KETL) - Up 4% to 104.78p (£229m) - AGM Statement - Graham - AMBER
A reassuring “in-line” trading update nudges these shares higher. I am tempted to go green on Strix, especially given management’s insistence that leverage will reduce. The rating is cheap but the deal-making abilities of the company are arguably unproven.
Restore (LON:RST) - Down 30% to 161p (£221m) - Trading Update & Board Changes - Paul - AMBER
The second profit warning this year, from a group whose acquisitions strategy seems to have destroyed shareholder value, and hollowed out its balance sheet. CEO steps down. Today's update guides FY 12/2023 profit down by about a quarter, so disappointing rather than a disaster. Could bid interest that was fought off earlier this year, return maybe?
Naked Wines (LON:WINE) - Down 11% to 88.5p (£65m) - Trading Update (PW) and Board Changes - Paul - RED
The founder CEO returns as Chairman. Reiterates guidance for FY 3/2023, but accounts are delayed - maybe on going concern wording, I speculate? Soft current trading. Revised strategy to attempt to generate more growth. Paul sees a lot of balance sheet risk here, and is very wary, best avoided I think.
Paul's Section:
Quick comments
Harland & Wolff group (LON:HARL)
We discussed Harland & Wolff group (LON:HARL) in the reader comments to yesterday's report, so have a look at this thread for my quick review of the late 2022 results. They're dire, is the short version, so I want to warn people that without an equity fundraise, this looks extremely precarious, and is totally dependent on a large debt facility. Material uncertainty in going concern statement. Very high risk, hence I want to get it into our system as a RED. One for gamblers, not investors, I'd say. The excitement with a previous spike in share price was large orders received by the company. It has ambitious growth plans in renewables, defence contracting, etc, but a very weak capital structure, that's the problem. So great care is needed for anyone considering an equity investment here, as the accounts look very high risk of heavy dilution or insolvency, at this stage.
Cake Box Holdings (LON:CBOX)
After last year’s accounting scandal, you would think Cakebox would be trying to keep its nose clean, and let the dust settle. Unfortunately, The Telegraph reports (and The Times) that the founder CEO is in court, accused of felling 132 trees in woodland in 2021, to make room for a new-build luxury house. Obviously we’ll have to wait until the judgement from the Court, but it’s not a good look to have a “criminal prosecution” underway for environmental vandalism - social media can quickly turn on companies & Directors that get embroiled in this kind of thing. So this puts another question mark over the behaviour of the founder/company.
Kooth (LON:KOO)
261p (pre-market) (£86m) - Placing, Contract Win, and Trading Update - Paul - GREEN
Kooth is focused on an app to help people (especially children) with mental health
Proposed placing - to raise £10m - at 300p - a 15% premium - very impressive!
Net proceeds to accelerate platform development and invest in US growth, as part of its international expansion strategy…
The Company expects to deploy c.£5m of the net proceeds of the Placing towards accelerating platform development and c.£4.5m towards investing in US growth as part of the Group's growth strategy.
Contract win - $188m over 4 years, contract in California.
Material upgrade to 2023 revenue guidance
Four-year contract to serve all 6 million 13-25 year olds in California
This California contract has been on the cards for some time, so it will be interesting to see how the market reacts, ie how much upside is already in the price? The 300p placing (15% premium) suggests to me that investors are excited about this deal, so we’re highly likely to see a big uplift in share price today, probably above 300p would be my guess (writing this at 07:36). That’s why I’m focusing on this company first thing today.
Other details -
The service will launch in Jan 2024
Revenues for FY 12/2023 “material upgrade” to at least £34m (up 69% on 2022)
“Highly material” benefit to revenues from new contract in FY 12/2024.
Timing of revenue is linked to usage, promotional activity, and product development. So it sounds as if we can’t necessarily take the $188m and divide it by 4 years. Presumably it’s likely to build gradually?
Hiring 200 staff in next 12 months to build US infrastructure - some execution risk here?
Future potential - this is likely to get investors excited, I think -
This is Kooth's second significant contract in the US, following the announcement of a pilot contract with the State of Pennsylvania in September 2022.
Kooth has identified additional opportunities in the US, a key market for future growth, underlining the scale of opportunity in the world's largest health care market and the Group's ability to localise its services internationally.
Paul’s opinion - really impressive stuff, this is exciting I think! How to value the company? Absolutely no idea at this stage. This looks like a situation where the newsflow is so impressive, we could see a big speculative surge in share price here. With nobody really asking questions about future profitability, for now, that comes later. Raising £10m to spend on expansion, means it’s clearly going to be loss-making and cash-burning as it expands. Maybe 300-400p share price in the short term? We’ll soon find out. Could be worth a speculative buy on the opening bell!
Kitwave (LON:KITW)
Up 4% to 325p (£227m) - Interim Results - Paul - GREEN
Kitwave Group plc (AIM: KITW), the delivered wholesale business, is pleased to announce its unaudited interim results for the six months ended 30 April 2023 ("the period" or "H1 2023").
For background, we reported positively on KITW twice this year so far -
28 Feb 2023 - 235p - superb results 10/2022. Reasonable price. Thumbs up - GREEN.
2 May 2023 - 271p - H1 TU slightly ahead. Paul likes it as a GARP share. GREEN.
We’re now at a share price of 325p, a hefty increase of 69% YTD - well done to holders! Is that rise justified, or is it time to start banking some profit?
Some H1 figures -
Revenue up 23% to £275m
Gross margin is low (as I would expect for a wholesaler), but improved, at 21.6% (H1 LY: 19.8%)
Profit before tax up 48% to £8.3m
Seasonality - there seems to be a strong H2 weighting to profit (H1 £5.6m, H2 £12.2m last year (LY), so bear that in mind.
Due to the seasonal nature of the wholesale business trading is weighted to the second half of the financial year. We remain confident that the positive momentum seen in the first six months will continue throughout 2023.
Current trading - this is positive -
Trading since the period end has been strong across all divisions and ahead of Board expectations at the time of the trading update released in May 2023. The Board anticipates that the Group's results for the full financial year will therefore be ahead of market expectations that were established at the start of the financial year.
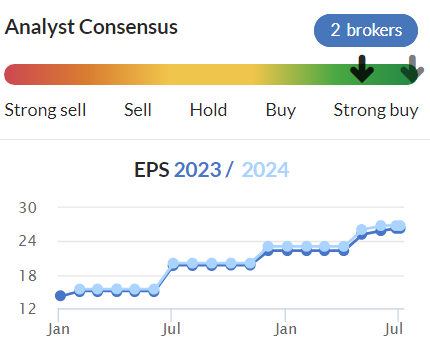
As you can see below, there’s been a considerable increase in forecasts, in stages, over the last 18 months -
Some of this is due to acquisitions, so I’d like to see the split between organic, and acquired profit growth.
Broker upgrade - Canaccord (many thanks!) has today upped its forecast from 25.9p to 29.0p for FY 10/2023.
KITW doesn’t seem to provide adjusted profit numbers, so is absorbing the goodwill amortisation. This doesn’t sound much though, stated as £0.4m in the commentary.
Debt - it is borrowing to fund some of the acquisitions, but this doesn’t sound excessive -
The increase in debt of £20.0 million since the year-end 31 October 2022 relates to the net cash outflow from the acquisition. Leverage has increased to 1.9x since the year end and interest costs have increased accordingly. It is expected that the strong continued cash generation nature of the Group will drive the principal debt down during the remainder of the current financial year. The Board is committed to maintaining a prudent leverage policy moving forward.
Inflation - I’m impressed that KITW has clearly succeeded in passing on inflationary costs to customers, and these comments are encouraging too -
The Group's cost base has been affected by inflationary pressures, with the majority of increases being reflected in labour and delivery-based costs. We are continually striving to mitigate such cost increases and as a result, the ratio of distribution costs to revenue is only slightly ahead of the prior period. It is expected that these cost pressure increases will ease over time, as we anticipate lower levels of fuel pricing and lower wage inflation compared to the last 18 months.
Dividends - it’s quite a juggling act to combine acquisitions and paying divis, but KITW is managing to do that. Stockopedia shows the forecast yield at around 3.5%, and today’s interim divi is consistent with that.
EPS - diluted H1 EPS is 8.7p. Allowing for the H2-weighting to profits, that seems to me we can probably expect about 25p full year EPS for FY 10/2023. Stockopedia shows 26.3p consensus, and KITW says today that it’s trading ahead, so maybe about 28-30p could be the right level to use for basing our valuation of the shares? That's consistent with Canaccord's latest 29p forecast, I like to sense check forecasts.
Hence at 325p per share, I make that a PER of between 10.8x and 11.6x, which seems perfectly reasonable, providing that level of profitability is sustainable.
Balance sheet - it’s acquisitive, so goodwill & similar are rising, now totaling £64m. If I deduct that from NAV of £74m, we only have £10m NTAV, so not much asset-backing to support the share price if trading were to deteriorate.
Gross bank debt is £37m, slightly offset with £3m of cash, so net borrowings of £34m. The £64m quoted in the commentary includes £30m of lease liabilities, which I ignore for the purposes of net bank debt.
The main financing for the business (as I would expect) is provided by its suppliers - trade creditors are £78m. That’s fine, providing the trade credit insurers are happy to maintain cover on KITW. I can’t see any reason why they would withdraw cover, so nothing to worry about there.
Overall then, the balance sheet is OK, but not strong. I think that matters because for any more material acquisitions, KITW should be looking at raising fresh equity, not taking on more bank debt. The quality & price of its acquisitions are a key consideration here. As the founder is a long-standing CEO, I presume he is likely to know the sector, and his competition, inside out. So that reassures me he’s probably making good acquisitions, and is buying good operators, with no skeletons in the cupboard. Hopefully. That would be a good line of questioning in a webinar actually - how well do they know the companies they’re acquiring? And have any gone wrong? Why are vendors selling? What prices can they be acquired at, and is this below the rating KITW shares attract? That’s key to making an acquisitive group work for shareholders - get a premium rating, then buy things cheaper than that! Rinse and repeat. It’s a great strategy that can create multibaggers, if well executed. I think problem acquisitions tend to happen when ambitious management stray outside their area of expertise, in an attempt to diversify.
Cashflow statement - looks fine. As expected, the big item is payment for acquisitions of £19.6m, entirely funded by £20m increased bank debt.
Paul’s opinion - I remain positive on this share. Despite the big increase in share price, I think that is justified by the improved earnings. Valuation isn’t stretched, although after such a big increase in share price, there are bound to be some traders banking profits.
I’ll stick to GREEN, as it’s a good business on fundamentals, and still reasonably priced on a reasonable earnings multiple.
EDIT: thanks to Stegga1000000 for flagging in the reader comments that large Director sales totalling £3.3m have just been announced, which is clearly negative for sentiment.
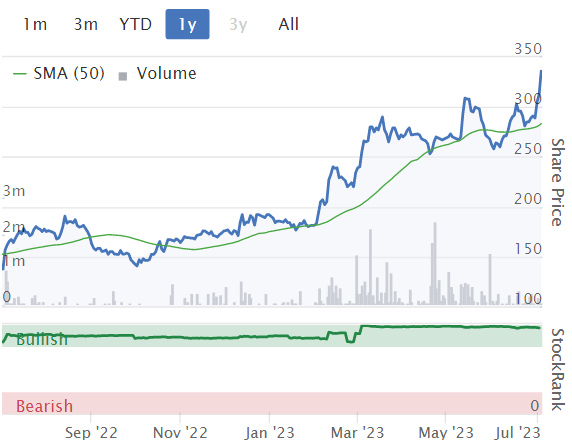
This share is the needle in the haystack of 2021 floats! So well done to shareholders who found it -
Restore (LON:RST)
Down 30% to 161p (£221m) - Trading Update & Board Changes - Paul - AMBER
CEO steps down -
Restore plc (AIM: RST), the UK's leading provider of digital and information management and secure lifecycle services, announces that by mutual consent Charles Bligh will be standing down as Chief Executive Officer and Board Director and that Jamie Hopkins, Senior Independent Director, has agreed to become Interim Chief Executive Officer, both with immediate effect.
An executive search process for a replacement CEO will be initiated also with immediate effect.
In addition, current Chair, Sharon Baylay-Bell, has agreed to become Executive Chair, also with immediate effect.
Trading Update (profit warning) -
Various factors have caused a deterioration in trading, helpfully quantified with revised guidance -
As a result of these factors, whilst the Group continues to demonstrate its cash generative characteristics, the Board anticipates that the adjusted profit before tax will be lower than previously expected and will be £31 million for the full year.
Adj PBT for FY 12/2022 was £41m, so the above guidance is a 24% fall in profit vs 2022.
The core business (70% of group profits) is storing of documents, this seems to be trading OK.
Other services are also trading OK.
Problems are in the digital business - eg. slower conversion of pipeline, and a slowdown in demand for bulk scanning of documents.
IT recycling is slower than expected (also mentioned in the last profit warning).
Cost-cutting is being done - reducing staff by 230, saving £1.1m in H1, and £3.4m in H2..
Paper pricing has seen a “sharp decline in recent weeks” - I wonder if that might have some positive read-across to newspapers, or packaging manufacturers? But it’s negative for RST, which receives money from selling recycled paper apparently.
Higher interest rates mean debt is now costing more - total interest cost of £9.6m expected in 2023, vs £5.9m in 2022.
Potential impact from non-cash impairment of goodwill.
Outlook - doesn’t sound too bad, not a disaster anyway -
The Board anticipates that the Group will deliver revenue growth for the year underpinned by the core storage and long term contract income that are a central feature of the Group's strength.
Cash generation remains good and net debt for H1 is in line with management expectations.
Whilst the near-term economic outlook remains uncertain, the fundamentals of the business remain strong, with the core long term contracted and storage revenues underpinning the profitability of the business, strong cash generation and the ability to implement inflation indexed price increases and structural cost savings.
Balance sheet - has been hollowed out by too many acquisitions. So intangible assets of £332m dominate the top of the bal sht.
NAV of £273m becomes NTAV negative £(59)m, or £(28)m if we’re generous and eliminate deferred tax (that’s usually related to goodwill). Not great, but not a disaster either.
Valuation - Canaccord has issued an update note, but not reduced its forecasts, which is very odd! Good thing I spotted that, as I almost published this with outdated forecasts in it.
So it looks like forecast for FY 12/2023 could come down from 22.7p adj diluted EPS, to maybe about 15p? That would mean the PER is now 10.7x for FY 12/2023.
However, forecast year end net debt of £95m is high, and quite hefty compared with the market cap now down to £221m.
So I’m wondering if divis might come under pressure to be cut, if debt reduction becomes more of a priority? So I wouldn't rely on the yield as being safe.
Also, with 2 profit warnings under its belt this year already, what’s the betting they make it a hat-trick later this year?
Paul’s opinion - I’ve never had a particularly strong view either for or against, with Restore, so we don’t cover it particularly closely here.
Roland reviewed it here on 15 May 2023, on a mild profit warning, concluding it looked quite good value (based on facts, figures, and forecasts at the time, as always - we don’t know what the future holds), but only viewing it as AMBER overall.
I seem to recall that Marlowe (LON:MRL) was trying to buy Restore not long ago, but it fell through. I wonder if the big drop in RST’s share price might now make it vulnerable to another bid approach? Looking at RST’s shareholder list, it’s just a collection of institutions, with no dominant individual or group, and little in management shareholdings. So it looks like a takeover bid would be easy to get agreed, if a suitable (>30%) premium were to be offered. Instis would probably be glad of the liquidity event, and ditching an investment that hasn’t really worked, but I’m guessing there.
At 161p, I’d say RST might be coming into buying range, but is not the sort of thing I would be interested in buying personally. I think there are cheaper value shares out there. And better growth companies. So RST sits uncomfortably between the two, of not really being value, and not growth either.
Also, I wonder if the acquisition strategy has been badly executed? The share price is telling us that acquisitions have not added value, and given that the original core business is performing well, but the rest isn’t so much, then that does reinforce my impression of a failed acquisition strategy. Probably why the CEO had to go.
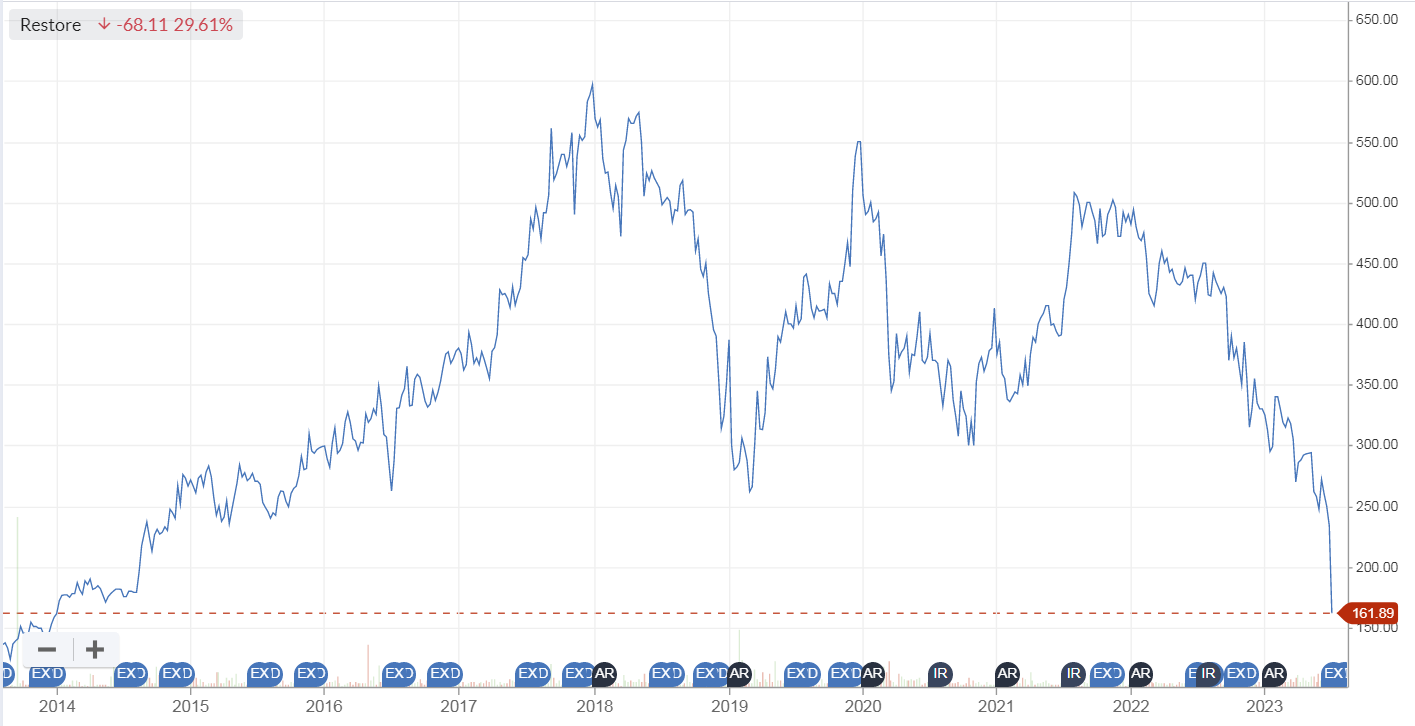
It's striking to see all the growth in share price disappear, and we're back to 2014 prices -
Naked Wines (LON:WINE)
Down 11% to 88.5p (£65m) - Trading Update (PW) and Board Changes - Paul - RED
Board changes - this is interesting. The founder, and former CEO Rowan Gormley, is returning as Chairman, replacing David Stead.
Another appointment is Jack Pailing, joining as an independent Director it says.
Nothing is said about Nick Devlin, the existing CEO, so is he staying put?
Gormley wants to resurrect a growth strategy -
Rowan Gormley, incoming Chairman commented:
"My thanks to David and the team for executing a challenging transition in a turbulent market. With a proven ability to deliver profit we now progress to the next stage, and develop plans to deliver profitable, sustainable growth. I am excited to return to a much larger business that has an exciting future ahead and I look forward to working closely with the reshaped Board to deliver on Naked's full potential."
Accounts are delayed -
Naked Wines plc announces that the release of its audited results for the 53 weeks ended 3 April 2023 (the "FY23 Results"), due on 6th July, has been delayed. A further announcement of a revised date will be made in due course.
The reason given is this (below), which I suspect might be related to the going concern wording, and whether the auditors can sign off on a going concern basis? -
As announced separately today, the Board has been strengthened and is revising the Group's plans with the goal of delivering sustainable, profitable growth and cash generation. In light of the revisions to the Group's plans the Auditors require additional time to complete their procedures.
Guidance is reiterated for FY 3/2023 -
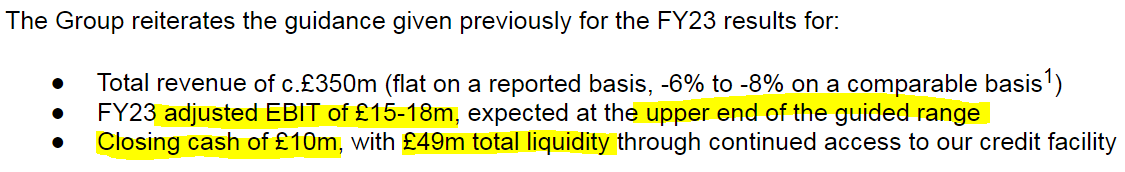
That sounds reassuring, but WINE has previously put too many things through as adjustments for my liking, in particular provisions against inventories. So I would need to see the full published results before forming a firm view on this.
Closing cash concerns me a lot, at £10m. This was £41.6m at 26 Sept 2022, so where has all that cash gone? Inventories were staggeringly excessive, at £209m in Sept 2022, so the idea was that this would be run down, and turned into cash. Yet cash has not increased since, it’s mostly disappeared, with only £10m left.
I suspect “Angels” i.e. customers, might be withdrawing their cash, which was represented by a creditor of £88m in Sept 2022. The trouble is, WINE seems to have spent their cash, and has never held it in a segregated escrow account, as it should have done in my opinion.
Current trading - sounds poor -
Sales in the first quarter of the financial year have been below expectations largely as a result of reduced levels of new customer recruitment. Extrapolating current trends through the remainder of the financial year would result in sales of around £300m.
Sales in FY 12/2022 were £350m, so it’s now anticipating a c.14% fall.
The strategy is now going to be changed to growth. But that costs money. Money which WINE hasn’t got. Therefore, I suspect a placing could well be on the cards here.
Paul’s opinion - I’m very wary about this share. It’s massively over-stocked with wine that it’s obviously struggling to sell - so I reckon more stock write-offs could be on the cards. The customer cash has been spent, instead of being segregated. Current trading is soft. The founder has come back to try to sort things out. It ran into going concern, and bank covenant problems in the recent past, and I suspect those risks could resurface.
All in all then, this smells bad to me, so I’m going to reiterate my previous RED view on 27 April. Thumbs down. We need to see the numbers, which I suspect could look horrible, and have more clarity on the cash position, bank covenants, and excessive inventories. This strikes me as a can of worms, I’d steer well clear for now, to be on the safe side.
Graham’s Section:
Duke Royalty (LON:DUKE)
Share price: 33.25p (+2%)
Market cap: £139m
Duke Royalty Limited (AIM: DUKE), a provider of alternative capital solutions to a diversified range of profitable and long-established businesses in Europe and abroad, is pleased to announce its audited final results for the 12 months ended 31 March 2023 ("FY23").
Duke continues to trade below the 40-45p area it was used to before Covid:

I covered many of the big-picture aspects of the stock in June.
Let’s catch up on the key points from today’s full-year results:
Recurring revenues +46% to £21.8m
Total revenue (includes the sale of royalties and the sale of equity investments) +19% to £21.9m.
Duke raised £20m at 35p in May 2022.
A new superior credit facility has been arranged, as I discussed last time.
Post-period end highlights.
Made a quick $2.4m profit from the “opportunistic” sale of one of its recent investments to a private equity firm.
Reached £6m in quarterly recurring cash revenue in Q1.
CEO comment:
"Having achieved £2.0 million per month of cash revenue in Q1 FY24, this represents the 11th consecutive quarter of delivering increasing quarterly recurring cash revenue. With this in mind, we have witnessed a very healthy and promising pipeline of new partners. The recent increase in deal flow has been encouraging, as it demonstrates the attractiveness of our proposition in a difficult funding market, and we are confident that our product continues to demonstrate its competitiveness against other financing options available to small businesses."
Higher interest rates: the Chairman notes that Duke has not increased the cost of the capital it provides to companies - at least not yet (“in the short-term”). The premise of Duke’s model is that it enjoys an initial yield of 12-13.5% on its investments, so I’m not sure if there is much room for it to increase from that level!
But the Chairman makes an important point that as rates have risen, this makes Duke’s offering more attractive, relative to other forms of funding that have become more expensive. He says “we have experienced a notable increase in both the number and quality of deal opportunities that Duke has been offered”.
Outlook excerpt:
…the higher level of global interest rates and continued lack of demand from the mainstream banks to lend to well-managed, profitable SMEs, puts Duke in an ideal position to selectively deploy further capital and increase market share. As a result, I expect to see a higher deployment rate in FY24 than we saw in FY23.
The dividend is running at 0.7p quarterly and the CEO reassures that it is well-covered by recurring free cash flow (yield is over 8% at the current share price).
Graham’s View
We already had a trading update in May, but today’s results do give us a few more chunks of information.
The main points to my mind are:
1. Balance sheet equity is £164m, with Duke’s investments being valued at “fair value” to arrive at this figure.
2. The company has exposure to c. 60 underlying operating companies. Diversification is reasonable but some investments have a fair value of £15-20m with significant risk to Duke if they failed.
3. Net debt is probably around £40m after the recent sale (it was £45m at the end of the financial year).
4. The new £100m borrowing facility has over £40m of available headroom and charges a margin of 5% over benchmark.
5. 94% of expected payments for FY 2023 have been received from royalty partners - that sounds good but I wonder if there is a risk of impairment associated with the other 6%?
On balance, I’m going to stick with my “Green” conclusion on this one because I do believe it offers investors reasonable prospects at this level. As I said last time, Duke has been around for long enough now to deserve some credibility - its portfolio has survived some extreme economic circumstances.
Now I’ve said that, the commentator’s curse does imply that a blow-up is just around the corner! Perhaps associated with the 6% of revenue payments for FY 2023 that have not yet been collected. However, the share price discount to book value, in my opinion, helps to price in this risk..
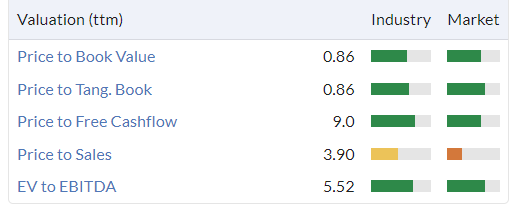
I should reiterate that I do expect Duke to raise fresh funds from the market, and perhaps it is waiting for sentiment to improve before it does that.
For this reason, I would be cautious about investing in Duke anywhere above book value, as you never know when a fresh round of funding could be announced. But at least the possible dilution would come with the benefit of a bigger and hopefully more diversified investment portfolio!
Strix (LON:KETL)
Share price: 104.78p (+4%)
Market cap: £229m
This producer of kettle controls and other water-related products has been severely de-rated in recent years:
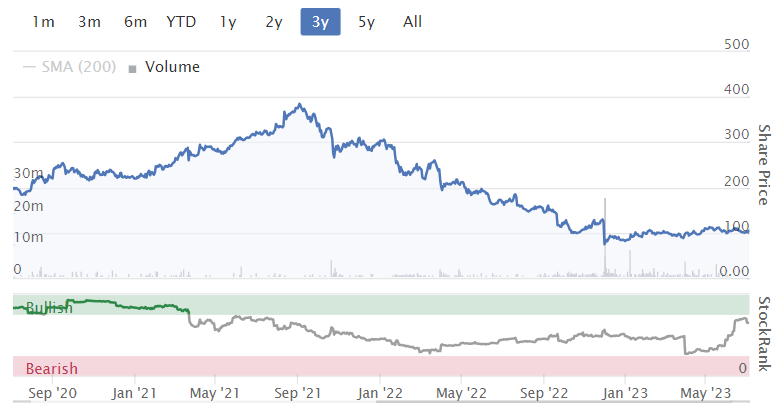
Investors (and humble analysts) have been worried about its debt load, as net debt grew to £87m as of December 2022.
Today’s in-line AGM statement from the CEO helps to reassure that performance continues to improve::
I can report that this trend has continued with Group performance in Q2 improving versus Q1. We are continuing to receive increased frequency of orders from customers, albeit with smaller quantities as they manage their cash balances prudently.
The net income estimate for the current year is £25.8m.
At the same time, the company does not seem very excited about the long-term prospects for its core kettle controls business. It says that its new growth phase will see it “further diversifying away” from kettle controls.
But before it spends big on further diversification/growth, it needs to manage the aforementioned debt:
"We will prioritise debt reduction with a clear plan to get net debt / EBITDA to below 2.0x during 2023 and to below 1.5x during 2024. As capital allocation decisions prioritise this, the Board, as previously announced, has decided after reviewing the level of net debt to propose a final dividend of 3.25p per share which would represent a total dividend of 6.00p per share."
In the previous financial year, the total dividend was over 8p per share.
Graham’s view
I was neutral on this before today and I remain neutral on it now.
Good points:
Cash generation is solid (I discussed this in March).
Trading in line with expectations at this stage of the year boosts confidence that performance is stable/improving, as expected.
Management insist that they will be careful and get their debt back under control.
Less good points:
It’s probably only a matter of time until more diversifying acquisitions are pursued, similar to the £38m acquisition of Billi, bringing various risks with them.
The apparent need to keep diversifying raises question marks for me about the long-term value/quality of the kettle controls business, which is where most of the value of Strix continues to reside. Are kettle controls simply ex-growth or are there more serious issues?
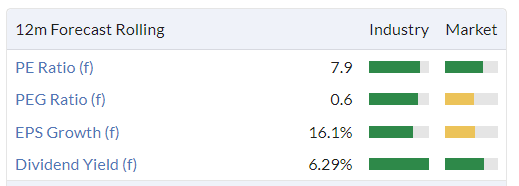
It could be argued that concerns are fully priced in at this level:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
Strix (LON:KETL) - "Encouraging AGM update & Investor Day insights" (new report here: https://www.equitydevelopment....)
The AGM update was encouraging and indicated that ‘green shoots’ continued to emerge, with momentum building during Q2 as the frequency of orders increased. Volumes, however, have yet to pick up, suggesting OEM customers are maintaining inventories and conserving cash. Significantly, the Group is seasonally H2 weighted with September to November critical months ahead of Christmas and Chinese New Year. Strix continues to trade in-line with market consensus (PAT of £25.8m) and as such, we see no reason to adjust estimates. The integration of the Q4 acquisition of Billi is on track, with a degree of excitement of the launch of the new one-tap system in Australia. We are particularly encouraged by the new product pipeline and the opportunity to gain a firmer foothold in North America.
We visited the facilities on the Isle of Man during an Investor Day ahead of the Group’s AGM. Meetings included an introduction to the Company, greater detail on the Chinese factory opened in Q3 2021, presentation of forthcoming product launches, and a factory & tool room tour (see main body of note for more).
We think the shares have been largely overlooked, sitting on a single digit FY23 PER and at a marked discount to its peers. Our fair value / share of 216p, based on several valuation models, is more than double the current share price.
Not listed but: 'Le Pain Quotidien has closed all but one of its sites across London after the bakery chain collapsed into administration, in a move that has seen the loss of 250 jobs.' ( I believe they have 8 stores). 'According to administrator Kroll, the collapse comes as Le Pain Quotidien’s operator, Brunchco UK Limited, was impacted by reduced revenues amid lower footfall across London, as well as rising costs.'
I thought it was interesting as this is a higher end bakery/sandwich place, so maybe the higher end consumer is not immune to cost of living crisis either. Also Rolex and Patek Prices are falling to near two-year lows on the secondary market.
Paul - regarding Naked Wines (LON:WINE) (i don't hold) you mention the concern around customer funds, but from my understanding the model of the business is that the customers self fund the wine producers to grow and produce wine solely on their behalf. So the company are right in using their customers cash to fund and purchase wine, the challenge for Naked has been that so much of that customer funds has been ploughed into funding so much wine that that their inventory growth hasn't kept up with demand.
From what i have read from their most recent statements and plans, they are significantly reducing their contracted wine with producers, but the impact of that has been slow as the company has tried to balance grower livelihoods with a desire to get inventory lower quickly. This has meant the inflow of cash from reduced inventory levels haven't come through and they have continued to burn cash as additional wine production still comes through from years past.
For me the key number to focus on would be cash flow over the next 2 years as inventory is expected to start coming down as supply will reduce dramatically. If they manage to get inventory levels back to 2021 levels then that's a cash inflow of £80+ million, which would dramatically improve the stability and balance sheet of the business (this is a very capital light business, so almost all of it will be cash flow positive), i think theres a good chance they could do this.
I think at its heart, Naked is a really interesting business, which particularly in the US benefits from clear and durable competitive advantage, capital light model and runway for growth and reinvestment, something which i think is under appreciated from a UK perspective.
Its a positive as well that Rowan Gormley will be joining the board again, and interesting to see a new board member who i believe is a stockopedia subscriber here.
Hi Joshua,
Thanks for your interesting comments on Naked Wines (LON:WINE)
You make a really good point, that the customer cash has been spent on wine, instead of sitting in the bank, so that has reduced my fears a bit about the balance sheet. Trouble is, that >£200m (at cost!) inventories figure could hide a multitude of sins, and the fact that they've already been slipping through write-offs (through adjustments) to inventories, makes me very nervous. What could the write-off be, if someone takes a fresh, and prudent look at inventories, and really takes an axe to them? £50m maybe? Who knows, it could be anything. Very excessive inventories or receivables usually contain lots of hidden problems. Even if they can recover cost, it might mean selling at negligible gross profit margins, thus pushing the P&L into a heavy loss. We just don't know, that's the trouble, there's so much guesswork here, hence why I want to be cautious.
Taking a step back, WINE's business model has never really worked. So it's not a growth story any more, it was always based on a rather creative way of claiming that existing customers were highly profitable & sticky, but then it had to spend all of that profit on new customers, just to stand still. It never made sense to me, the way they presented the numbers.
That said, Mr Gormley is outstanding at creating a buzz around his business, so who knows, he may be able to reflate the bubble in WINE shares? Stranger things have happened.
The big spike in the share price during the pandemic was obviously the lockdown boom in everyone ordering things on the internet with furlough money, and surplus cash from not being able to spend on leisure. Also I remember seeing some numpty US investor on CNBC talking about it as some kind of "platform" that could scale up into a vast market, and the shares spiked up massively the next morning, then dropped back down again within a day or two.
I think it was around 2018 when revenues dropped sharply, because they made the very surprising decision to sell off the Majestic Wine core business, and instead focus on Naked Wines.
Naked Wines (LON:WINE)
Hi Joshua
I'm a little late, but I wanted to comment that I completely agree with your thoughts here.
I recently took a small position after some deliberation and I am marginally reassured by Director Purchases today.
As you pointed out the current issue is that too much cash was poured into inventory.
But that inventory balance should start coming down now and I believe that the company - through effective working capital management and OPEX reductions - will have enough cash to buy the inventory it has on order for the next year or 2.
After that the underlying business, as far as I can tell, is actually cash positive, so there should be a lot of upside if it all goes to plan.
Fingers crossed.
A
Kitwave (LON:KITW)
Directors share sales:
http://newsfile.refinitiv.com/...
Just saw this.... brought the price down significantly on today's gains. (I think trading below today's opening now!) I own.
Thanks for flagging the significant Director sales at Kitwave (LON:KITW) - I make that £3.3m banked by Directors (today presumably), including the CFO selling £1.6m-worth, just over half his holding.
That's definitely a dampener on things, so I'll put an edit in the main article.
A lot of private investors follow significant sized Director buying/selling, so I suspect the price might well be soft for a while after this announcement. If the people who know the company best are banking profits, then it's difficult not to follow suit.
Mercia MERC - there is an Investormeet at 3pm today. I can't tune in so if anyone.....? I thought all looked pretty good here though much of the underlying increase in AUM was from the Birmingham acquisition which added >£400mn. Similarly with Foresight FSG there will be a results briefing posted on their website today and a follow up for analysts and later (11am) PIs on July 10th. Really super figures for last year - which had been clearly signalled in a recent trading update - but a little pressure on cash inflows in Q1 as PIs (I assume) removed some funds from OEICs. This is a much tougher year to raise money for equity investments and unquoted companies as we are all aware.
Is anyone invested in Mercia Asset Management (LON:MERC) , the technology venture fund and asset management business that issued final results today? Superficially, it has always looked good to me with a profitable asset management business, a dividend and 45p net asset value. What puts me off is if you pull down the accounts for any of their major investments. They all seem to be heavily loss making, cash guzzling, start-ups. I know this is what you get with venture capital, but I just wonder how these sort of companies are going to do in a higher interest rate world? That being said venture capital trusts still seem to be raising cash with the 30% tax relief available. Anyone any thoughts?
There is a Investor Meet the Company call with them at 15.00 today. https://www.investormeetcompan...
I invested in this a few years ago as a tuck away based on meeting the management at an investor event. It is hard to put a value on private businesses so it is all down to can the management sell on at a decent price. The management have science qualifications from memory so that has to help.
Centrica (CNA) was in a downtrend since 2013 when the price was 363. It went down to 37p in October 2020. Since then it has more than trebled. Coming down step by step is hard and you lose hope. climbing back on is equally difficult.
The chart looks amazing, the ranking is good and they may go higher for longer!
Results are out on 27 July.
More likely on the next downtrend
Good morning both.
Do either of you have any thoughts on Solid State? Continuing with positive results today and Solid State (LON:SOLI) is in the right markets for our times. It's been one of my best investments to date.
Hi Hedgecutter,
I've followed Solid State (LON:SOLI) for many years, and think I might have met management many years ago. It's always seemed a rather unremarkable, under the radar company, but has quietly built shareholder value over the long-term, through acquisitions. And a 5-bagger in the last 5 years I see (and a lot more if you bought in 2010 or earlier. Although most of the gains in the last 20 years came in 2 big, and quite rapid moves up. then it's had long periods of nothing much happening in between. Timing has been everything here!
There doesn't seem to have been anything particularly newsworthy of late - today's news says it's slightly ahead, so instead I focused on other companies which were reporting more price sensitive news, up or down.
I'd say SOLI looks priced about right for now, on about 15x forecast earnings. Although profits have stepped up very substantially from just a few years ago, so maybe we should look into why that happened? Maybe you could write something about it here, as I won't have time today, I need to look at the profit warning from £WINE
Regards, Paul.
Thanks for responding Paul,
One of the strengths that SOLI has is ruggedized computing and communications, just as government's are increasing their defense spending due to the Russian invasion. This has already won them contracts through NATO. I can't see that market shrinking any time soon. This also ties in with their move into the US market. They are an expansive and carefully acquisitive company with in-house design and various other strings to their bow, including medical equipment.
Hi Paul, a quick note to say that I am really enjoying your weekly podcasts - especially the macro ones. In particular I like the mix of anecdotal and factual. Also, on the subject of micro caps, please could you give me an update on LON:XJS (Conv) when you get time - disclosure I own LON:XJ308.
Hi Berksbee! It took me a couple of seconds to grasp what you meant LOL!
The XJS is going back in for an MoT re-test this afternoon, after I managed to fix the problems over the weekend. Keep your fingers & toes crossed!!
Hooray, she passed the MoT, so good for another 12-months of road legal use, after my little bit of fettling over the weekend (gluing back on the rear light cluster, which had fallen off, and replacing the windscreen washer jets with generic ones off Ebay costing £2.49 LOL!) :-)
Here's a recent photo of her. Amazingly long, and low (and quite narrow) compared with modern cars, where even superminis tower over her! Gorgeous to drive too, it's a KWE-modified one, with a £35k restoration (paid for by the previous owner, I'm pleased to say), so it has modern mechanicals underneath a 30-year old body). 4.0 litre straight 6, so not especially quick, but great on the open road, and does about 22 mpg overall, whereas the V12s are much more thirsty & complex to maintain.
Naked Wines (LON:WINE) Intraday RNS’s are rarely good news & this one is no exception
“Sales in the first quarter of the financial year have been below expectations largely as a result of reduced levels of new customer recruitment”
Results further delayed
Boardroom reshuffle announced
Not for me (nor was I a fan of the wines when I tried them, I thought them expensive for the quality)
You are being polite. The wines are absolutely rubbish value for money . I am in the wine business and fail to understand why anyone would invest in this business .
WANdisco (LON:WAND) has raised $30mn at 50p - leading to a 70% increse in the share count. Trading in shares expected to recommence on 7 July.
Wynnstay
Yesterday results as expected
Normalised profit now after the one off commodity gains of covid .
Trading below NAV and still knocks out 10 million a year profit .
Dividend increases for 19th year on the trot .
Definitely one for widows and orphans as well as farmers .
Would you be happy owning this business ? Yes
Simon Thompson recommends taking profits as share price going sideways for a period and that’s probably an ok tactic but I think it’s a decent “bedrock” share for a portfolio with very limited downside .
I think there’s a decent chance in the next 18 months of some seriously bad news coming out of the USA and catching us in the UK and in these cases the real solid value shares like Wynnstay will be the ones that don’t capitulate .
So think this remains a hold and leave it as a foundation share with limited downside and a further 19 years of increasing dividends .
I can see your point planetx on Wynnstay (LON:WYN) but with revenue/profits/EPS flatlining for a couple of years, shareprice downtrend and a higher yield available on an easy access savings account, Id rather stick my money in the bank I think.
Can it be called a value share in this market? only my personal opinion but Id value a solid, non growing company on 8x max right now which would be 330p on shores 2024 forecasts.
No one really makes money by leaving it in the bank except the bank of course .
Inflation definitely wipes out any interest earned .
Wynnstay has done some good acquisitions that will pull through and also has the extra strength to its balance sheet both of the covid retained profits plus they did a fundraise (10% I think at circa 580p from memory) .
So that balance sheet is bulletproof and way stronger than pre coviId
My personal preference is to own part of a business as opposed to put money in a bank and earn interest that is below inflation .
First choice is of course invest in yourself .
And that’s where is heading (at least).
Recently bought CRN ,thro' stoko sieves,using zulu type sieving. Bought a few,and this mornings results were rather good . Any chance of taking a look please Paul. ? Tony
Morning tony!
Yes, I spotted Cairn Homes (LON:CRN) - looks interesting on a fwd PER and divi yield both around 8, and small premium to NTAV.
I flagged it to Graham on our to do list, as it's an Irish company (housebuilder), so he might know it.
Regards, Paul.
As does another Irish Housebuilder Glenveagh Properties (LON:GLV)
Placing to raise £10 million at Kooth (LON:KOO) at £3 which is above last night's close of £2.61, to fund US growth after large contract win. Bid offer spread currently £3.30-£3.40 as I type. (I hold)
Kooth (LON:KOO) raising cash at a 15% premium plus a big contract win in California. Would be interested in Graham and Paul's view on this? not one I've given a second look previously but a premium raise deserves attention.
Edit. Would help if I refresh the page before writing as youd already commented on this. Thank you Paul.
Just a personal view on Kooth (LON:KOO) from my experience working in Education where it has been used. Over the past few years I have worked in a few schools that have accessed Kooth to support the students wellbeing. The reality is the uptake of the platform from the students was poor and in both cases Kooth came and went very quickly. My concern with Kooth is that although it might be able to win large contracts from companies wishing to support its workforce and demonstrate a commitment to their wellbeing, I am not sure the service will necessarily be retained over the long term once renewal comes around.
Solid State (LON:SOLI)
Final results out this morning. Slightly better than market expectations.
Reported EPS up 119% with adjusted EPS up 14%.
Current trading is described as positive.
"This, leads Board to expect revenue for the 12 months ending
31 March 2024 to be ahead of current consensus(1), reflecting year on year
growth in excess of 15%, and adjusted profit before tax to be marginally ahead
of current consensus reflecting circa 10% year on year growth."
The shareprice has been fairly weak over the last six months, though it has recovered a little in the last few weeks.
Morning all,
Excellent interims from Kitwave (LON:KITW) this morning, further upgrades.
I hold.
Yes looks good, Kitwave (LON:KITW) is a big Cockney Rebel favourite.
Director sales at 324p though. Though CEO hasn't sold any, that's the main thing.
CFO sold 500000…
Sounds like the Cake Box Holdings (LON:CBOX) CEO saved all the unused eggs from the cakes and smashed them into his own face. They say the value of a brand is the feeling it gives you it your stomach…
J Sainsbury (LON:SBRY) q1 number total sales up only 3.3% including fuel, fuel sales down 21.4% how are supermarkets going to deal with the shift to electric cars?
It is not just a shift to EVs. People are not buying petrol from supermarkets, so much now, as other petrol stations are cheaper. Just filled up at an Esso station at 133p a litre, my Morrisons is 147p. Even on the A12, most stations are cheaper. Even Asda are not that cheap anymore. It was on the news last night about the margins, they are making now, have never been wider.
No one forces the motorist to buy higher priced petrol and diesel, when lower priced supplies are available near by. Can’t understand why the Govt, with all the challenges it faces, feels that this an area for its involvement.
Think they just want to allow people to find out prices online rather than when you arrive at the forecourt, like most other products.
The problem is whole areas become expensive, when one puts up prices others follow. A town north of me, all the prices are high, it is like a cartel, but go further south and they are much cheaper. Supermarkets are not competitive on price at the moment. I refuse to pay 147p a litre, when I can get it cheaper. I hardly buy anything in Morrisons anymore because their prices have increased too much. The car park is now half empty, before it was fairly full, so I am not alone.
Prices should be available online, same as everything else.
'"Prices should be available online, same as everything else"
I'm surprised that one of the money advice co's doesn't provide a local service...or, as in the States, the local radio stations will sometimes include prices in the traffic news..
The proposed intervention is simply about information. No one is talking about controlling prices, but a market can only work if prices are transparent. True, there are sources available, but having properly public pricing, without having to drive around burning fuel to find out, would be a good step forward. And put pressure on those increasinf their profit margins.
Rusty2 re fuel prices - the supermarkets are moving away from using petrol as a loss-leader to get people into stores hence the margin may edge up. I suspect they will use that saving to have lower prices in stores. Fuel margin is 8%, VAT plus duty is 54%.
The margins now are more than 8%, hence the independents, that were more expensive, can easily undercut supermarkets. If I can buy Esso at 133.8p, that is about 10% less than my Morrisons. Those small garages out in the country that I never used, now are often among the cheapest. I'm seeing big differences across the country on petrol prices, diesel is probably even greater, in some areas, diesel is cheaper than petrol but in my area still more expensive. The Govt. are supposed to be doing something about it, increase competition and have daily prices available on line.
I use the Petrol Prices comparison website to find the cheapest fuel wherever I am - it relies on inputs from users, but is pretty accurate in my experience.
https://www.petrolprices.com/
Generally save £2-£3 each fill by switching to whichever of the 5 or 6 nearest stations are cheapest near me. As I fill up twice a week that is £2-300 per year.
Yes but prices are not always up to date. I use something similar. I don't fill up very often. I don't mind a few p difference but 14p a litre is considerable, that is around £6 on a tank.
I've used this app/website too and it's been around a while. It may not be perfect, and it may be more accurate in some regions than others, but I think that people who worry about the last few pence (I'm one of them!) on the price of petrol will generally already know where the better prices can be found. So much of the stuff in the news is one massive blame game intended to create hysteria for the benefit mainly of the media and politicians rather than the consumer.
We use Fuelio to log and monitor consumption on our two cars. This app also gives prices for all local petrol stations. Quick and easy to use
Good results from Foresight group (LON:FSG) if this is something that can be reviewed today? Its got a £500m market cap though, so maybe straying into mid-cap territory. AUM and revenues up 38%, and dividend up 46%. I am keen on alternative asset managers like this and Gresham House (LON:GHE) as the fees are much stickier than traditional equity fund managers. Bernard Fairman, the founder, still owns a large stake and runs the show. Obviously, infrastructure and private equity assets are coming under pressure with a higher interest rate environment and this may impact fundraising a bit. I hold.
Thanks topvest for reminding me of Foresight group (LON:FSG) which had somehow dropped off my watch list. I notice that Jefferies has today upped their target to 560 (was 540) with a buy rating.
I also notice that JP Morgan seems to have downgraded all or most of the housebuilder sector so will put my planned Taylor Wimpey (LON:TW.) buy on back burner for now at least!
Mark
My morning smallcap tweet: No let up in let downs
Restore (LON:RST) Trakm8 Holdings (LON:TRAK) Kooth (LON:KOO) Hydrogen Utopia International (LON:HUI) Science in Sport (LON:SIS) Aptamer (LON:APTA) Guild Esports (LON:GILD) Versarien (LON:VRS) Insig Ai (LON:INSG) Coral Products (LON:CRU) Synectics (LON:SNX), Strix (LON:KETL)
◄Restore (RST)► warns FY adj pretax only £31m. Blames continued weakness in Technology business, a reduction in demand for certain service lines and weak recycled shredded paper price. [SP=231.72 Cap=317m]
◄Trakm8 (TRAK)► FY-Mar. Outlook - warns H1 rev flat due to reinsurance cost and capacity issues but FY "to continue trend of improved performance with strong second half revenues, including from a significant software contract". [SP=14.9 Cap=7m]
◄Kooth (KOO)► $188m four year contract in California. Hikes FY23 rev guidance to £34m but significant upfront costs in respect of the contract. Increased EBITDA margin in FY24, and thereafter. £10m placing at 300p, a 15% premium. [SP=261 Cap=86m]
◄Hydrogen Utopia (HUI)► EU grant for 75% of expenditure of up to €450k in identifying a solution for creating value from such plastic waste through processing it into syngas and hydrogen. [SP=7.5 Cap=29m]
◄Science in Sport (SIS)► unsuspended on publication of AR. [SP=12.5 Cap=22m]
◄Aptamer (APTA)► guides FY-June rev in line. FY24 pipeline (not orders) for fee-for-service rev £2.2m. To cut op C/F to -£3m and plans to reach positive cash flow by the end of FY26, which will require approximately £6m rev by then. "In addition to trading income in July, further funding will be required in the short term in order to continue as a going concern." [SP=6.51 Cap=4m]
◄Guild Esport (GILD)► enters British F4 Esports Championship, its first in competitive simulated racing. [SP=0.62 Cap=4m]
◄Versarien (VRS)► GM stmt with op update. Cost base has been reduced significantly. [SP=1.9 Cap=5m]
◄Insig AI (INSG)► extends Richard Bernstein convert by six months to 30 Dec. [SP=15 Cap=15m]
◄Coral Products (CRU)► following better than expected results at Alma Products, with rev in the earn out period of £9.6m and an adj EBITDA of £0.6m, earn-out consideration will be £1.275m. Also unused property sold for £225k. [SP=14.65 Cap=13m]
◄Synectics (SNX)► c.£2m contract to supply specialist camera stations for Saudi Aramco's Zuluf development programme. A significant proportion to be delivered in FY-Nov. [SP=106.24 Cap=19m]
In line: KETL
Good morning Paul
Good trading update from Boku (LON:BOKU) this morning with both revenue and EBITDA ahead of management expectations. Also in a separate RNS some decent succession planning which is good to see. I would welcome any comments. (I hold).
Also an ahead of the ahead from Kitwave (LON:KITW) “Trading since the period end has been strong across all divisions and ahead of Board expectations at the time of the trading update released in May 2023. The Board anticipates that the Group's results for the full financial year will therefore be ahead of market expectations that were established at the start of the financial year.” (I also hold)
Strix (LON:KETL) AGM statement this morning - relatively upbeat and expect year to be inline with market expectations. That would give a p/e of 8.5 which makes the sp look cheap to me but there looks to be quite a wide annual range:
Duke Royalty (LON:DUKE) FY Mar2023, earnings per share 4.9p beating consensus forecast of 3.4p.
Good morning Paul and Graham, I'd really appreciate a quick comment on Mercia Asset Management's results if you get time. I'm tempted to add to our modest holding and will be guided by any observations from you and other Stockopedia members. Profit well down but FuM up, dividend up, lots of cash to play with and they have some exciting stakes in Game companies from previous updates, not mentioned here.
Any chance of a comment on last week's results from Marlowe (LON:MRL) ?
Morning Rod,
I'm not keen on Marlowe (LON:MRL) because of the very weak, overly indebted balance sheet. Quickly looking at its recent results, the adjusted P&L looks quite good, but the £191m long-term borrowings is a big concern.
It seems to be doing lots of very small acquisitions now, 4 since the year end.
No divis.
Overall, I'm struggling to see anything to get me interested in this share.
By all means give us your view, I'd be interested to hear what the attraction is.
Regards, Paul.
Bought early 2022 after placing (for purchase) following them walking away from Restore (LON:RST) bid in Aug 2021, showing restraint on price. Next thing they do is get a larger debt facility and promptly spend it on another 5 acquisitions.
Positives are
Approximately 85% of revenue was recurring (either SaaS, consultancy subscription or service contracts) and is underpinned by regulatory compliance
- compliance requirements make their services sticky
- director share purchases
- revenue generation above management targets
- forecast £45m profit for 2024
- recent comment on possible sale of division
Negatives include
- debt
- negative NTAV
- integration risk
- no dividend (or plan to pay)
For now, I'm holding on to see if they can successfully deliver on the integrations, with the possibility of debt reduction if the sale of the division happens.
Hi Rod. I looked at Marlowe (LON:MRL) after their recent results. I decided not to buy it because there are always massive adjustments between their reported EPS and their normalised EPS. This makes it impossible for me to value the shares. On 15th June (before results were out) the Stocko forecast EPS for the year to 31/03/2023 was 45.1p. The outcome was a reported figure of minus 3.96p and a normalised figure of 13.9p. Whatever way you look at it, they missed their forecast by miles! It would be handy if the "Earnings surprise" part of the Stockopedia screen actually worked because you could screen out companies that have missed their forecast by a long way. However, despite my reporting it to Stockopedia, this feature just does not work.