Small Cap Value Report (Tue 5 April 2022) - ECK, BKS, IGP, TPFG, MOON, QXT

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
I (Paul) have a crazy day today, as I realised my passport did not have sufficient (time) range to cover a forthcoming trip to Malta next week. So I had to fast track my renewal application, which involves driving from Bournemouth to Newport (South Wales) and back this afternoon!
Electric Cars
Using an electric car means carefully checking that it will have the range necessary, which it does thankfully for my trip today. I've already discovered that public chargers cannot be relied upon, because they're often out of service, or already being used, with someone else waiting to use it next. You also have to sit in the car whilst it charges, to ensure nobody else presses stop on the charging machine, and then puts the other plug in their own car (unlikely, but possible). Disputes are common.
For these reasons, a recent weekend trip to visit family in Cheshire (240 miles each way, easily done on one charge with 13% remaining) was blighted by me having to spend 4 hours at a service station, to re-charge the car for the return journey! It wasn't too bad, as the sun was shining, and the family brought some picnic chairs, and we sat on the grass verge by a Co-Op petrol station, having some Greggs and a natter! But it wasn't quite what I had planned for a family weekend.
My conclusion being that electric cars are fine for people who mainly do shortish journeys, starting and ending at home, but for people who routinely need to travel 250+ miles in a day, forget it! The charging infrastructure is woefully inadequate to make that a viable option at the moment. For two car families, having one electric, and one petrol car could make a lot of sense.
The driving experience of the car itself (a Porsche Taycan) is just stunning. Prodigiously quick, and it handles like a go-kart, yet as easy to drive as a Golf. There's instant, bucketloads of torque available at any speed, making overtaking hilariously easy, and fun. I miss the lovely sound of a powerful engine though, but the near-silence of each journey (apart from a bit of tyre rumble), and the ease of driving, means that you don't feel at all tired, even after a long drive. This is definitely the future, but we need hundreds of thousands of public chargers to make electric cars an easy option for everyone.
Agenda -
Paul's Section:
Eckoh (LON:ECK) - from yesterday. In line trading update. Are the shares cheap, having halved from last year's peak? In a word, no, but you can at least justify the valuation. So not over-priced any more. It's a tech company that has demonstrated little organic growth in recent years. So wouldn't be my top pick for a tech share.
Beeks Financial Cloud (LON:BKS) (I hold) - a £15m fundraise announced last night, has been successfully completed at 165p, only a 3% discount. This goes to show that institutions will support fundraises from companies which are delivering rapid growth & good news. Beeks looks superficially expensive, but I think this is the most exciting & credible small cap growth stock on the UK market right now. I'm very bullish on the long-term prospects of this company, given its rapidly accelerating, record order book.
Intercede (LON:IGP) (I hold) - issues a profit warning caused by delays to contract signings. Being almost 100% gross margin, this completely wipes out expected profits for FY 3/2022. Clearly a setback, but the finances are sound, and a market cap of only £27m now looks attractive to me. Recurring revenues cover almost all fixed costs, but investors just have to accept that timing of licences is not something IGP can control, so profitability is volatile.
Moonpig (LON:MOON) - not a bad trading update, although the boost to revenues has come from omicron, hence is hopefully temporary. Shares have dropped a lot from the inflated IPO price, but are still only coming into reasonable range. Weak balance sheet too. So it's not for me.
Jack's section:
Property Franchise (LON:TPFG) - I hold - strong results, as previously conveyed to the market. The shares remain modestly valued in my view, considering the resilience of the hybrid business model. Rising interest rates will be a concern for sales transactions, but this is offset by rental income, and I think there’s a good growth opportunity here over a longer timeframe.
Quixant (LON:QXT) - encouraging results from a smart UK small cap that supplies hardware and software to some much larger companies. There’s been a strong H2 recovery, with good visibility for FY22 and with order intake ahead of current year revenues and prior year order book. Notes from meeting with management have now been published.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Eckoh (LON:ECK)
40p (up 5% at 16:19)
Market cap £116m
Trading Update & Product Update
Eckoh is a global provider of customer engagement security solutions, supporting an international client base from its offices in the UK and US.
Our secure payments products help our clients take payments securely from their customers through multiple channels.
Nothing to get excited about here, it’s an in line with expectations update (and a helpful footnote) -
The Group expects results for the year ended 31 March 2022 to be in line with consensus market expectations* and will provide more detail in its pre-close trading update in early May 2022.
* Eckoh believes that consensus market expectations for the year ending 31 March 2022 are currently revenue of £32.1 million and Adjusted Operating profit of £4.9 million.
Recent acquisition is going to plan - which looks material, at £31m cost, relative to Eckoh's £116m market cap -
Eckoh, the global provider of customer engagement security solutions, is pleased to announce that the integration of Syntec, the payments solutions provider acquired for £31m in December 2021, is progressing well. Syntec's contribution to revenue and profits in the three months since acquisition are expected to be consistent with management's projections at the time of the transaction, and the initial steps towards realisation of market, product portfolio and cost synergies are proceeding on plan.
Product development is explained in some detail, which I won’t repeat here.
Broker updates - there’s good coverage of Eckoh, from quality brokers, Singers and Canaccord, so many thanks for their updates today.
Adj PBT has flat-lined for 3 years, which highlights the lack of organic growth. Cost-cutting is expected to give a boost to FY 3/2023, along with a boost from the Syntec acquisition.
FY 3/2022 is expected to deliver 1.4p adj EPS (PER of 28.6), rising to 2.0p adj EPS for FY 3/2023 (PER of 20.0)
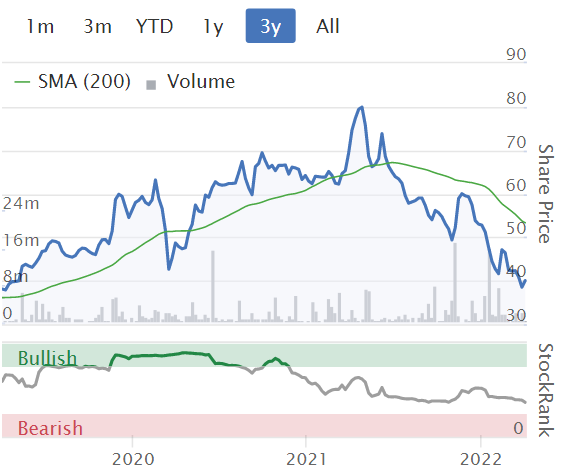
My opinion - Eckoh shares have halved from the (I would say irrational) high a year ago of c.80p. That’s now brought the forward PER down to about 20 - which is probably about right for a company that has struggled to show much organic growth in recent years.
Eckoh looks a decent quality business, that generates decent profit margins, and real cashflow.
However, the days of racy valuations for anything just because it’s tech, look to be behind us, or at least on pause. Therefore I can’t see any reason to chase Eckoh shares up in price, other than as a short term trade, which could be worth considering. Lots of things are bouncing right now.
ECK reminds me a bit of DOTD, with both being strongly cash generative businesses, but struggling to demonstrate organic growth. Maybe both are now a little old hat? Hence more likely to be valued as mature businesses, than growth businesses? Who knows.
The last 3 years has been a round-trip from 40p. Maybe it could bounce from that level again?
.
Beeks Financial Cloud (LON:BKS)
177p (up 3% today, at 09:19)
Market cap £116m (based on enlarged share count of 65.4m)
A £15m placing was announced last night, together with a Primary Bid offer for retail investors. The trouble is, why would I want to apply via Primary Bid, when they didn’t set a price? Would you buy anything else not knowing what the price is?!
Normally, when companies announce an accelerated book build, then it’s already a done deal, because a roadshow with institutions will have been carried out in the preceding fortnight or so.
This morning we got confirmation that the fundraising has been successful.
Terms -
- £15m raised (before fees)
- 165p per share, a modest 3% discount
- Placing: 8.79m new shares
- Primary Bid: 303k new shares
- Total new shares: 9.09m at 165p = £15.0m
- Existing share count was 56.3m, so this is enlarged by 16.1% to 65.39m shares
- Vendor (Gordon McArthur, founder/CEO) sale of 1.7m existing shares, raising £2.8m for him personally (no money to the company).
- CEO stake reduced from 26.29m shares, to 24.59m shares (37.6% of enlarged share count - still a very large founder’s stake). New 12 month lockup on his remaining shares.
My opinion - it’s no surprise at all that Beeks has done a fundraising. I mentioned in my last review that the balance sheet clearly needed strengthening, especially as rapid expansion is underway, with very strong organic growth.
Indeed, in a recent webinar, management sounded completely relaxed about funding, saying “Our balance sheet does need strengthening, that’s fairly obvious!” - if only all companies were so transparent.
Even so, this £15m equity fundraise is much bigger than I was expecting, although the 16% dilution isn’t excessive. Therefore, any concerns some investors may have had about funding, are now resolved.
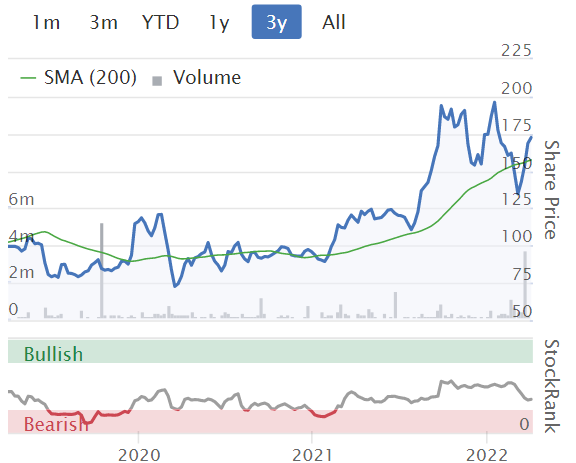
Management today comments that it has a “huge opportunity ahead”, and that in a nutshell sums up the investment case. It’s too early to value Beeks on a PER basis (which is only suitable for mature businesses). The organic growth here is exceptional, which is why BKS shares are my current favourite growth company, and it’s now my second largest personal portfolio holding, so bear in mind I’m not impartial - the organic growth here really excites me, and is rarely seen.
A company adviser told me that the size of the fundraise is indicative of the scale of the expansion opportunity that BKS has before it. The business model involves some up-front capex to buy more servers, etc.
Also, some of the funding is being used to accelerate R&D projects. That’s fine by me - Beeks seems to have first mover advantage in moving connections to international financial exchanges onto the cloud. Demand is soaring (last quarter saw record contract wins, at 3x previous record quarter) - when you have that kind of opportunity, it needs to be maximised, with short-term profitability becoming irrelevant. Particularly because contracts won then lock in clients in long-term recurring revenues.
Over-analysing historic numbers misses the point in my view, this is all about stellar growth, and what should end up being a highly profitable company that could even dominate this global market. Imagine what that could be worth, long-term? If things work out as I hope, then it’s not fanciful to see this becoming a 10+ bagger over say 5-10 years, but let’s not get too excited at this stage.
Valuation - for now, Beeks shares look expensive, there’s no doubt about that. So it’s not a share for value investors. Instead I see this as probably the best small cap growth share that I’ve come across lately, as it has such a big market opportunity, and orders are rolling in at an accelerating pace.
Management commented on the recent webinar that orders with large international tier 1 clients generally start off on a trial basis, which might be say £1m p.a. recurring revenues. As the clients gain in confidence, repeat orders then typically follow, with the first £1m p.a. client now having expanded to £6.5m p.a.. Therefore growth is strong, even before recruiting new clients, from existing clients expanding their purchases.
Another comment from management in the last webinar was, “Deal sizes we’re quoting for now dwarf what we’ve done before”. A big capital raise to fund expansion, backs this up.
I think this is a very exciting growth share, which is in my coffee can, and I’m looking to buy more when funds are available. Although it would probably need more upgrades to expectations to propel the shares on to the next stage, who knows? It’s tricky to value, and can look expensive or cheap, depending on how you look at it.
.
.
Intercede (LON:IGP) (I hold)
46p (down 21% at 08:45)
Market cap £27m
Trading Update (profit warning)
Intercede, the leading specialist in digital identity, credential management and secure mobility…
A disappointment here, with a profit warning for FY 3/2022.
Delays to a number of large new opportunities -
Whilst the number of new deployments is the highest in recent years, delays have been experienced with a number of large new opportunities that had been expected to close this year and consequently there has not been a substantial license order received during the year ended 31 March 2022. Furthermore, COVID-19 has continued to impact trading outside the US market.
Guidance -
- Revenues for FY 3/2022 expected to be £9.9-10.0m (9% below last year, or 4% down on constant currency)
- Company remains profitable (only just!)
- Recurring revenues largely cover the fixed cost base - which de-risks things largely
- Gross cash £7.8m - also, remember that the old borrowings on bonds are gone now, so the liquidity position is fine, no worries about solvency, given the high level of recurring revenues. Although the company is heavily reliant on one large, long-term contract in the US.
- $0.3m contract win announced today, looks a bit of a fig leaf.
Broker update - thanks to Finncap for an update note today. It’s not pretty, because of the operational gearing from contract wins, dropping straight through to the bottom line - lovely when it's growing, but brutal when it's slowing.
Revised forecast -
Revenue £9.9m (down from £11.5m)
Adj PBT £0.0m (down from £2.3m)
If these are genuinely delays, not cancellations, then FY 3/2023 could in turn be a bumper year, with the benefit of contract wins deferred from FY 3/2022.
My opinion - clearly this is a setback. Lumpiness of contracts is still an issue, and this announcement reminds us how nasty the operational gearing can be, when close to 100% gross margin software companies fail to close expected contracts by year end. It's a pity, because this disappointment obscures a lot of good work which has been done behind the scenes to improve the company.
I’m disappointed that growth has stalled, but the share price looks to me like it’s overshot on the downside. £27m market cap now looks far too low, hence I’d be inclined to add to my position, rather than sell. Although I’m also realistic that the company hasn’t managed to demonstrate sustainable growth yet, so investors understandably take a dim view of that.
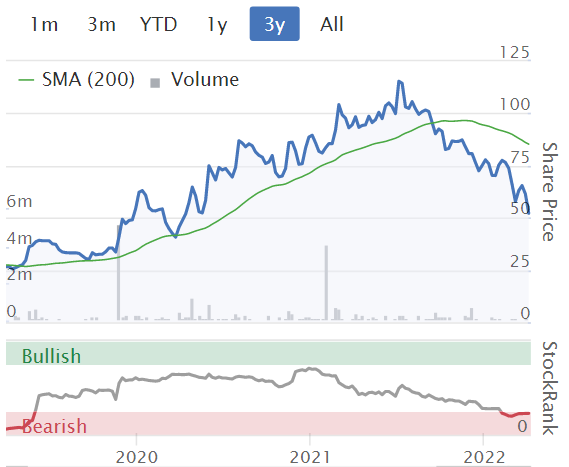
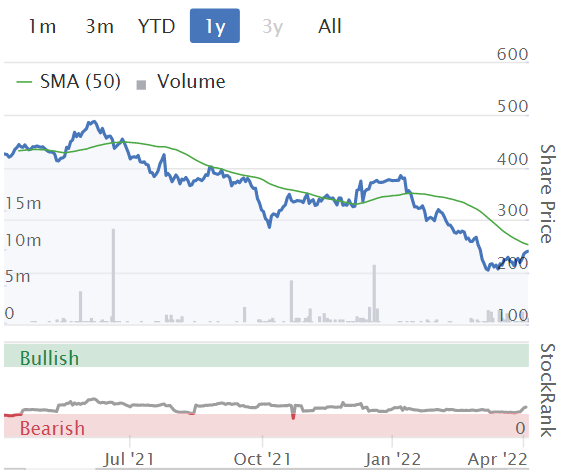
As you can see below, the share price has now scrubbed off most of the gains from the 3-year turnaround. It's a brutal market for small caps right now, so lots of charts look like this. But, the truth is clearly that performance has disappointed considerably, so the price deserves to fall - this is what happens when companies miss forecasts.
EDIT - I've just had a quick call with management, key points -
- They're frustrated & disappointed at contract delays, but not something they can control, when dealing with huge organisations, such as US Federal agencies (not able to disclose the name, for security reasons)
- Some large customers don't want to buy all the licences up-front, so the silver lining is that IGP gets follow-on orders, as they scale up new projects.
- Extremely sticky customers, very low attrition.
- Most business is in USA, with RoW (rest of world) almost shut down due to covid for 2 years, but signs now improving, as these markets are opening up again.
- Some of new contracts are displacing competitors - shows strength of Intercede's offer.
- New business being won through selling partners.
- Clear plan to develop the business in the next 3-4 years, Board remain very motivated. Apologise & take responsibility for this disappointment, but it's one bad half year, after 7 positive half years. Hope to have a more positive meeting in June, if delayed contracts are signed in this new year.
.
.
Moonpig (LON:MOON)
240p (up 1%, at 10:14)
Market cap £806m
This is one of many over-priced companies which floated on the growth boom fuelled by the pandemic, which has since crashed in valuation, almost into our usual (arbitrary) £700m top end for the SCVRs. I’m curious to take a look - will this be a one-off visit, or is MOON coming to stay with us for the long term, here in small caps land?
MOON’s year end is 30 April 2022.
Moonpig Group plc (the "Group"), the leading online greeting card and gifting platform in the UK and the Netherlands, today provides an update on its trading performance in the current financial year.
Revenue guidance is raised, but a refreshingly honest explanation is provided, that this is a temporary, omicron-related boost -
Trading performance has remained strong. We now expect that Group annual revenue in the financial year ending 30 April 2022 will be around £300 million, with the upgrade reflecting the temporary impact of Covid-19 on customer behaviour in late December and January. Our expectations for underlying revenue in FY22 remain unchanged at approximately £265 million.
Outlook - this is a little awkwardly-worded, it could have been clearer what they mean -
Trading in February and March has provided further evidence that supports our previously announced expectations of a permanent uplift in customer cohort frequency compared to before Covid-19. Accordingly, we remain confident in our existing expectations for the next financial year…
… we remain confident in the outlook for the year ahead. Moonpig Group has delivered a permanent step change in scale over the past two years, with a larger customer base displaying higher loyalty than pre-pandemic. The long-term opportunity remains vast, and we have never been in a better position to deliver against Moonpig Group's strategy to become the ultimate gifting companion."
Operations & IT are being expanded to handle expected future growth.
Medium-term target is annual revenue growth in the “mid-teens” - pretty good, if they can achieve it.
Margin “remains resilient”, and adj EBITDA target is 24-25% - sounds high, but it depends what they’re capitalising onto the balance sheet, which by-passes EBITDA completely.
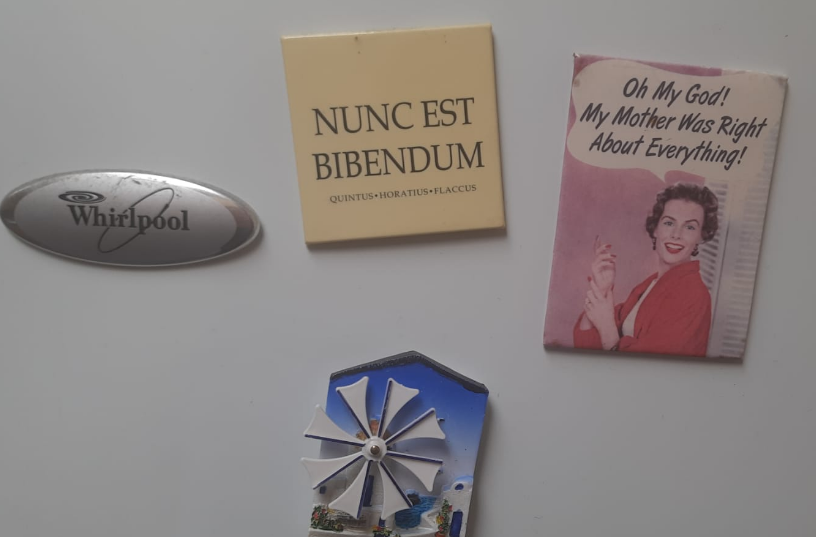
“Very successful” Mothers’ Day recently (my mother insists that this has nothing to do with her, or any other mothers, it’s originally a religious celebration between local clusters of churches. No idea if that’s true, but she’s usually right on everything, as I have reflected in my choice of fridge magnets).
.
My opinion - this update sounds pretty decent to me.
I like the fact that the valuation has crashed, as it makes a more interesting potential purchase.
There’s no available research on Research Tree, but going on the Stockopedia consensus for FY 4/2023, EPS is 12.0p - giving a PER of 20. If it can achieve the mid-teens growth target, then that looks a fair valuation.
Massive advertising spending means that many people will know the name, and you’re probably already humming the Moonpig-dot-com jingle! (Ha! If you weren’t, you are now!). There are competitors though, and we’ve seen from other online companies that online marketing can become prohibitively expensive, as the likes of Google and Facebook grab the profits for themselves by price-gouging customers.
Moonpig had a horrible balance sheet at Oct 2021, with negative NTAV and too much debt.
On balance then, think I’ve talked myself out of this one. A share that started off over-valued, and has only just come into reasonable territory (if it hits growth targets) doesn’t appeal to me in a market when there are so many other obvious bargains.
It might appeal to traders though, if the current bounce continues, there might be a 10-20% profit to be had, who knows?
.
Jack's section
Property Franchise (LON:TPFG)
Share price: 349.8p (+1.1%)
Shares in issue: 32,041,966
Market cap: £112.1m
Final results for the 12 months to 31 December 2021
(I hold)
Highlights:
- Network income +67% to £157m (17% like-for-like increase to £110m),
- Group revenue +118% to £24m (26% LfL increase to £13.9m),
- Management service fees (MSF) +57% to £14.7m (+19% LfL to £11.2m),
- Adjusted EBITDA margin of 81% and adjusted operating margin of 40%,
- Profit before tax +35% to £6.4m and adjusted EPS +61% to 27p,
- Net debt down from £8.8m to £2.7m despite £12.5m borrowed to fund Hunters acquisition,
- Total dividend up from 8.7p to 11.6p.
Like for likes exclude the impact of the acquisition of Hunters/Mortgage Genie and Aux Group disposal. Hunters in particular was a material acquisition.
We have increased our revenue every year since IPO and this was our eighth consecutive year with revenue up 118% to £24.0m (2020: £11.0m) largely driven by the acquisition of Hunters which contributed £9.8m.
Reflecting comments on the strength of the housing market made by Belvoir yesterday, TPFG’s sales agreed pipeline is up some 73% to £26.5m. A big chunk of this increase presumably results from the Hunters acquisition as well.
CEO Gareth Samples comments:
We experienced a surge in demand for residential property in 2021, reaching a level I have not experienced before during my 30 years in the sector.
How sustainable is that? The company is expecting 2022 to be much more like 2019 but anticipates growth regardless.
Looking ahead, we see an exciting period of further development for all our franchisees in 2022. While we expect over the year we'll see sales activity return close to 2019 levels, so far we have seen continued high levels of demand for both sales and lettings, well above pre-pandemic norms. Aside from market conditions, we have great confidence that the execution of our strategic initiatives, alongside the benefit of a full year's contribution from our acquisitions, will underpin continued growth this year and beyond.
The number of managed rental properties has increased from 58,000 to 74,000, while EweMove has had a record year, with 58 new territories sold compared to just 11 last year. On rents:
Typically, rent increases of 6% to 8% were seen during 2021, a trend that is continuing into the current financial year.
TPFG also launched a five year strategic partnership with LSL in April 2021 for the group’s financial services division.
The chairman (Richard Martin) is resigning soon and his commentary this year is particularly interesting:
Martin & Co opened its doors for trading in May 1986 in South Somerset. My franchisor epiphany came when in 1993 I read a copy of 'Behind the Golden Arches', the story of how Ray Kroc succeeded in building McDonald's into the world's largest franchise network. In the months that followed I set about designing the systems and procedures of our franchise model.
And:
Being a multi-brand franchisor, we felt the time was right in 2017 to re-brand to The Property Franchise Group. We thought we had a resilient business model and, when put to the test, by Brexit and Covid-19, it behaved in that way. In March 2021, we acquired Hunters, Country Properties and Mullucks. Then to support an expansion into financial services across a network heading towards 600 outlets, we signed a five-year strategic partnership with LSL Property Services in April 2021 and acquired a mortgage broker, Mortgage Genie, in September 2021.
I think these two quotes touch on two key points: the strength of the group’s franchise-led business model, and this more recent second phase: using that resilient, cash-generative business as a platform from which to diversify into other avenues of what is a very large UK housing market.
Outlook
Whilst we appear to have weathered the worst of the pandemic, none of us currently understand the implications of the conflict in Ukraine and the increasing cost of living. However, what we do know is that the Government has thus far been supportive of our sector, rental inflation is happening, and we are seeing greater sales activity than we were expecting so far this year.
So, possible upgrades should the current conditions persist for longer than expected. There’s a live private investor presentation on Wednesday 6 April 2022 at 12:30. You can register using the following link: https://bit.ly/TPFG_FY_webinar... results and a transformational year, probably reflected in the recent share price strength.

But TPFG’s valuation remains fairly modest given the business model and growth prospects.

As noted yesterday, the health of the housing market is a huge variable. TPFG’s business model should see it weather any downturn, but it could still be a consideration for those looking to time an entry into the stock.
House prices have increased drastically as a multiple of median earnings over the past few decades, and it looks like we’ll be getting interest rate rises going forward. It’s clear that there could be rockier moments in the years ahead.
However, the group comments:
Looking forward, I continue to believe that the housing market represents a strong investment opportunity. The UK government has demonstrated that the housing market is integral to a strong economy and that it will implement initiatives to support its continued strength. We need further properties to rent to satisfy our labour shortages and ensure capacity exists where that labour is required. Demand for rental properties remains strong and returns should increase. In addition, early evidence in 2022 suggests a healthy appetite remains to buy homes to satisfy post-covid lifestyle changes.
The fact that the UK government is supportive of the sector due to its importance to the wider economy is an important point. We’ve seen over Covid that governments are prepared to intervene these days in order to prevent short term economic pain.
However the sales market plays out, TPFG still derives a large part of its revenue through rent. Macro considerations aside, I think TPFG’s prospects are bright in terms of the group’s business model and ability to grow both organically and via acquisition.
We now have a Group which is capable of more rapid scaling up and we believe our network of local business professionals will soon challenge the largest of the corporate networks. Our year-on-year financial performance and returns are testament to the capital-light strength of our franchise model and, as it has in the US, we believe that franchising will become the dominant model in residential agency with TPFG augmenting our position as a leading player.
Belvoir reported yesterday, also with good results (quite similar on a like-for-like basis). I find it hard to pick between them really and think the market is large enough for them to both grow using fairly similar strategies. All in my opinion of course, so feel free present an alternative view!
Quixant (LON:QXT)
Share price: 150p (+3.45%)
Shares in issue: 66,450,060
Market cap: £99.7m
Final results for the year to 31 December 2021
Checking back over the notes, this is how we last summarised Quixant, back in January:
looks interesting. Founder/chairman remains largest shareholder. Ran into trouble before Covid, and lockdowns have since impacted. Some signs of quality though, and no equity dilution over what has been a difficult period. Solid balance sheet and possibly conservative forecasts, so could do quite well over the next year or two
It’s a provider of technology products for the gaming and broadcast industries, working as an outsourced technology and supply chain partner for major global industrial electronic equipment manufacturers. All of this is underlined by an encouraging culture of in-house R&D, new product development, and intellectual property.
The group started off in Gaming but has since branched out into other areas such as Broadcast, acquiring Densitron (where some of the management initially left to set up Quixant).
Densitron supplies display components to a wide range of industrial sectors, from which the Board has selected sectors in which there is the opportunity to develop tailor-made products, which are different to those readily available from broad-based technology corporations. We believe the Broadcast market represents such an opportunity, in which we have developed unique solutions which revolutionise the human machine interaction and control of Broadcast equipment. We delivered our second consecutive year of double-digit revenue growth in 2021.
I haven’t checked back in on the stock since the January write up, and see now that I missed an opportunity to take a closer look when the shares fell recently along with the rest of the market.

The shares are up by 6% or so this morning.
- Group revenue +37% to £87.1m (gaming division +56% to £47.3m, Densitron division +19% to £39.8m),
- Gross profit +29% to £25.9m,
- Adjusted PBT +315% to £5.4m and reported PBT up from a loss of £2m to £4.9m,
- Adjusted diluted EPS up from -0.4 cents to 5.95 cents,
- Net cash up a per cent to £17.6m.
Revenue in the second half of the year reached pre-pandemic levels and was the highest revenue performance since the second half of 2018, a strong recovery.
Good order intake through the year and into FY22 gives the group ‘excellent’ visibility of customer demand, while a recovery in end markets and new business wins have driven double digit revenue growth across the two divisions. So it sounds as though the outlook is positive.
There’s a results presentation tomorrow at 4:30pm here.
The group has grappled with electronic component shortages but has largely mitigated this, with a strategic stock purchase programme in January 2021 driving down delivery delays and mitigating against price inflation. This does remain an issue, but management has handled it well so far and there is some evidence it can pass costs on where appropriate.
While the strategic stock investments weighed on working capital, we nonetheless generated cashflow from operations of $4.4m (2020: $4.0m) and grew our net cash balance to $17.6m (31 December 2020: $17.4m). We expect to make continued investment in strategic stock to enable us to satisfy growing customer demand and new business opportunities in 2022 despite ongoing component shortages.
Conclusion
A particularly strong H2 and a positive outlook for the new financial year, backed up by in-demand technological products, intellectual property, and a strong balance sheet. This is a promising company in my view, although component shortages and wage inflation could have more of an impact going forward.
Quixant has grown its revenue very well in the past, although 2019 saw a bit of a dip, before Covid. This was due to underperformance from key customers at a time of higher customer concentration for the group. Since then the revenue base has diversified.

There are signs of a quality company here, but I wonder how large it can become? The group is confident it can target organic growth in a few different ways:
- New customer acquisition in existing markets, further diversifying the revenue base;
- Increase share of customer wallet by providing additional outsource solutions to become a fully integrated technology partner (an example of this is the recently launched range of turnkey cabinet solutions, which enable customers to focus exclusively on game software development and outsource their whole hardware offering to Quixant);
- Focused R&D to move up the value chain, including within the software stack; and
- Identify and target adjacent verticals that do not currently benefit from deep specialist solution outsource providers, such as Broadcast.
Alongside this could be the occasional strategic acquisition, should an attractive opportunity present itself. All in all, the situation piques my interest so I will be spending a bit more time on it.
On that note, I’ve just left a call with management so will publish the notes below once I’ve tidied them up.
Notes from meeting with management
The gaming market is important and is the group’s heritage, but Quixant is first and foremost a technology business. It works to differentiate itself from bigger corporations approaching its customers, by identifying large niche sectors which are poorly serviced offering from broader manufacturers.
Quixant’s first opportunity presented itself when some of the current management were working at Densitron, where they were making industrial computers. The gaming industry was in transition, from one arm bandit machines to video slot machines, and they started making enquiries to Densitron for this kind of product.
QXT mgmt felt there was a sufficiently compelling opportunity to build a business in isolation, with entirely new IP. From there they built the product and acquired customers, growing the business to 2013, at which point it floated in order to boost its credibility with customers (which were often much larger than Quixant).
The standard PC technology adopted for gaming video slot machines was poorly aligned to the regulatory and feature needs of the market. Quixant’s offering was more targeted and suitable. The customers don’t want to have to worry about the manufacturer of PC platform, they just want to focus on building their games.
Quixant therefore made an off-the-shelf compliant platform, freeing customers up to focus more on game design. There has been good success converting to that model and retaining customers over the years. Customers themselves have seen a very good rebound after Covid.
The group then looked for other markets where it can identify a technological trend, develop products for it, and develop deep sector knowledge from there in order to grow higher up value chain.
Densitron - industrial displays, relatively commoditised and high competition but broad sector exposure. Management can use this base to focus on higher return opportunities, such as the current Broadcast transition to touch screen technology.
Densitron is a ‘wonderful’ business exposed to many opportunities. Broadcast evolved as several companies already there wanted bigger displays for their software and ecosystems. A lot of what these customers use offer no tactility, which is important. Quixant is seeking to revolutionise the adoption of 21st century control mechanisms here, and has recently acquired IDS.
Historically, capex has been spent on gaming but more recently the focus has shifted to Densitron, where Quixant sees continued growth potential.
The group is also on the lookout for acquisitions that will bolster IP. These acquisitions could either deepen exisiting products to increase their value, and broaden the enterprise into adjacent markets. For example, tactile overlays have myriad end markets
Quixant is proud of owning IP and is focused on long term sustainable growth. It develops its own computer boards in house, has patented IP, and combines hardware and software into a unique offering.
Covid has been the key management issue; component shortages won’t ease for next few months but has weathered the storm well so far.
Gaming - still a ‘fabulous’ growth opportunity here, with good work done around customer retention and introducing new customers and revenue categories. There’s a more diverse mix of customers so revenue is healthier (see FY19 profit warning below). The growth engine that investors backed at float still presents a strong growth opportunity.
But then management identified the need for additional sectors. Broadcast has delivered its second consecutive year of double digit growth despite lack of trade shows. Management is attending a US trade show this month to demonstrate the products, which should really drive lead generation.
The group has exited the period with a well resourced and more experienced management team, no deep cost cutting, strong balance sheet, and no equity dilution.
Margin impact from supply chain issues has already seen in 2021. Quixant is passing prices on where appropriate but doesn’t want to profit from it. Structurally margins are intact and the group has worked with customers.
Quixant has used this period of disruption to strengthen customer relations. Customers weren’t interested in new products in FY20, just survival. Quixant was supportive and transparent, building up credibility customer management.
Then last year the situation flipped and Quixant couldn’t supply in full when demand was spiking. The team has been open and transparent with customers. It’s a regulated market so credibility required; retention has been good, doing a better job than others in marketplace. IP and tech remains high quality + strength of BS means QXT has been very helpful to customers.
FY19 profit warning - this was concentration risk on key customers. Gaming is all about quality of game, some customers saw reduced demand which had knock on effect on Quixant. No lost business.
It’s not all about the US market. QXT’s biggest customer prior to FY19 was Australian, so it can meet casino operations regulatory requirements across multiple markets. It has a sizeable business in Europe and a small footprint in Macau (lucrative but not big market for them).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
There's a reason the Tesla share price is where it is. They are way ahead on technology and I don't know why people don't understand that it's NOT EASY. Tesla sorted the charging problem 10 years ago. It takes us 20-30 minutes to get half our battery charged, an hour for the full thing (on a Tesla Supercharger, but a public Chademo is pretty fast too). We bought our Tesla 8 years ago, the more recent cars are faster. There is still nothing wrong with our 8 year old car. We've never serviced it (it doesn't need it). We've replaced tyres and one or two other things. The battery has hardly degraded at all.
However, the biggest mistake we made was buying the car and not putting the money we spent on the car into Tesla shares!
Do people realise you don’t have to fork out for a Tesla to join a cult.
I have a company lease EV car - a Citroen EC4. Lovely car to sit inside but absolutely dreadful range. It barely can manage 3/4 of the range it states whilst in Eco mode with no appliances turned on. I think the only EVs worth buying are Teslas.
£BKS
Would anyone be able to share a link to the Beeks webinar that Paul referenced in his report?
I’d very much appreciate it.
Thank you all!
Go on investormeetcompany.com and look for Beeks. You might have to register but it is free.
Thank you very much!
Interesting reaction to Intercede (LON:IGP) . Often on a warning a sp goes down at open and keeps on going down but this has done the reverse to the chagrin of those who bailed out first thing:
Yes, I've been watching Intercede (LON:IGP) for a while waiting for an opportunity to get in and first thing provided what I hope was an ideal opportunity. Markdowns for missed targets are severe at the moment but by all accounts, the sales were deferred rather than lost.
My view with this share is that those who use its services don't take that decision lightly and will be locked in for years to come and security of this kind is becoming increasingly necessary. Company quite possibly to be take out by a far larger player at some point. IMHO.
Yes, I've been watching Intercede (LON:IGP) for a while waiting for an opportunity to get in and first thing provided what I hope was an ideal opportunity
The problem with Intercede used to be that its technology was only really suitable for use with US Federal Agencies - which is a great moat as far as it goes, but they were on the wrong side of it. And they're deploying through integrators like Lockeed Martin who are taking the lion's share of the revenue.
Whether that's changed or not I don't know but given the way that the wider market for identity management systems has taken off - the likes of Okta (market cap of £19 billion) or Assa Abloy (£23 billion) for instance - you'd have to think the opportunity has passed them by. How on Earth can tiny Intercede compete with the investment those companies can make? Frankly most cyber-criminal groups probably have a bigger turnover than IGP.
The price is back where it was twenty years ago and there's been dilution in the meantime.
If they can start to bring in significant business from anything other than US Federal Agencies then it would be interesting. But otherwise it's hard to see where the growth will come from.
timarr
Thanks Timarr, that’s very useful
Hi Tim can't remember if I thanked you or not for your input into a question I asked on another thread if I didn't I appreciated you taking the time to reply and good to see you back posting on Stocko.
I came across Amedeo Air Four Plus (LON:AA4) using the Tiny Titans (Momentum Investing). Looks interesting and worth exploring further. I wonder if anybody else has it in their watchlist. Would be really interested to hear your views. Thanks.
£PGH full year 2021 presentation given to investors last week. They provide workforce benefits and services. In H2 they started to rebuild the insurance policy sales, which require face to face meetings, (although they are increasing their points of contact to include digital). In 2021, they achieved a record 86 new client wins. After the period end, they secured a 5 yr contract extension with Sage. In a sweet spot with employers needing to attract & retain talent. Lots of leavers for future growth. Video & podcast.
Hi Paul
Thanks for the EV opinion piece, really interesting. I own an 11 year old Touareg (you know what they say, the greenest car is the one you currently own) but my next car will be an EV (though I am hoping that is few years off, when the portfolio has performed sufficiently well, that I can go out and buy one without worry!).
I am not sure it is available in the UK but maybe you should have looked at the Mercedes EQS, which has a 700kms range and really well reviewed by Nico Rosberg at:
Even has built in massagers in the seats! Both a Taycan and an EQS out of my price point but if I was doing a long journey and couldn’t be bothered with the recharge hassle I would simply hire a ICE car from Hertz. But I don’t do many journeys over 100kms.
Regards
Michael
Our millenial sons recently visited us after sending us Moonpig (LON:MOON) cards. They were genuinely impressed by the quality (and size) of their cards. Given that millenials are key customers, I will continue to hold on the hope that, in time, my losses will reduce!
Re electric cars - right now (maybe Tesla aside) electric cars are great for those who tick a few boxes : typically drive short distances of <60miles in a day; have a driveway for home charging; can afford the upfront premium, both to buy a fancy cars and to pay a higher upfront cost, even leasing) to get the LT savings. Classic innovation and adoption curve - change happens first and fastest where most benefits accrue; scale then drops prices leading to virtuous circle of adoption (The Innovators dilemma Clayton Christensen 30 yrs ago!)
Mass adoption - coming VERY fast requires a much more aggressive and more competent, govt-led initiative to get infrastructure in place both visible (charging stations but also local grid infrastructure. However, the savings mean this is now an economic not environmentally driven change that is coming over the next 10-15years, based on lower fuel and repair costs. When China really gets going exporting cheap, small electric cars in about 2 years, really watch out for a rate of change.
Investing-wise, very difficult to be sure who will benefit most from this radical change except us all as consumers in the very long term.
Where is all the electric going to come from, we already have a shortfall of around 9% and around 40% of electric comes from gas and coal, renewables are only producing around 25% of our electric. Nuclear takes too long to build, doubt Sizewell C will be built for at least 15 years. Solar panels would be good to have if you have an EV. Batteries need to get cheaper on EVs and for home storage, Tesla is looking at changing to cheaper batteries,
I think clean energy is a good investment at the moment.
"We already have a shortfall of around 9%".
Yes I often find I have no electricity for two hours a day.
What I meant is we have to import 9% of our electric from abroad.
yes but we export it to when windy like today tomorrow and this then lowers the gas price.
But not very often and over the last year we imported 9% of our electric. We are still importing today.
Rolls Royce small modular nuclear reactors. These are nothing like Sizewell C style plants. They're modular constructed in factories and shipped to site.
Yes if and when they happen, will certainly be one one solution.
Inspired (LON:INSE) released full year 2021 results last week. Here's their presentation to analysts. They are a tech service provider supporting businesses drive net-zero, control energy costs and help them manage their response to climate change. They achieved strong growth financially & operationally. Rev +47%, Adj EPS +86%. For the outlook, Q1 started in line. Here's the video & podcast. Here's a link to Jack's comments last week.
Did management at Intercede (LON:IGP) explain why this announcement did not come with the contract renewal announcement on 30th March.
Mgt might be all custard and apple pie, but either they chose not to disclose (a/holes) or didn't know (incompetent). Sure there is a lot of growth - numbers suggest otherwise.
Lucky escape - sold with the intention to buy back in about 30 days or so - seriously doubt I will now. Chalk another one down to bull market BS
Anyone else think fancy electric cars are just a tax dodge for rich people not to mention a wonderful tax free inflation hedge, especially if you bought in 2020 / early 2021.
Surely, if it was really about the environment, taxes would be based on how much carbon it cost to make/transport the fancy car.
And unless the previous (presumably non-electric vehicle) is taken out of use, the emissions (and the tax) have been transferred?
ESG baby!!
A presentation from last week.
£WNWD FY21 results. A recent IPO. Tech in maritime intelligence. Strong growth due to world events (both supply chain and Russia/Ukraine war).
Here's the CEO&CFO presentation video & podcast.
We have Tp (LON:TPG) and Inspired (LON:INSE) to follow.
The Porsche Taycan is top of my list if I actually make some decent money this year. It is for spending after all. Well done Paul, totally deserved.
If the point in owning an electric car is to save the planet then you are probably wasting your time. A recent study by SAAB based on it’s own car, which it builds in both electric and deisel versions, showed that you need to drive 90,000 miles before the electric car produces less CO2 than the diesel version. This is mainly due to the high CO2 produced in the mining and manufacture of the battery.
I suppose then you'll tell us the battery will go.
Interesting and believable. Can you post the name of the survey? It did not come up on Googling...
Are you thinking of another manufacturer? Saab went out of business in 2011 and I don't believe they ever made an EV
Volvo perhaps ?
Saab Automobile AB is a defunct car manufacturer
It was Volvo
Tony,
Do you have a link to the report but it can’t be Saab.
For me another huge advantage of EV over ICE is localised pollution , which according to Statista killed 15,000 people in the UK in 2019 (maybe not all cars/trucks but I hazard a guess that ICE cars/trucks responsible for a lot of it).
Perhaps you should take to Twitter and discuss this with the new 9% owner, I suspect he might have a different point of view.
I think this is the Volvo report referred to:
https://www.volvocars.com/imag...
Exactly! Everyone talks about EVs from a CO2 standpoint, but the real undisputable win is in reduction of local pollutants (NOx, CO, particulates), particularly in urban areas which just happen to be where the majority of us breath.
Paul, You say " It’s too early to value Beeks on a PER basis (which is only suitable for mature businesses)." I see that they have four years history of positive EPS. Please could you tell us at what stage is this company likely to become a mature business in terms of using the PER for a valuation? Also do you come up with your own estimate of the intrinsic value of the company and what method do you use for that?
The problem with investing purely on a PER is that if you are a fast growing business investing for future profits then the PE can appear high and put investors off as "expensive". Fast forward 2 or 3 years though and profits explode upwards and the PE comes down. But by the time the PER hunter finds that stock attractive the likelihood is that the business has gone ex growth. ie it is no longer investing heavily in its business.
In the case of Beeks Financial Cloud (LON:BKS) they are taking all the new revenue and using it to invest because each new customer requires upfront spend. However, that customer is sticky and will spend many years generating revenue for the company. Plus the annual revenues will rise as they buy more from Beeks Financial Cloud (LON:BKS) as a trusted supplier. Thus a £1m p/a revenue stream today may well end up as £5m p/a from the same customer 3 years later. So margins appear artificially depressed at the moment and will rise from here.
For a stock like Beeks Financial Cloud (LON:BKS) I am more interested in revenue growth : why? because the customers they are getting are notoriously difficult to penetrate, but if you do, and perform a valuable service for them they will spend a lot of money with you. Many times an initial contract value and for many years to come.
Right now it seems that Beeks Financial Cloud (LON:BKS) has a niche in the cloud but a very big target market that is quite nascent in its use.
I think the rule of 40 is probably as good as any in terms of valuation metric for it.
Paul thinks this could be 5-10 times as big over 5 years. I don't disagree with the sentiment, there is certainly the opportunity for that but I'd be surprised if they aren't taken out by Microsoft, AWS or one of the others in the next 24 months personally.
David, Thank you for such a well considered & informative reply.
Hi
Below, a Shell EV charging station in Fulham London.
They demolished a petrol station and rebuilt this.
Usually 60 to 80% full when I walk past. Interestingly the vehicles are very mixed from van to small cars. Very wide range of brands. Also I am struck by how few Tesla's there are given that they are plentiful in West London. I suspect Tesla owners might charge from home as in this dense housing area, most people park in their street and link direct to their house or to the many charge points embedded into lamp posts.
Disclosure: I do not own any car, but invest in Tesla :)
Regards
Howard
https://youtu.be/L2vZeUgRFI8
Hi Paul,
re electric vehicle charging infrastructure: Osprey (YouTube link above, embedded below)
Quixant (LON:QXT) FY21 results overview video & podcast.
Canaccord have a price target of 240p. With an Adj Pre Tax Profit +48% (although I don't know what the adjustments are.) Certainly demand looks to have increased strongly and things are looking much more positive. Margins were affected by component increases which they are looking to manage going forward, along with the supply chain issues.
Property Franchise (LON:TPFG) FY21 results today. Group rev +118% £24m, Adj EBITDA +81% £10.4m, Adj EPS +61% 27p. Expecting sales in 2022 to return to 2019 levels although so far they cite a high demand for sales & letting. I'll be interested to get their take on the UK property market tomorrow, when we have a webinar, 6.4.22, 12.30pm. Register here.
Tomorrow evening at 6pm we have The Stockopedia/PIWORLD StockSlam, where 10 private investors pitch their best stock pick. Paul Scott is 'slamming' at this, so we are guaranteed high quality pitch from him. This is the last StockSlam for a while. We've had very few offers from investors to pitch (granted a huge number of investors who want to hear them). However we had to fall back on the same volunteers, which lacks originality, so we will give it a break for now. This week is uber busy at PIWORLD HQ so we won't get the edit of the recording out until next week. So, if you want to hear the pitches first, join us live: Register here.
Tracsis (LON:TRCS) H1 results are out on Thursday 7.4.22. Management are presenting on Friday (8th April) at 1pm, please join us live and ask your questions. A high quality company providing software and hardware to the rail industry, and data capture and analytics for various uses including traffic management and large events. On the rail side we've been waiting for traction to build in the USA, they've just acquired an American business, so we're excited to hear of their plans here. Register here.
Paul, is the tyre rumble still a genuine annoyance on the electric Porsches?
Hi BnB,
Sorry to everyone uninterested in EVs, I'm sure we'll get complaints!
Paul, is the tyre rumble still a genuine annoyance on the electric Porsches?
No, it's not an annoyance, and only really noticeable because there are no other sounds, since it has no engine, just a slight whir from the motor, which I quite like, it's a bit like a spaceship! You can get an optional artificial engine sound, which plays through the speakers, but I hardly specified any options (just a longer range battery, and turbo wheels) because they're mostly a waste of money, and you don't get the money back when you sell, even for high end options.
Given that the underseat/floor area is where the batteries are stored, I suppose there's not much room for soundproofing from the tyre noise.
When I drive my 30 year-old Daimler Double-Six, it's near-silent, so it was a bit surprising to find that an electric, brand new Porsche, has considerably more noticeable tyre noise than the Daimler (a 1960s design!).
I do worry that EVs are too quiet for cyclists & pedestrians, especially visually impaired people. I've nearly been caught out when cycling, and not hearing an EV approaching from behind. They should legislate to put some artificial (maybe wind-powered) noise generation at the front corners of all EVs, in my view, to make them audible nearby only.
I've heard that in China, some people attach a playing card, or similar, to the front fork of bikes, so that pedestrians can hear them coming. Nice idea.
Regards, Paul.
EDIT: the width of the Taycan is the main problem. It only clears the roller-shutter door of our underground garage at my flat, with a few cms to spare either side. Only a matter of time before I scrape it. Bulbous wheel arches look gorgeous, but make the car tricky & stressful to drive on narrow roads, or where you have to pass parked cars.
Thanks Paul. The tyre rumble is a real problem with Porsche’s sports cars because they don’t have much sound insulation (it adds weight). I’d love an electric Porsche but I really appreciate having a short-ish, narrow car in the country lanes I drive along, and Porsche’s EV’s are all flipping huge!
Hi Paul,
The cyclist/pedestrian issue is something I experience near constantly driving around in my Tesla! People just wander out in front of me and I have to slam on the brakes. Sometimes they are still blissfully unaware that they've nearly been run over even afterwards and they just carry on their merry way.
I do wonder as more and more young people seem to amble around staring at their phones and more EVs hit the road over the next few years if this will become a more pressing safety issue.
The phone zombies are a real hazard whenever I drive past the entrance to Reading Uni. Especially at the start of the academic year the new student priorities seem to be; first read the phone, second make new friends, and a distant third pay any attention to the A road they are wandering into.
While the issues with charging infrastructure remain, I feel that hybrids help. I have been using my other half's hybrid and it was great for small journeys. I didn't top up the petrol until I knew we had to do a long trip.
We used to put playing cards on the spokes of our bikes when I was a kid, a thousand years ago.
Surely everybody is interested in EV’s!
Not everyone, they are too expensive for many people. I'm considering getting one in about 5 years time if used prices have fallen to around £12,000, I need a range of over 200 miles and by then we should see how batteries are lasting and what the reolacement costs will be.
It was tongue in cheek Rustbucket, like you I hope my existing car last’s five years + and by then the technology will have moved on (and hopefully the production of batteries).
Regards
Michael
I see, not sure my current car will be with me in 5 years time as it’s getting on, I was thinking changing it last year but used car prices were crazy. I don’t do many miles so buying an EV now would not make much sense. Cars are the biggest waste of money.
Paul, there is a lovely black Jaguar XJ 3 series sitting in a garage wondering why you didn't take her. Every now and then she needs a good run out.
Paul, I too have done the Newport passport run and I can't recommend highly enough that you take an hour out of your day to visit (and walk over) the Newport Transporter Bridge, which is one of only two operational transporter bridges in Britain, and one of fewer than 10 that remain in use worldwide.
Great idea - but website says its closed for a year! Paul - Was it nor possible to recharge at the home of your friends/family - an important issue for all intending buyers...!
Would anyone have the slightest idea what Vin Murria is doing with Advancedadvt (LON:ADVT) . I accept that I was foolish to invest in a cash shell, based on a highly successful lead investor, but I am struggling to see how this plays out in a way that is positive for ADVT shareholders. I am down almost another 15% today. The discussions with Saatchi are interminable, and if it results in a walkaway she is surely going to have to consider liquidating and distributing funds (with a big haircut). There is a good chance that I am not seeing the bigger picture here......she will have some of the best advisors for sure, and there may be a value play that I (and the market) are totally missing. Buying in at £1.15 was pure speculative folly on my part.
I read sometime ago an article in the FT about SPACs, being the vehicle used to raise big money on the basis of acquiring businesses in the future. I think Advancedadvt (LON:ADVT) was based on this model?
I think they were suggesting that SPACS are more like Bonds than Equity, inasmuch as they are entitled to interest which can be converted to Equity, compared to pure risk punter Equity is in the normal course of events. This helps protect SPAC capital subscribers from dilutions etc, but could also they have a superior right to returns than other classes of subscriber if the business is being wound up etc.
That might mean in a potential wind up, your equity subscription may be used to pay off SPAC subscribers, meaning even greater reductions in return of capital.
I could have misread the situation, or got completely the wrong end of the stick, but might be worth checking the original admission documents.
If it makes you feel better, you're not alone! I sold at open this morning. It may recover but going into advertising (or even trying to) wasn't what I expected.
The Intercede (LON:IGP) profit warning today looks mild, from the directors' words, but follows a year of gradual decline. Is this a buying opportunity or a value trap?
The problem is that the PE rating was high, and expectations were for growth, not static or going backwards.
I have on my list to update my analysis later, but if we expect brokers to have a max eps of 3p for FY23 and in a bearish market for tech that has profit warned, 15x is the PE where it'll settle, I can see where the current 45p price is fair value.
(I hold)
Saw a wonderful lime green Porsche 911 GT3 RS , near the new indoor market in Newport last week.
Can't beat the sound of the engine on this and the amazing look and poise of the car.
I added to my position in Beeks Financial Cloud (LON:BKS) in the PrimaryBid offer yesterday (awaiting allocation).
I think on the published forecasts, the shares do look expensive. I think the market believes that the revenues forecasts (if not the bottom line) numbers will be beaten in FY23 and FY24. If I am right, further (modest) upgrades will be needed just to maintain the current share price. I believe significant revenue upgrades (or alternatively a sign the newest products can deliver higher gross margins) will be needed to drive the SP higher. But given recent momentum this looks a distinct possibility.
Paul, your experience with EV charging is the second I've read in my media stream today - see Iain Dale's piece in the Telegraph (or free on his blog here https://www.iaindale.com/artic... ).
I've just done a trip in my Tesla travelling from Cambridge - Lyon - Les Arcs for some skiing last week. Tesla superchargers the whole way. Stopped every two hours for coffee or food and comfort break. Chargers empty and so quick, not even enough time for a decent lunch. Returned on Friday, then up early to travel Cambridge to Liverpool on Saturday, then North Wales. Two short charges on the way, just enough time for a quick breakfast at Keele services.
Having had the Tesla for two years, I can see that Tesla has a massive lead in this market because they've created a connected product (Car, Chargers, Nav Software and operational data showing charger status). As you travel you can see how busy each charge station is, and the satnav reroutes you as appropriate. I think many people didn't realise that the charging network was such a huge asset for Tesla. If they open up it fully (and they already have in some parts of France), then I think it will only serve to protect their advantage (although some Tesla owners may be a bit peeved). Makes me wonder why services like IONITY are taking so long to roll out.
Good news on Beeks Financial Cloud (LON:BKS) fundraising. Seems like the market has responded well.
It depends where you live, some parts of the country have none or few Tesla superchargers, Lincolnshire none, Norfolk 3 and Suffolk none. So I don’t think opening up Tesla stations to others in my area will make much difference.
Hey Paul. Would be nice if you can look at £IOM
TU gives inline but with a better than expected cash due to reduced costs. I’ll try and write a few more notes when I can get to my pc.
Iomart (LON:IOM)
Charts look positive. Daily shows current price has just broken above resistance level. The weekly is very positive, showing the price still quite low with top of trend around £3 which would also coincide with broker target of 335p.
Paul I remember about 10 years ago driving to Newport from Devon for my appointment to renew my Passport. I was sent away for 4 hours so they could process the Passport after my appointment. Hopefully the process has improved.Good luck!
Hi portugull,
Yes, you order the passport online now (accelerated process costs £177), then just go to the available passport office (Newport was only one available this week) at an agreed time, to collect & sign the new passport. No doubt there's likely to be a delay, as is so often the case of public monopolies where you get what you're given! So I've written off the rest of the day.
Regards, Paul.
Electric cars.
Having the infrastructure (FAST charging points) illustrates how forward looking Tesla (Musk) is.
Electric car drivers do need to plan ahead ( having an up to date passport is particularly crucial for foreign travel):-
-make sure the car is fully charged before setting off
-for long distances decide where you will stop for a spot of lunch for recharging
-recognising areas of the country where the local councils are backward looking.
I have never witnessed a dispute and never needed to sit in the car while it charges.
Morning Paul, will you be covering TPFG later please ? Headlines look excellent. wondered if a comparison between TPFG,and the recent good results from BLV might be in order. Thanks Tony
will you be covering TPFG later please ?
We'll try, but really pushed for time today, and there are loads of companies reporting. I'll see if Jack can be persuaded to look at it! :-)
Regards, Paul.
Hi Paul
Thanks for the real life experience with your EV. So often, we tend to hear from evangelists who can see no problems or the opposite, rarely do we hear what normal life is like.
It does all make me wonder if we’ve messed this up and what we should be encouraging is hybrids so that the EV range issue is diminished so we could transition off ICEs faster. Then gradually regulate, or incentivise through the tax system, that the non-electric part of the hybrid does less and less.
On a stock related theme, do you have any views on how the transition to EVs affects the prospects of the vehicle retailers?
Graham
I do remember watching a Top Gear with James May saying that Hydrogen cars were the future because of how quick they were to fill up (basically it was like an ICE car without the emissions).
May this is the car version of VHS v Betamax (Betamax was considered to be the superior technology), thanks to a certain Mr Musk?
Regards
Michael
Tesla are opening up their charger network to public use in the next few months. Tesla drivers may not be best pleased but it should help overall.
https://cardealermagazine.co.u...
Paul, I remember a similar experience, things did not go too well, I had to return again next day for some stupid reason and that to a Passport Office with its adjacent car park that doesn't belong to it and policed by a n-zi. I can't imagine what it would have been like using an EV to do this.
Ip (LON:IPO) One of its companies has produced fusion via laser. Fusion is the Holy Grail of renewable energy. Mind you they've been saying that for the last 50 years and an error always seems to creep in somewhere.....
I’m old enough to remember the Fleischmann Pons cold fusion debacle in 1989 which has unfortunately coloured everything since.
But this work by Ip (LON:IPO) company First Light does look like a genuine breakthrough. To have achieved verified fusion with a spend of £45m is remarkable given the billions being spent elsewhere.
https://firstlightfusion.com/t...
Thanks for the heads up on this - I am an ex Physicist (many years ago) & was aware of their research but not how far they have come - this is a major step forward and validated independently by Gov' experts - one of the issues with the "cold fusion" debacle was the lack of neutrons generated at the correct energies - this approach seems to have shown the correct neutron energy profile expected from fusion so it appears to be real. Its a big step getting from a fusion demo to "break-even" (energy in = energy out) as shown by the JET tokamak at Harwell which has been running since the late 80's trying to increase energy out / burn times etc using a different approach. This is very encouraging BUT there are teams who have been using laser compression (in the US) who have been getting fusion but are nowhere near anything commercial.
I like the approach so may have a punt on this as Ip (LON:IPO) have several interesting companies / technologies.
As i understand it the problem with the 'cold fusion' debacle was that their Boron Triflouride detectors were giving false readings. They are notoriously unreliable.
Yes, I had a friend working in a research facility at the time of the cold fusion story. He said everyone saw the announcement on the evening news and was in the lab first thing next day to attempt to replicate the results. By coffee time they were getting nowhere and phoning round other labs to see if they were getting anything. By lunchtime it was written off.
Somewhere in an attic I have a copy of Scientific American where they analysed which universities could replicate the results and which couldn't. A significant correlation with latitude. :)
It was all a shame really as they felt under pressure to publish early and didn't check their data carefully enough and now reasearch into cold fusion is more or less taboo.
Hi Colin,
Thanks for this very interesting news about IP and fusion.
On a technical point, you wrote "one of its companies has produced fusion via laser". However, the link posted by John Eustace says the method used to obtain fusion by IP company First Light is firing a projectile at very high velocity at a target containing fusion fuel, using an electromagnetic launcher. Projectile fusion has some similarities wih laser fusion, because both are forms of "inertial fusion" which hugely compress the target in order to produce the enormous temperatures required for nuclear fusion, but projectile fusion does not use lasers.
Paul, which are your preferred companies for investing in the electric charging point space?
love the columns....
Rob
Hi CDM,
Paul, which are your preferred companies for investing in the electric charging point space?
It's not an area I know anything about, I'm afraid. I probably wouldn't be interested in investing specifically in that area, because it's difficult to see any company getting a sustainable competitive advantage. Heavy up-front capex too, to build the sites. A car dealer told me that the fastest charging points cost £250k to install, because they need their own mini electric substation!
We can buy shares in Chargepoint Holdings, listed in New York, ticker CHPT. I checked out the numbers, and it looks a bonkers valuation, for a company that (as you would expect) is loss-making.
In a vaguely similar area, I think Volex (LON:VLX) (I hold) seems excellent value right now, but as with so many things, the market seems to be factoring in a possible profit warning, despite it having issued solid trading updates recently.
Luceco (LON:LUCE) recently acquired an EV charging points subsidiary, but it's very small, and it's already quite a crowded space. Domestic charging points are cheap, and there are plentiful providers, so I can't see much of an opportunity there.
If you come up with any good ideas yourselves, do let us know!
Regards, Paul.
On Volex (LON:VLX) (I hold 5.1% position) I am just dumb founded by the fall. It is now down 46% from last year’s high.
I have not yet topped but I am tempted. I have no particular theories but I can only assume that:
- That the market thinks Volex won’t be able to pass increased raw material costs
- Recession will reduce sales
- The projected doubling in capex will be greater than projected.
On no news other than a good TU the sell off seems over done. But what do I know. And they supply Tesla with charging cables.
Regards
Michael
I am with you Michael...a very frustrating share...I am on my second go at it when it stop lost out last time, Three strikes and your out for me...lets see but am 5% down already! Results out soon I think.
I would say if they stopped issuing shares and got on with working with what they have, that might help.
Volex perhaps?
which are your preferred companies for investing in the electric charging point space?
Small Companies Sharewatch recently recommended £PODP. But I prefer Alfen NV (already profitable, well entrenched) and Chargepoint (US exposure, expensive but huge runway). Frankly, it’s all a bit of a punt because we don’t know how heavily the oil majors are going to weigh in.
On the EV theme I also hold ABB, Schneider Electric, Infineon, Aptiv and, yes, Volex
Forgive this sentence on EVs please guys, I have one son with the Taycan Paul (fabulous) and two with Teslas, the infrastructure for Tesla charging makes them a more sensible choice for longer distances.
Paul, I’m surprised about your EV experience. Porsche has a deal with IONITY fast chargers where you can charge 50% or so in the time it takes to literally have a coffee (or a full charge in about 50 minutes) and at 31p kWh, instead of IONITY’s usual charge of 69p kWh. There are plenty of these super fast and many other fast chargers on motorways, you just need to use an appropriate app to search for their location for your route and plan!
I've been after a Taycan for a while Paul, good choice. I can't bring myself to pull the trigger as I work from home permanently now and already have a 997 and 1972 Beetle that I use for the weekends and we have a BMW I3s which is utterly superb - full electric and a range of 180 miles, which is more than enough for our journeys during and my local Aldi allows me to charge for free! But yes, charging infrastructure and lengths of charges do need addressing before electric become viable although.
Onto some news today, I noticed that £BKS were offering a book build last night via PrimaryBid. I couldn't locate it though despite me scrolling through lots of closed offers. Not a very user friendly experience.
The Beeks Financial Cloud (LON:BKS) offer was only on the Primary Bid App. You cannot access from their website. All recent offers seem to be by this method
Good morning Paul. Couldn’t agree more on your assessment of EV’s. We love our iPace but on a recent trip from Cheltenham to Cambridge found that half the chargers were out of service. Genie Point even charged us £8 before failing to charge. Apparently I’ll get the money back at some point in the future (shocking customer service)!
On company related news: I’ve been watching Gooch & Housego (LON:GHH) as they have a record order book. Unfortunately they’ve had to issue a profit warning today. Worrying that they can’t take advantage of customer orders and won’t be able to catch up in H2.