Small Cap Value Report (Tue 5 Dec 2023) - OTB, TBLD, PEEL, OMG, 888, PRV

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
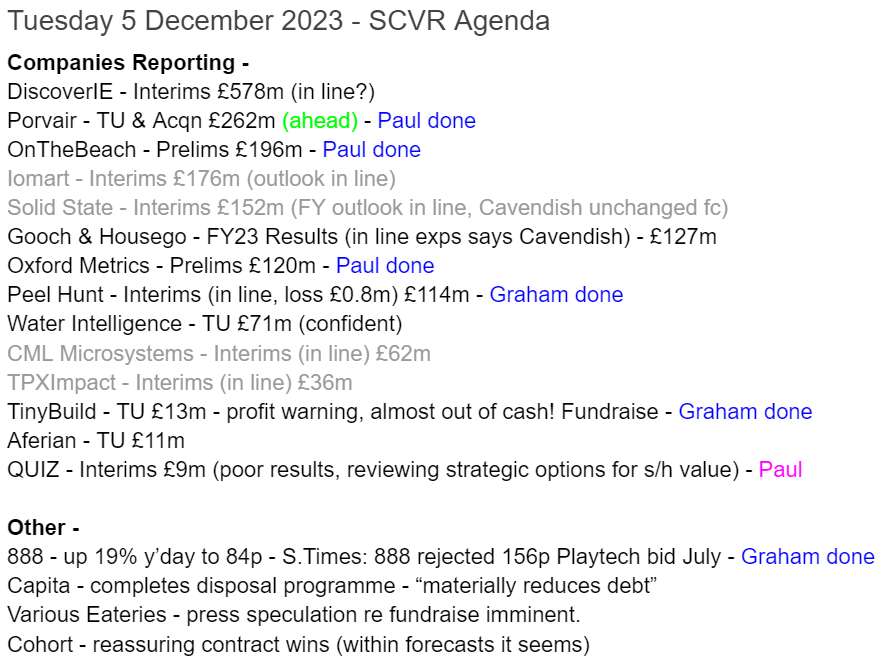
Very busy today, so we'll probably have to focus on things that are not just in line with expectations -
Summaries
On Beach group (LON:OTB) - up 15% to 135p (at 08:58) £225m - Preliminary Results - Paul - GREEN
Sparkling results for FY 9/2023, driven by continuing strong demand for holidays, and bumper finance income from the big cash pile. Outlook sounds really good too. Cash conversion not quite so good, due to heavy capitalised development spend, but is still enough to reintroduce divis shortly. I remain at GREEN, it's trading well, and looks reasonably priced still.
tinyBuild (LON:TBLD) - down 20% to 4.9p (£10m) - Trading Update and Litigation Settlement (profit warning) - Graham - RED
Another profit warning and this time it’s critical as it means that the company’s cash balance is running out. More funds are likely to be needed in January. It has been a shocking waste of shareholder cash. At least the CEO seems ok with the prospect of buying back in here.
Peel Hunt (LON:PEEL) - up 1% to 93.5p (£115m) - Half-Year Results - Graham - GREEN
Today’s interims seem more or less as expected with a small loss and no major change in performance. Cash reduces as the company pays off some loans. I remain positive on this with NAV of over £90m and well-placed to profit when sentiment and activity picks up again.
Oxford Metrics (LON:OMG) - Unch 91p (£121m) - Preliminary Results - Paul - AMBER/GREEN
Very good results for FY9/2023, and half the market cap is the net cash pile. An acquisition was made post year-end for £8.2m, leaving around £60m net cash for more deals, let's hope it's spent wisely. With an order book halved, and outlook comments that duck the question on FY 9/2024 expectations, I'm introducing a note of slight caution, going down from green to AMBER/GREEN - so still positive, but let's see how things progress.
888 Holdings (LON:888) - up 19% yesterday to 84p - Graham (I hold) - AMBER
No RNS but there are press reports - specifically from the Sunday Times - that Playtech (LON:PTEC) (market cap £1.3 billion) wrote to 888 with bidding interest in July. The indicative price was reportedly 156p for each 888 share, more than double last Friday’s closing price of about 70p and a significant premium to the share price in July (around 100p). Earlier this month, the FT reported that Draftkings ( DraftKings (NSQ:DKNG) , market cap £25 billion) also discussed a possible bid in July with some of 888’s top shareholders. 888 issued a profit warning in September that may have dented the valuation of any possible deal, and is carrying an enormous net debt position (£1.7 billion). However, its brands do have strategic value. If they are willing to rebuff both Draftkings and Playtech, then 888’s management and major shareholders must still be confident of the company pulling through this difficult period. [no section below]
Porvair (LON:PRV) - up 3% to 624p (£290m) - Trading update (ahead) & Acqn - Paul - GREEN
We commented here on 15/9/2023 that FY 11/2023 forecasts looked too low, so not a big surprise to get an ahead of expectations update today. Also news of a bolt on acquisition funded from self-generated cash. Nice business, reasonably priced I think, so I'm happy with GREEN.
Paul’s Section:
On Beach group (LON:OTB)
Up 15% to 135p (at 08:58) £225m - Preliminary Results - Paul - GREEN
About On the Beach
On the Beach Group plc is one of the UK's largest online beach holidays retailers, with significant opportunities for growth. Its innovative technology, low-cost base and strong customer-value proposition provides a structural challenge to legacy tour operators and online travel agents, as it continues disrupting the online retail of beach holidays. Its model is customer-centric, asset light, profitable and cash generative.
We reviewed OTB favourably on both 14/8/2023 (event: founder spent £2.5m on shares at 88p), and again on 13/9/2023 with a top end of range trading update FY 9/2023, good bookings, and better finance income on cash pile. I concluded it remained too cheap at 104p.
Looks like it’s going to be a hattrick for GREEN today too, with very nice results.
Key numbers FY 9/2023 -
Revenue up 19% to £170.2m
Adj PBT up 66% to £23.6m
Adj basic EPS up 81% to 11.6p (PER of 10.1x)
(I prefer diluted EPS to basic, so dilution from share options needs checking - just looked, it’s fine, diluted adj EPS is only slightly lower, at 11.5p)
Commentary says benefit from end of covid disruption, and that customers are protecting their holidays and cutting back on other things.
Big benefit from interest received on cash balances of £4.1m,vs only £0.3m LY, so OTB is a significant beneficiary from higher interest rates. Although it also had £1.5m of finance costs.
Marketing spend reduced as a % of revenue.
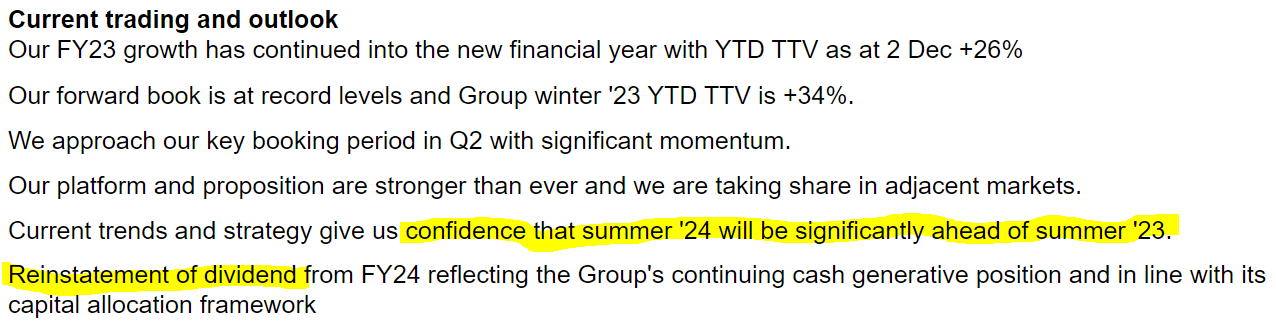
Outlook comments sound upbeat for next year -
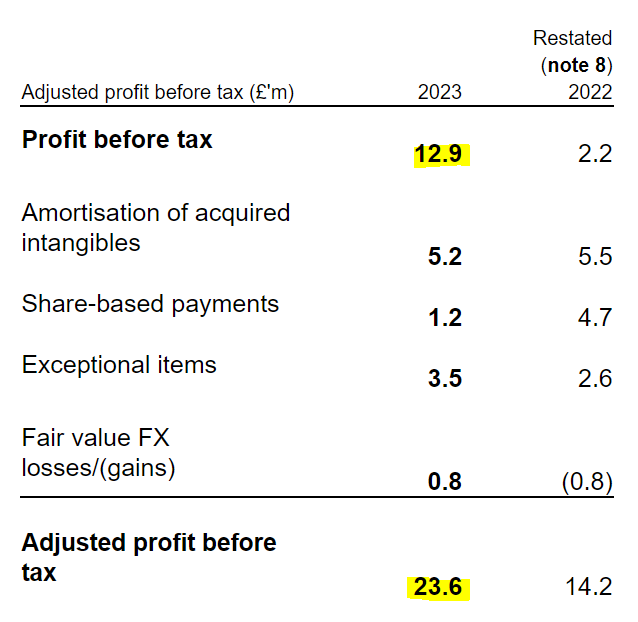
Adjustments to profit are quite large, with some of these being questionable -
Balance sheet - looks pretty solid to me, with £94.5m NTAV (after writing off £73.7m of intangible assets).
Note that there’s £108.6m of customer cash held in trust account, but shown on the balance sheet, and is released to OTB when the customer has travelled.
Big numbers on both the debit and credit side within working capital, but a healthy overall position here with net current assets of £86.2m.
Note that it took a £2m bad debt charge, so it would be interesting to get more detail on what this was - an intermediary going bust would be my guess - an airline, or travel agent perhaps? I would ask management what this £2m charge is for, and what steps the CFO has taken to ensure it doesn’t happen again?
Cashflow statement - some concern here. It made £22m positive operating cashflow after tax, but before finance income in both years, but spent £12m on capitalised development spend in FY 9/2023.
Overall the net increase in cash was £11.3m, well behind PBT.
No dividends were paid, but are set to be reintroduced.
Whilst cashflow is well behind profit, there’s still enough to pay fairly decent divis in future, providing we don’t see any more pandemics. Divis were not particularly generous pre-pandemic, but were well covered by earnings.
Note that the share count has risen about 27% compared with pre-pandemic, something to bear in mind when drawing lines on charts, as you’re not comparing like with like.
Paul’s opinion - I remain bullish on OTB - it’s modestly priced, both on FY 9/2023 results, and particularly considering the positive outlook, hence likely to achieve maybe 14-15p EPS in FY 9/2024 - so anything below 150p/share still looks attractive value to me.
The balance sheet looks good enough, although cashflow is somewhat behind profitability due to heavy capitalisation of development spending.
Divis should resume, although it’s not been a generous payer in the past.
Overall the recent rise, including today up c.13% to 132p, seems fully justified to me.
One query is whether we should rate travel shares on a permanently lower rating, now we know how vulnerable they are to disruption from any future pandemic-type events. That’s for each investor to decide.
Anyway, it’s another GREEN from me today.
Following very large Director buys often works, so the £2.5m buy in Sept by the founder was a very strong signal, as we discussed here at the time, so I hope some readers have made a bob or two on this, following his lead!
I'm surprised at how low the StockRank is here. Maybe that's been skewed by the impact of the pandemic on the last few years' results?
Also note that zooming out on the chart, the recent rebound in share price is barely a blip - indicating possibly more upside, if it re-rates to a higher PER maybe?

Oxford Metrics (LON:OMG)
Unch 91p (£121m) - Preliminary Results - Paul - AMBER/GREEN
Oxford Metrics plc (LSE: OMG), the smart sensing and software company servicing life sciences, entertainment and engineering markets, announces preliminary results for the financial year ended 30 September 2023.
Impactful headlines at the top of this results statement -
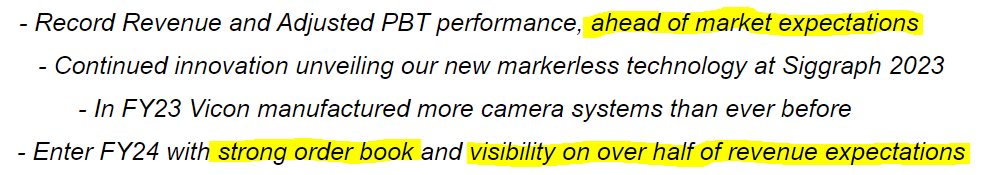
OMG is one we follow closely here. It’s distinctly unusual, since it’s sitting on a very large cash pile, which is 54% of the market cap. That’s should now be earning very nice interest income, yet finance income is only £1.56m on the P&L, suggesting an average interest rate received of only 2.4%. So an obvious question for management, is why aren’t they doing a better job with internal treasury, and maximising the interest income? I seem to recall they previously said something about wanting to keep ready access to cash for potential acquisitions.
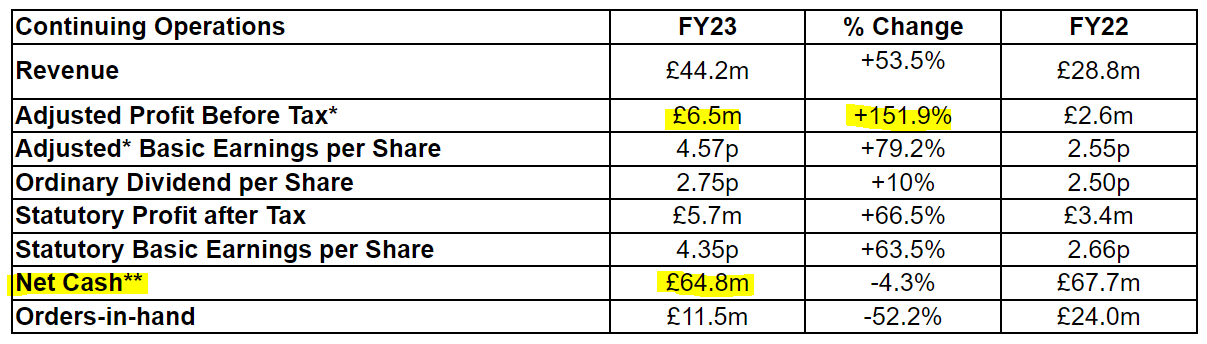
Vicon seems to have been the only operating division this year, after disposals, and an acquisition which has only recently been done in Nov 2023 (after the FY 9/2023 year end). It's clearly traded very well.
Given that Vicon has some exposure to Hollywood, I think there was investor worry about strikes possibly having an impact. There’s no sign of that in these results, with operating profit having almost doubled to £4.85m, then net finance income of £1.4m taking it up to statutory PBT of £6.25m. Adjustments are only £0.25m, to result in adj PBT of £6.5m.
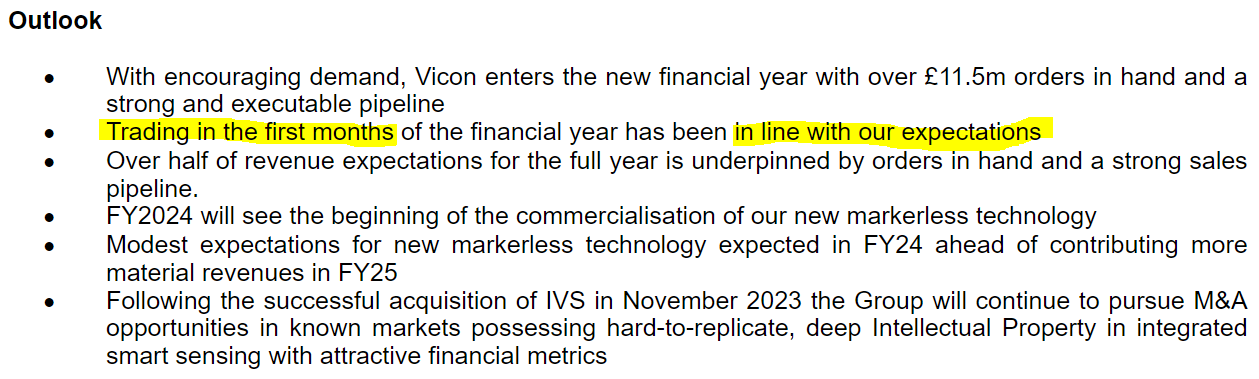
Outlook - sounds encouraging, but having searched the announcement, I can’t see any direct reference to FY 9/2024 expectations, which they seem to have dodged, which introduces a little doubt into my mind.
Also the order book has more than halved, from £24m to £11.5m, said to be due to supply chains normalising. But even so, that’s less visibility than a year earlier -
Acquisition of IVS happened post year-end, in Nov 2023. It says this is earnings enhancing, and sounds as if it’s in a similar/same sector (so less risk of them buying a dud, probably).
Details are here. The price was £8.1m, paid mostly in cash, plus 1m new OMG shares. This leaves OMG with plenty of remaining cash firepower, c.£60m for more deals. Let’s hope it’s spent wisely, as blowing the cash on a duff acquisition is probably the biggest risk for shareholders here.
Paul’s opinion - the simplest way to view this share, is to just halve the market cap, taking off the remaining £60m cash pile. Is Vicon + IVS worth the remaining £60m then? Based on its FY 9/2023 performance, I’d say that price looks perfectly reasonable, attractive even - but it depends on what the future holds, which being a mere mortal, I cannot predict.
I’d like to know more about the background of the new CEO, Imogen Moorhouse. In particular, what M&A experience she has? That’s key here, as half the market cap being a cash pile, demands that it’s either preserved, returned to shareholders, or spent wisely on value-adding acquisitions.
I’m a little uneasy at the outlook comments ducking the issue of confirming full year expectations. So for that reason, I’ll shift down slightly from green to AMBER/GREEN - so still positive, but a little more cautious here.
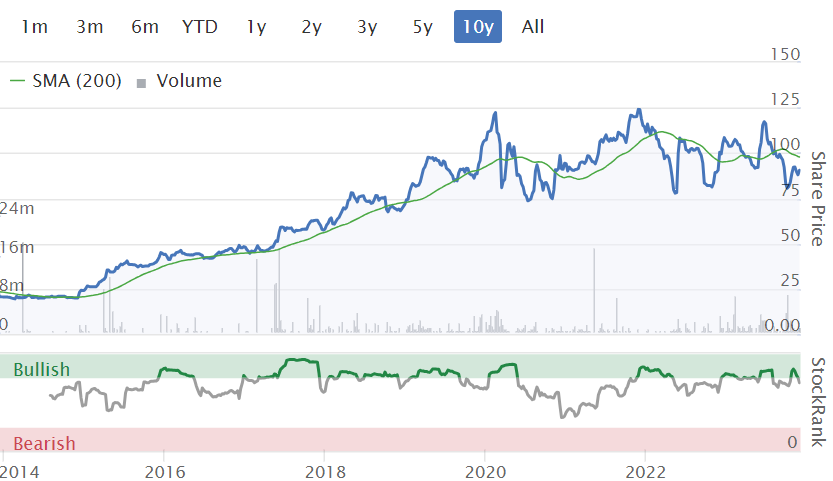
Shares haven't done much in the last 5-years, although zooming out to 10-years below does show nice shareholder value creation -
Porvair (LON:PRV)
Up 3% to 624p (£290m) - Trading update (ahead) & Acqn - Paul - GREEN
Porvair is a group of specialist filtration, laboratory and environmental technology businesses. Its businesses design and manufacture a range of bespoke consumable filtration products that are used in a range of niche filtration markets. It operates in three divisions: Aerospace & Industrial; Laboratory; and Metal Melt Quality.
We like Porvair here at the SCVR, because it’s a good quality business, making decent margins, with a lot of repeating business from high end consumable filtration products. It got through the pandemic well, with no dilution, and has also self-funded various sensible acquisitions of complementary businesses over the years.
My only gripe with PRV shares is that they’ve almost always looked too expensive.
That changed here on 15/9/2023, when I finally went GREEN on it, having worked out that the FY 11/2023 forecasts were likely to be too low. So allowing for a future beat against forecasts, the share price then of 598p actually looked a tolerable price to pay a couple of months ago.
Sure enough, it has indeed today issued an “earnings ahead of market expectations” update for FY 11/2023, but with no indication of how much of a beat, or what market expectations are.
Current market expectations are 33.7p, but I estimated that something nearer 40p looked on the cards, based on 20p interims, and upbeat outlook a few months ago.
Other details today say (for FY 11/2023) -
Higher margins
Flat revenue vs LY
Some sectors up, others down
Net cash of £14m at 30 Nov 2023.
Acquisition of EFC, a complementary Belgian company, earnings enhancing, E10.5m revenues pa, turns £14m cash pile into a “modest surplus”, so vague on exactly what has been paid for EFC.
Paul’s opinion - I reckon Porvair might be on a PER of about 15x right now, which brings it into my possible buys arena. Given that the price is only up 3% today, it looks as if almost everyone else had also worked out that the forecasts were too low!
Nice, quality business, and at a reasonable valuation, so I’m happy to stick with GREEN.

Graham’s Section:
tinyBuild (LON:TBLD)
Share price: 4.9p (-20%)
Market cap: £10m
tinyBuild (AIM:TBLD), a premium video games publisher and developer with global operations, provides an update on trading and a litigation settlement.
It’s an awful update from this video games company this morning, with a profit warning and talk of an equity raise.
Checking back on my recent notes, in September I noted that the company was still forecast to finish the year with cash of $10-20 million, and resisted the urge to give the company the thumbs down. I hoped they would find a way to avoid burning their remaining cash pile and “spending themselves into shareholder oblivion” - but unfortunately it seems that they have continued to do so.
People will point fingers at the company’s current CFO (since June 2023) who was previously (since Feb 2021) their head of M&A, and before that was an equity research analyst in the City.
However, if misfiring M&A deals were the only problem here, the situation wouldn’t be nearly so bad.
Internal spending on software development at TinyBuild has been extraordinary: $36m in 2022, and $17m in the first half of 2023.
And these internal investments have also been very unsuccessful, leading to huge impairments.
In December 2021, the company reported net cash of $48.8m.
This had fallen to $26.5m by December 2022.
Today we learn that cash has fallen to just $5.7m as of the end of November, and is “expected to be below previous expectations of $10-20 million at end of December 2023”.
Here are the key points from today’s update:
Trading is below expectations, with FY23 revenues now expected between $40-50 million (note the wide range!). Previous consensus forecast was $49.9m.
Multiple “Versus Evil” games have been delayed into 2024.
“Company is exploring near-term options to strengthen the balance sheet”, with the CEO and founder expressing a willingness to underwrite a raise of up to $10 million.
A “cost reduction plan” has been accelerated, but it’s clearly too late now from the point of view of avoiding shareholder dilution.
Litigation settlement - the acquisition of Versus Evil by TinyBuild in 2021 has resulted in a dispute between the sellers and TinyBuild. The dispute is settled with a $3.5m cash payout to the sellers. The CEO and founder of Tinybuild has made a personal guarantee to make the payment, should Tinybuild fail to do so!
Cash position - is expected to decline further and to be in the “low single digit millions” at the end of the year. New funding is likely to be needed by the end of January 2024.
Outlook - “cautious”.
The Company expects continued pressure on discounting in a crowded market for new releases. The planned launch of certain promising games in 2024 gives reason for optimism and this coupled with a leaner cost base could translate into strong operating leverage in the event of a recovery in video games sales.
Graham’s view
In hindsight, I should have been “RED” on this share already, but the company’s fairly recent insistence that it would finish 2023 with over $10m of net cash swayed me from doing so.
The CEO still owns 38% of the shares, which was another reason for me to think that the company would be more careful with its cash balance and reduce spending before things got out of hand. Apparently not.
The CEO’s willingness to take part in a new equity raise is perhaps the explanation we need: he would be happy to increase his stake in the business again, at this derisory valuation.
This is another 2021 IPO that represents a large wealth transfer from stock market investors. Over £100m of shares were sold, now worth pennies on the dollar.
I have to be RED on this stock now, with an unknown but probably significant level of dilution on the way.
Peel Hunt (LON:PEEL)
Share price: 93.5p (+1%)
Market cap: £115m
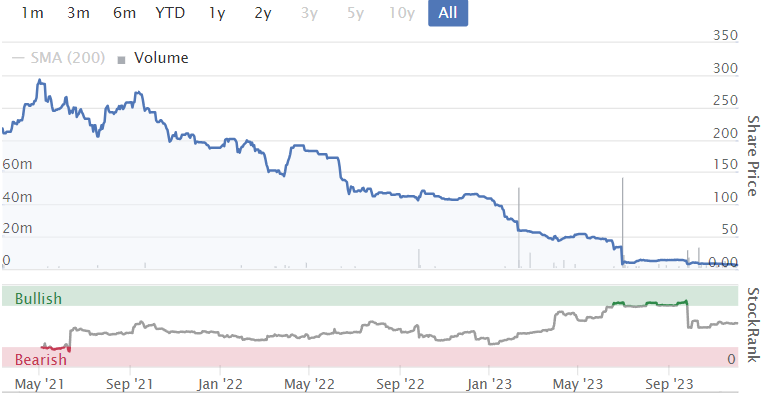
This was another well-timed 2021 IPO, but at least Peel Hunt’s share price has been stable for the past year or so.
Today’s interim results show a small increase in revenue year-on-year, and a pre-tax loss of £0.8m (H1 last year: pre-tax profit £0.1m). This reflects “the challenging macroeconomic environment and inflationary increases in costs”.
As I’ve said before (e.g. October), I think shareholders should be satisfied if these investment banks can achieve breakeven in very lean years such as this one.
One of the main attractions here is the balance sheet: net assets are holding steady at around £93m, with capital “comfortably in excess of regulatory requirements”.
The cash balance falls to £22m, “largely due to the accelerated reduction of long-term debt by £6.0m during the period”.
CEO comment: “we are well positioned for when market conditions improve”.
Average headcount declined by 2% as the company stays ready for whenever we might see that improvement.
Current trading/outlook: refers to the current wave of “take-private” activity, as shares trading too cheaply get taken off the market by strategic buyers:
Trading in the first two months of our second half has been broadly in line with the first half. Since the start of the second half, macroeconomic and geopolitical concerns have continued to weigh on equity markets and, whilst there are some signs of positivity, market activity remains relatively subdued. IPO and private fundraising activity continues to be muted. Take-private activity continues as valuations for UK quoted companies remain attractive, particularly to strategic bidders, and we have been delighted to support our corporate clients in raising equity finance to fund M&A transactions during the period.
Graham’s view
No need to change my view on this one. I remain positive around these levels, with the company well-positioned for a future bull market (patience may be required) and with the net asset backing reducing the risk.
The company has paid one dividend since its IPO, in the middle of last year.
It will be very important for me to see Peel Hunt returning cash to shareholders whenever it does get back into the black and is able to do so. These banks do need to demonstrate they are shareholder oriented whenever they can. But for now, it’s just a waiting game.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

111 comments
Tell him not to worry unduly. £42,000 or £49,000 in a year while you have a million in the bank should be ok either way!!
Another valued company that the price made no sense at all is being bought by US interests
Ten Entertainment (LON:TEG)
Well spotted Yiannos re Ten Entertainment (LON:TEG)
Based on current SP this could be a nice 50% upside if
a) true and
b) agreed.
More on Sky News...........
Bushveld Minerals (LON:BMN) An email from my investment platform this afternoon:
Dear Investor
We wanted to alert you about a Retail Offer by Bushveld Minerals Limited, a stock you hold with us.
As an existing holder you have the opportunity to buy more shares in the company via this Retail Offer.
The offer price for this Retail Offer is 3 pence per new Ordinary Share.
They must be joking! Sadly I have held this stock for nearly 3 years and failed to get out in time so am now left with a holding nearly 90% down from the cost (purchased at close to 20p!). Investing a relatively small amount of my equity portfolio in what was always a speculative venture seemed like a good idea at the time!. A vanadium miner with major interests in in the potential growth area of vanadium based battery storage was worth a punt I thought. How wrong can you be - there is no way I am going to throw good money after bad by taking up this retail offer. Any other investors out there with holdings in this highly speculative stock who will be brave enough to take up the offer!?
The Offer appeared in my ii account with this proviso "The company reserves the right to close the offer at any time without prior notice. Should you wish to participate please submit your subscription instruction as soon as possible". Like yourself ACounsell, I have held Bushveld Minerals (LON:BMN) for 3 years and consider that the cash was lost the day it was invested. After all, this is Africa.
Bushveld Minerals (LON:BMN) Sorry to hear your pain ACounsell. I held for 6 months in 2021 and gave up. I bought in at 18p and sold towards the end of the year at 10p. One of my better decisions!
Bingo Intercede (LON:IGP) major US order sp jumps 24% on he day, at last back from the depths for once patience was indeed a virtue although I'm now only 4% up. Surly this has far to go and has to be a possible bid target all that wonderful knowhow on the cheap.
I hope you don't mind me adding my few thoughts here on Plexus Holdings from yesterday.
From my understanding, Plexus pos grip technology is the entire solution.
Let me explain with a simple analogy. Your kitchen cupboards and drawers get loads of wear and tear so the screws, etc., come lose. This is what happens with conventional equipment used by oil and gas companies hence methane emissions, greenhouse gases. Conventional equipment needs loads of regular maintenance shutdowns to overcome these problems.
With plexus pos grip technology this doesn't happen at all. Pos Grip technology equipment doesn't need any regular maintenance shutdowns.
So, as far as I can see, all oil and gas companies need to be using Plexus pos grip technology.
Also, Plexus are back in the Jack Up business with help from SLB, Schlumberger.
The link to the plexus holdings website page is to help you understand their pos grip technology.
Here it is:- https://www.plexusplc.com
Plexus Holdings (LON:POS) An interesting Study of possible future costs to the USA oil and gas companies of Methane leakage on Morningstar. https://www.morningstar.co.uk/...
https://www.bloomberg.org/pres...
FROM THE LINK ABOVE:-
First-of-its-kind global methane initiative, with support of new $40M commitment from Bloomberg Philanthropies, will provide the transparency and accountability frameworks to help track and drive methane emission reductions from oil and gas industry.
You should create a different thread about Plexus Holdings (LON:POS.
I personally prefer to read interesting analysis, INCLUDING FINANCIALS , that some very very intelligent people post here and then make my own research and investment decision.
Hi Johnnycomelately,
I just replied to your yesterday post, but in essence, while what you say is correct, their "entire" solution is applicable to wellheads. There are many, many more potential sources of emissions (leaks).
I guess we are both right in our way!
Regards, Jon
Lowland Investment (LON:LWI) - results today show a few interesting charts, underlining how unloved the UK has become. Quite unbelievable. I suspect the catalyst for mean reversion may be "The Magnificent Seven" experiencing gravitational force in 2024!
Valuation levels
http://www.rns-pdf.londonstockexchange.com/rns/6268V_1-2023-12-4.pdf
Fund flows
http://www.rns-pdf.londonstockexchange.com/rns/6268V_2-2023-12-4.pdf
Share buy-backs on-top of 4% dividend yield
http://www.rns-pdf.londonstockexchange.com/rns/6268V_3-2023-12-4.pdf
Good charts - clearly show things all started going downhill in 2016 - I'll leave it there.
Thanks Topvest. Sobering reflection on how the world sees our economy/markets.
To add the Big Picture there is this:
According to the Office of National Statistics UK insurance and pension fund ownership of UK equities has fallen to just 4.2% in 2022 – of this total, pension funds owned 1.6%.
This is in contrast to 1997 when both insurers and pension funds owned 45.7% of UK shares. The portion of UK shares owned by overseas investors reached 57.7%.
Another trading 'glitch' in FTSE smallcap stocks at a time of historically low volumes.Not good!Anyone notice this?
'London Stock Exchange suffers new trading outages'
'Small-cap stocks affected in incidents that appear identical to glitch in October'
'The London Stock Exchange suffered two outages on Tuesday morning, hitting trading in hundreds of small-cap stocks and marking the latest glitch at a venue battling falling trading volumes. '
'Only stocks on the FTSE 100 and 250 indices and global depositary receipts, a certificate representing shares in overseas companies, were able to be traded.'
'The LSE first said it was investigating the issue at 9.29am, with trading suspended in companies including online retailer Asos, drinks maker Fevertree and polling business YouGov. At 10.17am, it said normal trading had resumed for affected stocks.'
'But just over an hour later the exchange suffered a second outage, hitting the same stocks again. “We are undertaking immediate analysis,” it said at 11.35am.'
Source : Today's FT.
Norcros (LON:NXR) nice broker note out for the unloved and often ignored norcros (not by me i must add being the perma fanboy here)- all they want for xmas is a p/e of 7.4 , probably the equivalent of a keeping 50's child happy!!
https://www.edisongroup.com/re...
If we apply the 7.4x forward P/E multiple to our estimate of FY24e diluted underlying EPS of 31.5p, we arrive at a value of 236p/share, implying c 45% upside to the share price
I quite like the lack of pimping up on the norcros broker notes - they strike me as being realistic and hopefully give some room to be beaten if the economy here and in sa takes a turn for the better. They arent afraid to say next year may be worse than this year due to the fact "it might be"
in the meantime i will subsist on my pe of 5 stale bread and water
Focusrite (LON:TUNE) .
I know many are keen on this at the moment. I held it in the past. I'm not sure that it's going to recover as quickly as expected as I'm not sure there is going to be an imminent splurge of spending.
I note this RNS of today entitled 'director dealings' but they are just nil cost options and not very many. If there were some actual director buys, I would be less sceptical.
Investegate | Company Announcement
Focusrite (LON:TUNE)
Closely followed by another RNS with a LOT of NIL cost options.
Maybe they have so many NIL cost options, there's no point buying any? :)
Is that good? Not my preference.
newsfile.refinitiv.com/getnewsfile/v1/story?guid=urn:newsml:reuters.com:20231205:nRSE7594Va&default-theme=true
#TBLD
Often its worth reading employee reviews on Glassdoor before investing in someone like tinybuild.
Moved to reply
Glenveagh Properties (LON:GLV) Anyone know if the Helikon Long Short Equity Fund Master ICAV holding through a financial instrument is a long or short ? They took a similar position in Feb 2022
Great $8m contract win by Intercede (LON:IGP) from Large US Federal Agency.
"This order, with an aggregate value in excess of $8 million, with all the
licence element of this contract being recognised in the Group's financial
year ending 31 March 2024 ("FY24"), means that the Group now expects financial
performance will be significantly ahead of market expectations for FY24*.
The Group wants to highlight that this contract is an exceptional order and
deemed 'one-off' due to the large number of perpetual licences purchased which
will be recognised in FY24."
And also a spectacularly well-timed purchase of shares by the chairman on Nov 22nd........
To be fair, his purchase was the day after upbeat interims. See Paul's SCVR review on 21/11 for commentary.
Subsequent edit - shares are now up 59% since Paul's positive review on 21/11.
It is a whopper for IGP.
Although a one off they do go on to add '... The Group believes that this new relationship has the potential to develop further as the Group's solutions roll out across hundreds of locations.'
I'd like to know whether their Fido offering played a part, it would be even more positive if so.
888 Holdings (LON:888)
If they are willing to rebuff both Draftkings and Playtech, then 888’s management and major shareholders must still be confident of the company pulling through this difficult period. [no section below]
could there not the element of them wanting to save face by them not admitting the business is worth less than they might pretend its worth?
Following Andy's comment yesterday, I must say I am also finding the usefulness of the traffic light system under stress. If something is running at a loss (Peel Hunt (LON:PEEL) ), can it really be classed green? Being "well positioned for a future bull market" sounds quite a lot like a prediction to me, rather than an assessment of the current trading and financial position?
Off the top of my head I remember Yu (LON:YU.) having great figures but getting a poor amber/red as profits may not be sustainable. A fair comment, but also a prediction of the future?
Sorry to be critical, but it is meant to hopefully be constructive. I appreciate the inherent difficulty in getting the balance right and I know DYOR and all that. I've been here a while but a new subscriber might find it a bit confusing. Interested in anyone else's thoughts?
Thanks for the follow up MattH. The inconsistency for me and the reason for me raising it was the discrepancy in colour coding between Frontier Developments (LON:FDEV) and Team17 (LON:TM17). FD has been making a loss and is also losing top line sales growth but was Green whereas Team17 is still growing top line and still in profit but they are now under pressure owing to development cost overruns and they were Amber/Red. Note that both companies have a mkt cap less than NAV.
On the matter of Green technologies which featured yesterday in the Smallcap chat. I see Velocys (LON:VLS) has had a recommended cash off of 25p per share -a far cry from the heights of its market valuation -by Madison Bidco on the basis of injecting $40m for capital investment.
Wasn't Abramovich involved in the early days of this Company?
0.25p. Thankfully a stop loss got me out at 6p
In a previous post Paul queried whether a large amount of Oxford Metrics (LON:OMG) PBT was actually from interest income and so we shouldn't 'double count' the profit whilst giving full credit for the cash pile. Today we find out they generated just 1.2m in interest income.(They probably should have done better , even if rates were much lower at the start of their financial year). So excluding the interest income we are still getting £4.8m of NOPAT on a 60m enterprise value. Management reiterating their 5 year plan targeting 70m revenues at a 15% PBT margin (tax very low due to tax breaks on R and D spending)
Oxford Metrics (LON:OMG) Progressive Broker forecasts have been increased today by 10% and 6% for 2024 revenue and EPS respectively so not sure there is any reason to worry about the limited detail on the outlook
Thanks for update on Oxford Metrics (LON:OMG) Paul. (I hold)
you wrote "I’d like to know more about the background of the new CEO, Imogen Moorhouse. In particular, what M&A experience she has? That’s key here, as half the market cap being a cash pile, demands that it’s either preserved, returned to shareholders, or spent wisely on value-adding acquisitions." According to Linkedin she has worked her way up the Vicon ladder for 23 years but does not actually include M&A in the list of her skills. I've wondered whether the drift in share price has been down to the company not having looked externally for a new CEO and/or director sales some months back.
No small cap shares can be traded at the mo and since 9.15am - so all market maker only shares. Only FTSE 100 and 250. Must be a cock* up. Last time this happened took some time to put right. Take the morning off. *apologies for use of bad word.
Thanks Robbie! Markets bit crap anyway 0-)
Porvair (LON:PRV)
Agree with BnB. A well managed growth orientated company trading well and on historically low metrics. I have been building a position slowly at prices between 530p and 600p
Hi Paul,
Re On Beach group (LON:OTB) you mention that;
" Adjustments to profit are quite large, with some of these being questionable"
Which of of 4 adjustments you highlight are reasonable as the PER would nearly double if not?
Thanks
Porvair (LON:PRV) - TU is probably not worthy of much investigation by the guys because it's broadly in line - revenue miss but profit beat on higher margins. Revenues were only held back in the life science segment with other divisions performing very well. And that is a known post-pandemic market weakness with multiple suppliers to that sector having a seriously down year. It is not unreasonable to assume better trading in due course for that segment and then the key will be to sustain momentum in the strongly performing other divisions. That would deliver considerable profit growth if margins stay high - which may be a challenge in a possible slowdown. Very steady long term growth record. And, at lower valuation today, an attractive acquisition candidate for a quality compounder like Halma, Ametek, Idex, Fortive etc.
On Beach group (LON:OTB) has a StockRank of 30 only and it passes 3 Short screens!
That will probably change when the figures are updated.
On Beach group (LON:OTB) only 2 short screens now and SR is now 64. I did not expect it to change that much. Probably go up again tomorrow as shares are up 10% today.
Titon
Rockwood imcrease to 27%
Looks they will get to just under 30% then stop .
They have “made their move” now with getting rid of Keith Ritchie outgoing chairman and puppet master of founding family .
It’s bounced up to 85p, anyone considering I think you’ll be able to buy lower in the next weeks . (80p )
hi planetx
Titon Holdings (LON:TON) and Colefax (LON:CFX)
I can see the appeal of Titon to you, largely related to the involvement of Rockwood and the likely exit from the South Korea joint venture.
But in a nutshell this is still a high risk nano cap with a high spread, low liquidity and sellers would have serious difficulties in trying to exit should things go wrong.
I noticed yesterday re Colefax you said;
Colefax, illiquidity and value traps and buy backs .
Had a rethink on Colefax.
Mentioned it to Lisa Sanderson of SDG who pretty much said good “family” company .
Looks like zero ambition in this company albeit a well run steady state asset backed nice company .
I always like the share buybacks here too but just dawned on me this is reducing sharecount and liquidity in an already very illiquid stock with family members who never sell and rubbish free float
No rush really but going to be a long slow process to slowly reduce without freaking out the share price .
Schoolboy Lesson learned that liquidity is important .
Doesn't Titon carry many similar risks (with the exception of buy backs), in particular the liquidity risk?
Obviously your money and your choice but nano caps are by their very nature high risk investments and probably best left to those, like you, with a very high risk tolerance.
This isn't meant as a criticism, merely an observation.
I do enjoy reading your considerable input on this forum and respect your honest and forthright views.
Hope Titon works well for you and I wish you every success in your investment choices.
Snazzy
Titon v Colefax
Huge differences .
Firstly I’m “overweight” in Colefax at circa 8% of my holdings , I’m not selling completely as it’s a very stable bedrock share that has actually been a blessing in the past period as it never really moves and is stuffed with cash / assets and no debt .
Will reduce to 4-5% and just let it run along, it’s a sleepy share but also a “sleep well” share . And the directors will continue to reward themselves for their sleepy management team unique .
Colefax is family / director controlled with family / directors running it as cash cow for their retirement so they won’t invest or grow .That’s not a terrible strategy .
Titon is vastly different and yes it’s a nano cap , I’m only building and it’s 1.5% weighting so small but I’ll try to get it to 5% level but no higher unless things really start to happen .
It just seems a very simple turnaround, to the point I could do it myself, the “backdrop” is the understated freehold which is if I remember 7 million but only in the books at 2 million . Rest is just very simple execution .
The risk is really if the product is rubbish and demand evaporates but even though the market is soft right now new regulatory requirements mean new builds have to be fitted with trickle vents .
Finally it is actually a fun thing to be involved with to see it unfold , I can take the pain (as well As the gain )
Rockwood will push it all along, it is strikingly similar tIo Crestchic
Rockwood / harwood have a very active approach to finding buyers so following then into a turnaround is worth considering .
They pretty much have no exit other than force the change through, improve , and exit .
I wonder how Rockwood plan to exit from Titon Holdings (LON:TON) What do they usually do with big stakes in illiquid companies?
They put the whole company up for sale.
....but on occasion after they've taken it private first....
#TPXimpact H124 results webinar at 12.30 today (following results published this morning.) Register here.
Full Year 2024 is in line as follows:
With the backlog or committed revenue at c90% of forecasts. They say the new business pipeline is very encouraging. Join us at 12.30.
A terrible update from tinyBuild (LON:TBLD) this morning. A major profit warning, settlement of legal battles and will be out of cash by January! Not an earnings, just a trading update, but thought I would put out a quick snapshot.
Unfortunately I hold this, one of the mistakes I count as the cost of education in the stock market :). Built a position around 40-50p thinking the valuation was great and couldn't go much lower, lol. Lesson learnt, hopefully.
Sorry to anyone else who is holding out there. I think this may be a coinflip whether it recovers or goes to zero, but expect a huge fall this morning, so not sure it will be worth getting out. As Paul has been saying recently I think the whole game development industry is a no go at the moment, though do believe when the industry turns they will all rocket, as long as they survive to that point.
tinyBuild (LON:TBLD) I sold this for a big loss back in June simply because I thought they would burn through the 10m cash they had.
In hindsight I should have done the same. Well done for having the conviction to do so!
Only plus is CEO offering to throw £10m of his own money at it. If that gets approval I will probably take up the rights.
I bought what I knew was a very speculative investment/gamble at 11p. (If it goes bump, well I have lost far more this year on my larger, lower risk holdings!)
Three lessons I have taken from this, that are now rules for me:
1) Don't buy IPO's, wait until they have been public for three years.
2) Don't buy in a down trend.
3) Sell on the first profit warning.
Those are generally good rules. Not buying in a downtrend is the hardest because you often don't know until six months after you bought!
Haha yes I agree. I've started using mental stop losses for new positions. That way if I'm wrong and the down trend continues my losses are capped. I know stop losses are a controversial subject, but since I've started using them I've found everything a lot easier and I've already avoided a couple of big falls, Calnex Solutions (LON:CLX) being one of them.
Agree ,it is difficult to break the habit of not to buy in a down trend. A lot depends on your strategy though. But it is better imo to buy in an uptrend when the downtrend has been broken out off.
I still have nightmares years later after buying Luceco (LON:LUCE) while it was in a downtrend. I bought at the bottom of the downtrend channel and sold at the top off that channel for a nice 35% profit. I was very happy at the time. Unfortunately the price I bought at was 33p.
All true, I'm waiting to see if I get away with Eneraqua Technologies (LON:ETP)
Sold most but kept a small holding, just in case they turn it round, they are in the right space
Hi NewInvestor1972
Do you give up on the On Beach group (LON:OTB) V easyJet (LON:EZJ) race ?!
Whenever I did not sell on the first profit warning I always regretted it.
Good rules.
If anyone needs strong evidence for not buying small cap stocks in downtrends then take a look at this chart. It shows the performance of UK small caps, comparing the top and bottom 5% by momentum rank. Following the trend pays, even if it seems high and scary to buy there!
The top 5% has over 700% return in the last 10.75 years... thats 21.5% annualised rate of return vs the bottom 5% which has resulted in you losing your life savings.
A case for sell the tinyBuild (LON:TBLD) and buy the McBride (LON:MCB) 's of this world!
McBride (LON:MCB) has a very chequered history, if you bought 10 years and held, you would not have done very. They were in downturn for many years until recently.
Yes, but if you only focused on buying and holding the top 5% of momentum stocks you would never have been caught in McBride (LON:MCB) 's multi-year downtrend. However, if you had bought it in the last month or so, you would have done very well.
Following their earnings announcement in mid-October, the momentum rank moved to 99 and has stayed there ever since. This means you could have got in a c.41p and would have a healthy 77% in 6 weeks.
Yes you will have done well if you bought McBride (LON:MCB) a few months ago, I was rather put off by Paul Scott review in the SCVR. Debt is too high, for me, as well.
Interesting, where did you get the data from?
You can find it here on the Stockopedia website:
https://www.stockopedia.com/le...
Interesting. But it is bottom 5% that has performed the best, this year, in £1m-100m stocks: https://www.stockopedia.com/le...
Micro caps 0-50m, even more so: https://www.stockopedia.com/le...
The Micro caps do perform very well but in reality, you will never be able to trade a strategy around them due to their illiquid nature. Small caps have just enough liquidity to make it viable as long as you don't overtrade.
One thing you'll notice is the stark difference between small and large cap performance... It just doesn't pay to be in large caps (historically speaking anyway)
Yes but large caps have outperformed recently, it really depends on the market. In a bull market small caps outperformed, in a bear market they tend to get savaged. The top 9 Momentum stocks are all large caps, then comes McBride (LON:MCB).
Yes large caps have done very well this year and have been a safe haven during this bear market, so definitely, something for me to learn from in the future. I've done some basic analysis of the top 5% momentum rank performance and if you want to optimise long run performance, you will stay in small caps, even if they are getting hammered in the short term.
Mid caps also perform well during the bullish years, but tend to revert harder during the bear markets, on average. Sticking to mid cap stocks can be good if you value liquidity or have a large portfolio.
Momentum has done poorly in the last 2 years, this screen has been particularly poor: https://www.stockopedia.com/sc...
I don't know the rules of the chart you are showing, can you give us more information?
The rules of the chart are:
UK stocks between £50m-£350m inclusive.
Rebalanced Quarterly
Excludes dividends, fees and spread costs
However, my backtested research shows dividends, on average, are 2.13% with an average spread of 3.7%, and you'll only pay stamp duty tax, on c.35% of your portfolio holdings.
However, if you filter out all stocks with a spread greater than 4%, the average spread drops to a very reasonable 1.7%.
Yes I have found it now, thanks. I just did a screen £50-350m, Momentum 95 and over, there are only 16 stocks. Some have done very well lately. 3 are bid situations, however none of them would have qualified, just before the bid.
Yes, I've been tracking this screen for several years now and I find the screen only offers 10-15 names, so more concentrated than the standard 20-25 names you see in the Guru screens / Naps etc. This may well go on to explain why it outperforms.
comparing the top and bottom 5% by momentum rank.
does the momentum rank not simply tell you that these stocks have done well - in which case confiming they have perfomed well should be no shock if thats teh samplem we have picked.
To me you would want to do sample and look forward 1 year bsed on ranks now and compare
Calcs may be fair and reasoanble but i suspect the fcat they have good momentum simpoly confirms price has "gone up in the past"
momentum here today may be or may not be here tomorrow
Had plenty of learning experiences myself!As long as they're not wasted.They're the cost of future success...The management there really put me off.I was lucky to avoid that one.
And you're right.. some are bound to rebound majorly when the market finally (!) turns....Cash burn is an issue there though.My personal punt is Frontier Developments (LON:FDEV) as they do have a series of successful titles in the past.That was my only reason to buy as i know nothing about the game dev industry personally and i'm not a gamer.Underwater currently ofcourse.
Had the pleasure of speaking to Onward Opportunities' portfolio manager & Investment Director Laurence Hulse.
Very smart man and he's confident that many stocks at these levels are a great opportunity. We talked about markets and some stocks he's holding/likes the look of.
Thank you Michael that was an good chat about the markets. He manages Dowgate funds so it would have been even more interesting to have dug down into some of their conviction holdings and why they like them.
As much as generalist chats are interesting, fund manager interviews are opportunities for them to pitch their conviction plays to the retail market who can then cherry pick which ideas to go away and look into further. For example Dowgate, who have very limited funds, just recently bought 3% of Pennant International (LON:PEN) (I hold), would have loved to hear more about their thinking behind such purchases...
Thank you. Yes, some fund managers do like to talk their own book (and I am no different!) but I'm aware some private investors have been hugely burned following fund managers into talked up stocks on platforms like mine, so I prefer it not to be solely stock picks etc.
Yes, Pennant has been the perennial turnaround. Was at its CMD last summer and the presentation was so technical it was pointless. Sandwiches mediocre too. But been following it since waiting for it to break out!
Appreciate the feedback.
My morning smallcap tweet: Decked by dreck
Peel Hunt (LON:PEEL) tinyBuild (LON:TBLD) Various Eateries (LON:VARE) Gfinity (LON:GFIN) Water Intelligence (LON:WATR) Ethernity Networks (LON:ENET) Taylor Maritime Investments (LON:TMIP) Aferian (LON:AFRN) DP Eurasia NV (LON:DPEU) Cohort (LON:CHRT) AdvancedAdvT (LON:ADVT) Porvair (LON:PRV) CML Microsystems (LON:CML) Quiz (LON:QUIZ) Learning Technologies (LON:LTG), Solid State (LON:SOLI), Tpximpact Holdings (LON:TPX)
◄Peel Hunt (PEEL)► H1-Sept. Headline trumpets rev in line but rest is a let down. Pretax -£0.8m "reflecting the challenging macroeconomic environment and inflationary increases". Outlook - H1 trading broadly in line with H1 with market activity relatively subdued. "IPO and private fundraising activity continues to be muted." [SP=91.63 Cap=113m]
◄tinyBuild (TBLD)► warns FY23 rev only $40-50m and net cash only $5.7m after unusually weak trading in October. Looking at fundraise of up to $10m. Rev mix remains tilted towards lower-margin third-party games, Co settles legal case, will pay $3.5m. [SP=6.25 Cap=13m]
◄Various Eateries (VARE)► re: speculation - planned fundraising of up to £12m at 25p, and a potential debt for equity conversion. [SP=27 Cap=24m]
◄Gfinity (GFIN)► has disposed of the remaining business and assets of its former Esports Solutions Division for £15k. [SP=0.06 Cap=2m]
◄Water Intelligence (WATR)► Jan-Oct rev up 6%, adj pretax (before non-cash expenses of amortisation and share-based payments; and non-core costs) up 14%. Confident. [SP=410 Cap=71m]
◄Ethernity Networks (ENET)► guides FY-Dec rev $3.6-3.8m ($2.97m) and EBITDA loss $3.8m max ($6.4m). Considering options to raise additional funding. Outlook - "we are hopeful that 2024 will be a transformative year for Ethernity and, with our careful cost control on the reduced operating cost base, our goal is to generate positive cashflow". [SP=1.93 Cap=4m]
◄Taylor Maritime Investments (TMIP)► sells Handysize vessel for $7.8m gross. [SP=63 Cap=267m]
◄Aferian (AFRN)► guides FY-Nov rev c.$47-48m and adj EBITDA c.$1.6-2.6m. Some sales delayed into FY24. [SP=10.05 Cap=11m]
◄DP Eurasia (DPEU)► 85p offer fundamentally undervalues co. Feedback from a significant proportion of shareholders concurs. [SP=88 Cap=128m]
◄Cohort (CHRT)► wins 5 yr follow-on contract for €16m from ELAC. [SP=510 Cap=212m]
◄AdvancedAdvT (ADVT)► update on move to AIM. Biz uodate and general boasting. [SP=83.8 Cap=109m]
◄Porvair (PRV)► guides FY-Nov earnings ahead of market expectations with higher margin on revenues likely to be similar to those of 2022. Buys EFC, a Belgian filtration business, for undisclosed sum. Expected to be earnings enhancing in its first year. [SP=608 Cap=282m]
◄CML Microsystems (CML)► H1-Sept in line. Guides FY rev slightly ahead of market expectations, with the majority of the growth due to the addition of MwT biz. Profit in line. [SP=389.78 Cap=63m]. I hold.
◄Quiz (QUIZ)► H1-Sept rev down 14% and pretax -£1.5m (+£1.8m). Online rev down 22%. Warns FY rev 6-8% and pretax below mkt exp. Review of the strategic options. [SP=6.6 Cap=8m]. I hold.
◄Learning Technologies (LTG)► sells Lorien $21.4m or 5.2x EBITDA. [SP=72 Cap=569m]. I hold.
In line: SOLI, TPX
Premier Miton (LON:PMI)
Popular amongst subscribers I believe and discussed in the past - I for one would be grateful for Paul/Graham's view.
PREMIER MITON GROUP PLC
FULL YEAR RESULTS FOR THE YEAR ENDED 30 SEPTEMBER 2023
Robust investment performance despite market volatility.
Premier Miton Group plc ('Premier Miton', 'Company' or 'Group'), the AIM quoted fund management group, today announces its final results for the year ended 30 September 2023.
Highlights
· £9.8 billion closing Assets under Management 4 ('AuM') (2022: £10.6 billion)
· Strong investment performance with 73% of funds in the first or second quartile of their respective sectors since launch or fund manager tenure
· Net outflows of £1,147 million for the year (2022: £1,076 million outflow)
· Adjusted profit before tax 1,4 of £15.7 million (2022: £24.3 million)
· Adjusted earnings per share 2,4 of 8.80 pence (2022: 13.79 pence)
· Profit before tax 3 of £5.9 million (2022: £14.9 million)
· Cash balances were £37.9 million at 30 September 2023 (2022: £45.8 million)
· Final proposed dividend of 3.0 pence per share (2022: 6.3 pence per share)
· Total proposed dividend for the year of 6.0 pence per share (2022: 10.0 pence per share)
· Significant continued investment in fund management and distribution talent to help create a modern, active asset management business positioned for future growth
Post period end
· On 1 November the Group announced the acquisition of Tellworth Investments LLP, a leading UK equity boutique with AuM of £559m as at 30th September 2023
· Tellworth offers both long/short and long only strategies to wholesale and institutional clients with potential for institutional distribution, building on Premier Miton's developing presence in that market
· A continued focus on inorganic opportunities alongside our clear organic growth strategy
Notes
(1) Adjusted profit before tax is calculated before the deduction of taxation, amortisation, share-based payments, merger related costs and exceptional costs. Reconciliation included within the Financial Review section.
(2) Adjusted earnings per share is calculated before the deduction of amortisation, share-based payments, merger related costs and exceptional costs.
(3) Merger related costs totalled £0.1 million during the year (2022: £0.1 million).
(4) These are Alternative Performance Measures ('APMs').
I would also like their view
Premier Miton (LON:PMI) I suppose it's cheap but looks pretty underwhelming - over a billion of outflows (more than 10% of opening AUM) and very mixed performance across the fund range. They just don't seem to offer anything distinctive - lots of generic UK equity funds. There are hundreds out there so why would you choose one of theirs?
On Beach group (LON:OTB) - results look good, nice cash position and ahead for next year
Yes, cracking results On Beach group (LON:OTB)
Current Trading and Outlook
• Our FY23 growth has continued into the new financial year with YTD TTV as at 2 Dec +26%.
• Our forward book is at record levels and Group Winter '23 YTD TTV is +34%.
• We approach our key booking period in Q2 with significant momentum.
• Our platform and proposition are stronger than ever and we are taking share in adjacent markets.
• Current trends and strategy give us confidence that Summer '24 will be significantly ahead of Summer '23.
• Reinstatement of dividend from FY24 reflecting the Group's continuing cash generative position and in line with its capital allocation framework
The outlook sounds positive for On Beach group (LON:OTB) and finally profits are broadly in line with (earlier revised) broker expectations which has not been the case for a few years...
One thing that does continue to concern me though is overhead costs. In 2019 these were 18% of (lower) revenues but they are now 30%. Overhead costs for FY23 were also 24% higher than FY22 which may in part reflect the need for more staff to cope with increased demand plus inflationary pressure on wages.
Edit - digging into this a bit more I am confused what 'overheads' includes and excludes for On Beach group (LON:OTB). They have overheads as £32.3m but 'Administrative expenses before exceptional items and amortisation of intangible assets' are £87.6m (and which don't look too bad versus previous year in an inflationary environment). Any ideas which of these items includes overheads?? I might write to the company.
They really ramped up recruitment at On Beach group (LON:OTB) between 2022 and 2023. I think they mentioned in a previous update that they've slowed down now, so hopefully this means with continued revenue growth (potential +34% for the winter season and beyond) we start to see some operational leverage to operating profits.
However, they do capitalise alot of development spend (ie engineer salaries internally) so these will start to weigh down in the years ahead.
As for travel demand... well... despite all the soft retail demand you see in the news, Brits still have a huge appetite to travel. Where does this money come from? Who knows. Even I have been surprised by the resilience of travel demand. But I have accepted this new paradigm of travel higher up the list in spend priority, for many people.
(I hold in the Boon Fund)
Bit of advice please !!
Best place for cash for 1 year ? Circa 1 million
“Schroeder’s government bond 12 months 4.9% after tax ??”
Met a friend of mine yesterday just sold his business and finally after 30 years of stress and graft he finds himself with a pot of money and no idea what to do with it .
He wants to put away 1 million for 12 months and asked what I thought to Schroeder’s uk government bond which he said
- was 100% guaranteed
- paid 4.9% tax free
As I have absolutely zero idea about gilts , bonds etc I said I’d ask for an opinion on here .
Can anyone offer a suggestion
I know he wants a 12 month lock away with zero risk whilst he unwinds and enjoys a breather .
What’s the best suggestions ?
Great question Planetx
I've recently purchased the 5% Gilt #TR25, which matures on 7th March 2025 (ie 16 months) & yields 5% (priced at par ie £1). The spread is minute (<0.2%) & all the income is tax free because the gilts are held within my ISA/Sipp.
Should be risk-free too given its issued by the UK government/Treasury vs Schroders
Paul
Thanks
He doesn’t have the luxury of ISA tax free wrapper
He says that schroeders had claimed theirs was governement backed which doesn’t sound right.
I’m better getting more info I think.
He’s a great designer / entrepeneur but as in many cases pretty rubbish with money .
It is not really the investment that is the primary issue here - the tax angle overwhelms the investment return over 12m.
And we have far too little information to comment really - how old is he, what are the CGT liabilities he's incurred in extracting the £1m (if any) and what is his ongoing income??
Has he paid off all his mortgages/debts? That is often the answer for the risk-averse in a higher rate environment. In effect you "earn" your mortgage rate free of income tax (but IFAs make no money from this one.....).
If he has, a low coupon gilt is the obvious answer so that he takes most of the return as capital as the gilt pulls to par (capital gains on gilts being CGT free). And it may be the wrong one without any knowledge of his circumstances!
He should be using up the full 3 years of pension carry back for himself, then his spouse, then both their ISA allowances....kids' pensions etc. If he's sitting on a large CGT bill then CGT rollover into EIS etc becomes interesting....and very risky.
I suspect he may need a better paid advisor - he doesn't need to pay fees for a year to Schroders or take any duration risk, and he can get far better control of his tax situation with one single gilt.
I lost a lot of money on an EIS...steer clear.
EIS either needs to be diversified, or a means to invest in something you have some insight & influence over.
By count I have had more losers than winners, but by value the gains on the winners easily outweigh the losses - even without any of the tax benefits.
EIS is just a wrapper, like an ISA. You can buy good things and bad things via EIS.
But yes, usually very high risk, even with diversification because the companies often sink or swim based on the performance of a few key individuals or one product.
The fees are also astronomical in % terms.
But if you are sitting on a large capital gain, the Treasury is effectively willing to defer the CGT bill so you can have some fun.
Outside a ISA it’s important to consider the tax implications. The 2026 1/8% Gilt will pay an effective 4.32% virtually tax free - the return is almost all capital gain rather than interest and the capital gain is not taxable. It can be readily bought and traded on HL etc. There’s a chance it will gain more earlier and less as it winds down to maturity if rates are cut soon, which would be a bonus. This is not financial advice of course but I own it in my family portfolios.
I've bought a couple of Gilts recently as per BnB - outside of an ISA/SIPP as the capital gain is tax-free whereas short term money in a savings a/c is taxable at your marginal rate - so despite getting slightly less growth to maturity on my Gilts over the next 18mths it is a better option than paying a whack of tax on the 5.08% I can get with Santander savings.
He should also consider (if he has one) his wife's accounts as well - dependent upon their tax position this might help.
Morning planetx - I can suggest Treas 0.25% Jan 2025 trades at 95 ….u need to hold to maturity otherwise u get hit with 2 sets of fees but otherwise pretty much risk free I’d say
Your friend needs proper advice from a professional. Surely he has a financial advisor if he has that level of wealth?
Of course he has financial advice from a fee earning professional .
He asked me what I thought yesterday.
This is the advice he had received .
As a contrarian and entrepeneur I find it very good strategy to not just accept financial advice from “professional financial advisors”but to DYOR also .
Hence I’m asking here .
Forearmed is forewarned .
Personally I think he’s nuts and given his proven track record and ability it is a really dumb move .
PS (replying to RCTurner
That’s actually a very interesting comment .
“Surely he has financial advisor if he has that sort of wealth”
What you will find is that founders / entrepreneurs when they finally a crystallisation event they are unprepared for it .
For years you are wrapped in the day to day building a business and then suddenly one day you get spat out into “the real world” with a suitcase or money and no idea or plan .
You will generally be a bit knackered, want a rest , want to enjoy life etc but your personal finances will be a bit all over the place with no real plan
He only asked me cos I went through the same 3 years ago .
The best advice I received was “treat your wealth as pots”
I’m 90% certain he’s going to do something really special in the next 3 years so I’m advising him not to put on a long lock away .
I’m the counter I guess to his “professional financial advisor”
The fact is a lot of "professional financial advisors" are pretty poor, especially when it comes to investment advice where there is sometimes a shocking lack of knowledge. Just one example, I know a couple of IFAs who couldn't understand why index-linked gilts fell so heavily over the last couple of years, as they were expecting them to perform well when inflation went up.
Gilts and Bonds
Not much discussed here and I enjoyed reading all the comments.
An ifa is needed. We don't know much about this person apart from its a man probably 50 to 60 with 1m cash and 1 1y timescale
If he doesn't have a house maybe good to buy one
If he has health issues probably cash
If he has problems with self control possibly an annuity
Otherwise would suggest senior secured corporate debt with a short duration.
I’m not asking for financial advice
Just the best place for 1 million tied away for 12 months .
That’s the actual Question
In that case simple - a short dated gilt, but make sure it is a low coupon one (that way the gains will nearly all come from capital and be exempt from CGT, the high coupon 5% gilt mentioned above would be clobbered with a lot of income tax!),
As mentioned above, one of the very low coupon guilts is his best bet I think - pull to par is tax free (no CGT on guilts). There's a 31 Jan 2025 0.25% guilt trading at c.95p. No limit etc and obviously fully govt backed (as they're the creditor!)
I suspect far better advice would be available here than from the average IFA, sad to say.
My personal experience (unwinding my parents' affairs) is that the advice is very narrow and focussed on commission & the administration awful. The one area where I felt to be gaining was in tax advice - until my mother died. Then we discovered the investments had been set up in the wrong name.........
The claim for negligence went surprisingly easily.......!
Morning PlanetX
Not zero risk, nothing ever is, but your friend may wish to consider putting a modest amount of his hard earned money into Jpmorgan UK Smaller Companies Investment Trust (LON:JMI) . it is to merge with JPMorgan Mid Cap Investment Trust (LON:JMF) early in the New Year. As a result there will be an overall reduction in fees and a change to the dividend policy. The latter will adopt the same approach as the successful Jpmorgan Global Growth & Income (LON:JGGI) in that it will pay a dividend based on 4% of NAV. Both trusts have the same management team of Georgina Brittain and Katen Patel and similar portfolios. Below is an extract from the 14 November RNS.
Jpmorgan UK Smaller Companies Investment Trust (LON:JMI) has a good medium to long term performance. It is currently out of favour but this should change as the interest rate climate eases. It presently trades at around a 13% discount to NAV. For these reasons I have been slowly building a position.
There is an excellent discussion on the Money-Makers podcast regarding the proposed merger, which is free to listen to. Link below.
Money Makers | Money Makers podcast: 18 Nov 2023 (money-makers.co)
The Board of JPMorgan UK Smaller Companies Investment Trust plc ("JMI" or the "Company") is pleased to announce that it has signed Heads of Terms with the Board of JPMorgan Mid Cap Investment Trust plc ("JMF") in respect of a proposed combination with JMF to be effected by way of a section 110 scheme of reconstruction of JMF (the "Scheme") and issuance of new ordinary shares of JMI as consideration for the transfer of part of JMF's assets (together with the Scheme, the "Transaction").
Following the successful completion of the Transaction, the enlarged JMI shall continue to be managed by JPMorgan Funds Limited ("JPMorgan"), with Georgina Brittain and Katen Patel as lead portfolio managers, and the Company shall pursue its existing investment objective and policy.
The Board believes that the Transaction will enable JMI's existing ordinary shareholders to benefit from continued exposure to the UK Smaller companies investment strategy, the greater economies of scale that are expected to result from the enlarged asset base, including cost efficiencies and greater liquidity in JMI's ordinary shares.
As part of the Transaction, the Board has also agreed the following changes:
- an enhanced dividend policy targeting a 4 per cent. yield on NAV per annum, calculated on the basis of 4 per cent. of NAV as at the end of the preceding financial year, payable in equal quarterly instalments;
- lower management fees: to be 0.65 per cent. p.a. on JMI's net assets up to £200 million and 0.55 per cent. p.a. on net assets above £200 million (currently 0.65 per cent. p.a. on JMI's net assets up to £300 million and 0.55 per cent. p.a. on net assets above £300 million);
- Significant cost contribution from JPMorgan by way of fee waiver;
- the enlarged JMI will be renamed JPMorgan UK Small Cap Growth & Income plc, with JUGI as the new ticker; and
- three directors from JMF will join the Board. It is intended that one of the former JMF directors will step down at, or prior to, the 2024 AGM.
Morning planetx interesting question with too little info but if I was looking for no risk over 1 year I would take a look at one of the NSI investments. Income Bonds are doing 3.6% up to a million with easy access and monthly interest. And of course no fees etc. But not exciting.
You can buy a low coupon gilt and benefit from the tax free gain generated when it matures. Or you could buy a solid near maturity QCB bond which benefits from the same tax benefits but gives you a better overall yield even after paying tax on coupons.
Putting money in Schroders is not good advice.
Planetx
I know you've already had loads of replies, but for what its worth a suggestion would be as it sounds like he does not want to worry about anything or have any hassle and to sleep sound at night with no risk of the firm his money is with going bust then not sexy and not the highest rate but Nsandi 3.65% gross up to £2mln 100% backed and what the hell put £50k into premium bonds too - Or he opens 12 accounts not in the same group and gets circa 5%.