Small Cap Value Report (Tue 5 July 2022) - SAGA, MERC, SUP, KITW, AO., DFS

Good morning from Paul & Graham.
Many thanks for your kind comments yesterday re my new small caps podcast. I'm happy to keep making these, on Saturday mornings, since there's clearly an appetite for them from you. The idea is to recap on the week's best (and worst!) small cap announcements. Then a bit of general macro/market musing. I think it helps me try to make sense of things too!
If we can spread the word, and drive some newcomers (and lapsed former members) to Stockopedia subscriptions (where there's more detail than in podcasts), then that will help keep the wolf from the door too. When markets plummet, many people disappear without trace, only to pop up again when the sun is shining again. Yet in the past, I've found that the work I do during bear markets tends to line up the big winners of the future (and avoid things that could go bust in the meantime).
Agenda -
Paul's Section:
Saga (LON:SAGA) (I hold) - a reassuring trading update, with proper guidance this time (£35-50m underlying PBT - much improved from circa breakeven for last 2 years combined). Insurance division is set to become less profitable per policy, due to a decline in new business. Travel continuing to recover, with good forward bookings in cruise. Debt is fine, with long maturities, and loose covenants. For long-term investors, I think there's plenty to like here, and am encouraged by this update, as the plummeting share price made me wonder if bad news was on the way. Turnaround taking longer than expected though, but it is happening.
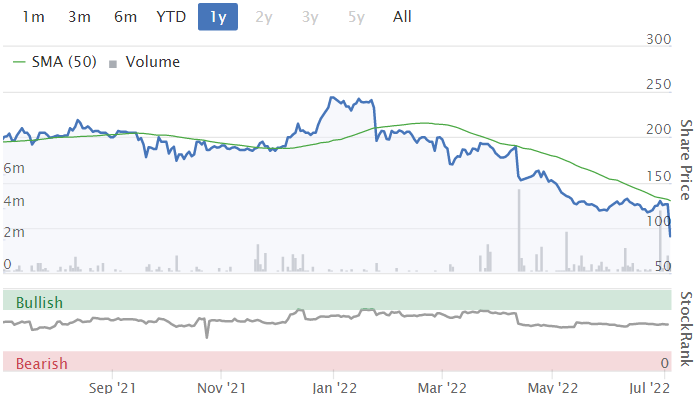
Supreme (LON:SUP) - a profit warning that's confined to the lighting division, where customer de-stocking has triggered a significant drop in expected profit for FY 3/2023. Divi payout ratio is being cut in half, but I'm satisfied that's not from weak finances, it's to prioritise M&A. Balance sheet is sound. Today's drop in broker forecasts is a bit shocking, so I'll need more time to have a think on this share, but for now the share price reaction looks about right after a bombshell warning today out of the blue.
AO World (LON:AO.) - a response from the company to negative press comment came out yesterday afternoon. It reassures that things are OK, until the last sentence, which reintroduces doubt over whether it might need to do a placing. I'm steering well clear, as it's too risky for me.
DFS Furniture (LON:DFS) - many thanks to MrContrarian for spotting this trading update, buried within an RNS about the CFO moving on. It's a good update, with profit for FY 6/2022 at the top end of guidance. As always, the deal-breaker is its horrendous balance sheet. Don't expect the divis & buybacks to continue in a consumer downturn, as they're already on a flimsy financial foundation. High risk, due to balance sheet weakness.
Graham's Section:
Mercia Asset Management (LON:MERC) (£133m) - final results from this fund manager and investor show a strong improvement in adjusted profits, and more exceptional gains on business disposals. This looks too cheap against earnings, suggesting the market is sceptical that these exceptional gains can be repeated any time soon. But supporting the valuation are balance sheet net assets of £200m, including the unrealised gains on Mercia’s investments.
Kitwave (LON:KITW) (£105m) - this food and drink wholesaler was listed on AIM in May 2021, and is a new stock for us to look at. Trading has picked up very strongly in the post-Covid environment, and brokers have materially raised their earnings estimates. The stock is cheap against forecast earnings but the company is carrying some debt and is likely to engage in further M&A, so there is an element of financial risk involved.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Saga (LON:SAGA) (I hold)
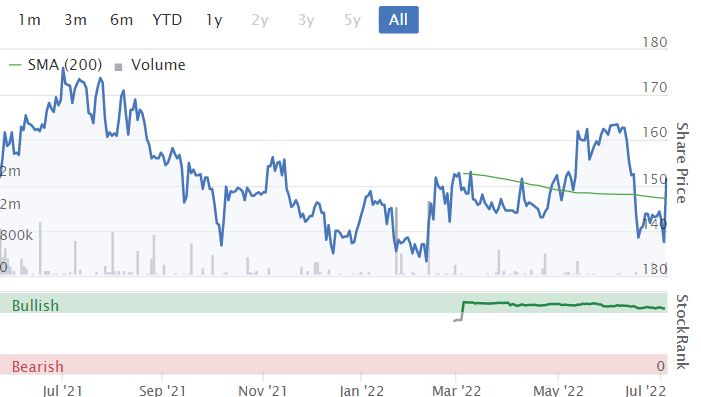
167p (before market open)
Market cap £234m
Trading Update (AGM)
Saga plc (Saga or the Group), the UK's specialist in products and services for people over 50, provides the following update on trading covering the period from 1 February 2022 to 4 July 2022.
PR headline -
Saga on-track to return to underlying profit
It’s worth noting that some of us were unhappy about the previous guidance given to the market, which was very vague, just saying they expect a profit this year, but not how much!
Management justified this on a webinar by saying there are significant uncertainties. Sure, but most companies can still manage to give a range of profit guidance, so I don’t see why SAGA couldn’t too.
Main points -
Insurance -
There’s been a decline in new business.
Profit per policy (home & motor) slightly down, “broadly maintained” at £73.
Margins expected to fall to £60 per policy next year (FY 1/2024), to drive growth.
Travel -
Current year FY 1/2023 - load factor now 73% for cruise, to rise to 75% (was 68% in H2 LY)
“Exceptionally strong” cruise booked load factor for this summer (no number provided).
Daily rate £319 (up 6.7% from £299 last year), which I imagine would recoup most increased costs (and fuel is hedged at start of each season).
Outlook for cruise sounds encouraging -
Strong launch of 2023/24 Cruise season with bookings representing a load factor of 34% and per diem of £312, both well ahead of expectations.
Holidays (i.e. the rest of travel division) - running at a “small loss”, “much improved” from last year. “Encouraging early signs” for recently launched next year bookings.
New guidance - I take it all back, about vagueness! We now get proper guidance for this year, which looks OK to me -
The Group expects to generate 2022/23 Underlying Profit Before Tax of £35-50m and grow future earnings from this level.
The expected outcome for 2022/23 is in line with the range of analyst expectations and compares to a prior year Underlying Loss Before Tax of £7m.
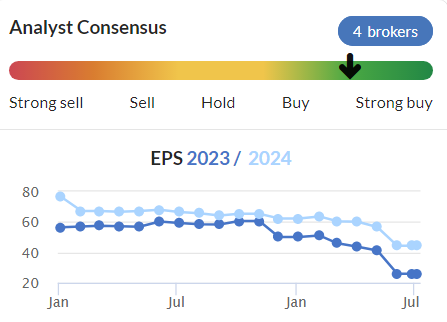
Actually, I’m really encouraged by this. The share price has been in free fall, so I was dreading this update, imagining that the roof might be falling in. Instead we have a reasonable outcome guided for this year, in what was always going to be a partial recovery year. Although note broker estimates have been reduced a lot (that's why the share price has fallen so much) -
Balance sheet & liquidity - a brief update -
The Group's balance sheet remains resilient with significant available liquidity; simplified revolving credit facility with reduction in commitment from £100m to £50m.
The important thing to note here, is that SAGA’s admittedly heavy debt is secure. It’s mainly 2 loans to finance its 2 owned (nearly new) cruise ships, so there’s a corresponding tangible asset, very much like HP on a van.
The other debt is a £150m [sorry, earlier typo corrected] (remaining) bond due for repayment in May 2024 (fixed rate 3.375%), and £250m newer bond, repayable in July 2026 (fixed rate 5.5%).
The 2 ship loans were £516m at Jan 2022, and are repayable in recently resumed instalments, ending in June 2031, and Sept 2032.
On top of which, SAGA maintains a big cash buffer, which was £187m at Jan 2022. So there’s enough in the kitty to pay off the first bond in full, and still leave a comfortable cash buffer. This is absolutely not a distressed situation.
The bank facility has not been used, and isn’t needed. So the available facility reduction from £100m to £50m makes sense, and probably lowers fees.
Therefore, I see SAGA’s debt (and hence equity too) as safe - no maturities, or interest rate risk in the foreseeable future. What a good thing it refinanced during the pandemic, with an equity raise (cornerstoned by Sir Roger de Haan, founder's son & long-serving former CEO), and a bond refinancing that looked unnecessary at the time, but has locked in ample, relatively cheap, fixed rate debt. So a very canny move, as it turns out. Compare that with larger rival Carnival, which is having to issue fresh debt at 10%+ interest rates. One broker even said recently that Carnival could go bust, in the worst case scenario.
Covenants (I looked at these again recently in the comments here) are fine - only applying to the ship loans, and set at a level where the group would have to be loss-making to trigger them. Since we’re guided today to a profit of £35-50m, then the ship loan covenants are not an issue.
Video of SAGA’s growth plan is here.
My opinion - I’m rather encouraged by this, in the context of a plummeting share price.
The main downside today is that insurance is becoming less profitable, probably due to changes in the rules on pricing, which we already knew about.
Travel seems to be recovering.
There are no issues at all with debt or covenants - that’s a complete red herring, as explained above.
I remain firmly of the view that this is a nice 2-year turnaround, and it looks like things are on track, although note that broker forecasts have been lowered considerably. So the turnaround is slower than I had originally hoped, but still very credible I think.
In the context of a market cap down to only £234m, this share looks very good value to me.
It’s been dragged down by Carnival (LON:CCL) recently I think, where debt issuance is looking distressed. SAGA doesn’t have any issues of that kind, with secure, and cheaper debt than Carnival.
Don’t expect miracles overnight with SAGA, but as a long-term hold, I think there’s a lot of potential here. I’m certainly more bullish today, than I was yesterday.
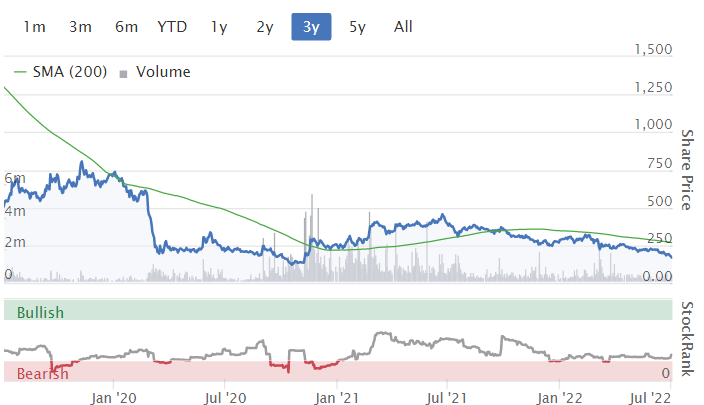
My hunch is that a reassuring update today, with proper guidance, could put a floor under the share price, after big recent falls. Who knows though, anything could happen in current volatile markets.
.
.
Supreme (LON:SUP)
87p (down 31% at 09:03)
Market cap £101m
I’ve had a generally favourable impression of this company, checking back through my notes:
10 May 2022 - company updated re McColls, and said it was “trading well”
12 April 2022 - strong trading update for FY 3/2022. Outlook was for another positive year for FY 3/2023, although tempered by cost increases.
7 Dec 2021 - interim results & outlook looked good to me here.
Clearly there’s a bombshell within today’s results statement, to have caused shares to drop 31% this morning.
Supreme (AIM:SUP), a leading manufacturer, supplier and brand owner of fast-moving consumer products, announces its audited final results for the year ended 31 March 2022 ("FY22").
Headline numbers look fine -
Revenue £130.8m (guidance on 12 April was >£130m)
Adj EBITDA £21.1m (guidance: >£21m)
Adj PBT up 6% to £17.4m
Adj EPS 12.8p (up 7%)
At today’s 87p per share, the PER is only 6.8
Net bank debt is modest, at £1.9m.
Divis - 3.8p final to be paid end Sept, 2.2p interim already paid = 6.0p total, yield of 6.9% - same as the PER, you don’t see that very often - but divis are set to reduce from 50% of profits, down to 25%, implying the future divi yield would drop at least half, down to maybe 3%, once we take into account lower profits and the lower payout ratio.
Outlook/ Current Trading - this is what has clearly spooked the market.
Profit warning -
The Group expects to deliver another solid, profitable year in FY23 but revenue and EBITDA are both expected to be below FY22 levels and below previous market expectations, driven by a recent marked decline in the Lighting category following a slow-down in sales compounded by customer overstocking in FY22.
Following discussions with its key customers the Group believes this slowdown in sales and profitability will be temporary and limited to the Group's Lighting category due to specific customer over-stocking in the past 12 months.
That’s a very interesting point about customers overstocking - Luceco (LON:LUCE) said something similar in its recent profit warning, so this looks like it could be a more widespread problem unwinding this year.
However, in this case, the problem sounds ring-fenced in one division, and temporary, so maybe not that bad? Although it does imply that FY 3/2022 results would have been boosted by over-stocking by specific customers, so we should probably be reducing the forecasts on which we value this share.
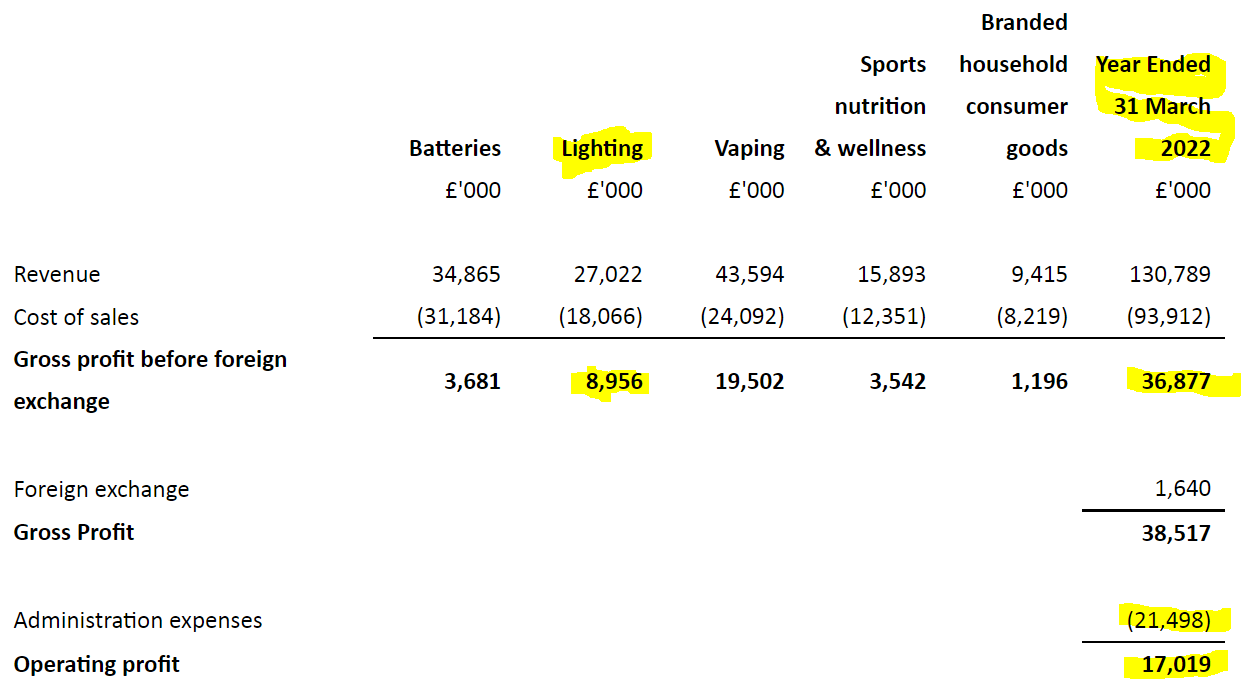
Actually, I hadn’t realised that lighting was an important category, but this note from the accounts shows it’s the second most profitable product category, after vaping -
.
Visibility is said to be good for the lighting category, due to long lead times. Profits are expected to improve again in FY 3/2024.
Vaping - outlook is strong, with +30% revenue growth expected in FY 3/2023. It surprises me that this won’t be enough to offset the weakness in lighting.
More acquisitions are planned.
Overall -
In spite of the short-term trading challenges in Lighting, the Board remains confident that the Group has a long runway of growth ahead and is increasingly excited by the prospects for growth in the vaping division.
Presentation - is tomorrow, 6 July, at 11:00 - register here.
Balance Sheet - looks fine, and has notably strengthened in the year, due to retained profits.
The current ratio is strong, at 1.95.
This looks a well financed business, and I don’t have any concerns at all about solvency or dilution risk.
The cut in dividend policy therefore looks genuinely motivated by a desire to focus cashflows on funding M&A, rather than a forced cut due to stretched finances, which is clearly not the case. Although I do wonder if perhaps the bank might have indicated they prefer to lend for acquisitions, rather than bumper divis?
Broker update - Equity Development updates its forecasts today, with 9.3p pencilled in for FY 3/2023. That’s down a hefty 25% on FY 3/2022 actual results.
At 87p per share, the forward PER is now 9.4 - quite good value, but as we now know that the lighting division profits are more flaky than imagined, a lower PER does make sense.
My opinion - oh dear, another company that’s saying demand was pulled forward during the pandemic, and supply chain problems. Although this only impacts one product category at SUP, and it does sound temporary.
Has the market over-reacted, with a 30% share price fall, on top of an already steep decline previously? Or is this a disaster, with an immediate sell being the best option?
My view is that, based on the information provided, this is certainly not a disaster.
However, it’s a significant change in outlook. Previously, this share looked like a steady growth story, augmented with organic & acquisitions growth. However, we now know that last year’s profits were probably peak earnings for the time being - the same is likely at many companies, I reckon.
I don’t currently hold, but still think this is a fundamentally good business. Although vaping does carry some product risk, say if some awful news about the long-term health impact were to appear. And nicotine is a hideously addictive, pointless drug (no upside, only downside).
On balance then, I still like the share, but less so than yesterday, because the facts have deteriorated.
The 30% drop in share price is probably reflecting the new, less appealing reality. Hence I think it remains sensibly priced.
Providing nothing else goes wrong, then long-term holders should get their money back eventually, I imagine.
.
.
AO World (LON:AO.)
48p (down 13% today at 11:15)
Market cap £232m
Response to Recent Press Reports
AO World plc ("AO" or the "Company"), a leading online electricals retailer, notes today's share price movement following press reports over the weekend…
This came out at 13:53 yesterday afternoon, but I’d already downed tools here after a busy morning.
In yesterday’s report I flagged the worrying Sunday Times article, saying that trade insurance had been cut for AO, which could trigger a cash crunch.
AO’s response made these points (I’ve summarised) -
- Current trading, and financial position, “remain in line” with mgt expectations, and guidance provided on 29 April.
- One credit insurer “rebased” (i.e. reduced) cover for some suppliers, reflecting slower business post-pandemic.
- To date, this has had no impact on liquidity, which is in line with exps.
- German closure update - previous range of £0-15m was wide, due to uncertainty over lease exit costs (useful info). Now expected to be at lower end - good news.
- Bank facility (RCF) of £80m is available until April 2024.
- Everything sounds quite good up to that point.
However, as is often the case, it’s the last sentence that undoes the reassurance, and introduces uncertainty over whether this means a placing is being planned?
In addition, the Company continues to consider and implement a number of ongoing initiatives and further actions to strengthen its balance sheet while optimising its focus on profit and cash generation against the uncertain macroeconomic conditions in the UK and the continuing global supply chain challenges.
My opinion - I think that last sentence was a really bad idea. It sounds as if a placing might be coming, which is likely to be at a discount - who would want to refinance a struggling electrical retailer facing a consumer downturn & ongoing supply shortages? Maybe the founders might buy it back? I’ve tried to find the original prospectus from 2014, but no joy. It would be useful to find out if founders took out a lot of cash in the original float, as that would affect how they might be inclined (and how rich!) now.I think there was press speculation about a possible attempt to take it private.
Anyway, my view is unchanged, I wouldn’t touch it. In more normal markets, and if they had omitted the last sentence, then I think this share might have bounced. Unfortunately not, as the price has continued sliding today.
Too risky for me.
.
.
DFS Furniture (LON:DFS)
150p (down 2% at 12:31)
Market cap £382m
Director Change (and trading update)
The CFO is to leave, but it sounds amicable.
He’s to join B&M European Value Retail SA (LON:BME) which is bigger than DFS, so it’s clearly a career move, hence not necessarily something for DFS shareholders to panic over.
An orderly transition is planned too, which also reassures that there probably hasn’t been a massive bust-up.
If a company puts out a trading update, then it needs to be headed accordingly, and put in the right category on the RNS, which this wasn’t. This update is just titled “Directorate Change”, so it doesn’t appear on the trading updates list. Many thanks to MrContrarian for spotting it, hence alerting me to have a look.
Trading update today - looks like nobody checked this for typos! (sloppy) -
Further to recent our [sic] Trading update and the successful completion of expected deliveries to our customers prior to year-end we now expect profitability to be in the upper half of the range for underlying profit before tax and brand amortisation previously indicated.*
*range previously disclosed on 9 June 2022 for full financial year underlying profit before tax and brand amortisation of £57-£62m.
My opinion - this looks surprisingly good. The main problem with furniture retailers hasn’t been demand (so far, anyway), it’s been actually getting the product made and delivered to customers.
Therefore, it sounds as if supply chain issues might now be easing somewhat?
Although I seem to recall furniture was one of the big categories showing a slowdown in spending, in some recent economic data, can’t remember the source.
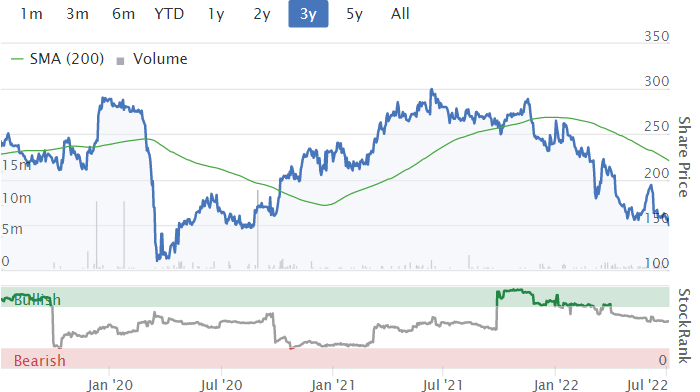
DFS also has a reckless share buyback going on currently, which I think is complete madness, given deteriorating macro conditions, and DFS’s desperately weak balance sheet.
When last reported, DFS had NTAV of negative £(255)m! They’ve spent the customer deposits, and run up bank debt on top of that.
The current ratio is terrible - current assets of £103.7m, but current liabilities of £387m! That’s a current ratio of just 0.27 - one of the worst I’ve ever seen. Although do bear in mind the furniture retail sector does run on negative working capital, but even so this is really extreme.
If I were a BME shareholder, I’d be seriously worried about what the new CFO is going to do to its balance sheet!
If there’s a severe, and lasting consumer downturn, then DFS would be very vulnerable potentially. As orders dry up, then positive working capital would unwind, worsening the cash position, as well as profits dropping.
DFS had to do an emergency placing when covid struck, and was lucky to have had keen support from major shareholders. Yet mgt didn’t seem to learn from that experience in 2020 - that its balance sheet is too weak to withstand an unforeseen crisis (or a recession). Instead they’ve been splurging the cash on more buybacks and excessive divis again.
For that reason, I would not rely on the high divis continuing at DFS.
I reckon that an incoming CFO might well want to pull the divis immediately, if they properly understand risk, and a deteriorating consumer backdrop.
For these reasons, and despite decent current trading, I’m steering well clear of DFS - too risky. Pity as the actual business is good, but its financial position is too weak.
.
.
Graham's Section:
Mercia Asset Management (LON:MERC)
· Share price: 30.25p (+5%)
· Market cap £133m
This is a regional asset manager which has broken above £1 billion in assets under management.
It manages a mixture of third-party funds and its own funds.
As of March 2022, Mercia has net assets of £200.6m. That gives you an indication of the company’s overall size (and also hints at an opportunity, since the market cap is significantly lower than this!).
Mercia invests across the spectrum from venture capital to PE and private debt.
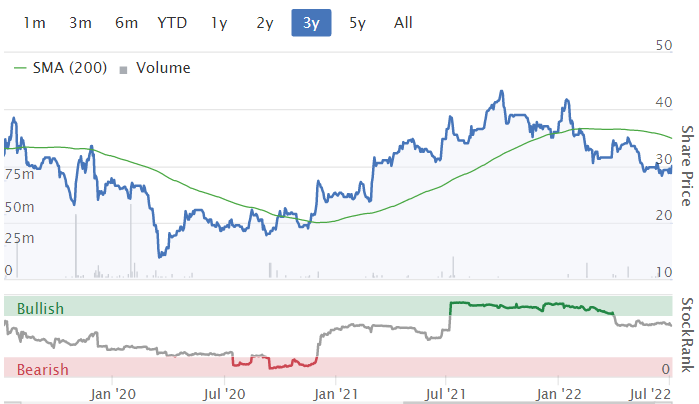
Its share price performance has been unexciting. Like many others, it collapsed in March 2020, then posted a strong recovery. That aside, the share price return has been dull, and long-term investors here have suffered:

I’m wondering has the market left a value opportunity on the table, after many years of boredom with the stock?
Today’s results show a pre-tax profit of £27.4m, down from last year’s £34m but these are enormous figures versus a market cap of just £133m.
Net assets per share were 32.1 pence in March 2020, 40p in March 2021, and now 45.6p in March 2022.
Different ways to measure profits
To help us understand the underlying profitability of Mercia, removing short-term fluctuations in asset values and gains/losses on business disposals, the company provides us with a measure of “adjusted operating profit”.
This profit measurement is much lower than the figures I’ve mentioned above, but it has taken off strongly from a low base: £0.5m in 2020, £3.3m in 2021, and now £8.4m in 2022.
This is Mercia’s profit before performance fees, gains/losses on disposals, and movements in the fair value of investments (and a variety of other things).
I can see the logic in using this measure, but I also think that it’s very conservative. If Mercia is good at what it does, then fair value movements in investments should hopefully be positive, and there should be gains on disposals more often than not! Also, you would hope for a non-zero performance fee.
In addition to all of this, Mercia earns interest on loans to its investees, and this is also excluded from adjusted profits.
It’s true that there is uncertainty around when and whether the investees will pay this interest, but Mercia earned £4.5m from this channel in FY March 2022. That helped to bump up pre-tax profit to the final figure of £27.4m.
In general, I think that the actual profit result should be much higher than adjusted profits. The adjusted profit numbers are still useful, though: they help us to see how the business performs even if there are no business disposals, no unrealised gains or losses, no performance fee, and excluding any interest received! It’s a very basic measure, but nice to have.
Dividend – Mercia has started paying dividends, and increases its final dividend to 0.5p. Total dividends for the financial year are therefore 0.8p, up from 0.4p in the previous year. The trailing yield is a useful 2.6%.
Faradion – the company had a huge win from the sale of a Sheffield-based battery technology company called Faradion in January. Cash of £19.4m was received from this transaction.
This transaction helps to explain the huge discrepancy between large pre-tax profits (which include the effects of selling Faradion) and smaller adjusted operating profits (which leave it out).
The discrepancy is further explained by a big uplift in the valuation of one of its holdings: ndreams, a VR game studio.
This company raised funds at a higher valuation than it had previously achieved, raising the notional value of Mercia’s stake in the business.
Future plans – after generating large amounts of cash from business disposals in the last two years, Mercia’s CEO says “we are unlikely to come back to our shareholders to ask them for more money to fund the Group’s direct investment activities”.
A year ago, Mercia set a target, to be achieved over the subsequent three years. The target was for £20m of pre-tax profit every year, and 20% growth in AUM every year.
It achieved the first of these, but not the second. AuM only grew by 2%, which the CEO explains as follows:
Although Mercia's assets under management are not open-ended, we have experienced higher than anticipated distributions to investors, ironically as a result of our excellent exit investment performance.
Mercia’s funds aren’t the OEICs (open-ended investments) like you might see from a traditional fund manager, so investors can’t just pull their money out of them whenever they want. However, they do make distributions to investors when there are large gains on disposals, and that is what happened in FY 2022.
My view
The progress made by Mercia has both surprised and impressed me.
When I wrote about it before, back in 2019, I was disappointed to see Mercia raising funds below its NAV, but the risk of that happening again looks to have evaporated.
I was also concerned about portfolio concentration, but I suspect that it has improved on this front.
And there is now far more evidence that the investment process works, and is repeatable.
The main difficulty is that the timing of disposals can’t be predicted, and unless you are very close to Mercia’s investee companies, it’s extremely difficult to predict the success or failure of any particular investment they have made.
So it’s really a question of trusting management and their process, and accepting that results will be lumpy from year to year.
It’s also about valuation: Mercia is trading at a discount to book value, has a worthwhile dividend yield, and is very cheap against trailing earnings. It has come to the attention of Stockopedia’s Ben Graham Deep Value Screen:
Risk factors? Well, if there are no big winners from the investment portfolio over the next few years, then underlying profits from fund management might not be enough to sustain the valuation.
It might also be reasonable to worry about whether the book value of Mercia’s investments would survive a high interest rate investment. This problem is not unique to Mercia, of course.
I’m very pleased to have had the chance to look at this one again. It’s on my watchlist.
.
Kitwave (LON:KITW)
Share price: 150p (+9%)
Market cap: £105m
This is a new stock for us. It listed in May 2021 at 150p, so IPO investors are flat so far. Today, it reports H1 results for the six months to April 2022.
This is a wholesaler with 27 depots supplying confectionery, soft drinks, alcohol, groceries, tobacco, ice cream, and so on.
The last time I looked at a wholesaler, it was Matthew Clark – whose reckless acquisition by Conviviality Group helped to send Conviviality into administration.
Conviviality had terrible balance sheet issues and shockingly poor management. So let’s head straight for Kitwave’s balance sheet and find some reassurance, if we can.
Figures for April 2022 show net tangible assets of £18m. At least this is positive, and might provide a small cushion for equity holders.
Working capital items are huge as you would expect for a wholesaler:
· Receivables £64m
· Inventories £40m
· Cash £6m
On the liability side:
· Payables £78m
· Borrowings £23m
It’s not stuffed with surplus assets by any means.
The company reports net debt of £46.6m, including lease liabilities. I think it’s reasonable to exclude lease liabilities from this calculation, and this leaves a more realistic net debt figure of £17.3m.
This reflects a foodservice acquisition which took place in February 2022, at a cost of £17m.
Overall, the balance sheet could be stronger, but I’ve seen much weaker ones from recently IPO’d companies.
Trading
H2 is running significantly ahead of expectations, and brokers have today revised up their earnings estimates.
Adjusted, diluted EPS is now expected to come in at 21.6p this year (previously 15.6p), then 22.9p next year (previously 17.5p). So the forward P/E on an adjusted basis is 6.5x.
Outlook
Strong comment from the CEO. Excerpt (I’ve added the bold):
With a track record of successfully integrating acquired businesses into the Group and having now executed our first acquisition since the Company's admission to AIM, we look forward to sourcing and acquiring targets that fit within our criteria, in line with our buy-and-build strategy. Meanwhile, efforts continue on converting opportunities for organic growth, such as through the roll out of the web-based trading platforms across the Group. These initiatives enable us to grow revenue and further improve relations with both our brand partners and our customers.
With trading having returned quicker than we expected post-COVID-19, Kitwave finds itself in a strong position to capitalise upon the opportunities available to it.
My view
I tend to think that wholesalers should trade at cheap earnings multiples. Perhaps Kitwave is now too cheap, given the prospects for the year ahead?
If the adjusted profits materialise as forecast, and are mostly converted to cash, that will help to drive down the debt figure and will boost my confidence that this is not another Conviviality in the making.
However, the reference to acquiring more targets in accordance with “buy-and-build” suggests that the balance sheet will be used in a more energetic way.
Careful investors will apply the IPO rule (i.e. wait for the stock to trade at a meaningful discount to the IPO price, before considering it).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Podcast..
Paul your podcast was brilliant and for one I think you should continue to publish. I know none of us can predict the market, your weekly view of the market as you see it is greatly appreciated as a week in the market at present is longer than a week in politics. Best
Paul, to provide a counter perspective to AO World (I don't hold) but I think it's an excellent business, run by a really competent manager. It operates as a capital light retailer with a strong culture of both operational efficiency and customer obsession. as it scales it passes back the efficiency and purchasing advantages it makes back into reducing prices for customers and improving the customer experience, widening their competitive advantage further. This has given them the number one position in online retail for main domestic appliances with over 50% market share. They've grown at over 20% per year and I would think that over the long term they have the opportunity to continue that growth as they expand into other areas of electrical retailing.
A capital light business that can turnover a large amount of volume, even with very low margins can be a really good business. Think Amazon as a well known example or Motorpoint (2% margins and 75% ROIC) here in the UK, which I believe you own as well, I see them operating very similar business models.
Heavy investments and losses in Germany and the Netherlands have covered over what is at its core a really solid UK business which generates cash flows and high levels of ROIC. My assumption would be that as they close down their German operation and market conditions normalise over the coming few years, they should be left with a market leading online retailer with good levels of profitability, cash flow and ROIC, which will start showing up in their reported numbers.
obviously news on the business is terrible at the moment, but I would personally not bet against them. Unlike a GAME which you used as a similar example, given the low fixed cost nature of AO I think that would give them various levers in which to pull where they would have the ability to navigate a sticky situation.
Of course I might be completely wrong, but just wanted to provide a counterpoint as I think it is a good business (not on the reported figures) but obviously there in lies the opportunity to uncover great investments when they go under the radar. Given the quality of some of the main shareholders in the business which include Greg Alexander (conifer), Phoenix Asset Management, Crispin Odey, William Burke etc.. there must be something to the business worth exploring further.
Hi Bully15,
Thanks for that, it's always good to hear a different perspective.
Some good points, well made, in your post.
I think for now, solvency/dilution concerns are too high for me to want to take the risk. However, if AO World (LON:AO.) does manage to successfully refinance, then I'll be happy to take a fresh look at it.
Regards, Paul.
Regarding Supreme (LON:SUP) the following extract from this morning's prelims sticks in my mind. If, as stated the nature of lighting sales facilitates good forward visibility of revenue. It strikes me that the significant decline in sales announced today was likely to have been apparent sometime ago. One could therefore ask whether the company had some indication of the developing situation when it provided an outlook for the current year in the Q&A to the trading update webinar on 25 April?
Just a thought, but it is all water under the bridge now and time to move.
"Whilst it is still early in the new financial year, the nature of lighting sales where a significant portion are sold "FOB" on long lead times means that the Board has relatively strong visibility into the latter part of the year and the expected weakness in trading."
Paul apologies if you have already addressed it but I couldn't see it, could you give us a view on Quiz. Appreciate not a great business but plenty of reasons to hold I felt (I do), which coincided with your own view last time round. Have to say 10% of portfolio in retail and that is part I regret most!!
Hi Camtab,
I've not looked at Quiz (LON:QUIZ) (I hold) yet, leave it with me, probably for tomorrow's report now.
Same with Equals (LON:EQLS) -it's on the agenda, but probably for tomorrow too.
Regards, Paul.
Various Eateries (LON:VARE) interim results presentation given to analysts with H1 22 results. They report a positive performance in spite of continued Covid disruption at the end of last year. They're making the most of vacant properties to get the best sites at the best price. They seem to be managing the general staff shortage issue well, likewise food inflation. Overall they are in line with expectations for the full year. We've been to Coppa at Putney and thought it was great. Video & podcast.
The 30% fall on Supreme (LON:SUP) this morning just shows how shaky the market is at the moment. Even with an earnings reduction in lighting, vaping growth should offset. This is a business with ROCE around 50% and it has doubled revenue since listing in 2019 . The operating margin is healthy for a FMCG business and I can't imagine vapers will stop vaping because of a cost of living crises - if anything they will probably vape a bit more. I'm disappointed in the new div strategy, proof will be in the pudding if new accretive acquisitions materialise. Nevertheless, at 88p it's easy to see upside here and hard to believe it can drop further. I have topped up this morning.
Hi Bronstein,
Re Supreme (LON:SUP) you said -
Even with an earnings reduction in lighting, vaping growth should offset.
Well that's the whole problem - updated forecasts from Equity Development show that is not expected to happen. The company says the same in its update. So all that growth expected from vaping growth is more than offset by the fall in lighting, which is a worry - as the fall in lighting must be a pretty serious downturn, although they claim it's temporary.
Thinking about it some more, this suggests there could be heavy reliance on one customer, that got over-stocked? So that's a key question to ask management, about client concentration in lighting, which I suspect could be the cause of this profit warning.
Regards, Paul.
Good point I will be asking tomorrow.
So, in case anyone rereads these. The answer was some concentration risk with biggest 3 lighting customers accounting for a third of revenue. Claim is that it was an industry wide phenomenon though
My recollection of watching a video presentation by Sandi Chadha (the CEO ?) . . . he explained that when they IPO'd they sort of got talked in to offering a dividend because it would make them appeal to Income funds as well as Growth but they hadn't really wanted to as their real strategy was acquisition and that this may have been a mistake, so a change to dividend policy is not a surprise.
Hi Paul, are your podcasts available on any podcast platforms? Thanks, Phil
Hi Philip999,
Hi Paul, are your podcasts available on any podcast platforms? Thanks, Phil
Not at the moment, as we're just at the trial stage. But it's easy to download, if you open it on a mobile device in chrome, then click the three dots next to the audio player, and select download (via WiFi), which can then be listened to if you wish, out & about.
Regards, Paul.
Thanks Paul
IG Design (LON:IGR) full year 2022 results webinar which Paul referred to in his excellent weekend podcast, well worth a listen. The new board come over well in the Q&A (the main presentation was pre-recorded). The outlook for FY23 includes a strong orderbook, 71% budgeted revenue (22: 60%) with a slight operating margin improvement, however this will be offset by higher financing costs. Management's focus is now on the existing businesses and no new acquisitions. Directors have been buying. It's an extensive Q&A and no questions were left unanswered. Video and podcast.
A general market observation was their comment on the UK supermarkets are far tougher to trade with than their US counterparts. I guess Heinz are showing us that.
Today, we've got the first of a two part series from Private Equity Funds who are represented by LPeC. Three funds will be presenting at each event, on how they invest in private companies or assets. Register for both here.
Today, 5 July, 2pm:
Thursday 7 July, 2pm
They're mainly UK, Europe and one a Nordic specialist. I'll be interested on their views on the broader macro background.
Boohoo (LON:BOO) issued 28,700,000 options to directors and some other staff last Friday, at zero cost or with a 1p exercise price, in the hope that it will incentivise them to do their jobs better. Don't they pay them a living wage, then?
Hi Paul - would you be able to take a look at Equals (LON:EQLS) after another positive update please? Company seems to be constantly upgrading expectations and lots of recent insider buying. Many thanks !
Sure, I'll look at Equals (LON:EQLS) next!
Sorry, am a bit bogged down, so EQLS will have to be tomorrow now.
deleted - posted twice in error
Supreme (LON:SUP) - if the discovery that its products are not so non-discretionary after all wasn’t enough, then the reeling in of dividends in favour of M&A - at a time when the market favours high shareholder returns - tells a story of enduring concern about growth. I’m out!
Hi BnB,
I've just published a section on Supreme (LON:SUP)
To be fair, the profit warning relates solely to the lighting division, not the other key product (vaping) which is experiencing good growth & outlook.
I hadn't realised that lighting was such a big earner for SUP.
Regards, Paul.
I hadn't realised that lighting was such a big earner for £SUP
To be fair, I had made the same misjudgement
Providing nothing else goes wrong, then long-term holders should get their money back eventually, I imagine.
I agree. I just think that it'll be recovered faster by a judicious re-allocation into less vulnerable beaten-down stocks.
Supreme (LON:SUP) - if the discovery that its products are not so non-discretionary after all wasn’t enough
That's not the case though if you read the RNS. Customers have been overstocking (this is not the same as the end customer stopping buying lighting products). I can only talk for myself but I spent £80 replacing all bulbs and tubes that were not already LEDs 6 months ago, including some Energiser LED 4ft tubes. Given ongoing high electricity prices I imagine others will likely be doing the same because the return on investment is now much shorter!
However, you'd think management would have been aware of the stocking situation well before today if there customer relationships were as strong as they like to make out. That would be my main concern.
All the best, Si
Today’s placing of 10m shares in Ashstead Technology (AT.), a fast growing marine services company, might be a worth a comment. The company, floated in 2021 at 162p a share, is one of the few new issues to have bucked the recent sell-off in small-cap stocks.
It is committed to growing its revenues at a low double digit rate by supplying small items of “mission critical” technology kit to operators in the offshore oil and gas and renewable markets. The latest placing by the two main shareholders of 12 ½% of the company at 200p a share has been done at a discount of around 10% to yesterday’s closing price, valuing the company at around 13 times consensus 2022 earnings and a historic ev/ebitda multiple of 7 times.
Last November’s IPO attracted a number of well-known investors including Fidelity, Chelverton, Jupiter and Schroder who together have a stake of around 20% of the business. The latest share issue means that the stake of the two biggest shareholders, who brought the company to market (Buckthorn Partners and the Arab Petroleum Investment Corp), falls from 55.7% to 43.2%.
Whilst it is likely that they will continue to reduce their stakes after the lock-ups expire, the release of extra shares to the wider investor community should improve the liquidity in a tightly held share.
I see we are in the extreme fear sector Fear and Greed Index - Investor Sentiment | CNN
Mercia Asset Management (LON:MERC) reported today. I think the value they represent is huge...but for me I always want growth and they have a solid and IMO idiosyncratic platform for it. They have also reach the point of being 'evergreen' (or self financing) in terms of future balance sheet investments and with enough cash that they can acquire 3rd party assets to manage with capital raise (like they did for Northern Ventures).
I wrote this yesterday:
https://www.stockopedia.com/co...
(Note I was £90m over on 3rd party AUM which is due to accounting for £45m that came after year end and then there was £45m of distributions from venture funds to clients)
mojo: How do the results today change your valuation of Mercia Asset Management (LON:MERC), if at all?
I think the best way to value Mercia Asset Management (LON:MERC) is to combine the book value of the balance sheet holdings (around 45p) with an earnings based value for the fund management business. Having looked at a few broker notes, they seem to think 8p is a fair (if prudent) value for the fund management side. So adding together, around 53p seems to be sensible value. Certainly looks cheap, but there are several others in the venture space that also look very cheap and with arguably more established track records, such as £GROW.
Distracted couple of days for me (today, tomorrow) so let me get back to that on the Mercia Asset Management (LON:MERC) post I started. Overall I think no change. Anything less than £40m for the asset manager is too low IMO once you factor in fee income and stickiness of mandates and compare to competitors (so that's 5% AUM or 2x revenue)....and really its a decent bit higher. NAV of investment portfolio + cash about £2.5m higher than I estimated. I got my snapshot 3rd party asset management AUM wrong at £850m when its £760m...big miss on face of it but £45m was me putting known gains in for year end 31 March when they are after year end and then the other but is £45 distribution to clients in H2 22 (sort of a good thing as they are showing money goes back...and some of that recycles back into new EIS given the favourable tax on doing it)
They have the cash to make acquisitoin(s) that add to AUM now and so fee income run rate. That is likely a catalyst for re-rating assuming they do it with own funds rather than market tap
I don't feel secure about much but at current price Mercia is pretty safe IMO
Anyone any ideas for the 2 day slump in the Sylvania Platinum (LON:SLP) share price. This follows a very recent positive Q3 report and Edison's follow up here https://www.edisongroup.com/pu... There doesn't seem to be any calamitous news anywhere. Any thoughts gratefully received.
Sylvania Platinum (LON:SLP)
They seem to have stopped their share buy-back as of last Friday, which may have been propping up the share price until then. Can't think of any other reason though!
Platinum, palladium and rhodium prices have fallen recently and thus the share price fall
The amount of catalytic converters been nicked round our way suggests there is a real demand for their product!!
Agreed, one of my neighbour's car had their one stolen too :(
Is it not pretty much tracking PGM spot prices, and propped up by share buy back as Cal said? Spot PGM down 15 percent in the last month?
Just had a quick look, am no expert.
Spot on.
Sylvania Platinum (LON:SLP) is almost perfectly correlated with the platinum price, Tharisa (LON:THS) less so.
Despite recent share price weakness, Sylvania Platinum (LON:SLP) has nearly doubled since the start of 2020, with £THS up 28%:
Hello Epsilon, how did you produce (ie was it a Stocko tool or just your own brilliance?) the chart you showed at 11.26 yesterday in response to my query on SP movements for Sylvania Platinum (LON:SLP) over Mon and yesterday? Thank you
PS SP movements for Sylvania Platinum (LON:SLP) seem to go against the stated forecasts/outlook only very recently from the company and backed up by the house(?) researcher Edison who produced a paper on 6th May https://www.edisongroup.com/pu... after a statement on 4th May https://www.edisongroup.com/in.... Hey, but what do they know?
Sylvania Platinum (LON:SLP)
The market may also be reacting (rightly or wrongly, I don't know) to the ESKOM power cuts.
https://www.reuters.com/busine...
Thanks for all you comments on £SLP. Spoke to both the broker and the PR company for Sylvania Platinum (LON:SLP) this morning. Both mentioned the end of the share buy back programme, and the latter mentioned the decline n the PGM prices.
As far as the share buy back programme is concerned, I hav seen other companies make an RNS statement to the effect that the programme is ended and either they are starting another given permission fro the previous AGM or just ending it because it has cone to the end of the amount promised. Neither is the case for Sylvania Platinum (LON:SLP) and I believe it would have been a useful RNS, in fact in my view almost an obligatory one from a PR point of view. Should investors really need to be checking daily amounts of buy backs to see whether they have come to the end of the lollipop?
As for raw material pricing, that is a different matter and investors need to keep up with that.
However, I have made the point to both the broker, and the PR company, and to Edison (the company's tame house researcher?) that there was a very positive forward looking statement from both company and backed up by the Edison report only a few weeks ago https://www.edisongroup.com/pu...that there were lots more positives than negatives and in no way would an 11+% SP reduction in two days be on the cards.
Feeling a bit hard done by. Justified in others' opinions here or unjustifiably feeling sorry for myself?
Seems to me when the Company announces a share buy back, MMs just increase their prices sell at an inflated price and when buy back ends drop price again. Important drain of company funds which we maybe should be aware of. Not massive but annoying nonetheless. Personally never been keen on buy backs it says, "we have nothing better to do with our money", my mind always goes "really!!!"
Sylvania Platinum (LON:SLP) stated at the commencement of the share buyback programme that it would end on 30th June.
Hello Edward John Canham, and Sylvania Platinum (LON:SLP) I see from another report 3 hours ago from ESCOM that one of the unions, Solidarity have accepted the terms offered and ESKOM hope the other two unions will be sorted today, and supplies become more normalized. See https://ewn.co.za/0001/01/01/s... Hopefully a bit of good news for Sylvania Platinum (LON:SLP) if it was in fact bad news recently!
Memo to self, do not invest in any retailers at the moment!! As regards Supreme (LON:SUP)
Quiz opened nearly 10% up and are back to even. They look pretty good results so I am thinking you are not the only one JohnDoe2378.
Hi Paul
Almost sounds like Supreme (LON:SUP) heard about your podcast and want to be featured in next Saturday's.
Sold at a loss some while ago but still suspect there's a strong business waiting to emerge here in a year or two's time.
Fully expecting Supreme (LON:SUP) to get battered today with their FY22 results looking in line but not much joy looking forward with the headline announcement that a sales slowdown within the lighting category is forecast to suppress revenue and EBITDA performance in FY23.
Buried further down is news of a dividend cut unhelpfully not mentioned under the Dividends section of the report - "... revise its dividend policy from a pay-out ratio of 50% of net profits to a minimum of 25% in respect of FY23 onwards."
I think this one may be in the doldrums for the foreseeable future.
Regards Supreme (LON:SUP) I have looked at the statement/report from many different directions and cannot find any positives beyond this years numbers - next years numbers are being downgraded and divi reducing significantly due to wanting to focus on acquisitions.
I am regretting letting this build up into one of my Top-3 positions and even being optimistic find it hard to see any recovery for the next 24mths.
I just hope they can deploy dome of their earnings/cash into significant profit enhancing acquisitions over the next 12mths and start to find a return to their previous ways.
Thanks johnsmith68, KveinS1, and jonno, for the heads up on Supreme (LON:SUP)
I've got it on my list to look at later this morning, but might do it next, as it sounds like a profit warning, and is down 29% in early trades - ouch, and bad luck to holders.
SUP has always struck me as a decent, entrepreneurial company, so I'll re-assess it now in the light of today's update.
Regards, Paul.
Unfortunately given market sentiment I think that Supreme (LON:SUP) will take a dousing today. The prelims generally read well, but the sting in the tail is in the outlook statement which predicts a decline in revenue and EBITDA for the coming year relative to today's results.
I hold. Decisions?
Only one to make. Sell!
Hi Paul,
I very much enjoyed your podcast yesterday, they are always very helpful and I hope that you are able to continue making them.
best regards Neville
Good few updates today from companies on here .
Equals - looks a great update and cracking company. I’m quite heavy on this in my portfolio so thought I would “test the pudding” and opened a current business account last week . Looks very slick and certainly far better than a bank and probably better in function than the brokers like moneycorp .Have sone usd purchases to make next few weeks so will report back if good .
Quiz - looks very good update on first glance. I held but gave up as I can’t really get excited about womenswear (actually I can but not as an investment)
Supreme - could get hammered today as “behind on lighting” features quite heavily in the RNS update. I think a better worded RNS will focus on “market leader in Vaping with growth in a growing sector” etc should have been the over riding theme .
Sell the sizzle not the sausage .
Saga - no idea what it all means which in itself is a pretty bad thing . Hopefully Paul can translate and sun it up for us thickos .
Kitwave - looks the standout update of the day and it’s been on my watch list . Looks a good business generating loads of cash and profit , on a low valuation , with a motivated and committed management , and sone good shareholders .
Looks very good indeed .
Nice summary, thanks planetx! :-)
Graham & I are planning to cover all 5 of those stocks today that you mention.
Best wishes, Paul.
Quiz (LON:QUIZ) finals today look encouraging at first sight. I hold and look forward to Paul's expert appraisal.
Surprised at so little interest in what look (until/unless Paul convinces otherwise) very good update from Quiz (LON:QUIZ) today. Maybe the lack of interest in retail shares like Quiz (LON:QUIZ) is a signal that the retail sector is near as low as it’s likely to get? Even Marks and Spencer (LON:MKS) is down 50% from peak last year but has bumped along between £1.30 and £1.45 for a good while. Small investors so often seem far more enthusiastic when share prices look inflated than when as now, some look stunning bargains.
Anyway to £QUIZ.
Revenues up 97% year on year
More full price sales....BUT BUT they say nothing about returns that are a serious problem for Boohoo (LON:BOO) and £ASOS.
Increase is gross margin to 60.3%
Rise in operating costs seem under control at 22%.
Cash inflows (previously outflows) £5.3 million.
Strong online growth.
Active customers well up (74%)
International revenues up 96%.
OUTLOOK does suggest sales could well be impacted by cost of living crisis. Otherwise confident,
I added a few more at over 11p this morning expecting the share to rise further. Instead it’s fallen back, admittedly on a big down day.
What am I not seeing please?
Revenue still down a lot from 2019.
Also receivables are up around £3m.
Previous holding of mine , and although , not the most expensive stock around , I find it difficult to see where the growth in revenue is going to come from. However, I wouldn’t be surprised if the price goes up from current levels.
Hi Paul
When you spoke to Unbound (LON:UBG) did they say what or who’s targets they are inline with? Apologies if I missed this in the podcast.
Keep up the good work.
Hi Revs8
When you spoke to Unbound (LON:UBG) did they say what or who’s targets they are inline with? Apologies if I missed this in the podcast.
I don't tend to query this point any more, because whenever I've asked mgt of many companies about mgt expectations vs market expectations, they always reply that it's basically the same thing.
It's often used during the year, because brokers don't produce estimates for half years usually, so it's more logical for companies to say they're trading in line with mgt exps.
Personally, I would prefer that companies would use a form of wording that says: performance is consistent with full year market expectations.
Regards, Paul.
I am sure Saga (LON:SAGA) may get the odd mention today. No idea what to make of the update, the word "behind" appears too many times for my liking, and even the word "loss" makes an appearance.
Profit before tax of 35-50m compared to 7m loss however swings me the other way.
I have no idea what to make of it, luckily we have experts on hand.
Going to batten down the hatches though.
Given the PBT figures I think the Saga (LON:SAGA) update is positive on the whole - it is essentially an in line with expectations update as the PBT figures are within analyst ranges.
When I bought Saga (LON:SAGA) I did so for the recovery in the travel arm and in spite of my rule not to buy insurance businesses as I don't generally understand them. Motor and home insurance policies are mentioned a being quite a bit down today but they reassure us of recovery next year. Do readers with more knowledge of insurance have views about the likeliness of this in a more competitive market?
Saga (LON:SAGA)
let’s be frank with the levels of non ship related debt this company has 30-40 mill of post tax profit pa is extremely poor. What is worse is that it looks like insurance margins and revenue per cruise passenger next year are both expected to drop. No immediate short term solvencies worries (there is boat load of debt to repay/refinance in 3-5 years) but add in cost inflation and current benefit of fuel hedges and it’s a very grim picture - this is just proving to be a poor quality business overall or they have issues that are going to take time to fi or beyond their control short term. Note with cruise ships one would expect them to be at their easiest to sell to customers and most efficient ref ongoing maintenance etc when they are new - what happens when these shiny new.
Hi rmillaree,
That's not entirely accurate. In particular, this is wrong -
(there is boat load of debt to repay/refinance in 3-5 years)
As I point out in the article, SAGA has a cash pile that covers the next bond maturity in May 2024. There's no other debt repayable until July 2026, apart from the (quarterly I think) ship loan repayments, which have recently resumed after an agreed pause during the pandemic.
Remember that £35-50m profit will translate into much more cashflow, due to the big depreciation charges on the ships. So cashflow at the current run rate should be ample to finance interest & repayments on the debt for the medium term.
The other points you make are reasonable though, and good to have a contrasting opinion, although maybe a bit too hysterically expressed ;-)
Regards, Paul.
Saga (LON:SAGA)
That's not entirely accurate. In particular, this is wrong -(there is boat load of debt to repay/refinance in 3-5 years)
Paul - my comments are completely accurate here - per the annual report detailing the maturity of financial liabilities as at 31/1/2022 a total of £712 mill is due in 2-5 years period . Note July 2026 is within the 5 year period (only 4 years away !!) so it is back loaded but still due in the exact timeframe i quoted (time flies unfortunately) . I am very very aware this is not a near term issue but my comments are 100% factual , correct and not misleading IMHO.
Remember that £35-50m profit will translate into much more cashflow, due to the big depreciation charges on the ships. So cashflow at the current run rate should be ample to finance interest & repayments on the debt for the medium term.
I am 100% aware the cashflow will be better than profits , i have never said or indicated otherwise - however over the lifecycle of "ships" they need to be paid for so ignoring the depreciation is ignoring a "real" cost to the business .
and good to have a contrasting opinion, although maybe a bit too hysterically expressed ;-)
I aint being hystrical here IMHO - whether debt is due to be refinanced now 3 years or 5 years it will still need to be refinanced sooner or later . If non ship related debt is at say 5 * net profits of the business - IMHO that is sketchily high total - not not manageable but far less than ideal. My issue here more than anything is the declining actual performace medium term that is again eroding at the safety net that has existed. In this regard i think i am being cautious rather than hyserical , thats my opinion though so fair play if the majority see me as being hysterical i am fine with that.
It will be interesting to see if there are updated numbers ref next year - if anyone has details of any changes (upgrades or downgrades) in that regard would be useful to know.
I do not think you are hysterical at all and you are correct to be cautious , especially now that the insurance sector is showing signs of decline. There is a massive debt here , that sooner or later will have to be dealt with in the long run . and , hence , the share price performance.
I don't think you're 'hysterical'. I'm staying away from SAGA for the exact same reasons. The market agrees. It's a dangerous time to invest in companies that have heavy debt. It's also dangerous to invest in companies that are in a long-term downtrend, no matter what the fundamentals.
Finally, covid is growing rapidly in the UK again, which will not help their business.
rmillaree,
The key point you ignored, is that SAGA already has £187m cash in the bank. This is likely to grow, due to the strong cashflows from both divisions. As I pointed out, this is more than enough to repay the bond repayment, in full, in 2024.
The ship loans should be easily serviced from cashflows from those ships.
Therefore there's no risk from the debt, providing the group remains profitable. I agree with you there, that it would be better to have less debt, but it's mostly from purchasing the cruise ships.
So I think you've cherry-picked negatives on debt, instead of looking at the big picture, which includes a whacking great cash pile (and of course the ships are major assets).
The rest of your points look reasonable.
I was only being flippant about your original post's style, given that we know & like you here, so sorry if that raised you hackles!
Regards, Paul.
A perfectly rational alternative view .... not in the least hysterical in my view. Thx for posting rmillaree.
I booked a Saga (LON:SAGA) Cruise that was cancelled because of covid and then got a refund. Ever since Saga have bombarded us, sending the same cruise brochures by expensive post time and time again, both for river cruises and ocean going cruises. It seems way over the top and a waste of money. Hardly a a week goes by before the next brochure arrives!
Many of the cruises are shown as “last few cabins” which might well be a ploy to encourage people to book. When checking, there are indeed few cabins left, but I’ve then checked a week or so later and found that there are still just a few cabins left but sometimes a few more than the last time, suggesting that there might be far more cabins available than they are letting on. It’s interesting that Saga (LON:SAGA) don’t seem to have provided clear information today on the level of cruise bookings.
I also get regular letters by post promoting their motor, travel and then Private Health insurance policies. The costs of this if they are sending these to thousands of people must be quite high just with postage for starters. It doesn’t suggest their business is that efficient.
Their two new cruise ships are state of the art and with so much included are not overly expensive. We’ve got their 3 year fixed price house and buildings policy and some of their insurance policies seem decent value. The monthly SAGA Magazine is very good. So SAGA have a lot going for them. Yet the share price is languishing. Partly because Paul made such a convincing case I held SAGA but took the excellent profit a good while ago. I’m pondering buying again as SAGA rejected a potential bid a couple of years ago (and didn’t inform their shareholders about it). So many UK Companies are seeing bids. A chance that Saga could too?
Ken
It seems the plethora of brochures is an industry wide issue. In our case substitute Viking for Saga. Huge waste of money afaic.
A cruise for 2 could easily cost £4000 for a week all in, with a huge gross margin to Saga (LON:SAGA) - filling the ship 100% vs 90% full will transforms the profit. The marginal cost of the last passenger is almost zero. You can afford a lot of 70p/time direct mail with different offers or just hoping a different person collects and opens the mail or it arrives just after John and Mary have told about their super holiday.
Hi Ken,
Thanks for that, interesting scuttlebutt.
It’s interesting that Saga (LON:SAGA) don’t seem to have provided clear information today on the level of cruise bookings.
They did actually - if you search for "load factor", that is the % of the ships' capacity that is occupied/booked, and "per diem" is the daily rate per customer.
This info was quite encouraging.
Just thought I'd flag it, because looks like you missed it.
Regards, Paul.
Thanks Paul. I had missed it and agree it looks encouraging.
Also Saga’s 3 year insurance policies can be cancelled as a Saga explain here:-
https://www.saga.co.uk/insuran...
Two major insurance winds for £SAGA
One is a headwind, as detailed today. The price regulations in Jan this year is depressing backbook existing customer renewal pricing, which Saga has alot of.
However, with rates rising, many new insurance players will exit the market this year and next year. They entered because cost of capital was virtually nil. But many of them don't have long term financing, big enough books to be economical, and rising claims means pressure. I expect the market to rapidly consolidate, and possibly Saga could end up buying whole books of customers at some point.
I am tempted to cut my exposure though, as there are plenty of macro headwinds for Saga. But it does look like the current price has all the bad news priced in already, given the very undemanding PE. However, there is also no catalyst for a rerating soon, given the lack of dividend, and insurance being rocky till next year.
(I hold in the Boon Fund)
Thanks Boon, very interesting.
An additional point that I forgot to include in the main report, is that SAGA says a lot of its motor policies are 3-year fixed price deals, which helps customer retention.
Does anyone know what the terms of these policies are, in particular whether the customer can exit early at no penalty, if they find a better deal? Hopefully not. If the customer is completely locked in for 3 years, then that could be very nice business.
Regards, Paul.
Hi Paul - they can exit early, yes. The promise is from Saga that the premium won't increase for 3 years, but the customer can break it each year... Not ideal in a world of high claims inflation...
Hi Paul,
Yes they can exit early and no cancellation fee is charged but their arrangement fee is non-refundable (which I guess could be circa £30?, or more?). When they say “non-refundable” I’m assuming any refund on the premium paid then has the arrangement fee deducted if it’s cancelled prior to the 3 year term. So in other words a cancellation charge in all but name!.
Extract from their T&C’s:-
“You may cancel your policy at any time, in accordance with the terms of your Policy Book, and your 3-year Fixed Price will end. On cancellation, the arrangement fee is non-refundable; however, no cancellation fee will be charged.”