Small Cap Value Report (Tue 5 Mar 2024) - SPT, INCH, OXB, RCH, BKS, SOM, GRG, IWG, KLR

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Obviously we won't be able to cover all the companies reporting today, but will select what we (and you, via the home page most viewed widget) are interesting, and the biggest price movers too -
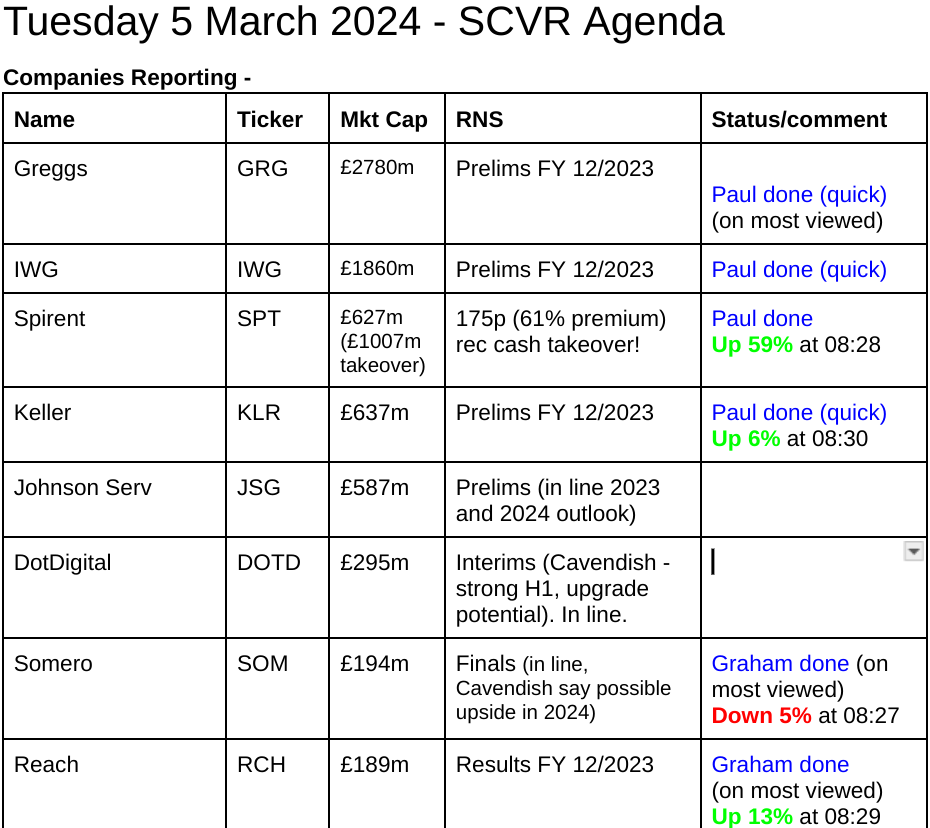
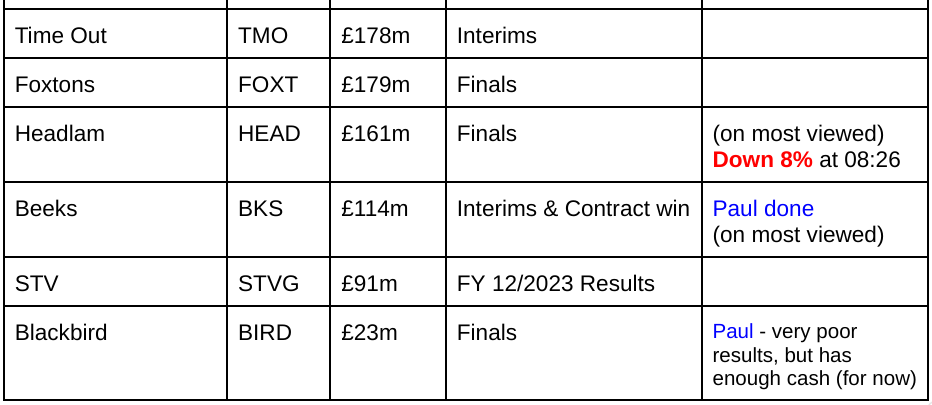
Other mid-morning movers (with news) -
Inchcape (LON:INCH) - down 10% to 609p (£2.5bn) - automotive distributor. FY 12/2023 results look good, with adj PBT up 35% to £502m. Adj dil EPS up 30% to 83.7p (PER 7.3x). Outlook caution might have triggered selling today? - “Outlook - moderated growth in the short term, accelerating in the medium to long term”. Bal sheet - only £349m NTAV. Finance costs have gone through the roof on P&L due to higher interest rates.
Oxford BioMedica (LON:OXB) - up 5% to 175p (£175m) - in line TU for FY 12/2023. Revised future guidance. Paul’s view - complicated accounts, cash burning on big R&D spend, but looks adequately funded for now. Too speculative for us at this stage, not really possible to value shares on a value or GARP basis. Looks like shares are trying to find a bottom?
Summaries of main sections
Spirent Communications (LON:SPT) - 108p (pre-market) £627m - Recommended takeover - Paul - PINK (takeover)
Cash takeover bid from a US competitor Viavi is at a lovely 61% premium. I think the price seems fair, given poor FY 12/2023 results, and cautious outlook. Let's hope a higher competing bid might appear, as with WIN!
Reach (LON:RCH) - up 10% to 65.7p (£209m) - Annual Results - Graham - GREEN
The investment thesis is slowly playing out as Reach makes the monthly contributions into its enormous defined benefit pension schemes, and the last phone hacking cases are settled. Stubbornly high operating profits relative to the enterprise value remain tempting.
Beeks Financial Cloud (LON:BKS) [Paul holds] - unch 172p (£114m) - Interim Results & Contract win - Paul - GREEN
In line with expectations for FY 6/2024. A large contract win is also announced. I recap on my current thoughts below, after a quick catch up call with management. I think the big recent share price recovery is fully justified, and medium-longer term, this continues to be probably my favourite GARP share.
Somero Enterprises (LON:SOM) - down 5% to 382p (market cap £182m) - Final Results - Graham - AMBER
Somero posts results in line with expectations, and forecasts for 2024 are left unchanged. These include flat revenues and another fall in profitability as the company invests in European expansion. I’m still a little concerned about US competition and staying neutral.
Quick Comments
Greggs (LON:GRG) - up 2% to 2760p (£2.82bn) - FY 12/2023 Results - Paul - AMBER/GREEN
Good figures, but adj dil EPS is only up 5.4% to 123.8p (PER 22.3x looks fully priced to me). Divis - 16p interim (paid already) + 46p ordinary + 40p special = 102p total for 2023, yield of 3.7%. Gaining market share, now a record 8.2%. Wider product range, opening hours, and lots more new sites planned. Outlook good, but unchanged -
“Greggs has started 2024 well, with like-for-like sales in company-managed shops growing by 8.2% in the first nine weeks. As we have previously reported, inflationary pressures are reducing and we have improved visibility of costs in the coming year. There is no change to management's expectations for 2024…”
I wonder if consumer spending might pick up after April's big pay rises, allowing GRG to beat 2024 forecast? Balance sheet is fine, with net cash of £195m.
Paul’s view - an excellent business, but share price reflects that, so priced about right I’d say. I’m happy to stick with AMBER/GREEN, meaning that I really like the company, but shares look a bit expensive.
Iwg (LON:IWG) - down 2% to 180p (£1.83bn) - FY 12/2023 Results - Paul - RED
A brief skim of the results shows lots of adjustments for inconvenient costs, but statutory results show another year of losses. Terrible balance sheet, with NTAV of negative £(1,043)m. I don’t see any attraction to this share at all, on fundamentals. Anyone else looked at it, and maybe you could explain the bull case to me?
"The Group remains cautious in its outlook and continues to focus on driving efficiencies and cost control. As a result, we are confident that 2024 EBITDA will be in-line with management's expectations..."
Keller (LON:KLR) - up 7% to 935p (£681m) - FY 12/2023 Results - Paul - AMBER/GREEN
Good numbers here - underlying dil EPS up 53% to 154p (PER 6.1x). Net bank debt down 33% to £146m. Total divis for year up 20% to 45.2p (yield 4.8%). Outlook -
“ our current level of trading together with our robust order book mean that we enter the new year with confidence.”
Modest pension deficit payments to end in Aug 2024. Balance sheet NTAV c.£400m, looks OK overall, although gross bank debt seems higher than I would like.
Paul’s view - I like it, and will stick with my AMBER/GREEN from last review on 17/1/2024.
Spirent Communications (LON:SPT)
108p (pre-market) £627m - Recommended takeover - Paul - PINK (takeover)
Marvellous news for SPT shareholders this morning - a recommended cash takeover at 175p - a big premium of 61% to yesterday’s close.
Technically, it’s 172.5p + 2.5p dividend.
Requires shareholder approval, and regulatory approvals.
Viavi is a NASDAQ listed company in the same sector, so it’s an industry buyer rather than a financial buyer - its market cap being about 3 times the size of Spirent pre-takeover premium, so quite a large acquisition for Viavi.
FY 12/2023 Results are out, but there’s not a lot of point in me reviewing those, as this agreed takeover bid has emerged. Adj EPS fell 60% to 7.6p. Outlook comments sound cautious, expecting difficult market conditions to continue in 2024 and maybe even 2025. Hence the Board decided the takeover bid offered more immediate value to shareholders.
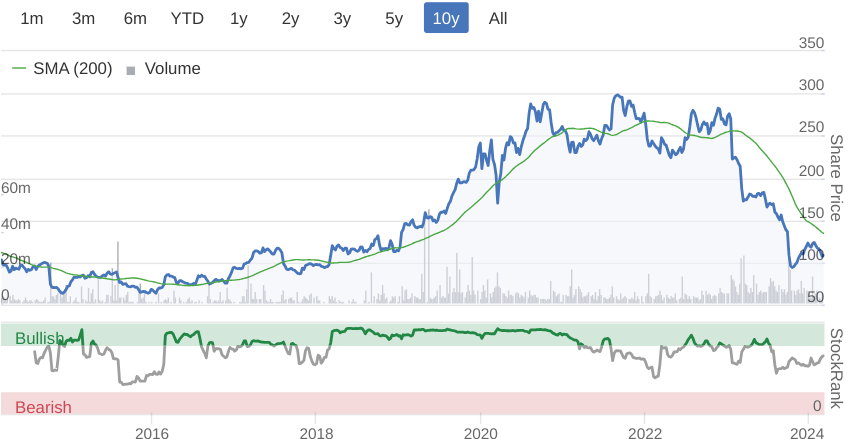
Paul’s opinion - a 61% premium looks generous at first, but zooming out on the chart below, you can see that 175p isn’t such a generous offer when compared with c.300p peak share price in the last 3 years.
Spirent performed badly in 2023, we reported on its profit warning on 4/10/2023, and again on 17/2/2024 where I commented on its terrible 2023 results, but signs of a turnaround in the outlook comments.
However, cautious outlook comments today suggest if SPT remains independent, that shareholders would have to wait a while for a big share price recovery. So I think accepting the bid (whilst hoping for a higher counter-bid from someone else, as happened with Wincanton (LON:WIN) makes sense).
A 61% premium is clearly something nice to put in the bank, allowing shareholders to recycle the money into another cheap UK mid-cap..
Beeks Financial Cloud (LON:BKS)
Unch 172p (£114m) - Interim Results & Contract win - Paul - GREEN
Contract win - is impressive, with an unnamed major bank. I think this was already in the forecasts/pipeline, and has had a long gestation measured in years so it’s pleasing to see it result in a contract. This was won in a competitive tender process, and BKS says it doesn’t compete on price, so it isn’t the cheapest.
Revenue will be £5m over 5 years, with associated up-front capex of c.£1m, and some front-loading of the revenues/cash receivable, if my understanding is correct. Beeks has listened to investor concerns about previously heavy up-front cash outflows, and has made favourable adjustments to deals since then. As before, the key point is “land and expand” - ie contracts nearly always start off small, then build as clients gain confidence in the system. Hence why growth produces such good compound annual growth rates - a lot of it is organic growth from existing customers, as well as winning new, larger contracts. Clients are very sticky, with low churn especially at the medium to larger end.
Will it need to do another placing? No. Shareholders asked BKS to stop coming back for smallish equity raises, so it raised more than it needed last time. Should be cash generative now. Only caveat is if they win a gargantuan deal, then a top-up placing might be possible, but obviously that would be from a position of great strength. So I’m not worried about any further dilution, which hasn’t been excessive in the past anyway. The owner’s eye means the founder doesn’t want to dilute unless it’s absolutely necessary.
Interim Results
Beeks Financial Cloud Group Plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce its unaudited results for the six months ended 31 December 2023.
Everything seems as expected in these H1 numbers.
Revenue £13.0m & annualised monthly recurring revenues £26.6m are both up 25% - excellent organic growth that is compounding nicely (revenue was only £5.6m in its first full year as a listed company, FY 6/2018).
Revenue for FY 6/2024 is forecast at £29.1m (Progressive), rising strongly to £38.5m in FY 6/2025, due to larger deals kicking in. This could still turn out to be conservative, as nothing has been included for a recent large exchange win, until it passes regulatory clearance.
Profitability - pick a number that suits! Many of us don’t like adj EBITDA, but tech investors and takeover bids do use multiples of this metric, so it would be foolhardy to ignore it, in my view. This was £4.6m in H1, up 28%.
Underlying PBT is up 113% to £1.4m in H1 (an H2 weighting is expected due to organic growth)
I regard share option charges as staff remuneration here, as all staff are shareholders (it’s not a perk for Directors at Beeks, very unusually). So I add back that £1.1m charge, getting to just above breakeven really as my interpretation of the real world level of profitability. Hence I’m happiest with the statutory PBT of £158k in H1, loss of £(762)k in H1 LY.
Capitalised development spending is reasonable for the size & type of business, at £1.4m per half year. Staffing levels have been stable, reinforcing that BKS should see more operational gearing from now, as bigger revenue deals kick in, on to a largely fixed overheads base.
Balance sheet - looks fine to me, with £25.4m NTAV.
As mentioned above, management don’t expect to need another placing, and the cashflow statement shows I think the first time it’s generated cash, with debt repayments exceeding the small reduction in gross cash.
This is work in progress anyway, with FY 6/2025 being what the company call a “tipping point” where significant contracts kick in, onto a largely fixed cost base.
Outlook - in line with expectations for FY 6/2024.
Future Growth and Outlook
We see expansion potential across the vast majority of existing customers and we are focused on the continued execution of our land and expand strategy.
Our high proportion of recurring revenue means we are confident in delivering results for FY24 in line with Board expectations and as previously announced, FY25 trading is anticipated to be significantly ahead of prior Board expectations.
Our core focus for the second half remains the conversion of our significant pipeline. We find ourselves with a firm financial footing as a profitable and cash-generative business, and we are well-placed to continue seeking to achieve growth acceleration in the current year and beyond.
Founder CEO comments - this strikes me as more bullish than the more measured tones in the past -
"The consistent growth we continue to demonstrate, combined with our confident outlook for this and next year, underline the size of the opportunity we are addressing. Financial markets are still only at the start of the journey to the cloud. With our proven offering and growing tier 1 customer base, which includes some of the largest financial organisations in the world, as well as our increasing profit margins and cash generation, we have never been better placed to seize the opportunity. Our focus for the second half remains the conversion of our significant pipeline."
Paul’s opinion - I’ve been bullish on this share for a long time, and it’s great to see the company clearly at a positive tipping point.
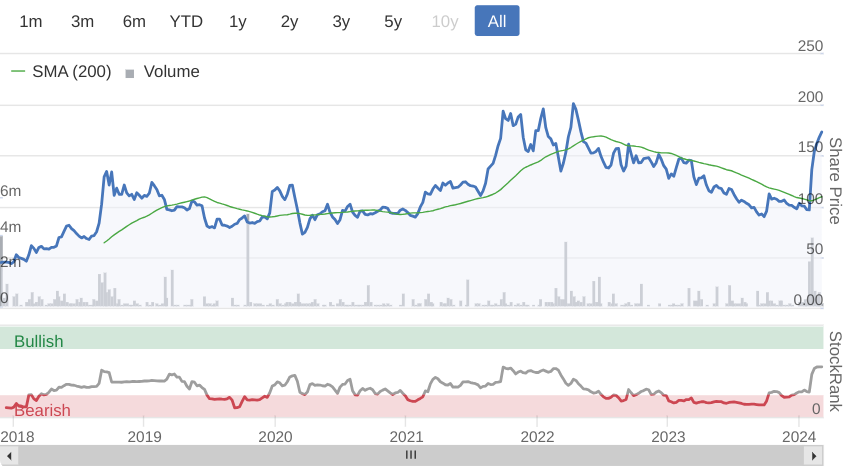
That said, the market has reflected this, with a big recovery in share price recently. Although it’s still well below the valuation when Beeks was a much smaller company. So it can be viewed either way - people are bound to bank some profits after such a big rise, but I’ve noticed two fund managers mention BKS positively in recent interviews, so maybe instis will be buying up the shares that smaller traders are selling? Who knows, over time this sort of short-term noise is irrelevant.
As a bull on this share (and with a small personal position in it, <1% of my personal portfolio), I’d like to buy some more when cash is available. So I’m hoping that profit-takers might erode some of the recent price gains! On fundamentals though, I think the recent share price recovery is fully justified by excellent newflow, and longer term I see considerable potential for further share price rises, before the company is eventually sold - the stated aim of management.
I think bears on this share are right in that their interpretation of the historical figures does make sense - lack of cashflow, no real profits, etc. However, investors are not buying the past, we’re buying the future - and things seem to me obviously set up for substantial growth in profits and cashflow as larger deals kick in, for investors who are prepared to be patient.
Chart since listing -
Graham's Section
Reach (LON:RCH)
- Share price: 65.7p (+10%)
- Market cap: £209m
A reassuring headline:
FY23 Progress on our digital strategy, long-term uncertainties resolved
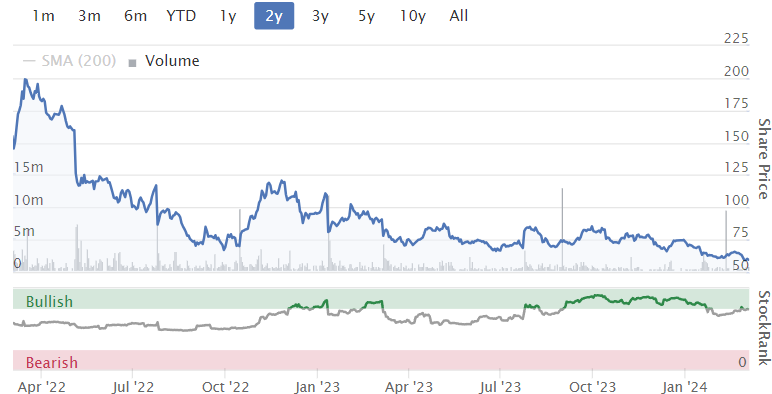
As readers will be aware, this stock has struggled under the weight of concerns over an enormous pension deficit, legal liabilities and declining newsprint revenues.
The result is a chart that looks like this:
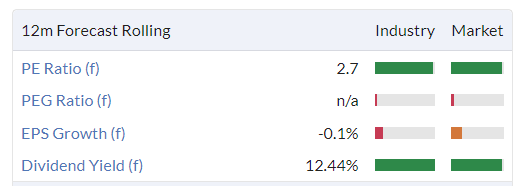
And valuation metrics that don’t appear to make sense:
I’ve been positive on this one, taking the view that management are running it for cash and for the ultimate benefit of shareholders.
Let’s dive into these full-year results a little.
CEO comment:
"This year we have successfully gained clarity on two significant long-term uncertainties in pension funding and Historical Legal Issues. With the end of these issues in sight, we have significantly reduced our obligations and have a clear path forward for the business.
Pension review
Reach’s various pension schemes are valued every three years; the valuations for December 2022 “are progressing” and should be finished before the March 2024 due date.
Going into footnote number 15 of today’s report, we can see in detail how much cash Reach is currently expecting to plough into its pension schemes every year. Some of these numbers were known already:
MGN scheme. £219m deficit. £46m contributions p.a. until Jan 2028.
Trinity scheme. £57m deficit. £5m contributions p.a. until 2027
MIN scheme. £74m deficit. c. £8m contributions p.a. until 2029.
EN88 scheme. £25m deficit. c. £3m contributions p.a. until 2026.
So total contributions are still expected to be around £60m p.a.
However, we are gradually getting towards the point when the contributions will no longer be necessary. The footnote also says this:
…the funding deficits in all schemes are expected to be removed before or around 2029 by a combination of the contributions and asset returns.
And the total amounts payable by Reach according to the current schedule are:
2024: £60.9m
2025: £60.9m
2026: £61.8m
2027: £59.8m
2028: £12.5m
2029: £8.6m
The final numbers remain unknown, as they depend on asset returns and all of the other variables that go into a defined benefit pension scheme. But if things go according to plan, contributions are expected to shrink dramatically from 2028, with all of the deficits eliminated in 2029.
So there are probably just four more years, including the current year, in which Reach will be run primarily for the benefit of its pension funds.
Legal liabilities - this old problem (arising from the phone hacking scandal) continues to rumble on but the end is in sight here, too:
December's High Court judgement provides a resolution on time limitation for Historical Legal Issues. This means that a significant number of outstanding claims can be resolved, and this should largely bring an end to future claims. The expected cost of settling has reduced by £20.2m
The provision that remains outstanding for this issue is now just £18.2m, which is “the current best estimate of the amount required to resolve this historical matter”.
Coming up with an enterprise value - adding together the current schedule of pension contributions (yes, this ignores the time value of money) and the legal provision I get total liabilities of £283m. Let’s treat this as debt and add it to the market cap (£209m). We could also add on financial net debt at year-end (£10m) and say that the enterprise value for Reach is about £500m. Investors could pretend that this is the market cap of the company.
Operating numbers:
Revenues down 5.4% to £569m
Print revenues down 2% to £439m, digital and other revenues down by 15%-17%.
Print volumes down 17%.
Digital revenues continued to disappoint:
Revenue has been impacted by lower advertising demand during a period of macroeconomic uncertainty alongside a material reduction in page views. Major platforms including Facebook have deprioritised news content over the year which in turn has driven a reduction in referral traffic for publishers across the sector.
Adjusted operating profit is £96.5m, down 9% year-on-year.
Actual operating profit is £46.1m, after a wide range of adjustments.
The adjustments are complicated but I tend to agree that they are substantially one-off items.
For example, they include nearly £27m of restructuring costs as Reach implemented a headcount reduction plan.
They also include a £20m impairment as the user of a print site sub-leased by Reach went into administration.
Outlook
Decline in online traffic will impact Q1 2024, but digital should see “growing momentum” thereafter.
On track for 5-6% reduction in operating costs in 2024.
Jan and Feb 2024 have been “robust”, full year outlook unchanged.
Graham’s view
I remain optimistic that long-suffering Reach shareholders might see a decent outcome here.
It will take a few more years to rectify the pension deficits, but with every month that goes by, shareholders can feel more confident that the end is in sight.
I also note that the print business is still the largest source of revenues by far, and its financials aren’t shrinking as quickly as you might think that they are, thanks to cover price increases. But I must admit that the 17% decline in volumes is striking - are printed newspapers headed for extinction, or is there a floor we might reach soon?
I’ll continue to give this share the thumbs up. As I said last year, it’s likely to be a low-quality punt. But the value on offer is tempting, with just under £100m of adjusted operating profit in 2023 vs. an enterprise value (including pension liabilities) of £500m.
Somero Enterprises (LON:SOM)
Share price: 382p (-5%)
Market cap: £182m
Lots of negative numbers in these full-year results, but the headline is positive:
A healthy North American market and significant contributions from Europe and Australia drive strong finish to 2023
The “exceptional” 2022 performance makes for difficult year-on-year comparisons. The results are in line with expectations:
Revenues down 10% to $120.7m
PBT down 19% to $33.2m
Cash flow from operations down 12% to $24.4m
$20m was paid out in dividends during 2023, along with a small buyback, so that there is almost no net change to Somero’s year-end net cash, which finished the year at $33m.
(Note that Somero’s share buybacks are designed merely to offset dilution from employee bonus schemes, not to reduce the share count.)
Strategic highlights - “investment in international markets yielding positive results” - Somero is building out in Europe and Australia.
New Year highlights - expecting more of the same in 2024.
Non-residential construction remains healthy with customers reporting high activity levels and extended project backlogs, and expect market conditions to remain consistent in 2024
Three new products launching in 2024, including the first step toward electrification with the launch of the S-940e in January
Broker Cavendish has made no changes to forecasts, which they describe as “pitched conservatively”. The estimates for 2024 include unchanged revenue ($120.7m) and another mild fall in profitability, with adjusted PBT falling to $31.6m.
The outlook statement confirms the above, explaining that profits are falling due to “modest incremental investment including the new Belgium service and training center and the annualised impact of strategic resources added in 2023…”
CEO comment snippets:
…we have been working hard to lay the foundations for accelerated growth overseas and so it is gratifying to see our efforts beginning to pay off. While trading in the US was subdued by factors outside of our control, the underlying market remains active and healthy.
2023 was one of our busiest and most productive years in terms of product development…
Looking ahead, the outlook is positive, with customers continuing to report high levels of activity and healthy backlogs. While the timing and extent of a return to more normal trading conditions in the US remains challenging to predict, our confidence in the long-term prospects for our home market remains resolute.
Graham’s view
Paul and I both have a generally positive impression of this company. It has been run with a very solid balance sheet despite paying out a very nice dividend stream to shareholders over the years.
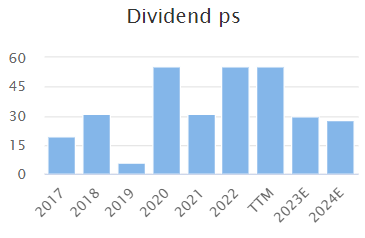
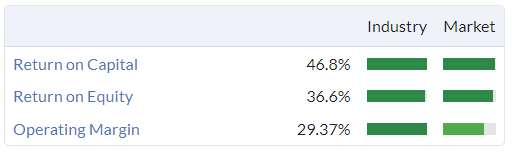
Quality metrics have been excellent, hinting at a strong competitive position that enables unusually strong margins:
However, personally I have been neutral on this stock since last year.
Of course, the cyclical nature of the construction industry has been a concern and 2023 was one of those years when the company took a few steps backwards, due to macroeconomic forces.
But I have also started to worry more about Somero’s competitive position. Please bear in mind that I am not an expert in this area - I am simply someone who has at various times over the years searched for alternatives to Somero’s products online.
Several years ago, I would struggle to find much online evidence of competition.
Nowadays, things are different. The websites for European competitors remain unimpressive (although better than they were several years ago), but the US has Ligchine which seems to be a direct competitor and is also able to export around the world. In 2020, Somero unsuccessfully claimed that Ligchine had infringed its intellectual property.
With some niggling doubts about competition, I’m therefore sticking with my neutral stance on Somero. I am sure that macro forces are also very important, but maybe competition is also restricting the company’s financial performance?
I could very well be overthinking this. With a StockRank of 98 and a nice cheap valuation, Somero could still offer great value here:
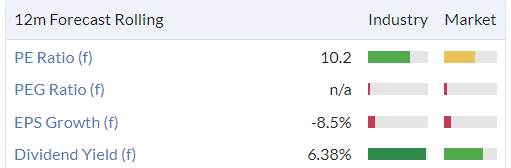
Paul adds: I've had a quick look, and my view is a bit more bullish than Graham's a rare occasion when we would colour code it differently. I understand Graham's excellent point about competition - very high margins and other quality scores do tend to attract competition in lots of sectors. However, for me the numbers & valuation are too attractive to be anything other than green. Especially as 2024 forecasts look conservative, and we could see upgrades. There you go, 2 opinions for the price of 1, what more could you ask for?!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

133 comments
Somero Enterprises (LON:SOM)
Any chance someone has picked up why the interest income is so low ($196k)?
I would have expected something more substantial given the large cash balance (>$25m)
Thanks
A
Somero Enterprises (LON:SOM)
I kinda guess it’s not really been top priority for them - possibly not helped by the fact they may have to hold funds in many currencies . As you have asked twice now and have had no sensible answer I might email them when I get time to see if there could be logical explanation . Hey ho at least the amount has tripled compared to previous year.
Not been following things in here lately (travel)...do we still have people foaming and fomoing about US market and particularly mega tech?...
Well treat this as a full bs comment (market calls except at panic/exhaustion bottoms usually are) but I think at least a short term top and maybe a more significant top is in on those names and recent price action (including both exponential up and today's dramatic down, particularly BTC which is a great proxy for sentiment)...
Obvs if you are a believer then there's a buying opp. But fyi markets and systems do not operate in exponential territory...the break.
I just dont get UK funds and company management at all. Why would they be interested in an offer for Spirent Communications (LON:SPT) at 40% lower than the peak only 12 months ago. Probably close to the bottom of the cycle.
Youve Liontrust, Aberdaberdeen, M&G,Aviva etc as main holders. Are they long term holders as they claim or just rubbish medium term traders now?
Spirent Communications (LON:SPT) Well the price action today would suggest they may not sell. UT of 750k of shares for 177p.
pj8 reference your post earlier on Renold (LON:RNO) the full title of the EBS is Employee Benefit Trust Corporation so they can legally hold Shares in the Company on behalf of the future Pensioners.
The Shares are not owned by Renold they are owned by the EBTC.
Excellent spot, thanks Portugull.
Headlam (LON:HEAD) - (I hold).
Some thoughts regarding todays FY'23 (to 31/12/23) results and PIWorld webcast.
That's enough random thought emptying for now.
My gut instinct tells me I've seen enough and should sell. I don't have sufficient confidence in management, no likelihood of SP recovery in short term plus risk of further profit warnings and dividend cuts. The only saving grace is the strong asset backed balance sheet (but a weakened cash position).
Snazzy
My gut instinct tells me I've seen enough and should sell Headlam (LON:HEAD)
And mine tells me to be patient. You’ve got a company that twice in a row has issued a horrendous profit warning that has not moved the needle on the price. That suggests to me that the market is not interested in lowering the price further. At least barring a market event. The entire market cap is supported by tangible assets, and we’re just waiting for the macro to improve. Yes, the company is a bit shit. But those are the stocks which rebound hardest when the market changes its tune. It just might take a bit of time.
Thanks BnB
I'm sure you're right.
Just wish they had a more inspiring management team.
Snazzy
Paul asked for the bull case for Iwg (LON:IWG) .
It is attracting attention from American funds as it radically changes it business model. The Greenhaven Road annual letter puts it thus:
'the company has introduced a new asset-light “partnership” model, which eliminates both cyclicality AND capital intensity. In this model, IWG asks landlords to put up all capital investments and pick up all operating costs of a location. In return for managing these locations, IWG takes a management fee, approximating 15% of revenues.'
https://static1.squarespace.co...
Todays RNS is also quite comprehensive (and bullish) on the matter, albeit they reported a loss but managed to introduce a 1p dividend.
Iwg (LON:IWG) I know you're looking for bull case, but sorry can't see it.
Terrible accounts, and I've heard that serviced office providers can be a fairly dubious crowd at times. Certainly would be wary of leasing to them, never mind buying their shares.
Thanks jinjah,
I appreciate you responding to my request for an explanation of the bull case for Iwg (LON:IWG)
It still doesn't make sense to me, as a small to mid cap value/GARP investor.
This all feels similar to previous tech booms, where we're expected to suspend normal valuation rules, and imagine that anything tech, and American, is somehow subject to completely different valuation rules.
I've seen that go very horribly wrong twice - in spring 2000, and in 2008. Again mildly in 2022.
Viavi Solutions (NSQ:VIAV) offer to acquire Spirent Communications (LON:SPT) at 175p is in my opinion way too low and does not reflect the long term intrinsic value of SPT, a company and a sector going through a cyclical downturn. No wonder VIAV sp is up 8% today on the news.
SPT is a high returns, high margins company with net cash (very low debt) which used to grow nicely before the downturn, in a sector where eventually telco will have to get on with their system testing capex currently/temporarily postponed. (i hold SPT).
Viavi Solutions (NSQ:VIAV) offer to acquire Spirent Communications (LON:SPT) at 175p is in my opinion way too low and does not reflect the long term intrinsic value of SPT, a company and a sector going through a cyclical downturn.
I agree. although that hasn't stopped me taking profits today. I see a long road out of the slump and I've got what I hope is a better use for the money in the short term. I'm still interested to understand your basis for your Calnex PO of 155p? You say you've made a "thorough analysis" so it would be good to see that expressed in numbers and timescales.
hi BnB
the 155p is the intrinsic value of Calnex Solutions (LON:CLX) from my analysis, reflecting my estimate of the earning power of the company and the projected cash flow discounted to today with an appropriate discount rate specific to the company but benchmarked with the sector CLX is in and with peers.
Timescale? I have no crystal ball. if it reaches my valuation in 4 years it will be circa 20%CAGR on todays price. Which is my target for my portfolio.
The inputs I have used for my valuation inevitably reflect my view today of the company, and the two recent PWs. No doubt if I am right on this company I will see an improvement down the line which will then be reflected in my future valuations.
Sometimes this wonderful situation makes me stay invested in the company and eventually multibag...
Mirroring earlier discussions I have been looking to increase the portfolios holding in cyclical shares that have been beaten down and from my view oversold. I tend to be fully invested so the problem is having to sell to buy.
Having done a fair bit of research, I liked the look of VP (LON:VP.) The share is trading close its lows despite broker forecasts having been raised. It has several specialist hire divisions that serve a wide range of activities, predominantly in infrastructure and construction , Torrent Track (rail infrastructure), Ground Force (construction - excavation) UK Fork (fork lift and specialist lifting) EES and TR Group (test and measurement, communications). Although most of is revenue is UK derived it also has a presence in Europe and Australia.
The down turn in construction has been offset by infrastructure, as a consequence EPS is forecast to increase this year and next. For the period ending September 23 pre IFS 16 gearing was less than 1.6 times.
The policy is to maintain dividend cover at 2 times. On current forecasts this gives a yield of close to 7.5% and PE of less than 7. My investment thesis is that infrastructure will continue to be in demand, rail, water etc and construction/house building is close to the bottom and will recover.
The founder and chairman, Jeremy Pilkington, owns 50% of the equity with over 30% owned by institutions leaving little free float, which means that liquidity is usually dreadful. There is also the possibility that Mr Pilkington will look to take the company private, however I view this as somewhat unlikely, as he put the company up or sale a few years ago and subsequently withdrew it, when no acceptable offers were forthcoming.
On the matter of liquidity, I tried to buy an opening position yesterday but was offered a spread of 5%, which I declined. I managed to buy a smallish holding today paying 1% above the mid price. Depending on how the situation evolves I will look to add.
TT electronics (LON:TTG) is a share that I have owned on several occasions with varying degrees of success, but it was yesterdays announcement on the disposal of three business units that made me look at the company afresh. All in all and as with VP (LON:VP.) I came to conclusion that it was just too cheap, trading close to its lows at less than 7 times, below book value and a yield of about 4.75%. This assumes of course that current forecast are in the right ball park. Hopefully the new CEO, Peter France will continue to prioritise debt reduction.
To fund the above I top sliced Howden Joinery (LON:HWDN) , an excellent company but where the share price looks up with current events.
I made exactly the same trades - including selling Howden Joinery (LON:HWDN) at similar levels to release some cash - back in December. I think we've both done quite well in the short term on Brickability (LON:BRCK). Your timing is a little more advantageous than mine, so well done, and I've had good early results with a couple of other purchases of a similar nature, like Sigmaroc (LON:SRC) . Now we need the new cycle to begin for shares to press on. My bank urges patience - not in H1 they say. But asset prices won't necessarily wait for the bell to ring!
Thank you BnB.
I have retained a modest holding in Howden Joinery (LON:HWDN) and coincidentally have a much larger holding in Sigmaroc (LON:SRC) which I have held for a couple of years and was until fairly recently holding at a loss. However having met the management team on a couple of occasions I bit the bullet and added significantly at below the 47.5p equity raise to fund the recent acquisitions. I admit to this being somewhat of a leap of faith, but so far it appears to have been a good decision.
I have also top sliced Brickability (LON:BRCK) but it remains a significant holding. TT electronics (LON:TTG) have results on Thursday I believe, so hopefully no nasty surprises. As for VP (LON:VP.) I believe that the share price should make good progress, like other cyclicals once interest rates start to fall. As to when this happens I don't know, neither off course does Andrew Bailey!
I hold Renold (LON:RNO) which is currently down 12% over the last 2 days and Ben Hazz questioned earlier today was this fall linked to the Employee Benefit Scheme which now owns 12.13% of the Company.
On 31st March 2023 the 22/23 Accounts for Renold showed the EBS held 7.49% so in this Financial Year they have upped their holdings in the Company quite significantly and are now the 5th largest Shareholder.
I recall that Wincanton (LON:WIN) for many years were the prisoner of their Defined Benefit Scheme when the Market Cap was £400m compared to £1.2 billion of liabilities in the Pension Scheme. We all know what transformed Wincanton.
So is it feasible that Renold (LON:RNO) are trying to replicate what Wincanton did and transform their EBS so that it frees up capital for acquisitions and/ or Dividends to Shareholders?
I like your thinking portugull. I’ve been puzzling why the EBS have been buying so heavily and the implications for Renold (LON:RNO) i hold.
I can't see how an employee benefit scheme can own any of the company.
A company cannot own its own shares, unless they're held in Treasury. An employee benefit trust is normally used to satisfy employee share plans. Cash goes in but it's a one-way valve - the company can't withdraw the cash. The shares held in the trust effectively hedge the future liabilities - the alternative is to create new issues when the share plans vest.
Pensions are a totally different beast altogether.
Somero Enterprises (LON:SOM)
Graham
In 2020, Somero unsuccessfully claimed that Ligchine had infringed its intellectual property.
i thought with this case was voluntarily settled by both parties with each party picking up their own costs - when you say Somero lost do you have any evidence they lost as you suggest?
I have the same information as yourself. Somero dropped their claim, and Ligchine dropped their counter-claim, and the exact terms of the settlement agreement are unknown.
Spirent Communications (LON:SPT) The bid price is now above the recommended offer price, so maybe the market is expecting a better offer.
The annual results for Keller published this morning looked good to me. Because they are a specialist type of civil engineering contractor, they normally have a higher operating profit margin than most civils contractors and achieved 6.1% in 23 results. They also have a very good long term record of paying increasing dividends - something like 30 years, iirc, and this years dividend is approximately 4.8% after a substantial increase and would have been 5.2% without today's rise in price.
For almost the entire lifetime of KLR, IIRC, they have been expanding, with occasional steps back, their worldwide operating footprint, while during the same period all other UK civils contractors have been closing their overseas operations. That, imo, gives them at least a modicum of protection from the traditional UK boom and bust civil engineering cycle, induced by the ease with which successive governments can slow down major road / rail / reservoir / sewage treatment /sea defence building etc, despite the long term damage this does to the economy, to give room for an election bribe of a penny or two off income tax, or other crowd pleasers.
Keller have often had localised poor results in one or other world region, but good results elsewhere usually offset the bad bits. The worst "bad bits" that I remember were a factory perhaps ten or more years ago where I believe the factory builder failed to achieve a settlement tolerance on the KLR foundation, which they overcame without too much pain, and a probably fraudulent management problem in one of their Australian companies. That Australian problem surprised me, because there is quite a history of that sort of problem in Oz and I thought KLR would scrutinise the abnormal figures before it became a serious problem, but they didn't. I'm not certain but I think that the current CEO was the CFO at the time of those problems, and in the current results there is much commentary on careful risk assessment and management oversight, so he probably had a worthwhile "education" while in the co-pilots seat, and is perhaps not the typical accountant pretending to be a CEO.
I see STVG is on your list. I would be grateful for your analysis. Like Reach, it has a pension fund deficit that will be paid off in a few years and the cyclicality of the business should be smoothed out now that >60% of revenue is outside advertising . Should be a good year for advertising revenue with the Olympics, The Euros and a general election .
Hi Ternheim,
I might change the name of our list from "agenda" to "companies reporting", as we always have to select from the list on busy days. If I had 3 or 4 writers, we could do everything, but it's just not possible with the current resources.
We're grateful for your synopsis of STVG, thanks!
Best wishes, Paul.
Re Headlam (LON:HEAD) Head - Surely we are close to a cyclical low now? Share price is back to Dec 2008 levels but its fundamental advantages remain (huge scale vs competitors, long established links to suppliers and customers, national warehouse network). The need for its services remains.
Market volume is said to be down 5% (and 20% below 2019) whilst share is flat. It probably can't stay low with a rising population and increased working from home. More new builds would be the most obvious trigger but RMI spend can only be held back for so long.
Operationally, it was interesting £Head cited first the purchase of £6.3Mn of CAPEX to improve service proposition for regional distribution. In the webinar it was indicated that some of this was catch up for previous under-investment. Perhaps that's evidence that it is re-focusing on these customers (who Likewise (LON:LIKE) have targeted). Trade counters, a key source of expected incremental growth are said to be on track and profitable from year 2
It's all very unexciting now - but with it trading nearly 20% below a conservative book value, surely it is just a waiting game for recovery.
What’s going on at INTERCEDE (IGP) it’s suddenly woken up and roared a bit
Penny.
As I tried to explain to you in a reply on Intercede (LON:IGP) on another site, there’s no point worrying as soon as the share has a down day or drifts down between news updates nor getting too excited when like today ,the share price is up a bit.
What matters with a share like Intercede is news like more Contract wins or a “better than expected” trading update and other potentially good (or bad of course) news. That’s share price moving news. And a bid at a big premium can’t be ruled out.
Intercede is not like some of the blue sky and/or very popular on ADVFN fun punts you perhaps favour for quick in and out profits where a lot of buying (often from mug punters) can see rapid (sometimes temporary) share price gains. I.e are you looking to invest or gamble? If the latter then imo Intercede is not the rapid fast gain (until big share price moving news sends the price way higher) you like to look for, as you might run out of patience waiting for the share price upside!
I hold Intercede (LON:IGP) as a potentially very rewarding quality buy as recent news and Contact wins are reassuring. Perhaps worth reading Paul Scott’s commentary (link below) after Contract wins to remind why you might have bought Intercede?
Good luck with your Intercede holding Penny.
https://www.stockopedia.com/co...
Ken, are you Mansplaning? Pretty aggressive towards Penny’s comment - why take it upon yourself to be irritated and patronising?
Renold (LON:RNO) has seen a 10% pull back in the past two days, there have been some chunky sells today. This appears to be linked to the communication around the company increasing its stake in the Employee Benefit Trust. I know af20001 asked about the potential impact of this yesterday but there was no concrete response. It could be the two are not linked but it seems more than a coincidence. Surely the company must believe the shares are good value if they continue to buy them. Can anyone shed any light?
Renold (LON:RNO) - Is there a destocking risk that we have seen with other manufacturers? - I don't know but would be interested to hear opinion of others who may be better informed.
My snapshot for dotDigital (LON:DOTD) interim results. Some pretty steady results I think, though I do notice they have struggled to grow EPS at the same rate as revenues for the past few years, which I'm not a fan of.
Not a stock I own, though I have been keeping an eye on. I'll wait for an acceleration in EPS growth before I consider buying.
Un-adjusted EPS decline due mainly to acquisition related costs:
Note 7 - “Exceptional costs relate to the amortisation of acquired intangibles £571,000 (FY22: £60,000, FY23: £120,000), acquisition costs of £477,000 (FY22: £nil, FY23 £100,000), Employers' NI on share option exercise of £143,000 (FY22: £nil, FY23 £nil), and professional fees related to the valuation of share options of £9,000 (FY22: £nil, FY23 £14,000).”
Hi Phil P, thanks for flagging up your youtube channel...just watched your 2023 review and really enjoyed it. You have a very similar strategy to me when it comes to trading, as well as good taste in books:)
I just wish I was as organised when I started, in fact I wish I was as organised full stop. Looking forward to watching a few more videos later.
Thanks Wolf, I appreciate the feedback and the watch. Hopefully the videos will improve over time as well as my investing skills.
hi Phil
What is the name of your you tube channel please?
Snazzy
Hi Snazzy, it's just Phil Perry, or @ PhilPerryInvestor
Don't expect too much editing etc as I'm learning as I go, but put out updates on my investing journey & strategies etc. Thanks for the interest.
Calastone has produced its monthly funds flow from UK open ends funds for February. "UK investors are piling into equity funds at the fastest rate in almost three years, according to the latest Fund Flow Index from Calastone, the largest global funds network. They added £2.66bn to their holdings in February, making it the best month for inflows since May 2021 – and the fourth best month on Calastone’s nine-year record." Unfortunately it then goes on to say "Meanwhile, Asia-Pacific funds had their third-worst month on record, shedding £229m, while UK-focused equity funds continued their long run of outflows. Investors withdrew £633m, in line with the average from the last couple of years." Not cheery news I am afraid.
Fantastic review of Reach (LON:RCH) Graham. Very well explained in simple terms, just what I was looking for.
Reach (LON:RCH)
So there are probably just four more years, including the current year, in which Reach will be run primarily for the benefit of its pension funds.
Hmmmmmm ?
i thought the whole point here is that companies make chunky payments medium term to get scheme back into solid position so that its not in too much deficit medium term.
I am not aware that company needs to project to infinty ref possible future shortfalls - so i have always been of the view that the lack of later payments doesnt mean that there will be no later payments at that later time , simply that there is no need to look too far into the future in that regard - being frank its big enough job allocating 80% of profits plus for next 4 years - pension scheme have their pound of flesh are they not simply parking any potential later issues till a time when there will be more clarity?
Do any holders here really think that the £1.5 billion assets will produce enough positive returns to be sorted at that point when history has suggested that exactly the opposite - ie that the reality is that up to now they have needed to fund extra money for one reason or another so why would that change long term ?
In this regard the proof of the pudding is being able to offload scheme or match liabilities with insured assets - so some indication that is happening with regard to the £1.5 bill would be the time i would presume its not an isssue.
Hey ho it could be that once planned payments tail of there are no more extra wads needed from down the back of the sofa - persoanlly i wouldnt preume that is the case though.
These defined benefit schemes have been the bane for many businesses. Those who benefited from winding them down and switched employees into defined contribution schemes early have benefited enormously. It looks like Reach's pension scheme is approx 75% of its Market Value so personally I would keep away (my limit is 5%) and these type of schemes are difficult to plug.
I was in a partnership where our Managing Partner many years ago moved employees over. It was a complicated and time consuming exercise as each employee had to be seen, counseled and agree as to the implications of so doing and we had to sweeten the deal quite heavily for them. Many of us didn't fully appreciate it then but, looking back, his actions saved the Partnership tens of millions of pounds.
Well I think it's a simple bet on getting out of their pension scheme which I strongly believe will happen as DavidJHill also believes. 4 years, in my view is an absolute MAX and I wouldn't be suprised if payments will end up being a lot less, depending on hedging etc... The fact that the CE has commented positively on this suggests they know they are in the final straight to offload the scheme, akin to Walgreen disposing of Boots' pension scheme to L&G last year (circa £5B?).
Then you have the underlying business which I see as a cigar butt, which can be restructured in a far more efficient manner (i.e. weekly rather than daily regionals as an example, which might draw in more readers).
Finally a data led business which is already doing well and can be commercialised in a huge way (already setup with Google analytics) and in my mind, it reminds me of Dunnhumby and Tescos.
Did I just talk myself into increasing my stake?
Reach (LON:RCH)
i agree in principle this is what they need to do to prove to the market that the pesnion is NOT a noose around their neck. In the absence of any specific confirmed plans that this can or will be done i will take the viewpoint is purely aspirational. If the company could get shot without spending hundreds of millions to get the deal over the line i would be expecting them to shout that fact from the rooftops NOW. I have seen no evidence of this shouting as of yet so i wont believe it till i have some reasonable evidence it aint a noose.
The only way for Reach (LON:RCH) to fully derisk the pension schemes would be to buy-out, ie transfer to an insurance company. The liabilities on a buy-out basis are likely to be higher than on an ongoing funding basis - the latter basis being the one that will drive the deficit contributions. I’d expect the buy-out basis to value liabilities at least 5% above the ongoing basis. Probably higher depending on the difference in discount rates/longevity assumptions used between the two valuation methods. Liabilities of say £2bn on an ongoing basis would mean at least another £100m to fully derisk once fully funded on an ongoing basis. Obvs scheme experience against the assumptions used will mean the funding position likely to differ by 2029. So big numbers of unknown movements /future costs of derisking when compared against the market cap. Numbers here unlikely to be accurate and just to indicate a possible quantum to fully derisk the pension.
Interesting discussion on Reach vs its pension fund.
But what interest me is this (there is a lot of assumption here more to look into prehaps) - noting the likes of Pheonix L&G etc are seemingly nice yielding value plays on the main market, if these guys are buying in the likes of Reach's pension on a de-risked basis and then investing - I ASSUME in a mixed but low risk type portfolio and I ASSUME the likes of Reach are currently having to invest in a very low risk (gilt inspired) type portfolio (with the main risk being Reach et al itself). Then in turn this would suggest the investment case for the Pheonix L&G is one of life expectancy vs decent fund returns ?
I would take that as a bull point for Pheonix L&G etc. What am I missing?
One possible risk to the insurers may be increased regulation, particularly if the payer of a large proportion of DB pensions switches to a handful of insurers from corporate UK. I’d have thought the government would want to ensure mass defaults wont happen. For instance, I understand that Just had to reduce the % of its assets held in lifetime mortgages (or similar) backing it’s annuity book to less risky/lower return assets.
That said there are a number of recent new entrants to the market, e.g. M&G, Royal London so they must see the pricing as attractive and no doubt have a good understanding of the assumptions and risks. So the historical pricing achieved by the incumbents may inferred to be attractive from that read across
Reach (LON:RCH)
i am presuming Phoenix only take on companies where they are in a position to effectively hedge themselves out of the equation risk wise. This may cost x million (hundreds) on top of whatever the position neutral defecit position is - or if a scheme is in surplus enough who knows Phoenix might be happy to take it on and pay even.
What is clear to me is that reach dont need the hassle of the scheme and would ditch it if they could do - so until such time as managment say "we are confident the scheme is at a or near a point that it can be fully hedged so no future contributions should be needed" or they say we are hopefully scheme can be ofloaded at cost no more than x million i will presume that they are on then hook for an unknown liability.
Note i am not saying BnB is wrong in their assumptions if they they think the pension may not be an issue they could very well be correct in that assumption - i am just minded not to believe that myself unless i get some real evidence from the company that that is the case - clear unambiguous speach. Note if deficit is coming down due to oversized contributions it would make sense that they may reach that point in the near or medium term. However on the flip side if assets only generate 2% return and need 4% return in any yeat that could add £30 mill extra that needs to be found.
Note all of this is without mentioning the obvious danger of counterparty risk - many financial institutions have thought they were fully hedged when the reality was the complete opposite. Not sure of the bonds issue last year cost any companeis "big wonga they were not expecting" - i suspect that might be the case but until its got shot there is extra risks in that regard.
I would take that as a bull point for Pheonix L&G etc. What am I missing?
I would guess phoenix do much the same as reach do - but simply dont have the schemes with risk that they need to generate inflation plus return - so overall i suspect the pots they manage have much larger safety net that allows them to hedge with others - that is the million dollar question here - if reach went to phoenix tomorrow and said how much do we need to pay now if cash for you to take it - that would imho be the sum i would value the pension issue at. I suspect that info may be known to management - if that is the case would be nice to know what that sum is.
Greggs and other Food Sector
I’m sending a possible “falling tide” is coming in the next 5-10!years in the processed food and fast food sectors .
The “wake the fuck ip” and “this is shit” Message is really starting to get traction .
I just wonder if we are approaching a sea change in national sentiment that will put food processors and fast food retailers firmly on the back foot .
I think it’s started to happen .
Good for real food producers and bad for the food processing industry that’s feeds us the highly processed food that leads to a country with an unhealthy and underperforming population that needs s health service that consumes its national wealth to keep everyone alive .
As a long term holder of Greggs (LON:GRG) I like to think that the 10 year share price graph suggests that management are quite able to adapt to changing customer preferences.
Not sure it’s that simple .
They sell highly processed food .
The move and swing is away from eating highly processed food .
There’s no way to sugar cost this , though they may well try sugar coating .
I liked their vegan pastie offerings when travelling back on the motorway from Cornwall.Literally every service station, big or small, had a Greggs and a Starbucks.
Hi Graham - one thing to note on Reach (LON:RCH) is that the actuarial deficit is quite likely to reduce (and possibly significantly) in the Dec 22 triennial. How much is unknown as we don’t know the extent of hedging and LDI that may impact the positive yield moves. So in theory that could mean a much earlier declining contribution curve.
Combine this with other cash requirements having now predominantly fallen away (ie earn outs and historic legal costs) and we could see strongly increasing cash generative business. That should underpin the 10%+ dividend yield.
The google decline of cookies makes first party data much much more valuable and Reach (LON:RCH) has bundles of it so that should help.
Market clearly was fearing a worse update but rise this morning makes sense to me.
A poster on advfn says this:
"The PPT is now on their website, just register your details and get it:
hTTps://assets.main.pro2.maf.media-server.com/66a681933ee14e358d2af8ab93a64bfd/Reach_plc_FY23_Presentation.pdf
Page 14 and 18 are particularly good reading.
Use of cash is (148) million.
But once the HLI and Pension savings start to kick in, then that use of cash is about 62 million. Subtract from the 113 million generated, that gives 50 million extra cash every year.
They could double the divi with that and still have 25 million left to develop the business."
Time Finance plc TIME, the AIM listed independent specialist finance provider, announces that the Group will provide a detailed trading update in respect of the financial year to 31 May 2024 ("FY24") on 26 March. The FY24 trading update will fully incorporate nine months of Group trading to 29 February 2024.
With continued strong demand from businesses across the UK for the range of alternative finance products that the Group offers, and with positive trading momentum continuing throughout December, January and February, the Board has confidence that FY24 Revenue and Profit Before Tax ("PBT") will now be not less than £31.5m and £5.7m respectively, each ahead of latest market expectations(1).
(1) Current market expectations at the date of this announcement are of FY24 revenue of £30.8m and FY24 PBT of £5.4m.
That is about the 4th upgrade to expectations within that nine months
I think the board and advisers of Spirent Communications (LON:SPT) have to be congratulated for not allowing any leaks of their bid, I can't see any volume/price spikes to suggest that. Just goes to show that it can be done.
The fact it's such a rarity shames the FCA for its failure to act on clear market abuse surrounding so many other bids and placings, including all the Sky News and Betaville type dramatics.
edit... and I'd add, I did once meet the tax/treasury guy at Morrisons who went to prison for insider trading of information relating to its talks with Ocado. He got what he deserved, but he must think he was unlucky.
Some of the prosecuted abuses are ridiculous like a BP M&A executive's husband in the US borrowing money to trade on a BP takeover she was working on whilst working remotely at home during the pandemic.How people think they would get away with this makes me think things are getting better with checking for market abuse somewhat.Perhaps it's AI technology like Palantir Technologies (NYQ:PLTR) 's being used to merge and quickly check different sources of data.Encouraging a Goldman Sachs (NYQ:GS) UK employee got caught trading inside M&A information recently.
You know, I think a simple strategy is to look at Paul's green flags, double-check the debt, Q-score and the returns on capital, especially where he uses the word "GARP", and then just buy-and-hold. I reckon I'd get much better results than whatever it was I've been trying to do the last few years.
Hi Mark,
Thanks, although to be fair, we often find the best businesses are too expensive on a short-term basis (Greggs being one of them!), so we often go amber, or amber/green with that type of share (good but expensive). So it's a tricky one.
Mind you my 2023 top 20 (the best GREENs that I manually choose) has done strikingly well, it's now 32% ahead of AIM (up 20.7% absolute) - I've left it running, with the spreadsheet still updating live prices. Mind you, one good year doesn't make a trend of course, it could have just been luck, and catching a few takeover bids.
Screening on Stockopedia, and selecting the highest quality companies, and being flexible on valuations (being prepared to pay up for the best companies) is probably a good long-term strategy too I imagine.
Regards, Paul.
Hi Mark,
Well LON:GRG is one of the few I got properly right. I bought back in 2010s when the share price was just north of £4.00. The reason I make this irritating post is is 2 fold. (have had a few dog investments too but I will not mention them).
1. I bought what I thought was a good company on the back of 2 bits of bad news that I judged to be one offs - both weather related. So IMO a good entry point to shares like this is often when there's a couple of PWs or dark clouds floating about.
2. Greggs have stuck to the UK and have made a successful foray in Ireland. If they ever could make an international move they might clean up. I know this has not been a happy hunting ground for others but...
Building materials distributor TPK might be worth a mention for the macro.
It's interesting to see a comment on ADVFN from Feb 2023: "Shocking interview on CNBC boss just wanting to talk about history and brands and not answering Qs on outlook etc" A portent of things to come.
Morning all. My snapshot for Somero Enterprises (LON:SOM) full year results. I guess I don't follow as many UK small caps as I thought as I haven't posted here in a while.
I've made some changes to the snapshot sheet, with an increased focus on momentum, which I have incorporated more into my investing strategy recently. The idea being I want to see green at the top of the columns, which means accelerating growth. I find it very useful to have a quick visual interpretation of how the company has been growing over the past few years. In Somero's case declining, though with a levelling off in revenue decline with forward guidance, maybe a return to acceleration soon.
I can't find anywhere on Stockopedia that's like the SCVR for US stocks (please let me know if there is). Not sure if I'm supposed to link to outside sources (I'll delete if not), but thought it may be of use for some people to know that I post these snapshots for all the US & large cap stocks I follow on my Twitter, or X as it's now called, what a stupid name. The link is in my bio, just click on my name.
Any way in terms of Somero I think these results are reasonable with some decent growth in Europe & Australia. We just need the US to return to growth, which they sound fairly confident of in their commentary, though maybe not for a while yet. I have held for a while.
Agree. Divi looks strong and on the basis of that I am happy to wait for 2025 when the US picks up.
Thanks Phil for your update and I am in full agreement (as a holder). Perhaps one I should've cut once it crossed a sensible stop-loss point, but am now holding on awaiting the recovery.
Also thanks for the direction to your X-channel. Very interesting. Best wishes for success.
Thanks Kevin. I'm in the same position, I definitely should have cut when the fall started, but at the time I didn't have proper rules in place. Now I have some rules I don't think it's worth selling at these valuations, though I do have a stop at 306p. The dividends at the moment don't hurt either.
Hi Phil do you have a link to your youtube site ? thanks
https://www.youtube.com/@PhilPerryInvestor
Bakkavor (BAKK) volume been higher good positive updates pretax profit GBP 70M vs 18.1m YOY, Revenue 2.20b vs 2.14b YOY
Reach (LON:RCH) another holding of mine that has caused some healthy discussion. Some bullet points:
The company's print revenue fell 2%, as a double-digit decline in advertising was largely offset by a strong circulation performance.
So circulation doesn't appear to be going down as much as the market expects.
Digital revenue fell 15%, it said on Tuesday, although it added that data-driven revenue - from registered users - continued to outperform the market and now represented 43% of its total.
This is where I see longer term value, the data aspect of people in a digital age.
Chief Executive Jim Mullen said Reach now had clarity on two significant long-term uncertainties in pension funding and "historical legal issues", a reference to phone hacking cases, giving it a "clear path forward for the business".
As in my previous posts advising that all historical issues seem to have cleared seems to be acknowledged by the CE.
ON TRACK TO DELIVER A REDUCTION IN FULL-YEAR OPERATING COSTS OF 5-6% FOR 2024
Restructuring and selling assets was always on the cards and they have started implementing their strategy.
13% yield whilst you wait for the improvements to come down to the bottom line. I've said it before, if I wasn't so much into Smiths News (LON:SNWS) I would have a much larger position here.
Reach (LON:RCH)
I stand to be corrected but it looks like pension contributions may perhaps stay at current levels until 2028 perhaps? - this year £60 mill (can anyone confirm if that is the case?) . They did say as things stand they expect those contributions will be £40 mill pa less from 2028.
Looks like the pension schemes are getting their pound of flesh now in the knowledge that there wil be another review by 2028 , in which case if payments need to stay higher then the promise of lower payments in the future NOW is worth little - they ned returns on the £1.5 pension scheme assets and based on this year those assets dont seem to be returning much.
How does the maths stack up here ?
If they make £70 mill net profit in 2024 and have to fund dividends at cost of £20 mill and pension scheme at cost of £60 mil - that leaves negative numbers practicably speaking.
Ok they may have greater than 100% cash conversion on profits but its not particuallry evident that much will be generated for shareholders if its confirmed they need to pay £60 mil pa into pension scheme till 2028 and profits going forward are no greater than £70 mill pa.
Lets face facts digital may be the future but even that revenue is down year on year (and more so that print)
Does anyone know what pension scheme contributions will be pa trll 2028 and how does this tally with posters prior comments that pension issue was nearly sorted (imho thats anything but the case) if that is the case - does that change things if contributions are higher than previously expected medium term.?
Rmillaree - you are forgetting about the 2022 triennial and the 2025 triennial. These will be positively impacted by the change in interest rate environment.
So worst case we are looking at 4 years of significant cash outflow that has now been agreed with trustees. But remember that other cash outflows (Express earn out payments, historic legal costs) abate so going forward there remains plenty of surplus to maintain a 10%+ dividend. I would also expect a big reduction in deficit post triennial (but can’t quantify as I don’t know their hedging approach) so we await that.
So you can have a 10%+ return a year on Reach (LON:RCH) whilst the pension deficit converts to surplus over somewhere between 3 & 5 years depending on portfolio construction/hedging…… at which point a business generating £100m of cash per annum for £250m
To answer your question - the end of this month will see a revaluation of the schemes. I believe that people cleverer than me have pencilled in £50m pa until 2028 given that the last revaluation would be based on zero interest rates so one would expect some uplift on that.
Disposal of assets I've always thought would assist bring in cash as and when is necessary, especially moving to a digital age. Currently listed as over £1billion with £163m actively up for sale (I'm trying to read this on my iphone so apologies if I haven't got the correct line).
This combined with the announcement that operating costs are dropping by £25m per year and will continue to drop, I don't think it is hard to see how the money starts to balance out?
Reach (LON:RCH)
Disposal of assets I've always thought would assist bring in cash as and when is necessary, especially moving to a digital age. Currently listed as over £1billion with £163m actively up for sale (I'm trying to read this on my iphone so apologies if I haven't got the correct line).
I am not aware of any material such assets other than those that earn their curent profits and the £80 mill freehold porperty - per todays accounts assets held for resale are £11 million. They do have £80 mill of freehold property - get rid of the property though and on lfl basis you would need to pay rent so have lower profits . I would agree there is probably potential to downsize property portfolio and realise some funds.
Note they do have £800 intangible assets - i take that to be their bread and butter on which they earn their £70 mill pa profit - if they sell those assets their future income drops.
Reach (LON:RCH) way too complicated to go into here but go and look at todays results and section Retirement Benefit Schemes for proper detail.
They helpfully show that a 1% favourable move in the discount rate changes the deficit by some £165m. Given the discount rate has moved since Dec 22 by circa 75bps the actuarial deficit will likely be £125m lower than shown in the deficit today. Ie total deficit more likely to now be circa £175m in total. Only the MGN pensions scheme was revalued in 2022, the others are still based on 2019 when the discount rate was about 3% different to today. Thus the funding profile requirement has the propensity to be materially quicker than currently projected. Add to that the increase in asset values since 2022 and that could be markedly so.
Once a scheme reaches neutral a run off provider like Just (LON:JUST) or Phoenix group (LON:PHNX) will take it on. They fully hedge it and then constantly adjust for changes in life expectancy etc. This is a growing trend amid strong demand from specialist providers. The nominal size is more or less irrelevant. It’s a bit like saying if I have two 5year interest rate swaps one with +£10m notional verses the other -£10m notional that I have £20m of risk - I don’t that is utter nonsense. I am exposed only to the rate differential (which is now locked in) and any counterparty exposure (which I can also hedge or daily margin). The assets and liabilities in the scheme work a similar way.
So this is a business that may need to fund £60m a year for up to 4 years whilst generating double that in operating cash flow. Over the 4 years you can have an 11% annual return via dividend and at the end of that potentially materially more. Then you have a business generating £120m cash with a market cap not much more than 2 years cash flow and a fully funded pension (that they will divest if they’re sensible).
Combine the 11% dividend and potential for a significant re-rating as deficit funding tails off and the long term annualised return profile looks pretty compelling for me now.
Reach (LON:RCH)
The nominal size is more or less irrelevant.
I simply dont belive this - surely the bigger the scheme assets and scheme liabilities the bigger thde risk if there may be a shortfall. Yes its possible to farm scheme off and yes its posible to get insurance cover have matched hedging (is any hedgeding foolproof gulp?) but surely the larger the size of scheme assets and liabilities the more risk there is that the assets have to suitably perform. The fact it can be done by others doesnt imho provde to me thats its possible with their specific scheme - each scheme presumably being different. Happy to be convinced otherwise by stuff coming out the words of the company backing up your confidence here.
Reach (LON:RCH)
Ding Ding seconds out for round 4 of today's oftentimes repeated heavyweight bout rmillaree v davidjhill.
Referees are currently scoring today's 10 rounds bout as a draw.
Who's your money on?
Personally I would never again touch a company with a high pension deficit having been burnt before but what do I know.
I'm just happy to be entertained by today's contestants.
Snazzy
Reach (LON:RCH) I’d say management have effectively signalled that today.
Sure you can wait until you see irrefutable proof but I suspect most of the value on offer will be gone by then. My point is that I believe the market is mis-pricing the pension risk and the facts that I do have at my fingertips from the company back that view up if I extrapolate the points. But they have helpfully spelt out the sensitivity impact on the schemes for the different variable such as changes in inflation, discount rates etc. so people can work that out for themselves.
Having looked at that I now think the scheme is materially better than 2019 and 2022 year end actuarial positions tell us. Therefore in the absence of any material downtrend in the 10Y UK rates curve I can see the light at the end of the tunnel.
Clearly this is never a stock you will get comfortable with though so that’s fine. We can’t all like the same stuff.
Yes larger pension = larger risk, irrespective of whether it in surplus or deficit. As davidhill notes a 1% move in interest rates moves the fund £165 million. If interest rates decline by 2% in the next 12 months, this is an increase in the deficit of £330.
but not if you hedge interest rate risk
I can't quite tell from the table if a 1% DR move is £165m up and £200m down or vice versa so I took the most conservative.
I would expect the scheme to hedge interest rates to a large degree sometime around now rather than leave variable but I can't tell for certain.
So larger pension does NOT necessarily equal larger risk. That's like taking a portfolio of notionals and going "omg thats large" without actually understanding the overall risk across the portfolio and how it moves.
If I have a £3bn liability in 30 years time and against that I have an inflation linked Govt bond also maturing in 30 years, is that more or less risky than a £500m liability backed by £550m worth of Gold bullion ?!
Notional size on its own DOES NOT EQUAL RISK!
Notional size on its own DOES NOT EQUAL RISK!
I would agree with this statement if stuf is fully hedged but if but if your assets and liabilities arent hedged/insured etc surely you agree that the larger the size of the pot the larger the risk. To me its pretty obvious they try to hedge where they can if its not too costly but that may simply not be affordable or doable - if they made promises ages ago that simply must cost wonga to deliver as the scheme assets cant match the return profile needed.
no I don't agree rmillaree
the absolute size of a portfolio is irrelevant. What matters is the construct of the portfolio and how that portfolio is correlated to macro or actuarial adjustments and the relative sensitivities (in a pension).
Saying a portfolio is more risky because it is larger is fundamentally wrong. You have to look behind the portfolio at the risk ladder. You can find large portfolios that convey far less risk than smaller portfolios; that is mathematical fact, it isn't subjective. So in the case of someone like Just (LON:JUST) or Phoenix group (LON:PHNX) they will look at the risk (not the absolute size) in determining what to bid for or when setting conditions precedent to take it on. That is the way the industry works.
Don't see it on the agenda above but just to note that Time Finance (LON:TIME) have reported this morning that they expect to be ahead of latest market expectations (slight beat of around 5.5% on a PBT basis by the looks of it).
Reach (LON:RCH) cost cutting continues, pension commitments down by £40m, +ve mgmt comments. First party data so important post cookie phase out as I've mentioned before:
"Our in-house first-party data capabilities, in particular our proprietary Mantis tool, will stand us in good stead as Google continues to phase out third-party cookies, a process we have now seen beginning in 2024. This will be a major shift in the landscape for publishers and advertisers, who for years have depended on third-party data to target their advertising. We will be significantly ahead of the curve on this front, with 12.3m registered customers, of which approximately 4m are active over each four-week period, and advanced capability to effectively place advertising using contextual targeting."
https://www.investegate.co.uk/...
P/E of 3 and yields 12%
Beeks Financial Cloud (LON:BKS) I listened to the podcast with Paul last week and never once have I heard such a bullish CEO that really rates the opportunities, without wanting to blow his own trumpet too loudly - either Gordon is a complete liar, or an astute businessman, who wants to under promise and over deliver, having been through quite a difficult growing phase. I strongly believe in the latter.
£5 million contract announced today, starting in 2025 and at £1m pa, this is probably the start of many, especially given today's outlook:
As previously announced, FY25 trading anticipated to be significantly ahead of prior Board expectations.
Together with meeting FY24 expectations, this is the share for me to rerate and given the nature of the business, there aren't many players out there and when it literally takes years to get approval from big financial firms and then they commit, they aren't going to go back as they have tested the ability of their products and are happy, which leads to more contracts, recurring revenue etc... Big moat, excellent IP and the groundwork has been done. I hold quite a bit, although possibly not enough!
Never been able to understand what is special about Beeks Financial Cloud (LON:BKS) service. Surely low latency connectivity close to exchanges isn't that hard to replicate?
Not sure that's right and more importantly once you are embedded in the system it will be very difficult for a competitor to displace given all the regulatory and other hurdles required to win the business. Beeks Financial Cloud (LON:BKS) seem to have first mover advantage and a track record established here that puts them on a strong footing.
Revenues are sticky but profits are close to zero so low profits are also presumably sticky. It justs seems a low profit business that gobbles up a lot of R&D and capital.
They have a 'land and expand' model and are in the process of landing the contracts which takes investment to benefit from the more profitable expansion that follows. They have also reduced debt with net cash increasing from £3.35m to £5.44m.
I think you need to understand the model a bit better Epitychia. This is a forward cash machine. Beeks Financial Cloud (LON:BKS) No differnt to AWS and Azure in that regard.
The Exchange win today should double EPS according to broker…..that tells you everything. In reality it has stopped burning cash and is now cash flow positive which was really the inflexion point.
If you constantly look in the rear view mirror you will completely miss the point of this business.
Beeks Financial Cloud (LON:BKS)
Davidjhill is exactly right and very well communicated.
I hold.
Beeks Financial Cloud (LON:BKS)
I do want to point out that today's announcement of a contract win is already included in forecasts for FY 06/25.
Canaccord, in their note of today, suggest that the previously announced exchange cloud win with the large global exchange has the potential to increase EPS by 50% based on an additional £10m of sales, or even double EPS based on an additional £20m sales in FY 06/25. There is nothing in the present forecasts for this.
Never been able to understand what is special about Beeks Financial Cloud (LON:BKS) service. Surely low latency connectivity close to exchanges isn't that hard to replicate?
The servers are easily implemented. The secret sauce is in the security and low latency redundancy provision to meet the most demanding of regulatory and commercial demands. It’s a narrow but potentially very valuable niche.
Hi jesseowens - massively hard to replicate and get financial institutions to sign up to. The Exchange deals Beeks Financial Cloud (LON:BKS) are doing and the institutions they are signing up are super sticky. These type of businesses generally trade on high PERs given revenue visibility and stickiness.
The USP is connecting physically to the exchange hardware. I get that. I am just not exactly sure who is going to want to buy their product - some hedge funds and some day traders ? Id be interested in insight on this.
Having said that their tie up with the Johannesburg Stock Exchange seems exciting - but is done via IPC as a j/v so how much of this "win" is down to IPC's inolvement? Still BKS starting to look interesting to me judging by the share price it seems others are ahead of me (I dont own).
For me the potential bear point would be the amount of profit Beeks Financial Cloud (LON:BKS) can earn might be dictated by the exchange itself a- s BKS is reliant on the connection that the exchange authorises. Having said that there are many firms getting rich for doing who knows what in the financial world so probably reasonable / decent earnings will be ok (unless worldwide regulators decide to copy the FCA consumer duty).
Incidentally tried to look up market cap of IPC Systems Inc and it appears to be owned by private equity. IPC looks like an interesting co itself.
Beeks Financial Cloud (LON:BKS) just looks such a turkey when looking purely at Stockopedia data which is all I can go on.
Figures for these tech companies can look horrible, but that is the past and not the future. Beeks Financial Cloud (LON:BKS) does 'similar' to AWS and makes Amazon.com (NSQ:AMZN) 70%, yes 70% of its profits! That was launched in 2006, and would have been in development for years. Depends when you want to get in for the ride, but purely on growth being announced, I think there's something here.
Beeks Financial Cloud (LON:BKS)
Cadmunkey,
Stockopedia rankings will not help when looking at these types of high growth companies.
To gain knowledge on Beeks, you can look at RNSs, Beeks company website, Annual Return, broker notes from Progressive and also Canaccord if you have a Research Tree subscription as well as interviews and presentations on Investor Meet Company and Vox. There is also a company interview with Beeks CEO Gordon McArthur by an interesting chap called Paul Scott. He does an excellent weekend podcast complete with noises he says are hiccups. All these are free to access. PI World is also an excellent resource.
I agree Michael. I have been a shareholder for a few years and think hearing the presentations and interviews essential to grasp what this is about. Gordon McArthur has implied that he could have exited for a lot of money previously but has a much higher (undisclosed) target price in mind. I don't think investors should be distracted by the £2.8m he took off the table in 2022.
Thanks Michael for the information I will do more research. I am a mere amateur investor compared to most people on here, so probably overly cautious if Stockopedia is negative toward a company.
Beeks Financial Cloud (LON:BKS) just looks such a turkey when looking purely at Stockopedia data which is all I can go on
It’s worth learning how to value tech companies. And that often means understanding, if not the technology, then at least the benefit that it brings to the customers. Ultra rich clients like investment banks will pay a lot of money for a competitive advantage – or even just to keep up with competitors who have made technological investments of their own. One thing for sure there is more growth to be found in the tech sector than anywhere else. And ultimately, that is what delivers the spectacular performance you see in the winners stateside. The key is to try to understand what the numbers will look like 3 to 5 years from now. Forecast sales data from the company and analysts is very helpful in this regard. Nvidia looks like the most expensive stock on the planet when viewed retrospectively. With a 3 to 5 year view, acknowledging that a lot can change over that period, it still looks decent value after 6 bagging in a year!
Plenty can still go wrong with Beeks, but, assuming progress is maintained, today’s price might look very cheap in a couple of years time.
Edit to add: just be aware that a failure to meet growth expectations inevitably results in big price drawdowns. Nvidia halved in value two years ago.
Beeks Financial Cloud (LON:BKS)
You are spot on BnB.
However, where forecast growth fails to emerge for whatever reason there is a very heavy price to pay.
High growth shares are mostly not for the risk averse investor. Buyer beware.
Snazzy
Absolutely right Snazzy. I’ve edited the original post to reflect your sensible warning.
Re Beeks Financial Cloud (LON:BKS) I’ve read the Progressive Equity note, it doesn’t identify any competitors…anyone know who they are?
Hello John,
Beeks Financial Cloud (LON:BKS) competitors:
Options Technology (UK)
Pico (USA)
Both Private equity.
Michael
Thanks Michael..appreciated
Beeks Financial Cloud (LON:BKS)
when looking purely at Stockopedia data which is all I can go on.
Why not look at very decent progressive note on the companies own website - this company is all about the future and clearly the future is more bright than the past here
https://beeksgroup.com/investo...
Beeks Financial Cloud (LON:BKS)
In my opinion Beeks does not have much of a moat, it's just a connectivity and hosted server provider, renting out cages/rack space in Equinix datacentres and hooking up clients to the Exchanges/ECN's/Liquity Providers using fibre Cross Connects.
As far as I can tell (please correct me if I'm wrong) Beeks does not offer any software solutions (single API, aggregators, OMS, risk system, algo's) that other providers like OneZero, Fluent Tech, MarketFactory, Itviti do. It's a crowded and competitive space which Beeks looks to under offer in. You can go on to any platforms website and see who they work with or have certified with:-
https://www.cmegroup.com/partn...
https://www.cboe.com/global/fx...
https://www.londonstockexchang...
Beeks Financial Cloud (LON:BKS)
In my opinion Beeks does not have much of a moat
Its sales that talk more than anything else - they have managed to quadruple sales in 5 years compared to where they were in 2020 and they are expected to ramp up profits to decent levels in same timeframe - so whilst knowing zilch about their competitive advantage (whether they have one or not) if the brokers forecasts are to be believed they are clearly doing something right that make their customers choose them. What that magic ingredient is i know not - perhaps its as simple as good customer service with reasonable pricing. Ok we should be wary about future forecasts being extra rosy - but i have seen nowt here to suggest this company is an any way pimping things up ref expectations beyond what is reasonable. I dont hold shares at present here so i certainly aint talking up a stock i hold.
In my opinion Beeks does not have much of a moat
Do you mean moat? Or USP? The moat lies in the stickiness of the product once installed. It is a horrendous risk for a financial trading or data business to change its core technology. So, once committed, the revenues are sure to stay in place for many years.
Beeks Financial Cloud (LON:BKS)
I used to hold Beeks - Bought between 122-168p in Feb/Mar-22, got out at 151p in Aug-22 for a small loss.
I don't think they have a particularly strong USP, but I wish them and all holders here success.
I don't see a long future in co-location. Google, Microsoft and AWS have partnered with major exchanges. Single and multi dealer platforms will be next. In less then 10 years connectivity providers will not be needed. My money's on Amazon taking over Equinix.
Greggs (LON:GRG) while definitely not a small cap, Greggs results today continue to impress
Record performance as they roll out new shops & concepts (see what I did there ;-))
Not cheap on most metrics but executing well, not sure why I don’t hold them
Greggs (LON:GRG) a great business with a similar vertical integration strategy to two other successful retailers, Games Workshop (LON:GAW) and Howden Joinery (LON:HWDN) which puts them in control of their supply chain, production costs, quality, efficiency and consequently margins and ROCE. I hold the “GB Terrific Three” quality compounders ;)
Sadly I can only claim Games Workshop (LON:GAW) out of the 3 but in my defence I have held since 2015…
AstonGirl you must be very pleased with the divs never mind the share price growth! Games Workshop (LON:GAW) I’ve been holding holding since the nineties. Unbelievable dividends worth 9x the original investment.
My morning smallcap tweet: Poverty of expectations
Blackbird (LON:BIRD) Headlam (LON:HEAD) Somero Enterprises (LON:SOM) Beeks Financial Cloud (LON:BKS) Active Energy (LON:AEG) Esken (LON:ESKN) Argo Blockchain (LON:ARB) Harland & Wolff group (LON:HARL) Oxford BioMedica (LON:OXB) Tern (LON:TERN) Petrofac (LON:PFC), Reach (LON:RCH)
◄BlackBird (BIRD)► FY-Dec rev down 32%. Pretax -£2.6m (-£2m). Tries ever so hard to be positive about FY24. [SP=6.24 Cap=23m]
◄Headlam (HEAD)► FY-Dec. Outlook - "market weakness observed at the end of 2023 has continued into the first few weeks of 2024". Also operating cost inflation still high. [SP=205 Cap=166m]. I hold.
◄Somero Enterprises (SOM)► FY-Dec in line. Guides FY24 rev 'comparable' and BITDA slightly lower due to "modest incremental investment". [SP=346 Cap=192m]. I hold.
◄Beeks Financial Cloud (BKS)► c. £5m five yr contract. Rev starts H1 FY25. [SP=174 Cap=115m]
◄Active Energy (AEG)► to get $1.65m as it settles dispute with Player Holdings which pulled out of deal to build a production plant. [SP=0.34 Cap=1m]
◄Esken (ESKN)► extension (to ?) agreed to yesterday's deadline for co agree to London Southend Airport bondholders' recapitalisation proposal. Negotiations continue. [SP=0.19 Cap=2m]. I hold.
◄Argo Blockchain (ARB)► still selling the family silver as it takes $6.1m for Quebec data center. Co will lose minimal revenue. [SP=17.5 Cap=119m]
◄Harland & Wolff (HARL)► becomes preferred bidder status for the Falkland Islands Port Replacement Project. It ould generate £100-120m rev over a two-year period, with works expected to commence this year. Don't all these clients know how perilous the co's finances are? [SP=10.09 Cap=17m]
◄Oxford Biomedica (OXB)► guides FY-Dec rev and EBITDA in line. Guides FY24 rev £126-£134m "reflecting the successful integration of ABL Europe and anticipated growth from new and existing client programmes". Three-year rev CAGR increased to 35%+ from 30%+. [SP=167.2 Cap=167m]
◄Tern (TERN)► Konektio goes bust so Tern's holding (£223k book) worthless. [SP=1.85 Cap=8m]
◄Petrofac (PFC)► still negotiating (see RNSs 4 & 20 Dec) with credit providers to get the performance guarantees which are contractually required for other recently awarded contracts. Making progress in exploring the sale of non-core assets. [SP=23.6 Cap=123m]. I'm short.
In line: RCH
Spirent Communications (LON:SPT) Recommended offer of 172.5p plus 2.5p special dividend. I hold, but that just makes me breakeven.
I'll make about 10% on my shares, given my break even is about 155p. Sell on the spike up or hold for a possible counter bid. Any one have advice for what to do when a takeover bid occurs?
Three things you can do.
Wait until it completes and take 175p. If you are sure it will go through or possible, a better offer will come along.
Sell some now and wait for the 175p for the rest. If some doubt or you need some money for something else.
If there is some doubt about the offer, then sell all now.
I'm inclined to the first option at the moment.
Spirent Communications (LON:SPT)
Thanks for the advice
Purely personal choice on what to do in these situations but my preference is to sell half & keep half. That way if a competing bid does come along you still benefit with half your holding. Should the bid fail for any reason you’ve got some profit
The recent bidding battle for Wincanton (LON:WIN) shows the benefit of holding on to some, correspondingly the failed bid for John Wood (LON:WG.) last year shows the disadvantage of holding on
Do let us know what you decide
Decided to sell half and keep the rest !
Spirent Communications (LON:SPT) Recommended offer of 172.5p plus 2.5p special dividend. I hold, but that just makes me breakeven
Same for me. And only because I took the risk of doubling down when shares hit rock bottom. A lucky escape.
Pure speculation, but this might be bad for Calnex Solutions (LON:CLX) . The latter sells much of its product through Spirent, and the acquirer may have competing products to distribute through Spirent’s channels.
Re Spirent Communications (LON:SPT) bid - this is from Calnex Solutions (LON:CLX) annual report
The Board believes that the Spirent throughput in FY23 is not indicative of the Group’s reliance on Spirent for revenues and that Calnex has strong direct relationships with the relevant end users. In addition, all products are branded as Calnex products when they are sold through Spirent and customers are fully aware that they are buying a Calnex product through the Spirent channel.
The Group has changed channel partners multiple times in the past and has managed this process with little disruption to trading.
FY23 saw a reinforcement of the commitment by Spirent and Calnex to the ongoing relationship with the signing of an updated distribution agreement.
Also see here for Calnex's niche
https://uk.sports.yahoo.com/news/land-major-hyperscalers-calnex-relies-154655123.html?guccounter=1&guce_referrer=aHR0cHM6Ly93d3cuZ29vZ2xlLmNvbS8&guce_referrer_sig=AQAAAH6YFrmMaUZ1eUUPMUYE824SW9jhY35IuVqtYS0sagc1KCuRwg89A9jL3N81A9kYCuXsyvmbgH0BkB9kDK_9dAQQ1ChqE3dmiLMSfa_TYDA0DFthOY9b5KyH2Ct_A4YMA-XfkLNfA6qlJmFw9zTSqWKqXy8sd1587e11XHZvXM4S
Calnex Solutions (LON:CLX) No reaction to Spirent Communications (LON:SPT) just buys this morning.
Calnex Solutions (LON:CLX) No reaction to Spirent Communications (LON:SPT)just buys this morning.
There was no reaction in Calnex when Spirent started to issue its series of profit warnings, despite the obvious revenue connection between the two. And look where Calnex shares ended up. Again there’s been no reaction again this morning, despite what I would describe as a bloody awful trading update from Spirent. Perhaps the possibility of a takeover for Calnex is balancing out the probability of another profit warning. Perhaps Calnex shareholders are just a bit slow off the mark. Or maybe they know something I don’t. But the recent recovery from 40p to 80p (now a still surprising 70p) looks way overdone.
Perhaps Calnex Solutions (LON:CLX) shareholders know they own a high ROCE, high margins and high growth company in a sector that is in a temporary downturn. Perhaps they know in the short term the market is a voting machine. Price Target from my thorough analysis 155p.
Calnex Solutions (LON:CLX) Price Target from my thorough analysis 155p.
Good to have someone take the offer of a discussoin. I don't disagree CLX is a good company and their products competitive. I like Tommy and his 'tache. And 5G and then 6G aren't going away. I just don't see that target coming close without some pain beforehand. Especially after Keysight's PW last month, the second in the last 3 updates. How do you get to that PO and in what time frame?
Perhaps they're seeing value in the shares as Spirent Communications (LON:SPT) was still taken out for a decent premium to its lows at the bottom of the telecoms invetsment cycle.And with several future growth catalysts when the telecoms industry, including the 5g rollout, starts capital spending again, as will be necessary.Not so great for longer term shareholders perhaps as Paul added.
SPT
A solid company going through a difficult macro environment.
I hold and intend to stay onboard. Don’t know who the acquirer is but good for them.
Spirent Communications (LON:SPT) - Viavi Solutions (NSQ:VIAV) only slightly bigger by market cap. Possibility that Keysight Technologies (NYQ:KEYS) which is 20x the size might be interested?
About the same. Let’s hope for a bidding war!