Small Cap Value Report (Tue 5 May 2020) - TGP, AIR, GETB, JSG

Good morning, it's Paul here with the SCVR for Tuesday.
Timings - a bit late today, but should be done by 3pm.
Today's report is now finished.
Please see the header for company announcements I'll be looking at.
Jack has kindly sent me a section on Air Partner (LON:AIR), which I've copied in below. Thanks Jack! Always good to have a contribution from you.
Tekmar (LON:TGP)
Share price: 120p (up 4% today)
No. shares: 51.3m
Market cap: £61.6m
(I have a long position in this)
Tekmar Group (AIM: TGP), a leading technology provider of subsea protection systems for the global offshore energy markets, announces the following trading update ahead of the Group's results for the year ended 31 March 2020 ("FY20" or the "Period"),
We're not seeing many positive updates like this at the moment - it's in line with expectations for FY 03/2020, together with a positive outlook statement.
- Revenues - up over 40% - despite Covid-related problems. All the more impressive given that Q4 (Jan-Mar 2020) is seasonally important to profits
- Order book at year end was up 39% on prior year, at c.£10m
- Net cash of £2.1m at year end
- Received a £3m loan via Barclays, under Govt's CBIL scheme - good to see this paying out
- Liquidity - well placed, given above cash headroom
- All sites continuing to operate, with only 8% of staff furloughed
- Temporary freeze on capex, recruitment, and pay rises, to conserve cash
- Outlook - demand for offshore wind remains strong
.
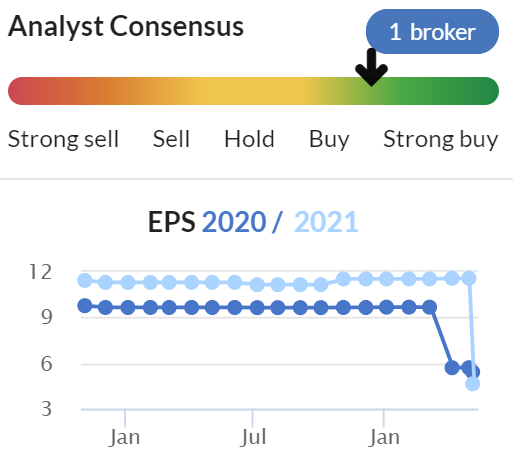
There is a catch though - the company warned on profits in Feb 2020, and broker forecast was considerably lowered. Hence it has only achieved the reduced forecast number. It's always worth checking this! See below;
.
.
Valuation - this is a rare case where I can actually use broker forecasts! Or rather, I could if there were any broker notes available, which I cannot find on Research Tree or elsewhere for Tekmar.
Going by the Stockopedia numbers (Thomson Reuters data) they have 5.41p EPS forecast for FY 03/2020, and we know the company is in line with that. At 120p per share, that's a historic PER of 22.2 - not exactly a bargain. I can live with that PER, because the order book is up a lot, and outlook promising. The company seems to have excellent niche products, in a thriving sector, hence why I like this share, and own a few.
The forecast for FY 03/2021 shows a fall in earnings, to 4.63p, which is now looking too cautious. It's very difficult with broker forecasts at the moment, because so many are out-of-date, prepared pre-covid, and with company guidance often withdrawn, brokers don't seem to want to stick their necks out with updated, more cautious forecasts. Strange, isn't that their job?! In this case however, broker forecast looks sensibly cautious, maybe too cautious now?
My opinion - I like this company a lot, it ticks a lot of the boxes for me - niche products in demand, decent profit margins, sound balance sheet, positive outlook despite covid. Imagine what it could be doing in more normal circumstances?
I reviewed the admission document in some detail here on 18 Feb 2020, when the company warned on profits due to covid disruption in China. That should no longer be an issue, hopefully.
Lack of liquidity in this share is a big problem. I had an order in to buy 10,000 shares after the profit warning, but my broker could only get 5,000 after trying all day. That does make me think, what is the point of it having a listing, if there's so little liquidity in the share? This so frequently happens with small cap floats - the brokers are lazy & greedy, and want to earn big fees with as little effort as possible. Hence the shares are sold in large lumps to institutions. Hence when trading in the shares starts, nothing happens? There can be negligible trades for years, in some smaller caps, for this reason. It's hopeless! All floats need to fragment the shareholdings as much as possible, in order to create an active aftermarket. Otherwise a listing is pointless.
Some companies solve this by getting management out there, going to investor events, doing presentations & webinars online, making sure broker research is widely available on Research Tree, etc, in order to stimulate some interest from private investors, and thereby gradually improve liquidity. This is all such basic stuff, I find it astonishing that I'm still having to implore the city, and companies, to take these basic, obvious steps, to make the most of their expensive stock market listing.
It's the lack of liquidity in this share which means I won't be increasing my position size, despite the reassuring update today. If there is a serious resurgence in covid in future, then I want to be able to sell most of my stuff easily, if needs be. At least having the option would be good. Hence I would rather have say 20 or 30 shares like Tekmar, and small position sizes, rather than buying lots, and being unable to sell. I've got enough of that type of position already! Also, I'm trying to broaden out into having some mid caps too, where the liquidity is marvellous of course. Being stuck in a load of totally illiquid micro caps can be horrible in a market crisis, as you're trapped & cannot get out often.
.
This section written by Jack Brumby:
Air Partner (LON:AIR)
- Share price: 48.75p (up 25.97% today, at 11:46)
- No. shares: 53.5m
- Market cap: £20.7m
Last time I looked at Air Partner (LON:AIR) , its shares were rangebound at around 100p. Today they are up some 25% up to c49p… Clearly I am a little out of the loop here.
As I understand it, Air Partner secures chartered airplanes for customers and provides other related services. I quite like the way this update starts:
This is the third update released during the COVID-19 pandemic and we anticipate communicating to shareholders approximately every four to six weeks during the crisis.
That’s a nice touch - clearly shareholders have been spooked by the lockdown, as you might imagine for an airplane broker and safety consultant.
Current trading
It turns out that the mass parking of airplane fleets is good news for chartered services. AIR says:
The Group has had a strong start to the financial year, with the unaudited accounts for February, March and April showing expected underlying profit before tax of £6m. April was a record month, predominantly driven by unusually high levels of activity in Freight and Group Charter. However, as expected, activity in Private Jets and Safety & Security remains notably lower than in previous years, although Redline has recently secured two new security contract wins.
Going into a little more detail, AIR says that Group Charter has been kept busy with COVID-related repatriation and evacuation work. The group is also flying agricultural workers into the UK from elsewhere in Europe - I didn’t realise this was happening - and there has been increased demand for “corporate shuttles” from UK and US customers that want to transport employees in a more controlled manner.
Freight has similarly been strong, with the group flying emergency shipments of protective personal equipment (PPE). Given all the chatter about PPE shortages and continued grounding of fleets, I could see this demand continuing in the short term.
The group’s Private Jets division continues to be weak, though, with people cutting out non-essential air travel. Safety and Security has also seen much reduced demand.
Cost management and cash
On this point, AIR comments:
At the end of April, the Group has normalised cash in the bank of £13m, excluding significant customer deposits and JetCard cash. The Group has access to a total debt facility of £14.5m, comprising of a £1.5m overdraft and a £13m revolving credit facility (RCF), which is drawn down by £11.5m as at 1 May 2020. The RCF is due to expire in February 2023.
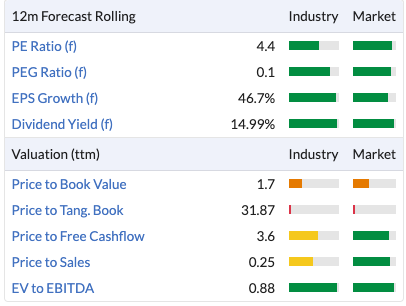
This seems to me on the face of it a strong position for a £20m market cap company, but I admit I am not up to speed with just how AIR operates. Other air travel companies have very high operating costs as a result of maintaining their fleets. If AIR has a more capital-light, outsourced business model then it might be better placed than most to survive and even, as we see, take advantage of heightened demand during lockdown.
I can see from the group’s balance sheet that it is quite asset-light, suggesting it does not actually own aircraft.
My view (Jack)
This is certainly worth a closer look.
In all honesty, I need to read up more on just how Air Partner operates and then I can take a better view on how well placed it is to continue operating. Most airplane operators are finding life incredibly difficult right now.
AIR’s share price has been hammered - is this an efficient market reaction or the baby being thrown out with the bathwater? It is possible that investors just ditched anything remotely to do with flying, regardless of business model. If so then there could be an opportunity here. AIR looks to have a more asset-light, flexible business model than other operators. I imagine a few people in the comments are more familiar with it than I am.
Either way, it certainly looks as though Air Partner’s services (unlike so many Passenger Transportation Service companies) are in high demand right now. The forward order book is encouraging for May and June with demand for Freight and Group Charter services remaining high.
Beyond that, visibility is limited for the group. But visibility is limited for everyone, I suppose. I can’t offer a more detailed view right now but I have tagged this one for further research. I might find something that turns me off - at this kind of valuation, there is usually something - but the group’s shares are also pricing in quite a lot of bad news.
If you subtract group cash, the company has a tiny EV of about £7m compared to FY19 revenue of nearly £78m… Air Partner is clearly seeing heightened demand for some of its services and yet this group is priced more cheaply than a lot of airlines with totally suspended operations. Perhaps it is actually negatively correlated to airlines in that the longer fleets are parked, the more demand there will be for AIR? If so, that is an opportunity given that its share price has so far been positively correlated with airlines.
I like the fact that the company is committing to regular communication throughout the lockdown, too. Worth further research to understand just how its operations stand to gain (or suffer) from current conditions.
Thanks Jack, back me (Paul from here onwards)
.
Getbusy (LON:GETB)
Share price: 68.5p (up 12% today)
No. shares: 48.9m
Market cap: £33.5m
GetBusy plc (AIM: GETB), a leading developer of document management and productivity software products, provides an update on trading in advance of this morning's AGM.
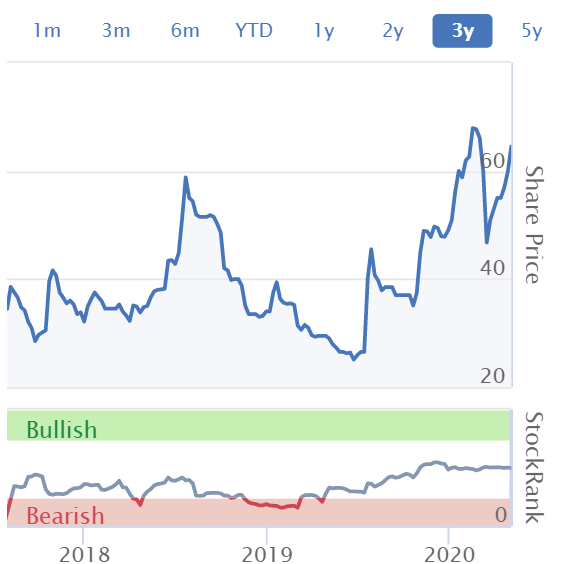
Preamble - a friend implored me to look at this earlier this year, which I did here on 3 Mar 2020. Re-reading my notes, my conclusion was positive, thinking that this share looks potentially interesting. Although I wasn't madly keen on the weak balance sheet (even after the recent placing), and did wonder if the company was perhaps trying to do too many things (3 products), on a tight budget? It has strong recurring revenues, and the 2 loss-making divisions could be shut down if they don't make progress, leaving behind a decently profitable core business. That's an attractive set up.
Overall, I like the investment case for GETB, and it's been on my watchlist since. It's topical too, with the trend towards working from home, and that we're in a tech boom in shares again, which feels quite similar to 1998-2000. Hence even small tech stocks can be multi-baggers in the current environment, with valuation being largely ignored. For now anyway, before the inevitable meltdown happens. That said, GETB's valuation looks reasonable at the moment.
Trading update today - this relates to FY 12/2020 to date.
This sounds reassuring;
The new financial year has started well, with double digit revenue growth and a small Adjusted Profit* being generated in the first four months of the year (the "Period").
On a constant currency basis, recurring revenue and total revenue grew by 20% and 15% respectively in the Period. Recurring revenue represented 90% of the Group's total revenue in the Period.
Note that this includes April, which is when the big impact of covid really hit. Therefore to grow revenue 15% in that 4 month period is quite good. Profitability isn't a big issue at this growth stage. As long as it's not haemorrhaging cash, then I'm fine with small growth companies not yet reporting profits. Particularly where there's a lot of potential operational gearing, as there is here.
More detail is given in the RNS.
Covid-19 impact - a bit mixed, here are the main points;
- GETB staff working from home is going well
- Accountants & bookkeepers make up 60% of revenues, so performance depends on health of their clients
- Increased risk of customer churn & reduced number of licenses
- Some clients stretching payment terms & switching from annual to monthly terms (bad for GETB's cashflow, as this would reduce deferred income & cash balances)
- Risk is spread - no customer is over 1% of recurring revenues
- Trade shows cancelled, so some marketing spend diverted to online lead generation
- GETB has stress-tested its cashflows in various scenarios, and believes it is OK to withstand crisis
Outlook - should benefit from long-term trend towards working from home
Reiterates 2020 guidance - very good, how many companies are able to do this?! Although the forecast figures are not particularly great;
We remain confident that revenue and Adjusted Loss* for 2020 will be in line with market expectations of £13.8m and £(0.6)m respectively.
* Adjusted Profit / (Loss) before Tax is Profit / Loss before share option costs, net capitalised development costs, finance costs that are not related to leases, and non-underlying items.
My opinion - clearly the recession which is hitting us now, is bound to do some damage to GETB, but also creates new opportunities. I remain of the view that this company looks interesting, and I can see why bulls like it. Having previously checked out the figures, I can't see any particular bearish points. A slightly stronger balance sheet would be nice, but not essential given recurring revenues.
I don't see anything in today's update to make me want to rush out and buy this share. It's reassuring rather than strongly bullish, in my view. Overall though, I think GetBusy looks interesting, and readers might want to take a closer look, if you're interested in small growth companies.
.
Johnson Service (LON:JSG)
Share price: 116.5p (down 2% today)
No. shares: 369.8m
Market cap: £430.8m
AGM Statement & Covid-19 Update
Johnson Service Group PLC (the "Company" or the "Group"), a leading UK textile services provider, provides an update on its strong financial and liquidity position and the actions taken in response to COVID-19 since its previous announcement on 20 March 2020.
This used to be a dry cleaning business, but it sold off that part, in order to concentrate on textile hire - e.g. uniforms, and linen/towels, etc for hotels, restaurants, etc. Therefore this must be an awful sector to be in now, and for some time to come. Bear in mind that it got into trouble in the 2008 due to having too much debt, and it looks as if history might be about to repeat, possibly?
The Group is continuing to see a significant amount of disruption across its markets, prompting the Board to implement appropriate mitigating actions...
Workwear business - holding up relatively well. The April figure is key, as that's after lockdown began, so minus 12% strikes me as surprisingly modest fall in revenues. I'm guessing that "trading" means revenues & not profits, in this context;
Organic growth within our Workwear business for the first quarter overall was slightly negative and trading in April was some 12% down.
Hospitality sector - a very different picture here, with the business at close to zero revenues current run rate, not a surprise;
Within HORECA, which serves the Hotel, Restaurant and Catering markets, we have ceased processing at the vast majority of our 18 sites as the demand for linen has significantly reduced from most sections of the hospitality market. Organic growth for the first two months of the year was particularly strong at 9%, however, March saw volumes reduce resulting in a negative organic growth in the month of 27%. In April, revenue fell by some 97% on an organic basis due to the closure of the vast majority of our hospitality customers.
- Furloughed a significant propertion of workers
- Senior staff & Board taken 20% pay cut for 3 months, admin staff taken 10% pay cut
- Capex halted, and discretionary spending
Net debt - not excessive when EBITDA was good, but in current circumstances EBITDA could be running at a loss, I imagine?
Net debt, excluding IFRS 16, at the end of March 2020 was in line with December 2019 at £87.7 million, resulting in a net debt to adjusted EBITDA leverage ratio, calculated in accordance with our bank facilities, of 1.3:1
Govt aid - it is using furlough scheme, and has deferred VAT & payroll taxes
Bank discussions - June 2020 covenant test waived, even though JSG says it should pass.
JSG wants 2021 covenants relaxed, and to draw down £40m accordion facility. Sounds like these have not yet been agreed by the bank.
It is also exploring other options of Govt funding, ie. loan schemes.
Divis being suspended, as you would expect.
The above makes me uneasy, as it sounds as if the bank has not agreed (yet) to the company's requests. This raises the likelihood of the bank possibly requiring JSG to raise some fresh equity before agreeing extended facilities & relaxed 2021 covenants. Or, the Govt schemes could provide the necessary additional liquidity.
No guidance is being given, due to uncertainty.
My opinion - probably the only thing worse than being a restaurant or hotel right now, is being a supplier to restaurants & hotels.
I've been flagging, for years, that JSG has a weak balance sheet, with too much debt. That doesn't matter in the good times, but becomes a problem when recession looms.
Banks are being very supportive in the main, so maybe the risk is not that great? It's just a risk that I would prefer not to take. If JSG would be a multi-bagger on emerging from this crisis, then it might have some appeal. But it strikes me the upside is not particularly exciting (maybe a 50% gain?) for taking quite a large risk. Hence I see risk:reward here as being unfavourable.
All done for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Jack, a useful contribution, but surely "aeroplanes" instead of "airplanes"?
Hiscox (LON:HSX) - I think that's only relating to the UK property policies where holders claim there is cover but Hiscox claims there is not. There is additional cost of US$150M to US$175M in respect of event, media, entertainment and travel policies which they say they are in the process of paying.
Hiscox (LON:HSX) have put out an after market announcement covering their possible virus commitments to clients. They also comment on their investment performance. Other insurers should do the same. Having said that, they reckon " the impact of a 12-week lockdown...[will result in an estimated cost of]... between £10 million and £250 million net of reinsurance", so hardly precise.
https://www.investegate.co.uk/hiscox-ltd--hsx-/rns/hiscox-ltd-trading-statement/202005051635010164M/
https://www.bbc.co.uk/news/bus...
Tim Moore, economics director at IHS Markit, said the data "highlights that the downturn in the UK economy during the second quarter of 2020 will be far deeper and more widespread than anything seen in living memory".
"The April survey reading is consistent with the economy falling at a quarterly rate of approximately 7%, but we expect the actual decline in GDP could be even greater, in part because the PMI excludes the vast majority of the self-employed and the retail sector."
The Purchasing Managers' Index (PMI) services index showed a record-low reading of just 13.4 in April, down from 34.5 in March. A figure below 50 indicates contraction. The final reading was slightly better than a preliminary - or "flash" - estimate of 12.3 that had been produced late last month.
my bad - I think it is Graham N who has the long position in DUKE not you Paul
Graham previously stated he had sold up his Duke Royalty (LON:DUKE) as it was a "riskier" investment. He has been proved right so far, as it has dropped more than 30% since he wrote that. They have a fair chunk of dosh out to a river cruise company, so that may need some patience.
Yeah, that kind of squares with the updates before. The recent trading has been great for their balances.
Just saying that Stocko says net cash of £13.5m for trailing 12 months, which may look exciting relatively to the mraket cap, I do not view it in the same way. Jet Card cash was c.£17m at the last year report.
Hi Paul what are your thoughts on DUKE Royalty #duke? The last time you mentioned them you had a long position - price has dropped significantly due to CV19 and dividend is very large BUT at risk. I used to hold this company - think it is quality BUT several of its largest royalty partners are badly impacted by CV19 )such as the largest partner which is a small cruise line).
I have added a few today at 18.6p as a punt but you understand their portfolio very well.....
Something extraordinary:
Total of 871 retail car purchases in UK last month of which three quarters were Teslas. I'm not sure which of those figures is the more staggering.
timarr
Interesting Data Timarr, according to autocar today..
"The model's relatively high sales can be attributed to the completion of online pre-orders made on Tesla's website before the lockdown. A number of sales are also likely to be to company fleets - which the SMMT says accounted for 70% of all sales in April. Recent changes introduced to the UK vehicle excise duty system saw EVs become exempt from benefit-in-kind tax, thus enhancing their appeal for fleet buyers."
https://www.autocar.co.uk/car-...
Such small numbers just shows how individual criteria can distort the picture. Essentially a massive collapse almost 100% without these wrinkles! Extraordinary as you say
Cash buyer for a Tesla anyone?
timarr - Those numbers on the right definitely don't add up to 871. Also, do you mean 3/4 were electric rather than tesla?
Agree though, interesting numbers. Could it be due to longer direct-from-manufacturer sales model?
Those numbers on the right definitely don't add up to 871. Also, do you mean 3/4 were electric rather than tesla?
The table includes non-retail sales, but I don't think the specific numbers are the key point really ... 97% fall in new car registrations.
timarr
There were 4321 sales in April - the 871 were private sales. The list posted above refers to 'Best Sellers' out of the 4321...............
I guess (maybe) that Tesla really only sell direct and their potential customers are prepared to buy on that basis whereas all the others mainly/only sell via dealerships, which are all closed for visitors. So Tesla sales much less impacted by current situation. Or maybe not.
Anecdote on Chris Harris' Collecting Cars podcast a few weeks ago. Tesla had to deliver c. 100 vehicles to somewhere like Holland before some looming tight regulatory (tax?) deadline. So they simply docked the container ship, unloaded the cars onto the quayside in two neat long rows (black and white), put the associated keys into two buckets on a table and invited the assembled punters to play lucky dip for a key and drive away their new pride and joy! Shows what can be achieved when you're not saddled with a sprawling dealer network and associated overheads.
TESLA- According to SharePad, Baillie Gifford has recently sold 6.15% of Tesla, leaving their funds with a holding of 1.56%. I have drawn no conclusions from this. I found this interesting, so I am sharing it.
What ? That a Peugeot got into the list TWICE ! Now that is staggering
Any views here on SYME?
A strange announcement from Lidco (LON:LID) this morning; effectively an RNS-NON with a very positive trading statement tacked on to the end.
https://www.investegate.co.uk/...
Boosted by COVID-19 driven demand for its Hemodynamic monitors, revenue for 2020 Q1 (3 months) was £4.4m, compared against £3.5m for the whole of 2019 H1 (6 months). Given each monitor sale gives rise to future recurring revenues, this increase in the installed base may well be sufficient to get LiDCO to a position of sustained profitability for the first time and certainly provides a solid foundation for improving future returns to shareholders through operational gearing.
The CEO and CFO presentation to ShareSoc this morning (now closed to registrations) is certainly very timely ....
https://www.sharesoc.org/events/sharesoc-webinar-with-lidco-lid-5-may-2020/
Re Air Partner (LON:AIR), a very reassuring statement, apart from the mystifying comment about their private jet division, where they say activity is "noticeably lower". My friends and colleagues with involvement in the bizjet sector, say it has been busier in the last quarter than it has been for a very long time. I'm waiting for some decent clarification from the company, but I can't help but feel they are being a tad cautious about this. (Unless they are losing market share, which I doubt). I hold.
Mighty relieved I must say at the news. but as you say slightly mystified by lack of clarity. I thought they said they were picking up quite a decent bit of business in the private jet sector. So having thought it was going to fall back again I bottled it and managed to come out with a bit of surprise profit. Never regret a profit but good luck if sticking with it. Lord Lee's top holding I believe.
Treatt (LON:TET) is Lord Lee's #1 holding, despite a newspaper recently saying otherwise. Yes, he also holds Air Partner (LON:AIR) and has expressed some confidence in its survival chances, if I remember correctly.
Could someone make the bear case for Air Partner (LON:AIR) ? Market Cap around £24 million, £3 million a year normalised earnings with low capital intensity and a net cash position. Due to Covid 19 disruption..they have earned £6 million in PTP in the last few months. Broking emergency charters and unusual freight orders like PPE has led to what must be their most favourable trading conditions ever . When travel does resume there will surely be greater demand than ever from corporations and HNW individuals to travel in private jets. If the company can maintain anything like this recent performance for the next year , the valuation will seem laughably low. If business as normal resumes, this still seems like a very modest valuation for a company that will surely have built up a considerable net cash position. I'm aware that there were issues with dodgy accounting in the past but wondering what else makes up the downside case ?
Air Partner (LON:AIR) bear case could include:
- recent accounting scandal raising concern about management and controls;
- series of recent acquisitions seem not to have worked out very well;
- sudden emergence of a lot of airline spare capacity;
- climate change and jets.
But also seems priced in and then some.
Only thing I can think of is that a lot of Q1 + April business seems to be freight. Will passenger airlines that own their own planes vs. lease them try to restructure to offer more freight offerings?
Even reading the details of their accounting 'scandal' the auditors found no sign of enrichment- it seems like somebody screwed up and rather than come clean created a mountain of accounting shenanigans.
Air Partner (LON:AIR) - I agree.
I hold this.
It seems unlikely that this performance will be repeated - we can surmise that the Government paid through the nose for those rescue flights.
It seems unthinkable that in a few months airlines will still be running at a single digit level of capacity, so I would treat this as a one-off bonus thanks to the virus.
I was not particularly excited about their recent acquisition and considered they over-paid for it. I think it'll be difficult to build in big margins here, and perhaps they could have been patient - now might have been a good time to rescue a company in distress.
The cash balance is illusory IMO, much of it is in Jet Card Cash which is not available to the business.
There is some upside from here I feel - I feel 70p-80p is fair now (I did have a bigger target on it when I bought, but I think there is greater uncertainty facing the whole industry now).
"The cash balance is illusory IMO, much of it is in Jet Card Cash which is not available to the business".
The Air Partner (LON:AIR) announcement today does say "At the end of April, the Group has normalised cash in the bank of £13m, excluding significant customer deposits and JetCard cash."
And £11.5 million drawn on a RCF, so a small net cash position I believe
Certainly this is a one off bonus but one that represents a very significant chunk of the market capitalisation earned in just a few months. One other surprising element is that profits seem to be accelerating substantially as the crisis continues. Pre tax profit for February and March was £2.4 million and for February March and April combined it was £6 million . With the company already declaring May and June to have encouraging order books the one off bonus may get considerably larger.
Air Partner (LON:AIR) I have a long position but another aspect of the bear case is that the balance sheet is not as strong as it seems since most of the cash was recently spent on the recent Redline acquisition
On a similar theme, anyone have any views on Signature Aviation (LON:SIG) (formerly BBA Aviation)? On the basis the wealthy will be flying first they should be well positioned and have less skeletons in the cupboard than Air Partner. They also look very good value by historical standards.
The PLC companies Vin Murray has been involved with have had a very good record
I think that the one change that has happened over the last few weeks is trying to change part of my brain from that of looking at "investing" with a 2+ year horizon of holdings, not quite a buy and forget, but find something good and hold unless something fundamental changes, or a better holding is identified. To starting to learn about trading and trying to think about how to use the market volatility to slowly recover some of the losses, only using part of my portfolio, to rebuild my capital base - and trying not to buy high and sell low...again!
Any recommendations on good books to read, or webinars etcetera?
Interesting. I have had a similar feeling that I should be more active than I have been in the past. I am sure it is a keenness to recoup some of my loses as soon as possible. However I am trying to resist the urge. I have never been a trader, always a longer term investor, and don't think I should change now. But it is interesting to hear someone else affected in the same way
I think you need different approaches in different market conditions. This epidemic has provided classic opportunism. There are two ways to go, buy a diversified range of investment trusts and leave it to them, or be active but get to know your stock as well as you can. Only golden rule I try and adhere to is 'do not trade out of boredom.' Sounds obvious, but trading is all about timing and spotting anomalies. One other obvious rule which is a much harder 'always leave yourself room to trade. Its very easy to get fully invested so I don't leave surplus cash in my trading accounts. Having said that I am fully invested in my ISA account. It took me 4 months to trade it back to profitability. If I hadn't cut the rot it would be half its current value. Its really not easy. Read all you can find, most of what you need is right here on this site, but nothing counts for experience. I love some of the sayings on stockopedia when you log in like 'if investing was comfortable you wouldn't make any money.' There is certainly truth in that. Everything Ed Croft has said in his videos about Brokers, newspaper tips, bill board posters and company presentations is exactly what I have experienced myself. There is a wealth of good research and experience from these guys to guide you, but you have to make the choices. Certainly the recent volatility has dissipated for now. So I am looking for high value momentum scores. There are ones like Ocado that slip through the net on score but can't argue with value. I don't concur with the Armageddon rhetoric of the IMF, yes there is some scary debt but we have moved on a long way with science, technology and communication since the thirties and of course population, needy customers!
Air Partner (LON:AIR) update: Underlying profit before tax: 3 months to April £6m. April a record month.
Market Value (last night): £21m
Normalised Cash: £13m
Enterprise Value: £7m
Market seems confused as to what Air Partner actually does - it's not an airline, it doesn't own planes.
Air Partner (LON:AIR) up around 20% at the moment. The underlying profit before tax: 3 months to April of £6m compares to £3m in the whole of H1 last year.
Market seems less confused this morning. Price up 23% as of 8:28 am
Management aim to communicate with shareholders every 4-6 weeks. Interesting company.
No confusion on my part - happy shareholder. Yip - agree - the valuation does not compute (certainly not helped by an institution dumping their stock at the bottom).
My morning smallcap tweet:
Tekmar (LON:TGP) Itaconix (LON:ITX) Entertainment Ai (LON:EAI) 1pm (LON:OPM) Mincon (LON:MCON) GetBusy (LON:GETB) SEC Newgate SpA (LON:SECG) 600 (LON:SIXH) Lidco (LON:LID) Argo Blockchain (LON:ARB) Cambridge Cognition Holdings (LON:COG) Batm Advanced Communications (LON:BVC) Mears (LON:MER), GetBusy (LON:GETB)
Tekmar (TGP) gudes FY(March) rev up 40% in line despite lockdown. Order book up 39%.
Itaconix (ITX) cash runway now until August. Cash at hand $0.3m. Has received $10k (sic) covid grant so far from US Gov't. First 4 months rev $0.6m, up 42%.
Entertainment AI (EAI) guides Q1 adj pretax in line. "Whilst the Group's Multi-Channel Network showed strong growth in audience views and watch minutes, because of the impact of Covid-19 and the market-wide reduction in digital video advertising spend, the Company does not expect this growth to translate into a similar increase in revenue...we believe that demand for our technology products will be acute given the pullback in digital ad spend and increased reliance on online sales."
1PM (OPM) approved for accreditation as a lending partner in Gov't covid scheme. One third of staff furloughed. Worst hit sectors are vehicles and property loans brokerage. Has agreed some payment deferrals. 25% of clients have requested such.
Mincon (MCON) Q1 rev up 4%. ross margin up to 35.2% from 33.6% reflecting a higher proportion of Mincon manufactured product. South Africa restrictions have started to ease. Order book remains generally steady. No problems with trade receivables.
GetBusy (GETB) trading: recurring rev up 20%, total rev up 15%. Some clear stretching of payment terms by customers in the UK. Conversion of new customer leads at Virtual cabinet has slowed considerably. Co confident that the Group's balance sheet is sufficiently resilient to withstand covid. "In the medium to longer term, therefore, we expect this situation to be a catalyst for significant growth in the market."
SEC Newgate (SECG) all businesses performing in line with or ahead of budget and management expectations. "Group has committed banking facilities available with maintainable covenants."
600 Group (SIXH) trading still tough and ongoing restrictions continue to create supply challenges, particularly in the general engineering sectors. Guides FY(March) broadly in line with previously revised expectations. Debt flat YoY and co is covenant compliant with adequate banking facilities.
LiDCO Group (LID) Q1(April) rev £4.4m up 179%.
Argo Blockchain (ARB) CFO steps down to NED.
Cambridge Cognition (COG) strong start to 2020 with £2.61m of orders booked in Q1.
BATM Advanced Communications (BVC) has launched ELISA Serological test to test if someone has had covid. Tests 3 antibodies, co believes this enables the detection of antibodies at an earlier stage than with many competing tests.
Mears (MER) guides operating losses during the full lockdown period, where an emergency only service is being provided, will be modest, and a small positive free cash flow should be generated. Co thinks it has sufficient liquidity but is agreeing extra £22.6m loan.
In line: GetBusy (LON:GETB)
Interesting move at M&c Saatchi (LON:SAA) :
https://www.investegate.co.uk/m-c-saatchi-plc/rns/holding-s--in-company/202005050710419387L/
I didn't know who she was either:
https://en.wikipedia.org/wiki/Vin_Murria
Thanks for highlighting that, I do know who she is. She's an extremely smart lady who I've done well following before. If she's in I'm buying. Just need to work out how much.