Small Cap Value Report (Tue 5 Oct 2021) - new cars, GHH, SCS, WIN

Good morning, it's Paul & Jack here, with the SCVR for Tuesday.
Free! Mello online event tonight at 5pm, trusts & funds. More details here.
Agenda -
Paul's section:
The BBC reports on SMMT data showing a big drop in new car sales.
Scs (LON:SCS) (I hold) - I'm spending most of this morning working through the numbers & narrative. So please bear with me, hope to have a big section up on this by lunchtime.
Wincanton (LON:WIN) - an in line with expectations year end trading update reassures, and has put +8% on the share price today. We do need to adjust for the large pension scheme cash outflows, which will limit divis until 2027. However, even allowing for that, the valuation looks quite attractive to me. Could be worth a closer look, in my view.
Jack's section:
Gooch & Housego (LON:GHH) - Profit slightly ahead of mgmt expectations. Looks like a good company that emerges from lockdowns with a reduced cost base and an improved outlook. Acquisition opportunities going forward, and work continues in collaboration with customers on new product development. The valuation prices a lot in for now though, I'd want a lower price.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
New car registrations
The BBC reports (using SMMT data) that UK new car registrations have fallen to the lowest level for two decades, due to widely reported problems that automotive manufacturers are having in sourcing essential supplies (particularly semiconductors).
Even though the total is low for September at 214k cars, it’s striking that 15% of those were electric. Maybe the recent ludicrous panic buying of fuel might trigger further increases in the sale of electric vehicles. Until of course the next logical step being electricity shortages & blackouts, because nobody thought to build enough power stations to cope with electrification of vehicles. That we have to look forward to in future, but it has a certain inevitability about it.
Sales of secondhand cars continue to boom.
I noticed that Vertu Motors (LON:VTU) (I hold) has been drifting down of late. Checking a few other competitors shares, they’ve also been dropping, e.g. Marshall Motor Holdings (LON:MMH) is down about 20% from its recent peak. This could be due to the sharp reduction in sales of new cars, possibly?
The interesting thing is that shortages of cars actually boosts profits at car dealers, because they can raise prices. The CEO of VTU pointed out this fact in the excellent recent webinar from PIWorld, available here.
Therefore I’m wondering if it might be time for me to top up my car dealer positions? On the basis that shortages of new cars mean higher margins, and a stimulus to secondhand sales. Although the unprecedented rise in used car prices can’t last forever. Also bear in mind that this year, they won’t benefit from business rates relief and CJRS (furlough) support. So it will be interesting to see how things pan out.
.
Scs (LON:SCS) (I hold)
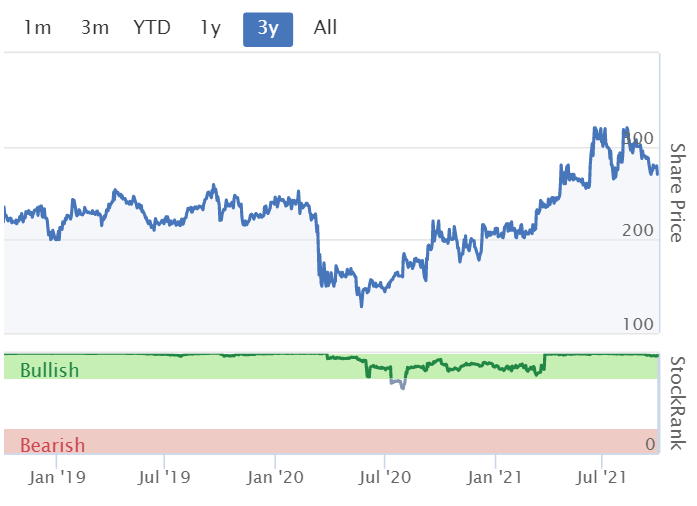
272p (y’day’s close) - mkt cap £103m
It’s taken me ages to go through these numbers from SCS with a fine toothcomb, but as it’s a big holding for me, and many readers, the time is well spent. Also, with the headline numbers strong (a considerable beat against forecast underlying EPS), and the outlook statement in line, I’ve been scratching my head as to why the share price has fallen 6% today, when I think it should have risen!
We need to bear in mind the backdrop though, with some small cap trader/investors in a general panic at the moment (belatedly) over supply chain problems, probably stop losses kicking in, etc. It seems ridiculous to me (given that supply chain problems are temporary & widely known about for months), but with many small caps, the low liquidity means that it only takes a few people to sell at the same time, and the price is marked down heavily. Then other people start panicking & sell to protect their profits, etc.
Conversely, with so much uncertainty out there re inflation/supply chains, I think we might be seeing something of a buyers strike too. I’ve not heard from anyone in my network of investors sitting on cash, who is deploying that cash yet. Why would they, when prices are coming down on a daily basis? There will be a buying stampede for beaten down small caps at some point, we just don’t know when, or which ones. I tend to buy too early, when we get sell-offs, so ignore me!
Anyway, let’s take a look at the numbers.
ScS, one of the UK's largest retailers of upholstered furniture and floorings, is pleased to announce its audited preliminary results for the 53 weeks ended 31 July 2021.
53 weeks impact on cashflow - I’m grateful to an an eagle-eyed friend (also a former retailing CFO) who messaged me first thing on this point. Most retailers internally account on a weekly basis. 52 weeks * 7 days is 364 days, one (or two in a leap year) days less than a 365 day year. Hence every c.5 years, they need to do a 53 week year to realign financial years. Usually though, the distortion is not material to profitability, but can cause significant balance sheet & cashflow distortions due to the timing of payroll and creditor payment runs. That’s what’s happened in this case.
Buried in the commentary (it should have been highlighted at the top), is this -
The cash generated from operating activities has decreased by £17.9m.
In the prior year working capital inflow totalled £27.9m largely due to a significant increase in customer deposits as our stores reopened following the first government lockdown. The level of customer deposits in the current year has increased by £2.4m.
However, this is offset by a working capital outflow as a result of the 53 week year capturing July month end payroll and supplier payments, together with a repayment of £3.4m VAT and PAYE/NI balances which were previously deferred in line with the government support offered as part of its response to COVID-19.
Supplier payments & payroll are typically the biggest cash outflows for retailers, with the other big one being property costs (rent + rates). Therefore, in this 53 week financial period, the cashflow and balance sheets will have been impacted by including 13 months supplier & payroll payments. The P&L won’t be impacted, because costs are apportioned to fit the period. It’s the cashflow & balance sheet effect which is significant.
I suspect that many investors have not spotted this - understandably, because it’s an important point which is not flagged in the highlights section. People don’t have time to plough through all the narrative, when we only have 7-8am to digest RNSs from multiple companies. So I wonder if this is a case of a few people selling, and asking questions later maybe? It doesn’t really matter to me anyway, as a long-term holder, but I just like trying to figure things out.
A deterioration in cashflow is always something that needs to be looked into carefully, as it can be a tell-tale warning sign of fanciful accounting. In this case, it’s perfectly straightforward - cashflows last year benefited from a number of one-off factors (e.g. inflow of customer deposits post lockdown, and stretching creditors (e.g. taxes). Whereas this year sees the unwinding of stretched creditors, and the impact of 13 monthly supplier/payroll runs in the period. That last factor will unwind next year, so cashflow will look better next year. This is all absolutely fine, and not a concern at all. Cash balances also remain enormous, and are nearly equivalent to the market cap of the company, even immediately after paying suppliers & staff for the month.
Hence anyone who thinks cash generation is poor, has got it wrong for the above reasons.
Revenues £310.6m, up 21.6% on last year. Last year was hit harder by the first lockdown, and this year had benefited from delivering products which were backed up in the extended order book at end of last year.
Order book at year end (31 July 2021) is also very large, at a similar level to last year, at £103.5m (inc.VAT), versus £104.7m a year earlier. In more normal conditions, pre-covid, the order book closed at £43m, so you can see the extent of pent-up, unfulfilled demand there, being about £60.6m (inc. VAT), so £50m in revenues terms (ex VAT) - about 13.5% of the new year’s revenue possibly, if supply chains do normalise by July 2022).
Therefore, SCS still has a substantial backlog of orders to work through, to benefit this new year FY 07/2022. This refutes the suggestion that FY -7/2021 was a one-off good year due to demand pulled forward.
Current trading & outlook - also good, with continued strong orders flowing in (I’m ignoring the -21% comp against LY, as that was an unusual spike (I’ve checked back), following re-opening from lockdown 1, so not comparable conditions at all) -

Supply chain comments - in my opinion, this is such a crucial issue at present, that companies need to give us a lot more information. Saying they’re mindful of disruption is nowhere near enough. I want to know how much it’s impacting things, do they have fixed price shipping contracts or paying inflated spot rates, how long the delays are, attitude of customers to delays, etc.
Flexible business model - furniture retail is a lovely sector, where almost everything is made to order, and many costs (e.g. staff commissions, and marketing) are variable, right down to zero, in extremis.
This shines through in SCS’s numbers. It coped astonishingly well with the whole pandemic period, had no need to dilute shareholders (unlike weakly financed larger competitor, Dfs Furniture (LON:DFS) ). Therefore, shareholders here can sleep very easily at night, even on a lumpy old mattress. Especially given the huge cash pile which has arisen from both balance sheet strength, and the negative working capital business model common to the sector.
Earnings - underlying diluted EPS came in way ahead of forecast, at 39.8p.
Stockopedia is showing broker consensus of 31.4p
In more normal market conditions, where people were not worrying about inflation/supply chain, then I think this share would have easily risen 10%+ on publication of such good numbers. Still, the way I see it, that’s just an investment profit deferred for shareholders, and an opportunity to buy more, in a seemingly irrational market, which is focused on short term macro problems. Although I suppose the bear argument is that short term problems could turn into a recession, something to ponder.
Dividends - 3p interim, and 7p final, giving 10p, a yield of about 4.0%.
Bear in mind the divis are highly likely to be increased back to historic levels (peak at 16.7p), which means anyone holding now is probably sitting on a future cash cow, which could be yielding 6-7% by this time next year, based on the current share price.
There’s also the future possibility of special divis or buybacks, with all that cash sitting there doing nothing.
Taxpayer support - now is not the time for big shareholder payouts, as SCS has benefited from taxpayer support measures (the last thing needed is a social media backlash, for example).
Business rates relief added a material £10m to profits, although profits were of course suppressed by the stores being closed for a long period in lockdown 3.
The CJRS (furlough) grant of £3.0m for FY 07/2021 has been repaid by the company - good stuff, that is the right thing to do.
Online sales - grew 146% to £46.9m, 15.1% of total revenues. Good growth, but note that DFS showed very much better growth, and total online sales. Plus of course newer competitor Made.com (LON:MADE) is mainly online, and young people in particular seem to like buying furniture online, which is surprising to people of my generation & older.
Although as SCS points out in the commentary today, it’s complicated, because a lot of people like to visit a showroom after having done their research online. Or maybe order online, after having pondered a purchase after viewing an item in store.
Bear in mind also, that I’ve seen some retailers call sales online, when ordered in store on a tablet! Which of course are not really online sales (thinking about Mothercare (LON:MTC) which used to do that when they had their own stores, pre-restructuring, which made them look desperate - which they were at the time, not now though).
New mission statement & growth plan - I’m fine with this. This section of the commentary just reads like basic common sense for running any business - e.g. focus on the customer journey, move more online, train & retain good staff properly, good product & showrooms, gain market share. Nothing at all earth-shattering there, which I like! The last thing I want is a new CEO coming in, wanting to make their mark with wacky & expensive changes in direction.
It’s easy to scoff at the basic points in today’s strategy update, but for me it’s perfect. Just sell decent sofas cheaply & profitably, then everyone is happy.
Exceptional items - is a credit this year, of £4.2m, hence the statutory profit being above adjusted profit - nice to see. This relates to reversal of some impairment charges last year, see note 4. I think we’ll see more of these reversals, because impairments (of leases & fixed assets) are not necessarily required, once problem sites recover.
EBITDA - my blood is boiling, looking at the total mess that IFRS 16 has made of these numbers. EBITDA looks stunning, at £48.5m (after exceptionals), but the number (required by IFRS 16) is pure fantasy. As the cashflow statement shows, “financing activities” includes £3.7m of interest on lease liabilities, and a huge £22.7m capital repayment of leases (I think this is inflated by about £6m due to catching up on deferred rents?). Paying rents is just part of the operating costs of the business. The result is that IFRS16 produces a massively inflated EBITDA number that is highly misleading. Blame the accounting standards people, not SCS (who are just following the rules).
Balance sheet - is lovely as ever, stuffed full of cash, an astonishing £87.7m, which is stated immediately after paying the monthly payroll & supplier payment run. I need to do some more work on this, but I reckon the figure would be nearer £100m once that one-off cashflow issue is taken into account. That’s the entire market cap of the company!
It benefits substantially from customer deposits (which would reduce somewhat as delivery times normalise in the long run), and the negative working capital cycle - which is permanent, and revolving, so we don’t need to net off creditors.
I remain of the view that it’s probably only a matter of time before private equity spot the anomalously low valuation & massive cash pile. Although SCS could be too small for many PE firms maybe?
Going concern - I do like these sections, when they include stress testing.
As I would expect, SCS sails through, even a severe but plausible scenario, with heaps of surplus cash still (which involves another short lockdown at peak trading period).
Also, I like the comments about trade credit insurance, saying that SCS could cope easily if all credit insurance was withdrawn. Trade creditors are only £15.4m (see note 9) so could all be paid off fully and only dent the £87.7m cash pile.
If I ran SCS, I would do deals with suppliers to pay them cash on delivery, in return for a say 1-3% discount. Might as well do something useful with the cash, and that would also mean that SCS would move up the pecking order in terms of what work the factories prioritise - the cash buyer gets their stuff made & shipped first, in my experience.
Valuation - I’m working on 30-40p EPS in future (remember it did c.40p for FY 07/2021). I’m basing that on a further recovery in sales from the order backlog, and stores (hopefully) being open 52 weeks per year in future. Offset by withdrawal of business rates relief, and allowing for additional costs from freight, etc.
At the current share price of 260p, that gives a PER of between 6.5 and 8.7 - cheap, with maybe 50% upside on a re-rating?
In addition, we have the entire market cap in cash! So we’re really getting the business for free.
Some people argue with that, who I would direct to study the balance sheet of Dfs Furniture (LON:DFS) and compare it with SCS. This demonstrates that it’s entirely possible to remove the entire cash pile, increase the debt facilities, and the business could continue to function as normal.
I’m not advocating that, just saying that it’s entirely possible.
Sooner or later a financial engineer is going to spot that, and make something happen.
My opinion - I continue to believe, based on these numbers, that this is probably the cheapest value share on the UK market, certainly in the sectors I look at anyway. There could be some obscure resources stock that looks cheaper, but is much riskier & more cyclical probably. A combination of low PER, and a massive cash pile, and high dividend paying capacity, is extremely unusual. I can’t think of anything that’s even remotely close to this.
But, the market absolutely hates SCS. Investors are just not interested. That happens sometimes, which is where patience is a virtue that should eventually pay off in the long run.
In the short term, there’s a risk that shipping problems could get worse, and trigger a profit warning. But as we saw with the pandemic, for furniture retailers, that just defers profit into a future period, so it doesn’t matter to long-term holders.
As you can probably guess, I think this looks an excellent value share, and the share price doesn’t make any sense at all to me.
Bear views - I’d be interested in hearing contrarian, negative views, as I may have missed something. These are things I’ve spotted other investors saying -
- Supply chain worries, as discussed above,
- Tougher competition from online, e.g. Made.com (LON:MADE) (probably a different customer though)
- Pandemic may have pulled forward future demand, e.g. WFH, home improvements popular
- Poor cashflow (discussed above, this is a red herring)
- Dashed hopes for special divis/buybacks (be patient!)
- Short term punters getting bored & moving on
- Resumption of lockdowns (not a problem, as SCS has shown it recoups sales later & has long order book to work through uninterrupted
- Something else could go wrong unexpectedly (true of all shares)
None of those points worry me at all, and as a long-term investor mostly, the prospect of doing nothing for the next few years other than collect in bumper divis, hopefully gain from a re-rating, and possibly receive a takeover bid, seems very attractive risk:reward in my opinion. Obviously, as always, DYOR, as you may come to a different conclusion.
.
.
Wincanton (LON:WIN)
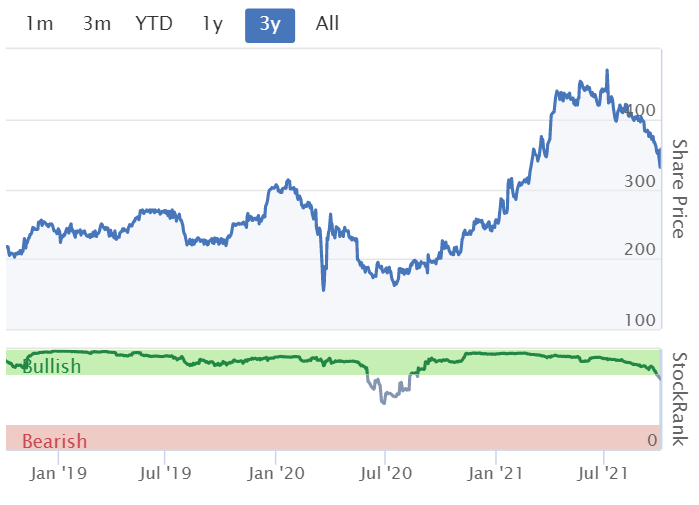
357p (up 8% at 12:18) - mkt cap £445m
Widespread daily news about the severe lorry driver shortage (caused by a variety of multi-year reasons) must have spooked some WIN investors, since it’s a logistics company. Hence the price drifting down. Today’s update has given it a decent 8% boost but we’re still almost 20% below the 440p price where Jack reviewed it here in early July.
We like Wincanton’s business, here at the SCVR, but we don’t like its poor balance sheet, and in particular the large scheduled cash outflows into the pension scheme, which total about £137m between now and 2027. We can’t just ignore that. These are major cash outflows, and will increase above that with inflation too (now elevated). That’s about 31% of the market cap, very much a material issue.
Trading Update - issued today.
Wincanton plc, a leading supply chain partner for UK business, today issues the following trading update ahead of its half year results for the six months ended 30 September 2021.
My summary -
Strong revenue growth throughout H1
All 4 sectors doing well, especially retailers
Acquisition (£23.9m) in Sept 2021 going as planned so far
Pipeline of new & extended business “remains encouraging”
Lorry driver shortages - this is interesting -
Wincanton continues to work closely with its customers in taking active steps to address the impact of the shortage of HGV drivers in the UK and to both attract and retain drivers. Closed book transport contracts, particularly in construction and FMCG, have been the most impacted parts of the business, however the Group has made good progress in agreeing rate changes to optimise service levels. A significant majority of Wincanton's contractual arrangements provide mitigation against cost pressures. The recent fuel shortages have not impacted Group profitability.
I saw a press article recently, saying that Wincanton is training up loads of new drivers - good stuff, but obviously that costs money, whereas in the past, cheap labour could be more easily imported, boosting company profits but suppressing overall wage rises, due to simple supply & demand - a point that is clearly being proven by current events. Apparently many drivers have left the sector, due to taxation changes, and unhappiness with ropey working conditions (sleeping in cabs in laybys, etc). Pay them properly, and the shortage will disappear over time.
Guidance - sounds fine - although I wonder if it might have out-performed, had it not been for the current problems with drivers, etc?
The Group remains on track to deliver full year profits in line with market expectations, reflecting the combination of strong retail volumes and the rate changes in closed book contracts. The Board remains confident in the future growth opportunities.
My opinion - I think Wincanton is clearly a good business, that has performed well in recent years.
Investors obviously need to factor in the pension scheme cash outflows, and stress test it, in case they get worse in future (or better, I have no idea, not my area of specialism). With inflation rising a lot, that could increase pension scheme liabilities, but rising interest rates (if that happens) could reduce liabilities. Lots of moving parts, so something for experts to consider.
Stockopedia shows a forward PER of 8.9. Even raising that (crudely) by 31% (see above) to take into account pension scheme outflows, I get to an adjusted PER of 11.7. Not sure if that’s a valid way to adjust for the pension scheme, but if it is, then WIN looks good value.
I wonder to what extent the lorry driver issue would impact the new year’s profits? Salaries seem to have gone up a lot, from c.£30k to £50-70k, although WIN seems to be passing on some of that to customers. Will this feed through to forklift drivers, and general warehouse staff I wonder? Staffing costs are likely to be a headwind anyway.
Overall, I think this looks interesting, and worth a closer look possibly by readers, if it floats your boat.
.
.
Jack's Section
Gooch & Housego (LON:GHH)
Share price: 1,265p (pre-open)
Shares in issue: 25,040,919
Market cap: £316.8m
Gooch & Housego manufactures photonic components & systems, working as a supply chain partner in aerospace & defence, industrial, life science and scientific research sectors.
Founded in 1948, it has transformed over the past 20 years from a craft-based company into a more technology-focused one after a spate of targeted acquisitions.
Key purchases include:
- Cleveland Crystals in 1999.
- SIFAM Fiber Optics in 2007.
- General Optics in 2008.
- EM4 and Crystal Technology in 2011.
- Spanoptic and Constelex in 2013.
- Alfalight and Kent Periscopes in 2016.
- StingRay Optics in 2017.
- ITL and Gould Fiber Optics in 2018.
All of the above businesses deal in optic instruments of one kind or another.
Alongside manufacturing sites in the US, the UK, and China are sales offices in France, Germany, Hong Kong, Japan and Singapore. Gooch has additional representation via a global network of distributors.
G&H's strong revenue performance in the second half of the financial year together with the benefits of our streamlining programme mean that Group profits are expected to be slightly ahead of management's previous expectations.
Trading in the second half has been good thanks to further strengthening in end market demand, despite currency headwinds and some supply chain constraints.
Industrial laser demand continues to be strong, in particular the semiconductor market where the group identifies a range of growth opportunities. Life science markets are performing well. Demand for medical diagnostics remains at previous high levels and orders for specialist medical laser products have been strong as this market recovers from the low levels of elective surgery during the pandemic.
Commercial aerospace volumes are not expected to recover until 2023.
Gooch has reduced its manufacturing facilities in the year from 12 down to nine, which should help reduce costs and improve profits.
Strong operating cashflow has allowed the group to further reduce its level of borrowings, although no figures are given in today’s update.
Outlook -
G&H has entered its new financial year with a ‘robust’ order book of £97.8m as at 30 September (2020: £92.4m), up 8.4% on a constant currency basis.
Industrial and medical lasers are demonstrating sustained recovery, while telecommunications and life sciences continue to perform well.
Active development portfolio targets key growth sectors and Gooch is working closely with its customers on their next generation products.
There remains substantial long term growth potential for our photonic technologies and system capabilities in all of our target sectors. G&H is well placed to execute on acquisitions that support our strategy.
Conclusion
There has been some 'drag' on performance due to currency headwinds, self isolation and supply chain issues. That aside, Gooch has weathered the storm well and emerges from lockdowns with a reduced cost base and lower debt, a robust order book, no equity dilution, and organic and acquisitive growth opportunities.
All in all, it strikes me as a good company that is well managed, a view probably reflected in the Quality Rank of 92.

But the valuation is rich, with a forecast PE ratio of some 30.4x. Forecast EPS will get nudged up but I imagine there's still quite a premium. It is growing, but I’m not sure that such a high multiple is warranted.

The balance sheet looks fine, with c£15m of cash set against nearly £20m of current liabilities and debt of nearly £22m. Note though that these figures are from the March balance sheet date and the company says the situation has improved further since then. The group has positive net tangible assets of around £60m (again, this has possibly improved - we’ll see in the full year results).
It’s reliably cash generative, too. There are a few signs here that indicate Gooch could be a good long term hold at the right price, but I don’t think today’s slight profit upgrade is enough to justify the high PER.
Putting the valuation to one side, I do like the company, so it’s one for the watchlist in case the market presents us with a more attractive entry point.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

107 comments
Hi
For those discussing the vehicle sales, EVs versus petrol/diesel and directions of trends.
Cathie Woods of ARK Investments offers a thoughtful view on these in her recent monthly update. This update covers US economy (e.g. inflation vs stagflation, vs deflation), monetary and fiscal policy, some relevant politics, the US market and some specifics.
ARK's views are often contrary to general market commentary as ARK focus on innovation and growth so IMO they offer thought provoking ideas which backed up by sound published research.
In brief her take on the US car market is that their current sales dips are a factor of heightened car purchases in the Covid period as people moved away from public transport by buying extra cars. Thus the US car inventories are now sitting in drive ways (not forecourts) hence sales dips. Plus, supply chain bottlenecks slowing new car productions.
She suggests the former factor is actually a more influential one than the latter (which will get resolved in time). As this is also a broader factor at play whereby in Covid people stuck at home bought goods, now consumers are switching over to services.
Further, she also points out that take up of EVs is definitely rising faster than traditional vehicles. Tesla showing strong numbers.
This vid is 39 mins for those who might like to listen.
Regards
Howard
Re Wincanton - driver wages, don't be mislead by the headline figures. Prior to the recent madness supermarket drivers and others, particularly those working for agencies could easily earn £50k+ however, these drivers are working the maximum, or near maximum, legal working hours which is 70 hours per week i.e. the equivalent of two weeks for an office worker. The legal maximum working time is three days at 15 hours and two at 13 hours, week in week out. Breaks are required but these can easily be 'demonstrated' as being taken but in reality a driver has probably worked nearly all of the 15 hours. It is possible, technically, to work 15 hours per day five days per week but this is on the condition that at least a three hour break is taken on the fourth and fifth days. This 'break' is easily achieved whilst still working e.g. when delivering to most Aldi and Lidl Distribution Centres the driver is also expected to unload his vehicle, this is a condition Aldi and Lidl impose on haulage firms delivering to them, place the pallets in the correct areas of the warehouse and to split the pallets where necessary. I know for a fact, allegedly, that a delivery to Aldi Goldthorpe (near Barnsley) can easily take 3.5 hours with a particularly complicated mixed load. The law requires the tacho to be set at 'Other Work' whilst doing this but many drivers, in order to get all their deliveries and collections done, put the tacho on 'rest' thus it appears that the driver has had 3.5 hours rest but in fact has not. So, when the media, who mostly are a bunch of $"%$£"$, shout about earning £70k that is possible but you need to do 70 hours per week and probably work for an agency where you are not necessarily certain of work every day. As for conditions, drivers get treated like dirt by some of the 'security' personnel at the supermarket distribution centres, I could cite examples but I don't have a good barrister on stand-by, and even some employers treat them like dirt, again, I could cite examples but won't. I know of one incident where a driver was threatened by the 'Goods In' person at one of the DC's for being late, he had, unbeknown to him, been given a delivery to do which had in fact been due the previous day. I could go on but you get the idea, and of course, the 'Great' British car/van driver ...... that is a whole other story.
Scs (LON:SCS) (no position)
I must admit to being somewhat confused by the cash generation here as there are so many moving parts.
Off the top of my head there was:
The company did not quantify how much more they will increase in the current year (nor if they will then stay elevated.)
("The payment of capital and interest elements of leases has increased by £6.4m, principally as a result of the benefit from rent deferrals negotiated with landlords in the prior year beginning to unwind. This will continue through the next financial year.")
The company claims that they generated £6.5m of net cash (excluding dividends).
Taking away the £7m benefit mentioned in 1. and 2 would surely result in cash generation actually being neutral or possibly even negative.
Looking at this slightly differently, if I strip out the negative Working Capital Movements in the Cash Flow Statement (ie adding back £8.4m) , and also remove the £7m benefit from 1. and 2. above, then cash generation was actually closer to £8m.
That would of course be very good for a £100m market cap company.
After writing that I've just recalled another benefit to cash flow - the £3.4m deferred VAT/NI payments.
So was underlying cash generation actually closer to £11.4m?
I feel quite confused by it all.
EDIT: I can see in the Notes the £3.4m repayment is already included in payables (+ an additional £3.2m has been paid, whatever this is) is already included in the change in Other Taxes (£12.8m - £6.2m = £6.6m) , so ignore the £11.4m comment above.)
For what it's worth, I do think the company does generate cash, but I personally would prefer more clarity.
----
On a separate but similar note, I would personally be wary of suppliers demanding quicker payments.
Traditionally SCS's suppliers are paid at the end of the month following delivery to the end customer, so possibly 60 days after a customer received their sofa.
So at a guess, a supplier might have been needed to wait 2-3 months between shipping off their goods and receiving payment from SCS.
Given the longer lead times. would a supplier be able to wait, for example, >6 months, which is probably the current situation?
If SCS is forced to pay suppliers before they have even received goods in the UK (and therefore before even the customer has fully paid SCS) there could be a serious drain on the company's cash resources.
All speculation of course, but I see no reason why the above could not happen.
Cheers
A
Hi abtan,
With respect, I think you've massively over-complicated the cashflow for Scs (LON:SCS) and got yourself into a bit of a muddle!
It mainly boils down to one thing only - last year there was a massive cash inflow caused by increased trade & other payables. This was mainly a large surge in customer deposits (DR cash, CR payables), plus stretching tax creditors. Hence the 26.7m cash inflow shown below.
This year, the customer deposits remained broadly similar, so no cashflow benefit from that, and stretched creditors were repaid back to more normal levels. Hence there was a £9.1m cash outflow relating to trade & other payables.
As you can see from these figures below, it was these factors which caused a big reduction in operating cashflow this year. It's nothing to be concerned about at all - last year the business was run to maximise cash (as were most businesses), whereas this year the figures have largely normalised. It's swings & roundabouts, and is not of any concern whatsoever.
Scs (LON:SCS)
Hi Paul
I'm not bothered by the working capital movements.
It's the one off benefits/repayments/deferrals/etc... that are confusing me.
Cheers
A
Scs (LON:SCS)
Abtan is the benefit of the business rates relief not simply a memo note that is completely not relevant to cashflow as the credit is simply part of the total operating expenses so like any other overhead that doesn’t specifically show up in cashflow - note there could be a timing element ref the cashflow but this would presumably show in payables or receivables change for the year in the same manner as any item that was paid in advance or arrears . The fact they do full line by rec from profit to ending cash generation is generally enough for me. If your item is still missing I suspect it’s in the payables change that paul has circled.
Hi
A bit of macro view old economy energy supplies versus renewables and the current miss-match of demand versus supply ..... worth noting I think (and its not because of Brexit).
Also a bit unexpected from Bloomberg to be pointing out realistic facts about challenges for this renewables agenda. It's hard to avoid facts sometimes, but encouraging to hear voices speaking some sense IMO from 28/09/21 2:55mins.
Regards
Howard
Our approach to energy is insane. There is a total lack of comprehension from policy makers, investors, academics, media, economists etc that we are first and foremost a society built on abundant excess energy. ESG decrees and policies from wherever are well meaning...but detached from this energy economy reality.
I find this all very frustrating. In June this year I wrote this opinion for a niche economics mag (I put some of them on Medium if I think more general):
https://mojomogoz.medium.com/e...
I got a lot of stick about it. Climate denier etc...
hi Paul
re Scs (LON:SCS)
(my first post so not sure how the £ticker works so if it hasn't worked here maybe someone can help)
Bear in mind the divis are highly likely to be increased back to historic levels (peak at 16.7p)
It seems to me that many companies who have cancelled / deferred dividends are simply taking the opportunity to re-base their dividends once re-instated. That may also be the case with SCS, in which case it could be many years before a 16p+ payout is back on the agenda.
Hi Paul , and again many thanks on your report on SCS.
I believe that with £50m cash, a profitable growing business and a ridiculous market cap of £100m , the first thing management should have done today was to announce a 10% buyback of their own shares. We are talking here about only 3.8m shares to be bought back.
They still would have been left with approximately £40m in cash!!!
Thank you for the detailed writeup on Scs (LON:SCS) Paul, very informative and much appreciated (I hold)
Just to highlight the lead times on sofas. I ordered in May from Sofology, was ready for delivery by July. The items had scuff marks so had to be replaced. The new sofas will come (estimated) in Feb 2022! I don't really mind as I get to keep the current ones whilst I wait for new new ones.
Why to be wary of Scs (LON:SCS)
1) Next 12 mths of sales has never been more uncertain. There is probably a cooling. Smoothed LfL could be quite disappointing (not a forecast just a risk).
2) Sun Capital (I think that's their name) bought SCS for £1 during financial crisis, took private and then re-floated c.2015. Great buy and great job. But despite helping to create a new superb model Sun never really got rewarded due to low price of SCS and lack of interest from buyer or investors. They exited rather grumpily at a low price and they will be in a hurry to get involved in microcap UK retail.
3) Micro cap value is a tough gig. The market would definitely sort out the underpricing of SCS if it were £10bn market cap and £5bn cash with value and cheap quality investors piling in. At SCS's size it will take a small cap activist to rumble things up and seek to get mgt to talk about their cash...
4) The signalling around their cash position is dreadful. It goes up and the dividend goes down. Why? Also they have furlough and rates relief that they haven't paid back (someone knowledgeable told me it could be c.40p per share worth). Will they pay back? Clarity would be good.
5) Given all the cash why such a paltry dividend. Maybe a special is coming? My hunch is that they plan to acquire...that's a huge risk IMO as SCS council house chic model is superb...its not clear that they can move up the aspiration scale or to adjacent product easily and well....and beyond the cost of acquisition there may be high investment demands. IMO the old CEO was a wannabe empire builder. The new CEO has not shown his shareholder return friendliness (yet).
The SCS out of down business model is superb and beautifully evolved (Sun Capital seemed good PE...but didn't get a reward for it!) but naturally limited in scale. Pushing it to high growth doesn't work. Note pre GFC in the early to mid Noughties they went gangbusters on expansion and that helped to push them under (it was the same CEO who retired recently.
SCS doesn't work for most PE. It could work for a sizeable family office that want to create a high cash dividend for themselves with modest upside growth.
SCS need to create their own motor...that means buying back a lot of shares over an extended period of time. They could easily target keeping current (paltry!) dividend and pushing eps up 5%pa thro buybacks. Add a little natural growth on top from new stores (and closing rubbish old ones from the mad expansion) and you've got a motor that pushed price up....
...but I think that ain't going to happen as mgt want to do something 'bigger'.
I would own shares if I believed mgt were going to do self help
(Clearly your downside is protected given cash levels)
Agree on £SCS. Also some big institutions are reducing holdings. The growth is unlikely to hold up, and the supply chain issues compound this. This sp will drop further by a chunk.
Not a small cap I know but just fun to see Greggs (LON:GRG) shoot up 10% on the news that they won't run out of sausage rolls!
As someone 'on the road' sometimes its a struggle to find HOT food other than McD. Not knocking McD in any way at all - the toilets were a lifesaver and drive-through genius - but your gut knows you can't survive daily on the fare. Service stations some attempt but sorry. Lay-bye greasy spoon sorry. Costa/Starbucks costly and not so healthy Mr Croc Monsieur. I have plugged into the satnav to find the nearest Greggs on occasion. The cold food is very good but with our weather need something warm please. Expanding outlets which is bold so certainly one to watch. Can park as well which is huge - wipes out the cafe/bakery shops on the High Street.
Also if park their outlet near someone else's electric charging points then ...
But does that make it an investment ......
Greggs (LON:GRG) just looked at the share price - good god - elephants do gallop. Bin the guru books.
' the toilets were a lifesaver'
My cycling club invented the concept of a Mcpiss.
Scs (LON:SCS) looks interesting and I'm looking forward to the write up.
I'd be interested on your current view of SNX. You reviewed it a year ago and it was on your watch list. It has weathered the covid storm and is now expected to go profit making in the second half after contract wins and reductions of costs. The contract wins for Berlin and London certainly look interesting and potentially could lead onto other cities following suit. Directors hold a little over 14%, albeit, mainly bought through the monthly share scheme. No debt, £3.5m cash, book value of £2.09 and a broker target of 230p-285p, this looks like it could be about to turn.
I dot not hold either of these shares.
We lease an electric car and use for local runs. Its range is up to 300 miles driven carefully. With a home charger and 5p per kWh offpeak electricity it is only charged in the middle of the night. So actually helps National Grid balance the electricity supply. Did take it to a public charger for fun once during the day to see how it worked.
Have driven a Tesla and considered leasing one. Others who own them tell me that maintenance costs are relatively high, brakes and tyre servicing aren't cheap. Reason given is that they are heavy cars. Certainly leasing companies charge a lot for a maintenance contract compared with an ICE car.
As a holder of Vertu, I am expecting it to benefit from higher second hand prices for some time to come.
"This could be due to the sharp reduction in sales of new cars, possibly?"
Paul, yes I think so, as new cars are not available or long waiting time, people have bought used cars instead, however these must be running in short supply now. I notice my local used car dealer has about half their normal stock. The stock also must be getting older as less new cars replacing the used ones? I don't buy new cars, I think they are a waste of money, you can get a nearly new car with about 40% off or you used to be able to. I won't be changing my car until things get back to normal.
12 months ago I got offered 22.5k for my E Class. I part exchanged it for an iPace 6 weeks ago for £30k and it had another 17k miles on it. And I got 0% finance on the Jag. Madness
Certainly things have changed recently.
There is more sense in buying new, if you can get one, as used car prices have gone up.
If I lived in London I may even buy an EV. But what is the depreciation like?
Ok if you are not in London where drivers will be hit with a daily charge if their petrol car is older than 2005 or they have a diesel older than 2015. Not a problem normally to change your car but not in these circumstances!
On Braemar Shipping Services (LON:BMS) I agree that it's sliding price seems out of kilter with the worldwide freight issues and the recent positive updates from the company. As someone else noted, I suspect the most recent shake in the share price is the news that sea freights have plunged in the last week. Nikkei Asia reported yesterday that "the cost of shipping a 40-foot container from China to the U.S. West Coast dropped nearly half in the previous four days, going from about $15,000 to just over $8,000. The spot rate for shipping to the East
Coast had fallen by more than one-quarter from over $20,000 to less than $15,000." Interesting that Clarkson (LON:CKN) hasn't reacted at all, whereas BMS is down circa 20% in the last month.
I think Braemar Shipping Services (LON:BMS) is wrongly priced (talking my own book), but it's always been quite illiquid and these in general have been selling off for the last month. All the best, Will
"If" the market is being efficient and supposedly looking forward 6-9 months it may be taking into account a big expected reduction in freight costs, though as you point out Clarkson (LON:CKN) hasn't really moved. I wonder if Braemar Shipping Services (LON:BMS) slightly chequered history is holding it back a bit and may require a couple more sets of in-line results for full confidence to be resumed?
I must admit I like the look of Braemar Shipping Services (LON:BMS) and certainly tempted here. The work I need to do first though is understand what the financials look like in a normalised environment. Market appears to consider the historically low $2000 container costs as having been unsustainably cheap and so my thesis is that it will maybe settle to a $4000 - $6000 range. If the numbers stack up there I might well look to buy some.
Paul,
RE: car dealers. One of their most profitable activities is servicing and spare parts. Surely one of the concerns has to be the availability of parts within the supply chain to allow servicing to take place?
FWIW I remember test driving a second hand Audi back in July with a missing door rubber because they had to use it to service a customers car!
All the best, Si
Ref electric car sales
Even though the total is low for September at 214k cars, it’s striking that 15% of those were electric.
Its interesting to compare how Telsa a pure electric car maker has done compared to GM in the latest 3 monthly period - ok there may be supply constraint issues at play here but its a very interesting illustration of what to me is a clear trend in favour of electric and or specifically Tesla cars.
If we look at what Tesla did July to September
Tesla delivered 241,300 vehicles globally in the July to September quarter, up 73% from a year earlier. Analysts had expected the electric-car maker to deliver 229,242 vehicles, according to Refinitiv data.
Compared to GM
GM on Friday said it sold about 447,000 vehicles from July through September, down 32.8% from a year earlier.
Thats a pretty stunning progress in a 12 month period here for the pure electric play v one of the old skool competitors.
Looking at the above stats i would say if and when the model 2 (bog standard car) comes along (presuming cyber truck also turns up) that may be sufficient to propel Telsa past GM ref total sales once volumes ramp up.
Perhaps the bods who think Tesla is a "fraud" won't believe these stats :) (Joking peeps)
Can you tell me what a delivery is? At least how Tesla chooses to define it.
BlueFrew
Can you tell me what a delivery is? At least how Tesla chooses to define it.
The broohaha about Tesla production - sales and deliveries has vanished now that there is nothing to broohaha about (there was wild consipiracy theories about tesla storing vehicles they couldnt sell or didnt work - back in the day -bunch of baloney) Telsa report both production and delivery totals each 3 month period. I just quoted the stat that appeared in the article. Note production in the period was a tad lower at 237,823 so no material difference between the two numbers.
Per the company themselves ref when they count deliveries they say the following.
“Our delivery count should be viewed as slightly conservative, as we only count a car as delivered if it is transferred to the customer and all paperwork is correct. Final numbers could vary by up to 0.5% or more,” the company said in a statement.
Its pretty plain and clear to me this 240k numbers seems reasonably accurate picture of where the company is at with regard to both production and sales. Note as per original post they may have benefited this period if competitors dont have cars that they can sell - thats not exactly their fault though.
Nope, it's all still there. The A/R balance keeps going up. They claim to have sold more Model S/ X than they produced but there's photographic evidence of >1000 Model S / X sitting in fields dusty and dirty.
There's a whole load of other things we could mention but this is the SCVR and I don't want to drift too far from topic. But, essentialy, Tesla represents the anti-thesis of these reports, not small cap and no value to be seen on any metric.
This is the fascinating thing about investing. Essentially we all have access to the same information but we can form completely different opinions to each other - in the case of Tesla, the opinions are often poles apart. We see things through different lenses.
Every single time a few days before end of quarter without fail, social media and various Tesla talking shops are full of people who have paid in full for a car, are assigned a VIN and a delivery date and the delivery date is delayed until after Q end.
When are things "transferred" with "correct paperwork"?
1 car purchase. 2x deliveries. Let's call one delivery a "financial delivery" in Qx and then an actual physical delivery in Q(x+1). Accounts Receivables secured.
One day this stuff will actually matter.
I think you are comparing Tesla's global sales with GM's US only sales.
JohnEustance
I think you are comparing Tesla's global sales with GM's US only sales.
Ahhh you are right in that regard , thanks for that correction - that number is deffo US only - based on last year that number possibly something just below 40% of global sales only - so Tesla aint nearly as close to GM as i thought was the case.
ok, the numbers may not be directly comparable, but the percentages are interesting, it suggests the swing to electric cars is well on the way (as does the 15% Paul quoted), also perhaps that as electric cars are significantly more expensive , (double roughly ?), that they are having less difficulty sourcing chips for them, because they're able to pay more perhaps ? Chip shortages are a pain, but inevitable, as if you lead with supply, you suppress prices, and risk your capital, if you follow demand, you get higher prices and quicker payback on your investment. Anyone have a feel for how long this will take to sort out ? 12 months or more ??
Mysale (LON:MYSL) anyone else thing this is starting to look very interesting. A few things happened of late including todays announcement
No.5 would you hold a share that is potentially going to be delisted in the UK to be transferred to Australia? Would require lots of PIs selling out of ISAs and those that don't want to hold Australian listed shares.
dual listed
I picked some Wincanton (LON:WIN) up this morning. logistics/supply chain is not normally a sector that interests me, but with all the issues going on, i think WIN is poised for a good year.
I will be treating this company the way i should have treated companies which import products when the supply issues started (dump positions which are likely to be harshly affected e.g G4M) - so once the supply chain issues clear up, i plan to move from it (as i reckon they're likely to have bumper profits this year, not meet them next year and i expect price to fall)
What i've learned this last month is to not be so 'sentimental' with shares. I find myself struggling to pull the sale trigger when a 25% profit turns to 10% profit. but with no end in sight to the downturn, it makes sense to take some! the share isn't going anywhere - I can always buy back in. I've found i need to be a bit more flexible with my approach. otherwise this year would have wiped out last year's progress - and my mental state along with it haha.
Got my eyes on SCS right now - looking like an absolute bargain, but will it drop further?
Morning all,
Bit of blue in my portfolio this morning! First time in a while...
Braemar Shipping Services (LON:BMS) (I Hold) seems to fall daily at the moment, now 25% off recent highs. I really can't understand it, surely they are in the perfect storm to benefit from the supply issues at the moment? in their recent trading update they were benefitting from the pressure on container space, is this a golden buying opportunity?
Braemar Shipping Services (LON:BMS) Yes and they put out an above expectations update only very recently. I would be interested to hear from anyone who thinks they might be negatively impacted by inflation or supply chain issues as although I hold here based on value I don't really understand the sector (so not a long term hold for me). If anything you would have thought shipping and air freight brokers would be in hot demand right now!
It might be an example of how there is irrational sell-off of some small caps. Redde Northgate (LON:REDD) is also down quite a bit which doesn't make much sense to me and as Paul says Vertu Motors (LON:VTU) should be benefiting tremendously from much better margins on used cars right now.
Yes, Redde Northgate (LON:REDD) is a strange one, don't understand it falling at all!
Hi JohnDoe
I took my profit off the table and let the market decide where the price will end up when the price dropped through £4.
One of the updated sell rules for me was 10% down from the previous high, or when , and hence there are several sells in the last few weeks such as Redde Northgate (LON:REDD) and Polar Capital Holdings (LON:POLR), I would intend to buy back (probably).
This is more a leftover from last year of capital protection, managing 5 portfolios (mine and families) so up and down but more about protect rather than just watch it drift back down again, particularly as these are typically smaller holdings so not an issue selling on the market.
Cheers
Tommy
Braemar Shipping Services (LON:BMS) I think the whole sector took a big hit yesterday. you might want to follow @mintzmyer on Twitter as he is a US based analyst who specialises in this area. As with all markets, i suspect this is a multi-dimensional puzzle; the lack of investment in shipping plus restarting in world economy has caused charter rates to go through the roof, but the lack of supply has an effect at some point on manufacturing which then slows down production and so on. Also look at £NMM chart from yesterday (US listed).
Regarding Braemar Shipping Services (LON:BMS), the share price does seems out of kilter with the current global supply chain issues and freight costs and more importantly the recent company announcements. I have skimmed through the latest Finncap research and RNS announcements, including the June prelims plus Roland's recent review on the SCVR and have bought an opening position.
Hopefully it will be a successful investment, but whatever thank you for alerting me to that possibility.
You are confusing share price performance to business performance.
The two are not always correlated. Many reasons including sentiment, time lag, information asymmetry, macro conditions, etc.
Agreed, the two are not always correlated, therein lies the opportunity. No confusion on my part. The company is performing well but the shares have been panned for whatever reason. I think the current share price does not reflect the improvements made by the new management team or the company's future prospects, hence my purchase.
Scs (LON:SCS), a lot of moving parts in the prelims that I have yet to digest, but to be going on with;
I may have missed some important points, but on initial reading, the business seems irrationally cheap to me with no debt, cash of £50m and trading on a forward PE of 8-9. I can't believe that Private Equity will not be interested.
I hold and so am likely to be a little biased.
It does look irrationally cheap - though it always seems to look that way so perhaps not a major surprise.
Problem is that any retail is getting smacked at the moment because all anyone can talk about are supply chain issues. These will be transient but investors aren't factoring that in at the moment.
Sosandar (LON:SOS) which I hold for example is down 12% this morning on no news and dropping daily. Now some 35% off the recent highs that accompanied a fantastic set of results. Despite the company hinting at a further good trading update just last week at the AGM (on the back of a successful TV campaign).
In most of these drops it's all on small volume - MMs are just walking stocks down from weak retail hands right now.
EDIT : On Scs (LON:SCS) I would say the high dividend compensates whilst you wait for a re-rate which is a bonus not found on the other retailers.
I know David. Having said below I cannot get interested in small uk shares I did have to pick up a few Sosander this morning, great opportunity, or so I feel anyway.
Sosandar (LON:SOS) traded some 1.8m+ shares (3 x daily avg. ) so far today, so a bit alarming..is it the spooks after Boohoo announced supply chain issues? (I hold and I'm waiting for them to go cash positive)..
Yeah - largish volume. Not obvious why. It tried to make a comeback but got hit with another 500k sales around 3pm again. Looks like someone unloading a reasonable size stake.
Personally I take a long term view to Sosandar (LON:SOS) as I just don't think I will time the trading of it. I expect it to become a major brand in the next few years - perhaps 10 or 20 times the current size but I recognise that few will share that level of optimism. I've therefore bought a stake I'm happy to stick away and leave alone. If the narrative changes then I will too but any short term supply chain disruptions won't be a reason.
I suspect reading between the lines at the AGM that progress remains good with a lot of new sign ups from recent TV advertising. Also, it strikes me that they are selling a lot more via Next and other platforms. We know that Next recently upgraded their forecasts as well so I expect sales to be strong, but obviously margins are lower on 3rd party marketplace sales.
Positive update from Wincanton (LON:WIN) today. It provides solutions to supply chain problems. A good space to be just now?!
Gear4music Holdings (LON:G4M) on the way down again today. I have checked on Trustpilot and they are recently getting 5 stars for delivery etc. Are there supply issues, with every company, I guess possibly not? Like many companies going down at the moment, I can not decide if I am missing a great buying opportunity, or there is a profit warning on the way. Any thoughts?
Hi Lefty,
FWIW, i sold my small holding in Gear4music Holdings (LON:G4M) first thing yesterday for a decent profit, over supply chain concerns and a possible profit warning.
I would wait until trading update in two weeks i believe, see how the land lies then. If it's positive, i would have no qualms about buying back in!
Thanks for your thoughts JohnDoe2378,
I am tempted to do the same, I am still in for a decent profit atm. I am tempted to sell everything atm, but not so sure I would be so good at market timing. I was 100% invested last month, but I now have 30% cash.
FWIW, i sold my small holding in Gear4music Holdings (LON:G4M) first thing yesterday for a decent profit, over supply chain concerns and a possible profit warning.
Baaaaaaaa! :-)
All the best, Si
Pardon?
Pardon?
Yesterday someone here called you a ruminant, so I was just saying hello.
All the best, Si
Surely a “Doe” is a Leporidae not a ruminant?
Gus.
I hold also rather shocking decline along with many others I have LUCE/BLV/SOM etc a nasty nasty spell. I to just also looked at G4M trust pilot reviews so far no apparent, logistics cost though will be affected for sure, this does give some comfort. Hi shipping costs will be seen as an opportunity and the industry will respond perhaps into over supply as happens with the miners.
trustpilot.com/review/www.gear4music.com
Lefty99, re Gear4music Holdings (LON:G4M) and lots o shares which have shown major increases in SP, there must be a lot of profit taking and returning to cash, as well as supply chain problems and possibilities of profit warnings. Tandem (LON:TND) must also be another candidate? Im sure lots of people here can think of more....and more?
Paul, please don't join the mass of uninformed commentators who think that more electric vehicles means necessarily more strain on the energy network. This has been comprehensively debunked by the National Grid!
I for one would be grateful if you could post a link to that comprehensive debunking from the National Grid.
Cliff Hughes - yes please post that link - I hold National Grid (LON:NG.)
Try https://www.nationalgrid.com/s...
The figure that really caught my eye was that peak electricity consumption was back in 2002 and demand has fallen 16% since then.
If you want to spend hours looking at electricity statistics then a good place to start is:
https://www.gov.uk/government/...
Most people I know seem to assume that electricity consumption has been constantly increasing, very few being aware of the huge reduction over the last 15 years.
Let me google that for you:
6 myths about electric vehicles busted | National Grid Group
6 myths about electric vehicles busted | National Grid Group
A fair bit of truth in that, but there's a lot of PR puff too, glossing over issues like timing of solar generation vs car charging peaks, and no real mention of charging difficulties - yes we mostly want to stop after a few hours for a coffee, but once most cars are electric how many fast chargers will service stations need to have if you aren't going to have to queue for a long time or have a 2 hour break? What about the vast numbers of people living in inner cities with no offstreet parking or even regular access to parking anywhere near their house? And who thinks fuel costs can remain at 2p a mile once a lot more cars are no longer paying fuel duty? As we keep being told, there is no magic money tree, that revenue will need replacing, by road charging for something similar.
I disagree. National Grid acknowledges that existing infrastructure needs to be upgraded for electric car charging. Excerpt below from FT article:
Britain’s energy regulator has promised to tackle one of the major barriers to installing more electric vehicle chargers along key trunk roads in the UK by making it cheaper for charging stations to connect to the electricity grid.
Motorway service operations have long complained that Britain’s energy networks are stifling the rollout of EV charging facilities by quoting up to tens of millions of pounds for the new connections required to deliver high speed charging. This is because local grids often need to be reinforced to accommodate the greater demand for electricity.
UK regulator to lower grid connection costs for EV charging - https://on.ft.com/2WLL7IK via @FT
You’re arguing a point the OP never made. His argument is one of capacity, yours is an argument of accessibility. Both valid points but not the same thing.
I am sorry to do this but my mind is looking more macro at the moment. I understand the idea of picking good companies and holding, but I also think, not often but periodically things do change. Brexit was a major move for the UK, set within the global changes including the impact of Trumps short tyranny which questions in a big way our "special" relationship. We now have some structural issues in the UK which may or may not be addressed and I believe global warming is going to be a drag globally on economies. All of which mean I find it hard to buy any UK stocks which rely on UK business at current levels. I don't mean to be a kill joy and I certainly will continue to read Paul and Jacks' excellent column but I am looking for diversifyers, both asset class and individual holdings. They do exist in the UK but I think I probably prefer the USD or even the renmimbi. Anyway just a few quick and under discussed if not irrelevant to this column thoughts. Best wishes to all.
Not small cap but relevant to the comments in the article. Melrose Industries (LON:MRO) trading update today says auto manufacturers are currently cancelling 25% of parts orders as the chip shortage bites. So car output is roughly 75%. Articles I’ve read suggest that EVs are being prioritised by the manufacturers because of the EU fines placed on ICE vehicle fleets if they, overall, have a higher than mandated average CO2 output. No brainer for the manufacturers to produce as many EVs as they can shift and even sell them at cost or a loss if necessary as the EU fines can be greater than profit margins.
Yes, looking forward to your comments on Scs (LON:SCS) Paul. Clearly on the basis of its cash, an opportunity for private equity, but too small and not really their thing?
Hi ridavies.
Re. Scs (LON:SCS) while I agree it’s on the small side I think it’s an ideal candidate for a private equity leveraged recap. Buy it, strip the cash, realise any freehold property or other hidden value assets (if there are any), releverage the remainder using the positive cash float (customers pay up front for a sofa that you pay the manufacturers for on deferred terms), add a nice fat consumer finance scheme for purchase to make (in)decent finance charge income, dress it up and flog it back to AIM in three years as a Dfs Furniture (LON:DFS) clone on a racy multiple. In fact, just need to find a few bob down the back of the sofa and I’ll do it myself. Simples.
Gus.
Paul, with regards to the cars, I would like to offer some insight. I run a car leasing business which I shall give a shameless punt to: www.just-leasing.co.uk
We had a record month in September. The new registrations will have helped that. People also seem to be taking advantage of the booming 2nd hand car market to sell.
The flip side is limited availability of new cars due to a shortage of microchips. This shortage is due to a fire with a major manufacturer, Covid lockdowns limiting manufacturing and an increase in demand from gaming consoles. As a result lead times for delivery are drifting all the time.
One step we have seen is discounts to leasing companies being pulled. As major buyers these can be as high as 17%. The impact on a Mini would be circa £100 p.m. over 3 years so £3,600 over the term.
I have held Motorpoint for some time. I was advised to follow Norbert Lou of Punchcard Capital. He bought Motorpoint in the UK and Naked Wine. I bought both and have had a 4 X return on Naked.
Electric vehicles are interesting. They are arguably technology so lend themselves to leasing. As battery lives, power and range improve people want new ones. I am unsure how they will be used as 2nd hand vehicles. I suspect a recycling programme might be more appropriate.
Thank you CamRaid re your comments on the car market. We are on our second electric, a Peugeot bought new recently, after selling our (bought 2nd hand) Nissan Leaf. We bought it at 4 years old and used it for 5 years, then traded it in. We were only using it for relatively short journeys but the battery decline was becoming a problem. Recent new cars have more than enough mileage for us at around 200.
Hi CamRaid.
Interesting insider commentary on the vehicle leasing market. Thanks for this. On your comment about the attraction of electric vehicles to leasing companies, how concerned are you/how do you manage the risk on the residual value element of your contracts?
In a previous life, I had some involvement in the analogous TV rentals sector in the late 90’s/early noughties. Rental companies seemed to be making out like bandits as early adopters constantly wanted to rent the newest kit (to cope with satellite TV and various changes in screen format etc.) so there was huge demand for expensive rental items such as plasma and HD kit etc.. Problem was that the rate of product evolution was so rapid that the bottom fell out of the resale market/kit residuals tanked and TV rental effectively died for all but the very lower end of the market as supermarkets and electrical discounters started selling previously high tech kit at a fraction of the previous price and the leasing companies could only crystallise a fraction of the expected residual. I see a similar risk with electric vehicles where the rate of technology change is such that this year’s state of the art is obsolete at the end of a three year lease contract.
Gus.
The difference being, most people can’t afford anything but a second hand car. There is no supermarket wanting to sell high tech kit for buttons in that market. So, whilst it’s a worry, it’s a lot less likely to happen to expensive capital purchases than with throwaway electronics. Even if the residual market collapses, all that will happen is leases get more expensive, which means demand for second hand cars goes up (less people can afford the lease) whilst supply contracts into the second hand market. It’ll eventually just balance out.
Gus, we are vehicle leasing brokers so do not manage back end risk. You raise a really good point.
The RV's offered in some instances seem crazy.
We have a deal on a well know electric van that costs £50k to buy. The deal is £200 a month for 2 years. Obviously the lease company gets an upfront discount but this is still an astonishing deal. The RV must be very bullish.
Talking of EV, does anyone have a view as to how good a move is Redde Northgate (LON:REDD) July news in EV space?: ''Redde Northgate plc (LSE:REDD), the leading integrated mobility solutions platform providing services across the vehicle lifecycle, is pleased to announce that on 9 July 2021 the Group completed the acquisition of Charged Electric Vehicles Limited ('ChargedEV'), a specialist in the supply and installation of Electric Vehicle (EV) charging equipment across the UK.'' Market cap a bit big but interesting company, StockRank 98 and good support by the Stocko Community.
Hi CamRaid, Any suggestion on where to follow Norbert Lou's recent buy/sell ?
Hi CamRaid would you happen to have a link to the fund/holdings ?
Thanks Andy
(The lecy used by the demise of oil refineries more than compensates for electric car use- some refineries consumption are equivalent to small cities)
(At the risk of SCVR being highjacked by SMMT car data) ...and night time charging when there is large spare capacity is easy with home charging (& generation) and the development of cheap, mass storage.
Maybe current grid/electricity cannot cope but relatively easily fixed over the 15 year transition timeframe - much more wind/solar/battery, more interconnectors, more efficiency etc. Mostly just requires pump-priming by govt (enabling regulation, subsidies) which this govt seems very prepared to do.
A much bigger issue for the whole European car supply chain from manufacturer to dealers will be reduced engine maintenance, much longer car lifecycles and Chinese e-car sales the way the Japanese/Koreans came in on much lower costs. These are 5yr+ issues but must put a ceiling on price progress from here..
Short term, I think it now late for buying dealers. Their prices are up and you have to believe the supply chain chip short can be sorted in 6-12 months - the forward-looking time frame the (big buying institutional) market tends to think in.
I already think I have delayed too long in selling £Redde that benefitted from the surge of used van sales price - now roughly 10% off peak.
Maybe current grid/electricity cannot cope
Why do you say that? Peak supply of electricity in the UK was 377 terrawatt hours in 2005. Since then electricity supplied has decreased by just over 20% to 296 terrawatt hours in 2020. According to National Grid peak demand was 62 GW in 2002 and since then peak demand has reduced by 16%. Total generating capacity reduced slightly in 2020 to 75.8 GW but still comfortably exceeds peak demand.
National grid have stated "When it comes to the capacity of the wires required to deliver that power to the nation’s EV charging points, National Grid’s transmission system is ever-evolving and suitably robust to cope with the forecast uptake in EVs."
I don't think that generation or grid distribution is the limiting factor for electric vehicle growth.
One issue with solar, is the peak generation is around mid day which is not usually when peak power is required. There are concerns that solar could overload the network at peaks times yet it does not produce anything at night time.
The issue with EVs is how will govt. tax them because they will be losing a lot of tax revenue from petrol/diesel. The other issue is the cost of electric has shot up this year.
Yes electric use has fallen in UK, however if everyone switched to EVs the use would soar, it uses around 30kw for just 100 miles, I use about 3kws per day, if I had an EV my energy use would rise considerably.
Another demand for electric is heating, as new homes will have electric heating rather than gas. Maybe these new homes should have solar and batteries.
Yes electric use has fallen in UK, however if everyone switched to EVs the use would soar, it uses around 30kw for just 100 miles, I use about 3kws per day, if I had an EV my energy use would rise considerably.
To give that comment some context I have done a back of an envelope calculation - If the average annual car mileage is 7000, the number of cars on the road around 30 million and the energy consumption of an electric car using your figure of 0.3 kwh/mile then the total electricity consumption if all cars instantly switched to electric would be 63 terrawatt hours per year. That wouldn't quite take us back to the 2005 figure for total electricity consumption.
LON:PTRO.Whoops. Timely contract win announced this morning with their' Meet the Company Presentation' in about 1 Hour, following on from lasts weeks encouraging Half year report.
Simon (and others), you need to tell us which company you're talking about!
Timely contract win announced this morning with their' Meet the Company Presentation' in about 1 Hour, following on from lasts weeks encouraging Half year report.
Easy to forget this time of the morning, so you're forgiven! ;-)
P.
Thanks Paul. Its these dark mornings too. It is LON:PTRO
You did actually say Pelatro (LON:PTRO) but it was lost at the beginning of your original comment because you didnt use the dreaded £ before it nor left a space after it! We all learn in time.
Thanks for the alibi ridavies. I edited in and still got it wrong! Anyway, must log on for the Meet the Company (£ LON: PTRO). Ed :Not very good with their timing . In the same email they say it starts at 9 till 10, but starts at 10! Will be recorded depending on when they press the record button
It was not in the original post.
It was right at the beginning of the post
Really, RayStraw? Or maybe I missed something.
'LON:PTRO.Whoops. Timely contract win announced this morning with their'
Meet the Company Presentation' in about 1 Hour, following on from lasts
weeks encouraging Half year report.'
Yes he edited it, hence the Whoops after it?
"I edited in and still got it wrong!"
At first glance it seems like good results from Scs (LON:SCS)
These weeks the good results means 5-10% drops. Looks like Scs (LON:SCS) is just following the trend...
On my reckoning SCS have a Market Cap around about the level of cash they are holding in the business - crackers !!! Paul - is there any justification for this other than the current market sentiment ?
£SCS Market cap £102m as I type, cash (excluding customers dosh) £50m
I am a bit surprised at the fall given the L4L sales outlook post year-end. Was the market wanting something even better than 12% L4L sales (vs FY19) in early FY22? Or is simply mentioning you are cognisant of supply chain pressures (who isn't?) enough to send you down 10% these days?
I agree ref Scs (LON:SCS) but I see its dropped by 6% on opening. This market is very hard to fathom out. Reasonable results, although some warning around shipping etc and a decent dividend (10p for the full year, 7p today for the final div). Still holding a massive cash balance on its books and good strong trading vs FY19.
Think I will just sit back and see what comes over the next few weeks. I've already top-sliced a few winners to get some cash ready for a down-turn, but now is the time to sit on my hands. I suspect we will see the continued gyrations for a while yet but hopefully once things settle down we can get back to decent results & stocks being rewarded. Def some bargains look to be being created - I have my eye on a few, but will try and sit a while longer and see if I can spot the trend turning, which at the moment continues downward.
which ones are you eyeing? (could be interesting)