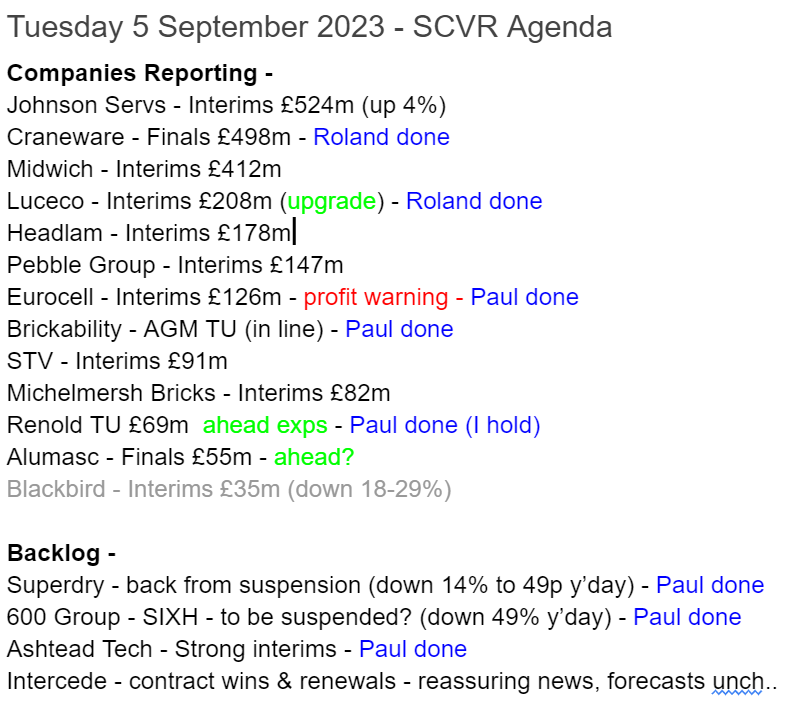
Small Cap Value Report (Tue 5 Sept 2023) - AT., SDRY, SIXH, RNO, LUCE, ECEL, CRW, BRCK

Good morning from Paul! Graham messaged me in the night to say he's unwell, so let's hope he gets well soon. As luck would have it, I prepared some backlog sections yesterday evening, so I'll still get a full report out for you today. Roland is helping out, as we've got many decent companies to look at today.
We'll leave it there for today.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
We'll probably manage about half of these, very busy today -
Summaries
Luceco (LON:LUCE) - down 5% to 124p (£205m) - Interim Results - Roland - AMBER/GREEN
Half-year results (to June 2023) from this electrical parts manufacturer show a smaller revenue decline than expected. Full-year profit guidance has been upgraded. I like the core business but have mixed views on the group’s acquisitive growth strategy. The shares look fairly valued to me.
Eurocell (LON:ECEL) - Down 9% to 102p (£115m) - Interim Results (profit warning) - Paul - AMBER
I still see this as a fundamentally decent business, but tough macro is hurting it right now - softer demand, lower gross margins, higher costs, have badly squeezed H1 profits. And another profit warning (as we expected here on 25 July) has been announced today. Decent balance sheet protects the downside. At some point the market is likely to start pricing in a recovery, but it feels to early to jump in.
Craneware (LON:CRW) - up 4% to 1,445p (£489m) - FY 2023 results - Roland - AMBER
Today’s results from this healthcare software business are in line and I can see plenty to like here. However, I’m puzzled by the apparent low profitability and a sizeable cash movement. I’d need to do more research to take a positive view, given the stock’s current rating.
Paul’s Section:
Ashtead Technology Holdings (LON:AT.)
Up 7% to 420p (£335m) - Interim Results - Paul - AMBER/GREEN
Dec 2021 float, has done really well, with shares hitting a new all-time high yesterday.
I’ve looked at the numbers before, and was impressed. Although previously I was puzzled how an equipment hire business for the offshore energy industry could generate such big profits, from such a small asset base?
Ashtead Technology Holdings plc (AIM: AT.), a leading subsea equipment rental and solutions provider for the global offshore energy sector, announces its unaudited results for the six months ended 30 June 2023 ("HY23" or "the period").
Fantastic H1 results here -
Revenue up 57% to £49.8m, 41% is organic growth.
Adj PBT up 88% to £14.3m - rapid growth, and a strong profit margin.
Statutory PBT is only a little lower, at £13.2m.
Adj basic EPS 14.2p (up 71%)
High demand from offshore oil/gas, and renewables.
Net debt (excl leases) looks OK at £26.4m.
Claims to have the largest independent fleet in a highly fragmented market.
Outlook - expects FY 12/2023 to be “comfortably ahead” of forecasts - the StockReport is saying consensus is 26.4p, so at a guess maybe we’re looking at c.30p for the full year? That would be a PER of 14x, which looks fair to me.
Growth rate expected to moderate in H2, due to tougher comparatives, so let’s not get carried away!
Balance sheet - fairly lightweight once intangibles are removed, with only about £14m NTAV - so hardly any hard asset backing here.
Paul’s opinion - superb numbers. However, I remain confused at how it is possible to generate such stellar profits from a small asset base? Maybe depreciation is super-conservative, and the book value has been written down for assets that still have a good rental life remaining?
It sounds like this company is really in a sweet spot, having the right equipment at the right time, with a resurgence in demand occurring, something we’re hearing from other oil services companies.
Ashtead Tech looks to be doing really well, but I worry that it’s enjoying a sweet spot that might not last more than a couple of years, because other companies are bound to spot the opportunity to make lucrative profits from an under-supplied market. So the risk I see is that feast could turn into famine in future.
In the meantime though, shareholders are enjoying a bumper period. Will it last though? That’s the key thing to research. Does Ashtead Tech have any defensible moat? Or is it just enjoying a nice patch from being in the right place at the right time?
I don’t know, am just flagging up the key questions to ask.
In the meantime, I cannot ignore such strong numbers, so have upped my personal opinion from AMBER, to AMBER/GREEN.
Superdry (LON:SDRY)
Down 14% to 49p yesterday (£47m) - resumption of trading - Paul - RED
See Friday’s SCVR here for my take on the pros & mostly cons of this troubled fashion retail/wholesale business. In a nutshell -
Bull points - receipt of £35m windfall from selling brand rights in the Far East is evidence that the brand still has value. Cash/debt position OK for the time being.
Bear points - moved into losses for FY 4/2023, and Q1 2024 trading sounds grim, especially wholesale (50% down), so forecasts now look pie in the sky. High cost seasonal borrowing facilities from specialist lenders Bantry Bay & Hilco (vultures circling?). Large deficit on IFRS 16 lease entries indicates many shops must be heavily loss-making. Tired brand that’s had its day?
Paul’s view - I hope they turn it around, and think this autumn/winter season could be make or break for this brand. On current performance, I don’t think it’s likely to survive throughout 2024, but you never know. Tenacious management might pull off a surprise, I’ll keep an eye on it for tangible signs of progress (completely lacking so far). So this share is now purely for gamblers I think.
600 (LON:SIXH)
Down 49% y’day to 2.85p (£4m) - Update - Paul - AMBER/RED
It’s below our usual mkt cap lower limit now, but I’ve followed 600 Group for years, and am curious as to why it plunged by half yesterday (Monday).
We last looked at it in Dec 2022, when Graham couldn’t see any reason for it to continue with a stock market listing, having sold off a division to reduce debt, leaving not much behind - a small, loss-making business with too much central overhead.
This announcement was issued after the market closed on Friday last week, which is clearly what triggered the 49% fall on Monday. Key points -
Audited accounts for FY 3/2023 won’t be ready by the 6 month, 30 Sept deadline, should be ready in October.
Shares will be suspended, with the last day of trading being Fri 29 Sept 2023.
Hoping to lift suspension on publication of Annual Report in Oct 2023.
Trading update - conditions continue to be difficult. H1 loss expected (no figures provided). Goodwill impairments will be needed (which doesn’t really matter).
However, this does matter, a lot -
The Group is considering various financial alternatives to its existing debt facilities which currently expire on 30 November 2023.
Paul’s opinion - that last bit, about financing options, sounds ominous. Could this mean a discounted placing, delisting, or distressed sale of the business? Who knows. I’d be surprised if SIXH survives in its current form. Net debt was only small at $2.5m (excl. leases) at Sept 2022, but might have increased since, I don’t know. The last balance sheet had adequate NTAV, but far too much cash was tied up in inventories and receivables. So reducing those, to repay the relatively small debt, could provide an exit route enabling it to survive perhaps? With inadequate information, I probably should mark it red, but the decent balance sheet NTAV makes me lean towards AMBER/RED - so serious concerns, but it might be able to pull through.
Renold (LON:RNO) [Paul holds]
30.75p (pre market) £69m - AGM Trading Update - Paul - GREEN
This industrial chains group with a big pension scheme, provides us with a 4-month update for FY 3/2024 to date (Apr, May, Jun, Jul 2023).
The short version - it’s a positive update -
As a result of the continued positive trading momentum, and an increase in activity from the recently announced Davidson acquisition, the Board now anticipates achieving results for the year ending 31 March 2024, higher than previously expected.
Detail -
Revenue is up 17% to £85.1m in the first 4 months, or 9% organic growth.
Order book at July 2023 is down 14%, due to supply chains, and hence order intake normalising.
Net debt at July 2023 looks OK, at £23.3m (only 0.6x EBITDA), and down £6.5m in 4 months. This will rise by H1 (Sep 2023) due to £4.9m acquisition related payments, and £2.6m earlier pension scheme payment.
Markets uncertain, with labour & materials inflation still high by historic standards.
Broker upgrade - many thanks to Finncap for an update note. It increases FY 3/2024 forecast aEPS by 6% from 5.2p to 5.5p. aPBT rises from £16.1m to £17.1m. Note there are no divis, as Renold is focusing capital on bolt-on acquisitions (and pension scheme payments).
At 30.75p per share, the PER is only 5.6x - very cheap for a decent quality business. However, part of the reason is the significant cash that the pension scheme demands, which of course doesn’t go through the P&L account, which is why companies with cash-hungry pension deficits should be trading on a low PER. Even so, I think the discount at Renold is looking too large.
Paul’s opinion (I hold) - really encouraging news, and it’s impressive to be achieving an out-performance (helped partly by an acquisition last year that is now kicking into this year’s numbers) in tough macro conditions.
Renold has impressed me a lot in recent years with an effective turnaround, debt reduction, and now it’s on the front foot buying other complementary businesses, in a fragmented sector.
Renold showed its strengths by sailing through both the pandemic, and also the energy/inflation issues more recently, so I think this is now proven to be a quality business with pricing power. It’s cheap too, and I think could end up as a bid target for a larger industrials group, possibly.
I’m encouraged to continue holding, as one of my core personal value shares.
You can see below how EPS is settling at more than double pre-pandemic levels.

Eurocell (LON:ECEL)
Down 9% to 102p (£115m) - Interim Results (profit warning) - Paul - AMBER
There have only been a handful of small trades this morning, so I don’t think we can determine much so far from the share price reaction to this profit warning.
Eurocell plc, the market leading, vertically integrated UK manufacturer, distributor and recycler of innovative window, door and roofline PVC products, today announces its half year results for the six months ending 30 June 2023.
Actions taken position the business well for when markets recover
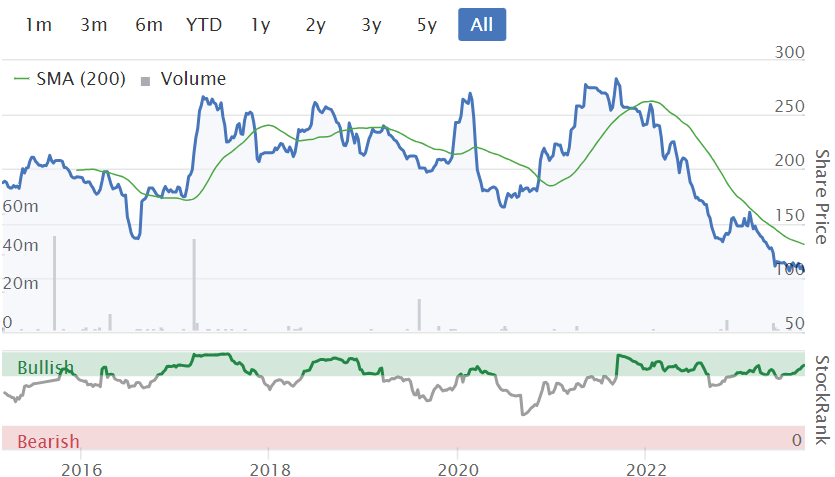
As you can see below, Eurocell hasn’t been the best performer since it listed in 2015. Although if you add on generous divis, things are not as bad as they seem. Note the dip for covid, then the strong recovery from the lockdown DIY boom, then an absolute plunge ever since. Surely it’s getting into oversold territory? I’m about to find out!
H1 numbers - poor results, although it says as expected (and clearly anticipated by the share price) -
Revenue down 2% to £184m
Gross margin well down, from 50.7% to 46.0%, with competitive pressures mentioned in the commentary.
Adj PBT down 62% to £6.0m - a very nasty drop, but still profitable.
Statutory PBT down 78% to £3.5m. Adjs of £2.5m mainly restructuring costs.
Adj EPS in H1 down 63% to 4.3p
Interim divi of 2.0p - encouraging that it’s still paying a divi, but this is well down from 3.5p interim divi last year.
Outlook - more bad news, not really a surprise given what macro conditions are like, and similar bad news we’ve already seen from the sector -
Further deterioration in market conditions since July Trading Update means full year performance now anticipated to be below our previous expectations
Broker updates - nothing available unfortunately. So I’ll have to wait until the StockReport updates for changes to broker consensus.
Balance sheet - is very robust, at £93m NTAV.
So shareholders can sleep soundly, safe in the knowledge that Eurocell should be able to comfortably ride out this soft patch.
Net bank debt is £15.2m, hardly changed from a year earlier. It seems to have an excessive bank facility of £75m, so it might make sense to say halve that, to save on arrangement fees.
Cashflow statement - all looks OK, although what stands out to me is that the divis are now looking excessive, with payment of the final divi costing £8.1m in H1. The interim divi has sensibly been trimmed, and I would expect the final divi to also be reduced. Although forecasts already assume a reduction in full year divis to 7.4p (down from 10.7p actual last year). With trading deteriorating, I wouldn’t place too much emphasis on generous divis continuing, they might be cut again I suspect.
Paul’s opinion - we already know this is a really tough sector right now. So the big question is about when, and how much, a recovery in earnings is likely to happen?
In the meantime, demand is soft, and gross margins weaker, whilst costs are naturally seeing upward pressure. That’s a horrible mixture for short term profitability, mitigated somewhat with cost cutting already done.
However, a recovery should see it rebuild earnings to possibly the pre-covid levels of c.20p EPS? There’s little to no risk of dilution either. Someone might bid for it, at these depressed levels, so possible upside there too.
As mentioned previously here, and in my podcasts, it seems to me that a recovery in builders & suppliers is not likely to happen any time soon - I forget which company it was, but someone said they’re not expecting a recovery until H2 2024. Although share prices are likely to start anticipating a recovery maybe 6 months before it actually happens. A sharp drop in interest rates, which is one potential scenario, could trigger a big rebound in housing & related products, possibly? I'd like to get in ahead of that.
Put that all together, I’m happier sitting on the sidelines for now, researching more, and picking my spot, adding to my watchlist, ready to pounce once the value becomes more extreme. It doesn’t feel like we’re quite there yet (but not far off).
Reviewing my previous notes, I mentioned on 25 July here that another profit warning could be on the cards at ECEL. As trading is likely to be tough for some time, I think AMBER is how I’m currently seeing this, although with upside potential once macro conditions (hopefully) normalise.
Brickability (LON:BRCK)
Down 4% to 49p (£147m) - AGM Statement - Paul - AMBER
Brickability Group plc (AIM: BRCK), the leading construction materials distributor…
This financial year is FY 3/2024.
I’ve been impressed with performance at this acquisitive bricks (and other building products) distributor. It’s differentiated by using a drop-shipping business model, meaning it doesn’t carry much inventories. Management impressed me on a recent webinar, giving clear answers to 2 of my questions. My tenure as a shareholder was only brief though, as it soon dawned on me that worries about macro are taking precedence in the short term anyway.
Previous coverage here was -
26/4/2023: GREEN - ahead expectations TU.
17/7/2023: AMBER/GREEN - good FY 3/2023 results, but I have increasing macro concerns. Mystery share for podcast after mgt impressed me on a webinar.
Today’s update summarised -
- Trading has been good, and in line with expectations for April-July.
- Vague about August trading, “typically seasonal”.
- “Cognisant” of volume reductions for housebuilders and manufacturers, due to macro.
- “More challenging trading environment” expected for remainder of FY 3/2024.
- Diversified product ranges mean it hopes to continue doing OK.
Broker updates - prior to today’s cautious outlook, broker forecasts had been trimmed a little, but this strikes me as inadequate, given the scale of the macro downturn (eg. we’ve seen housebuilders talking about order books being down 40%-ish, which is bound to feed through to much lower demand for bricks, it has to). BRCK said on the recent webinar that they had already planned for a 20% downturn in demand in their forecasts, which I suspect may not be enough.

I can’t see any revised forecasts today, but I think it would be safest to work on the basis that FY 3/2024 is likely to get progressively worse - which BRCK is basically telling us in today’s update.
Hence I think a profit warning looks increasingly likely, given that current forecasts have only been slightly trimmed, which is not consistent with the macro picture at all.
Paul’s opinion - the share price keeps getting cheaper and cheaper, so clearly investors are taking the fairly positive noises from the company with a pinch of salt. I think that’s sensible. A few months ago, we were looking at a possible H2 recovery in building, but that’s gone out of the window now I think. Hence shares in the sector should be lower.
I remain positive on BRCK as a share I want to hold in a recovery, but as with everything else, it feels too soon to be bottom fishing right now. I’m starting to sound like a stuck record here! So this is one for my watchlist, not my actual portfolio, at this stage.
Roland’s Section:
Luceco (LON:LUCE)
124p (-5% at 9am) (£205m) - Interim results - Roland - AMBER/GREEN
Luceco plc, the supplier of wiring accessories, EV chargers, LED lighting, and portable power products, today announces its unaudited results for the six months ended 30 June 2023 ("H1 2023" or "the period").
I looked at this business a few months ago and was left with mixed views. My general impression is that the core wiring accessories business is market-leading and highly profitable, but some of the other operations are less attractive.
Today’s interim results appear to be slightly better than expected, with a modest upgrade to full-year guidance.
We now expect full year 2023 adjusted operating profit to show clear progress on last year. This is above the current range of market expectations.
Let’s take a closer look.
Financial overview: Luceco’s half-year results reveal a modest fall in revenue and a more sizeable fall in adjusted profits, due to the impact of operational gearing.
Revenue down 5% to £101.1m
Operating profit down by 2% to £9.8m
Adjusted earnings per share down 13.8% to 5.0p
Interim dividend unchanged at 1.6p per share
Luceco’s statutory and adjusted operating profit were quite close – adjustments were not too large.
Pre-tax and after-tax profits showed bigger swings, but these appear to be due mainly to currency effects and related movements in the group’s hedging portfolio. These tend to even out over time, in my experience. I’d be inclined to ignore this factor and focus on operating profitability as a measure of underlying performance.
Profitability: management acknowledges that returns on capital will fall due to the “required investment in goodwill” from regular acquisitions.
I have mixed views on the group’s acquisition strategy but the commentary is certainly correct – organic assets do not result in goodwill on the balance sheet and thus appear to generate higher returns on capital than acquired businesses, where buyers typically pay a premium to asset value (goodwill).
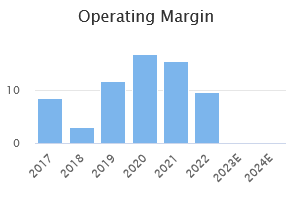
Luceco’s profitability metrics seem reasonable to me and suggest that profitability is returning to more normal levels after the peak seen during the pandemic:
H1 adjusted operating margin: 10.6%
Trailing 12-month ROCE: 14.0% (my calculation)
Free cash flow for the half year was -£8.0m, but the company says this reflects a return to more normal patterns of working capital after last year’s unwind. Net debt is also down to £37.6m (H1 2022: £53.9m), so I don’t see anything much to worry about.
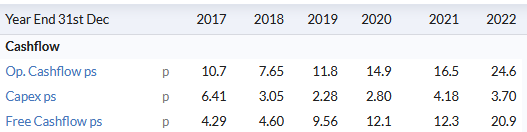
By choosing the interims on the cash flow tab on the StockReport, we can see that Luceco’s cash flow has been stronger in H2 in recent years. The group has generated positive free cash flow across each full year since at least 2017, according to Stockopedia data:
Trading commentary: Luceco’s trading last year was hit by cost inflation and destocking by major customers. The company suffers a certain lack of visibility in its retail and hybrid sales channels, where distributors buy stock in bulk and then sell stock gradually (Luceco has no visibility of this).
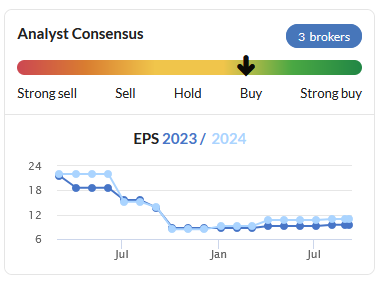
As a result, profit forecasts have been cut by c.50% over the last year:
At a group level, trading conditions appear to have stabilised and improved during the first half of this year:
“Customer stocking has appeared to return to normal levels at the end of H1 2023 following post-pandemic destocking
Non-residential demand continues its favourable trend
Despite economic headwinds, revenue decline has been less than expected
Material and freight costs pressures have subsided”
Trading at some more recently acquired businesses also seems to have been positive:
“Operational synergies at DW Windsor [an LED lighting business], within the most recent addition to the Group, contributed a strong first half performance with near double digit operating margin and some key contract wins.
EV business has grown further, with a strong pipeline of new products.”
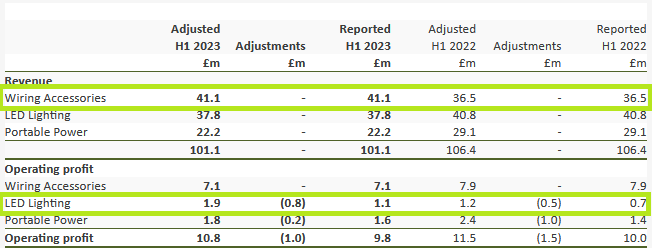
The impact of improved margins in the LED lighting business was evident in the segmental results.
However, the core wiring accessories business was the only division to deliver revenue growth in H1 and remains far more profitable, with a 17% operating margin vs <10% elsewhere.
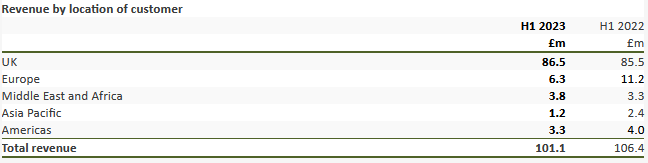
Personally, I question the group’s geographic expansion ambitions. It’s not clear to me if Luceco can gain the scale and competitive advantages it enjoys in the UK in Asia or the Americas:
Outlook: CEO John Hornby appears confident that the worst of the impact of inflation and destocking has now passed:
“Despite ongoing weakness in our core markets, we have made further progress since the July trading update and we now expect full year 2023 adjusted operating profit to show clear progress on last year. This is above the current range of market expectations.”
No explicit financial guidance is provided today. But adjusted operating profit was £22m last year and consensus forecasts I could see to today suggested a figure of £21.6m.
My feeling is that today’s upgrade is fairly modest and is probably already reflected in the share price rally we’ve seen since the start of the year:

Roland’s view: At current levels, Luceco shares trading on 13 times 2023 forecast earnings and offer a useful 3.5% dividend yield.
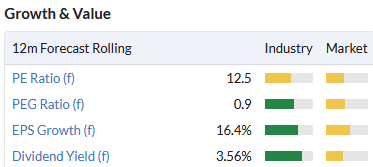
This valuation looks about right to me. While I like the group’s core wiring accessories business, I’m less convinced by the competitive strength of some of its acquisitions.
I think it’s also worth remembering the apparent lack of visibility on earnings here. Forecasts have been slashed over the last year and are currently around 50% of last year’s levels:

However, I don’t see anything serious to be concerned about here and I accept that the group’s strategy could deliver significant growth if it’s successful. On balance, I’m taking an AMBER/GREEN view.
Craneware (LON:CRW)
1443p (+4% at 9am) (£489m) - Final results - Roland - AMBER
AIM-listed Craneware produces software used by hospitals in the US to help track patient costs and manage their billing efficiently (and accurately).
Healthcare-related software seems an interesting sector to me, with growth potential. I’m currently a shareholder in UK healthcare software group EMIS (LON:EMIS), which is being taken over by a subsidiary of US healthcare giant Unitedhealth (NYQ:UNH). So I’m keen to see if there are any other homegrown software businesses that could provide a new home for my cash.
Graham covered Craneware’s last update in July, when the company reported full-year revenue at the top end of expectations. He suggested the shares could be “cheap through an American lens”, even though they trade on a P/E of around 20.
Results summary: today’s results cover the year to 30 June 2023 and appear to be in line with expectations.
Revenue for the year rose by 5% to $174m, with annual recurring revenue up by 1.6% to $169.0m.
Operating profit for the year rose by 6% to $19.2m, giving an operating margin of 11%. Adjusted earnings were $0.87 per share, versus Stockopedia consensus of $0.84 per share.
Cash conversion was also excellent. I calculate free cash flow of $23.6m on an underlying basis, which represents 120% of operating profit for the year.
However, actual cash generation for the year was boosted by $50m of cash received to be “held on behalf of customers”. This line item was less than $1m last year. I’m not entirely sure what this refers to, so I’d need to do further research to form a view on this.
Profitability: my main concern with Craneware is that its profitability seems quite low. Operating margins have deteriorated sharply as the business has grown – last year’s margin of 11% is unchanged from 2022.

Return on capital employed has also fallen sharply. My sums suggest a statutory ROCE of just 4.1% last year.
Even if I strip out the $235m of goodwill from acquisitions (see my comments on LUCE above), I only get ROCE of c.8%.
By way of contrast, EMIS has ROCE and operating margins in the high teens.
Outlook: chief executive (and 9.7% shareholder) Keith Neilson says that he expects to see “a more supportive market backdrop” in the US, now that the pandemic health emergency has been formally declared to be over (May ‘23).
Mr Neilson cites “a growing pipeline of opportunities” and says the business is “well positioned for FY24”.
However, the outlook statement does not include any fresh guidance on the outlook for profits.
Stockopedia consensus forecasts prior to today suggested only modest growth in earnings this year:
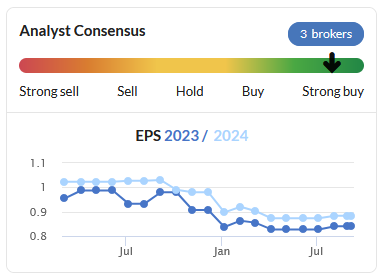
These estimates put Craneware on a forecast P/E of about 20, with a 2.1% dividend yield.
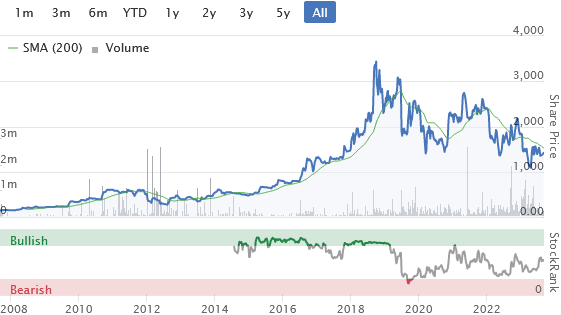
Roland’s view: I can see plenty to like about Craneware’s business. The shares have de-rated substantially from historic highs and I can imagine there might be an opportunity here.
However, I’d need to do more research to try and understand the group’s apparent lack of profitability and its cash situation. For now, I’m going to maintain Graham’s July view and go AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Pleased to say I met up with Jack (previous SCVR writer here) this afternoon, and had a lunch and a chat. He's doing great, working in the City now, as part of a fund management team for a top company. He's really enjoying it, and sends his regards to everyone here.
Eurocell (LON:ECEL) Relatively new CEO managing expectations with his downbeat phrasing?
I don't think he got the tone right but it is what it is. I missed the presentation, have to wait for catch up, not sure if anyone else made it?
Sigmaroc (LON:SRC)
As an addendum to my earlier post I looked at the Stockopedia director dealings that show no director selling, but plenty of buys/take up of placings in various sizes, going back 3 years. Sharepad confirms this theme.
Given that the share price, as most UK small caps, especially AIM, has been under pressure for an extended period, it is perhaps not surprising, but nonetheless I would suggest is generally positive.
I notice the Supreme (LON:SUP) has taken a bit of a hit today, down around 6%. I suspect this is linked to the Panorama documentary that aired last night regarding teenage vaping and the possible harm it can cause, much of which is focused on disposable vapes. I was always under the impression that Supreme did not produce disposable vapes and focused instead on a more adult market with its rechargeable/refillable vapes. However, I do remember that a contract was signed earlier in the year for the distribution of vapes from other big vape brands. I am unsure if they are the disposable vapes or not.
Does anyone with more knowledge than me know the specifics surrounding Supremes exposure to disposable vapes? These seem to be the target of any government restrictions or bans and what I imagine is holding back the SP as the business is doing very well at the moment.
I have a small holding but might look to top up on this recent dip as like many others I rate the management and fundamentals.
Many thanks
Ben
Supreme (LON:SUP)
I suspect the drop is also due to silly headlines such as the Mail "Could Britain be next to ban vapes?" whereas the talk has been about banning disposable vapes.
Supreme has a very small share of the disposable market and a ban on them would benefit it if there was an increase in the sale of its higher margin non-disposable products as a result.
The disposable market is totally dominated by ElfBar and Supreme now has a distribution agreement for these. ElfBar has obviously started to prepare for the possibility of a ban by moving to the next product up - which is a unit with a rechargeable battery into which disposable closed pods are slotted, so still no messing around with liquids:
https://www.elfbar.co.uk/elf-bar-pod-system (the main problem with the disposable is that the battery is sealed in plastic so difficult to extract for recycling and can cause fires if crushed in rubbish lorries).
However the publicity to comments has been one-sided - on the other side ASH is against a ban as it would "turbo-charge" illegal sales many of which have been found to contain hazardous banned substances.
Other than that there is the question of sale to underage people and I remember someone at SUP saying they favoured the same approach in shops as alcohol - the requirement of a licence to sell with any sales to those under age potentially leading to a loss of licence.
I asked a question at the interim presentation on these things last November and their answer to that (and a couple of other questions) is here ( start 39 mins 30 secs in):
Thanks for your response sharw. I'll check out the video once home. My thoughts were that this drop is due to media storm that will soon blow over. Low volume too, just 37 trades all day!
Yes - Supreme (LON:SUP) has less than 10% in the disposal vapes. Not a market they are in to.
They meticulously test their product for impurities unlike many other who just sample test randomly.
They are active in regulation and support bans on teenage vaping.
If the market gets more tightly regulated then Supreme (LON:SUP) will almost definitively benefit from that. likewise a ban on disposables will probably work out net neutral for them. They don’t sell or market to teens either and almost zero revenue is attributed to it.
I get increasingly angry with media that in my view is just ever more irresponsible in its click bait salacious nonsense. Not just in this topic but in general. We need more balanced debate across our media.
Perhaps (tongue in cheek here) investors could begin class actions against media that headline irresponsibly causing share price falls…….that might stop it!
Anyway, yes the share price fall is investors panicking over headlines, and in a pool with so little liquidity it might as well be called a puddle rather than a lake, prices will fall.
I found out the other day that some people come straight to the SCVR reports page missing out on other discussion threads at https://www.stockopedia.com/di... After Paul left here today-
Paul Scott runs through 22 stock ideas
was posted here: https://www.stockopedia.com/co...
I will not put the video up here so that you can see the list of stocks and make comments on that thread.
Warning: It is 90 mins long so get yourself a coffee/tea/something stronger first.
Hello Shar. Was this today, then, Tues?
Next question. Is this a regular thing?
ridavies - it was posted at 2 11 p.m. today. Periodic rather than regular. Last 2 were:
23rd May
22nd Feb
(Clickable)
Re: Craneware (LON:CRW) - I hold. It would seem this is still being valued through US eyes. Apart from a brief flirtation with being valued using UK metrics earlier this year, that has been the case for a long time. Given all of its revenue comes from the States, I would say that's reasonable. Yes, it has de-rated which coincided with the chaos in US healthcare after covid but with that now behind it, I could see this re-rating again. Given current bids for similar companies - EMIS (LON:EMIS) , Instem (LON:INS) and Ergomed (LON:ERGO) - I could easily see someone bidding for this as well. It's a quality company with a world-leading product with very high recurring revenues.
Thank you for your Eurocell observations and you Roland for Luceco, I agree with both comments and appreciate your analysis. After an unexpectedly successful weekend in the Masters Championships in Derby I'm afraid optimism and dopamine is overcoming reality this morning in the TU's affecting our portfolio. You're waiting on Eurocell shares Paul but we'll add a few more and the same with Luceco. We also hold MBH who's report today seems more promising to me than Brickability's.
I love the royal we!
Belvoir (LON:BLV) is a tiny cap, which you might want to comment on it for macro purposes.
Well, Belvoir (LON:BLV) has the advantages of recurring revenues from its franchisees, who in turn have reliable income from lettings. I think we covered it very recently actually. There's also plenty of activity from people remortgaging too, so it's a nice robust business model.
Good Morning Paul, the tagging issue is back, 2 on yesterday's report and most if todays, have gone missing.
Oh that's a nuisance about the tags, but don't worry, I check them all every weekend (am a bit behind from last week, but it's on the agenda!)
I don't hold Superdry (LON:SDRY) but I can imagine a slimmed-down range fitting into in Mike Ashley's empire...it's a very well known brand (far more so than Joules was) so I wouldn't be surprised to see someone 'rescuing' it....
Maybe but after it goes to 0………
Yes I agree yiannos1.
Many troubled retail/fashion brands do survive in a slimmed down form, but usually after equity holders have been wiped out completely. So as you suggest, it's very important for investors to distinguish between the brand surviving, and the equity going to zero.
Johnson Service JSG numbers caught my eye. Look very solid. Perhaps a mundane business with somewhat modest returns but looks well managed and on a strong recovery after a tough covid. Perhaps WFH is a minor negative? Any views/holders here?
I hold Johnson Service (LON:JSG) in 2 accounts, one underwater the other floating, make that what you will Wombat though I can see my required improvement in SP arriving in due course.
Roland,
Appreciate your writing up Luceco.
Liberum have upped their 2023 eps forecast by 12% this am, to 10.4p.
Maybe more interestingly, their 2025 forecast (ok, a way out so could be wrong), is for 13.4p.
If you think a p/e of 12.5 is "about right", then in Sept 2025 this stock would be priced at 13.4p x 12.5 =167.5p
That is 33% higher than now. Plus a couple years of 3.5% yield, equals a 40% 2 year return.
Seems ok to me!!!
I do hold a bit.
Chris
Whilst not small cap, I hold B&M European Value Retail SA (LON:BME) within Mum's portfolio, it has had a downgrade from "overweight" to "underweight" by JP Morgan this morning and dropped 5%, as this is one of the few successes this year as bought on the folks moving to buy at the cheaper end of the market, wondering do I just take the money off the table and let it all settle down?
I am assuming "underweight" = sell in this case.
thanks
Tommy
I wouldn't attach too much importance to broker downgrades if you're a buy and hold investor. Brokers want to generate business by encouraging investors to switch from one company to another in the same sector, often with little real justification. If you believe the investment case for a company is still valid, its better to sit out any short-term turbulence in share price, unless obviously there's a profit warning or some other unexpected development.
Tommy. I take little notice of broker sell and buy advice, except that if looking to sell I use the day of a bullish broker note and sometimes big share price gain on that day as a good sell opportunity and the same in reverse if there’s a Broker downgrade.
Armed with the same info on these larger Company shares, different Brokers come to very different conclusions with some saying buy and others sell, and their share price targets are often very different too. So take more note of Amy useful Broker comment than they’re often wrong but and sell advice.
A few years ago there was a survey of FTSE100 broker buy and sell advice and subsequent share price performance that year. What happened was eye catching! The Broker sells did for better than the Broker buys by quote a wide margin. AND the share that got the most Broker BUYs British American Tobacco (LON:BATS) ended up the very worst FTSE100 performer that year!
As for B&M European Value Retail SA (LON:BME) I took the profit after their last update as they were vague about prospects, and because I also hold and prefer Dunelm (LON:DNLM) but that decision is no more useful for you than that Broker advice!
B&M European Value Retail SA (LON:BME) are taking a big chunk of Wilko stores in that chain's break up. Dont know whether this 'risky' act has anything to do with the price drop
You called it right on Eurocell on July 25th Paul, we hold. I have quite a strong stomach which you suggested might be needed. I'm hoping you have time for a quick comment on their H1, I'm tempted to add for that continually receding upturn!
Thanks JASVFS!
I've just posted a section on Eurocell (LON:ECEL) , let me know what you think, as a holder. Quite an encouragingly small negative price reaction to another profit warning, which suggests to me that we might be getting somewhere near a low on it. But they're so illiquid, it would only take one fund manager to start dumping in the market, to smash the price down.
Regards, Paul.
Sigmaroc (LON:SRC)
This morning's interims take a little unravelling, which is unsurprising given the various moving parts, but Sigmaroc (LON:SRC) appears to be making progress given the industry in which it operates and challenging economic conditions.
I have met the management team lead by CEO, Max Vermorken a few times and have come away impressed. Apologies for the somewhat lazy cut and paste approach but I have lifted the highlights direct from the interims.
I hold
Strong H1 with resilient trading, further strategic progress, and full year expectations unchanged
SigmaRoc plc, the specialist quarried materials group, is pleased to announce its unaudited interim results for the six months ended 30 June 2023.
Financial highlights
Underlying[1] results
30 June 2023
30 June 2022
YoY change
Revenue
£290.0m
£247.1m
+17%
EBITDA
£54.9m
£47.6m
+15%
EBITDA margin
18.9%
19.2%
-30bps
Net Margin2
21.9%
21.2%
+70bps
Profit before tax
£33.0m
£29.1m
+13%
EPS
4.01p
3.61p
+11%
Cash and cash equivalents
£62.5m
£46.4m
+35%
Net debt3
£183.3m
£216.9m
-15%
Adjusted Leverage Ratio
1.69x
2.24x
-25
[1] Underlying results are stated before acquisition related expenses, certain finance costs, redundancy and reorganisation costs, impairments, amortisation of acquisition intangibles and share option expense. References to an underlying profit measure throughout this Annual Report are defined on this basis. Pro-forma financial information is presented on a like-for-like basis adjusting for impact of any acquisitions or non-recurring events.
2 Net Margin is EBITDA margin adjusted for impact of inflationary cost pass-throughs, such as energy, materials, and distribution
3 Net debt including IFRS 16 lease liabilities.
Financial highlights
· Strong H1, further demonstrating the resilience of the Group's model, together with its continued strategic development;
· LFL revenue growth of 13%, reflecting effective pricing actions and benefits of diversified market exposure;
· Underlying LFL EBITDA growth of 12%, with further productivity gains contributing to robust margins;
· Group volumes fell by 3% but demand remained resilient across key markets with dynamic pricing supporting Net Margin improvement;
· Underlying EPS increased by 11% YoY, despite finance costs doubling and impact of February fundraise;
· Adjusted Leverage Ratio reduced by 0.24x in the Period to 1.69x, comfortably below 2.0x target;
I am watching the InvestorMeet presentation as I type, seems to me that EBITDA is being used as a persuader so I remain unconverted. I don't hold Sigmaroc (LON:SRC) but was interested.
Edit: No dividends and shares being diluted like mad is a turnoff for me , the future may be orange but I am 79.
Hi
Summary portion of Sigmaroc (LON:SRC) RNS this morning
Interim Results 2023
Strong H1 with resilient trading, further strategic progress, and full year expectations unchanged
SigmaRoc plc, the specialist quarried materials group, is pleased to announce its unaudited interim results for the six months ended 30 June 2023.
Highlights
Financial highlights
Underlying[1] results
30 June 2023
30 June 2022
YoY change
Revenue
£290.0m
£247.1m
+17%
EBITDA
£54.9m
£47.6m
+15%
EBITDA margin
18.9%
19.2%
-30bps
Net Margin2
21.9%
21.2%
+70bps
Profit before tax
£33.0m
£29.1m
+13%
EPS
4.01p
3.61p
+11%
Cash and cash equivalents
£62.5m
£46.4m
+35%
Net debt3
£183.3m
£216.9m
-15%
Adjusted Leverage Ratio
1.69x
2.24x
-25%
Financial highlights
· Strong H1, further demonstrating the resilience of the Group's model, together with its continued strategic development;
· LFL revenue growth of 13%, reflecting effective pricing actions and benefits of diversified market exposure;
· Underlying LFL EBITDA growth of 12%, with further productivity gains contributing to robust margins;
· Group volumes fell by 3% but demand remained resilient across key markets with dynamic pricing supporting Net Margin improvement;
· Underlying EPS increased by 11% YoY, despite finance costs doubling and impact of February fundraise;
· Adjusted Leverage Ratio reduced by 0.24x in the Period to 1.69x, comfortably below 2.0x target;
Rest of RNS is here for those interested ....
https://www.investegate.co.uk/...
I hold.
Rgards
Howard
Paul
......“I remain confused at how it is possible to generate such stellar profits from a small asset base? Maybe depreciation is super-conservative, and the book value has been written down for assets that still have a good rental life remaining?”
An explanation of Ashtead Technology Holdings (LON:AT.) excellent returns from its available asset base and a probable customer Moat in an old IC article….
.......This change in customer behaviour (to outsource specialist subsea equipment) lead to the development of the group’s asset management offering through which, given its specialist knowledge and IT systems, Ashtead provides customers with asset management services. This allows customers to maintain their equipment fleets, which can then be deployed on their own projects or rented to other Ashtead Technology customers, thus generating a return for the asset owner from otherwise unutilised assets. It also embeds Ashtead within the customer’s organisation, thus creating a barrier to entry for other competitors.
Cleaver stuff!
Also we need to bear in mind for Ashtead Technology Holdings (LON:AT.) that in a high inflationary environment, many companies prefer hiring the equipment as opposed to buying it. This will be a tailwind for the short term probably for another year.
I hold
Good morning iwright7,
How interesting, thanks for your explanation of why Ashtead Technology Holdings (LON:AT.) generates such high returns from a small fleet. That makes sense, if they're borrowing equipment from other companies under-utilised stuff.
Thank you for pointing out this, which helps answer my query.
Regards, Paul.
I agree this is another set of strong results from Ashtead Technology Holdings (LON:AT.) although I think it’s worth bearing in mind some of the potential risks.
A key tailwind has been the increased demand from from oil/gas producers – up 50% YoY and at £33.5m still accounts for two thirds of revenue.
An interesting data point from Haliburton and upstream oil and gas providers is that they are now seeing a softening in service prices. Oil service providers have certainly benefited from increased investment due to both post covid economic recovery and energy sovereignty concerns. Lately producers e.g. OPEC+ have become more wary about supply and investment which will impact service providers.
AT.’s fast growing green energy division provides differentiation from pure play oil/gas service providers, but its oil/gas weighting still means its exposed to the ups and downs of the oil and gas sector.
I think this is important when £8m of the £13m of net cash generated from operations is being invested back into the business through capex. A core risk to this type of business is when and how much to invest in capacity.
A second concern for me is that whilst AT. is building a track record of beating expectations the legacy owners have taken advantage of recent strong results announcements by selling down their stake. I think their stake is down to 9% now so it’s not clear how much further this has to go. If you’re still keen it might be worth waiting to buy the dip!
It's a bit too expensive for the SCVR but I wondered if anyone had any views on the Gamma Communications (LON:GAMA) interims today, which looked fairly good at first blush?
Expecting FY results at the top half of expectations, net cash, profitable and growing, 90% recurring revenue, gross margin of 51%, and it doesn't look overly expensive.
https://www.investegate.co.uk/...
The opportunity going forward doesn't seem to be going away as the UK prepares to turn off PSTN and ISTN, but it isn't an area I currently know much about. Anyone have any informed views, particularly on what the downside might be?
timarr
HI Timarr,
I know a little on the sector from working with Gamma's opposition plus a high-level contact within Gamma. I wouldn't claim to be an expert. I hold Gamma shares. Firstly, internally, I know that Gamma are extremely bullish - they see the PSTN switch-off in the UK and the opportunity to consolidate/scale in Europe as big opportunities. My view is that their biggest advantage up to now has been basic competence at what they are doing i.e. providing a good product (that largely hides the complexities from customers) at a reasonable price. I have seen first hand how hard the opposition is finding it, however they are largely dis-functional in my view and therein lies the opportunity.
The primary risks that I see are:
RE:Gamma Communications (LON:GAMA)
Hi Robert
Thanks for taking the time to respond. I've always been puzzled at how difficult networking seems to be - whenever we have to have something done it always seems like the modern equivalent of the plumber sucking in his cheeks and shaking his head sadly, prior to muttering something unfathomable about ballcocks or big ends or some other double entendre (you may gather that plumbing is a mystery to me, somehow fluid mechanics never translated into any practical abilities).
I appreciate the list of potential risks - having worked for and with big telcos I rather discount the possibility that they might get their act together and do anything effective, but I take on board the other points. Their growth rate isn't what you'd expect for a high flying company, but they've derated along with the market to the point that they don't look especially expensive.
Well run companies doing difficult things well are always attractive, and there's definitely a market for reducing complexity for customers (look at Stripe, who've created a billion dollar business by creating an API, and then managed to protect their moat by loading services on top).
Will ponder on it a bit more, but lots of other cheap stocks around, and also lots of growth at almost reasonable prices. Bit like Christmas has come early - although (sadly) if I pop down to my local Wilko it appears it has.
Thanks again,
timarr
Renold (LON:RNO) - thanks Paul for comments. the PD is funded at agreed levels on a long term basis. it is c. 20% of profits. so even if we write off as a total P&L expense then adj eps would be c.4.4p and adj PE of c.7times. i also think with the bolt on opportunities, it is too cheap and possible bid target for a global player and world number 2 in a global market that's been steady in recent years. disc 1 of my top5 positions
On Renold (LON:RNO): for anyone nervous about the order book reducing I think it is also worth noting the house broker has also upgraded FY25 slightly (you can access the broker note for free on Research Tree or Finncap's own research portal online).
I believe the answer to your question (POSITIVE) about Luceco (LON:LUCE) is yes and would be very pleased if you could have a look at the interims today to see if you agree with me .(I hold )
Hi fred,
I roped in Roland to help today, who's had a good rummage through Luceco (LON:LUCE) - section is now up.
Regards, Paul.
I bit the bullet this morning Paul and dumped 600 (LON:SIXH) rightly or wrongly and bought Luceco (LON:LUCE) which I've held in the Past.
Silver Moon - can I persuade you to stop announcing your trades to us all please? It's interesting to you, but not to anyone else!
thank you
Morning Paul
Listened to your excellent weekend podcast last night. I always listen as it is highly informative, provides a quick synopsis of a number of the previous week's results and of course provides a great insight into the mind of a highly experienced investor. Additionally, you are quite funny! Would highly recommend to all.
I was particularly struck by your present YTD. You are up 34%, excluding the Seraphine buyout. This is a phenomenal result. Well done indeed. Must feel especially sweet after your difficult year in 2022. A great reminder to us all that having a bad year is not the end of the World. We all have a difficult spell sometimes.
Thanks also for the Instem name check
Michael
Thanks Michael, very kind!
Yes I had a disastrous 2022, mainly thanks to some bad sector picks (eg eCommerce), and maintaining high gearing in a bear market, which was madness in retrospect. So I've definitely done the right thing in closing my spread bet accounts, and only buying shares outright now. That leaves me free to focus on the research, and not have to worry about short term market gyrations. No more forced selling, ever! Also I've had a bit of luck this year with a couple of takeover bids for my largest holdings.
Given all the above, I hope people don't mind me crowing a bit about a better performance in 2023! ;-)
Regards, Paul.
How do i listen to the podcast? it use to be given here, but not anymore?
https://podcasts.apple.com/gb/...
How do i listen to the podcast? it use to be given here, but not anymore?
Go to any podcast provider, and search "Paul Scott small caps"
(they're brilliant by the way, I enjoy listening to them myself LOL! Its true!)
My morning smallcap tweet: Dip in or dip out
Eurocell (LON:ECEL) Tissue Regenix (LON:TRX) Ashington Innovation (LON:ASHI) Aurrigo International (LON:AURR) Celadon Pharmaceuticals (LON:CEL) Renold (LON:RNO) Time Out (LON:TMO) XLMedia (LON:XLM) Luceco (LON:LUCE), Vianet (LON:VNET), Sigmaroc (LON:SRC), Getbusy (LON:GETB)
◄Eurocell (ECEL)► warns FY-Dec below mgmt expectations. H1 profits down as expected but August very weak with "particularly severe decline in new build housing". [SP=113 Cap=127m]
◄Tissue Regenix (TRX)► launch of new BioRinse sterilisation product line for all sports medicine allografts that it distributes. [SP=50.4 Cap=36m]
◄Ashington Innovation (ASHI)► continues to pursue negotiations to acquire Cell Therapy and Calon Cardio-Technology. Also sacks its broker SI Capital following a breach of confidentiality. [SP=2.75 Cap=2m]
◄Aurrigo (AURR)► gets £482k grant to support pilot deployment of autonomous electric cargo vehicle at East Midlands Airport [SP=132.45 Cap=53m]
◄Celadon Pharmaceuticals (CEL)► three yr contract for the commercial sale of its cannabis product with a second UK pharmaco that could generate up to £1.2m of sales. First shipment will be made in Q4 2023. [SP=140 Cap=86m]
◄Renold (RNO)► guides FY-Mar24 rev higher than expected. Apr-Jul rev up 16.6%, 7% of which was from acquisition. [SP=30.44 Cap=69m]
◄Time Out (TMO)► management agreement to open a new Time Out Market at City Centre Bahrain. Plans to open towards the end of 2024. [SP=47.4 Cap=160m]
◄XLMedia (XLM)► provide 'premium' sports betting content to Atlanta Journal-Constitution. [SP=11.9 Cap=31m]
◄Luceco (LUCE)► H1-June slightly ahead of mgmt expectations,. Guides FY above the current range of market expectations. [SP=130 Cap=209m]
In line: VNET, SRC, GETB
SDRY is a dead brand walking. I’ve been in a few of their shops recently just for a look-see and they were devoid of customers. The offering is nothing special, the brand is dated, no big names are wearing it and you just don’t see it out on the street like you used to. I give it until the end of the New Year sales and then it’s curtains.
Yeah. Home good curtains might sell better. Faddy brands are bad news. Trendy is the last stage before tacky.
Renold (LON:RNO) AGM Statement overall positive -
Group revenue for the Period was £85.1m (FY23 equivalent £73.0m)
Order intake for the Period was £74.2m, a decrease of 2.7% (FY23 equivalent £76.3m), due to global supply chains easing, though the order book of 86m is higher than historic levels, not sure I fully understand the above two statement.
Net debt at 31 July 23 is down though is expected to increase by Sept 23.
Its bringing forward its pension payments which sounds positive.
So to the uneducated its looks like a mixed bag, only saved by the last sentence "the Board now anticipates achieving results for the year ending 31 March 2024, higher than previously expected."
The share price has been slightly volatile during recent days, who knows which way this will go today, or is all the above already known about?
Regarding the order book, I read it as for the 4 months that the reporting period covers, the number of orders that they took is down, but the overall level of orders remains at a high.
Alumasc (LON:ALU) has beaten forecasts with its final results, has a high Stockopedia rating, so worth a review?
Agree Gerald .Bought them when yield was higher than p/e a few months ago.
Nice start to the day, second profit warning from Eurocell (LON:ECEL)
Doesn't read that bad to me, just a bad year as expected - they just seem really gloomy. 'severe decline in new build housing' in the first sentence
Coming on the same morning as MBH's significantly more upbeat results, looks more company specific
Greaat point, Jeez, just read Michelmersh Brick Holdings (LON:MBH) chalk and cheese. I should have dumped ETP and ECEL tbf, oh well.
I must say Paul, Bravo. You called it 100% so far after the last trading update for Eurocell (LON:ECEL)
"Paul’s opinion - broker forecasts have come down in several stages already, and given the poor macro environment, it wouldn’t surprise me to have more forecast downgrades at ECEL and other companies in the building products sector.
So investors here need to have the stomach to endure the risk of another profit warning.
Then at some stage, the market starts to focus on the recovery potential, and the shares re-rate upwards again.
I remain bullish medium to long-term on this nicely financed company, but am half-expecting more disappointments in the shorter term. Hence I am watching from the sidelines, but I’d like to be in it for the medium term recovery, as with so many other cyclical shares.
So I think AMBER/GREEN seems best at the moment - i.e. some short term worries, but fundamentally a good business longer term."