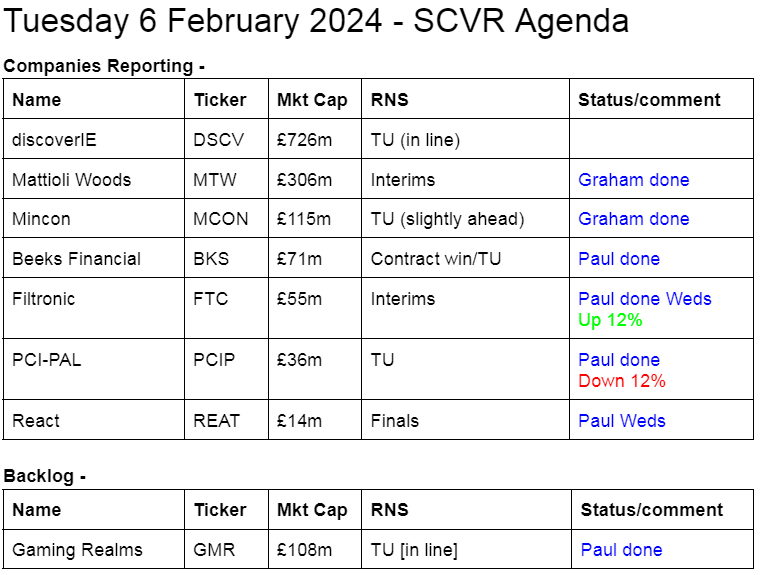
Small Cap Value Report (Tue 6 Feb 2024) - GMR, BKS, MCON, PCIP, MTW

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Other mid-morning movers (with news) -
Futura Medical (LON:FUM) - up 32% to 36.5p on trading update.
SysGroup (LON:SYS) - up 19% to 34.5p on update.
Renishaw (LON:RSW) - mid cap up 19% to 4080p. Interim results. Expects better H2.
XLMedia (LON:XLM) - up 8% to 6.9p - Exclusive partnership with Star Tribune.
Biome Technologies (LON:BIOM) - up 7% to 110p - trading update.
Springfield Properties (LON:SPR) - up 5% to 83p - £15m affordable housing contract signed.
Summaries
Gaming Realms (LON:GMR) (Paul holds) - Down 2% y’day to 36.7p (£108m) - Trading Update [in line] - Paul - GREEN
Another good year, with this gambling software company having established an impressive growth track record. Valuation still seems reasonable. Healthy balance sheet. Outlook says more of the same. I like it - growth at reasonable price.
Beeks Financial Cloud (LON:BKS) (Paul holds) - up 34% to 145p at 09:24 ( £95m) - Significant Contract Wins & Trading Update - Paul - GREEN
Excellent news re contract wins. Canaccord raises forecast profit for FY 6/2025, and it sounds like there's more potential upside once big contract passes regulatory clearance. Net cash has grown. I see this as an exciting growth share, and it's still reasonably priced.
Mincon (LON:MCON) - up 9% to 58.68p (£137m) - Trading Update (slightly ahead) - Graham - AMBER
Some reassurance for shareholders in this drilling engineer as the full-year EBITDA result is slightly ahead of previously downgraded expectations. Weak industry demand provides a challenge but the valuation here may already reflect the company’s difficulties. Worth a look.
PCI- PAL (LON:PCIP) - down 12% to 49p (£33m) - Trading Update - Paul - AMBER/GREEN
This seems an OK update, broker forecasts unchanged. Organic growth is continuing, and it's now reached breakeven after years of losses. I can't get excited about the growth potential, so am going with a lukewarm amber/green view. Patent case continues to be an expensive distraction, but seems to be going in PCIP's favour.
Mattioli Woods (LON:MTW) - down 1% to 581.5p (£302m) - Trading Update (in line) - Graham - AMBER
A solid update from this collection of financial advisory and wealth management businesses. The outlook for FY May 2024 remains in line and the company posts a small rate of organic growth, despite client assets shrinking slightly. Worth a place on the watchlist, in my view.
Paul’s Section:
Gaming Realms (LON:GMR) (Paul holds)
Down 2% y’day to 36.7p (£108m) - Trading Update [in line] - Paul - GREEN
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile focused gaming content, is delighted to announce its pre-close trading update for the full year to 31 December 2023 ("FY23").
“Slingo” is the key product, which is licensed by many online casinos.
Any doubts I had about the business model a few years ago have been dispelled by a highly impressive financial track record -
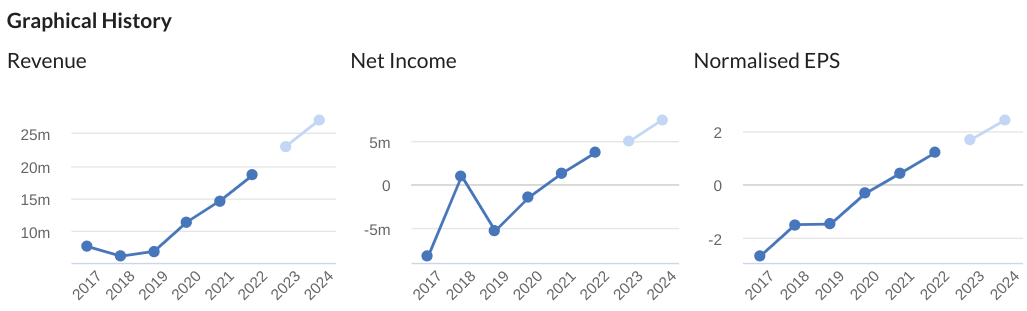
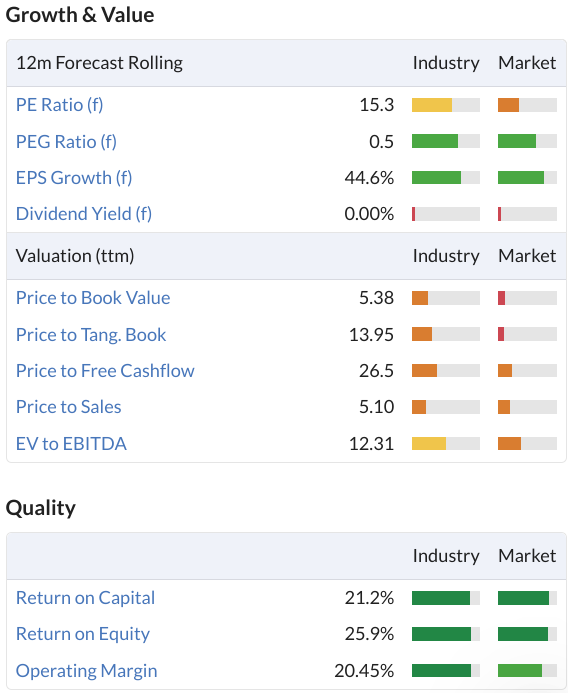
Despite this impressive record, and the high quality scores, GMR shares are on a modest PER for a growth share - scope for a re-rating, if growth continues maybe?
FY 12/2023 Trading Update -
Headlines -
Record Year
FY23 Record Revenue and adjusted EBITDA* with Growth of 23% and 28% respectively
The Company is pleased to confirm that it expects to report FY23 revenue of c.£23 million and adjusted EBITDA* of not less than £10.0 million, up 23% and 28% respectively year-on-year, in line with Board's expectations. The Company ended the year with £7.5 million of net cash.
It’s just not acceptable when companies only report EBITDA, and ignore all the other profit measures that investors need. So this is poor reporting from GMR.
Thankfully, Canaccord translates the numbers for us, and £10.0m adj EBITDA becomes adj PBT of £5.9m (2022: £3.5m) and adj EPS of 1.6p (2022: 1.2p).
At 36.7p, that gives a PER of 22.9x
Strong growth is forecast by Canaccord to 2.3p for FY 12/2024, a PER of 16.0x, so note that the lowish PER is dependent on a hefty increase in profits/EPS in 2024.
Balance sheet - I’ve checked the last one at June 2023, and it’s good. NTAV is only £8m, but its a capital-light business model with almost no fixed assets, and no inventories. Hence the NTAV is mostly receivables and cash, less a small amount of creditors. No issues here at all, it’s very healthy, and the cash pile has risen further to £7.5m at Dec 2023 year end.
Time to start paying divis, I’d say, as it has the capacity to do so, and it’s a cash generative business. There haven’t been any divis in the past.
Outlook - nothing specific, I think they’re just saying more of the same -
"The expansion into new territories and the addition of 44 new partners demonstrates our commitment to broadening our reach and enhancing player experiences. As we look ahead, we remain focused on delivering engaging content and expanding our footprint in key markets, ensuring that Gaming Realms continues to be a leader in the mobile gaming industry. We look forward to the future and the current year's performance with confidence."
Paul’s opinion - I turned positive on GMR in summer 2023, and it was a podcast mystery share in July 2023 at 31.7p, so usefully up since then. With decent growth in 2023 now under its belt, a good balance sheet, and a reasonable valuation, I continue to see this share positively, so it’s another GREEN from me.
Beeks Financial Cloud (LON:BKS) (Paul holds)
Up 34% to 145p at 09:24 ( £95m) - Significant Contract Wins & Trading Update - Paul - GREEN
Readers have been discussing the unusual volume of trades in BKS in the last few trading days. Today the Scottish-based cloud computing specialist (providing connectivity to financial exchanges) updates us positively.
I should say this is a personal portfolio holding of mine, and it was on my top 20 watchlist for 2024, because the outlook comments pointed towards accelerating growth. I looked through a modest miss against FY 6/2023 targets. The company has been telling us for a while that it’s got several slow gestation, but large contracts in its pipeline.
It sounds like some of the pipeline is turning into contracts now, and these are sticky recurring revenue type contracts remember, but which take a lot of time & effort to negotiate, winning the client’s trust. Beeks has a considerable moat I think.
06 February 2024 - Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce the signing of a multi-million-dollar, multi-year expansion contract for its Proximity Cloud offering, a new win with its Exchange Cloud Offering, and provide an update on a period of continued positive trading momentum in the six months to 31 December 2023 (H1 FY24).
This is very good news -
Having won a number of competitive tenders in H1 FY24, the Company now expects trading in FY25 to be significantly ahead of previous Board expectations for FY25.
Note that is jumping the current year FY 6/2024 and talking about the following year being “significantly ahead”.
Canaccord helps us out with an update note, many thanks. It leaves FY 6/2024 unchanged (Revs £30.0m, adj PBT £4.1m, adj EPS 5.6p).
FY 6/2025 forecasts are now: £39.6m revenue, £6.0m adj PBT, and 8.3p.
Put that on a PER of 20x (not particularly demanding given the strong growth), and I’m coming up with a share price of 166p, or 54% ahead of last night’s price. So BKS shareholders can confidently expect a bonanza I think, as the share price looks likely to put in a considerable upward move. I hope some members here have been patient, and not drifted away through boredom, which is a risk with this type of thing, where there can be long waits between important newsflow.
Exchange Cloud contract win - this is the largest type of contract that Beeks offers, with 2 existing clients. There’s a third one being added -
The Company is also delighted to announce the signing of a conditional contract with one of the largest exchange groups globally (the "Exchange") for its Exchange Cloud offering, a multi-home, fully configured and pre-installed physical trading environment fully optimised for global exchanges to offer cloud solutions to their end users. The deal marks the initial phase of an intended multi-year partnership between Beeks and the Exchange, and completion of the contract is subject to regulatory approval, following which deployment of services and recognition of revenue will commence.
This is the third major international exchange to sign up to the Exchange Cloud offering, demonstrating the significant potential for the offering. Beeks continues to see a building pipeline of opportunities across its Exchange Cloud offering.
Cash position - bears on this stock have criticised it in the past for being cash hungry, as often its contracts require up-front spending on cabling and servers. So it’s reassuring to hear that the cash position looks fine now -
In line with strategy, Beeks has achieved a positive free cash flow position in the period, with unaudited net cash increasing to £5.5m at 31 December 2023 (June 2023 net cash of £4.4m). The Board continues to be confident in achieving results for FY24 in line with its expectations.
Outlook - I’m confused by what this bit is saying - does this mean that there’s more to be added to forecasts from a “conditional” contract once it stops being conditional?
Having won a number of competitive tenders in recent months for projects commencing in the upcoming reporting period and excluding any contribution from the conditional Exchange Cloud contract, the Company now expects trading in FY25 to be significantly ahead of previous Board expectations.
Paul’s opinion - I need to properly digest all this information, but for now it seems clear that today sees a large increase in FY 6/2025 forecast revenue (upped from £34.6m to £39.6m), although a more modest increase in adj PBT (from £5.3m to £6.0m), so it sounds like there must be some additional costs too.
The £71m market cap is now obviously too low, so (writing this at 07:49) I imagine a considerable rise is on the cards, and people waiting for positive newsflow might find it difficult to buy in any decent size. Maybe a 30-50% share price rise today could be on the cards? We’ll soon find out, I like guessing just for fun!
CEO interview - I've fixed up an interview with the CEO of Beeks for my podcast channel early next week. So if anyone can think of any insightful questions, do leave a message below.
PCI- PAL (LON:PCIP)
Down 12% to 49p (£33m) - Trading Update - Paul - AMBER/GREEN
PCI-PAL PLC (AIM: PCIP), the global cloud provider of secure payment solutions for business communications, is pleased to announce a trading update for the six months to 31 December 2023 (the "Period" or "H1").
This sounds OK -
Revenue for H1 was in line with management expectations and up 20% year on year to £8.7 million (2022: £7.3 million). ARR at the Period end increased 23% year on year to £14.7 million (2022: £11.9 million), and as expected, H1 was the Group's first reported period of positive EBITDA since its re-launch as PCI Pal in 2016…
Since the Period end, sales have continued to grow strongly…
Cash is tight, but it has a borrowing facility available -
This continued sales momentum is driving the Group towards its profitability objectives. The Group finished H1 with net cash of £0.54 million (30 June 2023: £1.17 million), having paid out £1.1 million in costs relating to the patent case. The Company's debt facility is currently undrawn.
Strategic partnership with Zoom was announced in Nov 2023.
Patent case - was won in the UK (but Sycurio are appealing). US case set for Feb 2025.
The Board believes the risk of any material impact on the business because of the litigation has decreased substantially following its victory in the UK trial.
Paul’s opinion - it’s not obvious to me why the shares have dropped 12% this morning, on what seems an OK update.
Cavendish updates us (many thanks) and reiterates existing forecasts. These show nice revenue growth, and a breakeven adj PBT outcome of £0.1m for FY 6/2024. It feels like this has been a long slog to get to breakeven, after years of losses, but PCIP seems to have got there.
Cavendish has £1.0m adj PBT pencilled in for FY 6/2025. Not madly exciting, but hopefully there’s upside on that forecast.
I was amber/green last time, and that seems about right this time too. I like that PCIP is generating decent organic growth, and has now reached breakeven. Can the business scale up much more though? I’ve got some doubts there, it seems quite niche, and individual contracts are I believe quite small.
Hence overall I think it’s quite good, but doesn’t get me excited in the way that say BKS does (I hold), which I think has a much bigger market opportunity than PCIP.
The patent case has also been an expensive distraction.
AMBER/GREEN.
Graham’s Section:
Mincon (LON:MCON)
Share price: 58.68p (+9%)
Market cap: £137m
It’s a brief full-year trading update from this engineering group (focused on drilling tools).
We last covered the stock in October, when a profit warning was caused by weakness in the mining sector and the cancellation of some construction projects.
Today’s news is a little brighter:
Whilst market conditions continue to be challenging, as the mining and construction markets experience weaker demand, the Group's performance in Q4 was in line with expectations and we expect to achieve full-year EBITDA slightly ahead of the prior guidance of €20 million.
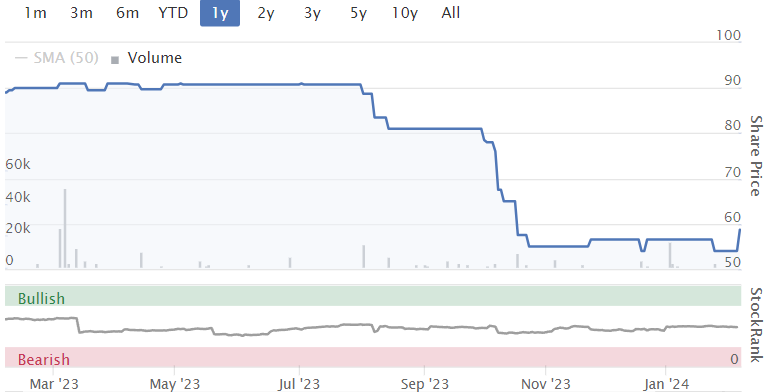
For context, the prior forecast was EBITDA of €28m, before this was downgraded to €20m in October. So the full-year result is still at a significant shortfall compared to where we were before the profit warning.
As previously mentioned, the company has reduced inventories and we should see a decent performance in terms of cash/debt (the company’s net debt was previously €15m).The low leverage multiple should, I think, provide a degree of comfort to investors.
Graham’s view
Not too much to chew on here; the key takeaway is that things didn’t get any worse since October.
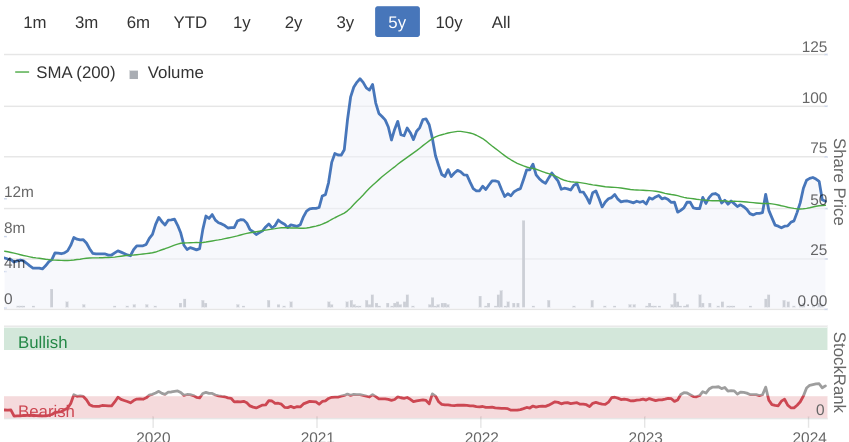
It’s probably fair that the shares continue to trade at a substantial discount to pre-October levels:
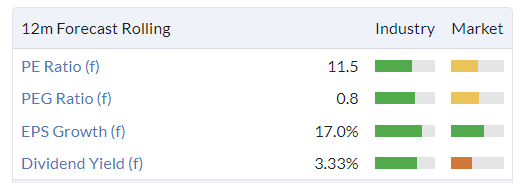
But that does mean we continue to have a cheap-ish multiple on offer here:
Last time I covered this one, I provided a list of the major difficulties faced by Mincon, and gave a view on whether or not they had been resolved. The remaining issues are:
Greenhammer - a hydraulic hammer system was supposed to be transformational for Mincon and for the mining industry, but it has run into complications. Not resolved yet.
Mining industry - weak industry demand continues to hold back revenues. Not resolved yet.
Balance sheet - the company is making progress on reducing debt. Partially resolved.
I remain neutral on this one, but I’d love to be able to take a more positive stance if news flow improves.
Mattioli Woods (LON:MTW)
Share price: 581.5p (-1%)
Market cap: £302m
Mattioli Woods plc (AIM: MTW.L), the specialist wealth and asset management business, today reports its interim results for the six months ended 30 November 2023.
We already covered the interim trading update from this company last month.
Organic growth is fairly slow at 4%; while recent events here haven’t been too exciting, the long-term picture shows great progress in revenues, with profits hopefully catching up soon.
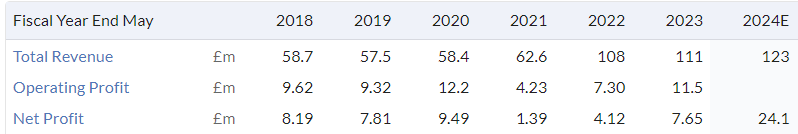
Declining client asset values have held back progress recently, but they remain substantial at £15.2 billion (only down 0.4%).
PBT for H1 comes in at £7.6m, with after-tax net income of £5.3m (H1 last year: PBT of £4.8m and after-tax net income of £3.0m). So profits are picking up even after all the costs that go with an acquisition-led strategy, e.g. £4m+ of amortisation was charged in H1 both this year and last year.
Dividend payouts keep steadily rising, with the latest interim dividend being 9p (last year: 8.8p).
The cash position supports this at £32.7m (equivalent to 72p per share).
Outlook remains in line with expectations.
CEO comment is happy with the performance:
"The first six months of this financial year saw the Group deliver improved organic growth despite the complex macroeconomic backdrop that persisted throughout the period. Our priority remains the delivery of profitable organic growth and we are pleased to report further progress towards our medium-term strategic goals, with revenue of £59.1m up 8% on the equivalent period last year (1H23: £54.9m) driven by positive performance across our pensions advice and administration, employee benefits and investment management operating segments".
Later in the report, the CEO reminds us that “we anticipate certain revenues will be more heavily weighted towards the second half reflecting increasing demand from clients for end of tax year advice, launch of new products and a higher proportion of pension client year-ends”.
The note from Singer observes that the company typically has a 45:55 weighting between H1 and H2, and they see a full-year adjusted PBT result of £33.9m.
On an unadjusted basis, perhaps we can see full-year PBT of £17-20m?
Graham’s view
This stock tends to fly under the radar but the track record is excellent and I think it deserves a little more attention.
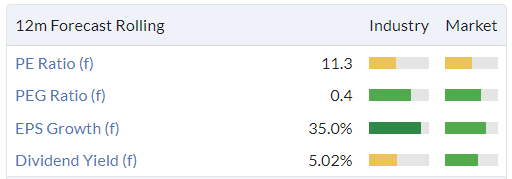
If you value it on the adjusted numbers it is currently offering value, but personally I like to see an attractive valuation even on unadjusted numbers before getting too keen on a stock.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

116 comments
Mattioli Woods (LON:MTW) - H1-24 showcases benefit of diverse income streams (new research report here: https://www.equitydevelopment...._)
H1-24 revenue (to 30 Nov 23) was up 8% y-o-y to £59.1m (H1-23: £54.9m), with 4% organic revenue growth. H2 revenue is typically higher than H1 due to end of tax-year advice and H2 bias of client year-ends, and we maintain our FY24 revenue forecast of £123.6m (+11% y-o-y). Adjusted EBITDA grew 10% from £15.0m to £16.5m with positive effects from organic growth (409 new clients, +13% over H1 23) and a changing revenue mix towards higher-yielding services.
The core pensions business was the standout performer with 21% revenue growth, driven by strong demand for advice and increased banking margin on cash balances.
MW has a strong net cash position of £32.7m, after paying £9.3m of dividends and £6.2m of acquisition-related payments. MW has no debt. Management maintains a confident outlook, with the interim dividend up from 8.8p to 9.0p.
Our revenue forecasts are unchanged with adjusted EBITDA forecasts down slightly due to lower Amati profits but statutory profits increase on higher net finance income. Our fundamental valuation remains unchanged at 900p per share (53% above the current share price). With powerful longer-term structural tailwinds supporting the wealth management sector (see page 16), we think a sector-median PER of 15.7 is too low. Moreover, with MW being so well positioned (page 17), we find it strange it’s PER of 12.3 is below this median. We see potential for a re-rating.
Volume leaders today-
Volume leaders today-
I've been buying Tritax EuroBox (LON:EBOX) these last three days - so the other orders must all be sells!!
I love the SCVR and all the comments. I learn so much from both. Even the derogatory comments make me think. They may be hurtful, hopefully not intentionally so, they still make me ponder.
I hold Plexus Holdings (LON:POS) like many on here. I've been looking at how they made their money in the past when they were making money. It looks to me like it came from the jack up rig wellhead rental with their POS GRIP technology. Unfortunately, they came out of this market, I think to spend more time on r and d for further uses for their POS GRIP technology. Now, thankfully Plexus Holdings (LON:POS) are back in this jack up rig wellhead market with their POS GRIP technology.
I know Plexus Holdings (LON:POS) isn't on the agenda today. I thought I would mention this, in case, there were any more points. Plexus Holdings (LON:POS) jack up rig wellhead rental with POS GRIP looks like it's cheaper and needs less time than conventional wellheads. I'm no expert, so hopefully, this will prove fruitful for them and for scalability too.
All comments appreciated.
I've forgotten what symbol to use to get the link in my comment here to £plexus. Please remind me.
The @ symbol does it. Plexus Holdings (LON:POS)
Thank you so much tic
Plexus Holdings (LON:POS) have been talking about returning to the jack-up market for years
https://www.rogtecmagazine.com... hopefully this time they really are
From the Plexus Holdings (LON:POS) RNS released on 24 January 2024:-
"Importantly, the Licence Agreement enables Plexus to continue to operate in the licenced surface production wellhead market in a material way, which provides the Company with the opportunity to exceed its historical revenues from this category of wellhead business. The Licence Agreement fee provides Plexus with a US$5.2m cash lump sum, which will be used in part to build new inventory for the Company's historical core jack up exploration rental wellhead and associated mudline hanger sales business, which is a sector Plexus has re-entered in co-operation with SLB."
And, from the Plexus Holdings (LON:POS) RNS released on 22 December 2023:-
"Looking ahead, there is good momentum in the business going into the new calendar year and our outlook is positive with a number of positive tender opportunities underway in relation to our recently re-entered wellhead rental for exploration drilling from Jack-up rigs. With this background, the Board continues to have the utmost confidence in Plexus and the role it can play in support emissions reduction and decarbonising strategies. "
This is about Plexus Holdings (LON:POS) returning to the jack up rig wellhead market using their POS GRIP technology and having the cash to do it.
Thanks…I’ve read those RNS’s…my point was that they should be interpreted through the lens of what they’ve said & done previously. ..they’ve now got a modest amount of money whereas previously they were near bankrupt ..I’m not sure where it goes from here but it’s certainly dependent on a lot of good stuff happening in terms of orders …otherwise all the £ get hoovered up by the cost base of the business…including some frankly indefensible director remuneration (imho)
Understood rhombold1 and thank you for your input.
I agree it all depends on orders.
The fact they've gone back into the jackup rig wellhead market with their POS GRIP Technology which is cheaper and much more time saving than conventional wellheads bodes well for future orders.
Unless Plexus Holdings (LON:POS) revenues increase enormously this is still massively overvalued. It is now just a rental business and should be valued accordingly (TBV). However it seems that the company will not require additional funding.
All the best to current holders.
Thank you yiannos1.
From Plexus Holdings (LON:POS) past accounts, they made most of their money and profit from their rental business in jack up rig wellheads with POS GRIP Technology.
It looks like a lucrative market.
Plexus Holdings (LON:POS)
It’s pretty obvious that a case for decent potential income here for this company - if the company has prospects of real tangible income and real tangible profits these really need to be communicated to the market - in the absence of any real evidence of this are investors note implying relying on hope rather than real expectation - when have investors been lead to belief the company will start to deliver ? Obviously part 1 of plan to improve balance sheet is done but I see no investment case without promise of real income and profits from here - in that regard perhaps we have to wait for material contracts to start getting signed ? If the company expects these to arrive these could be added to forecasts bible imho.
Thanks to those who responded to my post today on Serica Energy (LON:SQZ)
On Production Guidance for 2024 of 41k to 48k boe/day this compares to 40k for 2023. If 48k was achieved that is a 20% increase which would surely be a good result. Only time will tell.
Cash at 31 August 2023 was £333m. Capital Expenditure in 2024 on New Wells at £210m is surely going to see a big increase in Revenue in the second half of the year.
Thank you Ken Mitchell for your post which was very interesting in as much that FOMO affected your decision to buy back after selling. SP up 7.7p today.
4Basebio (LON:4BB) has not attracted any comment recently despite a 40% climb in the share price over the past three months and a significant amount of notifiable share movement. It briefly had a place in PI minds a couple of years ago (I believe Leon Boros was prominent holder). Does anyone follow the inside story of this stock?
The jam appears to be a couple of years away but it looks like the majority German holder is likely to be the determinant of its future. It would seem likely that a takeover will have this company disappear before PIs have a chance to benefit
Hi - I generally never comment on 4Basebio (LON:4BB) as it is very illiquid with just a few hundred shares often moving the MM price, but admit I own from 200p
If you talk to management they think the value of the business is far below the value ascribed by the market. Talking ones own book we might reasonably suppose but they have credibility, having built and sold a not dissimilar previous business, and there are some Private Equity deals in the same space that suggest they are right. They are funded, originally by cash injection following de-merger, but now by debt from the de-merged entity. This facility was agreed at the time. I think the directors would prefer to raise some equity and increase liquidity but have previously said not at this price level. Ultimately my take is the IPR of their synthetic DNA and manufacture process is a game changer in the industry but I don’t know what the timeline is on that. I suspect you may be right and an offer comes our way at some point but I’d anticipate that is north of 1000p as management own a decent chunk and will want a good cash element.
Has it ever been 200p? 4Basebio (LON:4BB)
Maybe something around listing on uk or prior to uk
Yeah when it was de-merged mojo it came on at 180p or 185p I think. I tried to buy 4 times the amount I got but they wanted 50p above the price and I was reluctant at the time so settled for 1/4 of the amount I wanted at 200p. In hindsight I should have paid up but a 25% mark up seemed steep…….doh!!
There were no trades at 200p on first day of dealing mojo, a few tiny trades at 205p but thats as low as it got.
Palace Capital (LON:PCA) - Might be worth keeping an eye out on one of Simon Thompson's favourites. That's a £1mn buy. Offer price is now 208p+ .
IMO, PCA could be included in Simon Thompson's Bargain Shares 2024.
Palace Capital (LON:PCA) - looks like a £1 mn sell to me.
I bought at 202.49p very near to it. So either a discounted block price or yes, a sell.
Maybe it's both!
Palace Capital (LON:PCA)
I hold.
I have been scratching my head regarding the recent share price decline and keep asking myself have I missed something. The share price action is totally out of kilter with the current know facts.
At the risk of having egg on my face I have concluded that the share price and thus the market is wrong.
The following is an extract from my post of 23rd September last when the share price was 229p.
On the basis of what is know and the recent RNS announcements, I would be happy to add to my existing position. It does seem a bit of a no brainer:
Since then the company has:
4 December General meeting : Obtained share holder approval to buy back a further 15% of its shares
Extract from the Interims 15 November:
Peter Gyllenhammer has also increased is stake to north of 13%.
Shoot the messenger
Simon Thompson- you just put me off !. I have held this for several years and am confident will see an announcement soon- from them "Thank you for your email. We do not have a date determined as yet, but expect to announce by 31 March."
Card Factory (LON:CARD) is testing its October low of 90p. From what I can tell this seems a really good entry point. The investment case seems significantly stronger than it was in October
1. Tellios have stopped selling.
2. Those who bought on hype or who followed CR are long gone.
3. The trading statement showed it is likely to be at the top end of market expectations, SP is down nearly 20% since that statement was released.
4. Stockrank of 98
The big downside that keeps getting brought up is the increase in wages in April. Whilst I am not discounting its impact, this will also impact a number of other retail companies who are not seeing their SPs at October lows as a result.
I have a decent sized holding and am currently sitting on a slight loss, so maybe my glass is half full as I hold a positive bias. I didn't want to sit and write a lengthy bull case for a stock many of us already know well. Despite this, I just can't see any reason for the SP to drop further from here. Does anyone have any indication of what I could be missing, are there reasons for a further decline that I am not seeing?
Cheers, BenHazz
Card Factory (LON:CARD) Regarding the minimum wage, if you look at their job openings they already pay above the current minimum wage for a number of positions. So they won't necessarily get hit by the full impact of the minimum wage increase, depending on if they want to pay above or at the minimum wage.
You also have to factor in that higher wages will mean consumers have more money to spend. Card Factory (LON:CARD) should also have some ability to pass on higher costs through modest price increases.
Certainly hope all the CR sheep have now moved on. Need to be careful holding anything that CR has previously pumped up as it will be full of short-term speculative traders who will rush for the exit once they think it's lost momentum.
Sorry what is CR?
https://x.com/rebelhq?s=21&t=I...
I assume you mean Cockney Rebel
As Tic Tac and Threepeat have confirmed, CR, I was referring to Cockney Rebel. He had Card Factory (LON:CARD) nearly a 1/3 of his whole portfolio at one stage and is a much followed (and copied) investor. He sold out just prior to results.
Re Card Factory (LON:CARD) - the negative story on min. wage is that everyone protects their differentials - so just above minimum wage people will demand a similar rise or go elsewhere. (although personally I am in the optimistic camp here as I think their customer base will gain and spend more so it will be a net win.
Re Card Factory (LON:CARD)
Hi Ben
How can you be sure Teleios Capital Partners have stopped selling?
Hi Norfolk, it is my understanding that as their position size is still large at the last RNS (11.7% of the company), they would be obliged to inform the market if there was a 1% drop in their overall holding.
"The thresholds for disclosure for UK issuers are 3% and every percentage point thereafter" - FCA
They last informed the marked on Sep 29th. So since Sep 29th, that would imply that any sales they have made have equated to less than 1% on the total shares in issue.
If my understanding is wrong here happy to be corrected by someone more knowledgeable!
Ok that sounds fair enough Ben!
Quick look at the chart and the price is below the 100day moving average, price has also gone sideways for 3 years and it dropped on what looked like positive results. All massive negatives for me.
I am very suspicious of the SP of Serica Energy (LON:SQZ) given yesterdays drop of 11% giving a closing price of 178p. What is going on?
At 24p Dividend this gives a yield of 13.5% valuing the shares at less than 2x free cash flow.
John Rosier last September said the shares were "bonkers" cheap when the SP was 226p.
Is this the market makers driving down the price to pick up shares on the cheap from weak holders? I hold. Any views from experts in Oil & Gas please?
I read more than I remember, but one annual report I read from a fund manager spoke about Diversified Energy (LON:DEC) and how UK reporting requirements meant that it could never get a proper valuation in the UK. I think it is all related to TCFD reporting, which makes manages have to report on how their underlying investments are from a climate/net-zero perspective. As a result, many are finding it simpler to sell than to explain. Coupled with ESG and the general move away from the UK market, there are few buyers around for shares in any UK companies, let alone ones with other obstacles in the way. All down to supply and demand.
https://kpmg.com/xx/en/home/in...
Diversified Energy (LON:DEC) is not like any other oil company and it is my humble opinion that it will lose almost all its value. You have to study in detail exactly what they do and the cost of these wells when it is time to shut them down. Current cash flows do not cover these costs; simply at some point in the future the price will be worthless.
I didn't think it was specific to DEC, I just got the feeling that holding O&G stocks was more hassle than it is worth for some managers, and given that marginal buyers and sellers set the price of shares, that might explain why so many O&G stocks look absurdly cheap.
ETF’s have grown so big that they are not interested in small caps in general ; even if they go up the gain for them is minimal and difficult to exit-it’s all about asset allocation and small caps limited liquidity.
However this provides the small cap value investor with unbelievable opportunities.
I think Diversified Energy (LON:DEC) is interesting because it is onshore US where there is a more benign attitude to O&G than in Europe/UK, and decommission costs are much lower onshore than offshore. The US government is concerned about energy security and DEC must be an important part of that. DEC have around 70,000 onshore wells across the US and these all have different productive lifespans, which makes it hard to understand when the wells actually have to be decommissioned. DEC's current commitment is to retire 200 wells per year using 15 crews (these crews also do third party work for the state or other operators - total capacity 450 wells, cost per well $21k) . The volume of trade on the NYSE is increasing and there could easily be a situation soon where more shares are traded in the US than the UK. DEC generates huge cashflows (mostly natural gas production) but a lot is being paid out as dividends at the moment. I think the company will reduce the dividend in order to fund more share buy backs (than currently the case) and to make new investments. Was Rusty Hudson hinting at this in his interview on Proactive 01/02/24? Dividend payments are forecast to be 43% of EBITDA in 2024 (Dowgate) which is not sustainable. Brokers are still forecasting a share price price target of over £25. If the dividend and share count are reduced, and DEC announces new asset purchases then the share price might start heading towards the broker targets. Obviously the O&G sector is rather unpopular at the moment, as D.P. says many fund managers don't want to get involved at the moment.
Hi spglet
I believe that things are not exactly how you state them here. It is my opinion that you have to look at the fair value of these assets and how much they charge the income statement. Then you have to look at what exactly is their liability on the day they are ceased.
Personal opinions after hours of research but Diversified Energy (LON:DEC) seems to be a rather risky investment (unless you are a short seller).
Although I have mentioned it many times-Just for clarity I never short stocks.
Thanks Yiannos for your reply. It's not easy to see what the liability is for any particular asset on the day it ceases to be productive. DEC present data at a asset-base level. We know from the FY22 Consolidated Statement that non-current assets are $M 3476 and non-current liabilities are $M 2837. I guess your point is there's not a huge margin between them?
The Income Statement for FY22 shows a gain for (natural gas and oil) property and equipment at $M 237.9 and an additional gain for assets bought below fair value, which is $M 444.7. Over the longer term, there must be decay in the way you describe. They present an asset-base lifecycle that spans 50 years, and I'd imagine the business will decline in the last 25 years.
Exactly as you have mentioned , but the reality is that they will last only until 2040 (maximum) and their costs will be more than their cash flows (even if you do not count the supposedly dividend payments!).
All the best
Good, I understand your points. All the best too.
I can't get my head around the numbers. In order for the SP to rise it is suggested that DEC announce further acquisitions. Over the next couple of decades let's say they get another 5000 donkeys to add to their existing 70000 = 75000. Even if the co. does manage to last 50 years the current rate of decommissioning would have to increase over 7 fold. If it continued decommissioning at only 200 per year it would take 375 years to decommission 75000 units. Being very generous and assuming it could afford these charges over its entire life (50yrs) it would need to decommission 1500 units per annum. Of course as time goes on the reserves will become depleted and income will subside considerably - thus making the decommissioning charges an ever bigger drag on finances and ultimately unaffordable. Unless they aquire yet more units but then that adds to the number that will need to be decommissioned and so and so on. I just can't see how the decommissioning expenses will not cripple DEC and this is being recognised at Gov.t level.
In the meantime they continue to pay massive dividends and are buying back shares. A number of fund managers have increased holdings (M&G reduced but I suspect they need to sell stuff for redemptions) as have a number of directors (and for what it's worth - me).
Roger. Fund managers buying? I've had a scan through RNSs for changes of holdings in co. and other than the M&G notifications all I can find is notices of reduced holdings - that is throughout 2023. Can you point me to a source of info showing the opposite? I rely on Stocko and Sharepad for this info, but readily admit that neither seems great at showing such holdings, particularly for DEC.
Blackrock have just annouced holding a sizable stake, 5.5%. So might be wrong there yiannoso1. Hold likes of Smiths News (LON:SNWS) to offset risk.
If you are referring to Diversified Energy (LON:DEC) I am definitely not wrong. You forgot to mention the share.
Can’t remember where I have read this recently but the headline was how Blackrock lost $1.7 trillion of clients money in 6 months.
All the best
Interesting comment: why are you dissatisfied with the liability for well closing in the accounts? They appear to allow for the costs at current cost plus inflation and discount with interest. They also show how the liability would change under different assumptions. What i am not sure about is how they deal with the uncerainty around the life of the well.
If we look at what the UK gas price has done over the past few months, could it explain why the share price has also drifted down/collapsed? How about the 30% divi on offer from DEC? Perhaps the market thinks that these dividends are too good to be true.
portugull
The shares fell yesterday after this underwhelming production update with production lower than expected and a largely unexplained reduction in the cash pile which perhaps increases the chance of the very big dividend being cut.
https://www.stockopedia.com/sh...
This disappointing update follows the recent news that C/E Mitch Flegg was standing down. Was he pushed? Was the Tailwind acquisition transformational? Jury still out on that. Are there now doubts about that very big dividend being maintained?
I sold early yesterday on my always sell on bad news rule but had second thoughts today and bought some back at a slightly lower price. Why? Serica Energy (LON:SQZ) does look very cheap. Could a bidder be tempted? If the dividend is maintained that’s a yield of around 14%. Was the share price fall yesterday on top of fall from over £4 overdone? Is SQZ now oversold? Enough questions to make fomo the main reason for reversing my sell decision.
Just a personal observation from about 30 years of working , trading , and investing in the stock markets-Increased volume means volatility and does not mean the share price will increase. I can give you so many examples (from only the start of the year) that this increased volume was followed by a substantial decrease of the stock price!
Hi Paul, thanks for covering Gaming Realms (LON:GMR), such a sparse update I've been waiting for your insights. I read it through once and thought Paul's not going to be happy with this. Hoping for more detail and maybe an investor presentation in April, but I continue to happily hold.
Amazon strikes ad data deal with Reach (LON:RCH) as Google kills off cookies
Media sector scrambles to deal with fallout from phase out of cross-website trackers
Tech giant Amazon has struck a deal with the UK’s largest publisher Reach over obtaining customer data to target online advertising, as the media industry scrambles to respond to Google’s move to axe “cookies”.
https://archive.is/TFJeV
As I've said before publishers like Reach & Future (LON:FUTR) are hording enormous amount of user data which is going to be very lucrative in the post cookie era imo.
EParo Thanks for posting this. I dont know enough about this business to understand the difference in revenue and profitability to a publisher in using cookies vs selling data to the likes of Amazon. The Reach (LON:RCH) share price reaction is muted. Appreciate, your insight.
It will but they just need to start demonstrating it which both have failed to achieve so far. I agree that Reach (LON:RCH) looks far too cheap on a PER of 2 though irrespective of pension. At some point in next few years those contributions will disappear and there will be a cash cow for much longer than the market is crediting it for. Should be worth at least double I’d say in my view.
However, as a play on the cookie killer Silver Bullet Data Services (LON:SBDS) looks extremely well placed with their 4D product. I bought some around 200p previously and (a) stupidly didn’t sell all the way to 20p despite reservations and then even more stupidly (b) didn’t buy at 20p when I spotted well before the market that the company was effectively hitting cash profitability but was valued at a mere £2m market cap. Far from my finest hour on either point - could have been a massively lucrative trade for me and I still anticipate it will do very well from here but I missed out on what is already almost a 10 bagger and what I think could be a 30 bagger or more. Talk about kicking myself !!!
I bought Silver Bullet Data Services (LON:SBDS) after the last fund raise, since when the price has pushed up quite a bit.
Their 4D AI product has just partnered with OpenX, who receive 365 billion ad requests a day!!
https://www.linkedin.com/posts...
US media giant Omnicom's (NYQ:OMC) media division is also using 4D AI. That's a big endorsement for a small company like Silver Bullet Data Services (LON:SBDS)
As you say it's a cookie killer play which may multiply many times over if they get a slice of this huge market.
Ken Wotton from Gresham House discusses Silver Bullet Data Services (LON:SBDS) here at 22:15 -
I've been adding Reach (LON:RCH) too.
Reach (LON:RCH)
At some point in next few years those contributions will disappear
Do you have any factual basis from presuming this is the case other than hope?
these shcemes often let companies do just enough to keep in credit that doesnt mean they arent on then hook for huge potential payments later.
At £1.8 billion of scheme liabilities of which £1.6 bill is uninsured (per last annual report 2022) - i would say unless they have given complete clarity its not going to be the case i would be presuming this could still be potential noose around their neck that could strangle them at some point in the future.
Apologies if they have offloaded scheme to external provider and now dont have that problem - when checking i tend to go to last annual report published.
Beeks Financial Cloud (LON:BKS) In answer to your question Paul I believe that’s exactly what it means. The very large contingent Exchange contract has had no forecasts against it and will start to come in only once finalised. Remember that with these types of deals the exchange offers the service to their customers so you suddenly have a very large distribution channel direct to your target market hence they won’t start to forecast those wins until the Exchange deal completes.
Very sticky financial services revenue businesses like these trade on a big multiples historically. 20* would be low - often more like 30-40. So we can see how there is not only a growing (and now cash generative) business in play but there is also a multiple expansion opportunity. I can see a case for 300p over the next year or so if momentum continues (30* 10p eps) but I can also see considerable upside to the 10p eps.
I’d be surprised if they last too long though - current valuation is far too cheap not to attract bidders imo so then we have to see how strong the board really are in negotiations. I hope they take a good advisor if it happens and don’t give things away on the cheap. Anyway pure conjecture on my part.
I hold of course so talking own book but this was really the news I was waiting for. The inflexion point.
Expert post as usual davidjhill. I think Stocko may be looking for someone to assist Paul & Graham writing the SCVR and think you would be perfect for the roll.
"Regulatory approval" is the fly in the ointment in this good announcement from Beeks Financial Cloud (LON:BKS)
As with all things Financial Services, when it comes to Regulatory Approval, timelines may be very long.... especially for novel solutions like Beeks'.
Especially if there's an incumbent tech provider (maybe not providing the same service, but will lose out financially to Beek's Exchange Cloud once live) who will be raising plenty of objections.
Smart of Beeks not to count this chick before it hatches, in its outlook guidance.
Different type of regulatory approval Boon - not one where other tech providers get the chance to object.
It will be around demonstration of resilience - likely timeline in those types of approvals 6-9 months. I presume they are some way through that but they don’t give details.
Supreme (LON:SUP) plc
("Supreme" or the "Company" or the "Group")
Commencement of Share Buyback Programme
Further to its announcement of 29 January 2024, Supreme PLC (AIM: SUP), a leading manufacturer, supplier, and brand owner of fast-moving consumer goods, announces the commencement of an up to £1.0 million share buyback programme ("Share Buyback") of ordinary shares of £0.10 each in the capital of the Company ("Shares").
The Board considers that the Group's strong balance sheet and cash generation provides an opportunity to repurchase shares at attractive levels, taking advantage of current market conditions. This initiative reflects the Board's confidence in the Group's future value and dedication to enhancing shareholder returns, alongside its continued investment in the Group's strategy. There will be no change to the Company's existing dividend policy.
Morning Paul.
Many thanks for the write up on Beeks Financial Cloud (LON:BKS). I've held for a while now and have been averaging down on weakness. This was a company that I flagged as a multi bagger and my hope is that this type of announcement is the first of many.
Cheers Andy
Obviously i held some via spreadbet for some 16mths that got closed a week ago at 98p....
But do also have in sipp thankfully
What was the interest cost on holding it on a spreadbet and did they close it or you?
I have held for a while too Andy, but rather than averaging down I topped up at 165p, 2 years ago!
React (LON:REAT) The adjusted EPS number includes adding back a significant charge for depreciation and amortisation of £1.8m, which not surprisingly flatters the EPS figure.
Does anyone know if that's normal? Both are regular charges, so that doesn't look right to me
It is increasingly normal but that doesn't mean that it's right.
Note e.g. the trading statement by Next PLC on 04 January
"For clarity, we will not be joining the companies that quote 'EBITDA' as a key measure of success. Capital spent on assets or technology that decline in value, and ultimately require replacement, must be accounted for in any reasonable assessment of financial performance."
And here is Warren Buffett on EBITDA (earnings before Interest, Tax, Depreciation and Amortisation
Re React (LON:REAT)
Normal. Reflects two relatively large acquisitions in last few years and the associated costs (amortising acquired intangibles like customer lists). Up to you how you view this and what ‘true value’ is. There are also fairly chunky earnout payments thro cash flow. Group says these are over by June 24 and post that adj ebitda and PBT coalesce
I see just before I posted I see a comment from Wol. If that is your chosen perspective then its correct...although I would suggest it means investing in earlier stage and small growth companies is not an area you want to focus on so much. With regard to smaller and high growth companies ebitda shows where earnings level could be 'normalised'...although that requires judgement on whether capital is used well or poorly.
A calvinistic view of value and earnings would make few small growth companies attractive...so pick your poison!
Thanks for the replies Wol and mojomogoz
In this case , there is further investment required, as they say in the outlook statement '... Investment in infrastructure to leverage efficiency-enhancing technology across the Group' ... 'The Group will therefore implement a considered programme of investment in people, processes and systems'
I seem to remember at a presentation that they said that the Laddersfree business had little IT and so this extra investment isn't a surprise.
They go onto say ;... The Group is currently engaged with a third-party software solution provider to design, build and deploy a new operating system for LaddersFree. Once operational, the investment will be recorded as a fixed asset and amortised over a three-year period.'
No figures are given but this must be a reasonably substantial investment for the group to develop the business, the cost of which will hold back profitability this year and maybe next as well,
It also shows that the development of acquired businesses has to be taken into account and to my mind shows the danger of treating amortisation and depreciation as 'one-offs', although I do understand your point mojomogoz
React
Looks ok to me but it’s all a bit hard work to really drill into with recent acquisitions .
Have to comfort myself that Christopher Mills and his Onyx have increased to 9%.
Too complicated to build a bigger holding until brain freeze factor is removed .
My morning smallcap tweet: From boom to boom
Filtronic (LON:FTC) Beeks Financial Cloud (LON:BKS) Fusion Antibodies (LON:FAB) Windar Photonics (LON:WPHO) Eckoh (LON:ECK) Novacyt SA (LON:NCYT) Mincon (LON:MCON) Roquefort Therapeutics (LON:ROQ) MicroSalt (LON:SALT) Quadrise (LON:QED) Live (LON:LVCG) React (LON:REAT), Biome Technologies (LON:BIOM), PCI- PAL (LON:PCIP), Discoverie (LON:DSCV), Alumasc (LON:ALU), Mattioli Woods (LON:MTW)
◄Filtronic (FTC)► yet another contract win: £7.8m follow-on production order and a payload development contract. To be recognised in calendar year 2024, [SP=25.85 Cap=56m]
◄Beeks Financial Cloud (BKS)► wins $2.3m Proximity Cloud expansion contract. Also Exchange Cloud contract (no £££). Guides FY24 in line and FY25 significantly ahead. Pre-RNS system working for some with SP up 11% yesterday! [SP=96.5 Cap=63m]
◄Fusion Antibodies (FAB)► wins $650k 1 year follow-on project with a US based biotechnology co. CEO trills "It is always thrilling and satisfying to share in our clients' successes." [SP=4.97 Cap=3m]
◄Windar Photonics (WPHO)► wins €1.3m of orders for delivery in 2024. Also a sales agency agreement with AC883 Nordic Trade Services, an established operator in the North American Wind Turbine sector. [SP=35.15 Cap=24m]
◄Eckoh (ECK)► strong levels of contract wins has continued in H2 with over £20m of contracted business closed since 1 Oct. Underpins growth expectations for the next FY. [SP=43.4 Cap=126m]
◄Novacyt (NCYT)► sale of Novacyt Taiwan falls through. The divestment is not material. Co "will continue to evaluate a number of options in relation to the future of the Taiwanese laboratory business." [SP=49.44 Cap=41m]
◄Mincon (MCON)► guides FY-Dec rev in line. EBITDA slightly ahead of guidance of €20m. [SP=50 Cap=137m]
◄Roquefort Therapeutics (ROQ)► update on its pre-clinical drug development programs, Randox licencing agreement and out-licencing discussions. [SP=5.9 Cap=8m]
◄MicroSalt (SALT)► announces its first strategy objectives. Didn't it have those in its IPO doc last month? Nearer term profitable growth will primarily be driven by B2B. "Early-stage discussions with three of the largest UK supermarkets to use MicroSalt technology in their own-label products, as well as suppliers of ready-meals and a fast food burger company." [SP=70 Cap=NA]
◄Quadrise (QED)► Collaboration Agreement with Cargill for trials of MSAR and bioMSAR fuels. [SP=2.09 Cap=33m]
◄Live Company (LVCG)► gets FY22 and H1-Dec results out at last. "Will remain suspended until it concludes its refinancing arrangements, including the previously announced placing, following which it will clarify its financial position and seek a resoration [sic] of trading." [SP=2.08 Cap=5m]
◄React (REAT)► FY-Sep. "Momentum from FY23 has continued into the new financial year, and despite the usual slow down across the festive period, the first few months of FY24 have delivered a record trading performance for the Group." [SP=1.35 Cap=14m]
In line: BIOM, PCIP, DSCV, ALU, MTW
Sanderson Design (LON:SDG) Unusually high volume yesterday afternoon: London Stock Exchange 2,232,697 (3.8% of free float) and Stocko 1,031,073 versus average volume 86,109.
Golden crosses made around 7 January.
Mulberry (LON:MUL) Superdry (LON:SDRY) Sanderson Design (LON:SDG) Beeks Financial Cloud (LON:BKS) Speedy Hire (LON:SDY) . Are the ones which stand out last couple of days
And Ricardo (LON:RCDO) today
Beeks Financial Cloud (LON:BKS) Significant Contract Wins and Trading Update - all as suspected and discussed yesterday and in previous days and thanks again to those on this board highlighting to us here the sudden increase in buying recently ahead of today's announcement.
Insider trading apparently alive and well or is that someone just has a fully functioning crystal ball? (I hold)
Maybe there's more alerts we could all setup looking at recent volume increases in small caps? Any ideas for best sites for this with configurable settings. Definitely looks like insiders trading this one
Thankfully volume is one of the few things that's near impossible to hide.
Wolfie - you did say before but I can't find the post - how do you follow these volume spikes? Thanks, doctor dave
Sharepad. You could add each company manually into advfn or IG etc. sharepad filters everything automatically
Ok thanks Wolf .... will take a look
Keep the volume flags coming Wolf on anything that looks of interest, thanks Andy
The spirit of Clarence Beeks alive and well!
Randolph and Mortimer would be proud.
My fave christmas film shame they never made a follow up.
Really good update from Beeks Financial Cloud (LON:BKS) . These types of businesses providing long term land and expand services to the financial industry tend to trade at 30-40* so a fwd PER of 14 suggest they can more than double on existing estimates. If momentum continues I’d bet on them getting taken out. They will fit one of the other providers strategy.
I wrote a separate thread on Filtronic (LON:FTC) suggesting their results would start pointing the way to a much improved future, and so they do. Very much inline, but talk of profits being "materially ahead" in 24 and 25. Clearly a company on the cusp of a step change.
But perhaps the biggest news was a new contract win for £7.8m, alongside a development agreement with the same customer that is unquantified. This for a company that just announced £8.5m revenue for the whole of H1. The future looks very bright.
But so does the valuation of Filtronic (LON:FTC) look equally punchy.
What profit and cash flow is expected to start to come through? Needs a big jump to justify current valuation. Not saying that won’t or can’t happen but I haven’t seen any forecasts that suggest it yet. Need to be seeing £3m PAT really and yet it is still loss making in H1. If anyone can tell me where they think the company will reach over 1-2 years I’d be appreciative as whilst I like the tech I am struggling to get my head around the valuation.
Amazon.com (NSQ:AMZN) didn't make much money for a while, but their USP rocketed the company. In this instance Filtronic (LON:FTC) IP happens to be much harder to create as per a friend of mine who worked in the semi-conductor industry has done the hard miles now ands should be set to be rewarded. I must admit, the tech stuff I leave to people who have bigger brains than me. I hold and Beeks Financial Cloud (LON:BKS) too which are both my largest positions in my ISA so hoping for a good day today.
Last July saw a step change in activity as I’ve set out on the Filtronic thread. Contracts went from being in the £350-500k area to £2m+ and have been growing strongly in frequency and size since. £25m of new contracts announced in 7 months, for a business that did £8.4m in H1. That is exponential growth. Minervini would tell you to ignore valuation when faced with such growth. The company has a history of over promising so I think the newish management wants to surprise to the upside. But if you wait for everything to be clear it will all be in the price.
Filtronic (LON:FTC) is not Apple (NSQ:AAPL) -you cannot ignore the valuation and you have to see the balance sheet/cash flow statement in order to see what exactly these contracts mean and their profit margins and make a valid investment decision.
yiannos1 - I agree, it is not an Apple (NSQ:AAPL), However, it might be like NVIDIA (NSQ:NVDA) was 10 years ago? Who knows, I don't have a crystal ball but I think tech companies will do well this year - and it's been stated before UK equities are ripe for taking out. I hold these alongside some boring plays like Smiths News (LON:SNWS) and Shoe Zone (LON:SHOE) for balance and divis. If one of the tech companies I hold becomes a multibagger then it's all good (looking like Filtronic (LON:FTC) has doubled my investment in a matter of months.)
>However, it might be like NVIDIA (NSQ:NVDA) was 10 years ago?
Unless a new world-changing use is found for RF antennas and amplifiers that Filtronic (LON:FTC) has a huge lead on, then no. This has happen to NVIDIA twice and it's a 173 bagger over 10 years.
That is one way to approach it. But Filtronic (LON:FTC) began announcing these much bigger contracts when the SP was 12/13p and they said they would be delivered in 12/18 months time. Now the SP is 29p and the contracts are getting bigger and more frequent and the company has said turnover for the next 2 years will be ahead and profit materially ahead. It is quite conceivable that in 6 months time the result will only be beginning to show the impact of the new contracts. By then I expect more contracts will have been announced and the SP likely 40/50p. By the time the market gets the information you want in order to make a valuation based investment decision I imagine Filtronic will have been acquired by someone
Nice speculative story and if it works for you then stick to it. I prefer to have actual numbers and profit margins in front of me and make my investment decision.
But I come back to valuation on Filtronic (LON:FTC) - I understand the excitement factor but what does it ultimately mean in hard cash flow terms?
I get why people would buy at 12/13p - then it was a £25m market cap and the play was around demand coming through from a hard to replicate product. Downside was limited. Now it is a £60m company that is still burning cash so there is a lot less room for error.
I see a lot about revenue but I don’t see anything about margins, profits or positive cashflow. I’m not saying it is overvalued necessarily, what I am saying is there appears to be no visibility over the numbers that ultimately matter and I’m trying to understand that.
If someone tells me on a 1 year forward basis the company expects to make £3m profit with a 100% cash conversion then I’m a buyer even at 20* PER as I can see the business momentum. But if someone tells me that is more likely £1m with a continued cash burn then I’m not.
Ok - I’ve found the new broker research. 18 months out the adj. EPS is 1p after todays announcement. So that means it’s on a forward 29* PER - not disastrously expensive but too rich for me.. Looks like cash is anticipated to be a little positive by a £1m or so.
I suspect I’d be a buyer if it drifts back but less so here unless there are even more upgrades.
I think the new broker research leaves a lot of room for updates. But Paul today said about Beeks:
"the outlook comments pointed towardsaccelerating growth. I looked through a modest miss against FY 6/2023 targets. The company has been telling us for a while that it’s got several slow gestation, but large contracts in its pipeline.
It sounds like some of the pipeline is turning into contracts now, and these are sticky recurring revenue type contracts remember, but which take a lot of time & effort to negotiate, winning the client’s trust. Beeks has a considerable moat I think."
I'd apply exactly the same to Filtronic (LON:FTC) who had previously announced one contract with Qinetiq (LON:QQ.) but today for the first time iirc announced another earlier contract was with BAE Systems (LON:BA.). I cannot imagine clients more likely to carry out comprehensive due diligence and, provided Filtronic deliver, to be sticky, repeat customers.
So I agree that there is execution risk here: can they produce in bigger volumes and maintain or improve margins? Absolutely.
As for the note today from Cavendish. Well, as I have set out in the Filtronic thread, the company has now announced £25m in new contracts since July, none of which have yet to find their way into the published results. Given that they announced £8.5m revenue for H1, the note suggests £15m for H2, followed by £24m for the whole of 2025. I would suggest that £15m ramp up reflects the new normal. If anything, the orders announced since (£19.1m since December 23!) suggest that far from slowing down, business is accelerating. That announcement of a new contract today for £7.9m is expected to be recognised in the calendar year 2024. So unless it is completed by April, that is all in the 25 forecast. In other words, before today's announcement of a new contract, the forecast would have been £15.1m for H2 24 and £16.1m for FY25. That just isn't credible for a business that seems to be firing on all cylinders. I reckon a more likely figure is that revenues will be maintained at H2 levels with new contracts on top. In other words, £30m for FY25, and £7.8m added to that today.
So I reckon the forecasts are being kept low to support a stream of "ahead" announcements throughout the year. But that is the bet we have to make.
Yes they could outperform the forecasts and that is the bet but defence generally doesn’t trade on 30* earnings whereas financial services plays definitely do. So I can see Beeks Financial Cloud (LON:BKS) on 30* but I would see Filtronic (LON:FTC) on 15-20* market multiples. That means if I’m generous I really want to get comfortable they can do double the forecast forward EPS to justify current share price and at the moment I’m just not seeing that in the margins. Anyway, haven’t looked in detail before so its piqued my interest at least and I will crunch the numbers a bit more at some point.
And of course as we have seen from many UK companies, being leaders in high tech components doesn't necessarily translate into profits or share price performance: eg Iqe (LON:IQE)
Ugh - don’t remind me about Iqe (LON:IQE)
Great tech useless commercialisation. Directors did very nicely though!!!! the new CEO looked highly credible but not much sign of life there either yet. Maybe I’m being harsh but he’s had what, 18 months?
David / ylannos
Filtronic
Think you need to look at the sector and the IP and then think about what PE applies .
LEO satellites for 100% sure is going to see significant growth in next few years .
Customers like Amazon, European Soace agency and Starlink are for 100% sure not going to switch to an unproven supplier.
The bull case is very clearly valuable , established and protected IP with very strong client base in a very hot sector .
Think if you believe that story you can apply a very high PE .
I just can’t see the LEO programmes stopping and Filtronic seem to have stumbled into the position of being a key supplier .
Not my normal value share for sure and I would be equally bearish if looking in from the outside .
Easy to be a believer and equally easy to shoot holes in the story .
I’d be far happier in Filtronic right now than most high PE growth shares .
Think this is really about learning about the sector and the IP and working out if you think it’s valuable .
Would I buy the company with that IP , client base and sector - has to be a yes .
Hi planetx,
I haven’t mentioned anything about Filtronic (LON:FTC) and its PE. I do not even know the PE of any company; meaningless figure like EBITDA. I understand there is something positive and I have mentioned it here about a couple of months ago.
I am interested about their profit margins and if they generate any positive cash flows. What’s their capacity as well? Have they got the capacity(very important) to increase revenues to a level that they will generate substantial cash?
If you have this information please share it with us.
Thanks
Filtronic
Ref - scaleability/ is it scaleable ?
Yes from Mello seminar the CEO was very clear they have capacity .
Back in the day when I was a young buck my first chairman asked “is it scaleable, that’s the only thing I’m interested to know “
When I get back from Java in a few days I’m going to go see Filtronic and get some feet on the ground feeling, nothing like a good look at a companies operations to help understand/ see scaleabilityand organisation and indeed general tidiness .
Great thanks
Very much interested to see this as well.
Let us know planetx - be good to get a view : thanks
Alumasc (LON:ALU) - Positive interims. Confident for full year expectations.
Good updates today from Eckoh (LON:ECK) Filtronic (LON:FTC) and Beeks Financial Cloud (LON:BKS) showing contract wins and increased revenue for 2024. Perhaps a sign that business confidence is returning.
Don't think you can extrapolate onto the general business envt from Filtronic (LON:FTC) - it operates in a very niche market, and the defence sector has dynamics all of its own.
Beeks Financial Cloud (LON:BKS) 2025 to be significantly ahead of forecasts + contract wins.
Broker ups eps15% with "scope for further upgrades down the line'
As discussed by many here, the clue was the volume spike.