Small Cap Value Report (Tue 6 June 2023) - NMRP, TM17, OMG, CHG, GHH, ZTF

Good morning from Paul & Graham.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
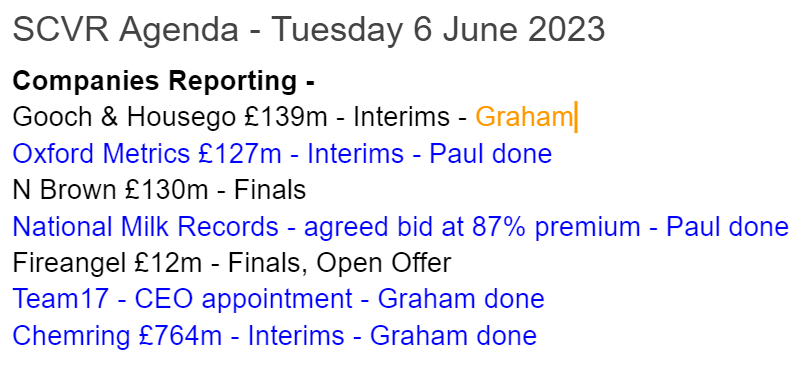
Summaries of main sections below
National Milk Records (OFEX:NMRP) Up x% (£y) - 215p agreed cash takeover - Paul - GREEN
Food giant ABF is bidding 215p cash (an 87% premium!) for this obscure little company that Graham last described here as a "High quality, under the radar stock". An excellent deal for shareholders.
Team17 (LON:TM17) - 350p (pre-market) (£510m) - CEO appointment - Graham - AMBER
This developer and publisher of independent video games announces that it has chosen the successor to its longstanding CEO. I’m leaning towards Green on this one but not quite able to give it the thumbs up yet.
Oxford Metrics (LON:OMG) - up 13% to 111p (£134m) - Interim Results - Paul - GREEN
Superb H1 results, and an ahead of expectations outlook statement, reinforced with a bulging order book. The net cash pile is almost half the market cap too. Loads to like here, and I think the shares are still cheap - but that requires management to use the cash pile wisely, and assumes continuing strong demand for its products.
Chemring (LON:CHG) - 280.5p (+4.5%) (£796m) - Interims - Graham - AMBER
H1 results are in line with expectations at this defence group, and expectations for H2 are unchanged. But there is more to be said as the order book surges to a record high and their “intelligence” services go from strength to strength. An interesting moment for the company.
Quick Comments
Gooch & Housego (LON:GHH)
Up 2% to 568p (£140m) - Interims - Graham - AMBER
This “specialist manufacturer of optical components and systems” announces strong H1 numbers. Revenues are up 32% to £71m and adjusted PBT improves to £4.5m. Full-year expectations are unchanged.
The company is in turnaround mode after it fell into unprofitability last year, and has just completed a review of strategy.
Its bloated order book has been addressed by additional capacity, with “good progress” in reducing order book arrears.
Input cost inflation remains a major factor but as the order book arrears are being dealt with, new orders should hopefully reflect the new environment. G&H are running a “structured programme to increase our prices on new quotes issued to customers wherever the competitive environment allows us to do so”.
The new strategy is titled “Delivering sustainable margin growth”. The company admits that it’s retaining parts of the existing strategy, “but with better execution and greater focus on achieving the desired outcome”. There are “areas where we need a different emphasis and new direction”. It sounds very much like evolution, not a revolution!
Graham’s view - this reputable industrial company continues to offer investors an interesting turnaround story. Brokers finnCap are forecasting adjusted PBT of £9m in the current financial year and £12m next year.
Zotefoams (LON:ZTF)
Up 2% to 348p (£169m) - NIKE contract extended - Paul - GREEN
Details are not given, due to confidentiality. However we are told that an exclusive agreement with NIKE is being extended to end 2029. All other terms (which we don’t know about) are unchanged.
The reason I’m flagging this announcement, is because it deals with my biggest worry about possible downside risk - given that NIKE is such an important customer to ZTF, the client concentration risk was high. Hence news that NIKE seems happy to commit for another >6 years, strikes me as very encouraging. A key risk has probably just been removed.
Paul’s opinion - one of my favourite shares, with a decent core business, plus exciting blue sky potential for its food/drink recyclable packaging, thrown in for free. The valuation is still looking a bit toppy, even after a recent fall from 400p to 350p. Risk:reward has today improved nicely, with news that the key customer contract has been extended considerably.
Paul’s Section:
National Milk Records (OFEX:NMRP)
115p (pre market open)
Market cap £24m
Shareholders will be celebrating today, with a very generous 215p (87% premium!) agreed cash takeover bid, from foods & Primark group, Associated British Foods (LON:ABF) .
It looks more of a strategic move, than a value investment, with the price being paid about 21x PER. It had never achieved that sort of valuation from the public markets, so there must be some strategic reason why ABF is prepared to pay more than the public markets.
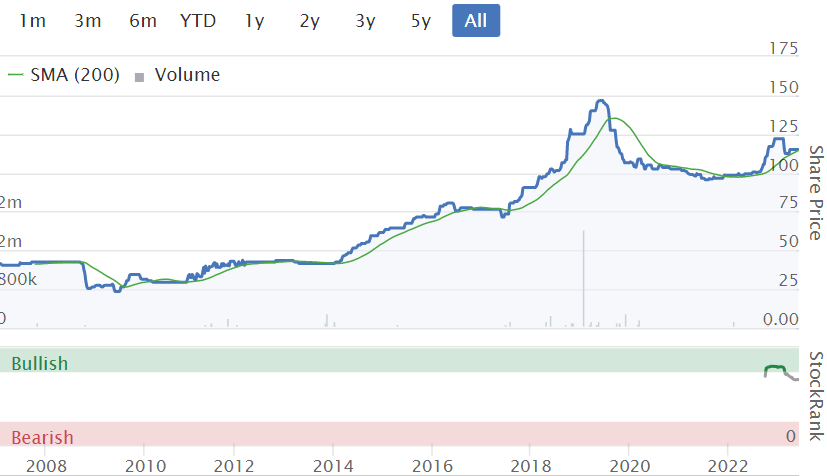
Nobody can complain about this - the 215p agreed bid is well above previous all-time highs for NMRP shares -
AB Agri (the ABF subsidiary which is buying NMRP) is already active in dairy products, so this looks a strategic move.
NMR seems to have a tight grip on a niche, which might be what ABF sees as attractive?
NMR regularly collects a milk sample from virtually every dairy farm in Great Britain, positioning it as a highly respected and present voice across the breadth of the national dairy sector. NMR's success has been largely driven by strong collaborative relationships with key industry players, including dairy farmers, vets, milk processors, third party suppliers, and major retailers.
NMR provides milk recording and testing services, invoicing upwards of 3,000 farms every month. In addition, NMR provides milk payment testing services to the majority of the UK's milk processors. Through its laboratories, NMR also provides disease testing services for individual animals and whole herd analysis. NMR continues to differentiate itself by developing new products and services and investing in alternative technologies, notably genomics and GenoCells.
It’s likely to sail through, with 69% support already indicated for the deal.
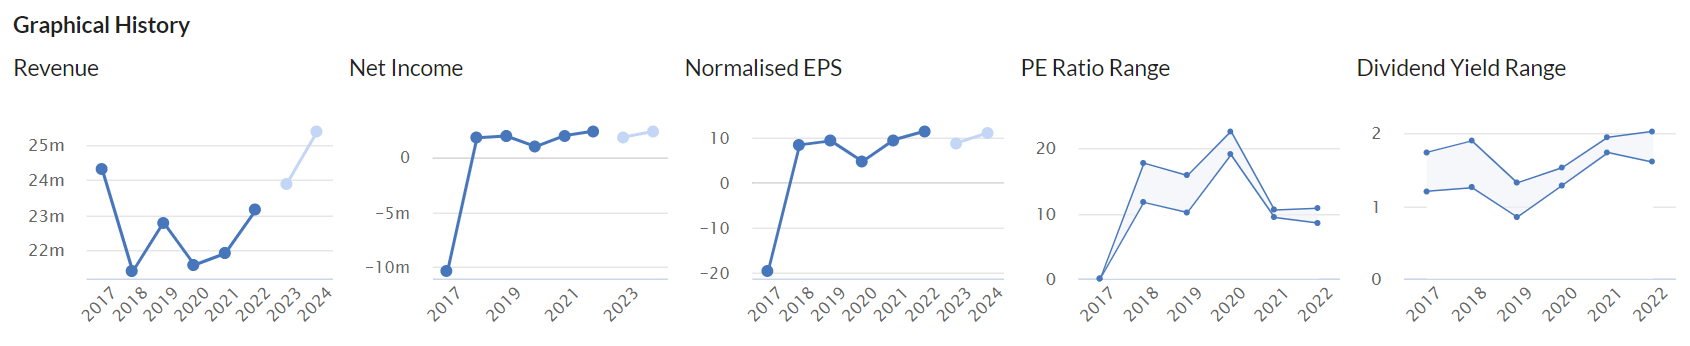
Paul’s opinion - a terrific outcome for shareholders, well done! I'd be interested to hear from any NMRP shareholders as to why you held this share? Nothing jumps out at me from the historical track record below -
Graham last looked at NMRP on 22 Feb 2023, seeing it positively, concluding "High quality, under the radar stock".
Oxford Metrics (LON:OMG)
Up 13% to 111p (at 08:08)
Market cap £144m
Oxford Metrics plc (LSE: OMG), the smart sensing software company, servicing life sciences, entertainment and engineering markets, announces unaudited interim results for the six months ended 31 March 2023.
We get 4 headlines at the top of the RNS today - my bolding -
Strongest ever half year revenue performance
Healthy order book provides confidence for the second half
Investing organically whilst actively pursuing the right acquisitions
Well placed to deliver full year performance above current market expectations
These numbers look terrific, and demonstrate how well operational gearing can work, when high margin products meet strong customer demand. Although note there was some benefit from delayed orders slipping from FY 9/2022 into the latest financial year (due to previous supply chain problems).
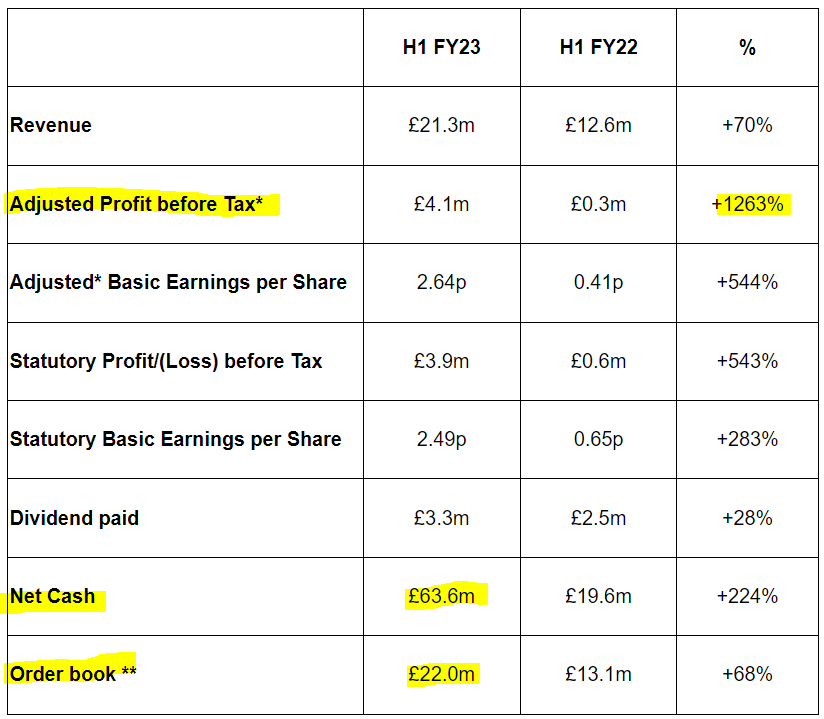
Cash pile – a very unusual feature of this share, which was obtained from selling off a part of the business that wasn’t performing well, at an amazing price. Net cash of £63.6m is 49p per share, getting on for half the market cap (130.2m shares in issue), so this is highly significant in valuing the shares.
It’s good to see that management hasn’t let the cash pile burn a hole in its pocket. The plan is to make acquisition(s) - so both risk and opportunity depending on what management decide to buy. With tech valuations now a good bit lower, the delay has probably been helpful.
Also note that finance income was £547k in H1, and on a £63.6m cash pile, that could increase to say £2.5m pa, if 4% could be achieved as interest received on the cash pile.
Balance sheet - is very strong. NAV is £78.4m, less intangible assets of £9.8m, gives NTAV of £68.6m, which is nearly all net cash. So a lovely position to be in!
Cashflow - not great, but the commentary explains that this is deliberate, building up inventories to ensure it can meet H2 sales. That’s fine I think - fast-growing companies do need to temporarily tie up working capital, it’s not necessarily a negative thing.
Outlook - I really like the strong order book of £22m, which means the full year figures should be achievable. Indeed, it says performance is now expected to be “above current market expectations”.
Progressive have issued a research note this morning, with PBT slightly revised up to £6.1m. That looks a very soft target, given that £4.1m has already been achieved in H1. With higher corporation tax, that results in adj EPS of 4.0p.
Personally I’d be surprised if the company achieves less than 5.0p EPS this year FY 9/2023, so expect another “ahead of expectations” type of update later this year.
My opinion - superb results, and a strong outlook, plus a massive cash pile, there’s lots to like here! So clearly I’ll be maintaining my positive view of this share, at green. OMG shares made it onto my “runners up” watchlist for 2023, so it’s good to see it continuing to perform well.
The big question is whether strong performance can be maintained? Doing a bit of googling, OMG’s main business, Vicon, seems to supply high end cameras. I recall a few years ago there was another company doing that, called something beginning with V, which made nice profits for several years, but then fizzled away and eventually delisted. The market just moved on, with better products being launched by competitors. So if I were researching OMG in more detail, I would focus on the question of how sustainable its competitive advantage is? It might just be in a sweet spot that competitors could erode over time? Although it’s good to see OMG spending plenty on R&D, which is vital for future success, as technology moves so fast these days.
In the meantime, the valuation looks quite reasonable to me. At 111p per share, I would first deduct the 49p per share cash pile, giving 62p valuation for the actual business. I think it’ll do at least 5.0p EPS this year, so a PER of just over 12 - it looks a bargain to me, if those profits are sustainable.
The other key point is what management does with the cash pile. Downside risk - they overpay for something. Upside risk - they buy something excellent at a good price. So this share is very much a bet on two things - strong demand for products continuing, and management using the cash pile wisely.
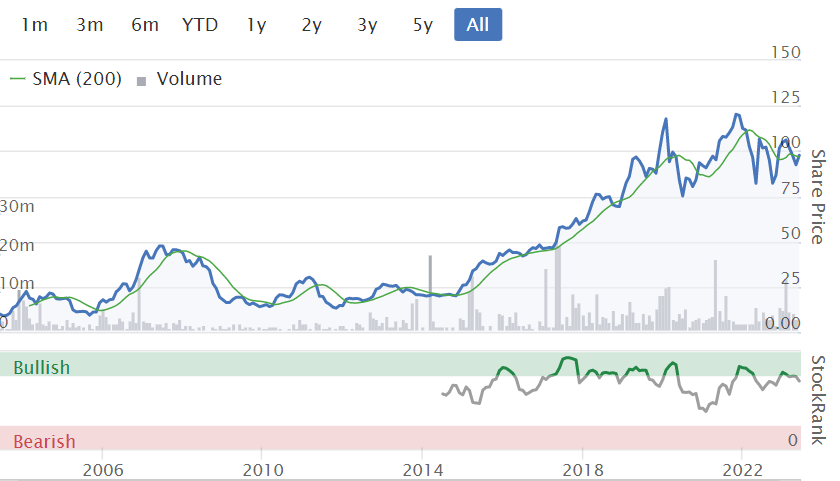
A very nice looking long-term chart below, and a high StockRank too -
Graham’s Section:
Team17 (LON:TM17)
Share price: 350p (pre-market)
Market cap: £510m
We previously reported on the planned departure of Debbie Bestwick, Team17’s talismanic CEO.
Just over two months later, we have a development:
Team17 Group plc, a global games label, creative partner, developer and publisher of independent ("indie") premium video games, educational entertainment apps for children, and working simulation games, is pleased to announce the appointment of Steve Bell as Chief Executive Officer. Steve will join the Board on 4 September 2023 as Group Chief Executive Officer Designate, formally assuming the role of Group Chief Executive Officer from 1 January 2024.
Bestwick will officially remain CEO until 31 December 2023, so the new CEO will have four entire months to work with her and learn about the company before he takes on the role.
It’s a perfect plan for a smooth transition. Remember that Bestwick is a co-founder of the company and 21% shareholder, so it’s in her interest to ensure that the new CEO benefits from her wisdom!
The new CEO joins from a marketing agency he co-founded in 1999, and that now has 1,000+ employees around the world.
There is no doubt in my mind that his experience will be helpful for Team17, but personally I do prefer to see people with industry-specific expertise at the top of companies. In other words, I’d like to see someone with gaming industry experience leading a company like Team17. I want the CEO to understand the point of view of the customer and to have a strong understanding of his or her competitors in the industry.
But I imagine that Team17 did a lot of work before making this decision. Comment by Bestwick:
As a Board, we have run a rigorous process to find a new Group Chief Executive and we are delighted to announce Steve as my successor. Steve's experience as a co-founder of a people-centric business means he understands the importance of our vibrant and inclusive company culture which remains the cornerstone of everything we do across the Group.
Graham’s view
I was previously neutral on this stock at £640m, before the announcement of the CEO departure.
At a £510m market cap, it’s more interesting. See previous coverage (here and here) for discussion of organic versus acquisition-led growth, and the adjustments made to the earnings numbers.
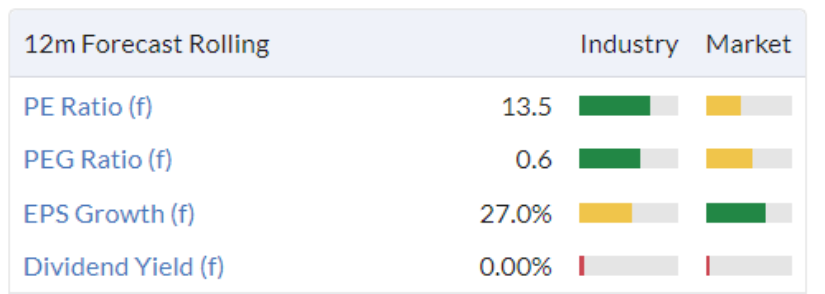
Overall, I’m going to stay neutral on this one, although I am leaning towards green. If they had hired a gaming industry veteran as CEO, then perhaps I’d have taken an outright bullish stance today.
Chemring (LON:CHG)
Share price: 280.5p (+4.5%)
Market cap: £796m
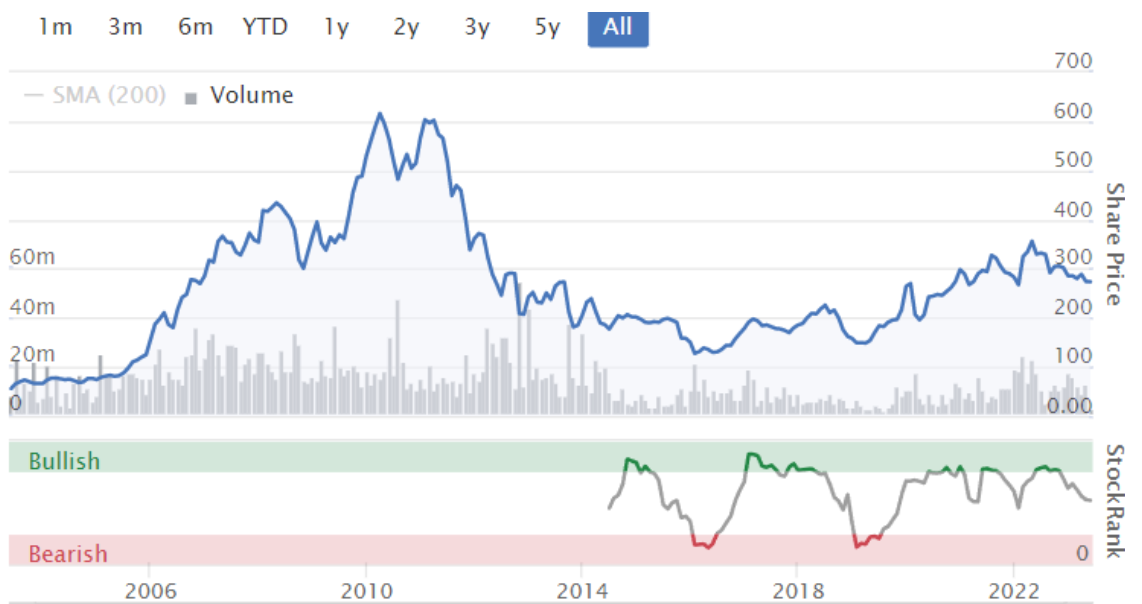
This defence share has been a strong performer over the past five years. But it’s not very easy to get the timing right with this one, as I know to my own cost:
Let’s briefly see how it’s doing currently, with the latest interim results for the period to April 2023.
H1 is in line with expectations. Key points:
Record H1 order intake £338m, plus 81% year-on-year.
Record order book in over a decade at £750m, plus 54% year-on-year. About one third of the order book to be delivered in the second half of the financial year.
The actual H1 results are less impressive than the order growth: revenues down 5% and underlying operating profit down 19% at constant exchange rates.
The US government’s spending difficulties have caused complications:
As previously announced, delays to order intake in 2022 following the extended US Continuing Resolution have resulted in a heavier weighting of trading performance and cash generation expected in the second half of the financial year for the Countermeasures & Energetics sector.
Net debt is only £25m which does not seem meaningful relative to the current size and profitability of the group. Cash generation in H2 should improve “markedly”.
CEO comment excerpt:
The outlook for the global defence market is increasingly positive, with strong growth predicted over the next decade. This growing visibility and the increasing desire of our customers to move to long-term partnering agreements gives us the confidence to continue to invest for the future, balancing short-term performance with heightened long-term growth and value creation. Chemring is well placed to capitalise on its many opportunities and with 90% of expected H2 revenues covered by the order book, the Board's full year expectations are unchanged.
Outlook
Chemring owns a business called Roke that made a big contribution to orders (£81m) and revenues (£78m) in H1. This is what Chemring has to say about its outlook:
…Roke has created an Intelligence as a Service business which combines proprietary datasets, AI, and customer facing platforms to provide nation state level intelligence to both government and commercial customers. Viewed as a key enabler of tactical success, our expectations are that this business can grow at 35% CAGR.
For the group as a whole, H2 expectations are unchanged, with expectations for “robust organic and inorganic growth”.
Graham’s view
I find the defence sector extremely tricky as the customers (governments) and the catalysts (conflict) are by their nature unpredictable. However, I am impressed by Chemring’s diversification into intelligence services. I would also be inclined to think that background conditions will remain favourable for Chemring for at least the next several years.
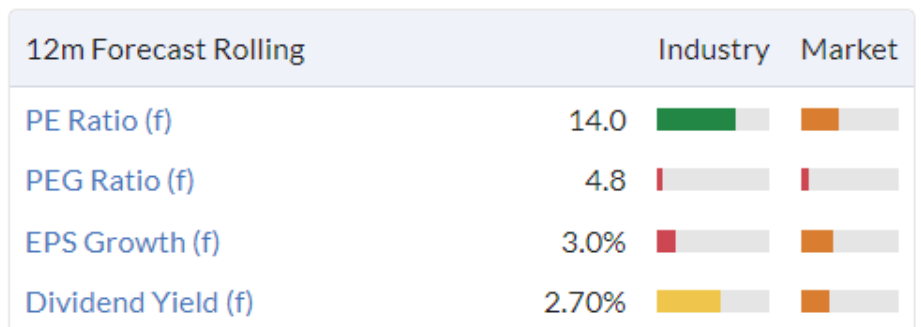
It can be argued that this is priced in now, after strong share price gains since c. 2019. I’m neutral on the stock but I do think it remains a worthy candidate for further research:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Oxford Metrics (LON:OMG)
A bit of a delayed entry here.
I was actually disappointed with the results for 2 reasons:
That seems quite high relative to the revenue generated.
It's certainly a quality company with some excellent customers e.g. COVER (TYO:5253) who were behind a lot of the revenue increase the period. It was therefore with some regret that I ended up selling after the update.
A
Regarding Oxford Metrics (LON:OMG) it’s worth flagging the sizeable director selling back in Feb. Latest results, valuation and outlook look good otherwise.
Chemring (LON:CHG) as long as Putin's Special Operation lasts.
An interesting trend that I've seen emerging in the non housing REIT type stocks is that valuers have been slashing values by some 15-20% BUT sales are being agreed much closer to the previous values. That suggests either someone is dramatically overpaying for assets, which seems unlikely, or valuers have been too trigger happy.
Examples of different type of non residential property REITs
Warehouse Reit (LON:WHR) had it's NAV slashed from 170-122p but sales post year end have gone through at 17% increases to book value. That suggests its actual NAV is closer to 140-145p so a share price of 97p looks erroneous
Newriver Reit (LON:NRR) had a much smaller hit to NAV as shopping centres and the like have held up better but nonetheless asset sales have been in excess of book
Aew UK Reit (LON:AEWU) just sold property at an 8% premium to end March book value and had similar sales earlier in the year at 6-7% premiums to Dec book value (which was higher than March)
Do wonder then whether there is hidden value starting to appear in these - very good dividend yields but assets appear under priced in quoted NAV. Suggests they are trading maybe at 40% discounts to real values?
davidjhill, i think you are correct. A friend who works in the industry told me a couple of weeks ago that “last month (April i assume) finally saw an uptick in the property index (IPD, i assume).
I picked up some NRR this am for my ISA. Shore Cap the brokers to NRR put out a note. P/e of 10.7x for the year to March 24, with rents growing. Yield of 7.8 with 1.2x div cover and NAV rising, albeit small.
Seems a safe place to put 86p a share!
Strongly agree davidhill. I’ve held several since the previous covid sector falls and they’ve been excellent investments. . The dip is less severe this time but it looks as though the bottom has now been seen,. There are some fab bargain Property Investment Trusts available now, on very wide discounts and very big often well covered dividends too.
This link on THE must use site for Investment Trusts shows the UK Commercial Property Trusts. Clicking on each one brings up a wealth of info. (Stockopedia is not as good a source for Investment Trusts as so many of the figures are irrelevant for Trusts and vital must know info like discounts to NAV and whether wider or narrower than usual etc are not included).
https://www.theaic.co.uk/aic/f...
Of the Trusts there I’ve held abrdn Property Income Trust (LON:API) Aew UK Reit (LON:AEWU) Alternative Income REIT (LON:AIRE) Ediston Property Investment (LON:EPIC) and Schroder Real Estate Investment Trust (LON:SREI) since the 2020 sector falls and picking up AEWU on huge discount at 63p and 13% dividend. EPIC pay monthly dividends and the rest pay quarterly.
I also hold Schroder European Real Estate Investment Trust (LON:SERE) and Tritax EuroBox (LON:EBOX) in the Property Europe sector. Here’s aic link to it.
https://www.theaic.co.uk/aic/f...
EBOX is at a huge 46% discounts despite having now bounced a bit. Phoenix Spree Deutschland (LON:PSDL) is my only sector loser and I’ve sold for now. It’s on a 53% discount. Could well become a great recovery buy, but not yet. Their next update might be the time.
Finally. This link is for an excellent site for dividend information. AND they update as soon as a dividend is announced. Each of the headings is well worth clicking on, starting with ex dividend dates heading. AND just enter the code for a share or Trust on the ex dividend dates page and it brings up its dividend history and if a dividend has been declared , the next time ex dividend date and pay day:-
https://www.dividenddata.co.uk...
e.g here’s the page for the astonishing Gulf Keystone Petroleum (LON:GKP) dividends last year ….but now hit (temporarily with luck) by current KURD/IRAQ spat so the most recently declared dividend has been cancelled to preserve cash. GKP unlike the Property Trusts is high risk, but the 40% dividends last year shows the cash flowing in and being paid out until recently, and probably again IF present shenanigans are temporary.
https://www.dividenddata.co.uk...
I also hold Schroder European Real Estate Investment Trust (LON:SERE) and Tritax EuroBox (LON:EBOX) in the Property Europe sector. Here’s aic link to it.
https://www.theaic.co.uk/aic/f...
EBOX is at a huge 46% discounts despite having now bounced a bit.
For my sins, I hold some Tritax EuroBox (LON:EBOX) and the NAV discount is not quite that huge. As of the recent interims the EPRA NAV was ~90p at the current GBP/EUR exchange rate. So a big discount, yes, but not the huge 46% indicated by the AIC website. I have no idea where they get a NAV of £1.32 from, but then I never trust their data anyway.
Personally, I can see the NAV declining further before it bottoms out, but we have to remember it is a DCF based valuation using a discount rate based on someone's guess on the future of interest rates. As others have pointed out, that's quite different from the valuations at which actual property transactions take place and that is really where the investment case lies, not a DCF value based on lots of guesswork.
As you can probably tell, I don't care much for DCF models.
Keywords Studios (LON:KWS)
Now trading on forward PE's of 17/15/14 for next 3 years. Looks remarkably cheap given growth history, record of over delivering and no real news to justify a 40% fall in SP in recent months.
I hold having top sliced at 2800p and bought back in at 1850p.
Don't know if it's just me, seems to be a lot of compelling valuations thrown up recently, for shares i hold and on my buy list?
I’ve been investing since 1984 and except during catastrophic market falls, i can’t remember seeing so many cheap small and mid cap stocks.
Small cap fund managers still appear to be getting outflows. The only buyers at the moment are companies, either buy backs or predators, and private punters who have some cash left following the rather nasty small/mid cap bear mkt we have had.
The big turn will come when asset allocators overcome their fears over Brexit, Truss economics, higher inflation etc etc and allocate blocks of money to the UK. No idea when!
But investing is about patience.
Does anyone know what has spooked the price of Keywords Studios (LON:KWS) since about 9 Mar 23?
Keywords Studios (LON:KWS) Someone said it was AI.
Keywords Studios (LON:KWS) . Alongside the AI factor mentioned by Rusty2, there might be an element of catch up with the softness seen in the wider video games and entertainment sectors over the last year or so. Recent loss of long-standing Chairman allied to the CEO being a relatively recent appointment could also be weighing on sentiment. There has been a tick up in short selling of the shares since March, but possibly mirroring the direction of the market primarily rather than a direct cause of the sell off in the shares.
Many thanks to veritas and Rusty2 for their replies about Keywords Studios (LON:KWS)
It's to do with AI. Goldman Sachs has an ETF shorting "AI Bear" stocks. KWS is one of them. They have targeted a number of European stocks particularly if they do translation or localisation of any kind.
Obviously this sparks a very interesting debate around the KWS share price. The environment will clearly change over the coming years for KWS and AI could be regarded as a threat but it could also be a significant opportunity.
KWS has been using AI for a number of years to help customers and they have made a number of acquisitions that will help too:
- Kantan AI – an AI-based productivity tool for localisation
- Helpshift – a conversational AI-led customer support platform for player support
- Mighty Games – software that uses machines to test games while in development, making testing much more iterative
Keywords have a significant number of staff and many of these may no longer be required as they use more AI tools going forward. This is good news as the industry has been struggling to find enough talent. This could be good for KWS margins.
Games are likely to become more complex and AI will obviously help reduce costs for games developers. This could mean higher volumes of work for KWS at a lower price. In terms of their own tech development, KWS should certainly hold an advantage, due to size (6% of the market), relative to outsourcing peers. I would therefore suspect that they will continue to take market share - however, there is a threat that AI allows some game producers to take more production back in house. I personally doubt this will happen. There has been a desire from the industry to outsource as much as possible for some time and the lumpiness of projects means that doing everything inhouse isn't as efficient.
The shares now trade on close to a 15x P/E for calendar year 2024. This is a significant discount to historic multiples of close to 30x.
Odd price action at Let's Explore (LON:LETS) post results of the tender offer
In essence once you remove tender shares there are 190m shares left in issue. At 3p that's sub £6m market cap. After tender cash is paid out the company will have circa £9m of net cash and isn't burning anything as the remaining business should be profitable.
So investors are selling their cash for 66p in the £.
I wish people walking up and down the high street offered to do that ! :)
EDIT : I know people will say "ah but they may buy another business" and if the management team were serial under performers burning investors cash I could understand that scepticism. But in reality the businesses the directors have previously run have all been sold at decent profits so they actually have a good track record of making money.
I should think that Let's Explore (LON:LETS) - going by a previous experience- expects its share price to rise substantially shortly, the best reason of all to make a tender offer! To me, tender offer is a dirty word.
I don't hold.
No not really Silver Moon. Let's Explore (LON:LETS) sold the main operating business for $25m which gave them a tangible net cash position of over 5p p/share. The tender offer was just a way of returning 65% of capital to shareholders.
The residual business is now £9m of net cash and a small enterprise that should b/e or make a small profit.
The market cap is sub £6m.
David
Looks a no brainer if your numbers are right
Though stock market is a bit illogical at the moment
Yeah - that's what I mean really Planetx.
Market is illogical right now but I guess that throws up opportunities too if you're patient.
I suspect you got a bunch of buyers at 3.75p buying before the tender went ex div for a 1p gain on 65% of their purchase and now that has gone are selling the remaining 35% at a loss of 0.5p. Probably equates to an arbitrage of 20% gains over a 3 month window but has left the market cap in an odd place where net cash is trading at a discount.
There is a webinar today at 12pm with the management of Hercules Site Services (LON:HERC)
Meet CEO Brusk Korkmaz and CRO Paul Wheatcroft who will provide an introduction to Hercules Site Services plc and update on performance following the publication of the HY results which were released yesterday.
Register here
Morning Paul, any chance of the readership getting your thoughts on XP Factory (LON:XPF) this week? I think it’s a large holding of yours, so you must have looked at it carefully. The results were viewed favourably by the market initially but the share price soon drifted back. The CEO was very positive about the adjusted ebitda figure but neglected to mention in any of the presentations that the company actually made a £1 million loss. Stocko has the quality metric as a healthy 0…The Oxford Street branch is always heaving, you have reported, and the Southampton one seems to be very busy too, according to Vox markets. So a loss is perhaps acceptable given the huge number of sites they have opened this year? Will they need another fundraise to support the rollout of all these new sites? It looks like a high risk/potentially high reward share. I would be happier if the CEO, in addition to talking up the company, would hold more shares.
Hi rogerh,
Re XP Factory (LON:XPF) - I do get frustrated by this one, because people don't seem to be able to grasp the concept that it's a rapid roll-out of new sites (which individually have excellent site economics). So the historic numbers are already out of date, and irrelevant, because such a large number of new sites were opened towards the end of 2022. It was profitable in 2022 if you accept the adjustments (which I think are fair), but on a statutory basis might not have been. People seem to be analysing the numbers as if it were a mature business, which it isn't.
The important bit is that it's trading ahead of expectations in 2023 so far, and the cash pile had risen from the year end level, by April 2023, so it's already cash generative. Therefore, no it doesn't need to raise more cash, but it might choose to do so, if attractive new site opportunities arise.
2023 results should be transformative, because they will include a full year of all the big new sites opened in 2022. That's the investment case in a nutshell. There's a note from Singers which is forecasting revenues almost doubling in 2023, and a big jump in adj EBITDA. With a heavy depreciation charge, that means forecast adj PBT is only £1.1m for 2023.
What interests me most, is the roll-out potential. There are loads of available sites, on very attractive deals where the landlord pays for most of the fit-out cost, and gives a 1-2 year rent-free period too. XPF has already demonstrated it's capable of opening lots of new sites quickly (it went from about 7, to 27 BBB sites in 2022 for example), and at only a modest cash cost. So now we know the format works, it's a simple roll-out to many more sites (lots are franchised, where the franchisee pays a 10% of revenue fee - de-risking things for the shares, and making things easier to manage).
I think there''s a lot of potential for this share. And as we've seen with the bowling companies, consumers are still happy to spend on affordable experiences, with no sign of demand waning.
XPF is the only pure play small cap in the experiential leisure field.
Regards, Paul.
P.S. Sorry I forgot to mention, I hold XPF personally - it's my second largest personal holding after BOTB.
P.P.S. I forgot to mention that the CEO is relatively young, with a young family, and is not independently wealthy. Hence why his shareholding is not that much. However, he is heavily incentivised with a very generous share options scheme, so our interests are very much aligned. There is also additional share issuance to come, from deferred consideration. Therefore, as I've mentioned before, the 150m shares in issue currently could expand to nearer 200m when all dilution is taken into account.
Thanks a lot for the reply Paul
Hi Paul,
I do grasp the concept (along with many others) , and maybe , just maybe , it might be you that doesn’t grasp it.
This company will certainly have to raise more cash , the share count will increase by at least 50% and it is not cash generative.
Good luck to all holders.
I am not a holder, but I am not sure I agree with you yiannos1. The real drain on cash is their expansion costs. They should be able to control those relative to cash. Otherwise cash is required for stock which they should have good payment terms on and labour. The risk element is that demand falls away. As we saw with Rev Bars investment back into the sites is important and often a few sites drag on the others.
XP Factory (LON:XPF)
Time will tell Y1, time will tell. I was intrigued enough to buy a small starter stake.
Their recently appointed NOMAD and Broker, Singer, show them being cash generative in 2023.
A new forecast for 2024 has appeared on the Stock Report following the input of the 2022 actual figures showing forecast EPS of @ 6p upgraded from 3.1p over the last month.
I'm going to see how it pans out.
Yiannos1, are you of the opinion that the business will not be cash generative even a few years into the future? If so, why is that? I am interested in your bear argument for the stock.
Do you mean in 10 years time?
I couldn’t answer that.
The management is trying to change the structure and the path of the business ie. The old one is not working ( red red flag).
What I do know though , is that it will need 100% a new fundraise , the management is paid too much in stock options and there is a deferred payment in shares as well.
Comparing this with Ten Entertainment plc is quite amusing.
Good luck to all holders.
"This company will certainly have to raise more cash , the share count will increase by at least 50% and it is not cash generative."
That is all factually incorrect, I'm afraid.
I am 100% correct (yet again, sorry). I‘ m afraid.
Just thought I will add my 2 pennies on this. I've went to the Oxford Street branch during half term with my niece and nephew and it was empty. We had a great time but doubt it is repeat business type of business. Also works very well during xmas for office parties - again one off in nature.
Any more evidence of business busy-ness at their either sites?
Any more evidence of business busy-ness at their either sites?
I spent a couple of hours in the Manchester site during my sons stag do a couple of weekends back. It was tolerably busy on a Saturday at 5 pm, but not teeming with folk. Upstairs a hen party performed the Whigfield dance, while downstairs was a predominantly male crowd, throwing axes and playing beer pong. It was fun as a one off but not somewhere I would be going back to without coercion. I think it’s a fad, not a long term winner of revellers’ money. However, I’m 60 years old, so not really the target punter.
I have been looking at bookings today, by trying to book across their range. In most places fairly easy to book.
Croma Security CSSG
Finally announces the deal for disposal of its vigilant security business .
Headline numbers are very strong with the sale representing over 90% of the company valuation (which was ludicrous)
Actually leaves Croma with a nice little business in a decent sector.
Deal involved cash and a loan note which is a bit annoying. Why sell a business you already own 100% of for a loan note ?
There’s over 2 million cash , plus another million option , and Croma is buying over 700,000 shares back from the vigilant team as part of the deal which is by my fag 5% reduction in share count .
All in all looks pretty well financially engineered if a little laboured it’s a nice move by a little minnow .
Spread is wide and executive reward is too high .
I’m going to hold and let this develop , it’s a very nice little company totally unloved in deep value territory,
I can understand the company, market , and strategy and it’s a good niche so I’ll let this unfold and hold on 3-5 year view .
7 million cash would have been nicer though .
The £3m loan note is all repayable between nine months to three years from now. The redeemable preference share is due to be redeemed in about a year.
So not too long to wait for all the cash.
My morning smallcap tweet: A punch in the mouth to wake you up
Gfinity (LON:GFIN) Barkby (LON:BARK) Fireangel Safety Technology (LON:FA.) Hellenic Dynamics (LON:HELD) Woodbois (LON:WBI) Ondo InsurTech (LON:ONDO) Croma Security Solutions (LON:CSSG) Ethernity Networks (LON:ENET) XLMedia (LON:XLM), Property Franchise (LON:TPFG), Billington Holdings (LON:BILN)
◄Gfinity (GFIN)► eats humble pie and closes the much hyped esports division "as the market for esports remains soft and the directors see limited profitable growth opportunities". Sells majority held Athlos (esports technology platform) for £1. Athlos has absorbed £1.5m of cash. Co will "focus on digital media and its significant position in the Gamer website industry". Down 99% in 5 yrs. [SP=0.14 Cap=2m]
◄Barkby (BARK)► £4.25m+ 5 yr order for subsidiary Cambridge Sleep Sciences. [SP=3.3 Cap=5m]
◄FireAngel Safety Technology (FA.)► £6.1m placing (with warrants) and £6.1m open offer at 5.05p, a 21% discount. Trading in line. CEO scrapers. He is thanked. Down 91% in 5 yrs. Yeah. Thanks! [SP=6.88 Cap=12m]
◄Hellenic Dynamics (HELD)► minor progress update. [SP=0.16 Cap=20m]
◄Woodbois (WBI)► cash crisis update - agrees the terminated bank debt repayment by Dec. Co "also working on the potential deferment of c.$1.5m of debts, which fall due at the end of June. Whilst the Directors are confident that the Company will obtain alternative funding in the coming weeks, should they fail to do so, the Company may be reliant on the deferment of these near-term creditors in order to continue to trade". [SP=0.42 Cap=11m]
◄Ondo InsurTech (ONDO)► results of Portsmouth Water LeakBot pilot. Use of the LeakBot has resulted in a 60% reduction in the number of leaks. Portsmouth Water is considering a wider rollout to reduce in-home consumption. [SP=22.5 Cap=17m]
◄Croma Security Solutions (CSSG)► sells Vigilant Security for £6.5m plus inter-company balances of £1.07m. Vigilant generated c. 29% of EBITDA in last half. Co will ocus on its higher margin Croma Locksmiths and Croma Security Systems businesses. [SP=46.15 Cap=7m]
◄Ethernity Networks (ENET)► secures supply of critical components required for contracts signed for the current year. Guides FY rev $3.3m. [SP=2.79 Cap=4m]
◄XLMedia (XLM)► sells domain and website, MoneyUnder30, for $675k. Completes the disposal of the Group's entire Personal Finance asset portfolio, in line with plan to exit non-core activities. [SP=8.85 Cap=23m]
In line: TPFG, BILN
RE Fireangel Safety Technology (LON:FA.) - I had to read it twice before finding where he was thanked. I bet Judith McKenzie of Downing was on the phone giving her personal thanks as well.. Marked in Stocko as involved in takeover situation from this morning. Glad to have got out at the last drop.
Oxford Metrics (LON:OMG) half year today - revenue up 70%, Adjusted EPS up 540%, half the market cap covered by cash following the sale of Yotta : https://www.londonstockexchang...
Gooch & Housego (LON:GHH) half year: recovering, revenue up 30%, Adjusted EPS up 26% - although another slug of non-recurring restructing costs in there.: https://www.londonstockexchang...
timarr
Another one where it kept drifting so I sold out. Looks fair value now assuming 4.5eps for FY. 48p in cash per share so I make it x14 PE
Sorry I'm referring to Oxford Metrics (LON:OMG)
Good morning Paul and Graham. We hold Croma Security Solutions, last looked at on SCVR by Jack in June 21, the shares have almost halved since then so does today's chunky disposal warrant a quick comment from either of you? It seemed good value to me then and looks even better now but I usually miss where the cautions are.
Yes, Croma Security Solutions (LON:CSSG) have sold their Vigilent subsidiary for £6.5m (albeit not all cash up front). The price represents 92% of Croma's market cap, whereas the business sold contributed an average of 36% of Croma's EBITDA over the last two financial years.
The remaining businesses - Croma Locksmiths and Croma Security Systems - are trading "comfortably ahead of last year", although reported results will "be impacted by a number of one-off exceptional costs incurred in relation to Vigilant and the Disposal". The intent is to invest the proceeds of the sale into growing the remaining businesses.
As they stand, the remaining businesses are tiny but, in my opinion, the share is materially undervalued at current levels.
There's a massive amount of trust required in terms of the deferred cash. Is it wiser to value Croma Security Solutions (LON:CSSG) on the basis that this cash is never received?
shanklin100,
In short, "no".
"In the event that the buyer defaults on any one payment due to the company under the loan notes the company shall have step-in rights to assume control of Vigilant at board and shareholder level"
Hi Paul and Graham, one that may have slipped through is the 3pm Friday announcement by Polarean Imaging (LON:POLX) regarding collaboration with Philips in their new MRI machine. Would you mind providing an update please?
Good morning ANDERSHOW08,
You mentioned an announcement from Polarean Imaging (LON:POLX) concerning a collaboration with Philips - http://newsfile.refinitiv.com/...
There's nothing I can add, or analyse, as there are no financial details in the announcement. It obviously sounds positive, but I wouldn't want to start speculating on the financial aspects.
It strikes me as odd that, in anticipation of FDA approval, POLX shares rose to, and briefly exceeded 100p per share. Then began to plummet once FDA Approval was obtained! They're now only 27p, having recently bottomed out at just 20p.
It's a stark reminder of how bull market high valuations can disappear in a subsequent bear market, even if the newsflow has been positive.
It's tempting to buy a few POLX shares as a speculative thing. Although the number 1 thing to research is how much cash remains, and how long will it last? If they have to do a big fundraise in current market conditions, it's anybody's guess what the price & level of dilution might be.
Regards, Paul.
Thanks Paul.
I’m not sure there is an immediate financial aspect, certainly cash flow, from the agreement as such.
I think it’s mightily important recognition of the tech that one of the big MRI players have chosen to integrate Polarean Imaging (LON:POLX) Xenoview product into their latest machine.
A great endorsement.
Agreed, the SP movement is baffling since approval, I think partly self induced in this market with the company highlighting what was an 18 month cash runway when no need to do so.
Hopefully the start of positive commercial traction after a slow start post approval.
Thanks for your thoughts.
This was from the February trading update, it's been down hill from there