Small Cap Value Report (Tue 7 Dec 2021) - SOM, TND, SUP, SDI, MERC

Good morning! Paul & Jack here. I'm working on a market comment section, so that should be up later. I know people like us to publish an opinion on markets, especially at times of great volatility.
Mello - tonight. There’s a free show tonight, starting at 17:30, with 6 company presentations.
Agenda -
Paul's Section:
Somero Enterprises Inc (LON:SOM) (I hold) - another upgrade to estimates, as I suspected might be the case when guidance was raised 21% on 8 Sept, but still looked light. We get another 7% earnings increase today. The PER is now only 10.7, and the divi yield over 7%. It's got pots of cash on hand too. The valuation looks crazily cheap to me.
Supreme (LON:SUP) (I hold) - interim results and outlook are pleasing. Balance sheet is solid. I like this company - entrepreneurial management, and it's establishing a good track record of decent & growing profits & cashflows. Valuation looks reasonable - looks a decent GARP share.
Sdi (LON:SDI) - very impressive interim results, boosted by one-off orders (as previously disclosed). I like this share a lot, and see it as an impressive acquisition vehicle, with experienced management. The valuation's a bit toppy for my personal taste though. It reminds me of Judges Scientific (LON:JDG) - which has been hugely successful for investors, pursuing a similar acquisition-driven strategy for niche, high margin small businesses.
Jack's Section:
Tandem (LON:TND) - (I hold) - Q4 revenue flat year-on-year (after being up 6% in Q4 2020) - a tough comp, as customers previously caught up on delayed orders from the first lockdown. Full year profit to be in line or slightly ahead of market expectations. Signs of cost pressures easing. Short term share price performance is difficult to predict as the low liquidity means relatively low levels of buying or selling can move the price, but the valuation remains modest.
Mercia Asset Management (LON:MERC) - positive momentum and the company’s core activity of investing in private, growing, regional enterprises in attractive sectors means it could play a useful role in portfolio diversification. Two aspects to consider: the direct investments and the third-party funds business. Not the most straightforward to value or forecast, but perhaps therein lies the opportunity.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Somero Enterprises Inc (LON:SOM) (I hold)
474p (yesterday’s close) - mkt cap £269m
This US-based company makes laser-guided concrete laying machines, to deliver perfectly flat floors, which are increasingly being demanded for warehousing (to allow for higher, stable, racking)
It’s one of my favourite companies, producing bucketloads of cashflow, divis, growth, repeatedly beating expectations, yet is still modestly priced. I just can’t understand why investors generally seem to eschew such a good company. There is a potential impediment with some brokers asking for a form to be filled in, for US tax purposes, although that’s very simple.
Somero® is pleased to provide an update on trading for the current financial year, ending 31 December 2021 ("FY 2021").
Raising guidance due to strong trading momentum to end H2
Strong trading, and consistent deliveries, mean guidance given on 8 Sept 2021 is now being raised -

It’s a pity they don’t provide a figure for adj EPS, because that’s the number I need to value the shares. EBITDA isn’t proper profit, so I loathe the current fashion to quote it as the main measure of profitability. Never mind, who’s quibbling when Somero once again surprises & delights investors with a further upgrade.
Checking my notes here from 8 Sept 2021 (interim results) - profit guidance was raised 21% then, to 40.0p EPS (converted from dollars into sterling). Although as I commented on the day, my own figures were much higher, with me expecting nearer 50p EPS for FY 12/2021. So actually, today’s increase isn’t a particular surprise, but is very welcome nonetheless.
Broker update - many thanks to Finncap for updated figures this morning. It’s now going for 59.0 US cents adj EPS for FY 12/2021. At £1 = $1.33 exchange rate, that’s 44.4p in sterling.
Valuation - at 474p per share, the PER is only 10.7 - that seems crazily cheap to me, unless you think earnings growth is likely to go into reverse, and there’s nothing to indicate that’s likely to happen.
Net cash of $39m is £29.3m in sterling, or 10.9% of the market cap. Strip out the cash (because it gets paid out in divis over time), and the PER would be below 10. How does that make any sense? This looks the wrong price to me, much too low.
Outlook - sounds alright -
In North America, market conditions remain healthy and positive, driven in part by demand for new warehousing, with customer workloads at high levels and reported project backlogs extending well into 2022.
My opinion - what a bargain this share is. I think it’s worth at least 50% more than the current price, which would only take it to a mid-teens PER.
Shareholders can sit back, and watch the divis roll in, as this is a highly cash generative business. The yield is now 7.1%, and we sometimes get special divis on top.
Yes it’s a cyclical business, but why is it being priced for a recession, when nothing else is?!
I think the market is overlooking the fact that SOM’s growth is not just cyclical, it’s also enjoying a long-term structural move towards warehousing with perfectly flat flooring - increasingly necessary for automated warehousing.
Hence overall my view is highly positive here. Can anyone else work out why the market rates this share so lowly? Have I missed anything?
.
.
SUP (I hold)
190p (flat today, at 09:00) - mkt cap £222m
Supreme (AIM:SUP), a leading manufacturer, distributor and brand owner of fast-moving consumer products, announces its unaudited results for the six-month period ended 30 September 2021 ("HY 2022" or the "Period").
Strong profit performance driven by organic growth, M&A and product launches
Highlights table below looks good - in particular there’s been a large fall in net debt - which occurred in H2 last year, it’s risen slightly in H1 this year.
As with all companies, we have to be careful about prior year comparatives due to the pandemic, which generally makes the prior year figures easier to beat.
Note the decent profit margin in both half years.
Gross margin rose from 25% to 30% - a big increase, “due to enhanced product mix and increased in-house manufacturing”
An inaugural dividend of 2.2p is also positive.

.
Outlook - sounds encouraging, and it’s good to see inventories increased in order to protect against supply chain disruption -

.
Balance sheet - inventories are up from £19.8m to £26.7m - as explained in the commentary, that’s to stockpile to prevent shortages - that’s fine by me, and looks a sensible move.
Working capital - is strong, with net current assets of £20.9m, a current ratio of a healthy 1.65 (in my view, anything over about 1.3 for this type of business is good).
NAV is £26.4m, less £3.8m intangibles, gives NTAV of £22.6m, which is absolutely fine - this business is healthily financed, and the numbers overall look very clean to me - no unusual items, or large adjustments.
Cashflow statement - I can’t see anything untoward here, it all looks fine.
Broker research - there’s an inaugural note here from Equity Development.
Forecasts are 11.7p for FY 3/2022, and 13.4p FY 3/2023.
At 190p per share, that’s a PER of 16.2, and 14.2 - which looks reasonable value to me, for a decent quality company with rising earnings.
Investor presentation - is at 11:00 tomorrow, 8 Dec 2021. Registration with ED is here. The CEO Sandy Chadha comes across particularly well on webinars, in my view - an energetic, proven entrepreneur - which is what I look for.
My opinion - this looks a good company to me, on a reasonable rating, so it receives a thumbs up from me. I already hold a small position, and it’s now on my buy the dips list.
Note also that SUP shares have been resilient in the recent small caps sell-off. It has an upper-medium StockRank, which is how I see it too.
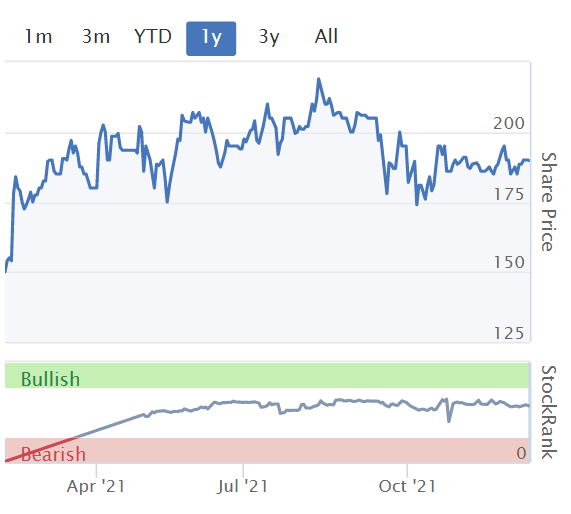
.
Sdi (LON:SDI)
190p (down c.3%, at 10:30) - mkt cap £188m
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing and control applications, is pleased to announce another strong set of results and solid operational progress for the six months to 31 October 2021.
Very impressive numbers today, a lot of which is organic growth, but also boosted by acquisitions, and one-off covid-related contracts - as disclosed previously.
H1 revenue up 75% (42% organic) to £24.7m
H1 adj profit before tax (PBT) up 89% to £5.7m - note the excellent 23% profit margin, indicating SDI’s businesses have considerable pricing power.
Adj diluted EPS is up 76% to 3.43p
Net cash is £1.1m (hardly changed in H1)
Bank facility of £20-30m (accordion) provides scope for further acquisitions, and the company seems very accomplished & experienced at making good acquisitions.
That all looks really good.
Outlook - is in line with expectations, with a helpful footnote too -
1 Analysts from our Broker finnCap Limited and from Progressive Equity Research regularly provide research on the Company, and the Group considers the average of their forecasts to represent market expectations for FY 2022 being Revenue of £45.05m and Adjusted2 Profit Before Tax of £9.2m
As we have previously disclosed, we expect sales and therefore profit in the second half of the year to be lower than in the first half, as the COVID-19-related orders at Atik have been mostly completed. Apart from this, we expect a continuation of favourable trading conditions seen in the first half and look forward to delivering a full year performance in line with market expectations.
This comment by the Chairman is interesting, and reminds me of Judges Scientific (LON:JDG) which of course has been a fabulously successful long-term investment -
I am more convinced than ever that SDI's business model, involving smaller niche businesses operating with a high degree of autonomy in technical, scientific and medical and life science market segments, offers a route to sustained value creation, and allows us to respond rapidly to events.
One-off covid orders - more information is given on this, and it does need to be adjusted for - i.e. don’t expect such rapid revenue or profit growth to continue -
Our Atik Cameras business continued to deliver, at a higher rate than in previous periods, cameras for use by a global OEM in RT PCR machines, which are (amongst other uses) the gold standard instrument for COVID-19 testing. We expect current orders, paid for in advance of shipment, to be fulfilled by January 2022, and we have no visibility of further orders.
This is a known factor, so not a cause for alarm. People just need to be careful not to extrapolate out H1 growth, and assume it continues at that rate when valuing the company. SDI has managed investor expectations well, being transparent about this issue, now and previously.
Balance sheet - looks OK to me. Highly profitable companies don’t need particularly strong balance sheets. This is fine, with a current ratio of 1.4, and no onerous long-term creditors.
NAV is £30.9m, less intangible assets of £25.7m (high because it’s an acquisitive group), leaving NTAV of £5.2m - that’s fine. As long as NTAV is positive, then I’m happy.
What I wouldn’t be too keen on, is if the company runs its NTAV negative by borrowing heavily to make more acquisitions. There again, given its track record & expertise in making good acquisitions, maybe shareholders might prefer SDI to push the boat out a bit, with debt fuelled acquisitions, to avoid dilution? With a market cap of £188m, and quite highly rated equity, I can’t see the harm in the company maybe raising £10m in fresh equity for the next acquisition(s) and matching that with debt. Anyway, that’s a decision for management.
Cashflow statement - looks very good, in H1 and comparative periods. No funnies in there, these look clean accounts, and it’s a genuinely cash generative set of businesses, which is using the cash to fund acquisitions - a nice strategy.
Valuation - thanks to Finncap for its update this morning. FY 4/2022 is 6.6p adj EPS, benefitting from the one-off orders. FY 4/2023 falls to only 5.3p, which I would hope to see beaten.
If next year’s forecast of 5.3p is not substantially beaten, then the 190p share price would be a PER of almost 36 times - which is too high.
There again, the company says it’s hoping to complete more acquisitions - “at least one in the financial year.”. More acquisitions could follow next year, so together with hopefully out-performance against the existing forecasts, might see it deliver say 6-7p EPS in FY 4/2023 - which would lower the PER (at 190p per share) to 27 - 32 - still quite high, but not outrageous for a high margin group of companies with a strong track record.
NB. Please note that unfortunately there is a data error on the broker forecast section of the StockReport here on Stockopedia. It erroneously says that 2 brokers have a strong sell recommendation on SDI shares. That’s wrong, please ignore, sorry about that.
My opinion - I do like SDI a lot. The valuation looks full for now, so it stays on my watchlist, as something that I’d like to add to my long-term portfolio at some point. It doesn’t feel the right time to be pushing the boat out on valuations, given current market conditions, so for me personally, I’ll happily sit on the sidelines for now, but with a firmly positive view about the company fundamentals.
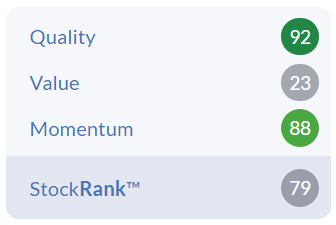
Neatly summarised by the StockRank system, as always!

.
Jack’s section
Tandem (LON:TND)
Share price: 601p (-4.6%)
Shares in issue: 5,244,116
Market cap: £31.5m
(I hold)
Tandem was one extremely neglected micro cap, struggling to generate meaningful revenue growth. This perception has changed over the past year or so, with shares rerating aggressively as demand grows. That means expectations have increased.

Covid has actually been an important catalyst (although management has worked hard behind the scenes for many years now) as the group sells bikes, ebikes, and outdoor leisure products - all of which have been in demand over lockdowns.
Tandem has its hands full managing supply chain disruption and rising costs, but it’s still finding room to push forward substantial growth opportunities. A key example is the new c80,000 square foot warehouse being built next to the head office in Birmingham. The project should create a more efficient and profitable business with greater capacity for expansion.
Still, this remains a Speculative, illiquid micro cap, and there has been a real opportunity cost to holding these shares in the past. Management and shareholders have previously found themselves at odds, too, so there are clear risks to consider (that said, tangible improvements have been made in this area - communications to the market are more frequent, and the group now has a broker providing research).
As reported in September 2021, Q2 revenue to 30 June 2021 was c14% ahead year-on-year. This improved in Q3 to 30 September 2021, with revenues 17% ahead of the prior year.
Q4 to 30 November 2021 revenue was broadly flat across the group when compared to the first two months of quarter four 2020, as the comparative period in 2020 was ‘particularly strong’ (back in Q4 2020, revenue was up 6% yoy).
There’s been a ‘robust’ performance from the toys, sports & leisure business with a number of licences including Peppa Pig, Paw Patrol, Spider-Man and Batman ahead of the prior year. Disney Princess, Barbie and Nerf have also grown strongly and Tandem’s own brands, including Stunted, Hedstrom, Kickmaster and uMoVe were all ahead of the prior year.
The group’s entry level golf brand, Ben Sayers, also continued to show ‘significant growth’ compared to the comparative period.
Stock availability in bicycles has improved, resulting in more despatches and increased bicycles revenue in November compared to September and October. Demand for Tandem’s lightweight Squish branded children's range remains very strong.
In e-mobility, the Wired range of e-scooters performed very strongly. Tandem expects this category will continue to expand in 2022 and has invested additional resource and capacity to meet the anticipated growth.
Home & garden products (mostly sold from Tandem’s online platforms), has been under greater pressure. This is a seasonal business, so that’s no surprise. Heating products and other indoor homewares are performing well.
As previously reported, increases in input costs, shipping and transport rates and adverse currency movements have placed pressure on gross profit margins in 2021 year to date. Notwithstanding these challenges, margins have held up well and we are beginning to see some early indications of improvements in costs, particularly with regards to freight.
Overheads remain tightly controlled and within our expectations, and as a result we expect profitability for the full year to be in line with or slightly ahead of current market expectations and we look forward to updating shareholders further in January 2022, following the Christmas trading period.
Conclusion
Some were expecting more definitive signs of growth at this point, but the update reads well once you consider Tandem’s lowly FY21 PER of 8.4x. Looking back, it makes sense that Q4 is a tougher comp: national retailers postponed orders in 2020 as the pandemic took hold, with delayed orders placed towards the end of the year.
And management has done a good job in ensuring the supply of its products and in managing costs, which are now easing. These past few quarters have not been a straightforward trading period and the team has proven its competence in running the day to day business.
The news that costs are improving is positive for other companies in similar situations. Not everyone is reporting this yet though, so Tandem seems to be slightly ahead of the curve.
Given that full year results could be slightly ahead, then the company might be slightly cheaper than the StockReport indicates. Of course, a lot of that depends on whether Tandem can maintain a step-change in revenue and the improved margins it brings, but I note brokers are penciling in an increase in FY22 earnings per share to around 78p.
The group is benefitting from some structural trends in bicycles, ebikes, and escooters, sparked by lockdowns but set to continue into the years ahead by some accounts. Tandem has done well to increase stock availability in bicycles, where revenue has grown, and its toys business is trading well. It is investing in escooters to meet anticipated increases in demand.
Perhaps holders were hoping for more but the signs are positive, in my view. It’s hard to say how the market will react, but Tandem stock has a history of frustrating holders in the short term. Illiquid stock moves can be extreme and I wouldn’t be surprised to see the price marked down. There are all the usual micro cap risks, such as poor liquidity.
But, ultimately, the shares are supported by a very modest valuation, resilient profitability, and some promising growth initiatives.
Mercia Asset Management (LON:MERC)
Share price: 37p (+1.37%)
Shares in issue: 440,109,707
Market cap: £162.8m
It seems as though community interest has been picking up in Mercia Asset Management.

The company provides ‘proactive specialist asset management’ and gives venture, private equity, or debt finance to regional small and medium-sized enterprises (SMEs) with growth ambitions. With so much activity centering around London, there could be good opportunities further afield for specialists.
Mercia provides capital across its four asset classes of venture, private equity, debt and proprietary capital: the group's 'Complete Connected Capital'. It initially nurtures businesses via its third-party funds under management, then over time Mercia can provide further funding to the most promising companies, by deploying direct investment follow-on capital from its own balance sheet.
The majority of its assets under management (AUM) is presently venture capital:

The vision is simple: to become the first choice for investees, investors and employees. Alongside this, it has stated twin strategic objectives over the next three years (from 1 April 2021) to achieve £60m in cumulative pre-tax profits and c.£600m cumulative growth in AuM.
Mercia currently has c.£948m of assets under management, so that would be a nearly two-thirds increase over three years.
Highlights:
- Revenue +20.7% to £10.1m,
- Adjusted operating profit up from £1.1m to £2.4m; operating profit +33% to £10.7m,
- Net fair value in direct investments +30% to £8.7m,
- Profit after tax +35.2% to £11.2m,
- Basic earnings per share +35.2% to 2.53p,
- Cash and short term liquidity investments of £52.1m,
- Net asset value per share of 42.4p.
There’s a big gap between adjusted and statutory operating profit. This is because the adjusted measure is operating profit before things like performance fees net of variable compensation, realised gains on disposal of investments, and fair value movements in investments.
Here’s the reconciliation (the highlighted row to the left is the current period, with the prior year comp to the right):

Much of the difference comes from ‘Fair value movements in investments’ - I understand why this is left out of the adjusted results, as it must be volatile, but it also reflects a fundamental aspect of Mercia’s business and so should be considered.
From the chief investment officer:
One of our two new strategic objectives over the next three years is to generate average pre-tax profits of £20.0million per annum, from a combination of the profits from our fund management operations plus the performance of Mercia's direct investment portfolio. Although I do not expect the contributions from fair value movements and realised gains to be delivered uniformly, I am confident that our assets have significant intrinsic value and we will see this unlock over the three-year period, as technical and commercial progress accelerate.
It is notable that the small net £8.7m increase in AuM comes despite c£39m of distributions to fund investors and shareholders.
The period under review saw net upward fair value movements of £8.7million, driven by significant commercial progress at Faradion Limited ("Faradion") and Intechnica in particular. Soccer Manager and Avid Games have also progressed well, and other fair value uplifts arose on the conversion of loans into equity at Medherant Limited ("Medherant") and progress against milestones at Sense. This was balanced against MyHealthChecked PLC's ("MyHealthChecked") share price fall from 4.4p to 2.0p.
Overall, assets under management ("AuM") increased 0.9% to c.£948m. Of this, c£762m is third-party funds under management, which is another aspect of the company to consider.
At the end of the period, we had c.£232million of liquidity across all our funds to support our future investment activity, plus a further c.£52million of cash on our balance sheet.
Investments
‘Investment momentum continues’ - in the six months to 30 September 2021, Mercia invested £55.1m into 74 businesses, including 38 new companies via its third-party managed funds' portfolios and £5.4m net direct investment into five existing direct investment portfolio companies.
The direct investment portfolio is valued at £110.3m (H1 2021: £101.6m; FY 2021: £96.2m) with 20 active companies (H1 2021: 22; FY 2021: 20). Further investments have been completed post-period end, with two new additions taking the total back up to 22.
The latest fast-growing companies added to the portfolio were Forensic Analytics Limited ("Forensic Analytics"), a provider of innovative software solutions to government and law enforcement agencies, and Pimberly Limited, a Manchester-based software-as-a-service company, ‘with both businesses being at a later stage to those historically invested in by our proprietary capital’.
There’s a useful breakdown of Mercia’s various investments in the chief investment officer’s review. Too lengthy to summarise here but worth a read, with c52% of portfolio investments in the Software and Digital Entertainment sector, c26% in ‘Deep Technology’, and c21% in Life Sciences
Outlook
As the 'COVID tide' starts to gradually recede, it leaves behind a new way of working for every UK business.
On the domestic front, we are finding that entrepreneurs in the UK regions have adapted quickly and coped well in many respects during the past 18 months… Mercia's ambitious resilience has enabled us to respond swiftly to these changes, guided by our vision of being the first choice for investees, investors and employees.
As the Group's positive momentum continues, we have a firm belief in Mercia's ability to make a valued difference across the UK, for the benefit of all our stakeholders.
Conclusion
This is the first interim period of a three-year strategic plan, so going back to that plan in more detail is probably a good starting point. It looks like there’s an investormeetcompany presentation today.
The valuation looks a little scary, with a forecast PER of 63.5x, but the unusually low EPS forecasts suggest to me that brokers are not modeling potential investment gains.

I’ve just had a quick look at some notes and that at least seems to be the case. That could lead to an opportunity, if you take a look at Mercia’s investments and conclude an out-of-consensus opinion on its prospects.
Or another way of thinking about it might be to simply multiply the forecast EPS by shares in issue (for FY22E), which gives about £2.5m of profit. The company itself says it is targeting pre-tax profit of £20m per year over the next three years. That would be more like 3.4p of EPS if you add in a notional tax charge of 25%.
So there’s certainly scope for your view to diverge with forecasts if you get digging into the portfolio companies and this third party funds business.
Mercia is an interesting company with exposure to high growth, specialist sectors, trading at a small discount to NAV of 42.4p. I think there’s two ways to look at the investment case: 1) to do a lot more work and have a high conviction view on the company’s direct investments and third-party business, and 2) to consider it from a portfolio perspective as diversification into high growth, regional enterprises.
The ex-London focus is a positive, in my view, and I think it’s worth doing more work here. It’s a difficult one to value but that might be where the opportunity lies.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
Hi Jack. Thanks for covering Mercia Asset Management (LON:MERC) . Tricky company to get to grips with. The starting point IMO is to split in two pieces and look at the dynamics and price of those pieces:
1) A listed VC vehicle trading at NAV. IMO its a pretty conservative NAV too due to the stage of investment and how Mercia invest. By being an accelerator for very early stage EIS or now VCT companies that they have nurtured Mercia tend to own dominant stakes in their portfolio companies. This means there's very little 'market price' in the mix (as opposed to something like Molten Ventures (LON:GROW) which is riding the market dynamics and aggressive pricing of VC and 'exciting' cos). I'm not saying their valuation are low (eg their largest position nDreams a VR/metaverse company is on high price to sales etc) but just that they have tended to not head into stratosphere. This gives downside protection and a degree of upside on exit and/or finance rounds that are more broad based. Clearly it introduces a risk in that they do need to socialise their holding into the broader marketplace (market and industry buyers)...but they have presence and seem to be able to this
2) A £760m FUM asset manager with high fee sticky business. This business currently not in the valuation at all so is free for investors today. What value should it have? Dunno. The dividend they pay comes from the op cf from this (they said on call yesterday that they may also sometimes use excess cash from proprietary realisations too...inc special divs...this is more idea than policy at the moment it seems). So above when I said 2.5% yield for fy22 (might be a touch high but just using for illustrative purposes and is where I think they will go...they are on course for at least 1.6%) that's being paid wholly or mainly from asset management earnings. 2.5% translates into a 17% yield on asset management if we give it a conservative (given type of biz they run) 3% of FUM valuation.
3% FUM valuation means asset management has £23m value. So add that onto £163m market cap. 3% seem low and then factor in that its a growing high fee long term mandate business. What can we get to? 10% of current FUM wouldn't be ridiculous if fulsome and something to be earned.
Clearly the two businesses are intertwined and not separate so sum of the parts analysis needs to be done with that in mind. Also, they don't hide that they could seek equity finance to make another acquisition like Northern Ventures. They've made a good job to date of that acquisition so why should they get a discount to valuation for that ambition when say an Sdi (LON:SDI) gets priced up for the same?
Moving parts....I think when you unpick the biz is undervalued for what it is and that is before factoring in growth which comes from both balance sheet investments (that are now maturing whereas 2-3 years ago still a bit unripe) and asset management 3rd party FUM.
In addition, current NAV of VC piece only (which equates to whole market cap as if asset mgt doesn't exist!) is about 1/3rd cash. This is safety...but its also a cost in that VC investing has J curve effect whereby new investments take time to show value...but they do have maturing investments to put opposite that...so on balance there isn't a reason to value below NAV unless sceptical about them (remember that costs don't eat into NAV as asset mgt biz covers them)
Mojo - thanks for an excellent write up on Mercia Asset Management (LON:MERC) (I hold)- which is not to diminish Jack's coverage - just to say that in my view multiple independent views give a much richer picture. And it seems that you likely have quite a lot of experience in this area - so thanks for sharing.
Like you I particularly like the evolution to the current position where the fund management funds the organisation without diminishing the growth story of the investments. But then I am a sucker for a growth story sitting on top of a business that pays the daily bills and this one ticks my boxes there.
Reasonably impressed with management so far as well. But I reckon it will take a while to get to know them. I think I'd be worried if they came over too polished and shiny?
And of course I like that it's been fishing long-term in a non-London pool and developed broad connections to Universities outside London - which I think offers opportunities to outperform in the very longterm. After all its not an accident that the industrial revolution did not start out in the square mile :-)
I only have a modest (for me) holding here - but assuming things continue to develop as well as they seem to be I'll be looking to increase it as soon as I can free up some funds,
cheers
Mark
Thanks. Its a tricky one to understand. One where the layers peel back a bit. I have a moderate to large position for me. I tend to be a bit early/contrary and then will run with things. I'm hoping to run with Mercia Asset Management (LON:MERC) for long while. Not my most exciting holding but I can see a double over 3 years from here which is my usual minimum criteria.
I've been in for a while (2019 sometime). Actually from before there last raise which annoyed a number of PIs...however I expected a raise as it was clear the business would need a bit more financing if one looked in detail so I was surprised at the surprise! Then surprised at the Northern acquisition...but impressed that it looked good buy.
I'd bought a bit sub 30p thinking cheap enough even tho raise coming (and an exit would have bumped price on me so decided to take a piece). Then participated in the raise but only modestly. Then I got lucky with covid sell off and double whammy on their sp whereby discount widened AND they needed to write down value of some of their more industrially exposed investments...the nature of the beast here is that you need to recognise your lumps early and wait for the sugar...and the biggest write up in value of a holding this interim was one of the industrial companies they had written down.
Overall I think they are good. The negative that everyone knows about is that they will tap market if they find another acquisition that fits...hopefully they can acquire the AUM without much dilution through good structuring. But at c.£1.4bn 3rd party funds which they are approx targeting through organic and inorganic (hopefully lot of former) it becomes v hard to ignore the value of their 3rd party asset management business.
Completely agree with Edward below, i have no idea why people seem to obsess over the US withholding for SOM, i'm more than happy taking 85% of a roughly 7% yield on a fantastic business where growth is by FAR the primary driver of returns....
74% return over the last 1 2months and people are put off by the thought of losing 15% of the dividend yield!
Am i missing something here?
Over the last year £1k invested sees £740 in growth + £121 in dividends (rough example and paid at the end of the 12 month)
£18.27 is withheld for US tax.....
I agree, 75% of a good div is good, and not worth obsessing about. However, there have been cases reported in the past, and I can't remember where, of people who should have been paying 15% actaully paying the full 30% as their broker failed to reclaim. That sort of issue is worth chasing up and checking.
Somero Enterprises Inc (LON:SOM) @peterg I think you mean 85% not 75%? Yes worth checking, some platforms fail to claim back the 15% tax. Or 30% if in a SIPP.
HL are pretty good on this sort of thing.
OK, I can't subtract!
It looks like Ig Group (LON:IGG) have paid Spectra Systems (LON:SPSY) dividend with 30% deducted, I will take this up with them.
A J Bell appear to have deducted tax at 17.6% for my Somero Enterprises Inc (LON:SOM) dividends in my ISA (0% for those in my SIPP). I’ll ask them to explain the calculation.
ignore the above comment. It’s15%. Well done AJBell.
Ig Group (LON:IGG) have taken off 30%, just been on the phone for about 1 hour with them, they will be looking into it. I won't hold my breathe.
I've had an update from Ig Group (LON:IGG), they did initially deduct 30% but there was contra entry some weeks later and then a new payment with 15% tax deducted, so they got there in the end.
Mercia Asset Management (LON:MERC) I thinking the best way to value is in 2 parts - the value of the assets held on balance sheet (42p) plus the fund management company using an earnings multiple (this is quite hard to gauge as it scaling up an only recently became profitable, but must be worth at least 10p). So on this basis the share price should be over 50p
Hi Paul,
I do hope that you will be able to post the market comment section that you have been working on, I always enjoy and value your opinions on markets, volatility, macro issues etc etc.
I imagine if you post it with tomorrows report rather than today, then more will see it.
Keep up the brilliant work Paul, and all at Stockopedia, I appreciate this superb service.
Regards Neville
Thanks Neville.
My market comment stuff might have to wait until the weekend, there's so much going on, and now market sentiment seems to be turning positive again, so it's maybe irrelevant? (I was thinking about how to deal with a downturn).
It's the same for everyone, you can only write interesting things when you want to, and it flows.
Best wishes, Paul.
Mercia Asset Management (LON:MERC)
Investor meet the company at 15:00 today
Somero Enterprises Inc (LON:SOM) - What account you buy it in can make a difference. Assuming you fill in a W-8BEN form (easy to do), you would receive 85% of the dividend in the UK in a regular account, with the balance being offsettable against UK tax liability. In a SIPP, you can get paid gross. But in an ISA, you lose the 15% withholding tax and there is no way to recover it. So purchasing Somero Enterprises Inc (LON:SOM) (and other high dividend US stocks like Spectra Systems (LON:SPSY)) in an ISA should be avoided.
Somero Enterprises Inc (LON:SOM) - So purchasing Somero Enterprises Inc (LON:SOM) (and other high dividend US stocks like Spectra Systems (LON:SPSY)) in an ISA should be avoided
Not sure that is accurate. Agree that if held in an ISA you wont be able to reclaim the US tax (15%) deduction. The net (85%) dividend you receive in the ISA will not attract UK tax.
However, if the shares are held outside an ISA then although you can reclaim the US tax (15%) against your UK dividend tax bill (where total dividends, UK and overseas, exceed £2000 annual allowance) you will have pay your marginal rate of dividend tax on the net (85%) dividend received.
Agree that at the basic dividend tax rate of 7.5% you will be better off outside an ISA as you are effectively able to reclaim half of the 15% overseas tax (i.e. pay 15% but reclaim 7.5%).
However, if you are a higher rate taxpayer then your dividends in excess of the £2000 annual allowance will be taxed at 32.5%. Therefore, outside an ISA you will be liable to pay 32.5% on your total gross dividend (i.e. 32.5% on net 85% dividend received plus effectively an additional 17.5% on that part already taxed overseas to make up to 32.5%) and hence will be much worse off.
You will be no better off outside an ISA if your total dividends (UK and overseas) are less than your annual allowance of £2000. This is because you wont have a tax bill to reclaim your overseas deducted tax (15%) against.
In summary you will only be better off holding shares outside an ISA where 1) You are a basic rate tax payer and 2) Your annual dividends (UK and overseas) exceeds the £2000 annual allowance.
Snazzytime
I think the point slowandsteady was making that it was better to use SIPP than ISA
ref this points
Agree that at the basic dividend tax rate of 7.5% you will be better off outside an ISA as you are effectively able to reclaim half of the 15% overseas tax (i.e. pay 15% but reclaim 7.5%).
No - you cannot do this (unless rules have changed recently) , although hmrc will often allow an incorrect claim to be made without raising thje issue at the time . I.e its easy to presume you can do what you thinjk you can do - sadly you can't. Tax reclaimable is limite to tax charged on that single line item of income (that was certainly the case last time i checked)
You will also be worse off outside an ISA if your total dividends (UK and overseas) are less than your annual allowance of £2000. This is because you wont have a tax bill to reclaim your overseas deducted tax (15%) against.
Is this bit correct ? are you comparing same net amount in ISA and non ISA (not sipp?) - if the same amount is received and no dividend tax is due then is this not a draw?
re Somero Enterprises Inc (LON:SOM)
hi rmillaree
I think the point slowandsteady was making that it was better to use SIPP than ISA
Perhaps - but that's not what he said.
No - you cannot do this (unless rules have changed recently) , although
hmrc will often allow an incorrect claim to be made without raising
thje issue at the time . I.e its easy to presume you can do what you
thinjk you can do - sadly you can't. Tax reclaimable is limite to tax
charged on that single line item of income (that was certainly the case
last time i checked)
Thanks for your correction. I was asuming a claim could be made automatically.
Is this bit correct ? are you comparing same net amount in ISA and non ISA (not sipp?) - if the same amount is received and no dividend tax is due then is this not a draw?
Agree - I edited my comment but not before you replied - apologies.
Somero Enterprises Inc (LON:SOM)
This seems to come up every time Somero do anything - 85% of a very good dividend from a high quality company is better than most I'm looking at currently.
Phil
Hello, Paul, and thank you for your regular reports on Somero. Your enthusiasm is communicative to the point that over the last three years I have built a position which is well over the daily volume traded on most days. Lovely, says I, the paper profit is now about 50 percent plus solid dividends. BUT, there's a hic, and this may be why you find the stock under appreciated. It's, precisely, that daily volume. Thanks to Somero I now look at this figure when investing in small companies. In effect, I am a prisoner of Somero, however happy I may be. There's no way I could cash in on my capital gain without taking a substantial haircut for lack of sufficient demand. I have concluded that the company is so overwhelmingly attractive that it must sooner or later become the object of a takeover bid. It is only in this way that I will realize my profits, and then some. But I'm no longer willing to continue investing in a frozen asset. An American company like this trading on the AIM exchange is just too limited in volume to attract high figure investors.
Maybe sell in stages as you did to buy in?
That would seem to make sense. If illiquidity is a real issue due to the size of an individual's holding, and the level of risk is higher than is comfortable, progressively reducing exposure has to be the way to go -- even if that means some loss of gains from holding the share.
Paul Scott's own story about the perils of being stuck in illiquid stocks and highly leveraged when the market turns down is salutory. Of course, if a holder is not using much margin, there is a chance that paper losses won't convert into cash despite illiquidity.
Somero Enterprises Inc (LON:SOM)
Agree that's normally a problem, and to be frank, the spread normally is not too good.
However, volume today at 1.6m shares was quite refreshing - some are suggesting this was an overhang cleared (?!?)
Phil
Tpximpact Holdings (LON:TPX) interim results presentation by CEO & CFO. They are super bullish, having exceeded what they promised at listing. They seem to go from strength to strength. With these results, revenue +77%. Profit after tax +109%. Adj dil EPS +81%. The full year is in line with upgraded expectations. They present their new vision by 2025 of 10-15% organic revenue per annum & £200m run rate revenue. Firing on all cylinders. Video & podcast.
Hi Paul
Interesting to see that the current Stockopedia consensus EPS forecasts for Supreme (LON:SUP) are higher than those estimated by Equity Development.
As you state. ED have 11.7p and 13.4p for 22 and 23. Current consensus at Stockopedia is 13.2p and 15.2p. 5.8p EPS in H1 so plenty still to play for.
On the dividend front, both show 6.6p for 2022 albeit ED are more conservative for 23 at 7.3p vs 7.61 at Stockopedia.
Given Supreme (LON:SUP) stated in their FY results
"As highlighted at the time of our IPO, we intend to pay dividends to shareholders in an aggregate annual amount equivalent to approximately 50% of net profits, retaining the balance of earnings from operations to finance our future expansion. Our dividend payments are expected to be split into a one third interim dividend and a two thirds final dividend and we expect to declare our first interim dividend following the publication of our interim results for the six-month period to 30 September 2021."
I am wondering whether ED have not been paying attention! Certainly their estimated dividends and EPS are completely inconsistent, showing a much higher payout ratio than is Supreme (LON:SUP) stated policy.
Excellent results from Premier Miton (LON:PMI) today, well ahead of forecasts in Stockopedia, seemingly no reaction from the market!
Indeed this historic year, they nearly made the forecast for the current year.
And with £47.7m of cash on the balance sheet earning nothing.
Operating cash generated of £36.5m, minus tax, lease and capex of £9.4m gives free cash of £27m. On an enterprise value of £228m, a fcf yield of nearly 12%. And that is historic.
By the time upgrades have come through, this will be on a single figure p/e with about a 7% yield, cash of 17% of mkt cap, generating a fcf yield of over 12%.
If that isn't a small cap with value, i don't know what is!!
You might have guessed, i hold.
C
Premier Miton (LON:PMI) I guess everyone roughly knew their AUM (and hence their profits) so probably no surprises to drive a re-rating. I must admit I'm slightly less keen than I was given their large exposure to UK equities which continue to see large outflows. That said, things seem to be holding up well for them with solid inflows.
Bouden54, re: UK seeing large outflows.
I'm not sure this is true.
Have a look at page 8 of the results presentation:
https://www.premiermiton.com/w...
UK only funds under mgmt grew from £2.0bn to £3.1bn during their fiscal year. That's 52%. The Allshare was up about 21%, so even with some outperformance, that is a reasonable inflow. Page 31 of the presentation shows the growth of each of the individual UK funds.
The area that has seen outflows has been the externally managed multi asset business. This is now down to under 16% of assets under mgmt. It also has a lower than average margin to PMI as they have to share the fees between PMI and the managers of the underlying funds. This area has been a drain on the group for the last few years, but is now becoming much less relevant, allowing margins to expand significantly in the future.
Bizarrely, 30 mins later, i still hold! :)
C
Sorry I was talking about large outflows across wider industry. Premier Miton themselves seem to be doing well, but I've seen several stories about large flows across the UK equity sector as an whole. I think my point still stands that they could be vulnerable to further outflows in UK equities, even if they have withstood this so far.
Indeed, good point, i misunderstood your original comment.
Hopefully the exceptional performance of the Funds will mitigate that issue....but it is difficult to swim against the tide forever.
Maybe people missed results for Premier Miton (LON:PMI) amongst the other 10 RNSs today. I did and I hold quite a few (although less than a few months ago)! Puts the yield up to a nice 5.7%.
Hi Paul,
Somero Enterprises Inc (LON:SOM) is my largest holding. It ticks so many of my criteria for investing.
“Hence overall my view is highly positive here. Can anyone else work out why the market rates this share so lowly? Have I missed anything?”
This is almost exactly what I’ve been thinking. Assuming there are no hidden demons then I’m just trusting that the market is very good at realising true value in the longer term.
Hi Revs8,
Thanks. The thing I like about my (medium-sized) position in Somero Enterprises Inc (LON:SOM) (I hold) is that those bumper divis just keep rolling in. So whilst there's not been any re-rating (in fact the PER is falling!), at least the share price edges up slowly, and there's a lovely flow of divis to keep us happy.
It reminds me a bit of Avesco years ago, which was irrationally cheap, and paying nice divis, for a long time. The eventual outcome there was stellar, when the company was restructured & sold.
Hi Paul,
I've held Somero Enterprises for a number of years now.
I spent some time in the flowing concrete business, whilst working in Canada/USA. a few moons ago.
This has enabled me to understand how Somero has managed to capture value from this market for such a long period of time.
It would appear that Somero is categorised as a Construction Stock. It should be looked at in a different way!
SM
Somero Enterprises Inc (LON:SOM)
Hi SmilingMickey
Thanks very much for the comment.
I wondered whether you would be able to share any of your own personal insights from the world of flow concrete?
Does Somero really have a unique, niche product as they claim? Is the ability to produce a flat level floor the true benefit of using Somero, or is it the machines they produce and high customer service that give them their USP? Maybe both?
I'd definitely be interested to see how you would categorise them, if not under Construction.
Many thanks in advance!
A
Hello Abtan,
Somero's US customers are in the main smallish local construction businesses who have experience of use of flowing concrete in flooring. They would be run by entrepreneurial folk who employ construction workers as and when they win contracts. If they win a flooring contract (with say Amazon) for a building, they will probably not have the in house expertise to progress it without support. This is where Somero comes in. Their costs will have been allowed for in the quote! The end user/contractor will both have the confidence that a flooring job is likely well done and will not require ongoing expenditure on repairs etc if it is supported by Somero's expertise.
Note that Somero's volume of business moves up and down (in the US) depending upon the overall level of construction business at the time. However its margins do not. They are the market leader by a mile. In my view they are a service business with a superior level of IP in a market they dominate (for now.)
Somero Enterprises Inc (LON:SOM)
Thanks smilingmickey,
I'm particularly surprised that "Their costs will have been allowed for in the quote!"
This is quite remarkable really. I always thought the construction business would pay for the Somero equipment, but if it's Amazon et al essentially paying for this, then that makes Somero an even more enticing proposition.
Presumably once a contractor is on-boarded they may continue to use Somero in the future too, irrespective of whether the end warehouse user specifically requests them?
Thanks very much again for taking the time to respond - most appreciated!
A
£SOM has not always been a steady investment. Between May 2018 and Sept 2019 the price fell by more than 50% from a peak of around 400p on the back of consecutive profit warnings ahead of 2018 FY and 2019 HY results. Adopting an approach based on Stockopedia's profit warning analysis or even a very generous stop loss I suspect most people would have sold out at some point during this period. Unfortunately I did (!) and it is very frustrating to see the price nearly triple from its lows. This tends to support Paul's view that long term holding is the best way to go for most shares despite Ed's success with the annual rebalancing of the NAPS portfolio.
Yes I was tempted to sell up. at one point I did reduce my holding slightly during these dark days. However Somero always generated enough cash and continued to pay handsome dividends when they considered it prudent to do so.
Holding an undervalued stock for the long term can be no bad thing!
Good morning Paul, would it be possible to look at maiden H1 results for Supreme (LON:SUP) ?
The results confirm strong progress, a 3.5% dividend, and slightly ahead of expectations going forward, which I am hoping could result in a beat. Thanks you.
Sorry Paul, just noticed below that you are going to cover Supreme (LON:SUP) .
I don't understand why i can't buy Somero on the Barclay platform.
Somero Enterprises Inc (LON:SOM), Probably to do with the US tax, can you buy Spectra Systems (LON:SPSY) ?
Some platforms can’t be bothered to handle this issue.
Exactly this, it's the US ISIN number despite being LSE listed. I spoke to them yesterday about Spectra Systems (LON:SPSY) and explained that there were a great many platforms taking their dealing custom. They "assure" me they are looking to introduce this capability early next year.
So can anyone please explain - Why is Somero - an American company, quoted on the LSE. Appreciate they do have a UK office - but it does seem odd ? thanks
Re Somero; this is an old favourite, you will find this has been covered before . Somero was for a while held by a UK private equity company, which found it easier (for them) to take it public in the local UK market.
Somero has been notable in the high level of attention to its UK market shareholders and should you be in Fort Myers they have been very welcoming to shareholders visiting their Head Office.
Somero Enterprises Inc (LON:SOM)
Why is Somero - an American company, quoted on the LSE.
Direct answer from Jack when quizzed by Paul yonks ago as follows
JC:
Yes. In 2006 before we listed on the AIM, we were owned by a private equity company calledThe Gores Group, out of California in the US. They had brought other companies publiconthe AIM, and they thought that that would be the best fit for us, given the size of the companyat that time.So that is how we started our journey on AIM and it has been a wonderful journey. We thinkit is the right fit for us, because we have ... at our size, we wouldn’t fit well on the NASDAQin the US market, and I believe we are the right size for the AIM. And we have been very,very pleased with the calibre of the investors and the shareholders we have got. They are veryquick to understand the value proposition of Somero. And on top of that we get a NOMADthat can give us guidance to make sure that we are staying within governance and all of theissues that we have. So it has been a very, very pleasant experience for us.
http://qualitysmallcaps.co.uk/...
Have you filled out a W-8BEN form to enable trading in US securities?
Or based on other comments here it could be that it's a rubbish platform.
No issues for me with Halifax or HL.
Hi PeteJame
Try AJBell you invest, they made it super easy for me and I get the full dividend in my SIPP.
PeteJame - I trade in Germany with the Deutsche Bank. For the first time a purchase order of Somero was refused. Something to do with Deutsche Börsen quality criteria. I suspect there's another reason, but I haven't found an answer.
Somero Enterprises Inc (LON:SOM), This has come up before about Deutsche Bank, from memory it maybe to do being AIM listed.
Can you buy Asos (LON:ASC) ?
Ref Somero Enterprises Inc (LON:SOM) , I think it is Deutsche Bank's individual decision and unlikely to relate to Deutsche Börsen quality criteria or other German regulatory rules. My broker is DeGiro which is owned by (and a branch of) flatexDEGIRO Bank AG. "As a German regulated bank, flatexDEGIRO Bank AG is primarily supervised by the German financial regulator, the Bundesanstalt für Finanzdienstleistungsaufsicht (BaFin)."
DeGiro didn't offer Somero Enterprises Inc (LON:SOM) as a product until a couple of weeks ago. I emailed them a request to add the product after getting frustrated that I couldn't buy what looked to be a very promising stock. It took them less than 36 hours to add Somero to their product listing. I was favourably impressed.
No problem with Interactive Investor after I filled out the W-8BEN form.
I have had this problem - there are other shares you can’t buy in your isa or SIPP with Barclays - these are all American linked although London listed. I suspect it is a cost thing but if moving brokers would not be so massively inconvenient I would do so as I am prevented from buying some v good companies - apart from somero I think spectra systems is another example. You should complain and demand an explanation. If enough people complain maybe it will change
Why not open another ISA next tax year with a different platform?
Water Intelligence (LON:WATR) would be another.
Letter from Barclays in the post today about starting to allow international trading
Me too !
Arden have just released a broker report for Somero Enterprises Inc (LON:SOM)
I personally am not keen on the Arden reports, but they do have a similar valuation for SOM as fincapp does. 750p and 755p.
I'm wondering about Solid State (LON:SOLI), as i'm not sure about its application of adjustments to operating profits, are they reasonable? thoughts?
re Solid State (LON:SOLI) (I hold), the Note 5 in the accounts details nearly a million of adjustments and amortisation relating to the two companies they have bought, which seems to account for most of the difference between reported and adjusted profits. There are different views on how one should regard these accounting adjustments - Paul usually argues that you should concentrate on the cash, Graham Neary used to argue that if a business is writing off chunks of value in the companies it has just bought, then it must have paid too much for them. There are also share based payments charges, which I think most people reckon are better set against profits.
Do you have any specific worries about these particular adjustments?
I think the US tax on dividend’s is an issue for Somero Enterprises Inc (LON:SOM) as it appears to be for Spectra Systems (LON:SPSY) Both excellent companies which are very cheap and which I hold .
Yes can be an issue, but I hold Somero Enterprises Inc (LON:SOM) in my SIPP, so not an issue with US tax.
If you fill in a W8 BEN you will get withheld 15% by the US. This you can then claim as a Foreign Tax credit and off set it against your UK dividends in your tax return. same for any foreign stocks. I'm not sure re SIPP but you get withheld in an ISA
I believe the base withholding tax is 30%. You should get half back in an ISA and all of it back in a SIPP.
This is because the US authorities apply the same rules as they apply to analogous accounts held by US tax payers so we get equal treatment.
Somero Enterprises Inc (LON:SOM)
JohnEustace
"You should get half back in an ISA and all of it back in a SIPP."
I think the problem with some SIPP providers is that they don't all ensure you pay no tax on us divis even when forms have been completed , so whilst divis can be paid in full not all sipp providers deliver what they should do in that regard ! - luckily for me my sipp provider does ensure i get the full divi.
I hold in my ISA with Iweb and I get clobbered for the full 30%. Iweb say it is something to do with the dividend being paid in CREST form and thus there is nothing they can do about it. Something to bear in mind if you use Iweb.
I hold in my ISA with Iweb and I get clobbered for the full 30%. Iweb say it is something to do with the dividend being paid in CREST form and thus there is nothing they can do about it. Something to bear in mind if you use Iweb.
Of course they can do something about it! Other brokers manage just fine with a completed WBEN form which can be signed on-line, no fuss. I have an Iweb account but don't really use it because they are a "peanuts = monkeys" type operation. Try and do anything even slightly out of the ordinary and you get their standard "Computer says No..." response. With brokers you get what you pay for, unless you're with Barclays by the sounds of it - they sound proper rubbish!
All the best, Si
I don't disagree. I wasn't saying "they can't do anything about it" as a defence of them. It's what they tell me when I ask why I keep getting hit by 30% US With holdings tax. I mention here as a heads up to others who may use IWeb.
Don't shoot the messenger! ;-)
iweb are 'proper rubbish'. It is run on the cheap, trying to contact them is a nightmare and when something goes wrong, as it inevitably will, they are unable to sort it out, even when you make a complaint. I moved, and haven't regretted it.
Paul or Jack take on marmite stock Mercia Asset Management (LON:MERC) ?
Mkt cap at NAV if use very conservative approach of adding direct inv portfolio £110m and cash £51m
Factor in that there is a 3rd party funds biz £762m FUM (funds under mgt) in mainly high and sticky fee income venture/PE type business and you can add something to the 'NAV' to get to the market cap being at discount to NAV. Debatable where the valuation on 3rd party stuff should be put...I think higher end due to fees and stickiness...and relative novelty of space they operate in (there's a barrier given their non London network).
Tripled interim dividend payment...as the biz moves into net FCF from operational basis (ie from 3rd party funds biz) -> looks like at sp at start of today we have approx >2.5% annualised dividend now assuming they at least double their final dividend from 0.3p to 0.6p
Pretty uniquely positioned business in that it invests in early stage growth businesses ex London. Until now the portfolio has been relatively immature so the growth J curve for early stage businesses has been a headwind (ie lose money early thro write downs before winners show through) plus there was a covid hit too. Now we are much more in position for some write up and positive realisations. Note, they have historically recognised and managed their under performers well (these hits come before gains).
The only potential disappointment is that they didn't have growth in 3rd party FUM during 6 months. Always lumpy and partly they had relatively high distributions at c.5% of 3rd party FUM as tailwind. But some post period end wins and pipeline looks good.
Tricky to look at and value as really its two businesses folded into each other - a listed venture cap fund and an operating company (asset manager).
Its not likely to be a short term rocket but there's a very strong underpin to valuation and meaningful potential for incremental value creation. Quite diversifying holding as not caught up in market betas and sentiment too much. Plus as the balance sheet investments are non London with Mercia holding significant stakes the valuations are conservative protecting downside and giving chance of good uplift on developments and exits
Mercia Asset Management (LON:MERC) - additional point for perspective
Re dividend. Lets say they are now at 2.5% yield as they double final dividend. That's c.£4m pa.
Apply (very conservative) 3% of FUM valuation on 3rd party asset management biz with £762m FUM ->£23m valuation on that. Means that the yield on that biz is 17%pa! They pay the dividend out of the cashflows from 3rd party biz and not the cash generated from realisations in the proprietary balance sheet investments (as that cash is used to reinvest and grow/evergreen the balance sheet investments).
Point? Should probably give a higher valuation to the 3rd fund biz. At least double my conservative above? Can be debated what...but maybe there's £50m of straight unrealised sum of the parts value in Mercia today...before we factor in growth etc?
I like Mercia Asset Management (LON:MERC) and have a medium position - less than I have in Ip (LON:IPO) - but as you say it gives some handy geographical and market diversification and optionality.
Interesting company. I looked at Ip (LON:IPO) and Molten Ventures (LON:GROW) amongst others - both more exciting than Mercia Asset Management (LON:MERC) and in the case of IP definitely a greater upside potential. Molten has been the pick of the bunch in performance terms. I believe Mercia has a better balance of upside/downside than both and a somewhat more prosaic (so 'robust', 'durable', etc IMO) value generation process than the other two. I like IP and have thought about it...I dislike Molten as I think its powered by meme and public market valuation dynamics and has large downside potential that if/when it comes perhaps breaks their corporate model. I think Mercia has the most 'undiscovered' value and growth potential to it and has durability. Time will tell
Is there any chance to share your views on the latest news from Iomart (LON:IOM)? They seem to be broadly in line with the "lowered" expectations from the last trading update in October...many thanks
Good looking half year numbers from KINO. I would appreciate a second opinion.
Initial contract for "a cognitive cleaning operation for Compass' marquee clients". Is this brainwashing? No, it's toilet and meeting room cleaning based upon usage as well as schedules.
Joy :-)
timarr
I love a good preamble! Keep up the great work guys!
Good morning Paul. Your comments on this morning's Half Year Results from Supreme (LON:SUP) would be appreciated.
I second thoughts on £SUP
Sure, Supreme (LON:SUP) (I hold a small amount) is on the to do list, should be up by 9am
Regards, Paul.
Supreme (LON:SUP) might be worth waiting till tomorrow as they have a presentation.
Sdi (LON:SDI) seem to have delivered good interim results.
The one off Covid income remains a feature and no doubt a concern for some.
This is a long term hold for me. I love their transparency and the fact they always seem to underpromise. No hype.
Paul, I would welcome your thoughts.
Morning CamRaid,
Yes I'll be looking at Sdi (LON:SDI) later this morning.
Regards, Paul.
You are a scholar and a scout!!
I think he is a Gentleman and a Scholar.
Somero Enterprises Inc (LON:SOM) (I hold) further improved guidance figures. This company is riding the warehouse construction wave and the management appear to have excellent control. A breath of fresh air in the recent climate for small cap stocks. We’ll done to those who bought the recent dip.
SOM great new products launched and on the way, great company, what's not to like in since April 2020