Small Cap Value Report (Tue 7 July 2020) - SOS, HFD, PHTM, RCH, FCAP, PCIP, ALT

Good evening/morning, it's Paul here with Tuesday's SCVR.
Estimated timings: I'm aiming for 2pm finish. Edit at 13:37 - make that 3pm, some companies are taking longer to work through than I anticipated.
Update at 15:10 - today's report is now finished.
.
Reminder for Mello Virtual
This is coming up, this Fri & Sat, 10-11 July. It will be just like a normal Mello investor event, but online.
I've been roped in to comment about small caps in a panel discussion, so am looking forward to that.
David has kindly provided Stockopedia subscribers with a 50% discount code: SCVR50
Sorry if you've already paid full price (which I have too), but it's so cheap anyway, it's not worth getting into a lather about it either way.
There are some stand-out speakers, including quite a coup getting Sir Martin Sorrell as a keynote speaker! His very forthright views should be illuminating.
Pub re-openings, part 2
Expert industry sources (mostly Mark Brumby of Langton Capital) told me that the pub/restaurant re-opening is being phased, and that some operators had decided to defer Super Saturday to Manic Monday instead. Therefore, out of duty to my readership, I felt compelled to research what was happening in Bournemouth once again this Monday evening.
Pleasingly, Bigdish (LON:DISH) dining app (in which I have a >3% holding) seems to have done a soft relaunch, as I successfully booked a table for 1 (under the name of Billy Nomates!) at Nativ - a small, and basic African themed independent takeitaway/diner. To say that staff were welcoming is an understatement! They welcomed me like a long-lost friend, which was wonderful. Mind you, I have been re-reading the Dale Carnegie classic, "How To Make Friends & Influence People", which reminded me to smile and be generally affable. The results of doing that are genuinely remarkable - people respond so well to warmth. This is probably my new favourite book, having slightly eclipsed Superforecasting, which I've read twice now.
As my old PE teacher, Tim Hall, at Poole Grammar, used to say in a broad Dorzet accent, "Yer get out, what yer puts in!". He applied that to sports. He was right. I put in nothing into sports, and got nothing out. Chasing balls around a field has always struck me as mindless, and always will. But his general philosophy of getting out, what yer put in, is very true in other areas.
Oh yes, I got 25% off my delicious grilled chicken & prawn skewers at Nativ, and I recycled my 25% discount into 2 pints of Nigerian lager (excellent actually), and some fried plantain. The manager said they had been open right throughout the lockdown, and takeitaway business had been good. Which reinforces a point we were discussing yesterday - restaurants have to do takeitaway well, in order to survive until dining in returns properly.
Next, I decided to revisit the 800 to 100 capacity O'Neills across the road. As luck would have it, the burly but affable doorman with the bushy beard from Saturday, was also working today! I said, Hello again, and he remembered me, invited me to sanitise my hands, then took me to a table outside. As he led the way, I said, "You appeared in my stocks & shares blog this morning. I described you as burly but affable". Without hesitation, he affably retorted, "I'll take that. My mother calls me far worse!". I was about to make another joke, speculating what insults his mother might use, but thought better of it.
Many businesses forget that the person at the front, interacting with your customers, IS your business in their eyes. Put someone bolshy there, and they do incalculable damage to your business's reputation & longevity, something that many business owners seem oblivious to. That very point is told via a story about surly Dept Store staff in the Dale Carnegie book actually.
I had to download yet another drinks ordering app, but was rewarded with a crisp, bubbly pint of Peroni, in the evening sunshine outside O'Neills, which was bliss. I read another chapter of my biography of Cecil Rhodes, as unlike many millennials, I like to acquaint myself with the facts, before virtue signalling about the past. Blanket memo to millennials - people in the past were all nasty! Get over it.
After that, I decided to have another go at the Slug & Lettuce. It did occur to me that my previous mishearing of "buggy" might have meant a mobility scooter? After all, when offering ID to prove I was over 18, some sarcastic doorman in Cheshire did once tell me that "We don't take bus passes, Grandad!" to the hilarity of my niece & nephew at the time. That was at Christmas.
Slug & Lettuce is another Stonegate chain, which is probably regretting its debt-fuelled acquisition spree now. Anyway, the doorman was very professional - he looked a bit like a semi-retired wrestler, with a neck which was considerably wider than his head. But he couldn't have been more welcoming, and explained the one-way system to get to the toilets, etc. Then some drunk girls came in, and said they had a reservation for 8. Then one said, "No, it's not 8. It's 6 people, plus two". They were going the wrong way around the one-way system, which took a while to resolve. A bit like me on a boris bike.
After that, I went somewhere else, where was it? Oh yes, the Moon & Pig, yet another Wetherspoons, in the Square. This I'm afraid was a bad experience. The doorman sounded Italian, was wearing a clear plastic visor, and seemed quite agitated. His dictatorial tone, stand here, do this, do that, immediately put my back up, so I started challenging him. My standard phrase now is, "Relax, I'm immune", and then wave my antibodies test result at them. This generally does not go down well, so I might stop doing that. In fact, it's always gone down between quite, and very badly.
In the end, I asked the agitated doorman, why he's so agitated. "Because I'm high risk, I'm diabetic", he replied. Oh I see, well I quite understand. You shouldn't be on the door, I quietly commented. "I can't afford not to work", he explained. Food for thought, isn't it. Life can be complicated. Anyway, the Area Manager of 'Spoons probably needs to reallocate him to other duties pretty damn quick, before he alienates the rest of their customers.
Inside the Moon & Pig (where chavs tend to congregate), it took 12 minutes for my pint to arrive, by which point I was ready to leave, having to endure the mindless cackling of some drunk women opposite. I did notice, whilst leafing through the Wetherspoons in-house magazine on the table, that it had a short section condemning our hero, Mark Brumby of Langton Capital! It turns out that Mark had inadvertently chosen his words incorrectly, and the full force of Tim Martin's wrath seems to have descended upon Langton Capital, resulting in an apology. Fair enough I suppose, if commentators get things factually wrong, we have to put it right asap. There's no shame in that, it's good practice.
Are there any additional points learned from tonight's rigorous research?
1. The new rules need to be handled in a firm but fair way. Nobody likes being told what to do. So pubcos please note - a door Nazi security person, is a very quick way to send customers to your competitors.
2. Eating out again, in any kind of restaurant, is pure joy! I've missed it so much. Tip the staff well, and smile a lot. It's stressful for them too.
3. Ordering apps - is it an imposition having to download & use multiple apps for different pubcos? Not really. A lot of them seem to use the same QR code as you enter, to register your visit, for tracing purposes. The drinks/food apps only take maybe 5 minutes to set up. I don't have a problem having 4 or 5 different ones on my smartphone. They all work in much the same way. I'm sure things will become more slick as time progresses.
4. Pubs were quite busy on a Monday. So it looks as if the public are already getting the point that we need to spread our socialising out during the week, and not all rush into town on a Saturday night. Maybe that is easy when half the workforce is on furlough? Things might change again when people go back to work, or are made redundant?
5. Staffing - the burly but affable doorman told me that staffing had been reduced. Hence he was more upbeat about profitability, despite reduced customer numbers. He struck me as pretty intelligent, so maybe we need to get some data about that from trading updates in the next few weeks, before drawing a conclusion?
.
Overall - I think the stock market could be correctly balancing risk:reward at the moment. I don't see hospitality shares as being particularly cheap, but that's fair, given that 2021 should see a return to normality, against poor results for 2020. Maybe the stock market could be correctly weighing up risk:reward? It looks about right to me.
That's probably enough about pubs for this week!
On to today's news.
.
Sosandar (LON:SOS)
12.4p (up 20% today) - mkt cap £23.8m
(I'm long)
Q1 Trading Update (relates to Apri, May & June 2020) - I went through the last update with a fine tooth comb here on 9 June 2020. Current trading sounded quite good, and spending was slashed because of covid, to preserve the dwindling cash pile. We all know Sosandar's going to need another fundraising later this year, it's obvious, whatever management say.
Q1 revenues are up 54%. This is good, but down from the 62% previously reported for April & May. So it looks like growth slowed somewhat, I make that +38% growth in June alone. Not bad, but the effect of reduced marketing spend looks like it's starting to be felt, with slowing growth (cunningly obscured in the RNS today). Q1 last year is a soft comparative, as it was before the big marketing spending splurge started in autumn 2019.
Profitability - this sounds a lot more encouraging;
As a result of the growth in sales together with a significantly decreased marketing spend, the Company has seen losses in Q1 reduced by c.70% compared to the same period in the prior year.
In June, the Company's monthly sales performance improved again, with a strong gross margin from a shift back to full price purchases following some promotion and discounting in early April. As a result, the Company recorded results very close to breakeven in June.
That gives the impression of an increasing sales growth trend, which is not true, as demonstrated above, sales growth was slower in June than in April + May. Being very close to breakeven in June is excellent news. However, bear in mind that the company was operating on a skeleton staff, having furloughed many staff, and having slashed marketing spending. Those are not normal conditions. However, it does show the excellent flexibility of an online business model - in tough times SOS can dial down its costs drastically, in a way that physical retailers can't so much.
Marketing - spend has been greatly reduced, but they've still managed to in crease new customer numbers by 24%. That does beg the question whether previous marketing spending was wasted money, at least partially? If growth can still be achieved at a respectable pace without much marketing spend, then I'm all for that. "Controlled and careful" new customer acquisition (i.e. marketing) will resume in the busy season from Sep to Dec.
Cash burn - April seems to have gained an extra day!
Cash at 30 June 2020 remained broadly flat at £4.4m, showing only a very marginal decrease since 31 April 2020. Whilst the Company remains prudent in its approach to discretional spend, carefully monitoring KPIs and cash management, it expects to cautiously increase marketing spend and investment in new products going forward in order to accelerate top line growth.
This is reassuring, but is being boosted by the furlough scheme, and probably VAT deferral, although that is not mentioned. Can it reach breakeven without another fundraising? Extremely unlikely in my view. I think it's likely to need another £4-5m fundraising later this year, or early next year. That's not necessarily a problem, because breakeven is at least in sight now (maybe next year?), and we know it can slash costs if needed. But it does mean that shareholders should probably brace for another c.20% dilution.
My opinion - I had rather cooled on this share, after a poor update earlier this year. It seemed to be going off the boil. But fair play to the team in Wilmslow, they're a tenacious bunch, and you certainly can't fault them for determination to make this work. Once scale is achieved, then things could get very exciting, but it's still well short of the c.£20m p.a. revenues needed to reach breakeven.
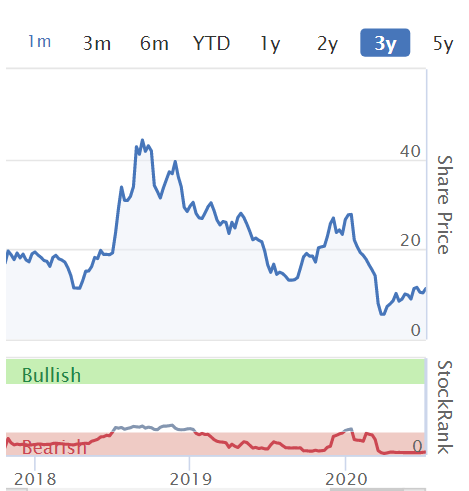
Overall, I think the current price is reasonable, and I'm happy to hold. I have lightened the load somewhat along the way, so it's no longer a huge outsized position for me, it's now a regular mid-sized position. That was because the increased dilution from repeated fundraisings has reduced the % upside, hence why I don't want to be massively overweight in this share any more.
.
.
Halfords (LON:HFD)
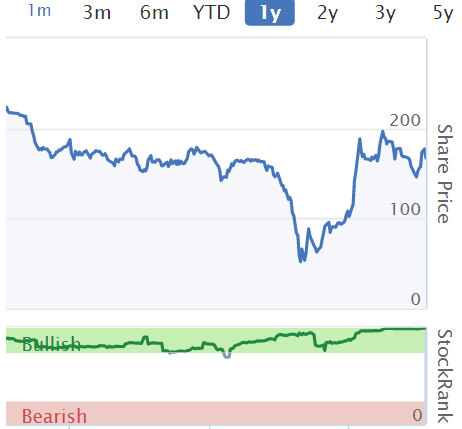
167p (down 6%) - mkt cap £332m
Preliminary results - for the 53 weeks to 3 April 2020.
Halfords has suffered less than some other retailers through this crisis, because it was classified as an essential retailer, hence allowed to keep its stores open. It also benefited from the trend towards cycling (likely to continue, as people seem reluctant to get on buses, trains, or tube).
Underlying EPS was almost flat against last year, at 24.3p (adjusted for 52, instead of 53 weeks). The company says that underlying profitability is ahead of guidance. At 167p per share, this is a lowly PER of 6.9
Free cashflow is said to be £54.6m - impressive.
Net debt of £73.2m doesn't seem excessive.
Large adjusting item of £32.1m relates mostly to an exit from Cycle Republic.
Current trading & outlook - the FY 03/2020 results are good, but include very little disruption from the covid lockdown, which began in late March. Recent trading for the 13 weeks to 3 July, is -6.5% on a LFL basis. This shows a much better trend, since LFL sales were down -23% in the 4 weeks to 1 May. It's a pity the company didn't provide a table, with more granularity on the sales throughout Q1, but the trend seems to have strongly improved within the quarter.
Cycling is the stand-out sector, with +57.1% revenues in Q1. That's offset by reduced motoring spending.
Cautious outlook due to macro & virus uncertainty.
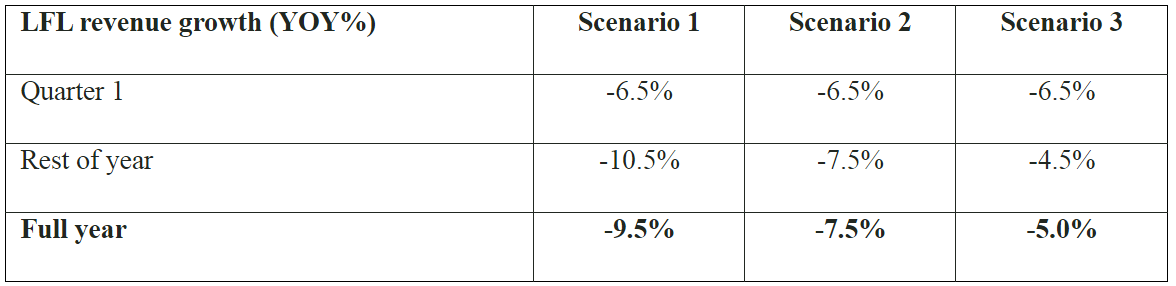
Scenario planning - this section is absolutely excellent, and shows what all companies should be doing to guide the market (but very few actually are). Here are the company's range of scenarios, moving from left to right, I would characterise these scenarios as: bad, middling, and OK;
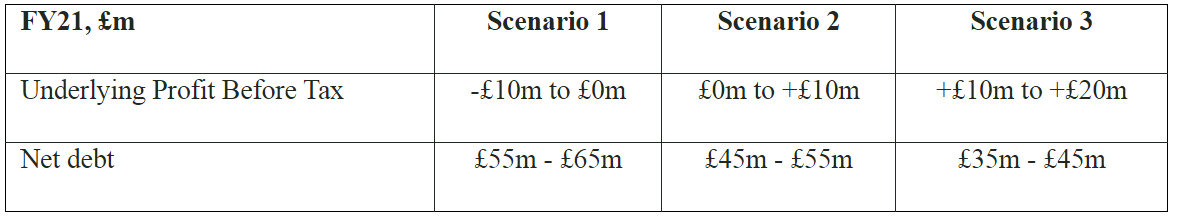
A second table is then provided to show how each scenario translates to full year profits;
.
The way I look at this, even in a downside scenario where sales deteriorate from the -6.5% LFL achieved in Q1, it only results in a small loss, or breakeven overall result. I suppose that could present problems with bank covenants, but it doesn't look in any way threatening to the survival of the company.
We have a range of profitability from -£10m to +£20m above. That compares badly with the £55.9m underlying PBT just reported for FY 03/2020. Hence make no mistake, FY 03/2021 is going to be poor in comparison. That's why this share is rated on a low historic PER.
Balance sheet - is weak. NAV of £365.8m, less intangibles of £395.7m, gives NTAV negative, at £(29.9m)
Is the company at risk of going bust? Probably not, but with current year trading looking to be not much above breakeven, then the bank might be questioning if they want such a large potential exposure? Hence I'd say there's a more than 50% chance of Halfords doing an equity fundraise to strengthen its balance sheet. That would be a very good idea actually, as its shares have done a lot better than most retailers. So fixing the roof when the sun is shining is always a good idea. My invoice is in the post!
Note the big lease liabilities on the balance sheet. Unfortunately, IFRS 16 doesn't give us the information we actually need - i.e. which leases relate to profitable shops (where the lease liability is irrelevant), and which lease liabilities relate to loss-making shops (these are the problem leases).
Liquidity - sounds fine;
Our positive trading performance in Q1 and the additional measures we have taken give us confidence in our ability to trade through the pandemic and end the year in a sound financial position.
It has over £200m of liquidity available from bank facilities, plus £25m contingency funding under CLBILS. That's fine, as long the bank remains happy to extend such large borrowing facilities.
My opinion - Halfords is doing OK, in difficult economic circumstances.
I can't see any reason to rush out and buy the shares. It looks priced about right, and I wouldn't be inclined to chase the price up any higher.
.
.
Photo-me International (LON:PHTM)
54.8p (up 1%) - mkt cap £207.2m
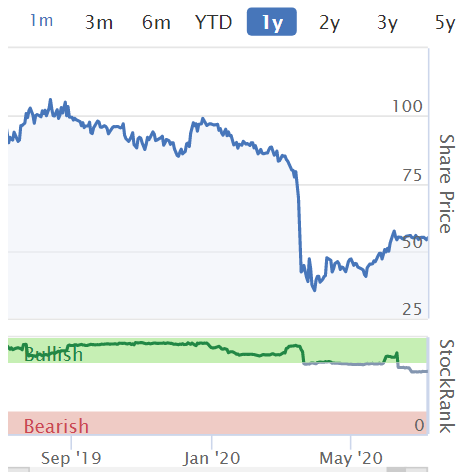
I hadn't realised this share had dropped so much, not having recovered much from the crash in March, which suggests things are not going terribly well at the company;
.
.
Results for FY 04/2020 - this is an unusual year end, so being April, it takes in more of the covid crisis than other companies which are mostly reporting end March year ends at the moment.
Underlying PBT is down 35.6% to £28.4m
The company blames covid/lockdown for the shortfall, and it's useful to have the impact quantified;
|
There's also quite a hit from exceptionals, of £23.7m. this takes reported PBT down to only £4.1m (down 90.4% on LY)
COVID-19 has severely impacted each business area and early indications are B2B, children's rides and, to a lesser extent Identification, will be the most challenging from which to recover... "The pandemic has and continues to have a significant impact on all the Group's end markets, resulting in lower consumer demand. The Board believes that activity levels could take some time to return to pre-COVID-19 levels.
I think that's blown it for me, I'm not interested in investigating this any further.
The other problem with this company, is that it doesn't split out profit by division. That makes it impossible for me to analyse the figures meaningfully.
Uncertainty over whether photo booths will still be needed in the future for passport/ID photos, etc, has been a question mark hanging over this company for many years.
My opinion - I don't know how to work out what this share is worth, as we don't have enough information. Also, who knows whether photo booths will still exist in say 10 years' time? It strikes me as a dated activity that may not be necessary in future. Maybe this share is a fag butt type of share?
Dividends can't be paid under the terms of the French Govt support scheme, if I'm reading that correctly?
Overall, I feel there are too many uncertainties about its business model, and not enough financial information to assess whether the growth areas of launderettes, and other kiosks, are worthwhile or not.
The severe impact of covid, and outlook comments which sound subdued, are making me feel that the depressed share price is probably justified.
.
Reach (LON:RCH)
77.6p (down 13% today) - mkt cap £232m
Trading update - this newspaper group (formerly Trinity Mirror) has suffered quite badly in the covid crisis. Revenue for Q2 is down 27.5%, slightly improving to -23.9% in June, still really bad.
Restructuring - there's another wave of cost-cutting & redundancies (12% of workforce), to reduce costs by £35m annualised, at a cost of £20m.
Digital revenues are also falling, which is very disappointing, as the upside case for this share is that it can transform itself into a digital advertising company, as the newspapers gradually die off.
Dividends - suspended currently, will keep under review.
Pension schemes - are huge, and funding them is a big drain on cashflow. Recent falls in interest rates makes the problem worse, due to increased liabilities, although asset values will have also probably increased.
My opinion - the fall in revenues is too large for me to want to get involved here. They say that covid has accelerated many existing long-term trends, and that seems to very much be the case here too. That said, as we've discussed many times before, RCH has proven an amazingly cash generative business over many years, despite shrinking circulations. That's partly through constant cost-cutting, but also from cheap bolt on acquisitions, being a consolidator of struggling print businesses.
Overall, I'd only be interested in having a punt on this, if the share price revisited the 25p levels where we got involved (very profitably) a few years ago. At 3 times that level now, I don't see any attraction to this. Although it's surprised the market before, and might do so again, you never know.
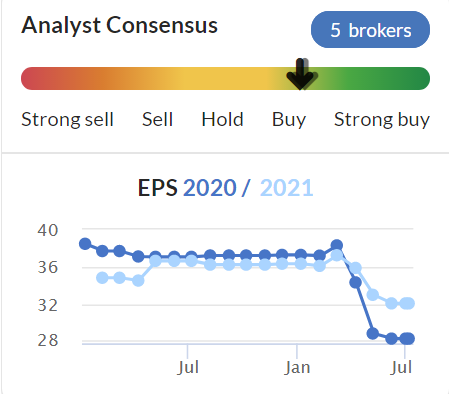
I'm wondering if the broker forecasts might be too ambitious, even though they've already been reduced somewhat:
.
.
Finncap (LON:FCAP)
22.5p (up 7%) - mkt cap £38m
Results for FY 03/2020 are out today, and are poor. Adj EPS was only 0.8p (LY: 2.86p). That's a pricey PER of 28, but to be fair market conditions were bad, so a poor result was expected. Brokers are cyclical businesses, and a lot depends on deal flow. Therefore I'm more interested in the outlook, because fees should be abundant at the moment, due to so many companies needing to raise fresh equity to strengthen balance sheets.
Outlook & current trading - looks good, with Q1 (April, May, June) revenues of £9.8m (LY Q1: £6.5m). Cost base "significantly reduced", and good cash generation. Cash position is strong.
.... In the shorter term, our pipeline of deals for the first half remains good and we will continue to deliver on our strategy for growth."
My opinion - I find FinnCap an absolutely excellent broker. For small caps in particular, they encourage company management to see active investors, not just institutional investors. What FinnCap get, and some other brokers fail to understand, is that in small caps it's the private investors who create the liquidity, and therefore set the market price. Therefore, brokers should be encouraging and developing contact between investors and companies. FinnCap are great at doing this, whereas others such as Numis and Peel Hunt are diabolical in that regard (but good in other respects).
Because FinnCap is so helpful to private investors (also making its research freely available through its own portal, and via Research Tree), and arranging numerous company meetings which I often attend, then I'm pleased to see it is trading well at the moment, with a good pipeline of deals. I see it has recently moved offices, although wonder how much longer brokers will need offices at all, given that working from home has worked seamlessly for many of them.
Are FinnCap shares attractive? I can't get madly excited about them, since the market cap is small, and earnings tend to be erratic from smaller brokers, hence you can't necessarily rely on the divis. Therefore I'm probably neutral on this share, but a big fan of the people & the approach they take towards being so helpful to private investors. There might be a possibility of FinnCap consolidating the sector, as most people seem to think there are too many smaller brokers, chasing the same business. I'd be delighted if a few of the stuffy & haughty old brokerages that look down on private investors were to disappear, and get swallowed up by FinnCap.
.
Pci- Pal (LON:PCIP)
41p (up 2% today) - mkt cap £24.2m
(I'm long)
I have a small long position here, because a friend who is a sector expert reckons it's good. He usually gets it right, which is good enough for me. I'm not going to try to blag it, but instead admit that I don't fully understand what the company does. It's something to do with software that allows customers to make payments by card over the phone, whilst keeping their card details private.
PCI-PAL PLC (AIM: PCIP), the global provider of secure payment solutions, is pleased to announce a trading update for the year ended 30 June 2020.
Trading update today - sounds good;
The Group continues to build strong momentum and has made further significant progress across its key growth metrics.
The Board confirms that trading for the year ended 30 June 2020 was in line with current market expectations.
Therefore it looks like a business which is not particularly vulnerable to covid issues, obviously a positive. Although it does mention a dip in call volumes, which are now recovering.
Apart from this short term decline we experienced little impact on our expected recognised revenues for FY20.
Although it does warn about an adverse impact in FY 06/2021;
In terms of new business sales, we have seen some delays in decision-making and contract signing as a result of prospective customers prioritising their own handling of the pandemic. The majority of these instances have not resulted in lost sales, rather a delay to anticipated close dates. This has naturally had an impact on our Q4 new sales which would have been even stronger than reported above but for the pandemic.
These delays will though have a knock-on impact in reducing recognised revenue in FY21 due to the nature of our revenue model.
Revenue of £4.4m for FY 06/2020 looks ahead of forecast. that's good, but I'm a bit concerned at the scale of losses - FinnCap has (on cue!) published an update today, forecasting adj PBT of £(4.2m) for FY 06/2020. Clearly the company needs to grow its revenues fast, to get anywhere near breakeven, let alone profits.
Details are given about contract wins, so there seems to be more growth in the pipeline. This share is all about growth happening, and losses reducing.
Cash - it raised £5.0m in March 2020, so should be OK for liquidity into 2021, I imagine.
Outlook - this sounds like a mild profit warning below, but revenue growth of 50-60% is still pretty stunning!
As we start FY21 with a strong level of TACV, and as referenced above, some of the ongoing delays in decision-making and contract signing have inevitably created some degree of uncertainty as to the timing of both new deals being signed and implementation timing of new and recent contract wins. Whilst we remain confident of delivering significant year on year growth in FY21, given the current environment, it is prudent to adjust our market guidance downwards for the year to account for these factors. As highlighted above, we are confident in the long term strength of our market opportunity and now expect to grow revenue by between 50 to 60% in FY21.
My opinion - a bit of a mixed update. Strong growth, but it's still heavily loss-making.
I need to learn more about this company. Diary date - 3pm this Thursday (9 July) - the company will be doing a presentation plus Q&A on the excellent InvestorMeetCompany platform. It's open to all, register here.
.
Altitude (LON:ALT)
22.6p (down 21% today) - mkt cap £15.5m
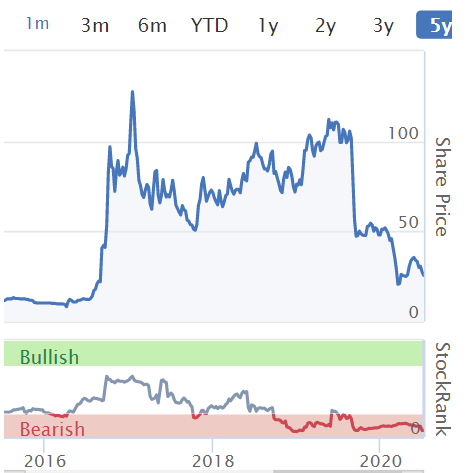
Investors got very excited about this company for several years, believing that its online platform for promotional goods would be the next big thing. It started to go wrong in Aug/Sept 2019, and has now come most of the way back down again. Here's the 5-year chart;
.
The number of shares in issue has gone up from 43m in 2015, to nearly 69m now.
Reading through today's update, it sounds as if cash is getting tight, hence I would work on the basis that it might need another placing, resulting in further dilution.
As you would expect, its market has been clobbered by the covid/lockdown situation, the company can't be blamed for that.
Liquidity - this is self-explanatory;
However, subject to continued steady recovery in transactional volume through 2020 in the promotional products market, we believe the Company has sufficient financial resources and liquidity to see the business through to more normalized market conditions.
OK, maybe it won't need a placing after all? But it sounds finely balanced to me.
My opinion - neutral. I'd want to see some figures, but the 31 March 2020 results won't be released until end Sept 2020. Plus of course, that won't reflect much of the covid period, which mainly hit in April onwards.
Overall - too uncertain, so I'm not interested. I wasn't 100% convinced about its business model to begin with, but have punted on the share in the past.
.
Right, that's it for today, thanks for reading & commenting (well I haven't read the comments yet, so I'll reserve judgement on that!). See you tomorrow :-)
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

117 comments
Sosandar (LON:SOS) are so addicted to comparative figures that it is impossible to work out all of the actual figures! It gets really wearing after a while. The June break even figure is one that I'm taking with a pinch of salt. Does it include returns or are returns still suspended?
Re: Pci- Pal (LON:PCIP)
Just listened in to their InvestorMeetCompany presentation of back of Paul's update. Liked what I heard. Seen to have a product that customers want/need. Lots of big reputable companies, SaaS business model with good earnings visibility. Good international growth. Seem to be executing well. No hyperbole in presentation. As an investment, it could have legs.
Amur Minerals (AMC) - Nickel Mining Exploration Company with the licence to mine one of the world's largest Nickel deposits in the world (1.5 Million Tonne of Nickel @ approx 13,000 USD per Tonne)
Micro Cap Pick and in my view a got very good potential for great returns with the SP sitting at a very low level.
There is a huge post Covid 19 move to EV Vechicles
This has cased a huge increase in demand for Nickel.....
See below article
Amur Minerals - (LON:AMC) - The Start of the Final Rise! (Nickel Mining)
https://www.stockopedia.com/content/amur-minerals-lon-amc-the-start-of-the-final-rise-nickel-mining-zak-mir-update-631283?order=createdAt&sort=desc&mode=threaded
There are a few more before this latest one if interested....
Again DYOR
I'm bullish on Halfords (LON:HFD) , the shares have been hated for years but now seem to have several factors in favour.
1. Government incentives and investment in cycling, e.g. vouchers and cycle lanes.
2. People and kids using bikes to exercise and commute, given the risks of public transport, gyms and team sports.
3. Staycation trend, money being spent on bikes, roof boxes, bike racks etc rather than foreign holidays
4. Large stores that easily allow social distancing.
5. Anticipated legalisation of E-scooters
6. People moving to rural areas or suburbs need more cars, accessories, parts & servicing.
7. Recession would mean cars kept for longer requiring parts & servicing. Older cars more likely to use non main dealer servicing.
8. Business rates relief, anticipated jobs retention and consumer incentives.
9. Exercise at home trend boosting sales of turbo trainers
10. After selling cycle republic Halfords (LON:HFD) now focuses on the low and mid price brackets for bikes which should hold up better in recession.
Boohoo (LON:BOO)
"No enforcement has been used during the visits and officers have not at this stage identified any offences under the Modern Slavery Act 2015."
https://www.gla.gov.uk/whats-new/latest-press-releases/07072020-multi-agency-visits-to-leicester-factories/
Nice find. Thanks for sharing
I read a year or two ago when Leicester garment factories were in the news that policing it is extremely hard as they are located in large semi derelict buildings...somewhat a warren of them and a warren inside (I haven't been to Leicester since I was a kid so really can't remember). I think this was FT story but not sure. It was also suggested that officials didn't want to find the problem due to complex political and race related issues.
Hi peterthgreat,
Re card usage or not, it strikes me as odd that people are reportedly getting agitated when asked to provide name and contact number at pub door, but have been happy for yonks to pay by credit card and/or make a gastropub table reservation that includes giving name and contact details......
ATB
I have a question to ask Paul or anyone else who has visited pubs over the past few days. What options were provided when it came to paying? Was it the usual credit card options or was there an option to use PayPal or perhaps even mobile billing of the type developed by Boku Inc? There has been an acceleration in the shift to non-cash forms of payment as a result of the pandemic and I wondered if this was also occurring in pubs which I have tended to regard as one of the last bastions of cash payments?
Hi peterthegreat,
Re paying in pubs, it's either contactless, or paying through the ordering app, by scanning in your card details using your smartphone's camera (and only if the payment card is quite new, and the silver numbers haven't yet rubbed off). Google pay is another card payment option, and several others were listed on the apps.
So it looks to me as if cash is now a thing of the past in pubs.
Regards, Paul.
Thanks for your reply Paul. It sounds as though the pub trade is contributing to the acceleration in cashless forms of payment. I find it amazing that, until recently, 85% of global consumer transactions were still made by cash. Even within Germany most retail transactions were in cash until recently but have accelerated dramatically as a result of COVID-19. I have held VISA shares for quite a few years but have recently added PayPal and Boku as I think the trend toward cashless payments on a global scale is unstoppable.
Ref Boohoo (LON:BOO)
A head line from Retail Week Twitter post
'Asos, Next and Zalando cull Boohoo brands amid slavery allegations'
https://twitter.com/RetailWeek...
REgards
Howard
Paul - on Reach (LON:RCH) analyst numbers look about right to me but possibly a bit light rather than other way around. If you play around with changes in revenue against last year then they assume the remainder of this year won't see any pick up against June numbers and I find that hard to believe, though clearly not impossible.
Also the £35m annualised cost savings based on the reduced revenues and EPS of 28p actually pulls the numbers back up to an EPS of 40p for next year. The business will make almost all of that in cash, so really your comments on not wanting to own unless 25p suggest you'd like to buy at 0.6* one years cashflow....wow - wouldn't we all..... :)
I see this as about fairly priced given the uncertainty and if you take the view that I do that it will throw off lots of cash for years to come then medium term I see it back at 150p+ which gives a good annualised IRR on a 3 year view.
I have been re-reading the Dale Carnegie classic, "How To Make Friends & Influence People", which reminded me to smile and be generally affable. The results of doing that are genuinely remarkable - people respond so well to warmth. This is probably my new favourite book, having slightly eclipsed Superforecasting, which I've read twice now.
Paul,
The Carnegie book is good but if you really want to understand the power of influence the best books are by Bob Cialdini: https://www.amazon.co.uk/gp/product/B002BD2UUC/ref=dbs_a_def_rwt_bibl_vppi_i0
Ignore the awful cover, the contents are worth it! I'm not saying this book changed my life but understanding the techniques he describes which are widely employed everywhere you look, and spotting them when used against you, did greatly enhance it. I can't recommend this book highly enough to people I know.
All the best, Si
Thanks Simoan, I'll check out your book recommendation!
His follow up book is even better:
Pre-Suasion
Rarely can I agree with simoan ;) ....but I agree that Cialdini books are excellent
ASOS follows Next's lead in dropping Boohoo (LON:BOO) products from it's website.
Zalando have dropped Boohoo (LON:BOO) also. Seems likely to enter panic selling phase soon.
Do you have any other thoughts on Boohoo (LON:BOO) Paul?
Laughing This is a tricky one for PAUL
Why? I think he's already said that he sold out of Boohoo (LON:BOO) a little while ago.
Hi Paul
See your keeping your head down on Boo.
No view to share?
John
I wrote about it in yesterday's report! Maybe check before posting stupid comments.
Boohoo (LON:BOO)
My 16yo daughter (and her mum)...past users of Boo....were very keen to know that I didn't own any shares in it.
Daughter says that her friends and social media connections will boycott them. How durable is that? Dunno...but Boo has probably struck a very bad time to have people protest it...for whatever reason the mob is more strident now through the covid lock down and if they trip the wire, the fire is going to burn. And if covid cases are linked back to them 'profiteering' then its lights out baby.
I've read things that suggest to me that Boo know they are breaking the rules and are directly connected to the wrongdoing.
Two scenarios:
BULL:- Company acts aggressively to rectify image. This hits both revenue and profitability short term and growth medium term. The shares trade on a low teen multiple at c.50-100p
BEAR:- Steps above are taken...but the whole franchise crumbles without a high growth engine to power it. Talented staff retention is problematic. Purgatory from customers and retailers like Next is long (people want to parade their righteousness). Change of ownership and brand is only route forward. Assets are transferred to another entity at bargain basement price.
I'm a long term Boo sceptic so take my view with a pinch of salt...next few days will tell us whether this fire burns. Note, they've been rather roughshod with shareholders too...although no one cared when the price was going up.
@mojo
Do your wife and daughter know the other brands that Boohoo (LON:BOO) owns and, if they do, do they have the intention to boycott them too?
Yes re PLT....not sure on the other one (Nasty Girl or the recent acquisitions...so need to ask).
Interesting that Jupiter (good) bought Merian's (meh) stake on the plunge...that makes me doubt my negativity a little (although still biased that way....partly as I've never felt their economics made sense...a bit magical)
Jupiter acquired Merian - they didn't buy their stake, it came as part of the acquisition.
Haha...chalk that doubt off
Such a seemingly audacious swoop under conditions of duress made me think that there must be some super non public insight.
Afternoon mojomogoz, Your comments remind me of a scene from a relatively well know movie - "I'll have what your having" to paraphrase - No idea what it might be - but it certainly helps your free flow posting here on Stocko!
Jupiter completed the acquisition of Merian Global Investors Limited on 1 July 2020.
I believe/think they are transferring all funds from Merian to Jupiter.
My daughter always sounds surprised that Boohoo also own PLT and Nasty Gal, despite the fact I've already told her this on several occasions!
To my mind the real issue is that proper enforcement of working conditions leads to the loss of their edge, which I see as very slick marketing allied to the flexibilty of having cheap labour conveniently located close to home. Erosion of margin due to less-cheap labour close to home or erosion of flexibilty due to cheap labour further from home will be far more telling than any boycott IMHO, although that all assumes that the government's stated intention to act outlives the short attention span of the press and public.
Give her a break chap, she's only two.
Hi Mojomogos...I understand your concerns but this is nothing knew...I have acted as a consultant for a Leicester based company run by a British Indian guy..most of his support staff are of similar ethnicity to him and he treats them like Sxst , he is totally ruthless...and I have taken the recent retrace in Boohoo£Boo to get involved ...this may not turn out pretty but unfortunately if you have been in business long enough as I have , you are going to have days when your customers and your wider audience see your work as the work of the Devil .
The current situation for Boo may not appear good but tell us something new as Leicester is a hornets nests of problems , in all manner of businesses.
Of course I find it appalling that anyone who works in Leicester in any capacity is subject to poor conditions, lower than legal minimum wages etc etc but I bet my bottom dollar I know the ethnicity of the owners who allow this to take place with their staff...Tony
Tony...I could be invested in Boo by next month...
I like growth...but I like the company to have some hair on it too as IMO its through the rough that I get to understand whether the company has the mettle or not.
So for me, this is a chance to see and feel what Boo is made of. I remain on sceptical side as I think a rise in input costs creates a real problem for them and its seems to me that this will happen now (no escape). If this problem runs on a bit we get to see whether the company are good allocators of capital...or whether they were a good growth/hype machine that sucked in extra funds to keep the magic growth-go-round spinning.
I really don't know...I've been on the sceptic side...but that is partly character etc
Interesting. I'll be looking....and perversely extended pain would be a rather good thing IMO. My hunch is that it wont blow over quick this time. My daughter/wife were aware of the acquisitions from last time...but weren't bothered. But this time they are incensed.
TBH it's all very well kids not being bothered about BOO, but one thing that recent history has taught us is that things change very quickly.
I mean, we have had symbols of people who were involved in the slave trade for how long? Suddenly, the current climate they decide they don't want them any more. BTW I am not commenting on whether this is correct or not (another discussion).
If it became fashionable enough sentiment among the target market could switch overnight. What if a group of celebs made a boycott? BOO seems concentrated enough in the UK for this sort of thing to be quite meaningful.
So just because someone says it now is nothing definite. Last year if you'd asked councils to rename certain things, they would have no intention of doing so.... now it seems fair game.
I should say it's fairly unlikely. I mean, there are probably quite a lot of people very unhappy with China for various reasons. Some of which make the BOO stuff look trivial, IMO. There may be a few people that do boycott, on the whole few people are going to stop doing business with them or using their country to manufacture things. Neither will many stop getting cheap electronics like Huawei or Xiaomi as long as they undercut other brands in price.
The big sports retailers and brands, we won't name them but we know who I mean - they regularly have scandals about their workers, the factories etc. They promise to do better, everyone forgets (or more likely never actually cared) the sales keep on coming and we rinse and repeat the process every couple of years.
I'm not saying it's right (in fact, I say the exact opposite), but if it's cheap or "must have", people will continue to buy it.
Plus ca change.
Boohoo (LON:BOO) products have been pulled from the Next online store after the high street retailer said the fast fashion giant “has a case to answer” over allegations of labour exploitation.
It's instructive to read and contrast Next's statement on modern slavery. They look like a business that takes the issue seriously. I'm always impressed by their management presentations.
https://www.nextplc.co.uk/~/media/Files/N/Next-PLC-V2/documents/corporate-responsibility/human-rights-and-modern-slavery-2019.pdf
SOS - I actually sold out this morning. From memory at the last update you thought the company was selective with its figures? This morning I felt the RNS looked very unbalanced and thought management were simply trying to cash in on the BOO debacle. Any company who furloughs most of its staff & cuts marketing can temporarily make things look better than they really are, but 1 month! I hate RNS’s which cherry pick numbers rather than providing balanced financial information. This is sad as I like the company!
When is the regulator going to enforce proper RNS reporting? My biggest bug is when RNS’s refer to “in line with market expectations”....... How do I know what market expectations are! For goodness sake quote them! Rant over....!
Your best post ......I have nothing intelligent to add to any investment discussion, but I thoroughly enjoyed your pub market research. It is a lighter style of writing and the better for it. I share your views of PE .....
I have a minute holding (1.25% of pf) in Boohoo (LON:BOO) The issues seem to be in no particular order:
System won’t let me update but just wanted to add that I will almost certainly top up today (to say 2%) and add further on any future price weakness.
Loving the preamble Paul, and your dedicated research. Can I live your life please?
Great review as usual, Paul.
Thank you also for reminding me of the first book I read (in the 1940's): Dale Carnegie classic, "How To Make Friends & Influence People".
Throughout my working life, until December 2018, I bought this book for sales personnel joining the companies - hundreds of copies over the years. I believe it was published in 1935 and has resulted in thousands of people today giving courses around the principles it put forward.
Sorry if this is not on investing.
Love the dedicated research Paul! When are you going to write a book?
sorry for the late request, thank you for a great pre-ramble you write so well, will you be covering Reach? Reach (LON:RCH)
and in other other news (early lunch)
On £G4M
Cameron Mckenna article on RPM in Music instrument sales
"The CMA’s enforcement against resale price maintenance (RPM) in the musical instrument sector continues as the CMA issued fines of over £4 million and £1.5 million to the musical instrument suppliers, Roland and Korg for engaging in RPM at the end of June. Separately, the CMA also took action against a retailer in an RPM case for the first time, with a musical instrument retailer, GAK, agreeing to pay a fine to settle its case."
Whether the impact is positive or negative, dont know.
Photo-me International (LON:PHTM) - sorry entered the wrong ticker
Paul - Really enjoyed reading about your research trip into Bournemouth. Thank you.
I loved the preamble today. Several laugh out loud moments make it worth the stocko sub by itself.
Love your daily intros. Cool that you went to Poole Grammar School, i went there too!! I did my A-Levels there in early nineties...maybe you were there too? Although you look younger than me!
Another great pre-amble Paul and interesting to read of your experience from someone here not rushing back to the boozer. I read on the BBC app this morning that I think 3 pubs have now been closed due to someone visiting them on Saturday who has now tested positive for Covid-19....so it begins.
Results this morning from Photo-Me International (LON:PHTM) which has been reviewed in the past on here. I've been a long term holder, averaging up over the years and now sitting on a loss. Thinking seriously of bailing out due to better opportunities for my money. The loss of dividend (for potentially years), breach of a French bank loan covenant (though expect a satisfactory outcome), lots of restructuring and seeing the cash balance reduce makes me think I should sit this out. Maybe revisit in a few years. If you have time to share your view Paul or any others that is welcome. (But please don't anyone say the usual of the UK accepts camera phone pictures so the business is in "terminal decline", this is already explained in the results and they are a global business where most countries don't have such allowance. Plus they are a diversified company not just focused on ID photos.)
£PTHM Paul if you get time I would be interested in your thoughts I have it on my radar for the last ~6 months based off the PI World interview with Lord Lee (Aug. 2019) - he had recently bought into it, mentioning that he likes the acquisition of the french fruit juice vending business (does mention it is slightly more speculative than normal) . As someone (Lord Lee) who appears not to jump in and out of stocks I thought it warranted some attention...
Photo-me International (LON:PHTM) - Paul thanks for your comments, I appreciate you looking at it and all the other names of course. PS looking forward to reading more of your comments on how the unlock is unfolding in Bournemouth.
I am in the same position as you having held on over the last couple of years .Read the RSN at 7 :30 this morning and got to the "breach of covenant " and not allowed to pay dividends for the foreseeable future and decided that the money would be better employed elsewhere. Sold at about 8:15 for a thumping loss !!!
Good luck
Great article so far, Paul, informative but also laugh-out-loud funny!
£Boo - everyone seems to be saying it's an overreaction and a cheap entry point.
All I can see is:
- Margins will significantly decrease as the current factory reportedly pays people about half the national minimum wage.
- a big part of Boohoo (LON:BOO) success is there ability to market well. Getting celebrities and influences to promote their products - who's going to want to promote this now?
- One of boohoo main advantages compared with other competitors is its low price point for customers - this is out the window now.
- the conditions of workers in these factories was highlighted years ago but it seems has been swept under the carpet by boo as this same issue has reappeared yet again.
- its accounting practices have been questioned by short sellers, this seems more likely to be true now considering ethical boundaries boohoo has breached. Yes its not their factory its just a supplier, but when they've been questioned about this in the past surely they'd think to do some due diligence should be done on similar factories in the future?
- Short term disruption in moving to another factory.
I don't hold (clearly) but haven't shorted either. I just keep seeing 'over reaction', perfect buying opportunity ' so wanted to voice some thoughts
On Boohoo (LON:BOO)
Reccomend The FT Alphaville article on this, who gave a h/t to a twitter feed called small caps live.
"An interesting twist, they say, is that Morefray Limited, the name on the boxes being packed, has I5 Holdings listed as a person of significant control. I5’s only director is a chap called Shahzad Fakhar Irshad.
Jalaludin Abdullah Kamani, the brother of Boohoo co-founder and boss Mahmud Kamani, now owns a big bit of the me-too fast fashion website ISawItFirst. He has quite a bit of corporate overlap with Shahzad Fakhar Irshad and I5 (such as here, here and here). Their assistance might therefore be valuable as Boohoo seeks to establish the identity of the sub-contractor and reviews with urgency its relationship with any suppliers who have contracted work there."
Not looking good.
The thing which worries me more than anything is the fact they raised £200mio from shareholders for strategic brand buys and didn't buy anything worthwhile.
They so far have only used it to give the son £300mio of investors money and buy Oasis and Warehouse for pennies which is a terrible move for shareholders.
The operations of the business is very good and the factory story is probably an overreaction but this wasting of shareholder's funds is a big red flag.
Paul I think we should be forever grateful to you for your selfless research. Your liver must be taking a spanking and you must be putting on pounds (not in the wallet sense, although of course I hope that is the outcome!)
Positive update from £AVG. Trading is close to original expectations with net debt reduced since the interims and two new contract wins. The unexpected bonus is that planning permission has been granted for the residential development of a 7 acre site in Luton for 1000 dwellings. The site is currently occupied by one of its subsidiaries Hayward Tyler, which is to relocate elsewhere in Luton. It is reasonable to extrapolate that the realised value of the site will be significant relative to the company's current market cap of around £72m. Just my view, time will tell?
I hold
Agree the Avingtrans (LON:AVG) update is positive. However, revenue announced for 2020 is only £114 million, against forecasts (in Stocko) of 125 million. Possibly O&G weakness was hitting well before year end. Trading is stated to be close to expectations, but no mention of increased COVID related costs. Still, they look as if they can come through relatively unscathed, which is good. I hold.
Boohoo (LON:BOO)
How much damage the bad publicity around the Leicester factory will do is clearly guesswork but I am inclined to think the share price drop is an overaction based on:
1) It seems clear Boohoo had no direct relationship with the factory
2) Boohoo has put out a very strong response vowing to drill down to its subcontractors
3) any reputational damage is likely to be confined to the Boohoo brand and unlikely to affect Pretty Little Thing (arguably the more important brand in the stable), Nasty Gal, Coast, Warehouse etc.
The more likely long term adverse effect is to put up the cost/price of some of their products.
But overall I think now is the cheap entry point I have been waiting for.
I would be more worried about their waste of shareholder's funds to buy brands from his family.
Maybe but these brands are consolidated and there are undoubtedly going to be questions about the relationship between the local suppliers and the family running BooHoo. Whats so great about BooHoo that you must invest in it? If its 'moat' turns out to be these sweat shops and they are closed down what next? Barge and pole I think.
Hi Paul I think you said recentlu you would go back into BooHoo if the price fell back, are you tempted to buy once the price stops falling?
Stocko is showing it on a PE of 35 this morning and the price still heading down
BOO down to just above 250p as I write. That is another 15% down. Too tempting for me and I bought a few....but with a few concerns.
Are the funds now selling out? Has the story changed? I guess it may have and will heavy fines follow? More to the point, if the company does get stuck with this reputation....and the investigation by the Sunday Times found that workers are making clothes under the label of Nasty Gal for £3.50 per hour....my 14 and 20 year olds will refuse on principle to buy there again and the brand will be toxic for a while. But that sure is a huge two day fall....so in for a possible bounce.
Merain UK Mid Cap has 8% of BooHoo which represents 12.5% of the fund.
RNS Yesterday Merain went from 9.8% to 0%
RNS yesterday, Jupiter acquired Merain and that stock now comes as a Jupiter holding.
Really good sleuthing there. Don't know where else one would find it. (Hope it's correct!)
It literally states it in the Jupiter holdings RNS
From the RNS "As of 1 July 2020, Merian Global Investors Limited is owned by Jupiter Fund Management Plc. Any positions in Merian Global Investors Limited are transferred to Jupiter Fund Management Plc."
Boohoo (LON:BOO)
Yes, funds could well look to reduce their holdings. One thing to consider is the increased focus on ESG from any Asset manager / Equity fund / Investor perspective. Investors are more focused on potential reputational risk than any time in the past and this has only accelerated under COVID (look at continued strong performance of Impax Asset Management (LON:IPX) for example of increased demand for 'responsible investing').
I invest in the UK on behalf of a European Debt fund and our LPs are increasingly ESG focused (our portfolio companies have to fill in ESG questionaires etc) and we look to run our business on a 'carbon neutral' basis.
I do not know what impact this may have on Boohoo (LON:BOO) but any fund managers with overweight positions may be sitting a little bit uncomfortably at the moment. They will no doubt have to report up the chain to their superiors and investors on these developments...
Also bought a few - unfortunately not at 250 though. Cant see this as more than a short term blip.
For me, I was tempted to buy around 260p today, but didn't have any available funds, and didn't want to sell anything other holdings. I'm watching it closely though, and might start buying if it continues falling.
Anybody who follows me on Twitter knows that I am a big fan of pubs, not so much in the evening but in the mornings/lunchtimes, when I enjoyed nothing more than going to my local, which was usually pretty quiet unless there was a football crowd around, and sitting by myself with a copy of The Times and a pint or several of Carlsberg, having the occasional bit of banter with the staff and some of the other regulars.
I’ve been quite surprised at how little I have missed the pub, or at least at how quickly I got used to having a different routine on my days off, having a few beers at home instead with the newspaper and some daytime TV going on in the background.
I gather that quite a few of the pubs in my area (Paddington) are now open again but that my own local isn’t due to re-open until 1st August. I had planned on making my first return to a pub on my day off tomorrow but my feeling now is that I’m not sure that I can be bothered.
Do I really want to be greeted by burly bouncers, sign in and leave contact details so that I can be tracked and traced and potentially be made to self-isolate for 14 days if another customer tests positive or claims to have tested positive, and sit behind a plastic screen? I’m really not sure. I think I’ll probably wait until August when my local reopens.
For the Royal Exchange, it is worth almost any hassle.
Off topic but has the Royal Exchange closed for good?
How to Win Friends and Influence People is a book I never read but have just downloaded a copy from Amazon to my Kindle. Amazon cannot rate it highly as it charged me 75 pence and my wife said at 75 years of age surely can't need it. My aim is to read it in the early hours when I toss and turn worrying about the next acquisition of one of my dogs. I get up and read some of the most boring book on my Kindle before crashing out. Hopefully your recommendation will turn out to be both soothing and rewarding Paul!
William
Hi all, just wondering if you knew the reason for falls in Inspecs (LON:SPEC) Inspecs over the last few, seems to have fallen considerably the last 2 days and fallen on Stocko rankings. I have looked for news articles but can't see any.
Thanks
I would also be interested in any insights or facts. I am holding 8% of my portfolio at 205p.
I do note that the spread can be massive and a few decent consecutive Buys or Sells can change the midprice by +/- 5-10%.
Sosandar (LON:SOS)
Very decent trading update today , particularly pleasing is the close to breakeven comments about June - ok they can massively reduce advertising in one month to get an unrepresentative picture - but to me this is the first real indication that the company has the ability to generate real profits and cashflow , i haven't particularly doubted it but the picture painted by the numbers has not been clear whilst they having been on their "bought growth splurge"
I guess they may have benefited from a bounce in June with the get out of our onesies brigade as people go back to normality and leave the house.
Not sure i 100% trust the company that this one month stat is not spin , so i would be really interested to see if there are any forecasts that are now showing much reduced losses going forward. they are still between a rock and a hardplace here in that spending cash now to get to high level of sales quicker isn't a stupid strategy.
With a market cap of under £25 mill i can see decent some upside potential here if this June month isn't a blip - note q1 is the quiet period of the year too , although against that they may have benefited from physical store closures in the period.
company wins typo of the year award here with the following classic you would expect of an 18 year old trainee bottom marks too whoever proof read this one.
Cash at 30 June 2020 remained broadly flat at £4.4m, showing only a very marginal decrease since 31 April 2020.
Note unfortunately they either need to get cashflow positive or raise more money soon , i am always slightly wary that when companies know they will be raising cash they tend to be 6 pint glasses lined up full. Perhaps we should expect some primary bid news coming soon - i wander if Paul will have radio silence here today :).
Ref primary bid raising cash at discount as seems to be popular- does anyone know if generally speaking one has to be an existing shareholder to participate in these offers ?.
Hi rmillaree, generally you don't have to be a shareholder to participate in Primary Bid offers, though recently for some you tick to say if you are, and then get priority.
Regards
Phrases about pots and kettles and people in glass houses spring to mind:
"company wins typo of the year award here with the following classic you would expect of an 18 year old trainee bottom marks too whoever proof read this one."
I can't actually see any typo in "Cash at 30 June 2020 remained broadly flat at £4.4m, showing only a very marginal decrease since 31 April 2020."
"31 April"
johnsmith68
Phrases about pots and kettles and people in glass houses spring to mind:
Yes guilty as charged i always paste in haste - so apologies in advance and arrears for the many numerous typos you will find in my posts.
RDI REIT (LON:RDI)
Trading update today - basically surviving, debt covenants extended. Mish-mass of assets, hotels, offices, retail.
More interesting is the recent announcement Starwood Capital have taken a 29.42% stake. Starwood are a big player, owning properties globally $60B AUM. Well, they bought their stake in RDI at a 50% discount to last reported NAV.
I hold a small number, expecting a buy out, although it could take some time.
I think I'm in the same place with £RDI. Sitting on a loss, but the Starwood purchase made me a lot more comfortable, and the mix of properties means they are getting through. Because of the past, it'll take better news on the shopping front to raise the price purchase, but at least they are safe, I think, and buy-out should be over 100p (I'd still have lost, but I'm not putting more in, just be gratefult to move on). Seriously, everyone, I'm struggling to be enthusiastic about much in Britain except £GRID.
What a great read first thing in the morning Paul. Your descriptive writing is brilliant - when are you going to write that first book? By the way, great update from SOS today with a big tick up. Have a great day. Charles
Paul, Sir.
Can we have your thoughts on Plus500 (LON:PLUS) 's trading update today please? Smoke and mirrors.
I'm enjoying the more personal adventures of your blog Paul. Thanks for including these sections!
wonderful piece Paul. You really must write a book. Or dare I suggest it. Set up your own website :)
very amusing and informative preamble this morning. Ended up reading sections to my kids over breakfast! Excellent choice of top two books too.
£SOS
Q1 Trading Update Year on year growth with significantly reduced losses as a results of strategy shift implemented in response to Covid-19. .....
Close to breakeven sounds good for £SOS but are costs artificially low right now? In the previous update it said 60% of its workforce is furloughed and senior management had taken a pay cut. There's no mention of anything about that this morning.
The revenue growth is encouraging but is compared to a poorer quarter last year.
It's an interesting company but I worry about short-term dilution from another fundraising.
My morning smallcap tweet:
Renewi (LON:RWI) Seeing Machines (LON:SEE) Sosandar (LON:SOS) Reach (LON:RCH) Velocity Composites (LON:VEL) Live (LON:LVCG) RDI REIT (LON:RDI) LPA (LON:LPA) Altitude (LON:ALT) SkinBioTherapeutics (LON:SBTX) Avingtrans (LON:AVG), PCI- PAL (LON:PCIP)
Renewi (RWI) Q1 ahead of initial Covid-19 adjusted expectations with earning hit €8m less than guided. "We remain alert to the potential for a decline in late cycle activities such as construction."
Seeing Machines (SEE) US House votes for bill that will set to mandate DMS from 2024. Still needs Senate and Presidential approval. But Euro NCAP delays the '2022 and 2024 rating', co does not expect any material impact to near-term forecast for Automotive revenue.
Sosandar (SOS) Q1 rev up 54%, loss down c.70%. Also June neared breakeven. Plans to ramp up marketing spend towards the end of Q2. Cash down only slightly in May & June.
Reach (RCH) cost cutting and job losses ('transformation to accelerate customer value strategy') after Q2 rev falls 27.5%. June down 24%. Cuts to save £35m PA. Customer registration target increased to 10m by 2022 (was 7m).
Velocity Composites (VEL) new framework agreement to 2022 with an existing customer. No £££.
Live Company Group (LVCG) wins 2 contracts. Q2 poor but no nos. Cost cutting & job losses.
RDI REIT (RDI) June Q rent collection 70%, up from 54% in March. Cash at hand £80m.
LPA Group (LPA) £3.3m contract wins in rail mkt. Majority of output expected through next FY.
Altitude (ALT) trading in line. "Subject to continued steady recovery in transactional volume through 2020 in the promotional products market, we believe the Company has sufficient financial resources and liquidity to see the business through to more normalized market conditions."
SkinBioTherapeutics (SBTX) progress on this and that but no mention of sales. Cash £2.1m down £0.4m in half.
Avingtrans (AVG) guides FY(May) rev £114m up 9%, adj EBITDA at least £11.5m (£9.4m). Order book and prospect pipeline remains strong overall but some reduced prospects in specific sectors, notably in O&G. Credit headroom over £10m. Two new nuclear sector contract wins worth £6.4m.
In line: PCI- PAL (LON:PCIP)
Results out of PCA this morning; better than I expected.
I hold and will continue to hold a decent sized stake.
I read another chapter of my biography of Cecil Rhodes, as unlike many millennials, I like to acquaint myself with the facts, before virtue signalling about the past. Blanket memo to millennials - people in the past were all nasty! Get over it.
I'd suggest reading more than one, Rhodes was an incredibly complex character and biographies tend between hagiography and character assassination. My preferred one was Rhodes: The Race for Africa by Antony Thomas which isn't exactly positive - Rhodes set the prototype for apartheid after all - but does provide some balance.
But I'd take issue with the argument than all people in the past were nasty. Different yes, but hard to read anything about Wiliam Wilberforce without recognising that morality fundamentally doesn't change that much. It was entirely possible for people 200 years ago to differentiate between right and wrong, it was just that there was nothing to stop the rich and greedy doing the latter if they wanted to.
I'd also add that most history is written about rich people. When Rhodes was storming around Africa my great grandfather was an indentured labourer, a condition not too many steps away from slavery. That was in Britain not much over 100 years ago. My ancestors would have had much more in common with the people Rhodes and his ilk exploited than the man himself. We have no idea how lucky we are to live in the age we do.
timarr
Wholeheartedly agree timarr, family history research is such an eye-opener isn't it. My mother's family were displaced from Cornwall when the tin mines were challenged by cheaper imports 200 years ago. They became economic migrants to the coal mines of NE England where the owners operated a cartel of subsistence wages. Tough times but everyone was in the same boat generally and the majority moved on and worked their way out of poverty. Saddens me that so many today think that somebody else should be sorting out their problems.
well as someone who lived in Rhodesia way back in the 60’s, I much preferred life with no internet,little traffic,no phones,telex,facs ,television etc etc. It was a simpler life for sure but we were a lot more social in those days and I have great memories of the years spent there .
“ When Rhodes was storming around Africa my great grandfather was an indentured labourer, a condition not too many steps away from slavery. That was in Britain not much over 100 years ago. My ancestors would have had much more in common with the people Rhodes and his ilk exploited than the man himself.”
Our ancestors tend to be a very varied bunch once we go back a few generations. I’m not suggesting that your other seven great grandparents were not equally poor as this great grandfather but for many people it is pretty varied, particularly as you go back a bit further to the next generation or two as there are so many of them.
Clogs to clogs in three generations, as the saying goes.
My comments on BOO:- Seen & heard lots of bullish comments the last 24hrs on the lines of "girls dont give a crap they will still keep buying BOO's stuff", often naive comments from those with shares of BOO say that. What these people fail to realise is that this is now a tainted brand that celebs, such as Kendal Jenner wearing a BOO £15 dress, will think twice about accepting work from such a brand now. The same for institutions. People put to little an emphasis on brand identity because its difficult to compute that into EPS. So, when Kendal accepts another contract with a competitor and not BOO how is that supposed to help BOO EPS? It has all the signs of a company that has peaked and going south. Other signs such as the Kamani's cashing in on amounts of shares. Or buying ailing businesses to boost the enterprise value and so their shares would be worth more for more of a future sell off. This exploitation of workers in this industry always has a convenient blind eye card played by these big industry players so they can maximise EPS. Do NOT think this is a bargain share as it stands now, it is not. It is going to plummet further..... the Trade Unions have now had a sniff of blood and all manner of 'fair trade' companies looking to pile on the misery on BOO. This is what happens, brand has been tainted.
At first I pegged the Boohoo drop as 'classic market over-reaction', but when you think about it for two seconds; they use suppliers based in the UK for fast turnaround, and they were shifting tonnes of gear throughout lockdown- where did they think the clothes were coming from, if not local manufacturers flouting lockdown rules?
Re Boohoo (LON:BOO)
“ where did they think the clothes were coming from, if not local manufacturers flouting lockdown rules?”
I think that is perhaps rather harsh. The lockdown was not so strict that you couldn’t go to work if your job couldn’t be done from home. So, the fact that suppliers were still making clothing doesn’t signify a breach of lockdown in itself. While Boohoo’s volumes were strong, the high street retailers were much reduced so there’s no a great deal of reason to suspect that the suppliers couldn’t handle extra volume from Boohoo.
One would have had to audit the factories to know and sending someone to inspect the factories during lockdown could be argued to be non-essential travel.
I think the biggest indicator that a garment is likely to be made under poor working conditions is that it is very cheap. And the great British public have generally decided to turn a blind eye to that in the past.
According to the FT, BooHoo buys 75% of the clothes made in Leicester. It isn't a stretch to argue their lockdown success has triggered a COVID outbreak in a British city. Which is annoying, as I hold- however considering selling at a loss today, as once cabinet ministers start pledging a 'crackdown' this could go rapidly south.
"According to the FT, BooHoo buys 75% of the clothes made in Leicester"
Is this true? It seems very risk concentrated.
I would have thought that BooHoo might have visited it's largest suppliers at some stage and have some knowledge of their operations?
Think you mis-read. They buy 75% of the clothes made in Leicester, not 75% of their clothes are from Leicester.
Agreed. I think a lot of people (myself included) don't quite realise how much young women's fashion is influenced by social media, 'influencers' and celebrities. Whether you think it's a waste of time or not, a lot of people spend hours scrolling through instagram getting their fashion ideas from people who most of us have never heard of, but who have a tremendous sway over the market. Given we are running at peak woke at the moment there is no chance that Boohoo will be getting promoted by them, indeed it's quite possible that there will be a big backlash towards the company on the back of this news, as if there is one thing social media likes it's a campaigning hashtag! It's also the top article on the Daily Mail website, and if you know the Daily Mail you know they do like to put the boot in.
I've bought Boohoo before and did quite well out of it, but I personally won't be buying in as I think it may have a lot further to drop.
Boohoo (LON:BOO)
What these people fail to realise is that this is now a tainted brand that celebs, such as Kendal Jenner wearing a BOO £15 dress, will think twice about accepting work from such a brand now. The same for institutions.
I am on the sidelines ref Boohoo (LON:BOO) - but i would presume exactly the opposite unless they are stupid enough to not address any specific issues raised and provide sufficient lip service. Boo have had these exact same issues thrown at them before (i believe) and that has been public knowledge for quite some time - so it would be two faced of anyone to ditch the brand now as they would already have know the score had the done their own research - celebrities are 10 a penny if not more and celebrities ebb and flow popularity wise anyway. I don't think boo has even been about the celebrities anyway other than being a useful tool to get noticed as the brand (no something they need so much nowadays). If we look at the history of similar accusations against similar companies most of the major brands have been put through this wringer and then it has been back to normal very soon afterwards.
My only thoughts would be costs will increase and margins will be affected when they take action- so the shareprice fall is natural - and being a growth stock the fall is amplified, so i don't really have an idea of whether the future price will be up or down.
I think with the Boohoo (LON:BOO) client base beeing the gen z and millennials and present situation re BLM that any hint of modern slavery will be detrimental to the brand, mix that with the ShaddowFall report late May 2020 and I can see troubled times ahead for the share price.
Additionally the BooHoo response to the issue hasn't been as good as it could have been on the matter.
I personally expect other online suppliers of fast fashions get the same tarring from Leicester links.
Sold my holdings today, made a loss, dust myself down and move on.
My daughters are in this age group and I asked the eldest if she had seen much backlash to BOO as a result. Limited comment on it and so far as she is aware no big celebs on 'insta' have mentioned it. Would it stop her and her friends buying clothes from BOO or PLT? no.
my two granddaughters aged 18 and 16 visited today,and I took the opportunity to ask them about Boohoo. They love the clothes and brand and although did not like to learn about the cheap labour,this they said would not stop them buying the clothes .
'I read another chapter of my biography of Cecil Rhodes, as unlike many millennials, I like to acquaint myself with the facts, before virtue signalling about the past. Blanket memo to millennials - people in the past were all nasty! Get over it.'
How dare you use research, facts, data and equanimity!
There's no use for these things in the cultural revolution.
Another interesting read to finish the night off, I hope Stocko are paying expenses for all the extra curricular activities you undertake on our behalf, nite nite
Thanks Bob! An evening preamble buys me a lie-in in the morning, so I'm happy to absorb the expenses personally :-)
such dedication !