Small Cap Value Report (Tue 7 June 2022) - BIFF, TED, PHTM, GHH, NRR

Good morning, Paul & Jack here. Today's report is now finished.
Agenda -
Paul's Section:
A couple of brief company comments -
Biffa (LON:BIFF) - not a share I’ve ever looked at (it does waste management). It announces today a possible cash takeover bid, at 445p per share - a 37% premium. From America again, where investors seem keen to buy up UK listed companies. Maybe more takeover bids could trigger a recovery in the UK market generally, as it’s signalling to us that valuations are now attractive to bidders. [no section below]
Ted Baker (LON:TED) - another company that’s up for sale, in a formal sales process. The preferred bidder has pulled out. The company is deciding whether to proceed with any of the other approaches it has received. Looks like the chances of a successful bid are receding, so it might make sense to bank profits here.
Looking at TED's FY 1/2022 results, they look poor to me (still heavily loss-making), so little tangible evidence of the turnaround working. Balance sheet looks adequate for now, but if losses continue, it would probably need an equity fundraise. I’m steering clear. [no section below]
Photo-Me International (LON:PHTM) - a positive update, with guidance raised. Finncap note reveals the profit split across the divisions - key info I've been asking for. This reveals the fast growing laundry division is producing a third of group EBITDA. That's game-changing (positive) information. A PER of 8, and a rising yield over 4%, for a growing, net cash business, which is self-funding rapid roll-outs of new machines, looks to me a highly attractive buying opportunity.
Newriver Reit (LON:NRR) - the market doesn't seem to like the results from this property REIT. I think it looks interesting, with a dividend yield now over 8% [EDIT: but set to fall next year, due to disposals], and debt has been greatly reduced from disposals, so it's not financially distressed any more. Worth taking a closer look I think.
Jack's section:
Gooch & Housego (LON:GHH) - staff absences and supply chain shortages have impacted H1 performance but the group says its record order book points to a better second half. The share price has come down quite a lot now, which makes it more interesting, but it’s far from bargain territory. I would want more tangible signs of growth at c20x forecast earnings, but there are signs of quality here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Photo-Me International (LON:PHTM)
70.6p (yesterday’s close)
Market cap £267m
Photo-Me International plc (PHTM.L), the instant-service equipment group, provides an update on the Group's trading for the six months ended 30 April 2022.
This is the halfway mark in FY 10/2022.
How nice (and unusual) to be seeing some positive news -
Trading above expectations leads to upgraded FY22 forecasts
Key points -
H1 revenue up 24% vs LY (driven by recovery in photobooths, e.g. for passports, esp in UK & France)
Net cash £41.4m
Demand “stronger than ever”, due to easing of travel & socialising.
Trading recovered to pre-pandemic in all markets except Asia. Japan expected to recover when covid restrictions removed.
Laundry division - performing well. Installed 53 machines per month. Further growth planned.
Trading “extremely positive” from new “Flex” low cost laundry machine - rapid roll-out planned.
Pizza vending machine “proving very attractive” - “great future development opportunity”
Doing well despite consumer uncertainty.
Inflation - significant increase in supply chain & raw materials, but has “strong position in markets”, and “significant pricing power”
H1 results due out in mid-July.
Guidance for FY 10/2022 - assuming no new covid restrictions -
Revenue up at least +20% vs LY
Adj profit before tax (PBT) £47-50m
Valuation - as I’m typing this, the share price is up 10% to almost 78p.
Many thanks to Finncap for publishing a new note this morning to help us.
This note is particularly helpful, because it gives a breakdown of where the profit comes from, which I’ve not seen before.
Photobooths 55% of FY 10/2021 EBITDA, as I thought, the main profit earner.
Laundry machines 34% of EBITDA in FY 2022, which might be a typo, perhaps they meant 2021? This is a lot more promising than I imagined, and the number of machines grew 16% in just 6 months.
Finncap estimates 9.8p adj EPS for this year, FY 10/2022, up 46% on LY. At 78p currently, that’s a PER of only 8.0 - which strikes me as excellent value.
Forecast divi for this year is 3.3p, a yield of 4.2% - but I think there’s upside on the divis, as they’re well covered, and the company has net cash, so its dividend paying capacity looks very good - I think this is a safe, and rising yield - which is attractive.
Finncap's price target of 123p (raised from 105p today) looks entirely realistic to me.
My opinion - this looks excellent. Now I finally have the information I need (a breakdown of which activities generate the profits) then I’m much more bullish on this share. The problem with photobooths is that they’re structurally declining, but people have been saying that for the last 20 years, and they’re still churning out big profits.
Laundry is much more significant than I thought, and growing fast. Plus there are a few other bits & bobs, like juice & food vending. Armed with this new information, I’m now leaning much more in a bullish direction with this share - the growth in laundry & food machines looks more than enough to offset future declines in photo booths, hopefully.
A low PER, decent balance sheet, good & growing yield, plus self-funding the roll-out of successful new machines in other categories (mainly laundry) looks very attractive to me. Plus it's got pricing power, so shouldn't be hit by inflation. Main markets also recovering. No wonder the major shareholder tried to buy it recently! That lowball offer lapsed in March 2022.
I didn’t expect to be this impressed with PHTM, but it gets a very solid thumbs up from me! This share looks one of the best value shares I’ve seen for a while, and it’s very tempting to buy some.
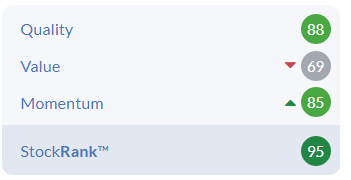
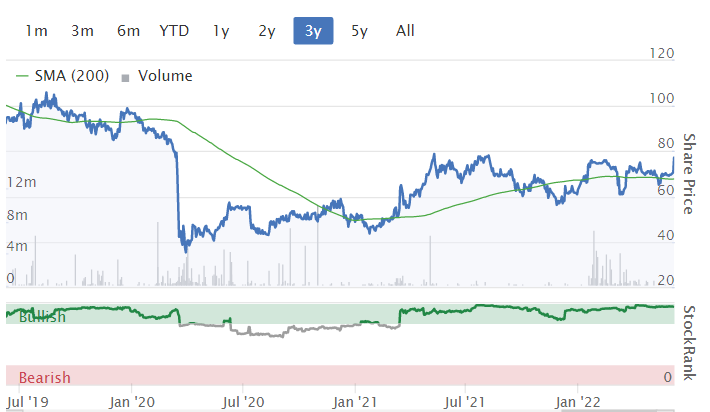
High StockRank is the icing on the cake too!
.
.
Newriver Reit (LON:NRR)
88.4p (down c.12%, at 11:23)
Market cap £270m
I’m not sure why the market has sold off this property REIT share by 12% today, on decent volume too, over 4m shares volume printed so far today. I’ve followed this share for years, because management presented very well at a Mello event, and it just got me interested in the company. I tend not to follow the sector, and only understand the basics of it really.
Key points -
Disposals - substantial, and recently at book value, the biggest one being its Hawthorn pubs division.
Debt - greatly reduced due to disposals, and now quite low at LTV (loan to value) of 35% - says it has surplus capital now.
Property portfolio is retailing mainly, value retailers mainly, in low rent, high occupancy minor shopping centres.
EPS seems to be reported differently, as Underlying Funds From Operations (UFFO) at 9.2p, which is ahead of the upper end of guidance given on 21 April 2022 trading update, of 8.8p
Dividends - particularly attractive, as REITs have to pay out nearly all profits as divis, to keep their tax status. Today FY 3/2022 divis are 7.4p, giving a very attractive (and probably sustainable, given low gearing) yield of 8.4%, at the current 88.4p share price.
EDIT- many thanks to Bouden54 and ChrisW, who helpfully point out in the reader comments below, that the divis at NRR are forecast to fall next year, due to disposals. So that means the yield would drop to just under 7% (based on 6.0p divis and 88.4p current share price), still good though). End of edit.
Net asset value per share (EPRA basis) is 134p, so the share price of 88.4p is a nice 34% discount. Is that justified? It seems a bit excessive to me, given that the property portfolio has already been heavily written down in value, in the last couple of years. If property values hold up, after big falls in the pandemic, then the discount to NAV could gradually reduce or disappear, giving potential decent upside for shareholders, on top of the bumper divi yield. It’s up to you to make that call though, I have no view on commercial property values, other than that higher inflation tends to pull property prices up over the medium to longer term. Although investors might seek higher rental yields, thus exerting downward pressure on capital values, who knows how it will pan out?
Occupancy (95.6%) and rent collection (96%) look good, and improving.
Outlook -
- Improved liquidity in capital markets.
- Retail parks in demand from investors, and values rising.
- Shopping centres less positive, but values have stabilised after long declines.
- NRR expected to be insulated from consumer caution, due to tenants generally selling essentials, not discretionary products.
- More disposals planned.
- Keeping a buffer of capital, given uncertainty.
My opinion - NRR shares look interesting to me, on a fairly superficial review.
So readers, as always, would need to do your own, more detailed research.
An 8.4% dividend yield (EDIT: set to reduce to c.7% next year), and a robust balance sheet with modest gearing, seem a good place to start.
Thinking about the downside risks, there could be more insolvencies of tenants, now the rent moratorium has ended. Although NRR’s biggest client list reported today looks impressive, mainly big names.
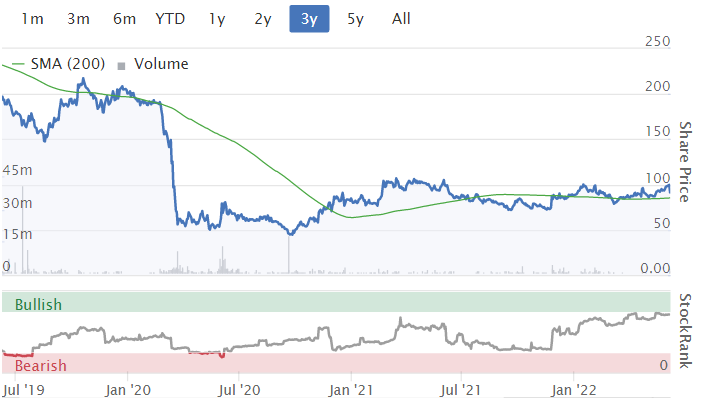
NRR was a much higher risk situation during the pandemic. It’s been transformed since the Hawthorn disposal, and big debt reduction. So it’s a much safer bet now, yet the share price has just gone sideways since early 2021, which doesn’t seem to reflect the improving fundamentals.
Conclusion - NRR shares could be worth readers taking a closer look. Let me know what you think!
.
.
Gooch & Housego (LON:GHH)
Share price: 926p (+8.3%)
Shares in issue: 25,040,919
Market cap: £231.9m
Interim results for the six months to 31 March 2022
Gooch & Housego manufactures photonic components & systems for the aerospace & defence, industrial, life science and scientific research sectors.
- Revenue -7.4% to £54.1m,
- Adjusted profit before tax -26.6% to £3.6m,
- Adjusted basic earnings per share -24.8% to 11.8p,
- Net debt ex-IFRS 16 is up £1.2m to £5.9m,
- Interim dividend is up 0.2p to 4.7p.
Statutory results come in some way below the adjusted results after accounting for amortisation and non-recurring items (statutory profit before tax of £1.2m and statutory basic EPS of 6.9p).
Revenue has been constrained by pandemic related factors. COVID related staff absences at its US and UK sites, plus supply chain shortages (particularly for electronic components from Asia). Gooch has consequently invested in increased capacity and progress has been made with recruitment of operators and securing our supply chain.
Labour markets remain competitive in both US and UK and this has 'gated' the rate at which we have been able to add staff to service our growing order book. Real progress in the hiring and training of operators has been made in the first half of the financial year. There has been wage and material inflation across the period, but the Company is passing on those additional costs in the form of price increases across most of its portfolio.
Adjusted profit before tax down due to lower volumes and investment in R&D and manufacturing capacity.
The group’s order book is in good shape at least, standing at a record £119.9m (31 March 2021: £92.8m), an increase of 29.2% or 25.6% at constant currency. H1 order intake was 1.42 times H1 revenue.
Here’s the revenue performance by segment:

High demand for industrial lasers, in particular from semiconductors. The company has increased market share here, while Medical lasers continue to benefit from the return of elective surgery. A&D (Aerospace & Defence) has been affected by customer driven delays and new programmes not yet progressing to volume phase, but recent order intake has been strong.
Balance sheet
Group remains in a strong financial position. A new five year revolving credit facility ($40m committed/ $30m uncommitted) was put in place in March. Net tangible assets of around £64m and a good current ratio, 3.5x.
Conclusion
Gooch says it has a ‘clear route to mid-teens returns in the near term through organic growth, internal investment and our well-established acquisition strategy’. Perhaps, but trading has been tricky recently, the shares are not obviously cheap, and I’m generally wary of companies pointing to an H2 weighting amid the current changeable conditions.
The chart’s not appealing to me right now. Even after halving recently, shares still trade on around 20x forecast earnings. I do think this is a good company though, so perhaps some kind of premium is warranted.

It seems like revenue growth has been stalling. The past couple of years have obviously been a difficult environment for most operators, so I’m not extrapolating this performance by any means. But I would be hoping for a return to growth at the current valuation.

And the order book is at record levels (hence a degree of confidence from management about a better H2 performance), while net debt is very manageable, so the company looks in fine shape fundamentally. It is capable of passing on costs, taking market share, and investing in capacity and R&D.
At the current level, Gooch looks more interesting than the last time I covered it, when it was in the 1,200p range, particularly if there is a longer term growth opportunity based on superior quality and IP. But I’m still not madly excited by the valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Mark
Sorry to hear your moving on. Hope it works out.
I have the occasional email exhange with Mark (father?) who seems to think simiarly to me on many things :-)
Best of luck for the future
Regards
Michael
who is Mark? I know Jack is moving on but am I missing something ?
Sorry to hear you are moving on Mark…. :-)
Regarding Photo-Me International (LON:PHTM) (Not holding by the way) I may be able to add a little value. People often ask why don't people buy a new washing machine instead of going to the laundrette. I live in Paris and the problem is not cost of a washing machine, the problem is land value. To fit a washing machine in you need two square meters (one for the machine, one to empty it). Here one square meter costs 10,000 euros, therefore if you are lucky enough to own your studio apartment you need 20,000 euro's for a bigger apartment to fit it in. Most people rent but it's the same problem, if you want a bigger apartment then you need to find an extra 100 euros a month for a new landlord. Hopefully, you can now see why people choose to go to the laundrette. The alternative is to live further away and spend more time commuting to work.
I don't want to question your essential thesis ... but, when it comes down to the detail, I think you are overstating (by quite a lot) the incremental space that a washing machine requires:
i) by and large the square metre in front of a washing machine will be shared use and already essential for other purposes (like walking from the kitchen to the garden) ... incremental space requirement is 1 m2 not 2 m2.
ii) you should always expect to be able to stack anotherdomestic appliance on top of a washing machine (a refrigerator, perhaps ... maybe a dishwasher) ... so you have to halve the space required again (we're down to half a square metre in total now!)
Sure ... using a shared laundry facility at a supermarket makes economic sense for a good few people ... but it will also be a very poor bargain for a whole lot more.
Having read Roland's update on (LON:NRR (I hold)) in April and today's FY report
does the ~12% drop in the sp this morning make for a buying
oportunity? The yield is very attractive and the company is well run
and naturally cautious so this would seem to be maintainable. The
negative metrics are both 'accounting' figures and are the result of the disposal of the (always) problematic Hawthawn Pubs.
The company has made a great fist of turning around and clearing out the parts that were difficult.
Thanks for all your work on Stocko, Jack, and best wishes for the future.
Hi guys - is Newriver Reit (LON:NRR) on the agenda today?
Thanks for everything Jack
Bit of a head scratcher on Newriver Reit (LON:NRR) (I hold). Seems to have been a build up preceding results and a fall post results but all looks fine.
8% dividend yield with a NAV that has risen in H2 from 131 to 134p so estate has returned to growth and hefty income with the stock trading at 60p in the £ on TNAV and pretty low LTV now having deleveraged significantly.
Would expect it to trade close to NAV over time but in todays world I am comfortable with a tax free 8% income.
Newriver Reit (LON:NRR) Remember that dividend will be reduced next year to around 5-6p (income next year will be reduced due to the sale of the Hawthorn assets).
estimates are still for over 6p as the UFFO from core business expected to offset some of the Hawthorns pub contribution. So divi is still 7% and expected to grow from there so actually only a slight reduction.
davidjhill, careful on that 8% yield.
Liberum have lowered their dividend forecasts to 6.1p for 03/23 and 6.6p for 03/24
Chris
Great point re NRR's divis reducing next year, many thanks Bouden54 & ChrisW thanks for flagging this. I've edited the article, and given you both a name check in it! Much appreciated, it's very helpful to flag up anything like that which I've missed.
Regards, Paul.
Catching up with news...best wishes Jack. Your input here and on specific stock notes will be missed.
Serica Energy (LON:SQZ) is top of my "consensus" screen with 4 strong buy recommendations. It also has an F-score of 9 and beta less than 1.
Looking at the profit and dividend forecasts I cant understand why it has sold off from over £4 to £2.65. Can anyone enlighten me?
The chart looks like the price might be forming a bottom so I have started buying.
RE: Serica Energy (LON:SQZ)
Looking at the profit and dividend forecasts I cant understand why it has sold off from over £4 to £2.65. Can anyone enlighten me?
I imagine it's because of the windfall tax ... sorry, "temporary, targeted energy profits levy". From yesterday:
The Board notes the significant fall in the Company's share price in the run up to and particularly following the UK Government's announcement on 26 May 2022 of an Energy Profits Levy.
They also noted that their pre-planned £60 million investment in the North Sea should offset a significant proportion of the profit impact. Although even they don't seem quite certain:
Based on our current understanding of the Levy, this programme will qualify to benefit from these incentives with each £1 invested by Serica offering an overall tax saving of up to 91.25 pence
https://www.investegate.co.uk/...
timarr
Revs8...made me have a look.
BP selling their 5% stake seemed to trigger a sell off 28/04.
Further sell off 26/05 when government announced a 25% tax on oil and gas companies.
The update yesterday seemed to indicate potential tax incentives against investments they make (but they still have to spend the money)
Just looked at the 2021 year end and see.
FY 2020 - 23,800 Boe per day - for a loss of 2.9 million.
FY 2021 - 22,200 Boe per day - profit 386 million.
I know its a very simplistic view, they made less gas in 2021 and made a lot of money...so down to elevated gas price? (would need to check) their potential profitability or not, and with the Government wiping 25% of this off through Tax, how will this effect future profits?
I agree though, looks interesting but do kind of see the recent decline, particularly the 26/05 sell off.
There have been quite significant changes at Serica Energy over the last couple of years. Firstly the profit share arrangement with BP that was a left-over from the purchase of the Bruce field has expired, Secondly there have been significant production outages in the last year or two whilst the upgraded or replaced old pipeline infra-structure - they were suffering from the oil field equaivalent of blocked arteries. Thirdly, they are investing to bring in nearby undeveloped gas fields which they can link to their existing infra-structure. So to assess the potential of Serica in the next few years you need to look at a lot more detail that just the last few years' figures. I hold.
Worth noting that they hold a significant cash allocation, so the fall in enterprise value is even sharper than the fall in share price. The sell off obviously triggered by the windfall tax, although even the very worst scenario seems to be more than priced in now. They should also be able to largely offset the tax through their existing investment plans.
re Serica Energy (LON:SQZ), I think it is part of a general sell-off triggered by the windfall tax. Yes, £SQZ's planned investment programme means it will not be paying much, but - if profits are subject to a 65% tax rate, then the PER on which you value it has to be halved or more. I hold, much miffed.
Biffa (LON:BIFF) landfills are FULL of future treasures particularly 1950-70’s plastic for gasification purposes, metals etc etc all can be recovered by gasification which is a green energy process that turns all the rubbish into usable components, oil, metals, carbon black etc all the whilst creating clean energy. The byproduct is hot water. It’s sad our government is not helping UK companies build plants and innovations in this sector outside of wind and solar. I expect that our rubbish will be all brought up from those more visionary and probably sold back to us one day for much more! I hold an interest in a UK company called Mishagas who have spent years getting the due diligence, reports and paperwork required, also their patents. The government support has only been directed in trying to get the Chinese to pay to build it!
TSStubbs. Tell me more about Mishagas please. Cant find anything about it.
I hold shares in a quoted company Powerhouse Energy (LON:PHE) which is working on small scale plants that can be placed around the country (11 in the mediumterm and 70 in the longer term) and deal with local materials which cannot be easily recycled.
The current development plant is on the Wirral / Merseyside and they have also just gained planning permission for another in Scotland - see their news on Stocko 9.6.22
They also see the need to build public and local authority as well as government interest in the technology, and have announced plans to create a UK based, Global Technology and Innovation Centre (GTIC), which it aims to open in early 2023 - see their news on Stocko 24.5.22
The GTIC is designed to add strength to building the technology readiness
level (TRL) of technologies and systems PHE has within its offering, so
reinforcing the company's growth strategy.
As you say, it is sad that the government is not pushing these developments with its own money.
Incidentally, I understand the international rights have been 'sold' to a recently quoted company Hydrogen Utopia International (OFEX:HUI) but Powerhouse Energy (LON:PHE) will receive royalty or equivalent rights on all installations. Currently Hydrogen Utopia International (OFEX:HUI) are focusing on a Polish development.
All small beer at the moment, but these operations on a not-so-small/local basis offer the opportunity of dealing with locally produced materials with reduced transport costs. They will also be scalable if volumes justify. Their output (other than water!) can be electricity for local industry / homes or hydrogen for eg local transport services.
After all, relatively small scale and local is a popular theme. I see recently that the Government is helping fund Rolls Royce and partners in the development of small scale nuclear reactors for local use. Why not for plastics which cannot be recycled?
Another 3m buyback from £VTU.
I think continuing to use excess capital to reduce the share in circulation seems a very smart thing whilst the share price is so low. With the Fixed Asset based this is surely going to be value added for shareholder long term if that bid finally comes in.
Pleased with Photo-Me International (LON:PHTM) update (I hold).
Its my largest share holding and is a very strong update, and is a blessed relief in these turbulent times.
"FY 22 revenue to be at least 20% above FY 21", would take that for all my holdings this year.
The "ME" brand role out of machines, food, laundry, etc is worth reading into if you are interested.
Roland did a SIF write up on them a couple of months ago (worth a look) and added them.
Morning Paul.S
I think you're on to a winner with Photo-Me International (LON:PHTM) - section just published on it. Looks a cracking value/growth share. Wish I held, but no spare cash available right now :-(
Regards, Paul.
Thanks Paul, One winner in twenty won't perhaps be enough ;-0
I used their Laundry machines which are attached to supermarkets, you stick your massive wash on and go do your shopping, which got me interested!
Re Photo-Me International (LON:PHTM) 's Revolution washing machine "you stick your massive wash on and go do your shopping".
This Laundry segment is a very attractive business IMHO. Surprisingly high barriers to entry (relations with land owners like Supermarkets, engineering team to service, high capital upfront - but then very low operational costs and high ongoing profit/machine, against a "baseload" long term if niche need (big items, too much/too hard for a domestic machine like duvets) .
(To Supermarkets, very similar to EV charging in some ways - a way to draw people in for an old style big in person shop. Another trend to follow.)
Problem is, it is tied into balance Photo-Me International (LON:PHTM) business which is still a pretty opaque with a dominant, ageing shareholder and operational CEO. What's more ,the key business that is providing cash short term may/may not disappear overnight with a technical or regulatory change - so overall risk vs reward not as good as it looks I feel.
The key for me would be to tease out whether the surge in revenues from Photo Booths currently, is sustainable. This is pent-up demand (ie two years worth of expiring passports) as people travel again this year.
I am kicking myself because Photo-Me International (LON:PHTM) was on my immediate list to buy (see my short writeup in my Boon Fund May report from last Thurs). My research showed that 70p was a good price to buy (which was the price before the Trading Update). However, due to current market volatility I've taken a 10% haircut to all my target buy prices, so was waiting for a 63p entry point. But missed the boat, consequently.
(sadly, I don't hold at the moment)
Morning Paul & Jack
Photo-Me International (LON:PHTM)
This company appears to be discounted on the assumed demise of the photo booth which may be unfounded. (I didn't use a photobooth for my latest passport photo (Covid lockdown etc) and can now see why its worth spending £5 getting it done properly!) They are also diversifying into laundrettes which may be a growth area.
Would either of you have time to cast an eye over the revised guidance?
The revised guidance and the phrase “demand for the Group's services is stronger than ever.” make me believe that the company could return to growth with an associated SP re rating.
Hi Revs8,
Yes I agree with PHTM, looks excellent value.
I had a similar experience recently with doing my own photo for a new passport. It was surprisingly tricky, finding a place to get the right light, and a blank background, then fiddling around with multiple attempts to get the photo right & within the rules so it wasn't rejected. Using a photobooth could remain an easier option, and I imagine that various countries' authorities might decide it's easier for them to insist people use a photobooth, since it will save them having to reject so many photos that people take themselves on iPhones. Maybe, I'm guessing there.
Regards, Paul.
P.S. Also I forgot to mention that PHTM booths are apparently doing something with biometric data, so could remain relevant longer term perhaps? Does anyone know more about this angle on things?
I renewed my passport last year. Was very impressed with the AI process that evaluated my photo and eventually passed my third attempt as successful. That seemed to signal a step change in submitting photos.
No position
Jon
I read (I think it was a Photo-Me International (LON:PHTM) annual report) that the biometric data is helpful in preventing fraudulent/erroneous applications. I read in a previous Photo-Me International (LON:PHTM) statement that they hoped in time the UK gov't would reverse the decision to allow selfies on passports. At very least it might prevent France and other large markets from allowing selfies.