Small Cap Value Report (Tue 7 Mar 2023) - FOXT, HAT, WIN, CLX

Good morning from Paul and Graham!
Agenda:
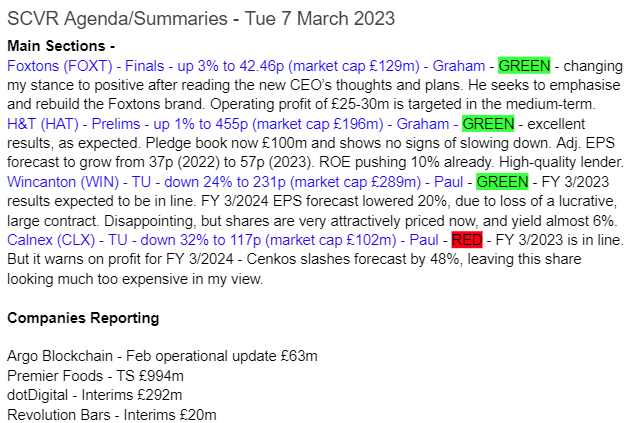
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Wincanton (LON:WIN)
- 231p (down 24%)
- Market cap £289m
Trading Update (profit warning)
Wincanton plc, a leading supply chain partner for UK business, today provides an update on its trading performance and outlook.
FY 3/2023 will be OK, with results to be in line with expectations (PBT up >5%, despite headwinds)
Net cash expected to be £0-10m at 3/2023 year end.
Problems have emerged for FY 3/2024, specifically the loss (on retendering) of a large and high margin HMRC contract, which will now end June 2023.
“More challenging external environment” is also mentioned.
Revised guidance - FY 3/2024 profit will be “materially lower than current market consensus” of £63m PBT. I usually take “materially” to mean at least 10%.
Many thanks to Liberum for crunching the numbers for us, and making them available on Research Tree, this is incredibly helpful -
FY 3/2023 is 41.5p
FY 3/2024 is now dropped 20% to 30.4p, so the PER is now only 7.6x on the reduced forecast, which strikes me as good value, for a fundamentally sound business.
My opinion - this is a disappointment, but not a disaster.
It just goes to show how external investors don’t really know what’s going on at any company. We like to think we do, but (as I mentioned, coincidentally in my last podcast), there can be lucrative contracts that underpin profits, which we’re not aware of (as companies don’t disclose commercially sensitive information like that). Disclosure on client concentration tend to only focus on revenues, which is obviously nowhere near as important as profitability.
So I suppose losing a contract like this is just an inherent risk within any logistics company.
The downside is that this has clobbered the positive story of WIN being resilient, and passing on cost increases to clients. The nice trend of rising EPS has now broken, with the FY 3/2024 revised 30.4p EPS taking us back to 2017-18 levels. Hence it can’t really be seen as a growth stock any more.
That said, on the upside, the valuation was already cheap, and is now 24% cheaper.
This should also increase the dividend yield to almost 6%, providing divis aren’t cut, which they shouldn’t be, as dividend cover is still good, even on the lowered forecasts.
Overall, I’ll stick my neck out here, and say that I think it’s sufficiently good value that I’ll remain green in my opinion. Indeed, I’ve been looking for an opportunity to buy this share, and so might use today’s plunge as a chance to open a starter size position. Trouble is buying on profit warnings can be a mistake, so maybe we should have a cooling-off period before hitting the buy button? I think in time, this share should recover, and in the meantime it should pay generous divis, so although this is a disappointment, I think the value is now strong.
Calnex Solutions (LON:CLX)
- 117p (down 32%)
- Market cap £102m
Trading Update (profit warning)
This morning’s 32% share price plunge has wiped £48m off yesterday’s market cap of £150m - ouch, my commiserations to any holders here.
Calnex Solutions plc (AIM: CLX), a leading provider of test and measurement solutions for the global telecommunications sector, provides an update on the Company's trading performance for the financial year ending 31 March 2023 ("FY23") and the outlook for the following year to 31 March 2024 ("FY24").
FY 3/2023 is in line with expectations, with “solid” trading noted in H2.
Revenue & profits are up “double digits”.
FY 3/2024 is now expected to see lower profits. It blames this on macroeconomic uncertainty, leading to its telecoms customers being more cautious, with orders described as “subdued”.
An H2 weighting is mentioned, which can sometimes be a precursor to another profit warning, if the expected recovery doesn’t happen.
Cenkos updates us (many thanks) with FY 3/2024 forecasts really slashed, down from 7.0p EPS previous forecast, to just 3.6p. At 117p, the share price looks expensive, so the current share price assumes that profits are going to recover considerably in future years.
My opinion - this is such a big reduction in forecasts, that I’m not interested in buying this share. It’s not an attractive proposition, where you’re having to assume a big rebound in future earnings, in order to justify the current price (let alone any upside). So it’s a thumbs down from me unfortunately. Risk:reward just doesn’t seem attractive to me at the current price.
Graham's Section
Foxtons (LON:FOXT)
- Share price: 41p (pre-market)
- Market cap: £125m
We discussed Foxtons only yesterday, but they are back this morning with full-year results for FY December 2022.
The headline numbers are very encouraging and include contributions from various acquisitions.
Revenue +11% to £140m
Adj. operating profit +56% to £14m
PBT +115% to £12m
Earnings per share 3p, total dividend 0.9p.
Lettings revenue grew 17% as the company emphasised this side of the business. Interestingly, lettings volumes were actually down 7%. But in a sign of inflationary pressures, the average revenue per lettings transaction increased by a quarter.
In sales, it’s the opposite: sales volumes nudged up slightly, but average revenue per sales transaction softened..
Looking ahead, they have a “medium-term growth ambition to deliver £25m to £30m operating profit”, to be achieved through growth in all three divisions (lettings, sales and financial services).
Outlook - Trading in January and February is in line with expectations, but 2023 is expected to be “more challenging than 2022”, due to the obvious factors of interest rates and inflation.
Lettings - currently experiencing low volumes, high rental prices. In the medium-term, Foxtons is looking for organic growth of 3%-5% here, plus 20% return on capital from acquisitions.
Sales - new buyer activity reduced after the mini-Budget and the sales pipeline is still feeling the effects. Over time, Foxtons is looking to grow market share from 3.4% to 4.5%.
Financial Services - refinancing activity is resilient, but new mortgages depend on the wider sales market. 7%-10% revenue growth is the medium-term goal here.
Comment from new CEO (excerpt):
"My operational review is complete, whilst Foxtons has strong foundations, core operational failings have throttled historical performance and prevented significant unfilled potential from being realised.
"Operational improvements are being made at pace to rebuild our competitive advantages, including embedding a more confident articulation of our brand, investing in revenue generating headcount and improving our data platform to fully harness the power of our industry leading database.
My view
I’m impressed by what the new CEO has written today. He has been in post for about six months and has come up with what sounds to me like a clear plan for improvement, along with specific, measurable goals for each division of the business.
He doesn’t want Foxtons to be just another estate agent: he wants their brand to be visible and powerful, and has brought back the Foxtons Mini:
He also wants to “turbocharge a high-performance sales culture”. Sounds like exactly what they need!
This company has been a horrible performer over the years, and there’s no getting away from the labour-intensive and dog-eat-dog nature of the estate agency business. There’s also the highly cyclical nature of property sales transactions to consider (although it is now mitigated by the focus on lettings).
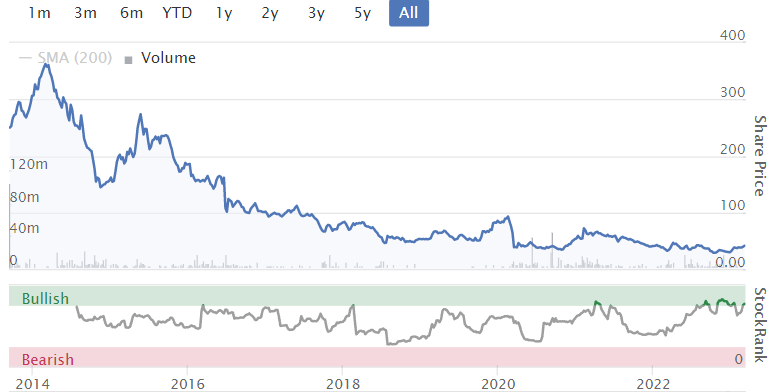
So I’m reluctant to give this company the thumbs up. I don’t consider it to be truly high-quality, for the reasons mentioned above. But the new CEO has done enough to persuade me to cautiously take a more positive stance on it.
H & T (LON:HAT)
- Share price: 455p (+1%)
- Market cap: £200m
The UK’s largest pawnbroker has also published results for FY December 2022.
I covered the corresponding trading update in January.
The results are excellent:
PBT £19m (last year: £10m excluding a non-recurring expense)
Pawnbroking pledge book surges 50% to over £100m
Jewellery sales up 25% to £45m but at a lower gross margin
Forex earnings almost doubled to £5.7m, exceeding pre-Covid levels
What is not to like here?
The company raised £16m of fresh equity in September, to help satisfy the enormous demand for pawnbroking loans. I am generally very happy to see H&T borrowing (rather than raising equity) to fund expansion, but the enormous surge in demand over the past year has been on another level.
CEO comment:
Trading performance continued to build steadily throughout the year, materially ahead of initial expectations. This trend has continued into the new year. January 2023 was a record month, both for lending demand and for online retail sales, the value of which reached £1m in a single month for the first time. As at the end of February 2023 the pledge book had seen further growth and stood at c. £104m. We also continue to see strong demand for our FX services. We continue to believe that FX represents a growth opportunity for the Group.
FCA issue - there was a problem with H&T’s unsecured credit product, which it no longer offers. The company agreed with the FCA a programme of redress for some customers, and 80% of eligible customers have now been given their redress payments. I don’t think this issue needs to be of any concern to investors now.
Pawnbroking - since this pledge book is so large, it’s worth spending a few moments to discuss what’s in it!
Most loans are around £200 and have a contractual term of six months.
85% of loans are redeemed, i.e. the customer pays in full and takes back ownership of the pledged item. On average, customers do this after 97 days (thus saving on interest).
H&T lends 65% of the value of the item. Watches have become more common and are now 15% of the loan book - these tend to be larger loans for longer terms.
The pawnbroking risk-adjusted margin (annualised revenue as a percentage of the pledge book) reduced from 69.5% (2021) to 60.9% (2022).
The company explains this as follows:
We have seen a normalisation of demand across the spectrum of loan sizes, with a growing number of requests for larger value loans. As expected, this has resulted in a moderation of the risk adjusted yield to historic levels, which at c. 61% is in line with the risk adjusted margin reported at the half year.
It makes sense that small loans would need to have the highest profit margins, and larger loans would have lower profit margins.
Store numbers have increased to 269 (last year: 257) and more openings are planned this year. I hope they will do as they promise and open new stores in a “measured and carefully considered manner”, so that they can avoid the perils of over-expansion.
Balance sheet: the company has net assets of £164m, or £137m if you strip out intangibles. It has a small net debt position of £3m.
Broker forecast: EPS is forecast to grow from 37p (2022) to 57p (2023).
My view
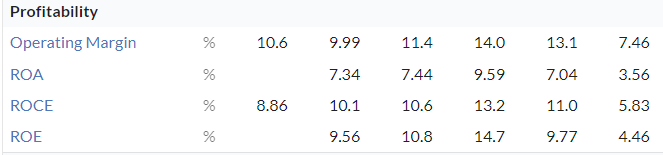
It looks like H&T generated a return on equity of 10% for the year (based on a quick calculation), a big improvement on the number currently showing in the StockReport:
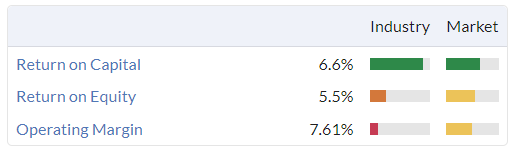
I’ve been hoping to see ROE improve here, and it has already - with a continuing positive trend hopefully taking it to even higher levels.
That’s the major challenge for H&T, in my view: they have an asset-rich balance sheet with a vast quantity of gold and other precious metals, jewellery and watches. They have a huge pile of customer receivables. But can they manage these assets efficiently enough to generate an acceptable ROE?
They’ve had double-digit ROCE and ROE before - these numbers are from 2016 to 2021, scrolling left to right:
For me, there’s enough quality at H&T to justify paying a premium to book value. Price to book value is currently 1.45x, after writing down intangibles to zero.
What makes it stand out for me is that it is, by some distance, the largest pawnbroker in the UK. The loan book at Ramsdens Holdings (LON:RFX) is less than 10% of the size. H&T essentially has a lock on this type of lending in the UK and I believe there is value in having that position.
Other types of short-term, non-bank consumer lending face an unfriendly regulatory environment, while competitors in the pawnbroking space lack the deep, specialist expertise of H&T (who now own the watch servicing company Swiss Time Services).
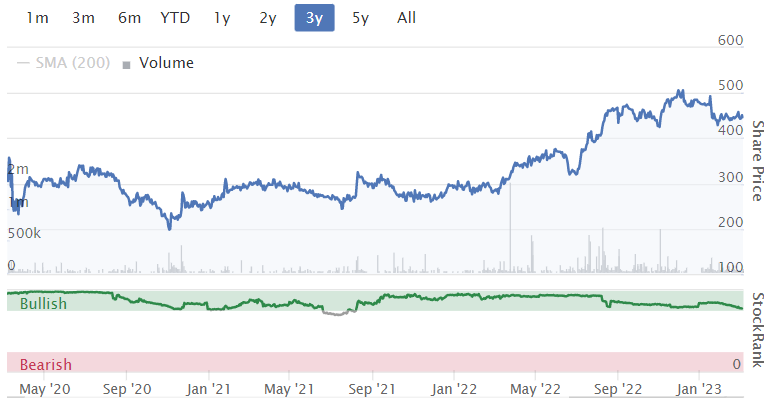
So I’m going to retain my positive view on this one, even after the share price gains seen in recent years:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Calnex Solutions (LON:CLX) At 117p, the share price looks expensive, so the current share price assumes that profits are going to recover considerably in future years.
A fair bit of negativity being expressed in Paul’s report and by those who shared the trip down today. And there may be a second lurch to come before orders turn around. But this is not an idiosyncratic company-specific warning caused by a strategic error or product failure. Every single company in the telecoms testing field has warned on revenues and profits in the last couple of months as big telcos temporarily tighten their belts in anticipation of the recession that may not now occur. Yet the need for investment in 5G is a powerful multi-year tailwind that will reassert itself in the not too distant future. And those test kits will start flying out of the door again. Keysight, Spirent and Calnex are all good companies whose profits will likely rise again to new highs, whatever the short term outlook. Just look at the historical progress and think about what rests on the 5G rollout - IOT, Industry 4.0, e-mobility etc etc. I think Spirent looks attractive as of today and I bought US-listed Keysight after its recent warning.
Keysight Technologies (NYQ:KEYS)
Is something happening with the 5G story? Have read not too good around airports as disrupts aircraft landing systems. No real insights sorry but something of import -like drones at Heathrow not so long ago. Need to research why a cliff today for Keysight Technologies (NYQ:KEYS) - but a nice find in the large US forest - thanks. Sorry not SCVR off message.
I agree - it's short-sighted to value Calnex Solutions (LON:CLX) on one 'very conservative' (Cenkos's words) forecast of a reduction in profit, largely based on the reported deferral of orders by their main customer, Spirent Communications (LON:SPT) . The long-term tailwinds, as you say are in their favour.
While I agree that you are being asked to pay up front for future growth, that is the case with very many shares - some where the price is completely detached from reality such as WANdisco (LON:WAND) which Paul is keen on. I would say that the risk/reward actually looks quite good here. Unless, of course, you think that 5G is going to go away, which I am not sure is either likely or possible.
I'm kicking myself a bit today regarding Calnex Solutions (LON:CLX) . I noticed two large director sales on 17th and 19th January at around £1.92.
They say directors' sales are not necessarily a bad sign, but exactly the same thing happened with Strix (LON:KETL) not long ago. That is a large sale followed by profit warning a few months later.
Not sure what lessons to learn from these two examples if any? With hindsight Strix (LON:KETL) was a higher conviction holding because of its good cashflow and not too demanding multiples. In contrast Calnex Solutions (LON:CLX) was trading ona high PER only justifiable for a growth company.
One thing I HAVE learned over the years is to run profits and cut losses. So I sold Calnex Solutions (LON:CLX) today for 30% less than yesterdays price. Ouch!!!
Commiserations Mark but TBH the director sales you mention and the profit warning from Spirent Communications (LON:SPT) ( a Calnex Solutions (LON:CLX) customer) on Jan 20 were a pretty good indication of what could happen.
Add Kape Technologies (LON:KAPE) to that - directors sold £M at top of the market, now buying it all back at a lower price!
In a way the warning signs were there; I'm looking through my notes for Ethernity Networks (LON:ENET), I wrote down, on the 26th Feb (2 weeks ago), that there was news on Ericsson announcing:
"Ericsson AB reported a bigger-than-expected drop in fourth-quarter earnings after some of its major customers for 5G networks pulled back on spending because of an uncertain economic environment.... and then they slashed 6% of their workforce"
So it would be obvious that downstream companies like Calnex, where their testing volumes depend on telco infrastructure rollouts, would suffer. This is an example why it pays to identify leading signals in the market, to then track, to be able to make a quick exit. Companies never announce profit warnings timely, they always do it quite a few weeks after management starts to see weakness.
BTW - if anyone is invested in Ethernity - I would say get out now, given the bad 5G / Telco investment news at the moment.
Only the sale on the 19th could really be regarded as 'large'
On Reach (LON:RCH)
Results are reported as in line but SP has dropped ~11% (7/3/23 12:44). This may be because print was down (as expected) but online revenue fell too - and that was not expected.
Skimming the RNS (Reach plc - Full Year Results - 52 weeks to 25 December 2022)
I think it is quite well written (I think I understand most of it - probably my first mistake)
In the outlook: "While external factors are affecting near term performance, consistent strategic delivery is supporting the growth of higher quality digital revenues, which with our US expansion, puts us in a strong position to grow when macro headwinds subside. Profit expectations for the full year are in line with the current market consensus(3)." and (3) says "consensus adjusted operating profit for FY23 is £95.4m."
I decode the comment "Digital revenue of £149.8m (FY21: £148.3m) was up 1.0%; growth of 56% in data-led revenues offset by macro related decline in market yield for ad space sold programmatically in the open market, which was down c.33% during the year and c.40% in H2"
as the value of the digital ads sold direct by auction has fallen (a lot) - and I and possibly the market was not expecting this . This is the main point of uncertainty for me - is this a structural change in the business model - or are advertising income likely to bounce back - idk.
It looks like inflation pressures had a greater than expected impact as well (a 38m impact on profits)
They are cutting costs "We're confident that our cost action plan will enable us to reduce operating costs by between 5% and 6%."
but if they are not careful what is being cut may well be the content that attracts attention in the first place.
There are comments on US expansion and people aged under 50 (i.e. not newspaper readers) - but I see it as jam tomorrow.
The dividend is being paid.
I think I will continue to hold, admittedly mostly on the basis of the jam tomorrow (usually a mistake)
I finally lost patience with Reach today. The trading outlook for 2023 is not encouraging but my main reasons for selling are related to the pension scheme. The management have not been able to agree the triennial pension valuation with the trustees for 2019 (now 2 years late). In addition, they also seem to have missed out on the opportunity to de-risk the pension scheme in the second half of 2022 when interest rates were spiking. All this means that the Group will continue to pay £53/4m p.a. for the next 4 years into the pension scheme. This represents a material part of forecast cash generation and unless the profit outlook improves significantly I believe that they will potentially struggle to generate sufficient cash to continue to pay the dividend. Having been in a strong cash position the Group is now drawing it's RCF (£15m out of £120m) - I cannot imagine the banks being keen for the RCF to be used to pay shareholders in the future.
In the long term , there still is the potential for Reach to multi-bag but I suspect there will be more bad news the short term and I for one will watch from the sidelines until the news flow improves.
Reach (LON:RCH)
Ref pension - your assumptions as to what they could or should have done seem very optimistic if i am being honest - they have huge scheme assets and huge scheme liabilities - nearly £2 billion a pop - i suspect doing anything isnt easy ref being nimble. I am flumoxed as to why you would be so confident the huge millstone wouldnt be a millstone. Ok some peeps have come along and said "you dont need to worry about that" but i would be pretty certain if they could have got shot of scheme they would have done exactly that. Note i am not saying the future wont be good its just all so "uncertain" and in that regard nothing has really changed - albeit if profits are slipping away this really could get messy quickly if that continues.
On Wincanton (LON:WIN) if I were to try to assess whether to buy, I would be trying to find out more about the lost HMRC contract.
Clearly it was high margin. Are HMRC are bringing it in-house, or have they found a new supplier? Does this new supplier have something superior to Wincanton, and thus this is the first of many contracts that walk out the door? Will Wincanton have to renew at lower rates for their upcoming renewals, because they fear losing more volume?
Both these scenarios will continue to punish the share price due to contracting margins. So it is important to assess whether this HMRC loss is a one-off.
I totally agree which is why I sold Wincanton (LON:WIN) . Buying or even holding at the moment is a pure punt, we just don't know enough about the situation. And while I respect Paul's views I think buying a stock in this situation on the basis that it's a good dividend payer is a bit risky. Look at Persimmon - cut its dividend by 75% (from memory).
Slightly tangential, but a UPS driver of 30 years in the home counties told me that it has never been so quiet. Having said that, I do have a small position in DX (Group) (LON:DX.)
Hi Paul, Any comments on Saietta (LON:SED) would be welcome. I am really interested in it - but fearful of fundraise and "jam tomorrow". Fortunately I have been waiting for a bottom. so no losses (for me) yet
Stockopedia rates it a Sucker stock.
Well SED!
hi wolfspirit
I'd be extremely cautious if I were you. The bottom may well be zero.
Snazzy
A few days ago, I emailed Spectra Systems (LON:SPSY) as follows:
I am an investor in Spectra. In December 2020, announcing the investment in Solaris Biosciences, The Honourable BJ Penn, Chairman of Spectra, stated:
"Solaris intends to deploy, in new markets, technologies related at a core level to those utilized by Spectra in its current markets. This is therefore an exciting acquisition by Spectra which is intended to introduce it into biotech and healthcare markets. The Directors of Spectra are confident that the transaction described herein will enable Solaris to launch its first prototype device within 24 months."
That 24 months ended on 14 December 2022. Has there been an annnouncement of the propotype by Solaris, or any update to the expected launch date?
I have received this reply from Nabil Lawandy at Spectra.
There's no RNS about this, so far as I can see, though there may have been an RCS.
For context, this is what Spectra said about Solaris in their results last September:
Solaris BioSciences Investment Asset
In December 2020, the Company made an investment in Solaris BioSciences, whose results are consolidated by the Company. The technology is entirely optical and has three major target opportunities which are all focused on extremely low volumes of biofluids: blood plasma viscosity for inflammation, milk viscosity for dysphagia in newborns, and protein markers for cancer survivors to track metastasis. The combined market opportunity for a two-minute, microliter sample volume (pinprick) tests are believed to be well over 1 billion per annum in consumables.
During H1, Solaris BioSciences Holdings was formed as a UK company and has obtained EIS status with HMRC. Solaris has also engaged W H Ireland to undertake a private equity financing which is currently underway.
Just FYI.
Thanks for those comments . However I can’t get the end of nabil’s reply.
I have great hopes for £spsy I hold
(LON:ITS) In the style - I tried to warn people on twitter about this one. Can't believe people were piling into this dog on the back of moronic rampers on there. Was obvious something like this was going to happen.
Yes I agree. We didn't even bother commenting today on LON:ITS, as it was so obviously worthless - as pointed out many times in the SCVRs here previously.
System1 (LON:SYS1)
It's not a happy ship in the board room.
https://www.investegate.co.uk/...
Snazzy
It is such a shame that the management and board are making such a hash out of what I think is a really good offering at System1 (LON:SYS1)
There needs to be a clean sweep of both board and management really. The new CEO is somewhat new, but in a way was also responsible for the failures over the last 2-3 years, having been part of the c-suite already. I actually used to work with him almost a decade ago, and my view of him back then is that he's a safe good pair of hands, but not sure he has the entrepreneurial spirit to really drive Test Your Ad.
That's why I sold out last year from System1. I keep tracking, just to see if there's a better setup or pricing to get back in. But so far, I'm not convinced yet.
hi Boon
Interesting insight, thanks.
Like you I have recently exited System1 (LON:SYS1).
I lost patience after the strategic review which I felt had a very unsatisfactory outcome in simply allowing John Kearon, the founder, 22% shareholder and former CEO (but still pulling the strings as President) to de-camp to USA to try to increase sales.
I have never been impressed with the founder. He clearly knows the product inside out but he is, to me, just a typical over optimistic marketeer. He comes across at presentations as a bit of a mad professor. He does not seem ideally suited to a leadership role at board level.
The company are presently burning cash and have ongoing frictions both at board level and with key investors. There seems to be focus only on increasing sales and little or no commentary on profitability.
Good luck to those who remain invested but I've seen enough.
Snazzy
Every time I read about Foxtons (LON:FOXT) I am reminded of its founder, John Hunt. His helicopters fly over our house about 5-6 times a week en route to his country estate. (He has the carbon footprint of a small European nation). It is a living reminder of the rewards of capitalism - and in our case, timing your exit!
Foxtons (LON:FOXT) CEO bonus plan (SCVR Nov2 22) was based on 70p share price being reached... I like the colours on the mini.
It is probably coincidental, but there have been several rumblings about next year in several shares today - particularly Wincanton (LON:WIN) and Calnex Solutions (LON:CLX) and they have been punished severely in the market. I know Wincanton (LON:WIN) has lost a contract, and Calnex Solutions (LON:CLX) is forecasting muted expectations in telecoms - both quite separate reasons, but maybe we should review the rate of recovery with caution?
Calnex Solutions (LON:CLX) supplies Spirent Communications (LON:SPT) and both have given cautious/negative outlooks this morning. So I suspect that's related to investor's view of the sector, which itself is responding to a weaker economic environment.
I agree and both suffered this morning, admittedly only 13% drop for SPT.
I still prefer to stay with SPT for the long term. It has good record, a bigger company and the statement was a cautious outlook which may prove to be over cautious looking 1-2 years ahead.
The economists debate whether we are moving into a weak recession or a deep one, either way, manufacturers are getting more cautious about the outlook, and adjusting their planning accordingly. This is what happens in recessions. I don't imagine that Calnex Solutions (LON:CLX) - I hold - will be the only small AIM company reporting a weaker outlook for 2024.
I'm hoping there's a read across to Ramsdens (we hold) in H&T's Prelims today. All looks well in pawnshop land. You gave H&T the green light Graham in January, if you have time do these prelims meet your expectations?
Hello JASVFS, I have found Ramsdens Holdings (LON:RFX) has suddenly gone weak in the last few weeks without any obvious reason. The webinars have been very positive and the trends in key elements like foreign exchange, website development, product sales and expansion into SE seemed likely to sustain an uptrend....but not so very recently. We will see whether there is a positive read across from H & T (LON:HAT) though the market has not received their results today in a positive mood.
H & T (LON:HAT) is also down about 10% from its highs for no apparent reason. Surprised to see it down today after a very robust update. They are never going to be sitting on high P/Es but seems they are both undervalued quite a bit at the moment
I agree ridavies, we'll have to be patient holders. In nervy markets shares drift off unless there's an almost constant stream of upbeat news and that isn't Ramsdens Holdings style, I'm bullish.
Hi JASVFS, I've covered HAT now. Yes, they do! G
Greggs Greggs (LON:GRG) update looks to be good.Can you review it Paul?
Big market cap to not say please for!
ha ha
Yes C Wright, Greggs (LON:GRG) seems to go for strength to strength with their very up to date and broadened offering, plus opening a huge number of stores each year so organic expansion creates an encouraging base and ever increasing economies of scale. They always seem to be ahead of the trends if not creating them themselves.
No hot cross buns, no Greggs (LON:GRG)...
The yield quoted at 11% can be misleading since a tax deduction on payment of the dividend of 20% reduces the effective yield to 8.8%
For Greggs (LON:GRG) stocko showing 2.4%
2.24% on my screen.
Not if held in ISA or SiPP.
What tax deduction?
Hi Paul, hope you are having a good day. Just a quick question about Regional REIT (LON:RGL) . The stock is trading well below its net tangible assets and it yields 11% in dividends. Am I missing something that the market knows???
Appreciate your comment.
I used to hold Regional REIT (LON:RGL). I have no specific knowledge of why the market values the business as it does but one reason may be the forthcoming changes in energy efficiency requirements which hang like a dark cloud over most of the commercial property sector. Existing legislation, the Minimum Energy Efficiency Standards (MEES) prevents landlords from granting new leases or renewals of existing ones on commercial properties with an Energy Performance Certificate (EPC) below E. But next month MEES will apply to all privately rented property, and it will be an offence to continue to let a commercial space with an F or G EPC rating even in the middle of a lease term. The next phase of legislation is proposed in the Government’s UK Energy White Paper, Powering our Net Zero Future. This states that all non-domestic properties will need to have at least a C rating before they can be let from April 2027, and from 1 April 2030, it proposes that the requirement will be for all properties to have at least a B rating. This is bad enough (from an owner's perspective) but you also need to be aware that the Standard Assessment Procedure (SAP) for calculating EPCs - the algorithm - will shortly be changing from a cost basis to a carbon basis (SAP 11). At the moment it's easier to get a "C" for a building if it has a gas boiler, because the current algorithm assumes gas is cheaper than electricity, but in future buildings will need to have heat pumps, renewables, storage technologies and smart control devices. Also they will need to be draught-proof and insulated to a degree far above what is typical at the moment. Cast your eye round the average office, industrial building, large supermarket, car showroom, etc. and ask how much it is going to cost to get to B. There is a "get out" - changes must be "cost effective" but nobody knows how that is going to be defined. The mere fact that improvements are expensive is unlikely to be sufficient reason to leave things as they are. Remember that if commercial properties cannot be let the owner not only loses the rental income but also has to pay insurance, maintenance, and full business rates. Commercial property is a bit of a minefield at the moment. There is still money to be made but be careful.
I hold. I believe it is concern about recession and Increased interest rates. Apparently in a recession office space is the worst performing property class and the regions do worse than London. RGL invest in office space outside the M25. Increased interest rates means that Income assets like property need to pay a higher yield to maintain the differential over cash and bonds. The whole Property sector has been marked down but RGL more tham most.
Also many people are still working from home, so demand for office space is probably still contracting. Companies will be looking to reduce their office sizes where possible.
All the UK REITs are sitting on big discounts - mainly due to rising rates, as well as recession fears. Regional REIT (LON:RGL) probably more badly affected than others given it is a pure office play - a sector that faces its own headwinds, and I don't think their properties are in very desirable locations (think dreary business parks). The last time I looked they also had quite high debt, so that could be another factor.
Thank you all for your help. Much appreciated it
Hi MrShanker, I'm sorry I didn't get around to this yesterday but I think you have received some excellent replies from the community. RGL will publish their full-year results on 28 March so perhaps we will be able to include them in the report that day,
Best wishes. Graham
I also hold and agree with the other posts re debt, sentiment towards offices and the energy certification challenges.
We all know people who have said they will never work in an office again and we also know of companies which have, or are, eliminating offices. Last week HSBC announced they would be leaving their 1 million sq foot office at Canary Wharf for something half the size.
However, Regional REIT (LON:RGL) reported recently that most of its tenants had already returned to office working -with the exception I think of three properties housing government departments :( although leases were being renewed. I think that the pure play focus on offices outside the M25 will pay off and the debt seems manageable so this seems an opportunity to lock in a very handsome yield for the future, although it may get cheaper still in the months ahead -who knows!?
Michael C’s very informed points about meeting the new energy certification requirements are also important to bear in mind and if anyone wants to learn more there was a very interesting Investor Meet Company presentation by Aew UK Reit (LON:AEWU) a couple of weeks ago where they describe how they are managing the transition. https://www.investormeetcompan...
I have listened to the AEW REIT presentation which neils mentioned and noted the following which is very relevant to Regional REIT (LON:RGL) and also the MEES problem. I think it tends to confirm what I said above.
Offices: Just as an outlook on that sector [offices] I have some concerns about office occupation and not quite knowing where that's going to settle yet. Clearly it's settling at levels much, much lower than prior to the pandemic, and I absolutely believe in offices but I know they will not be used to the extent that they were before and in addition to that the environmental credentials for offices are becoming significantly more important to tenants and that's really being reflected in investment values at the moment, and I don't quite know if the market has quite got a handle on the costs required in order to meet tenant demand there, so I think there's a lot of capital expenditure coming through non-environmentally [?] offices so it makes me slightly wary of the sector and I'm grateful that we have a low exposure in a few select assets. We might look for some opportunity here if it's priced in line with alternative use values but I would expect that to be fairly few and far between. Later in the presentation they expressed marked pessimism about the office market generally - they said they do see a future for centrally located buildings in vibrant exciting cities with at least a B EPC. I guess that means they wouldn't be interested in the sort of property that Regional REIT (LON:RGL) specialise in.
Industrial: [giving an example] we managed to improve the environmental performance of this building and had the EPC re-assessed following improved insulation to the new roof of the building and we moved the EPC from a C67 to a B44... and that means it will be resilient to all the new regulations coming in as of April this year up to 2030 - but it cost them over a million CAPEX to get there.
MEES - [good flowchart at 39m] - confirmed the points I made about the regulations - they have 6 units in 2 buildings which fail the April deadline for an EPC rating of E or better. One building is rated G on its EPC which they are going to demolish and redevelop, and one rated E which they hope to refurbish.
Graham PLEASE. Any thoughts
My morning smallcap tweet: WIN lose
MGC Pharmaceuticals (LON:MXC) Skinbiotherapeutics (LON:SBTX) Saietta (LON:SED) In Style group (LON:ITS) K3 Business Technology (LON:KBT) Wincanton (LON:WIN) Calnex Solutions (LON:CLX) Hercules Site Services (LON:HERC) Argo Blockchain (LON:ARB), Revolution Bars (LON:RBG), Reach (LON:RCH)
◄MGC Pharmaceuticals (MXC)► positive result from in-vitro pre-clinical study on CimetrA's mechanism of action. It's an anti-inflammatory. [SP=0.47 Cap=18m]
◄SkinBioTherapeutics (SBTX)► AxisBiotix-Ps, a food supplement to alleviate the symptoms associated with Psoriasis, approved for EU market. [SP=23 Cap=40m]
◄Saietta (SED)► some revenue delays. Guides FY23 rev up 40%, FY24 100%+. Cost cutting so that no fundraise needed for FY24. CEO to step back to "focus primarily on strategic business development". [SP=35 Cap=36m]
◄In The Style (ITS)► result of strategic review: no offers for whole company. sale of op biz for a measly £1.2m, de-listing. Remember a year ago? "The Group has continued its excellent growth to achieve a strong sales performanc...We have a strong pipeline of new partnerships and collection launches". [SP=6.9 Cap=4m]
◄K3 Business Technology (KBT)► €1.6m 3 year contract, the largest ever software licence contract for its flagship fashion product, K3 fashion. [SP=110 Cap=49m]
◄Wincanton (WIN)► guides FY-Mar in line but has will lose a HMRC logistics services contract from June. This and a challenging external environment means FY24 pretax will be materially lower than market consensus of £63m. [SP=305.5 Cap=379m]. I hold.
◄Calnex Solutions (CLX)► guides FY-Mar in line but financial performance in FY24 will be below FY23. Blames customers taking a more cautious approach. [SP=172 Cap=151m]
◄Hercules Site Services (HERC)► Amey appoints HERC sole supplier of suction excavator services to the National Highways Area 7 (East Midlands) contract. £2m initial order, will be reviewed every three years, or earlier if required. [SP=41 Cap=26m]
◄Argo Blockchain (ARB)► mining revenue in February $3.76m from $3.42 in Jan. [SP=13.25 Cap=79m]
In line: RBG, RCH
We can cry on each other's shoulders - I too hold Wincanton (LON:WIN which I bought expecting steady trading and a re-rating when the pension deficit problem goes away. Looking at the chart I should have accepted that I had mis-timed my entry and got out last week for pretty much what I paid for it. There was a huge bear flag which I saw but decided to hold on valuation grounds. The RNS is awful - says "materially below" expectations for 2024 but no help whatsoever in deciding whether today is the bottom or the beginning of a long decline. EDIT sold at 230 and I am now even more cautious about investing in businesses which can be hammered by the loss of a single big contract.
Hi Paul, if you are doing Revolution Beauty (LON:REVB), please could you comment on (IAS 17) vs (IFRS 16) and why both are shown, which one you prefer etc.? Thanks
Do you mean @RBG ?
£rbg
Yes! Revolution Bars (LON:RBG)
Apologies it was meant to be Revolution Bars (LON:RBG) !