Small Cap Value Report (Tue 7 May 2019) - Financial Archaeology, PURP, KAPE, BEG, TET, SCE, DIS, KOOV

Good morning!
Lots of announcements to look at today - since most of them are just trading updates, I will keep my comments briefer than usual.
- Purplebricks (LON:PURP)
- Kape Technologies (LON:KAPE)
- Begbies Traynor (LON:BEG)
- Treatt (LON:TET)
- Surface Transforms (LON:SCE)
- Distil (LON:DIS)
- Koovs (LON:KOOV)
Financial Archaeology
In among today's trading updates, I noticed that the Financial Reporting Council has delayed its complaint procedure in relation to a financial executive at Autonomy (AU), the British software business acquired by HP. He is currently facing trials in the US.
What's remarkable about this is that the alleged misdeeds took place up to and including 2011.
How can it take eight years for the authorities to investigate these matters? A rhetorical question.
Short-seller Jim Chanos described Autonomy as "one of his absolute favourite shorts" back in 2012, and admitted that he was crushed by HP's acquisition of it for £7.4 billion, causing its share price to surge by 78%. He went on to make some money shorting HP.
(Autonomy was a "roll-up" of software businesses which made heavy use of merger accounting - something to keep in mind.)
Even though Chanos lost money on the trade, he deserves credit for spotting the story in real time, along with some other short-sellers. He described the funny business as "hard to miss, if you just looked at the accounts".
Indeed, a few brave sell-side analysts were public about their concerns, too. Paul Morland at Peel Hunt published a note with the headline "Accounting Red Flags" in June 2009. Ten years ago next month!
By contrast, the regulators are still bumbling along nearly a decade later, trying to figure out what happened.
We might also consider the famous case of Quindell (now Watchstone (LON:WTG) ), where the man at the heart of the story has within the last year threatened to put a new company on a major stock exchange.
As far as I know, the Serious Fraud Office is still investigating events at Quindell from around 2011-2013. At least the FRC came to a decision on this one last year.
Their extraordinary slowness is why regulators are sometimes referred to as financial archaeologists - they study things in the distant past, not the present day.
Another metaphor I quite like is that they are pathologists. Instead of being the policeman who races to the scene of a crime and shoots the bad guy, they prefer to turn up later, count the dead bodies and figure out the cause of death. They don't want to be blamed for the collapse of a company, so they will nearly always let it collapse on its own first.
Last week, Tesla (in which I have a short position) raised $3 billion from investors in the following circumstances:
- Its CEO had committed a massive securities fraud in the prior year and then, in my opinion, Tesla had ignored the settlement agreement with the SEC which had been designed to prevent future fraud.
- The prospectus filings for the capital raise presented a very different picture of the company in comparison to the rationale presented to investors during the private conference call. In the call, Elon Musk said that Tesla's existing businesses were just "a backstop of value". But the prospectus filings did not even mention the words "autonomy" or "self-driving", which were the basis of his claims in the conference call of future value creation.
- Involvement in c. 600 legal actions (total count, including historical cases), according to PlainSite.org.
My concern is that this could turn out to be another Autonomy, or even another Quindell (which also got bought out). While I don't think that Tesla will get bought out, my main concerns for holding a short position in it are that:
1. To the extent that the company or its officers are guilty of any criminality, the authorities may turn a blind eye, ignore it for as long as possible, and/or treat it with kid gloves. Crime may go unpunished.
2. For as long as prosecutions are delayed or non-existent, the company will be free to raise money indefintely. The SEC will not stand between Tesla and the capital markets.
The simple lesson we can take away is that shorting is very difficult! But sometimes, it's hard to resist.
Purplebricks (LON:PURP)
- Share price: 129.3p (-4%)
- No. of shares: 303 million
- Market cap: £392 million
Trading Update and Directorate Changes
I've been a long-term bear on this one and I'm afraid that I don't see any particular reason to think that it should bottom out soon.
Revenues for FY April 2019 are within guidance and cash finished the yeat at > £62 million.
- UK - "out-performing the market", though growth is likely to be unexciting.
- Canada - "in line with expectations".
- Australia - Purplebricks is exiting the Australian market. Orderly run down.
- US - this bit is v. important:
"The Board has materially cut investment in marketing and other overheads to reduce expenditure to sustainable levels and begun a strategic review".
The wording of this paragraph makes it sound to me like this could be the precursor to abandoning the US. We will have to wait and see. It has always seemed a bit crazy to expand to the US, a very different market, while still learning how to make money in the UK.
The Chairman acknowledges this, apologising to shareholders:
"With hindsight, our rate of geographic expansion was too rapid and as a result the quality of execution has suffered. We have also made sub-optimal decisions in allocating capital. We will learn from these errors and will not make them again."
Founder/CEO steps down. Another huge change. Note that he is also an 11% shareholder. He is replaced by the COO.
My view - this would have made for an excellent short, and might still make for a good one. What kept me away from it was the cash-rich balance sheet and the apparent willingness of certain institutions to put money into it at silly valuations.
If it shutters the US and Australian operations swiftly, it might be able to avoid running its cash balance down too low. The company's broker is now predicting an adjusted PBT loss of only £12 million in FY 2020. It had previously forecast an adjusted PBT loss of £37 million.
If it avoids running out of cash, then there is no guaranteed catalyst for share price collapse, and the share price could continue to levitate around the current levels.
But is it worth the current valuation? I can't see how: declining UK growth, mixed reviews from customers, no moat against competition and three of its most important executives have already quit this year. And yet it trades at more than 2x forward revenue.
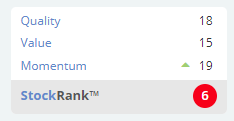
It's classified as a Sucker Stock:
Kape Technologies (LON:KAPE)
- Share price: 89.5p (-0.6%)
- No. of shares: 144 million
- Market cap: £129 million
Trading is in line with expectations.
Within this, customer subscriber growth has exceeded expectations. Kape provides apps and software designed to protect online shoppers and improve computer performance.
This could be worth researching in greater detail. Total subscribers grew by 14% in the first quarter alone to 945,000, beating management expectations. I guess it takes time for this to convert into meaningful revenues.
Growth in Kape's VPN (virtual private network) products is particularly strong - I know from having lived abroad just how useful these sorts of products can be, and I would think that the overall market for VPN products should have a great long-term outlook.
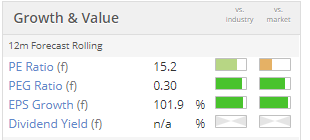
Perhaps this forward P/E multiple is too cheap for a growing company with a good outlook?
Begbies Traynor (LON:BEG)
- Share price: 68.5p (+14%)
- No. of shares: 114 million
- Market cap: £78 million
This multi-skilled insolvency practitioner puts out a positive update: revenue and profits for FY April 2019 will be comfortably ahead of market expectations.
Cash collection was also ahead of expectations, leaving net debt at year-end of £6 million.
Outlook is good too, with a "strong order book and favourable market conditions".
So times are good at Begbies, even if it's not yet enjoying the type of windfall profits it saw in 2009-2011.
I suspect that it is priced about right at the current level, at a low double-digit earnings multiple.
Treatt (LON:TET)
- Share price: 400p (-2.4%)
- No. of shares: 59 million
- Market cap: £235 million
Treatt Plc (the 'Group'), the manufacturer and supplier of innovative ingredient solutions for the flavour, fragrance, beverage and consumer products industries, announces its half year results for the six months ended 31 March 2019.
The historical results don't seem very important, as major growth initiatives haven't kicked in yet: the US site will be fully operational next month, while the new UK site hasn't even begun construction yet.
The outlook sounds good, and full-year results are anticipated to be in line with expectations:
With order books comfortably up on a year ago, we expect the encouraging performance in H1 to continue into H2.
It is heavily exposed to the US (38% of revenues) and says the market there is being driven by premium beverages - another sign of the "premiumisation" of the drinks industry.
My view
The H1 results aren't actually very good, as a non-core business in Kenya has become loss-making. Treatt is now trying to sell this business. Hopefully it won't be a drag on results for much longer.
ROCE: unlike last year, Treatt hasn't published its return on capital employed. This is disappointing, as I consider it to be a very positive sign whenever companies publish this metric.
Based purely on its track record, growth plans and positive prospects, I think Treatt could generate an above-average ROCE (>15%) over the long-term, potentially making for a good buy-and-hold.
StockRanks agree that is deserves an above-average QualityRank. The algorithms are less enthusiastic about the Value.
Surface Transforms (LON:SCE)
- Share price: 10p (-23%)
- No. of shares: 136 million
- Market cap: £14 million
I am new to this company. This is the description on its website:
Surface Transforms are experts in the development and production of carbon-ceramic materials and the UK’s only manufacturer of carbon-ceramic brakes for automotive use.
It has been listed since 2002 and progress since then has been slow. It expects FY 2019 revenues of c. £1 million.
Three customers have had delays or other problems, and a compensation claim with another customer hasn't concluded yet. The FY 2020 forecast is being reviewed to take into account "the consistent experience of late SOP (start of production) and production delays".
It still expects these contracts to be fulfilled, but cash breakeven is pushed back to mid-2020.
This one is beyond my risk tolerance.
Distil (LON:DIS)
- Share price: 1.9p (-9.5%)
- No. of shares: 502 million
- Market cap: £10 million
(Please note that I have a long position in DIS.)
Superficially this has a lot in common with Surface Transforms: it has been listed since 2001 and is still very small. FY 2019 revenues are forecast at just £2.5 million.
It fits within my risk tolerance, however, because it makes consumer products (spirits) and I anticipate that it will generate profits for investors in the years ahead. It made an operating profit of £100k in H1. The balance sheet is healthy.
Paid-for research published today suggests that adjusted PBT should come in at £160k for FY March 2019, same as last year and in line with expectations.
I was looking for an improvement in the bottom line, given that revenues are set to have grown by some 25%.
On the other hand, you could argue that the precise out-turn is unimportant at this stage! After all, nobody is buying this stock at a £10 million market cap because of its P/E ratio. It's all about whether its labels gain traction and become prized brands in the rum, gin and vodka trade. If they do that, then its long-term profitability is pretty much assured (and it will have the option to sell its brands at a hefty valuation, if it wants to).
Main points from today's update:
- Q4 revenues and volumes down 33% and 32%, as Distil prioritised Q3 for promotional activity. Q3 revenues had been up 29% (it's a much more important quarter than Q4).
- Q4 marketing spend only up 10% year-on-year (Q3 marketing spend was up 51% year-on-year).
- New flavour of Redleg Spiced Rum to launch over the summer (caramelised pineapple!)
(Source: Morningadvertiser.co.uk)
My view
I would prefer if financial progress was faster, of course. On the other hand, the company has managed expectations very professionally and has hit its targets - well done to them for that.
This is one of the very few "early-stage" companies that I've invested in. It's important that I am patient with it and give it the time to grow. Hopefully, in a few years, it will have a pleasant outcome for shareholders.
The StockRanks are poor - most companies at this early stage don't succeed. Though it does have a QualityRank of 80.
Koovs (LON:KOOV)
- Share price: 8.15p (-6%)
- No. of shares: 356 million
- Market cap: £29 million
More dilution on the cards for shareholders at this Indian fashion website.
46 million shares will be issued at 8p, making Future Group a 26% shareholder.
Another 24 million shares may be forthcoming, if shareholders approve the issuance of preference shares. The blended issue price of the entire deal is 15p per share - but I would want to read the small print.
The partnership between Koovs and Future group involves concessions in stores, shared studio facilities and Future group products being sold on the Koovs platform.
In addition to the funding update, there is a trading update for FY March 2019. It makes no reference to performance versus expectations.
I don't like this company's track record and it is forecast by its own brokers to make an EBITDA loss all the way through FY 2022. Still uninvestable.
All done for today, thanks for dropping by!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
For any interested a report I did on Kape Technologies (LON:KAPE) was published while I was away on holiday, hence the late notice - Here's the link
Kape Technologies (LON:KAPE) For those who might be unaware, Teddy Sagi is the majority shareholder. He has an interesting past which includes jail time, fraud and having a listed company he controlled buy other -arguably worthless- companies he owned personally. There was quite a bit of trouble concerning this during his time at Playtech. [He is no longer involved with Playtech.] A Google search provides other accusations. I have no position in KAPE.
From the FT, 2015:
Following this purchase Unikmind is interested in 103,500,002 Ordinary Shares, which represents 69.71 per cent. (now 71.9%) of the entire issued share capital of the Company. The entire shareholding of Unikmind is held by a trust, the sole beneficiary of which is Teddy Sagi.
https://markets.ft.com/data/announce/full?dockey=1323-12289915-6F0VCR6JQ32PD9PPPE2IBCCJPV
I think Graham and James Anderson can both be right about Tesla.
Anderson is taking a very long term view. At least ten years and possibly more like 15 or more for some stocks. The SMT investment philosophy is very much that of patient capital.
Graham’s short is, I would think, more about what might happen to the share price in the near term. So, if it is a poor short term investment but a good long term investment then both could turn out to be right.
HI Graham
As a previous sufferer in Quindell I saw that you say that Quindell was bought out ( I assume you mean by Slater and Gordon) but do you know the current situation with Quindell. Are the Serious Fraud Office taking action against the dear old Rob Terry ( I have just discovered that they took action in 2013 and action is ongoing)?
Thanks
John Knight
Hi John (post 25)
I know this may seem incredible given the length of time involved, but investigations into Quindell are still on-going by the SFO. Meanwhile, as you say, Rob Terry has set up again with some familiar faces from his previous ventures in insurance and....Quob Park wine anyone? Yours for a whopping £100 a bottle (a discount of 50% on the anticipated selling price of £200).
https://www.quobpark-vineyard.com/shop/sparkling-wine/quob-park-classic-cuvee-rose/
Caveat emptor. That applies to shares as much as wine.
I think I will stick to Blue Nun. And when the time to comes to float his latest venture (as it inevitably will), I think I will pass on that too.
PK
The con man's description of his wine is beyond parody:
"Blend: The blend of Chardonnay and Pinot Noir.
Tasting Notes: A beautiful, vivid wild strawberry pink with a hue of red onion skin on the rim.
Nose: A whiff of magnolia blossom followed stridently by perfumed wild-strawberry compote with a hint of buttered white sourdough toast.
Palate: Rich mouth-filling flavours of strawberry balanced by zingy tart cranberry and pithy Amalfi lemon notes. The texture is creamy with a clean, crisp, yeasty finish.
Ageing: Ready to drink in 2020."
Thanks Graham, thanks for the write up. It would be interesting if you could get Don on your podcast show (I'm not sure if that's what you meant, or a chat offline). I also hold with a long term view - main hope is the Redleg brand taking off, though operating in a very competitive space.
Interesting that Graham mentioned Jim Chanos. The latter is adamant that the US fracking industry is essentially loss-making. Why? Well, it commonly uses full cost accounting methods. The costs are capitalised and then subjected to depreciation. There also appears to be serious issues in regard to the calculation of break-even points. If he is correct, it has huge implications for the oil industry which, contrary to popular mythology, is very far from dead. And, of course, there are lots of under-researched oilers on the AIM market.
Purplebricks (LON:PURP) still has the vast Woodford overhang to unwind. Canada property market is collapsing. As we see from internet retailers vast marketing spend is required to generate business. There will be no new buyers from growth investors, as the growth thesis has been proven false. No reason to think that the price will do anything other than drift downwards.
Graham, your introduction today on Financial Archeology is a fascinating read. Thank you!
Cheers Paul!
given how much the markets are down today and the general gloom following Trumps tweets, its a wonder purple bricks has only fallen 4%
No offence to any holders but its pretty bad news and i'd have expected it to tank 10% or more
I'm not sure I agree with you here.
I have had a small short on Purplebricks (LON:PURP) for some time (Without checking back, I think it was from c. £4) and if anything today's announcement makes me consider whether I should close it.
The idea that they were flushing away cash on dubious loss-making international expansion made the short continue to look attractive. If they are exiting this, then the short case is reduced to the simple case that they are overvalued for their earnings (the UK business is apparently profitable) - overvaluation is in my view insufficient to make a short justifiable.
However, there is probably just enough here for the moment to keep me short.
Canada is performing inline "The Board has a strong belief in the future opportunities in this market." Reads to me that future profits are still based on hope rather than evidence.
USA "the board has materially cut investment in marketing and other overheads to reduce expenditure to sustainable levels and begun a strategic review." That sounds jumbled to me, without the investment in marketing they cannot succeed, so are they just refusing to bite the bullet and close down the US operations yet? Unless perhaps they are looking to take the decision State by State which perhaps might make some sense - although as i'm unconvinced that the business model is strong even in the UK this would still give me some encouragement to stay short.
For now I will stay short and review the final results in July, the cash costs of closing Oz and stalling the USA (& perhaps by then deciding to close it) might well be enough to cause further gloom, even though I suspect it is a rational business decision.
kind of what I meant. you just put it better than me. i expected a bigger fall but it felt like something was holding it up
that said it did end up 12% down afterall
nice short. Agree with your timeline - seems to be some kitchen sinking going on, perhaps a bit more from any incoming CEO - potential to turnaround in 2020
I find Graham’s and Paul’s intros to their articles really interesting and welcome observations that are not simply focussed on the UK’s Small Cap space. For me, it helps to paint a broader picture.
Graham writes:
I recall an insolvency partner in Deloitte & Touche explaining to me that his role is to come on to the battlefield when the battle is over and bayonet the wounded.
While it is interesting to have comments about the TESLA saga, I find it strange that this is given priority over reporting on the smaller companies.
I must stress that I really enjoy the daily inputs from Paul and Graham and have been an avid reader of them for many years.
Hi Graham, you might be interested in these opposite views of two investment trust managers about Tesla:
https://www.trustnet.com/News/2265582/tesla-likely-to-become-worlds-largest-company-says-scottish-mortgages-anderson/
http://www.morningstar.co.uk/uk/news/186610/jupiters-clunie-james-anderson-should-sell-tesla.aspx
Thanks - it's funny that the fellow at Jupiter Fund Management (LON:JUP) has shorted 1/3 of SMT's shares and SMT itself!
Hi Graham,
Scottish Mortgage Trust has an excellent 5-year performance record of +175% (compared with +6% for Jupiter Absolute Return). So by shorting Tesla's shares, you are taking the opposite view to a very successful fund manager. Of course, you might be proved right.
Hi Graham - you may be planning to cover anyway if you still hold - Distil (LON:DIS) trading update. No change to mgt expectations today for full year though rev and vol down 32 and 33% YOY for Q4. Also say this was expected due to strong Q3. Plus Easter falling outside Q4 this year - not sure how much difference that actually makes as it would be consumers not retailers purchasing over Easter weekend?
Cheers
Hi gary, I think Easter did making a difference although I can't quantify that. I'd like to chat to Don @ Distil to get a deeper understanding of the ebbs and flows of sales. Thanks for the suggestion anyway. G
Thanks for the suggestions - will try to incorporate. G
Begbies Traynor (LON:BEG) I hold based on valuation and potential counter cyclical behaviour.
Would be interested to hear Graham's analysis.
Incidentally, I have an RNS alert with Morningstar for this stock and still have not received the e-mail at 9:08 am.
Hi Graham,
I have always had a soft spot for Surface Transforms (SCE Mkt Cap about £11.5) who always seem a moment away from breaking into the main manufacturing market with their revolutionary high performance brakes. It has upped its manufacturing capacity successfully over the past five years and now, as announced today, the car OEMs (and aircraft in a smaller way) are letting SCE down with delays rather than cancellations. IMHO the share price is back in very interesting territory though there could well be a further fundraising at some point despite the protests to the contrary in today's statement (management expect £1.9m cash to be enough to take the Co to cash breakeven by mid calendar 2020). Stockranks hate it, correctly to date, with a score of 15 (and probably falling!!). I am not a holder.
I would be interested in Kape Technologies (LON:KAPE) too, please, Graham. On the face of it, things sounds rosy with the figures mentioned... but when I looked at the finals previously I was put off by low revenue growth and the low ROCE and margin figures on Stocko.
There is a Q4 update from Distil (LON:DIS) which looks a bit scary on the face of it.... "revenues and volumes were in line with our expectations, being 33% and 32% lower respectively, reflecting the additional stock build by our distributors during the third quarter", though management claim it is part of their strategy being "a result of the earlier phasing of our promotional activities, the sales benefits of which were seen in the third quarter, which is our major trading period". I think you hold Graham...?
There is an update from Kromek (LON:KMK) stating revenue growth for the full year 2018/19 and EBITDA profit will be in-line, and with a confident outlook; the share are reacting moderately positively.
There is a positive update from Victoria (LON:VCP) stating results will be in line, positive lfl of 3%, increased margin of 100bps with them forecasting a similar margin update in 2020.
Begbies Traynor (LON:BEG) requested please - can't buy any right now but listed price on HL hasn't moved.
Don’t know about the “brown trousers” for Purplebricks (LON:PURP) but it certainly seems that it is indeed a castle built on sand in many ways. The hubris of costly overseas expansion before they’ve got their domestic operations generating free cash flow was a sight to behold. Hope everyone here that held this one got out before the roof started collapsing.
My morning smallcap tweet: Brown trousers for PurpleBricks.
Bidstack (LON:BIDS), Begbies Traynor (LON:BEG), ImmuPharma (LON:IMM), Purplebricks (LON:PURP)
Bidstack Group (BIDS) £5m placing at 12.5p, a 19% discount. Placing "gives us the financial resources to capitalise on our strong current position."
Begbies Traynor (BEG) guides FY rev and profit comfortably ahead of market expectations thanks to a number of successful fee realisations combined with continuing strong performance from both operating divisions.
Immupharma (IMM) delays Managed Access Program for Lupuzor while talks continue with potential corporate partners as well as consulting with regulatory advisors on potential pathways to market.
Purplebricks Group (PURP) Founder & CEO resigns. Immediately reverse some of his plans. Exits Australia, blames execution errors and challenging mkt. Rows back on US - "materially cut investment in marketing and other overheads to reduce expenditure to sustainable levels and begun a strategic review." CEO is thanked.
"Ah CEOmisery. The misery you feel when you expand too rapidly but got nothing more for your money."
Morning Graham,
Kape Technologies issued a trading statement today ' Kape has made a strong start to the financial year with trading in-line with expectations. We have seen significant progress across the business, with customer subscriber number growth exceeding management expectations.'
Would be interested to hear your view please.
Michael