Small Cap Value Report (Tue 7 May 2024) - FDEV, MACF, NTBR, SEE, NEXN, MCON

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
Other mid-morning movers (with news)
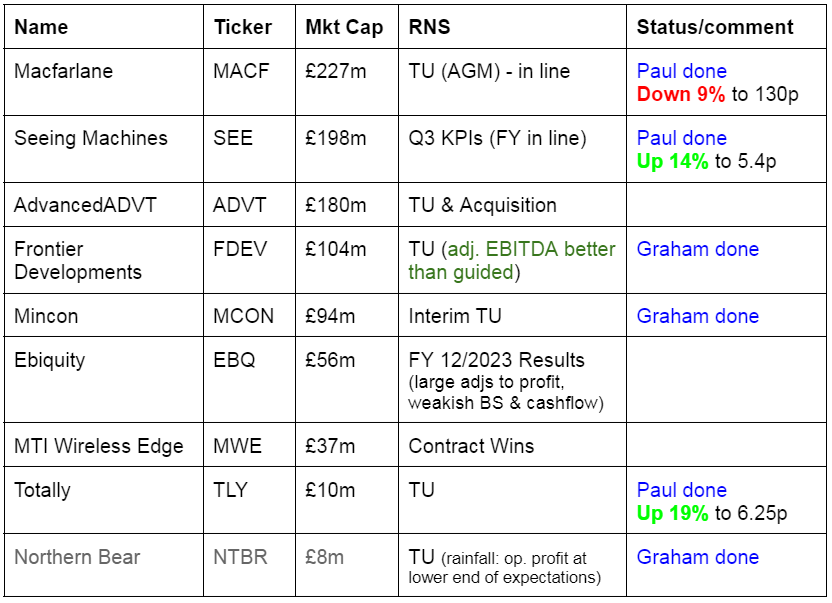
Totally (LON:TLY) - up 19% to 6.25p (£12m) - Trading Update - Paul - AMBER/RED
“... pleased to report improved performance…”. Expects FY 3/2024 to be £106m revenues (down 22%), and EBITDA of £2.3m (doubled from £1.1m last year). Only gives gross cash figure of £2.3m, says net debt unchanged from H1 (wasting our time having to look it up - it was £800k at 30/9/2023 - cash less a £2.5m bank loan - with headroom on covenants it says). The last balance sheet was weak, with NTAV negative at £(11.4)m, so I’d say placing/dilution risk here is high. Cashflow in 2022 & 2023 looks alarming, with a £15m cash pile having largely disappeared (due to £5m contingent consideration, £2m divis [now stopped] and adverse working capital movements). Cost-cutting done, to save £3.5m in annualised costs.
Paul’s opinion - chance of a turnaround maybe? The track record is so weak, as is the balance sheet, that’s it’s not something I’m interested in. It’s not clear if it’s even a viable business, and seems to be permanently either in restructuring, or seeing contracts go wrong, or cancelled. Could be a speculative punt for the brave though?
Nexxen International (LON:NEXN) - up 7% to 239p (£334m) - New $50m share buyback - Paul - AMBER/RED
Checking my notes, this $50m buyback was previously announced on 15/3/2024 (seeking authority for $50m buyback). Management tells us today that the shares are under-priced. Rightly or wrongly, I’m steering clear of this share, as I saw red flags (see SCVR 17/8/2023).
Northern Bear (LON:NTBR) - down 4% to 56p (£8m) - Trading Update - Graham - GREEN
It is a mild profit warning from NTBR. However, given the extent of rainfall experienced in recent months, the company still considers it a very good result - implying an obvious mismatch between forecasts and reality! In any case, the share continues to trade at a level that should get value investors interested.
Seeing Machines (LON:SEE) - up 13% to 5.35p (£224m) - Q3 KPIs - Paul - AMBER/GREEN
This driver-monitoring systems company has a June year end, so we get a Q3 update today, Jan-Mar 2024. The growth rate has sharply accelerated, of vehicles produced with SEE technology installed in them. Lots of detail is provided, the key part being this -
“As we see our high-margin royalty revenues increase, we reiterate we are on track to meet FY2024 expectations and achieve a cash break-even run rate during FY2025.”
Paul’s view - I’ve previously been critical of the poor financial track record, multi-year losses, and heavy dilution from multiple fundraises. However, I turned positive on SEE shares after management explained to me that European legislation is now driving adoption of its driver-monitoring systems. SEE gets a modest royalty per unit fitted to each new vehicle. IF the bull case plays out, then this could rapidly grow into a lucrative, high margin income stream for SEE. I think it looks interesting.
Summaries of main sections
Frontier Developments (LON:FDEV) - up 6% to 280p (£110m) - Trading Update - Graham - AMBER
This trading update is ahead of expectations, and I am happy to maintain my amber stance. FDEV’s back catalogue, including the launch on consoles of a previously PC-only game, along with cost cuts, have reduced the scale of their losses. But they do remain loss-making and in desperate need of a big hit.
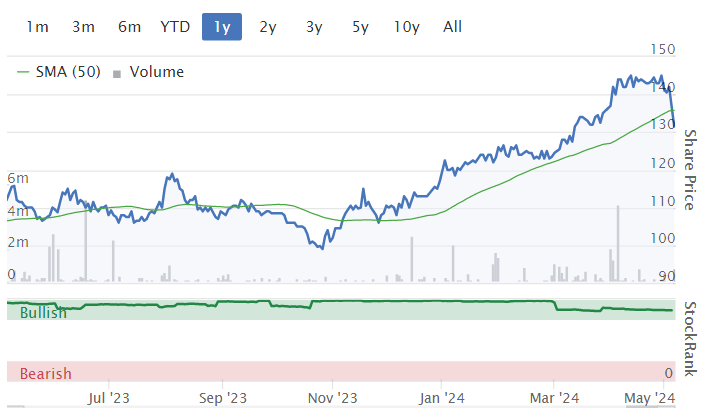
Macfarlane (LON:MACF) - down 8% to 131p (£208m) - AGM Trading Update - Paul - GREEN
Weak Q1 performance is announced, but expecting a recovery in H2, so FY 12/2024 expectations unchanged. My enthusiasm for this value/GARP share isn't significantly dented though, it remains appealing value in my eyes.
Mincon (LON:MCON) - up 2% to 44.85p (EUR €98m) - Interim Trading Update - Graham - AMBER/GREEN
Small signs of green shoots here as Mincon gives investors positive commentary on both mining and construction; subdued demand from the mining industry has been one of the biggest headwinds here. I’m cautiously and tentatively going AMBER/GREEN, hoping that good financial results will follow.
Paul’s Section:
Macfarlane (LON:MACF)
Down 8% to 131p (£208m) - AGM Trading Update - Paul - GREEN
Through its two divisions, Macfarlane Group services a broad range of business customers, supplying them with high quality protective packaging products…
The current financial year ends Dec 2024.
“Challenging” Q1 - sales down 9.5% vs 2023, due to weak demand and price deflation, partly offset by strong gross margins, and benefit from acquisitions.
FY expectations unchanged though, as it expects an improved H2.
Cash position looks fine at 31/3/2024, with net cash of £4.7m (up from £0.5m at 31/12/2023), although it would have been more useful to be told the average daily net cash/debt figure. A one-day snapshot of cash is of little use. Lots of headroom, with £35m bank facility until Dec 2025.
Valuation - Shore Capital has an undemanding forecast of 12.5p adj EPS for FY 12/2024 (down slightly on 12.8p actual for 2023). That puts MACF on a PER of only 10.5x, which looks good value to me. The forecast dividend yield is 2.9% after today’s drop in share price - not bad, considering MACF is also self-funding bolt on acquisitions too.
Paul’s opinion - today’s update strikes me as a moderate negative, so the 8% drop in share price seems about right. I’m not keen on H2 weightings, as that increases the risk that tough conditions might continue. Although the UK economy does now seem to be starting to resume growth, and it mentions customer de-stocking, which is only temporary.
Overall, I’m happy to stay at GREEN as it’s a decent business, at an attractive valuation in my view.
Graham’s Section:
Frontier Developments (LON:FDEV)
Up 6% to 280p (£110m) - Trading Update - Graham - AMBER
This troubled video games developer issues an update for FY May 2024.
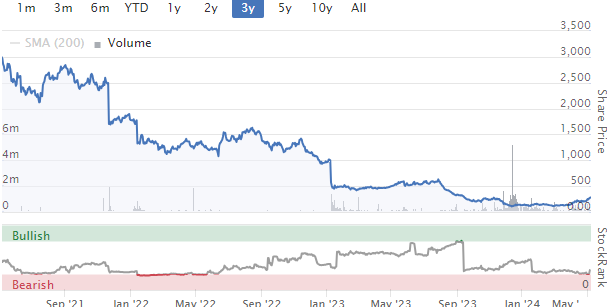
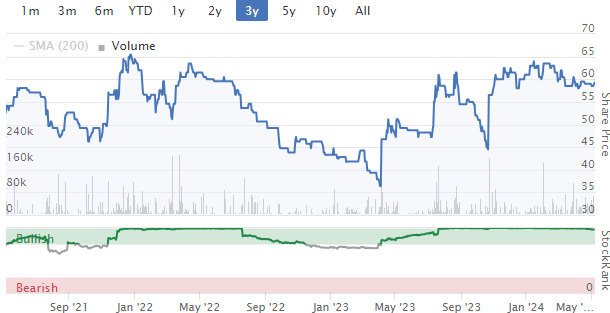
I don’t think it’s controversial if I say “troubled”, given the 3-year chart:
The most recent trading update in April offered some reassurance that the company’s cash pile may have stabilised and that the company was trading well.
The company has refocused on its “creative management simulation” games, such as Jurassic World Evolution 2 and Planet Zoo, and these have performed “particularly well”.
Planet Zoo continues to sell well on consoles (previously PC only).
The company’s financials are therefore better than expected.
Revenues for FY24 are now expected to be at least £85m: according to a note from the broker Liberum, the consensus figure was £83m, while the StockReport suggests £84.2m.
Adj. EBITDA is unfortunately still negative, with a loss of “£5m or better”. However, it could have been much worse as Liberum had pencilled in a £13m loss.
FDEV is benefiting from a higher gross margin percentage as they sell more of their own intellectual property instead of publishing the work of other developers, and they have been cutting costs.
CEO comment:
"I am pleased to announce that our expectations for our financial performance in the current financial year have improved following the excellent reception to Planet Zoo's arrival on console and a good ongoing performance from our other CMS titles. We are making strong progress following the reset of our strategy during 2023 and I'd like to thank our people for their support during a difficult period in Frontier's thirty year history. We look to the future with renewed confidence."
Graham’s view
I’ve been harping on about various reasons for optimism here - see the coverage in April for a reminder.
But the overarching reason for doubt remains: how to predict the success of a studio that only releases a few flagship games (maybe only one) in a year? Big CMS games such as Planet Zoo take a long time to develop.
On FDEV’s website, the only major game I can see coming out soon is F1 Manager 2024. The previous iterations of F1 Manager have received pretty good reviews, but they have not done well enough to prevent some of FDEV’s worst ever financial results.
For now, performance is resting on the back catalogue and the prospect of a fresh big hit in the CMS genre, at this point in time, seems speculative to me.
The shares are still “cheap” but I can’t go any higher than AMBER for now.
Something that wasn’t mentioned in today’s trading update is the cash balance: forecasts suggest that it is currently falling from its last reported level (£23m). The closer it gets to zero, the more likely it is that I will be forced to change stance to AMBER/RED, unless there is evidence of major title launches coming soon.
Northern Bear (LON:NTBR)
Down 4% to 56p (£8m) - Trading Update - Graham - GREEN
We have an FY March 2024 update from Northern Bear, “the AIM quoted group headquartered in Northern England providing specialist building and support services to customers across the UK”.
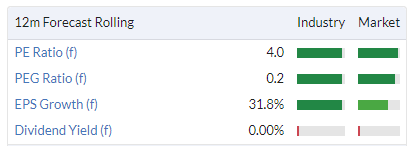
We don’t cover this one as often as we could, due to the very low market cap, but it continues to trade at an apparent PE Ratio of about 4x.
However, today’s trading update is a very mild profit warning, due to rainfall.
…the Group has continued to trade well… There has been significantly higher rainfall than normal during H2 FY24, with rainfall in the North East at 153% of the long term average per Environment Agency statistics, and a total of nine named storms. This has inevitably caused some disruption to the Group's site activities, consistent with the wider construction sector.
Results are therefore “broadly in line”, with operating profit at the lower end of expectations, which is “a very positive result in the circumstances”.
Graham’s view
I’ll maintain my thumbs up stance on this share, due to the apparent cheapness.
For the SCVR record, I should mention that we’ve had some changes to the company structure at NTBR in recent times:
Canadian investor Jeff Baryshnik has been trying to exit for some time and there is still an apparent overhang (owns 10.97% as of the most recent filing).
The company repurchased £3m of shares in a tender offer in December.
The largest % shareholder is now a UK-based individual.
NTRB continues to come across as a nano-cap that’s worthy of further research by value investors.
Mincon (LON:MCON)
Up 2% to 44.85p (EUR €98m) - Interim Trading Update - Graham - AMBER/GREEN
This Irish engineering group has faltered in recent times with a major profit warning last October. Demand from the mining industry has been weak, filtering through to lower revenues and lower profits.
Today’s update covers 2024 year-to-date, with the following bullet points:
Q1 2024 revenues “broadly flat” vs. Q4 2023 as the market remains “subdued”.
Order books “have begun to recover”, suggesting optimism for Q2 and the rest of the year.
Positive commentary on the outlook for both mining and construction.
Some other points:
They have further reduced working capital by reducing inventory.
(GN note: they already reduced inventory by 9% from Dec 2022 to Dec 2023. Inventories were €69.7m as of Dec 2023, a very high figure against annual cost of goods sold €111m).
They are closing a carbide (drill bit material) manufacturing business in Sheffield, in order to transition to lower cost sources of carbide supply.
Greenhammer: the elusive project is having an extended test in Arizona, “with positive results”.
Subsea: another named project “has met a number of key milestones with some of the leading developers in offshore wind in attendance”.
Outlook: positive.
Graham’s view: I’m leaning towards a more positive stance on this share today.
For one thing, the share price is 15% lower than it was when I reviewed it last time (in March).
Today’s commentary suggests that mining industry demand has finally stabilised after all the Covid-related disruption, with customer inventories now “largely normalised”.
And the Greenhammer project must, surely, be on the way to mass commercialisation on the back of this extended positive test in Arizona?
Meanwhile, reduced inventories should be positive for cash flow, and result in continued improvement in the net debt position.
I’ll tentatively put this one at AMBER/GREEN, but will have no hesitation in switching back to neutral if good financial results don’t follow soon.
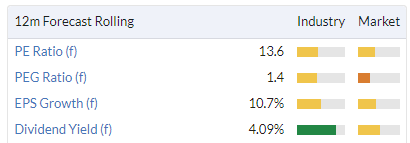
And for those who like an income, this company has paid the same flat dividend for many years, currently yielding 4%:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Huge fall for Redde Northgate (LON:REDD) today anyone know why?
Redde Northgate (LON:REDD)
hmmm was about to go into panic mode (its one of my top 5 holdings) but shareprice looks up to me today and at 12 month highpoint ? not sure where you have gotten your data from ?
Check google
294.50 GBX −91.00 (23.61%)today
Closed at 392 at 4.30... I never understand these freak trade prices post the close ... hoping an expert might enlighten us ? Many thanks indeed
£REDDE
yahoo stockyand lse dont seem to have the drop that google is showing - hopefully google is the wonky donkey (gulp)
https://www.londonstockexchang...
https://uk.finance.yahoo.com/q...
On LSE a trade was incorrectly entered at 294.50p for 30k shares, it looks like. It was reversed and re-entered at 394.50p. So yeah, Google has not picked up the correction.
IG Design (LON:IGR) having a nice post earnings bit of buying pressure as Paul mentioned could well happen.£2 a share on the cards soon too?
IG Design (LON:IGR) I noticed Cockney Rebel bought in last week and echoed Paul's comments in his weekend post. Maybe CR will bring some of his followers with him. (I hold)
IG Design (LON:IGR) were over £7 in 2020, so it is quite possible. I hold.
Cockney Rebel is a fan of the 'bowl' recovery play isn't he?Fingers crossed!Markets have dare i say been 'bottoming' for a few previous' star shares'.Just saw a worked posted afterhours trade of over £200 k go through.And another of circa £40 k.Good volume today.
Exactly two weeks before we all meet up again in Chiswick as it is our Mello2024 investor conference taking place on Wednesday 22nd May & Thursday 23rd May 2024 at the Clayton Conference Centre in Chiswick, London. The two day investor conference that will include nine top quality keynote speakers, eight educational workshops and panel sessions, 40 exhibiting companies plus over 80 company presentations for investors to evaluate and understand their current or future investments. https://melloevents.com/mello2024/
Purchase your ticket and get 40% OFF! Use code M24EB40
Ticket Options
One Day £99.00 Two Days £169.00 (Just £59.40 or £101.40 with 40% discount)
BUY NOW: https://www.tickettailor.com/events/melloeventslimited/1201351
If you have never been to one of our two day conferences before then clearly you are missing a great opportunity to engage with management teams and also network with hundreds of likeminded investors so we are offering virgin tickets at just £30 for either of the days so that you can see what it is all about.....a big discount from £99.00 and if you do not agree having spent the day with us I will give you an annual pass to our virtual shows on top. I just want investors engaging with all these quality smaller companies. This offer is only if you have never attended before so please be fair to all those who pay much more.... Simply enter the code NEW2MELLO24
As a thank you to the Mello community for supporting us through the pandemic and since our first conference in Derby in 2014, we are offering a loyalty discount for those who have attended three or more in-person Mello events.
LOYALTY DISCOUNT....Have you attended three or more in-person Mello events? If so, you are entitled to our loyalty two-day ticket at just £67.60
Use Code LoveM2024 https://www.tickettailor.com/events/melloeventslimited/1201351
Terms and Conditions Apply. Please note that loyalty tickets are non-refundable and ticket holders may be subject to proof of eligibility. The loyalty rate is limited to 100 tickets only.
We hope you can join us and stay tuned for our 10th Anniversary in the Autumn!
Quick note as appreciate this is a company in formal winddown
NB Global Monthly Income Fund (LON:NBMI)
It has just confirmed another ~48.7% of shares to be bought back by a compulsory redemption at 70.87p, current price to buy is 57.9p via AJ Bell. Not available through all platforms.
I have been averaging down during the process through reinvesting each redemption so a small capital gain on each transaction. Small part of the portfolio, but a profit is a profit, not as much as some would make but happy all the same.
Deal goes ex on 21 May 2024.
Good look.
Tommy
Does this mean if I buy shares today at 58p the company will be looking to buy them off me at 70.87p after 21 May?
Eurocell (LON:ECEL) - for info I've noticed forecasts have been increased today. FY24 up 13%, FY25 up 11%. Not sure if this was already known through broker notes but news to me...
Thanks! Hadn’t noticed that, decent business and one which will dramatically recover its earnings when RMI returns to strong growth - which I wouldn’t say we are light years away from!
Ryanair is down (around 6%), due to lower short term forecasts for customer pricing. Read across has sent easyjet, and Jet2 lower - surely just a short term headwind (excuse the pun). Buying opportunity imo on Jet2 but may wait to see if it drifts lower in the next couple of weeks.
Ryanair shares were down 6.4% at 1354 GMT,
with easyJet EZJ.L and Lufthansa LHAG.DE shares also down
after O'Leary's comments.
"Looking at summer ... We thought pricing would be up 5-10%.
We're heading to flat (pricing year-on-year) to 5% up, which is
surprising with a lot of the Airbus AIR.PA fleet grounded for
maintenance," he told Reporters in Brussels.
Thanks for this. I was looking to see why Jet2 was down.
the markets sometimes amaze me - all the budget airlines were down by a similar amount at exactly the same time - I thought it was due to tensions in Egypt - so thanks for the info it was off the back of the Ryanair Holdings (ISE:RYA) statement
Centaur Media (LON:CAU) takeover talks off. Reminded myself yet again don't try and buy into a share on hope of the discussions coming off positively for a quick buck :(. Felt like 50s was a decent value from the previous scvr reviews and poster comment so may now be a hold and see it they deliver on their capital market day plans. Thoughts?
I have added this pm. Cash flow returns have improved markedly in the last five years and I do think with Harwood/Aberforth in the driving seat we will get the value realised at some point.
I wonder if the "no bid" is because Harwood's price expectation couldn't be met by a PE buyer wanting it on the cheap. Maybe only a matter of time before someone else comes calling?
Hi Paul,
Thanks to you, Graham, and the team, for your work here. I wanted to add some positive points to the discussion about Nexxen International (LON:NEXN) as I believe there's a bit more to consider - also incorporating elements from your previous update where you mentioned several red flags.
Management has certainly not covered themselves in glory over the past 2 to 3 years. They've managed expectations poorly, having to downgrade targets several times since the last and largest acquisition. While I realise this isn't entirely their fault (a lot has happened in the last couple of years), overall, I think volatility in the business and sentiment may well remain over the next period however I would say that Nexxen appears to be making positive strides, and sentiment in the advertising industry should at least start to improve from multi-year lows.
For transparency, I sold a large percentage of my holding in 2021 but have continued to hold the balance and added over the last year.
Best wishes,
Michael
Card Factory (LON:CARD) detailed write up and author suggesting > 50% upside:
Card Factory, a leading UK-based, vertically integrated retailer of greeting cards and a significant seller of celebration essentials and gifts (balloons, party supplies, picture frames, stuffed toys, etc.), has cultivated a strong brand identity by excelling in value, quality, and selection. Despite competitors possibly matching them on two of these dimensions, it’s highly unlikely any can surpass Card Factory across all three. Card Factory is in a position to earn high returns on capital for many years to come. Volumes of the greeting card market are set to remain flat or be in slight decline, and the market is viewing Card Factory as a member of a declining market when, in fact, Card Factory is poised to continue to gain market share in greeting cards and grow share in the growing market of celebration essentials and gifts. Like most of the companies we look for, with Card Factory trading at only ~7.5x EV-to-normalized-free-cash-flow, the market perception is that Card Factory is getting weaker when it is, in fact, getting stronger. We expect Card Factory’s free cash flow to grow at low teens over the next five years and the cash flow generation over this period will be greater than the current enterprise value of the firm. We believe this company has comfortably greater than 50% upside.
https://pernasresearch.com/res...
There were a very chunky couple of trades on Card Factory (LON:CARD) this morning:
How do you know if they are buys or sells?
also can you advise where you can access this type of info?
Large trades necessarily have both a buyer and a seller. They are different from small trades done via market makers.
Didn't find the write-up particularly compelling if I'm honest - Card Factory (LON:CARD) looks cheap but struggle to see how it's going to grow much when its core product is in a steady (albeit slow) decline. The bull case seems to be on them taking market share, but this surely needs to be balanced with possibility of new competitors coming into the market (eg Cards Direct seem to be expanding quite rapidly).
Card Factory (LON:CARD) but if you’d watched the capital markets strategy then you would know that it isn’t really about them taking market share at all Bouden54. There is much more to the growth story than that, including international expansion and changes to mix of products with higher margins.
Outside of Christmas cards I see no decline in their core cards market either
Card Factory (LON:CARD)
Hi Bouden
Fair comments on Card Factory. Good to get an alternative view. Makes me revisit my own rationale for holding.
The future of Card Factory seems to me to be based on maintaining their Value proposition through strong distribution and vertical integration. Business is now generating a lot of cash, hence paying off debt and getting freedom to reinstate dividends as a result. Next step probably buybacks. You're right that the market for cards is declining, partly due to changing habits and online greetings and aided by the price of stamps! The decline rate is slow though and by closing underperforming stores and opening better located, better value stores they should stay strong for the forseeable.
They have been building distribution through third party locations too, like Matalan, and I can see this 'wholesale distribution' increasing. Overall a bit like Smiths News? Good, sound profitable business effectively in long term run off. Run off will be extended by slow change in consumer behaviour.
Also is it fair to say competitors come and go. Without writing off Cards Direct we've seen off Birthdays, Clinton Cards, Paperchase and I'm sure others will have their moments in the sun. Card produce most of their own cards and are difficult to beat on price, if you want to make any money at least.
Appreciate it may not be an investment for everyone but I'd hope to see 150p once Telios have made their minds up and become a solid holder or manage to exit. Might take another 12 months? Might take longer.
And reference Rhomboids comment - I believe Dean Hoyles was the Founder here, on Wakefield market, and started (or at least owned most of) The Works. Then spent lots of money getting Huddersfield into the Prem and got the ex CFO of Card to join him when he retired post float.
Card Factory (LON:CARD) thx for the link….founder is apparently called Danny Hoyle …for years I’ve been labouring under the misapprehension he was called Dean Hoyle …albeit his son is called Danny
No mention either of Cards Direct…which is growing rapidly & profitably whilst offering substantially cheaper cards
Substantial cheaper cards? You can buy 10 cards for a £1 in Card Factory (LON:CARD) . I looked at Cards Direct and their cards looked quite expensive. Next time l go into town, l will check the prices.
Cards Direct only have 61 stores, Card Factory (LON:CARD) have over 1,000. Not got the 2023 figures for Cards Direct, in 2022 the growth in revenue was about 10%.
Hi Rusty2 re Card Factory (LON:CARD)
I was relying on this write-up https://mallardresearch.substa...
they are certainly competitively priced..but perhaps I was overstating matters somewhat
Hi Paul, I struggle with Seeing Machines (LON:SEE) being tagged as Amber/Green which looks at odds with your colour coding criteria.
The company has made losses over successive years, has massively diluted holders, has run up substantial debts, is not expected to be in profit in FY24 and is a stockopedia "Sucker Stock" for a reason. The market they are in looks to be competitive, so I am not sure how strong a moat I perceive, nor how quickly it could be at risk of being competed away.
There is an interesting story behind it and I don't rule out that it could develop with some supportive tailwinds, but right now, I would label it Red based on your scale, but would accept Amber/Red. Anything with Green does not seem to fit the criteria as I read them...
Fair points, thanks 1James1n1 - maybe I should have gone AMBER with Seeing Machines (LON:SEE) ? I totally agree with you about its history, which has been poor. However, the key point is that legislation is now driving demand and we can see the faster growth coming through in today's update. Also it confirmed broker forecasts today, and re-confirmed cash breakeven next year, which should mean no further equity fundraises.
There's actually very little credible competition at the moment, and it's in pole position to win big, long-term contracts. Also note the big investment (via convertible loans) from a Canadian automotive parts maker a while back, which adds a lot of credibility I think.
So I think it's now sufficiently close to taking off, to justify taking a moderately positive stance on SEE. We have to look out for those tipping points where previously bad companies are beginning to deliver the goods, and SEE looks like it's at such a key positive tipping point. Hence I want to get that across with the colour-coding, that risk:reward has possibly turned positive now.
Thanks for your input, always good to discuss!
Regards, Paul.
Sorry, but no way is Seeing Machines (LON:SEE) a RED. Paul has got it right in my opinion with AMBER/GREEN. Note, FY24 ends next month for them. Forecasting BE in '25. And another bumper quarter on quarter incoming.
Summary says Paul done for Seeing Machines (LON:SEE), but I'm not seeing anything. Is it just me?
Sorry, I jumped the gun! I've done SEE now, in the % movers section. Sorry for any confusion!
Might have been different 45 minutes ago.
Has anyone got any thoughts on YouGov (LON:YOU) ? I haven't seen any discussion about it on here, but I may have missed it. It is down over 30% YTD, with most of the dip being after the half year results back in March, but it has continued to dip further since. From my understanding, the dip is due to "Statutory operating profit down by 53% to £9.5m (HY23: £20.4m), due to exceptional costs of £18.4m largely in relation to the CPS acquisition and related debt financing."
Looking at the Stock Report here, and with expected future growth, I am starting to think it may be an attractive buying opportunity. If it hits 2025 estimates, it will only be trading at a PE of 15.7.
"Has anyone got any thoughts on YouGov (LON:YOU) ? I haven't seen any discussion about it on here, but I may have missed it".
To find the answer go to the YouGov (LON:YOU) Stockreport and click on the 'Discussions' tab. You will find quite a number including a SCVR last October at the interims.
Interesting, this fell off my list somehow... so I haven't been running the chart.
Ive just had a quick refresh.... I know in Dec investors were upbeat about YouGov (LON:YOU) following the capital markets day revenue and margin targets being announced earlier in the year. Broadly these looked like a double of revenues over medium term at an improving or stable margin. If we take 5 years as medium term then this sounds interesting..... as you say, a sub 20x PE for 20% ish revenue growth....seems highly attractive. So for me, it went on the watch list. At the time I had some feedback that sellers such as Liontrust were depressing the price...and that would run its cause in time. The previous revenue targets had "broadly" been achieved, forgivable since the CAGR in revenue was 19%...which is impressive.
This year we have been updated twice.... Q1 was slow but Q2 was thought to be picking up strongly .... and then H1 nos were disappointing against this back drop. Underlying growth of 2% is hardly stellar. They have maintained full year guidance, hinging on H2 ....but interestingly updated medium term guidance to incl. the GFK panel business they acquired last year. This was producing revenue of €134m which is £115m yet £150m was added to the medium target. on my crude maths this is a downgrade in growth by 20% from 20% CAGR to 16%. 16 is still good mind but never the less.... We have two disappointing trading statements and the current year expectations hang on H2 and a lower medium target in the space of 6 months.....following an equity placing to raise funds for an acquisition.
This could all be a storm in a teacup.... but you can imagine "pod" managers have all dumped this as the story is moving right on them and that won't help them make their nos for the year. If you have some reason for believing the numbers will hold ( Elections should help) then could a be a good short term punt. Longer term I quite like the idea just a few question marks hanging over it for now.
YouGov (LON:YOU)
great comments RDHOWARTH - it kinda shows how fickle the markets can be ref that little bit of tweeking with regard to the numbers. Perhaps the cardinal sin here for growing companies is to over promise then fall flat on those predictions - for any business repeating 20% growth yoy for 5 years on the spin is a tough ask when you have reached semi maturity stage. i alwasy worry too with any marketing type business whether they will be prone to belive the hype that they probably tend to use to keep clients happy - as you say with an election this year is an slight drop off in projections a sign of worse to come if this should be a boom year ref their services? I have always been wary about believing the hype ref this company but if the stocky numbers are not over pimped up they certainly seem to be doing doing something right and i would say there looks like next to no hype in the shareprice nowadays - so perhaps then entry point now is fairly decent with the hype gone.
Thank you, RDHOWARTH. That is a really helpful and insightful write-up. I was hovering over the buy button this morning, and I have decided to take a small punt. Bought in at 852p.
MACFARLANE (MACF) A business that seems to have all the right credentials. The one exception declining capital turnover (sales per capital employed). How they increase sales or improve capital allocation is a big test. Bolt ons will not work forever.
Any thoughts what's driving recovery in Inspecs (LON:SPEC) over last couple of weeks - over 10% gain today - could just be a sign of general recovery throughout..?
I suspect re Inspecs (LON:SPEC) everyone who wanted to sell the share had already done so and so it had to go up. The 10% increase today is doubtless the result of a positive writeup in Small Company Sharewatch over the weekend.
Sentiment seems to be turning positive for UK equities after 2 years plus of nobody wants them. Perhaps it is the much anticipated fall in interest rates or a perception that the UK economy is not as bad as the doomsayers would have one believe, despite the best efforts of politicians of all hues.
I saw the recent article regarding Coutts strategy of significantly selling down its holding in UK shares. It reminded me of the quote by Peter Lynch which I am paraphrasing 'if one thinks like an institutional investors one invests like an institutional investor".
Time will tell if this is an inflexion point for UK shares; hopefully I have read the runes correctly, but as always no guarantees.
All the best
Sentiment seems to be turning positive for UK equities after 2 years plus of nobody wants them.
I'm up remarkably equal percentages across all geographies YTD. That's definitely an improvement from UK stocks on recent years but not an outperformance so far.
The UK indexes have been rising since end of October 23, even the AIM is up over 10%. That was the low point, in the last 2 years. My UK folios are outperforming my US ones this year.
Northern Bear (LON:NTBR) embarrassing trading update. Apparently it rains in the north of England (I hold).
Northern Bear (LON:NTBR) i thought the TU was refreshingly fair and honest.
the RNS didnt blame the rain. they specifically quoted 9 named storms and rainfall as being statistically higher than average. they seemed to want to recognise their teams for doing a good job despite these donditions to achieve profit within the range (as they say themselves at the lower end of range).
i read this all as very positive because, to me, it implies that the mgt team expect profits next year to be higher with normal weather.
Northern Bear (LON:NTBR) are small, but have consistent profits, are on low ratings (but micro cap), and have a recent policy to engage more with shareholders.
last year the mgt team geared up to buy back 20% of share count in a tender.
disc. its in my top 5 hldgs.
Northern Bear (LON:NTBR) One thing that is worth accounting for is that despite peoples perception of global warming simply being that the earth gets hotter, one of the biggest changes to be expected in a climate such as ours is increased rainfall and more severe storms. I would be wary of claims that we could return to "normal weather". I think it is more likely that this weather is here to stay and may even get worse.
Northern Bear (LON:NTBR) i agree re the climate conclusions.
my interpretation is that they were giving weather stats to explain why they hadn't beaten fcsts. this was an 'in-line' update. they view this year's weather as impacting them 'exceptionally' - they still hit fcst. i trust the mgt team that they expect less weather impacts in most years i.e. profits would be higher. if this year is the new norm i think this mgt team will adapt as they seem to have done through Covid, supply issues, interest rate hikes etc..
a few year ago the share price was falling , as investors assumed the bad weather then would impact profits. they issued a trading update saying (something like) 'we are aware of market fcsts. we are aware of weather. we are on track for forecasts so we haven't issued a profit warning. if, we are not going to hit forecasts we will issue a TU. '
anyways, i hold and like the company as steady with good yield.
Northern Bear (LON:NTBR)
. I think it is more likely that this weather is here to stay and may even get worse.
any man made climate change normally** takes decades to show up material changes - so imho this statement is pretty much complete nonsense from a statistical viewpoint - specifically with regard to rain in newcastle. Yes change over time but no way is the rainfall in newcastle going to reach a sudden tipping point where it jumps 150% one year and stays at that higher level on average going forward - thats pure nonsense stuff .
being honest rainfall is the lesser of the evils where ntbr work - up here ice and snow is what tends to bring work to a complete halt for extended periods more than rain (albeit they do have a roofing division where rain may be more of an issue). In that regard its a matter of fact that due to climate change we get far less snow and ice up here than we used to - as winters are much less likely to have extended periods of snow and ice compared to averages 40 years ago - its win win win ref climate change imho for ntbr with less severse winters than back in the day.
ref todays update it is what it is - and results being broadly in line with some bi tching about the rain is fine to me.
** - we may be in the crapola if the Gulf steam stops or materially slows at some time in the near future.
Yes - you are correct that on a year by year basis it is unlikely to be consistently replicated. I should have been more clear that I was talking about much longer term timelines. From short-mid term investing perspective it would probably not matter and could provide opportunity. However, longer term we can expect more rain and more extreme weather rather than the inverse. Good point on the mild winters, there must be some companies that will benefit from that longer term.
Northern Bear (LON:NTBR)
i think specifically with regard to Northern Bear territory i would tend to somewhat disagree - imho its clear that up here in the Newcastle area the warming of the climate means there is likely to be less extreme cold snaps and most of the issues that delay construction work for extended periods are related to that kind of weather event imho - i see zero suggestion that Newcastle will become a hotbed of climate related extreme weather events and imho extra rain matched with less extreme cold snaps is probably an overall benefit or probably neutral at worst. Happy to follow any evidence that suggests otherwise though - what is clear to me is that the generic advise that everywhere will have it worse is clearly untrue - for some areas and specifically ones that start with poorer weather to staRT WITH(and longer winters) - climate warming can easily be a win win situation overall as one gets less of then harshest effects of winter which more than compensates for a bit extra rain , that can be so even when global man made warming is an issue. On the ground here up North it is noticeable how many less "really bad days" we tend to have in winter now compared to 40 years ago - in summary ntbr are hopefully overall beneficiary here.
Interesting NE viewpoint on the weather. Here in the Pennines by contrast, winters have been MUCH worse of late - not due to temperatures, which have moderated as you say, but on account of the biblical levels of rain these last few years. You mention that a little bit of rain is no big deal, and that makes sense assessing a relatively dry region, which is benefitting from a low base level of precipitation relative to the west and an only moderate absolute increase in rainfall amounts. But in the already very damp NW, a lot more rain is really creating a lot of difficulties.
I did try living in Manchester for 3 years when i was a student - even back then it always seemed to be overcast or raining or both - give me a bit of sunlight and less chance of rain any day of the week and i am happy even if the temperature may be down a few degrees on what you get in the west/mountainy regions.
The east of the country certainly has it much better. My son moved to Suffolk last year and he says it barely rained there at all this winter. Probably an underestimate but, coming from the north, you can imagine how much drier it felt. On the other hand, we get all the best scenery!! Yes, Northumberland is lovely - and gloriously empty - but it's not possible to outdo the Lakes or N Wales, even the Dales, until you head north of the Trossachs - and then it gets even wetter!
I'm in Suffolk, near the coast. It certainly did rain last winter, February was over double the average. March was a bit below, April about average. Over the last 6 months rain is well above average. 2022 was well below average.
Just from personal experience (I live in the NorthWest) the rain has been relentless and has definitely impacted my appetite for social activities. Things are improving now and pubs round here are absolutely packed when the sun is out.
Conversely we've had a another bank holiday wash out, and whilst on a visit to the Lakes yesterday it was noticeable how quite the pubs are for a bank holiday Monday. One I'd expect to be packed was empty at lunchtime.
Had a chat with a landlord and apparently people headed home early due to the weather as they'd had loads of cancellations for lunch.
So in summary it seems reasonable to see a decline in trade if people are hiding in front of TV rather than getting drenched running to the pub door.
My Out of Town M&S was very busy during the downpour of yesterday. Also their Summer ranges of clothes seemed to me (admittedly I am no fashionista) bright and alluring
Yet other parts of the country had good weather, in the south east and East Anglia, it was generally fine. Friday we had some rain but Saturday was lovely sunny day, Sunday bit more cloud and Monday dry but more cloudy. The northwest is the wettest part of England. Had a week there once, it rained all week, also had some good weather at other times.
Graham notes that the largest shareholder is now a UK based individual.
Worth checking out who it is and doing a quick google on the name.
Call me old fashioned, but that would make it a no-deal for me.
Northern Bear (LON:NTBR) "Worth checking out who it is and doing a quick google on the name.
Call me old fashioned, but that would make it a no-deal for me."
I think that's all nonce-sence.
Northern Bear (LON:NTBR) good point for readers to be aware of. I've considered at length previously and discussed with mgt before i started buying. its an intetesting aspect - because the company is small other shareholders are notifiable whilst any same shareholder could be in a larger PLC and we wouldnt know. Prob not for discussion here so DM me if intetested to share further thoughts.
My morning smallcap tweet: SIPP-a-dee do dah
CAP-XX (LON:CPX) Revolution Bars (LON:RBG) Northern Bear (LON:NTBR) Zotefoams (LON:ZTF) AdvancedAdvT (LON:ADVT) Frontier Developments (LON:FDEV) MTI Wireless Edge (LON:MWE) Aferian (LON:AFRN) Mincon (LON:MCON) Totally (LON:TLY) Graft Polymer (UK) (LON:GPL) Solid State (LON:SOLI), Seeing Machines (LON:SEE), Macfarlane (LON:MACF)
◄CAP-XX (CPX)► YTD bookings up 14%. B/E target remains 2026. [SP=0.08 Cap=2m]
◄Revolution Bars (RBG)► GM to approve fundraise delayed to "enable the Board to more fully update shareholders with respect to the progress of the FSP , M&A process and any other proposals". [SP=1.6 Cap=7m]
◄Northern Bear (NTBR)► guides FY-Mar rev broadly in line but adj op profit at the lower end of expectations. Blames heavy rain in North East. [SP=60.25 Cap=8m]. I hold.
◄Zotefoams (ZTF)► alliance with China's Suzhou Shincell New Materials: agreements on technology licensing from Shincell to Zotefoams, development and market co-operation, and regional product distribution agreements. ZTF will pay c.£9m over 5 years. [SP=432 Cap=211m]
◄AdvancedAdvT (ADVT)► buys Celaton and AI driven document management business of £5m net in a related-party transaction. Also vague trading update - "revenue and adjusted EBITDA continued to perform well". [SP=135.28 Cap=180m]. I hold.
◄Frontier Developments (FDEV)► guides FY-May rev £85m+. Adj EBITDA -£5m or smaller, better than previously guided. Cites "excellent reception to Planet Zoo's arrival on console and a good ongoing performance from our other CMS titles". [SP=265 Cap=105m]
◄MTI Wireless Edge (MWE)► wins $3m of orders for delivery this FY. [SP=41 Cap=37m]
◄Aferian (AFRN)► extends the maturity dates of its senior loan facilities and its shareholder loan. [SP=7.25 Cap=8m]
◄Mincon (MCON)► Q1-Mar mixed. No orders for large construction projects. "Some contraction in construction activity in North America and Europe and a slight contraction in our mining & geothermal/waterwell revenue." However order books began to recover, positive about the outlook for the remainder of FY. [SP=46.6 Cap=98m]
◄Totally (TLY)► guides FY-Mar rev £106m down 22% and EBITDA c. £2.3m. Cost cuts. Outlook - market continues to be difficult. [SP=5.25 Cap=10m]
◄Graft Polymer (GPL)► gets patent for dual hydrogel multi-crosslinking haemostatic composition. Forgets to say what territory the patent covers. [SP=0.16 Cap=m]
◄Solid State (SOLI)► wins $5.1m US order for delivery from Q2 calendar 2024 to 2025. [SP=1378 Cap=156m]. I hold.
In line: SEE, MACF
Angle (LON:AGL) I hold
Paul I didn’t pick up your remarks in Friday’s SCVR until late so decided to post a response this morning.
There is no disputing that many small stocks, especially medical related, burn cash in early stages and are continually seen as ‘jam tomorrow’. However, I believe you are behind the curve with AGL which I believe is very near to break even.
To pick up on some points you make and add some further information:
“An eye-catching RNS, saying it’s done a deal with giant AstraZeneca to develop a prostate cancer detection system for use in studies. Trouble is, the deal is only worth £550k to Angle, and is long-term in nature”
The assay in question is not a detection system. It will take a few months effort to develop, is based on work already done, and will facilitate the analysis of already captured Circulating Tumour Cells. Re ‘long term’, the pharma approach will involve longitudinal studies ie employ repeated measures to follow particular individuals over prolonged periods of time. Each study will generate income from day 1. An interview with the CEO can be seen at https://www.proactiveinvestors...and gives details of the assay and potential financial benefits.
You didn’t mention this is the second contract with AstraZeneca announced within a week, the first relating to Ovarian cancer and which should be available for use sooner. Two other commercial contracts have been signed recently, one with major Japanese pharma Eisai Inc . Talks with other large pharmas are ongoing.
It is worth noting that Angle have stressed “The new androgen receptor assay will also be an important addition to the menu of assays we can offer other customers." ie Angle retain the rights.
“Cash was £22.2m at 30/6/2023, and it said the cash runway lasts until Q1 2025, despite cost-cutting”
Not despite but because of pragmatic cost cutting – including closing the US lab for now and doing the work at Guilford. The company seem well aware of shareholder dilution issues and are trying to avoid any more. It is not a done deal that a fundraise will be required but results are due out this month.
“Why get involved?” DYOR fully – it’s an individual’s decision.
“ It’s a pure punt at the moment” Your opinion, but at this point in time very far from mine.
“Stuff like this should not be listed on the stock market.” Totally disagree. It is the investor’s decision to put up cash – and that includes both private and professional fund managers. I’d rather have the option to support a ground breaking UK company than many of the other companies listed on AIM.
There has also been progress on other fronts but it’s not for me to highlight here. There is a discussion thread under AGL mentioning significant events post FDA approval.
Please advise where to find the discussion thread.
https://www.stockopedia.com/co...
Angle (LON:AGL) is not on my watchlist as it is outside my strategy sweep, so i know nothing about the company, but i thought this was a very fair post.
Paul and teams analysis is excellent in its efficiency and content. for me, like the market it is a percentage game. Paul and team have applied the same process and come up with a 'dismiss' conclusion. A subscriber has a totally opposite view but has posted in a clear, respectful and structured way.
i have no idea what will happen the shares / company, but its a delight to get information from totally opposite view points, which allows me to make my choices and DYOR.
thanks all.
Angle (LON:AGL) - and most importantly meant to add, that if Angle (LON:AGL) go on to be successful and the share price multi bags, that in no way means that Paul had bad analysis, or was 'wrong'.
IMO he is applying a very consistent and high quality processs that on average delivers great results. of course some will slip through the net, or end up being losers.
but what i want as a subscriber is a consistent process to kick start any thinking and quality reader challenge if they have more detail, presented not in a i'm right, you're wrong, but in a team concept way.
totally agree ! do like your commentary Paul , but not sure you got AGL correct
Angle (LON:AGL) clearly dividing opinion. I put a note on the share 3 years ago...April 21. It appeared to be flying at the time and the sp was at 103p. Where is it now? Big rise to 21p today.
Maybe this time it is different . Stocko stats still show big losses forecast. Jim may well be right and these new contracts are the dawn of the new era. He knows this business inside out. Good luck any who venture in. But it appears more of a gamble than an investment imo.
I think I should emphasise that I'm just reporting the facts & figures, and a view based on those things, plus of course the awful financial track record at Angle (LON:AGL) . It's been listed 20 years, with the story being basically the same over all that time. Bursts of speculative excitement come and go, as you can see -
It's never made a profit, and burns through prodigious amounts of cash each year. The cash runway is now about a year (Q2 2025) - starting to get close to danger territory where it will have to ask for more cash again. Recent experience shows that companies like this, which run out of cash, are usually treated brutally by the providers of the next wave of cash. This is why blue sky projects are better off having long-term, committed funding from venture capital or private equity. Being at the mercy of public markets, and their wild mood swings, is a terrible structure for this type of company, in my view.
All I'm doing is pointing out those realities & risks. If you think it might suddenly turn into a fantastic company, good luck to you, and I hope you're right. But that's not what our reports are trying to do. We just report the facts from a value/GARP investing perspective, then you can assess the blue sky potential separately, and decide whatever you like, it's your money after all!
But I'm definitely not going to stop pointing out unpalatable truths, and readers can then weigh up your own personal view, and how you see risk:reward.
Paul.
I'm glad you followed up with this very reasoned response because it made me check myself. I had twitchy buyers fingers and started seeing diamonds and pound notes! Of course it's down 10.5% the next day. You have to be so careful with volatile stocks like Angle (LON:AGL) that look like they could be a big turnaround story.