Small Cap Value Report (Tue 7 Nov 2023) - MTRO, LUCE

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Metro Bank Holdings (LON:MTRO) - unchanged at 42.45p (£73m) - Q3 Trading Update - Graham - AMBER
This challenger bank reports that deposit outflows have returned to “more normal ranges” following the announcement of its proposed fundraising package. I take the opportunity to review this package, concluding that it has treated equity investors well in the circumstances.
Luceco (LON:LUCE) - down 4% at 104.7p (£168m) - Q3 Trading Update - Graham - AMBER/GREEN
This electrical and lighting group confirms that trading is in line: expectations have already been upgraded twice in the current year. I’m more lukewarm on this than my co-writers as I find the sector too volatile, but I can also see the attractive features of this share.
Graham's Section
Metro Bank Holdings (LON:MTRO)
- Share price: 42.45p (unch.)
- Market cap: £73m
Continuing the coverage of this one from October, when the company admitted that it was considering a range of options including equity issuance, debt issuance, and asset sales.
Shortly afterwards, it announced a capital package worth £325m: £150m of new equity and £175m of risky debt (“MREL”) paying 12%. On top of that, it would refinance £600m of existing debt.
As far as the equity was concerned, £150m was to be raised at 30p per share (the share price was 37p on the day the company responded to press speculation).
The equity raise hasn’t gone through yet, so the share count remains at 172 million.
When it happens, it will result in the creation of an additional 500 million shares. That's a dilution of about 300%.
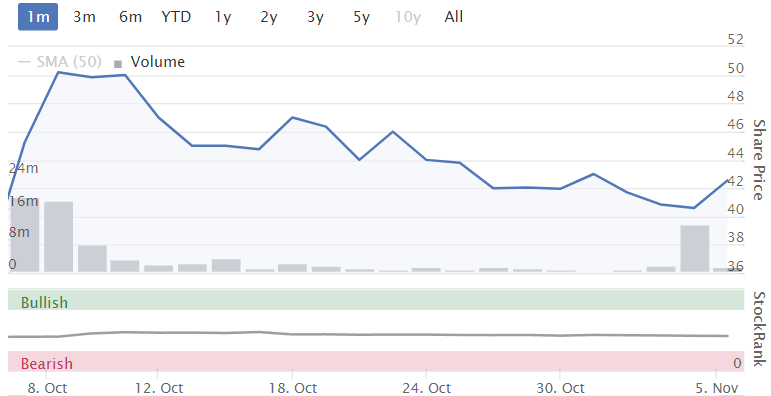
However, the share price in early October was already pricing in lots of bad news for the existing equity, and the proposed 30p fundraising price is not nearly as bad as it might have been.
Indeed, the share price is currently higher than it was when I covered the company in early October, before the fundraising was announced.
All of which brings us up to speed for today’s Q3 trading update.
The table of new data is as follows:
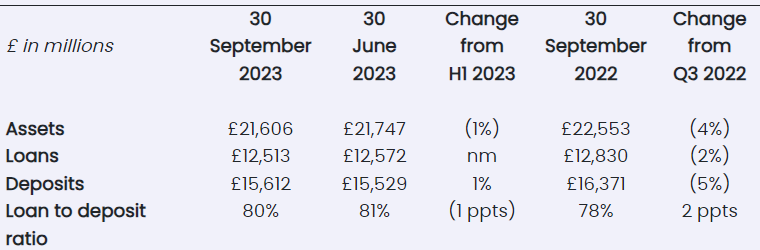
Over the three months to September 2023, we have a slight reduction in the loan to deposit ratio, i.e. this metric becomes slightly safer.
Deposits rose slightly over the three months. As speculation around the bank’s financial health mounted, outflows then rose, but:
As announced on 8 October, post quarter end Metro Bank noted an increase in deposit outflow rates in advance of the announcement of the capital package. Since the announcement, daily flows have returned to more normal ranges.
Ok, so perhaps this doesn’t mean “completely normal”, but at least it’s “more normal”.
We also learn in today’s update that Q3 saw “continued momentum in Personal and Business Current Account growth and customer acquisition as well as a modest statutory profit after tax.”
Graham’s view
There was a divergence of opinion here last time we looked at this one - I was the divergent opinion which didn’t want to put a “Red” rating on it, which was an unusual stance to take!
While acknowledging the risk of severe dilution for shareholders, I thought that the shares were already doing a good job of pricing this in: June 2023 net tangible assets per share were £4.42, ten times the share price! It was either going to zero or it was going somewhere else - and the “somewhere else” could be significantly higher than the current share price!
I also observed that the bank’s capital ratios - CET1 and Total Capital - were well above the minimum requirements, and it claimed to be profitable.
We now have the details of the planned fundraising. It doesn’t treat the existing equity too badly, in my view, especially considering that Tier 2 bondholders are taking a haircut as part of the deal.
Yes, we have dilution of 300% but based on the interim figures the shares would still be trading at a big discount to tangible book value, even after this fundraising. Of course it remains to be seen what level of impairments this balance sheet might ultimately inflict on investors.
In conclusion, I think it’s reasonable for me to maintain my Amber stance on this one. I have little temptation to invest in the stock myself, because there are many other financial stocks I prefer. And this one could still turn out to be a zero. But the axe hasn’t fallen yet, and there is still no guarantee that it will.
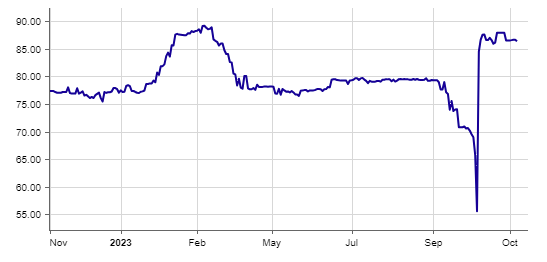
The company’s 2025 bond is currently trading at 86p, up from a low of 57p:
Luceco (LON:LUCE)
- Share price: 104.7p (-4%)
- Market cap: £168m
Luceco plc ("Luceco" or "the Group"), the supplier of wiring accessories, EV chargers, LED lighting, and portable power products, is pleased to provide the following update on trading for the three months ended 30 September 2023 ("Q3 2023").
This update is in line with expectations.
Key points:
Q3 revenues up 8.3% year-on-year.
Adj. operating margin just below 12% in Q3, vs. 10.7% in H1.
Net debt falls from £43m to £30.5m during Q3 (seems to be because of a working capital unwind).
Net debt ratio of 0.9x, below target range 1-2x.
CEO comment:
Whilst demand from energy saving professional projects continues its positive path; we are seeing some impact of reduced demand in certain of our end markets as the UK consumer continues to experience economic headwinds. Luceco's strong cash generation in the quarter was particularly encouraging, and with our low levels of net debt, the Group is well placed to invest in growth and enhance earnings in line with strategic priorities.
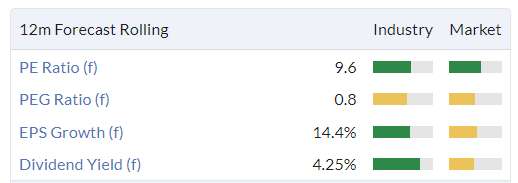
Estimates: with thanks to Research Tree, I see that Liberum has left its EPS estimates unchanged for this year and next (but it notes that these estimates have already been upgraded twice in 2023). The EPS estimate for the current year is 10.4p, rising to 11.7p next year. So the current PER is about 10x.
Liberum says “the strength of the balance should enable a return to value-adding M&A”.
Graham’s view
Roland covered Luceco’s interim results in lots of detail in September.
The last few years have been a rollercoaster:
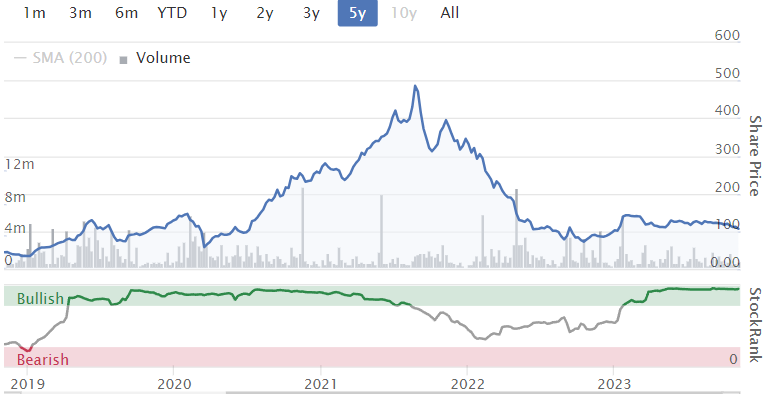
In line with Roland’s view (and Paul’s view from July), I am warm or lukewarm on Luceco shares.
Profits are volatile but the company does have a track record of consistently generating at least some profits and dividends have been paid since 2019 (albeit with a dividend cut in 2022).
Quality is above-average according to the ROCE figures, and I note that there is plenty of alignment on the Board of Directors. The Chairman leads an investment company that is Luceco’s largest shareholder (22%), also apparently owning 6% in his own name. The CEO owns 18%.
However, electrical and lighting products aren’t a sector where I feel at home - companies in this space are vulnerable to spikes in demand, and I’m not sure what their sustainable competitive advantages might be.
I’m happy to defer to my co-writers and leave the stance here as Amber/Green. Valuation does appear to be reasonable, with a modest debt load relative to profitability and with post-Covid trading having normalised. So the outlook for shareholders should hopefully be quite good!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
was looking for the link to Pauls results spreadsheet but can't seem to find it. Anyone share please
https://docs.google.com/spread...
Paul - Noticed you weren't around today. Very much hope all is well with you and your family and you were just taking a much deserved day of rest. It is on the days where you aren't around that you really notice how much content you plough through each and every day to keep us readers interested and informed! Cheers. Ben
Seraphim Space Investment Trust (LON:SSIT) Space trust hits new lows after Sky report they are looking at setting up a side car fund to raise funds due to the large discount. Interesting fund/sector but I could never get the conviction in it to invest.
it was gus 1065
Google finds this sort of thing quite easily if you include site:stockopedia.com in the search
https://www.stockopedia.com/co...
DWit199 Thank you for a very handy tip on how to get Google to search any website for anything!
Anybody here interested in commenting on Anglo Asian Mining (LON:AAZ) . I know miners are not mentioned here often but nice move on the news that an agreement has been made "to implement certain enhancements to its operations and procedures." and "the Company is now free to restart all its operations. ......mining will recommence immediately. The Company's heap leach operations continued to operate throughout the recent partial shutdown, but without addition of ore. ....copper concentrate from SART, will return to its former levels."
"The Company maintains its Full Year 2023 production guidance of 30,000 to 34,000 gold equivalent ounces ("GEOs"), as announced in its 2023 Interim Results."
For good or for bad I have held Anglo Asian since September 2016 (initial buy at 62p) and buying on and off since then (so I am underwater) and have tried to act like an owner rather than a trader. So I did not follow Ed's advice in "A practical guide to keeping losses small" and sell or buy more (I don't have any spare cash and anyway it is my largest holding).
Three things stopped me selling:
I think in the current market it is all too easy to get shaken out of companies because it is too hard looking at the drawdowns.
Anyway I was glad this morning that I was still in Anglo, when my teenage son WhatsApped me to ask what was going on with Anglo Asian (he owns a few). Yes I realy don't look!
Regards
Michael
Hi Michael, I think you make a great point on market news being exemplified in the share price, it certainly provides some opportunities when there are overreactions. Other than the low volumes causing more defined moves, In the current market I believe a lot of investors are ready for a bounce in the next 6-12 months and want to position themselves accordingly. They don't want to have money tied up in something where they see that short/medium term bounce being limited by near-term company performance. For those holding cash, the shares that outperform in the near term or show improving trends will be the ones that investors will be keen to shift money into once that bounce happens.
Hi Michael, I see that my spreadsheet recording dividends paid noted that there would not be any Anglo Asian interim dividend paid this autumn. Hopefully this December's Annual Report will tell me a Final will be paid in June 2024, there is a lot going on in the company so a hiccup is excusable. I've held and bought more shares in Anglo Asian Mining (LON:AAZ) over the last 3 1/2 years and like you am underwater. I did buy more during the recent dip and should the share price recover to what it stood at 7 months ago I'll be a happy PI.
Michael, for me AAZ is a less than one percent holding but like you I have held from initial purchase at a much higher price than today because I have ceased monitoring my shares as regularly as I used to. As I have a SIPP portfolio that has too many small cap shares that I have retained I have not performed well in the last few years against the FTSE index being down a less than 1% including dividends over the last year. Like you I have retained most of my Tremor hoping for better days despite Paul’s justifiable pessimism.
As I have cash I wonder whether this is now the time to top up my holding in AAZ.
Was just reading an interesting piece from Bruce Packard on IPO stats in the last couple of years. Thought I'd take a look at this years crop of wonderful businesses.
I hardly ever read admission documents but REGTECH OPEN PROJECT (LON:RTOP) was the worst I'd ever seen. Utter junk, red flags everywhere. I commented on it here and forgot about it.
Somehow this was pumped up to 180m market cap? days after the float, on nothing.. before collapsing 97% from peak. All this in just over 2 months.
Hi Wolf, An interesting table that you have presented here. Can you explain what happened with Admiral Acquisition? To my untrained eye it seems like two differents floats at different prices on the same day. Thanks.
No idea c038, sorry
Maybe just shorting every IPO is the way to riches. Could have made a killing on CAB Payments alone.
Hi ochstui, I'd say any largish new company which isn't a penny share is well worth looking at as a potential short. Sometimes get a decent rally after they float, short term at least, but after that the laws of gravity tend to kick in. Risk of a takeover is almost zero also.
I'd actually marked down the lock-in dates on Cab Payments Holdings (LON:CABP) which I was looking to maybe short a few weeks before. Unfortunately it's already fallen 80% which rather screwed up that plan.
Interesting Q3 trading statement from Persimmon (LON:PSN) today, signs of a recent recovery in buying activity in the 5 weeks since start of October. Sales per outlet now a respectable 0.59. Forecast house completions for 2023 have risen from 8000-9000 at Q1, to the top end of this range at the H1 and now forecast to be 9,500. Signs of green shoots at last? All housebuilder shares have benefitted today. I was also encouraged by the Bellway (LON:BWY) update on 17 October which said on house completions:
"The Board notes however, that a wider than usual range of outcomes are possible, and the final volume outturn will depend on the trajectory of mortgage interest rates and the strength of demand in the autumn and spring selling seasons".
As interest rates appear to be trending downwards this is adding more to the upside than the downside in my view.
My current favourite in this space is not a housebuilder as such but a contractor - Tamdown, listed as Nexus Infrastructure (LON:NEXS) . After a profit warning on 3 October ,the market cap is down to £7.2m but they had £14.6m cash at the year end. (30 Sept). They have an order book of £46m and expect further contracts imminently based on "live conversations". with customers This is a well run company with a good reputation with customers operating in the south east of the country. The current low market cap gives a risk of it being taken private of course, but it has only recently sold various divisions (hence the cash pile) and the whole group didn't come to the market until I think 2018. Has very little visibility it appears, and may recover nicely if housing market improves.
Could be a special situation if they decide to gear the business with some bank debt and return cash to investors. This was in fact the plan at the time of the sale of the two divisions but I suppose the uncertainty around the housing market has delayed that. Could be an interesting one!
The parameters you set out in the 12 m forecast are favourable net debt is falling and the investor is being paid to wait with a reasonable dividend and the directors have substantial investment in the Company.in 2021 the share price reached almost 500 p.i reckon the company is a buy as its outlook is improving.
Err - which company are you talking about??
Err - which company are you talking about??
I thought it was Luceco (LON:LUCE)
Hi John.
I see this is your first post ...so welcome. If you type the "at" sign a wee box will appear which enables you to search for the security you are are talkin about.
Cheers
Alastair
You need to type @ to get the box to appear.
Luceco (LON:LUCE). I would take the 500 high with a pinch of salt. It had a tremendous bounce after the Covid drop and was further buoyed by an abnormal amount of lockdown house improvements. I have held since 2019 and my feeling at the was that anything above about 380 as pure froth. That said it is well run with good management and I think the notion that c.120 is “about right” is nonsense. It’s margins have been hit in recent times, but largely as a result of a combination of external factors (supply chain costs) and destocking, so should be temporary. Assuming margins are rebuilt, I would not be surprised to see fairly brisk retracing to about 250 as soon as the current buying paralysis abates.
Am I the only one finding it SO frustrating that it seems to be only this excellent Small Company thread bulletin board where quality posts, comment and articles get the recognition they deserve?
e.g already today there are some excellent posts on Private Equity Investment Trusts that I hold and they’ve already got a lot of deserved recommendations. Yet these are not the intended focus of this bb.
Charles Mitchell started a new Investment Trust thread recently. Those PE posts here today would me more appropriate there. But! Had they been posted there instead there would have been far fewer readers, and probably little recognition and quite likely, no replies. This seems to be the ONLY Stockopedia bb that gets widely read.
it.
There are great high quality articles posted by both subscribers and Stockopedia staff where the same applies. E.g from Edmund Shing, Roland Head, including on dividend stocks todsy, and Megan Boxall. Again had they been written here, there would have been SO much more quality follow up and FAR higher readership.
Don’t know whether anything can be done about this?
It must also be a bit frustrating for Paul and Graham when they slave away covering several updating small Companies in considerable detail, then to find very little comment on them some days.
How much better if instead those excellent (but off topic posts for this bb) could appear on appropriate well read and popular mthreads away from here.
Agreed. It's habit too. I would contribute to that, but I can't even find it. Probably half our family holdings are ITs. I think things with a very low possibility of going bust are an important balance to the excellent SCVR. Where is it, please?
https://www.stockopedia.com/co...
I also agree.
And if anyone would like to start a regular thread on small cap miners, I would be thrilled!
I completely echo this point. I have recently been searching Stockopedia for information on Investment trusts. The search function only seems to yield a few specific trusts plus some posts from 10 years or so ago!
There are links to learning pages (ie financials) but many of the links do not yield anything as the page seems to have been suppressed. Not sure if it is my ignorance of the site, but this thread suggests otherwise.
How should we be using the site for best results?
Thanks to raggedtp for the link.
I am a bit of an investment trust fan BusselsLad - try the AiC website. A good start is searching the golden oldies and dividend hero's - 75% of the best trusts are in these two lists. Always best to go for larger trusts, other than for small caps, where Aberforth, Harwood and Montanaro are good.
I would agree - certainly there needs to be a more active discussion on Investment Trusts and perhaps gilts and other investments as well in the current climate.
A number of efforts have been made in the past to give better structure to the board with company specific threads. These seem to be crowded out and then comments get lumped together on SCVR.
As stated, the search function on the board needs some improvement.
SCVR involves a lot of work. It might have fewer reads than historically but I think that this might be private investors losing interest in a downturn.
The Stocko page layout does not help. It uses a lot of screen 'real estate' to display discussion threads and then compounds the problem by not grouping related threads into subject categories, through which we could then take a deeper dive into topics of interest. As a result we get immediate sight of only a relatively small number of recently active threads.
Given that the search facility is also very limited, the Stocko community conversation collapses down in practice to SCVR with other threads mostly fading quickly out of use and out of mind.
It's a pity. There is a lot already available here (hidden somewhere) which nobody can benefit from ... and there could be so much more generated if the community forum design was given more careful attention.
For example, there was an excellent earlier group of threads focused on investment trusts curated as best he could by GusXXX (I think) ... a very knowledgeable and affable poster, no longer active on this forum, sadly. It contained a lot of useful information and interesting discussion. I've searched for it a couple of times but can't find any trace. It's lost wisdom and a lost opportunity to learn.
The Stocko page layout does not help. It uses a lot of screen 'real estate' to display discussion threads and then compounds the problem by not grouping related threads into subject categories, through which we could then take a deeper dive into topics of interest. As a result we get immediate sight of only a relatively small number of recently active threads.
Absolutely, the one third of the SCVR page taken up by 'Securities Mentioned' is in my very humble opinion a complete waste of space, if you are/were interested in one of the Stocks in the SCVR you would just look it up anyway. This space could/should be where the rest of the 'Discussion All Posts' is displayed thus jogging subscribers memory that the SCVR is not the only thread or discussion available.
I keep waiting for the Product team at Stocko to prioritise Community improvements, as well as improvements to User Generated Content.
So far, they've just been focused on just the "core" data. Which is the data on stocks and shares. Fair enough, that is what we sign up for Stocko for. But this does not give a competitive moat; plenty of other websites/services that also do Stock Data. And this data is not unique (apart from StockRank).
However, I bet most of us don't switch to competing services because of the Community, SCVR, and user generated content we can find here. This "data" is arguably more valuable to Stocko - you can't find it elsewhere, ergo subscribers will be sticky and pay to get access.
I just wish the Product Management team at Stocko realises that if they invest in the Community data and UGC data aspects of Stocko, they could really boost retention rates.
Completely agree. The quality of discussion here is why I read every day, but it is near impossible to search for a specific stock for commentary back through history.
Thanks for the mention Ken. As it happens have been researching the PE Trust sector prior to writing a blog. Couple of interesting situations-like Dunedin Enterprise Investment Trust (LON:DNE) . Some to avoid as well in my opinion. Hope to finish it by Friday, work permitting.
ken Mitchell, Sounds an excellent Idea.
Hipgnosis Songs Fund (LON:SONG) See the ex chairman of the taken over music fund Round Hill has been appointed Chairman of Song. I held RHM but just watch Song as had little faith in the board. Maybe now we will see some more realistic valuations and communication from SONG. Not rushing to buy at the moment as suspect there could be a downward re-valuation of the music portfolio.
Interesting trading statement from Bank of Georgia (LON:BGEO) - looks like regulator published the 9m results of all regulated banks in Georgia so company had to update.
Given direction of travel seems to me like they are trading ahead of expectations. Stocko has avg consensus of 1240gel profit but looks to me like group profit should be closer to 1450gel
Anyway a PER of 3, a dividend moving towards 10%, strong capital and liquidity buffers and own funds exceeding market cap. This still looks very cheap to me.
Not a small cap, but remarkable price action in RS (LON:RS1) this morning. As a holder I read this morning’s TU with a deepening sense of trepidation. I expected a 20%+ fall at 8am but decided that selling at the pandemic lows would not do justice to the progress the business has made since its digital transformation. I was genuinely conflicted as I decided recently to up my game on profit warnings and did spend some time debating whether to be more trenchant with the holding.
My expectations were fully met when it opened 22% down. What a pleasant surprise to see a steady rebound to only -5% just 30 mins from open. Whether it holds this level who knows, but I wonder if this action tells us something about the market?
I was very disappointed with the update and I found the lack of guidance challenging. I also should have been more alive to the increased leverage following the acquisitions. I likewise feared the worst and considered selling at the open… fortunately I waited for some stability to return (who knows if that was the right call). Good luck holders
RS (LON:RS1) at times like these it pays to look at the record of revenue and earnings growth since the business went digital in the middle of the last decade. Throw in low levels of debt, good cash generation, a valuation 30% below the norm and a well covered dividend in the upper range for quality industrials. For sure, Diploma it is not, but nor is it valued anything like. When the macro improves, the probability of an upturn in fortunes - with both profits and valuation multiple expansion - is reasonably high. In the mean time, let’s be relieved that many seem to see it the same way and, if unconvinced, you have the option to sell at only a small debit compared to last night.
I'm not a holder, but I have used their site in the past as a customer and I was satisfied with their experience. They have great returns on capital. The company says the net debt is now £502m, quite an increase! Analyst forecast net profits of ~£250m for2024, so I don't think we have anything to worry about.
"Industrial revenue has been robust despite the challenging macro and geopolitical environment but cyclical weakness in electronics has been exasperated by customer de-stocking."
My own view is that, OK, there some macro and stuff to worry about, but things should get better. The company has a high Stocko Quality score and a low PE of 12. If I held these shares, I wouldn't sell. It's still on my watchlist jostling for position in ISA top-up season.
Just my own point of view, of course.
So, shares were down 5% in early trading, currently up 2.7%. I hope nobody got fleeced.
So, shares were down 5% in early trading, currently up 2.7%. I hope nobody got fleeced.
RS (LON:RS1) Shares actually opened more than 20% down. So hasty sellers got badly whipped.
CEO statement at RS (LON:RS1) made me laugh this morning. Drop in sales is apparently "exasperated by cyclical destocking". Very good. Unlike the team who wrote and checked the release! Could I suggest exaggerated might be more appropriate or is the CEO really that difficult to deal with?
RS (LON:RS1)
I think the original word wanted was exacerbated. Sounds a bit more like exasperated. Possibly the CEO dictated that and never bothered to check the result. Possibly to an AI dictation machine. I have seen some hilarious subtitles on TV that have been done that way. Also once had a frustrating phone call to some British Gas automaton that repeatedly told me it did not understand. In desperation the final time it asked me what I wanted I said quite clearly "speak to human being" but it did not understand that either.
SDI (LON:SDI) And as if by magic after my comments yesterday, the CEO buys some shares
RNS to say Mike Creedon has bought 42,606 shares at 116p average price which is £50k total: a reasonable amount (but fairly insignificant after his substantial sales)
The shares are currently shown slightly up
4imprint (LON:FOUR) has upgraded expectations for this year in spite of trading challenges = opportunity to increase market share.
4imprint (LON:FOUR) has upgraded expectations for this year in spite of trading challenges = opportunity to increase market share.
I took this as a lowering of expectations for next year
“In recent weeks we have seen some evidence of softening demand patterns typical of a more cautious macro-economic environment”
I’d expect to see forecasts reduced from the current 10% growth in FY24 as the year progresses. Great company and I regret selling a while back. I would buy again on weakness.
UPDATE: I see shares have reversed into a 7% fall. Looks like I'm not the only one who sees a profit downgrade in the crystal ball. I'd be a buyer on that likely weakness however. These guys are top operators. Just need to identify a target price. I think 4250 might be fair value if a slowdown eventuates next year and I'd find them pretty attractive there even at a higher PER when the negative operating leverage kicks in.
Hi BnB,
I was reading the RNS whilst getting ready for the school run. I saw the reference to updating full year guidance and reference to PBT being revised up to $130m vs previously $125m as upgrading expectations.
Agreed the share price has moved down notably so far which I guess is due to:
Their reference to seeing a softening in the market of a more cautions macro-economic environment, which they spin into opportunity to increase market share.
As a long term holder I know the share price can be quite volatile with Stockopedia confirming a Beta of 1.571. Maybe some are scared by the macro picture or profit taking?
The business (quoting North America) is still growing although at a lower clip than last year. With a forecast recession then it's a question of can some growth be maintained or the effects of a down market mitigated.
I think 4imprint (LON:FOUR) is well managed and still a good long term investment for me. The short term (1-2 year) outlook is not so positive. This maybe a top up opportunity for me if it was not my 2nd largest holding, with a substantial difference to my 3rd largest holding.
Closed down 12%, looks a bit overdone, I may top up tomorrow.
4imprint (LON:FOUR) - I think 4250 might be fair value if a slowdown eventuates next year and I'd find them pretty attractive there even at a higher PER when the negative operating leverage kicks in.
Well I didn't have to wait until mid 2024 for that target to be (almost) hit. True to my word, I bought three quarters of a position. A PER below 15x for FY24 seems very reasonable for such a quality operator. So watch out for a much better price in the near future!!
What added to my comfort were the three reports from analysts where Cavendish upheld forecasts into next year despite acknowledging the macro warning. More pertinently, Liberum (house broker) and WH Ireland actually raised theirs.
Thought I was reading Paul’s most recent post for Plexus (LON:POS) then realised it was from 2016 lol. I though that market cap and share price doesn’t look right… if it does my shares are worth a fortune. (Not as much as Paul’s would be mind you haha)
Hopefully they get back there eh
https://www.stockopedia.com/co...
My morning smallcap tweet: Shite Club
Actual Experience (LON:ACT) Naked Wines (LON:WINE) Kromek (LON:KMK) XP Power (LON:XPP) Restaurant (LON:RTN) MTI Wireless Edge (LON:MWE) Harland & Wolff group (LON:HARL) Nanoco (LON:NANO) Intercede (LON:IGP) Futura Medical (LON:FUM) Galliford Try Holdings (LON:GFRD) Induction Healthcare (LON:INHC), Kinovo (LON:KINO), Cloudcoco (LON:CLCO), Luceco (LON:LUCE), Zotefoams (LON:ZTF), dotDigital (LON:DOTD)
◄Actual Experience (ACT)► goes bust because securing new revenue contracts and significant sales has taken longer than expected. Suspended. [SP=0.45 Cap=1m]
◄Naked Wines (WINE)► weak US makes co set FY rev fall guidance to 12-16% from 8-12%. Adj EBIT now £2-6m from £8-12m. CEO scarpers. Chmn says "My view is that this shortfall is largely to do with execution, which in turn is largely due to Nick Devlin splitting his time across both the role of CEO and US President". [SP=45 Cap=33m]
◄Kromek (KMK)► collaboration agreement with new partner to develop Cadmium Zinc Telluride based detectors for photon counting computed tomography. [SP=5.54 Cap=33m]
◄XP Power (XPP)► placed £43.9m last night at 1150p, an 11% premium! [SP=1032 Cap=204m]
◄Restaurant Group (RTN)► no extra cheese for holders as PizzaExpress owner decides not to make competing offer. [SP=66.3 Cap=511m]
◄MTI Wireless Edge (MWE)► wins order worth $1m over the next 14 months. [SP=34.53 Cap=30m]
◄Harland & Wolff (HARL)► c.$1.5m contract for Harland & Wolff (USA), its first. Co "is very active in building its pipeline of opportunities in the USA". [SP=14.75 Cap=26m]
◄Nanoco (NANO)► two year Joint Development Agreement with Asian chemical customer. "With proof of concept now achieved, the key goal of the JDA is to optimise the material for the performance required by a number of global electronics applications. Once this is successfully delivered, the subsequent stage will involve scale up to industrial production levels during 2026 and 2027." [SP=17.76 Cap=58m]. I hold.
◄Intercede (IGP)► wins order for over $1.4m, "underpins the Group's revenue for FY24 and creates contracted revenue backlog for FY25". [SP=57 Cap=33m]
◄Futura Medical (FUM)► on the up as M8 Pharmaceuticals takes up rights to extend licensing agreement (currently Brazil and Mexico) to market MED3000 in a further 14 countries in Central and South America. [SP=29.64 Cap=89m]
◄Galliford Try (GFRD)► wins £87m contract to deliver a further phase of the new build-to-rent development in London. [SP=235 Cap=242m]. I hold.
◄Induction Healthcare (INHC)► FY-Sep rev down 14%, pretax -£2.4m (-£4.5m). Outlook positive apart from continued headwinds with Attend Anywhere renewals but does not have in line guidance. [SP=28 Cap=24m]
In line: KINO, CLCO, LUCE, ZTF, DOTD
Zotefoams (LON:ZTF) update in line with expectations this morning. Of real interest was the increased focus on the ReZorce packaging project. Clear milestone of Early 2024 set for market trials and a focus on the project runs throughout the RNS. Compared to the previous update this is a great reminder that they think they are close to unlocking something transformative. (I hold)
Zotefoams (LON:ZTF) also David Sterling is departing after what seems like a short time but we are told since 2000. I've held since they split off from ICI!
Zotefoams (LON:ZTF) Yet the shares go down and down, I also hold.
One of Paul's favourites.
Zotefoams (LON:ZTF) I'm hoping those that don't want to be in the share have a chance to get out this morning on some added liquidity. Got a feeling it might have a better afternoon and drift into the green once that happens. I think the potential upside could be huge longer term so I'm happy to hold as I'd hate to miss out should there be any major developments.
dotDigital (LON:DOTD) - small beat on both top line and adjusted eps. Not cheap but positive outlook from recent bolt-on
The post period acquisition of Fresh Relevance's personalisation technology and talented team marks a leap forward in our strategy, accelerating our product roadmap and opening up new, high value market opportunities. We start the new financial year with solid global foundations, a substantially enhanced product offering and a robust financial position. We have had an encouraging start to FY24 and look forward to our continued profitable growth.
Plus 17p of net cash per share.
I hold
Croma
Interesting little company with a now 6 million market cap .
Had quite a year of change selling off the vigilant security part of their business which was high turnover low margin security .
Leaves then with quite a nice business, focussed , seen to have a good strategy in an ok sector .
2 million cassh
2.2p dividend
Making maybe 1 million profit in remaining business
Margins increasing
Owns a lot of their properties .
Trading on NAV (presumably based on freeholds and cash)
From memory management are rather well rewarded .
I’ve got a decent holding (circa 1.8% of the company ) and it’s very illiquid micro cap territory with a big spread and hard to get in / out of .
But have to say quite interesting what they are doing and they have made some smart changes this year
Can see this doing well in the next years they seem to have a plan .
We are with you on this planetx but with about 1/3rd of your holding, we'll add a few more after today's statement.
Good to hear
Actually I’m 1.48% now I cracked a bit last month and sold a few when I trimmed across the board as I had put myself in the stock rich / cash poor situation .
I might try to make it next AGM if you feel like going could say hello in person
Last time I looked they were only making about £30k profit a. per shop which I thought was too low. Is it better now?
I have a few and bought a few more today: 4x EV/EBITDA, cash generative, long growth runway from buy and build. Had been waiting for a positive update after the divestment and this seems to be it .
Oakley Capital Investments (LON:OCI) I don't own... I did look at a while back and although I remember liking a lot of what they are doing just don't like the PE space at the moment. Anyway I mention as Dubens has bought 200,000 shares in addition to other purchases - as largest holder he can't be ignored. Discount to NAV substantial at 35%.
Starting with the caveat that there are no guarantees in life, including investing, it strikes me that well managed PE investment trusts on extreme discounts and based on recent announcements are absolute buys.
Oakley Capital Investments (LON:OCI) in addition to this morning's announced purchase by founder Peter Dubens, Mr Dubens and another director spent £400,000 their own money on shares last weeks. Current, Steven Tredget is well worth watching. Link below.
Q&A with Steven Tredget, Partner at Oakley Capital Investments - Vox Markets
Harbourvest Global Private Equity (LON:HVPE) discount to NAV around 45%. Recent interims reported 3% NAV growth. Have recently completed a £25m share buy back. Shares subject to buy back have been cancelled. Directors have currently spent around £1.7m buying shares this year. Also from interim results published on 25 October:
New share buyback and review of dividend policy
· The Board and Investment Manager have recently conducted a review of the case for share buybacks using the established framework.
· Following this, the Board will conduct another share buyback and intends to repurchase $25 million of shares.
· The Board plans to discuss with shareholders and non-holders to explore the possibility of distributing to shareholders on a regular basis some of the cash generated by realisations of HVPE's net assets, thereby enabling direct participation in NAV growth.
HgCapital Trust (LON:HGT) trading at a 20% discount to NAV. Excellent long term record. Recent disposals all made at a premium to carrying value.
17 August: partial sale of TeamSystem at a premium to carrying value
This transaction values HGT's investment in TeamSystem at approximately £33.3 million. This would represent an uplift of £13.5 million (68% or 2.9 pence per share) over the carrying value of £19.8 million in the Net Asset Value ("NAV") of HGT at 31 March 2023.
5 September: sale of Commify at a premium to to carrying value
This transaction values HGT's investment in Commify at approximately £21.9 million. This would represent an uplift of £5.3 million (32% or 1.2 pence per share) over the carrying value of £16.6 million in the Net Asset Value ("NAV") of HGT at 31 March 2023.
25 September: sale of Silverfin at a premium to carrying value
This transaction values HGT's investment in Silverfin at approximately £18.8 million. This would represent an uplift of £3.1 million (20% or 0.7 pence per share) over the carrying value of £15.7 million in the Net Asset Value ("NAV") of HGT at 31 August 2023.
PE is not a new phenomenon and the above trusts have been around for a long time. They derive no benefit from inflating the carrying value of their holdings. All of the above are held in family portfolios and I am currently adding to Oakley Capital Investments (LON:OCI) and HgCapital Trust (LON:HGT) as funds allow.
I have substantial holdings of Oakley Capital Investments (LON:OCI) Harbourvest Global Private Equity (LON:HVPE) ICG Enterprise Trust (LON:ICGT) Apax Global Alpha (LON:APAX) Pantheon International (LON:PIN)
In my view private equity is excellent value just now. One of the exit doors is temporarily blocked, the IPO route, but valuations are modest in these funds, they all aim to hold profitable companies rather than VC start ups, and there is a fair bit of dry powder left in the industry. This will fuel bids.
I think we've got another 18 months of more modest activity until the cycle turns, but turn it will. In the meantime these firms can pick up new investments at lower valuations, which will lead to higher long term gains. There will be a bit of short term nervousness over future investment commitments made at this stage of the cycle.
The long term performance of PE funds is really excellent. I'm a holder despite my age (69).
Annual charges in PE
I checked the HL. site and it says the annual mangement charge of OCI is around 8%
It is like a hedge fund , you pay a huge fee , they deserve to have large discounts and no hope of repeating the return of the cheap money anytime soon. I ignore the directors buying spree.
I just checked it. It says 2.6% on HL. A little high but not crazy by PE standards.
I'm on a 25% to 40% uplift on 2021 purchases. OK, very driven by a single very large exit, but that is ttheir job.
It's a 2% management fee on committed capital plus 20% performance fee charged after an exit is achieved. It's pretty standard. The average discount is 30% so that's not really a reason to get involved. If Dubens is buying maybe One of the larger investments will be sold soon..... I think the space could be tricky but for the well run business this will be an opportunity.