Small Cap Value Report (Tue 7 Sep 2021) - TED, CNC, MIDW, LUCE, MEAL, RNWH

Good morning, it's Paul & Jack here with the SCVR for Tuesday. Welcome back Jack, and thank you to Roland for covering, much appreciated, as it makes my workload a lot more manageable, especially welcome when I'm away from home.
Today's report is now finished - we covered 6 companies, trying to focus on the more interesting ones. Apologies if we missed anything you like, there were far too many companies reporting today to cover everything.
Agenda -
Paul's Section:
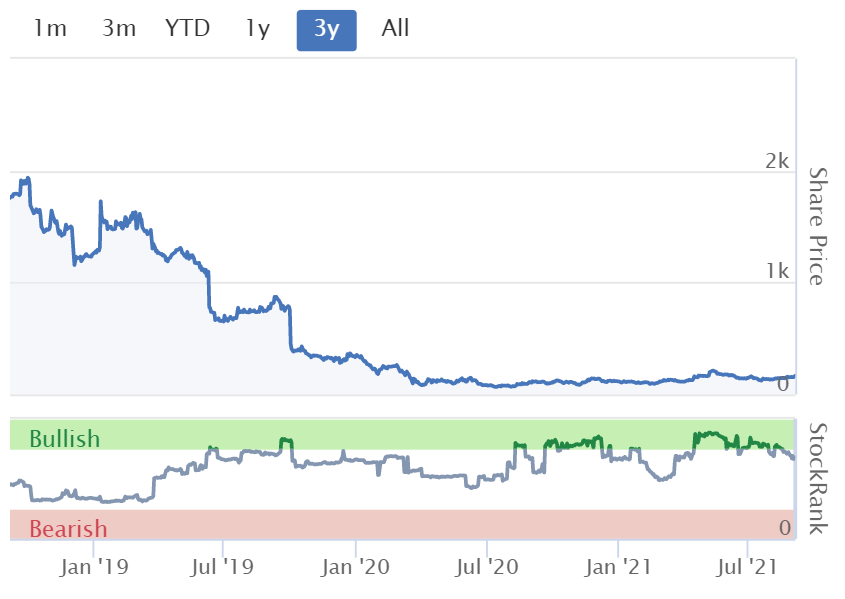
Ted Baker (LON:TED) - a lacklustre Q2 trading update, in my opinion. It's in line with expectations, but it's expected to be loss-making this year. Not much sign of online growth, and store sales still well below pre-pandemic levels. An unconvincing turnaround so far, in my view, so why get involved?
Luceco (LON:LUCE) - sparkling interim results - this company has done amazingly well in the last year. Fascinating commentary on supply chain issues, and cost inflation - worth everyone reading, as it has read-across for many other companies.
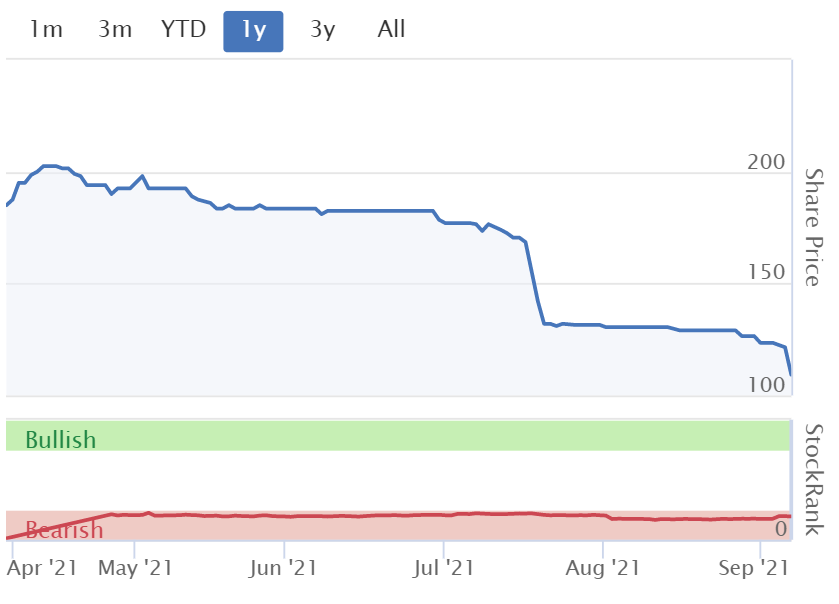
Parsley Box (LON:MEAL) - this niche ready meals company has flopped since floating about 6 months ago, with the price now roughly half the peak. Slower growth, and heavy marketing spend combine to produce a thumping H1 loss.
Renew Holdings (LON:RNWH) - another strong update, materially ahead of forecast for FY 09/2021. Impressive!
Jack's Section:
Concurrent Technologies (LON:CNC) - solid company with a multi-decade operating track record but pedestrian growth in recent years. This is a good company with a strong balance sheet and decent longer term potential, but management is clearly communicating short term headwinds.
Midwich (LON:MIDW) - specialist audiovisual distributor reporting improving trading momentum. It has scale on its side and a busy acquisition pipeline, but business is relatively low margin and a recent c40% rerating limits the attraction
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Ted Baker (LON:TED)
167p (y’days close) - mkt cap £308m
Ted Baker Plc, the global lifestyle brand, today provides an update on trading for the 16-week period from 25 April 2021 to 14 August 2021.
The current financial year is FY 01/2022.
Sales in line with expectations, significant improvement in full price mix
There’s lots of detail in this announcement, so I’ll try to pick out the key points.
Store sales - still well below (minus 45%) pre-pandemic levels. The +142% rise against last year is meaningless, as shops were mostly closed in lockdown 1 -
Store sales were +142% vs Q2 FY2021 and -45% vs Q2 FY2020. While many of our stores were open during the trading period, footfall remains below prior levels and continues to be stronger in out-of-town and regional locations where we have a smaller physical presence.
This confirms what we’re hearing from many other retailers - that town centres are struggling, and not returning to previous levels of footfall. Although that could improve as workers return to offices.
Out-of-town sites doing better, which again is in line with what other retailers have been saying.
Ecommerce sales - this doesn’t impress either, although last year’s comps would be tough, because stores were closed, so most business moved online last year -
Group eCommerce sales decreased 25% and represented 39% of total retail sales (2021: 67%), reflecting highly promotional stance last year ahead of balance sheet recapitalisation. Compared to Q2 FY2020, Group eCommerce sales increased 17%.
Wholesale & licence revenue is 29% down on pre-pandemic levels.
Eyewear licence partners doing well, up 27% on pre-pandemic sales, but no context is given. Instead of a text based update, it would have been much more illuminating to have provided data, in a table, showing the breakdown of sales, and performance of each channel - which is conspicuous by its absence.
Gross margin - up 500bps for retail sales, but again no context is given. Sounds like the business was discounting heavily last year, so the margin should be better this year.
Liquidity -
As of 14 August 2021, net liquidity was £105.8m comprising £15.8m of cash and £90m of bank facilities. The Group has material liquidity headroom against anticipated peak cash requirements in September/October 2021.
Net cash seems to have fallen from £66.7m when last reported at end Jan 2021, to £15.8m now. End January does tend to be a seasonal peak for cash in this sector, so it’s not particularly surprising that cash has since fallen.
That said, I’m not comfortable with TED being reliant on bank facilities. Banks don’t like lending to loss-making companies, so I’d say there’s an elevated risk of TED needing another placing to shore up its balance sheet.
Tosca Fund are big backers, and they tend to be very gung-ho, so would probably prop it up if more funds were needed, but who knows what the price would be? The price of further support from Tosca could be to heavily dilute other holders, maybe? It’s happened once already.
Diary date - this will be more useful than a trading update which gives various statistics, but little overall context. Whereas results will reveal how trading & the financial position look in detail. I look forward to crunching these numbers in November -
Ted Baker will announce its results for the 28-week period ended 14 August 2021 on 11 November 2021.
Outlook - note they claim a strong balance sheet - often an amber flag to check because like so many things, if it needs to be said, then it may not necessarily be correct (but that's open to interpretation of course with balance sheets) -
"The Ted Baker brand remains strong, evidenced by YouGov's recognition of Ted Baker as the second most popular luxury brand in the UK. Our product also continues to strengthen, and we are pleased by the start to the Autumn/Winter 2021 collections which is being well received by our customers. Combined with our robust balance sheet and strong cash management we are well placed for the future. It is still early days in the recovery, but we are confident that Ted is starting to emerge from Covid a stronger and more resilient business."...
Trading momentum continued to build through the period, with the last four week exit rate for Retail better than the overall Q2 performance for Retail sales.
The point about brand recognition is important - there’s no doubt that TED is a valuable brand, which is pretty much the entire bull case for this share - that dismal performance (pre-pandemic, as well as during the pandemic) can be turned around.
Forecasts - the latest numbers from Liberum (many thanks to them for sharing with us) are for a loss before tax of £(22.6)m this year FY 01/2022, bouncing to a profit of £28.8m for FY 01/2023.
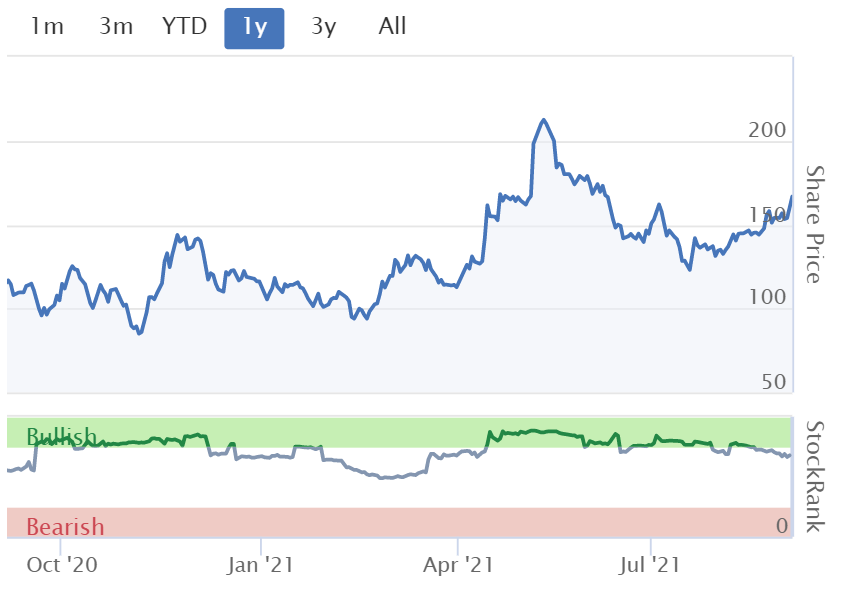
My opinion - I remain negative on this share. There's not enough evidence yet of a proper turnaround. Things seem to be improving, but from very bad, to just bad (so far).
I’d be surprised if the 2023 profit forecast is achieved, it’s usually more of a struggle to drag a fashion business back into profit, after a long period of under-performance, if it’s achieved at all.
Many (probably most actually) attempted turnarounds in this sector fail. The critical success factor is getting out of expensive leases, and moving sales largely online. I don’t see any evidence that is happening here, on anything like the scale needed.
Another placing looks likely to me, with unknown further dilution. The share count has already ballooned from 55m to 185m, hence the share price won’t be returning to anything like former glories, because there are so many more shares in issue now.
I’d say this share is just a gamble on a possible turnaround. There’s not much evidence of a turnaround to anything like the level needed to make it a significantly profitable business again.
Today’s update is too vague - you wouldn’t find Next (LON:NXT) issuing such a woolly update. Whenever companies/advisers ask me what information investors want I say “Just do what Next does - chapter & verse, facts & figures, not waffle, or cherry-picked numbers with no context”.
I look forward to seeing the interim results in November, which should give us a better idea of what’s really going on. As things stand, the company still seems to be loss-making, and it could need additional funding, if the bank get jittery (e.g. if covenants are breached).
I cannot see any reason to take on the risk of owning this share, just on wishful thinking that a turnaround might happen.
.
.
Zooming in, for clarity -
.
.
Luceco (LON:LUCE)
474p (slightly up) - mkt cap £760m
Luceco plc ("Luceco", or the "Group" or the "Company"), a manufacturer and distributor of high quality and innovative wiring accessories, LED lighting, and portable power products, today announces its unaudited results for the six months ended 30 June 2021 ("H1 2021" or "the period").
Strong progress and well positioned for long-term growth
Key numbers for H1 -
- Revenues £108.2m (up 51% on H1 LY, and more impressively up 31% on pre-pandemic H1)
- Very high profit margin, with adj PBT at £18.5m - is that sustainable though?
- H1 adj EPS of 9.8p
Current trading - sounds like a little wobble here, and being an importer the key issue is container ship freight cost/delays -
We have made a decent start to the third quarter. We have an encouraging order book from Hybrid and Retail customers that we are working hard to ship amid continued sea container shortages, and macro leading indicators such as planning applications and architect/surveyor workloads suggest a good second half.
We have recently seen a softening in late July and August in previously very robust UK Professional Wholesale demand which has slowed the Group's rate of revenue growth compared to H1. This could be attributable to both contractors and homeowners taking well-earned post-lockdown holidays en masse at the end of the academic year, but we are keeping the situation under review.
Supply chain disruption - this section is worth repeating in full, because it has much wider significance for other companies in any sector that makes, or imports physical goods. I’m impressed with Luceco’s openness in explaining the situation to investors. It sounds like they have things under control -
Healthy market conditions have been beneficial to our performance but increased demand for goods over services during COVID has also brought widespread supply chain disruption, making it more difficult for us all to serve the customer, and resulting in cost inflation. The average cost of copper and plastic in 2021 to date has been 37% and 71% higher than 2020 respectively. The cost of a sea container from China to the UK has increased nearly five-fold over the same period. We estimate the total annual cost of inflation to Luceco to date will be £20m, a 15% increase in our cost of goods sold, of which £13m will arise in 2021 and £7m will be deferred into later years by hedging arrangements.
We have had little option but to update our selling prices in response to this industry-wide phenomenon, albeit with a slight lag due to notice periods and order lead times. We expect 75% of our update to be in place by the start of the fourth quarter, with the remaining 25% to follow in early 2022. Some of the profit gap caused by the lag has been filled by impressive efficiency gains from earlier manufacturing investment, whilst strong operating leverage from 2021's sales growth has further mitigated the impact at the operating margin level.
Outlook/Guidance - a very clear update is given -
A selling price update of this magnitude whilst gaining share underlines both the value of our brands and the widespread nature of the underlying inflation. We have navigated the inflation challenge well to date but we are not complacent. The mathematical reality is that cost inflation will always dilute the gross margin % even if every pound is passed through. This situation is also fast moving. For instance, we have recently received notification of a further 40% increase in sea container rates for the fourth quarter that we may not be able to pass through until early 2022. All of this leads me to conclude that we will see some gross margin compression as we navigate this post-lockdown inflationary phase in the second half, albeit mitigated by solid operating leverage on strong sales growth. We continue to expect to achieve Adjusted Operating Profit of £39m for FY 2021, as previously guided, although temporary margin compression and the recent softening in Professional Wholesale demand over the summer may have curtailed any potential upside.
There’s more detail given, but I’m already reaching the limits of what is reasonable to copy/paste here! I suggest that all readers should have a look at Luceco’s commentary today, as it’s full of pointers which are very likely to have read-across for many other companies. In short, it seems to me that we’re entering a period where there’s likely to be very considerable supply chain disruption, and considerable inflation.
That’s creating a lot of opportunities for the best managed companies, which have stocked up in advance (as LUCE has), and are hence able to raise selling prices, with less competition.
However, it’s also likely to lead to profit warnings from (maybe smaller?) companies with less supply chain expertise. This is going to be a very interesting autumn/winter, for sure, with banana skins galore, we just don’t know where they are.
Balance sheet - looks absolutely fine to me. Inventories have gone up considerably, but in the current situation of supply chain disruption, I see that as a positive thing, as it means continuity of sales to customers, rather than running out of things. The small amount of debt is not a problem.
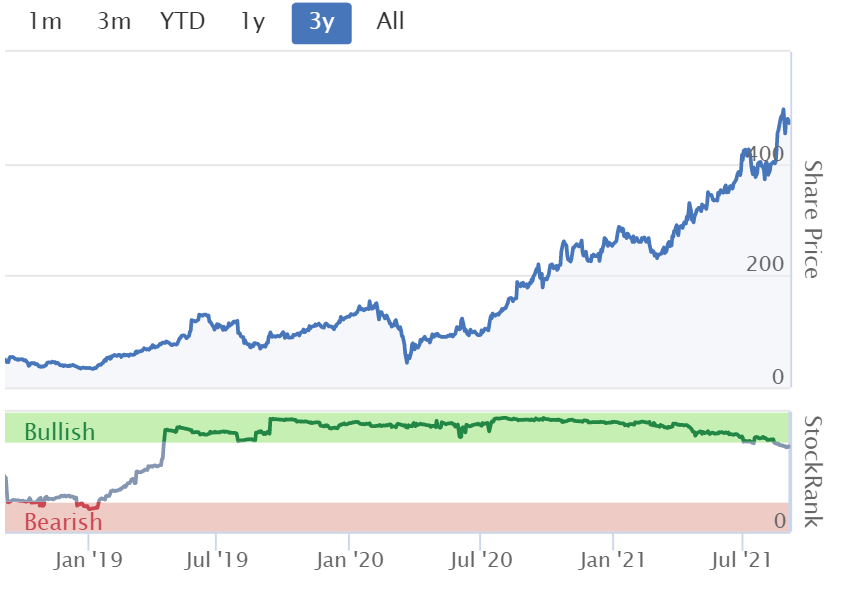
My opinion - this is a tricky one. Luceco has performed brilliantly in the last year, with profits soaring thanks to strong demand, combined with production efficiency gains.
That’s been reflected in a roaring share price rise, and repeated hikes in broker forecasts.
Today’s commentary is impressively detailed and open, which gives me confidence that management are in control. I certainly wouldn’t bet against this company.
However, it seems to me that demand may have peaked, and that supply chain issues and cost inflation are very clear headwinds, introducing uncertainty. It sounds like LUCE will be able to pass on price rises, with a time lag. It has leading brands that are trusted in the trade, as the commentary explains. However, the very high net profit margin could leave it vulnerable to being undercut on price by competitors, maybe? One company’s bumper profit margin, is someone else’s opportunity, especially with products that don’t seem to contain much unique IP.
On balance, if I held (which I don’t), I’d probably be top-slicing some of the profits after a great run, just to be on the safe side, and running the rest for the long-term. As always, that’s just a personal opinion, and everyone will see things their own way.
No doubt doing the precise opposite would probably work out best, that seems to happen so often!
.
.
Parsley Box (LON:MEAL)
110p (down 9% at 10:54) - mkt cap £46m
Parsley Box Group plc (AIM: MEAL), the rapidly growing direct to consumer provider of ready meals focused on the Baby Boomer + demographic, today issues its results for the six months ending 30 June 2020 (the "Period").
A trading update on 19 July announced that H1 revenue growth would be c.26% up on H1 LY.
So revenue announced today is in line with that, hence shouldn’t have surprised the market.
Maybe it’s the scale of the H1 loss that has spooked investors? Key figures for H1 -
- Revenue £14.0m (in line with expectations), up 26% on H1 LY
- Most revenue, £11.0m is repeat custom - an impressive statistic - but it also calls into question the effectiveness of the heavy marketing spend in attracting new business
- Gross margin of 51% is respectable, and slightly increased
- Pre-exceptional EBITDA is a heavy loss of £(3.6)m
- Exceptionals relate to IPO costs, so it's fine to strip out those costs of £1.35m
- Net cash of £6.5m
Marketing spend was £4.85m in H1 - a staggering amount, to generate only 26% rise in revenues. On the plus side, this is discretionary spending, so could be switched off, or greatly reduced, leaving what would then probably be a breakeven, or modestly profitable business relying on repeat orders (which are much larger than average orders).
Balance sheet - is fine for now, but won’t be if they keep burning through the cash pile on not very effective marketing spending.
My opinion - they need a re-think here, with massive marketing spending only delivering slower growth - so I think a much leaner marketing approach is needed - a bit like the position Sosandar (LON:SOS) (I hold) found itself in a while back. The beauty of online businesses, is they have so much flexibility on costs (with marketing spend being the big one, and it’s discretionary, and can be flexed almost immediately to whatever suits market conditions).
The concept is niche in my view, with a small addressable market, but once some customers repeat order, then MEAL can do well from larger repeat orders. So it’s an interesting niche business in my view.
My concern since the IPO in March 2021 was that the float on AIM could have been timed to benefit from one-off growth from the pandemic. That concern seems to have proven correct, with slower growth since, despite a huge hike in marketing spending.
Having said all of that, the market cap has almost halved, and is now only £46m. Should it be any higher than that though? Probably not, as things currently stand.
I hardly ever touch IPOs, because they’re nearly always over-priced, and over-promoted, and often miss growth forecasts. However, once the hype has dissipated, and the price halved, then things could be worth a fresh look, with improved risk:reward, arguably.
The other thing to consider is that small cap IPOs are usually very illiquid, because the brokers are lazy, and just place chunks of shares with institutions, leaving very little subsequent market liquidity. Hence there could be an opportunity here if an institutional holder loses patience and decides to exit, dumping stock in the market. If that happens, I’d be a buyer at say 50-60p - that's roughly what it's worth to me, so the current price of 110p doesn't attract me. There are plenty of other shares to choose from.
.
.
Renew Holdings (LON:RNWH)
835p (up c.4% at 11:55) - mkt cap £650m
Renew (AIM: RNWH), the leading Engineering Services Group supporting UK infrastructure, provides the following trading update ahead of the release of its full year results for the financial year ended 30 September 2021 on 7 December 2021.
Continued strong trading; full year performance expected to be ahead of current market expectations
Guidance is usefully raised, impressive coming near the end of the financial year -
As a result of this sustained positive momentum, the Board now expects the Group's full year results to be materially ahead of current market expectations with adjusted operating profit expected to be no less than £50m versus a current consensus forecast of £45.8m.
Forecasts - I can’t find any broker updates, which seems a bit bizarre for a company with a decent sized market cap.
Working from existing consensus EPS for FY 09/2021 of 46p, and lifting it by 10% (as indicated in today’s guidance for operating profit) suggests about 51p EPS for this year.
A share price of 835p puts RNWH on a PER of 16.4 - quite high for a sector that is often problematic & hence lowly rated. Although a premium looks justified due to RNWH’s superb long-term track record.
My opinion - not a sector that interests me, but RNWH seems to have a better business model than others in its sector which have come a cropper.
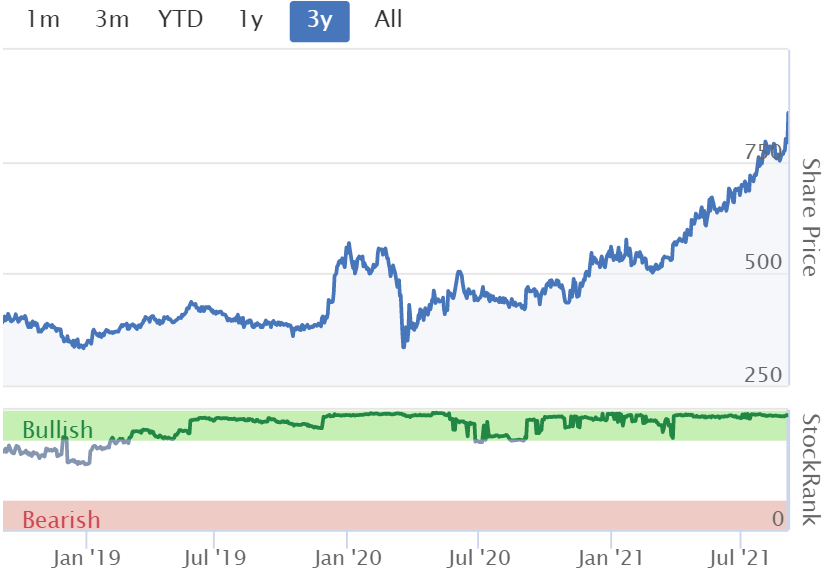
Performance has been really good, and shareholders have been rewarded with a big rise in share price.
Looking at this chart, and the valuation, I wonder if it might need to pause for breath & consolidate a bit at some point?
.
.
Jack’s section
Concurrent Technologies (LON:CNC)
Share price: 98p (-5%)
Shares in issue: 73,363,490
Market cap: £71.9m
(I hold)
Concurrent produces a range of high performance Intel processor boards used by customers in the Defense, Security, Aerospace, Telecommunications, Transportation, Medical, and Industrial markets. These chips are designed to withstand harsh conditions and are sold worldwide. It was classed as an essential defence supplier through Covid so maintained production and did not need any government support.
But the group has struggled to excite the market in the past. Revenue progress over the years has been steady but costs have tended to rise as well, meaning profits haven’t quite taken off. This comes across in the modestly declining operating margins.

We last covered it here in an update to the market that saw shares down on the day. I interpreted the update more positively and took a small position after a drop in the share price.
There are issues - supply chain problems are being flagged by management - but this is a cash generative, dividend paying small cap that habitually invests millions of pounds into research and development so it strikes me as well run over longer time frames.
The question is can the group translate all this hard work into profitable growth for shareholders? The group is closing its India office, which will cut costs, and the savings can be reinvested in UK headcount and other ventures, so that’s a possible catalyst, along with some management changes. Nevertheless, this remains more in the ‘sensible, quality’ category compared to stocks with riskier and more aggressive rerating potential.
I am pleased to announce the trading performance has continued on from the strong results reported for 2020, with solid sales in the first half of 2021 and a growing order book, despite the challenging worldwide supply chain disruption.
Financial highlights:
- Revenue +1.1% to £9.3m,
- Gross profit +4.1% to £5.1m, gross margin up from 52.9% to 54.3%,
- Operating profit +33.3% to £1.6m,
- Profit before tax +25% to £1.5m,
- Earnings per share +29% to 2.09p,
- Interim dividend per share +4.5% to 1.15p,
- Cash balance up from £10m to £12.4m.
Probably the two key dynamics to highlight are the record order book of £15.9m (up from £13.9m on the same period last year) set against ongoing component shortages, which are ‘being managed’.
The chairman says:
There remains uncertainty on the timing of some shipments in Q4 2021 and into 2022, driven by component availability, which may slip revenues into 2022 but there is no evidence yet of cancellations from customers.
The unprecedented worldwide supply chain shortages are a major risk to all companies. Although Concurrent has so far protected the supply of goods, ‘the situation is deteriorating and is expected to last well into 2022’. So the group is not out of the woods yet, in fact the risk here is increasing.
Net cash from operations is up strongly, from £1.48m to £2.79m, but this is helped in part by trade payables growing from £0.49m to £1.65m. Perhaps this is a consequence of the strong order book, perhaps it is Concurrent stockpiling inventory.
Sales within the defence market increased to £6.6m (H1 2020: £6.3m) representing 71% (H1 2020: 68%) of revenue and exports were 91% (H1 2020: 96%). While defence is still the primary target market, the team sees opportunities in the telecoms and other sectors ‘which are being pursued with vigour’.
India office - this is now closed and savings here are funding the expansion and re-alignment of engineering capabilities in the UK.
Product launches - Intel has elevated Concurrent to Titanium partner status, which is a vote of confidence. Meanwhile, the launches and deployment of the new 3U CompactPCI and AMC boards have continued, along with the development of software products.
Management changes - The end of the first half also saw the beginning of the transition from Jane Annear to Miles Adcock as CEO. Additional senior hires are being made with the introduction of an HR Director and a Quality & Business Improvement Director. The new team will revise the medium and long-term strategic plan focusing on product lead times and revenue growth.
Balance sheet - is strong, with no debt and cash balances at 30 June 2021 of £12.4m (H1 2020: £10.0m).
Conclusion
Assuming a simple doubling of HY EPS gives a possible FY figure of 4.18p, which would put the group on 23.4x forecast earnings. That’s quite punchy based on the growth track record and supply chain dangers, but there is scope for better levels of growth in future. Concurrent has a good reputation and continues to invest - R&D spend is down but still comes in at a healthy £1.6m.
Importantly, the group has so far been able to pass on supply chain cost increases resulting from wide-scale electronic component shortages. Gross margins are actually up in spite of these pressures.
The record order book currently gives good visibility of future revenues but the timing of some shipments in Q4/21 and into 2022 is uncertain due to the widely reported electronic component availability. This could be an area to focus on for those considering the timing of a potential investment, particularly given the valuation.
Yes this is a well run company managed for the long term, but there are developing headwinds out there and the short term could be bumpy. Today the market might well focus on the growing supply chain risks and delayed revenue. If things deteriorate then a profit warning is possible, due to events beyond management’s control. It’s impossible to say for sure.
It’s a good company, but is now the right time to be invested in it? Or should we not overthink the purchases of high Quality Rank stocks? Something to think about. I lean towards the latter over the long term (within reason) but management is clearly communicating some shorter term risks here.
Ultimately it comes down to your investment horizon. Some investors trade and others accumulate long term holdings over time. The strong demand and record order book here is key for the longer term and Concurrent has been a solid, dividend-paying hold for truly patient investors.

But in the short term the shares have risen and there are well flagged headwinds that might keep the neutral investor on the sidelines for now, to see how the next year plays out.
Midwich (LON:MIDW)
Share price: 618p (+1.31%)
Shares in issue: 88,735,612
Market cap: £548.4m
This is a specialist AV distributor to the trade market with operations in the UK and Ireland, EMEA, Asia Pacific and North America. Distribution business models are tough - most of the profit typically flows to the manufacturers that own the IP.
Some do well. Usually those that are sensibly well run and have a scale advantage over competitors. Those players can then leverage their scale advantages, outcompete rivals, and acquire them if it makes economic sense, thus further strengthening their advantage.
Midwich might fit this mold, saying it ‘operates as the sole or largest in-country distributor for a number of its vendors in their respective product sets’. So it’s a distributor of scale operating a buy and build model with strong customer relationships. I’d still mark margins and competition as areas of concern though.
Trading momentum continues, with margins recovering
Financial highlights:
- Revenue +29% to £390.1m,
- Gross margin up from 14.5% to 15.1%,
- Gross profit +35% to £59.1m,
- Adjusted operating profit +240% to £13.9m,
- Adjusted profit before tax +306% to £13m,
- Adjusted earnings per share +278% to 9.4p
There is some difference between the adjusted and statutory results. Statutory profit before tax was £7.1m (up from £2.5m loss before tax), and earnings per share was 4.79p (up from 3.29p loss per share).
The differences come from acquisition related expenses, share based payments, amortisation charges, and changes in fair value of derivatives.

Quite a lot of adjustments, particularly with the share based payments. Should they really be adjusted out?
Flipping over to the cash flow statement confirms that Midwich is an acquisitive company.

There is a further difference between earnings and cash flows. Operating cash conversion is just 31% due to investment in working capital to support business growth. The same period last year did see cash conversion at 127%, however. And working capital investment does hint at a favourable outlook.
Furthermore, the group paid out a 3p special dividend in the period, on top of a 3.3p declared interim dividend. Quite a small special dividend in comparison to the 614.4p share price though.
Trading momentum continues to improve, as do gross margins, while market share has remained stable.
The Board continues to monitor its share of vendor business in each of its key markets and remains confident that, overall, the Group has at least maintained and in many cases grown its market share.
Trading since the period end is in line with the board’s expectations and ‘well ahead of the comparative period’.
The higher margin live events and hospitality markets are starting to recover in a number of territories, although we believe there is still a considerable way to go… There is a more significant level of enquiries and activity in [the corporate] market, and we now expect that this will start to be converted into orders and revenue in early 2022.
Gross margin up is positive, with signs of operational gearing. This represents a significant step towards returning to the margin of 16.5% achieved in 2019.
Acquisitions - NMK Group at the start of the year, Midwich’s first Middle East business. eLink in Germany. A strong pipeline of further acquisition candidates.
Territories - Trading in EMEA showed the greatest improvement, with revenues up 65% year on year, and net profit substantially higher. Both acquisitions contributed positively and organic revenue growth was 58% to £210.2m.
Performance in the UK & Ireland improved significantly after the easing of the severe lockdowns earlier in the period. Revenues increased 25% to £128.6m, helped particularly by the contribution from new vendors launched in late 2020 and H1 2021. The live events, entertainment and hospitality markets have remained subdued, but it is anticipated that further easing of restrictions should enable these markets recover.
Revenue in North America was 41.8% lower than the same period in 2020 at £29.1m due to exiting a low margin fulfilment arrangement in North America. Asia Pacific was relatively flat (£22.2m) but recent lockdowns in Australia and New Zealand are now affecting business.
Balance sheet - a lot of goodwill and intangibles here on account of the acquisitions. A net debt position of around £73m. It looks a little weak to me.
Conclusion
This is a big, acquisitive business with operations across multiple geographies. As noted above, consolidating distributors of sufficient scale can do well if they are managed competently and acquire with discipline. They often remain low margin however and so external price pressures or a drop in quality of strategy execution can hurt.
Putting that to one side for now, it does seem as though Midwich is well placed for a continued improvement in trading momentum (but does that make it a trade or a long term hold?)
Its markets and business should continue to improve steadily across the remainder of 2021 and into 2022. Midwich points to research published by industry trade body AVIXA in June 2021, which suggests that following a sharp Covid reduction the market is expected to grow by 8.4% in 2021 and then at a compound annual rate of 7.2% for the next five years.
But the shares are already up c40% over the past quarter. Returning to FY19 levels of profitability (21.7p of earnings per share) would put the group on a PER of 28x. That sounds expensive for what this business is.
Brokers are forecasting FY22 EPS of 26.5p though, so whether or not that truly is expensive depends on the rate of acquisitions and the prices paid for them. Midwich has managed to grow revenue at a fair clip but margins here will likely always be low so it’s hard to get too excited about the opportunity.
It does stand to benefit from a return to normal though.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Appreciate your response and comment that valuation depends entirely on future growth. I was surprised and disappointed....no more ..no less...but you seem to have taken umbrage to that comment. That was not my intention. I stand by my comment that you commented on 2 companies with much small market caps...that is a fact...so stay cool and keep smiling.
This is largely a self help community. If you want to share some thoughts on Bango, I’m sure others here will have a discussion with you. I know a couple of the posters are very negative on the stock and think NHN will be siphoning out revenue and profit via the JV to the detriment of BGO
I take the opposite view and think the NHN JV is a positive.
I am surprised and disappointed that you have not commented on the BGO results today. The market cap. is £160m which is much more than Parsley Box and CNC so your priorities confuse me. I would appreciate your assessment on BGO....negative or positive. You also did not comment on CNIC last week so I wonder are you giving fast moving international tech growth companies a miss!?
I am surprised and disappointed that you have not commented on the BGO results today
A quick sweep this morning suggested about 20 companies reporting news that would fit into the SCVR remit. Obviously not all of those can be covered and the writers will generally write up the reports that interest them most.
So if anyone has a company they especially want considered then they should get in early and write something interesting to pique Paul or Jack's interest. For instance - what is especially interesting about Bango (LON:BGO)?
timarr
dereksp - I hope you make a full recovery. :-)
dereksp.......I think you need to give Paul a reason to look at a share if it isn't on his own personal investment horizon. If you explain why you got into it, what you see as interesting, how you interpret the results etc etc then I am sure he will help out.
There are so many companies reporting on a daily basis you've got to give the man a reason to invest his time into it.
Alternatively ask for others views - there are a lot of very knowledgeable people on this site who I am sure will assist if their interest is piqued.
dereksp,
Bit of a life hack here - if you start any comment, to anyone with "I'm surprised and disappointed that you have not..." then you'll immediately piss them off & they won't want to help you.
There were about 20 companies reporting yesterday, we can't cover everything, simple as that. We report on things we know & understand, profit warnings & profit beats, as priorities.
I did have a look at Bango in the evening, out of curiosity, and it's a tiny, speculative company, that doesn't actually make any significant or genuine profits, once you take into account capitalised development spending. Eking out modest revenues from a tiny cut of payment processing.
As the title here suggests, we come at things here from a value investing slant. On that basis, it's difficult to see any value at all in Bango at current levels of revenue, certainly nowhere near the £160m market cap. Why is it valued so highly? Because growth is strong, and people are forecasting profits in future.
I'm not in the business of forecasting/guessing what growth might be, and what profits (if any) it might end up making. Hence we can't add any value here by reporting on Bango. We'll stick to our knitting.
If you think it's a great company, then feel free to do a write-up yourself, however brief, on Bango. That's the idea, we all throw our ideas into the pot.
Bango could grow into something good, or it might not. I've not got a crystal ball, so don't have a view on it. But the valuation rests entirely on hopes for future growth, because there's no value in the company as it stands, were revenues to stall at the current level, in my opinion.
Given the fuss you made, I'm also surprised & disappointed - that the figures weren't more appealing! Oh well.
Paul.
Bango (LON:BGO)
Thanks for taking the time to add your comments Paul much appreciated. I also had a look last night too and came way feeling quite positive here ref where business is trending (50% sales growth is good for any business type?) . My original summary thoughts are on wednesdays pages as i hadnt seen your comments here.
Overall i actually came away reasonably impressed actually - if you compare their growth and potential for operational gearing kicking in on the bottom line as sales increase and excellent customer base its certainly interesting. Data of the kind they will hold on transactional data is highly saught after nowadays - so it does seem even based on the reasonably modest expecationsfor next year - revenue growth from only from £15 mill to 18 mill they will do 5p EPS next year (we are only 4 months away from that being this year too) - if we take the viewpoint they are investing to grow it really does look like this has potential to ramp up that 5 eps number quickly if sales take off and flow through to the bottom line. It is all a bit opqaue though payment processing and data anslysis etc and i do have doubts about their moat - i dont normally invest in early stage tat this does seem to have some attractions i must admit in that it seems like it shouldnow be in phase where profits and cashflow should be trending very nicely going forward. In summary it looks like this company may be on the cusp the nice step change into real profits and real positive cashflow
Are there any opinions on Redx Pharma PLC which is on an astral trajectory following a Sunday Share Tip?
Redx Pharma (LON:REDX) - personally the lads could try and put lipstick on a pig, but without specialist aka insider knowledge then if its in the Stock Rank red zone then why waste the time. Get nearer to SR50 then it's not a blind punt.
Paul would be interested in you thoughts on Alumasc (LON:ALU) results
Good morning,
Placing at 450p for Science (LON:SAG), at a premium to last nights close.
CEO selling 2m shares...
Yes, plenty of recent action at Science. As the placing and CEO share sale were at a small premium to the preceding market price, and the CEO still owns over 20% of the company, I don't feel worried by these developments but would welcome any other comments. It makes sense to do the placing and CEO share sales at the same time but I note that the CEO had to get permission to sell his shares just a few weeks before the relevant lock-in period expires so I wonder if there is an element of urgency with the placing (to do with Sciences accelerating acquisition activity?). Perhaps the press release was also hurriedly written as it says the CEO gave the lock-in undertaking on 30th September 2021!
Northbridge Industrial Services (LON:NBI)
Anyone know why the shares went up 16% just now?
Northbridge Industrial Services (LON:NBI)
ST has tipped them in the Chronic Investor Alpha publication.
Northbridge Industrial Services (LON:NBI) - lots of fingers in oil and defence my current interest points (I'm the contrarian ESG :), but maybe when the moving averages start to take off over 200p then worth looking into.
Gamma Communications (LON:GAMA) down 6% odd today. Figures look quite good on first glance with revenue and profit before tax up 23% and 24% respectively compared to the same period last year. However digging down organic growth looks slightly lacklustre; in Europe - growth looks roughly flat compared to last year when ajusting for the acquisitions, 9% in the UK isn't exactly shooting the lights out either. Given the fairly high rating this company is on - fwd P/E of 35, I'm not surprised by the market's reaction.
I am receiving invites to Stockslam, which is great don't get me wrong. Quite frankly an invitation to anything is quite welcome. However I am not intending to attend. I find that the market has just dried up with opportunities. I am a bit prone to being convinced by a good story and I need not to buy any stocks at present. I want reality to catch up with the prices. So that is the only reason I am not attending, full in knowledge that if a great opportunity is out there Stockslam will help you find it.
Thanks for the reminder, I just signed up. I hear what you are saying but there are still opportunities out there, they are just much harder to find. I sold out of a few positions in the last couple of weeks to build some money for the eventual crash but someone could have said we have been due one for the last 5 years (excluding the COVID crash.)
If I see something I live but feel its too hot I tend to just put it on a watchlist and see if it becomes more attractive later. Sometime it does and sometimes it just carries on marching upwards.
That's why I'm struggling with my BBB ISA and SIPP! 50% and 58% cash holdings respectively.
There are still great opportunities though. I took a new position in Appreciate (LON:APP) last month, and this month have taken a position c.13% of my portfolio in gold etf £SGLN
I only hold shares where I have a strong conviction that a 40% gain over a 12-18 month period is possible. To offset inevitable duds and sideways investments, as well as the occasional wipeout and still end up overall up, as long as a fair few of them come good.
Really don't agree with that - I think there are still many great opportunities out there if you look. Lots of good quality companies that are way too cheap - a random selection from my own portfolio includes Harworth (LON:HWG) Scs (LON:SCS) Secure Trust Bank (LON:STB) Saga (LON:SAGA) Phoenix Group (LON:PHNX) Sylvania Platinum (LON:SLP) B.p. Marsh & Partners (LON:BPM) Capital (LON:CAPD) Premier Miton (LON:PMI) Vertu Motors (LON:VTU)
Phoenix Group (LON:PHNX)
Yep the pressure really is now on the CEO to deliver an increase in shareprice and or chomping dividends !!!!!!! - his missus has just splashed out 400k buying shares in the company !!- for his sake lets hope he delivers poor lad as if he didn't have anough pressure running the business!
Maybe she's more patient than you
"Maybe she's more patient than you"
You are deffo quite possibly correct in that regard :)
I agree........am waiting for a few of them to pop as well. Looking at their fundamentals and ongoing TU's many of them seem ripe for a rerate. The big unknown is the impact of the shipping costs & delayed products and the lost chips. Hopefully mitigation plans will mean the CEO's have done their homework and all will be OK.
Ra International (LON:RAI)
Ref todays sweet contract win i must point out the following
this contract is joint venture.
the award of a significant new contract in a joint venture with ECC, the US based global construction and environmental remediation contractor.
The award is split between 5 awardees with "RAI and their joint venture partner combined" being treated as 1 out of the 5
five year contract for design and construction services supporting their base on the island of Diego Garcia in the Indian Ocean. The contract ceiling for this award is USD 249m and RA International and ECC will compete for individual task orders with four other awardees.
Ie if this work is split equally between all parties involved the $249 quoted figure would actually be $24.9 mill over the 5 years by my clacs!!! - 1/2 of 1/5 and wee all know of means multiply by (try doing a half divided by a half in your head peeps)
No details of any splits have been provided so any splits are completely unknown until company gives us more of a clue.
Todays results don't say much - looks like there is further asset w/off coming later in year ref mozambique - if i am being honest i was probably expecting higher exceptional costs ref mozambique bearing in mind the abrupt halt of this huge contract - so they seem to have managed downside well (or kicked it down the street at interims!)
I have today sold out of my holding , i think the short term outlook here isn't great and the price has done well to stay over 60p this morning (sell price) . To me this was always something of a risky speculative investment - its not expensive particularly based on expected 2022 numbers but it used to be dirt cheap so 75% plus gain from my start price is pretty good result and i am happy despite suspicion i should be hanging around for teh long haul having toughed it out through covid. I would say i am not particularly negative here - i would have been happy to hold but i just feel at present there may be short term weakness in price short term and am happier jumping ship to redeploy funds elsewhere - when i jump ship shareprice normally does well when i have left the building so probably good news for holders that i am gone.
Another acquisition by Marlower at circa 5 X adjusted EBITDA. This should be value creating giving how Mr Market values their earnings within the Plc.
Another for Luceco (LON:LUCE): if you have time fellas.
Re Concurrent Technologies (LON:CNC) one should add that Lord Lee gave it a good airing at Mello last night. He has follwoed the stock for years, and now holds again. He laid great emphasis last night on the arrival of a new CEO.
Re CNC. Not only is Lord Lee a committed shareholder, he is a very useful ally with 71% of revenue being supplied from defence. 'From time-to-time the member receives hospitality from the All-Party Group for Defence and Security which over the course of a calendar year exceeds the registration threshold.' Partner status with Intel is also a cherry on the cake. The results are always worded cautiously, despite that the dividend and cash balance have been on a steady upward trend for years.They make record order books sound like an impingement. The shares can be quite illiquid at times, and that causes some volatility as with most small companies. Its taken a good 12 years to become a 5 bagger, but a lot more solid than a bank or oil major. Security and defence are not issues that are going away sadly.
Re Concurrent Technologies (LON:CNC) one should add that Lord Lee gave it a good airing at Mello last night. He has follwoed the stock for years, and now holds again. He laid great emphasis last night on the arrival of a new CEO.
That's all well and good, but in the short-term there is no revenue growth and the warnings about possible lack of components is concerning. Already this has caused sales to slip into the next FY. It's one I have been watching closely as I like the company but I have been wary of buying in due to the downward trend in margins and ROCE - not something I like to see. Hopefully, something the new CEO can fix.
All the best, Si
Parsley Box (LON:MEAL)
I really can't see anything to like here.
Sales seem ridiculously anemic with H1 sales up only 6% on h2 2020 if my calcs are right. I wouldnt normally use sequential 6 months periods but it is useful indicator in fast growing businesses IMHO. Ok there probably is some seasonality at play here that is unknown.
Company however seem much more upbeat than me so my ramblings possibly are of the madman variety - i would say the positive vibes don't appear to come atached with any useful numbers despite July and August being done and dusted. Here is the glass firmly full opinion though.
"Our business continues to see rapid revenue growth and adjustments to the blend of marketing channels are delivering positive momentum on new customer recruitment."
The move into chilled food leaves me feeling somewhat cold - are old bods really gonna pay £4.50 for delivered chilled meal when they can get full choice from iceland for half the price delivered free with larger portion sizes.
Nothing seems to stack up here - it simply doesnt look like they have high enough sales growth to get to "decent" profitability fast enough without having to dilute. Looking at the shareprice its a rare occassion where Mr Market actually seems to agree with my thoughts looking at the shareprice decline.
Nothing is lost though if they can keep lid on costs keep sales growing and get cashflow positive that would give them sold base - looking at the stocky numbers it appears that before today they expected to deliver profits for 2022 of £0.9 mill and sales growth of 37% for that year (wowsers that doesnt sound so bad does it) - i see didly squat evidence this expectation will become reality based on this 6 month period. My suspicion is that if they want to grow that fast next year it will come at heavy price to the bottom line numbers - and its mcuh easier to sell stuff if you sell it below cost price lets be honest !
I agree with your analysis, wasn't convinced about this company when they first floated. Such a competitive industry for starters, M&S also were offering similar no-chill meal types but i've not seen them in recent months, maybe they weren't selling? The chilled food option calls into question their original USP, which was no-chill food?
So now they're competing with with all the big players with their 'premium chill meal' option. Premium being £3.99, can't be that premium really can it?
Just not impressed by this company at all i'm afraid!
what do you guys think of Vistry (VTY) that released its update today?
Vistry (LON:VTY) - builds houses on low margin and large cap. There is money in them their hills but I just can bring myself to buy into housebuilders. Morgan Sindall (LON:MGNS) warming to.
Ra International (LON:RAI) in line for H1, but as Mr Contrarian notes below, the big news is the new contract from the US navy Facilities Engineering Systems Command Far East for $249m but looks like it needs a little explaining. Management will present H1 results and answer questions in an #RAI webinar tomorrow 8.9.21 at 10am. Join here.
The other webinars this week are:
The Stockopedia/PIWORLD StockSlam tomorrow 8.9.21 at 6-7.30pm. Join here.
Pebble (LON:PEBB) H1 results Thurssday 9.9.21 at 1pm. Register here.
Further September webinars for Somero Enterprises Inc (LON:SOM), Property Franchise (LON:TPFG) & Litigation Capital Management (LON:LIT) can be found and registered here on the PIWORLD events page.
Finally, we've had lots of positive feedback to the Beginners Guide to Mining Stocks by Richard Greenfield with a deep dive into Trident Royalties (LON:TRR) Shanta Gold (LON:SHG) & Capital (LON:CAPD) Well worth a listen/view: Video & Podcast.
"The Group has a long track record of outperforming the market." This is the opening statement in the interim results from Luceco (LON:LUCE) Luceco today ( I hold )and the results support the statement - would be interested in your view .
Full year results out for Alumasc (LON:ALU) . Look pretty good with a slight beat for EPS against recent update July forecast (23.7p vs. 23.5p).
https://www.investegate.co.uk/....
Share price has retreated a little bit of late. Some comment on supply issues (material and labour shortages, increased freight costs) but generally pretty upbeat. Also comment on favourable development in pensions deficit position due to rising gilt yields/investment returns but no figures given.*
Gus.
* Just seen in the footnotes, details given on the pension deficit. c.£14.7m positive swing due to increased portfolio value/reduced liabilities.
Jack - would you have time to review Alumasc (LON:ALU) and Sylvania Platinum (LON:SLP) today, please (I hold both)?
My morning smallcap tweet: Untangling the City's intestines
Ra International (LON:RAI) Blackbird (LON:BIRD) Ted Baker (LON:TED) Gaming Realms (LON:GMR) Renew Holdings (LON:RNWH) Parsley Box (LON:MEAL) Michelmersh Brick Holdings (LON:MBH), McBride (LON:MCB)
RA International (RAI) significant new JV contract from US Navy. "5 year contract for design and construction services supporting their base on the island of Diego Garcia in the Indian Ocean. The contract ceiling for this award is $249m and RA International and ECC will compete for individual task orders with four other awardees. " [SP=60 Cap=103m]
Blackbird (BIRD) a global broadcast company has licensed core video technology for 5 years. "This is the first OEM licensing deal of its kind for Blackbird and is worth an expected minimum of €2m." A thrilled CEO says ""We are thrilled." [SP=33.92 Cap=115m]
Ted Baker (TED) Q2 rev in line, significant improvement in full price mix. Trading margin up over 500 bps. "It is still early days in the recovery, but we are confident that Ted is starting to emerge from Covid a stronger and more resilient business." [SP=166.04 Cap=307m]
Gaming Realms (GMR) first Slingo game has now gone live in Pennsylvania with BetMGM. More games scheduled to follow shortly. Will apply for Ontario iGaming licence. "Ontario, Canada, has announced its intention to become a regulated iGaming market which is expected to be larger than any of the regulated U.S. States which currently allow iGaming." [SP=34.8 Cap=100m]
Renew (RNWH) guides FY adj op profit at least £50m (forecast £45.8m). "Activity levels are supported by long-term regulatory spend and the positive outlook for UK infrastructure." [SP=793 Cap=624m]
Parsley Box (MEAL) H1(June) rev up 26%. Pretax -£5.4m (-£1m). Op C/F -£4.6m. Net cash £6.2m. Outlook "Higher price point and new product range expected to deliver further growth in H2".Fundraise on horizon? [SP=119 Cap=50m]
Michelmersh Brick (MBH) guides FY profit modestly ahead of exp. H1(June) rev up 10%, EPS up 23% on 2019. "Alongside this positive outlook we remain watchful of some of the broader risks impacting our sector and the UK economy and we continue to see the potential for disruption to our labour and haulage availability and wider inflation risks. As a result, we expect our profit to weight moderately towards the first half." [SP=145.95 Cap=138m]
In line: McBride (LON:MCB)
Great trading update from Renew Holdings (LON:RNWH) (I hold):
Continued strong trading; full year performance expected to be ahead of current market expectations
Morning Chaps - would be grateful for your views on £LUCE. Thanks very much, Chris.
Good morning, Paul
Interim results from Bango (LON:BGO) out today. I believe real progress is being made in the EUS and customer base.
It would be nice to hear your thoughts.
looks like it’s starting to become cash positive now which is a real turning point. If it can start to self fund it’s growth then it can takes away and further fund raising
small cap Concurrent Technologies (LON:CNC) (Interim Results for the six months ended 30 June 2021) and mid cap Iqe (LON:IQE) (2021 Interim Results) reported this morning some news worthy of consideration here surely.
It's been said many times, but bears repeating.
Why not point out what about these results is worthy of attention? I am sure the guys look at a list of who is reporting today. If you would like coverage a little steer about why would be helpful.
Absolutely - if you want something covered it is up to you to make a persuasive case as Paul has said on many occasions. Obviously Paul and Jack have finite time and have to be selective.
Hi Paul. Would value your thoughts on the interim this morning from Parsley Box (LON:MEAL)
Thanks in advance