Small Cap Value Report (Tue 8 Oct 2024) - IGP, SNR, VTY, SUS, LGRS

Good morning from Paul & Graham!
That's it for today!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
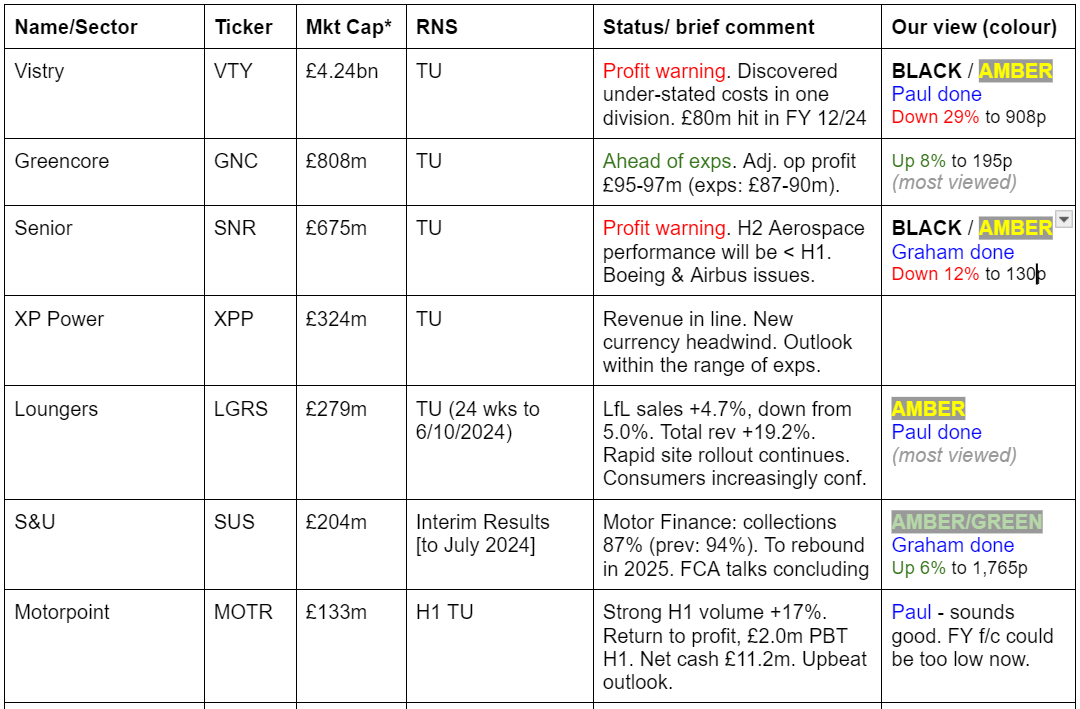
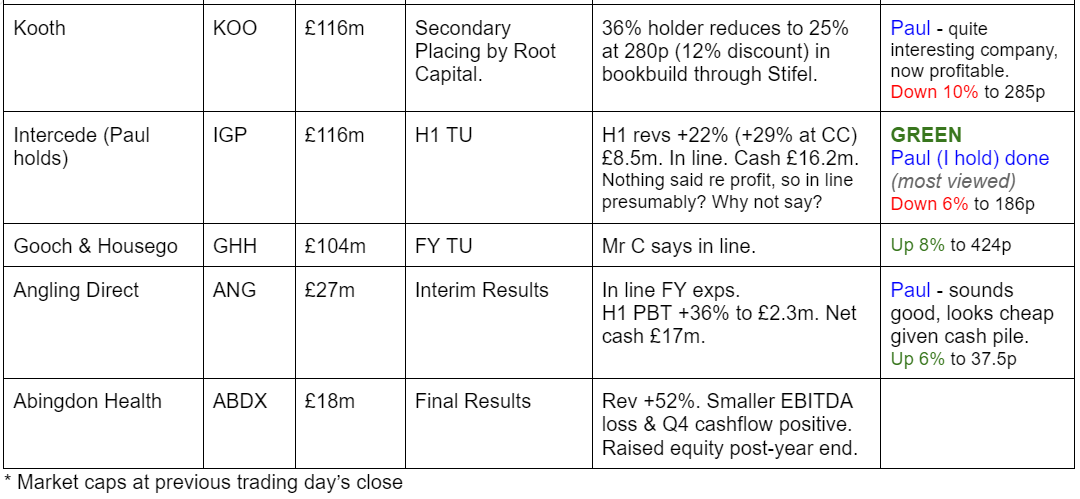
Summaries
Intercede (LON:IGP) (Paul holds) - down 9% to 180p at 08:23 (£106m) - Trading Update - Paul (I hold) - GREEN
A vague update today that only mentions H1 revenues (up 22%), not profits. Slightly disappointing, in that I had hoped for an ahead of exps update today, given the strong newsflow. Although Cavendish make it clear that beating exps in H2 looks likely. Plenty of cash. The growth story looks one of the best in the UK market, in my view - hence why I own this personally.
Senior (LON:SNR) - down 13% to 128.2p (£538m) - Trading Statement (profit warning) - Graham - BLACK / AMBER
I’ve been caught out here as I thought the valuation at c. 150p was interesting earlier this summer. However, problems at Boeing and Airbus have damaged the short-term outlook at Senior’s Aerospace division. The problems could be fixed by next year, but a neutral stance appears most sensible now.
Vistry (LON:VTY) - down 29% to 910p (£3.01bn) - Trading Update (profit warning) - Paul - BLACK (PW) / AMBER on fundamentals.
Bombshell announcement of an £80m black hole at its Southern division, due to 10% understatement of costs. Raises a lot of question marks now over the reliability of group-wide financial control. But a 29% share price fall could be creating a buying opportunity for this well-financed, and successful housebuilder. I need more information to firm up, so am sitting on the fence for now, whilst being tempted to have a little trade for a bounce on it, I must admit!
S&U (LON:SUS) - up 6% to £17.54 (£213m) - Interim Results - Graham - AMBER/GREEN
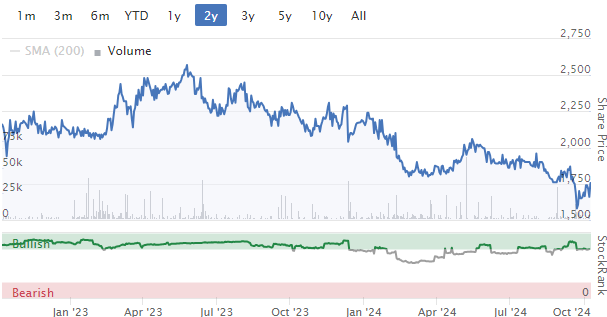
I’m bravely giving this an upgrade to AMBER/GREEN as it appears that talks with the FCA may at last be concluding. Perhaps it’s a risky call but these shares are trading below net asset value (£233m) when they previously traded at a substantial premium.
Loungers (LON:LGRS) - up 3% to 274p (£284m) - Trading Update - Paul - AMBER
An annoying trading update that doesn't tell us how it's traded relative to market expectations, but in other respects sounds positive. LfL revenues have fallen slightly, but are still well above inflation. Rapid site roll-out continues. I think it's a good business, but in a tough sector. Shares are too pricey to interest me, and I think JDW (I hold) is better value for money, both the shares and the products!
Paul’s Section:
Loungers (LON:LGRS)
Up 3% to 274p (£284m) - Trading Update - Paul - AMBER
Loungers, a leading operator of all-day café/bar/restaurants across the UK under the Lounge, Cosy Club and Brightside brands, today announces a trading update for the 24 weeks ended 6 October 2024.
Continued market-leading like for like sales growth, and 17 new sites opened during the period
This is another “trading update” that ignores the key requirement that investors have - to be told whether or not it’s trading in line with expectations!
We’re left to deduce what’s going on.
I note that the analyst consensus graph on Stockopedia shows forecasts for both FY 4/2025 and 4/2026 has been trimmed by 4-5% since June, so maybe that’s why they don’t want to directly confirm market expectations - instead quietly reducing expectations in the background, and then no doubt meet/beat the lowered forecasts in early 2025?
Is that deceitful, or just good expectations management? That’s up to you to decide, I’m just pointing out the facts we have available -
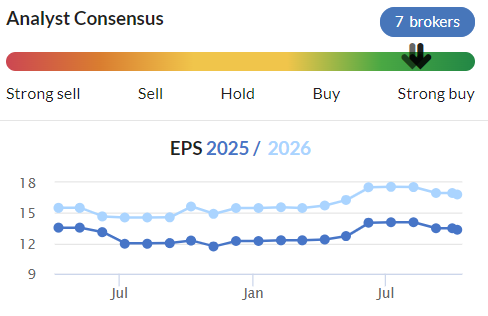
Broker notes - from Panmure Gordon and Equity Development are available to us today, very helpful.
Both have similar forecasts, of 11.7p and 11.2p for this year, FY 4/2025. Strangely this is well below the consensus figures above, of 13.3p, which means the PER is actually higher than the Stocko figures. I’ll go with the specific broker numbers today, so at 274p we have a PER of 24x the average of the two broker forecasts. That strikes me as much too high given this is a horrible sector, although LGRS does seem to be regarded as best in class operator, and is quite rapidly expanding through its self-funded roll-out of new sites.
The other bull point is that margins are improving, and LfL revenue growth is now well above inflation, with some costs moderating, so there’s an interesting case to look at the hospitality sector with fresh eyes, as there could be some operationally geared profit improvements in this sector.
LfL revenue growth YTD has moderated from 5.0% to 4.7%, implying that the most recent 13 weeks was below that, maybe nearer 4%? That’s enough anyway I think, given that general inflation is now low at c.2%.
Total revenue is up 19.2%, reflecting all the new sites it’s opened.
“Loungers has opened 17 new sites during the period (H1 FY24: 16 new sites), taking the total portfolio to 273 sites as at 6 October 2024… A further 18 sites are scheduled to open in H2, continuing the increased roll-out programme following the 36 new sites opened in the previous financial year.”
I’m not aware of the total market potential for LGRS, but by way of comparison, cheaper competitor JDW (I hold) recently reported having about 800 UK sites, and sees potential for c.1,000. So I suspect LGRS potential size is similar, meaning the ultimate size might be about 4x its current size, which certainly makes it an interesting investment proposition.
Consumer confidence comments are encouraging -
“From what we are seeing across our sites, UK consumers are feeling increasingly confident and want to go out and enjoy themselves across all parts of the day. That confidence, combined with the variety, breadth, flexibility and relevance of our all-day offering, is reflected in our continued sales success."
Non-property net debt of £12.2m is modest, almost negligible given the good cashflows, so no issues there. Although its claimed “strong” balance sheet only has c.£42m of tangible net assets, unlike a lot of bar operators which own their freeholds (but have hefty debt usually), LGRS does not - it leases property. Capital-light, and more flexible, but leaving them subject to rental increases out of their control when rent reviews happen maybe? Personally I much prefer lots of freeholds, and hedged debt (as JDW has structured itself - I hold).
Paul’s opinion - I still baulk at the valuation. LGRS looks a good business, but in a horrible sector, where it’s very difficult to make money. Eg the ED note shows it's forecast to make only £16.1m adj PBT this year on revenues of £402m, only a 4% margin. Although it hopes this could rise to 5.1% by FY 4/2027. There should be some economies of scale from purchasing more keenly, especially from breweries, as more sites open and purchasing volumes rise, so that sounds credible to me.
ED forecasts big increases in EPS from 11.2p this year, to 14.8p and 18.5p in subsequent years. Although at 274p/share, I’m being asked to pay 14.8x the forecast profits 2 years in the future! Whereas I can buy better funded JDW on 14x this year (FY 7/2025) forecast earnings, and get much better tangible asset backing, and recently reintroduced divis. Although slower growth.
On balance then, I’m happier holding JDW, as I’m getting value for money today (a bit like its meal + pint deals at £10.37!). I’ve mystery shopped several LGRS sites, and they’re nice, but nowhere near the value for money at ‘Spoons, albeit with a different customer base - probably people driving BMW 3 or 5 series, whereas 'Spoons customers are more likely to be driving a Transit, or catching the bus!
Conclusion - LGRS is clearly a good business, in a tough sector, but I don’t think the shares offer enough value to tempt me in, in a market which regularly throws bargains at us right now. AMBER again.
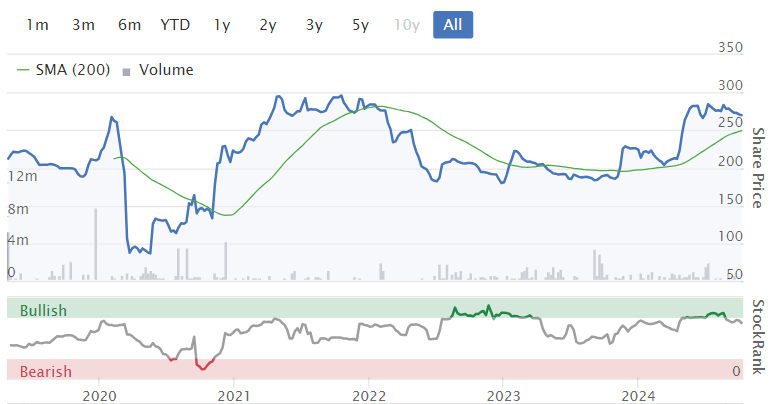
Since listing - all those new sites opened, but no shareholder value created -
Vistry (LON:VTY)
Down 29% to 910p (£3.01bn) - Trading Update (profit warning) - Paul - BLACK (PW) / AMBER on fundamentals.
A bombshell announcement from this leading housebuilder, which has a differentiated business model of building houses in partnership with typically public sector organisations - very much a positive thing in my view, as it hasn’t been impacted by the last 2 years’s slowdown in the private housing market.
Summarising today’s bombshell -
Accounting problems discovered at its South division.
Affects 9 out of 300 (total company) developments, but some are large-scale.
Build costs understated by c.10%.
Profit hit £80m FY 12/2024, £30m FY 12/2025, and £5m FY 12/2026.
Revised adj PBT guidance of £350m FY 12/2024.
“We believe” that problems confined to South division, and mgt changes underway.
Independent review launched to “fully ascertain the causes”.
It reassures on other matters -
“The Group continues to expect to deliver total completions in excess of 18,000 units in FY24 and continues to target a net cash position as at 31 December 2024 (31 Dec 2023: net debt £88.8m). The Group remains committed to the £130m share buyback programme announced on 5 September 2024.
The Group is confident in its unique Partnerships strategy. Notwithstanding the one-off adjustment announced today, we remain committed to delivering a strong increase in high quality mixed tenure housing, our medium-term target of £800m adjusted operating profit, and £1 billion of capital distributions to shareholders."
Valuation - given that new adj PBT guidance is £350m, and it says the impact of this “one-off” understatement of costs is £80m in FY 12/2024, then that presumably means previous guidance was £430m adj PBT. I don’t have access to any broker notes, old or new, so private investors are really disadvantaged in assessing situations like this, whereas the city will get better information from analysts that of course have access to the company that we don’t. Hence why in situations like this, I tend to assume that people selling in the market (especially larger trades) probably know more than me, so it’s risky to do the opposite and buy the dip, without full information.
Given that the above implies a c.19% drop in FY 12/2024 adj PBT, and assuming the same percentage applies to EPS, then I make that a drop from c90p forecast EPS, to c.73p.
The trouble is, they say this £80m profit hit is a one-off, to correct previously understated costs. So I’m not sure what EPS figure we should base our valuation on. 73p is the best guess I have, so that would mean a PER of 12.5x based on today’s lower share price of 910p, which sounds about right to me.
Accounting problems - these can often linger for several reasons. Trust in the whole accounting function is badly damaged by this type of revelation. The job of the central finance team is to pore over the details, and make sure that the individual divisions are getting their numbers right. So £80m of costs slipping through the net without the division or the central finance teams correctly accounting for them is a big deal.
How much financial control is there generally in the group? It sounds to me that it’s clearly not good enough.
We’re told the problems are confined to just the South division, but how do we know that? Lax financial controls tend to be group-wide in my experience, and the central team failed to correct these errors or misstatements previously, suggesting to me that there could be wider problems here. But we have no idea, it’s purely guesswork. I would rather wait until the full review has been completed & reported to the market. Very often other things come out of the woodwork when a bigger review is done.
Paul’s opinion - I previously liked this share, and explained why my view was GREEN on 9/7/2024 - based on it putting out positive trading updates, and completely shrugging off the downturn in the wider sector. Also there has been fabulous growth at Vistry, and its business model is clearly excellent.
Compare this track record below with other housebuilders! (although the forecast net income blob for FY 12/2024 will come down to a similar level to the previous 3 years after today) -
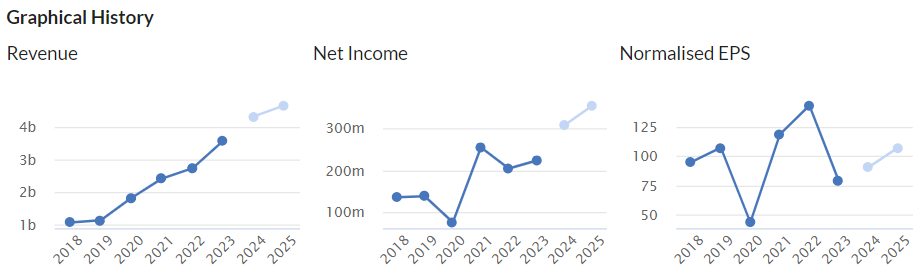
VTY was valued at a price to tangible book of 2.0x. By my rough calculations that should now fall to 1.42x, making it a lot more attractive on an asset value basis.
The forward PER is also reasonable, as calculated above.
Yet we have further downside risk, if this substantial costing error turns out to be a wider problem.
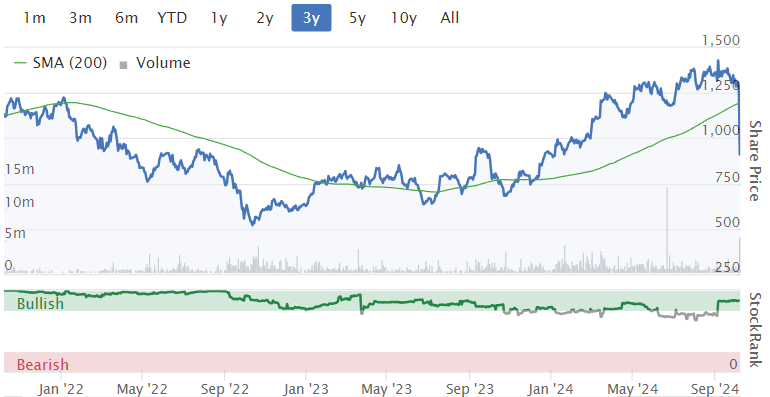
Therefore there’s considerably more guesswork now in valuing VTY shares. It’s up to you to decide if the 29% drop today is excessive, or fair? I would argue that it only takes shares back to their Jan 2024 price, so maybe the bull run this year was overdone?
Given I don’t have enough information, and there’s guesswork involved, I’ve got no choice than to move down to AMBER for now. We could consider moving up again at a later date, once the situation becomes clearer.
Although it is also quite tempting to jump in with a little trade here too, in case there’s a bounce!
Three-year chart picks up today's big fall to c.910p -
Intercede (LON:IGP)
Down 9% to 180p at 08:23 (£106m) - Trading Update - Paul - GREEN
“Intercede, the leading cybersecurity software company specialising in digital identities, today announces the following trading update for the six months ending 30 September 2024 (H1 FY25).”
This is not really a trading update, since it only mentions revenues and cash, but not profits. There are several other companies today which have done something similar, so I hope this is not the start of a trend where the key information that we need (are profits in line with expectations or not?) is dodged. Doing this is counter-productive, as it introduces doubt in investors' minds.
H1 revenue growth has been strong, +22% (+29% at constant currency) to £8.54m -
“This is in line with management expectations.”
Given the strong newsflow of contract wins & renewals this year, I was initially disappointed that today’s update is not ahead of expectations.
However, an update note from Cavendish gives useful extra context, saying that “FY 25 forecasts should be comfortably achievable”, and that each contract win/renewal announcement de-risks the forecasts, making it more likely that IGP will meet or beat expectations later this year - the same pattern it delivered last year.
FY 3/2025 forecast is £16.1m revenues, and £3.0m adj PBT. This is down on FY 3/2024, which benefited from a large, one-off contract win late in the year.
So achieving £8.54m in H1 means that H2 now only needs to deliver £7.56m. Given that IGP is clearly on a roll, with frequent contract wins, and a successful strategy of selling through channel partners, then I reckon it’s well set up to beat forecasts later this year. That’s a key thing I look for - companies that look set to beat forecasts, rather than promising us an H2 weighting in order to catch up (often a deferred profit warning).
So slight disappointment that we didn’t get an ahead exps update today, but I think it’s likely one is in the pipeline, all being well.
Valuation - is lofty, but that’s because IGP is a credible growth company now. Forecast is 4.2p for FY 3/2025, likely to be beaten, so I’ll go with 5.0p EPS as more likely. At about 180p (down c.9%) in early trades, that gives a PER of 36x - which is quite high, but far from outrageous for a high margin growth company.
Cavendish mentions that IGP tech is best in class. Plus a reminder from me that IGP’s markets are global, reference sites are second-to-none with an astonishing existing client list including numerous US Govt Depts, and some of the world’s largest companies. Demand is also increasing, due to concerns over cybersecurity and the weakness of simple passwords, so online credentials management seems a great growth area to be operating in.
I see a lot of potential in IGP, for a not very expensive £116m market cap. It’s already profitable & cash generative, and has plenty of cash at c.£16m and no debt.
H1 results are due out on 26 Nov 2024.
Paul’s opinion - unchanged. I see a big opportunity here, and so far it’s working out very well indeed.
Today’s update could have been stronger, so I can understand why some short-termers might be banking profits today.
More patient investors should do fine on this share I think, because it’s clearly set up for more positive newsflow in H2.
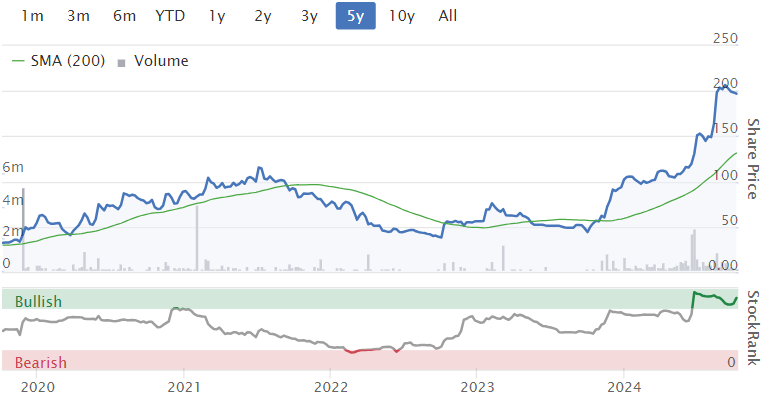
Shares have 4-bagged in the past year, so some profit-taking & consolidation is probably necessary in the short-term.
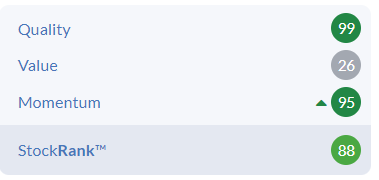
Summarised well by the StockRanks - very high quality and great momentum, but not a value share!
Graham’s Section:
Senior (LON:SNR)
Down 13% to 128.2p (£538m) - Trading Statement - Graham - AMBER
Senior plc ("Senior" or "the Group"), an international manufacturer of high technology components and systems, principally for the worldwide aerospace & defence, land vehicle and power & energy markets, today issues this Trading Update for the nine months ended September 2024 (the "Period").
We don’t cover this one too frequently but in August I was AMBER/GREEN at 150p, after some weakness in the share price created a more tempting valuation.
That share price has however dropped lower today after some bad news: the Aerospace division continues to meet complications in its dealings with the major aircraft manufacturers and their suppliers.
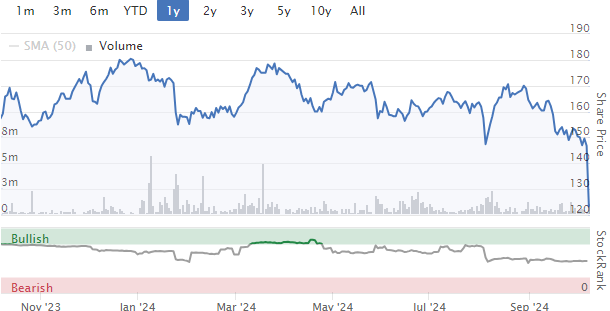
Boeing was already a source of difficulty but now Airbus is proving to be a challenge, too.
In the near-term… as has been extensively reported, the commercial aerospace manufacturing industry is facing temporary but significant headwinds.
Boeing: production rates of the 737 MAX have been restricted after the Alaskan Airlines incident early in 2024. Additionally, there is a current employee strike at a commercial aircraft site
Airbus: facing supply chain challenges, particularly on engines and interiors. There’s an “imbalance of supply into different parts of the aircraft”. One of Senior’s customers, a supplier to Airbus, intends “to significantly reduce scheduled deliveries from Senior in Q4 of this year before returning to normal during Q2 next year”.
Senior is responding in what sounds like a highly proactive manner to these difficulties: there are furloughs and permanent headcount reductions, spending cuts, postponed capex, etc.
Separately to the problems in the Aerospace division, Senior’s Flexonics division has seen no major change in its outlook since the interim results.
Other key points:
Group revenue +5% year-to-date, driven ironically by growth in Aerospace.
Outlook for the full year is “broadly unchanged” for Flexonics. In Aerospace, H2 will be lower than H1.
The issues facing the company are “clearly temporary in nature”
Graham’s view
My upgrade to “AMBER/GREEN” here was clearly a mistake. I’ve had a positive impression of Senior for a long time and so when I saw it trading at what seemed to be a level that offered value, my instincts were to take an interest in it.
As far as today’s disappointing news is concerned, I tend to agree with the company that the problems it currently faces are temporary. Strikes and supply chain challenges come and go. They do however serve to emphasise the challenging markets in which Senior operates. As I’ve pointed out before, Senior has struggled to generate a double-digit ROCE and maybe the simplest explanation is that it’s difficult to generate very high returns when a large part of your business is supplying components to Airbus and Boeing.
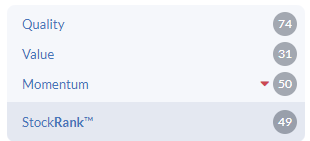
The StockRanks are completely neutral on this one and given that I’ve been caught out by today’s profit warning, I’ll defer to them for now and go back to a neutral stance.
S&U (LON:SUS)
Up 6% to £17.54 (£213m) - Interim Results - Graham - AMBER/GREEN
S&U, the specialist motor and property financier, today announces its results for the six months ended 31 July 2024.
This is another company I’ve been a fan of for many years, but where I downgraded my view after the FCA started taking an interest in its forbearance practices.
The effects of this are visible in today’s financial results. Here are some of the headline numbers:
H1 revenue £60m (H1 last year: £55m).
H1 net income: £12.8m (H1 last year: £21.4m).
And in the motor finance division (“Advantage”) specifically:
PBT £9.4m (H1 last year: £19.1m)
Collection rate: 87% (H1 last year: 94%).
Impairment charge: £18m (H1 last year: £7m).
In S&U’s property bridging division, revenues and profits were both up strongly, from a small base.
So the decline in overall profitability is all down to the motor finance division, with that large impairment charge standing out as the culprit.
I have all the time in the world for Chairman Anthony Coombs, and look forward to his reports. Here is some of what he had to say about the difficulties in Advantage Finance:
On the initial basis of only 10 customer files, a s166 notice (swiftly followed by adoption of "voluntary" restrictions) has significantly constrained Advantage's ability to interact with and manage its traditional customers, with whom it has happily worked for the past 25 years. Strong Trustpilot ratings, an industry-leading uphold rate with the Financial Ombudsman Service and a long record of profitable trading with over a quarter of a million customers historically are evidence of this record. Successful repayment programmes, access to credit and improved credit ratings for these customers have always characterised Advantage Finance.
Happily, patient explanation, better documentation and retraining have now produced a more consistent and stable balance between the FCA's requirements for customer protection and the commercial risk and reward of supplying motor finance.
I note again that yet another public company is using its Trustpilot (LON:TRST) ratings as a key metric that it wants to highlight to investors!
Today’s report doesn’t provide any clear timeline in terms of when the ongoing regulatory intervention might cease, but the Chairman does say: “As negotiations with the Financial Conduct Authority conclude, this hiatus in performance is expected to prove temporary and a rebound anticipated for 2025.”
This wording has changed from previous statements. In August, negotiations were “nearing their conclusion”. In September, they were “actively pursuing a conclusion”. And now, it seems that negotiations are at last concluding!
Funding
S&U was always exceptionally well-capitalised, but its gearing has soared in recent periods. Gearing (the ratio of borrowings to equity) is now over 100%, as net debt of nearly £240m exceeds equity of £233m.
For comparison, gearing was 85.5% in January 2023, and only 55% in January 2022.
The company describes this as “continued relatively low gearing” but I’m not convinced that this is true relative to its own historic track record.
And not only is gearing much higher than before, but the company has used up most of its banking facilities - its total facilities add up to £280m. It says that it has “ample headroom” and that “facilities will be supplemented if required”.
Compared to the rest of the industry, I don’t think S&U are taking unusual risks with their balance sheet. But by their own high standards, the current situation strikes me as unusual.
First dividend will be 30p (last year: 35p).
The Outlook statement includes the following quip:
Appropriately, the last word should therefore go to Harold Wilson, Labour PM in the sixties. "I'm an optimist" he said, "but I carry a raincoat". Accordingly, we embrace the future with our usual cautious optimism.
Graham’s view
This is going to move in the opposite direction to SNR today. I’m going to stick my neck out and suggest that this is worthy of an AMBER/GREEN stance.
As I’ve said before, I believe that S&U/Advantage is a responsible lender, both objectively and by reference to other motor finance lenders. I accept that there’s a lot of scepticism in the comments when it comes to Trustpilot ratings, but for what it’s worth here again is the link to Advantage’s Trustpilot page.
These shares are now trading below book value - something they didn’t do for a long time. Perhaps the FCA intervention will have a lasting effect, and it no longer deserves to trade at a premium. But this is a family-run business with a terrific long-term track record, and I doubt that it did anything terribly wrong. So I’m interested in it again here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
JASVFS, one of the few things I like more than trading is fishing. I don't think I've ever bought anything from Angling Direct tho, I'm interested in fly fishing and it's not really the place you'd go to for that.
I've seen so many angling shops close over the years it always seems a tough gig to make money. At least being online it won't be full of old guys drinking coffee all day not buying anything tho, and the large cash pile is nice.
In the past if I had a decent week trading Id buy a treat for the wife,kids or myself (ok it's normally myself) just to keep my interest up. I went through a phase of buying a new fly rod every few weeks until I had a cupboard full. I only ever use the same 2 so it was all a bit pointless, but even my buying spree wasn't enough to prevent the local shop closing.
Litigation Capital Management (LON:LIT)
Wondered why these spiked. Huge win close to $0.5bn : assuming they can recover it then this has got to be worth some $40-50m to Litigation Capital Management (LON:LIT) once you factor in the proportion of their own balance sheet investment and fund performance fees. That’s almost a third of the market cap on one case alone.
Thinking of Monday 7th October RNS for Beeks Financial Cloud (LON:BKS) which I don’t hold but am interested in, I wonder if over-optimism is pushing the share price too far. Could Beeks share price be riding for a fall? This is the Bollinger chart below:
Interactive Investor sees things this way:
This is how things stand today and since there is no moat according to ii and being speculative the future share price moves are an unknown IMHO.
Unfortunately ii doesn’t really know what it’s talking about Silvermoon
There is a very clear economic moat for Beeks Financial Cloud (LON:BKS) : exchanges rarely change provider to something unknown if there is something that is proven and works. It’s a very big moat and revenues tend to be super sticky so clearly this is an algorithm that doesn’t understand the underlying business.
Where the price goes who knows but critical infrastructure to financial services like these tend to trade on 30 to 40 PERs so at 6p adj eps that’s not particularly rich. If they hit existing forecasts and add in something from the Nasdaq contract then 1 year forward will be looking at 10-15p eps so I can make a case for anywhere between 200p and 600p over next couple of years which is pretty wide!!
But as we all know shares drift up and down quite considerably over the course of the long term picture so who knows if you’ll get a better entry point if patient. I waited with Marks and Spencer (LON:MKS) for what felt like an age for it to drift back to 240p but picked some up there and pleased I managed that.
Your reply is exactly the kind I was hopeful my question would bring to the fore David so here's my thanks. I was confused about the lack of moat as I was sure I'd read somewhere that there is a strong one so now I'll be keeping some funds on the back burner.
As a likewise 'tea leaf' reader this is now way above mean reversion into overbought territory. Ichimoko tells a similar story with cloud breakout on 12 February and has boomed past its longer term resistance of 200. I like round numbers so see 250 as more sensible. Guessing aside still don't understand what they do and suspect too small for the big sharks to even bother looking at - except when they find out about their new contract ... eek.
Hi HH - this sounds interesting. Which company are you referring to ? Thamksv
Beeks Financial Cloud (LON:BKS) just though maybe get acquired but not suggesting that is a good strategy.
Paul, I love your comparison of Loungers customers to 'Spoons customers..." I’ve mystery shopped several LGRS sites, and they’re nice, but nowhere near the value for money at ‘Spoons, albeit with a different customer base - probably people driving BMW 3 or 5 series, whereas 'Spoons customers are more likely to be driving a Transit, or catching the bus".
Call me pretentious, but my monocle nearly fell out with
with laughter....
Thanks Dieselhead2,
Glad you enjoyed my little joke! One has to be so careful these days to find a form of wording that doesn't "offend" people who secretly enjoy being offended! Also of course I'm a keen 'Spoons customer myself, and I walk to the Mary Shelley, so being given a lift there in a Trannie would be luxury :-)
Cheers! Paul.
MPAC (LON:MPAC) I received approx 7% of my original holding as an allocation for the retail offer, which tallies with the small print in today’s RNS. That compares to dilution of 35% which shows the offer to have been well subscribed. It’s a good trade to sell them today, but I’ll be holding on with keen interest in the company’s progress.
Re Vistry
It might have been more helpful if Vistry had clarified the shortfall by business brand as well as geographical divison ( Southern).
The paragraph at the end of the announcement seems to refer to the Countryside Partnerships brand which is the B to B arm of the business. It is not clear why this brand is specifically mentioned - it looks a bit strange and out of place, as if the press release might have been edited...
"The Group is confident in its unique Partnerships strategy. Notwithstanding the one-off adjustment announced today, we remain committed to delivering a strong increase in high quality mixed tenure housing, our medium-term target of £800m adjusted operating profit, and £1 billion of capital distributions to shareholders."
Investors might want to ask a few more questions before buying the dip.
Vistry (LON:VTY) CEO buy of £200k, shows a bit of confidence, though admittedly not material to his overall holding.
Vistry (LON:VTY)
The difference between a real blackhole and a made up one:
- Vistry find a £80m black hole and the shares moved down 30%. Everyone is concerned that it is the tip of the iceberg.
- Rachael Reeves finds a made up blackhole of £20 billion. The market does not move. No one is the least bit worried about it being the tip of an iceberg.
Your comment is countered by others' previous remarks who have blamed Rachel Reeves for the UK's underperformance. The £22bn is essentially made up of unfunded spending commitments announced by her predecessor - its impact can be seen in the market level of interest rate of Treasuries.
The £22bn is essentially made up of unfunded spending commitments announced by her predecessor
i thought that was nonsense (happy to be provsed wrong) - ie i dont think they denied that £9 bill of that £22 billion came from their decision to dish out public sector pay rises that the tories had not planned. If thats the case the £22 billion is a lie they are sticking too. Note there are always ongoing adjusts ref tax receipts and the like and shortfalls - its par for the course that figures change over time and are not set in stone. So there may be some truth here in them having been shafted but it seems to me like they have lied to make it sound bigger than reality and also pimped up the issue. £13 billion in the scheme of things is really a normal rounding error - she Reeves should know that and deal with it like the rouding error it was - other than perhaps point out some home truths.
hey ho the IFS did warn us pre election
As early as March, after the Spring Budget, the IFS said that “Government and Opposition are joining in a conspiracy of silence in not acknowledging the scale of the choices and trade-offs that will face us after the election”.
https://fullfact.org/economy/l...
Effectively the IFS say that the Tories did indeed effectively try to cover up the £22bn, as the spending was clearly going to be needed or already planned for, but also that Labour (and everyone else) should have known about it, and probably did.
https://ifs.org.uk/articles/ps...
, but also that Labour (and everyone else) should have known about it, and probably did.
well its more than that she created the extra shortfall by awarding the bumper pay increases not planned for- and that was part of the £22 billion - the linked article seems to confirm that its basically a lie here by labour when it says the following.
I certainly don’t buy the idea that the additional £9 billion or so that Reeves has now allocated to public sector pay is part of an unexpected black hole.
I am not entirely convinced its ever right to call unplanned events a black hole - imho the process is what it is and early estimates are only ever that and will need changing - so to me its pretty disingenous calling ita black hole at all. Leaving the kitty bare perhaps . IMHO if they were on then ball they would have flagged up the issues pre election - they had sight of the books could and should have run numbers they were expecting tories to run and then looked smug afterwards perhaps. They chose to ignore all of that despite knowing the score so they could then get elected on a promise they could perhaps not fully keep but then blame the other lot. Standard worst fare you can get. all that mattered at the time was getting elected.
£22bn is about a 1.8 percent error in annual Government spending so, some black hole,
Its a projection that continually needs updating thats the whole point - so it was an adjust of 1% - so 99% accurate. With an extra 0.8% spent on the public sector payrises (labours choice and not black hole) . I think anyone who can estimate within 1% aint doing too bad and a 1% difference is not the mountain that labour are trying to make it out to be - imho , bearing in mind they chose not to look under the cover too much according to articles linked today.
imho its fairly common for swings of £10 billion due to updated news - for example as recently as last month they were handed a £10 billion potential windfall.
https://www.reuters.com/breaki...
Not sure why anyone would have expected no minor issues like this when you have a change of guard - imho its a complete non story that labour are trying to make a story for whatever reason.
lets keep politics off the SCVR please unless DIRECTLY related to something economic/investment... many thanks
To me Vistry (LON:VTY) has moved into the much lower margin contracting world (2/3rds group vs 100% housebuilder B4), and the market has just woken up to the risks.
Which means the valuation multiple will also probably struggle to recover, even when the temporary contract problems have normalised.
I agree with you Paul. My experience is that money is made in shares when profits rise and the market re-rates to a higher multiple; and vice versa. If Vistry (LON:VTY) is going to make lower profits and be re-rated as a contractor then the share price is not going to increase much from today's correction. Will profits be lower? Yes, if costs continue to rise or if they remain static but are underestimated elsewhere in the business. I was looking at the costs of below-ground drainage and ducting components recently and I nearly fell off my chair.
My concern about the whole sector is that the value of land banks may be overstated. In fact I think they are. If I am right there might be some big write-downs to come.
The problems are not temporary if costs continue to rise or if they remain static but are underestimated elsewhere in the business. I was looking at the costs of below-ground drainage and ducting components recently and I nearly fell off my chair
I’m happier owning the supplier end of the trade Alumasc (LON:ALU) Volution (LON:FAN) Genuit (LON:GEN) - particularly when mandated by regulation -than the contractor/builder (insert usual suspects here).
Re Vistry (LON:VTY) , I agree with comments from Paul, Michael and BnB above. I was initially impressed with new management's turnround of Bovis (as it then was) although nervous when big, partly debt fuelled acquisitions became a significant feature. I sold out earlier this year when they confirmed the complete changeover to contracting. As Paul says, it's a strategy of high ROCE (in the good times) at the cost of tiny margins. In my experience, contractors almost invariably end up with some poor contracts which, with tiny margins, too easily tip the company into losses. Vistry's margin targets for contracting looked unrealistic and when you put that pressure on local management, some will fix forecast numbers to win contracts within group margin terms, only to be found out when it comes to delivery, as seems to have happened here. Commiserations to holders but I won't be jumping back in despite the savage price reaction.
PS on Vistry (LON:VTY) post, like BnB, I'm a happy holder of Alumasc (LON:ALU)
All good info thanks guys, I'm close to 10% up on my buy this morning, I think that will do..
I'm a day trader today!
Well, why not - If the market is going to be erratic, take advantage I say
Theoretically, they are trying to become a British NVR- faster asset turn and lighter balance sheet yields higher ROE then you smash all the cash into buybacks to juice the EPS. If you look at the commentary from the US hedge funds involved in Countryside who got rolled into Vistry and the ex-NVR man they got on the board the signs are pretty clear. NVR has been an absolute monster stock, whether the model will translate to the UK is another matter....but, assuming buybacks are a big part of the financial engineering strategy, then depressed multiples are exactly what you want.
Thanks Gmjs, that's fascinating about NVR (NYQ:NVR) and the comparison with Vistry (LON:VTY). I don't follow US stocks so hadn't come across NVR (NYQ:NVR) and missed the link via Countryside. Net income margin at NVR is over 16% which is impressive. I recall that when I was involved in contracting many years ago, there was a company called Biwater which consistently made good money from contracting for the water industry (unlike our subsidiary!) but it was private and owner-managed. NVR also has a mortgage banking and title service business which may boost the group margins. Nonetheless, if Vistry can do half as well as NVR for half as long, it will be a great success: good luck to all holders.
Thanks for adding the tickers SheriffJEB! I have no idea whether or how well NVR (NYQ:NVR)'s model translates to the UK but that's the playbook here. I remember when Vistry (LON:VTY) unveiled their new strategy about a year ago it included some incredibly aggressive targets- something like 40% returns on capital and returning 1/3 of the market cap to shareholders via divis and buybacks within 5 years- so I imagine there's huge pressure on the various divisions to deliver. Pure speculation but perhaps overly aggressive forecasting and US-style blunt force management contributed to today's news...
Zotefoams (LON:ZTF) No official ReZorce progress update, but reading the article in this link (dated 4th Oct), it sounds like product won't be on shelves for consumer testing until Q1 2025, meanwhile share price keeps slipping! I hold - Patience required.
https://www.packagingdigest.co...
re Zotefoams (LON:ZTF) post from Dazza64 - This reads ok to me, versus how the shares are travelling. Perhaps someone closer to it can identify any chinks in this story.
Hello RDH. Always value your posts. Could you identify which company you are referring to here ?
Senior (LON:SNR) has reported in admirable detail today about the problems in the commercial aerospace industry as Boeing stumbles in trying to get its delivery rate going and Airbus also is frustrated in reaching its increasing rate as delays amongst its myriad of suppliers continue to slow the whole process. As investors we should be looking across the names we hold for knock on effects, and for me, I am particularly concerned for Velocity Composites (LON:VEL) where the long awaited (and much needed) start to commercial deliveries might be under threat. This morning’s fall suggests others may be thinking on the same lines. On a better note Gooch & Housego (LON:GHH) says today that things are going well in their aerospace business but I think this may be more military and refit than commercial new aircraft. I would be interested to hear from others with insights
Guess this would be similar for Melrose Industries (LON:MRO) then. Believe they are seen as a pure play aerospace these days with emphasis on commercial sector. Share price has been drifting here too.
This (I hope) could feed though to a positive for Amedeo Air Four Plus (LON:AA4) , an aircraft leasing company (I hold).
One of the main uncertainties for this company is what to do with their A380 fleet when their current leases expire with Emirates (starting 2026). With difficulty in new plane deliveries, I see an increasing likelihood of Emirates either purchasing the planes from AA4, or extending the leases. Either option would benefit AA4 as opposed to the other options available to them, sell on the open market or scrap. Which I think the company is currently priced for.
Perhaps one for others to research if it sounds interesting to them.
Thai Airways will likely come out of bankruptcy protection in Q2 2025 which should also be a boost for AA4. If the quarterly dividend of 2p can be maintained, AA4 will be flying!
SmallCappy
Amedeo Air Four Plus (LON:AA4) have committed to paying the 8p annual dividend (it’s paid quarterly) until 2026. That’s a yield of 16% at the current price. I bought as a risky punt at 34p a couple of years ago and get a 23% annual dividend, helped by dividend increases. The share price looks fully valued now it’s up to 52p. It’s guesswork what the final value of the planes leased to Emirates will be, so anyone looking to buy now will get a useful amount back in dividends but with uncertainty about the share price at the end of that lease period.
Ken,
re: Amedeo Air Four Plus (LON:AA4) - you are correct the 16p of divi's are locked in although the company has stated it is undergoing a full strategic review with its asset manager and other advisors the results of which it will announce before the calendar y/e quite possibly when it announces its half year results in December. They are certainly locked in based on their expected cashflows for the next two years although the strategic review could result in a decision to sell one or more of the assets ( with associated leases attached) and then the divi position may change.
I got involved in this sub 40p last year and viewed it as an investment with a relatively low risk on the downside ( 24p of divis out of secure cashflow) before the first of their lease mature. I saw and still see the upside potential - much more difficult to quantify due to the lack of visibility of residual value assumptions made by AA4 at the end of the leases.
They have 12 aircraft - 6 leased to Thai Airways ( 4 x A350's and 2 x B777's) and 6 x A380's leased to Emirates.
Thai Airways have been in administration ( Thai equivalent) since Covid times but have survived and are now in a very good financial place and look like they will come out of administration in the next 6 months. Either way they have extended their leases as part of the restructuring that took place and AA4 will at some stage realise the value of these assets by selling the assets with leases attached. Both types of aircraft ( Particularly the A350's) are sought after and the resale value is only going up due to in particular the production problems at Boeing with the B787.
The A380's are very interesting - when Airbus announced they were discontinuing production - the assumption was that Emirates would hand back the assets at the end of their lease and walk away - a real problem for AA4 as there are essentially no other operators and they would have been sold for scrap. Now Emirates are clearly stating that they want to continue to use the A380's post 2026-28 when the AA4 leases mature. They have invested heavily in maintenance facilities for the A380's and have the full support of Tim Clark the driving force behind Emirates becoming one of if not the best Airline in the world over the past 20 years. They are also retrofitting 110 out of 123 of their A380's in a multi-billion dollar program.
So it seems pretty clear that they will want to purchase or lease but most likely purchase the 6 A380's owned by AA4 when their leases mature. Coincidentally Doric Nimrod Air Two (LON:DNA2) a similar aircraft leasing company have just sold ( Aug 24) 5 A380's to Emirates at the end of their lease period for USD50m each.
In conclusion,
based on
1) Greater clarity from Emirates on A380 fleet staying in service
2) Thai airways coming out of Administration
3) the background industry position including aircraft production problems/delays and the number of people travelling surpassing pre-covid levels
I think there is a reasonable chance that the gap between the NAV at AA4 and its SP will continue to decrease.
That was a great reply betjeman, but because you posted it late in the day it got less recognition than it deserved. It was full of information and analysis and in far more detail than I’ve posted on Stockopedia. I luckily was alerted to Amedeo Air Four Plus (LON:AA4) by a poster on the now defunct Mike Walters website when the share price was only 34p and up till then had dismissed it and Doric Nimrod Air Two (LON:DNA2) and Doric Nimrod Air Three (LON:DNA3) as too risky. By buying when I did,I get most of my stake back in dividends.
Would you be prepared to paste your post to the latest Investment Trust thread here on Stockopedia? There are some excellent posters on Investment Trusts there who might not read this bb.
If you are happy to do that or alternatively for me to paste it there, here’s the thread for the October Investment Trust thread. Charles Mitchell who set it all up and worked in the sector, starts a new thread every new month:-
https://www.stockopedia.com/co...
While I have high hopes for Velocity Composites (LON:VEL) (clever idea that supports the increased use of carbon fibre in aircraft parts construction with good margins as it offers considerable savings and deep moat given all the approvals needed) I sold all this morning on the read-across from Senior (LON:SNR) . Been caught too often recently with big falls on profit warnings (albeit most of a temporary nature) so I'd rather not take the risk and then have to wait for the recovery.
Don't know whether I was responsible for the 6% fall today but the timing was spot on ;-)
On a generally dismal day the market has reacted well to an ahead of expectations trading statement from Greencore (LON:GNC) .
Greencore (LON:GNC) Tesco buyers queuing up outside GNC head office tomorrow morning, demanding further price discounts …!
Markets having a healthy dose of the jitters. HK down 9%.. now flat on the month...but up 20% since fed cut. China is up 4.6%, up 4.5% month to date, and up 28% since pre Fed. All seems ok. Some crappy news being taken badly in the UK and then we have CPI, Fed minutes and UK budget weighing on things. Equity vol (VIX) is elevated and more importantly so is Bond vol (MOVE) at 23 and 124 respectively. If I had to make a call I would say we are a little exposed to a hot CPI print, on the back of the employment number. Lets hope its in line and well behaved... not too weak not too strong is probably best.
Im a little surprised by the Senior (LON:SNR) ( I don't own) statement, I thought it was manageable but it fits the profile of stocks Im interested in. So infrastructure exposed in aerospace defence and energy... goes on the watch list for me. These industrial stocks are quite hit and miss at the moment. Strikes and policy disruption not helping. Longer term they are where I want to be.
No fishermen (sorry fisher-people!!) so far on Stocko today? We're not either but we do hold Angling Direct and I'm wondering about going for a bigger catch today. HY results today, Rev up 5.6% -UK retail and online up 8.4% and 2,8% -pbt up 35.7% eps up 31% -gross margin + 1.6%. I like the MyAD membership up 50% too. Have we landed a future big one or do I need cold water splashing on me? Paul you gave it Amber on Aug 21st without any comments.
Angling Direct (LON:ANG)
Hi Jasvfs, I own a few of these and they are very easy to own, EV/EBITDA of 3x, £17m net cash against a £27m mkt cap, you can see it's a clear value play.
However they have gone nowhere for 12 months and could go nowhere again for another 12 months so you have to consider the opportunity cost in tying up your money here indefinitely.
They have so many levers to pull and I think they play it ultimately a little too safely, but in this volatile trading environment they have managed to protect the downside..
Boredom is my main adversary here but yes, they are very cheap and the business is in safe hands and doing well.
Angling Direct (LON:ANG)
The H1 results were a little mixed for me but overall positive. Turnover growth of 5.76% when adjusting for inflation and a few new store openings was not great but gross margin improved, which they put down to a greater mix of own label products, which should continue into H2 and '... our increasingly sophisticated and agile ranging, buying and pricing practices' - that needs to be clarified but perhaps means volume discounts or sourcing from cheaper suppliers.
The most positive thing for me was the comment that trading in August and September was ahead of the H1 run rate, if that continues then despite the seasonally weaker H2 they should beat current EPS estimates of 1.75p. If for instance they are close to breakeven in H2, EPS could be in the 2p region.
The winter weather is important, heavy rain for instance would lower sales but they look to be well set.
The IMC next week may provide more clarity
The lost decade?
10 years ago the FTSE Aim index traded at 720. Today its at 735. Remarkable.
Last 10 years:
CPI up 36%, RPI up 49%, AIM index up 2%
What is going on?
Spent the last 10 years anticipating Rachel Reeve's changes to IHT relief?
Wow. That's amazing. Gives more fuel to my thinking of just ditching AIM stocks and funding an index fund instead.
My perception of AIM is there's just a lot of trash in it dragging the index down. If you look at the biggest daily gainers and losers, it's almost always pre-profit companies, often pre-revenue companies which should really be seeking seed or VC funding. They fact that they are listing rather than seeking that funding could be a signal that they can't access that funding - could be a big signal that they're not exactly the cream of the crop.
I doubt anybody has done the analysis but I'd be interested to know what the AIM performance would be if you excluded pre-profit or pre-revenue companies because there are clearly a lot of good quality companies listed but the index as a whole is getting dragged down.
I'd also be interested if anybody's views on AIM - I could be completely wrong here, it's just the feeling I get when looking at a lot of the companies listed.
Some of the fall is down to stocks being taken over, or moving to the main market or delisting. Keywords Studios (LON:KWS) which £2bn, will go soon, due to a takeover. The Aim100 is worth around £36bn, so that will be about 6% loss. The index is weighted, so the few large stocks have a big impact. One of the largest was Asos (LON:ASC) that is down around 80% over 10 years. Few of the largest stocks have done well in the last few years, Boohoo (LON:BOO) is down about 90%, Fevertree Drinks (LON:FEVR) down about 80% from peak, Burford Capital (LON:BUR) has halved.
Some smaller stocks have performed well such as Cerillion (LON:CER) and Warpaint London (LON:W7L).
The recent falls have been blamed on speculation about Labour's changes in IHT.
The FTSE100 also did not rise over 10 years, if you look back a few years.
I love to see updates from my investments, and if my company had gone public I would definitely have erred on the side of more rather than less, but I fo wonder if Intercede (LON:IGP) take it too far. Some of the recent updates have been frankly silly, announcing tiny orders. There was one in September which included news of an order for 0.15m, aka 150k.
I have no issue with a CEO shouting from the rooftops about juicy new orders, but I think it’s gone too far with IGP and that fewer larger announcements would serve them better than a myriad of modestness.
Personally I would prefer companies only to announce new orders if it means earning forecasts need to be raised...otherwise it should already be in the share price.
That's a bit harsh. It was about announcing the aggregate orders of $1.9mm for Intercede (LON:IGP) which is over 10% revenues so significant. The $150k one was a small part of that. I'd rather know about those contracts than not as long as it's not one announcement per contract (unless large).
Paul,
Beeks Financial Cloud (LON:BKS) . Excellent write up yesterday
My question is if Beeks offers a point to all points immediate service what did the exchange do before Beeks Financial Cloud (LON:BKS) came along or is it just the white label aspect that's so appealing to the exchange??
Thanks. I'll look at the webinar on IMC later today as well
Disclosure I hold a small position
Hi Threepeat,
"My question is if Beeks offers a point to all points immediate service what did the exchange do before Beeks Financial Cloud (LON:BKS) came along or is it just the white label aspect that's so appealing to the exchange??"
Why don't you submit that question to management through the IMC portal, as it's quite technical I don't suppose anyone here will know for sure, but could only guess.
Regards, Paul.
Regarding Beeks Financial Cloud (LON:BKS) , Michael Lewis wrote a very readable book on high speed trading called Flash Boys a few years ago.
I don't think it benefits the exchanges directly, (unless some folk decide to trade a smaller exhange such as the JSE as they feel they have an arbritrage opportunity as a larger player in a smaller pond?), just those wanting to trade on it.I wondered if there are any direct competitors offering a similar service and why nobody had bothered with the regulatory hurdles to offer it beforehand, such as a US outfit?I do know the huge players have had their own blackboxes and cabling/other network to optimise order flow speed to the exchanges for a long while.But that's obviously only the huge players who could afford it.I guess big high frequency trading/order flow market makers such as Citadel would.I got the impression Beeks offers more than just speed and has some other proprietary software running on their blackboxes, perhaps for various hft trades.
I didn't read it that Beeks Financial Cloud (LON:BKS) can do what the exchange couldn't do before with bare metal servers, but they can do what other cloud providers can't do.
I’m not an expert in this area (but I am a cloud architect at a leading financial institution) but typically you are looking at dedicated lines or public infrastructure (comms, internet etc). Public infrastructure typically isn’t going to meet any capital market SLA’s and from a security perspective it’s an absolute nightmare. Dedicated lines are expensive and obviously even if you go via a third party you are only getting part of a solution for this domain. Beeks has broad connectivity in place across most of the major markets and takes care of a lot of the security, upgrade and on demand flexibility as they have wrapped it all into a capital market centric service. It makes things pain free to a domain that will pay for top tier service that is easily consumed.
Good news today from Gulf Keystone Petroleum (LON:GKP) on their dividend policy, and they’ve announced a big 5.5% interim dividend too. Ex dividend is October 17th and pay day October 31st.
If the pipeline ever reopens then GKP could again be paying even bigger dividends. I held before the pipeline closure when dividends peaked at around 88p in 2021. Now the share price is down to 132p. It’s up a bit on this news today.
Gulf Keystone Petroleum (LON:GKP) seems to be coping very well despite the pipeline closure.
And for those who like buybacks there’s news on those too.
I hold.
Good post Ken. Beat me to the draw! Like you I hold but timely top slicing means I am not too far below water. I agree, the risk reward on this looks compelling. GKP, in its current constrained state, has managed to run a profitable business that can get access to the revenues it is due. If the pipeline reopens it will double - in the meantime we're being paid to wait.
Intercede (LON:IGP) I have held for years and added along the way. Todays drop tripped a generous STOP. The MM wins as I have to buy back in.
I long ago stopped lodging stop losses with my broker. I maintain a trailing stop loss myself by updating a spreadsheet, and enter any sell trades myself.
Vistry (LON:VTY) Market reaction looks way overdone to me. I was thinking 10-15% drop. Currently 35%! I'm going to continue to hold for the time being. Profit warning down to a mistake made in costing in one location with a small'ish impact. Puts profits back to where they were last year (give or take) instead of up 15%. Considering the state of the property market and the uncertainty of the new govt that doesn't seem so bad. Also compared to peers who are all struggling. Sounds like I'm trying to justify myself - but I really do think this one has dropped out of proportion. It'll be interesting to watch. (Stats say I'm wrong to continue to hold!)
Good grief! Thanks for flagging Vistry plummeting, I'm going to take a look at that now, as it's an excellent company with a good business model I think. Could this be a buying opp? I'll let you know in about an hour.
Vistry (LON:VTY) Market reaction looks way overdone to me. I was thinking 10-15% drop
The fall in profit is nearly 20% so that’s the minimum you should have expected. Then there’s a credibility discount to apply - how many other projects will turn out to have been poorly costed? Thridly, shares had ridden ahead of themselves on the conviction that the name was the gold standard. Not looking so smart now. So that’s a third reason to slice. Does 30% still look harsh bearing all that in mind?
Vistry (LON:VTY) The 20% fall in profit only affects one year, while shares should reflect profits over all future years. On this basis the fall looks overdone, although as you say there is now maybe a credibility issue that needs to be factored in.
Hi BnB - you don’t usually drop the market cap by more than the one off impact of an event when the shares trade at 12* which is what appears to have happened at Vistry (LON:VTY). What that is saying is the reduction in profits is permanent which clearly is not the case here. It is a one off impact spread over 2 years so against a market cap of 4.5bn should make a few % difference - not a 30% drop,
The most likely scenario is that investors consider it poor fiscal discipline and could there be other sites where this has also occurred. Ie it has brought into question the quality of the profit. Management need to address that carefully - they have said it is limited to one division where management has clearly been fired and as long as that is the case it should recover. One slip up is unfortunate, two would cause long term harm……….
David, I completely agree with your logic surrounding the (hopefully) one-off and contained nature of the warning, but the UK market is not known for its logic and calm. Though, of course, the drop is a combination of the three factors I highlighted. My third point, that shares had been riding spectacularly high, should not be ignored. This is a big blow to confidence.
On the other hand, could be a good opportunity for those who missed the boat first time round.
I think another point worth considering on Vistry (LON:VTY) is that the share has only fallen back to the level occupied by its (untainted but perhaps less well positioned) competitors in that it is now approximately 60% above the lows of Oct 22 - cf Gleason, Bellway etc. Jefferies had issued a cautious note only last month, based on its stretched valuation. And Berenberg warned in March, presciently it appears, on operational delivery challenges.
When I look at the companies I hold which are now underwater, examples Reckitt Benckiser (LON:RKT) , Spirax (LON:SPX) , Smith & Nephew (LON:SN.), Diageo (LON:DGE) , GSK (LON:GSK) , they are all companies which which I have held through profit warning(s). If I had sold straight away after the first warning I would be better off. I have resolved in future to sell straightaway. (Let's see whether I can actually do it!)
It's hard to sell a company which you bought, but usually there's another shoe to fall, the general view is that profit warnings come in 3's. It's partly because everyone in the company is embarrassed (rightly) by a profit warning. The management obviously, the Chair and NEDs are worried about their "reputation", so everyone is quick to agree the various remedies that claw some of the difference. these are often optimistic and there are also potentially other problems that weren't forseen.
Agree with all of this by Bnb regarding Vistry (LON:VTY) .
The other point I would make is that this black hole seems to have been unearthed incredibly recently. Only a month ago the CEO was all smiles being interviewed by The Times and patting himself on the back for his “inspired” decision to focus on affordable housing. So at that time there was absolutely no inkling of today’s bombshell.
It strikes me that maybe two/three weeks at most is not enough time to really get to the bottom of the issue such that you can be 100% confident that it is an isolated, confined and one-off matter.
I think it’s highly unlikely that other developments will become embroiled in this mess. I suspect it’s limited to the 9 developments mentioned.
They have 300 live developments, so for 9 out of 300 sites (3%) to hit profits by 18% means it was one almighty ‘mistake’. It’s a fundamental and major error in estimating costs. It’s not labour cost, brick costs etc…it’s a giant error or even something a bit smelly in one team.
But, it can’t be something group-wide. It sounds like it’s not even Southern Area-wide, as it only affects 9 of the 46 sites in that division. The big investors will want to be sure it’s not group-wide, but from my 20-odd years in construction this feels very much like a one-off issue, and we can expect an announcement in the next months explaining what has been done to stop this ever happening again.
I am very much sticking with Vistry. A massively disappointing giant hiccup, but the model and the market-conditions make this a superb long-term investment.
Vistry (LON:VTY) The substantial share purchase today by the CEO suggests you have called it spot on Andrew.
Sounds like someone internally below board level may have been mis-stating the financial position and HQ has only just picked this up. I guess the immediate market reaction today is there may be poor financial controls.
Quite a good chance when the dust settles that this will turn out to be the contained incident set out in the RNS, but until there is a fuller explanation there's a cloud over the share price.
Forgive the question as this might not be the right forum but I wondered what peoples thoughts are about the options of what to do with holdings (large cap - Not tech) before the budget where gains are in the region of 80-180% percent?
I doubt anyone knows - I would have thought large caps would be most able just to plod on - the pre budget discussion is out of proportion to what labour need to do to keep things ticking over - so I suspect it may be business as usual - it’s probably more about what suits your plans ref investing ? I look more at current inherent value than gains or losses personally - when I bank a profit tho stuff often keeps on rising - doh
Vistry (LON:VTY) profits warning, citing unexpectedly higher building costs
Feel a bit underwhelmed by intercedes Turnover when compared to H2 last year. Its sales are not seasonal so why the drop from £12,970,000
Alex,
Intercede (LON:IGP) won an $8m order reported on 5 December 2023. All the licence fees were reported as revenue in 2H24.
In the RNS announcing the win IGP said "The Group wants to highlight that this contract is an exceptional order and deemed 'one-off' due to the large number of perpetual licences purchased which will be recognised in FY24."
In their CMD IGP showed their numbers stripping out the one off licence fee income.
Morning Paul,
I look forward to hearing your views on Intercede (LON:IGP).
Revenue is up 22% in nominal and 29% at constant currency to £8.54m, which is a decent clip on any view.
With FY25 revenue forecast at £16.1m, IGP need £7.56m in H2 to meet forecasts. This would be a decline in H2 vs H1 of £0.98m or 11.5%. H2 has usually been stronger than H1 (it was flat in FY23).
Last year, IGP used “in line” / “underpins” wording for TUs and contract win RNSs up until 5 December, when it started to issue "ahead" updates.
IGP's half year TUs always have the form revenue, whether the revenue is in line and cash.
Any ideas for the biggest beneficiaries if Rachel Reeves changes the fiscal rules tomorrow to allow more spending on infrastructure?
Any ideas for the biggest beneficiaries if Rachel Reeves changes the fiscal rules tomorrow to allow more spending on infrastructure?
Hedge funds shorting Gilts ;-)
More seriously, contractors and equipment hire companies
Even more seriously, none of the above as government initiatives get bogged down in confusion, conflict and delays
Hi BnB
I hold several picks and shovels companies, small caps, that should benefit from an upturn in infrastructure spend and house building. All purchased at around the current prices, with the exception of Sigmaroc and Eurocell (LON:ECEL) (LON:SRC) which were bought around 60p and 145p respectively . They are all modestly rated given the current malaise and all have said to a greater or lesser extent that the pick up in construction/house building has yet to materialise. In no particular order they are:
Van Elle Holdings (LON:VANL)
VP (LON:VP.)
Brickability (LON:BRCK)
Sigmaroc (LON:SRC)
Eurocell (LON:ECEL)
Michelmersh Brick Holdings (LON:MBH)
Most pay a dividend and Michelmersh Brick Holdings (LON:MBH) and Van Elle Holdings (LON:VANL) are cash psoitive. However VP (LON:VP.) and Michelmersh Brick Holdings (LON:MBH) have warned on profits, but there shares have largely held up.
Brickability (LON:BRCK) should be a significant beneficiary of cladding remediation and will obviously will benefit from any pick up in house building.
Eurocell (LON:ECEL) is currently in the process of its second share buy back and Sigmaroc (LON:SRC) , which I think haS significant potential is the second largest producer of lime and lime products in Europe and in my view has a very entrepreneurial CEO in Max Vermoken.
I also hold Kier (LON:KIE) which I bought after selling Galliford Try Holdings (LON:GFRD) north of 300p. having bought it around 167p. My thinking is that as the former continues to reduce its debt the rating should rise from a PE of around 7 to 10 or thereabouts, Galliford Try Holdings (LON:GFRD) trades on a PE of around 12/13.
Not sure if this helps , but wish you well in whatever you decide.
PS: I would add that my portfolio of 23 shares, many of which are AIM listed is currently taking a bath due primarily to the uncertainty regarding the budget. It has now given up its 15% gain for the year.
Good list of shares there. One other name I would add and currently hold is Severfield (LON:SFR) - recent trading updates have been solid and they're doing buybacks as well as paying generous dividends. FWIW also has a stock rank of 99
Hi Jonno
I think you meant those helpful ideas for someone else!
Oops! Should have been in reply to jesseowens!
I believe of the huge amount set aside in the Biden administration for infrastructure spending very little of it has actually been spent, just as a comparative example. Bureaucracies grind exceeding slow!
My morning smallcap tweet: Fees on Down the Road
Literacy Capital (LON:BOOK) Loungers (LON:LGRS) EPE Special Opportunities (LON:ESO) Fusion Antibodies (LON:FAB) Motorpoint (LON:MOTR) Brooks Macdonald (LON:BRK) S&U (LON:SUS), Intercede (LON:IGP), Gooch & Housego (LON:GHH), XP Power (LON:XPP)
◄Literacy Capital (BOOK)► agrees to hike mgmt fee 67% to 1.5% because "The Investment Manager is also keen to make investments in its use of data, technology and back-office functions". and some other guff. [SP=488.5 Cap=294m]
◄Loungers (LGRS)► sounds in line. [SP=270 Cap=281m]
◄EPE Special Opportunities (ESO)► share buy back. [SP=152 Cap=67m]
◄Fusion Antibodies (FAB)► AGM stmt - H1 rev up 5%. Cash in line at £464k end Sep. No plans for an equity placement. [SP=4.2 Cap=4m]
◄Motorpoint (MOTR)► guides H1-Sep rev up 17% and adj pretax c.£2m(-£3.7m). Strong momentum going into H2. In line? [SP=153 Cap=133m]
◄Brooks Macdonald (BRK)► buys LIFT-Financial Group Ltd and LIFT-Invest for £30m plus £15m max contingent. Co will "leverage the opportunities this transaction will create" natch'. [SP=1860 Cap=306m]
◄S & U (SUS)► H1-July. Aspen Bridging 'sparkling' but Advantage Finance weak with transactions down 13% as it lends more cautiously. However be reassured that it's "in Advantage's very DNA to nurture their valuable customers". [SP=1660 Cap=202m]
In line: IGP, GHH, XPP
Impax Asset Management (LON:IPX) - AUM +0.7% in Q4, -0.6% in FY24, dividend yield 7.4% - link to new research here: https://www.equitydevelopment....
AUM closed FY24 (1 Oct 23 - 30 Sep 24) on £37.2bn, 0.6% down y-o-y. Net outflows over FY24 totalled £5.8bn, largely offset by a positive investment performance of +£5.3bn and a contribution of +£0.3bn from the acquisition of Absalon Capital Management in Q4.
As flagged, outflows were heavily impacted during the year by Impax’s largest distribution partner, BNP Paribas, and some other clients in European private wealth, reducing their clients’ weighting to equities in favour of money market funds, to take advantage of higher interest rates.
However, Q4 (1 Jul – 30 Sep) showed improved flows of -£1.2bn, considerably less than the -£1.9bn of Q3. Investment performance added £1.1bn. Impax noted that redemptions in European private wealth had dropped sharply in Q4 (with further improvements in flows expected as interest rates fall), it had experienced stronger market conditions more generally, and that its outlook is positive.
AUM on 30 Sep of £37.2bn is only a fraction below our forecast of £37.3bn and we maintain our FY24 forecasts. We do however reduce FY25 forecasts as a return to positive net flows looks likely to take a little longer than previously anticipated.
Loungers (LON:LGRS) - "Come rain or shine, Loungers delivers" - new note with audio summary available here here: https://www.equitydevelopment....
Loungers has achieved record 1H25 revenues of £178.3m, +19.2% on 1H24. 16 new Lounge bars and one new Cosy Club, together with last year’s new sites, contributed 14.5% whilst 4.7% LFL sales outperformed industry growth by over 3% due to Loungers’ all-day attractions.
This growth is especially strong considering the unseasonal weather, the negative impact of the Euro 2024 football tournament and the fall in UK consumer confidence.
Although our 2H25 estimates look cautiously set, inferring c.3% LFL and c.10% new site revenue growth, we make no changes to our FY25E forecasts at this stage, given the consumer uncertainty ahead of the Autumn Budget on 30 October.
The 273-site group still has huge scope to grow towards its ambition of over 650 sites, driving 14% CAGR in Revenues, and 21% CAGR in Adj. EPS FY24-FY27E. We believe this high growth is not reflected in the group’s valuation and reiterate our Fair Value of 370p / share (8.0x cal. 2025 EV/Adj. EBITDA).
8 days ago when Venture Life (LON:VLG) published interim results I wrote "It irritates me when companies say that full year will be inline with "management expectations" because we don't know what they are. We do know what market expectations are and the outlook there is a big miss because Cavendish have just slashed eps by 16% from 5.5p to 4.6p".
Paul replied "All too often I'm afraid the PRs make interpreting RNSs a game of cat & mouse. They try to hide the bad news, we have to unearth it. It's one of the reasons why I'm not worried about so-called AI making my role redundant! It needs experienced humans to untangle the web of lies & deceit that we are often presented with at 7am each weekday ;-)"
IMC has now put up the Q&A from the Venture Life (LON:VLG) presentation and you can listen here: https://www.investormeetcompan... Hit the Q&A tab (top left under date) and listen to Q 9. I must give the CEO credit for taking the point on board and saying that in future it is probably better if they refer to market expectations.
Very helpful reference sharw. I hadn't realised you could see the individual questions raised and answers in the IMC presentations.