Small Cap Value Report (Tue 9 April 2024) - GMR, W7L, GHT, SCE, SUS, ORCH, SBDS, IPX

Good morning from Paul & Graham!
I've got to finish a little earlier today, so I did a section on GMR last night to compensate. Today's report is now finished due to time constraints. I'll circle back to a couple of the interesting companies reporting today, later this week.
Looks like it should be a good day for my 2024 share ideas, with a takeover bid for Gresham Technologies (LON:GHT) although the premium looks disappointing, and an ahead of exps update from one of our favourites, Warpaint London (LON:W7L) . Can I catch up with Graham?! (EDIT: drat, just realised W7L wasn't on my 2024 top 20)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
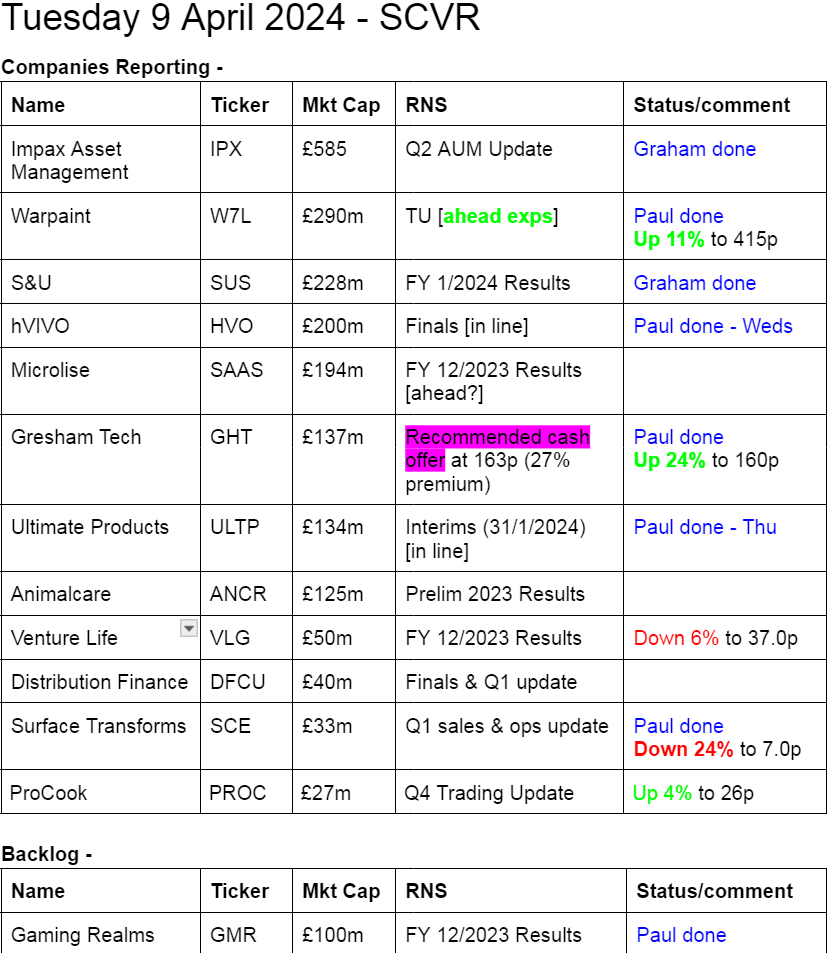
Other mid-morning movers (with news) -
Orchard Funding (LON:ORCH) - up 41% to 22.5p (£5m) - H1 Results - Paul - AMBER
Reports £1.1m PBT in H1 - not bad for a £5m mkt cap company.
It says the fraud (I mentioned that here on 1/3/2024) was isolated & shouldn’t recur.
Lending related to GAP insurance is falling, as previously indicated.
Notes that shares are c.a quarter of NAV, so they’re looking at options, including potential delisting (which would normally cause the share price to fall), and a possible tender offer.
Paul’s view - I flagged the huge discount to NAV on 1/3/2024, and the dominant major shareholder, and the risk of delisting. Yes there seems to be value here, but the risk of ending up holding shares in a private company puts me off. The commentary today from ORCH makes it sound as if they’ve already decided to delist. Hence why I think it might be a mistake to chase the share price higher, but only time will tell.
Silver Bullet Data Services (LON:SBDS) - down 11% to 105p (£18m) - Board Changes - Paul - AMBER
Group CFO seems to have been dumped & replaced with immediate effect, and a new NED also appointed. SBDS looks an interesting company, but I don’t know how to value it, and the share price has been very volatile of late.
Summaries of main sections
Gaming Realms (LON:GMR) - 33.8p (£100m) - Annual Results 2023 - Paul - GREEN
I look at the rather complicated figures from this gambling software provider. Is it a profit miss? Yes and no - EBITDA is slightly ahead, but a higher depn/amort charge means adj PBT is below expectations. EPS boosted by negative tax charge. Continuing organic growth is expected. Cash position looks fine. Overall, I remain positive, but ask some questions about the business model below.
Warpaint London (LON:W7L) 375p (£290m) - Trading Update - Paul - GREEN
One of our favourite shares delivers the goods once again - with yet another ahead of expectations trading update! Not a big surprise though, as I commented here on 12/1/2024 that the forecasts looked way too low. Expect the shares to resume the upward trajectory, I remain very positive.
Gresham Technologies (LON:GHT) - up 24% to 160.5p (£134m) - Recommended offer - Paul - PINK (takeover bid)
Big shareholders have clearly pressurised the company to put itself up for sale, so they can exit an otherwise illiquid investment. This agreed 163p cash bid from a US private equity firm looks to have been the best deal around. Not an exciting premium of 27%, maybe there's a possibility someone else might come along and better that price?
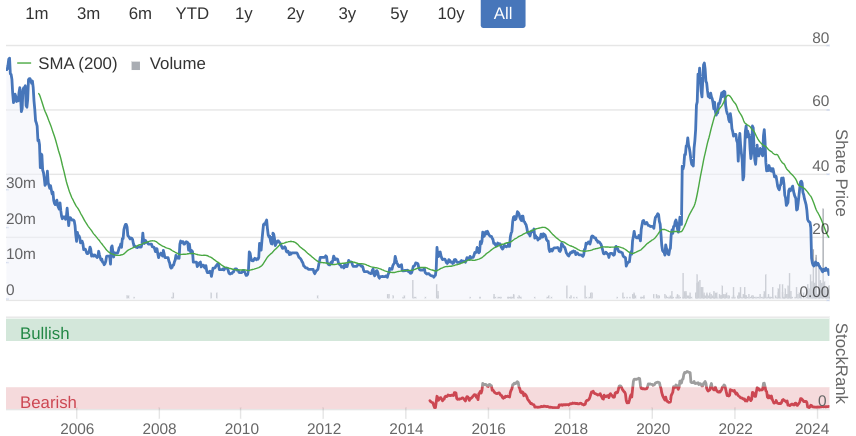
Surface Transforms (LON:SCE) - down 27% to 6.75p (£24m) - Q1 2024 Sales & Operations Update - Paul - RED
Shareholders take another battering today, as it once again reports more production problems, and a clear need for more funding. Hence I have to move down from amber/red to RED, due to the increased likelihood of yet another discounted placing being needed. The product and order book look exciting, but actually achieving the production ramp up is proving a deeply painful and high risk process.
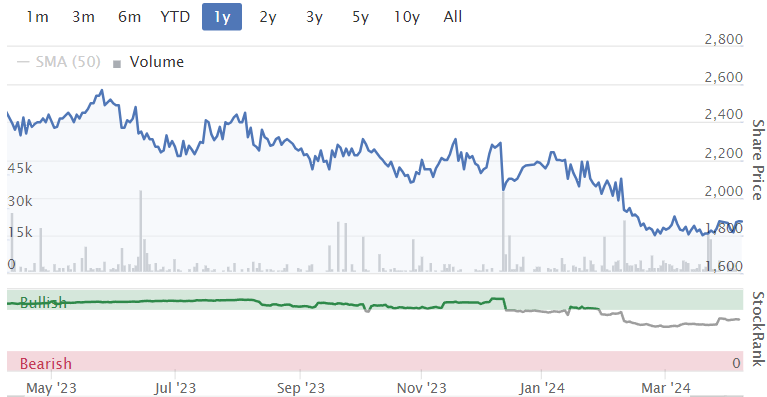
S&U (LON:SUS) - unchanged at 1873p (£228m) - Results to 31 Jan 2024 - Graham - AMBER
These full-year results are impacted by a range of issues including regulatory action, higher rates on borrowings, and a weak consumer. Both Advantage and Aspen remain profitable, but conditions are more difficult than before. I’m neutral until we have regulatory clarity.
Impax Asset Management (LON:IPX) - unchanged at 440.8p (£585m) - Q2 AUM Update - Graham - GREEN
Outflows have unfortunately picked up here, but CEO Ian Simm suggests that broader sentiment has picked up in recent months for environmentally-focused investors. I remain positive on this one as I continue to view it as a quality long-term growth stock.
Paul’s Section:
Gaming Realms (LON:GMR)
33.8p (£100m) - Annual Results 2023 - Paul - GREEN
These numbers were published last week, on 2/4/2024.
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile focused gaming content, announces its annual results for the year ended 31 December 2023 and Q1 highlights for 2024.
26% increase in Revenue and 29% increase in Adjusted EBITDA1 in Record Year
I reviewed the FY 12/2023 trading update here on 6/2/2024.
Guidance provided by the company and Canaccord at the time was:
Revenues £23m, adj EBITDA £10m+, adj PBT £5.9m, and 1.6p adj EPS. Net cash of £7.5m.
Actual numbers released today are:
Revenue £23.4m (a 2% beat), adj EBITDA £10.1m (1% beat)
PBT is £5.17m, but I think that’s unadjusted.
Canaccord is now showing £5.4m adj PBT for FY 12/2023, which seems to be a £0.5m profit miss against what was expected previously. By comparing old and new forecasts, I can see the shortfall is caused by the depreciation & amortisation charge (actual) being £4.1m, vs a previous forecast charge of £3.0m, which looks like an error in the original forecast, partly offset by a £0.4m gain vs forecast on interest costs.
The way I look at this, the actual 2023 results are an overall £0.5m miss against adj PBT forecast, but due to non-trading items (depreciation, amortisation, and finance costs). So I think we can probably forgive this.
Adj EPS forecast was 1.57p, but actual has come in way above, at 2.02p! This is due to an unusual corporation tax line, which is negative, at a £758k tax credit in 2023, thus boosting EPS artificially. The tax credit is due to recognising deferred tax assets. I think we should probably be normalising the tax charge to say 25%, which would adjust EPS down from c.2.0p to about 1.5p.
It’s rather complicated, but my conclusion is that EPS is being boosted by negative tax, so I wouldn’t want to value this share on the inflated EPS figure of 2.0p, something nearer c.1.5p is more realistic for valuation purposes, so the PER is about 22.5x, which is quite a lot higher than I was expecting.
It would be worth asking management what, if any, additional tax losses would be available to offset against future profits? The retained P&L is showing a £(26.5)m deficit, so if the tax position is anything close to that, then it might continue benefiting from little to no corporation tax, who knows?
UPDATE: the CFO was asked about tax losses in the webinar today. He replied that they've got UK tax losses (I think he said £26m), but pay tax on US earnings. It's something that gets reassessed each year end. They have anticipated 2 years' tax losses in 2023, and there could be more in future.
Forecast for 2024 - interestingly, Canaccord’s figures assume a fall in depreciation & amortisation charges again, which is the figure that was significantly wrong in the 2023 forecast. Therefore, I suspect its jump from £5.4m adj PBT (2023 actual) to £8.8m forecast 2024 could be too optimistic by about £1m. So I’ll estimate £7.8m adj PBT for 2024, take off a normalised tax charge of 25%, giving £5.85m PAT, divided by 295m shares = 1.98p my estimate for FY 12/2024 adj EPS. That’s a bit below the 2.3p that Canaccord calculates.
At 33.8p EPS, the PER for 2024 is 14.7x for Canaccord, and 17.1x for my estimate.
Neither is expensive to be fair, for a company generating strong organic growth.
Recurring revenues? I’ve never been able to ascertain how much of GMR’s licensing revenues are contractually recurring, and how much are one-offs? The word “licensing” appears 44 times in the results, but I still find myself confused about how exactly the business model works.
UPDATE: I asked this question in today's webinar, and the CEO gave a very clear reply, saying almost all the licensing revenue is recurring revenue (typically a revenue share paid by the clients). Great news!
Also what IP protection does GMR have over its games? What is to stop competitors launching similar but slightly different games, and undercutting GMR, I wonder?
Social publishing is not doing well, with its EBITDA almost halving to £0.8m. This was more than offset by gains in the all-important high margin licensing revenues. So my question is whether social is a dead end, or can it be returned to growth?
Balance sheet - is healthy with c.£11m NTAV, including £7.5m cash (and no debt). As mentioned before, I think the finances are now healthy enough to commence divis, but the company seems reluctant to do that. So no divis for now.
Cashflow statement - is OK, but note that operating cashflow of £9.3m was more than half consumed by £4.8m investing activities - nearly all of which was capitalised development spend. So actually the business is not as cash generative as I would like for a £100m market cap company. Although further revenue growth expected in 2024 should flow through to improved cashflow.
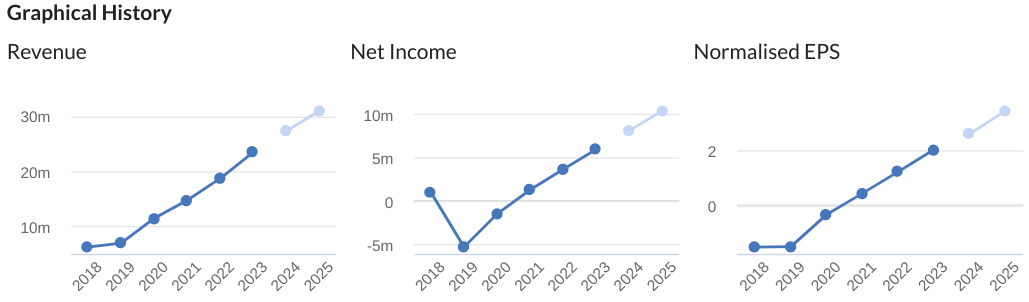
Also, I should say that GMR’s overall position is absolutely transformed from when I remember reviewing it in 2018-19, when it almost looked a basket case, certainly precarious financially with a weak balance sheet, and loss-making. The position today is unrecognisable from that, and you can tell from the commentary with the 2023 figures that management are justifiably proud of what they’ve achieved.
Consider these graphs, which are remarkable -
Outlook - sounds positive -
…the Board is confident in the Group's strategy and expectations for the rest of the current year…
"We have had a promising start to 2024…
Paul’s opinion - I’m happy with things overall, having had a good rummage through the numbers. The shareholder register is striking for having little institutional holders. I wonder if the next UK small caps bull market could see this share re-rate from institutional buying, perhaps, once they start to see fund inflows?
I’d like to better understand some specifics of the business model, but there’s no getting away from the fact that performance has been excellent in recent years, and it sounds as if the outlook is also rosy, with continued growth likely.
So it’s another GREEN from me.
There's an InvestorMeetCompany webinar today at 10am.
Warpaint London (LON:W7L)
375p (£290m) - Trading Update - Paul - GREEN
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands is pleased to provide an update on current trading and confirm the date for release of the Group's results for the year ended 31 December 2023.
Strong trading continues in Q1 2024
Q1 revenues are up 28% to £23.5m
Margins (gross, presumably) are “robust”, and ahead of 2023.
Cash position is £7.5m (with no debt) is down from £9.0m at Dec 2023, due to…
Increased inventories “to satisfy expected demand later in the year”.
FY 12/2023 results to be published on 24 April 2024.
Overall - it’s ahead! -
Accordingly, given this strong start to the year, the outlook for FY 2024 is now expected to be ahead of the market's current expectations.
Forecasts - Shore Capital puts out a helpful update note, saying its 18.6p EPS forecast for FY 12/2024 is “at least 10% too low”. That won’t come as a huge surprise, as it didn’t escape our notice previously that rising from 18.0p (forecast) in 2023 to only 18.6p in 2024 seemed unrealistically low, and implied growth was stalling, which it clearly wasn’t in reality.
As I commented here on 12 Jan 2024, my view is that a much higher forecast of c.25p looks realistic for FY 12/2024, and maybe 30-35p EPS in FY 12/2025. Today’s news reinforces that my much more aggressive idea for future profit is looking correct. Which means the shares are still potentially cheap, assuming nothing goes wrong.
Paul’s opinion - the recent dip in share price looks to have provided a nice buying opportunity. I’m working on the assumption that another ahead of expectations update today, the latest in a long series, shows that sitting tight here and enjoying the ride is the best approach. We’re likely to end today back above 400p I’m guessing, and I can see the ground being laid for another push upwards - maybe to 500p+ in due course?
W7L remains one of our favourite shares here, so it’s obviously going to be a continuing GREEN view.
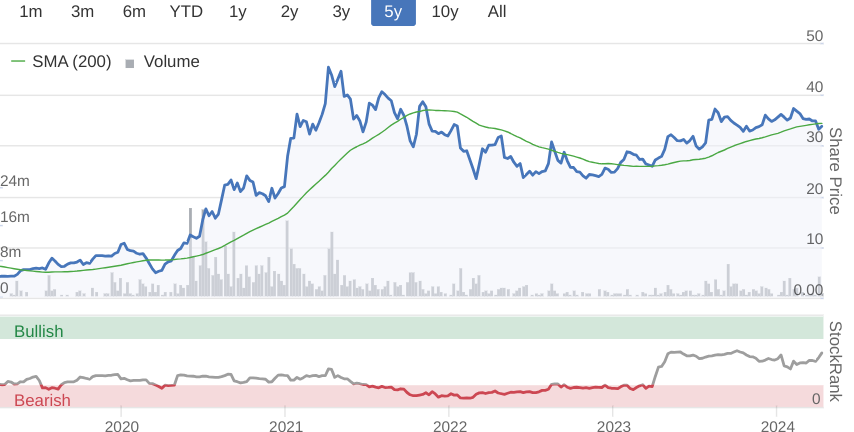
Stockopedia is also very keen, with a high StockRank -
Gresham Technologies (LON:GHT)
Up 24% to 160.5p (£134m) - Recommended offer - Paul - PINK (takeover bid)
Who’s the buyer? A US private equity firm called STG Partners, LLC, via a company called Alliance Bidco Ltd.
Price? 163p in cash, plus a 0.75p dividend.
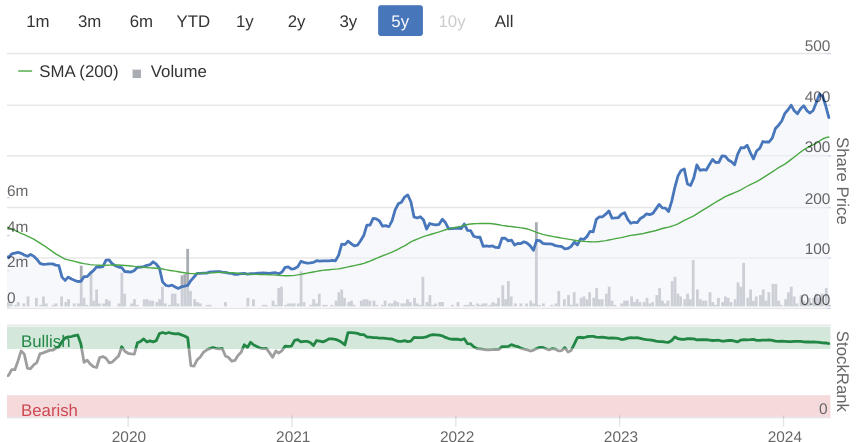
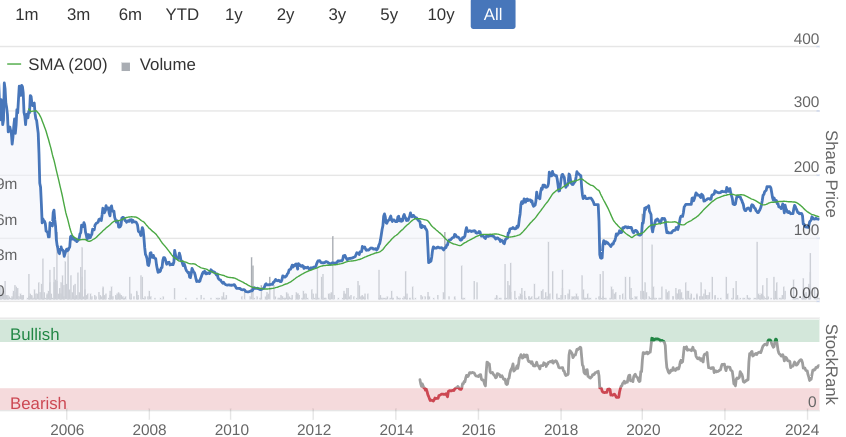
Premium? Only 26.9% above last night’s closing price, so this looks a disappointingly low bid, hence I wonder if shareholders might reject it? Looking at the chart, I think a bid needs to be 200p+ to look fair.
Recommended - so the Board of GHT has agreed to this bid.
75% vote at a shareholder meeting is required to agree the bid.
Directors only hold 0.5% of the company.
Shareholders holding 45.4%, including the largest shareholder Kestrel (with 23.9%) are supportive of this deal.
On price, GHT says -
...the Cash Offer values Gresham at 12.9 times adjusted EBITDA and 30.8 times adjusted cash EBITDA for the year ended 31 December 2023 as estimated by the Gresham Board and detailed further in paragraph 8 of this Announcement. Having sought to obtain competitive alternative proposals, the Gresham Board considers the above multiples to be attractive.
The rationale mentions low liquidity in GHT shares, and the pressures of being on the public market, as opposed to more generously, privately funded competitors.
Paul’s opinion - this deal is all about providing a liquidity event for large shareholders, who want to exit. Hence why there’s 45% support for this deal, despite it only being at a modest premium.
Surface Transforms (LON:SCE)
Down 27% to 6.75p (£24m) - Q1 2024 Sales & Operations Update - Paul - RED
Surface Transforms (AIM:SCE) manufacturer of carbon fibre reinforced ceramic disc brake materials provides the following sales update for the three months to 31 March 2024…
“Reconfirms unchanged sales guidance of £23m for the 2024 financial year.”
Q1 2024 revenues were £3.0m, flat vs the previous quarter.
“Significant improvements” in the previous production problems.
This bit doesn’t exactly fill me with confidence -
The prime remaining operational challenge relates to continuing high levels of scrap from processes that are not yet fully capable. Again we regard these issues as a learning curve and note, that considerable success has been achieved in recent weeks in reducing scrap. We expect to continue these improvements over the coming months unlocking further capacity.
“Customer situation is stable”, with revised delivery schedules.
Outlook - this is the bombshell unfortunately -
We are maintaining sales guidance of £23m for the year ending 31 December 2024. However the scrap problems in particular have absorbed a sizeable amount of working capital and cash.
The Board are assessing options to address this short term issue.
Surely if they're having to scrap production, then that is a loss - it's not absorbing working capital, it's destroying cash. That is unless scrap can be economically recycled into fresh production, I don't know. The word "scrap" suggests it's a write-off, rather than just having to re-work faulty production, but I'm guessing there.
Paul’s opinion - yet again, SCE needs more cash. We already knew that the rescue deal late last year wasn’t going to be enough, but I didn’t expect it to be signalling the need for more cash quite so soon. I wonder if there might be some way of getting customers to fund working capital in advance by offering discounts?
It’s painful watching a promising UK company with a large order book struggling to commercialise things - not just a lack of proper funding, but also interminable production problems, which make it sound as if they’re figuring out how to make the products as they go along.
It’s tantalisingly close to commercial success, so I think shareholders probably need to be philosophical about the likelihood that another equity raise seems almost inevitable.
Does anyone actually believe that they’ll hit the £23m revenues target for FY 12/2024, given the track record?!
I don’t recall SCE mentioning problems with scrap before. That sounds serious, in that they don’t seem to know how to actually make the product. Surely that’s fundamental?
Previously we were giving it the benefit of the doubt here with amber/red, but I think the clear need for yet more funding, and ongoing production problems, means the risk meter has just gone RED again. I’d rather wait for these problems to be resolved, and buy once the trajectory is more obviously heading for success. Dilution risk strikes me as too high again.
This share must be incredibly frustrating for everyone involved, given that it took so many years to achieve big demand for the products, but actually producing them has proven so difficult. It's easy to criticise of course, I really do hope this project succeeds, but it's not something that I would want to be backing at this problematic stage.
Graham’s Section:
S&U (LON:SUS)
Unchanged at 1873p (£228m) - Results to 31 Jan 2024 - Graham - AMBER
S&U plc (LSE: SUS), the motor finance and specialist lender, today announces its preliminary results for the year ended 31 January 2024.
Paul covered S&U’s profit warning in February.
The profit warning was attributed to “…poor consumer confidence, continuing high interest rates, cost of living pressures and regulation…”, resulting in a weak H2 repayment performance at the motor finance business (90%).
Headlines in the full year results:
Revenue +12% to £115m
PBT down 19% to £33.6m.
The impairment charge is up by £10m (to £24m), and is the primary reason for lower profitability.
Final dividend for the year is 50p (last year: 60p). Total dividend is 120p (last year: 133p). Given the increase in corporation tax this seems like quite a generous payout to me. Especially when you consider that earnings per share fell to 209p (last year: 277.5p).
Net borrowings increase by £30m+ to £224m.
Net assets increase by £10m to £234m.
See that net borrowings are now almost as large as the company’s net assets: this is reflected in a “gearing ratio” of nearly 96%: the company calculates its gearing as net borrowings divided by net assets.
Pre-Covid, S&U had a gearing ratio of c. 65%. It always impressed me that the company performed so well despite not seeming to borrow as much as it could, or as much as its rivals would be inclined to borrow.
However, in recent years, the company’s risk tolerance has increased. Will they allow the gearing ratio to go over 100%, I wonder? It’s still a modest amount of leverage, but perhaps no longer in the ultra-safe category it previously inhabited.
Chairman comment from Anthony Coombs is typically memorable:
Enthusiastic and supportive customers underpin S&U's long success and guarantee its future. Current trends, both at Advantage and Aspen, prove that S&U has an abundance of these and trading since our year-end is encouraging. Of course, challenges remain. As Marcus Aurelius, a second century Roman Emperor and Stoic philosopher once said, "sometimes the art of living is more like wrestling than dancing". Confident in our people, business philosophy and the markets we serve so well, we wrestle on.
In his longer “Review” section, he goes on to again blame “a combination of prolonged and raised interest rates, a British economy sliding towards recession and, most of all, a flurry of regulatory activity” for the fall-off in profits.
Both customers and investors may be interested in the notice at the top of Advantage’s homepage:
IMPORTANT NOTICE: DISCRETIONARY COMMISSIONS
Advantage Finance can confirm that as a firm we have never used any form of Discretionary Commission Arrangement and has never allowed the broker to influence the interest rate for any potential customer. Therefore, this action being taken by the FCA does not apply to Advantage Finance and any of its past business.
This division is responsible for nearly all of the increased impairment charge, and its PBT fell from £44m to £37m.
There is a sign of S&U pulling back on its risk appetite, with annual net advances (i.e. new loans made during the year) falling from £187m to £176m.
However, the total value of the loan portfolio still continued to grow.
Comments by Anthony Coombs highlight the following important points:
Higher interest rates have increased the interest payable on Advantage’s borrowings.
The FCA has made “inquiries” into Advantage. One of these is around broker commissions.
Another inquiry is “focusing on affordability, forbearance and vulnerable customers“. This inquiry “has increased Advantage's costs and inhibited both the range of products we offer our customers, and our ability to sensibly help them maintain their loan repayments - which bolsters their future credit rating”.
Expanding on this later, he says “imposing restrictions on customers' ability to address their arrears, in pursuit of comprehensive and sometimes intrusive affordability assessments, may inadvertently lead to a preventable worsening of their credit scores”.
This sounds particularly important:
In response to ongoing concerns regarding the cost of living and its declared objective to "deliver quantifiable consumer benefits," the FCA has launched comprehensive inquiries across the industry, affecting approximately two-thirds of non-prime motor finance companies. In anticipation of the findings, Advantage has consented to specific limitations on its repayment processes. These modifications have temporarily influenced monthly repayments and recovery efforts.
The long-standing CEO at Advantage has retired and is replaced by a new CEO with experience at MotoNovo and Aldermore.
This division slowed down its aggressive growth: the loan portfolio only grew from £114m to £130m.
PBT was flat at c. £5m, despite an increase in finance costs of £3.6m.
S&U is optimistic on the outlook for house prices this year, seeing a rise of up to 5%, and possibly more in the South East (where most of the bridging loans are made).
Graham’s view
I’m a long-term fan of this family business, and a former shareholder.
But I switched to an “AMBER” stance on it late last year, due to the Chairman’s bearish language and my concerns over the possible consequences of the FCA inquiries.
The FCA’s actions are now having a real impact on the business, even if it’s true (as I believe) that Advantage has done nothing wrong.
Of course even without the FCA’s actions, the company would still need to grapple with interest rates staying higher for longer, and more customers experiencing difficulty with their repayments than had previously been the case.
It has taken the shine off the stock’s valuation, which tends to trade at a big premium to other lenders and at a premium to book value.
It now only trades around book value.
I calculate that S&U’s return on equity for FY Jan 2024 was 11%, an unusually poor result.
But my instincts are that in the long run, S&U will achieve the ROE of 15%-16% that it has in the past. This depends on a normal regulatory setup and economic backdrop. I have more faith in the latter than I do in the former.
For now I’ll remain neutral, but I’ll be very happy to give this one the thumbs up again when there is some clarity from the FCA.
Impax Asset Management (LON:IPX)
Unchanged at 440.8p (£585m) - Q2 AUM Update - Graham - GREEN
We looked at the Q1 AUM update from this fund manager in January.
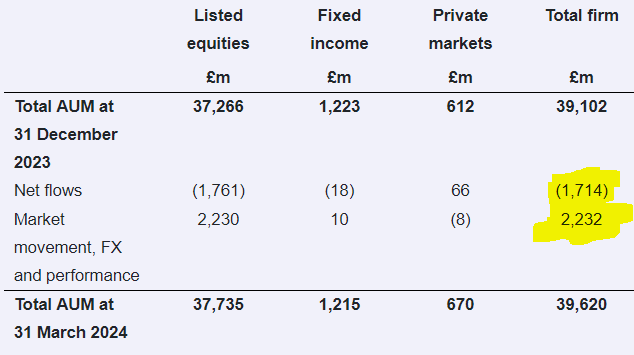
Net outflows have increased to £1.7 billion (Q1: £1 billion).
But once again, market movements have saved the day, more than fully offsetting the negative flows.
The result is a small increase in AUM, from £39.1 billion to £39.6 billion (+1.3% quarter-on-quarter).
Here are the thoughts of CEO Ian Simm, who describes the outflows as follows:
"I am pleased to be able to report another quarter of rising AUM in the context of sustained positive market sentiment. Although our net flows were moderately negative, the outflows were overwhelmingly from a small number of intermediary clients largely representing European private wealth, and we again recorded an increase in the number of institutional clients, and no segregated mandate terminations.”
Despite the relative weakness in the last couple of years, he says “asset owner sentiment around the transition to a more sustainable economy and associated areas of Impax expertise has improved in recent months”.
Clearly this is not yet reflected in the flow data, but maybe Q3 will be better?
Estimates: thanks to Paul Bryant at Equity Development for providing some estimates. These are:
AUM £41.1 billion at the end of this year (FY Sep 2024), rising to £46.1 billion (FY Sep 2024).
EPS 31.3p this year (FY Sep 2024), rising to 37.8p (FY Sep 2025).
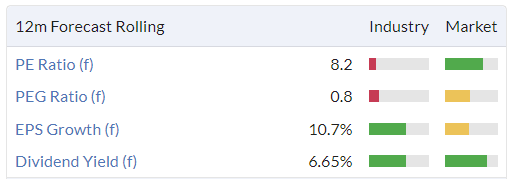
It is forecast that the dividend will remain flat at 27.6p (yield 6.2%).
Valuation: PER is 14.5x.
At the current share price, investors get £68 of AUM for every £1 invested in Impax stock.
Graham’s view
I’ve been positive on this one and I’m inclined to remain that way today as I see this as a long-term growth stock going through some temporary challenges.
A reminder of the deflation experienced by this stock:
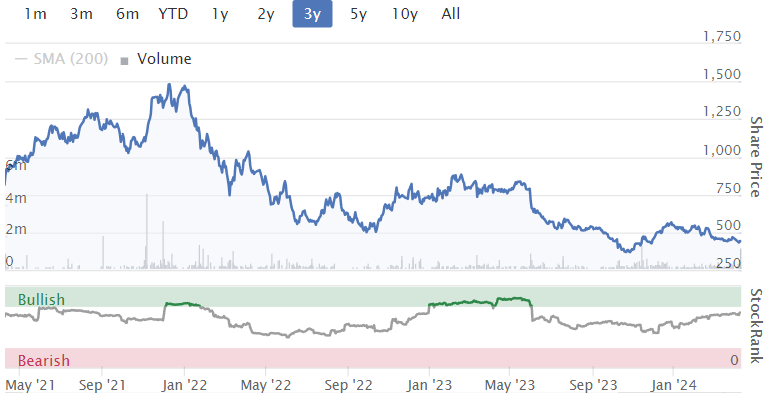
Up at the more testing valuations, I always thought it was a fine company, but was too expensive.
Now it trades at a fraction of its former levels, because it’s experiencing some outflows - this is when value investors should be interested in it, in my view. And I’m looking forward to seeing how it fares as it expands its offering, particularly in fixed income.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Seems to be a big old rampfest post Avacta (LON:AVCT) presentation.
What are your thoughts Paul Hill?
Know you're a big fan.
I hold a few, just in case
I work in the life science industry and the risk reward profile on Avacta (LON:AVCT) [I hold] is now better than it's ever been in my opinion with enough cash to progress their lead asset to a value inflection point after a painful fundraise. The therapeutic window on AVA6000 looks very promising with greatly reduced toxicity on their FAP targeted doxorubicin warhead vs standard chemo with early evidence of efficacy. Yes, there is a lot of attention on this one but that doesn't mean the science isn't solid but with all drug development the risk is high and moderating my exposure (5% of portfolio).
Over the years there have been frequent Israel based tech companies that have ended up providing costly surprises to their AIM shareholders. In Windward (LON:WNWD) I really thought that I had found a respectable company wth a sound, even exciting, future, and so far everything has been going well.
This afternoon we have the news that Ami Daniel has transferred his entire 6.5mm shareholding to a Jersey-based broker and the news, understandably, has smacked the share price. Cannacord is not picking up the phone and two contacts at Alma Strategic Communications are "not available"
Can anyone here provide a good/innocent reason why a CEO should do this other than to make a surprise sale?
Windward
Looks ok to me another director did exactly sane in February .
Maybe tax related .
I nearly bought in 6 months ago as I think it looks a good technology but looked too high risky so instead I sent the money to a man in Java I have no contract with and have known a year .
I think this is just silly market reaction to no real news based on the other 7% shareholder did exactly sane 2 months ago .
Looks a tax move if company sold at future point those gains may be tax free but I am certainly no knowledge of Israeli tax law .
I assumed tax too as Jersey is one of the more respectable global havens.I'ma bit annoyed i missed the lows in Windward (LON:WNWD) as i had my eye on them pre the conflict.I think the fact they mentioned a broking company spooked naturally.I assume they mean share broking and not any other kind of brokerage like shipping registered there or some other company he owns.Long shot perhaps.I doubt he would sell substantial amounts after this reaction though....
Might be worth while checking out the goliath in this industry Kongsberg Gruppen ASA (STO:KOGo) which is a chunky long-term hold for me and which has 5-bagged over the past 5 years. I cannot see how Windward (LON:WNWD) has the global credibility in this space, notwithstanding their recent contract win (for which they don't appear to have the FCF or capital to implement). I just cannot see where their competitive advantage lies. Open to all comments / ideas as always and could be wrong.
MPAC (LON:MPAC) just noticed management have some 3 year options granted but performance conditions are interesting.
Only vest in full if cumulative EPS exceeds 150p over a 3 year window. So in effect they have to average 50p p/a. As this year is expected at 38p EPS that suggests they see strong upside - ie EPS will need to be north of 65p in the 3rd year. At that point we could be looking at more than double current share price I’d imagine.
Then they have to hold for a minimum of 2 more years so needs to be sustainable.
Quite like this! Gives me a flavour of where management think they can get to over next couple of years.
Mpac
Are they free charge options or do they a market price entry point ?
Looks ok if as you say but please not free charge as that’s a dilution (theft I prefer to use the actual term )
MPAC (LON:MPAC) (I hold) A 25p exercise price I believe and we are only talking about 224,000 shares for the whole board, so just over £1m at current market price of £4.37.
That's not much dilution and an absolute bargain if they deliver cumulative EPS of £1.50 in the next 3 years. As Davidjhill suggests, the management must see rising EPS over the next 2/3 years for them to structure it this way.
A decent incentive for them to deliver and worth every penny if they do, I whole heartedly support this CEO and his bullish ambition for the business.
Not as good as buying shares in the market as a sign of confidence and still a bit of a freebie .
But apparently that’s how you motivate senior teams to deliver exceptional performance , or at least we are told so .
All party of the gravy train but at least in this case the gravy train has to get up to a decent speed .
Still think it’s largely bullshit and entitlement but that is Unfortunately the drivel we lap up .
Don’t think warren buffet and Charlie were fans on share options schemes let alone at a strike price hugely below market rate .
Still the greed in us condones it as we take the “if I get rich I don’t mind “
But to be fair not the worst, the RBG scheme of a few years back was totally outrageous yet they “got away with it” though if they completely screwed the company so no one got anything yet they lost nothing but shareholders did .
Have to disagree with you there Planetx, share options attached to decent hurdle rates are, in my opinion, the fairest way to align the interests of both the management and the shareholders. People should be incentivised, nothing wrong with that.
That's how I see it anyway and if I were in their shoes I too would want a decent pay day if I delivered the goods for my shareholders...
Let's just hope they do because this has now become my largest holding.
Yes but the strike price should be market price !!!
not 90% below it
Hi Planetx
I also like Director buying in the market and the directors have bought some themselves previously though small I think.
Not all options are bad. There is an appropriate remuneration amount that should be calculated on a total compensation basis for a board member. I’d rather less of this in fixed salary and cash bonuses and more of it in options structured the way these have been done by MPAC (LON:MPAC) . It incentivises management without heavy dilution and is aligned to my interests as a shareholder. The set levels are ambitious but not unrealistic and reward sustained success in a restrained way. This is the sort of reward that I see as being good for everyone.
I dislike companies like Tclarke (LON:CTO) where director comp vastly outweighs any benefit derived for shareholders - and that’s not option related either. Then you get some very greedy options as you say that don’t penalise failure but reward success disproportionately. This is really the responsibility of the NEDs to control. They don’t get options and should balance that on behalf of shareholders. Unfortunately too often that is not the case.
Just to let you all know that Mello2024 launched this morning and many of you will have received the email with full information. Do take advantage of all the discounts and come and join the 200 or so Stockopedia subscribers who regularly attend these excellent networking events. Paul and Graham will be there and Ed usually does a talk...
Two day event on 22nd and 23rd May...As I write 37 have already bought their tickets. Do come and join us
Mello2024 – Mello Events
Just bought my 2 day ticket, thanks for the link with the discount
Never been to anything like this so really looking forward to it
Staying for 3 nights in the hotel with my wife and looking forward to hopefully putting a face to the stocko name of some members maybe even while having a beer
Is there educational aspects to these events? Or is it pretty much only companies trying to sell themselves
Either way I'm sure I'll have a much better time than being at work
Callum
Why the drop in defence stocks this morning
What is causing g the slide in defence stocks this morning Qinetiq (LON:QQ.) BAE Systems (LON:BA.) Chemring (LON:CHG) all down to name but 3
Any ideas
I hold the first two
Rheinmetall AG (ETR:RHM) is down 6.9%; BAE Systems (LON:BA.) down 4.4%; Chemring (LON:CHG) down 4.1% and Kongsberg Gruppen ASA (STO:KOGo) is up 0.8%; Rolls Royce is down 3.6%. I hold all. They all got a little ahead of themselves ... that's all. The medium-term prognosis remains highly positive in my view. I am in the middle of writing an article for an Israeli site and when finished will post a link here for those interested in aerospace and defence stocks.
Yes some are down but not all, Avon Protection (LON:AVON) and Cohort (LON:CHRT), are slightly up today. I did consider topping up my Rolls-Royce Holdings (LON:RR.) but will wait. I thought Cohort (LON:CHRT) would have fallen, see the chart, I sold out a while ago waiting for a dip.
Froth coming off, probably needed post the near 45 degree share charts. I'm happy to continue to hold/ top up. Defense spending is multi year, not a 1/2 year bonanza like selling bikes during covid
Hello,
Defence companies getting whacked, why??
Goldman Sachs said in a note released on Tuesday that European defence
stock valuations now likely presented more downside than upside risk going into 2025
Hi
Ref defence stocks comments and broader European and some UK (large caps) sell offs .... this note (below) seems to explain some aspects of the price drops ranging from Rheinmetall AG (ETR:RHM) to Leonardo SpA (BIT:LDO) to Rolls-Royce Holdings (LON:RR.) and many others. I hold these three and others impacted.
The note is here ....
UPDATE 1-Rheinmetall leads defence stocks slump as traders worry after record run
 Leonardo SpA
News11:18 am(Adds analyst comment, detail, updates shares)MILAN, April 9 - Germany's Rheinmetall
RHMG.DE led European defence stocks into their biggest one-day
drop in a year on Tuesday, with traders turning nervous about
the sector's record-breaking run and analysts pointed to
potentially stretched valuations.
Defence stocks have been among the best performers in Europe
for over three years as portfolio managers poured money into the
sector, betting on rising military spending in the wake of
Russia's invasion of Ukraine in February 2022.
Goldman Sachs said in a note released on Tuesday that
European defence stock valuations now likely presented more
downside than upside risk going into 2025.
"While our Portfolio Strategy team are relatively
constructive on the European Defence outlook, they are not
recommending EU Defense given the challenging valuation premium
and recent outperformance," the note said.
A gauge of European aerospace and defence stocks .SXPARO
was down more than 3% by 0956 GMT, on track for its biggest
single-day fall since March 2023. The index has doubled in value
since Russia's invasion of Ukraine.
One Frankfurt-based trader said there was no immediate
reason behind the plunge and pointed to possible profit taking.
Rheinmetall was last down 10%, set for its biggest one-day
fall since August 2022.
Sweden's SAAB SAABb.ST , Italy's Leonardo LDOF.MI and
France's Dassault Aviation AM.PA were also among the biggest
fallers on the index, down between 4.3% and 8.6%.
At 20 times its expected earnings, defence stocks trade at a
45% premium to the broader European equity market .STOXX ,
versus a historical discount of 10%, according to Goldman Sachs.
(Reporting by Danilo Masoni, Additional reporting by Marleen
Käsebier; editing by Alun John and Dhara Ranasinghe)
((Danilo.MasoniTootsie Roll Industries (NYQ:TR).com; Reuters Messaging:
danilo.masoni.thomsonreuters.comThomson Reuters (NYQ:TRI).net))
Regards
Howard
Cohort (LON:CHRT) seems to be doing okay [I hold] as does Avon Protection (LON:AVON) [I don't hold but wish I did]
Hi Paul, if you get a chance could you take a look at HVIVO, thanks
On Surface Transforms (LON:SCE) I have decided to sell out this morning.
A -80% loss for me!
I've been in two minds about their automotive products and the environmental future of braking technologies. Yes their product is light weight and reduces sprung weight, however regenerative braking is the future but wether it can ever be enough to eliminate the requirement for waste heat friction and dust producing brakes is an unknown question? Then again cars are getting ridiculously powerful and will need ridiculous brakes.
And not to mention the extra weight of EVs - carbon brakes are very suited for that.
I've lurked on enough car enthusiast forums to form a view that Surface Transforms (LON:SCE) brakes are generally seen, technically, as better than the Brembo ones. Also cheaper I believe? So if they can crack the manufacturing and a good gross margin, then they are golden. But that seems elusive at the moment... and management are bumbling along...
I recall Surface Transforms about 20 years ago when I think it was located in Ellesmere Port. It appears to have made very slow progress since.
I caught this ffrom the 2023 interim announcement in OCT 2023.. My bold..
"Our operating loss (before non-recurring items) was£4.6 million compared to £2.4 million in thesame period last year. This is due to a number of ramp-up issues we experienced as our production capacity increased to meet growing demand. These ramp-up issues resulted in lost contribution of £1.6m and costs of £0.9m with equipment failures and scrapped production. We have overcome these technical challenges and do not expect these outlays to re-occur. Indeed, the work completed has resulted in improved production processes and the design of proprietary equipment."
My thoughts 20 years ago was that this was a specialist manufacturer trying to produce above average products for non-production line niche markets. This is usually a high margin business which factors in the cost of development trials and inevitable failures as part of doing business.
This niche type of business is light years away from supplying major auto companiies manufacturing on a production line needing reliable volume production delivered in the right place at the right time.
I am intrgued as to where Surface Transforms (LON:SCE) see themselves ending up in the supply chain and who their eventual market will be.
Dont hold
Good decision
I am very disappointed with the bid for Gresham Technologies (LON:GHT), a stock which I have held for a long time. What is the point of taking a long term view on companies, if the institutional investors take such a short-term view? Over the past decade Gresham Technologies (LON:GHT) has been building itself a revenue stream with a pretty much un-breachable moat. For this sort of niche software business, an exit PER of around 18 is robbery.
Presumably Kestrel reckons it can use the money better elsewhere. And in current markets they are probably right. But for the private investor who just wants to put his money somewhere that is generating a reliably increasing revenue stream and is at no risk of going bust, it is very, very frustrating.
I'm not so sure. Don't forget that Gresham Technologies (LON:GHT) was already facing the headwind in 2024 from the end of an £8.5m legacy contract that had a 13% margin. That's 17% of 2023 revenues. On top of that you have mention in the statement of 'extended sales cycles in financial markets' going forward. Kestrel being OK with the deal after holding the stock for such a long period, at little or no profit, is also a bit of a red flag.
Ultimate Products (LON:ULTP)
I hold
A well managed business performing well against a challenging economic backdrop. Capex light, financially sound with excellent cash conversion. 10% share buy back pending, which according to Equity Development will add around 7% to adjusted eps. Minimal difference between statutory and adjusted profits, which in my books is always a good sign.
Destocking by its supermarket customers is now easing but the growth opportunity lies mainly in Europe I would suggest with the development of the company's Petra brand. Trading in line, the shares are cheap on FY24 PE of 9.9 and 5% yield and forecast FY25 PE of 9 and 5.5% yield.
Hopefully there will be a cease fire in war torn Gaza, that should hasten an end to the shipping disruption in the Red Sea, which will be a positive for the company.
The management team lead by founder Simon Showman who has migrated from CEO to Chief Commercial Officer and CEO, Andrew Gossage have substantial holdings and logic suggests they will not lack for incentive to move the business forward.
A lot to like in my opinion.
Paul/Graham your views would be appreciated, time permitting.
Jonno
Agree saw them at. Mello .
Own their own brands which is good including Slater .
Well run .
Bit too much of a make everything in China importer which is not something that interests me though there is nothing wrong in that but the business is basically make a load of electrical stuff for x in China, stick our logo on it , sell it for 2x .
Good business actually I used to hold and was down to the X factor semi final when I was choosing where to jump invest a chunk after Mello .
Ultimately what put me off is totally illogical if not regionally racist but I didn’t fancy investing in scousers .
Chose the geordies and went deeper into Filtronic .
In this case chose right ,
Newcastle 1 - Liverpool 0
Sorry that’s a stupid post but I’m on my 5th day in bed after bad food poisoning so have to amuse myself whilst drinking my self concocted ginger/garlic/lemon/honey drink thar does seem to be working
ill get my coat but yes good company
Sorry to hear of your malaise planetX. I have a good knowledge of food poisoning and the related microbiology having spent a career in public health. Not sure whether the causative organism has been identified, but will leave that to you and your GP.
I am unsure of the background of the management team at Ultimate Products (LON:ULTP) , but the company is based in Oldham. More Mancunian that Liverpudlian perhaps.
Get well soon,
Ultimately what put me off is totally illogical if not regionally racist but I didn’t fancy investing in scousers
I think of Ultimate Products (LON:ULTP) as an Oldham company, not far from my home just over the border. And yes I hold for steady income with capital appreciation, though it’s not really characteristic of my tech-heavy fund - I just like a bit of local representation.
PS Hope you feel better soon - you’re grumpy enough on a good day ;-)
I think one of the top two was a scouser maybe the FD .
So a scouser FD in a Lancashire based company a red flag for any true Yorkshireman .
War of the roses and all that .
Mother from Lancashire, father from the North Riding. Born in Manchester, grew up in Newcastle. Cursed to support the Magpies for the rest of my life.
Hey, all of the North could do with more investment (even Sunderland ;-)).
Silver Bullet Data Services (LON:SBDS)
I don't hold but admit to being interested in Silver Bullet.
I know a few on here are invested, to me this mornings board change news suggests a fundraise in the offing. Any thoughts from the more informed?
Silver Bullet Data Services (LON:SBDS)
Hi Helvellyn- I don’t think the CFO change has any implication on funding. I know management want to minimise dilution and should now be cash flow positive. Remember they already did a small fundraise not so long ago to give them more headroom.
However, as has also been noted on here that headroom will remain relatively tight but equally the development on their 4D product has now been done and the team shrunk down again. Outside of this the business is not capital heavy so I think any fundraise will be if they see an opportunity to accelerate sales. However, I’m not sure I see what that would be from here - winning new clients feels more reputational to me.
I suspect the change is more a function of anticipating a much larger business going forward.
Just bad timing with results next month for CFO to suddenly depart with no prior warning??
Yes that’s fair topturkey. Timing could be better.
I bailed out of Silver Bullet Data Services (LON:SBDS) at 160p after a great run - I think they are going to need to do another fundraise. Once that happens though I may be back in.
Thanks Paul for circling back to Gaming Realms (LON:GMR) (I hold) - much appreciated. It looks like a possible GARP share to me although it'll be interesting to see what is said in today's IMC meeting about new territories having admitted in the results statement that no material new markets were entered during 2023. My fear would be if they have picked all of the low hanging fruit and growth into new markets becomes much slower going forward. Also they glossed over the poor performance of Social publishing so I'll be looking to see how they respond to questions about that aspect too.
Thanks also for the astonishing levels of output and coverage and for the always informative and entertaining podcasts too. Great stuff - it makes me tired just thinking about the workload.
John
I listened in to the Gaming Realms (LON:GMR) pres on IMC this morning and thought they were pretty good at answering key questions. Paul has already covered off response to his query on Licencing revenue - some 97% recurring - and they also clarified the tax issue. That may have been Paul again. US they have to pay tax on profits, UK they have plenty of losses to write off was my take.
Development spend is 3/4's Games, 1/4 Platform. They claim it has to be written off against when the revenue comes in so amortise Game spend over 5 years and Platform spend over 3. Doesn't seem unreasonable but makes the accounts complicated, imo.
On the cash balance I thought they fudged. They acknowledge it is building but simply said it could go on Buybacks, Divi or Investment (including acquisition).
Revenue expectations for the next few years looked promising. They see these games building reach for 4 or 5 years from launch in each market. More US states and substantial development in Canada expected this year. Apart from the sp a happy hold for me. Might be money tied up for a while that could do better elsewhere is the only concern but ok within a portfolio?
That's a good summary of the presentation. These are my notes for Gaming Realms (LON:GMR) :
Founder led by Michael Buckley and Mark Segal
- pretty much all of senior management team have gaming experience
Slingo IP acquired in 2015 but brand has been around for thirty years
-> GMR took Slingo to the real-money gaming sector
-> all games hosted on their RGS gaming platform
-> Slingo has its own section on gaming sites which makes it stand out
-> more operators = more players = more revenue
-> operator cohorts also tend to keep delivering growing revenue over time
B2B - Content licensing (core) and brand licensing
B2C - Social gaming (Freemium model with ad revenue)
Looking to add British Columbia, West Virginia, Greece, Lithuania, Switzerland, South Africa
-> with these ranging from ready to launch to making the first steps in the region
-> plenty of growth opportunity remaining
Content licensing growth basically all in US and UK
-> although 3/4 of that growth from existing operators rather than new ones
-> Canada and Italy growing fast but much lower revenues
-> will tailor content to these markets to improve sales
-> US states still growing apart from New Jersey which seems to have fallen a bit?
Distribution of games from other studios is a nice niche
-> won't be a big part of the business but happy to do this
Capitalisation of development costs not covered by amortisation
-> £2.7m on developing games and £1.1m on enhancing the platform
-> won't expense these directly to amortisation because games take maybe a year to go live
-> want to balance spend and revenues
-> amortise games over 5 years and platform over 3 years
-> games from 5 years ago or more still deliver revenues so amortisation schedule seems appropriate
Licensing revenues - which are one-off and which are recurring
-> almost all is recurring (97%?) which gives some future visibility
Tax credit because of large tax losses - £28m or some
-> pay tax in the US but don't currently pay tax in the UK
-> current losses probably cover about two years but might extend a bit
New Jersey sales have peaked?
-> very competitive market and updated their platform there last year
-> so had to republish games again which caused some volatility
-> also when New Jersey was the sole market it took sales from other states
-> hopeful that sales here will rebuild back again
Growing cash balance
-> could pay dividends or do share buybacks or invest the money elsewhere?
-> considering all of these avenues
(EDIT: drat, just realised W7L wasn't on my 2024 top 20)
Do you see yourself as Dick Dastardly or Mutley, Paul?
Sorry, couldn't resist!!
Double Drat! I got spooked by chatter here on Thursday about makeup shares in general and someone giving their target price of 32.70 and sold about 1/2 my holding in Warpaint London (LON:W7L) .
Anyway, can't complain and a big thank you to the Stocko team for drawing this one to my attention at 162.7p.
Warpaint London (LON:W7L)
Yes, I questioned the suggested £2.70 target price that day, as it sounded wrong, in my opinion. I've long held the opinion with this company that the Y/E 2025 forecasts look too low for the FY/E 2024!
I would not listen to the advice of the chicken bone shugglers ... stick to the fundamentals: finance, marketing, distribution, branding etc. Warpaint London (LON:W7L) is a superb long-term compounder in my view and is emerging as one of the more interesting shares in my portfolio.
Yes. You can’t blow your own crumpet for that one.
LOL poker111, well spotted from last weekend's podcast. The trouble is, I'm having to speak, read, and think all at the same time. So sometimes the wrong words come out! :-D Blowing my own crumpet was a good one though!!
From memory Paul, you also forgot to pick Warpaint London (LON:W7L) in your Top 20 last year too- third time lucky perhaps? ;-)
Impax Asset Management (LON:IPX) - Investment performance drives 6% H1 AUM growth
AUM was up by £2.2bn or 6% over H1-24, reaching £39.6bn on 31 Mar 24 (30 Sep 23: £37.4bn). This is slightly above the trajectory required to meet our FY24 AUM forecast of £41.1bn (+10% annual growth), but taking a cautious approach our FY24 forecasts remain unchanged.
A very strong investment performance was the growth driver in H1, contributing +£4.9bn (+13%) while net outflows were £2.7bn. We maintain our strong conviction that medium-to-long term structural factors favour Impax, but also flag some positive shorter-term cyclical data points which support Impax’s comments.
With strong growth prospects, margins and balance sheet, our fundamental valuation remains 800p per share, over 80% above the share price, and we see a PER of 14.5 as undemanding.
Link to research report: https://www.equitydevelopment....
Takeovers set to continue ....
"April 8, 2024 at 10:25 AM GMT+1
British stocks accounted for 70% of companies mentioned at least twice in an informal survey of 18 risk-arbitrage desks, traders and analysts conducted by Bloomberg News in March.
They included companies such as betting firm 888 Holdings Plc and Direct Line Insurance Group Plc. Overall, Amsterdam-listed Allfunds Group Plc won the single greatest number of votes.
The FTSE 350 Index’s record 45% discount to the MSCI World Index on a key M&A valuation measure, the multiple of enterprise value to earnings, is luring bargain hunters. Recent predictions have touted the UK as ripe for a takeover wave following a period of deteriorating business confidence and tough financing conditions."
Source: Bloomberg https://www.bloomberg.com/news...
A subscription site but three free article views per month I believe.
hVIVO (LON:HVO) in rude health at last, patience may indeed be a virtue, let the good times roll
hVIVO (LON:HVO) numbers were very good. More importantly the outlook - on track for £64m revenues and H1 weighted (much better than H2 weight we see from other companies) suggests a beat could be on the cards later in the year imo.
The company have also evidenced the strength in their business model - despite a characterisation study being cancelled they are still in-line. This is because of the 10-20% non refundable deposits, so those cancellation fees drop straight to the bottom line. It is one of the reasons pretty much all of net cash can be treated as their own, because even if there are pre-payments those are never refundable.
Margins strong at 23% (helped a little by accounting treatment of the new Canary Wharf facility funding) but once 2024 is out of the way the company expects to move upwards again towards 25% with a 4-5 year revenue target of £100m. That’s a CAGR of around 11-12% which, given the strength of the offering looks modest/achievable to me.
Brokers upgraded 12M target to 40p for what it’s worth.
Surprised it’s fallen a little but probably people buying ahead of results.
Surprised it’s fallen a little but probably people buying ahead of results
Other possible explanations include the lack of another big upgrade to forecasts disappointing investors who have been spoiled in the recent updates, or, counterintuitively, the apparently “in the bag” H1 weighting, which could be interpreted as declining earnings momentum in H2 - and, by extension, beyond.
All idle speculation of course, which buy and hold forever (okay 3-5 years!) investors can ignore.
Yes - that’s what I mean BnB - investors buying ahead of results expecting upgrades and then selling on in-line results and moving elsewhere. Anyone who follows this stock knew that wasn’t going to be the case. The forward look had already been articulated a couple of years back.
hVIVO (LON:HVO) have the full year (90%+) in the bag already and visibility into 2025 so no issues with declining earnings momentum. They are signalling the opposite. In reality the new facility in CW is opening early - that means earnings are brought forward hence the H1 weight, but this also generates free capacity further down the year - if they also sell that then i suspect there will be an earnings upgrade.
Hvivo and the temptations
Looks good
But what puts me off personally is that everyone is talking about it .
Feels a bit frothy .
There is definitely a feeling of money coming into the market and starting to feel like a small bull run is going to come where I think almost all stocks are going to catch a rising ride .
Temptation now is to chop and change and jump out of stocks you’ve held that might even have held their own in the bear market into new stars that are going to the moon etc and there are shares that are getting talked about a lot .
I’m not saying right strategy is to sit tight on your long term stuff or to jump into something that has momentum .
Sure everyone if feeling the same
I think some of the dross will start to jump sharply as easy money drives up the market .
No answer here , I’m waiting for SDG now to drop under a quid cod that’s silly
hVIVO (LON:HVO)
I don't know much about the company but I did watch a presentation by the CEO at the LSE about a month ago. He was a polished presenter and I think he was brought in to commercialise the company which, from the results, he has managed to do well. Considering how well he thinks hVIVO (LON:HVO) is doing, I was rather surprised he appeared to be hoping for a takeover. I put this to him in front of the audience but he denied it.
Not sure everyone is talking about hVIVO (LON:HVO) Planetx (sorry to hear of your food poisoning btw…..ugh!!) and its not like they are expensive or ahead or peers on valuation…..
But you are correct that money is starting to dribble into the market and that tide could easily lift all boats.
Speaking to my broker who has been saying investors are actually starting to focus on valuations (and particularly the valuation gap) again
On that basis I bought Liontrust Asset Management (LON:LIO) in my ISA. An 11% yield which looks covered even in a poor market. Trades on 10* PER whereas in a rising market historic averages are 13-15*. Add to that increasing AuM through inflows and increased prices and we could have a virtuous circle effect. Given the net cash no balance sheet concerns for me. If I’m wrong I get 11% p/a so I only need 4% capital appreciation per annum for it to meet my average annual target and if I’m right it could double in double quick time….geddit :-) !!!!!
Sanderson Design (LON:SDG) starting to look interesting I agree. Under a quid and I will take some too I think.
SDG
I’m pretty certain there’s a big sell order in the market from one of the major shareholders .
I took three pretty decent chunks in succession today and the price did not budge .
Normally it is very illiquid and a decent bite would spike it up .
Can buy plenty at 101.6 and sell at 1.0075 Which is pretty tight spread .
Sometimes on these smaller stocks with no liquidity you have to be bold and when there is stock to buy have to take the plunge .
Can’t see it going sub a quid but I’ve held some back in case it does
That’s the bowl fund pot emptied !
There's a 5,053 on the bid at 100p
There's a 13,806 order on the ask at 102p
Lion trust and my new scapegoat strategy
Bowl strategy is ongoing
Think I’ll run a parallel scapegoat strategy which requires a lot less of my work and may produce huge gains with minimal effort .
As David clearly knows his burnt onions and his thoughts seem clear on liontrust seems no reason for me not to buy this company and I can be secure in the knowledge that even if the shares fall I have the luxury of blaming someone else .
So David ok you are the first entrant to the scapegoat category and I hear you so I’m 100% following your advice and if it all goes south it will be all your fault .
Liontrust bought got my blame game first contestant .
As always USER (use someone else’s research )
Oh dear oh dear Planetx - I hope you have not been hallucinating on the concoction you’ve been making and consuming all day :D
Maybe LUSER is better (Losses use someone else’s research).
I thought you hated Asset Management stocks?
I do hate them
But I love you
Love beats hate
hVIVO (LON:HVO) Agreed on all counts David. After reading the RNS, I was expecting a tick upwards by about 2ppts.
They are hosting an IMC this evening so will be interesting to see what Mo says at that BnB.
Hi David,
I'm curious whether you have bought into Cathal Friel's latest venture European Green Transition (LON:EGT) , which IPO'd yesterday. I remember you saying you would back him early doors with new business propositions. I bought some just now.
Re Saga (LON:SAGA) , I share your dilemma. I have a medium-ish position and am wondering whether to buy more before their results. Underlying profits are supposed to be more than double last year (£21.5M) and it would be a very good time to announce a partnership venture for their cruise ships. My car insurance was with Saga last year and the renewal terms last month were for an increase of more than £200. I did find a cheaper provider (RAC) but the majority of quotes were similar to Saga. So I can see their insurance business being in much better shape before too long.
Hi Roger
I haven’t bought any European Green Transition (LON:EGT) as I don’t have any visibility over what assets they may or may not buy. I will watch it though and see if I see any value. It’s an odd one as it is outside of Cathal’s usual modus operandi which concerns me a bit - buying undervalued pharma assets is not the same as buying distressed green energy assets. I’m sure he will be talking it up so I will watch and wait.
Saga (LON:SAGA) I haven’t added to yet. Suspect I will kick myself but it’s had too many false starts in this recovery phase so I want to see some optimism from the new CEO. I’d like to see him buy some shares too!
Just to mention that European Green Transition (EGT) are presenting on the Mello show this coming Monday MelloMonday 15th April 2024 – Mello Events
Solid TU from Warpaint London (LON:W7L) this morning [I hold]. Strong top line growth with improved margins in Q1. Forecasting to beat market expectations for 2024. Worries about sector read across appear unfounded for this brilliantly run company.
Thanks for giving Gaming Realms (LON:GMR) the once over Paul - much appreciated! Also looks like Gresham Technologies (LON:GHT) might put you ahead in the '24 stock challenge with Graham perhaps :)
My morning smallcap tweet: Scrap performance chews cash at SCE
Cirata (LON:CRTA) Gresham Technologies (LON:GHT) Surface Transforms (LON:SCE) PROCOOK (LON:PROC) Active Energy (LON:AEG) Warpaint London (LON:W7L) Microlise (LON:SAAS), Ultimate Products (LON:ULTP), hVIVO (LON:HVO)
◄Cirata (CRTA)► Q1 bookings $0.7m ($2.1m). due to order delays. Reconfirms FY24 bookings guidance of $13-15m. [SP=49.5 Cap=57m]
◄Gresham Technologies (GHT)► 163p (+0.75p div) rec offer, a 27% premium. [SP=125.31 Cap=105m]
◄Surface Transforms (SCE)► holders left eating brake dust again as Q1 rev only £3m, same as prev Q4 and lower than internal target. "The single point of failure capacity constraints have now, almost all, been resolved." Keeps FY sales guidance of £23m but high levels of scrap in the factory has absorbed a sizeable amount of working capital and cash. Co looking at ways to raise cash. [SP=9.25 Cap=33m]. I hold.
◄ProCook (PROC)► Q4 rev up 5%, in line. Guides FY-Mar U/L pretax £0.5m to £1m, marginally ahead of market expectations of of £0.4m. [SP=26.8 Cap=28m]
◄Active Energy (AEG)► puts up CoalSwitch assets for sale - co "unable to raise sufficient working capital to build and/or operate a CoalSwitchÒ production facility within the appropriate timeframe". [SP=0.45 Cap=1m]
◄Warpaint London (W7L)► guides FY24 head of the market expectations as strong trading has continued in Q1. [SP=376.88 Cap=291m]
◄Microlise Group (SAAS)► FY-Dec rev in line, adj EBITDA up 15%, head of market expectations. Guides FY24 in line. [SP=167 Cap=194m]
In line: ULTP, HVO
Ultimate Products (LON:ULTP) - "Balancing sales growth with cash flow generation" (Interim Results)
Stable profits (EBITDA) and a marked reduction in bank debt were key features of Ultimate Products’ (‘UP’) interim results, released today. The company also announced its intention to buy back up to 10% of its shares. FY2024 full year results are expected to match current market expectations.
With revenue expansion likely to resume in H2 2024, and continue into FY2025, we argue that UP is more than capable of generating sales growth and free cash flow simultaneously.
Underlying 6% sales growth, a robust portfolio of six Premier Brands, the ability consistently to convert profits into cash and the prospect of a buyback programme support our view that UP’s shares merit a valuation significantly in excess of current levels. With a keen eye on relative valuation, we base our unchanged 250p fair value on 1.3x EV/sales, 10.3x EV/EBITDA and 14.7x P/E ratio. At this share price the dividend yield would still be 3.4% - i.e. in line with peers.
New research report here: https://www.equitydevelopment.co.uk/research/balancing-sales-growth-with-cash-flow-generation-interim-results