Small Cap Value Report (Tue 9 Aug 2022) - APH, BWY, RPS, HAT, LOAD, ZTF

Good morning from Paul & Graham. Today's report is now finished.
Agenda -
Paul’s Section:
Alliance Pharma (LON:APH) (£511m) (no section below) - many thanks to JCPr for flagging up (in yesterday’s reader comments) a very unusual situation here. The auditor, KPMG, seems to have resigned, and published a vague, but critical-sounding resignation letter, saying its relationship with the company broke down, over a corporate governance concern. Here is KPMG’s brief & vague letter, and APH’s response. These letters are rare, and are not issued lightly. Hence personally I wouldn’t want to be holding this share, as I’d be worrying about what has gone on at the company to prompt KPMG to issue this unusual public criticism. Deloitte is the new auditor, so another big name firm.
Bellway (LON:BWY) (£2.9bn) (no section below) - not a small cap but… I like to read housebuilder updates, for general read-across to the economy as a whole. Things sound fine here. Continued strong demand. Mortgage availability remains good. Low unemployment. Help to buy scheme ends in March 2023, but doesn’t seem a concern. Building cost increases offset by higher selling prices. Ongoing planning challenges (delays). Availability of materials gradually improving, but still some regional shortages. Net cash of £245m (listed housebuilders generally have really strong balance sheets, far better than at the outset of previous recessions). Record output expected in FY 7/2023, but H2 weighted.
My view - I like the housebuilding sector right now - valuations have come down heavily, balance sheets are robust. Interest rates are only expected to rise to c.3-4%, which doesn’t strike me as anywhere near enough to trigger a housing market crash. Higher nominal incomes suggests house prices could remain robust, but nobody knows at this stage.
RPS (LON:RPS) (no section below) - congratulations to shareholders here, with an agreed, cash, takeover bid at 206p announced - a tremendous premium of 76%! Wow, that’s a superb exit price. Interim results are also announced, with trading ahead of expectations, and a good outlook. The bidder is WSP - a large Candian consulting group, which is itself valued highly (Stockopedia shows a forward PER of nearly 25). Therefore paying a 76% premium for RPS takes RPS’s valuation up from a forward PER of 14.5, to 25.5, similar to WSP’s.
I always look at takeover bids, and see if there were any obvious signs to have spotted. There’s nothing in RPS’s numbers previously to get excited about. Looking through previous SCVRs, to me, it looked quite a good company, priced about right. I suppose the opportunity here was to investors who spotted that valuations abroad seem to be much higher, thus making RPS more attractive to an overseas bidder. Well done to investors who spotted that! I wonder if there are other companies/sectors where similar disparities exist between UK valuations, and those abroad, which could see takeover bids? Any ideas? There’s obviously an element of luck too, because takeover bids are very difficult to predict. Bidders can be attracted by aspects of a company that might not be obvious from its figures. Anyway, it’s great to see a generously priced takeover bid, let’s hope we have more, to give the UK market a boost.
Zotefoams (LON:ZTF) - I've spent a few hours looking at this, on publication of good interim results today, and ahead of expectations outlook against lowered forecasts, which have today been raised by 6%. I also had a good Zoom with management, to deepen my understanding of the company, its products, and a Q&A session. I've got a favourable impression of this share, and it looks set up to beat market expectations after a strong H1 & good order book. Balance sheet is fine, and benefits from freehold property factories. Debt is likely to come down considerably in the next few years, as big capex programmes are now done. Blue sky upside is in for free, with re-Zorce recyclable drinks carton. Overall, it's a thumbs up from me.
Graham's Section:
H & T (LON:HAT) (£165m) - barnstorming results from the UK’s largest pawnbroker. The pawnbroking pledge book is up by 27% in six months and daily lending volumes are 40% higher than they were pre-Covid. Revenues and profits are both up by more than 40% compared to a year ago, and the company continues its dividend tradition (payouts every year since 2007). The very difficult economy means that H&T’s services are in greater demand than they’ve ever been. I don’t see this improving in the short-term, so I think it’s possible that H&T can hit its broker forecasts of much higher profits in the years to come. The new management team is doing a fine job: if they can continue their selective approach when it comes to acquisitions, and open new stores very carefully, I expect shareholder satisfaction to remain high.
Crestchic (LON:LOAD) (£64m) (+16%) [no section below] - this is a designer, manufacturer and international supplier of load banks to a wide range of industries. Until June of this year it had the less interesting name, “Northbridge Industrial Services”. However, in 2021 it carried out a strategic review and decided to make a disposal, leaving it to focus on its load bank business. This business has had an excellent post-Covid year and has now raised its expectations three times.
Today’s trading update is significantly ahead of expectations: the FY 2022 revenue estimate is increased by 9% to £42.5m, and the EBIT forecast is raised 36% to £7.5m (by Equity Development). FY 2023 estimates also see substantial upgrades (the EBIT forecast for next year is now £8.1m). The demand for rentals is particularly strong, as Crestchic reports having secured “its largest ever hire contract”, and there is some visibility for 2023 as “a significant proportion of the work secured over the past two months will continue into next year”. Major tailwinds include the growth of data centres worldwide and increased oil and gas exploration in Asia and the Middle East. Price increases are being passed onto customers “sensitively” to maintain sales margins.
This company has some interesting features: it has a track record stretching back to the 80s, it designs its own gear (although I don’t know if there is proprietary technology involved), it has international diversification, and it is comfortable with both rental and sales. Judging by its new profit forecasts, and very low borrowings, there’s a case to be made that it’s undervalued at current levels.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Zotefoams (LON:ZTF)
273p (up 12% at 09:40)
Market cap £133m
9 August 2022 - Zotefoams plc ("Zotefoams", the "Company" or the "Group"), a world leader in cellular materials technology, today announces its interim results for the six months ended 30 June 2022.
I’ve got a call with management arranged for 10:45, so I’d better do some work on these numbers and think of something intelligent-sounding to ask them.
H1 revenue up 23% to £59.0m (up 21% at constant currency)
Cost inflation offset by selling price increases - a key positive in my view.
Gross margin held steady at 28.9% (seems quite low though)
Profit before tax up 42% to £5.7m (a healthy 9.7% profit margin) - great to see profit rising faster than revenue.
No adjustments to accounts, which I like. Growth has been mainly organic, so there’s only £2.3m of goodwill on the balance sheet [source: 2021 Annual Report, note 12]
“Good momentum” for H2, with strong order book.
Net bank debt £37.0m, but this looks fine because it’s secured on freehold property in the books at cost of £31.6m (see note 10, 2021 Annual Report) - including a large site in Croydon (since 1938!), and another in Kentucky, USA - it’s great that ZTF owns its main factories (Poland is leased).
Inflation/supply chain -
"Input inflation, other than energy pricing, has moderated and supply chains are operating more normally, however, there is a heightened level of risk associated with macroeconomic factors and the demand environment.
Outlook - positive -
"Whilst remaining mindful of these risks we now expect full year underlying profit to be ahead of current market consensus expectations.
I suggested to management that a footnote would be useful to explain what market expectations are. Their broker didn’t like that idea, apparently. Time to change broker maybe? After all, it’s a small cap, so Peel Hunt & Investec are not suitable brokers, as they don’t have any interest in private investors - but we’re the market for small cap shares, hence the misalignment.
Bank debt - looks quite high, at £37m. I asked whether interest rates are hedged, which they’re not - the rationale being that debt should reduce quite quickly now the main capex has been done.
A competitive tender process was undertaken (smart move!) that resulted in ZTF staying with Natwest & Handelsbanken, but on improved terms.
Going concern note - nothing of concern, it’s fine.
Balance Sheet - looks fine to me. It’s a fairly capital-intensive business, with £95m of fixed assets, but that includes £31.9m in freehold sites.
There’s a pension deficit, but I confirmed with the company that deficit recovery payments are fairly modest, at under £1m p.a.
Customer concentration - is a risk, with the largest customer (Nike) generating 33% of H1 revenues.
Aviation sector - now a tailwind as demand gradually returns.
New products - ZTF has developed a novel, fully recyclable drinks carton, called re-Zorce. There could be exciting future upside from this, if the product takes off. Management says there’s considerable interest in it, but it’s pre-revenues, being in trials which are now scaling up. This could be a nice catalyst for a re-rating, if the newsflow is good in future. Or it might not, so I would see this as a bonus if it comes off.
Valuation - estimates are raised today, to 14.4p for FY 12/2022 - a PER of 19.0 times, which seems expensive, but I wonder if the forecast is set too low? Full year PBT is forecast at £8.8m, but it’s already made £5.7m in H1, leaving just £3.1m to do in H2. Seasonality usually evens out between the 2 main divisions, another reason to expect H2 to be similar to H1, and hence beat forecasts for the year.
So I reckon the actual out-turn for 2022 could be better than forecast. In difficult macro times, we need modestly set forecasts.
Quite punchy growth is forecast for 2023 & 2024, at 21.8p and 27.5p EPS respectively. If those numbers are achieved, then I think a share price of 273p now would probably have increased maybe 50-100% by then.
My opinion - I’ve just had a really good Zoom with management, to try to better understand this business. My impression was certainly positive, so it was worthwhile spending the time to dig a bit deeper in this today.
It’s strange that broker consensus forecasts have been falling (from about 18p, to 13p) this year, yet the company has now put out positive interims, and is ahead of (lowered) expectations. Still, that’s preferable to forecasting too high, then having a profit warning.
Overall, I give ZTF a thumbs up - this looks an interesting business, well-managed, and performing well. Hence I think it’s a good one for readers to do some more research for yourselves on, taking a long-term view of course. I’ve no idea, as always, whether or not this is a good time to buying the share, that’s up to you to decide.
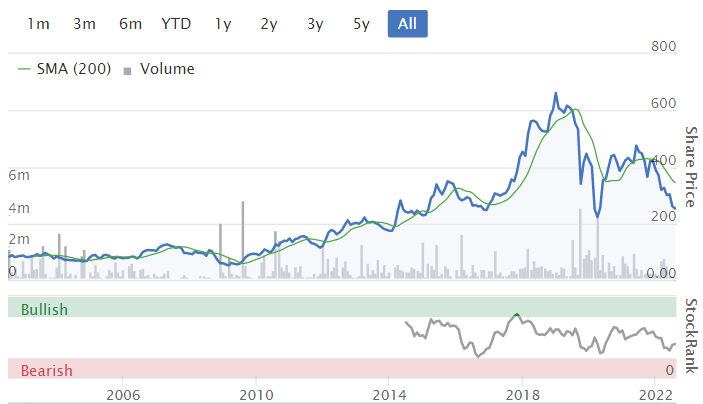
Looking at its long-term chart, ZTF shares got onto a fancy, growth company rating previously, but have since sold off heavily onto a much more reasonable rating. Hence I find this much more attractive as a value/GARP investment proposition, than in the past.
.
Graham’s Section:
H & T (LON:HAT)
- Share price: 414.5p (+1%)
- Market cap: £165m
This is the UK’s largest pawnbroker. I don’t currently have a position in it - maybe I should!
Today’s interim results follow a trading update last month that gave us a glimpse of what these numbers might be.
It turns out that the pawnbroking pledge book is even bigger than that trading update suggested. This loan book is now £85.1m (versus £84.2m according to the trading update).
This is up by 27% in six months: an extraordinary growth rate for a mature business. It’s a sign of a very difficult economy, as demand for these loans is “at record levels”, and lending volumes are “40% above pre-pandemic norms”.
It also doesn’t hurt that the average price of gold was up by more than 10%, compared to last year, as this allows for larger loans on the same items.
Retailing is doing very well, too - retail sales of £20.8m (H1 last year: £12.4m).
I’ve gone back to check the pre-Covid performance in H1 2019. That year, H1 retail sales were £18.5m, and the number of stores was substantially lower than it is today. So I think the retail performance still has a distance to travel, to make a complete recovery.
That doesn’t worry me too much, however, because what really matters here is the pledge book, and its performance is stunning.
It’s the large pledge book that distinguishes H&T from all the other small lenders, even from other pawnbrokers. Back in H1 2019, H&T’s pledge book was smaller by more than a third.
Let’s see how this translated to revenue and profits:
- Revenue £77.8m (+49.7%)
- Operating profit £7.4m (+41.2%)
- Pre-tax profit £6.7m (+44.3%)
These numbers are not adjusted - they are the statutory accounting results.
Balance sheet
Net assets finish the period at £139m, after £3m of dividends were paid out. Excluding intangibles, book value is £116m. So H&T is now trading at a meaningful premium to book value - something that I thought H&T deserved.
There was a large cash outflow, as it’s not possible for H&T to grow its pledge book at a fast pace without borrowing to do so. Receivables (a proxy for loans outstanding) increased by £18m, and this was paid for from H&T’s profits and with the help of a £15m increase in borrowings. All told, net debt finished the period at £8.6m.
Outlook
Some key points from the outlook:
- The company is looking to expand its geographic coverage. I would have said the existing coverage is already quite good, so I hope they are very careful with this. Remember that 70 stores were acquired as recently as 2019. Five new stores have opened this year, and another three are opening this month. Hopefully the terms of new leases are flexible and cheap.
- Consolidation: the company thinks that more opportunities to consolidate the sector may present themselves. I’m not so sure about that: with a high gold price, the sector is likely doing well, making it a bad time to make more acquisitions. The purchase of Money Shop in 2019 was a special situation.
- Retail/FX are both set for a strong year. In retail, H&T has recently gained additional expertise in watches and is developing this line of business. In FX, overseas travel continues to recover and should support FX demand.
And the main point: that demand for pawnbroking will remain robust in these conditions:
We anticipate continued strong demand for our core pawnbroking product as the impact of inflation on the consumer increases the need for small sum, short term loans at a time when supply of credit is more constrained than has been the case for many years.
My view
I’m surprised that the H&T share price hasn’t moved much today, but I guess people were expecting the good news. See how much the share price had already moved in recent weeks:
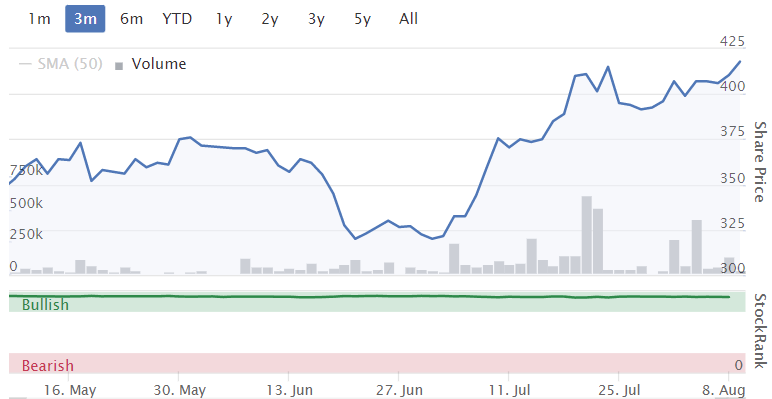
The company’s broker previously flagged that it would raise this year’s PBT estimate by 15%-20%. It has today raised the estimate by 18%, to £18.7m.
For FY 2023, it is forecasting PBT of £28.8m, and then £33.6m in FY 2024. This is based on the massively larger pledge book continuing to grow.
I do think that these very large increases in profitability are possible. My only concern is that management might throw caution to the wind and sign lots of leases, or make acquisitions, at prices that aren’t in the long-term interests of the company.
To be clear: I don’t think they’ve put a single foot wrong so far. Their acquisition of the watch repair business makes good strategic sense to me, and I have no problem with the pace of store openings thus far. I just know that when profits are booming, it can be very difficult to say no to deals!
H&T’s current CEO joined the business in late 2020/early 2021. You can view an interview with him here, where he talks about “evolution not revolution”. If he can stay true to that mantra - and say “no” to as many deals as possible - I’m confident that he’ll succeed.
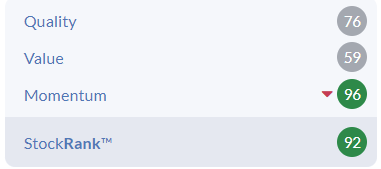
This is also a Super Stock, with good quality and extremely strong momentum:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
A small point. Peel Hunt provide some basic financial input to ii - now owned by abrdn - which is I think the second largest online platform for private investors in the UK. I occasionally use their research as a checking tool. So not entirely useless to smaller PIs with an ii account.
Elementis (LON:ELM) - RWS Holdings PLC (LON:RWS) - Spire Heathcare Group (LON:SPI)
seem to me to be prime takeover candidates and are held by Odyssean Investment Trust PLC (LON:OIT) - ELM and RWS have substantial overseas earnings and hidden value and Spire has a large land bank and its largest holder Mediclinic International is being taken over at this time.
Can't see RWS being taken over unless Andrew Brode wants to sell. Think he has around 23% of RWS. A sale of his holding probably wouldn't be CGT exempt, and the resulting cash would attract a big IHT bill when he passed it on to his children.
RWS Holdings (LON:RWS) Bear in mind Andrew is 80 and Barings considered a bid earlier this but did not proceed. The bid was not resisted. AB is the largest shareholder and would have a major influence on any bid.
Bearing in mind various good quality companies are being taken over by North American companies I would not discount a bid. I HOLD.
Thanks for the comments on Alliance Pharma (LON:APH) Paul. (I hold but not as many as I did yesterday). In the end I decided it was just a small cockroach in the kitchen, as it was just about a £10m provision for a fine, but it was still a cockroach.
Crestchic (LON:LOAD) (no position)
Congratulations to all holders today. That's a lovely c20% increase and I regret not buying last month when planetx kindly shared his site visit thoughts with us.
One of the main things that has put me off from buying is that we haven't had any numbers all year and it's already August.
With 2020 and 2021 being unusual years, I'm not really sure how profitable the company will be, or perhaps more importantly, how much free cash will be generated.
I'd be particularly interested in seeing what Operating Costs look like so far this year. Will they increase in line with revenues? Or will they be relatively fixed? Were there any government-support numbers in last year's results? It's hard to tell what is "normal" from only 2 years of data.
---
Crestchic (LON:LOAD) is the #3 player in the market, which makes the growth even more remarkable. I would have thought they might struggle against bigger players (if memory serves me correctly, I think Siemens is #1.)
Another doubt I had was that Nvidia reported this week and stated that their data centre revenue were hit by supply chain issues.
30% of Crestchic's revenues in 2021 came from Data Centres.
I was very close this morning to pressing the Buy button, but I often find that being trigger happy does not always work out for me. Having said that the company does seem very lowly valued and I imagine that I'm overthinking it.
Sadly I think I'm going to wait for the numbers next month when I will undoubtedly regret not buying today.
GLAH
A
I've always liked H & T (LON:HAT) Graham, and remember writing here a couple of years ago what a good advance purchase it would be with recession looming and if Gold didn't nose dive. Somehow or other I divested myself of a holding in the interim thus ignoring my own assessment. However I did buy a very nice second hand watch from their online store 18 months ago, it doesn't keep time but one mustn't sweat small details, and H&T have at least bought a repair business now to repair all the duffers they sell, that's what you call a sticky customer.
As a slight detour H&T, if readers have one to hand locally, is very good for foreign currency given that most high street banks have lost interest in cold hard cash. I took some funny money of my fathers into a H&T during lockdown to swap for the coin of the realm, and being a bit long in the tooth Dad had under counted it (by some considerable amount). I'd have been none the wiser were it not for a very honest teller in the store. First class business.
Excellent report on HAT, thanks Graham
You're welcome Martin! G
Has anyone (more savvy / knowledgeable then me about figures / acquisitions) taken a look at Supreme (LON:SUP) (I hold) who today announced they’re buying Cuts Ice who own T-Juice, I can vouch they offer superb premium E-liquid, namely their best seller ‘Red Astaire’ my all time favourite and the sole e-liquid I use. I think / hope in the future this will prove to be a really good profitable acquisition.
re £SUP (I hold)
Supreme (LON:SUP)
[Edit - good old Stocko why does £epic work on one line and not another?]
The detail of this morning's announcement is difficult to unravel because it is the trade and assets that are purchased, not the companies themselves, which are subsidiaries of Rocket Science Holdings and no figures are given.
At the end of the day I trust the business acumen of Sandy Chadha to make an earnings enhancing aquisition.
@sharw. When the £epic fails to translate for me, it's usually because I put a full stop after it.
It is a bit inconsistent, can't see any fullstops. Sometimes putting a , after it makes it work but not always. It does not work with . and ? after it.
Why would a company sell it’s trade and assets only ? I don’t understand … ? What aren’t they selling ?
Supreme (LON:SUP)
Dan B - they are not selling the companies as such. What bits they are keeping I know not as I was not a fly on the wall during negotiations. In particular I have looked at the holding company - ROCKET SCIENCE HOLDINGS LIMITED Company number 10300031 - and it has an interesting share structure. Lloyds Bank via Lloyds Development Capital holds 200,000 shares, Nigel Quine 250,000 and two others 61,111. Nigel Quine resigned from all 3 boards in February. Make of that what you will - we do not know what was going on but those involved in negotiations would.
I think we should concentrate not on that but on what is being brought in to Supreme. Apart from brands at the other end of the price spectrum from the 88Vape budget end there is some leading expertise as spelled out in Edison's Report.
We also need to look at revenue. Supreme's vaping division was £43.6m to 31/3/22. Cuts Ice was £15.7m to 28/2/20 but then it was hit badly by lockdown because it traded mainly through physical vape shops that were closed and so revenue was £11.1m to 2/21. I think they have learned from this and a search for Red Astaire shows it is now in many of the leading online vape shops. Hence I suspect that revenue to 2/22 (not published) will be not just back to 2020 levels but could be heading towards £20m. That sort of volume would be quite an add-on to Supreme's existing.
thanks @sharw yes seems more detail is required and some shenanigans going on at Rocket Science, totally agree though an interesting acquisition allowing Supreme (LON:SUP) to enter the premium end of the market, looks promising
Too late to edit but need to correct myself - the report is from Equity Development, not Edison - embedded link is correct.
Thank you for that Graham, I'm hoping there's a read across to Ramsdens (we hold).
I hold both H & T (LON:HAT) & £RFX. Holiday cash is a larger part of Ramsden's business so it is the extent to which that has recovered that I expect to be the biggest factor when their results come out.
RPS (LON:RPS) Paul in your last analysis (24th June) you observed that 'Sector expert Simon Hedger @vodkaquickstep on Twitter has pointed out the takeover potential here, and he’s got it right about that in the past with other companies, so that's something to consider' so you did provide everyone the correct information... I checked out his Twitter feed today and he is commendably restrained on the takeover coming to fruition
Hi colin1862,
Thanks for that, I'd forgotten mentioning Simon Hedger here re RPS (LON:RPS)
What a result for him, I wonder what else he's got his eye on?!
Regards, Paul.
Regarding the RPS (LON:RPS) takeover, I would suggest that Ricardo (LON:RCDO) is developing a similar profile. Summary from recent trading update by new CEO, Graham Ritchie. Ricardo (LON:RCDO) is modestly price, more so than RPS (LON:RPS) prior to today's offer. I hold.
'I am delighted that, over the course of the year, we have continued to deliver in line with our expectations. We have made significant progress in FY21/22, delivering a very good financial performance with increased order intake across all our business segments and a strong operating cash conversion.
Since joining the Group in October 2021, I have completed a thorough review of the business and recently launched our sharpened strategy, shaping Ricardo's future to become a leading environmental and energy-transition consultancy.
We will achieve this by establishing a clear focus that prioritises high-growth and high-margin solutions and by being rigorous and disciplined in our execution. By doing so, we aim to deliver sustainable and profitable growth, creating value for our shareholders, our colleagues and our customers.
This is an exciting time for Ricardo'
Hi jonno, thanks for flagging Ricardo (LON:RCDO)
I remember looking at RCDO a while back, and thinking it looked a good business, and reasonably priced. I think there might have been some problem, or restructuring, but can't remember the detail now.
Looking at RCDO's StockReport, it seems very attractively priced (fwd PER 11.4) compared with the 25x PER take-out multiple for RPS. That's assuming RCDO meets/beats expectations though. Ah I've just spotted the TU dated 26 July 2022, which said FY 6/2022 was in line with expectations. Strong order intake, and £340m order book at year end, up 15% on prior year. Net debt coming down.
This looks an excellent spot, thank you! I'll do some more work on this, and might have a little dabble.
Regards, Paul.
Your welcome Paul, I intend to add using dividends as my portfolio is fully invested and held within an ISA, which means having to sell to buy. Somewhat restrictive but imposes a degree of discipline.
Good luck
Crestchic (LON:LOAD)
I see that Equity Dev are forecasting 9% sales growth in 2023 which looks too low to me given that the load bank market is forecast to increase at 10%/annum and this years sales are forecast up 37%. In addition a previous Stocko contributor who went on the recent Crestchic site visit, commented that their old factory site appeared to him to be not fit for purpose and that in contrast the new factory site that increases production capacity by 60%.
So looks like Crestchic (LON:LOAD) may well continue to out preform. I topped up this morning.
ED........Stripping out the loss-making Tasman Oil Tools business (including joint ventures), we anticipate revenue growth improving to 37.5% yoy in FY22, followed by 9.1% in FY23 and underlying EBIT margins to rise from 12.9% in FY21 to 18.8% by FY23. With interest payments remaining at low levels, this feeds through to adj. PBT and a more than doubling of adj. EPS yoy in FY22.
Crestchic
Regarding the site visit and what I saw / discussed with them / the chairman Peter Hook .
We walked round their existing facility and as we walked round I said
“Is this honestly where you have been doing all your production”. , they were working on a 350k loadbank destined for the US military in San Diego (submarine I think)
I asked how on earth they got it out of the building as there seemed to be access apart from through the staff car park .
“Errr, we have to get all the staff to move their cars every time we move goods in /out it’s a total nightmare “
In a nutshell the existing facility was pretty much not fit for purpose and as someone with a level of manufacturing experience it was far from ideal.
The lack of capacity increased leadtimes significantly and also meant they could not build inventory levels .
When we came to the new facility it was crystal clear this would be a game changer , I asked how much this Couid do for turnover .
He says they could now produce 300% more do this would last them for the foreseeable future .
I then pointed out that I thought it would only last them 24-36 months as their sales would double within 12 months due to
- shorter leadtimes
- ex stock inventory
The new facility isn’t quite operational so this isn’t even kicking in yet .
And that they needed to be looking at what happens after that , We agreed “this would be a good problem to have “.
I don’t think the market has recognised this nor does it need to, Operational efficiency and ability to produce product in a strong market when previously you had been hamstrung is a big game changer .
To be honest if I had seen the first facility on its own I would never have invested, .
Anyway clearly Im a fan
Hello Graham, I dfont kow whether you are in today.
You commented on Mincon (LON:MCON) yestrday. I was sometime in ancient history a shareholder of this stock. I became utterly bored out of my mind with it, wondering where it was going. The quality seemed great, the service great but where was it going? I am still in the same frame of mind.
You mention Greenhammer as a potential game changer and maybe it is the time........... Who knows? I can only say that the company doesnt really go much further on what Greenhammer will bring and when. You dont either, to be frank. I have done some research - as we are always encouraged to do and quite rightly. I have followed Greenhammer back and the most meaningful reference I have found was back in 2018, as follows:
Michael O'Dwyer, Irish Times Tue Dec 11 2018 - 17:51
Irish engineering company Mincon Group PLC has started using a new drilling system which it claims is a potential "game changer" for the mining industry.
The Irish engineering company, which specialises in developing, manufacturing, and servicing hard-rock drilling tools, successfully fitted its Greenhammer technology on a customer rig in Australia last week. The system is "working in line with expectations", according to an announcement by the company.
Mincon, which posted a 30 per cent rise in pre-tax profits in the first half of this year, is aiming to achieve up to three times existing drilling speeds using the new hydraulic hammer system. "The Greenhammer technology is a significantly disruptive product, delivering substantially higher performance than the existing products in the market, thus the market for it is significant," said Colin Sheridan of Davy Stockbrokers.
Further testing
If the technology is brought to market, customers will need fewer rigs to carry out drilling operations in the same time as previously. “If you need a certain number of holes drilled per day, using the old system you might need 10 rigs. Using this system you might need three or four . . . The system actually saves [the customer] a lot of capex,” said Mr Sheridan.
The technology will now undergo further testing. Mincon said it expects that this phase may take several months “while the integrity and robustness of the system in use is trialled and improved”.
Following some delays developing Greenhammer this year, its use in production now represents “a large step towards commercialisation” of the technology which and is “likely to become a game changer for both Mincon and the industry,” said Mr Sheridan. He said that Greenhammer is likely to deliver revenues in the 2019 financial year.
“While some risks to the ultimate commercialisation of the technology remain, we have now passed a critical point where the system becomes significantly more likely to be commercial,” said Mr Sheridan.
Now, I start to get excited - 3/4 rigs generating the same output as 10 rigs formerly, but look at the dates of the report. End of 2018, likely to impact profits in 2019......but it didn't happen. I guess that Covid 19 could have had some impact from 2020 onwards, but where is the progress now?
In fact, if this is as game-changing as it could potentially be, does Mincon (LON:MCON) have the patents and the corporate power to take advantage of it? It would be great to have a conversation with the management to get a true update of the current expected time lines for significant scale implementation. By the sound of it from the Irish Times report in 2018, every mining company of whatever size should be falling over themselves to take advantage of it. We are talking revolution here, aren't we? Are we? Help me, someone.
Hi ridavies, thanks for doing some digging into Greenhammer. I couldn't go into the details because I don't know them myself! It's an intriguing wild card but whether it is really worth anything and will succeed, I have no idea. As you say and as management will admit, it has been in the works for a long time. Best wishes, G.
Crestchic (LON:LOAD)
This is a fantastic update and well worth a few minutes of your time to read - the 3rd ahead update since the beginning of the year - today significantly ahead.
Peter Harris exec chair has truly transformed this biz since he took over.
Initially a conglomerate of the high potential Crestchic and the poorly performing Tasman - today the sale of the final part of Tasman was reported. This means everyone can focus solely on Crestchic.
I went the opening of the new factory in early July. The business had a family feel about it. I spoke to various members of staff who had worked there for ages, they recommended their friends to work there.
I spoke to Peter Harris who had his feet firmly on the ground and knows exactly what to do to get this biz performing well. I note there were no figures in the update but I am very confident the Interims on 29th September will read well. This business has strong tailwinds which I always look for in an investment.
I started investing end 2020 and have been adding since. Happy holder.
Investegate |Crestchic PLC Announcements | Crestchic PLC: Trading update-significantly ahead of expectations
For all the happy Crestchic holders below , Equity Development have bumped up EPS est. by 37% and now see Fair Value / share at 283p . Full note is here: https://www.equitydevelopment....
HAT - excellent interims today, all important areas up including EPS and the dividend. Moved from net cash to debt to fund inventory
Staffline (LON:STAF) - Non Exec buy of 350,000 @39.664
Hello eParro, re £STAFF non exec in this case is part of the principal shareholder, Henry Spain so they are increasing their share. Picking up shares in the market I guess after the disappointing Trading Statement recently where the shares fell around 10%.
Crestchic definitely becoming the Liverpool of my portfolio .
Bizarrely share price spiked down yesterday so I added.so for one seem to have time it well
Look to be 7-0 up and cruising to the top of the league
1-0 Great rising tide sector
2-0 New facility just opened is going to massively enable them to improve capacity and operational efficiency (I visited last month )
3-0 Management and staff are seriously grounded and run a tight ship
4-0 The rental fleet book value is very undervalued as everything over 10 years is written off yet they actually have a life of 20-30 years . This is either income stream or clear profit when sold .
5-0 Very good client base, US military , “a Voldemort major online retailer who cannot be named” , etc
6-0 Very big barrier to entry so a big most
7-0. Finslly despised if the Middle Eastern oil drilling section .
Valuation still modest
@ planetx - I was also at the factory opening - maybe we met!
Michael - next time for sure , I’m the scruffy one
Haha!
RPS (LON:RPS) takeover announced at 206p (SP 117) from WSP Global. Well done to all holders, especially PI 's Simon Hedger (@vodkaquickstep) and @Battlebus141 who have advocated them for years. I have a much smaller holding than I did but pleased nevertheless. And RPS (LON:RPS) results today also positive.
Delighted with the all cash offer for £RPS at a hefty premium. Great bit of analysis from Simon Hedger that put me onto this one so kudos to him.
It’ll be hard to find a suitable replacement offering good performance and dividends with premium buyout potential.
Any suggestions welcome.
Good surprise update from Crestchic (LON:LOAD) this morning. They seem to be in a sweet spot at the moment.
Still appears to be on a relatively modest valuation, although I don't think it will get to a racy multiple, some share price increase should come through based on earnings improvement alone.
Greyster
Trading significantly ahead at Crestchic. Third increase in expectations during 2022. They look to be adapting well to supply chain issues by purchasing and refurbishing used equipment. Extensions signed on existing contracts and it has also signed its largest ever hire contract.
Have they done any investor presentations recently on IMC etc? They do not seem to be coming up in my searches since they changed their stock ticker.
Crestchic (LON:LOAD) - wow! Not a single number mentioned:
https://www.londonstockexchang...