Small Cap Value Report (Tue 9 Feb 2021) - FCCN, JOUL, TND, D4T4, BRCK

Good morning, it’s Paul here with the SCVR for Tuesday.
Hooray, down votes have been abolished! That gets rid of the negative energy, and bickering hopefully (I'm an optimist!)
Timing - TBC
Agenda -
French Connection (LON:FCCN) - (I hold) - mystery buyer of 25% is disclosed
Joules (LON:JOUL) - (I hold) - Acquisition of Garden Trading
Tandem (LON:TND) - Positive trading update for FY 12/2020
D4t4 Solutions (LON:D4T4) - CFO leaving, and a mini trading update
Brickability (LON:BRCK) - Trading update - raises guidance for FY 03/2021
.
French Connection (LON:FCCN)
(I hold)
25p - mkt cap £24m
The Takeover Panel says on its website that French Connection (LON:FCCN) entered an offer period at 07:00 on 5-Feb-2021, although I'm not sure if holders of 1% or above are meant to disclose that yet. I haven't seen any disclosures as yet. My total position (including a spread bet) is slightly over 1%, so I need to keep an eye on that.
There was a TR-1 standard disclosure at 16:10 yesterday, that the 25% stake sold by Mike Ashley's Frasers (LON:FRAS) has ended up being bought (25.33% of FCCN) by Apinder Singh Ghura of Newcastle.
I've googled this name, and the only things that come up are Directorships, so I went to Companies House and found this person listed as an active Director of 10 companies based in Newcastle and Manchester. I've been through the latest accounts for all of these companies, and list them below in order of largest balance sheet NAV:
- Chan Property Group Ltd - £5.2m NAV
- Chan Commercial Ltd - NAV £2.8m
- Willow View Care Ltd - £985k
- Newport Lane Estates Ltd - NAV £74k
- Northumberland County Developments Ltd - NAV £100
There are 5 more companies which have been incorporated in 2019 or 2020, hence have not yet filed accounts, namely;
- FCMUK Ltd - incorporated Sept 2020 - and clearly bearing a striking resemblance to French Connection's logo "FCUK", so maybe this was set up as a vehicle to get involved with FCCN in some way?
- MIP Holdings Ltd - incorporated Oct 2020 - wholesale & retail of clothing
- Phantom International Ltd - incorporated Feb 2020
- Apparel Sourcing Group - incorporated Sept 2019
- Wraith Holdings International Ltd - incorporated July 2019
Activities of the companies are a mixture of clothing wholesale/retail, property, and a care home.
Conclusion - there's nothing particularly earth-shattering there, it looks like a moderately wealthy individual, involved with a variety of small companies. If anyone finds out anything more about why this individual has bought a 25% stake in French Connection, then please let us know!
What are the shares worth in a takeover situation? They're only worth what someone is willing to pay. That's also assuming that Stephen Marks will be prepared to agree a price for his life's work (he founded the company in 1972 I believe). My view has always been that the brand licensing, and profitable wholesale divisions within FCCN have a decent value. I think an acquirer could also strip out a lot of central costs (which look too high) and maybe ditch the loss-making retail sites using a CVA or pre-pack. There's scope to develop the licensing side of the business too, e.g. a successful deal with DFS shows that the brand has continuing customer appeal. It's also used on spectacles, sunglasses, perfume, handbags, etc. There's plenty of potential there in my view to expand the licensing operation, which made £5.5m revenues last year, and I doubt there would be much costs associated with that, licensing revenue is usually mostly profit.
Time will tell, but I'd be disappointed with less than 50p per share exit price here. There's got to be a fairly high chance that no deal is the outcome, as Marks is notoriously difficult. The finances were shored up last year with a working capital loan from Hilco, and a US Govt-backed loan for its USA operations, so the business is not in any financial distress at the moment. The last interim results were awful though, with a terrible gross margin, indicating heavy discounting. It won't be able to trade at that level of losses indefinitely.
.
Joules (LON:JOUL)
(I hold)
160p - mkt cap £173m
Joules, the premium British lifestyle brand, is pleased to announce that it has acquired The Garden Trading Company Limited ("Garden Trading"), a digitally led retailer of home and garden products inspired by the British countryside and lifestyle trends (the "Acquisition").
This looks a very good fit, of a fast-growing brand that already sells on Joules’ marketplace, Friends of Joules, through its own website, and via c.1,000 stockists.
The figures for the acquired company look good too -
- Revenues £16.8m, FY 11/2020 (for context, JOUL is forecast c.£202m this year)
- Revenue growth of >40% on prior year - excellent
- Profit before tax of £2.0m - a strong profit margin of nearly 12%
Cost of the acquisition -
Cash £4.5m
New Joules shares - 2.83m valued at 159p = £4.5m (with lock-up)
Deferred consideration up to £3.5m (at least £3.0m in cash) - subject to performance targets for FY 11/2021
My opinion - this looks a cracking deal, buying an excellent profitable business for what seems a bargain price.
GTC looks a quality company, and an obviously good fit with Joules, in terms of its brand, products & customers.
GTC is cash generative, and has minimal capex requirement. Management says it’s not about cost synergies, but driving growth, and utilising GTC’s design & sourcing expertise to enhance Joules’ ranges, as well as growing its own sales & profits.
Broker forecasts will be raised, to include profits from GTC in Joules FY 05/2022. It’s expected to be neutral for the few months left of FY 05/2021.
A firm thumbs up from me, this looks an excellent deal.
It took me a few years to get my head around Joules, but it's now in the buy & hold forever section of my portfolio. Key points are that it's selling mostly online now, including its own marketplace for other brands, and has a very distinctive brand & products, not a me-too retailer.
.
.
Tandem (LON:TND)
560p (up 9%, at 09:24) - mkt cap £28m
Tandem Group plc (AIM: TND), designers, developers, distributors and retailers of sports, leisure and mobility equipment, announces a trading update ahead of its annual results for the year ended 31 December 2020 which are due to be announced in March 2021.
- Slow sales over Q3, as previously reported
- Q4 improved (6% up on LY Q4)
- Full year revenue £37.1m
- Gross profit margins strong
- Operating costs down 11%
- Stock availability issues improved towards year end
- Pension scheme - triennial valuation agreed, 5% increase in company contributions (note that increased divis could trigger higher pension payments)
Overall -
Group profit before tax is therefore expected to be materially ahead of the prior year. The strong trading performance also enabled cash generation which helped to strengthen the balance sheet position further.
Outlook - encouraging start to 2021, despite pressures (e.g. covid, travel restrictions, longer lead times, cancelled or deferred product exhibitions).
Current trading - sounds very strong -
Notwithstanding these issues, revenue to the end of January 2021 was approximately 75% ahead of the same period last year with back orders fulfilled as stock was received. Our forward order book across all parts of the Group is also substantially ahead of last year which is encouraging.
Inflationary pressures building - this is something that worries me on a macro level -
The US dollar is currently weaker than previously which is a positive although Far East costs are under great pressure due to material price increases, global demand and the adverse relationship between United States dollar and Chinese renminbi.
Freight costs & disruption - has read-across for lots of companies -
One of the most pressing current issues is with respect to freight where, despite having part of our freight requirement at fixed prices, there has not been enough capacity in the system to fulfil demand, coupled with port congestion and COVID-19 related delays. To ensure supply we are currently being quoted many times the rates we were paying in the Autumn of 2020. Whilst we have continued to import products, in some cases we have chosen not to at this time, although it is unclear when freight rates will begin to reduce to allow this to become commercially viable again.
Diary date - 25 March 2021 for FY 12/2021 results.
My opinion - this announcement is very detailed (I’ve just covered the main points above, see RNS for more). It sounds very good to me - strong trading in 2020, and a positive outlook.
I don’t have any forecasts, so can’t do a valuation on it.
.
£d4t4
(I hold)
307p (down 4% at 13:30) - mkt cap £124m
D4t4 Solutions Plc (AIM: D4t4, "the Group" or "D4t4"), the AIM-listed data solutions provider, announces today that Chief Financial Officer, Charlie Irvine, has decided to leave the Group to pursue another opportunity outside of the public markets. Charlie will leave following a period of three months' notice and in the interim will remain with the Group to ensure an orderly handover of his responsibilities. A search has been initiated for his replacement and further announcements will be made in due course.
Not ideal. Investors don’t like it when a CFO departs, because sometimes it can be a warning sign that something isn’t right. On the other hand, people change jobs for all sorts of reasons.
It doesn’t sound acrimonious anyway, in that he’s staying on for an orderly handover.
There’s a mini trading update buried in the text also -
"The Group continues to perform well and I look forward to updating shareholders on the Group's progress following the forthcoming year end."
The year end is 31 March 2021. Last year it provided a year end trading update on 8 April, so that’s a good date to add to our diaries for similar reporting this year.
My opinion - I hope this is nothing to worry about, and it’s reassuring that the group performs well. There was an excellent write-up about the company in well-known tip sheet Small Company Share Watch recently, which added useful colour to my understanding of the company.
Its software & services look very interesting, and highly relevant in today’s world. Although the company is still very small, and needs to scale up with more big contract wins.
.
Brickability (LON:BRCK)
67p (up 1% at 13:43) - mkt cap £154m
Brickability Group plc ("Brickability" or "the Company" or "the Group"), the leading construction materials distributor, is pleased to provide the following update on trading.
The current financial year is 31 March 2021.
- Strong recovery continued in H2
- Lockdowns since Nov 2020 had “little material effect on trading”
- Rigorous cost control maintained
- Market improving, and housebuilding sector remains fundamentally strong
- No negative impact from Brexit
- Order books healthy & believes that “demand will remain strong”
Guidance -
As a result of the above, the Group now expects an adjusted EBITDA* of at least £16 million for the full year to 31 March 2021.
*Adjusted EBITDA is defined as earnings before interest, tax, depreciation, amortisation, exceptional and acquisition costs.
The statement doesn’t say how that compares with market expectations, which would have been helpful. Although I do like the specific guidance figure given.
Cenkos & Zeus, two of my favourite brokers for research, have covered BRCK before, but I can’t see any updates from either today on Research Tree, which leaves me a bit stuck.
Looking at an old Cenkos note from Nov 2020, it had pencilled in £15m EBITDA, so “at least £16m” today is up about 7%. If I apply the same percentage rise to adj EPS, it goes up to 4.9p for this year. That’s a PER of 13.7 - which looks about right for a building supplies distributor.
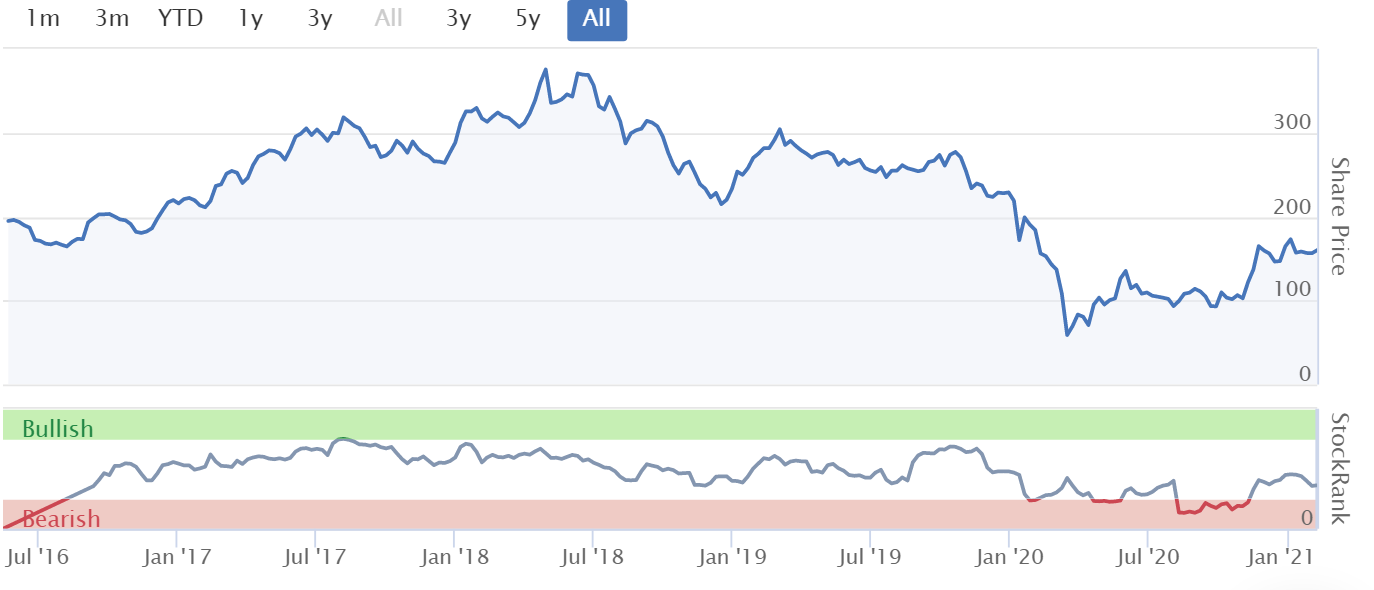
My opinion - like so many other shares, this has risen strongly since the vaccine news turned positive last autumn. What is going to propel it higher still? As the 3-year chart shows below, it’s back to pre-covid valuation, which is maybe high enough?
Although looking at consensus forecast for next year, that suggests strong earnings growth to 6.2p. So if that’s achieved, we could be looking at more upside on the current price maybe? I don't have a strong view either way, but good luck if you do take a shine to this particular share.
.

.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

89 comments
4.7% of the co shares placed today by Tom Joules in a book build and done in 2 hours at the market price, not a sniff of a discount. Demand or what?
JOUL: as of today 25th February, the Stock Report is giving JOUL qualifies for Altman Z-Score Screen ("Short Selling)" as being 1.8 or under yet from another source its Altman Z-score for 2021 is 2.7. Don';t understand; data error?
Joules (LON:JOUL) it says 1.79 today on the Stockreport. It is the 26th February today.
Where is it 2.8?
I start a comment, sometimes with beer involved, and then delete it as on second review does not meet the 'relevance' 'is anyone interested' 'will we make MONEY' - and mostly the answer is NO.
Thing twice - click once.
Replying to my own post (lockdown syndrome). £OKCD Ocado annual results 'resulted' in a dip. A 13 point risk analysis maybe scared a few off. This is a good long term format or not. Clear others will catch up and be cheaper. Fulfilment is not as easy as having customers wheel a trolley out of the door, as the SCVR online/bricks debate. Not sure Sunak can do the online tax to food but level playing fields and all that. Stocko rating at SR 52 so in the 'review' zone for sure.
Pls reinstate up and down votes. It adds to the colour and pizzaz of social media, abolishing it makes comments section blander
Just seen the thumbs down has gone .Good riddance - saves me the job of going round clicking them up 1 !?? Hated the environment they created.If you don't like a comment or disagree then respond politely or - even better respond just in your own head.
Just seen the thumbs down has gone .Good riddance - saves me the job of going round clicking them up 1 !??
I thought it was just me who did that :)
Best decision ever to get shot of the thumbs down.
Well as I am no longer allowed to vote with my thumb, I have to just say that I disagree with you on this point, rmillaree . I have been known to upvote a post that I thought was harshly downvoted too. But on balance I thought the downvote was useful as an alternative to people posting twitter like "wrong" posts (perhaps like this one!)
Whilst it is only a very minor thing, I thought it was a semi useful counter to the echo chamber effect that I see developing, to a very small extent at this stage I should say.
couldn’t agree more Gromley. I will miss the laugh it gave me when people were downvoted and either:
A) found it annoying enough to comment angrily
B) found it annoying enough to say how little downvotes mattered to them
I don’t think I’ve ever downvoted anyone (maybe once or twice in a year for blatant stirring the pot) and don’t think I would in the future but I will miss the “little Britain” atmosphere it brought. Boo to sanitising the SCVR...
If I may disagree politely, I don't like comments like yours complaining about downvotes, they add nothing to the discussion.
I agree syrio, so I could have just given you a thumbs up but that would equally not added to discussion.
Hi Paul, Mello was great, so informative. Can you explain SCS; cash rich, with EV greater than Mkt Cap. Thank you, just learning.
Hi Susan,
This comes down to IFRS16 accounting rules. SCS (LON:SCS) have £112m of capital lease obligations on the balance sheet (most of this is future rents for their properties).
This is treated as debt by the bean counters, so despite having all of that cash (I cannot recall now if some of it belongs to the customers, by way of prepayments/deposits) they are seen to have "net debt" overall.
Hi Gromley, that's the answer that I came to but you put it much better.
Susan,
If you go to the stock report for SCS and look at accounts then balance sheet you get figures for 9 previous years. If you run down the column for 2020 you'll see a big increase compared to 2019 for Gross Property, Plant And Equipment and Total assets, and similar jumps in various liabilities. These can point you where to look in the latest balance sheet back in September where note2 explains it. Happy digging.
If you click on market cap and enterprise value at the top of the stockreport it will show you definitions and explains the relationship between them if that helps.
Quick look at the Joules (LON:JOUL) chart, for anybody interested.
Not the cleanest chart / setup in the world, but a couple of observations which may help those looking to enter.
Price has consolidated recently, with the MA's squeezing together. The first buy area shown (which price is in now) would be a more aggressive 'pocket pivot', which is still below the recent highs. This can offer an early entry point, though a full breakout is not yet confirmed.
The key level to break is 180p, a round number which aligns with the recent highs. a break of this level, on volume, would be more significant imo.
The volume profile is not the cleanest, several spikes during the recent consolidation. Ideally a noticeable increase will be seen as price moves up and breaks the key levels.
Hi Breakout, really like your additions to the forum bearing in mind momentum is 1 of the 3 stockrank key variables and price is one sub of momentum. From my experience thin stocks like Joules tend to break more TA "rules" than keep to them (within a given time perspective, daily), however sometimes by stepping back to weekly timeframes the support/resistance/divergence view clears. Like FA not a perfect science, just useful insight/probabilities. All the best with your investing.
Thank you GInvestor, appreciate that.
I'm normally reviewing the charts of the companies mentioned in the SCVR and posting if I find something which I think can add some value. Hopefully complimenting the excellent analysis from Paul and Jack.
My own trading / investing method is very much based on identifying the right entry point to minimise drawdown and reduce stress. I think it's a valuable skill for any trader / investor, but I understand TA doesn't come naturally to everybody.
I agree with your comments, thinly traded stocks do tend to have messier charts, and zooming out to the weekly can sometimes provide a better view - I'll bare those comments in mind going forwards.
https://www.joules.com/gift-gu...
Just looked at their website as a consumer. I thought it was very poor, pictures too small and indistinct , navigation not clear and very few products. I could not find any information about where they are manufactured or materials used. I found this unsatisfactory as a consumer and put it in my forget as quickly as possible category!
They seem to be made in China. Not surprised they don’t shout about it. What I found shocking was the prices, £60 for a casual shirt. Profit margins must be good.
Morning Paul, one you've covered in the past Avation (LON:AVAP) has issued info today on the bond that matures in May 21 and some general updates, any chance you would have a look at this?
Hi Danto,
I covered Avation (LON:AVAP) for years, but found that it's quite complicated, and takes too much time to pick through the detail. Just because of the sheer volume of trying to cover about 500 companies here, I'll stick to the simpler stuff. Sorry about that, but hope you understand.
Regards, Paul.
For me this was the elephant in the room and now it is closed the worry should go away about financing. However, that was done at a cost : in essence around 9% of the upside has been diluted above 114p so by my calcs TNAV goes down by around 15p (assuming full dilution on the 6m warrants) to around the 260p level from memory.
My view is that it was needed to be done - an extension for 5 years is good (you'd hope the aviation industry is operating normally by then!) but it does have a small effect on the equity.
Collections seem ok given the industry problems and they have a good amount of cash so liquidity is now fine in my view. Some asset sales will help bring leverage down a little.
I hold and was getting concerned about the bonds. I'm much more comfortable now that has been dealt with. I don't see the share price roaring back myself until there are more than just chinks of light in air travel opening up again but then they are not a lessor to international air travel, more domestic/regional as well as being heavily AsiaPac focused, so these routes are less hit and will bounce back quicker.
Overall I think they are pretty well run and so I'm happy to hold as I feel they should get back towards NAV over the next 2 or 3 years. My mistake was not bailing as this unfolded. I'm undecided about buying more at this stage.
Pleased to see the bonds extended at not too great a cost. There was also some detail in the update about current business. This is a highly levered business, so earnings are essentially the difference between 2 very big numbers - the lease income and the finance costs/depreciation. A small drop in lease income can easily wipe out earnings, and it was indicated in the update this will indeed be the case, so not expecting any earnings for next couple of years. Likewise, a small drop in value of aircraft can have a big impact on NAV, again due to the gearing.
Hi Paul, I completely understand no problem.
Thanks for your insight David, my initial thoughts where the bond deal seemed ok as it could have been far worse and circa 10% dilution from warrants is ok. The concentration in domestic/regional is what attracted me as a hold in the eventual reopening plus the large inside holding.
Thanks, Dan
(LON:REAT) Presenting at Mello today. A tiddler that isn't interesting to most people but acorns and oak tress etc etc
Morning grout123 - React (LON:REAT) - Acorns to Oaks
Is that a code for potential 100 bagger?
Ummm...excuse me for being a total cold shower....
React (LON:REAT)
I own it (from earlier in turnaround). I think its got prospects and the management team is interesting with potential to be excellent for it in the next few years (Shaun Doke CEO will need to prove he's more than a good salesman as they grow...but maybe exec chair is CEO in-waiting with scale and is at least a good and experienced mentor to provide oversight and guidance).
I really don't think its a good thing for tiddlers like this to be ramped through Mello. Too much money online squeezing through too little market cap. Mello really needs to start at the >£300m type area given the following it has. React is a modest portfolio position for me that I'd need to increase 5x to get to full weight...but at modest portfolio size I still hold decent bit of company.
This ramp is too soon for React unless they have rather stellar operating momentum as well. I think they have shown good turnaround and stabilisation but they are yet to show they have a genuine growth motor.
Today I think stock is priced as if its a decent margin growth company...and it could price a decent bit higher if it shows that through 2021. HOWEVER, today is pricing this as certainty...ie the price is all hope rather than show-me.
I believe React are making an error to embrace this Mello euphoria-ramp at this stage of their development.
I do think its got a good oppurtunity ahead of it and it may well be a future oak tree....but that is a long long way away. Like a decade project to be decent sized sapling and then another decade plus to be the oak.
The only reason to embrace this euphoria now is early 'inside' holders on turnaround looking for exit and/or high valuation for acquisition (mgt have stated explicitly this isn't on cards for next 18+ mths). Makes me feel they are going to try and talk up narrative now and then raise cash for piggy bank....a reprehensible phenomena during this covid bull market madness ie the idea that 'dry powder' = upside!!!
Weird rant over. I like the company.
Hasn't the CEO, who was on last night, got form in this (from his Redstone days)?
Exec Chair you mean?
I think he and his ex CFO (who's NED at React (LON:REAT) now - Michael Joyce) are clean on what went on there and exited before the funnies and didn't have anything to do with it.
He seemed to do decent job at Redstone although that's a retrospective by me.
I think he and Joyce are quality guys to have around at this tiddler.
Yes, sorry, Chairman.
Hee hee....good presentation by React (LON:REAT) today on Mellobash...and they answered most of my anonymous questions....I anonymised as I had asked them before and been a bit cold shouldered on them so refried them a little different today! TBH that they didn't quite answer them before makes me feel the company is a bit premature in showcasing itself.
Still think it's too early for them to be on this sort of Mello promotion forum and they need to earn their price move more slowly proving it step by step rather than seeking to dazzle the Mello hordes with then idea of the next big thing. I disagree with Paul Scott re their overall suitability for listing etc as there's a real niche franchise to grow at decent to high margin that means with £10m of revenue they can be valued at £30m etc. In addition there's the niche roll-up opp...like a Sdi (LON:SDI) but higher quality at they are actively managing and combining ;)
Note, covid work was not very important for them and probably cost them as much work as it gained them.
Lets not stop at 100...
I'd like to know how much provision they're making for the mental health of their workers given the gory nature of their business. I can see a world full of claims against PTSD coming their way, so I would hope they have adequate processes and insurance against that risk.
React (LON:REAT) Something I looked at after the claim of being able to cover anywhere in mainland UK within 4 hours (can't remember if this was a target or already achieved) - was the amount of employees they have. Stocko lists this as 30 (may be out of date)
I'm thinking (but absolutely don't know - so please correct me if you do). That they'd have layers of staff. Some directly employed full time, some contractors and some zero hours. And an ability to do these jobs at short notice all over the country would mean being able to have access to resource relatively quickly - having people effectively (but not necessarily contractually) on call.
So to bring it back to the potential for claims by staff - I'm not sure to what degree the people that do the work for them, actually work for them ie are they independent contractors, sub contracted or agency workers - and how this might impact any claims.
And I also wonder if it's not baked into the job. Could one reasonably expect not to see and deal with such things having agreed to do this kind of job. (This again assumes they don't send someone out who is an office cleaner to mop up a crime scene).
They have partnership arrangements with sub-contractors. It is these relationships that are critical to meeting that service standard.
The presenter for £REAT struck me as a bit too rampy, in his presentation last night! I'm not keen on management who seem focused on talking up the share price in an over-excited way. It's a miniscule company trading barely above breakeven. That's with the benefit of covid boosting its decontamination cleaning activities. Why is it listed on the stock market? A £7m mkt cap (generous) company that does cleaning services. Is that really the best thing we can find?! I appreciate the share price has had a nice speculative run, but what's going to propel it higher from here?
Well, providing the opportunity to raise equity capital, like React (LON:REAT) did in June 2020, seems like a pretty good reason to me.
Paul mentioned back in Jan 2020 that VR Education Holdings (Vr Education Holdings (LON:VRE)) 2019 revenue was only 1.02m Euros, EBITDA loss of 1.5m Euros. At that time it had 6-months of cash burn in the bank, and would need to re-finance after that.
What is the best way to estimate the current cash burn and how long before re-finance would be needed? A step by step guide (if you have time) would be most useful!
Paul - regarding your opening comment on French Connection (LON:FCCN) the company statement here https://www.stockopedia.com/sh... includes:
"Under Rule 8.3(b) of the Code, any person who is, or becomes, interested in 1% or more of any class of relevant securities of the offeree company or of any securities exchange offeror must make a Dealing Disclosure"
Thanks sharw, I've just emailed the Takeover Panel, asking for their guidance re FCCN. I remember years ago they were very helpful when I had to make another disclosure.
1% of FC. You must have some serious beans.
1% of FC. You must have some serious beans.
I'm careful with the housekeeping!
Not a bad recovery from where you were during the credit crunch Paul amazing what one can do when picking up the reduced bread at 4.50pm at Asda seven days per week.
I'm careful with the housekeeping!
LOL - Lockdown has been a blessing for the 'housekeeping' hasn't it!
Anyway Paul, on the subject of your beans - I know you have had to RNS previously but I was impressed on how investegate presented this one.
I don't know who this "W.H. Ireland" chappy is, but at least you got top billing (on my monitor at least).
I have to be honest, that I thought you'd been chasing the wrong hare with French Connection (LON:FCCN) , but there is some degree of vindication perhaps in the current situation.
Nice !
No doubt Paul will do a more comprehensive analysis but Garden Trading looks a very good acquisition by Joules (LON:JOUL) today - extends into adjacent space with very complementary brand/range; plan to keep a growing brand but add Joules branded range in same space; already online and profitable for only (claimed last year) >16% net profit margin on sales of £16MN. MD will stay on for a year and is incentivised by deferred consideration
Crucially, "Garden Trading has been a leading seller on the Friends of Joules digital marketplace since Joules launched the marketplace in 2019." ie both sides know each other and share "similar values, culture and customer-centric approach"
Usually, this is PR nonsense but platform owners do get a real inside track here to see what works and cross analyse what their consumers also buy before acquiring. Much less risky than what has been done on French Connection (LON:FCCN) by the 25% stake buyer. Also makes one think about what Next (LON:NXT) might do over time which I think is well placed to develop a middle England focused , 'better' online platform (in a good/better/best world of ranges). I will be looking at both (EDIT to correct AIM code) Sanderson Design (LON:SDG) and Sosandar (LON:SOS) (I hold) through this lens when they report.
great post Zipmanpeter and I’m totally convinced by online retailers offering a platform as has been historically seen with Next (LON:NXT) with a selection of premium brands to augment their in house offering and as has been seen with the flurry of acquisitions at Asos (LON:ASC) and Boohoo (LON:BOO)
Interested in your comments about Sanderson Design (LON:SDG) (I hold). I Really don’t see Sanderson Design (LON:SDG) evolving into an online platform but see it’s growth primarily in the strength of its existing brands and ability to build strong partnerships with other retailers, as has been seen with Next (LON:NXT) and its exclusive product range of Scion homewares. IMHO Sanderson Design (LON:SDG) has a unique opportunity with the strength of its brands to grow through the shift to online.
M.
Apologies for going off topic but was really great to see Maggie Thatcher on Mello last night. An excellent show all around
LOL I forget she's there in the background (my Maggie Thatcher cardboard cut-out), but it seems to amuse people, and everyone comments, so a good ice-breaker on Zooms! Mum scowls and says, "That bloody woman!" every time she visits.
It was very amusing indeed! I think I better get one of Vince Cable delivered asap
Hi falsegods re background cut outs @ Mello Mondays
Surely you would have Chris (Next slide please) Witty
I see on Citywire this morning that Shore Capital are questioning the ability of Boohoo to scale up and manage the enlarged group, talking about execution risk, and banging the old drum of Corporate Governance again. I guess there is an execution risk, as there always is with large acquisitions, but they have done OK so far. I think I would be concerned if there were any more brand acquisitions in the near term though.
Yes there must be some execution risk here. BOO will need to manage the systems and people changes to incorporate the new businesses and then make sure that their design teams understand the new and different customer bases. I guess the biggest risk is that the management team will be overstretched.
Having said which if only half of the recently acquired businesses succeed that would still be a decent result. I don’t think they had much trouble funding the acquisitions - probably stuck a hand down the back of the sofa to dig out the £25m needed for the last job lot of businesses. Overall though it would be good to see progress on some of the recent acquisitions before any more businesses join the group.
I saw that Shore Capital note on Boohoo (LON:BOO) yesterday. I really cannot understand what their agenda is? The analyst seems to be resolutely sticking to a negative view, despite looking a wally every time BOO smashes forecasts with its figures.
The old chestnut of Corporate Governance has been done to death, and BOO could scarcely have done more to address it. They're fixing it, so shareholders should be happy with the incredibly detailed & comprehensive actions taken on the supply chain.
Strangely, Shore also talks about higher cost of imports. He doesn't seem to realise that it's cheaper to import. Leicester was used for speed & convenience, not low cost. Freight is expensive at the moment, for everyone, but once that normalises, then BOO is likely to be bringing in cheaper product from Pakistan, Bangladesh, etc, like everyone else does. That's positive for margins, and should recoup higher costs from Leicester for the product still made there.
All these new brands take time to digest, and then grow. What we should see is analysts start to include bolt on sales from Debenhams & the Arcadia brands. Initially very small increases, which BOO will probably smash, as they usually do!
Then we've got 35% organic growth (as last reported in trading update, on mgt call) from the main brands, plus the new brands coming on top. Hence guidance of 25% p.a. revenue & profit growth in the medium term, is likely to be seriously thrashed.
As an aside, I'm reading a terrific investment book at the moment, which points out that 25% p.a. growth for 21 years, produces a 100-bagger!
All the negativity on BOO is just background noise. This is a hold forever share for me now.
Regards, Paul.
Actually Paul, a 107.42 bagger, but in such a situation whose worried about the extra 7.42 bags!
I think I've read that book, is it called 100 baggers or something like that? It was a good book and more sensible than the title implies. It's more about good businesses not penny share boom or bust type stuff.
did it mention any pre 100 baggers ?
It's a while since I read it but one mentioned was Monster, the drink company. It's a American book I think but no worse for that.
Bitcoin has done 125 bags in the last 5 years. Some of the covid testings stocks have done well over 100 bags in the last 52 weeks. All Active Asset Capital (LON:AAA) has done 150 bags in the same timescale.
The next lot of 100 baggers are all out there, waving at you......look there's one!
Hi barnetpeter
Is All Active Asset Capital (LON:AAA) a real company? I cannot find any sources of substance about it. Searched Investor Chronicle site and Google. Also, their website which is quite light.
I recall I looked at it quite a few months ago and felt uneasy about it then.
Do you have any useful information on it, or links to further insights?
Regards
Howard
Looks very dodgy to me, looking at some of their interests, I would not touch with a bargepole. Loads of Covid in that area of Myanmar, not to mention a military coup.
Hi herbie47
I concur with you, and there are many other better options to look into, but I am quite curious about £AAA. I have found that digging into things like this does add to my general understanding about the market and some of its participants.
I wonder if any others have insights to offer up about All Active Asset Capital (LON:AAA) ?
EDIT: Oh there seems to be quite an over-lap of Major Shareholders of All Active Asset Capital (LON:AAA) with one of their portfolio companies Asimilar (LON:ASLR) . At least one of those shareholders seemed to have some not too complimentary press about their activities within AIM companies and share prices. That's read flags for me.
Regards
Howard
ASLR has links to DEV which is an ED tech play I have held both for a while I can see lots of growth but significant risk
Hi Cleeve
Thanks for the added insights. I have followed up a little on your points.
Can't quite work out why Entain (LON:ENT) through Intertrader Ltd seems to be part of the major shareholdings as well as a few recognisable entrepreneurial names (e.g. Nigel Ray, Christopher Akers to list two).
From my brief looksee there seem to be connections between All Active Asset Capital (LON:AAA) Asimilar (LON:ASLR) Dev Clever Holdings (LON:DEV) $ED Entain (LON:ENT) and latterly the BGL Group Ltd. I'm sure several others if I were to dig more deeply.
And, I just cannot work out why All Active Asset Capital (LON:AAA) keeps rising so much so rapidly.
I'll continue to watch as I'm quite intrigued but too cautious to act at all.
Regards
Howard
I think the Myanmar property is a legacy issues an not anything that anyone is interested in
One of my big holdings been in for a while - check out sentience and mesh holdings all v interesting AI plays
Think I'm reading the same book right now. "100 Baggers: Stocks that Return 100-to-1 and How to Find Them - Christopher Mayer"?
The title was almost a bit off putting (not that I don't want to find a 100 bagger!) but it had a lot of good reviews. As doug2500 said, the book is a lot more sensible that the title implies. It's definitely helping me to think about investments in a different way, and over a different time scale. Next read: HG Wells - The Time Machine.
Check out Smart Money - Stephen clapham .I'm halfway through and its kept my interest (Ive been investing 25 years +))He aims it at intermediary investors + .A great insight into his world (ex analyst) and thought processes in selecting stocks and viewing the bigger macro-economic picture
Goldman raises Boohoo price target to 510 (460) pence - 'buy'
Barclays raises Boohoo price target to 530 (510) pence - 'overweight'
I suspect the book is “100 BAGGERS STOCKS THAT RETURN 100-TO-1 AND HOW TO FIND THEM” by Christopher Mayer. The idea for the book was from 100 to 1 in the Stock Market by Thomas Phelps, which I am yet to read but is on my Kindle.
Others here might find AltaFox Capital’s research into the highest performing stocks over the last five years. Starting with $ZYXI with a TSR of 9,119% down to OB:GSF with a TSR of 350% TSR. AltaFox Capital is run by Connor Haley , who is no 2 (and often no 1) on the Microcap Club league table.
There are plenty of SCVR favourites in the Slide Deck including Games Workshop (LON:GAW) Boohoo (LON:BOO) Future (LON:FUTR) Frontier Developments (LON:FDEV) Fevertree Drinks (LON:FEVR) £BVXP.
Well worth a study.
The deck is at:
https://static1.squarespace.co...
Regards
Michael.
I really like BOO too, although I tend to ask my friends about clothing and their feedback hasn't been great. However when I ask them about the alternative brands they own, they always favor them. I am awaiting a decent entry for a position! Once it shows us some steam.
Beeb sounds unaccustomedly positive on the Boohoo (LON:BOO) acquisition trail https://www.bbc.co.uk/news/bus...
Re Boohoo (LON:BOO), Yes, and a bit more on https ://www.bbc.co.uk/news/bus...
Hi Ben1
I assume the £BOO Shore note is note is not available to “normal” investors like me? (I have done a Google search to no avail). Even though I have owned the company since 2015!!
As an aside even Stockopedia has Boohoo (LON:BOO) as a falling start and yet if you look at the chart from the mid-July low the price is definitely in an up trend. Almost odd. Oh well at least it is up today. I hold, my second largest position (12.5% of pf).
Thx
Regards
Falling Star is because of the high quality ranking but low value and momentum scores.
I didn't see a research note from Shore (don't know if there was one), just a write up with quotes on the Citywire website . For some reason it wouldn't let me cut and past the whole webaddress as a link (if that makes sense), but if you cut and paste the below it should work. I may have registered with them ages ago, but I certainly don't pay for it!
https://citywire.co.uk/funds-insider/news/the-expert-view-boohoo-ceres-power-and-electrocomponents/a1462274
Hope that works for you
I Like that you have quantified your holding %, you talk sense on this board.
Full year results from Amino Technologies (LON:AMO) this morning (I hold). The outlook is good as it continues to transform to a software led company helped by the 24i acquisition. They set out an ambitious 2025 strategy.
Notes out from finnCap and Progressive this morning show 2022 p/e 12.2 and 11.7 respectively. Viewed from the software side this is hardly demanding! finnCap has a 215p target.
There is an IMC presentation at noon tomorrow. Meanwhile here is a brief clip:
https://www.youtube.com/watch?app=desktop&v=kclwiLrF67U&ab_channel=Amino
Paul or Jack - any thoughts? In August Jack concluded " I don’t see any reason to get involved until there are concrete signs of the strategy bearing fruit". Does today's report show signs?
A very encouraging trading update from Water Intelligence (LON:WATR) this morning [I hold].
Revenue of $37.9m versus the broker consensus of $35.0m. EPS is not given in the statement but, based on pre-tax profits of $4.2m and applying a normal tax rate for the business, I make them c. 21c, versus 18c consensus.
The underlying revenue trend is up and the reacquisition of four franchisees in the second half of last year plus one so far this year will certainly drive revenues up materially again in 2021. This growth will be further accelerated by a full year contribution from business flowing from the two new insurance company agreements closed in Q4 2020
Against this background, and with the 2020 outcomes already well ahead of the 2021 consensus forecasts, in my opinion further material broker upgrades are inevitable.
Edit. WH Ireland have upgraded 2021 to $43.0m revenue (from $36.9m) and 26.5c EPS (from 20.1c). Dowgate have similarly upgraded to $45.0m revenue (from $37.7m) and 26.0c EPS (from 21.1c).
Morning Paul , would be pleased if you looked at £AMO (Amino Technologies ) - in a Covid year and a transitional period when they have changed from a hardware led business to a SAAS business they have managed to improve sales , margin , profitability and cash flow - in addition they have reinstated the dividend . For your benefit the paragraph below explains what they do - its a high growth area .
"Amino Technologies plc is a software-led, global Media Technology company. We deliver modern TV experiences, the way viewers want them. We do this by creating the solutions that Pay-TV operators, broadcasters and content owners need to make it easy for people to connect to the TV and video they love."
I have not looked at Amino Technologies (LON:AMO) before, but I am grateful to fred9566 for pulling out the company description from the RNS.
Eh?
"is a software-led, global Media Technology company."
So they are a software company - I presume the 'led' means there might be some hardware involved as well.
"We deliver modern TV experiences, the way viewers want them."
Does that even mean anything?
"We do this by creating the solutions that Pay-TV operators, broadcasters and content owners need to make it easy for people to connect to the TV and video they love."
So they provide some form of technology for the user interface to TV & Video streaming.
That sounds quite a sexy subject area, but maybe one that might be challenging to form a moat around?
They are obviously quite an established company having formed and listed in 2004, with revenues peaking at $100m in 2017, $83m in the latest year.
I presume that there was some change in strategy (going beyond the move to SaaS) at some stage,
The front page of their website seems to present the investment case as being all about the future opportunity; which is a bit troubling for a company that has been around for 17 years.
There is nothing here that inclines me to look any further at this stage, but as there does seem to be some interest here, it would be great to see a short synopsis of the bull case.
The 10 cents EPS reported today appears to be quite a miss compared with the 13p forecast shown on Stocko (19 cents back in 2017) and I infer from sharw's post that the 2022 forecasts are around 15 cents. This might look quite cheap, but it comes down to how much confidence one could have around those future earnings and whether there is even more to come in future years.
Hi Gromley
re Amino Technologies (LON:AMO), as I own, whether wisely or not, I thought I might add a little.
1 As you say, they are a software company.
2 They are B2B, their customers are small to medium size TV operators who want to add internet streaming to their existing cable services (because if they don't their customers will leave them).
3 Business is almost entirely international, owing to a lack of TV operators in their target market in the UK
4 Bull case is being a software company with plausible growth prospects on a PER of about 13, and with a reasonable track record of being cash generative. (Operational cash flow divided by capex more than 2.)
5 There was a hiccup two years ago when they decided to stop supplying the set-top boxes as part of the deal with TV companies, and to turn themselves into being primarily a software business. Next year should see the benefit of this coming through to profit. Hence the relatively low rating at the moment.
6 Bear case is that long-term the business model for the TV operators no longer works. imho that's the judgement call to make on this share.
Hi Sundaytrader,
Thank you so much for your response - it gave me a lot to think about.
I just spent about 30 mins writing a detailed response and then the link to Stocko failed. I will bite my lip as to why!
No time now to rewrite my reply, but I will try to come back to it later in the week as your excellent reply does deserve a response!
My morning smallcap tweet:
Nucleus Financial (LON:NUC) £D4T4 CAP XX (LON:CPX) Abingdon Health (LON:ABDX) Water Intelligence (LON:WATR) Symphony Environmental Technologies (LON:SYM) Numis (LON:NUM) Northbridge Industrial Services (LON:NBI) Tavistock Investments (LON:TAVI) Brickability (LON:BRCK) Tandem (LON:TND)
Nucleus Financial (NUC) rec offer 188p, a 12% premium but 42% up on pre offer talks RNS. [SP=166.33 Cap=127m]
D4t4 Solutions (D4T4) CFO to leave in 3 months 'to pursue another opportunity'. He is thanked. [SP=320 Cap=129m]
CAP-XX (CPX) guides FY(Dec) rev up 10%. EBITDA loss (ex share options amortisation) c. A$1m. Order book doubled. Also co now an approved supplier to a global smart phone mfr and separately has commenced the formal process to become an accredited supplier to a global Automotive Tier 1 Component Supplier. [SP=12.5 Cap=57m]
Abingdon Health (ABDX) collaboration and co-marketing agreement with Abcam, a global leader in the supply of life science research tools and reagents. [SP=90.56 Cap=87m]
Water Intelligence (WATR) guides FY(Dec) pretax up 78%, above mkt exp. "Our results are ahead of market expectations, despite Covid." Didn't the analysts know about covid? [SP=482 Cap=74m]
Symphony Environmental Technologies (SYM) guides FY(Dec) rev up 19%, Shipping delay meant it missed a 30% rise. Op cashflow -£1.4m. No in line stmt. [SP=18.01 Cap=32m]
Numis (NUM) first 4 months of FY21 rev up 50%. "The deal pipeline for the remaining two months of the first half is encouraging." [SP=332 Cap=358m]
Northbridge Industrial Services (NBI) guides FY(Dec) adj pretax modestly ahead of management's expectation, and slightly ahead of 2019. Rev broadly flat. Sales mix reduced gross margin. Demand is expected to strengthen in Q2, across all geographies, and grow again in H2. [SP=99.65 Cap=28m]
Tavistock (TAVI) guides YTD(Jan) gross rev broadly flat due to fall in new Advisory business - lockdowns. Guides FY(Mar) EBITDA significantly up. In line? [SP=1.94 Cap=12m]
Brickability (BRCK) recent lockdowns had little material effect on trading. Guides FY(Mar) adj EBITA at least £16m. In line? [SP=66.5 Cap=153m]
Tandem (TND) guides FY(Dec) rev c. £37.1m up 75% and pretax materially up. "Stock availability, although slower than we would have hoped for, improved towards the end of the year to enable a strong finish to 2020 for the cycling businesses." Pension deficit: contribs to rise 5%. Trustees must have had their tummies tickled given the huge trading improvement. [SP=522 Cap=26m]
In line: £
Morning Paul, regarding Mr Ghura and French Connection (LON:FCCN), looks like the Guardian got to him first. He has no plans to launch a bid, but keeping options open and stated, “We used to supply the high street but we can’t be doing that now. I like to invest in things I understand and clothing is something I have been doing for a long time. To me this is a good investment and a good brand.”
Here's the full French Connection (LON:FCCN) Guardian article for anyone interested (it's not long):
https://www.theguardian.com/bu...
Hoping you get time to look at Tandem (LON:TND) today Paul who, on the face of it, seem to have released a positive sounding trading update.
Morning Paul. Any chance Rm (LON:RM.) is on your list today?