Small Cap Value Report (Tue 9 Jan 2024) - GLE, MTW, QTX, IPX, SHOE, SIG, HAS, IUG

Good morning from Paul & Graham!
I'm getting up really early every day at the moment, trying to finish the full article on my 2024 share ideas, which is turning into a nightmare, but it's almost done. We scored a lovely (lucky!) early success yesterday, with the positive update from CMC Markets (LON:CMCX) which both Graham and I picked for our 2024 lists. For anyone who missed it, here's Graham's Top 10 ideas for 2024. The real-time prices spreadsheet for both our 2024 lists is here (note there are 2 tabs, at the bottom) -
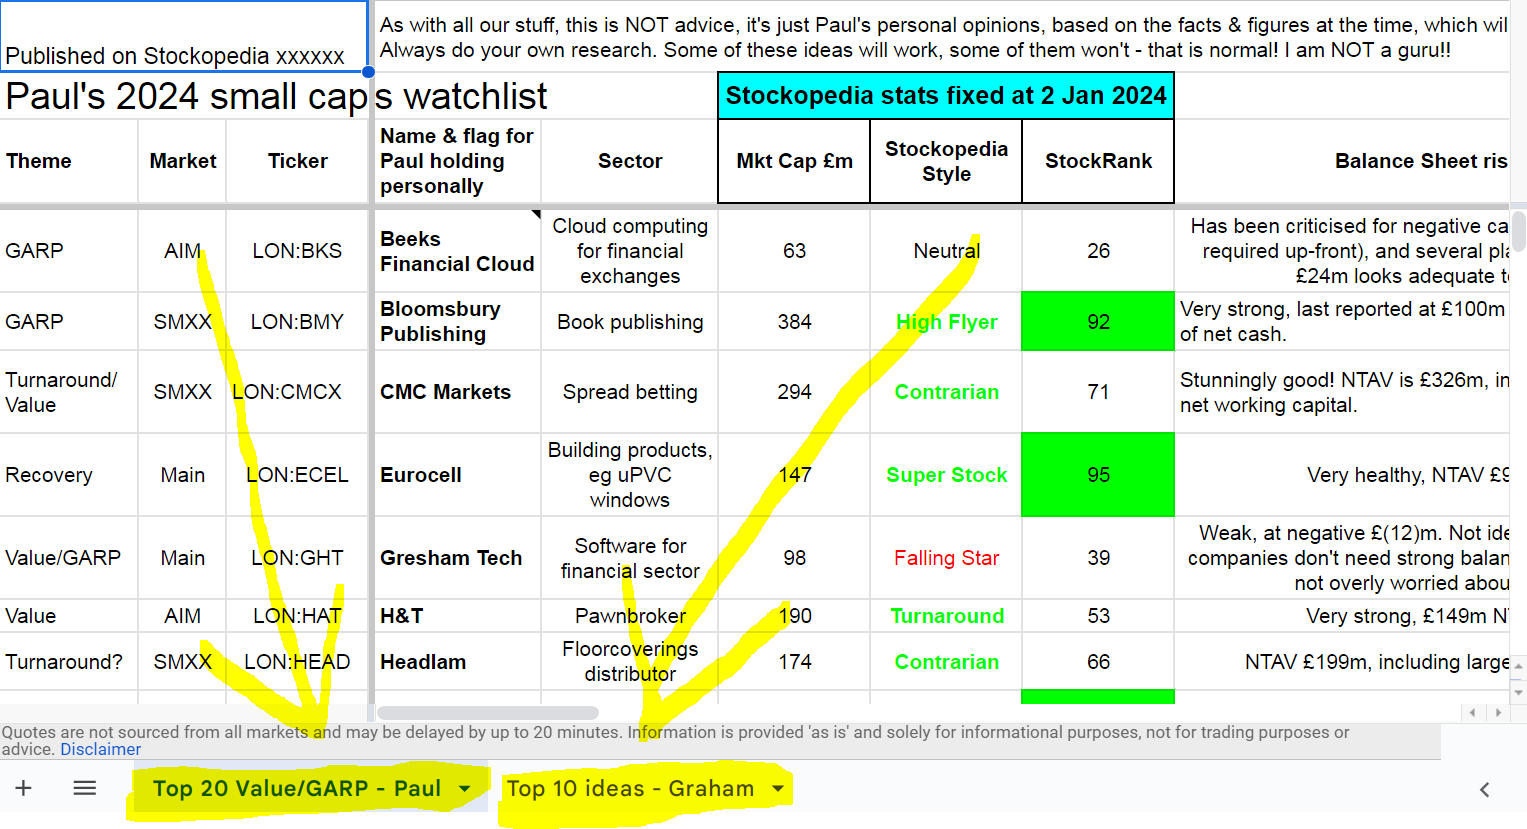
Why not make a personal copy of this spreadsheet, and add your own share ideas to a new tab (using "Duplicate" on the tab button at the bottom)? Then we can compare performance amongst readers at the year end! You could publish a screenshot of your choices, or provide a link using the "Share" facility (anyone with the link can view, is the best setting).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Live prices tracking spreadsheet for Paul & Graham's 2024 share ideas (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs) - search on any podcast provider for "Paul Scott small caps", or web link here.
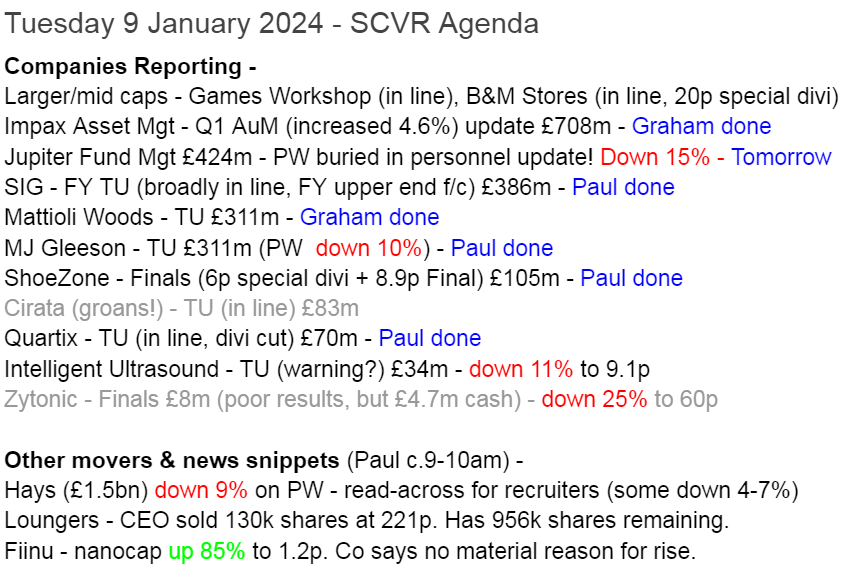
Getting busier now!
Summaries
MJ GLEESON (LON:GLE) - down 11% to 479p (at 08:31) £279m - H1 Trading Update - Paul - BLACK (profit warning) AMBER on fundamentals
Affordable house builder warns that gross margins below expectations, but doesn't say anything about FY 6/2024 profit expectations, and Liberum leaves forecasts unchanged - correction, a new note has just come through from Liberum that lowers forecast EPS by 22%, apologies. Good outlook comments, and Dec 2023 order book strongly up. Looks fully priced after strong recent rally, hence I've changed down from green to AMBER.
Mattioli Woods (LON:MTW) - unch. at 600p (£311m) - Trading Update (in line) - Graham - AMBER
It’s an inline H1 update from this serial acquirer of pensions and investment advice businesses. Modest organic revenue growth gets a boost from acquisitions. I like the company but the stock might be priced around right here, all things considered.
Impax Asset Management (LON:IPX) - unch. at 534p (£708m) - Q1 AUM update (forecasts unchanged) - Graham - GREEN
More outflows here of around £1 billion in Q1, but AuM has risen anyway thanks to positive market movements. The expansion of its fixed income offering appears to make sense. This stock was severely de-rated over the past two years and I now see it as a value opportunity.
Quartix Technologies (LON:QTX) - Unch 145p (£70m) - Trading Statement - Paul - AMBER/GREEN
In line update for FY 12/2023, and also confirms guidance for FY 12/2024. Putting through general price rise in Feb 2024, should boost profits. Possible trim to divis this year, as cash wasted on a small acquisition. Good growth in France. I like back to basics strategy of founder, returned as Exec Chmn. Not a bargain, at 17x earnings, but I'm leaning slightly towards a positive view.
Shoe Zone (LON:SHOE) - up 2% to 230p (£104m) - Final Results FY 9/2023 [in line] - Paul - GREEN
Lovely results, a bit ahead of forecast. Low PER and generous divis/buybacks. Balance sheet is fine, with net cash. Forecasts FY 9/2024 look beatable, so probably beating expectations as calendar 2024 plays out. My only concern is possible loss of some market share to aggressive Chinese direct to consumer operators like Shein and Temu.
SIG (LON:SHI) - up 2% to 32.7p (£388m) - FY 12/2023 TU - Paul - AMBER
Performance has come out towards the top of a tight range for underlying operating profit - but it's not a good measure as finance costs eat up half of it, leaving only a c.1% PBT margin. No sign of the turnaround working as yet, with broker forecasts in an inexorable downtrend. Balance sheet looks just about adequate. Not high risk, but getting margins up to 5% looks a tall order. If it's achieved though, on £3bn revenue, that would be a striking result, giving 2-3x possible upside on the share price I reckon. I'll watch from the sidelines, as it's a large business that clearly needs a lot of sorting out.
Paul’s Section:
MJ GLEESON (LON:GLE)
538p (pre-market) £314m - H1 Trading Update - Paul - BLACK (profit warning), AMBER on fundamentals
Apologies for this section which might seem muddled. I had to edit it because Liberum issued 2 notes this morning, with the first one (sector note) leaving Gleeson forecasts unchanged, which was what I initially worked on. Then a second note shortly afterwards, cut GLE forecasts by 22% due to its profit warning. Nightmare!
MJ Gleeson plc, the low-cost housebuilder and land promoter, provides a trading update for the half-year ended 31 December 2023 (the "period") ahead of announcing results on 15 February 2024.
Completions (sales)in H1 down 14% on H1 LY (last year)
Forward order book (586 plots) is up 84% vs 31/12/2022 comparative LY.
Gross margins lower than expected - this has triggered a 22% reduction in broker forecast EPS -
Additional costs relating to a number of older sites, along with the cumulative impact of current market conditions including extended site durations, sales incentives and multi-unit sales, are now expected to result in full year gross margins falling below expectations by circa 1.5% to 2.0%.
Net debt - doesn’t matter to me, as GLE is so well financed -
Reflecting the significant investment in bringing forward a higher proportion of home starts before June 2023 the Group will report net debt of £18.7m at 31 December 2023 (30 June 2023: net cash £5.2m). The cash impact of this investment is expected to unwind over the next two years.
Outlook -
Against the backdrop of stabilising interest rates the Board anticipates a recovery in demand for low-cost housing in the seasonally busier selling period over the coming weeks and months. Gleeson Homes also continues to negotiate further multi-unit sales and expects to enter into agreements over the coming months for delivery of homes in the current and next financial year.
That’s an important positive point above - housebuilders are no longer entirely dependent on consumer demand for new houses, they’re also now negotiating bulk deals with buy to rent investors.
There's also a possible (likely?) resumption of Govt support measures to stimulate the lower end of the new houses market, which is Gleesons space of course.
Broker update - thanks to Liberum for its notes this morning - highly recommended reading, as one covers the whole sector, not just Gleesons, but was clearly written before GLE's profit warning - so its 42.5p EPS forecast is already out of date. It's now 33p.
Quite surprisingly, it says that the big rally in housebuilding shares means most are now fully priced. That’s my view too, I wouldn’t be chasing these any higher right now. Also Liberum flags planning delays as a growth-limiting factor. It’s great when brokers put out balanced views, instead of just talking things up.
Edited - Liberum trims forecasts for some larger sector peers, but left GLE unchanged in a sector note (which was obviously written before GLE's profit warning today!). However, a second note has just come through from Liberum on GLE specifically, which cuts FY 6/2024 forecast EPS by 22% (from 42.5p to 33.0p), and a cut of 26% for FY 6/2025 from 49.4p to 36.4p.
Due to the cyclicality, PERs are not necessarily a good way of valuing housebuilders. I also like to scrutinise price to tangible book value. GLE was at a lovely discount some time ago, but is now showing as a small premium, at 1.1x NTAV. Still superb balance sheet support, but no longer free money! Although we'll have to reassess that after seeing what level the share price settles at after today's fall.
Paul’s opinion - yesterday’s 8% rise to 538p looks a bit much. Given the strong surge in the share price of late, I’m shifting down from green to AMBER - the current valuation looks about right to me, so immediate upside maybe gone for now? Even a risk of short-term profit-taking perhaps? It depends - how much will the market focus on the still difficult market conditions, or instead might it look through those and focus instead on the more positive outlook now that mortgage rates have fallen sharply, and the big increase in order book above? I don’t know, typing this at 07:46, but I’m guessing we could give back yesterday’s large gain, I suspect some investors/traders might bank profits in early trades, but we’ll find out in a few minutes!
EDIT: as mentioned above, a new note has just come through which does cut forecast EPS by 22% to 33p for FY 6/2024. So yes, it's a profit warning.
Anyway, it’s up to you to decide if the glass is half empty, or half full here? I think the price looks up with events now, after a great run.
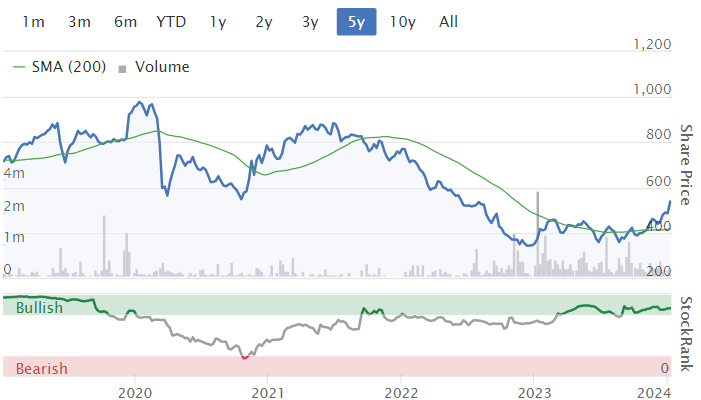
Powerful recent rally more obvious when we zoom in to 1-year chart - then today's profit warning -
Quartix Technologies (LON:QTX)
Unch 145p (£70m) - Trading Statement - Paul - AMBER/GREEN
Quartix Technologies plc, a leading supplier of subscription-based vehicle tracking systems, software and services, is pleased to provide an update on trading for the year ended 31 December 2023 (the "Period").
Performance for FY 12/2023 - is in line with Cavendish forecasts -
The Board estimates that revenue, profit (adjusted EBITDA) and free cash flow for the Period will have been £29.8m, £4.9m and £3.1m respectively. The Company's cash balance at year-end was £2.3m.
Of course EBITDA is not profit! I’ll have to explain this to the Exec Chairman when I meet him in February! (and show him the recent update from Next (LON:NXT) which reinforces this point!)
Anyway, £4.9m adj EBITDA turns into £4.6m adj PBT, and 7.9p, according to Cavendish, so a PER of 18.4x - not exactly a bargain, but not excessive either, in my view.
Outlook for FY 12/2024 -
We look forward to achieving further growth in 2024 and are confident of achieving market expectations2 for the new financial year."
[2] The Company believes that market expectations for 2024 are as follows: revenue: £32.1m ; free cash flow*: £3.4m ; adjusted EBITDA: £5.4m
A note from Cavendish (many thanks) shows that £5.4m EBITDA almost all turns into real profits, adj PBT £5.1m - so as with Intercede (LON:IGP) this is another company scoring an own goal by quoting the often inflated EBITDA measure, when PBT is nearly as much, yet is a far more credible measure, so should be highlighted instead of omitted.
This is 8.2p forecast for FY 12/2024, so at 145p the 2024 PER is 17.7x, which I think is looking more reasonable than previous over-valuations.
Dividends - might be cut, to reflect the lower cash pile of £2.3m. This is due to cash wasted on an acquisition by the former CEO, which hasn’t worked. So I don’t see this as a recurring problem, the company should return to paying previously more generous divis in 2024 or 2025 onwards, I’m guessing.
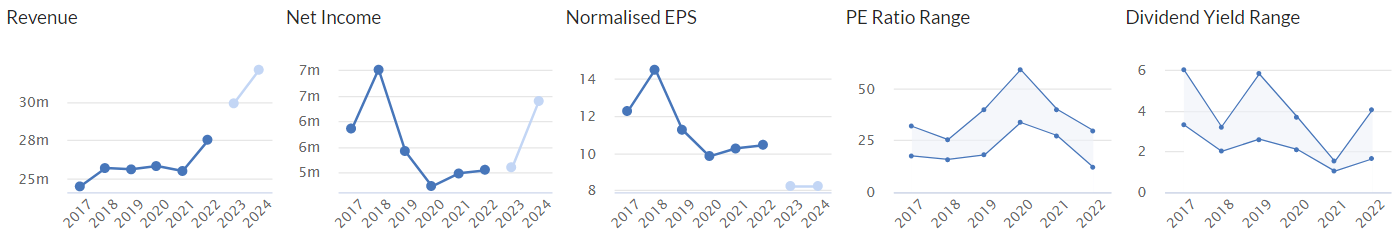
Quartix is a bit like Fonix Mobile (LON:FNX) - a cash generative, capital-light technology business that can safely pay out its cashflows as divis to shareholders. What a refreshing change from all the cash consuming jam tomorrow companies that expect us to hope they can generate some real cashflows at some point in the future. None of that nonsense here with QTX I’m pleased to say! This is a proper business that makes money - albeit profit growth has been elusive, with EPS having been in a downtrend for 6-7 years - that has to improve to get back to a growth company rating -
International - France is the standout good performer, having risen to £7.4m ARR at Dec 2023, up 22% in the year, and not a million miles behind the home UK market, which is £16.5m ARR (only up 2%).
I get the impression that the recently returned Exec Chairman is pursuing a back to basics strategy - focusing on growing the key markets, and avoiding distractions.
USA is struggling at only £3.1m ARR, down 5% - maybe a new strategy might be needed here?
Other small European markets are growing nicely at +45%, but from a low base, so ARR only £2.1m exit rate end 2023.
Don’t forget attrition - customers leave for a variety of reasons, at a rate of about 13% pa, so Quartix has to recruit new business at that level just to standstill.
Price erosion is another problem, and was -4.6% in 2023. Put that together with customer attrition, and the growth of new subscriptions needs to be nearer +20% just to stand still overall financially.
Price increases - this could be significant - it says that 80% of subscriptions will be subject to a selling price increase from 2/2024, which could nicely boost revenues & profit.
Upgrading equipment - the issue of sunsetting of old 2G mobile networks has reared its ugly head again (in France this time), with a £4.1m exceptional cost to be provided for in the 2023 accounts. Ouch, that's material. This is a real, cash cost, so arguably should be provided for in advance, with an annual charge to the P&L spread over X years, rather than after the event as an exceptional charge. By not providing for potential future costs of this kind in advance, you could argue QTX is overstating profits.
Cost-cutting & efficiency steps are being taken, both for hardware and overheads. Sounds good.
Paul’s opinion - I’m keenly watching Quartix, for signs of renewed focus and resumption of profit growth, now the founder is back as Exec Chairman.
I’ve skipped over some of the detail in today’s update. I’d say overall this update sounds reassuring, and I’m leaning slightly towards the positive side, given the confident outlook, and price rises from Feb 2024. So let’s up this from amber to AMBER/GREEN.
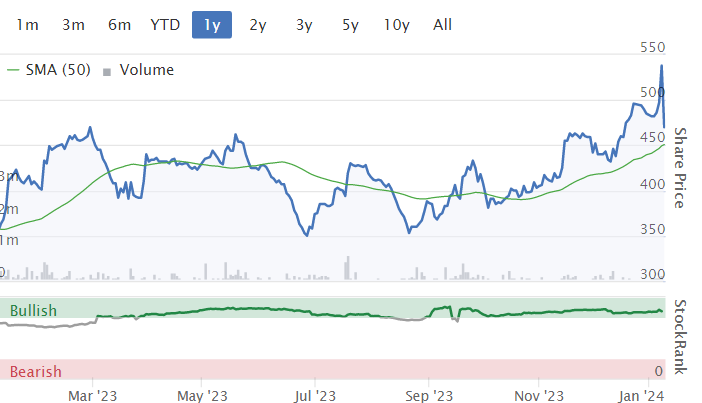
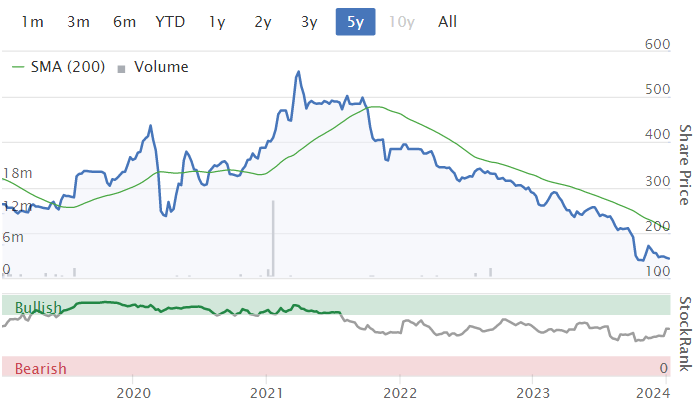
This is a firm share price downtrend, and with the PER in the high teens, it would need earnings upgrades to turn this around I think -
Shoe Zone (LON:SHOE)
Up 2% to 230p (£104m) - Final Results FY 9/2023 [in line] - Paul - GREEN
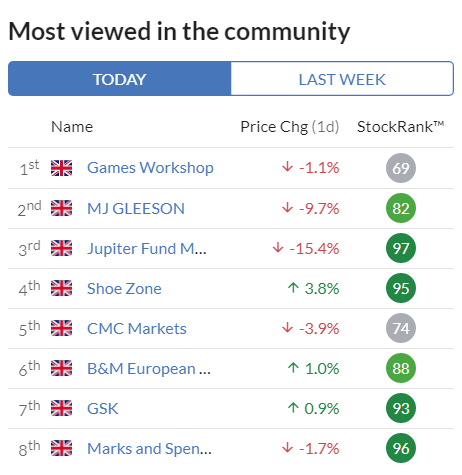
I spotted ShoeZone in the top viewed companies widget on the Stockopedia home page, so we try to follow your lead and review the small cap companies you’re most interested in!
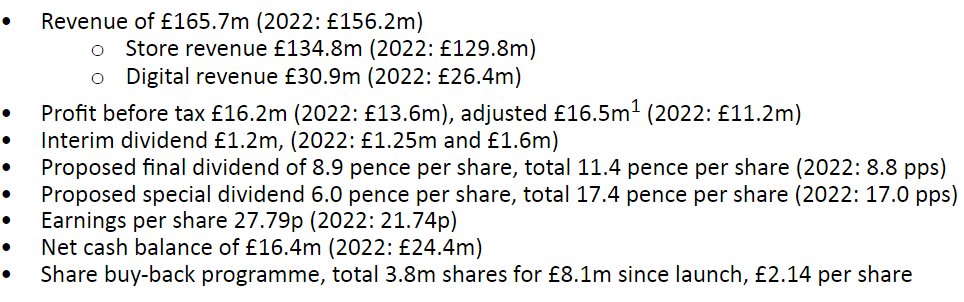
Impressive highlights table below, and note the big focus on shareholder returns through divis and buybacks -
Broker update - Zeus helps us out with a note this morning. It says FY 9/2023 results are in line with expectations.
Adj diluted EPS is 27.6p (beating Zeus forecast by 6%) for FY 9/2023, giving a PER of a modest 8.3x (up a highly impressive 53% on LY).
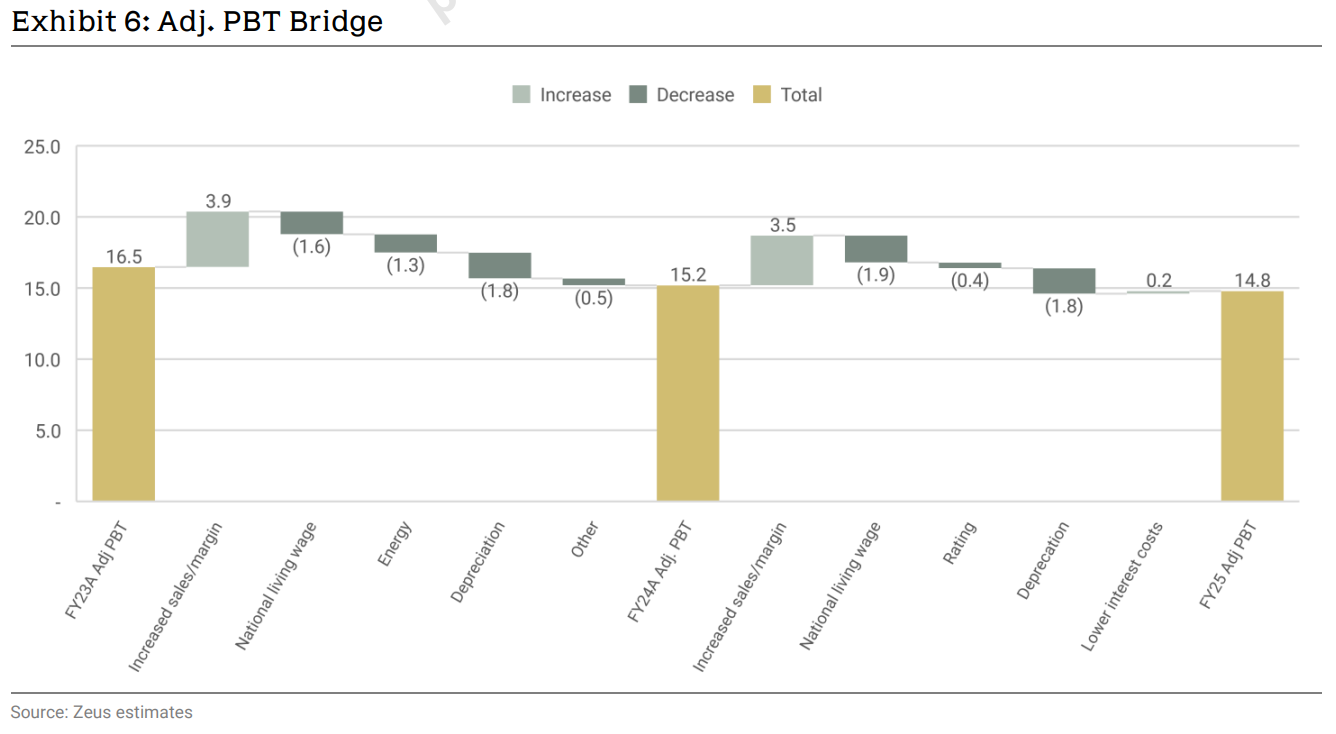
Zeus expects a drop to 24.7p adj EPS in FY 9/2024, and 24.0p the year after. Various factors explain this (eg living wage increase, and higher depreciation), there’s a really useful profit bridge here from Zeus (I hope they don’t mind me reproducing it here with thanks) -
Balance sheet is healthy, and ungeared. So I don’t see any risk from the generous shareholder returns, nor dilution being a risk.
Paul’s opinion - an impressive company, well managed by founder owners. Sites portfolio is actively managed (short leases) to exit smaller stores, and concentrate on larger & more profitable shed type retail units (“Big Box”) and “Hybrid” stores of around 2,000 sq.ft. in high footfall locations. “Original” stores are smaller, at c.1,250 sq.ft.
Online is creeping up nicely, and has a very low returns rate, and are often physically returned to stores, thus avoiding 2 lots of postage costs.
Forecasts seem modestly set, so if I were to bet on this, it would be that a revived consumer in 2024 might well cause earnings beats rather than misses.
The only downside scenario I can come up with is over the business model. It buys cheap shoes made in China, and sells them for a fat profit margin c.62%. The trouble is, Chinese companies have started selling direct to consumer now, Shein and Temu, and they must be taking a (probably small) slice of the market. These competitors are extremely aggressive, and do not operate to make profits. Hence I think there’s a very real risk that SHOE might lose some market share to them. If it reaches say 10% of SHOE’s revenues lost, then at 62% margin that would more than halve its profit. So keep you ear to the ground, and if you hear of lots of low income people buying shoes online from Temu or Shein, then I’d keep close to the exit.
However, for now, overall SHOE looks very good, so I’m GREEN.
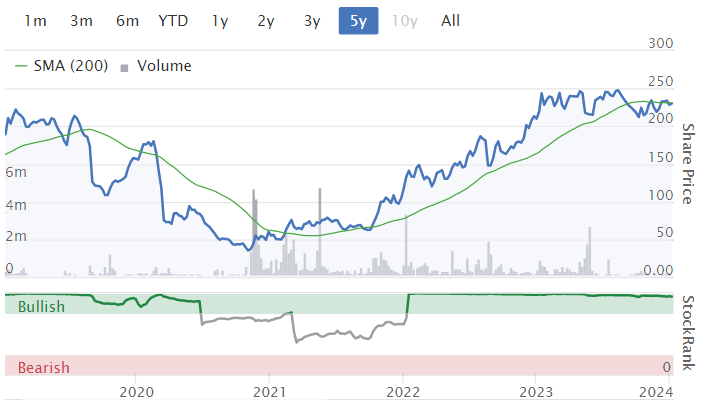
Wonderful performance from the pandemic lows, and it's completely shrugged off the more recent 2-year bear market in UK small caps, very impressive -
SIG (LON:SHI)
Up 2% to 32.7p (£388m) - FY 12/2023 TU - Paul - AMBER
SIG plc ("SIG", or "the Group"), a leading supplier of specialist insulation and building products across Europe, today issues a trading update for the year ended 31 December 2023 ("FY23").
We’ve not looked at this one since a year ago, on 16/1/2023, when we flagged improved profits in 2022, and reduced leverage, so an interesting turnaround. Shares have since been on a round trip back to the same level now as Jan 2023.
Unfortunately, progress has been backwards on fundamentals, with the FY 12/2023 forecast at 3.05p in Jan 2023, but it’s now down to only 0.75p
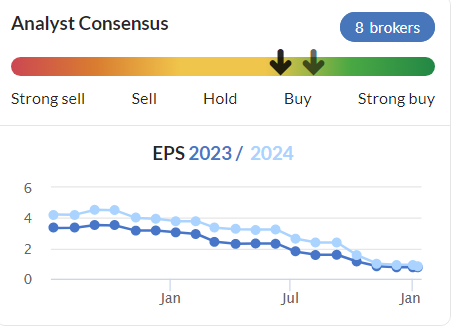
As you can see below, it’s not really making any money, on £3bn revenues - so what exactly is the point of this company?
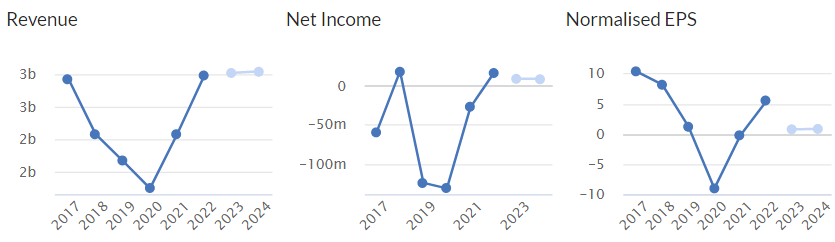
If it can get back to 2017 & 2018 levels of EPS, c.10p, then that would be interesting at a share price of 33p. But it looks like something structural has gone wrong here over the years. Also note the share count has almost doubled over this timescale in the graphs above, so 10p EPS then would only be 5p now.
Today it says that underlying operating profit should be in the upper range of £50-55m, but at the interims the £32.7m u/l operating profit became £15.0m u/l PBT (due to hefty finance costs).
Balance sheet was £140m NTAV at June 2023. Adequate, but I note there’s a deficit on the fairly large lease entries, suggesting an inefficient network of sites that needs pruning perhaps?
Paul’s opinion - this looks like a large, sprawling business, that’s not really making any meaningful profit margin despite shifting lots of products. So it probably needs a root & branch sorting out. The CEO has been in place for a year, and talks about efficiency improvements. If he can transform performance to the medium term target 5% operating margin, that would be c.£150m pa operating profit, less say £30m finance costs = £120m adj PBT. Take off tax, and put that on a PER of say 10-12, and we’re looking at upside potential of 2-3 times the current share price, by my rough calculations.
Trouble is, how likely is that to actually happen?
Downside risk looks fine, I don’t see any major risks in the numbers. Maybe one to research more closely, and the key point is to determine how likely profit improvements are. Judging from the constantly declining broker forecasts above, there’s no sign of improvement as yet. Hence I’d be happy to sit and watch rather than guess at if/when performance might improve. So I’m happy with AMBER for now.
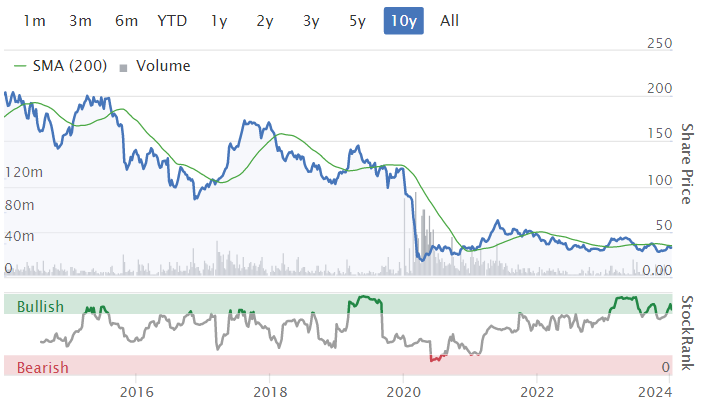
The 10-year chart suggests this share could only ever be a shorter term trade, for optimists, not a long-term investment -
Graham’s Section:
Mattioli Woods (LON:MTW)
Share price: 600p (pre-market)
Market cap: £311m
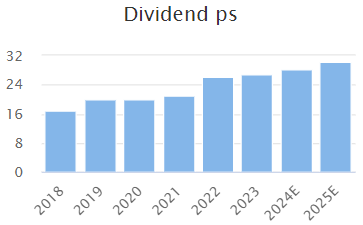
It’s been a while since I last covered this one (April 2023), when I described it as a successful consolidator of wealth management businesses. It has a pleasing track record of making profits year in and year out, and paying a dividend that tends to increase over time.
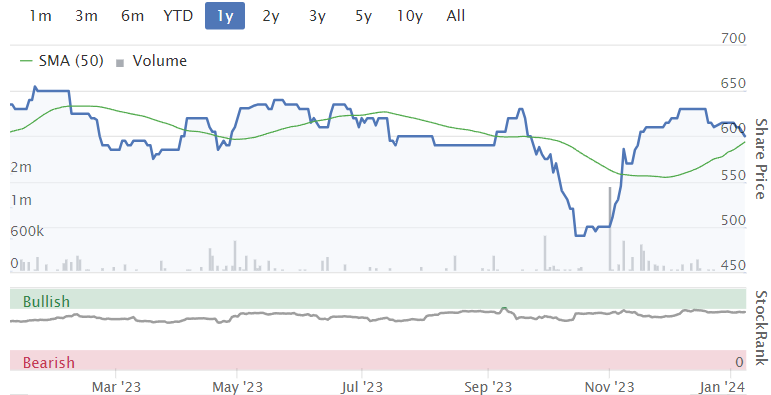
But its share price didn’t get very far in 2023:
Today we have a H1 trading update from the company, for the period to November 2023.
Key points:
Revenues up 8% to £59.1m, including acquisitions.
Organic revenue growth 4%
Clients assets slightly lower at £15.2 billion, due to downward market movements.
The company notes that revenues in H2 are “historically higher than in the first half”. It will need a boost in H2 if it’s going to hit full-year forecasts.
Estimates: Equity Development have helpfully published a note with an unchanged full-year revenue forecast of £123.6m. They are forecasting adjusted net income of £23.3m, and statutory net income £12m.
Cash: £32.7m
Comment by Ian Mattioli: highlights the company’s ability to generate revenues in different ways and to benefit from the need for advice as tax rules change.
Revenues were 8% higher and the Group delivered organic revenue growth of 4%, reflecting the resilient nature of our revenue model combining fee-based revenues for specialist advice and administration with ad-valorem investment management revenues linked to the value of clients' assets, despite a slight fall in the value of client assets under advice and administration during the period."
We enjoyed particularly strong growth within our core pension consultancy and employee benefits business segments, with the proposed changes to pension and tax rules announced in the Chancellor's recent Autumn Statement driving strong demand for advice.
Outlook: in line with expectations. Let’s use some bullet points to cover this:
The value of new enquiries is up strongly (22%) - although it’s not clear how much of this will translate to higher revenues.
There was “pressure on asset values” in H1. Perhaps this has already turned around a little in H2?
New client relationship management system.is being delivered as planned.
Inflationary pressures on costs. Cost-saving initiatives in H2.
Graham’s view
I’m inclined to leave my AMBER stance on this one unchanged. Overall, I think the stock has many positive features - founder involvement, a track record of successful consolidation in a fragmented market, and an attractive dividend stream.
But for an advisory business, I’m not sure if a premium rating is justified. Note also that the PE ratio below uses the adjusted forecasts; it would be significantly more expensive if valued on earnings after all costs (especially acquisition-related costs).
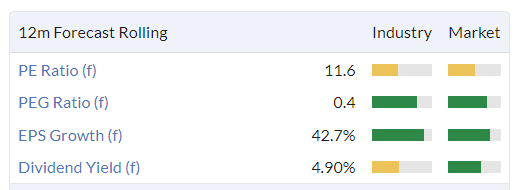
Stockopedia calculates the operating margin as 10%, i.e. MTW does not earn the chunky margins of something like a fund manager or a major stockbroking platform. I wouldn’t expect it to, but I do think that it’s important to bear this in mind.
In conclusion, I’m not entirely convinced that this one is undervalued.
Impax Asset Management (LON:IPX)
Share price: 534p (unch.)
Market cap: £708m
This environmentally-focused fund manager nearly made it onto my list of favourite ideas for 2024.
This morning we have a Q1 AuM update for the period to December 2023.
AuM is up 4.6% over three months to £39.1 billion (so you get £55m of AuM for every £1 invested in Impax).
There were outflows of nearly £1 billion, offset by positive market movements.
Comment by Ian Simm, founder and 7% shareholder:
This quarter, after more than 12 months of market headwinds, the investment performance of our principal strategies has strengthened significantly, underpinning a 4.6% jump in assets under management. Although asset allocation decisions at some of our wholesale clients have led to net outflows this quarter, we've retained all our material client accounts and added some significant new ones, particularly in Europe.
In a separate RNS, the company announces that it is acquiring Absalon Corporate Credit, which will bring in c. £350m of AuM, for an undisclosed amount.
Estimates: Equity Development have not yet adjusted their forecasts higher for the current year, which they describe as “a conservative approach”. They see AuM growing 10% this year.
Graham’s view
Firstly, I think it’s great news that Impax is expanding its fixed income offering - environmental investing is typically associated with equities, infrastructure and private equity, but why not corporate credit? It makes perfect sense to me that Impax should have a strong set of fixed income products, and should continue to invest in this area.
Secondly, on the subject of outflows. Let’s remind ourselves of how Impax’s AuM evolved last year:
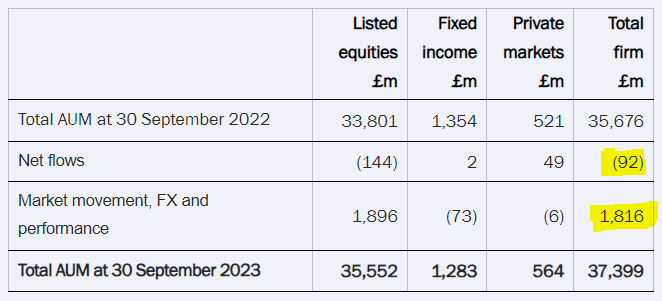
The above table shows that net flows last year were close to zero, but AuM continued to grow thanks to positive investment returns.
Flows turned negative towards the end of the year, with an outflow of around £900m in Q4.
Now, in Q1, we have a further outflow of around £1 billion.
The loss of momentum should be seen in the context of the Impax share price marching back down from its former heights:
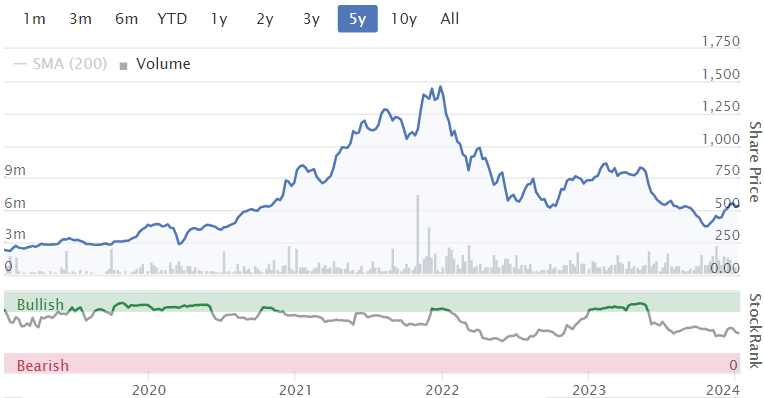
Personally, I tend to be relaxed about outflows. In fact, I tend to like them - because they can often result in a share price overreaction!
Note that Impax’s AuM has continued rising despite recent outflows: from £35.7 billion as of Sep 2022, to £37.3 billion as of Sep 2023, to £39.1 billion as of Dec 2023. Revenues can be very robust even during a period of client withdrawals.
While I do have some worries about the stability of demand for ESG investing, at the end of the day this is a high-quality company (in my view) and it’s trading at a reasonable price. The PER is 15.6x according to Stocko.
A reminder of the quality metrics:
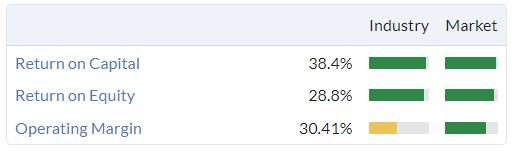
I do expect inflows to resume here at some point in the medium-term (perhaps not this year, but perhaps by the end of 2025?). With market moves also likely to carry AuM higher, I have no hesitation in keeping my positive stance here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

110 comments
Hi Jmallin1972. I use investegate.co.uk . You can set up customized alerts on there, and it's free. But I don't know if you will be able to set up exactly the kind of alert that you want.
Hays (LON:HAS) recovered much of its loss today, closing at about -7% (I think at one point it was over 15% down). What's odd though is that Robert Walters which initially opened down about 7% and did start to recover, ended up closing -9.5%. Not sure the last time I can remember a stock falling in sympathy further than the other stock that initially caused the fall. Perhaps the market is taking the view that Robert Walters is suffering more than Hays at the moment; or could just be random market behaviour. Will be interesting to see if these find support from here or whether this is the start of a deeper pullback for recruiters.
MJ GLEESON (LON:GLE) was similar, down 15% in the morning, closed down 8%.
Robert Walters (LON:RWA) is a lot smaller, so more vulnerable?
Re Shoe Zone (LON:SHOE) , I would appreciate if anyone could kindly help me with a query working out their free cashflow per share.
From their final results, I have taken their net cash flows from ops and then subtracted the net of PPE purchases and sales (as I believe this is essentially their Capex spending). I would normally take this to be the free cashflow and divide by the number of shares, but I wonder if I should also be taking account of the capital element of lease repayments and subtracting this?
Any thoughts appreciated
Yes, I would deduct all lease cash payments from cashflow to get to Free Cash Flow. The split between finance and capital lease payments in terms of cash flow is in my view erroneous - they are lease payments all the same
thank you
In the light of Gleason RNS ,there have been several comments on builders ,. Have held Bellway, and Vistry in the past few years ,when they did so well with goverment backed schemes , but have been out of this area since covid hit.
I still run a set of sieves devised by CD Refs,basicly a 'zulu' interpretation. If you fancy a builder , Cairn[CRN] is sieveing and the stats and stoko rating look VERY good .
I have a decent holding with a few %age points gain , as it started to sieve around august.
Whil'st Irish rather than UK firm , the market there has some correlation to here ,namely a large shortage of housing stock - unlike here the govt is still backing 'help to buy schemes' - it also appears to be in a better position to continue this, rather than here where we are so deeply in debt. When you look up their website you realise they are doing a lot of building, and seem well thought of .
Those same sieves threw up TIME finance as well, and that looks a strong hold again'st stats even after a good run.
Had the good fortune to take a strong position in Ashtead Tech ,early last year ,my share of the year with over 90% gain. The current figs ,in my view ,make it a strong hold / buy. My take on Slater 'peg' mean it is still under 0.7 Jim would suggest that was a strong buy ,all other figs. falling into line. Good luck in this new year to all your 'picks' Tony
A look at a few asset managers since they bottomed around Nov last year. Apart from Jupiter they've all been a pretty safe way to play the year end rally. Some decent gains especially from Impax.
Impax Asset Management (LON:IPX) +42%
Foresight group (LON:FSG) +22%
Premier Miton (LON:PMI) +30%
Polar Capital Holdings (LON:POLR) +11%
Liontrust Asset Management (LON:LIO) +13%
M&G (LON:MNG) +16%
Jupiter Fund Management (LON:JUP) +3%
Borrowing Graham’s summary on Supreme (LON:SUP):
"Risks would seem to be priced in here given that Supreme has built up a really solid track record in recent years. In addition to being a distributor, it does own a vape brand, and the distribution deal should stay in place for the foreseeable future.
At a PER of 7x and with great momentum it looks cheap:"
Graham notes bear points include regulatory risks around vaping (and ethical concerns), Supreme doesn’t actually own Elfbar, and Supreme's ability to generate consistent profitability. Demand in the lighting industry can also be highly volatile.
Since Grahams's report, Supreme has recently acquired, out of administration, the trade and assets of protein manufacturer FoodIQ UK Holdings Limited for a consideration of £175,000. FoodIQ is a state-of-the-art, fully-automated contract manufacturing facility which was opened only 18 months ago at a cost of £1.2m. This has the potential to add up to 40% to Supreme’s wellness manufacturing capacity. The new wellness production capabilities should help bring in new customer opportunities.
I have bought today.
Just on Chinese websites in China the population (in Shanghai at least) seem obsessed with ordering on line. Of course they work long hours so is a convenient time saver. The service seems good too albeit the poor delivery people must be exhausted. Innovations come quickly too. On some sites you can photo a product and the system will find it on their website. So there will be pressure from China continuing as they seek to expand their offerings abroad.
easyJet (LON:EZJ) opening up holidays from Germany, France and Switzerland today, . Worth a watch this year, they have so much opportunity to grow
I didn't realise this was in their plan but Just to explain this a bit, From Berlin for example EZJ now offers holidays as well as flight only. So flights, Transfers and hotels as an opaque package.
They have a competitive advantage as they own the airline, so can give themselves exclusive discounts on the flight, they still make more as it's with a hotel and transfers which are better margin than flight only
It will take time time to get traction but it's a fantastic opportunity. The have already got the online traffic. They can slowly open up holidays for the rest of Europe.
I didn't realise they flew to so many destinations from Berlin.
.
Hi Paul,
Thanks for the review of Shoe Zone (LON:SHOE) [I hold}. My operational concerns for Shoe Zone are two-fold:
All that said, the lady told me the store hit its Christmas target, it was, and I quote "SLIPPERS GALORE!" It's only one store but we're a long way past their year end now and what's most important is where this financial year is heading, about which we're a bit in the dark.
After J D Wetherspoon (LON:JDW) and ME International (LON:MEGP) maybe your next mystery shop will road test some Shoe Zone slippers....
The Shoe Zone (LON:SHOE) shops I have visited or walk past, always seem very quiet, I can see why they have stopped evening openings, maybe in larger cities it would be worth it but not in many other areas.
Slippers, they have been really pushing them lately, had numerous emails about them. I have bought some, not bad for summer, but they do pong a bit after a while. I wear Sheepskin ones in winter, they never pong.
Their marketing is getting a bit too much recently, I may have to unsubscribe.
Hi Paul
I don’t really understand your comments on Shoe Zone (LON:SHOE) around Chinese competition.
Most people buy shoes in a store - not online as no sizing is ever really the same and whilst you may get away with that in clothes; shoes are a different story so it would appear unlikely a pure online retailer would eat up market share.
Shoe Zone (LON:SHOE) have started selling more online so we need to look at why that is successful and it appears to come down to the fact that returns are done in store (ie Omni-channel). Customers are happy to buy online because there is a store nearby they can return to. Presumably they buy regularly from Shoe Zone (LON:SHOE) and therefore know the relative sizing. If they need a half size up/down they pop in and exchange. If not they’ve save a trip.
Given the dynamic I can’t quite understand why you keep raising that point. I totally get it in relation to online fast fashion eating online fast fashion but this isn’t the case. In fact it even isn’t the case with Omani-retailers like Next (LON:NXT) in clothes either.
Maybe I’m missing a real risk so would like to understand, given the above, why you think Shein and Temu represent such a risk to someone like Shoe Zone (LON:SHOE)
Cheers as always
David
Hi David
I've commented above on Shoe Zone (LON:SHOE) about online competition.
I agree
Shoe Zone (LON:SHOE) (I hold), I 100% agree with you David, especially with regard to kids shoes. I just don't believe people are buying say 4 boxes of shoes from an online Chinese retailer, keeping one and then going to all the trouble of returning the other three, working families just do not have the time or energy for that.
This is why the Shoezone model works so well, it takes all the pain out of the transaction and the fact their numbers today were so good is case in point.
Sorry Paul, i'm a huge fan but I think you're underestimating Shoe's business model and overestimating the cheap Chinese import threat.
I buy shoes for my children on-line...usually good quality merchandise bought tactically during promotions. I live overseas and there are practical reasons why on-line long distance shoe purchase makes good sense ... the quality available in the local market is generally very poor and not inexpensive.
I'm not 'representative' but I can vouch for the fact that, if you use a reputable foot measurement gauge and try to buy a little ahead of actual need, buying shoes on-line is really straightforward and saves a boatload of cash. I haven't tried sourcing from China. Perhaps I will give it a try and see how it goes.
Paul, got his fingers burnt on Boohoo (LON:BOO), because all the Chinese sales in the US. I think he is overreacting. The Chinese have not had such an impact in the UK yet. I have bought a few items from Temu, some are rubbish but some are ok and very cheap. For example cycling gloves for 67p, have seen similar for sale in UK for £15. Fleece hat was just over £1., 10m nylon cord was 19p. About 1/3 I have got refunds on. Everything is shipped via air. If you have to return it, then it costs them again, as you get a free return on every order. Can't see them making any money. But Temu are similar to Amazon, they are a host for sellers. There are many different companies on there, as far as I know Temu, don't make any items.
Lots of the items you will see on ebay or Amazon but around 5x the price.
Never bought any shoes from them, had a look and nothing of interest to me. Many Chinese shoes are too narrow for me.
I have bought shoes off Amazon, because can return free, if not right.
Have bought some slippers from Shoe Zone.
I don't see Shein and Temu being a big threat to Shoe Zone (LON:SHOE)
Temu are owned by the Chinese giant PDD.I had seen their ads allover the net but never bought from them before, as i assumed everything would still arrive months later and be impossible to return with no english customer service.I presume like Shein this has improved a fair whack since i last bought items from a wholesale Chinese seller by mistake on Amazon.Perhaps the Temu app and associated Amazon like logisitic facilities etc.. have started solving that particular problem?
I don't know much but PDD's sales and marketcap has been on a tear recently (and i totally wouldn't underestimate their reach), in stark contrast with Ali Baba's and a lot of the sentiment around general Chinese economic conditions amongst the property meltdown and governmental sector crackdowns.
'Temu tops the most downloaded free app charts in the U.S. and some
European countries including the U.K., and became the most downloaded
free shopping app in Japan and South Korea within months of being
launched in July'
https://asia.nikkei.com/Spotli...
However i agree for shoes, including kids shoes, unless you really know the brand, most like to be able to try on a pair of 2 and easily return.It's a hassle enough buying several clothes sizes, since even as a guy 'vanity sizes' can differ so much, and having to package them up and return them again.
Delivery takes about 5 days. If late they pay you £5. Returns, not actually had to return anything, they just refund me, either a credit or refund on my credit card. Sizes tend to be too small. Some items are nothing like the images. Reviews are misleading as there is a default to 5 stars, which a lot people just do.
Minimum order was £10 but now is £15.
Re Shoe Zone (LON:SHOE) , I would appreciate if anyone could kindly help me with a query working out their free cashflow per share.
I have taken their net cash flows from ops and then subtracted the net of PPE purchases and sales (as I believe this is essentially their Capex spending). I would normally take this to be the free cashflow and divide by the number of shares, but I wonder if I should also be taking account of the capital element of lease repayments and subtracting this?
Any thoughts appreciated
Carrs
Christopher Mills increasing to 14%
Seems to have also started it’s “J Curve” recovery .
I’m pretty certain they’re going to try to force to break this up and unlock the value that way .
Management change has already happened out with the old guard in with the new .
I’m at a 1/3 of a position would increase but no cash and with the exception of Colefax which I Have lost patience with can’t see anything to bullet ..
what is the best site to use to get an alert when fund managers increase their stake in a certain share
No idea
I only keep an eye on the RNS of all my holdings and watch lists just to see who’s coming / going
Shares in London-based Oxford Nanopore Technologies (LON:ONT) currently down by 15%
The company issued a revenue warning, citing a slowdown in China and the Middle East, along with staggered purchases from large clients.
Full-year revenue expected to be 169 million pounds ($215.2 million), falling short of the consensus expectation of 177 million pounds, according to brokerage Peel Hunt.
Nanopore blames recent U.S. trade rules that have heightened regulation of advanced artificial intelligence (AI) semiconductor sales, leading to slowed growth in China and the Middle East.
The company also flagged a hit to second-half underlying revenue due to delay purchases by large customers.
Peel Hunt: "Management must be more disciplined in deploying capital – pursuing top-line growth at the expense of all else is vanity and risks the balance sheet."
Pacific Biosciences Of California (NSQ:PACB) tumbled yesterday.I didn't read the earnings report as i'm not a shareholder, although i think it's still unprofitable like Oxford Nanopore Technologies (LON:ONT.It's good to see some innovative, loss making companies, being supported at decent market caps still within the FTSE though.Good luck to management!
Stewart Milne a Scottish House builder has gone bust. 300 to 400 redundancies. Taylor Wimpey (LON:TW.) Persimmon (LON:PSN) plus one other big house builder are due to put out a TU this month. I'm not convinced the house builders are a good investment just yet. I've spoken to a few younger people with mortgages and the eye watering amounts they are paying back, is unbelievable. Repossessions are not yet high. However, people seem to be handing the keys back. MJ GLEESON (LON:GLE) just might be the start of a correction for house builders. I'm a self employed electrician who has plenty of work at the moment. Plenty of other trades have a famine or feast situation.
I agree these might be a bit overbought Gutty, I held MJ GLEESON (LON:GLE) , Persimmon (LON:PSN) and Taylor Wimpey (LON:TW.). They have made me a nice 20-30% each but I have sold all three after seeing Gleeson struggle today. I could be wrong but I feel the downside potential after trading updates far outweighs the potential upside. Long term Gleeson actually sounded upbeat about building houses, but the market focused on the profit margins being tightened. I have been looking at some of the building materials suppliers recently (BnB did a great post on rotation into cyclicals) and think that might be a better area to be exposed to over the coming months, I liked Brickability (LON:BRCK) enough to open a position and I like TT electronics (LON:TTG) although frustratingly that jumped 7% yesterday.
As always, a lovely dose of droll, pithy sanity from Terry Smith in his annual Fundsmith letter. These are always a good read:
https://www.fundsmith.co.uk/me...
"Collectively they [Fundsmith's holdings] are over a century old"!!
Jupiter Fund Management (LON:JUP)
Further to my earlier post I have decided to sell my smallish holding. I found the title of the RNS somewhat disingenuous. I have a sizeable holding in Polar Capital Holdings (LON:POLR) which is my preferred asset manager. My other finance play is IG group (LON:IGG) that has recently recruited a new experienced CEO, Breon Corcoran, previously CEO of Paddy Power.
I will use the funds to add to other holdings where I have greater conviction or to top up recovery plays such as Pressure Technologies (LON:PRES) Flowtech Fluidpower (LON:FLO) or M&C Saatchi (LON:SAA) once I have further news on trading. I shall also cast an eye over Kier (LON:KIE) that looks potentially interesting.
All the best.
Hays (LON:HAS) not a small cap, issued a profit warning today, that has caused other recruiters share prices to fall, such as Robert Walters (LON:RWA) down 7%.
'Sell when the story changes'. That's something I've learned from paying attention to Ed's excellent masterclasses. So from being one of my biggest holdings which I've held on to for a year I've now sold out of MJ GLEESON (LON:GLE) . The share price seems to have stabilised at the moment but I just can't see any significant upside from here for a long time to come now. I'm grateful to Investors Chronicle for the impeccable timing of their article which has helped cushion the blow of the profit warning!
When all around you are selling, that’s the time to buy . Not my quote , but I think pertinent in MJ GLEESON (LON:GLE) and some other house builders. Personally, not worried in the short term , and expect mortgage rates to fall over next year or so. And no doubt the incoming Labour Government , with probably a large majority , will make building more homes, especially for the lower income families, a top priority .
MJ GLEESON (LON:GLE) don't really think the story has changed - was always likely that short-term trading was going to be soft, but the long-term prospects look good given the structural demand and lack of supply for housing. That said, I did sell last week (at 500p) as felt the rally had gone a bit too far. Even after today, the share price is still slightly up YTD, so feel it could weaken a bit more - might look to buy back in if it retreats to 450p.
https://www.retailgazette.co.u...
Chapel Down (LON:CDGP) Majestic Wine reporting very strong Christmas trade . As they had sold out of all but one of the Chapel Down products that they stock a few days before Christmas I am assuming that punters appetite for “finer” and more expensive wines is a very good read across for the Kent wine maker. I kept an eagle eye on Sainsburys and Marks and Spencer shelves and from what I could see I was surprised at the movement in the sparkling wine, especially at Sainsburys.
I think it is people trading down from buying champagne, which is what I did this year.
I see that Paul is ready has registered a groan for Cirata (LON:CRTA) - the late and deeply unlamented Wandisco. I too thought that attempting a turnaround from the shattered remains was beyond hope and fully in line with a Stockrank of 2 (!).
But... I have to admit that today's update shows exactly the clarity of purpose and target that suggests that they may have the right stuff. They are discussing results to December, just nine days after the month end, this is good. There are no "EBITDA"s or "adjusted"s, just straight talking with an understanding that cash is the only real game in this territory and that is above forecast for the year end. They have added a target on their back by stating that look to be cash breakeven by the end of '24.
Making this work will require steely-eyed determination and grit ,as well as abit of luck, I think they may have the former and will deserve some of the latter
More Bike Industry Armageddon
For those holding the likes of Tandem / Halfords etc yet more industry meltdown .
Orange bikes went into administration last week this was a stalwart UK brand albeit one that lost its way in the past year or two as FS frame designs evolved and they did not .
I ‘met up with one of my old suppliers from Taiwan last week and they said the big boys like specialised and Trek scott are sat on huge stock levels .
Seemingly off the record specialised elected to bury 300,000 helmets in a farmers field in China as it was cheaper than storing them.
I do think the bicycle industry is an exception as it was almost a perfect storm of inflated orders, poor controls and lack of strength of character by industry leaders not to control their orders.
I do still quite fancy tandem but the issue is they have blown their cash pile on a warehouse they now don’t need and are exposed to lenders for the first time and the top tier management are not credible .
Halfords have enough breadth to do ok but don’t expect the bicycle division to do any better than tread water for 18 months .
Thanks for your thoughts again on this. At what point do you think you'll be interested in making a return, or are you waiting for Tandem to go bust?
Not sure, the issue is the industry completely changed in the 30 odd years I did my stint, and to be honest you can only do that level of intensity once in your life .
What started as founder led businesses such as Mike Sinyard / specialised , Fausto pinarello , Ernesto colnago , Ugo De Rosa and UK side. Chris at CRC , Mitch at Wiggle, Jim at Ribble changed from founder led to corporate private equity driven loaded with debt and the bicycle industry is just hard work and amateur hour as the corporates don’t get it and the entrepeneur a have gone .
It’s not the same era and for where I am now the stress levels are too high, I never enjoyed the times we had 80-100 staff and I wasn’t suited to that . Plus I don’t ride my bike much any more and don’t have that passion I once had, passion gets you a long way when you are fortunate enough to love what you do for 30 years . I was very lucky
The fun parts of business for me is the early creation / build phase with a small group of great staff and I’m pottering with that at the moment with three companies and it’s just great fun .
It’s funny I was speaking to Dave Brailsford who used to work for me and we has a few great years he’s now involved at Man Utd and lives in Monaco.
I never left Sheffield and still take my dog on the same walk every morning and sit in the sane chair at the sane cafe and over the years you accept your self and find your niche .
Don’t think I would be interested in a “proper” company again with staff, HR, and red tape and structure and meetings let alone corporate compliance .
What I wouid probably be more attracted to is acquiring brands and licensing then, that is clean royalty and retained long term value .
I came very close to buying Hot Tune once, was the underbidder to Sports direct, and had a good look at Bench which was just out of my league - but acquiring a distressed brand and giving it breathing soace , then finding commercial partners that leverage the brand and pay a nice clean royalty looks the sweet spot .
Anyway sorry that’s a bit self focused but you did ask .
That's a very inciteful response, thanks.
Dave Brailsford happens to be someone I respect very highly so brilliant that he used to be on board with you. I take his marginal gains very seriously and try to use those % increases in a lot that I do.
As an aside, Richard Arnold (ex-Man Utd CEO) was drowning his sorrows in a boozer local to me in Cheshire, beinf quite wistful; however, he did have a long go at the club achieving some great commercial success.
I would have thought these distressed cycle businesses would be hoovered up by Mike Ashley, probably post liquidation?
I’m pretty sure Ashley will mop up Wiggle / CRC
Hi Planetx,
It's great to hear some of your insight in to the bike industry (very sad about Orange, classic brand!!) I grew up riding and racing mountain bikes, using a lot of your gear too :)
"What I wouid probably be more attracted to is acquiring brands and licensing then, that is clean royalty and retained long term value ." I thought this podcast episode would be very interesting to someone like yourself regarding this - A different perspective with Stephen Julius who was involved with the Indian Motorcycle Company and buying the brand licenses etc out of administration (I think) and eventually selling to Polaris, it's a great and inspirational story nevertheless.
All the best,
James
Janes
Thanks
I’ll have a listen
Great post.
Very Interesting from a buying perspective. I have always bought TREK and was considering another purchase. Had noticed more discounting, especially on last year's models. Hign stock levels would explain this.
The bike industry seems to have had a very difficult time. Orange must be the 3rd/4th major brand go to go the wall?
Think it’s way more, off top of my head -
Orange
Wiggle
Raleigh uk part accessories
Stanton
Planet X
Moore large (number 3/4 wholesaler)
abroad
Van moof (big one)
fahrrad.de.
Wiggle just sold a load of bikes very cheap but they seem to have stopped that, I even bought a qty they were that cheap .
Trek are very good bikes can’t go wrong with trek .
I recently bought a new bike. £3500, reduced to £2000. If my wife was not with me, I would have bought two.
Well they say the optimum number of bikes is n+1 (where n is the number you have already).
Or s -1 (where s is separation)!
I am more in to electric bikes nowadays, but the mainstream manufacturers have overcooked the golden goose with their latest prices for an emtb - whilst you can find the odd bike for £3-4k most mainstream brands are now £6-12k. This is ridiculous and from what I can see from both LBS and online is stock on huge discounts trying to shift it. No wonder they are going bust.
I just hope Halfords (LON:HFD) are more reliant on their motor servicing arm than their bikes - although tbh their bikes are not overly priced (even some of their decent brands like Boardman).
I think Halfords (LON:HFD) have been reporting poor bike results for a while now, so I suspect they won't be taking a hit as that forecast has been built in for future periods.
i wander if vehicle industry will be similarly affected - i did see an item the other day that suggested van prices where now showing material reversion to the mean at last - i think its well known the second hand car market has tanked (especially electric cars and especially porsches).
I hold Redde Northgate (LON:REDD) and have been awaiting the normalisation of van prices which hadnt previously happened - i dont have any specific worries ref redd as imho is kinda factored into the price at present and they will have some benefit if they can actually buy new vans more cheaply - so their strategy seems fine - plus they are doing more long term contracts en masse. albeit i dont blame anyone who is steering clear just in case as they have alot of vehicle value on their balance sheet.
as there is potential for oversupply in general though i would not want to be going near most of this sector with a bargepole. Perhaps Redd have been lucky that halfords didnt agree a merger of equals if their business is likely to worsen further than the worsening of teh previous update.
if there is large over supply for some items i would imagine that could take a long time to unwind - as so often with suply and demand led stuff it can be feast or famine and theere has been feast of exepnsive bike/electric car purchases that last 18 months to 2 years.
Jupiter Fund Management (LON:JUP)
Somewhat naughty and misleading headline referring to personnel changes but no mention of a trading update. I missed the latter; that will teach me to read the whole RNS.
I have a small holding and at present am undecided whether to hang on to it. AUM is up year on year and performance fees are expected to be £10m, which is ahead of previous guidance. Also it appears that investment performance has stabilised and is trending more positively in the 4th quarter
Unhelpfully I am not able to find any broker notes. The shares will recover once retail sentiment improves but that will only happen I suggest when interest rates start to fall, which hopefully will be sometime later this year. The positive about selling is that it releases funds, albeit not a large amount for investment elsewhere, the negative is that it will crystallize a loss, which over time will I suspect be recouped.
Any views from other Stocko members or Paul/Graham
Wasn't Jupiter a preferred 'value' play on this site just weeks ago? I remember it being mentioned again and again. What now after this update?
Jupiter Fund Management (LON:JUP) stock rank 98 so what’s going / gone wrong ?
(I hold, ouch!)
I hadn't spotted that Ben Whitmore was leaving to set up his own firm. Jupiter Sp Sits has a great track record so no doubt plenty of money will move with him.
Memories of Woodford leaving Invesco Perpetual - what could possibly go wrong?
Jupiter Fund Management (LON:JUP)
No money will go with Ben as he has agreed a 2 year non-compete so will not be able to accept it nor create similar funds. Much more likely is that Jupiter will simply continue to use Ben by allowing him to manage said funds on behalf of Jupiter.
The profits warning isn’t really a profits warning - I think people are making a mistake in reading that into it the statement.
What they actually said was that funds outflow result has been impacted by a delay in receiving money on new mandates. I.e That means a small reduction in fee revenue - it isn’t material unless those mandates never fund, which is not what was said. Plus they said that performance fees are now greater than expected. Put the two together and what you actually have is probably neutral or even slightly positive in terms of 2023 profit. The y/e end funds outflow is probably circa £300k off bottom line per month delayed imo. The performance fee beat appears to be greater than that.
I don’t hold but I think people are putting 2 and 2 together and getting 5 on here.
I wasn't expecting the money to move on day 1 DavidjHill, Woodford set up Patient Capital 12 months after leaving IP and his income fund 24 mths after.
What are the odds that Ben's Sp SitsFund is launched after 24 mths?
Woodford was a cult in a massive bull market hyped up almost continuously by the mainstream media. He was an anomaly in fund mgmt terms.
Ben, whilst good, is not. He will most likely do a deal with Jupiter Fund Management (LON:JUP) that suits them both. It’s a win win. He gets immediate funds to manage the fees of which help cover his overheads, Jupiter get continuity. They’ve more or less said so in the announcement.
We have a section on Jupiter that is ready to go up first thing with tomorrow's report (I wrote it after covering MTW/IPX today). Cheers. Graham
Keep an eye on Agronomics (Anic) stock pickers looks very good value in a expanding market
Agronomics (LON:ANIC) will need more cash sometime not too distant to replenish its firepower (got to take part in new rounds with existing investments or face dilution from new money). In addition, the Jim Mellon is skimming off a fairly hefty performance fee in a way that is open to some abuse if valuations are inflated
TBC some of the underlying investments are interesting...but there is a high uncertainty about commerciality and how much more money will be required to get some holdings to an exit or standalone commercial position
Excellent results again from Shoe Zone (LON:SHOE) although not a surprise after their TU a few months ago.
Good summer trading and container prices seem to be a driver of this. Fewer stores this year and they move from own label to hybrid stores seem to be making a good impact with average in store sales (exc store opening and closings) rising from £360k to £417k. This can be seen in my local store in West Sussex where after a refit from a standard store to a hybrid store in 2022 budgeted sales doubled and footfall has been positive every time I've been in the town.
This seems to be a good story of growth against the doom and gloom of high street trading by revising product ranges and getting on line sales going well.
Shareholders including the majority owners the Smith brothers are also rewarded by a growing dividend and a special dividend this year.
I look forward to Paul and Graham's view.
Happy new year to all fellow subscribers and commentators
Threepeat, I have just jotted down my notes on my thoughts. There is a wider question to be had further, but this seems to be a really good, well run company and their efficiency drive setup in 2021 really seems to be bearing fruit.
I suppose to add balance, there were a couple of points that I wrote down which could be considered negative:
My wider question, and I will use this share as an example of my limits of a PI, is when to exit and deploy capital elsewhere, cut, or add...
I bought in 2021 at around £0.80, so have roughly tripled the investment, not to mention receiving dividends, which for 2023 works out to roughly 22%.
At what point does this become a coffee can stock, or when does a profit warning come in a suddenly undo the good work? Whilst I realise that this is down to an individuals risk appetite, what do others consider.
Part of me wants to take the money and find other opportunities, but I did that with Ten Entertainment (LON:TEG) bought at £1.80, sold at £3.00, then in comes a bid situation, current price of £4.17, . For what it is worth I bought into Legal & General (LON:LGEN) for the 'safety' of approx 8% yield, whilst the market was really struggling. Whilst I took this as a script, obviously, I'm disappointed, but don't have a crystal ball and cannot wait to exit and use the money elsewhere. Average up into Shoe Zone (LON:SHOE)...???!
Shoe Zone (LON:SHOE) looks a great business and well managed but to add to Paul's early warning on Shein/Temu taking share there is a more immediate concern. Planetx highlighted the recent trebling of container shipping costs from Asia. With shipping avoiding the Red Sea for the foreseeable this could tie up a lot of containers and increase inventory as well as cost of getting it here. Might dent first half of this year.
Thanks for your note Viz. I did the note mistakenly thinking Paul was not going to comment.
Your comments are valid especially in light of no outlook statement. I suspect growth will continue with turning standard shops into hybrid stores. When this is complete I think the hybrid store concept will be rolled out where aren't any stores at all. Locally to here higher priced shoe shops are closing (Russel & Bromley) and Clarks always looks empty, not surprisingly at their prices.
I don't see Chinese imported shoes being a concern, give the need to try on from a trusted brand and as you say stores are a good returns point
My only concern is the shipping container cost rising re Suez problem. This is a stock where under promise and over deliver is normal.
For me it is a coffee can stock and with the founders still there it may take until their retirement for a decent offer north of £4 to prise them out.
If after a good rise a PW does occur you're still well in profit and after all not losing money is the key especially when you take dividends into account which is one of my central tenets
Im in roughly same situation. It is tricky as you are supposed to run your winners. My own estimate is that this share has another 10 to 30% in it. Plus good dividends. Have done a small top slice to buy something else I wanted to invest in. Decided to hold at least until qualify for dividend and then keep reviewing price performance against market. There are other appealing options out there at present which may increase more in price long term but this is a solid quality family run company with a good track record well aligned with shareholders which appeals to me.
Freight costs have gone up considerably recently, due to the problems around the Red Sea.
The 2024 forecasts surely look light don't they when they have said margins are expected to improve? Are there any updated forecasts this morning? SP seems stuck in the absence of an outlook statement and current (negative) forecasts.
Foresight group (LON:FSG) looks a fairly solid update from this alternative asset manager (focused on areas such as renewable energy infrastructure). Investors tend to be locked-in for long periods, so quite sticky revenues compared to more retail focused fund managers. Looks decent value on a PE around 11 and paying a 5.5% yield, although never seems to get much attention. Worth noting that Gresham House (GHE) was fairly similar and received a bid at a 50% premium last year.
MJ GLEESON (LON:GLE) at the reduced price is a good opportunity in my view to buy or , top up in my case. Definitely believe a Labour Government will be encouraging more house building especially in the sector that Gleason specialises in. A strong balance sheet so no short term worries
Stockopedia share prices are not live, generally around 20 minutes behind, sometimes more.
I did suggest that before 8am, that the previous days movements were zeroed, then it would be clear that any movement after 8am was todays.
It is quite confusing around 8.20am, especially as Stocko. use the last trade price, rather than mid prices.
Agreed Rusty, previous day price moves should be zeroed before 8am
Impax Asset Management (LON:IPX) - "AUM up 4.6% in Q1 and fixed income acquisition" (new report & audio here: https://www.equitydevelopment....)
Impax recorded a solid Q1 of FY24, with AUM growing by £1.7bn (+4.6%) to £39.1bn on 31 Dec 23 (30 Sep 23: £37.4bn). This is above the trajectory required to meet our FY24 AUM forecast of £41.1bn (+10% annual AUM growth), but as it is very early in the financial year and markets remain volatile, we have taken a conservative approach and not yet adjusted our forecasts.
It has also announced an acquisition in the fixed income segment. While not huge in the context of the group (£351m or just under 1% of group AUM), fixed income is seen as strategically important and a significant growth opportunity, particularly in the US. Impax Asset Management Ireland Limited has entered into an agreement (subject to closing conditions) to acquire the assets of Absalon Corporate Credit, a fixed income manager of two strategies.
We remain bullish about the prospects of the sustainable investing market generally, and of Impax specifically. The positive AUM update for Q1-24 and the Absalon acquisition reinforce this view and our fundamental valuation remains at 800p per share, 50% above the current share price.
Marks and Spencer (LON:MKS) had a good a Christmas "M&S food sales up 12.1% year-on-year in 12 weeks to Dec 30"
However how much is that due to inflation, food prices have increased considerably, in the last 12 months.
But remember that Marks and Spencer (LON:MKS) continue to sharpen their pricing, as Machin is well aware of the competitive environment in which he operates, so I expect on Thursday the numbers will show Marks inflation below food RPI.
Maybe. I was shocked by some of the prices in Aldi for their Christmas products, such as mince pies were £1.99, pretty sure they were £1 in 2022. Got some in the Co-op for nothing, usual price £1.25
Food inflation in November was 9%.
You got your mince pies for nothing! If that's not the mark of a good stock picker I don't know what is! :-)
Just download their App. claim your free mince pies. Easier than stock picking in the UK markets.
Rusty how do you know how M&S did over Christmas ?
The news is in the trade magazines: The Grocer, Retail Gazette, and others.
There was this: https://www.stockopedia.com/sh...
There are various other reports comparing sales of food retailers, over Christmas.
Full update from Marks and Spencer (LON:MKS) is on Thursday.
Jupiter Fund Management (LON:JUP) - Interesting that the institutional funds they hold are up by £3.2bn over the year. Hopefully a sign that funds are starting to flow into the market again. Total AUM was up on the year as a result.
Thats based on the table that they provided in the RNS
So a profit warning for mj gleeson and now the price is up 8%??
It’s down 13 percent
Are you sure?
The price is down 14%, 8% was yesterday's price, Stocko. don't have live prices.
But they really should...
I notice Jupiter Fund Management (LON:JUP) slipping out a Trading Update in an RNS entitled "Jupiter Fund Mgmt - Savvides to join Jupiter; Whitmore to leave" No mention of the Trading Update in the title.
Yes, a warning Jupiter Fund Management (LON:JUP)
At the start of the year we stated that our internal forecasts were for 'modest net outflows' for 2023. While we reaffirmed this expectation with the trading update in October 2023, a delay in the funding of some institutional mandates combined with weaker than anticipated retail sentiment in October and November 2023 has led to an incrementally more negative flow outcome than we had anticipated. Total net outflows for 2023 are expected to be £2.2bn.
https://www.investegate.co.uk/...
Although AuM up to £52.2bn from £50.2bn last year and higher performance fees. The market has reacted negatively - understandably given the manager of 20% of its funds is going to be leaving - but there are some positives here and we're still in the middle of a turnaround.
My morning smallcap tweet: Holistic value proposition my arse
Tremor International (LON:TRMR) MJ GLEESON (LON:GLE) Live (LON:LVCG) Mobile Streams (LON:MOS) Seeing Machines (LON:SEE) Intelligent Ultrasound (LON:IUG) Chamberlin (LON:CMH) SIG (LON:SHI) Quartix Technologies (LON:QTX) Hiro Metaverse Acquisitions I SA (LON:HMA1) Kooth (LON:KOO) Eden Research (LON:EDEN), Cirata (LON:CRTA), Digitalbox (LON:DBOX), Mattioli Woods (LON:MTW), Unite (LON:UTG)
◄Tremor International (TRMR)► becomes Nexxen (NEXN) tomorrow - "an exciting next step in the rebrand we embarked upon several months ago with a mission to unite our brands, simplify our story, better highlight the holistic value proposition blah blah blah". [SP=197.6 Cap=366m]
◄MJ Gleeson (GLE)► warns FY-June gross margins falling below expectations by c. 1.5-2%..Blames additional costs relating to a number of older sites and weak demand. H1 saw 14% fewer units sold. [SP=530 Cap=309m]
◄Live Company (LVCG)► re-iterates that it is in the process of finalising its accounts with completion envisaged by end of Jan. [SP=2.08 Cap=5m]
◄Mobile Streams (MOS)► £300k placing at 0.06p, a 14% premium, to to fund the expansion of its operations in Mexico and for working capital [SP=0.06 Cap=3m]
◄Seeing Machines (SEE)► to unveil latest Guardian technology at giant tech show CES 2024. It has Drowsiness Detection with refined microsleep detection and eye-gaze tracking. [SP=5.32 Cap=220m]
◄Intelligent Ultrasound (IUG)► warns FY-Dec rev up only 10% to £11.2m. Simulation rev c. £1m behind expectations, mainly due to weak sales in Europe and China and recognised revenue being slightly less than expected in Q4. Guides FY24 rev £14m-17m and continues to expect reaching profitability with its current cash. [SP=10.2 Cap=33m]
◄Chamberlin (CMH)► £830k placing at 2p, a 30% discount, for working cap. [SP=2.7 Cap=4m]
◄SIG (SHI)► guides FY-Dec rev up 1% with LFL down 2%. U/L op profit in the upper half of £50-55m guided. FCF only c.£4m. [SP=32.07 Cap=379m]
◄Quartix Technologies (QTX)► guides FY-Dec rev £29.8m up 8%, adj EBITDA (which it calls profit) £4.9m and FCF (excl purchase of Konetik Deutschland) £3.1m. ARR up 8%. 'Cash balance' £2.3m - is that net cash? May cut div from usual level. [SP=150 Cap=73m]
◄Hiro Metaverse Acquisitions (HMA1)► to delist and pay £10.72/sh. Says it will not be possible to complete a business combination before the deadline. [SP=NA Cap=NA]
◄Kooth (KOO)► launched its digital mental health platform and mobile app in California on 1 Jan. "As indicated previously, the contract has an expected value of $188m through to June 2027." [SP=314 Cap=114m]
◄Eden Research (EDEN)► California approves Mevalone. [SP=6.1 Cap=33m]
In line: CRTA, DBOX, MTW, UTG
I hold Tremor International (LON:TRMR) , oo-er! so hoping to see you eating your words Mr Contrarian!
Games Workshop (LON:GAW) half year results out this morning. Obviously not a small cap but well followed and was of course mentioned in the recent multi bagger webinars as one of the ten baggers over the last decade.
This is my biggest holding and rather like Next (LON:NXT) , it really is just an exemplar of good management and reporting. Absolutely zero PR nonsense, zero EBITDA and straightforward, owner aligned commentary.
Results are inline but in my (not unbiased) opinion, stellar. This just keeps on trucking, with record sales, record profits and record dividends in spite of the macro environment.
Just a few snippets that I picked out:
"Our decisions are focused on long-term success, not short-term gains."
"increased cash buffer to £75 million ... three month cash cost of running Games Workshop - on a rainy day we'd prefer to be able to look after ourselves"
"we own .. some of the best under exploited intellectual property ('IP') globally."
"continue to grant licences to carefully chosen partners that respect the need for us to have complete ownership of our unique IP, to ensure no harm is done to the core business"
"improved core gross margin and managed operating expenses well"
"revenue growth (+11.0%) Retail (+12.3%) Trade (+12.6%) Online (+4.9%)."
"Gross margin at November 2023: 69.4%"
"£64.2 million in dividends during the period (2022/23: £54.2 million)."
"Cash generated from operations - £116.9 million (2022/23: £104.7 million)."
"not planning any share buybacks or acquisitions."
"The Warhammer hobby continues to spread globally."
"81% of our stores delivering like for like growth in the reported period."
"UK is recording record sales levels"
"North America retail is also at record sales levels"
"new Australia site is planned to be operational in April 2025."
"Registrations for My Warhammer continue to grow at pace and we have 576,000 active users at the period end (2022/23: 346,000) up 66% on prior year."
"Email Subscriber numbers, (defined as the number of people who opened one of our emails in the last six months) were 570,000 (2022/23: 476,000)"
"Warhammer+ subscriber numbers are 169,000 at the period end (2022/23: 115,000)."
Re. Amazon deal: "We remain confident we will bring the worlds of Warhammer to the screen like you have never seen before."
"growing emerging markets: sales to Mexico, Thailand and closer to home in Switzerland, are at record levels"
All in all, just bloody marvellous.
Thanks for the write up johnsmith68, it's interesting reading. I agree that Games Workshop (LON:GAW) is a fantastic growth company, though I'm not quite as excited by these results. Plenty of good to take, however revenue and profit growth is way below the historic average and licensing revenue, which gives a nice boost to profits has declined. They invested a lot of money & time recently in improving operations, so I expect this is just a temporary deceleration until all the new systems are running smoothly. I'm interested to see if they can get back to that mid/high teens growth rate though.
Any way I thought I'd add my snapshot in here to add to your post. I've owned Games Workshop in the past and have it on my watchlist to re-enter at some point.
Re Games Workshop (LON:GAW) - maybe not as hot as 20-22 -> people re-getting a life.
Market and investors like to do a bit of angst...but the reality is that GAW is already priced like its a modest or ex-growth biz given its underlying margins. In fact to get negative one needs to believe that they are going to invest regardless of 'peak sales' and chase the dragon into oblivion?
Clearly they needed to invest to catch up with themselves given how last few years took off...that takes some cogitation as a business, particularly when you truly own the entire creation of product like they do (in a meta physical as well as physical sense)
Stand back a little and GAW is a good to great value opp....IMO obvs. Try not overthink this one...and its probably got decent sales growth ahead still
Why do the Stocko ratings have its 'Value' so poorly rated then?
As its not cheap on any sort of ordinal or cardinal type ranking that is taken to give relative value in a fairly simplistic quantitive context either at market or sector level...these measures don't use any long duration growth or profitability forecasts and of course long term estimates are thin on the ground so can't really do that cross sectionally...
...but in world where long term profit and growth forecasts were broadly available and somehow normalised such that we don't implicitly assume overall GDP is going to be 20%pa then Games Workshop (LON:GAW) could look good value even cheap.
If you think the future looks something like the past at GAW (not necessarily such a high level of top line growth but some growth and high margins) then it looks cheap IMO.
Thanks for the reply, I think I am guilty of taking the metrics at face value too easily.
Thanks Phil for your excellent spreadsheet and summary of Games Workshop (LON:GAW). It's good to get a cool headed assessment to challenge my enthusiasm (the market reaction today seems to agree with you too.)
For me, as a core long term holding, the most important thing is for me to be sure that the hobby and the market can keep growing into the future.
I'm sanguine about the licensing revenue because it's currently the icing on the cake but has the potential to provide massive upside in due course. I wonder if the Amazon deal will fire the starting gun on the development of this potential. It's obvious that management are aware of the potential when they talk of owning "some of the best under exploited intellectual property globally".
I like that they are still managing to grow the hobby in all geographies and the excellent metrics on registrations and subscriber numbers (My Warhammer, Warhammer+ and Email) all point towards growing interest and engagement which can only be positive for future revenues. The growth in emerging market territories as well as record sales in the UK and USA are also pointing towards future growth.
The current P/E for such a high quality and high margin, vertically integrated, growing business whilst punchy, is not excessive historically in my opinion.
This has probably been asked/mentioned before, but am I right to be concerned/interested in how often sp movements are followed by a price affecting RNS? For example, MJ GLEESON (LON:GLE) up 8% yesterday, trading update today.
Or am I just naïve?
Interesting to see what way price goes today. Up 8% today, but trading update looks like a profit warning?
MJ GLEESON (LON:GLE) [I hold] was up 8% yesterday not today, it's lost that gain and more in early trading. Yesterday has to be seen in the light of other house builders rising to some degree, and a 'buy' recommendation in a 2 page Investors Chronicle spread - immaculate timing. Price can only fall today, increased reservations are at the cost of already tight margins.
MJ GLEESON (LON:GLE) I also picked up from somewhere yesterday or Sunday that someone was about to announce some excellent mortgage offers - somewhere around 3.5% fixed for 2-years I seem to recall, which I suspect must have made some people believe that housebuilders (and related stocks) might therefore be expecting a pick-up in sales.
No holdings.
I think that was more based on the Investors Chronicle article. But it does seem to happen from time to time.
No way! Of course insiders don't buy or sell ahead of a price sensitive announcement. That would be insider dealing.
But just maybe their uncles and aunts, friends and colleagues might decide to buy or sell coincidentally before an announcement.
There is a widely known market saying "Buy the rumour, sell the news". But from where would that rumour come?
A statistical analysis of volumes, price movements and RNS announcements would pick this up easily if the supervising bodies were truly interested in stamping out insider trading. But would they really want to shop their mates? And wouldn't finding that insider trading is commonplace damage the credibility of the exchanges?
Mattioli Woods (LON:MTW) - On track for 10% annual revenue & profit growth (new report & audio summary here: https://www.equitydevelopment....)
H1’24 revenue (to 30 Nov 23) totalled £59.1m, 8% up y-o-y (H1’23: £54.9m), with 4% organic revenue growth. H2 revenue is typically higher than H1 due to end of tax-year advice and H2 weighting of client year-ends, and we maintain our FY24 revenue forecast of £123.6m (+11% y-o-y).
MTW remains in a strong net cash position (£32.7m v £45.0m on 31 May 23), giving scope to pursue opportunities. Cash is as expected with c. £9.3m paid in dividends and some tranche-payments of previous acquisitions made. We expect cash to exceed £40m by year-end.
As in FY23, MTW has reported growth within the core pension consultancy and employee benefits business segments, with the proposed changes to pension and tax rules announced in the Chancellor’s recent Autumn Statement driving strong demand for advice.
Our sector PER analysis suggests potential for a rerating of both the sector and Mattioli Woods, where our fundamental valuation remains 900p / share, 50% above the current price.