Small Cap Value Report (Tue 9 May 2023) - PURP, RNO, TTG, MACF, MCON, MSLH, HSW, CSH, BOO, MIDW, CTG

Good morning, it's Paul & Graham here today.
Today's report is now finished, at 13:02
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
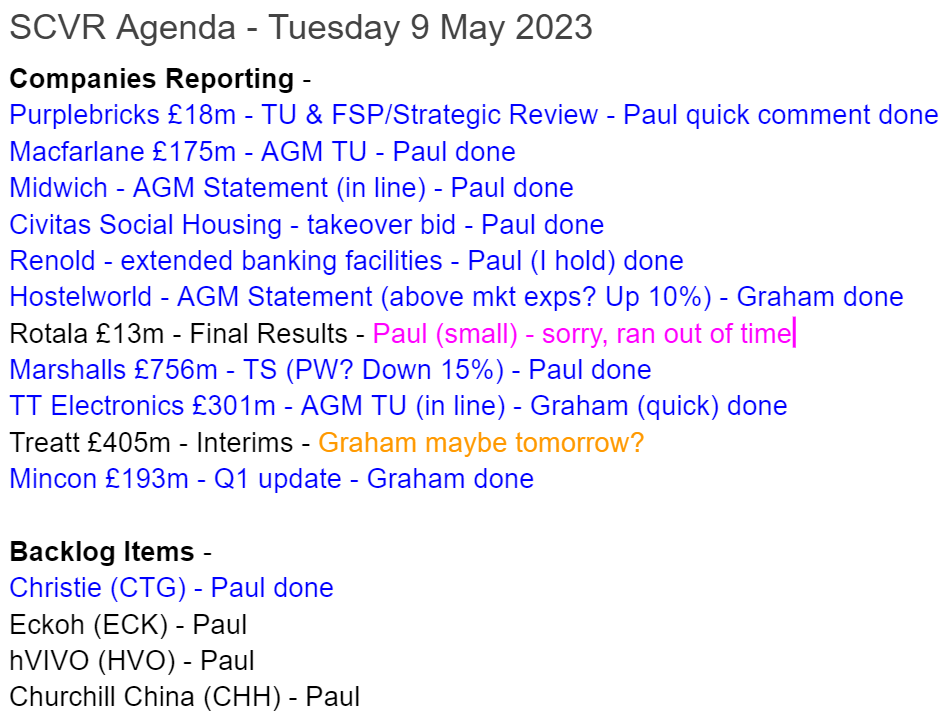
Summaries of main sections below
Mincon (LON:MCON) - 90.75p (unchanged) (£213m) - AGM TU - Graham - AMBER
Broker estimates are unchanged this morning (pencilling in 7% growth) despite news that Mincon’s mining-related revenues are suffering from an exploration slowdown. I want to give this stock the thumbs up but news flow remains very mixed. It stays on the watchlist for now..
Marshalls (LON:MSLH) - down 15% to 252p (£641m) - Profit warning - Paul - AMBER
Lowers expectations, but declines to give any specific guidance, and no broker updates available. So we're in the dark. Blames macro factors, slowdown in housebuilding, and slower discretionary house repair/maintenance. I'm struggling to reconcile this with upbeat recent comments from brick sellers. Maybe best to avoid the whole building supplies sector for now? Or anticipate a recovery later? Debt is also a concern at MSLH after a major, ill-timed acquisition of Marley in April 2022.
Hostelworld (LON:HSW) - 140p (+8%) (£170m) - AGM statement - Graham - AMBER
Profitability is ahead of expectations at this hostel-focused online travel agent. Bookings continue to recover and bed price inflation is also significant, leading to record revenues. The company has refinanced its onerous debt facility and now looks much more investible.
Christie (LON:CTG) - 135p (£36m) - FY 12/2022 results (released 24 April) - Paul - AMBER
A backlog item, I looked at it over the long weekend, my notes are below in a main section. It looks quite good, and looks set up to produce better 2023 results than 2022's OK numbers, as a loss-making stock-taking subsidiary is now back in profit. Might be worth a look, but doesn't excite me enough to go green.
Quick comments:
(no additional sections below)
Purplebricks (LON:PURP)
5.5p (pre-market) (£17m) - Update - Paul - RED
A disastrous update today from this declining online estate agent (of sorts), so expect maybe a 50%+ share price collapse today.
Key points today are - shareholders have refused to put in more cash. Sale process needs to be concluded quickly before it runs out of cash. Only £9.1m cash remaining end April. Customer finance provider is getting difficult & withholding some cash. “Small number of parties” in discussions over a takeover deal, but would be “materially below” current share price, if at all.
Paul’s view - this now looks like it could be a zero, or close to zero, for shareholders. Why would a bidder take on all the liabilities? Much easier to wait for it to go into administration, then just buy the brand name for peanuts, with no liabilities. Bad luck to any holders. It’s staggering how much cash the company has burned through, but it’s clearly just not a viable business model. Time to salvage whatever cash you can, and move on, I'd say.
Renold (LON:RNO) (Paul holds)
27.5p (pre-market) (£62m) - Extension of banking facilities - Paul - GREEN
Renold, a leading international supplier of industrial chains and related power transmission products, is pleased to announce it has reach agreement for the extension of its core banking facilities that were due to mature in April 2024.
Bank facilities enlarged from £61.5m to £85m + £20m accordion for acquisitions.
Santander has joined the existing banking syndicate (now 4 , instead of 3 banks)
3-year term to May 2026, with a 2-year extension option.
Key covenant (Net debt: EBITDA) loosened from 2.5x to 3.0x.
Paul’s opinion - I bought some Renold earlier this year, as I think the long-running turnaround has worked well, and this share looks a good quality business now, at a modest valuation. Remember the big pension deficit outflows are part of the reason for a low rating though. More debt brings more risk, but also allows Renold to expand its way out of the pension deficit problem (i.e. diluting it in a larger group, once more acquisitions are done).
Overall then I view this share positively, as does Stockopedia, with a StockRank of 90, and clearly also the banks see it positively too.
TT electronics (LON:TTG)
169.8p (pre-market) (£301m) - AGM TU - Graham (quick) - GREEN
We have an AGM update from this electronics manufacturer: the important news is that expectations are unchanged as “momentum from last year has continued”. As I noted when I initially turned bullish on this stock, the cheap earnings multiple attached to this one belies some robust underlying growth trends. Revenues for the first four months of 2023 are up 16% year-on-year (at constant FX), with a record order book and this year’s forecast revenues (£629m) now “almost fully covered by orders”.
Among TT’s priorities, mentioned today, is free cash flow. TT did become temporarily overleveraged last year, but that situation now appears to be under control. An old pension fund is no longer going to drain it of any further cash, and the leverage multiple should move below the 2.0x level which is the company’s stated upper limit. I’ll continue to give this stock the green light while it has a single-digit P/E ratio, hoping to see 2023 results emerge with much lower impairment and restructuring adjustments.
Macfarlane (LON:MACF)
112p (unch) (£177m) - AGM Trading Update - Paul - GREEN
Headquartered in Glasgow, MACF makes & distributes packaging materials.
Today it says -
Solid start to 2023 - on course to meet full year expectations
Acquisitions are being self-funded - 2 made so far in 2023.
Negligible bank debt of only £0.1m, with a facility of £30m.
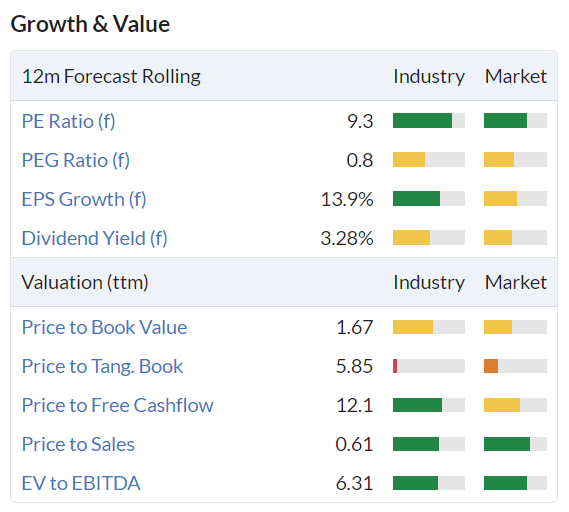
Paul’s opinion - valuation measures below look very attractive to me. This seems a decent business, at a modest valuation. Patient investors could do well here, I reckon.
Civitas Social Housing (LON:CSH)
Up 43% to 79p - recommended cash offer - Paul
Not a share we cover (because property REITs take a long time to research), but well done to any holders. Although this agreed 80p cash bid does possibly look opportunistic? The bidder seems to be a Hong Kong based investment company.
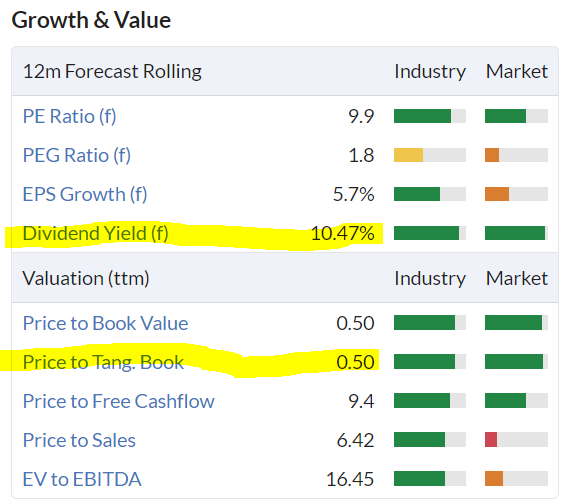
The valuation measures that look particularly cheap (see below) are an amazing dividend yield, and a price of only half tangible book value. These numbers always have to be manually checked, because there might be a reason for them (eg. something has gone wrong more recently, that won’t be reflected until the next published accounts).
I see another company with “social housing” in the name is up 17% today, Triple Point Social Housing REIT (LON:SOHO)
It certainly looks as if the REITs sector could contain some other oversold bargains? Worth having a trawl through, to look for big discounts to NTAV, and very high divi yields, perhaps? Although avoiding basket cases with too much debt is the main risk factor with property shares.
Boohoo (LON:BOO)
Down 5% to 44.3p (£560m) - press reports - Paul - RED
I noticed weekend press reports that Boohoo is said to be demanding 10% discounts from its suppliers. This is always a bad sign, in my experience, of a business that is struggling. Hence I'm wary of this share for the time being, and it's been a long time since we last had a trading update.
Paul's view - the ESG stuff has all just been background noise. The reason the share price has collapsed, is because profits and growth have collapsed. Can they turn things around? Maybe, but as time goes on, I'm increasingly wondering if the golden era for fast fashion eCommerce may be over? Although lots of competitors have gone under, so maybe more market share for BOO, and lower marketing costs possibly? There should also be positive margin tailwinds from lower freight costs. But I don't want to be in the business of hoping, and guessing, that didn't work well in the past! So this is an avoid for me, until we have an up-to-date trading update, when we can look at it with fresh eyes.
Midwich (LON:MIDW)
Down 1% to 446p (£407m) - AGM Statement - Paul - GREEN
A growing distributor of audio-visual equipment, internationally.
Today it says some markets are challenging, but overall trading expectations are unchanged. That sounds fine to me, and I like the valuation here too, forward PER of 11.6x, and a 4% yield. The general tone of today’s update sounds fairly confident, I can’t smell a future profit warning between the lines!
Graham reviewed it in March, and was a little tight only going amber, so I’ll push the boat out and give a green opinion on this, taking a medium term view, as always - we don’t know what share prices will do in the short-term of course, that’s down to sentiment. I imagine this share could re-rate to a higher PER in a bull market.
The balance sheet isn’t the best I’ve seen, but it’s not terrible either.
Paul's Section:
Marshalls (LON:MSLH)
Down 15% to 252p (£641m) - Profit warning - Paul - AMBER
Marshalls is a UK manufacturer of stone, concrete, and other landscaping, building, and roofing products. Today’s update is for Jan-Apr 2023.
LFL revenue is down -14%, although the large acquisition of Marley took overall 4m revenue up 12% to £227m.
Reasons given: uncertain macro, reduced housebuilding, and lower repairs/maintenance. This is strange, as the brick manufacturer/distributors have recently reported solid trading. So it’s not clear to me what’s going on.
In the first quarter of the year, National House Building Council new housing starts were 27 per cent lower than 2022, which had an impact on the performance of all the Group's reporting segments.
Actions taken - cost-cutting, and production efficiency improvements.
Some clarity is provided with the divisional performance statistics -
Landscaping products (the largest division) - revenue down 21%, hit by reduced new housebuilding, and reduced discretionary spend.
Building products - revenue down 9%. Bricks, masonry & mortar only down modestly. Drainage & aggregates held back by deferred housebuilding starts.
Marley roofing (acquired last year) - revenue down 6%. Integration is going well.
What to make of all that? I find it confusing! Why would some product categories be down a lot, but others not?
Belgian subsidiary disposed of in April 2023, was trading at a slight loss.
Net bank debt has risen £29m to £220m since Dec y/end, due to seasonal working capital. It is prioritising debt reduction. This looks too high for comfort.
Outlook - short-term challenging. Year-to-date trading below expectations.
It doesn’t quantify, or give any indication at all, as to how much worse 2023 is now expected to be compared to its original budget.
Paul’s opinion - there are no broker updates on Research Tree, so I can’t take this any further, and am not able to value this share.
Bank net debt of £220m looks worryingly high, now that profit is missing target. So that’s enough to scare me away for the time being.
The last balance sheet at Dec 2022, which includes the big Marley acquisition is very top heavy with goodwill (at £560m), and long-term bank debt of £247m stands out as being too high. So it looks as if they made a mistake with a badly mis-timed, large acquisition. Is it terminal? I’d say no. The balance sheet still shows NTAV of £102m, and I imagine the bank is likely to play ball, and give MSLH time to generate the cash to get bank debt down.
All of that does put a question mark over the valuation of equity though. Should we be cautious because of the problems this year, or look through it as an aberration caused by the mini budget last year, and anticipate improved trading maybe in later 2023, or 2024? That’s your call, I don’t have a strong view either way.
Overall then, I just see this share as neutral, AMBER.
It does raise questions about how we should be seeing other building products shares? I was keen on the brick makers/distributors, which have reported OK trading of late. But with MSLH reporting a slowdown, then surely it’s only a matter of time before the brick companies follow suite with slowdowns? I think on balance maybe it’s best to avoid shares of companies selling building-related products for the time being?
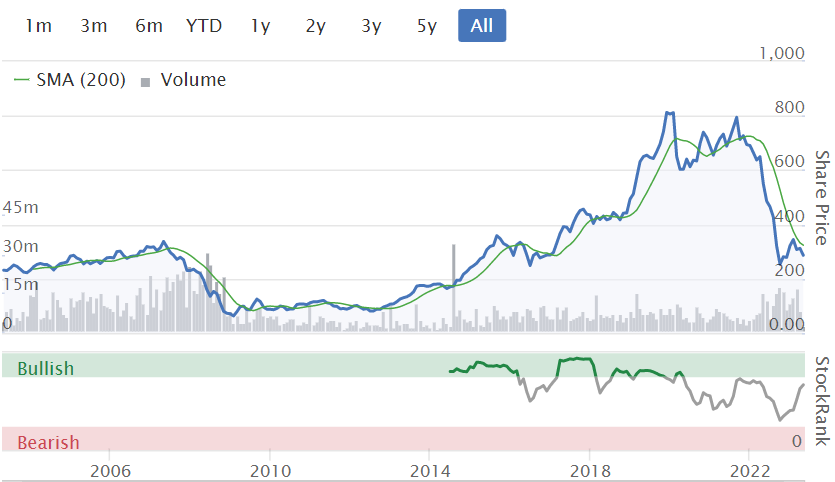
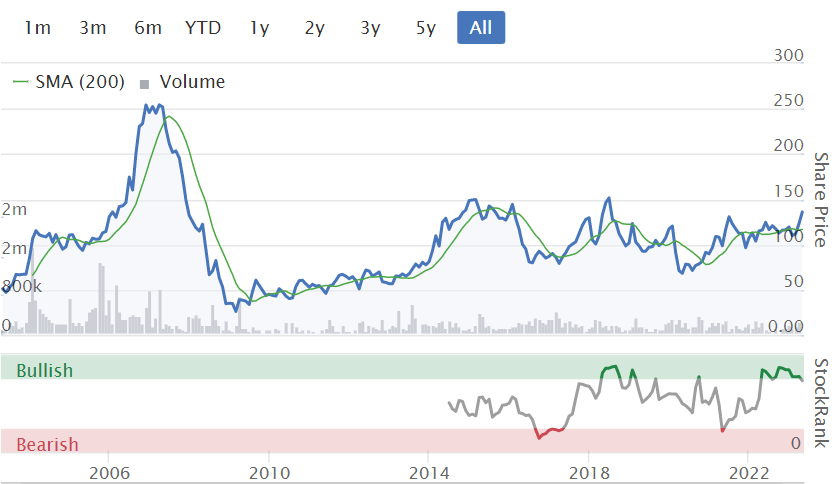
Amazingly, MSLH's share price is back down to where is was 20 years ago. Although there have been dividends received along the way, so the total shareholder return would look better than just the share price chart below.
Christie (LON:CTG)
135p (Friday’s close)
Market cap £36m
StockRank: 73 - Fwd PER 9.4 - Divi yield 3.5%
Lord Lee flagged up this share to me, he reckons it’s really cheap, and has a disclosable stake so is backing his judgement with his money, a good sign in my view! So I took a look over the long weekend. Here are my notes.
April 24, 2023 - FY 12/2022 Results published.
Various divisions, with most important one being 38 offices which provide commercial property valuation & sale of businesses. Also a loss-making stock-taking division.
2 pension deficits eliminated now, making £1m pa cash savings in future, allowing an increase in divis perhaps?
Net cash position improved to £7.2m at 12/2022(was £4.6m a year earlier)
Total divis for 2022: 3.75p
No dilution over covid: 26m shares in issue last 6 years.
One major shareholder: Philip Gwyn owns 28%, and other Gwyns about 5%. Ruggs own 11% (Ch & CEO). Who are they, and what are their intentions? Lord Lee holds 4.2%. Unusually, no institutions hold over 3% - strange, why not? De-listing risk?
FY 12/2022 PBT £4.4m (up from £3.9m in 2021)
Corp Tax charge up a lot, £1213k in 2022, vs £316k in 2021, hence PAT & EPS fell in 2022.
Diluted EPS 12.15p (LY: 13.3p), so PER is 11x - looks about right?
Pension changes - look odd, needs investigation - eg. £20.6m actuarial gain, less £13.9m cost of “asset ceiling” - what is this?
Balance sheet is adequate at £5.5m NTAV - fine as it’s asset light (only £1.1m fixed assets).
Onerous leases perhaps? There’s a £3.6m deficit on IFRS 16 entries.
Not particularly cash generative.
Trading has now returned to normal, after covid disruption.
Loss-making division (stock-taking & inventory) made a £2.1m operating loss in 2022, but this could be eliminated in 2023, thanks to covid disruption not repeating, and new client wins (eg Stonegate & other pubs groups).
Outlook - expects H2 weighting in 2023. Hoping to improve on 2022 operating margin of 7.9%.
Paul’s opinion - I can see there are catalysts for 2023 numbers to improve on 2022. But this share has gone nowhere for 20 years, so I’m struggling to see why it would re-rate onto a higher PER?
Overall though, I see more positives than negatives, so am leaning towards green, but it’s not quite exciting enough, so I’ll stick with amber for now.
Graham’s Section:
Mincon (LON:MCON)
Share price: 90.75p (unchanged)
Market cap: (£213m)
We digested this company’s full-year results for 2022 back in March.
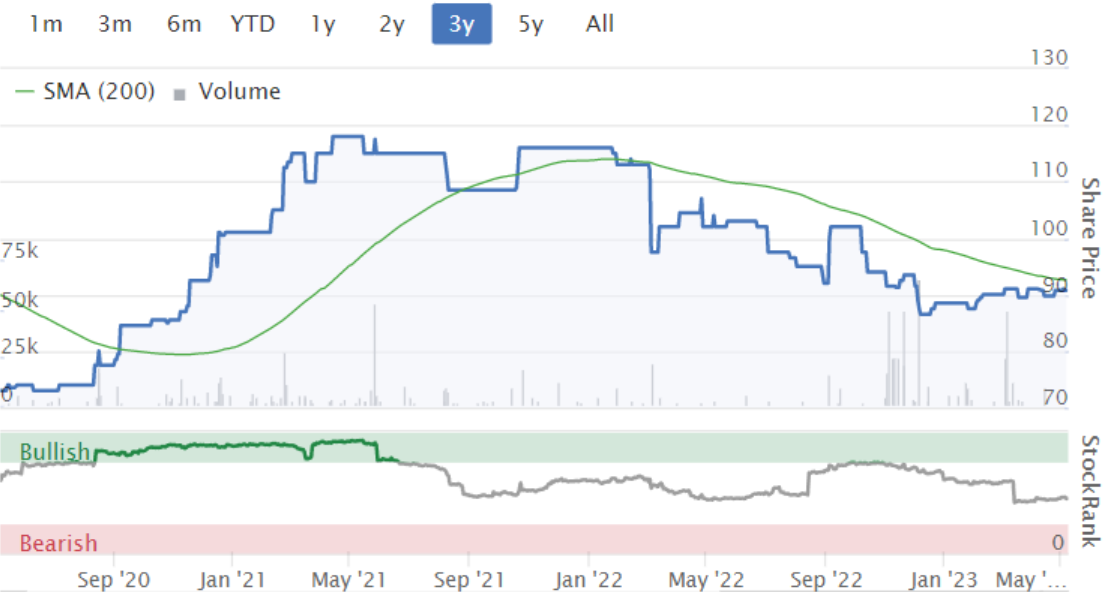
Mincon designs, manufactures, sells and services rock drilling equipment, and updates us this morning with the news that Q1 revenues are “marginally behind” Q1 last year, due to a slowdown in mining exploration activity. More positively, trading with the construction sector remains strong in both North America and Europe.
When it comes to profitability, Mincon has been held back by input cost inflation and also by a large order backlog which necessitated the use of expensive air freight. Thankfully, both of these issues are being tackled and the company reports an increase in gross margin so far in 2023. Higher prices are being passed onto customers and a smaller backlog is enabling the use of cheaper freight options.
Finally, their new hydraulic hammer system “Greenhammer” remains in focus as Mincon tries to ensure that it doesn’t have any more reliability issues with its drill rig. They are now working with “a leading global rig manufacturer” to come up with a solution - I wonder how long this might take?
Broker estimates for 2023 are unchanged this morning (revenues €182m, adj. EBIT €21m), with the expectation that mining revenues will improve as the year progresses.
Graham’s view
I wrote previously that I could turn positive on this stock if news flow turned more positive, but unfortunately today’s update still leaves tricky questions to be answered: how long will the mining slowdown last? And how long will it take until Greenhammer’s rig issues are resolved? I still like this company and the valuation appears to be reasonable, but in my view it hasn’t quite done enough to justify a positive stance.
Hostelworld (LON:HSW)
Share price: 140p (+8%)
Market cap: £170m
This share price has quietly doubled over the past year:
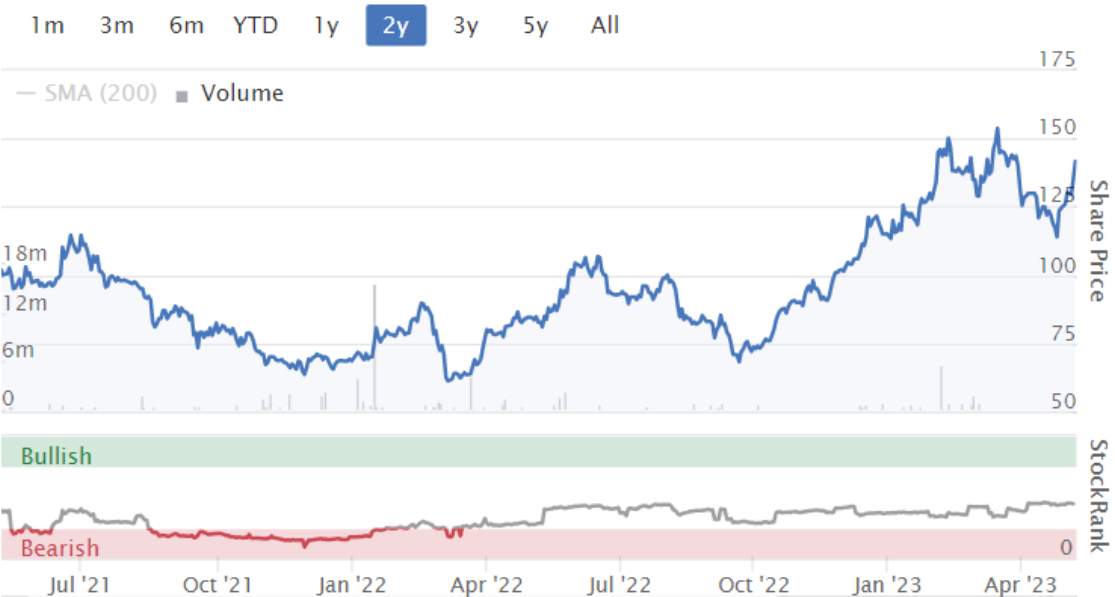
Well done to holders, as they’ve bravely continued to own this share through horrible trading conditions and some poor financial results. The share price is now higher than it was in December 2019, just before Covid struck the travel sector!
The company describes itself as “a leading global social network powered OTA [online travel agent] focused on the hostelling category”. I remain sceptical of the claim that it’s building a valuable social network for people who stay in hostels, but then again I haven’t stayed in a hostel myself for twenty years so maybe I’m just too old to appreciate it?
The Chairman will make a statement at today’s AGM including the following information:
The strong start to 2023 has continued
“Bookings in many destinations are above 2019 levels”
Bed prices are higher than 2019.
With higher bed prices and the number of bookings improving, the result is that Q1 revenues are at a record level. Revenues in 2019 were €81m, while forecast revenues for 2023 as of last night were €86m.
Profit beat: adjusted EBITDA for 2023 is now expected to be within a €16.5 - 17m range, versus prior expectations of €14.6m.
A word of caution: in 2022, HWS reported an adjusted EBITDA profit of €1.3m, but the operating loss was €13.6m.
Debt refinancing: one of the major issues at HSW, from my perspective, has been a debt facility that was too big (€30m) and too expensive (9% + Euribor). In excellent news released today, this “legacy facility” has been fully refinanced.
€10m was paid off
New €10m term loan
New €7.5m RCF
New €2.5m overdraft (undrawn)
The new 3-year facility charges just 3.75% plus Euribor, and the rate reduces as the leverage multiple reduces below 2x.
Chairman statement:
This new facility, with materially lower interest costs, significantly strengthens our balance sheet, represents a strong endorsement of our post-pandemic performance, and consolidates the firm foundations upon which we will drive profitable growth and create shareholder value."
Graham’s view
I’m very pleased for HSW that it has substantially solved its debt issue (of course it will still have to satisfy the terms of its new facility). If we use simple assumptions and put EURIBOR at 3%, the company’s annual interest bill has reduced from €3.6m to €1.3m, i.e. over €2m of savings per year, with further savings to be had if it makes further progress reducing its leverage. There are substantial savings for a company of this size.
This news, combined with a recovery in bookings and revenues, leads me to think that HSW should be able to start generating material profits again before long. It was doing this from 2017 to 2019, before disaster struck.
But now we have Hostelworld 2.0, with a new app designed to help travellers meet up. The company says that this innovation is “proving to be hugely popular and has helped deliver market share gains in key markets”.
I’m tempted to give this stock the thumbs up but I’ll hold back for now, as I wait for adjusted EBITDA to translate to real profits that can justify a £170m market cap. At this valuation, I think it’s fair to say that quite a lot of success has already been priced in here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
PROCOOK (LON:PROC) - CEO bought 510k @27p on 5th May. Fackelmann GmbH declare a rise in holdings to 12.084% - RNS earlier. StockRank has gradually started creeping up. Something cooking?
The O'Neil clan hold nearly 69% of the company, that may set the timer off
Hi
Just a quick question, has anyone had the dividend for @Somero Enterprises (LON:SOM) hit their account yet?
I appreciate that IWeb are not particularly the fastest snail in the race so might just be somewhere in the system.
Thanks
Tommy
HL gave me mine last friday
not yet for me, im with halifax.
Truegent - Iweb is a trading name of Halifax. But no frills and v cheap (no annual charge and £5 per deal) - well worth a look. However, and it's a real bugbear for me), they refuse to reclaim the US tax using a W8BEN form for Somero - won't clearly explain why, but simply state that it's because Somero are a US company listed in the UK - ie not listed in the US. Can you confirm what the position is for your holding via a Halifax branded platform?
I'd be v interested in how many Somero holders there are who use Iweb / Halifax.
i didnt know any of the above but ive had somero shares with halifax for a few years and never had any problems with dividends. i do recall filling out the W8BEN form though at some point...
Truegent - could you check what level of tax you're paying on Somero dividends? I'm guessing it will be 30%, but would be v interested if it's 15%!
Came in today AJ Bell.
Civitas Social Housing (LON:CSH) (no position) was targeted by a short seller in 2021 and has never really recovered. Also, there's been a lot regulatory examination of social housing which read across to Triple Point Social Housing REIT (LON:SOHO) (I hold) - specifically some of their property managers have been identified as needing improvement. Worth a read of the RNS announcements if you are considering.
Paul, noticed the below on The Times Business Brief:
DELOITTE: The Financial Reporting Council has started an investigation into the accountancy firm’s audit of the fashion retailer Joules for the year ended May 20, 2021. Joules collapsed into administration in November after failing to secure rescue financing. It was bought out of administration by Next and its founder, Tom Joule.
Best
Mark
Wow, just got in to see that my largest holding Civitas Social Housing (LON:CSH) has gone up 40%+ on a recommended takeover.
I will now review my other holdings on large discounts to NAV such as Triple Point Energy Transition (LON:TENT which I think was on a 40% discount, last time I looked. That said, I see that CSH is being bought for 80p, but today’s updated NAV is over 109p. So the HK property developer is getting a quality portfolio, with very few vacancies, 20+ years leases, and Government backed rent at a 26.6% discount.
The market is certainly being very generous to overseas purchasers at present!
Last month I looked at both Civitas Social Housing (LON:CSH) and Triple Point Social Housing REIT (LON:SOHO) , buying CSH as a Stocko comparison said it was the better of the two. I note that CSH is classified as a Neglected Company while SOHO is seen as Philip Fisher Growth. Being a Reit I have my doubts about SOHO as I held Picton Property Income (LON:PCTN) from 2013 till 2018, selling out at 92 pence and today its price is 74 pence. I might just prefer your Triple Point Energy Transition (LON:TENT) Martin when I get the CSH compensation.
Macfarlane (LON:MACF) AGM Trading Update (I hold)
My thoughts on this mornings Q1 figures. (Edit: Just seen that Paul has commented on MACF this morning – thank you – it seems that I am in agreement, this note adds a little more detail on what might be happening under the covers based upon the Q1 revenues and timing of acquisitions extended to the FY).
Confirms FY expectations unchanged. Management has established a record of caution and conservative accounting, which has served them well in recent years not have issued a profit warning and with profits rising YoY thoughout the turmoil. The company has a second half weighting, so I’d not expect management to push the boat out on Q1 figures.
I commented - here - last week in the SCVR 2nd May2023 - on the latest acquisition that market forecasts seemed to be consistently behind company progress.
I see from the stockreport that market forecasts have been – quietly - raised this morning to revenue of 315m (from 312m) and net profit of 15.4m (from 15.3m) and eps (adj?) of 11.8p (from 10.8p) for the current year. (edit – I’ve just found an upgrade from Shore Capital (house broker) on the acquisition can be downloaded free from Research Tree – Thank you Shore Capital - looks like these figures have now worked their way throught the consensus?)
Although that’s a healthy uplift to market expectations – I notice that its still a forecast of a fall in net profits in FY23 of 15.4m versus 15.6m in FY22 – presumably due to the increase in corporation tax expected in FY23.
So how do the upgrades this morning relate to the in-line management expectations? Hard to tell. I suspect that the brokers are still a little behind the curve on progress. So I’ve run the figures through my own simple spreadsheet – it’s complicated by the combination of 1 acquisition in distribution in may 22 and 2 acquisitions so far in 23, 1 in May 23 in distribution and one in March 23 in manufacturing.
My pro-rata estimate for FY23 based solely upon the contributions of the acquisitions is for an additional £12.5m of revenue to £303m (£315m current forecast) and additional profit of £1.45m (at 25% tax rate) to £16m (£15.4m current forecast).
How does my estimate result in lower revenue and higher profit than the market expectations? Time to take a dive into the Q1 figures.
This morning’s update gives Q1 revenue figures of +4% growth in distribution and +14% growth in manufacturing. Looking at my spreadsheet on a pro-rata basis (Q1 figures are not revealed)
Distribution. It looks like revenues are effectively flat to slightly down – excluding the effects of the Packmann acquisition.
Manufacturing. It looks like revenues are up quite strongly – around 6% - even after excluding the effects of the Sutton acquisition in March.
Overall. My simple assumption is that organic profit and revenue are flat upon FY22 then added the effect upon revenue and profit of the acquisitions.
Is this a likely outcome? It’s certainly plausible – management reported that they have put through inflationary price rises in distribution with profit and revenue being supported by the price rises but offset by the falling volumes (particularly from e-commerce). Packaging distribution looks to be difficult in the current economic environment where high inflation tends to hide lower levels of volume being bought in the economy?
I wonder if there is something of a re-shoring effect giving a tailwind within manufacturing which tends to be a more specialist/bespoke provider to aerospace/automotive/pharma – Robinson also reported strong figures recently?
There are plenty of moving parts I’ve not considered using this simple approach – changes in capex, interest rates, amortisation and depreciation for example – overall the upgraded market forecasts look reasonable if more cautious in profit. Looks to me like I’m a tad on the optimistic side (not unusual it has to be said) with management in the middle and the brokers tending towards the low side. Given the number of profit warnings coming through on small caps that’s no great surprise? If progress continues – and/or perhaps another small acquisition – then my estimates give room for a further upgrade later in the year?
The share is lowly rated on current progress let alone the track record of management in continuing to buy-and-build through the years. This is a game of waiting for management to do their thing and the market to reflect the quality of those results in the price. Tortoise not the hare!
Cheers
Mark
I really like Macfarlane (LON:MACF) as a business and did hold for a while a few years back.
One thing that concerns me a bit is that one of their largest customers is Parsely Box as I understand it and I'm yet to be convinced this has a long term future. If they went bust what would be the impact on Macfarlane (LON:MACF) sales/margins? I'd be inclined to discount this to zero and then determine if it is still cheap.
If anyone has that kind of detail I'd be appreciative
Macfarlane (LON:MACF)
One thing that concerns me a bit is that one of their largest customers is Parsely Box as I understand it
Ah. Thank you David - that's a fascinating question.
And its allowed me to look a bit at Macfarlanes customer concentration, stock write-offs, trade receivables and credit control. Lucky me. I got caught out a bit by the Zytronic warning last week over two large customers, so credit control turns out to be something I ought to be paying more attention to in future?
Well you did ask!
I'll start with Macfarlane. Turns over about £300m with around £20m in pre-tax profits and according to the website it has 20,000 customers and 'low customer concentration'. Whatever that means? Certainly no list of top customers in the risk register, where customer concentration doesn't get a mention, but credit control, trade receivables (60m) and loss allowance (0.795m ), inventories (£22.6m) and stock provisions (0.633m) and stock write-offs ( 0.384m) do get mentioned.
Parsley-Box. I know its a case study on the Marfarlane web-site, mainly because it's a temperature controlled design thats fully recyclable? There are plenty of other household names alongside like Lakeland, Curry's, Peak, ACER but I don't know if that says anything about how important they are as customers? Seems more to be promoting their design ability for well-known names? Obviously it's going to be a little more important than 1/20,000 the average customer. I'll try to put it into a ball-park.
I'm afraid that I know very little about Parsley box, other than its another of the class of 21/22 IPO's that bombed? Been taken private after haemorraging cash and with sales falling quickly. So to get a handle on it I downloaded the 2021 report filed at companies house (The last filed report). Which tells me
Revenue 20m (approx)
No of orders: 488k
Av order value: £43
Av meal value: around £5 (looking at website)
Number of meals about 1m annually (and going down fast .....?)
The macf box is for 4 meals according to the case study - so that 250k boxes annually.
Price per box? Hmmm. I'll put a finger in the air at 50p (it's actually a small box inside a larger one with a couple of sachets to accept the coolant) at 250k annual quantities?
Or £125k a year?
That's assuming that Parsley box order levels are still anything near 500k a year (its no secret that they aren't?) and that all the meals are supplied in macfarlane temp controlled packaging (they might not be) and that Marfarlane are the only supplier (they might not be)? So its probably an over-estimate? Even if you double it - it's still insignificant <0.1% - assuming of course that my rough estimates are in the right ball-park?
Even if they wrote off a year's worth its well within their current provisions? That's never going to happen as they monitor credit risk and require pre-payments for bespoke order cover. Macfarlane stock turn is really quite colossal?
Interesting exercise. I'm satisfied ( though you might not be on the basis of my finger in the air )- that something like Parsley box does not represent a risk to Macfarlane? More than likely it's rapidly declining figures are already contained within the e-commerce volume declines that Macfarlane have commented on in the last year?
Does that sound about right?
cheers
Mark
Nice bit of work.
Macfarlane (LON:MACF) and my box calculations - Whooops!
1 was losing the plot. Lost a factor on the back of the envelope - it was something like 4m meals and 1m boxes annually. Maximum. Or it was before sales started to fall off a cliff.
So that makes it £500k revenue. Less than 0.2% revenue. In any event - these are not accurate figures, just intended to be ball-park,
apologies,
cheers
Mark
Thanks Mark - that's helpful. I think I might write to management and ask them what their maximum exposure to any single client is. At least that would allow us to compare and might be a good exercise anyway.
I agree that Macfarlane (LON:MACF) have carved out a really good niche position in a very large commoditised industry and seem to be well trusted.
Will take another look
Just to echo earlier comments. Paul's weekly Podcast is brilliant. He is not only an excellent wordsmith/analyst but is also eminently listenable to across the airwaves - a rare combination.
He did mention Goodwin's (GDWN) £48 tender offer briefly on the last podcast. Would be nice to read some debate on Stockopedia of the pros and cons of taking up the offer. It appears that the Goodwin family, who own over 50% of the equity, are not going to participate. What sort of signal does that send? Does it hasten the time when the family decide to take the company private?
Quite why it remains a quoted company is baffling since it has no need to raise fresh capital.
Re Goodwin (LON:GDWN)Goodwin (LON:GDWN) from my various meetings with them over the years I’ve never had any intimation that they’d contemplate going private…a full listing on the LSE is seen as an advantage when they tender for governmental contracts globally & they are v proud of the shareholder returns they’ve produced over many many years…many shareholders are ex staff members…& engineering industry peers..eg Castings Castings (LON:CGS) chair Brian Cooke..it’s my largest position by far & I’m obviously biased but I would be staggered to see them take it private …incidentally can anyone think of a tender where the price was struck at 25% above mkt price ..& 20% higher than the ATH from way back in O&G heyday..
'Quite why it remains a quoted company is baffling since it has no need to raise fresh capital.'
That is something I see mentioned quite a lot. Which does bemuse me somewhat.
Are you really saying that companies that don't need to raise fresh capital should delist? I hope not. I have very little interest in investing in companies that have a need to raise fresh capital.
Conversely I'd very much prefer that small companies with good profits, no debt, good cashflow, growing profits and revenue don't delist - or get bought out - I'd have not a lot left to invest in?
Goodwin (LON:GDWN) I'm a latecomer - I've been watching it for years but it's always seemed on the expensive side to me, but I like the current prospects and have bought a small position with what little spare cash I could find down the back of the sofa,
cheers
Mark
If anybody hasn't listened to it I would highly recommend the Small Caps Podcast which Paul does at the weekend. It's a really good way of recapping what you might have read (or missed) in the week. It's even better when it is on Spotify by 10.00am on Saturday and I can listen to it in the gym! On Tpximpact Holdings (LON:TPX) I would say that there is new leadership and I bought at 23p because the new Finance Director bought £50K shares. I figured that if they could get a financing away ( which seams likely if the person responsible for doing the deal was showing optimism) they would probably at least double and more likely triple or more. I assumed the money I put down had a very real chance of going zero, which really helps when sizing your bet.
Biggest decliner in FTSE 250 today is Marshalls (LON:MSLH), not helped by AGM comment "Group revenue contracted by 14 per cent reflecting the uncertain macro-economic climate, a reduction in new house building and continued weakness in private housing RMI activity." Was thinking of buying some Ibstock (LON:IBST) but now looks a bit early.
The brick manufacturers have all put out quite solid udpates recently, so the update from Marshalls goes somewhat agaisnt this. Don't know the company well but wonder if it is a specific area they're exposed to that's been weak. I know until fairly recently they always traded on a high multiple (around 20x) which I never really understood.
I posted this last month, but now including the latest version. UK government data on delivery of bricks in the UK. Last data in this chart is March 2023.
Quite a dramatic decline, so i might be inclined to believe Marshall's blaming the macro environment. Imports of bricks may have suffered the most, but i can imagine domestic brick manufacturers and distributors are still affected.
I am still fuming following the RNS on 21st April that iEnergizer (LON:IBPO) are going to delist.This is legalised theft.
I also got caught by Fusionex who delisted in 2017/18. On both occasions I lost over £5k.
What can we do as Private Investors to influence the LSE to amend the Rules?
I am sure I am not the first Investor to think that the Rules on Delisting need changing and quickly. Surely the answer is that if a Company decides to delist then the Shares are Suspended IMMEDIATELY. Shareholders should then be repaid within 2 months at the Share Price at closing on the day before the delisting Announcement. The RNS must be at 7am and not at any later time.
Would AIM listen if every Subscriber to Stockopedia wrote to them and urged them to amend the Rules on Delisting.
If they will not listen instruct Burford Capital (LON:BUR) to bring a class action against Aim for our losses!I am serious this is weak regulation and we are the mugs.
Actually I think it's pretty simple. You need to ensure the free float in a listed business exceeds 50%. That way for a share to be de-listed, which requires 75% of shareholders acceptance, you need independent shareholders to agree it is in the best interests of the business and all shareholders.
Investors can, of course, do this themselves by not investing in anything where a single shareholder (or shareholders acting in concert) owns more than 50% but a listing rule would be worthwhile.
You can't have a market whereby the only way to de-list is if all shareholders are paid the prevailing market price before the announcement. No market would ever go for that.
Deleted.
Is there any possibility that iEnergizer found that a listing on the LSE was a necessary part of giving credibility to what is effectively an Indian company giving services to blue chip companies (especially in the US) ? I have read the comments on needed funding early on, which would certainly have been a factor - but maybe they found that they just didn't need the UK listing to convince new clients any more (or have sufficiently good relations with existing clients) of their business in the back streets of Noida (and I mean no disrespect to Indian companies - but it would be a hard sell to the fortune 500 companies that they claim to have).
I just hope that iEnergizer (LON:IBPO) bombs - the ESG procurement criteria score by their customers may suddenly look a lot worse. Plus the pressure to onshore now. I hope iBPO crashes and burns and his acquired 100% can have the sort of devaluation he created for us.
AIM should also look at why there aren't going to be many listings in UK - eg. all the inflated IPOs just to give PE liquidity events and then bomb out, showing it has just been an insider gravy train.
If they lose the IHT advantage then suddenly the goose is cooked rather than allowed to lay eggs.
Very positive AGM statement from Hostelworld (LON:HSW) this morning. They are Raising FY EBITDA guidance to €16.5 to €17m (vs €1.3m for FY22), but perhaps more significantly, they have recently paid off €10m of debt and successfully renegotiated their outstanding (very-expensive>9%) debt to 3.25 to 3.75% over EURIBOR.
Probably worthy of a follow-up comment from Stockopedia Towers given there was some concern over their long-term financial viability back in August.
Hostelworld (LON:HSW)
Valuation
I don't understand why this company is so highly valued.
I can't imagine cash generation being much higher than 10m EUR for 2023 (it was 11m EUR back in 2019) and the current market cap after today's bounce is 195m EUR - this looks expensive to me.
My best guess is that there's also c.10m net debt still on the books + 4.4m EUR of Payment in Kind debt, which was mentioned in the Early Repayment RNS earlier this year
I'm assuming that this latter figure relates to warrants associated with the loan agreed in 2021.
Finance Costs
Whilst the interest % on the new loan facility will be much lower (Euribor + 3.75% vs Euribor + 9.00%), I don't think the benefits are are great as they seem.
For most of 2022 Euribor was negative, so the debt interest in 2022 was probably c 8%-9%.
https://www.euribor-rates.eu/e...
Euribor today is currently c3%, so debt interest going forward will be c 6.75%.
https://www.euribor-rates.eu/e...
There was also a 2% early payment fee for the previous 30m EUR loan from HPS.
Having said all the above, it's undoubtedly a good thing that the new facility is in place otherwise the debt interest rate would be 10%, rather than the 6.75% + 2% repayment fee noted above.
But assuming that there will be little or no debt in 2024, it looks like it will only be a very short term benefit.
A
Thanks for the comment Abtan. I suppose it's being valued as a social network/tech stock, not just a travel agent! G
I have to say market is behaving strangely in relation to valuations these days that even arbitrage opportunities get no credence
You can buy Let's Explore (LON:LETS) at 4.1p and tender 65% within a month for a 10% gain so over 120% annualised returns on offer.
Then the residual 35% is backed by net cash at around 5.5p (assuming you give no value for the shell or the HBE business (which is break even / profitable)
And yet people are selling in the market at 4p a 12% discount to the price they can tender for in just 20 something days time......that's just a bizarre investment decision, but I guess it just goes to show the state of the UK smaller cap market these days.
I had lunch with a large PE house the other day and we were discussing listed valuations in the UK being at such a discount - they just smiled and were rubbing their hands. It's a big medium term problem for investors in general though.
"... listed valuations in the UK being at such a discount - they just smiled and were rubbing their hands. It's a big medium term problem for investors in general though."
problem = opportunity
not if all the better ones get taken out and liquidity increasingly dries up alas
Paul
Is there any chance you could give your views on the results last week from Cambridge Cognition Holdings (LON:COG) ?
Hi FREng,
I looked at 4 backlog items over the weekend, and need to type up my notes for those first.
But I've made a note to look at Cambridge Cognition Holdings (LON:COG) (I hold) after that. The quick version is that I thought the last results/outlook for COG seemed quite encouraging. Although in a difficult market, I'm not sure how much thrust the share price will be able to generate in the short term?
So I've gone back to sleep on it, with regard to my own personal, small, long-term holding. I'm not minded to add to it at the moment, but when market conditions generally in small caps turn more positive, I'd possibly consider topping up again, dunno. Hence overall I'll probably be amber on it for now.
What's your view?
Regards, Paul.
Thanks, Paul.
I'm convinced by the longer-term view on Cambridge Cognition Holdings (LON:COG) expressed by the anonymous person who commented on your podcast. The order book is growing, as Michael Tee also noted, and the directors have topped up their holdings in recent weeks at more than the current SP. I have just today added to my own holding.
Regards
Martyn (FREng)
re Cambridge Cognition Holdings (LON:COG) , I have just seen this useful comment from "Anonymous" on Paul's small caps blog website.
-----------------
"With respect to Cambridge Cognition, I thought the results/outlook were excellent. This is not a management team prone to hyperbole and I am certain they are not talking about growth and excitement in the future without good reason. I also think that many investors do not yet understand how backward looking the reported profit numbers are for this business. Essentially you are recognising revenue that was contracted 1 to 2 or even 3 years ago (later stage neurodegenerative clinical trials can last for 4 years or longer) against an expenditure that is preparing for trials that will winning say 2 or 3 years ahead.
The two leading indicators about the future shape of the business, in my view, are the contracted order backlog, if they keep a positive book to bill ratio, then overtime revenues will move towards this backlog number. Cash, because of the significant difference between the cash from the software sale and how they are able to account for it, cash builds up long before the accoutning recognition of the software sale. My understanding is that the software sale (90%+ gross margin) can only be accounted for as each test is consumed, so if a trial contains 100 tests, 1% of the software sale can be recognised each time a test is administered. The other thing to note is that if the trial were to terminate early there is no clawback on the software sale. In essence the cash is the sale and accounting treatment is yet another work of accounting fantasy.
I also think it is worth keeping an eye on what is being sold. So we have 3 revenue buckets, Software with 90%+ gross margin, Services with 50% to 60% gross margin and hardware with 5% to 15% gross margin. I think it is worth noting that both of the acqustions they have made in the last 6 months, fit almost entirely in to the software category and will carry 90% plus gross margins. The sales potential for both as a share of current Cambridge Cognition revenue is significant but for Winterlight it is very significant. Increased sales of Winterlight and Clinpal products have the potential to significantly improve blended gross margin across the group. With some sales success in these areas mid 85% blended gross margins are a possibility with a 2 year view. Management is saying a return to profitability in second half of 2024 (I think it is possible to infer that 2024 will be a profitable year) and MATERIAL profitability in 2025 and beyond.
This is one of the few truly world class business on AIM. The CEO here should be on your interview list in my opinion."
Hi FREng and Paul Scott
Cambridge Cognition (LON:COG)
This is interesting to read. I have been invested since April 2020 and agree with much of the contents, in particular that management are understated. Forecasts they give have been beaten during my time as shareholder. Indeed, if you had a chance to listen to their results webinar last week, you will hear they were actually a bit disappointed that that hadn't won more contracts. Nevertheless, they were ahead of initial 2022 expectations.
I also agree that it's not the 2022 rev that you need to concentrate on but the Order Book which stands at £19.6m, increasing YoY. Margins are still close to 80% even allowing for the lower margin hardware portion of revs. This is presumably hardware that can be re-used for future clients so the margin will likely improve.
I wrote a note on last Thursday's SVCR post the results and podcast with some views.
I think that although the acquisition of Winterlight may appear expensive at the moment, Voice-markers has such great potential that you have to get in early or someone else will. Matthew Stork said that some of their existing clients were interested in the type of services offered by Clinpal and Winterlight. He was also really quite excited by the quality of the funnel, as well as the volume. Matthew has successfully grown, managed and commercialised the existing Cambridge Cognition business and sees the additions as excellent fits creating an end-to-end solution.
It is of note that Matthew is actually "Dr Stork, has twenty-five years’ experience of managing companies in the med tech sector and expertise in AI, IT, diagnostics, medical equipment, and pharmaceuticals. He has a degree in pharmacy from the University of Bath, a PhD in Artificial Intelligence in Medicine from King’s College London, and an MBA from London Business School. Before becoming CEO of Cambridge Cognition in 2019, he held managing director and divisional leadership roles within GE Healthcare Digital, InHealth Group, ArjoHuntleigh, Canon Medical Systems (formerly Toshiba) and Smith & Nephew."
COG operates at the intersection of 2 high growth and high margin sectors of software development and clinical trials for CNS. There are massive sector tailwinds. This is where I like to be positioned, rather than attempting as we all do as children, to go up the down escalator.
Beware, as a holder I am biased.
Michael
After thinking about it for a few years I've finally booked my tickets to mello Wednesday! Hope to say thanks to Paul and Graham for all their analysis in person :)
Capita (LON:CPI) Capita are holding a webinar for private investors today at 12.30pm.
Helen Parris, Director of Investor Relations and Stephanie Little, investor relations manager will provide an update on performance following the publication of the FY22 results which were released on 2 March. There will be time at the end of the presentation for you Q's.
Register here
Hello Yellowstone,
I have been looking at Kenmare Resources (LON:KMR) recently, which has a very good StockRank. I watched a presentation that they did on your Youtube channel, and they came across very well. They answered quite a few questions that I had thought about looking at the recent annual report - but one that did not come up is the granting of licenses for their mining operations by the Mozambique government. They highlighted it as a growing risk (which I agree with as the deadline seems to be Dec24), when in comparison to their annual report in 2020. Obviously, I assume that they will let investors know as soon as they do, but any updates would be welcome !
Hi Paul - enjoyed the macro podcast again.
You mentioned Hostmore (LON:MORE) and the refi scheduled for late 2023 in the presentation. I went back and listened to the relevant bit again and confirm they said they expect to start late 2023 and complete Q1 2024. I think they will need 2023 nos esp since H2 "should" be very cash generative. Obviously you can't rule out a placing but since they plan to be debt free the following year, it would be a surprise to me. Fingers crossed....im guessing their plan hinges on a low 0-2% LFL perf .....so with cost pressure easing...and potentially more cuts coming....I am hopeful for a strong recovery.
Morning all.... as its US CPI data week... I had a look at the numbers which are pretty interesting.
Mth on Mth 2022
0.86, 0.89, 1.34, 0.56, 1.11, 1.37, 0.0, -0.03, 0.2, 0.4, -0.1, -0.3
2023
0.81, 0.43, 0.33
We await April. April probably a nothing done number....because we only lose 0.56% prior year. May and June on the other hand we lose 1.11 and 1.37...and so as we all know inflation should fall.
Current yr on yr = 5%.
If I flat line (ish) March 0.3% for the rest of the year .... we bottom in June at 2.7%.....above Fed target...and then rise thereafter .... ending the year at 4.5%. Of course this will not happen....but it gives you a useful line in the sand...0.3% may be taken well today...but trouble is brewing later this year.
There is no real edge in this analysis except the Bond market remains heavily inverted and screaming for cuts... whist the US CPI data doesn't really support this. Falls in US CPI are pretty rare 2008, 1949, 1954 are the only post war years. Between 1920 and 1932 CPI fell 32%....most of that between 1929 and 1932. I hope that isn't coming and I am not suggesting it is.
The current issue was caused by a combination of monetary policy and fiscal policy. The debate may move on from the current focus on monetary policy. It doesn't look like inflation is going away.... this has implications for various assets. Im not sure how the market is going to take rising inflation and monetary policy on hold....but I assume its uncomfortable in long bonds? unless the economy hits a brick wall. The pinch point is at the end of the year.
A rosier picture would be CPI flatlines from July... I guess the $ needs to stabilise....and then inflation ends the year at 2.7% but will fall a little further first which would be positive.
Valuations of UK stocks are much more attractive...the Nasdaq gain of 17% looks out of place to me... I remain fully invested but hard not to feel a little more cautious. I feel better about gold potions. Real estate and housing could face a tougher H2. Mild inflation is not too bad for stocks to be honest...especially cheaper stocks.
I was thinking about this in March, and was wondering historically how close we were to the often quoted 2% rate. I found the CPI index represented by 100 in 2015 an easier way for me to understand it, anyway, hope my figures are correct.
My morning smallcap tweet: Heads they win and fails you lose
Kanabo (LON:KNB) Trackwise Designs (LON:TWD) Let's Explore (LON:LETS) Purplebricks (LON:PURP) Amala Foods (LON:DISH) Marshalls (LON:MSLH) Mincon (LON:MCON) Hostelworld (LON:HSW) XLMedia (LON:XLM) Osirium Technologies (LON:OSI) Plant Health Care (LON:PHC), Macfarlane (LON:MACF), Windward (LON:WNWD), Midwich (LON:MIDW), TT electronics (LON:TTG)
◄Kanabo (KNB)► £2.54m placing with warrants at 2.88p, an 11% discount. Needed partly for product development focused on pain management. Hope they have something for shareholders then. [SP=NA Cap=NA]
◄Trackwise Designs (TWD)► tells EV OEM customer "delay in Parts production completion and therefore the impact upon the Parts price, has been caused by the EV OEM". Gives OEM until 2 June to remedy the breach. [SP=0.61 Cap=3m]
◄Let's Explore (LETS)► tender for 65% of cap at 4.75p. Also loans to 3 directors to allow each of them to exercise their respective Director Options in full. Yeah, that sounds fair. [SP=NA Cap=NA]
◄Purplebricks (PURP)► guides FY23 in line but warns on FY24. Cash tight. Formal Sale process: several rounds of bidding so far but "transactions being contemplated, if concluded, would be expected to deliver returns to shareholders materially below the Company's current share price." [SP=5.48 Cap=17m]
◄Amala Foods (DISH)► fantastic news for long suffering shareholders: the directors are "working hard" to achieve an RTO and lift suspension. [SP=NA Cap=NA]
◄Marshalls (MSLH)► warns FY23 below mgmt exp. Blames fall in new home starts. [SP=292.29 Cap=739m]
◄Mincon (MCON)► sounds in line. [SP=NA Cap=NA]
◄Hostelworld (HSW)► guides FY23 rev above market expectations of €14.6m. [SP=132 Cap=160m]
◄XLMedia (XLM)► revenue share agreement in North America with bet365. [SP=11.49 Cap=29m]
◄Osirium Technologies (OSI)► AGM stmt sounds OK. [SP=NA Cap=NA]
◄Plant Health Care (PHC)► PHC68949 gets first stage of regulatory approval for commercial use in Brazil. [SP=10.1 Cap=32m]
In line: MACF, WNWD, MIDW, TTG
Good to have you back Mr C