Small Cap Value Report (Tue 9 Nov 2021) - ANG, SOS, ALFA, CRPR

Good morning! It's Paul & Jack here with the SCVR for Tuesday.
Agenda -
Paul's Section:
Angling Direct (LON:ANG) - cyber-security attack from yesterday's RNS. Looks quite serious, we're now into day 4 of ANG's transactional website being down. It was hacked, and customers have been redirected towards PornHub. Plenty of banter has ensued, but will it do lasting damage?
Sosandar (LON:SOS) - I recap on this very fast-growing womenswear fashion brand, after an excellent presentation last night at Mello. It's not cheap, but the growth is now stellar, and I reckon they're set up to beat forecasts this peak trading period, driven partly by strong third party sales. Looks an exciting growth company to me - measured by facts & figures, not just wishful thinking!
James Cropper (LON:CRPR) - interim results look OK, with a good recovery in revenues, and a modest increase in profits. Note the pension deficit. I can't see anything to get excited about in these numbers.
Jack's Section:
Alfa Financial Software Holdings (LON:ALFA) - strong momentum continues. This software provider is of increasing interest to the community and broker EPS forecasts have been upped multiple times recently. Shares look pricey but, with the wind in its sails, the group deserves some kind of premium.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Angling Direct (LON:ANG)
66.5p - mkt cap £51.4m
This announcement came out yesterday. Many thanks to gus1065 for flagging it in the comments section. We’ve seen quite a few cyber attacks on companies in recent years, including ones I remember being Cake Box Holdings (LON:CBOX) and Nwf (LON:NWF) - both of which seemed to be dealt with fairly quickly & without excessive cost or disruption to the business.
I’m a bit more concerned about the cyber attack against ANG because its transactional website is a large part of its operations. If that isn’t properly protected, then the business has a serious vulnerability. It said this yesterday -
Angling Direct PLC ("Angling Direct" or the "Company"), the leading retailer of fishing tackle products and equipment, announces that it is currently managing a cyber security incident after detecting unauthorised activity on its network late on Friday 5 November 2021. This unauthorised activity shut down the Company's websites and these remain inactive. Some of the Company's social media accounts have also been compromised.
I’ve just checked, and we’re now on day 4 of the cyber attack, and ANG still hasn’t got its websites up & running, there’s just an error page.
The hackers stated, through Angling Direct’s Twitter account (which they took control of) that all customer details have been sold - as follows -
.

.
Social media is buzzing with what seems to be good-humoured banter about this incident, but the longer this downtime goes on for ANG’s transactional websites, then the more damage it could do - e.g. some customers are asking on social media if ANG has gone bust?
I thought this re-imagining of ANG’s logo in Pornhub's colours (so I am told) is rather amusing (from Facebook) -
.

.
The announcement from yesterday goes on to say -
The Board has appointed external cyber security specialists whose investigations are underway to establish what happened. Work continues round the clock to bring the websites back online while our 39 retail stores across the UK have remained open and continue to trade.
My opinion - clearly this is embarrassing, and highlights that ANG doesn’t have adequately protected IT systems. It could be expensive to sort this out, but ANG has pots of cash in the bank - possibly why it was targeted? Whether to pay the ransom? That’s always the quandary isn’t it?
Is there a risk of a class action against ANG from customers whose details have been sold by the hackers? I don’t know, but it must be a risk. Maybe ANG should send all its customers a gift voucher to apologise? IT security isn’t cheap to sort out either, so the costs could run into the hundreds of £k’s, or even low millions, who knows?
It’s a pity, because ANG shares were twitching away, like live bait, on my watchlist. It looks a fairly decent company, although note forecasts are for a reduction of profits once Govt support measures are phased out (it’s been a big beneficiary from the business rates holiday, for example).
Other investors might see this as a potential buying opportunity - the cyber problem is likely to be fixed fairly quickly, and most men are aware that pornography exists on the internet, so how many are going to be genuinely shocked? More likely it will prove a rich source of jokes for some time to come.
.
Sosandar (LON:SOS) (I hold)
32p (up 3%, at 08:21) - mkt cap £70m
This womenswear brand appeared on Mello last night, with the joint CEOs and CFO doing a very good briefing, and Q&A. I jotted down a few key points, so am sharing this with you below. NB the full briefing covered a lot more ground, so these are just particularly noteworthy points below -
40% of revenues now come from emails to the customer database - almost cost-free
Cost of customer acquisition has more than halved to £20-25
Lifetime value of customers? CFO wouldn’t be drawn on this, saying it was too early stage. I was a bit surprised at that, as LTV is a key metric that is used to create a LTV/CAC metric, a key KPI for all eCommerce businesses. Although LTV is always just an estimate, so personally I don’t place too much reliance on it.
Supply chain - “no material impact” - “well stocked”, and “great visibility” of stock intake over peak trading period.
Some upward pressure on cost of products, but has been offset by ordering larger quantities - economies of scale.
Greatly increased stock at key 3rd parties (Next, M&S, and John Lewis - all of whom approached Sosandar, wanting to stock its distinctive ranges)
Great start to this FY (03/2022). “Well on road to profitability”
Question about stock clearance - “Stock is selling so fast, we don’t need to clear stock elsewhere”. Also test & repeat business model limits problems from slow selling lines.
Returns rate? CFO refused to give a figure, just saying it has “normalised” from artificially low levels during pandemic. I wasn’t keen on this. The company has given returns rate in the past, so stopping doing so struck me as not ideal.
“Only scratched the surface” of third party, and own website sales - i.e. plenty more market share to go for.
Sourcing? Turkey & India are now the biggest. China, and others also.
My opinion - I jumped the gun with this share, buying it far too early, at the original IPO, when it was little more than a startup. With hindsight, that was too speculative, hence a mistake. For a couple of years things looked a bit dicey - strong growth, but heavy losses and repeated fundraisings.
However, something changed seriously for the better earlier this year. Revenue growth has gone through the roof, and broker forecast is for c.£24m revenues this year, and close to breakeven. I reckon that forecast could be smashed, with £25-30m looking far more likely to me, if you extrapolate out from the interim actual results, and apply the usual seasonal uplift for peak H2 trading. Hence I suspect the company is probably already profitable.
Trading on the 3rd party websites seems to be really taking off, and this is guaranteed profits, due to the way the deals work - SOS makes about 55-60% gross margin, and the websites charge a c.38% fee. The rate of stock turn is very high, so there’s considerable customer demand for SOS’s differentiated products, carefully targeted mainly at over-30 women, who want stylish, but flattering clothes - an underserved niche.
Valuation? £70m market cap is certainly not cheap any more, but this reflects the stellar growth being achieved, and the likelihood that this is now a profitable business.
All in all, an excellent presentation, and I’ll be sitting tight on my SOS shares for a long time - it can be a terrible mistake to sell out, just when a company has turned the corner, as the best is often still to come.
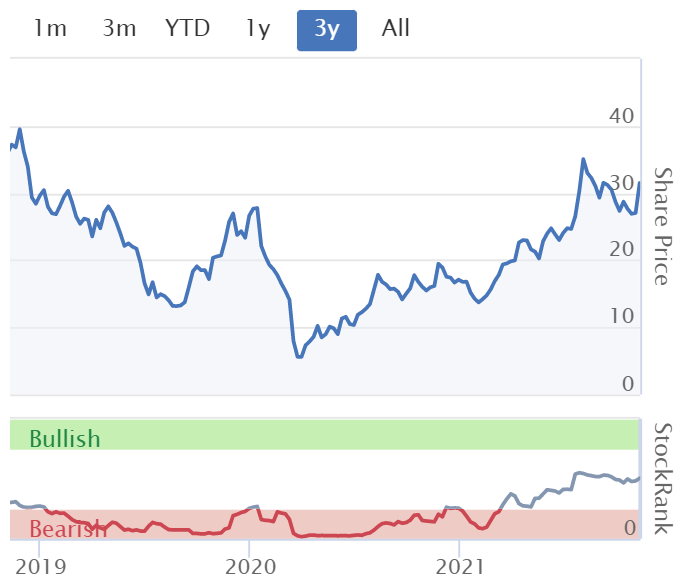
Note how the StockRank system is also reflecting SOS coming of age as a proper company, no longer blue sky.
.
James Cropper (LON:CRPR)
1365p (up 11% at 109:09) - mkt cap £130m
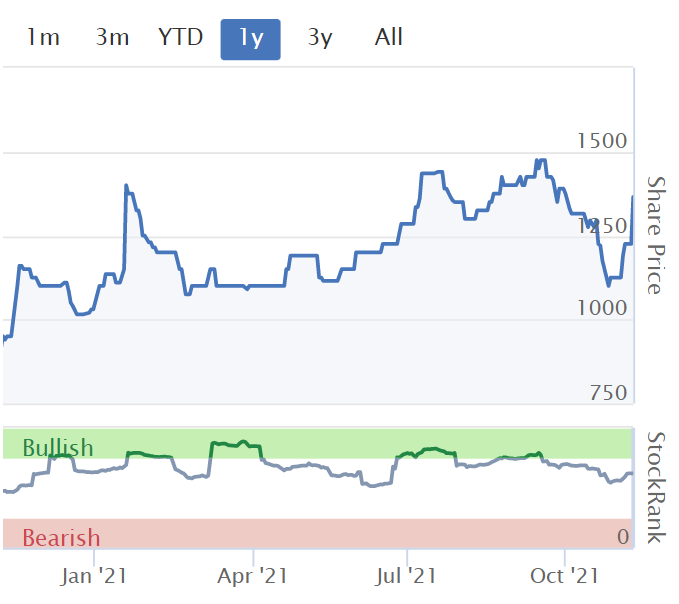
This is another interesting small cap chart, like so many others - which fell sharply in the seemingly indiscriminate drops in Sept/Oct this year, but is now bouncing back strongly. It’s very difficult to know how to handle market corrections like that - do you follow the sellers, assuming something must be wrong? Or do you ignore it as background noise? I’m definitely leaning towards the latter.
.
If I’m invested in a decent company, with good long-term fundamentals, then I won’t be panicked into selling, even if the price falls sharply. That’s when stop losses can be an absolute menace, closing you out of things due to normal market volatility, hence why I don’t use stop losses personally. Although there’s arguably a good case for new investors using stop losses, and they can be handy for speculative shares where there’s little fundamental backing to support the price - which are often the sort of story stocks that new investors congregate in.
Another point to consider, is that right now, I think some investors have sold due to the uncertainty over supply chains issues, inflation, and energy costs. Therefore it makes sense that those shares would recover quickly once the market is told that supply chain issues are under control.
All of the above is exacerbated by the dynamics of UK small caps, in that the prices tend to be very volatile, and can move a lot, on quite small volumes.
Back to Cropper.
The advanced materials and paper products group is pleased to announce its Half-year results to 25 September 2021
I reviewed Cropper’s FY 03/2021 briefly here in June, but couldn’t see much to get excited about, and there wasn’t any proper guidance from the company.
Revenues for H1 this year are up 46% to £49.8m - no big surprise there, as prior year comps are the period that was hardest hit with lockdown 1 in 2020.
Adj profit before tax of £2.3m doesn’t strike me as much of an uplift on £1.3m in the prior year’s H1, I would have expected a much larger increase in profits, for such a big increase in revenues.
Interim dividends reinstated.
Capex has resumed, to increase future production capacity.
The “Colourform” packaging products sound interesting - plastics-free, very current, and a nice potential growth area. That reminds me of Zotefoams (LON:ZTF) which we looked at the other day, which also has a new product for environmentally clean packaging. Colourform was only £1.7m revenues in H1, so early days.
Outlook - rather vague again, with the key bit saying -
In the nearer term, the full-year results are anticipated to show strong growth from the pandemic.
Balance sheet - looks fine to me, although note there is a £17.1m pension deficit.
Remember that real world cash payments into pension schemes can often be far worse than the accounting deficit suggests. So whenever final salary pension schemes exist, it is essential for investors to check the notes to the last Annual Report, to fully understand the situation.
There can be a lot of potential risk with pension schemes, given that interest rates, and inflation seem to be areas of considerable uncertainty at the moment.
My opinion - I can’t see anything particularly interesting in the numbers, or the valuation.
Maybe investors are betting on product innovation driving future growth? Perhaps holders of this share could tell us why you rate it, in the comments section? It's good to pool our knowledge.
.
Jack’s section
Alfa Financial Software Holdings (LON:ALFA)
Share price: 209.3p (+7.33%)
Shares in issue: 300,000,000
Market cap: £627.9m
Alfa Financial is a leading developer of mission-critical software for the asset finance industry. Shares remain down on where they listed a few years back.

But the trend is improving and Alfa has been getting interest from the community. Brokers have also been consistently upping their EPS estimates, so this is very much a stock on the move.


Revenue in the third quarter was strong at £20m, significantly ahead of £16m for the same period last year with high levels of chargeability which has continued through October. Cash generation has remained strong.
Delivery performance has remained excellent. Fifteen successful go-lives of Alfa Systems had been delivered at the time of the half year results in September, and this has now increased to 23.
The pipeline has gone up from seven at the half year stage to eight currently, with a ‘large prospect in Europe’ added. TCV (‘Total Contracted Value’) has risen from £125m at 30 June 2021 to £128m at 30 September 2021.
Outlook - Alfa now expects to exceed revenue estimates for 2021 by a further c3%.
Andrew Denton, CEO, said:
This has been an outstanding quarter in what has been an outstanding year for Alfa. We are delighted to see continued good progress across all areas of the business. Already this year more new customers have started using Alfa Systems in more geographies than any year in our history… we continue to have growing confidence in the outlook for the business.
Conclusion
There have been some slip ups in the past but Alfa appears to be hitting its stride, with analysts clearly struggling to fully price in the change in trajectory. The group clocks up some good quality metrics and is flagged as a top QM stock.

But the valuation is expensive. With this kind of stock, it depends on how big the market is and how well the products are placed to take share. ‘Expensive’ isn’t necessarily always expensive if future cash flows are set to grow substantially over the long term.

Nevertheless, while it’s hard to argue against the direction of travel, the upside has diminished somewhat.
It all depends on the earnings potential though and it’s still worth investigating the size of the opportunity given the strong momentum. It looks like a good business - perhaps its days qualifying for the ‘small cap’ report are numbered?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
volex( I hold)
Results are out tomorrow and the share price closed down 6% today. Rough guess as to what the results will say tomorrow?. I may be being cynical! But how do these kind of leaks (apparently) happen?
Let’s see what tomorrow brings,
Rant over with.
Volex (LON:VLX) It's up an obscene amount in the last year backed by hefty director buying. 6% sounds like noise to me.
Results due Thursday 11th (I hold).
Quite possibly related to the Tesla fall on Musk's possible pledge to sell 10% and I note that Ti Fluid Systems (LON:TIFS) is also down almost 6% - but quite how this relates to EV sales is difficult to see.
Might also/alternatively be related to the China property crash's effect on global growth.
Or, why don't we just wait to see what the numbers look like? As normal. That's what investors do.
Volex (LON:VLX), Results not out until Thursday 11th November.
James Cropper (LON:CRPR) I think this is actually quite a good company to be invested in. (I do not hold). Looking at the chart it has broken out of the downward trend recently and I would expect it to hit new highs within the next year giving a 25% increase ontop of the dividend due to those holding on 08/09/21.
The interesting part of Croppers is the new TFP which I see only improving in time. The TFP is a man made fibre made using a similar process to paper making. It is extremely light weight and strong, used for military bullet proof vests and also for airplanes.
I live local to this company and often see people who work there. I'll ask how the company is doing next time I see someone.
James Cropper I beg to differ Paul. I really like the hydrogen part of their business and see that as a real growth area. Looking at most Hydrogen companies they are on ridiculous valuations and I wonder if this isn't a back door in. Main issue I have with them and why I don't hold is the market is way tooooo tight.
LON:ALFA Just to add to Jacks commentary and comments on value - a super solid balance sheet, very rich major shareholders and has paid 2 special dividends in the last 12 months of 15p and 10p, only one of which is showing on stocko.
Sosandar (LON:SOS) completely agree Paul. The previous trading update confirmed it for me but last nights presentation was interesting, not because I expected any new information but I was on the lookout for any change in tone or demeanour from the last results presentation. I would say it was even more positive, which strongly hints to me that October has continued to go extremely well. On that basis broker forecasts look light. I felt at the interims that £27m+ and breakeven was more likely to be achieved so have been waiting for signs of upgrades and I agree with you that £27-30m is probably where they land, so maybe a 10-25% revenue upgrade to come.
It seems there is now a clear momentum behind a business that is no longer burning cash and is in demand.
Also worth keeping in mind that Q3 and Q4 last year weren't great for Sosandar (LON:SOS) - Q3 saw +6% revenue. With Christmas parties looking set to be unaffected presently then H2 should see very strong growth.
Interestingly I was looking at the John Lewis and Marks And Spencer (LON:MKS) websites this morning and Sosandar (LON:SOS) products feature among the top 10 best sellers of 'new in' products which is a good sign.
yep good points Patrick. Interesting that Sosandar (LON:SOS) products are featuring so prominently.
oops posted in wrong place
I'm put off Sosandar (LON:SOS) by their lack of consistent data. They are happy enough to share metrics when they are good but get vague when they deteriorate. Which leaves investors trying to interpret tone and body language which isn't good enough.
Hi John,
I'm put off Sosandar (LON:SOS) by their lack of consistent data. They are happy enough to share metrics when they are good but get vague when they deteriorate. Which leaves investors trying to interpret tone and body language which isn't good enough.
I don't completely agree with you there, but understand the point you're making. Sosandar was floated by Adam Reynolds, who's a lovely chap, but does tend to be a bit rampy! So there have been communications issues in the past with SOS. That said, I think it's getting better.
I checked back at the last trading update, and what it said on returns, which was this -
Now that returns rates have normalised in line with buying behaviour, the diversified category mix has also proved to have a positive effect on returns rates which are at a lower level than pre-pandemic.
So in the Mello presentation last night, you could see them giving replies to questions which reflected what was said in the RNS, which is actually very professional - that's what the rules are for listed companies - no new material information to be given in presentations.
If the company has decided to stop publishing the returns rate, thats fine, as it is quite commercially sensitive. But I'd rather they just told us that, rather than fudging the question!
I've bolded the key bit above - returns are lower than pre-pandemic, which is encouraging I think.
I will feed back this point to mgt, as I'm intending on dropping them a line to say thank you for doing Mello. They've been very receptive to my sometimes quite blunt/critical feedback in the past, to their credit.
Regards, Paul.
Hi Paul,
Is the returns rate at Sosandar (LON:SOS) really commercially sensitive - or just something that management are sensitive about letting shareholders know about to save themselves from criticism?
Obviously Sosandar are a much smaller business but the comparator in retail reporting is Next. A full read of their reports feel like sitting through a day long board meeting but that degree of openness only helps build shareholder confidence and respect from their competition.
hi John - the "returns" number could well be deemed sensitive so the presentation last night wasn't the place to announce it. I think the CFO was professional in that regard. I would personally prefer they did show it in the trading statements but I do think it is worth noting that Sosandar (LON:SOS) is nowhere near as big or mature in terms of the business model and range as Next (LON:NXT) so, asking them to deliver Next (LON:NXT) type consistency of metrics at this stage of the business is a bit much I feel.
The broad answer around returns is that it very much depends on product mix. Dresses have quite a high return rate whereas denim and loungewear have pretty low returns. Sosandar (LON:SOS) is in the process of very much widening its product range out of the former and is now up to around 2000 lines I think.
The result of this is that if you tried to compare its return rate pre lockdown to the period during lockdown you would get what looks like a big drop but that is because of the introduction of loungewear and the lack of dress purchases. Post lockdown you would see that rate go up again as more dresses get bought. I think management are a bit cautious about the absolute %ages because they didn't want people getting carried away one way or another. I say this because they have been consistent since lockdown began in steering investors away from thinking the returns rate was dropping for any other reason than the product mix and likewise now as it rises again. It is below pre pandemic levels but I would expect that as the lower return product range is also now in place.
since the range is now significantly broadened I would expect this returns number to become much more consistent going forward so agree it is something they should start to re-introduce.
Interesting discussion, but the returns rate is basically background noise. What's far more important is that sales growth is >100% pa, gross margins are strong, etc. That's what drives the business and the share price not whether the returns rate is 48% or 45%
Not a small cap anymore although it wasn't too long ago that it was and I'm sure many readers here have an interest in Games Workshop (LON:GAW) .
I've always wondered why the long standing CEO, Kevin Roundtree has so little skin in the game and today's RNS confirms that he holds 9,139 shares which is less than a million quids worth of a £3bn+ market cap business. Considering he's worked there for 23 years, it seems a relatively paltry amount to hold and it's the one thing that puts me off taking a larger position (after all if it's not a compelling proposition for the CEO, then why would it be for me?).
I'd love to hear any contrary views or to understand if there might be a good reason that I'm missing?
I guess if he is moving the share price in the right direction then why worry.
Hi johnsmith68.
I probably share the same behavioural bias of most investors in liking to see my investments’ management having material skin in the game. The counter view of course is that in terms of personal wealth risk management it sucks. If you have your monthly income, occupational pension and presumably professional reputation tied to a single company why would you also want to invest a big chunk of your personal wealth into the same enterprise? If the whole thing goes belly up lack of diversification will wipe you out. Unlikely perhaps, but I know several former City colleagues who bet the shop on their former employer, Lehman Brothers, buying stock all the way down as the business imploded during the sub prime melt down who were left virtually destitute when Lehmans went bust and with few prospects of getting a similarly well paid job. I don’t think many prudent investors would put their entire net worth into a single enterprise yet we somehow expect our senior executives to do just that thing.
Gus.
Thanks Gus for that alternative perspective - some very fair points. I still can't help feeling that he might have somewhat of a larger holding than he does but I absolutely agree with the diversification argument.
Beximco Pharmaceuticals (LON:BXP)
"Beximco Pharma introduces world's first generic molnupiravir, an oral
antiviral drug for COVID-19 treatment"
Sounds interesting, mitigating the disappointment of stalled vaccine supplies from India, and the market has marked up at the moment.
Have a small stake here as the metrics look good but bit wary of the strange UK share structure as noted by Roland:-
https://www.stockopedia.com/co...
Would be interested in others views
Phil
Beximco Pharmaceuticals (LON:BXP)
Have a small stake here as the metrics look good but bit wary of the strange UK share structure as noted by Roland:-
I held this one nearly 15 years ago so at least it is a long established company in the terms of being UK listed.
Morning Phil.
I’ve held Beximco Pharmaceuticals (LON:BXP) for several years. It has a slightly odd backstory which is worth looking into (of all things, Wikipedia gives quite a thorough potted history) but I’m comfortable holding long term and it fills a unique gap in the portfolio (Indian sub continent healthcare) without some of the impracticalities of trying to hold a locally listed share. One reference point I keep an eye on is the share price on the local Dhaka exchange. Last time I checked it was about 195p, roughly double the level on the LSE and it has been consistently at or around this kind of discount for a long time. I think that but for its unusual backstory the U.K. listed shares would re-rate to a much higher value. That may never happen but to my mind provides some downside protection.
Gus.
Thanks Gus & rmillaree
FWIW...... I had a wander over to the Merck page and noted this:-
https://www.stockopedia.com/sh...
Perhaps more interesting than I originally thought if the US Government are buying another $1bn, although obviously Beximco Pharmaceuticals (LON:BXP) won't be able to sell in the developed world.
Phil
Sounds like a phishing attack on £ANG...
Cod only knows how they will resolve it all ...
Being a Fin-tech business they should be able to cope.
Paul, would love your thoughts on James Cropper (LON:CRPR) and their H1 results today. Still with a big pensions deficit, but with return to growth for all three businesses, the topline is in good shape. Energy costs tripled but still managed a £2.3m operating profit. Plans to build plant in the US for (presumably materials for) electrolysers i.e. positioning themselves to benefit further from the huge growth in "green hydrogen" where they already have a strong position in some parts of the market, especially materials for fuel cells.
Outlook includes "It is expected that the Group will continue to grow in the second half."
I hold (and topped up this morning)
I assume it is OK to post this ?
A friend sent me this Vox Markets YouTube vid with Paul Hill and Paul Scott.
Paul Scott on top form .
Q&A with Paul Scott of Stockopedia - YouTube
Morning Dicktrade,
Thanks for posting that link to my interview (done on Sunday) with Paul Hill - who's a highly accomplished small caps investor, so we interviewed each other a bit!
I didn't want to post the link myself, as it might have looked a bit conceited, so thanks for doing so.
We run through a lot of my favourite small caps, and how Paul & I see the outlook. Hopefully people might find it interesting.
Regards, Paul.
Hi Paul,
I thoroughly enjoyed it. Lots of valuable nuggets in there , especially on the psychology of investing.
Richard
This was a superb hour-and-a-bit with lots of companies covered and some brilliant insights.
Thanks for doing Paul. It covered a few of my holdings and touched on numerous companies regularly covered here so I am sure it has something for everyone.
Well done.
Agree that this is an excellent discussion with lots of nuggets in there. Paul S we know of course, but Paul Hill is also a great commentator with interesting ideas
For me, being relatively now to Stockopedia, I hadn't picked up Paul's speciality of retail/online so I will pay extra attention in this area from now on!
Any insights from Mello Monday last night? Particularly interested in Sosandar (LON:SOS) I missed it!
Thank you
insights into Sosander clothing: as a massive online shopper for clothes I have some expertise on this area.
I am not impressed with their range of clothing, high price and in my eyes nothing special, with an over-reliance on animal prints and synthetic materials. The customer reviews are both numerous and excellent though!
Interesting comments on Sosandar (LON:SOS), which brands do you regard as being better quality and value?
Mrs. Monty is not a fan either and made 2 observations when I canvassed her opinion:
1."Mutton dressed as lamb" or something to that effect. Meow.
2. Prices far too high, relative to better quality elsewhere.
The first opinion I largely ignore as an investor (individuals are not the market, taste varies), the 2nd worries me much more, as repeat custom is vital.
Just another data point to throw in the pot.
Sosandar (LON:SOS) Difficult to get right, some older women have commented, that they don't want to be dressed, in old women's clothes.
I have only seen the adverts on TV and to me they looked smart, I would not have thought of "Mutton dressed as lamb" but then most of the models were quiet young, 30s?
Surely it depends on your age?
High prices are ok, if they can sell them, if they grow, then maybe prices could be reduced, without affecting the margins? But I have some concerns, if the quality, is not good.
What are the favoured brands in this sector?
Sosandar (LON:SOS)
Monty Carlo (or should i say his missus)
2. Prices far too high, relative to better quality elsewhere.
, the 2nd worries me much more, as repeat custom is vital.
I don't hold Sosandar but is that not exactly what prospective holders want to see?? - reasonably robust pricing at play -the proof of the pudding is that sales are increasing and that repeat business always seems to be acceptable based on stats company have presented. In summary surely they want customers who are happy to pay that extra £10- £20 per item because they arent penny pinching and they are happyw ith whatbthey get. I don't see how Sosandar could ever win in their field if they were charging the same as the less exclusive competitors who have bigger scale and more pricing power. Ref quality - as ChristineH has pointed out customer reviews are good - that suggests quality is ok.
One could argue i guess that if they are more expensive and don't have enough unique designs they may hit a brick wall at some stage in future if their customer pool is more limited - so perhaps they may have issues at some future stage iftheir customer profile is suchthat their TAM (total addressable market) mnay end up being lower than one would expect. Hopefully as they grow the brand can naturally expand into new areas if needs be ?
You only have to look at their repeat orders to see that (2) isn't right and is a number that is growing strongly. It's highlighted in the deck somewhere which I don't have to hand but seem to think it is between 2.5 -4 times a year.
It appears that people think prices are reasonable and quality is high; reviews reflect that. The level and frequency of wear from influencers (who are not paid) is also high which again suggests quality and price points are good.
Sigh.
It's not a matter of "right" or "wrong", the whole sector is much more nuanced than that.
It is more a case of trying to work out how large the addressable market is for faux leather dresses (by quality my wife was referring to fabric, not manufacture) at a premium price point, and whether that market will stay with Sosandar (LON:SOS) as fashion moves on next season.
Even the less fashion-led Next took a tumble one year when they admitted their buyers had got it wrong one season.
This is a brutally competitive market - you need to generate both brand loyalty and anticipate fashion. My wife will buy 3 or 4 things from a certain retailer one year and be happy with them, then buy absolutely nothing the following year - their catalogue getting binned after a 3 minute browse and she will switch her custom elsewhere to one of about 25 other brands....
Just my observation. Neither right nor wrong.
It is worth listening to Paul on Sosandar (LON:SOS) in the excellent video interview posted elsewhere here today. He mentions Sosandar (LON:SOS) having developed a certain "fit" that brings customers back, and also that the clothes are designed to be less revealing where ladies over 30 prefer them to be less revealing... I'm not entirely convinced that other retailers ignore this, but interesting stuff.
Have felt exactly the same since they launched. Had conversation with them several years ago re how may women wont wear polyester/nylon as it is uncomfortable. I wish them well but would not shop there myself.
My wife is not impressed either but I think their range looks good. Their KPI's also look good and management seems to be very excited, and confident, at their progress. I also bought too early but have added at not much more than my original tranche. It could run out of steam but if current momentum continues for another year it could provide a superb return for decreasing risk.
I have been a consistent ‘naysayer’ when it comes to Sosandar (LON:SOS)
Paul has probably got fed up with my negativity. So, my congratulations now to Paul and everyone else that got onboard here at the right time. My original concern was that the whole premise was very high risk - two fashion commentators are suddenly going to set up a online retailer to sell to a part of the market that they believe is underserved. A bit like a restaurant critic suddenly opening a chain of restaurants. It may work as planned but it is very high risk.
It will be very interesting to see how profitable the sales through Next and JL are once more numbers are available. As mentioned above, fashion is fickle and so it will be interesting to see if they can continue to call it right. Probably there’s a fair chance they can now they have learnt from their mistakes.
Black swan event possibility - logistics trouble. They are wholly dependent on Clipper, as I understand it, for handling all their order fulfilment and returns. They are a tiddler in Clipper’s business so will have little clout in the event of disruption.
Other more likely possibility. Copycats. There’s basically no moat here. So, if their success continues they are bound to see increased competition. Their ‘underserved’ market subsector may become very well served quickly destroying their margins.
No position myself. But I can see that short term it looks far less risky than before and could be a good investment.
Morning all,
Gattaca (LON:GATC) still falling. The price action since final results has been more akin to a profit warning!
Looks very cheap now, unless i am missing something?!
I'm not getting why this ''Superstock'' is in apparent free fall.
SR 98 today with Q 86, V 92, Mom down to 79.
Sept 15 it was ''Superstock'' SR 99 Q 87, V 88 and Mom a whopping 99!
See my comments from last week when the stock was featured by Paul and Jack.
I agree mercury61.
I m having the same issues with some of my highly ranked shares that seem to be in free fall.
I haven't been doing this for long, but it is not easy to pick winners just by looking at the Stock Ranks. Most of my successes have come from solid FTSE 100 companies, who don't always fit the criteria for a high stocko score.
Gattaca (LON:GATC)
JohnDoe2378
Gattaca (LON:GATC) still falling. The price action since final results has been more akin to a profit warning!Looks very cheap now, unless i am missing something?!
I guess this issue with this company is thats its record of posting shareholder value looks woeful - the losses booked in 2018 and 2019 alone seem to outweigh all the profits made in the other years since 2015. So this company has had £3.5 billion turnover and not made a penny for shareholders -not exactlty a ringing endorsment of its business model. Recruitment is a very low margin game and look at other similar companies that have stuggled in this sector seems very much like this has been a lifestyle business for directors.
Ok we are looking forward and not backwards - i remember Volex was a similar walking zombie a few years back - so potentially if there is a turnaround to ensure they make decent margins perhaps they they will not repeat past woes. Must admit that when a company that has been trading for many years finds the need to reinvent itself i do sometimes shake my headand wander if its simple desperation that they simply need to try something different. Looks like in current year recently started they are hoping to eak out1% margin ref bottom line numbers if things go right -high turnover business-large debtors and only 1% dropping to bottom line (is that pre exceptionals??) suggest this is not a quality business based on past numbers and forecasted numbers. Note there is potential here if the new Stem skills focus works -but the market must be looking at net fee income down 16% and increase in sales headcount of 16% and saying this company is not for me.
Looking at where we are and p/e of 10 with its pasty history of low margina and zilcho profits why are you thinking this share is cheap based on where we are ?
Also Renewi (LON:RWI) H1(Sept) rev up 11%, U/L EPS up 213%. Expects a FY beat.
Once again, no rambling. Come on Paul, we want a morning ramble! Just kidding (a little). Keep up the good work. Much appreciated. We do take it as not advice and find it extremely useful to see an accounts view on the companies.
Another acquisition for Ideagen (LON:IDEA)