Small Cap Value Report (Tues 11 April 2023) - KOO, BOWL, HFG, CINE, MJH, SMD

Good morning from Paul & Graham.
Today's report is now finished at 13:00
A big thank you to Roland for covering for me last week, so I could grab some time off in the lovely, unspoiled little island of Gozo. I'm out here for another 3 weeks, so alternating holiday & work from one week to another. Of course I can't stay away from the markets, even when on holiday, but it was relaxing not having to write reports every day. Anyway, off we go again!
Podcasts - I'm doing 2 each weekend now - one covering individual company results & trading updates in brief, and the second being general market/macro news & views. These went up on Saturday, here.
Also, I recorded a very interesting podcast with renowned investor Richard Crow, @ CockneyRebel, who as usual was full of interesting share ideas, and an upbeat assessment of the outlook, so that's worth a listen. The more I think about it, the more I suspect he may be right about the outlook for consumer stocks not being anywhere near as bad as markets seem to currently be assuming. We know about all the doom & gloom, but there are also some positive things on the horizon -
- Inflation set to fall from c.10% to c.3% by end 2023, according to the Bank of England and other forecasters.
- Interest rates - have probably nearly peaked, and won't need to be at this level once inflation has been tamed. Dangling the prospect of falls in interest rates, which of course would be very nice for asset values such as shares. IMF report on that here.
- Millions of households receiving big pay rises this month, of c.10% (state pension, benefits, and minimum wage all going up by roughly that %)
- Dramatic falls in wholesale energy costs, that "will be like a big tax cut" (R.Crow) once it feeds through into household and business bills later this year.
- Improvement in gross margins for non-food retailers in prospect, from collapse in the price of container rates to import goods, and factory gate inflation having ended, or even going into reverse, from factories competing for more cautious orders.
- Full employment, or at least very low unemployment - if that continues, then households are not likely to cut back spending further.
- Signs that many households are prioritising holidays & leisure, above buying more physical things - a buying opportunity in those sectors maybe?
How this will all interact with everything else, and all the known negative factors, I don't know. Lots of companies now seem to be saying that wage inflation is their main headache, so we need to be seeing companies finding ways to improve productivity.
As mentioned in several of my recent podcasts, I'm selectively very bullish on cheap, good quality small caps, where I think we currently have abundant buying opportunities. Investor sentiment is so negative towards small caps, that it reminds me of previous market lows, where we end up kicking ourselves afterwards, saying why didn't we ignore the gloomy mood and just snap up the bargains? I could be wrong of course, and this is all just my opinion, based on the current circumstances. Anything could happen to change things, I'm not clairvoyant! Although people rarely regret buying up bombed out shares, in times of peak gloom, in good quality companies.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Not much news today.
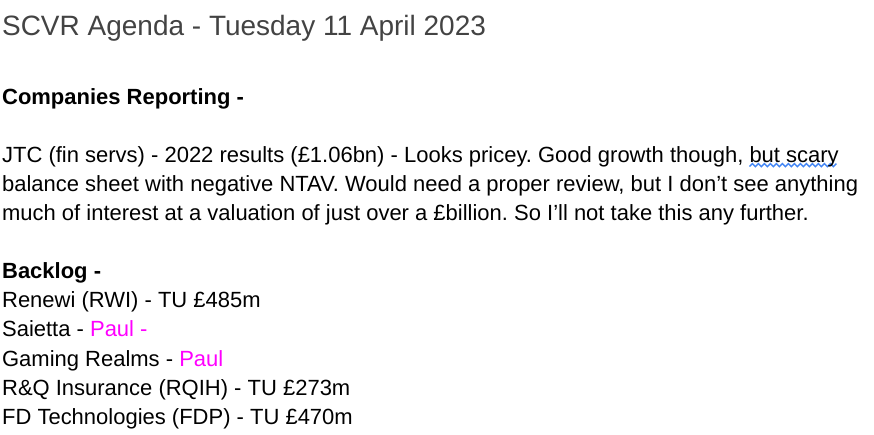
I've changed the format today, so what is in our agenda screen shot below is what we didn't get round to looking at today. Stuff we have looked at, is included in the summaries below. Mainly backlog items left, so I might have a look at those later today, and put it up tomorrow. Or, I might walk down a 1:3 hill to Ramla beach, and drink beer there for a bit, can't decide which! See you tomorrow :-)
Summaries of main sections
(more detail below)
Kooth (LON:KOO) - FY results - 230p (market cap £76m) - Graham - RED
Digital mental health provider published in-line results last week. Future US growth is the big unknown. The UK growth runway already looks limited to me. Has lots of work to do to justify its current market cap.
Hollywood Bowl (LON:BOWL) - H1 Trading Update - up 3% to 252p (mkt cap £434m) - Paul - GREEN
A positive-sounding H1 update, but it ducks the question of whether it's trading in line or not. Healthy cash position. Reasonable valuation. Continued self-funded expansion/refurbs. There's a lot to like here. The big unknown is whether current strong customer demand (and hence big profits) is sustainable or not?
Hilton Food (LON:HFG) - Finals/CEO change - 677p (market cap £607m) - Graham - AMBER
Weak results, as expected after profit warnings in late 2022. The company is optimistic that seafood performance can turn around. Very low margins and bank debt demand caution.
Quick comments only
(no sections below)
Cineworld (CINE) - Chapter 11 update - down 27% to 1.27p - Paul - RED
Yet again, it emphasises that existing equity is worthless under a restructuring plan. Yet the shares are still trading - how come? Is there some angle on this that I've missed?
MJ Hudson - another disaster - shares suspended - Paul - RED
Disposals agreed, but “it is highly unlikely that there will be a substantial, or any, amount available to Shareholders following payment of all creditors and costs.” - bad luck to holders, looks like a wipe-out for existing equity.
Spectral MD Holdings (LON:SMD) - Business combination - up 75% to 47.5p (at 12:11) (market cap £67m) - Paul - AMBER
An interesting update, which caused an 88% spike up in shares price first thing this morning, since moderated to a still impressive +61% (45p per share at 11:50). It is proposing to list on NASDAQ via an acquisition vehicle called Rosecliff Acquisition Corp I. The deal seems to provide more access to capital, and greater exposure (and a higher valuation, said to be 101p per share, with caveats).
Paul’s opinion - this looks potentially interesting, although with some way to go yet before it’s a done deal (said to be in Q3 2023). I reviewed Spectral MD here in Jan 2023, it’s unique I think, in that all revenues come from (substantial) repeat grant revenues from the US authorities. So it looks a binary outcome development project. Could be an interesting punt, but only with money people can afford to lose.
Paul’s Section:
Hollywood Bowl (LON:BOWL)
252p (up 3% at 08:28)
Market cap £434m
Hollywood Bowl, the UK's largest ten-pin bowling operator, is pleased to announce a trading update for the six months ended 31 March 2023.
The company’s headline summary shouts -
EXCELLENT PERFORMANCE DEMONSTRATING CONTINUED STRONG CUSTOMER DEMAND
H1 revenue £111.1m - up 10.9% vs H1 LY, but only 3.5% of this is like-for-like (LFL) from existing sites, with most growth coming from new sites. I’m not impressed with +3.5% LFL growth against a year earlier, well below inflation of about 10%.
Canadian business - represents about 11% of total revenue, not to be sniffed at. More new sites are happening.
UK - continuing investment in new sites, and updating existing sites. 2 new sites are both trading ahead of expectations. 2 additional sites planned for H2. There are currently 69 UK sites, and 9 Canadian sites.
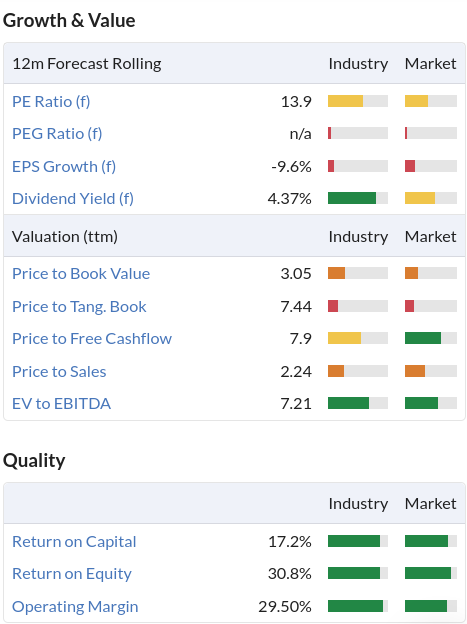
Net cash of £44.1m as at 31 March 2023 looks very healthy, and is just over 10% of the market cap. BOWL is a very cash generative business, so it looks really comfortably financed, to continue self-funding further growth, and it’s paying a forecast yield of 4.4% too.
Outlook - BOWL side-steps saying how it’s performing vs market expectations (which is the whole point of trading updates!), it’s so annoying when companies do that, and introduces doubt -
The Group is confident about the prospects for the business in FY2023 based on the strong first half of the year and the continued attractiveness of its offering but remains mindful of the ongoing economic backdrop.
Does that mean we can expect it to meet market expectations? By implication, using the words "excellent" and “strong” for H1 trading, it implies they might beat least in line. The general tone sounds upbeat too. We shouldn’t have to guess though. Trading updates are not PR exercises, we just need facts - are you trading below, in line, or ahead of expectations? Maybe advisers have told them to be cautious in case the economy worsens?
Another complaint from me is that BOWL doesn’t get any broker research out to us via Research Tree - a glaring omission for a company that’s bound to have lots of private investors holding its shares.
These are all pretty basic things.
Paul’s opinion - this is clearly a very nice business, and reasonably priced.
I like the strong balance sheet, self-funded growth in new sites/refurbs and expansion into Canada, all without any need for borrowings. All this is being done whilst paying a respectable dividend too (although divis are now a lot less attractive given that investors can park money in risk-free cash accounts and get c.3-4% in interest).
There’s really only one key question - is the current boom in customer interest in bowling sustainable longer-term? Your view on that depends on how you’ll see this share.
I don’t know about that, so am basing my decision on the figures, and positive tone of this update, so have to give it a thumbs up.
High quality metrics below, and a reasonable valuation too -
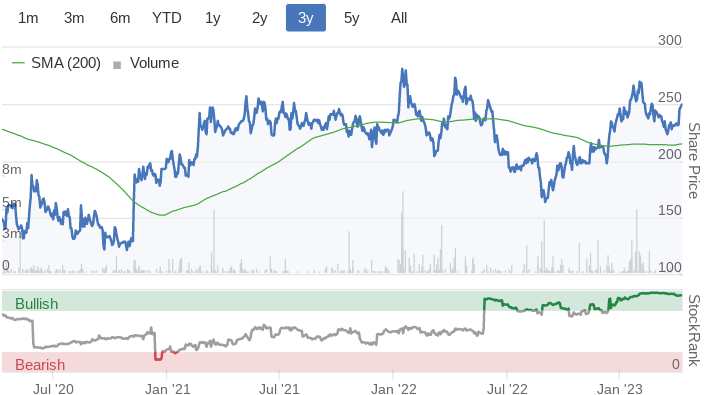
Stockopedia really likes it too - note the StockRank almost on maximum now -
Graham’s Section:
Kooth (LON:KOO)
Share price: 230p
Market cap: £76m
Kooth PLC is a digital mental health and wellbeing company working to provide a welcoming space for digital mental health care, available to all.
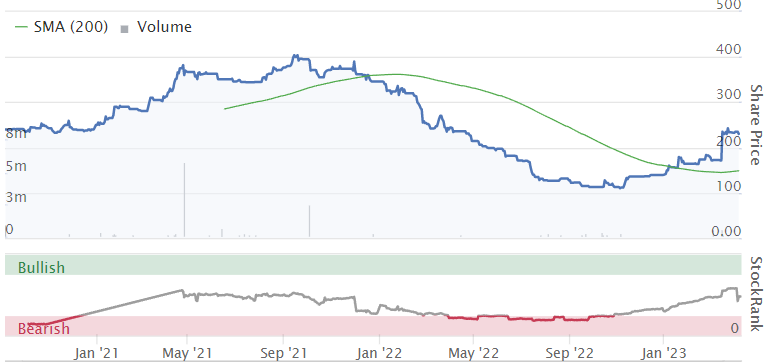
We have rarely covered this one. It was discussed by Jack and by readers back in April 2021, with the share price c. 350p. That was in the middle of the Covid-inspired tech boom, and Kooth itself had IPO’d into this environment, in September 2020.
Last week, it issued full-year results for 2022:
Revenues +21% to £20.1m (in line with expectations)
ARR +25% to £21.1m
Gross margin 68.9% (last year: 69.5%)
Adjusted EBITDA £1.6m (last year: £2.1m)
The fall in adjusted EBITDA is explained by “investment in the US and the end of COVID projects offsetting the benefits of the US ramp up”. So results had been temporarily boosted by Covid-related work.
Cash at year-end was £8.5m.
US expansion
Kooth is working on a US expansion strategy that includes a $3m pilot contract in Pennsylvania and also a proposed contract in California “to support all 13-25 year olds”. This Californian contract is still being finalised, and flows from a huge spending plan by the Governor Gavin Newsom.
The company trumpets the fact that 95% of revenues are derived from contracts that are 12 months or longer, and that net revenue retention is 107%.
However, we need to remember that they are selling to the NHS and other large institutions - to my mind, it would be quite disappointing if they weren’t operating on the basis of long-term or recurring contracts, and weren’t able to generate more revenue from their existing customers every year.
After all, this is an unprofitable company trading at a multiple of several times its revenue - it needs to have at least a few quality features, to justify this valuation!
Also, I think it’s worth noting that Kooth defines recurring revenues as “contracts with a duration of 12 months or more”. This definition doesn’t fill me with a lot of confidence, as many companies have contracts that last 12 months or more but that are certainly not examples of recurring revenue.
UK growth prospects
60% of 10-25 year olds already have free access to Kooth in the UK. Doesn’t this imply that growth prospects in the UK are already very limited, based on the existing product set for young people?
The company seems bullish on the outlook for increased NHS spending on mental health generally, but will this translate to increased revenues for Kooth?
The company does have a product for UK adults (Qwell), and 8.8 million people now have access to it. ARR from this product is now £3m.
Outlook
The company is extremely positive on growth prospects in the US, but notes that decision-making at the NHS has recently slowed down:
Kooth is extremely well-positioned to respond to the long-term demand for digital mental health services in the US and UK, with a proven track record and detailed efficacy profile, strong recurring revenue and a net cash position.
In the UK, the NHS is not only grappling with the backlog aftermath of the pandemic, but is also dealing with the reorganisation of NHS England…
While this reorganisation offers great potential for Kooth in the medium- to long-term, we have seen near-term decision making slow down as a direct result of these newly formed organisations finding their feet, filling new roles, and starting to define their population health strategies. We are starting to see the 'end of the beginning' for this reorganisation, and I'm optimistic that it will provide greater opportunities for Kooth.
Financial performance review
Revenues - 21% growth is not to be sniffed at, but investors tend to expect very fast growth from companies at this stage of their development.
Administrative expenses (excluding share-based payments, depreciation and amortisation) - grew by 29%, a significantly faster growth rate than revenues.
On an absolute basis, these expenses increased by £2.7m, which was more than the increase in gross profits.
The pre-tax loss for the year is £0.8m (last year: £0.7m).
Capitalised software development - £3m of costs skipped the income statement and went on the balance sheet instead, in the form of capitalised development costs. The net boost to P/L from this procedure was £0.9m, as £2.1m of existing intangible assets were amortised.
Development spending looks set to ramp up:
Investment in product and development continues to be significant to the Group and we anticipate capitalising software costs at a higher rate over the next few years during a period of accelerated international product investment.
Cash flow was ok; the company benefited from the use of share-based payments, from an income tax credit, and from stretching out its payables (I think this relates to some upfront customer payments).
Graham’s View
Overall, I’m going to have to give this company the thumbs down.
My reasoning is that the company is trading at a price to sales multiple of about 3x (using 2023 expectations), but it doesn’t have enough of the “quality” features that I look for when an unprofitable company is trading at a rich valuation:
Customer concentration with public sector institutional customers.
Possibly limited UK growth prospects as so much of the population already has free access to Kooth’s current products.
US growth could succeed but is highly uncertain. Kooth’s current position is that it has one pilot contract and one contract being finalised from a Governor whose state’s finances are shaky.
Expenses growing faster than gross profits.
Development spending is only going to grow; the cash pile is safe for now but should be watched carefully.
I don’t completely rule out the possibility that this could succeed for its investors, but at the present time it looks like a long-odds bet.
Hilton Food (LON:HFG)
Share price: 677p
Market cap: £607m
This share is back with us in small-cap land, after making it into the FTSE-350 index:

It issued two profit warnings last year, the most recent of which came in November, covered by Paul. Paul also looked at the first profit warning here.
Economic conditions took bites out of both volumes and margins, and seemed to particularly impact seafood.
Let’s catch up with the current state of play, with results for FY 2022 (year-ending 1st January 2023).
Revenue +16.5% to £3.8 billion (acquisitions boosted this growth, along with expansion to New Zealand and price inflation).
Volume growth much more modest at 4.3%
Adjusted operating profit down 3.3% to £71m
Reported operating profit down 14.8% to £54m. A fire in Belgium in 2021 caused more exceptional items.
Net bank debt surges to £212m after heavy spending on acquisitions, joint ventures and capex. Undrawn facilities allow for an additional £106m to be borrowed, and the lending syndicate has agreed to keep the facilities open until 2027. The lenders seem happy for the time being.
Interest cover reduces to 4.5x adjusted operating profit. This is not at a distressed level but it’s not very comfortable either. Note that this multiple can change rapidly - it was 11x last year! But higher debt, higher interest rates and lower earnings have taken their toll.
The dividend is maintained at 29.7p for the year. That’s a significant expense: c. £26.5m, although it is covered twice by reported operating profit.
Management change: the company has a new CFO (an internal hire) and a new CEO who is hired from the Co-op.
Profit margin was only 1.8% at the operating level in 2022, down from 2.2% the prior year. The seafood business is named as the culprit.
Outlook and current trading
Performance since the beginning of 2023 is in line with expectations in a “challenging” environment. The company references continued supply chain and inflation concerns.
Looking further ahead:
Our short and medium term growth prospects are underpinned by the acquisitions of Foppen, Dalco and Fairfax Meadow, the new partnership in Singapore and recovery in our UK Seafood business as well as further opportunities arising across our markets by the development of our cross-category business and the application of our supply chain management expertise.
Graham's view
The bottom line of the income statement is very disappointing with only £17.7m of after-tax profit that’s attributable to shareholders. That's after generating £3.8 billion of revenues!
And we have to remember that the enterprise value is effectively £800m+ after adding the bank debt on.
So it’s probably quite easy to make a bear case for this stock, even after the sell-off in 2022. There could be continued pressure on margins, especially when it comes to seafood - the price of fish was one of the first things I noticed when I did an analysis of my household budget last year, and I can’t have been the only one!
The very poor margins make me want to give this stock the thumbs down, but the track record is quite solid when you look back on performance in prior years:
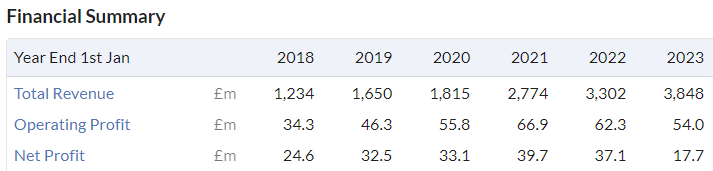
I think on balance I’ll stay neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Kooth (LON:KOO) Ps Graham, the $4.7b scheme which includes funding for Kooth's recently announced California contract was signed off in the 2021 budget; https://ebudget.ca.gov/2021-22...
"TRANSFORMING CHILDREN AND YOUTH BEHAVIORAL HEALTH
The Budget includes a comprehensive statewide transformation of the behavioral health system for all Californians age 25 and younger—so more children can grow up to be healthier, both physically and mentally. This investment expands evidenced-based programs, trains new behavioral health workers, and creates a statewide portal that can connect young people with telehealth visits and other interactive tools. This expanded system is designed to identify behavioral health conditions early and improve long-term outcomes."
Quite curious that you would assume a government body would be awarding contracts on an unfunded basis...
Kooth (LON:KOO) Both Paul & Graham need to do some further research before commenting on a company they apparently don't understand at present. You've both completely misunderstood their business & revenue model in the UK whilst ignoring huge recent progress in the USA.
I'd encourage both of you to read their annual report which was released last week; https://investors.kooth.com/wp... Page 19 describes the business & revenue model
"By working with commissioners we will determine the population they want to provide
support for, for example, 11-18 year olds. With our 20+ year track record and over 25
million data points in our platform, we can estimate the likely uptake of service within the
first year. This enables us to provide an annual subscription that covers the digital platform and
practitioner support that we will be providing. Our team of Kooth Community Mental Health
Champions will promote Kooth to local communities, schools/universities, healthcare Kooth enables individuals to access a range of tools and therapies to support their individual wants and needs.
This approach, which spans self-therapy and professional support (including counselling), is a key differentiator for Kooth in the industry. It demonstrates the ‘one size does not fit all’ approach that we view as fundamental to empowering individuals to take control of their mental health. At the same time, it creates economic benefits as we continue to build new self-guided therapies that require less intense direct support from practitioners and welfare organisations. In addition, our marketing team will focus on building awareness for Kooth in the local region through both PR and digital marketing campaigns.
As individuals sign-up and usage grows, we build the business case to grow contracts further
to meet increasing demand and usage. We grow our contracts based on the increased usage of
the platform, or to support additional age groups such as 19-25 years."
So contract value is based on platform usage and by my calculations they have penetrated around 1.5% of the UK market, leaving them with plenty of runway. I.e. In 5 years if 2 children in every class of 25 used Kooth's services (versus ~0.7 at present), then the current UK contract value would grow roughly 3x to around £55m. As they scale operational leverage will kick in driving bottom line profit, as the only fixed cost of increased usage is hiring new practitioners.
In addition, a labour government is highly likely to increase spending on digital mental health services, which would provide another tailwind for UK revenue growth...
Regarding the US expansion, Graham states it's 'highly uncertain'. Well 8 months ago they didn't have any US revenue, now they have a pending statewide contract with California that once finalised will have a "highly material impact on revenues and ARR from 2024 onwards."
Furthermore, last week some fantastic feedback from their Pennsylvania pilot study was reported; https://eu.goerie.com/story/op...
"In its first year, over 100,000 students in Pennsylvania were able to take advantage of online interactive digital education and self-monitoring tools, peer-to-peer support in a safe anonymous forum, and access to on-demand, one-on-one counseling. Most importantly, in only a few months of operation, 20 incidents of self-harm were avoided, saving lives and preserving families."
The pilot was valued at $3m, so if it is rolled out statewide the ARR will likely also be 'highly material'...
The bottom line is that there appears to be a path towards significant profitability & accelerating growth which has developed in the last few months. If you want to take a bearish, backward facing view (like the Stockopedia ranking system always does for growth companies on the verge of success) then so be it, however you will miss the boat. If they can grow PBT to £5-10m then there are plenty of AIM peers to re-rate towards, such as CER, EYE, SAAS, IQG, TRCS, IDOX, DOTD etc. Nevermind the dozens of US listed entities that trade on an average EV/NTM of 6.2x https://www.meritechcapital.co...
Hi AimingHigher,
Thanks for the additional detail on Kooth.
I'm probably a bit more positive on it than Graham is, and listened to a podcast about it last week which sounded quite interesting. The contract pending with California looks impressive, and I believe was up against over 200 competitors - let's hope Kooth didn't get squeezed too hard on price, as it's all very well winning contracts, but we want those to be profitable contracts.
I'm happy to keep monitoring Kooth, and personally I would have probably marked it AMBER for my personal opinion, but Graham's proving harder to convince at this stage!
Regards, Paul.
Cineworld (LON:CINE)
Just looked at the "Securities mentioned" screen on the right - Market capital £24m, Sales £2,450m - lest we forget ........ "Sales are vanity........."
Titon Holdings (TON) lots happening .
Pretty big albeit speculative holding of mine.
CEO out on Friday
2nd biggest shareholder sold on Friday that’s 10% of the company
Off market transaction and incoming is Rockwood taking them to 20%.
It’s a bargain basement valuation by my calculation well over 50% below NAV , bit of a Benjamin Graham cigar butt.
Big positive is the freehold massively underpins the share price plus it is actually in a very good sector as new laws mean housebuildets etc need to build with their technology on ventilation .
Korean operation is a sideshow and needs selling .
Very easy to talk to them and they seem very responsive to shareholder interest .
It’s an interesting one albeit micro cap territory and definitely needs a turnaround CEO
Does remind me of Crestchic .
Titon Holdings (LON:TON)
First thing I think when I come across a listed company with a MV of only £7m is "why is it listed". Heard the minimum fees to keep a listing (including NOMAD, broker, listing fees, etc...) is @ £100k - so they're spending 1.5% of their MV each year on keeping a listing - why? They're unlikely to do an equity raise.
Then I realized I'd looked at in the past. Used to be a Simon Thompson favorite. People who want to take this further may want to look at wimbletonsprinters comment here:-
https://www.stockopedia.com/co...
IIRC there were some posters on other Boards that suggested the Korean operation inflated profits.
Be careful, and definitely DYOR in depth.
Morning planetX,
Titon sounds interesting need to get my research head on. Rockwood get more right than wrong. Not sure how you found out about the off market transaction?
I know that Rockwood have money to invest from the Crestchic takeover and according to Richard Staveley, Rockwood are looking at/ have taken positions in 5 new companies. They are canny investors although no one gets it right all the time and patience is required.
As mentioned below, Wimbledon Sprinters comments are worth a read.
Keep well.
All the best
Not talked about recently, but may times before, is anybody else second guessing Zoo Digital (LON:ZOO)? I ask based on the Stockopedia M-Score listed as "HIGH" (maybe it always was and I just noticed or did it change?). Also re-reading the press release about supporting a "major hollywood studio" in February - why not name the studio? Perhaps there is a valid business reason not to do so, but I have to say, it gives me pause. Just wondering if anyone else is thinking along these lines.
On the other hand, the news out of Korea seems good...
Zoo Digital (LON:ZOO) it has been high since 18th July, 2022.
thanks!
Interesting RNS from Tekcapital (LON:TEK) which I hold and I think others here do too. Not for widows and orphans, as they say.
"Innovative Eyewear, Inc. Launches The First ChatGPT Enabled Smart Eyewear"
Hollywood Bowl (LON:BOWL)
Paul
Does that mean we can expect it to meet market expectations? amd . We shouldn’t have to guess though.
To me the update can't be read as saying anything other meaning than they are firmly on target to meet expectations for 2023(see quote at the botttom) - i don't see how the specific comment that they are confident about prospects for 2023 can mean anything other than they are on target. In some respects the fact they are "confident" ref 2023 prospects suggests that if anything they are more likely to updrade than downgrade ref the current year - they didn't have to use the term confident but they did.
Don't disagree with your anoyance it isnt spelled out as clearly as they could have done it - but to me it is clear they are on target to meet expectations. (feel free to prep the egg for my face later in the year - or sooner if there are any broker downgrades for this year basd on todays news)
Per the company today
"The Group is confident about the prospects for the business in FY2023 based on the strong first half of the year"
Today's video postcard from Gozo!
Hollywood Bowl (LON:BOWL)
Paul - the question is - why does it trade on a 40%+ premium to Ten Entertainment (LON:TEG) given both in the same space, growing at similar rates and are the main two large bowling providers in the UK. The rest being fragmented. Both have managed their costs well and neither are facing a cliff on energy costs etc.
Either Ten Entertainment (LON:TEG) is significantly undervalued or Hollywood Bowl (LON:BOWL) is overvalued. I'd tend to argue the former so I'd sooner own them given the relative valuation difference.
A question that has occurred to me as well David. The Canadian expansion potentially provides greater upside for Hollywood Bowl (LON:BOWL) if it gets it right, however the reverse is also true, as it adds risk.
To paraphrase Howard Marks the more you bet, the more you win, if your numbers come up, but the more you lose if they don't.
I hold Ten Entertainment (LON:TEG) where I believe the share price better reflects the value.
I hold Hollywood Bowl (LON:BOWL) but can't see much between the two. Perhaps director remuneration might make one's mind up.
Well on that basis you should buy Ten Entertainment (LON:TEG)
The CEO salary is £100k more at Hollywood Bowl (LON:BOWL) and the 100% max bonus was also paid which is another £100k
To be fair both remuneration policies are almost identical : 100% max bonus, 150% LTIP vesting in similar ranges. There is very little in it but Hollywood Bowl (LON:BOWL) are paying more for their directors.
Ten Entertainment (LON:TEG) vs Hollywood Bowl (LON:BOWL)
Isn’t the price difference down to the relative levels of gearing and historically higher returns on capital at the latter? I’m not convinced that the differential returns will persist into the future, but there’s no denying that higher debt levels create more uncertainty for the former.
Ten Entertainment (LON:TEG) has no net debt. Net cash of over £10m
Very helpful. Sharepad shows net debt of GBP 190m - hence my observation. I'm inclined to believe you rather than the software, but an explanation would be even better! Thanks.
I think you've got to be careful about how net debt is calculated and shown on stocko and the likes of Sharepad. They very likely include leases which the accounting standards count as debt whereas it isn't "real debt" as in bank loans etc. As an example Howdens on stocko shows huge gearing but it ALL lease on the stores and depots.
Sorry, a hobby horse of mine
hi BnB - yep Steves is right. the net debt shown for both Ten Entertainment (LON:TEG) and Hollywood Bowl (LON:BOWL) on the likes of Stocko and Sharepad is all leases. It does annoy me as it masks the real position of the business in my view.
So Ten Entertainment (LON:TEG) is actually a net cash position.
All in all when I compare all metrics between the two businesses I struggle to understand why one would trade at a 40% discount to the other. I accept that might mean one is overvalued rather than a re-rating for Ten Entertainment (LON:TEG) but I really don't think so.
Ten Entertainment (LON:TEG) have net cash and trade on a fwd PE of 8* and a dividend of 5% and that just feels too cheap for a good well run business. Todays statement from Hollywood Bowl (LON:BOWL) should be a good read across on trading given they are very similar businesses too.
I'm just sitting here expecting value to ultimately play out but its frustrating. Hopefully I am right :)
Ten Entertainment (LON:TEG) ( I hold)
I have owned both in the past. I think the extra liquidity has helped BOWL and also the superior return profile historically. Its less clear that there is sufficient justification anymore.
I recently met TEG and asked them about BOWL and Canadian expansion. They did not see why they would go down this path when the opportunity within the UK was still so great.
One other point re the numbers. Last years numbers from both were pretty stellar and well above 2019 levels. Beating those numbers lfl by even a few percent is very creditable in my view.
I own TEG only now because its valuation gives me more downside protection.
Good old IFRS 16. Thanks and good luck with your investment. It's not my bag in terms of business sector but it seems a solid business and does look good value. My fear is that these low valuations for UK stocks will become ingrained as the RoW looks the other way - and the value that we perceive never materialises.
If UK shares undervalued for what ever reasons. Expect more opportunisic bids, private equity interest and buy outs in smaller cap sector.
Ten Entertainment (LON:TEG)
It was certainly something along those lines BNB - perhapos worth a comparison of the differences now compared to say 5 years ago. I havent looked but i would guess ROC is likely to have improved for Ten Entertainment (LON:TEG) recently - whether thatsa new reset or simply them benefiting to favourable market conditions.
Kooth (LON:KOO) Seems remarkable that 60% of 13-25 year olds have access to their product in the UK - and I've never heard of it in the mainstream press. Maybe it's called something else?
Anyway, assuming that a v small % actually currently avail themselves of the product - what happens if this % increases? Does it increase their revenue? Or does it increase the expense of delivering the product? Or neither?!
Very interesting snippet this morning https://apple.news/ARB_vz8BQQC...
One million cigarette smokers will be offered vape starter kits as part of a government "swap to stop" scheme…
Hoping this might benefit Supreme (LON:SUP) although details have not been announced it’s expected to cost £45m over two years.
agree - but irrespective of any additional benefit from government programs Supreme (LON:SUP) look pretty cheap to me anyway
Paul, I enjoyed you podcast with Richard Crowe. Thanks.
I hope this is the correct chart for shipping freight costs. If not here is a link.
https://www.statista.com/stati...
Also another google search: https://www.drewry.co.uk/suppl...
Timbo. ; believe these are not results as such, but just notice of filing those results, notice of AGM. etc.
Regards. Geoff
Correct - I checked too
Hi Paul. Please could you take a look at Belvoir (LON:BLV) and Eurocell (LON:ECEL)? Both have reports out today. Really enjoying your podcasts also! Thank you for doing them
"More people entertaining at home as cost of living bites.
Sales of home accessories and furniture rose sharply in March, as people ate out less to save money and entertained at home instead, new figures suggest.
The British Retail Consortium (BRC) said this helped total retail sales increase by 5.1% last month compared with a year earlier.
It comes as the cost of living remains high, putting pressure on households."
Source: BBC https://www.bbc.co.uk/news/bus...
Loved your three podcasts Paul, thank you — a fascinating listen!
Morning all, a thought on interest rates. I'm in the process of selling a property and the buyer has realised that mortgage rates have dropped since she approved her current offer in Feb, so she is changing provider now. Another point, I can get 4.5% interest on cash now, so I do wonder if income stocks "only" offering 5-6% are worth holding?
Problem is that 4.5% on cash is possibly only for 12 months or so and meanwhile your money is locked up so you’re stuck if market conditions change. On a 12 month view it may well look attractive vs returns on equities but if you’re investing longer term, it may not be the best risk/reward. Been caught out on this myself.
My morning smallcap tweet: Claims processing
Ilika (LON:IKA) MGC Pharmaceuticals (LON:MXC) Woodbois (LON:WBI) GSTechnologies (LON:GST) EnSilica (LON:ENSI) Spectral MD Holdings (LON:SMD) MJ Hudson (LON:MJH) Global Invacom (LON:GINV) LSL Property Services (LON:LSL) Hollywood Bowl (LON:BOWL) Rockwood Strategic (LON:RKW)
◄Ilika (IKA)► first customer shipment of Stereax miniature batteries from its UK manufacturing facility. It ''launched' the Stereax battery in 2016! [SP=45 Cap=71m]
◄MGC Pharmaceuticals (MXC)► £1.2m placing at 0.44p, a 21% discount, to advance clinical trial progress. Also CannEpil, a CBD drug for Drug Resistant Epilepsy, now available by Named Patient Request in UK [SP=0.55 Cap=30m]
◄Woodbois (WBI)► Q1 update. Rev up. "Further efficiency and cost reduction measures to allow for additional, profitable growth are planned, including some reconfiguring of production lines, but these are anticipated to be implemented during the annual closures in December 2023" [SP=1.1 Cap=27m]
◄GSTechnologies (GST)► re SP rise: "The Sandbox Application has been assessed by the FCA who have verbally indicated that it is eligible for, and undergoing," [SP=1.1 Cap=18m]
◄EnSilica (ENSI)► $1.3m contract extension. To be booked this and next FY. Royalties now estimated at $15m (was $5m) over 5 yrs. [SP=69.7 Cap=54m]
◄Spectral MD (SMD)► to get Nasdaq listing via Business Combination with Rosecliff Acquisition Corp, a special purpose acquisition company listed on Nasdaq. Values co's EV at $170m, equivalent to c. 101p per share (assuming no redemptions). Will raise $20m (assuming no redemptions). [SP=29 Cap=39m]
◄MJ Hudson (MJH)► to sell its Data & Analytics and Business Outsourcing Divisions for up to £40m (debt free). Co owes c. £33.7m "and it is expected that further funding will be required to the point of completion of the sale of the Business Outsourcing Division". Highly unlikely to be a substantial, or any, amount available to Shareholders. Proposes de-listing.
A little recap of this disaster: Fundraise at 30p in Aug. In Oct there were small changes to guidance following audit adjustment but trading was 'encouraging'. Shares suspended at 12.5p in Dec as it didn't get audited FY ready in time. SP=13 Cap=27m]
◄Global Invacom (GINV)► audited FY op expense, loss and EPS different from Feb's unaudited stmt.. EPS now -$5.72, was -$4.85. Change due to treatment of the deregistration of a wholly-owned subsidiary. [SP=4.7 Cap=12m]
◄LSL Property Services (LSL)► sells remaining D2C brokerages for £7.8m (for First2Protect) plus up to £10m for Embtace (7x calendar '24 EBITDA). FOllows strategy to focus financial services activity on business-to-business services. [SP=257 Cap=269m]
◄Hollywood Bowl (BOWL)► guides H1 rev up 11% (up 3.5% LFL). "Cash generation has been strong, with a net cash position of £44.1m (£49.6m." [SP=235 Cap=404m]
◄Rockwood Strategic (RKW)► guides FY-Mar) NAV total return 21%. [SP=1781.1 Cap=46m]
Thanks for the weekend Podcasts Paul, I find them extremely useful and often go back on the week and pick up on the reader's comments that you highlight. As some quality replies appear later on in the day on each of the reports. I am also finding the 2nd podcast on Macro views very useful. Keep up the good work and of course, enjoy beautiful Gozo!
Thanks marcusb, that's very kind! There's no doubt the reader comments added to the SCVRs are just as important (sometimes more so!) than the reports. Hence why I like to flag them, and occasionally name check subscribers who have posted particularly useful comments, in my weekend podcasts. There always seems to be a sector expert lurking, for almost everything, which is brilliant! Especially as we don't have to wade through lots of junk posts here, which plague free bulletin boards.
almost therapeutic to hear the odd bird chirping in the background of a podcast
I find the flashes of humour quite uplifting, particularly when Paul calls out the ridiculous and indefinable.
indefensible - effing autocorrect!
There's a place in Hull reserved for the inventor of predictive text Jayman.